

Overview
The article explores an important question for young parents: should you sell your Restricted Stock Units (RSUs) right after they vest? By considering this option, you can reduce risks tied to stock price fluctuations and the potential pitfalls of having too much wealth concentrated in your employer’s stock. Imagine the peace of mind that comes from knowing your investments are secure.
Selling your RSUs can provide immediate liquidity, which is essential for those unexpected expenses that come with family life. It simplifies tax reporting, making it easier for you to manage your finances without added stress. Most importantly, diversifying your investment portfolio can enhance your financial stability and help protect against potential losses, ensuring a brighter future for your family.
Together, we can navigate this journey toward financial well-being. It’s important to understand that these decisions can have a significant impact on your family’s financial health. By taking proactive steps, you can create a more secure environment for your loved ones, allowing you to focus on what truly matters—your family’s happiness and success.
Key Highlights:
- RSUs are subject to stock price volatility, which can lead to financial losses if the stock drops after vesting.
- Concentration risk arises when a significant portion of wealth is tied to employer stock; diversification is recommended to mitigate this risk.
- Families should aim to keep employer stock holdings to no more than 10-30% of their investment portfolio.
- Immediate sale of RSUs after vesting provides liquidity for urgent expenses and helps reduce exposure to company stock risks.
- Selling RSUs can simplify tax reporting and minimise capital gains liabilities, as the sale price often matches the vesting price.
- Tax implications include ordinary income tax on vested RSUs and potential exposure to Social Security and Medicare taxes.
- Maximising contributions to tax-deferred accounts can reduce overall tax liabilities resulting from RSU income.
- Diversification across different asset classes is crucial for reducing risk and enhancing returns in investment portfolios.
- Bright Advisers offers personalised investment strategies to help families manage RSUs and achieve financial goals.
Introduction
Navigating the complexities of Restricted Stock Units (RSUs) can feel overwhelming for many families. It’s essential to recognize the potential risks and rewards involved in this journey. Understanding the implications of holding or selling RSUs is crucial to safeguarding your family’s financial well-being and achieving long-term goals. So, the pressing question arises: should families sell their RSUs immediately after they vest, or hold on in hopes of greater gains?
Imagine if you could make informed decisions that truly benefit your family. This article explores key reasons for considering an immediate sale, highlighting the benefits of liquidity, the risks of concentration, and the tax implications that could significantly impact your financial strategies. Together, we can navigate this journey, ensuring that your family’s future is secure and prosperous.
Assess the Risks of Holding RSUs
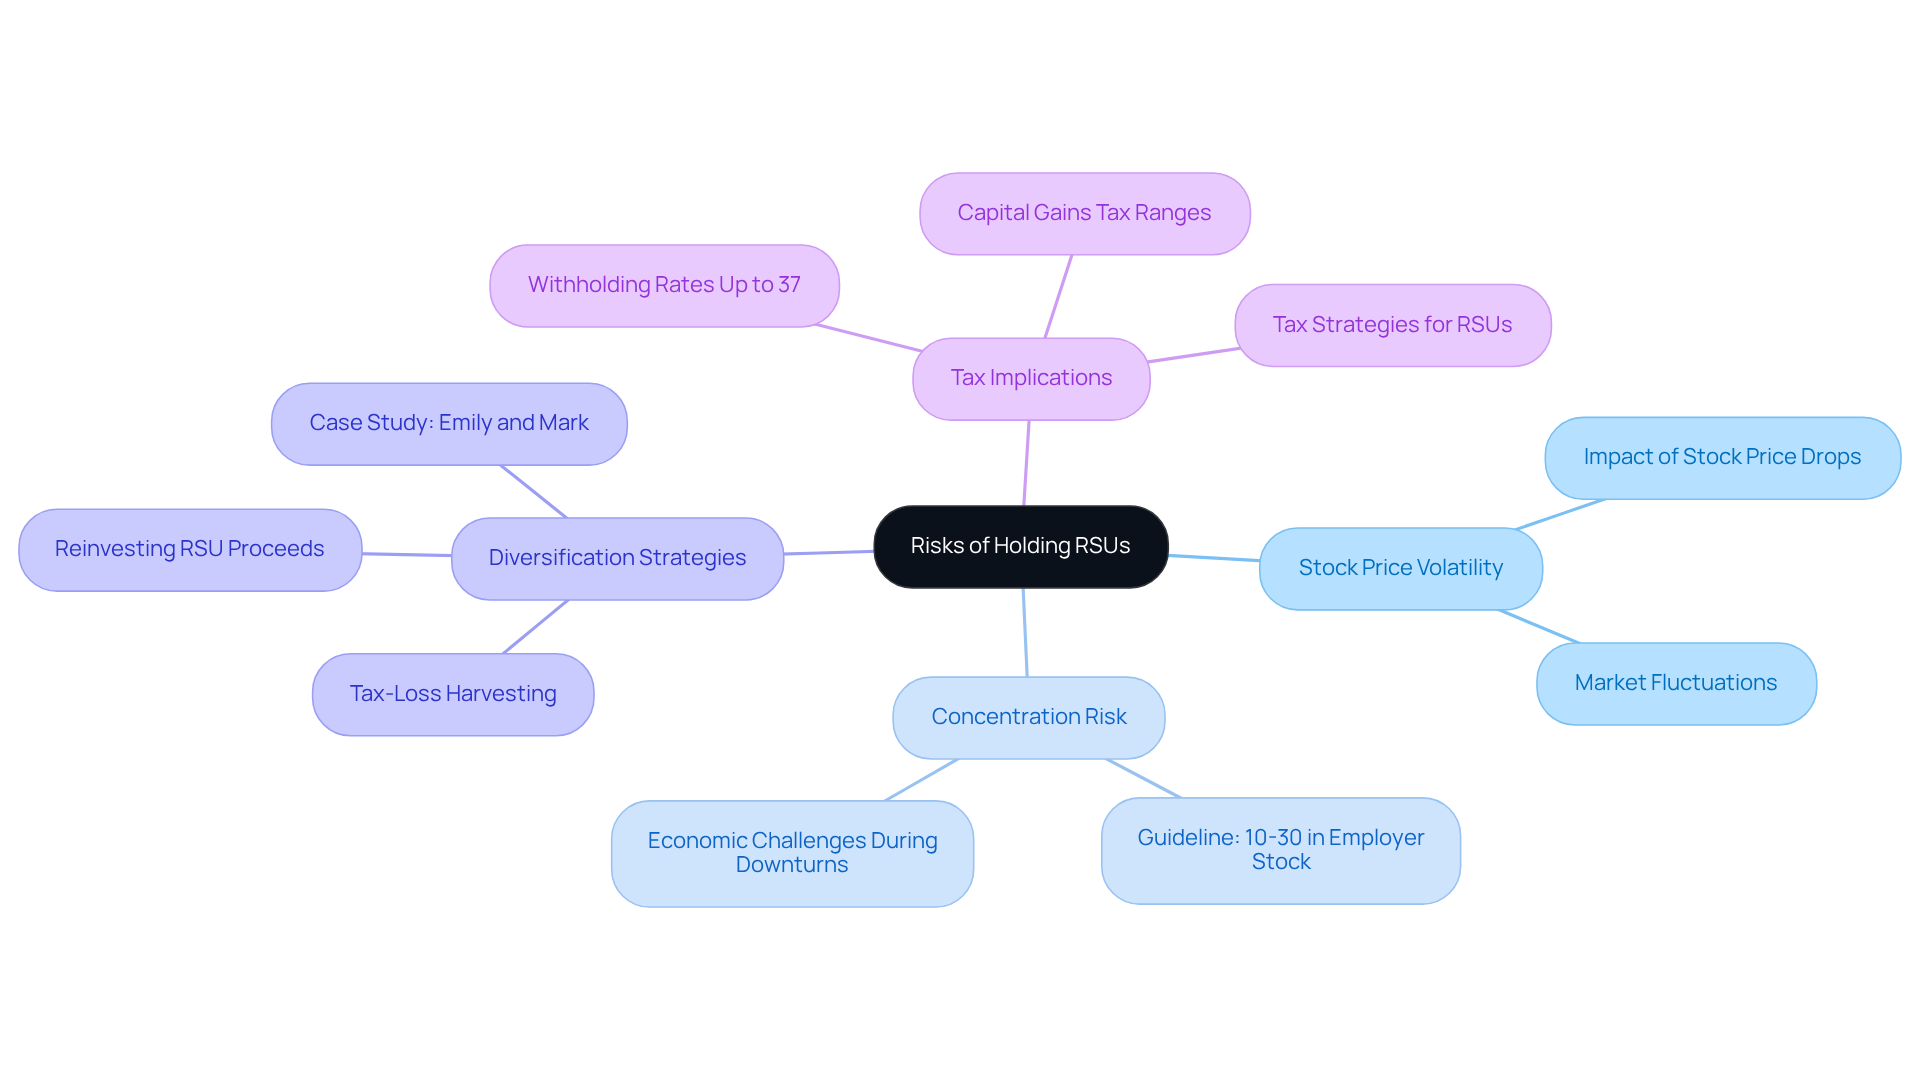
Understanding the potential risks associated with Restricted Stock Units (RSUs) is essential for ensuring your family’s financial well-being. One significant concern is stock price volatility. The value of RSUs is closely tied to your company’s stock performance. Imagine if the stock price drops after your RSUs vest; this could lead to unexpected financial losses. Such volatility can create uncertainty, especially for families aiming to build wealth across generations.
Another critical issue to consider is concentration risk. Many employees find that a substantial portion of their wealth is tied to their employer’s stock. This can pose serious economic challenges during downturns. A common guideline suggests keeping employer stock holdings to no more than 10-30% of your investment portfolio to help mitigate this risk. Without proper diversification, families may inadvertently jeopardize their financial stability, particularly if the company encounters significant difficulties.
It’s important to grasp these risks to ensure your financial strategies remain robust and adaptable in the face of market fluctuations. For instance, individuals who actively manage their RSUs can consider what should you sell RSU right away to limit exposure, which can help better safeguard their wealth and work towards their long-term financial aspirations. Additionally, families should be mindful of tax implications, as RSUs may be subject to withholding rates of up to 37%. Employing strategies such as tax-loss harvesting or seeking advice from a tax professional can optimize your tax situation related to RSUs.
By integrating strategies that address stock price volatility and concentration risk, families can navigate the complexities of RSUs more effectively. Take, for example, Emily and Mark, who partnered with Bright Advisers to manage their investments, or Allison and Brian, who improved their financial situation through strategic tax planning. Their experiences highlight the importance of tailored wealth management solutions in achieving economic security. Together, we can navigate this journey, ensuring your family’s financial future is bright and secure.
Explore the Benefits of Immediate RSU Sales
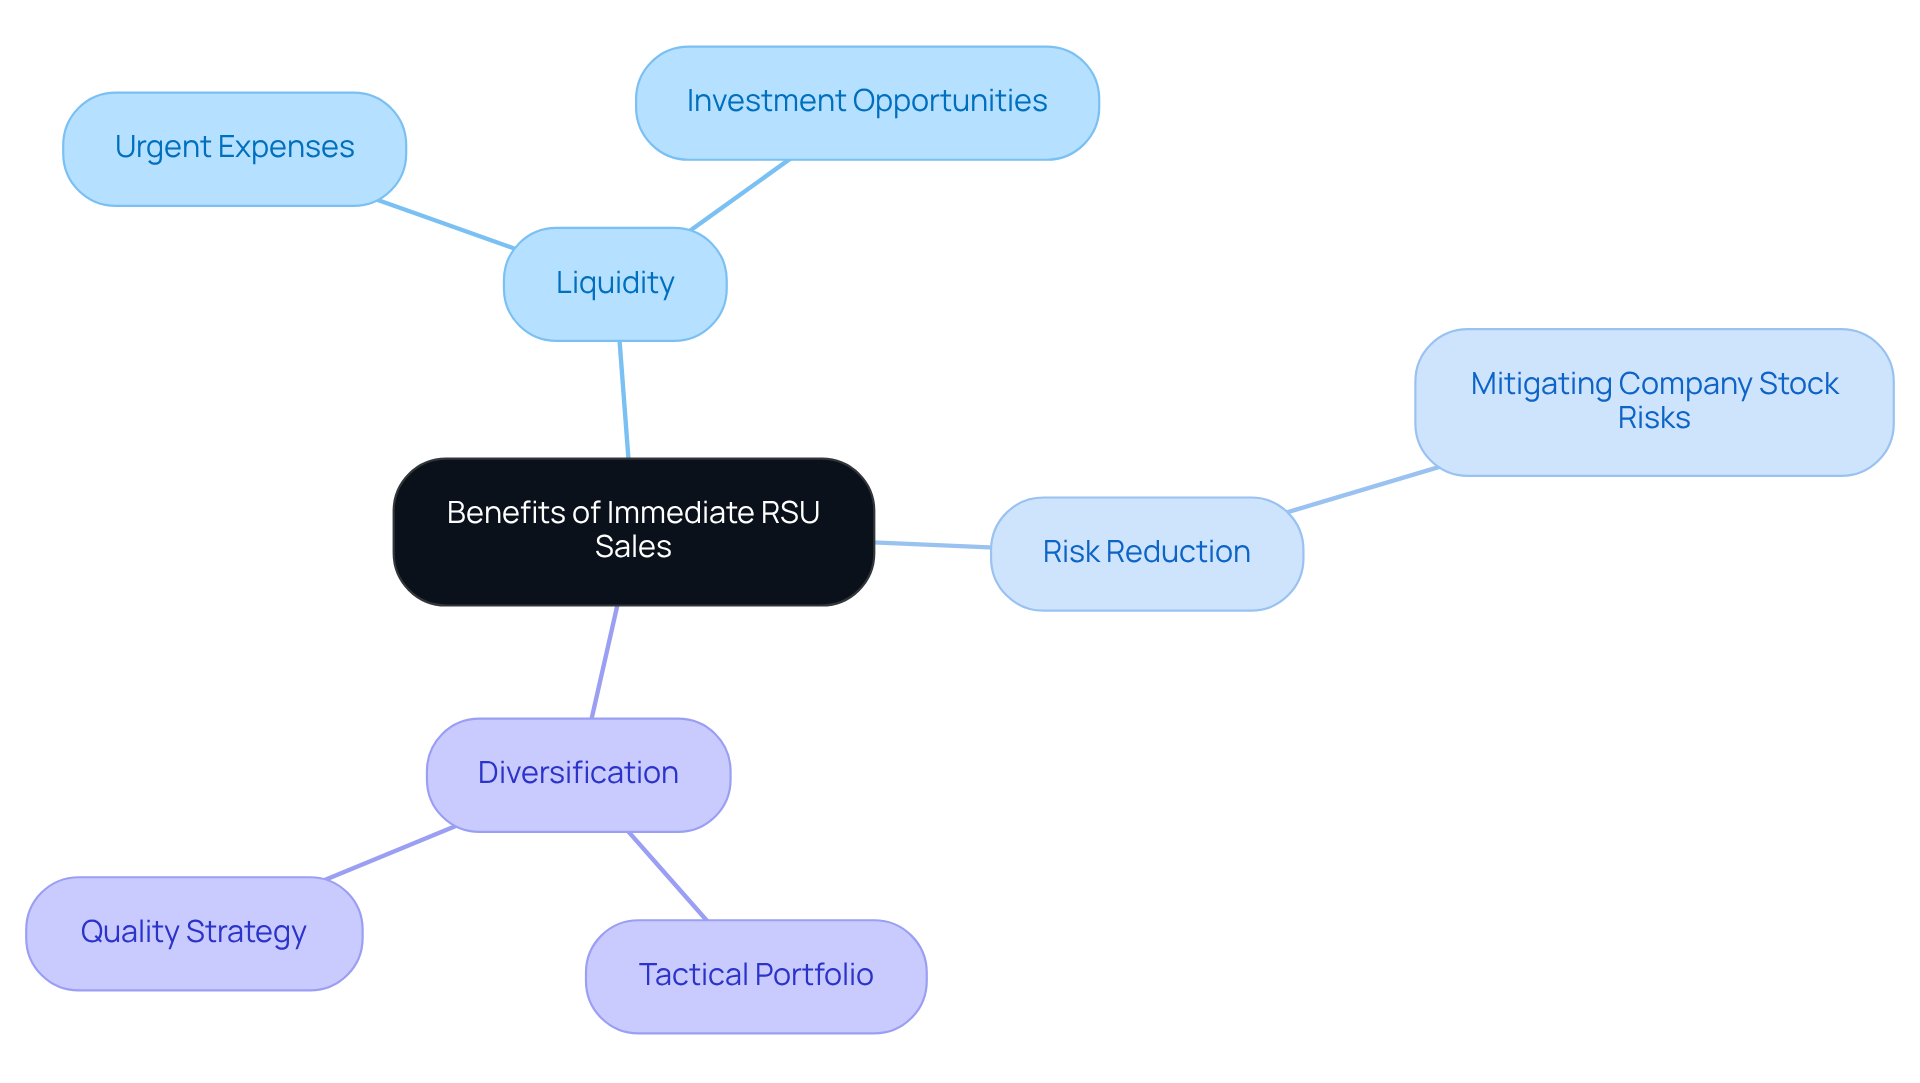
Selling RSUs right after vesting can be a game-changer for your family’s financial plan. Imagine having instant access to cash when you need it most—whether it’s for urgent expenses or exciting investment opportunities. This liquidity is vital for achieving significant goals, like buying a home or funding your children’s education.
Furthermore, selling RSUs immediately helps reduce the risks associated with holding too much company stock. It’s natural to worry about potential losses if the stock price takes a dip. Statistics show that diversifying your investments can enhance risk-adjusted returns, making it essential for families to reinvest the proceeds from RSU sales into a well-rounded portfolio.
At Bright Advisers, we understand that every family’s needs are unique. That’s why we utilize innovative strategies, such as smart beta and factor investing, to help you create a hyper-personalized portfolio that aligns with your family’s goals. By diversifying your investments across different asset categories—like our Tactical Portfolio and Quality Strategy—you can effectively manage risk while enhancing your growth potential, ensuring a more secure economic future for your loved ones.
As Louis Odette, Chief Investment Officer at Opes Wealth, wisely advises, “If you had received that compensation in cash, would you go out and buy the company stock with it? If the answer is no, then you might be wondering, should you sell RSU right away? This approach not only aligns with sound financial practices but also empowers families, like Emily and Mark, to make informed choices that prioritize their long-term well-being.
We’re here for you on this journey. To learn more about how Bright Advisers can assist you in navigating your financial path, we invite you to join our waitlist.
Understand the Tax Implications of Selling RSUs
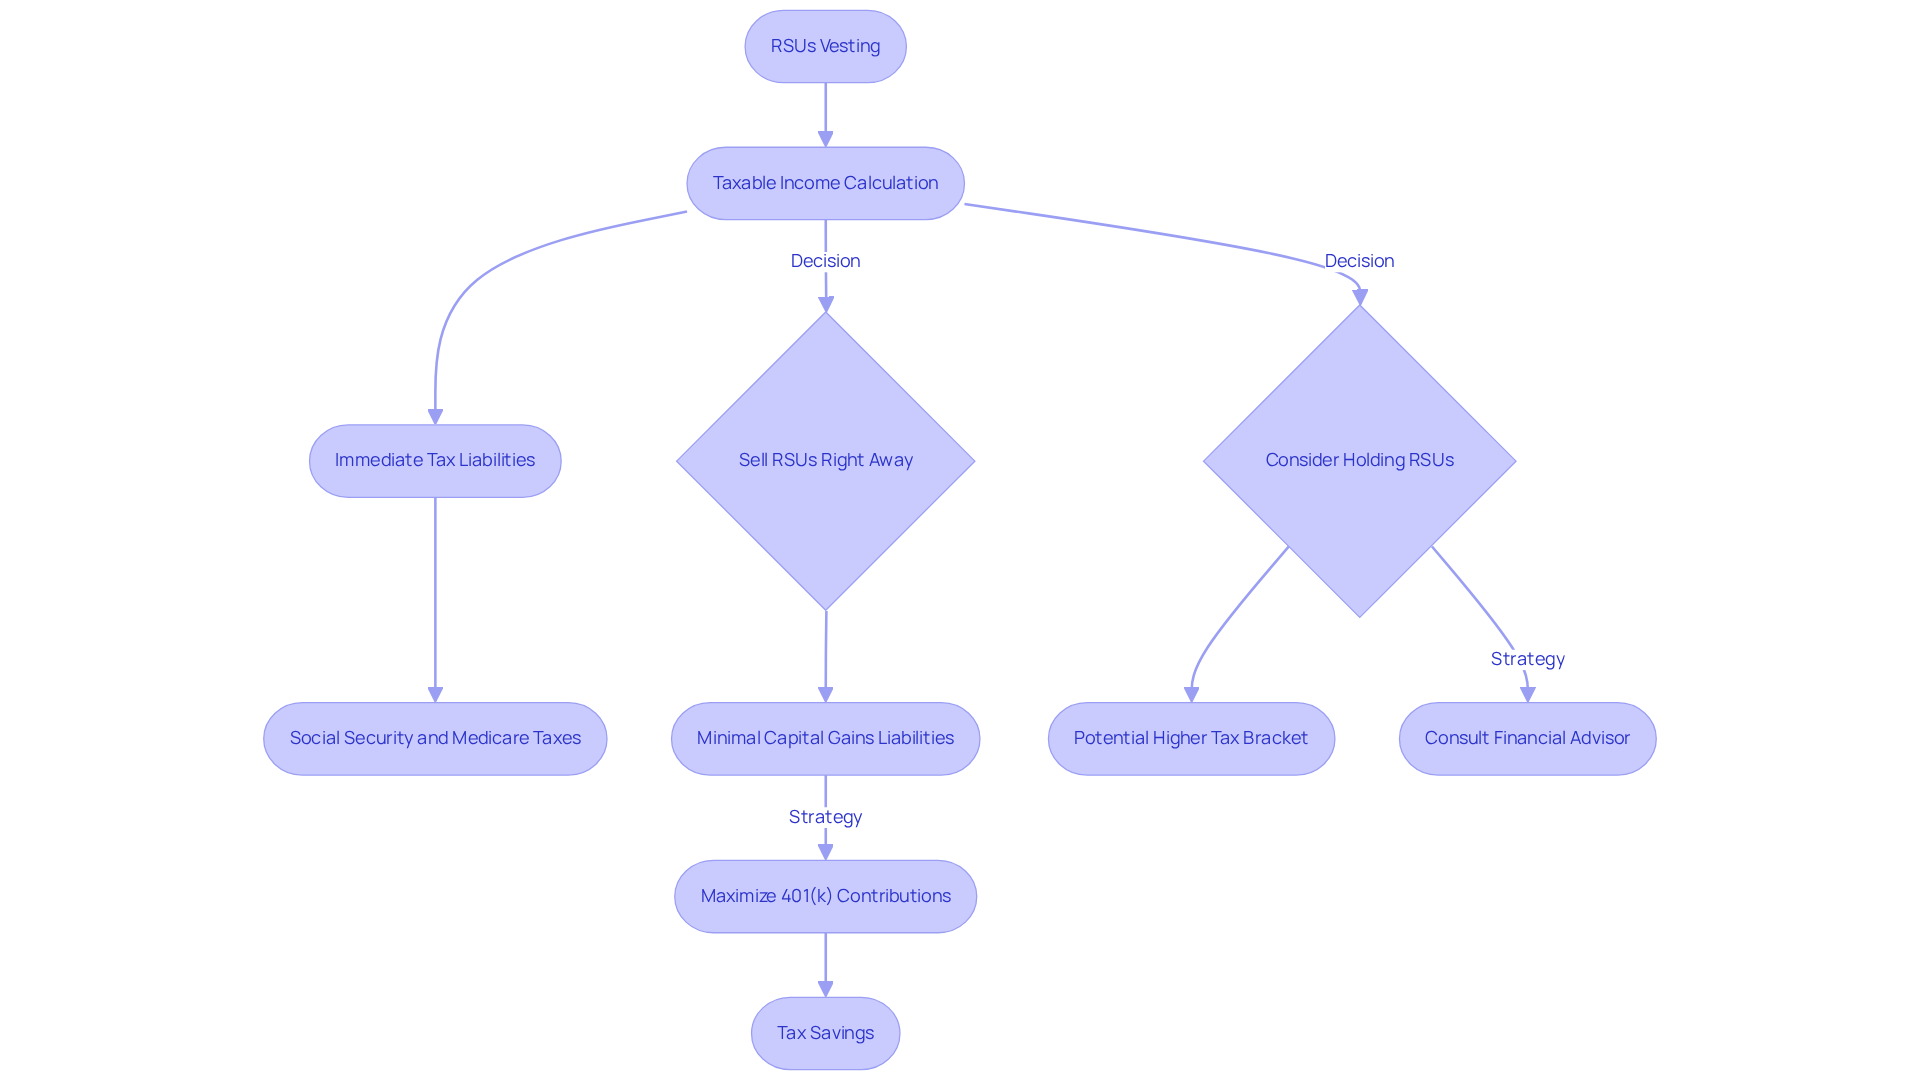
When Restricted Stock Units vest, they are taxed as ordinary income based on their fair market value, which can lead to immediate tax liabilities for employees. Imagine if an employee has 1,000 restricted stock units vesting at a market price of $50; they would face a taxable income of $50,000. It’s important to understand that Social Security and Medicare Taxes add 7.65% to the tax obligation for RSUs, a factor that families should consider in their financial planning.
However, there’s a silver lining: if you are considering what to do with your shares, should you sell RSU right away, it can significantly reduce additional tax implications. Generally, there are few to no capital gains liabilities should you sell RSU right away, as the sale price closely matches the vesting price. This approach not only simplifies tax reporting but also enables families to manage their tax obligations more efficiently.
For example, families can use the proceeds from the sale to maximize contributions to tax-deferred accounts like 401(k)s or IRAs, potentially saving thousands in taxes. Contributing $9,500 to max out a 401(k) could lead to a tax reduction of $2,280. Understanding these tax consequences is crucial for families looking to enhance their budgeting and avoid unexpected tax liabilities. You might consider whether you should sell RSU right away, as doing so can help prevent moving into higher tax brackets due to additional income from those units.
Moreover, families should be aware of the potential for Alternative Minimum Tax (AMT) exposure due to RSU income, which is especially significant for high-income earners. Implementing strategies like timing the sale of RSUs or consulting with a financial advisor can help families navigate these complexities effectively.
Just as Allison and Brian learned to improve their financial situation through strategic tax planning with Bright Advisers, young families can benefit from tailored wealth management solutions. Together, we can navigate this journey toward economic security and freedom, ensuring that your family’s financial future is bright.
Prioritize Diversification in Your Investment Portfolio
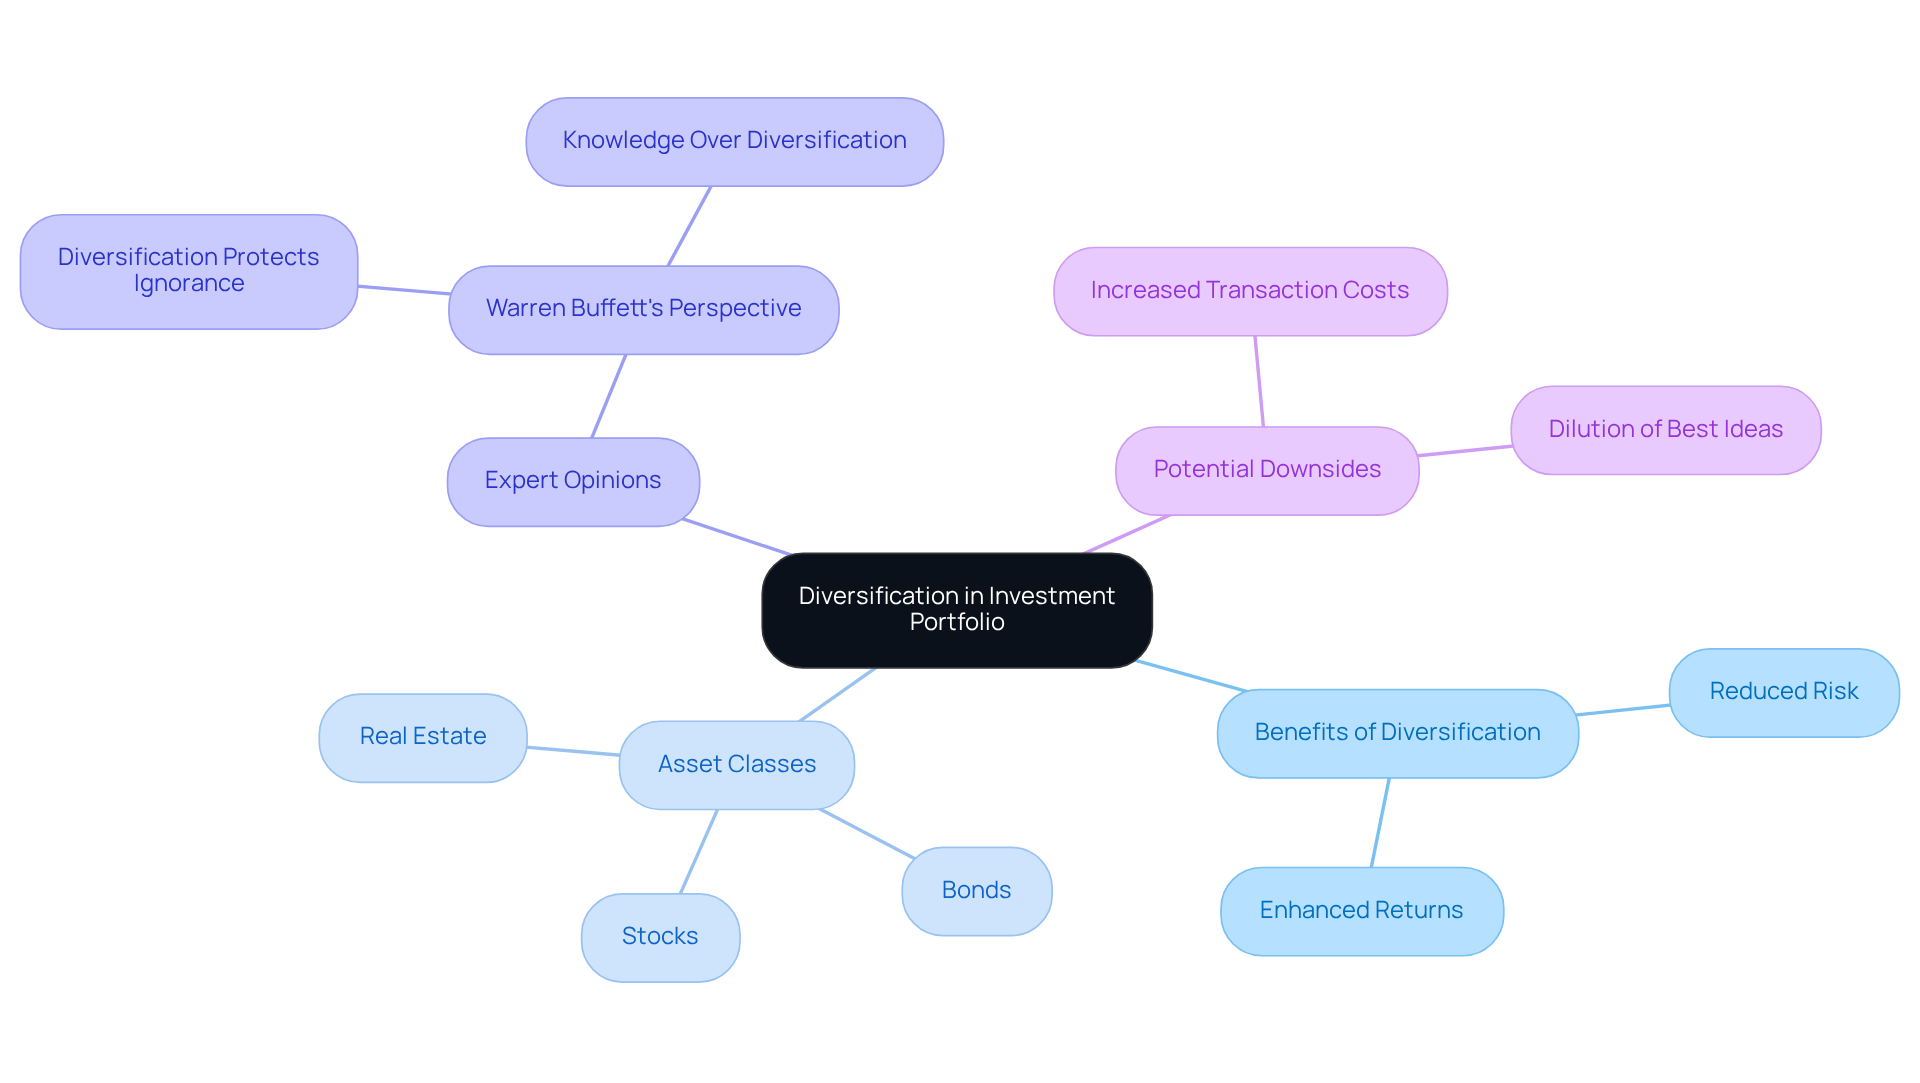
Diversification is a fundamental principle of investing that can significantly reduce risk and enhance returns. For families managing their wealth, prioritizing diversification in investment portfolios is essential. Imagine a platform that connects your financial goals with your investment strategy—Bright Advisers offers just that. By helping households distribute investments across various asset classes, such as stocks, bonds, and real estate, it reduces the impact of market volatility on your family’s financial well-being. This strategy not only safeguards against potential losses from any single investment but also opens doors to growth opportunities across different sectors.
In the context of Restricted Stock Units (RSUs), you might wonder, should you sell RSU right away by considering selling vested shares and reinvesting the proceeds into a diversified portfolio. This approach can assist families in achieving a more balanced and resilient financial future. Bright Advisers empowers families with hyper-personalized investment portfolios and financial planning solutions, easing anxiety and securing futures through effective resource allocation.
Research shows that a diversified portfolio can lead to better long-term outcomes, helping manage risk while optimizing returns. For example, Berkshire Hathaway’s holdings are diversified across roughly 47 securities, with 44% of its portfolio in Apple. This illustrates the effectiveness of a well-rounded investment strategy. Financial specialists recommend this method, emphasizing that it allows families to navigate market uncertainties with greater confidence.
Warren Buffett wisely notes that “diversification protects ignorance” and suggests that individuals with a deep understanding of specific investments may not need extensive diversification. However, families should also be mindful of the potential downsides of over-diversification, such as increased transaction costs and the dilution of their best investment ideas. Ultimately, prioritizing diversification is vital for families aiming to enhance their financial health and secure a prosperous future. Bright Advisers is committed to minimal fund fees and tailored wealth management solutions, ensuring that families receive the support they need on this journey. Together, we can navigate these financial waters and achieve your family’s dreams.
Conclusion
Navigating the world of Restricted Stock Units (RSUs) can feel overwhelming, but it’s essential to consider both the risks and rewards involved. When deciding whether to sell RSUs immediately after they vest, families can significantly influence their financial future. By understanding the potential challenges of holding onto RSUs—such as stock price volatility and concentration risk—families can make informed choices that prioritize their long-term financial security.
Imagine if you could enhance your family’s financial stability. Key insights from this exploration reveal the importance of liquidity, the benefits of selling RSUs right away to reduce exposure to company stock, and the tax implications that come with these transactions. Families are encouraged to explore strategies like diversification to strengthen their investment portfolios and mitigate risks associated with holding employer stock. Stories of families who have successfully navigated these challenges highlight the importance of personalized financial advice and proactive wealth management.
Ultimately, your journey toward financial stability and growth hinges on informed decision-making. By weighing the benefits of immediate RSU sales against the risks of holding, families can better position themselves for a secure future. Embracing strategies that prioritize diversification and effective tax management can empower families to navigate the complexities of RSUs with confidence. Remember, together, we can pave the way for a prosperous financial future.
Frequently Asked Questions
What are Restricted Stock Units (RSUs)?
Restricted Stock Units (RSUs) are a form of compensation offered by employers that give employees the right to receive shares of the company’s stock after certain conditions are met, such as vesting periods.
What are the main risks associated with holding RSUs?
The main risks include stock price volatility, which can lead to unexpected financial losses if the stock price drops after the RSUs vest, and concentration risk, where a substantial portion of an employee’s wealth is tied to their employer’s stock, potentially jeopardizing financial stability during downturns.
How can stock price volatility affect RSUs?
Stock price volatility can create uncertainty for employees, as a drop in stock price after RSUs vest can result in financial losses, impacting the overall wealth-building efforts of families.
What is concentration risk regarding RSUs?
Concentration risk occurs when a significant portion of an employee’s wealth is invested in their employer’s stock, which can pose economic challenges, especially during market downturns. It is generally advised to limit employer stock holdings to no more than 10-30% of an investment portfolio.
What strategies can help manage the risks of holding RSUs?
Individuals can actively manage their RSUs by considering when to sell them to limit exposure and safeguard their wealth. Additionally, employing tax strategies, such as tax-loss harvesting or consulting with a tax professional, can optimize the tax implications associated with RSUs.
What are the tax implications of RSUs?
RSUs may be subject to withholding rates of up to 37%, which can significantly affect an individual’s tax situation. Proper tax planning is essential to manage these implications effectively.
Can you provide examples of how families have successfully managed their RSUs?
Emily and Mark partnered with Bright Advisers to manage their investments, while Allison and Brian improved their financial situation through strategic tax planning. These examples illustrate the importance of tailored wealth management solutions in achieving economic security.
List of Sources
- Assess the Risks of Holding RSUs
- Restricted Stock Units and Building a Diversified Portfolio (https://brightonjones.com/blog/restricted-stock-units)
- RSUs: A Guide to Understanding Restricted Stock Units | Facet (https://facet.com/equity/understanding-restricted-stock-units-rsus-taxes-vesting-schedules-pros-cons)
- Restricted Stock Units: How RSUs Works for Startups (https://cakeequity.com/guides/restricted-stock-units)
- How Do RSUs Work – A Look into the Lifecycle (https://zajacgrp.com/insights/understanding-the-life-cycle-of-restricted-stock)
- Quotes on Volatility • Novel Investor (https://novelinvestor.com/quote-category/volatility)
- Explore the Benefits of Immediate RSU Sales
- Should You Sell RSUs Immediately? — EquityFTW (https://equityftw.com/articles/should-you-sell-rsus-immediately)
- Restricted Stock Unit (RSU): A Complete Guide to RSUs (https://carta.com/learn/equity/rsu)
- When Should You Sell Restricted Stock Units (RSUs)? – OPES Wealth (https://opeswealth.com/when-should-you-sell-restricted-stock-units-rsus)
- Restricted Stock Units and How They Work | Wealthspire (https://wealthspire.com/blog/restricted-stock-units-rsus-how-they-work-6-common-misconceptions)
- Understand the Tax Implications of Selling RSUs
- Understanding RSU Tax Rates: Comprehensive Guide with Calculator (https://advisorfinder.com/resources-for-clients/tax/rsu-tax-rate)
- How Are Restricted Stock Units (RSUs) Taxed? (https://smartasset.com/investing/how-are-restricted-stock-units-taxed)
- RSU Taxes Explained + 4 Tax Strategies for 2023 (https://cordantwealth.com/rsus-tax-saving-and-hedging)
- Prioritize Diversification in Your Investment Portfolio
- What Did Warren Buffett’s Diversification Quote Mean? (https://investopedia.com/ask/answers/031115/what-did-warren-buffett-mean-when-he-said-diversification-protection-against-ignorance-it-makes.asp)
- Four Reasons Why Portfolio Diversification is Important (https://ifa.com/articles/portfolio_diversification_important)
- Quotes on Diversification • Novel Investor (https://novelinvestor.com/quote-category/diversification)
- Why Portfolio Diversification Helped Investors in 2022 (https://morningstar.com/portfolios/why-portfolio-diversification-helped-investors-2022)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading