

Key Highlights:
- SLATs are irrevocable trusts set up by one spouse for the benefit of the other, allowing access to trust resources while keeping them out of taxable holdings.
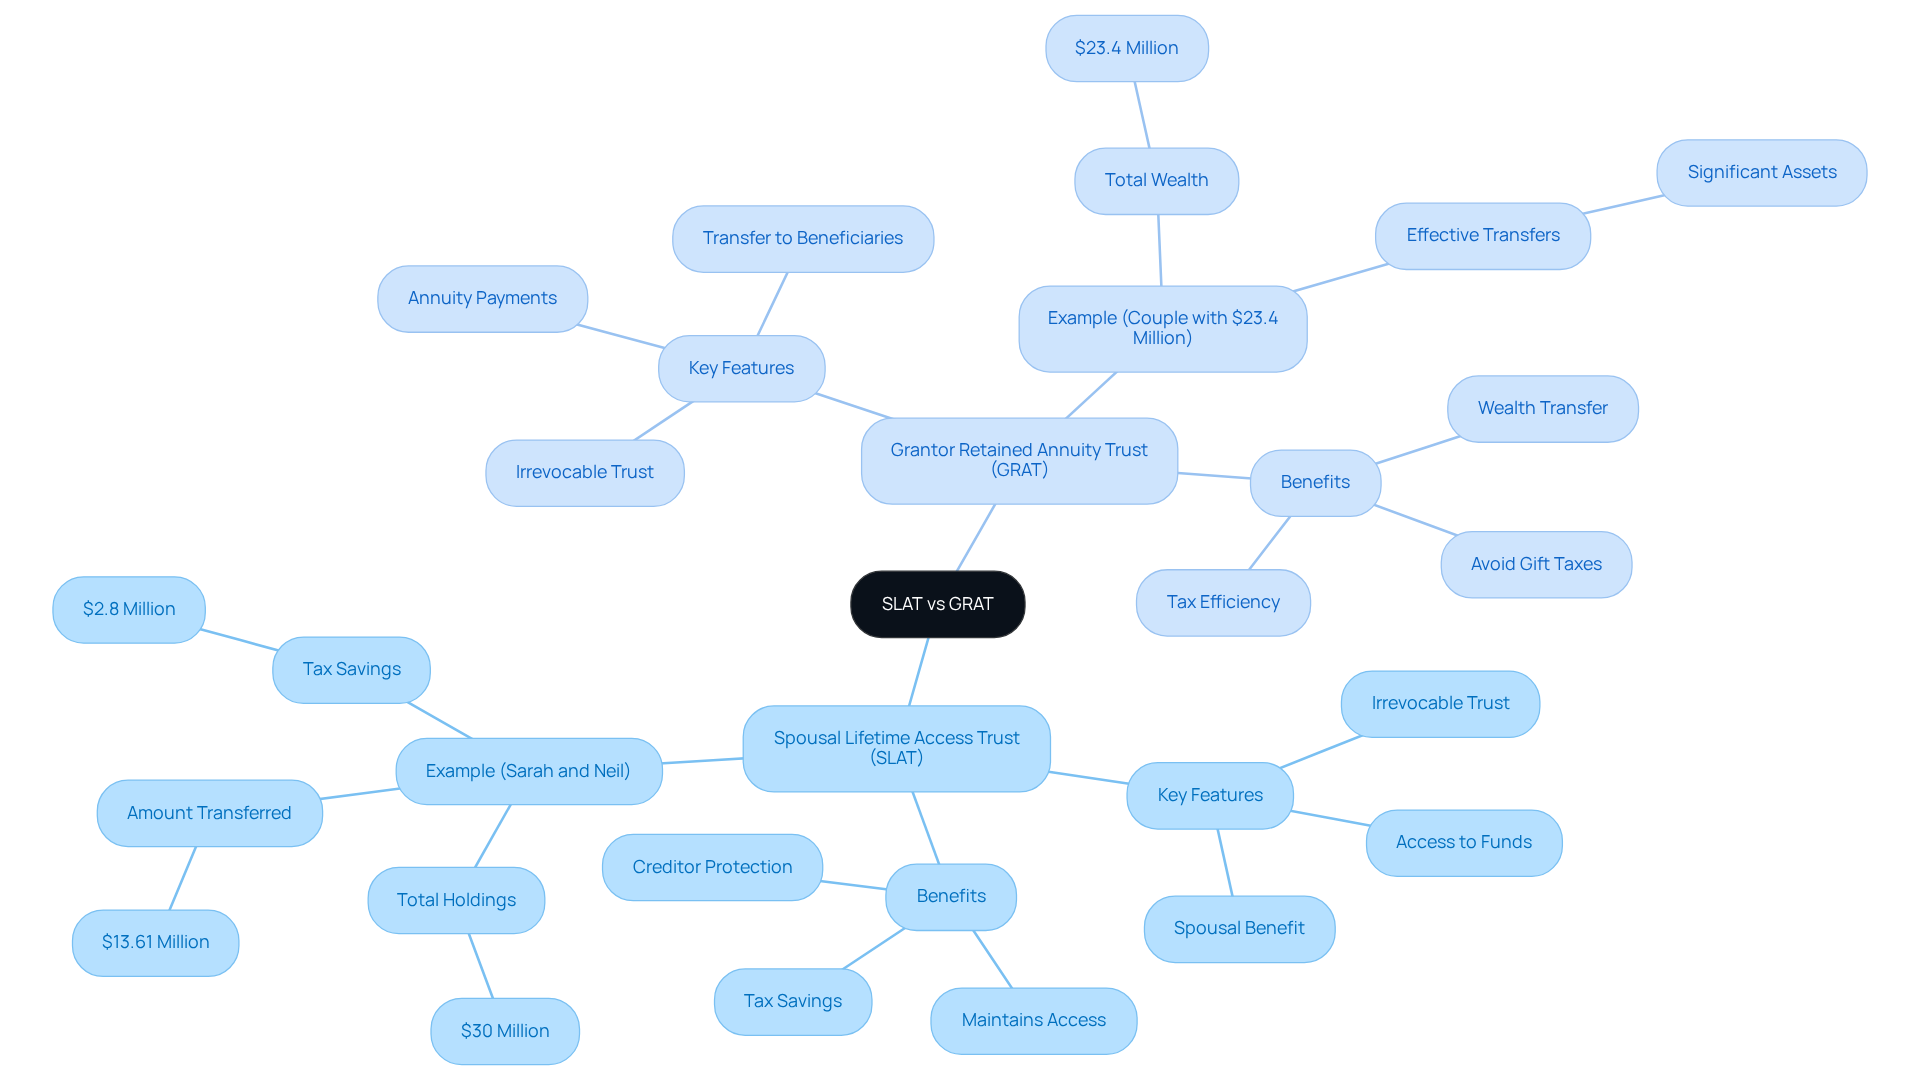
- For example, a couple saved over $2.8 million in estate taxes by using a SLAT to transfer $13.61 million of their $30 million holdings.
- GRATs allow the grantor to receive annuity payments for a specified period, with remaining assets transferring to beneficiaries afterward, minimising gift tax implications.
- An example shows that a couple with $23.4 million can effectively transfer assets through a GRAT, leveraging high exemption levels to avoid tax liabilities.
- SLATs prioritise spousal access and financial security, while GRATs focus on tax efficiency and wealth transfer.
- Both SLATs and GRATs have unique benefits tailored for different family financial situations, making understanding their differences essential.
- Challenges of SLATs include the irrevocable nature and potential loss of access to resources if the beneficiary spouse dies.
- GRATs may revert assets back to the grantor’s estate if the grantor dies before the trust period ends, negating tax benefits.
- Consulting financial planners is crucial for navigating SLAT and GRAT complexities, especially with impending changes in tax exemptions.
Introduction
Navigating the complexities of estate planning can feel overwhelming, especially for families eager to secure their financial futures. Imagine if you could simplify this journey and find peace of mind. Among the many strategies available, Spousal Lifetime Access Trusts (SLATs) and Grantor Retained Annuity Trusts (GRATs) shine as powerful tools, each tailored to meet unique financial needs.
As you explore your options, a crucial question arises: which strategy – SLAT or GRAT – aligns best with your family’s financial goals and circumstances? It’s important to understand the distinct benefits and limitations of each approach. By doing so, you can make informed decisions that will positively impact generations to come.
We’re here for you, ready to help you navigate this journey with compassion and understanding. Together, we can explore these strategies and find the right fit for your family’s future.
Understanding SLAT and GRAT: Definitions and Key Features
Navigating the world of financial planning can feel overwhelming, especially for young parents. Considering a Spousal Lifetime Access Trust (SLAT) can help you understand the differences in SLAT vs GRAT. This irrevocable trust is set up by one spouse for the benefit of the other and potentially their children. Imagine having the peace of mind that comes from knowing your loved ones can access trust resources during their lifetime, while also keeping those resources out of the grantor’s taxable holdings. For instance, consider Sarah and Neil, who had total holdings of $30 million. They utilized a finalized gift SLAT, transferring $13.61 million, which saved them over $2.8 million in future estate levies while ensuring Sarah had access to funds when needed.
On the other hand, when considering SLAT vs GRAT, a Grantor Retained Annuity Trust (GRAT) offers a different approach. This irrevocable trust is designed to reduce gift levies. The grantor receives annuity payments for a specified duration, and any remaining resources in the GRAT transfer to the beneficiaries after this period. This strategy can ideally increase in value without incurring additional gift taxes. For example, a couple with a combined wealth of $23.4 million can effectively transfer significant assets through a GRAT, leveraging current high exemption levels to avoid substantial tax liabilities.
Both trusts serve unique functions in legacy planning. The comparison of SLAT vs GRAT shows that SLATs prioritize spousal access and monetary security, while GRATs focus on tax efficiency and wealth transfer. As families increasingly seek effective wealth planning strategies, understanding the differences in SLAT vs GRAT becomes essential. This knowledge empowers you to make informed choices that align with your family’s financial objectives.
Consider the challenges faced by high-income families like Allison and Brian. They may not fully recognize the financial opportunities available to them due to insufficient tax planning. With proposals to to $3.5 million, it’s crucial for families to act quickly. By exploring these strategies, you can maximize your benefits before potential changes in tax legislation.
Remember, we’re here for you. Together, we can navigate this journey toward securing your family’s financial future.
Benefits of SLATs and GRATs: Evaluating Advantages for Families
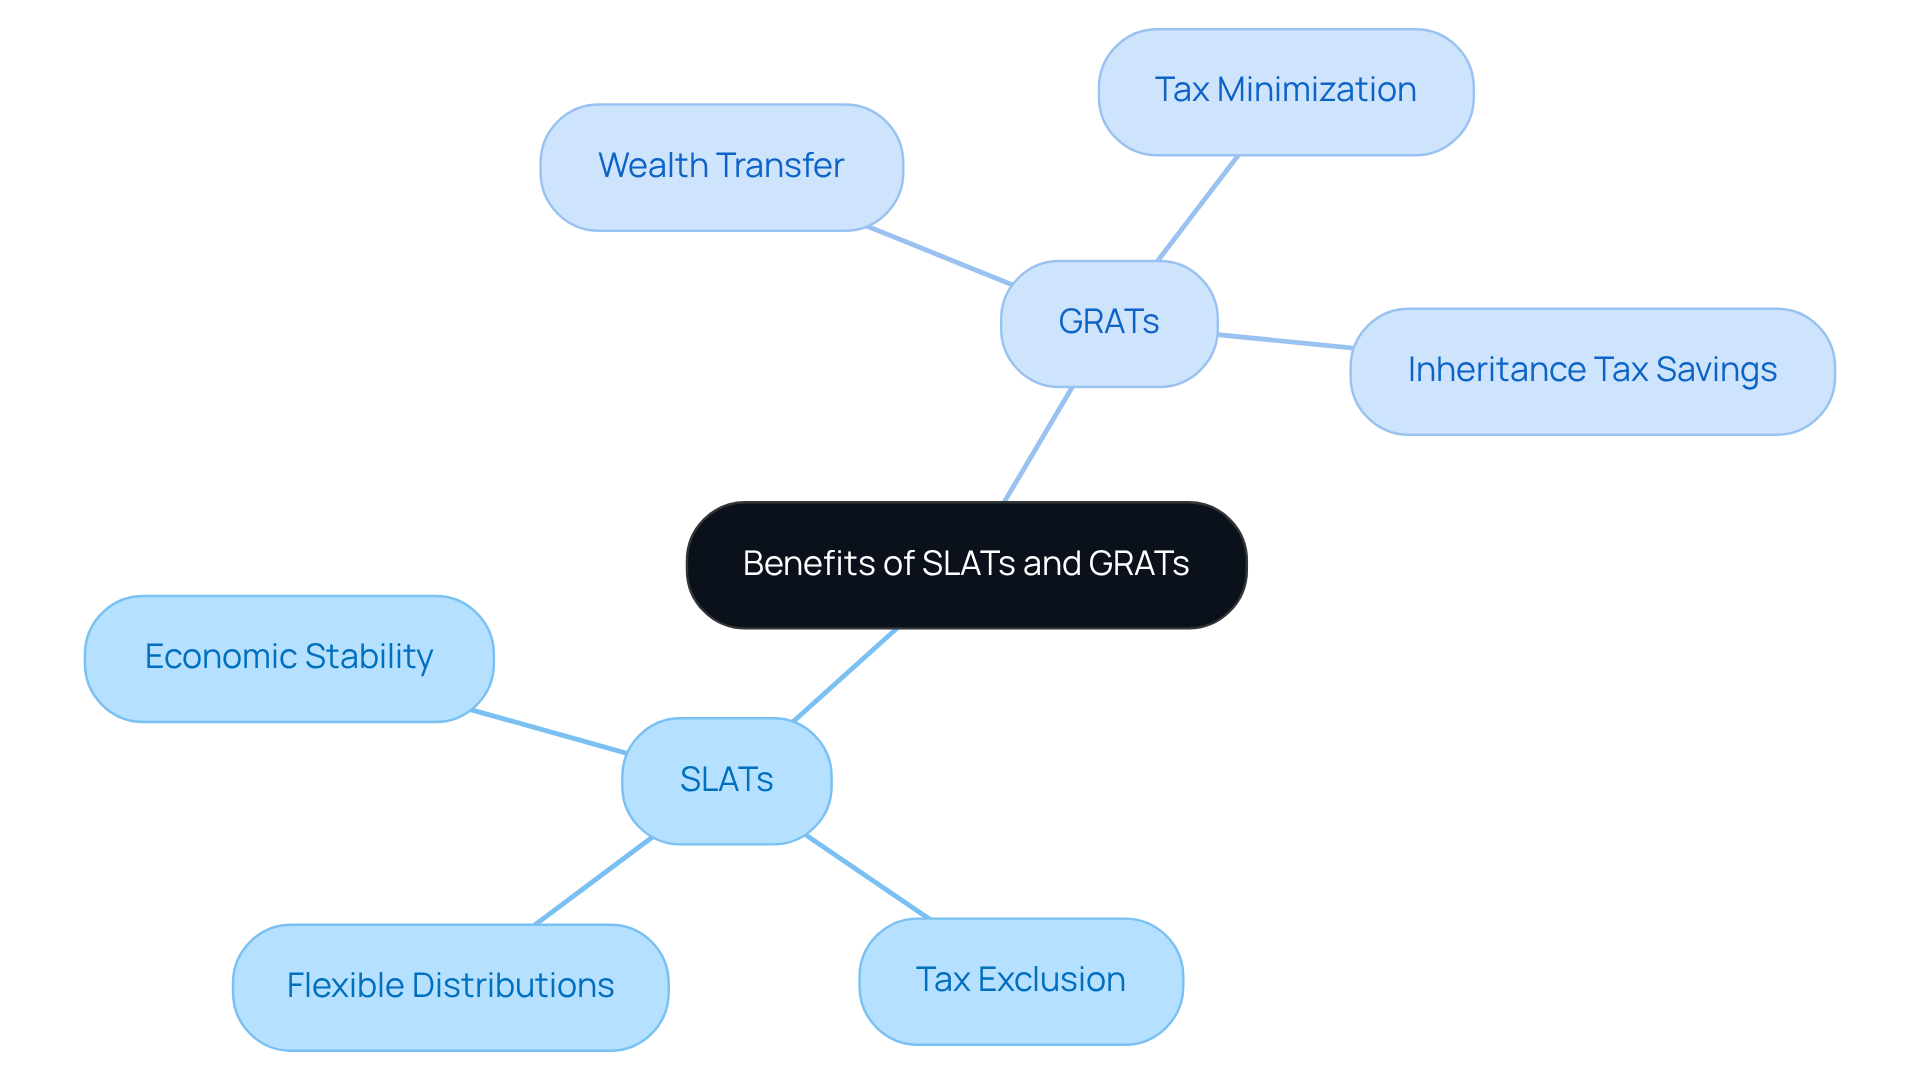
Imagine if you could secure your family’s financial future while navigating the complexities of wealth management. When comparing SLAT vs GRAT, SLATs, or Spousal Lifetime Access Trusts, offer a wonderful way to ensure economic stability for the beneficiary spouse. They efficiently exclude properties from the taxable estate, which can lead to lower estate taxes. This flexibility in distributions is especially beneficial for families facing fluctuating financial situations.
On the other hand, in the discussion of SLAT vs GRAT, GRATs, or Grantor Retained Annuity Trusts, shine when it comes to transferring appreciating properties to heirs with minimal tax implications. By locking in the property’s value at the time of transfer, any increase during the trust term is passed on to your loved ones without tax. This makes GRATs a powerful tool for wealth transfer, particularly for high-net-worth families.
For instance, families utilizing GRATs can significantly reduce gift taxes. There are many cases where large assets were transferred without incurring tax, resulting in substantial inheritance tax savings. As we approach 2025, the strategic use of GRATs becomes even more crucial. With potential changes to estate tax exemptions looming, it’s vital to act now to .
When considering estate planning options, it’s important to understand the differences between SLAT vs GRAT, as both offer unique benefits tailored to meet the specific needs of families like yours. Together, we can navigate this journey and ensure that your financial legacy is secure for generations to come. Remember, we’re here for you every step of the way.
Drawbacks of SLATs and GRATs: Identifying Risks and Limitations
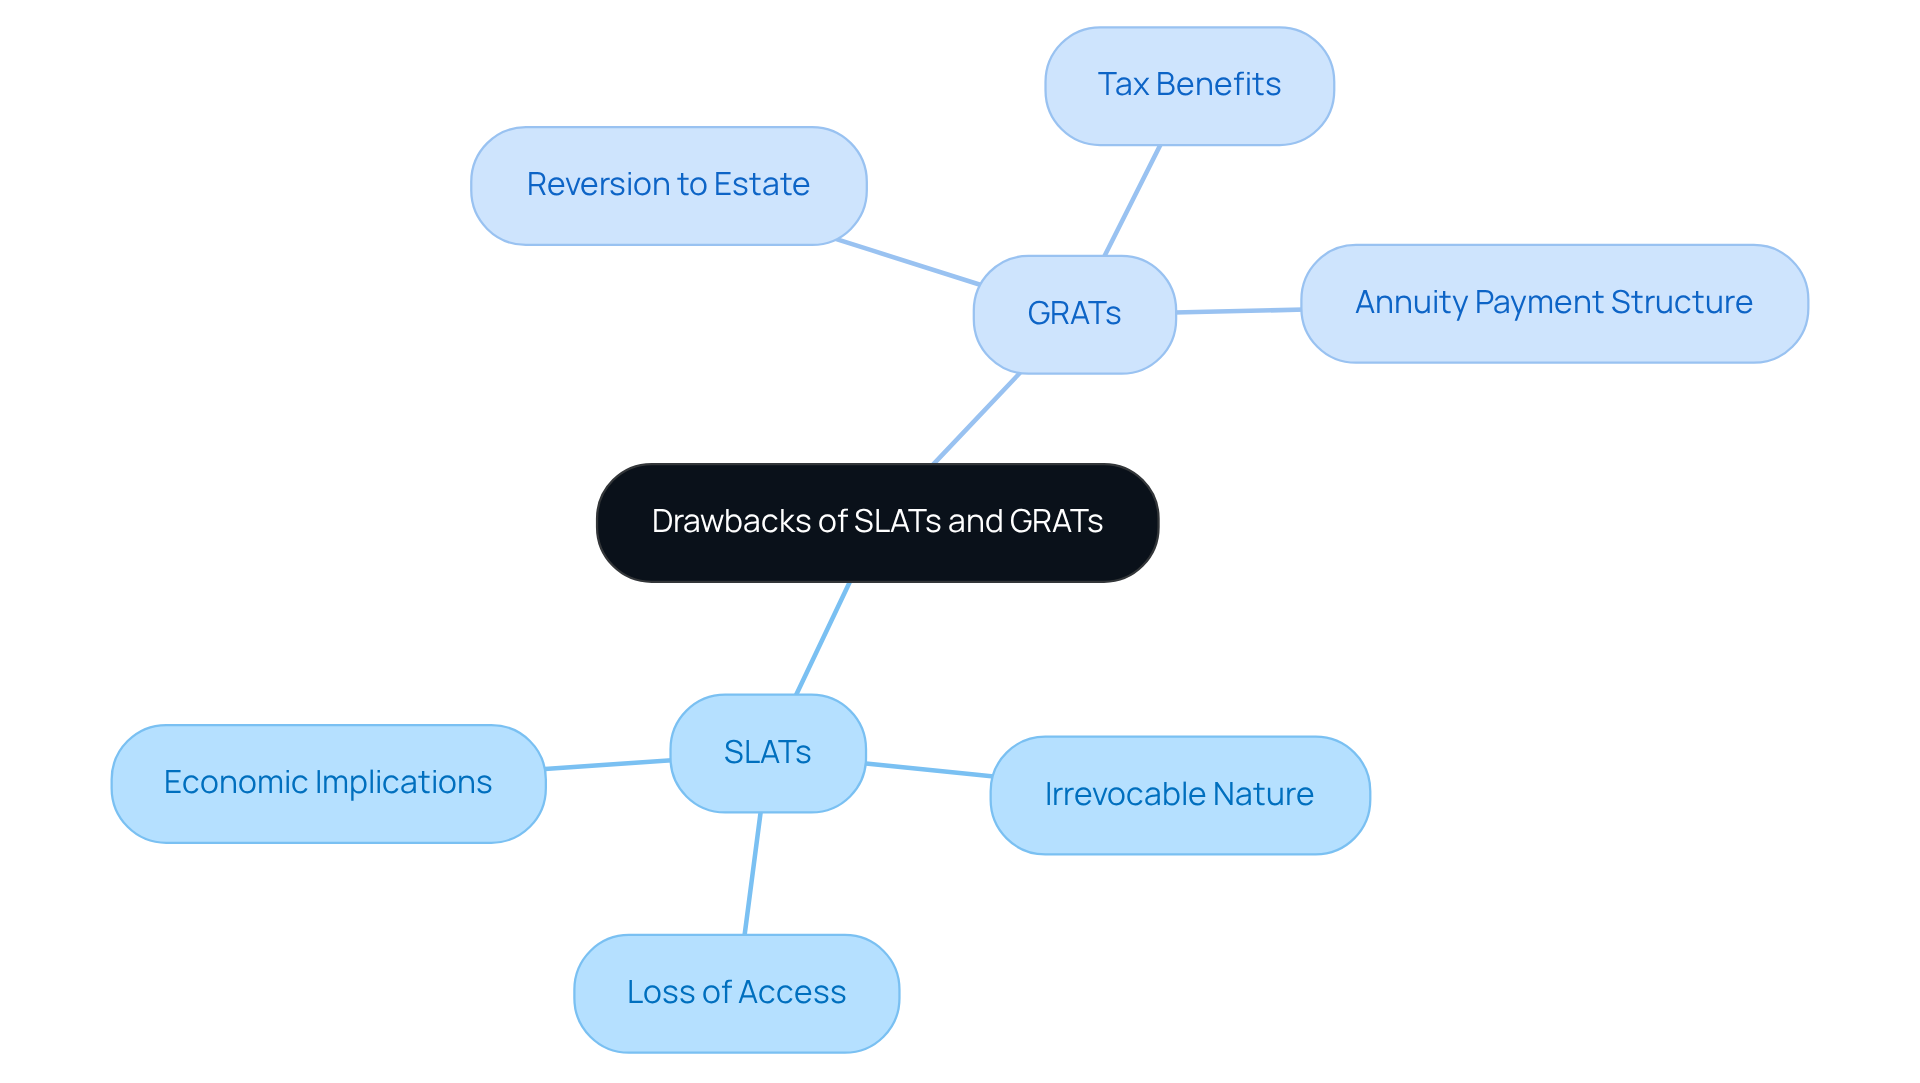
Navigating financial planning can feel overwhelming, especially for young parents. When considering SLAT vs GRAT, it’s important to note that SLATs, or , offer a way for the beneficiary spouse to access trust resources, but they also come with their own set of challenges. Imagine the worry that arises when you consider the irrevocable nature of these trusts. Once property is transferred, it’s locked in, and if the beneficiary partner were to pass away, the surviving partner might lose access to those vital resources entirely.
It’s crucial to think about the economic implications of these trusts, especially with the current lifetime gift exemption standing at $13.61 million per individual. This is a significant amount, but it’s essential to approach it with caution and care.
On the flip side, when considering SLAT vs GRAT, GRATs, or Grantor Retained Annuity Trusts, are designed for tax efficiency, yet they also have limitations. Picture this: if the grantor passes away before the trust period concludes, the assets could revert back to the grantor’s estate, potentially negating the tax benefits you hoped to achieve. Plus, GRATs require careful planning to ensure that annuity payments are structured correctly. If not, you could face unexpected tax complications.
As financial specialists often emphasize, consulting with asset planning professionals about SLAT vs GRAT is vital. They can help you navigate the complexities of both SLATs and GRATs, especially with the impending decrease in tax exemptions set for 2026. Remember, you don’t have to face these challenges alone. Seeking expert guidance can help you avoid potential pitfalls and ensure your family’s financial future is secure.
Together, we can navigate this journey, ensuring that your family’s values and goals are at the forefront of your financial planning.
Suitability of SLATs vs GRATs: Choosing the Right Strategy for Your Family
Choosing between a slat vs grat can be overwhelming, especially when you’re trying to do what’s best for your family. It’s important to consider factors like your family’s unique situation, your financial goals, and how much access you want to have to trust resources.
Imagine wanting to provide immediate financial support to your partner while also being mindful of inheritance taxes. In this case, a SLAT might be the right fit for you. On the other hand, if your focus is on transferring wealth efficiently and minimizing tax liabilities on assets that are likely to grow, you may want to consider the differences between slat vs grat to determine which is more suitable.
It’s essential to remember that you don’t have to navigate this journey alone. Consulting with a financial planner can help you evaluate your specific circumstances and find the best strategy for your estate planning needs. Together, we can ensure that your is secure and aligned with your values.

Conclusion
Understanding the nuances between Spousal Lifetime Access Trusts (SLATs) and Grantor Retained Annuity Trusts (GRATs) is essential for families like yours, who are striving to secure a bright financial future. These estate planning strategies offer unique advantages tailored to your needs, whether you’re prioritizing spousal access or looking to minimize tax liabilities. By grasping these differences, you can make informed decisions that align with your family’s financial goals and legacy planning.
Let’s explore the key features and benefits of both SLATs and GRATs. SLATs provide vital access to funds for a beneficiary spouse, ensuring economic stability while also reducing estate taxes. On the other hand, GRATs shine when it comes to transferring appreciating assets to heirs with minimal tax implications. As families face potential changes in tax legislation, it’s crucial to explore these strategies to maximize financial benefits and protect your family’s legacy.
Ultimately, the choice between SLAT and GRAT should be guided by your family’s unique circumstances and financial objectives. Consulting with a financial planner can offer valuable insights and help you navigate the complexities of estate planning. By taking proactive steps now, you can secure your financial future, ensuring that your values and goals are preserved for generations to come. Remember, we’re here for you, and together, we can navigate this journey.
Frequently Asked Questions
What is a Spousal Lifetime Access Trust (SLAT)?
A SLAT is an irrevocable trust set up by one spouse for the benefit of the other spouse and potentially their children, allowing access to trust resources during their lifetime while keeping those resources out of the grantor’s taxable holdings.
How does a SLAT benefit families?
A SLAT provides peace of mind by ensuring that loved ones can access trust resources when needed, while also helping to save on future estate levies.
What is a Grantor Retained Annuity Trust (GRAT)?
A GRAT is an irrevocable trust designed to reduce gift levies, where the grantor receives annuity payments for a specified duration, and any remaining assets are transferred to beneficiaries after this period.
What are the primary differences between SLAT and GRAT?
SLATs prioritize spousal access and financial security, while GRATs focus on tax efficiency and wealth transfer, allowing assets to grow without incurring additional gift taxes.
Why is understanding SLAT vs GRAT important for families?
Understanding the differences between SLAT and GRAT is essential for effective legacy planning, empowering families to make informed financial choices that align with their objectives.
What challenges do high-income families face regarding financial planning?
High-income families may not fully recognize the financial opportunities available to them due to insufficient tax planning, which can lead to missed benefits.
What should families consider with potential changes in tax legislation?
Families should act quickly to explore wealth planning strategies, especially with proposals to lower the federal gift and inheritance tax exemption, as this could significantly impact their financial planning.
List of Sources
- Understanding SLAT and GRAT: Definitions and Key Features
- Benefits of a Spousal Lifetime Access Trust (SLAT) (https://carrellblanton.com/benefits-of-a-spousal-lifetime-access-trust-slat)
- Estate Planning & Tax Law Constantly Evolve | How to Execute An Estate Plan (https://satovsky.com/2020/10/21/estate-tax-law-is-constantly-evolving-and-unpredictable)
- SLATs: An Estate-Planning Strategy for Couples (https://schwab.com/learn/story/slat-trusts-estate-planning-strategy-couples)
- The Listen to Lawrence Letter – Pros and Cons of SLATs – Davidow, Davidow, Siegel & Stern, LLP (https://davidowlaw.com/listen-lawrence-letter-pros-cons-slats)
- The Estate and Gift Tax: An Overview (https://congress.gov/crs-product/R48183)
- Benefits of SLATs and GRATs: Evaluating Advantages for Families
- Benefits of a Spousal Lifetime Access Trust (SLAT) (https://carrellblanton.com/benefits-of-a-spousal-lifetime-access-trust-slat)
- Understanding Grantor Retained Annuity Trust (GRAT) (https://westernsouthern.com/retirement/grantor-retained-annuity-trust)
- How A Grantor Retained Annuity Trust (GRAT) Can Save You Millions In Estate Taxes (https://financialsamurai.com/grantor-retained-annuity-trust-grat)
- SLATs: A Marriage of Tax Benefits and Flexibility (https://marinerwealthadvisors.com/insights/slats-a-marriage-of-tax-benefits-and-flexibility)
- Spousal Lifetime Access Trusts (SLATs): Benefits, Risks, and How They Work – Sterlington PLLC (https://sterlingtonlaw.com/spousal-lifetime-access-trusts-slat-benefits-risks)
- Drawbacks of SLATs and GRATs: Identifying Risks and Limitations
- 99 Quotes About Risk to Inspire You to Great Things (https://riskology.co/99-risk-quotes)
- Best Inspirational Quotes | 50 Quotes On Taking Risks (https://carenmerrick.com/50-of-the-best-inspirational-quotes-on-taking-risks)
- SLAT Trusts: Risky or Rewarding? 7 Things to Be Aware Of… (https://ironpointfin.com/slat-trusts-risky-or-rewarding-7-things-to-know)
- Is a SLAT Trust Right for You? Benefits, Risks, and How They Work | SC&H (https://schgroup.com/insights/blog/investment-banking/slat-trust-benefits-risks-and-how-they-work)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading