

Key Highlights
- Understanding business structures is crucial for families to minimise tax burdens during company stock sales.
- Common structures include Sole Proprietorship, Partnership, LLC, S-Corporation, and C-Corporation, each with distinct tax implications.
- Sole Proprietorships and Partnerships face higher personal tax rates, while LLCs offer flexible taxation options.
- S-Corporations avoid double taxation but have shareholder limits, whereas C-Corporations are subject to double taxation.
- Strategies for minimising tax liability include timing the sale, tax-loss harvesting, instalment sales, gifting shares, and utilising tax-advantaged accounts.
- Choosing the right sale structure, such as stock sales over asset sales, can help avoid double taxation.
- Utilising 1031 exchanges and investing in Qualified Opportunity Zones can defer capital gains taxes.
- Post-sale financial management should focus on reassessing wealth goals, investment strategies, tax planning, estate planning, family conversations, and budgeting.
- Bright Advisers provides expertise in navigating tax complexities and ensuring families make informed financial decisions.
Introduction
Imagine feeling overwhelmed by the complexities of company stock sales and the looming tax implications that come with them. It’s important to understand how different business structures can impact your family’s tax situation, especially when you’re trying to keep more of what you’ve earned. But with so many strategies out there, how can you and your family plan for a successful stock sale while keeping your hard-earned wealth intact?
In this article, we’ll explore some smart strategies for planning your company stock sale, helping you make informed decisions that can empower your family’s financial future.
Identify Business Structures and Their Tax Implications
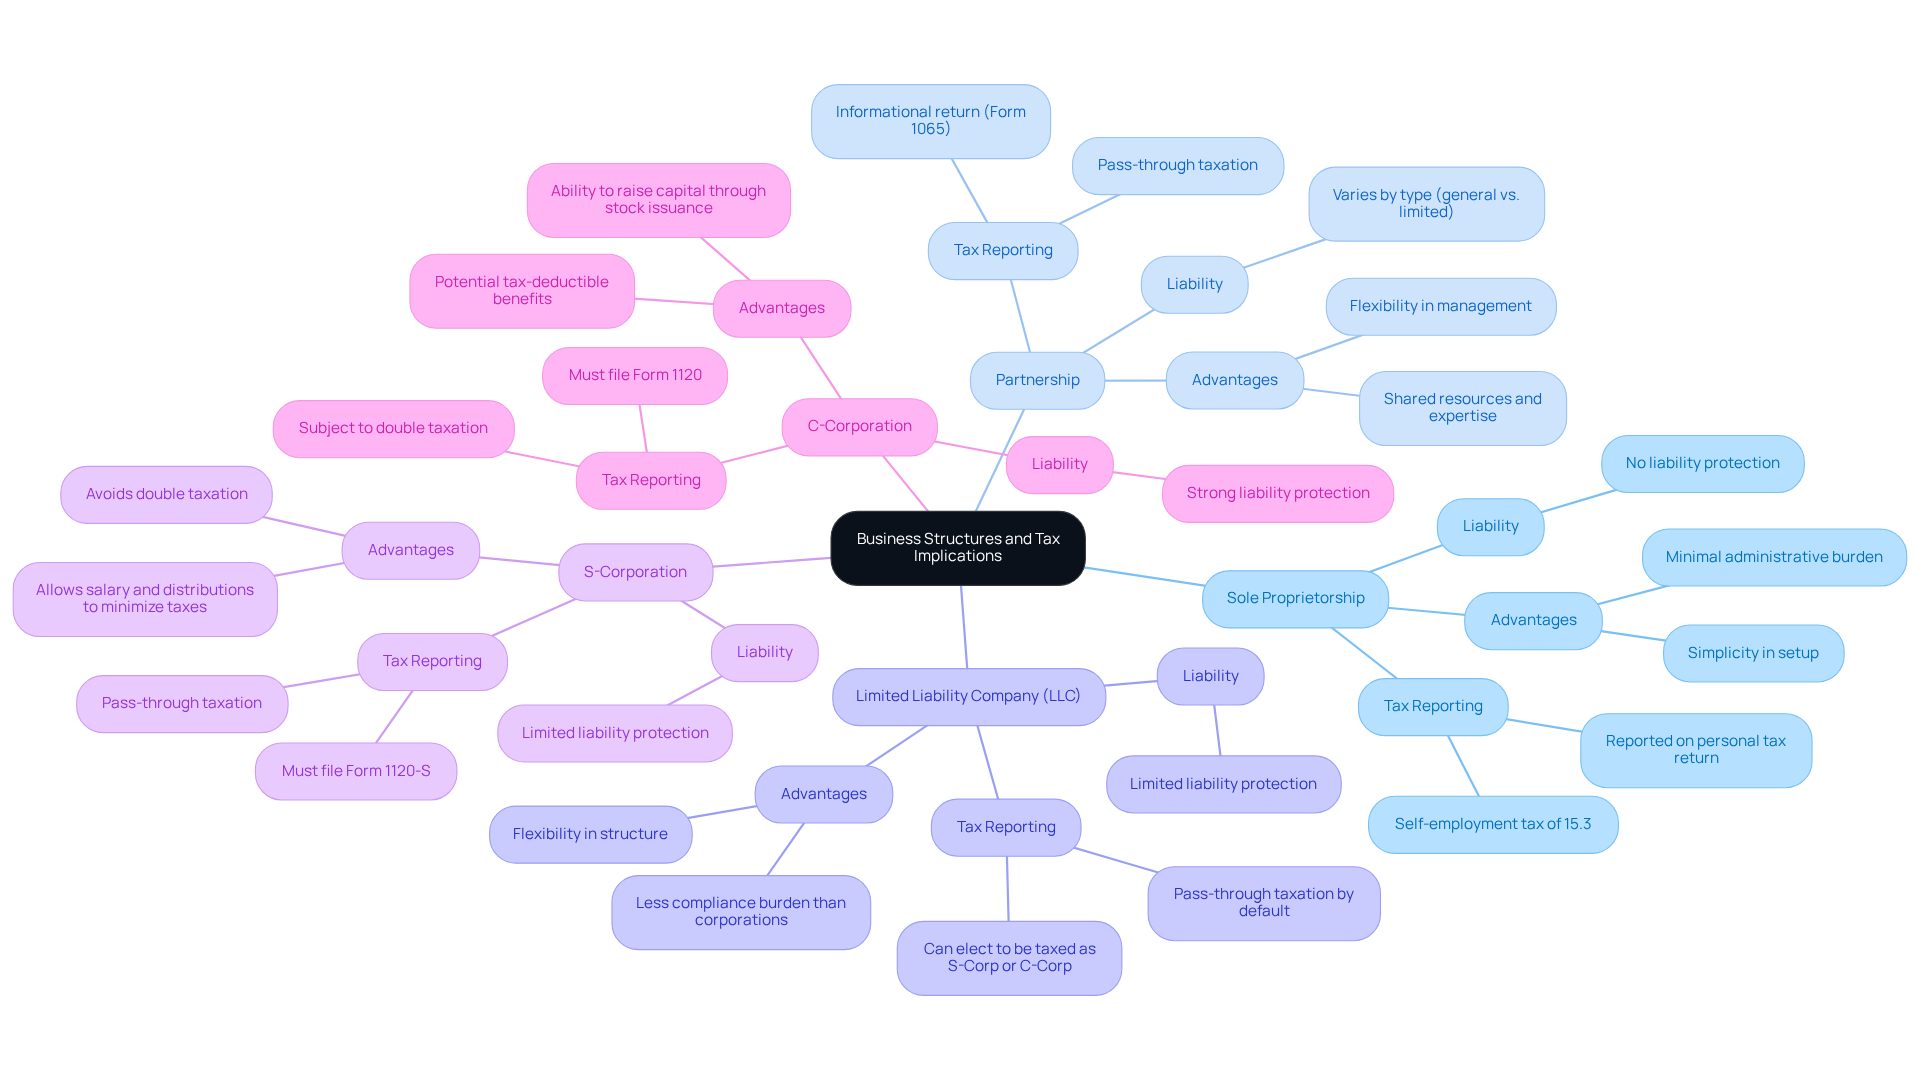
Imagine facing a major financial decision, only to realize that the structure of your business could impact your family’s future. Understanding these structures can assist families in their company stock sale tax planning, potentially reducing their tax burden when selling. Here are the common structures:
- Sole Proprietorship: Income is reported on the owner’s personal tax return, which can lead to higher tax rates on profits, often reaching up to 37% for high earners.
- Partnership: Similar to sole proprietorships, profits pass through to partners and are taxed at their individual rates, which can also be substantial depending on personal income levels.
- Limited Liability Company (LLC): This structure offers flexibility in taxation; it can be taxed as a sole proprietorship, partnership, or corporation, depending on the number of members and elections made.
- S-Corporation: Profits pass through to shareholders, avoiding double taxation, but this structure has restrictions on the number of shareholders (limited to 100) and requires compliance with specific IRS regulations.
- C-Corporation: Subject to double taxation, profits are taxed at the corporate level and again at the shareholder level when dividends are distributed, which can significantly increase the overall tax burden.
Navigating the complexities of tax obligations can feel overwhelming, especially when you’re trying to secure your family’s future. Without the right guidance, families might miss out on opportunities to save money and invest in their children’s future. For instance, S-Corporations can provide significant tax savings by allowing owners to split income into salary and distributions, minimizing self-employment taxes. In contrast, C-Corporations may be less favorable for small businesses due to the double taxation issue, making S-Corps a more attractive option for many family-owned businesses.
Just like many families, Jay & Emma turned to Bright Advisers for help in easing their financial worries while preparing for their children’s education and retirement. By establishing a comprehensive budget and selecting investment strategies focused on diversification, they balanced growth potential and risk management. Likewise, Emily and Mark, who sought economic independence, gained from a comprehensive evaluation of their monetary circumstances, enabling them to make knowledgeable choices regarding their asset sales and tax consequences.
Moreover, households ought to recognize that the highest federal income tax rate on long-term capital gains and dividends is 20%, which is pertinent when engaging in company stock sale tax planning. With the right support, you can turn these challenges into opportunities for your family’s financial growth. By utilizing Bright Advisers’ expertise in tax planning, households can navigate these complexities and secure their financial futures.
Plan Ahead to Minimize Tax Liability Before the Sale
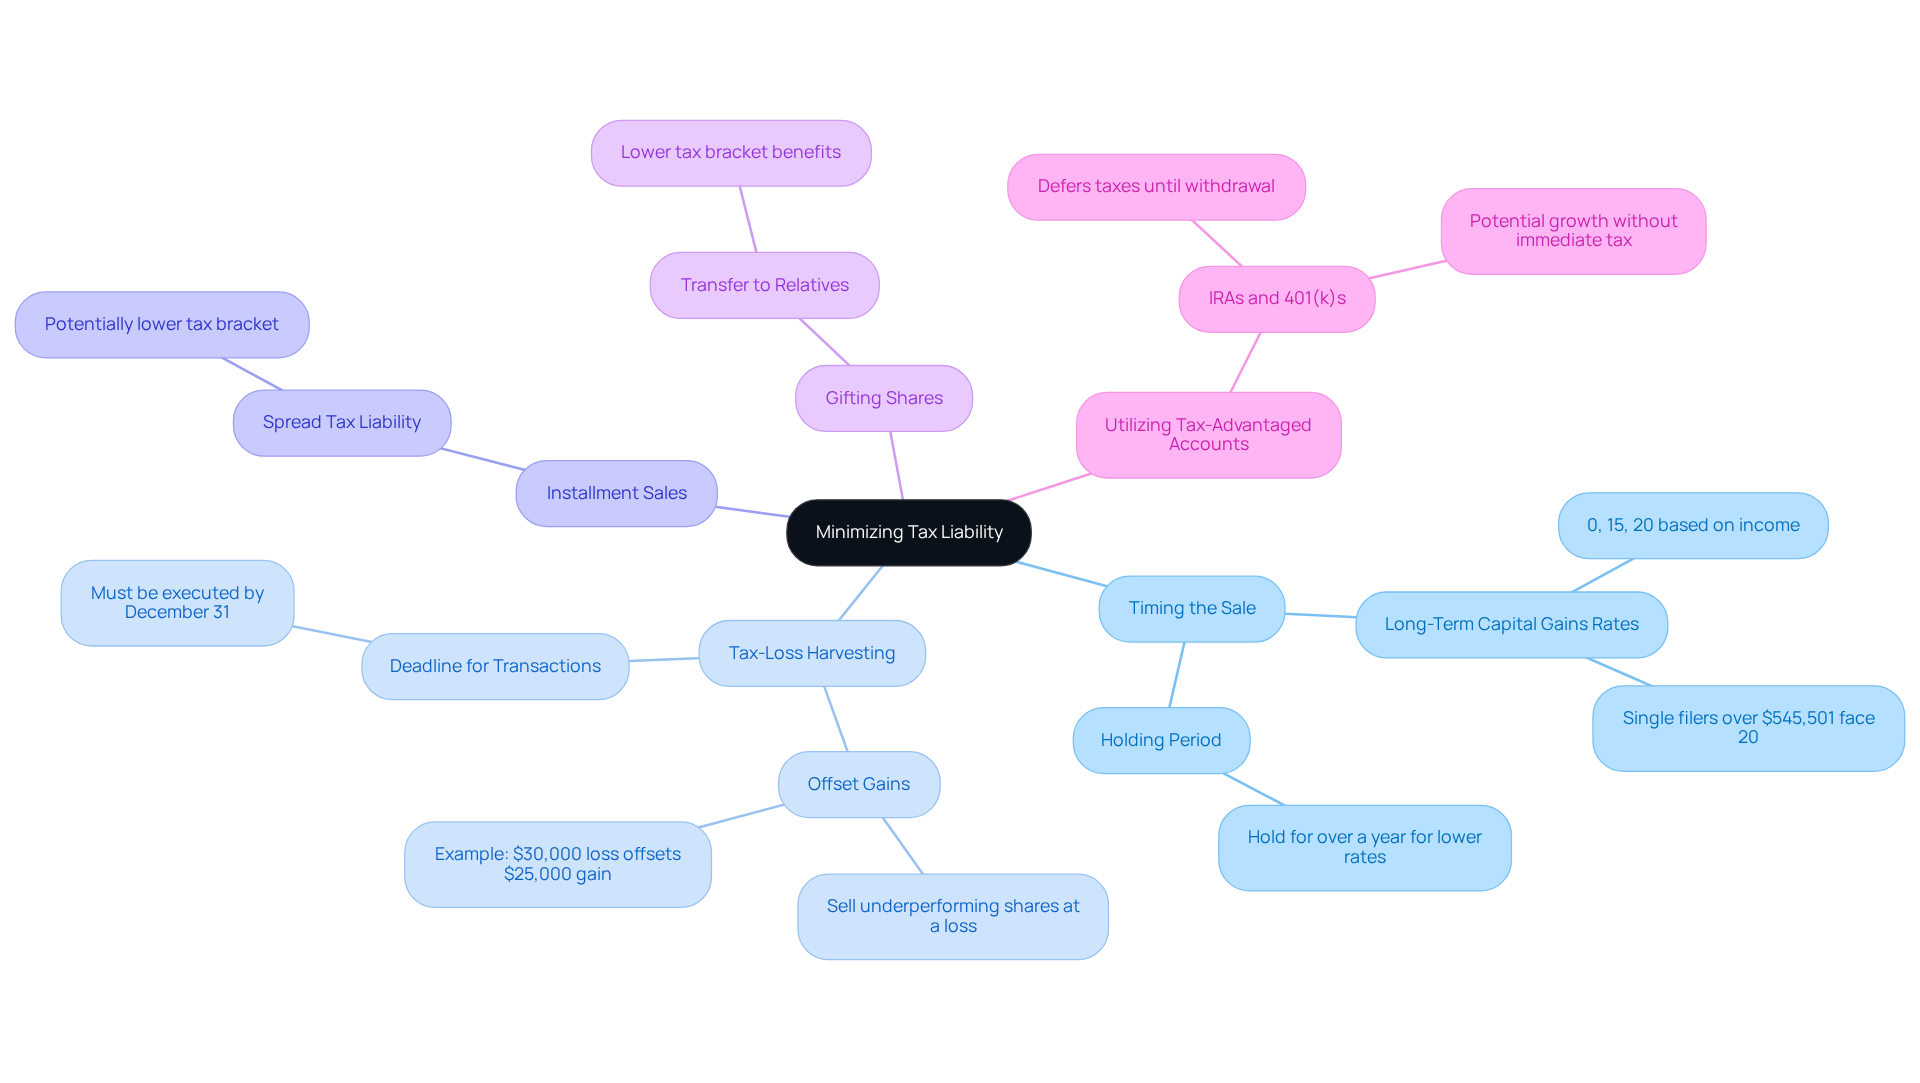
Imagine the relief of knowing you can keep more of your hard-earned money through effective company stock sale tax planning when selling company stock. For families like Allison and Brian, minimizing tax liability is crucial, and there are several strategies to consider.
- Timing the Sale: Holding onto shares for over a year can qualify you for lower long-term capital gains tax rates. These rates can be significantly less than short-term rates. For 2026, the long-term capital gains tax rates are 0%, 15%, or 20%, depending on your income. For example, single filers with income over $545,501 will face a 20% rate, while those earning between $49,451 and $545,500 will be taxed at 15%.
- Tax-Loss Harvesting: This approach allows you to offset gains by selling underperforming shares at a loss. If a household sells a stock at a loss of $30,000 and realizes a gain of $25,000 from another investment, those losses can offset the gains, resulting in no capital gains taxes owed. Just remember, these transactions need to be executed and settled by December 31 to be effective. This method is especially important for families wanting to make the most of their financial resources.
- Installment Sales: Structuring the sale as an installment sale can help spread the tax liability over several years, potentially keeping your family in a lower tax bracket.
- Gifting Shares: Transferring shares to relatives in lower tax brackets can lighten the overall tax burden. This strategy can be particularly effective if the recipient is in a significantly lower tax bracket, allowing for more favorable tax treatment on the gains.
- Utilizing Tax-Advantaged Accounts: Selling stocks within tax-advantaged accounts like IRAs can defer taxes until withdrawal, allowing for potential growth without immediate tax implications. This approach is beneficial for families looking to manage their investments while reducing tax obligations.
By embracing these strategies, families can ease their tax burdens and hold onto more of what they’ve worked so hard to build, ensuring a more secure economic future. Without proper tax planning, families like Allison and Brian might miss out on valuable savings that could make a real difference. Bright Advisers is here for you, ready to assist families in navigating these complexities and making wise wealth decisions that preserve assets across generations.
Disclaimer: Past performance does not guarantee future results. Securities investments are subject to risk. Advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Implement Tax-Advantaged Strategies During the Sale
Imagine facing the sale of your family business and feeling uncertain about how to minimize your tax burden with company stock sale tax planning – you’re not alone in this journey. Many families struggle to navigate the complexities of company stock sale tax planning, often feeling overwhelmed by the available options. But there are several tax-advantaged strategies, such as company stock sale tax planning, that can help you ease this burden and secure your family’s financial future.
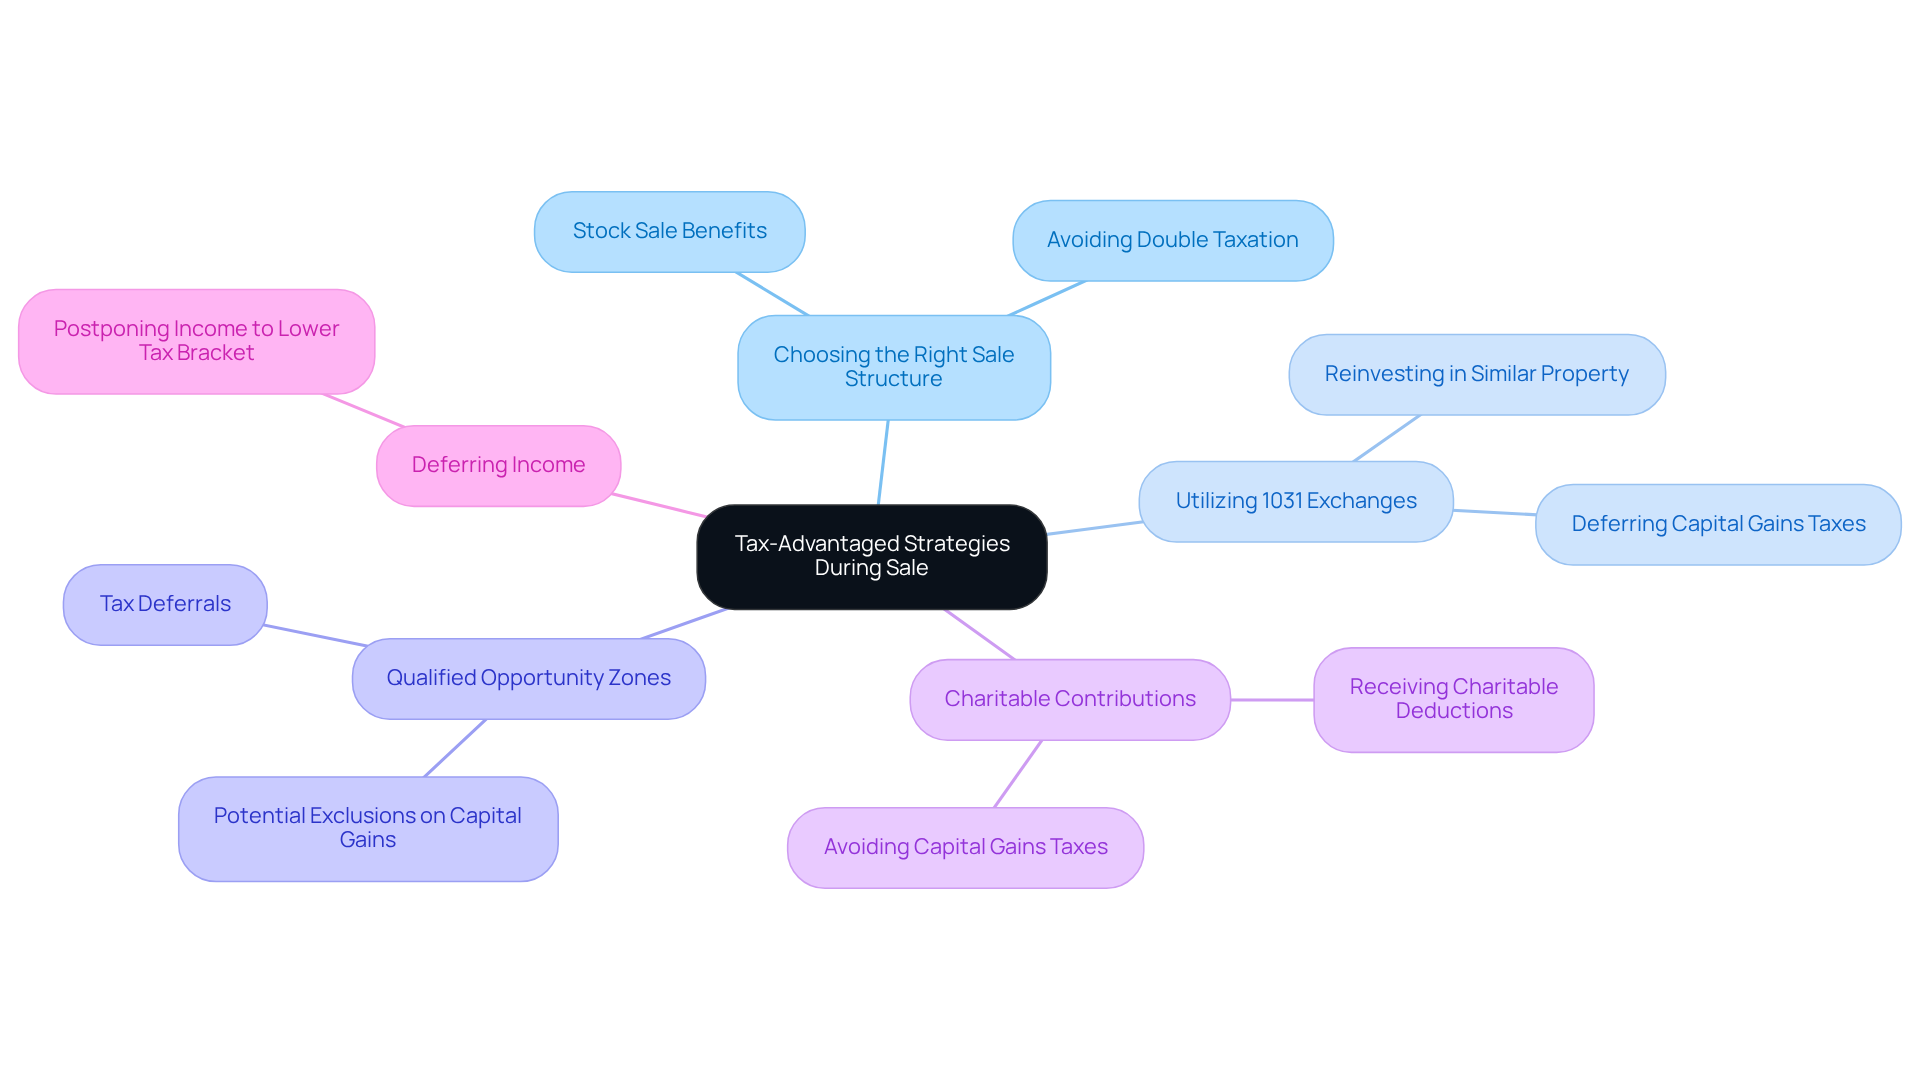
- Choosing the Right Sale Structure: Opting for a stock sale over an asset sale can be a smart move. This choice often helps with company stock sale tax planning to avoid double taxation, as sellers typically face lower capital gains levies compared to the standard income levies associated with asset sales.
- Utilizing 1031 Exchanges: If it fits your situation, consider a 1031 exchange. This allows you to defer capital gains taxes by reinvesting the proceeds into similar property, helping you maintain your investment potential while postponing tax obligations.
- Qualified Opportunity Zones: Investing in Qualified Opportunity Zones can be a strategic option for families looking to grow their wealth. This approach offers tax deferrals and potential exclusions on capital gains, making it a win-win for your financial goals.
- Charitable Contributions: Donating appreciated stock to charity not only helps those in need but can also enable you to avoid capital gains taxes while receiving a charitable deduction. This can effectively reduce your overall tax burden, allowing you to give back while benefiting your family.
- Deferring Income: If possible, consider postponing income from the sale to a future tax year when you might be in a lower tax bracket. This simple step can help minimize the tax impact on your family.
By implementing these strategies, families can not only reduce their tax burden but also secure a brighter financial future for their loved ones. It’s important to understand the consequences of equity versus asset sales in terms of company stock sale tax planning, as asset sales may lead to increased taxes for sellers, while equity sales often qualify for capital gains rates. Consulting with experts at Bright Advisers is essential; they can help you with company stock sale tax planning and navigate the complexities of capital gains taxation to enhance the effectiveness of these strategies. Through their collaboration with Bright Advisers, families like Allison and Brian not only optimized their tax situation but also secured their children’s future through education funding and gained the ability to retire sooner. With the right guidance, you can turn potential tax challenges into opportunities for your family’s future, ensuring a legacy of financial security and growth.
Address Post-Sale Financial Management and Planning
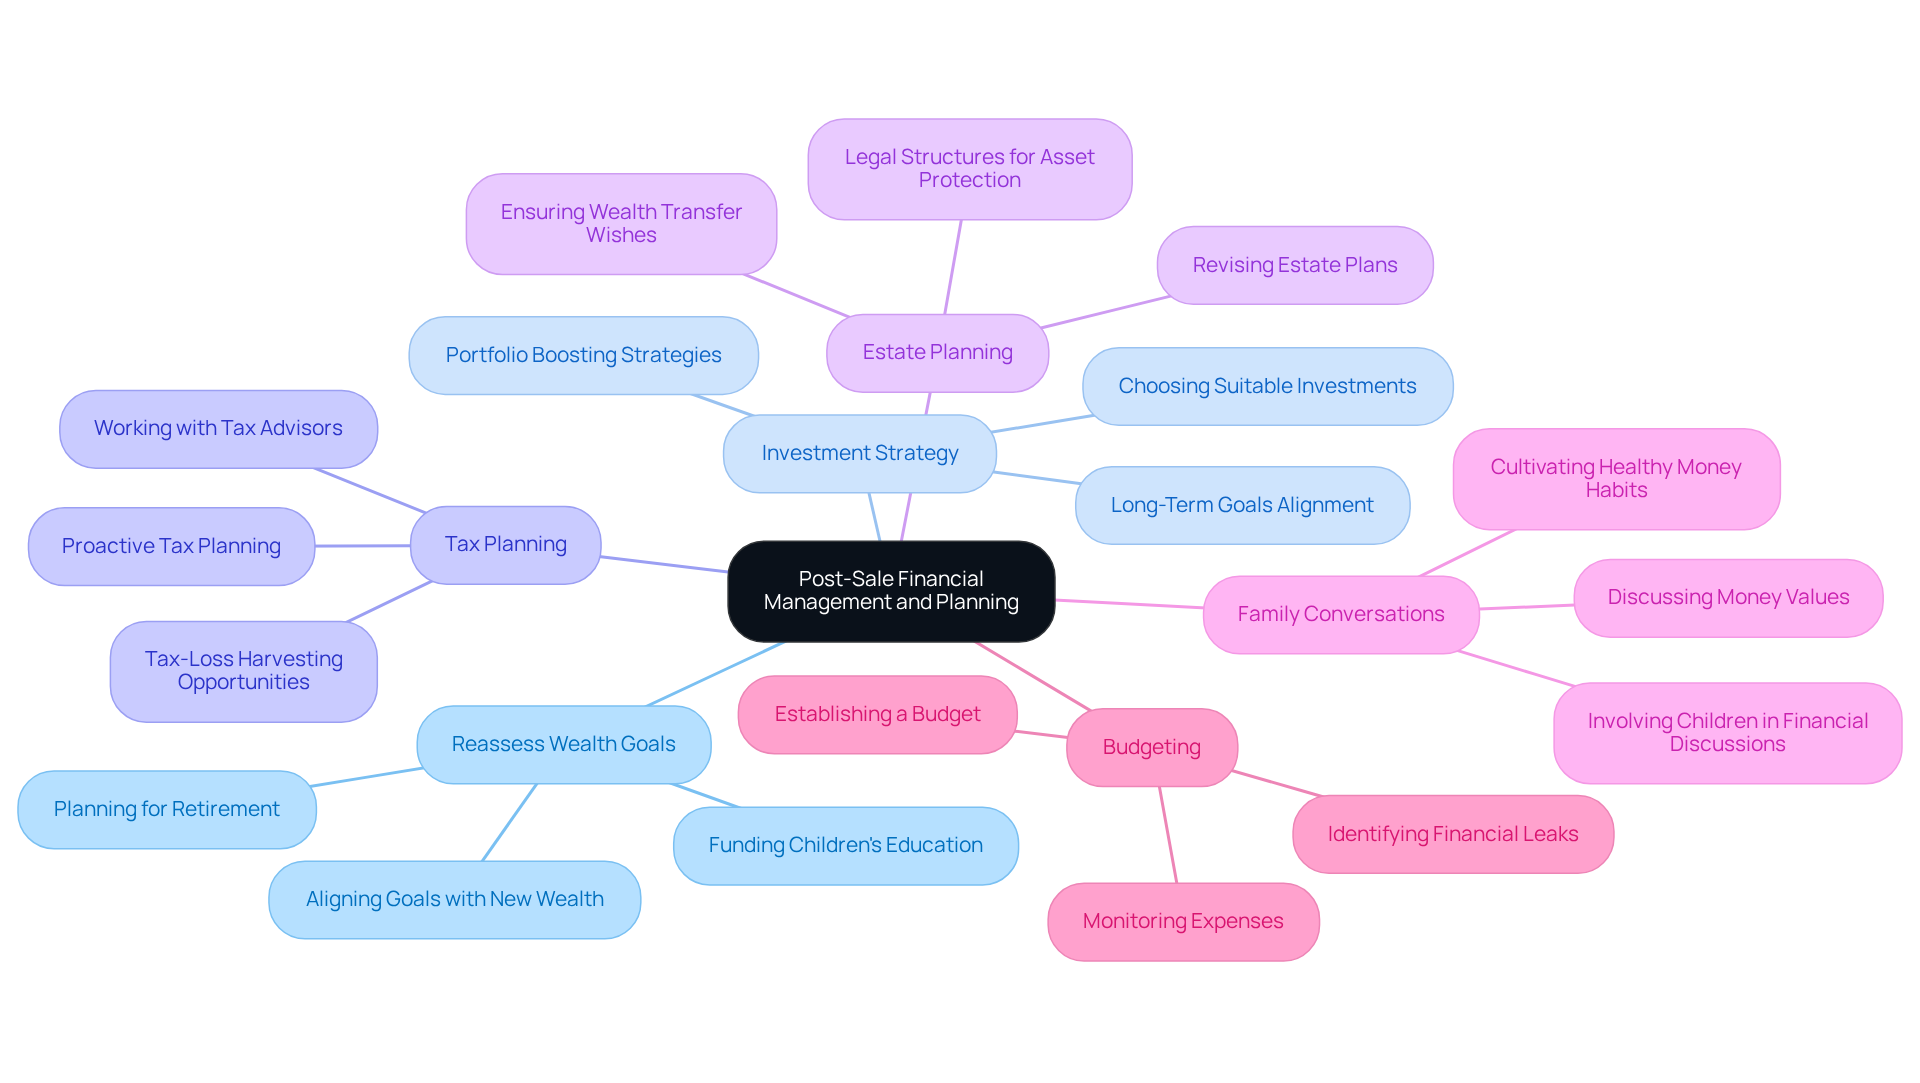
Imagine the possibilities that come with newfound wealth, but also the challenges of managing it wisely. After selling company stock, families should prioritize effective financial management to secure their financial future:
- Reassess Wealth Goals: This means looking closely at how to fund your children’s education and plan for retirement, making sure your family’s financial goals fit your new situation. With a projected $124 trillion wealth transfer expected in the United States through 2048, reassessing these goals is more important than ever.
- Investment Strategy: It’s important for families to choose investments that match their comfort level and long-term goals, and we can help you find the right strategies to boost your portfolio. Experts agree that a thoughtful investment strategy can really make a difference in building your family’s wealth over time.
- Tax Planning: Working closely with a tax advisor can really help families navigate their tax responsibilities with ease. Families should explore opportunities for tax-loss harvesting in future investments to mitigate tax impacts. According to a recent survey, 60% of wealth management offices anticipate market growth, making proactive company stock sale tax planning even more critical. Bright Advisers specializes in company stock sale tax planning strategies that can assist households in navigating these complexities.
- Estate Planning: Revising estate plans to reflect the new economic situation is essential. This ensures that wealth is passed on according to the wishes of the household and that all legal structures are in place to protect assets. As Benjamin Franklin wisely stated, “An investment in knowledge pays the best interest,” emphasizing the importance of understanding estate planning.
- Family Conversations: Meetings with relatives to discuss money values and objectives promotes literacy among children. This prepares them for future wealth management and instills a sense of responsibility regarding family finances. Involving children in these conversations can assist them in cultivating healthy money habits early on.
- Budgeting: Establishing a budget is crucial for monitoring expenses and preparing for future monetary objectives. As emphasized in various studies, budgeting assists individuals in identifying and removing small monetary leaks that can accumulate over time. Bright Advisers provides extensive budgeting services that can help households in maintaining monetary discipline.
By concentrating on these areas, families can effectively manage their wealth and ensure a secure economic future. By taking these steps, families can not only secure their financial future but also create a legacy of financial wisdom for generations to come.
Conclusion
Imagine the worry of not knowing how to navigate tax implications after a stock sale, feeling uncertain about your family’s financial future. By understanding how different business structures affect taxes, families can find ways to ease their financial burdens and protect their wealth. With the caring guidance of Bright Advisers, families can confidently make choices that support their dreams for the future.
Key strategies discussed include:
- Timing the sale of stocks
- Utilizing tax-loss harvesting
- Considering installment sales or gifting shares to minimize tax liabilities
Additionally, tax-advantaged strategies such as 1031 exchanges and charitable contributions can further optimize financial outcomes. Families like Allison and Brian have successfully navigated these challenges with the support of Bright Advisers, ensuring they retain more of their hard-earned wealth.
Ultimately, proactive financial management post-sale is crucial. By reassessing wealth goals, refining investment strategies, and engaging in open family discussions about money, families can cultivate a legacy of financial literacy and responsibility. By taking these steps, families can turn potential tax challenges into opportunities for lasting financial success, ensuring a brighter future for generations to come.
Frequently Asked Questions
What are the common business structures and their tax implications?
The common business structures include: – Sole Proprietorship: Income is reported on the owner’s personal tax return, potentially leading to higher tax rates up to 37% for high earners. – Partnership: Profits pass through to partners and are taxed at their individual rates, which can be substantial. – Limited Liability Company (LLC): Offers flexible taxation options, allowing it to be taxed as a sole proprietorship, partnership, or corporation. – S-Corporation: Profits pass through to shareholders, avoiding double taxation, but has restrictions on the number of shareholders (limited to 100) and requires compliance with IRS regulations. – C-Corporation: Subject to double taxation, where profits are taxed at both the corporate level and again at the shareholder level when dividends are distributed.
How can understanding business structures assist in tax planning for families?
Understanding business structures can help families in company stock sale tax planning, potentially reducing their tax burden when selling. For example, S-Corporations can provide tax savings by allowing owners to split income into salary and distributions, minimizing self-employment taxes.
What is the highest federal income tax rate on long-term capital gains and dividends?
The highest federal income tax rate on long-term capital gains and dividends is 20%, which is important for families to consider when planning for company stock sales.
How can Bright Advisers assist families with tax planning?
Bright Advisers can help families navigate the complexities of tax obligations, ensuring they do not miss opportunities to save money and invest in their children’s future. Their expertise in tax planning can turn challenges into opportunities for financial growth.
What are the potential drawbacks of a C-Corporation for small businesses?
C-Corporations may be less favorable for small businesses due to the issue of double taxation, where profits are taxed at both the corporate level and again at the shareholder level when dividends are distributed.
List of Sources
- Identify Business Structures and Their Tax Implications
- Tax Implications of Business Structures: Sole Proprietorships to S Corps (https://investopedia.com/articles/personal-finance/120915/which-type-organization-best-your-business.asp)
- An Overview of Pass-through Businesses in the United States (https://taxfoundation.org/research/all/federal/overview-pass-through-businesses-united-states)
- 5 Common Business Entities and Their Tax Implications – GRF CPAs & Advisors (https://grfcpa.com/resource/5-common-business-entities)
- Sole Prop vs LLC vs S-Corp vs C-Corp: Tax Savings Guide – Fraim, Cawley & Company, CPAs (https://fraimcpa.com/sole-proprietorship-llc-s-corp-c-corp)
- Business Entity Tax Guide: LLC vs S-Corp vs C-Corp vs Partnership | SDO CPA (https://sdocpa.com/business-entity-tax-guide)
- Plan Ahead to Minimize Tax Liability Before the Sale
- Tax-loss harvesting explained | Vanguard (https://investor.vanguard.com/investor-resources-education/taxes/offset-gains-loss-harvesting)
- Capital Gains Tax Rates: Short-term vs. Long-term (https://schwab.com/learn/story/how-are-capital-gains-taxed)
- Capital gains tax: Definition, rates, and ways to save | Fidelity (https://fidelity.com/learning-center/smart-money/capital-gains-tax-rates)
- Continuous tax-loss harvesting yields more potential for tax benefits (https://am.jpmorgan.com/us/en/asset-management/adv/investment-strategies/separately-managed-accounts/tax-managed-solutions/continuous-tax-loss-harvesting-yields-more-potential-for-tax-savings)
- Long-Term Capital Gains Rates for 2026 (https://experian.com/blogs/ask-experian/long-term-capital-gains-tax-rates)
- Implement Tax-Advantaged Strategies During the Sale
- Asset Sale vs. Stock Sale for Businesses (https://53.com/content/fifth-third/en/financial-insights/wealth/business-transition/asset-sale-vs-stock-sale-for-high-net-worth-business-owners.html)
- Tax Implications of Selling Stock vs. Selling Assets (https://wgcpas.com/article/tax-implications-of-selling-stock-vs-selling-assets)
- Defer Capital Gains Taxes with a 1031 Exchange – Asset Preservation, Inc. (https://apiexchange.com/defer-capital-gains-taxes-with-1031-exchange)
- What is a 1031 exchange and how does it work? | Fidelity Investments (https://fidelity.com/learning-center/wealth-management-insights/what-is-a-1031-exchange)
- Address Post-Sale Financial Management and Planning
- Family Office Study 2025: Statistics, Research, and Insights (https://pbig.ml.com/articles/family-office-report.html)
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- Wealth-Building in 2025: Generational Investing Statistics | IPX1031 (https://ipx1031.com/investing-statistics-by-generation)
- Money Talk: 10 Great Quotes About Personal Finance (https://3riversfcu.org/resources/financial-education/detail/money-talk-10-great-quotes-about-personal-finance)
- Preserving generational wealth: Four family office… (https://andsimple.co/insights/preserving-generational-wealth-four-family-office-strategies)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading