

Key Highlights
- Before selling stock, tech employees should develop a tax strategy to maximise financial benefits for their families.
- Understanding your tax bracket and timing stock sales can significantly impact tax obligations.
- Tax-loss harvesting allows investors to offset profits with losses, reducing taxable income.
- Short-term capital gains are taxed at ordinary income rates, while long-term gains benefit from lower tax rates.
- High-income earners may face additional taxes, such as the net investment income tax (NIIT).
- Diversifying investments post-sale can minimise tax burdens and reduce financial risk.
- Tax-advantaged accounts like IRAs and HSAs can enhance savings and lower taxable income.
- 529 plans offer tax-free growth for education expenses, making them a valuable investment for families.
- Real-life examples illustrate how families have successfully navigated tax planning with the help of Bright Advisers.
Introduction
Imagine feeling overwhelmed by the complexities of stock sales and the tax implications that could impact your family’s financial future. A thoughtful tax strategy can help you maximize your returns and minimize liabilities, especially if you have equity compensation. We’re here to help you navigate this.
Yet, many families may not realize the simple steps they can take to improve their tax situation before selling stock. How can you make informed decisions that not only protect your wealth but also ensure your family’s financial well-being? Together, we can navigate these challenges and ensure your family’s financial well-being is secure.
Establish a Comprehensive Tax Strategy Before Selling Stock
Imagine the worry of not knowing how to maximize your hard-earned money for your family’s future. Before you consider selling your stock, particularly as a tech employee with equity compensation, it’s important to discuss large stock sale tax planning for tech employees to develop a tax strategy that benefits you and your family.
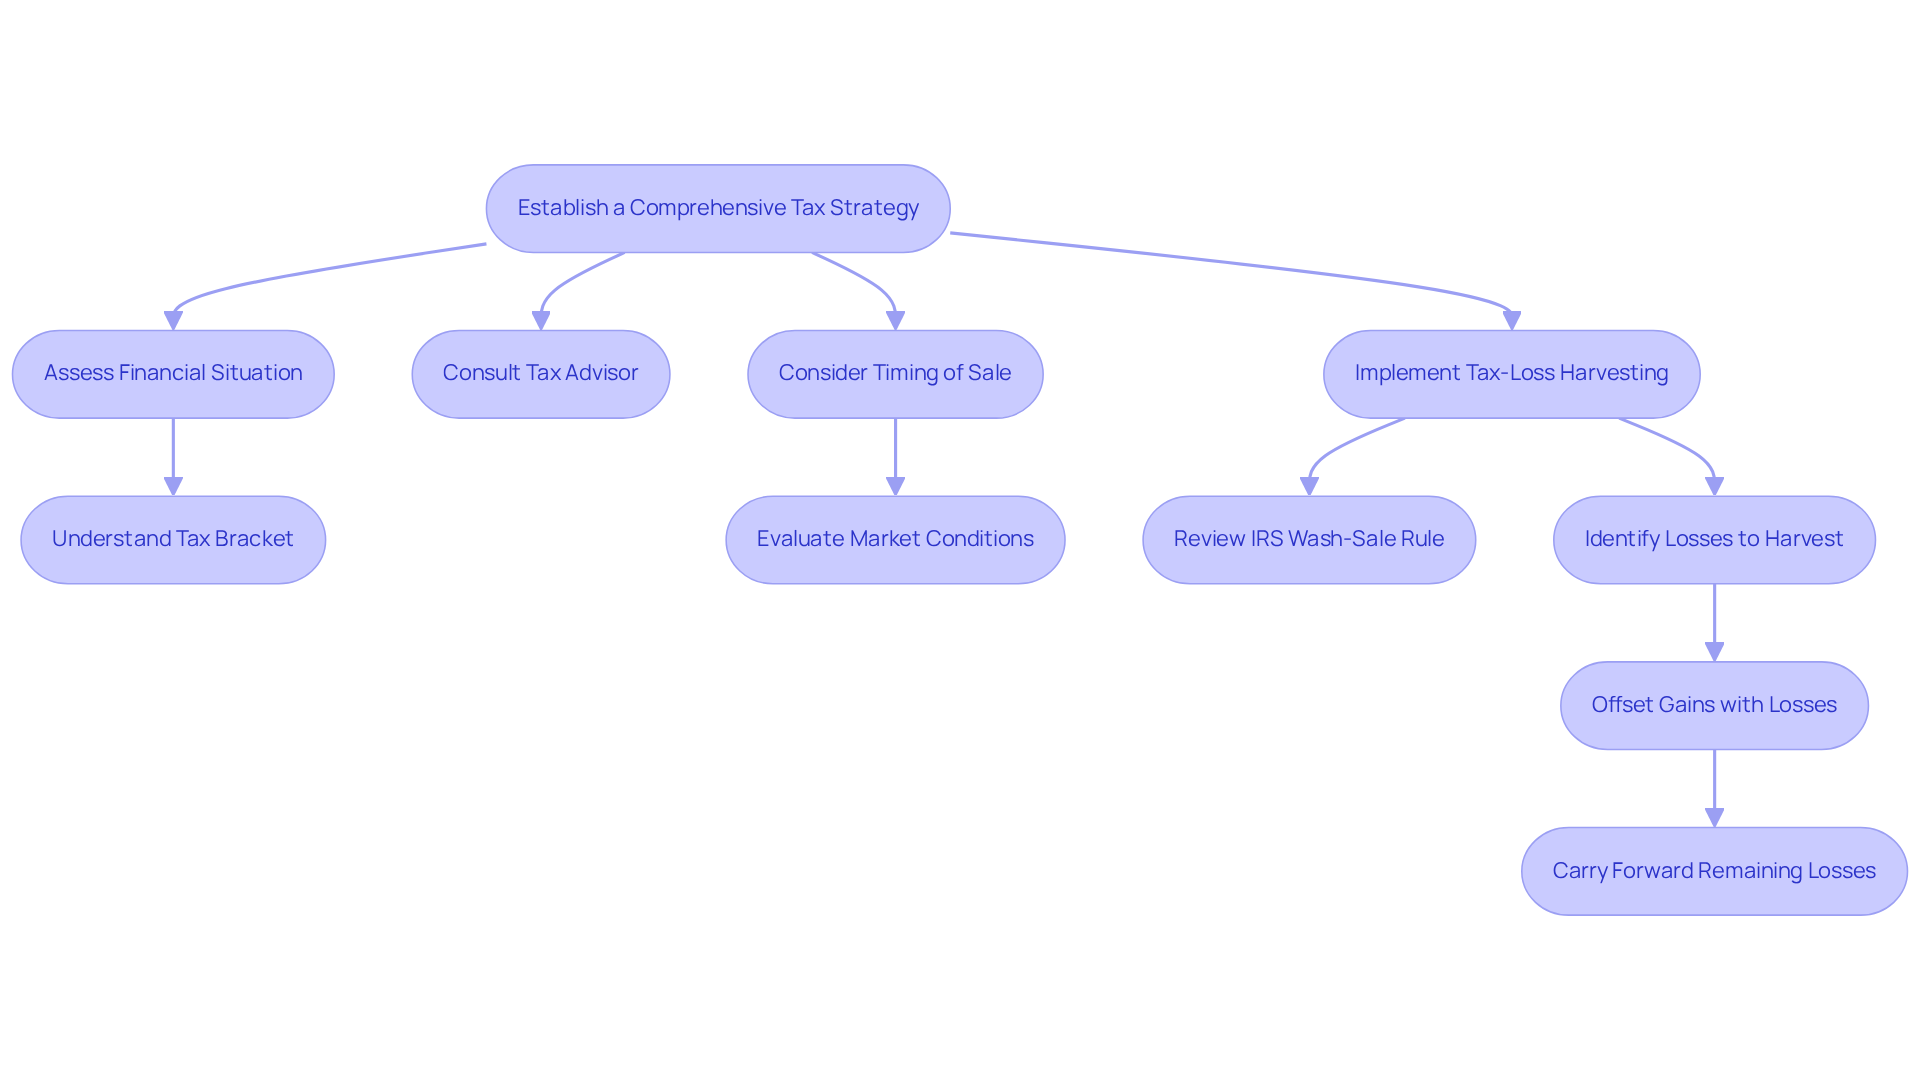
Start by taking a close look at your financial situation. Understanding your tax bracket and how large stock sale tax planning for tech employees affects your taxes is key to making informed decisions. Talking to a tax advisor can really help you figure out the best time to sell. For example, if you sell in a year when your income is lower, you might pay less in taxes.
One helpful approach is tax-loss harvesting. This means you can balance out your profits with losses from other investments, which can lower your taxable income. For instance, if you have stocks that have lost value, selling them in the same year as your appreciated stocks can help balance your gains and losses.
In one case, an investor made a $20,000 profit from a short-term investment while also facing a $25,000 loss from another. By offsetting the profit with the loss, they avoided taxes on the profit and could use the remaining loss to offset ordinary income, leading to significant tax savings.
Experts agree that tax-loss harvesting is especially beneficial for high-income earners, as it allows for strategic management of capital gains and losses. Just keep in mind the IRS wash-sale rule. It means you can’t claim a loss if you buy the same investment back within 30 days of selling it.
A real-world example of successful tax planning is the story of Allison and Brian, a couple who sought guidance from Bright Advisers to improve their financial situation. Despite their significant incomes, they were unaware of the opportunities they were missing due to insufficient tax planning. Through their collaboration with Bright Advisers, they optimized their tax situation, secured their children’s future through education funding, and gained the ability to retire sooner. By incorporating tax optimization into their comprehensive financial plan, they experienced the peace of mind that comes with financial security, allowing them to enjoy more quality time with their loved ones.
Understand Capital Gains Tax Implications for Stock Sales
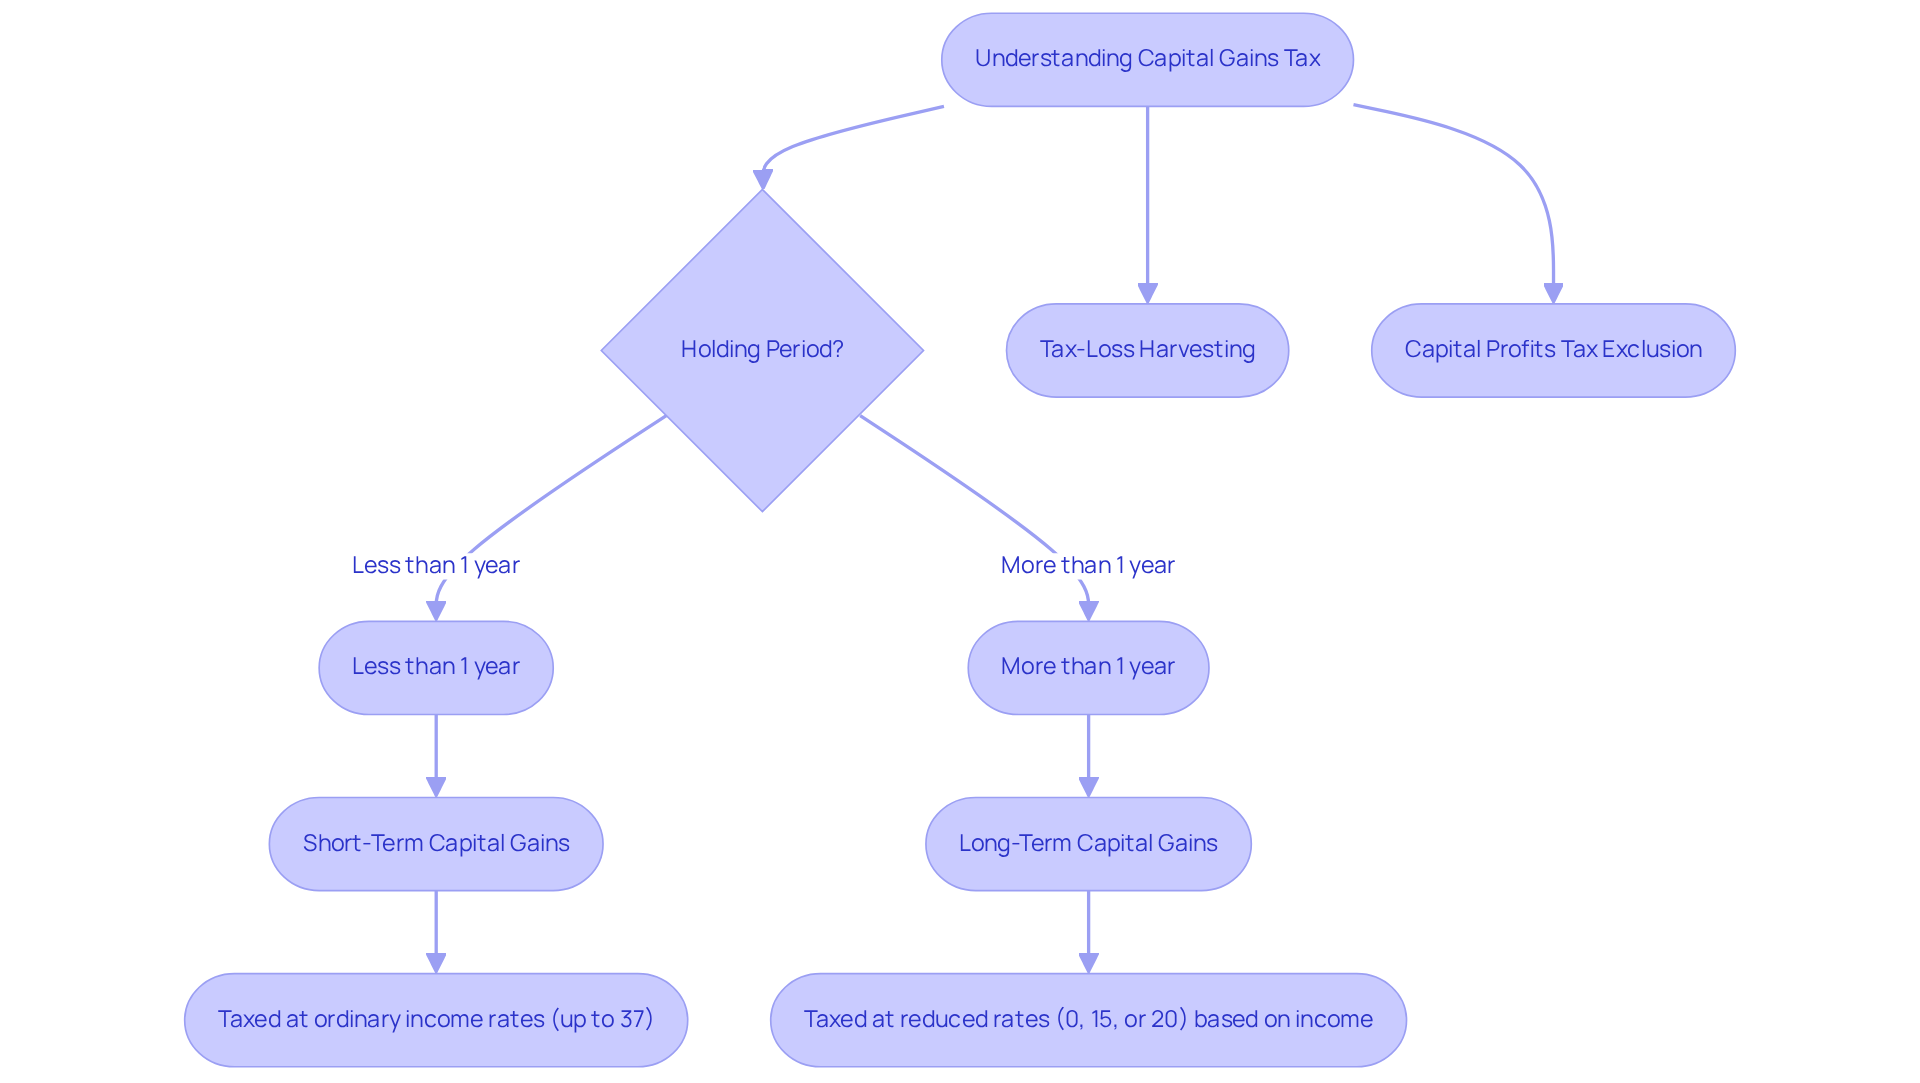
Understanding large stock sale tax planning for tech employees can feel overwhelming, especially for high-income families trying to secure their financial future. Capital profits can be short-term or long-term, based on how long you’ve held the asset. Short-term capital profits, for assets held for one year or less, are taxed at ordinary income rates, which can reach up to 37%. In contrast, long-term capital profits, for assets held longer than one year, benefit from reduced tax rates of 0%, 15%, or 20%, depending on your income level.
Imagine the peace of mind that comes from knowing when to sell your assets for the best tax outcome. If you sell stock that you’ve owned for more than a year, you may qualify for the reduced long-term capital tax rate, significantly lowering your tax obligation. It’s important to keep track of your holding periods and consider the timing of your sales to enhance tax efficiency.
In 2026, single filers with income surpassing $48,350 and married filers earning over $96,700 will be liable for capital profits taxes. Additionally, the net investment income tax (NIIT) adds an extra 3.8% on investment income for high-income earners, further impacting your overall tax burden.
Let’s look at how families like yours have navigated these challenges successfully. For example, homeowners who have lived in their property for at least two of the past five years may qualify for a capital profits tax exclusion of up to $250,000 for individual filers or $500,000 for joint filers. This exclusion can significantly reduce tax liabilities when selling a primary residence.
A relevant example is the experience of Allison and Brian, a couple who sought guidance from Bright Advisers to enhance their financial situation through effective tax planning. They realized that inadequate tax strategies were costing them money despite their high incomes. By collaborating with Bright Advisers, they optimized their tax situation, secured their children’s future through education funding, and gained the ability to retire sooner. Their success narrative highlights the significance of large stock sale tax planning for tech employees in effectively navigating capital gains tax consequences.
Additionally, strategies such as tax-loss harvesting can assist in offsetting realized profits with losses, enabling families to manage their tax obligations more effectively. By implementing these strategies and being aware of the current capital gains tax rates, families can navigate stock sales with greater confidence and financial acumen.
Disclaimer: Past performance does not guarantee future results. Securities holdings are subject to risk. Advisory services are offered through Lifeworks Advisors, a registered financial adviser.
Diversify Investments to Minimize Tax Burden Post-Sale
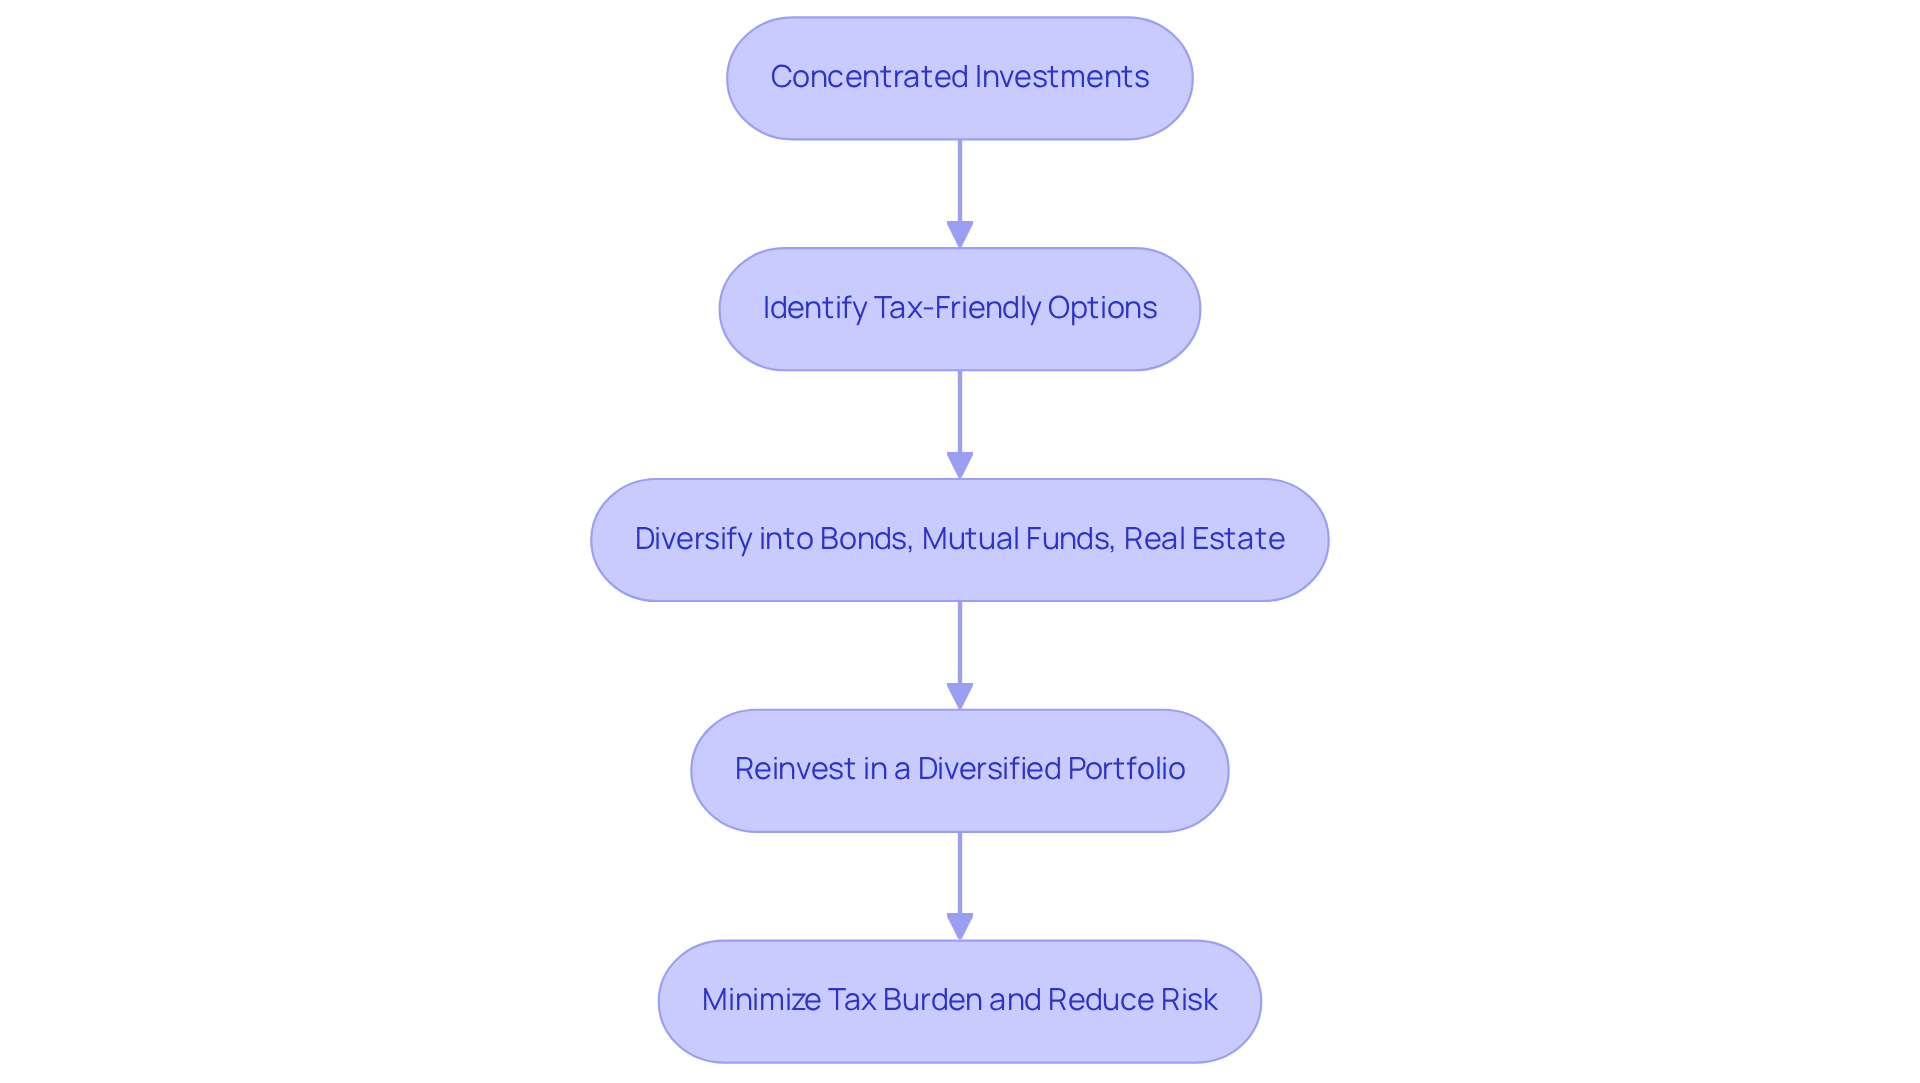
Imagine the worry that comes with having all your investments tied up in one place. After selling stock, it’s crucial to diversify your investments to minimize tax burdens and reduce risk. Concentrated stock positions can lead to significant market volatility, which may jeopardize your family’s financial stability. By spreading out your investments into different areas like bonds, mutual funds, or real estate, you can find more stability in your returns.
Choosing tax-friendly options like index funds or ETFs can make managing your taxes a little easier, giving you peace of mind. For instance, when you reinvest in a diversified portfolio, you can potentially offset future capital gains with losses from other investments, thereby reducing your overall tax exposure. Imagine the stress of watching your family’s financial future hang in the balance due to market fluctuations. By diversifying, you can breathe easier knowing your family’s financial future is more secure.
This way, you’re not just protecting your wealth; you’re also working towards the dreams and goals you have for your family. Taking these steps today can pave the way for a more secure tomorrow for your family.
Leverage Tax-Advantaged Accounts and Strategies for Optimal Outcomes
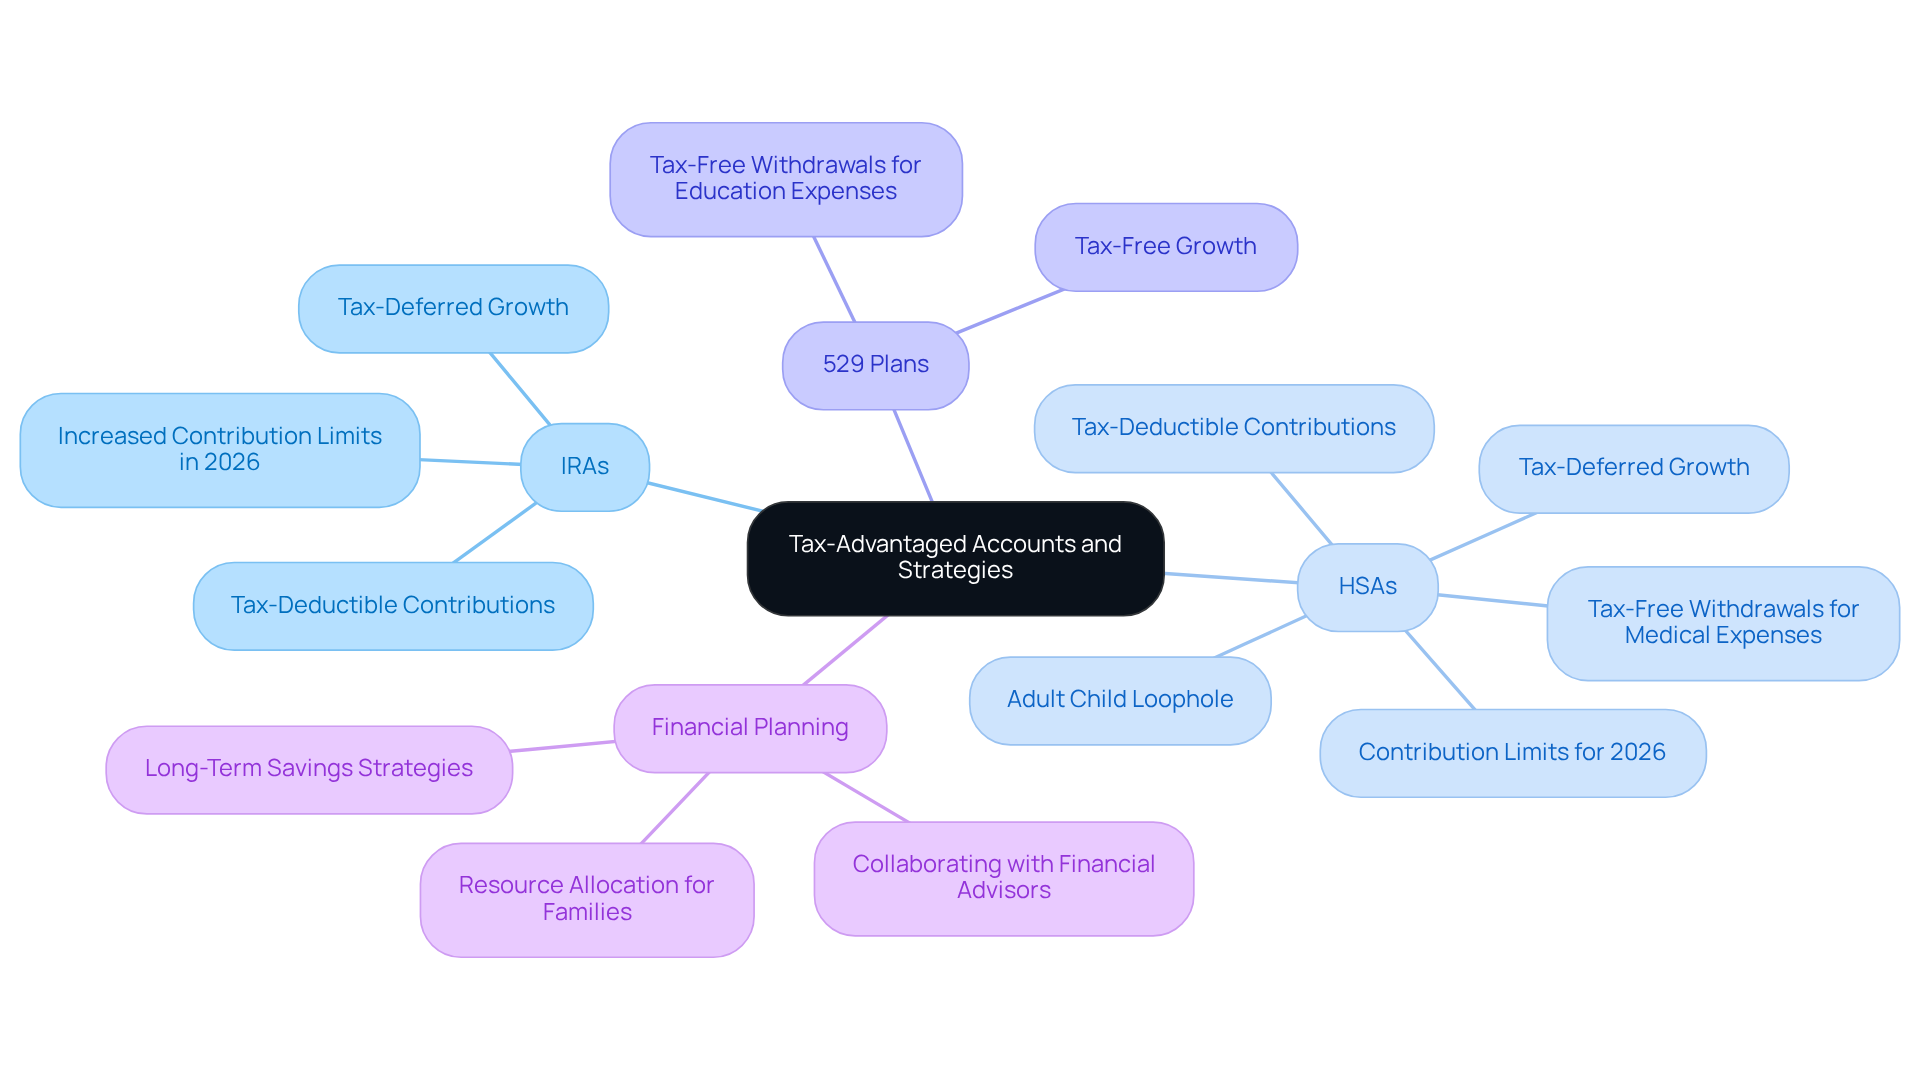
Imagine if you could boost your savings just by using the right accounts, like IRAs or HSAs. These accounts can really help you save more money for your family. For instance, contributions to a traditional IRA might lower your taxable income, giving you a little extra breathing room. Plus, the money you save in these accounts grows without being taxed until you take it out in retirement.
Health Savings Accounts (HSAs) are especially beneficial. They offer a triple tax advantage:
- your contributions are tax-deductible,
- the growth is tax-deferred,
- and when you use the funds for qualified medical expenses, it’s tax-free.
In 2026, the contribution limits for HSAs will increase to $4,400 for individuals and $8,750 for families, which means even more savings potential for you.
And don’t forget about 529 plans for your children’s education. They allow for tax-free growth and withdrawals for qualified education expenses, making them a smart choice for families looking to invest in their kids’ futures.
With these accounts, you can lower your taxes now and save for your family’s future. For example, families in the 36% tax bracket could save up to $2,790 by fully utilizing their HSA contributions. This not only helps with immediate tax savings but also promotes future economic stability for your children.
Consider the story of Emily and Mark, a couple navigating demanding careers while pursuing economic independence. By collaborating with Bright Advisers, they created a thorough strategy that involved improving their tax situation and planning for their children’s education. Likewise, Jay and Emma, who sought to alleviate monetary anxiety, successfully balanced their current obligations with long-term goals through effective resource allocation and investment strategies. These examples show how Bright Advisers can help families like yours achieve financial security and the freedom to make choices about work and life.
With the right support, you can create a financial plan that not only eases your worries but also secures your family’s future.
Conclusion
Imagine feeling overwhelmed by tax planning as you navigate the sale of your stock holdings, unsure of how to protect your family’s financial future. A well-structured tax strategy not only safeguards your financial well-being but also helps you make the most of your hard-earned income. By understanding capital gains tax implications, leveraging tax-loss harvesting, and utilizing tax-advantaged accounts, families can significantly reduce their tax burdens and enhance their overall financial health.
Think about how timing your stock sales can make a real difference for your family’s financial health. Recognizing the benefits of long-term capital gains and diversifying investments post-sale can empower you to take control of your financial destiny. Real-life examples, like the experiences of Allison and Brian, show how effective tax planning can lead to substantial improvements, such as securing education funding for children and achieving earlier retirement.
Ultimately, the significance of proactive tax planning cannot be overstated. Families should consider collaborating with experts like Bright Advisers to develop a comprehensive financial strategy that addresses their unique needs. By taking these steps, you can not only minimize your tax liabilities but also pave the way for a more secure and prosperous future. By reaching out for support, you can turn your financial aspirations into reality, ensuring your family’s dreams are not just wishes but achievable goals.
Frequently Asked Questions
Why is it important to establish a comprehensive tax strategy before selling stock?
Establishing a comprehensive tax strategy is crucial for maximizing your hard-earned money and ensuring it benefits your family’s future, especially for tech employees with equity compensation.
What should I consider when planning for a large stock sale?
You should closely examine your financial situation, understand your tax bracket, and how large stock sale tax planning affects your taxes. Consulting with a tax advisor can help determine the best time to sell.
What is tax-loss harvesting and how does it work?
Tax-loss harvesting is a strategy that allows you to offset profits from appreciated stocks with losses from other investments, thereby lowering your taxable income. For example, selling stocks that have lost value in the same year as selling appreciated stocks can help balance gains and losses.
Can you provide an example of tax-loss harvesting in action?
An investor who made a $20,000 profit from a short-term investment and faced a $25,000 loss from another investment offset the profit with the loss, avoiding taxes on the profit and using the remaining loss to offset ordinary income, resulting in significant tax savings.
Who benefits most from tax-loss harvesting?
Tax-loss harvesting is particularly beneficial for high-income earners, as it allows for strategic management of capital gains and losses.
What is the IRS wash-sale rule?
The IRS wash-sale rule states that you cannot claim a loss if you repurchase the same investment within 30 days of selling it.
Can you share a real-world example of successful tax planning?
Allison and Brian, a couple who worked with Bright Advisers, improved their financial situation through effective tax planning. They optimized their tax situation, secured education funding for their children, and gained the ability to retire sooner, leading to greater financial security and quality time with their loved ones.
List of Sources
- Establish a Comprehensive Tax Strategy Before Selling Stock
- Tax Loss Harvesting Tips: Smart Strategies to Cut Taxes & Boost Returns (https://wealthenhancement.com/blog/essential-tax-loss-harvesting-tips)
- Tax-Loss Harvesting Can Work Year-Round for Investors—Here’s How | Morgan Stanley (https://morganstanley.com/articles/tax-loss-harvesting)
- Reduce Capital Gains Tax on Stock Sales: 6 Strategies for 2026 | Cache (https://usecache.com/companion/reduce-capital-gains-on-stock-sale)
- Tax-loss harvesting explained | Vanguard (https://investor.vanguard.com/investor-resources-education/taxes/offset-gains-loss-harvesting)
- How to Cut Your Tax Bill with Tax-Loss Harvesting (https://schwab.com/learn/story/how-to-cut-your-tax-bill-with-tax-loss-harvesting)
- Understand Capital Gains Tax Implications for Stock Sales
- Capital Gains Tax Rates: Short-term vs. Long-term (https://schwab.com/learn/story/how-are-capital-gains-taxed)
- What is capital gains tax? | Vanguard (https://investor.vanguard.com/investor-resources-education/taxes/realized-capital-gains)
- Capital gains tax: Definition, rates, and ways to save | Fidelity (https://fidelity.com/learning-center/smart-money/capital-gains-tax-rates)
- Diversify Investments to Minimize Tax Burden Post-Sale
- Is Your Portfolio Too Concentrated? | Morgan Stanley (https://morganstanley.com/articles/diversify-risks-concentrated-positions)
- Mastering Concentrated Stock Positions: Strategies for Risk, Diversification and Taxes (https://creativeplanning.com/insights/investment/concentrated-stock-positions)
- Tax-Efficient Ways to Diversify Concentrated Stock Positions (https://financialplanningassociation.org/learning/publications/journal/OCT24-tax-efficient-ways-diversify-concentrated-stock-positions-OPEN)
- Concentrated Stock Position Strategies | Diversify Your Portfolio (https://nepwealth.com/insights/strategies-to-manage-a-concentrated-stock-position)
- Concentrated positions | Fidelity Investments (https://fidelity.com/learning-center/wealth-management-insights/diversify-concentrated-positions)
- Leverage Tax-Advantaged Accounts and Strategies for Optimal Outcomes
- IRS Increases 401(k) and IRA Contribution Limits for 2026 | Windes (https://windes.com/401k-ira-contribution-limits)
- How Much Can an HSA Save in Taxes? (https://hsaforamerica.com/blog/how-much-can-an-hsa-save-in-taxes)
- HSAs: An Overlooked Retirement Savings Vehicle | Morgan Stanley (https://morganstanley.com/articles/health-savings-account-retirement-tax-advantages)
- The Tax Benefits of a Health Savings Account (https://hsacentral.net/consumers/tax-benefits-health-savings-account)
- The triple tax benefits of health savings accounts (https://ameriprise.com/financial-goals-priorities/insurance-health/benefits-health-savings-accounts)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading