

Key Highlights
- Capital gains taxes apply to profits from selling assets like stocks, with rates varying based on the holding period.
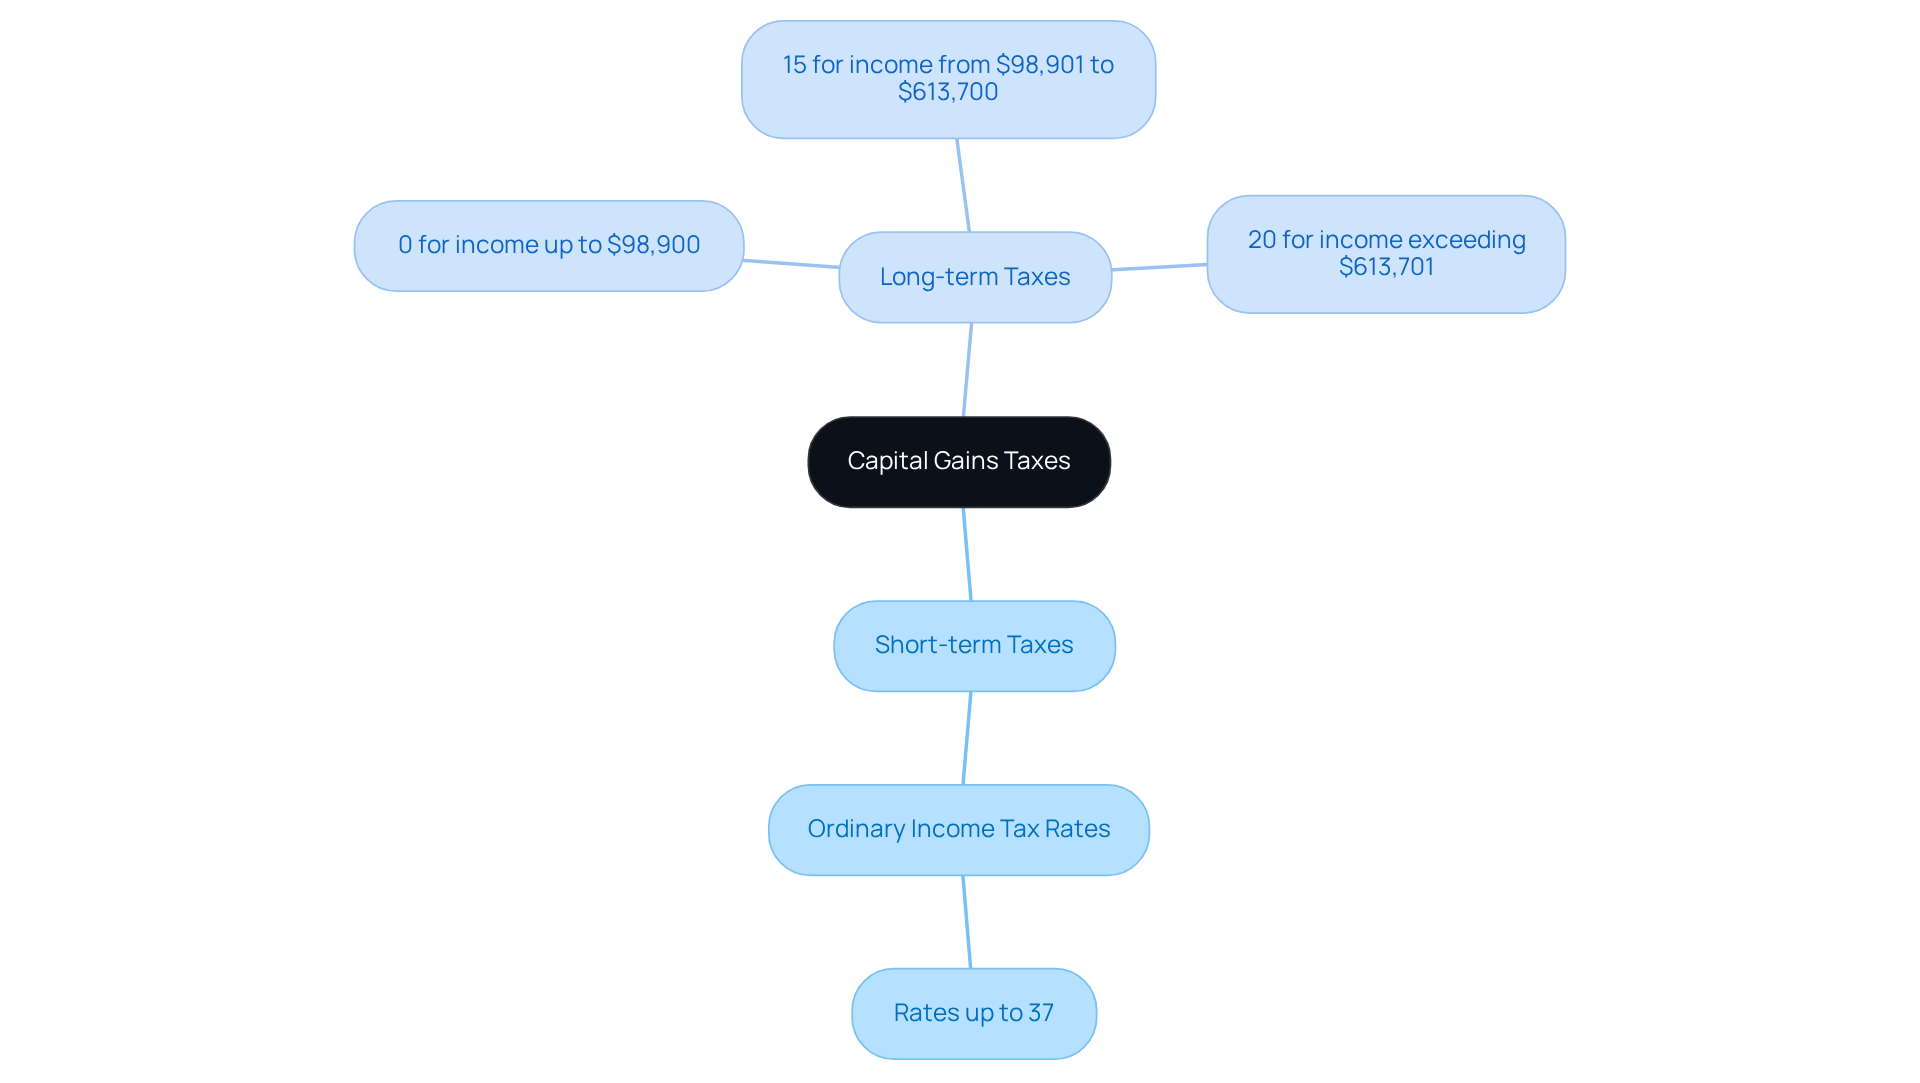
- Short-term capital gains are taxed at ordinary income rates, which can be as high as 37%, while long-term gains benefit from lower rates of 0%, 15%, or 20%.
- Understanding tax implications is crucial for families, as significant tax bills can impact financial goals like funding children’s education.
- The stepped-up basis rule can help families avoid taxes on inherited assets if held until death.
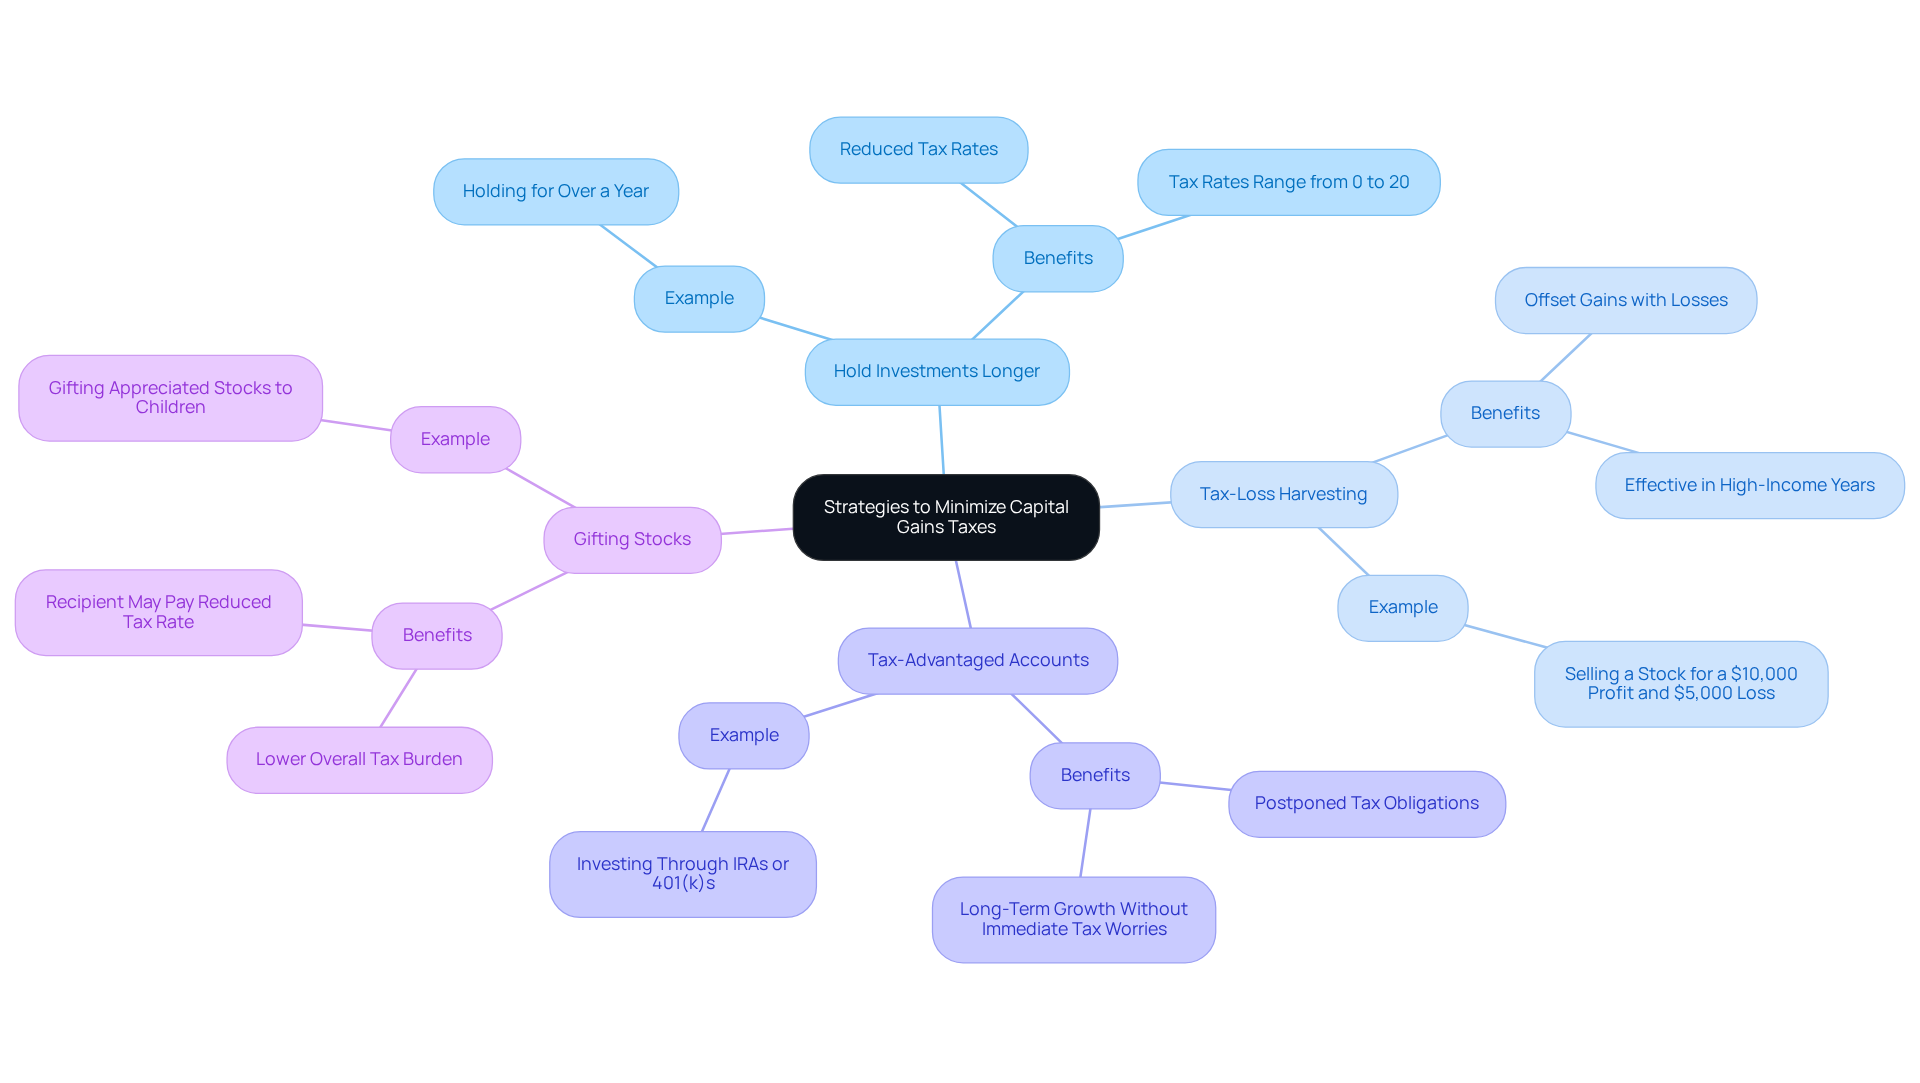
- Effective strategies to minimise capital gains taxes include holding investments longer, tax-loss harvesting, using tax-advantaged accounts, and gifting appreciated stocks.
- Tax-loss harvesting allows families to offset profits with losses, reducing overall tax liability.
- Maximising retirement contributions can lower taxable income, providing more financial flexibility.
- Professional guidance from tax advisors can help families create tailored tax strategies and navigate complex tax laws.
Introduction
Many families feel lost when it comes to understanding capital gains taxes, but it doesn’t have to be that way. Navigating these complexities can feel daunting, especially when you’re trying to secure your family’s financial future. Imagine being able to turn the challenge of capital gains taxes into a stepping stone for your family’s financial future. As stock sales can lead to significant tax implications, understanding these nuances is essential for making informed decisions that truly benefit your loved ones.
Together, we can explore how effective strategies can lighten your tax burden and help your family achieve its dreams. By embracing these strategies, families can ensure their hard-earned assets truly support their long-term aspirations.
Understand Capital Gains Taxes and Their Impact on Stock Sales
Imagine facing a hefty tax bill just when you’re trying to secure your family’s future – this is the reality of capital gains taxes for many young parents. Capital gains taxes apply to the profit from selling an asset, like stocks. If you sell an asset you’ve owned for a year or less, you’ll face ordinary income tax rates, which can climb as high as 37%. On the other hand, if you hold onto your investments for over a year, you could enjoy lower tax rates – 0%, 15%, or 20% – which can make a big difference for your family’s finances.
As a parent, understanding these tax rates is crucial; they can significantly impact your family’s financial plans and dreams. For instance, if your household sells a stock that has appreciated significantly, you might face a hefty tax bill that could hinder your ability to fund your children’s education or other long-term goals.
Let’s take a moment to think about Emily and Mark, who turned to Bright Advisers for help after inheriting farmland that skyrocketed in value from $50,000 to $800,000. Without proper planning, they could have faced a financial obligation exceeding $150,000 due to appreciation-related charges. However, by implementing effective financial strategies, like utilizing the stepped-up basis rule, families can avoid these levies altogether. This guideline allows heirs to receive assets at their current fair market value, potentially eliminating taxes on profits if the assets are held until death.
In 2026, the long-term tax rates for married couples filing jointly are structured as follows:
- 0% for income up to $98,900
- 15% for income from $98,901 to $613,700
- 20% for income exceeding $613,701
This layered framework highlights the importance of timing and planning in tax strategies related to profits.
Ultimately, by understanding the tax implications of profits, you can adopt a large stock sale tax strategy to take proactive steps in protecting your family’s financial future, ensuring that your hard-earned assets truly benefit your loved ones. For more personalized strategies, we invite you to join our waitlist at Bright Advisers, where we provide comprehensive financial planning services through Lifeworks Advisors, a registered investment adviser. Please remember that past performance does not guarantee future results, and all securities investments are subject to risk.
Implement Effective Strategies to Minimize Capital Gains Taxes
Many families feel overwhelmed by the complexities of capital gains taxes, unsure of how to minimize their burden. But there are effective strategies that can help ease this stress and align with your family’s financial goals.
-
Imagine holding onto your investments a little longer to ease your tax worries. By retaining stocks for over a year, you can benefit from reduced long-term tax rates on profits, which range from 0% to 20% depending on your income levels. This approach can lighten your tax burden, giving you more room to breathe financially compared to short-term capital profits, which can be taxed as high as 37%.
-
Think of tax-loss harvesting as a way to turn setbacks into opportunities for savings. This strategy involves selling underperforming stocks to offset profits from successful sales. For instance, if you sell a stock for a $10,000 profit but also sell another for a $5,000 loss, you can lower your taxable profit to $5,000. This method is particularly beneficial in high-income years, as it can significantly reduce your overall tax liability.
-
Consider using tax-advantaged accounts to help your family’s investments grow without immediate tax worries. Investing through vehicles like IRAs or 401(k)s allows you to postpone obligations on profits until withdrawal, providing a strategic advantage for long-term financial planning.
-
Imagine gifting appreciated stocks to your children, helping them while also easing your family’s tax burden. By doing so, you can lower the overall tax burden on your household, as the recipient may pay a reduced capital gains tax rate when they eventually sell the stock.
These approaches not only help in handling finances but also align with your household’s long-term monetary objectives. For instance, a family once shared how they used tax-loss harvesting by selling a stock at a loss to counterbalance profits from another investment, leading to substantial tax savings. By embracing these strategies, you can take control of your financial future and ensure your family’s long-term stability.
Leverage Tax Planning for Enhanced Investment Returns
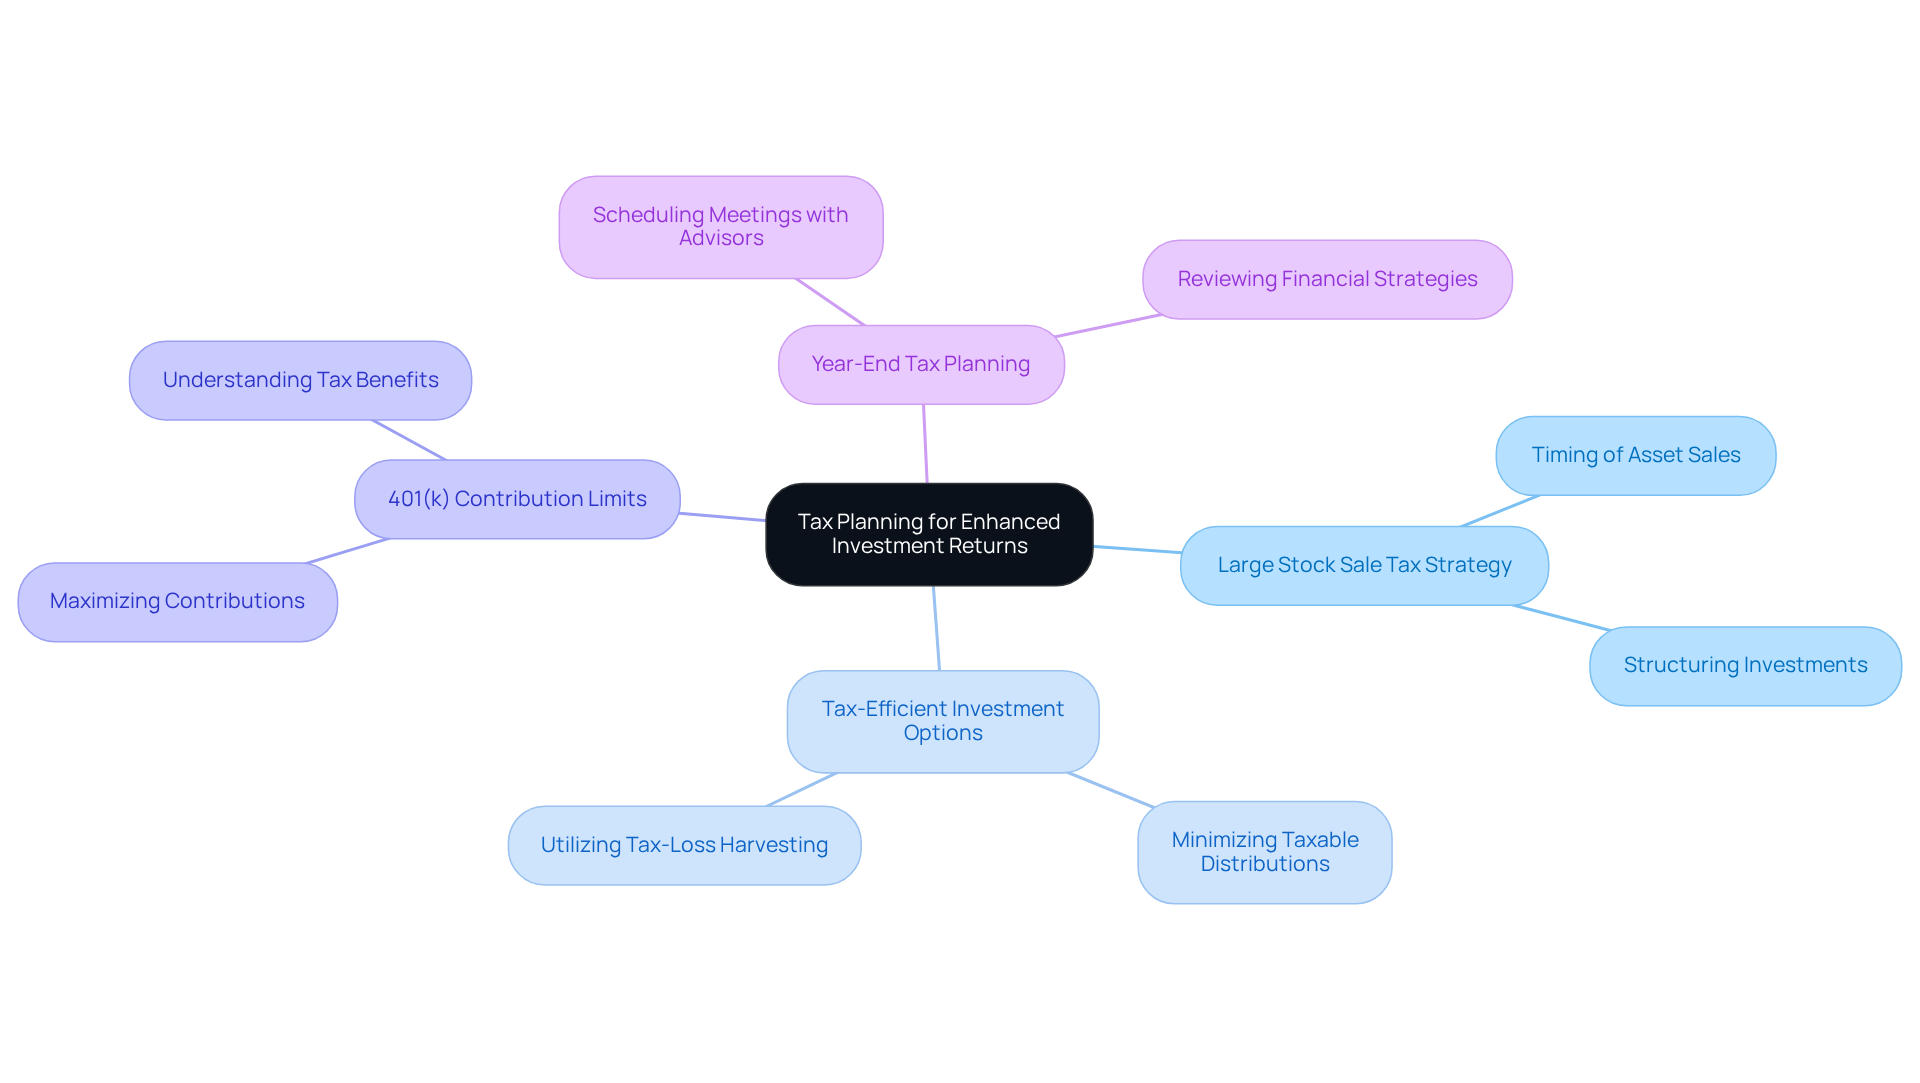
Imagine the worry of not knowing if you’re making the most of your hard-earned money. Effective tax planning, particularly through a large stock sale tax strategy, can be a game-changer for families, helping you enhance your investment returns and secure a brighter future for your loved ones. Understanding your tax situation can empower you to make choices that benefit your family’s future, including the implementation of a large stock sale tax strategy when deciding when to sell assets or how to structure your investments.
Choosing the right investment options can help keep more money in your pocket. For instance, think about tax-efficient vehicles that minimize taxable distributions. You can even balance out your gains with losses from investments that didn’t perform well, which can save you money come tax time.
Imagine the peace of mind that comes with knowing you’re making informed decisions. When you plan effectively, you can feel secure knowing your family’s future is protected. Take Allison and Brian, for example. They realized they were missing out on financial opportunities due to inadequate tax planning. By collaborating with Bright Advisers, they optimized their tax situation through a large stock sale tax strategy, secured their children’s future through education funding, and gained the ability to retire sooner.
Families should also be aware of the 2025 contribution limit for a 401(k), which is $23,500. Maximizing retirement contributions can lower your taxable income, giving you more flexibility. Finally, scheduling a year-end tax planning meeting with a wealth advisor and CPA is crucial for effective tax management. Together, we can navigate these strategies to ensure a brighter financial future for your family.
Seek Professional Guidance for Tailored Tax Strategies
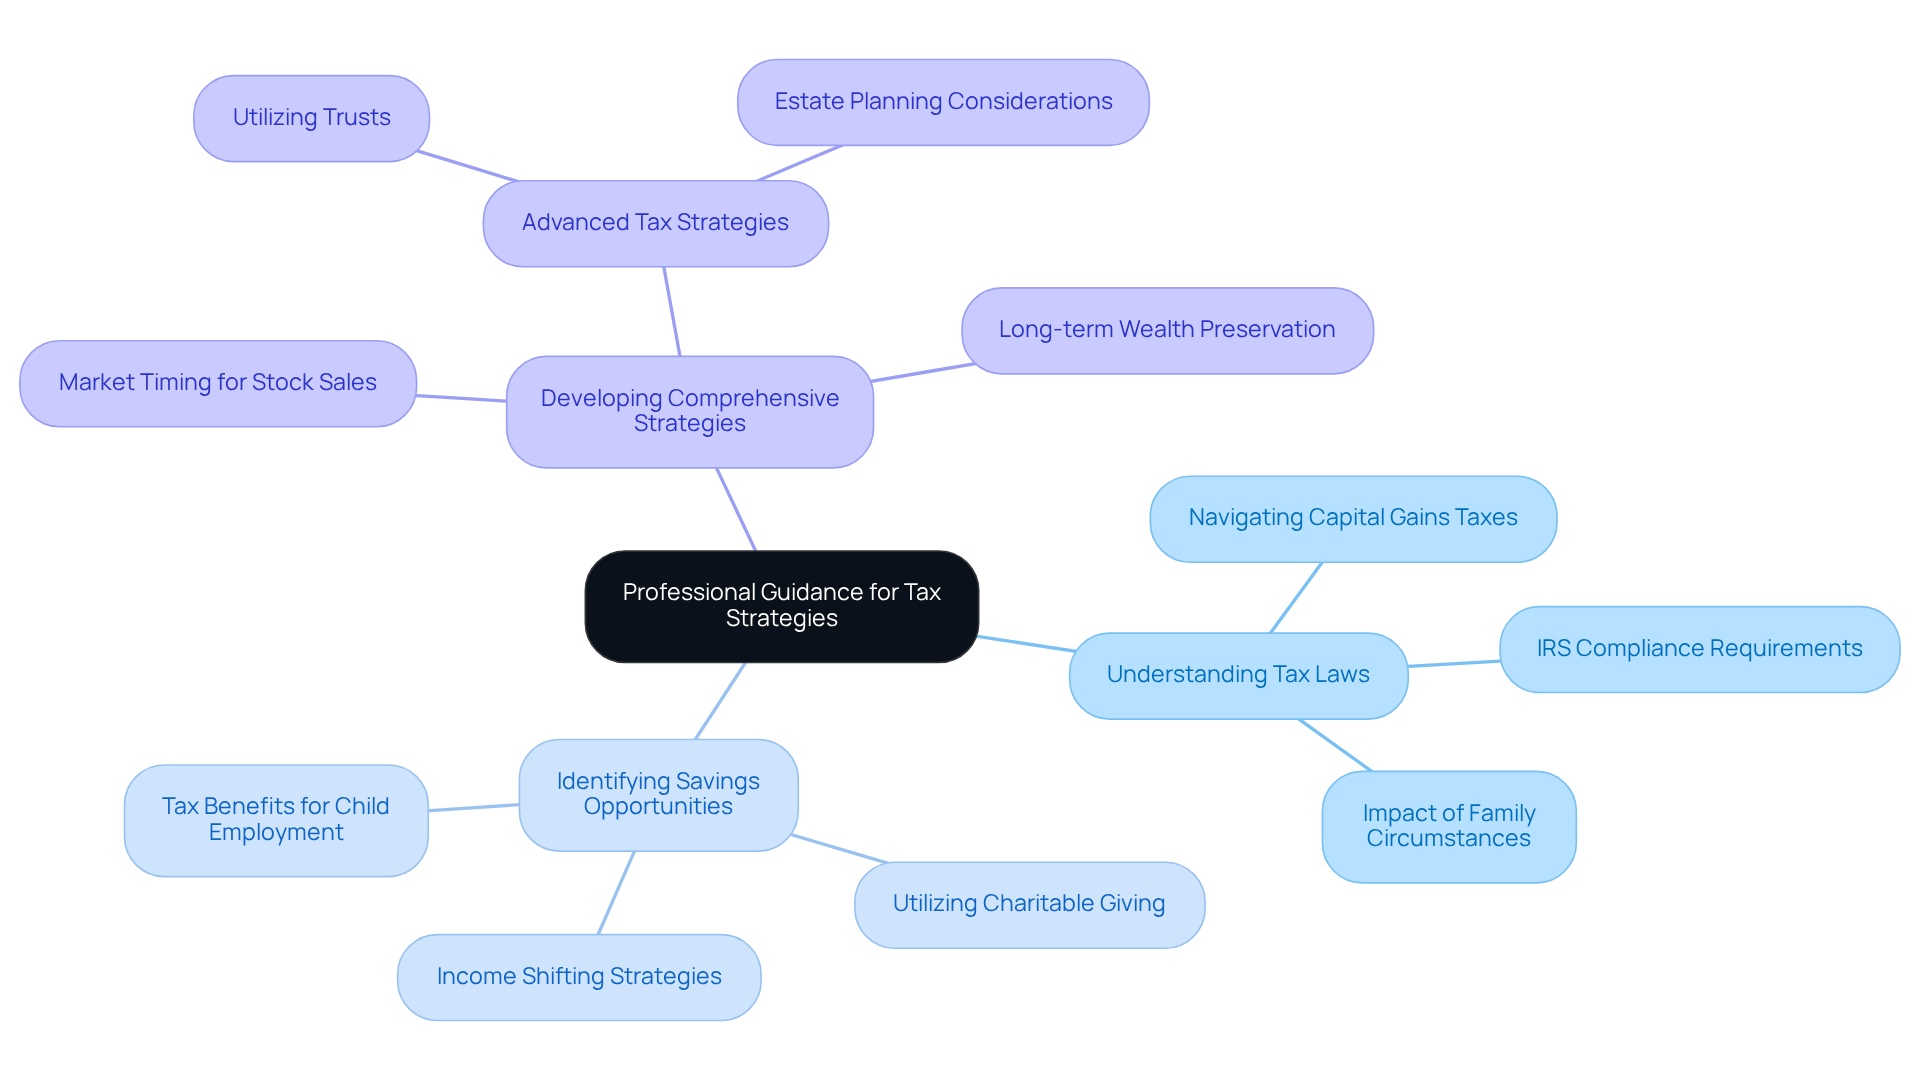
Many families feel overwhelmed by the thought of navigating capital gains taxes and stock sales. Finding the right tax advisor or financial planner can help your family create a plan that fits your unique needs. These caring professionals can help you understand the ins and outs of tax laws, identify opportunities for savings, and develop a comprehensive tax strategy that complements your overall financial plan.
Imagine having someone by your side who can assist in determining the best timing for selling stocks, taking into account market conditions and your family’s tax situation. They can also offer insights into advanced strategies, like charitable giving or utilizing trusts, to effectively reduce tax liabilities.
When you work with someone who understands your family’s needs, you can make choices that truly benefit your future. With the right support, you can transform your financial worries into a brighter future for your family.
Conclusion
Imagine feeling confident about your family’s financial future, even when faced with the complexities of capital gains taxes. Understanding how these taxes affect stock sales can help your family make smart choices that protect your wealth and support your dreams. Many families feel lost when it comes to capital gains taxes, unsure of how to tackle them. But by grasping these concepts, you can navigate this landscape with greater ease.
The strategies we’ve discussed, like holding investments longer for lower tax rates and utilizing tax-loss harvesting, offer practical pathways to lighten your tax load. When you use these strategies, you can gain peace of mind about your family’s financial future. It’s important to remember that proactive tax planning can align with your family’s values and goals, making a significant difference in your financial journey.
Collaborating with professionals like Bright Advisers can empower you to navigate the complexities of tax laws. They can help you develop tailored strategies that fit your unique situation, ensuring that your hard-earned assets truly benefit your loved ones. With the right support, you can turn financial challenges into stepping stones for your family’s future.
Frequently Asked Questions
What are capital gains taxes?
Capital gains taxes apply to the profit made from selling an asset, such as stocks. The tax rate depends on how long the asset has been held.
How are capital gains taxed based on the holding period?
If you sell an asset owned for a year or less, you will face ordinary income tax rates, which can be as high as 37%. If the asset is held for over a year, the tax rates can be lower, at 0%, 15%, or 20%.
Why is it important for parents to understand capital gains taxes?
Understanding capital gains taxes is crucial for parents because they can significantly impact financial plans and goals, such as funding children’s education or other long-term objectives.
Can you provide an example of how capital gains taxes can affect a family’s finances?
For instance, if a household sells a stock that has appreciated significantly, they might face a substantial tax bill that could hinder their ability to achieve financial goals.
What is the stepped-up basis rule?
The stepped-up basis rule allows heirs to receive assets at their current fair market value, potentially eliminating taxes on profits if the assets are held until death.
What are the long-term capital gains tax rates for married couples filing jointly in 2026?
The long-term tax rates are structured as follows: 0% for income up to $98,900; 15% for income from $98,901 to $613,700; 20% for income exceeding $613,701.
How can families protect their financial future regarding capital gains taxes?
By understanding the tax implications of profits and adopting proactive tax strategies, families can ensure that their hard-earned assets benefit their loved ones.
Where can families find personalized financial strategies related to capital gains taxes?
Families can join the waitlist at Bright Advisers for comprehensive financial planning services provided through Lifeworks Advisors, a registered investment adviser.
List of Sources
- Understand Capital Gains Taxes and Their Impact on Stock Sales
- Capital Gains Tax Rates: Short-term vs. Long-term (https://schwab.com/learn/story/how-are-capital-gains-taxed)
- Do This Now to Avoid Massive Capital Gains Tax on Your Family’s Inheritance | Repair The Roof Podcast – % (https://daytonestateplanninglaw.com/episodes/do-this-now-to-avoid-massive-capital-gains-tax-on-your-familys-inheritance)
- Capital gains tax: Definition, rates, and ways to save | Fidelity (https://fidelity.com/learning-center/smart-money/capital-gains-tax-rates)
- How are capital gains taxed? (https://taxpolicycenter.org/briefing-book/how-are-capital-gains-taxed)
- Implement Effective Strategies to Minimize Capital Gains Taxes
- What is Tax-Loss Harvesting? Rules & Examples | New York Life (https://newyorklife.com/articles/what-is-tax-loss-harvesting)
- Capital Gains Tax: What it is and how to reduce it (https://ffbkc.com/blogs/managing-money/capital-gains-tax-what-it-is-how-to-reduce)
- The economics of tax-loss harvesting (https://thetaxadviser.com/issues/2023/sep/the-economics-of-tax-loss-harvesting)
- Minimizing Capital Gains Taxes (https://brightonjones.com/blog/minimizing-capital-gains-taxes)
- How to avoid capital gains tax (https://empower.com/the-currency/money/how-to-avoid-capital-gains-tax)
- Leverage Tax Planning for Enhanced Investment Returns
- Year-End Tax Planning Strategies for High-Net-Worth Families (https://creativeplanning.com/insights/taxes/year-end-tax-planning-high-net-worth-families)
- Using Tax Brackets to Manage Your Taxable Income (https://schwab.com/learn/story/using-tax-brackets-to-manage-your-taxable-income)
- Want to Keep More of Your Investment Returns? Consider These Tax Moves | Morgan Stanley (https://morganstanley.com/articles/tax-efficient-investments-keeping-your-return)
- Impact of Taxes on Investment Returns | U.S. Bank (https://usbank.com/investing/financial-perspectives/investing-insights/impact-of-taxes-on-investment-returns.html)
- 4 Essential Tax Planning Strategies Every HNWI Should Know – Agemy Financial Strategies (https://agemy.com/blog/4-essential-tax-planning-strategies-every-hnwi-should-know)
- Seek Professional Guidance for Tailored Tax Strategies
- Family Office Tax Planning | Expert Strategies (https://assetvantage.com/blogs/family-office-tax-planning)
- Family payroll saves $3000 annually in taxes (https://instead.com/resources/blog/family-payroll-saves-3000-annually-in-taxes)
- 5 things that trigger your tax strategy going from online-only to a tax professional (https://greaterny.nyloffices.com/resources/articles/5-reasons-to-see-a-tax-professional)
- Tax Procrastination Statistics 2025 – IPX1031 (https://ipx1031.com/americas-biggest-tax-procrastinators-2025)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Philanthropy for high-income W-2 families at Bright Advisers.
Keep reading