

Key Highlights
- Beneficiary designations determine who inherits assets upon death, crucial for life insurance, retirement accounts, and bank accounts.
- Primary beneficiaries receive assets first, while contingent beneficiaries inherit if the primary is unable to.
- Failing to name a contingent beneficiary can lead to assets reverting to the estate, causing stress for families.
- Regularly reviewing beneficiary designations is essential, especially after major life events like marriage or divorce.
- California laws govern beneficiary designations, and understanding these is vital to avoid legal issues.
- The probate process can be lengthy and costly if no beneficiaries are designated, taking 6 to 18 months and incurring fees of 4% to 7% of the estate’s value.
- Gather necessary documents, including death certificates and current designations, to facilitate the process of changing beneficiaries.
- Maintain communication with financial institutions to ensure a smooth transition and address any delays or disputes.
- Consulting an estate planning attorney is recommended if conflicts arise between a will and beneficiary designations.
- Bright Advisers emphasises fiduciary duty and transparency, offering tailored wealth management solutions for families.
Introduction
Losing a loved one is never easy, and understanding how to care for their wishes can feel overwhelming. This guide will gently walk you through the essential steps for changing beneficiary designations after a death, highlighting how these legal directives play a vital role in estate planning.
Many families find themselves unsure of where to start when faced with these changes. This uncertainty can lead to stress and conflict during an already difficult time. Together, we can navigate this journey and ensure that their wishes are honored.
Understand Beneficiary Designations
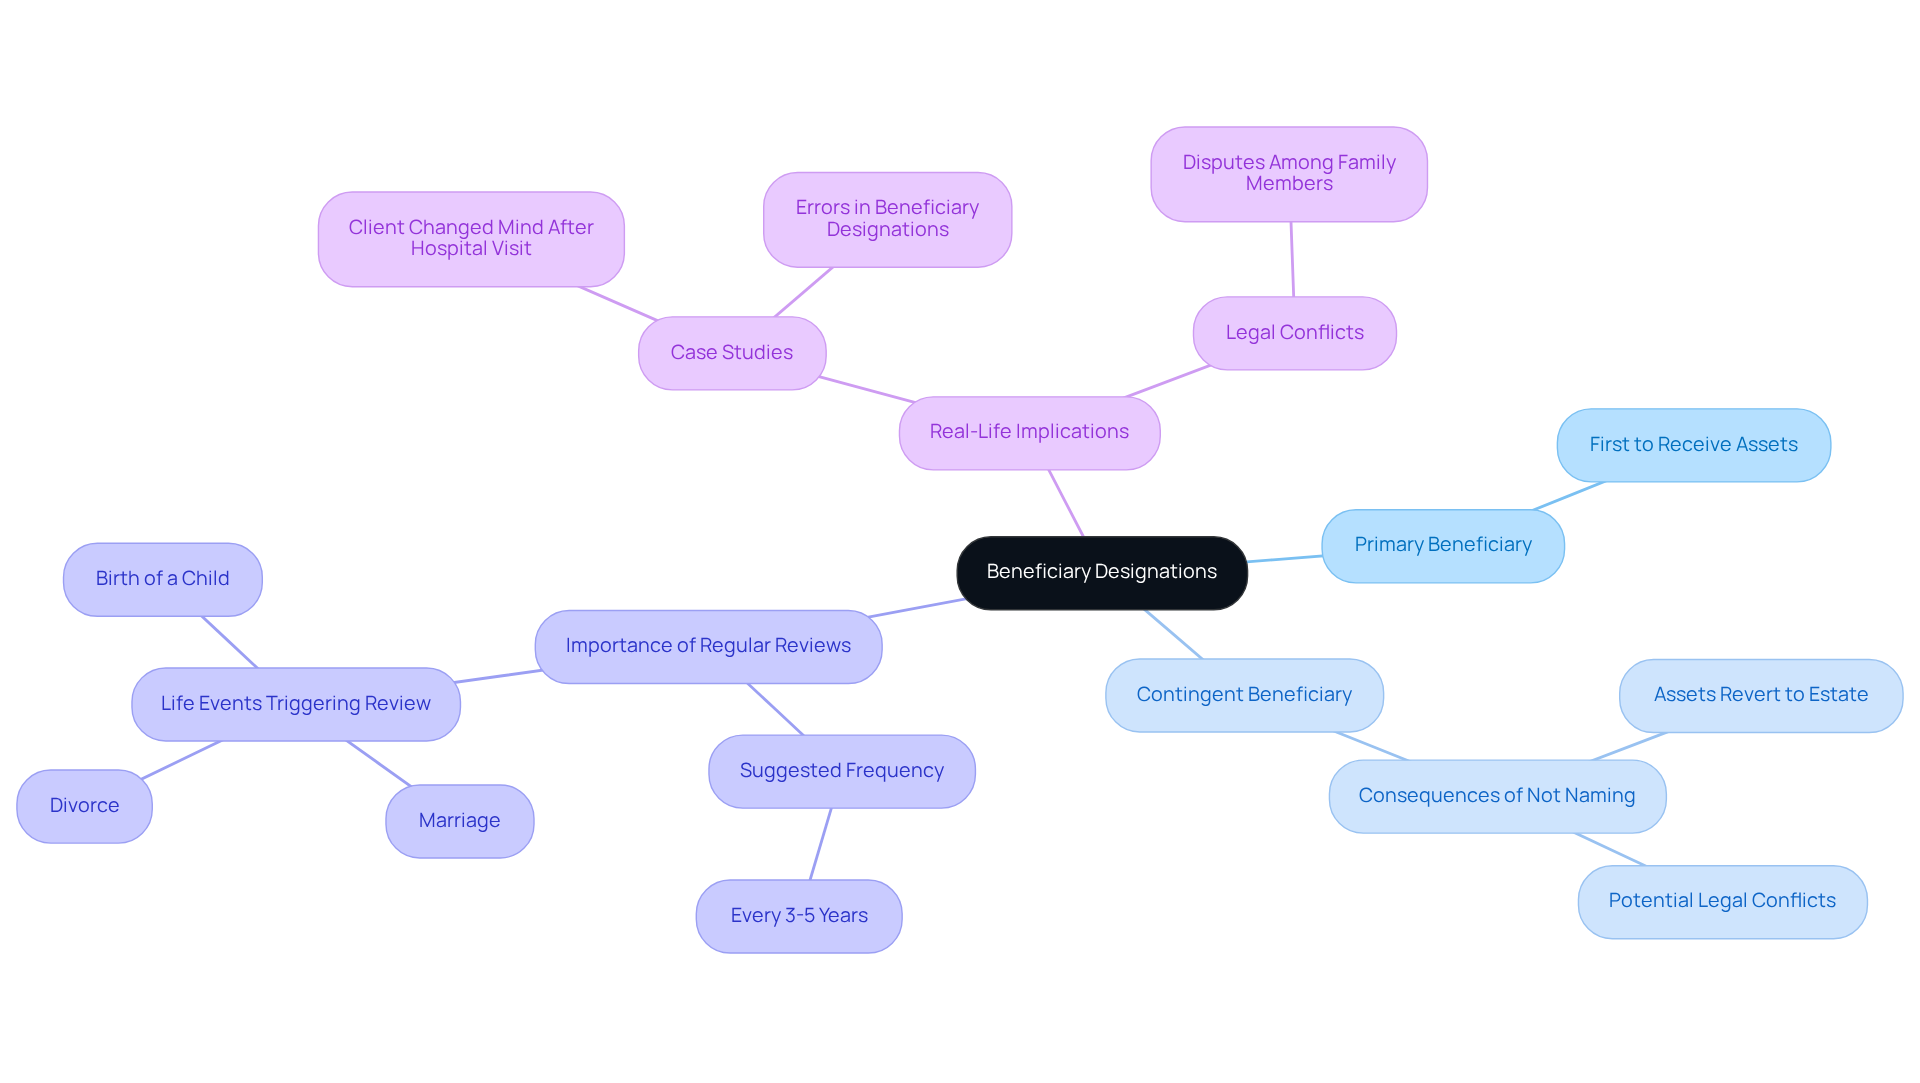
Imagine the peace of mind that comes from knowing your loved ones are taken care of, even when you’re not there to guide them. Beneficiary designations help ensure that happens. These legal directives determine who inherits your assets upon your death and are essential in various financial accounts, including life insurance policies, retirement accounts, and bank accounts, particularly in the context of changing beneficiary after death.
Understanding the distinction between primary and contingent beneficiaries is essential.
- Primary Beneficiary: The first individual designated to receive the asset.
- Contingent Recipient: This individual obtains the asset if the primary recipient is unable to do so.
It’s important to understand that if you don’t name a contingent recipient, your assets might go back to your estate, which can create unnecessary stress for your family during a tough time, highlighting the significance of changing beneficiary after death. Consistently assessing and revising these classifications is essential, especially following major life events like marriage, divorce, or the arrival of a child, which may necessitate changing beneficiary after death. Furthermore, changing beneficiary after death can lead to legal conflicts among family members, particularly if the changes contradict the directives outlined in a will.
Consider the story of one client who reconsidered excluding an estranged child from his allocations after a hospital visit. This highlights the necessity for adaptability in these choices. Experts suggest reviewing recipient assignments every three to five years to ensure they align with your current preferences and family circumstances, particularly in the context of changing beneficiary after death. This proactive approach not only safeguards your assets but also simplifies changing beneficiary after death, allowing for a smoother transition for your loved ones.
At Bright Advisers, we recognize that young families, such as Jay & Emma, Emily & Mark, and Allison & Brian, encounter distinct monetary challenges. By including recipient assignments in a thorough monetary strategy, families can safeguard their children’s future and help ensure that their wealth legacy is maintained. Our tailored wealth management solutions empower families to navigate these complexities, providing peace of mind and financial security for generations to come. Consistently revising recipient assignments is an essential part of this process, particularly in the context of changing beneficiary after death, enabling families to adjust their plans as their situations evolve. We emphasize our fiduciary duty and transparency, ensuring no hidden fees or conflicts of interest, and we offer customizable monthly fees to suit your needs.
Review Legal Considerations
Navigating the aftermath of a loved one’s passing can be daunting, especially when it comes to changing beneficiary after death. Before making any changes, it’s important to grasp the legal implications involved:
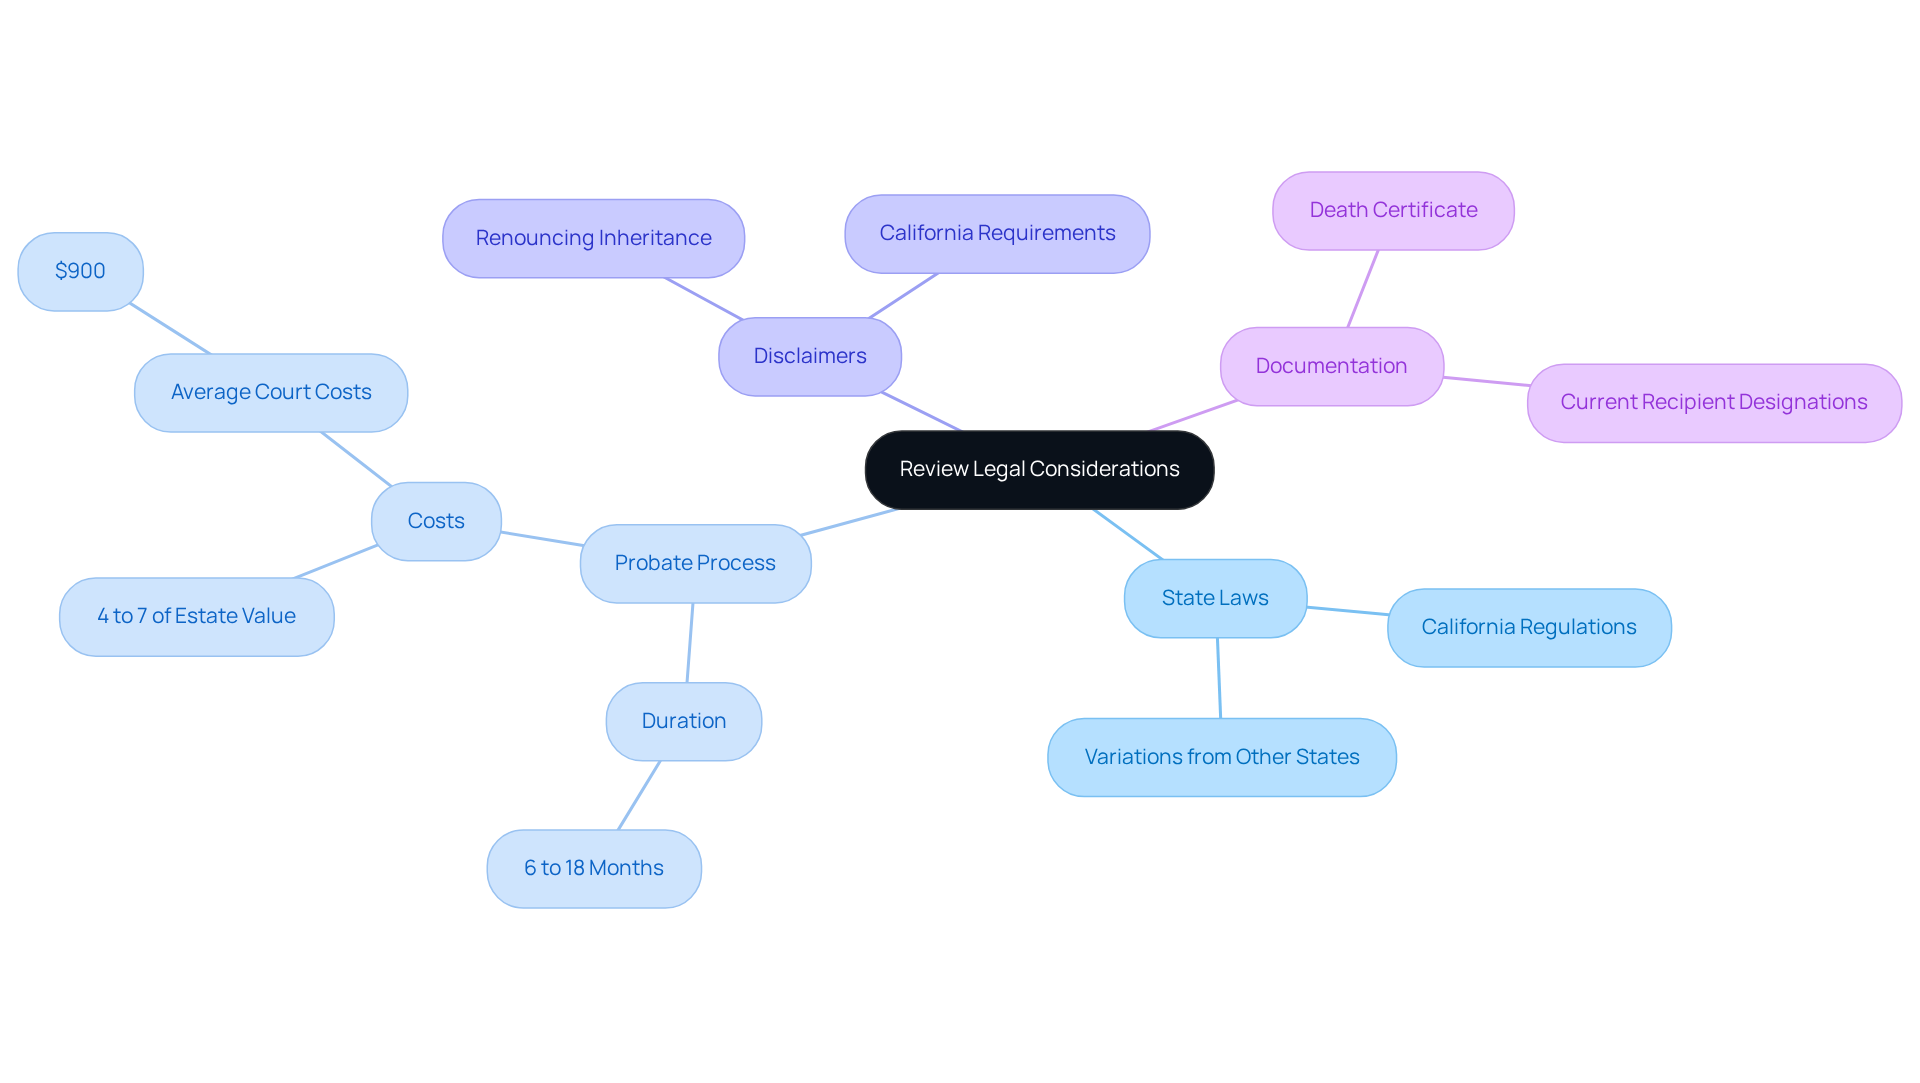
- State Laws: California has specific regulations governing recipient designations, which can vary significantly from other states. Familiarizing yourself with these regulations is essential to ensure compliance and avoid potential legal issues.
- Probate Process: If no recipient was appointed for certain assets, those assets could end up in probate, which can be a lengthy process. It often takes between 6 to 18 months and may incur fees ranging from 4% to 7% of the estate’s total value. The average total court costs in a typical probate case are approximately $900, which is important to consider when planning.
- Disclaimers: Recipients may choose to renounce their right to an inheritance, allowing the asset to pass to a contingent recipient. This disclaimer must be executed in accordance with California state laws to be valid, including specific requirements that must be followed.
- Documentation: Take a moment to gather the necessary documents, like the death certificate and any current recipient designations, to help ease this process. Proper documentation is essential for facilitating the process and ensuring that all regulatory requirements are met.
Understanding these factors can help simplify the process of changing beneficiary after death, allowing you to focus on what truly matters during this difficult time. As California’s probate filings are projected to grow significantly, being informed about these legal considerations can ease your burden and help you focus on what truly matters-your family.
Follow Step-by-Step Instructions
Imagine facing the daunting task of changing beneficiary after death of a loved one. It can feel overwhelming, but we’re here to guide you through this process with care.
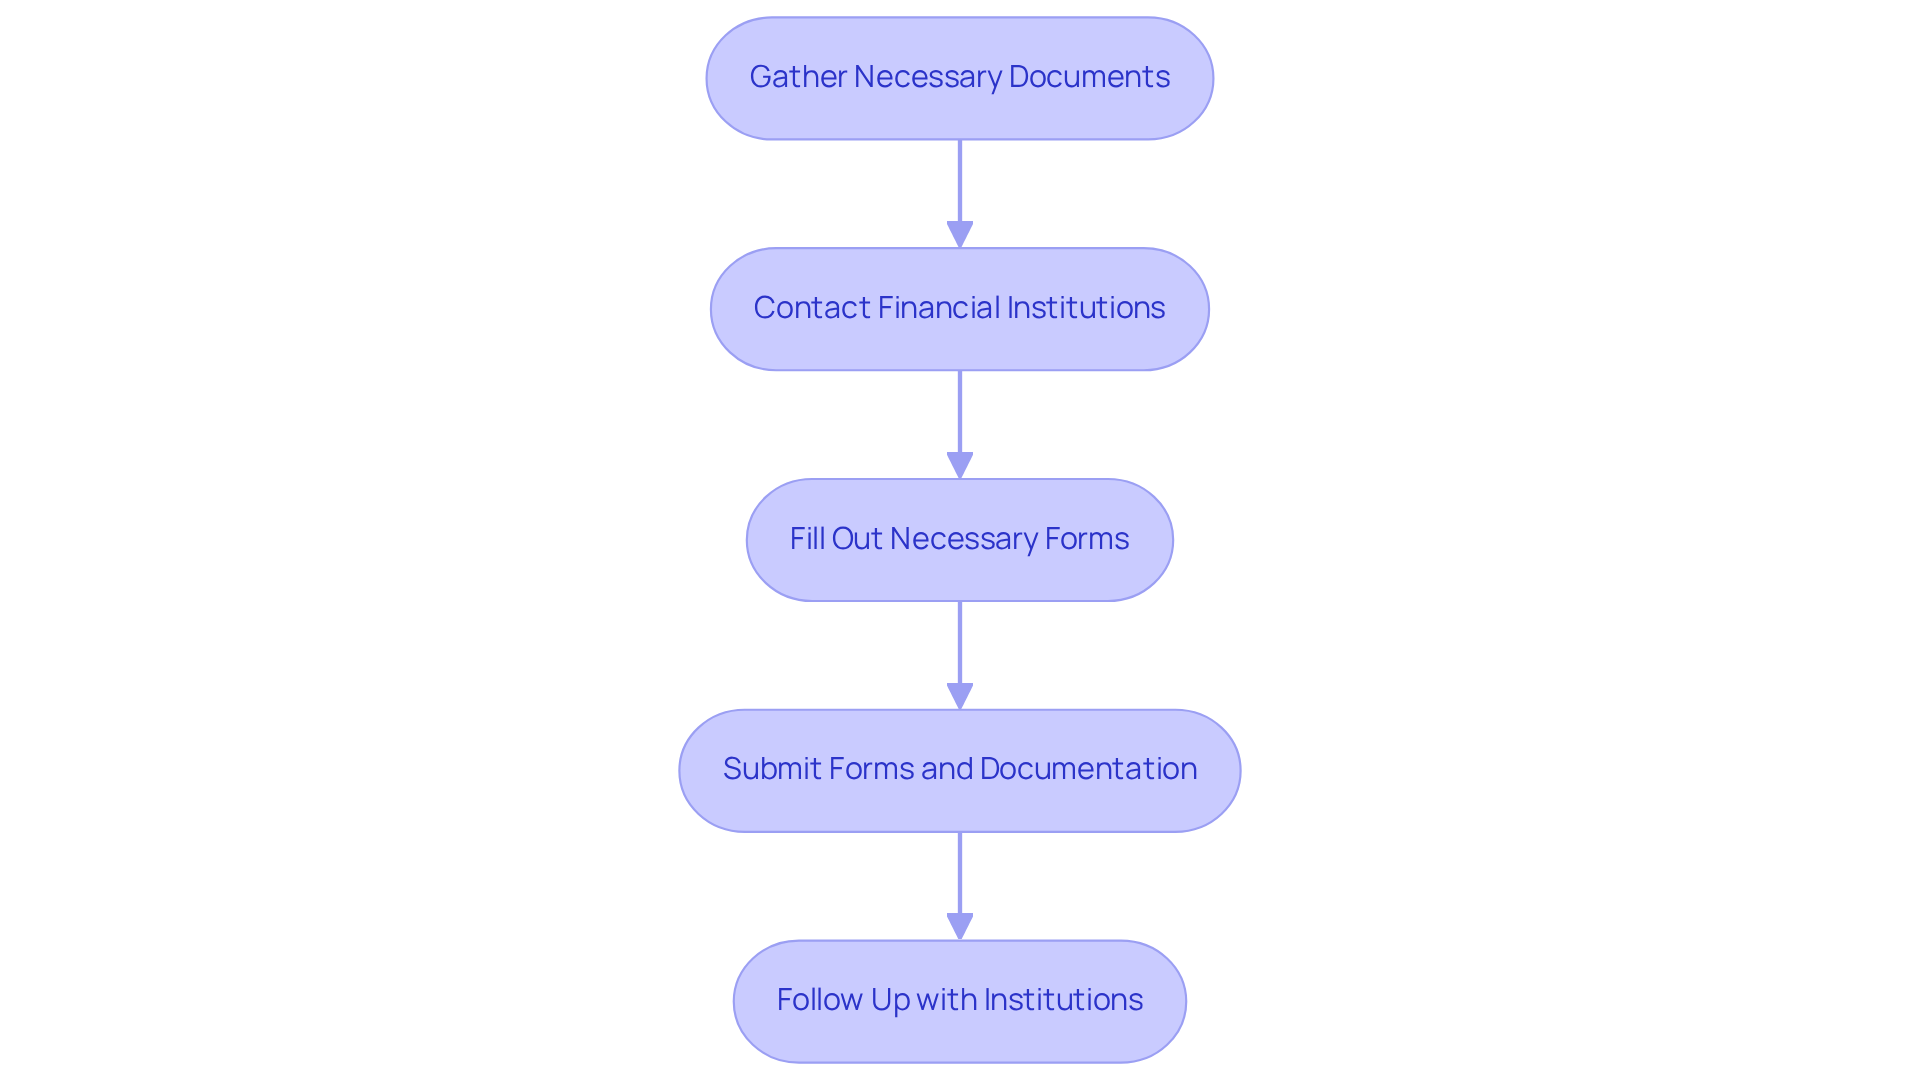
Start by gently gathering the necessary documents you’ll need during this time. This includes financial documents like life insurance policies and retirement accounts, along with the original certified death certificate and proof of identity for the new recipient.
Next, reach out to the financial institutions with compassion, letting them know about your loss. They can provide specific procedures for changing beneficiary after death. Many brokerages have specialized teams ready to help you navigate this process smoothly, ensuring you avoid common pitfalls.
Take a moment to fill out the necessary forms, ensuring you provide accurate information for the new recipient. Remember, missing or incorrect documents can lead to delays, which can be especially stressful during this time.
Once you’ve completed the forms, kindly submit them along with the required documentation. If the account isn’t in the designated format, some brokerages may ask for certified letters from the Clerk of Superior Court, which could extend the transfer timeline.
Finally, follow up with the institutions to confirm that everything has been processed smoothly. Keep copies of all correspondence for your records. Delays can happen if paperwork is incomplete, so proactive communication is essential. Remember, life insurers typically take 14 to 60 days to pay out the death benefit after the claimant files the request, so patience may be necessary during this time. Taking these steps can ease your burden and ensure your loved one’s wishes are honored, allowing you to focus on healing.
Troubleshoot Common Issues
Navigating the process of changing beneficiary after death can feel overwhelming, especially when unexpected challenges arise.
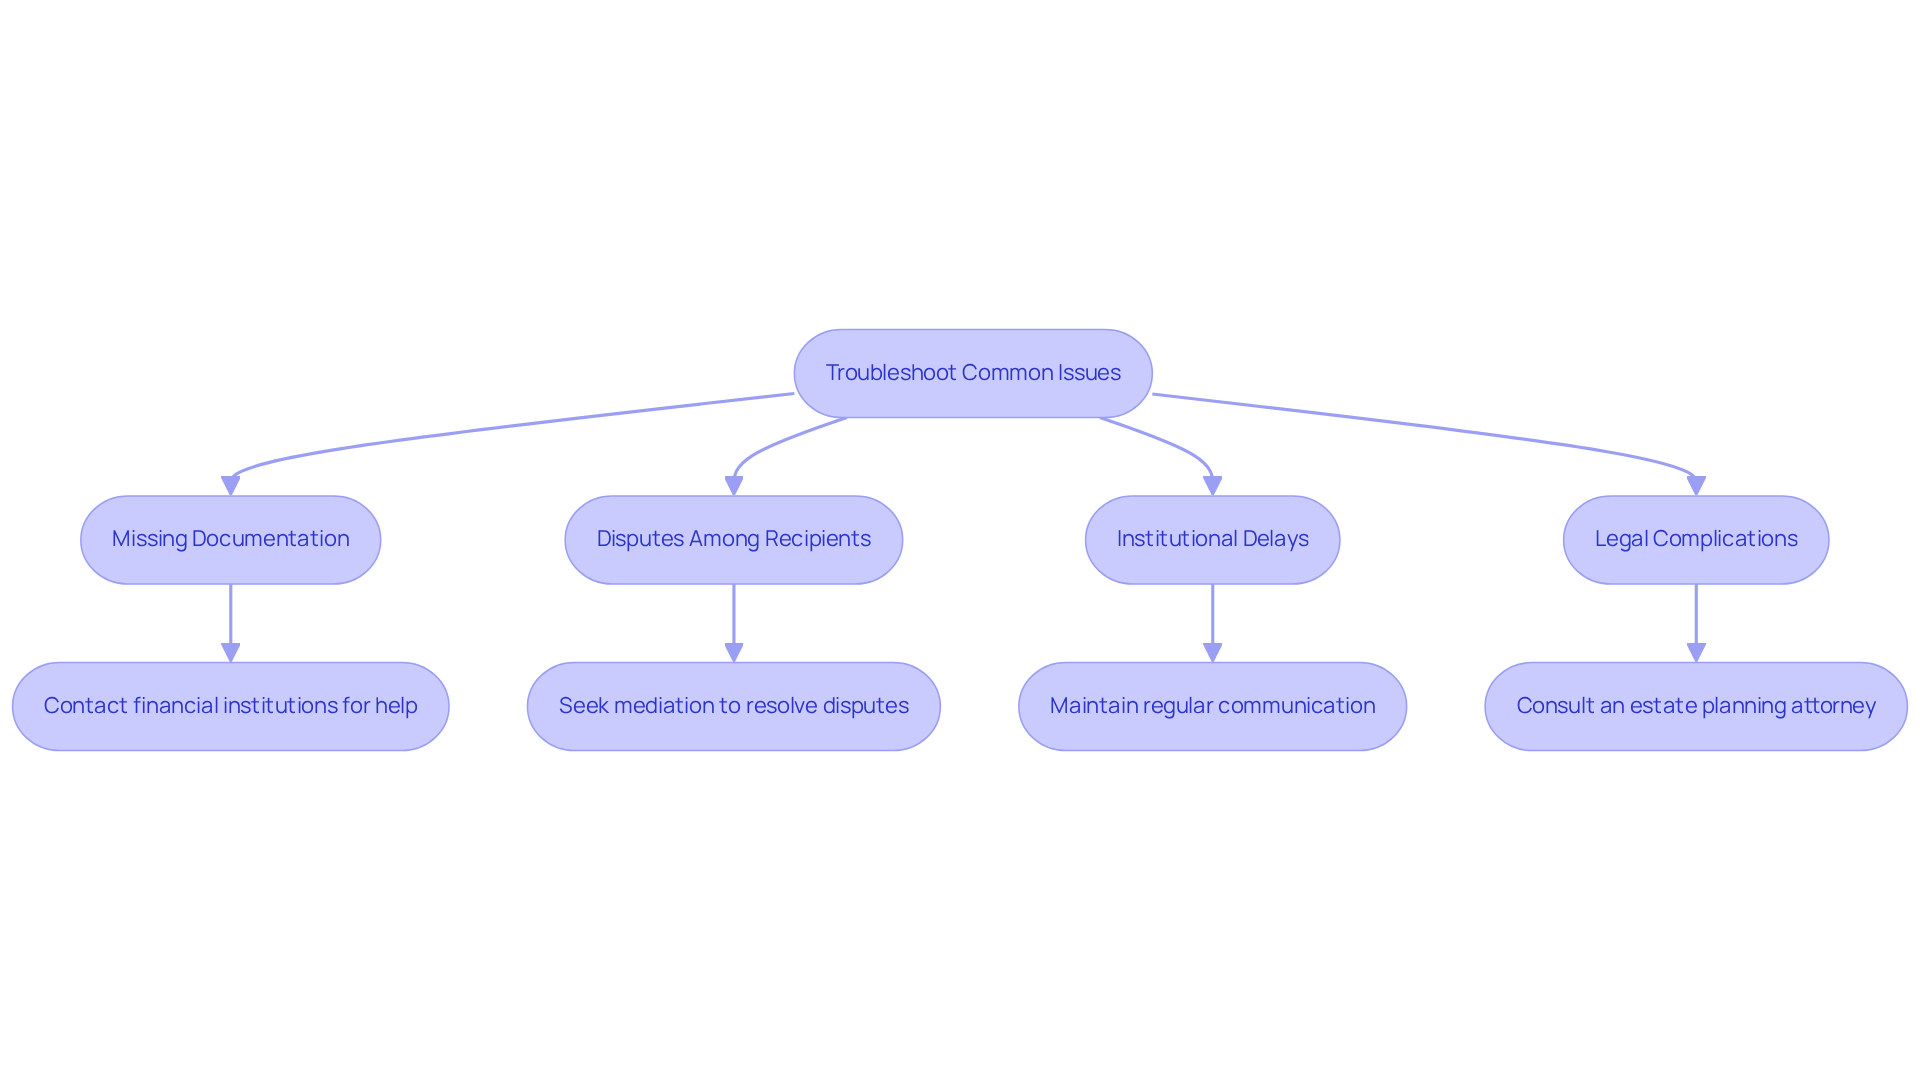
- Missing Documentation: If you can’t find the necessary documents, don’t hesitate to contact the financial institutions for help. They often have alternative methods for verifying the deceased’s identity, which can help facilitate the process. Many families find that missing documentation can complicate this process, but you’re not alone in facing this challenge.
- Disputes Among Recipients: Conflicts may arise when several recipients disagree on changes. In such cases, mediation can be a valuable tool to resolve disputes amicably. According to expert Tiffany Johns, seeking mediation can help ensure that all parties express their concerns and work towards a mutually acceptable solution. Notably, 66 percent of people involved in sibling disputes over a will reported no regrets after the dispute ended, highlighting the potential for resolution.
- Institutional Delays: Imagine waiting weeks for a response while trying to manage your family’s needs. To mitigate this, maintain regular communication with the financial institutions to ensure your request is prioritized and to stay informed about any necessary steps. Addressing these delays early can prevent escalation and preserve family relationships during what is often a challenging time.
- Legal Complications: If the deceased’s will or trust conflicts with the beneficiary designations, consulting an estate planning attorney is crucial. They can help navigate the complexities of the situation and ensure compliance with legal requirements, protecting the interests of all parties involved. The emotional and financial drain of unresolved disputes can be significant, making professional guidance essential.
Additionally, regularly updating estate documents is vital to reflect current wishes and life circumstances, which can change over time. Taking proactive steps now can save you from future heartache and stress.
Conclusion
Navigating the aftermath of losing a loved one can feel overwhelming, especially when it comes to financial matters. It’s so important to know how to change beneficiary designations after losing someone you love. This ensures their wishes are honored and helps keep your family’s financial future secure.
But don’t worry; you can navigate this process with clarity and compassion by following some simple steps. Key insights from this guide emphasize the importance of:
- Regularly reviewing beneficiary designations
- Understanding the legal implications
- Being prepared with the necessary documentation
By taking proactive measures, like consulting with financial institutions and seeking mediation in case of disputes, families can avoid common pitfalls and ensure a smoother transition during a challenging time.
Beneficiary designations are truly important in estate planning, as they help protect your loved ones and ensure your wishes are honored. Engaging with a fiduciary advisor like Bright Advisers can provide the necessary support and guidance to navigate these complexities, ensuring that families make informed decisions that align with their values and goals. Taking this step not only honors their memory but also secures your family’s future, allowing you to focus on healing together.
For personalized assistance, reach out to Bright Advisers at hello@brightadvisers.com or call (714) 987-2967 to explore how to safeguard your family’s financial legacy.
Frequently Asked Questions
What are beneficiary designations?
Beneficiary designations are legal directives that determine who inherits your assets upon your death. They are essential for various financial accounts, including life insurance policies, retirement accounts, and bank accounts.
What is the difference between a primary beneficiary and a contingent beneficiary?
A primary beneficiary is the first individual designated to receive the asset, while a contingent beneficiary receives the asset if the primary beneficiary is unable to do so.
Why is it important to name a contingent beneficiary?
Naming a contingent beneficiary is important because if you do not designate one, your assets may revert to your estate, potentially causing unnecessary stress for your family during a difficult time.
When should I review and potentially change my beneficiary designations?
It is advisable to review and revise your beneficiary designations every three to five years or after major life events such as marriage, divorce, or the birth of a child.
What can happen if beneficiary designations contradict a will?
Changes to beneficiary designations that contradict the directives outlined in a will can lead to legal conflicts among family members.
How can changing beneficiary designations impact my family’s financial security?
Regularly updating beneficiary designations helps ensure that your assets are distributed according to your current preferences, simplifying the transition for your loved ones and safeguarding their financial future.
What is the mission of Bright Advisers regarding wealth management?
Bright Advisers aims to help families make wise wealth decisions and preserve wealth across generations by providing tailored wealth management solutions.
What commitment does Bright Advisers make regarding fees and conflicts of interest?
Bright Advisers emphasizes fiduciary duty and transparency, ensuring there are no hidden fees or conflicts of interest, and offers customizable monthly fees to suit clients’ needs.
List of Sources
- Understand Beneficiary Designations
- Out-of-date beneficiary designations are a common and costly mistake (https://cnbc.com/2018/04/16/out-of-date-beneficiary-designations-are-a-common-and-costly-mistake.html)
- The Importance of Keeping Beneficiary Designations Up to Date – Lewicky, OConnor, Hunt, Meiser (https://lohmlaw.com/blog/the-importance-of-keeping-beneficiary-designations-up-to-date)
- Beneficiary Designations: Why You Should Regularly Update Them (https://jerseyelderlawyers.com/beneficiary-designations-why-you-should-regularly-update-them)
- Primary vs. Contingent Beneficiary: What You Need to Know (https://westernsouthern.com/life-insurance/primary-vs-contingent-beneficiary)
- Understanding The Effects Beneficiary Designations Have On Your Estate Plan – Sprouse Shrader Smith (https://sprouselaw.com/understanding-the-effects-beneficiary-designations-have-on-your-estate-plan)
- Review Legal Considerations
- What to Know About the Cost of Probate | Sheela Stark Law Group, APC (https://lawyerstark.com/blog/what-everyone-should-know-about-the-cost-of-probate)
- California Probate Filings: Future Projections and Trends – DRS Law (https://drs-law.com/2025/05/01/california-probate-filings-future-projections-and-trends)
- How Long Does Probate Usually Take in California? (https://cpwalkerlaw.com/blog/long-probate-take-california)
- Why Is Probate Taking So Long? Expert Insights (https://theheritancelawyers.com/blog/why-is-this-probate-taking-so-long)
- Follow Step-by-Step Instructions
- Aflac Supplemental Insurance (https://aflac.com/resources/life-insurance/how-long-does-life-insurance-take-to-pay-out.aspx)
- How long does it usually take for a brokerage to transfer assets to beneficiaries, and are there tax forms I should expect? – NC (https://piercelaw.com/news/probate-question-and-answer/how-long-does-it-usually-take-for-a-brokerage-to-transfer-assets-to-beneficiaries-and-are-there-tax-forms-i-should-expect-nc)
- How to Update Your Beneficiaries After Major Life Changes | Hailey-Petty Law Firm, PLLC (https://haileypettylaw.com/update-your-beneficiaries)
- How Long Does a Life Insurance Claim Take to Pay Out? (https://jasonturchin.com/blog/how-long-does-a-life-insurance-claim-take-to-pay-out)
- Period It Takes for Beneficiaries to Get Notified After Death | Nelson Law Firm (https://nelsonlawfirmbluffton.com/blog/period-it-takes-for-beneficiaries-to-get-notified-after-death)
- Troubleshoot Common Issues
- Most Common Reasons for Beneficiary Disputes of an Estate Plan (https://hackardlaw.com/blog/most-common-reasons-for-beneficiary-disputes-of-an-estate-plan)
- 10 important statistics about sibling estate disputes | Lesser Lutrey Pasquesi & Howe, LLP (https://llphlegal.com/blog/2018/05/10-important-statistics-about-sibling-estate-disputes)
- How to Handle Conflicts Between Beneficiaries During Trust Administration | Middle Tennessee Family Law (https://middletennesseefamilylaw.com/blog/how-to-handle-conflicts-between-beneficiaries-during-trust-administration)
- Family Disputes and Estate Planning: How to Prevent and Resolve Conflicts Among Beneficiaries (https://bmcestateplanning.com/blog/family-disputes-and-estate-planning)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading