

Overview
Navigating the complexities of estate planning can feel overwhelming, especially for young parents. Imagine if you could ensure your family’s future while bypassing the burdens of probate and maintaining privacy. The article offers a comprehensive, step-by-step guide on naming a trust as the beneficiary of a brokerage account, highlighting the significant benefits that trusts can provide in your financial journey.
As you explore this important topic, consider the common challenges that arise when establishing and managing trusts. It’s crucial to understand that you don’t have to face these complexities alone. Consulting with legal and tax experts can make all the difference, ensuring that your trust is set up correctly and effectively.
We’re here for you, ready to support you in making informed decisions that align with your family’s values and priorities. Together, we can navigate this journey, ensuring that your loved ones are protected and that your wishes are honored. Take the first step today towards securing your family’s future.
Key Highlights:
- A fiduciary arrangement involves a trustee managing resources for a beneficiary’s benefit, allowing for bypassing probate and maintaining privacy.
- Types of trusts include revocable (modifiable during the grantor’s lifetime) and irrevocable (permanent with stronger asset protection).
- Key terms: Grantor (creator of the trust), Trustee (manager of the trust), Beneficiary (recipient of the assets).
- 30% of estate planners use trusts to enhance financial security for clients.
- Trusts can simplify asset distribution and protect sensitive information from public scrutiny.
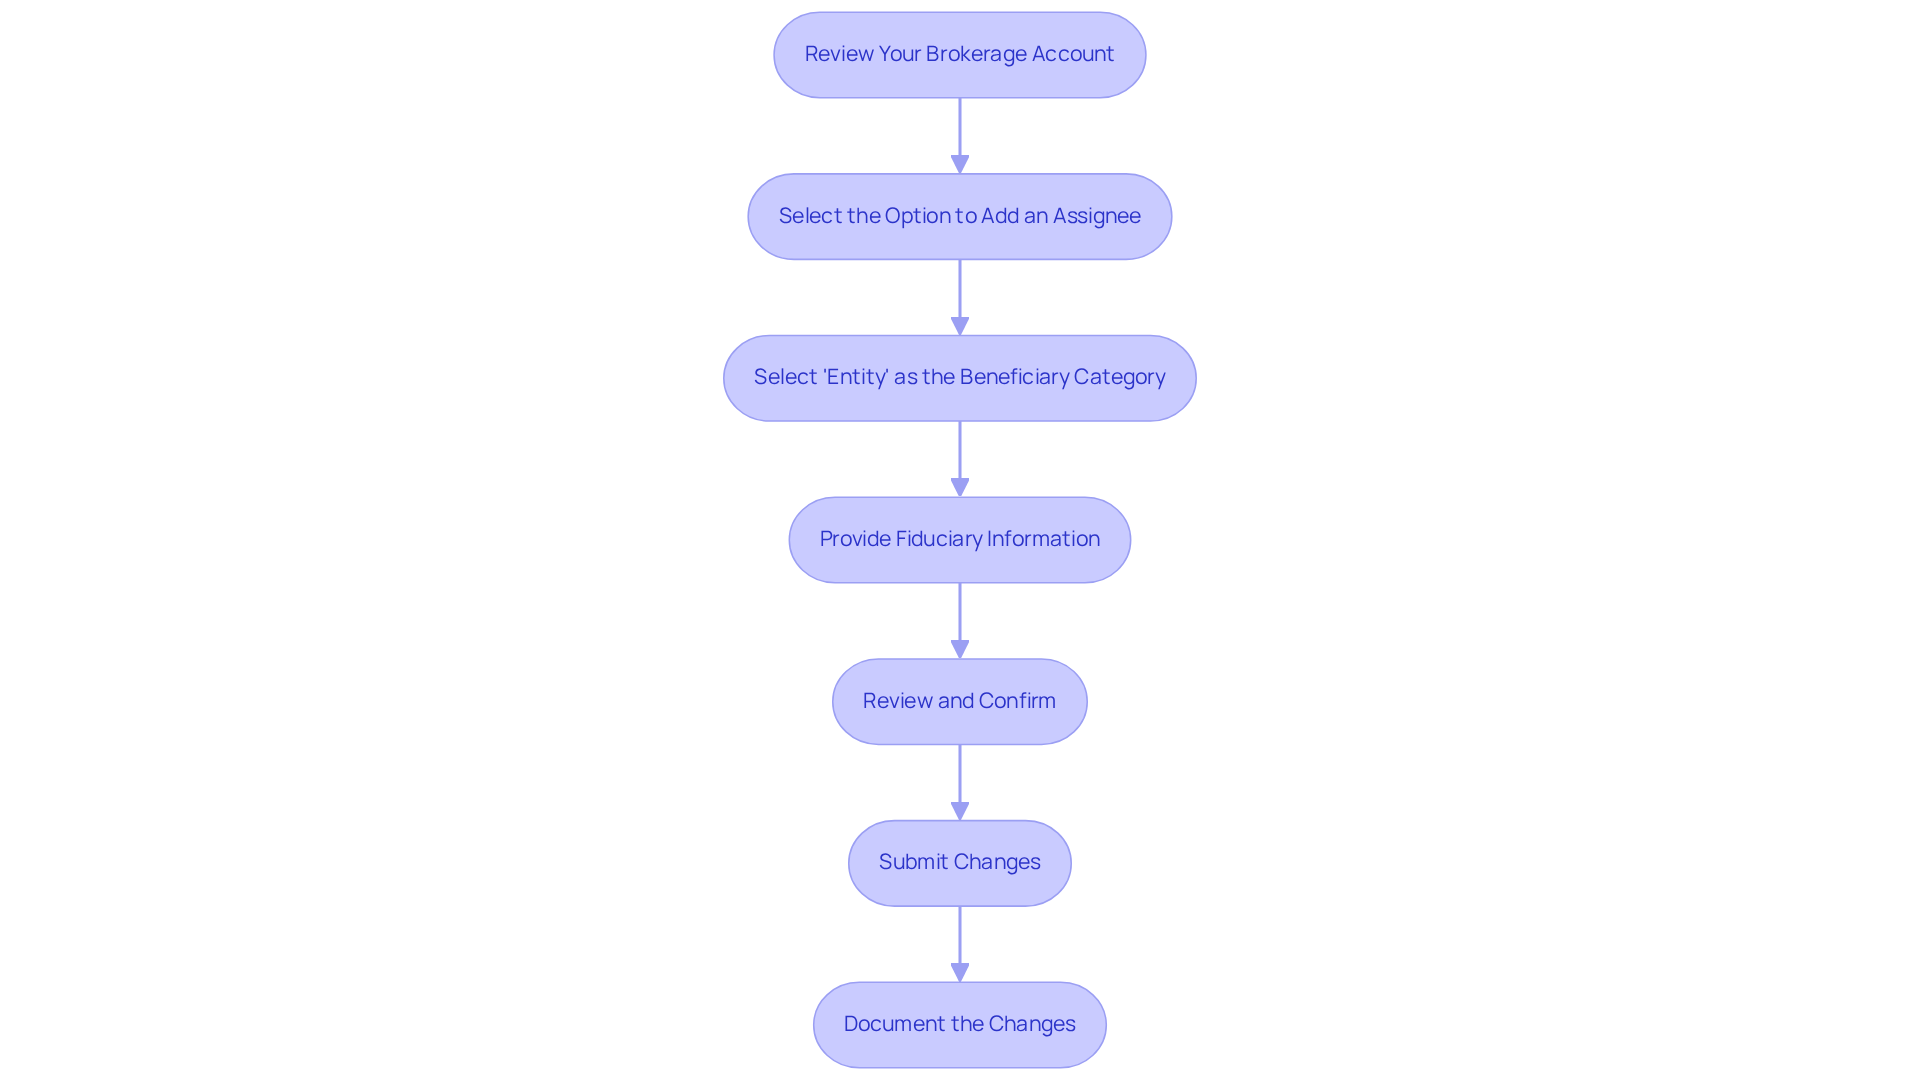
- Steps to name a trust as a beneficiary include reviewing the brokerage account, selecting ‘Entity’ as the beneficiary, and confirming the information.
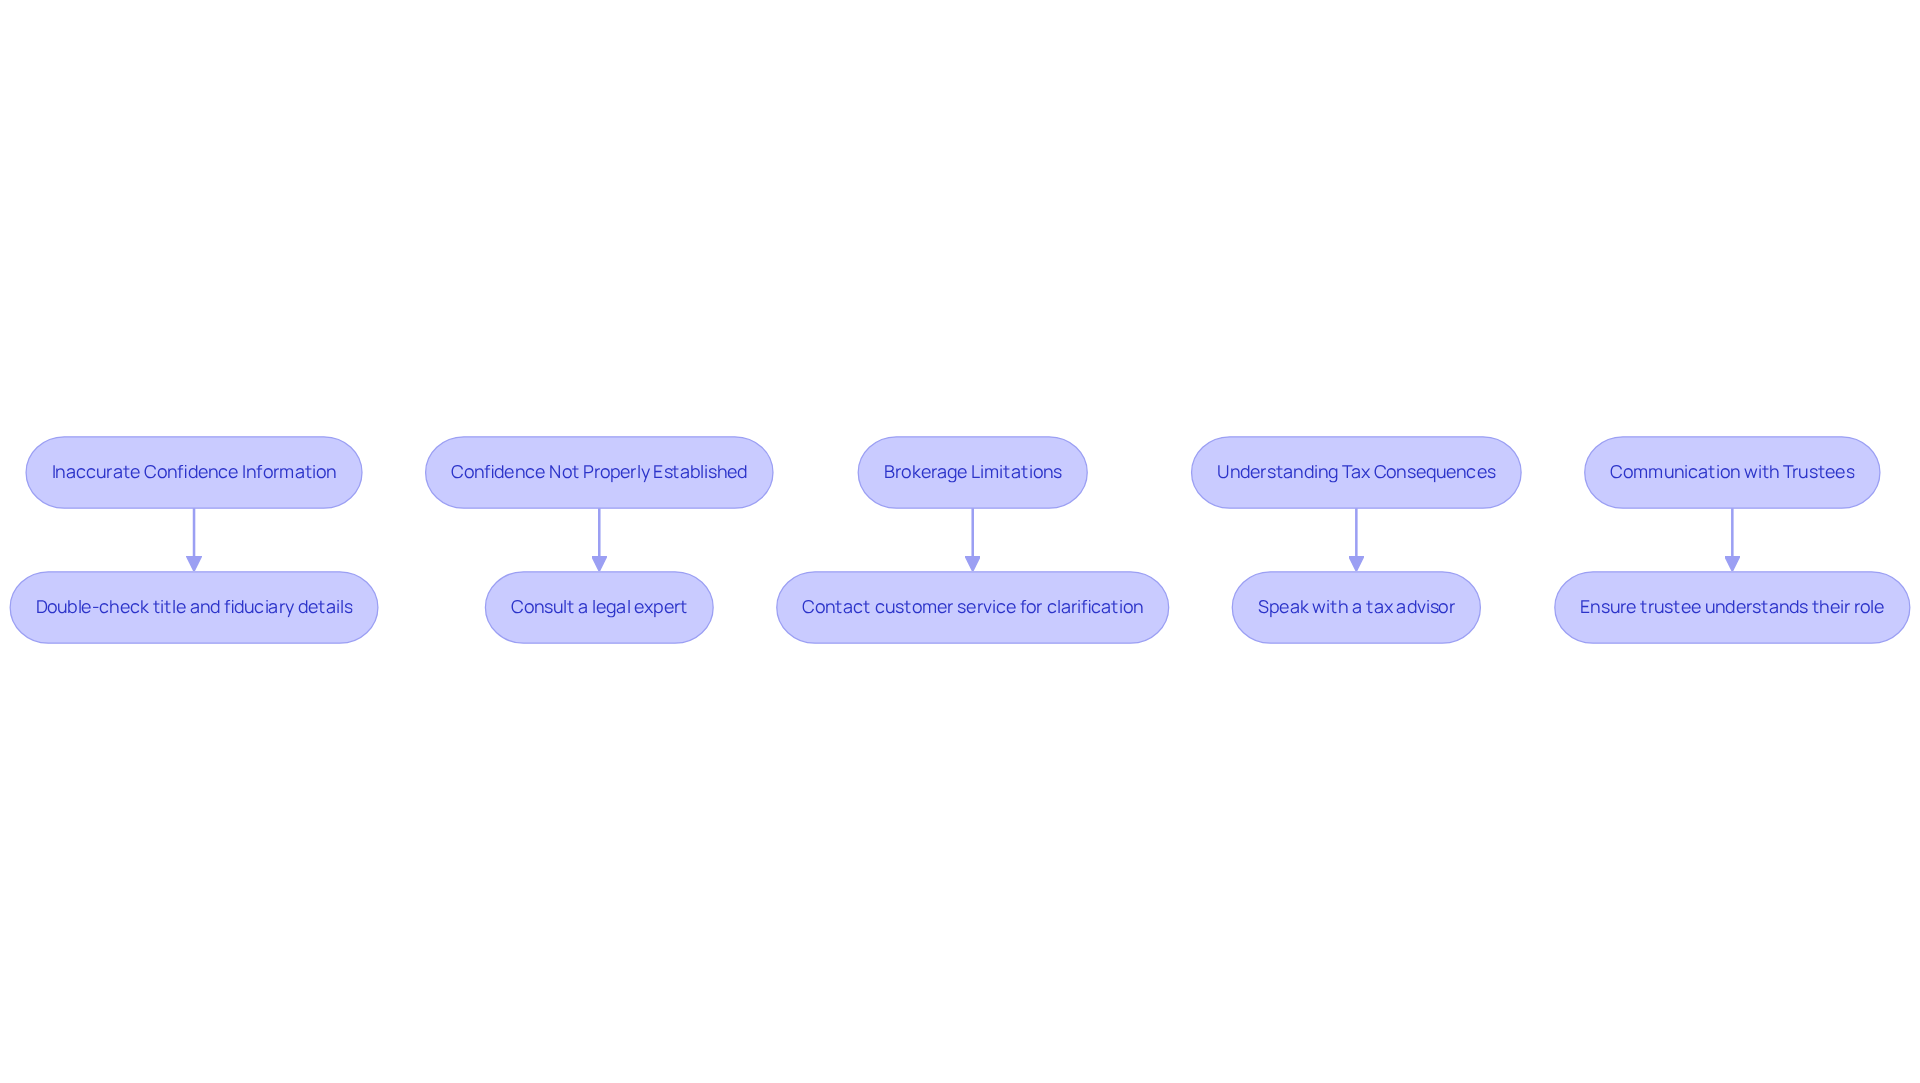
- Common challenges include inaccurate information, improperly established trusts, brokerage limitations, tax implications, and communication with trustees.
- Consulting legal and tax experts is advisable to navigate the complexities of trusts and ensure proper execution.
- Only 32% of Americans had an estate plan in 2024, highlighting the need for proactive updates to beneficiary designations.
Introduction
Naming a trust as the beneficiary of a brokerage account can significantly streamline the transfer of assets, offering both privacy and control over distribution. Imagine the peace of mind that comes from knowing your wishes will be honored long after you are gone. This strategic move not only helps bypass the often lengthy probate process but also ensures that your family’s needs are prioritized.
However, navigating the complexities of trust types, legal requirements, and potential pitfalls can feel overwhelming. It’s important to understand that you are not alone in this journey. Many individuals grapple with these challenges, and it’s perfectly normal to seek guidance. Together, we can explore the best options to secure your family’s financial future.
By taking the step to name a trust, you are making a choice that reflects your love and care for your family. This decision can safeguard their interests and provide them with the support they need during difficult times. Remember, we’re here for you, ready to help you navigate this process with compassion and understanding.
Understand the Basics of Trusts and Beneficiaries
A fiduciary is a legal setup in which a trustee oversees resources for the advantage of an intended recipient. Imagine naming a trust as the beneficiary of a brokerage account; it provides considerable benefits, such as the capability to bypass probate, preserve privacy, and exert enhanced control over resource distribution. This method ensures that your properties are conveyed seamlessly and effectively after your departure, without the delays and expenses related to probate court.
It’s important to understand the different types of trusts—like revocable and irrevocable trusts—as each type has distinct implications for control and taxation. For instance, revocable arrangements allow changes during the grantor’s lifetime, while irrevocable arrangements offer stronger protection of resources but cannot be modified once set up.
Becoming acquainted with important terms such as:
- Grantor (the individual who establishes the arrangement)
- Trustee (the person or organization overseeing the arrangement)
- Beneficiary (the individual or entity obtaining the assets)
is crucial for navigating this process effectively. Many individuals are recognizing the advantages of these arrangements in estate planning. Recent statistics indicate that approximately 30% of estate planners now employ them to enhance their clients’ financial security.
Real-world instances emphasize how estates can bypass probate and maintain confidentiality. For example, families have effectively utilized estate plans to avoid the lengthy probate process, enabling quick access to funds for their loved ones. Moreover, estates can create a level of privacy that recipient assignments alone cannot supply, protecting sensitive financial details from public examination.
Integrating a trust into your estate strategy not only simplifies asset allocation but also enables you to determine the conditions under which your heirs receive their inheritance. This ensures that your desires are respected long after you have departed. Together, we can navigate this journey and ensure your family’s future is secure.

Follow the Step-by-Step Process to Name a Trust as Beneficiary
-
Review Your Brokerage Account: Begin by logging into your brokerage account and navigating to the section for designating recipients, usually located under account settings or profile.
-
Select the Option to Add an Assignee: Look for an option labeled ‘Assignee Designation’ or similar, which allows you to add or edit assignees.
-
Select ‘Entity’ as the Beneficiary Category: When prompted, choose ‘Entity’ from the list of beneficiary categories, indicating that you plan to designate a legal entity instead of a person.
-
Provide Fiduciary Information: Enter the fiduciary’s name, establishment date, and the trustee’s contact information. Ensure the name of the arrangement matches precisely as it appears in the document to avoid any discrepancies.
-
Review and Confirm: Carefully double-check all entered information for accuracy. Verify that the trust is correctly set up and that you have the authority to name it as a recipient.
-
Submit Changes: Save or submit your changes. You may get a confirmation email or alert stating that the recipient assignment has been successfully updated.
-
Document the Changes: Maintain a record of the revised recipient assignment for your personal files. Notify your trustee regarding the assignment to ensure they are aware of their responsibilities.
Imagine if you could secure your family’s future with ease. Current trends suggest that naming trust as beneficiary of brokerage account can provide families with more control over resource distribution and help in circumventing probate, which can be a prolonged and expensive procedure. For instance, the estates of Michael Jackson and Prince highlight the importance of appropriate recipient assignments to ensure that assets are allocated in accordance with the wishes of the deceased.
Financial advisors stress that frequently revising recipient assignments is essential, since situations can alter considerably over time. As Brian Dobbis observed, ‘Appointing a fiduciary recipient is both tricky and complicated, with potential unintended consequences if not implemented and executed according to the myriad of IRS rules and regulations.’
Additionally, with only 32% of Americans having an estate plan in 2024, it is essential for families to take proactive steps in updating their beneficiary designations. By following these steps, families can effectively secure their financial legacy and ensure their loved ones are taken care of. Together, we can navigate this journey, aligning with Bright Advisers’ commitment to providing tailored wealth management solutions that empower financial security and freedom.
Furthermore, Bright Advisers emphasizes minimal fund fees, ensuring that families can maximize their investments while receiving comprehensive services such as estate planning and tax strategies, which are crucial for effective wealth management.
Identify Common Challenges and Solutions in Trust Naming
-
Inaccurate Confidence Information: It’s easy to make mistakes when entering confidence details. To avoid any confusion, please double-check the title name and fiduciary details against the official document. Your peace of mind matters.
-
Confidence Not Properly Established: Before you designate a confidence as a recipient, ensure it is legally formed. If you have any doubts about the arrangement’s status, consider consulting with a legal expert. We’re here to help you navigate these complexities.
-
Brokerage Limitations: Some brokerages may have specific criteria or limitations regarding naming trust as beneficiary of brokerage account. If you’re unsure, don’t hesitate to reach out to customer service for clarification. Knowing your options can ease your worries.
-
Understanding Tax Consequences: It’s important to comprehend the tax implications of designating a fund as a recipient. A conversation with a tax advisor can help ensure you understand any potential tax consequences for your estate and its recipients. Let’s work together to secure your family’s future.
-
Communication with Trustees: Make sure your trustee is fully informed about their role and responsibilities as a beneficiary. Clear communication is crucial for the smooth execution of the trust’s terms, ensuring that your intentions are honored. Remember, you don’t have to do this alone; support is available.
Conclusion
Naming a trust as the beneficiary of a brokerage account is a thoughtful step that brings a host of benefits. It allows you to bypass probate, maintain privacy, and have greater control over how your assets are distributed. This approach not only simplifies the transfer of wealth but also ensures that your wishes are honored long after you are gone. Understanding the different types of trusts and the roles of grantors, trustees, and beneficiaries is essential for effective estate planning.
As you navigate this process, it’s important to follow key steps to designate a trust as a beneficiary. From reviewing your brokerage account to ensuring that all information is accurate, each step plays a vital role in facilitating a smooth transition of assets. Common challenges, such as inaccuracies in trust details and brokerage limitations, can be addressed with practical solutions, helping you overcome these hurdles with confidence.
The significance of proactive estate planning cannot be emphasized enough. By taking the initiative to name a trust as a beneficiary, you can secure your family’s financial future and steer clear of the complications often associated with probate. Embracing this step empowers families to take control of their financial legacy and underscores the importance of informed decision-making in wealth management.
Imagine the peace of mind that comes from knowing your loved ones are protected and your wishes will be honored. Together, we can navigate this journey, ensuring your family’s future is secured and your values are preserved.
Frequently Asked Questions
What is a fiduciary in the context of trusts?
A fiduciary is a legal setup where a trustee oversees resources for the benefit of an intended recipient.
What are the benefits of naming a trust as the beneficiary of a brokerage account?
Naming a trust as a beneficiary allows you to bypass probate, preserve privacy, and exert enhanced control over resource distribution, ensuring properties are conveyed seamlessly after your departure.
What are the main types of trusts?
The main types of trusts are revocable and irrevocable trusts. Revocable trusts allow changes during the grantor’s lifetime, while irrevocable trusts offer stronger protection of resources but cannot be modified once established.
Who are the key individuals involved in a trust?
The key individuals involved in a trust are the grantor (the individual who establishes the arrangement), the trustee (the person or organization overseeing the arrangement), and the beneficiary (the individual or entity obtaining the assets).
How common are trusts in estate planning?
Approximately 30% of estate planners now employ trusts to enhance their clients’ financial security.
How do trusts help in bypassing probate?
Trusts allow estates to bypass the lengthy probate process, enabling quick access to funds for beneficiaries and maintaining confidentiality of sensitive financial details.
What control does a trust provide over inheritance distribution?
A trust enables you to determine the conditions under which your heirs receive their inheritance, ensuring that your desires are respected long after you have departed.
List of Sources
- Understand the Basics of Trusts and Beneficiaries
- Annual Statistical Report on the Social Security Disability Insurance Program, 2023 (https://ssa.gov/policy/docs/statcomps/di_asr)
- Why Retitling Non-Retirement Investment Accounts Into a Trust Beats Relying on Beneficiary Designations Alone (https://laurenrioslaw.com/why-retitling-non-retirement-investment-accounts-into-a-trust-beats-relying-on-beneficiary-designations-alone)
- Monthly Statistical Snapshot, August 2025 (https://ssa.gov/policy/docs/quickfacts/stat_snapshot)
- Follow the Step-by-Step Process to Name a Trust as Beneficiary
- Alarming Estate Planning Statistics (https://financialsense.com/blog/21022/alarming-estate-planning-statistics)
- Naming a Trust as a Beneficiary – Ethos Capital Advisors (https://ethoscapitaladvisors.com/naming-a-trust-as-a-beneficiary)
- Estate Planning Statistics to Read Before Writing Your Will (https://legalzoom.com/articles/estate-planning-statistics)
- Naming a Trust as a Beneficiary of Retirement Accounts | Lord Abbett (https://lordabbett.com/en-us/financial-advisor/insights/retirement-planning/naming-a-trust-as-a-beneficiary-of-retirement-accounts.html)
- Estate Administration – Step-by-Step Guide and Timeline | The Maryland People’s Law Library (https://peoples-law.org/estate-administration-step-step-guide-and-timeline)
- Identify Common Challenges and Solutions in Trust Naming
- Pitfalls and Solutions For Beneficiary Designations When Your Kids are Minors | Bryant & O’Connor Law Firm (https://bryantoconnor.com/blog/2023/11/pitfalls-and-solutions-for-beneficiary-designations-when-your-kids-are-minors)
- Beneficiary Designation Mistakes to Avoid | U.S. Bank (https://usbank.com/wealth-management/financial-perspectives/trust-and-estate-planning/common-beneficiary-designation-mistakes-to-avoid.html)
- Understanding the Influence and Impact of Stakeholder Engagement in Patient-centered Outcomes Research: a Qualitative Study – PMC (https://pmc.ncbi.nlm.nih.gov/articles/PMC8993962)
- Naming a Special Needs Trust as Beneficiary of Your IRA or Retirement Plan – Special Needs Alliance (https://specialneedsalliance.org/the-voice/naming-a-special-needs-trust-as-beneficiary-of-your-ira-or-retirement-plan-3)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading