

Overview
Understanding the 5-year rule for transferring a Roth IRA can feel overwhelming, but it’s essential for your family’s financial health. This rule states that earnings from your Roth IRA can only be withdrawn tax-free after the account has been open for at least five years, beginning with your first contribution. Imagine if you could navigate this process without the worry of unexpected taxes or penalties on early withdrawals.
It’s crucial to grasp this rule to ensure you’re making the best financial decisions for your family.
- Detailed steps on how to transfer your IRA are available, emphasizing the importance of careful planning.
- Consulting with a financial advisor can provide you with the support you need to comply with regulations and make informed choices.
Together, we can navigate this journey, ensuring your family’s future is secure.
Key Highlights:
- Roth IRAs allow after-tax contributions, leading to tax-free growth and withdrawals under certain conditions.
- You can withdraw contributions at any time without penalties; however, earnings have a 5-year rule for tax-free withdrawals.
- Roth IRAs do not have required minimum distributions (RMDs), allowing for longer tax-free growth.
- For 2025, contribution limits are $7,000 for individuals under 50 and $8,000 for those 50 and older, subject to income limits.
- The 5-year rule starts on January 1 of the year of your first contribution; early withdrawals of earnings may incur taxes and penalties.
- Transferring a Roth IRA involves selecting a new custodian, opening a new account, contacting the current custodian, completing forms, and monitoring the transfer process.
- Consulting a financial advisor can provide tailored guidance and help navigate the complexities of Roth IRA transfers.
- Utilising online tools and staying informed about IRS guidelines can enhance understanding and compliance during the transfer process.
- Documenting all communications and being patient during the transfer process are crucial for a smooth transition.
Introduction
Understanding the intricacies of Roth IRAs can feel overwhelming, especially when you’re considering transferring accounts. The unique benefits of these retirement accounts—such as tax-free growth and withdrawals—are often clouded by the complexities of the 5-year rule that dictates when you can access your earnings. As you think about moving your Roth IRA to another broker, it’s vital to navigate this important rule, as it can significantly influence your financial strategy.
Imagine if you could ensure a seamless transfer while maximizing the advantages of this powerful retirement tool. What steps can you take to make this process easier? We’re here to support you every step of the way, helping you make informed decisions that align with your family’s financial goals.
Understand the Basics of Roth IRAs
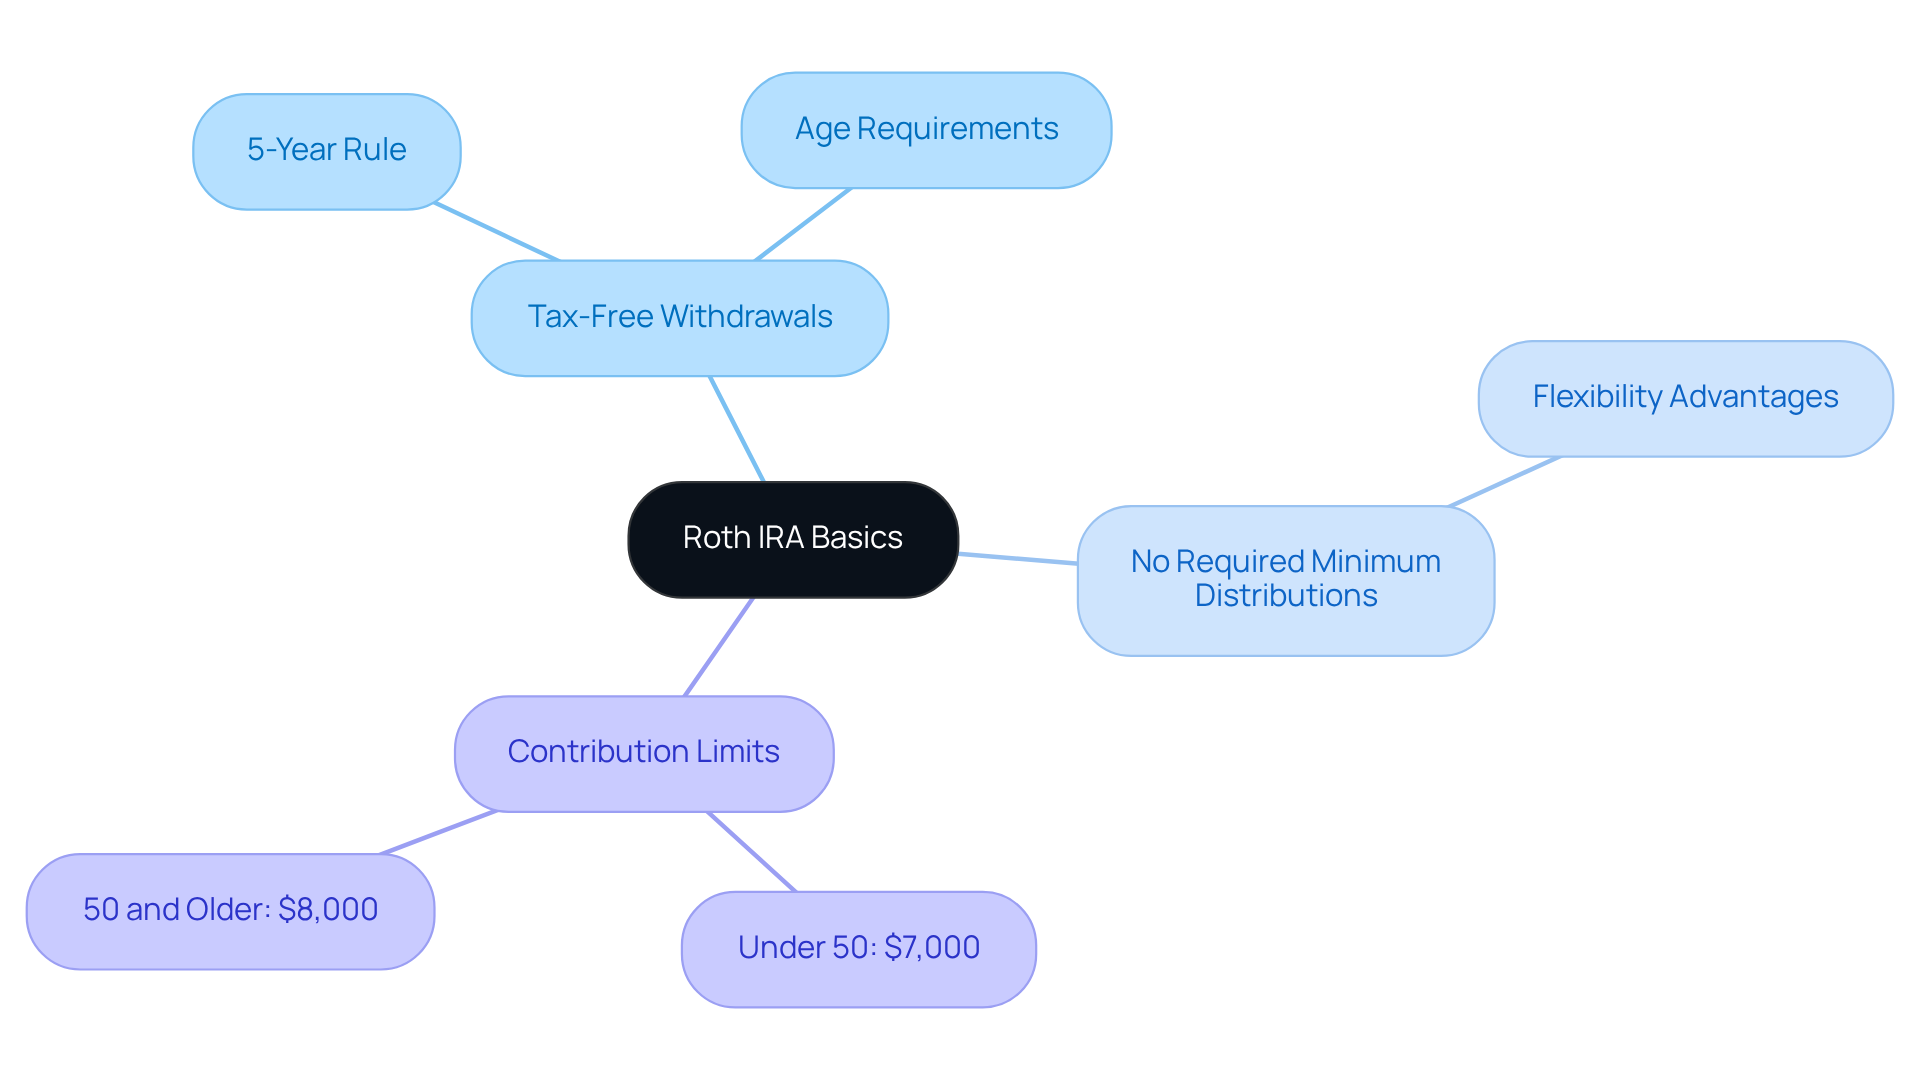
A specific type of individual retirement account allows you to contribute after-tax income, meaning you pay taxes on your contributions upfront. Imagine the peace of mind that comes with tax-free growth of your investments and tax-free withdrawals in retirement, provided certain conditions are met. Here are some key features to consider:
- Tax-Free Withdrawals: You can withdraw your contributions at any time without penalties or taxes. However, it’s important to understand the transfer Roth IRA to another broker 5-year rule, which states that earnings can only be withdrawn tax-free if the account has been open for at least five years and you are at least 59½ years old.
- No Required Minimum Distributions (RMDs): Unlike traditional IRAs, this type of IRA does not require you to take distributions at any age. This flexibility allows your investments to grow tax-free for longer, which can be a significant advantage for your family’s future.
- Contribution Limits: For 2025, the contribution limit is $7,000 for individuals under 50 and $8,000 for those 50 and older, subject to income limits.
Grasping these fundamentals can empower you to make informed decisions about your IRA and understand the significance of the transfer Roth IRA to another broker 5-year rule. Remember, we’re here for you as you navigate this journey toward securing your family’s financial future.
Navigate the Roth IRA 5-Year Rule
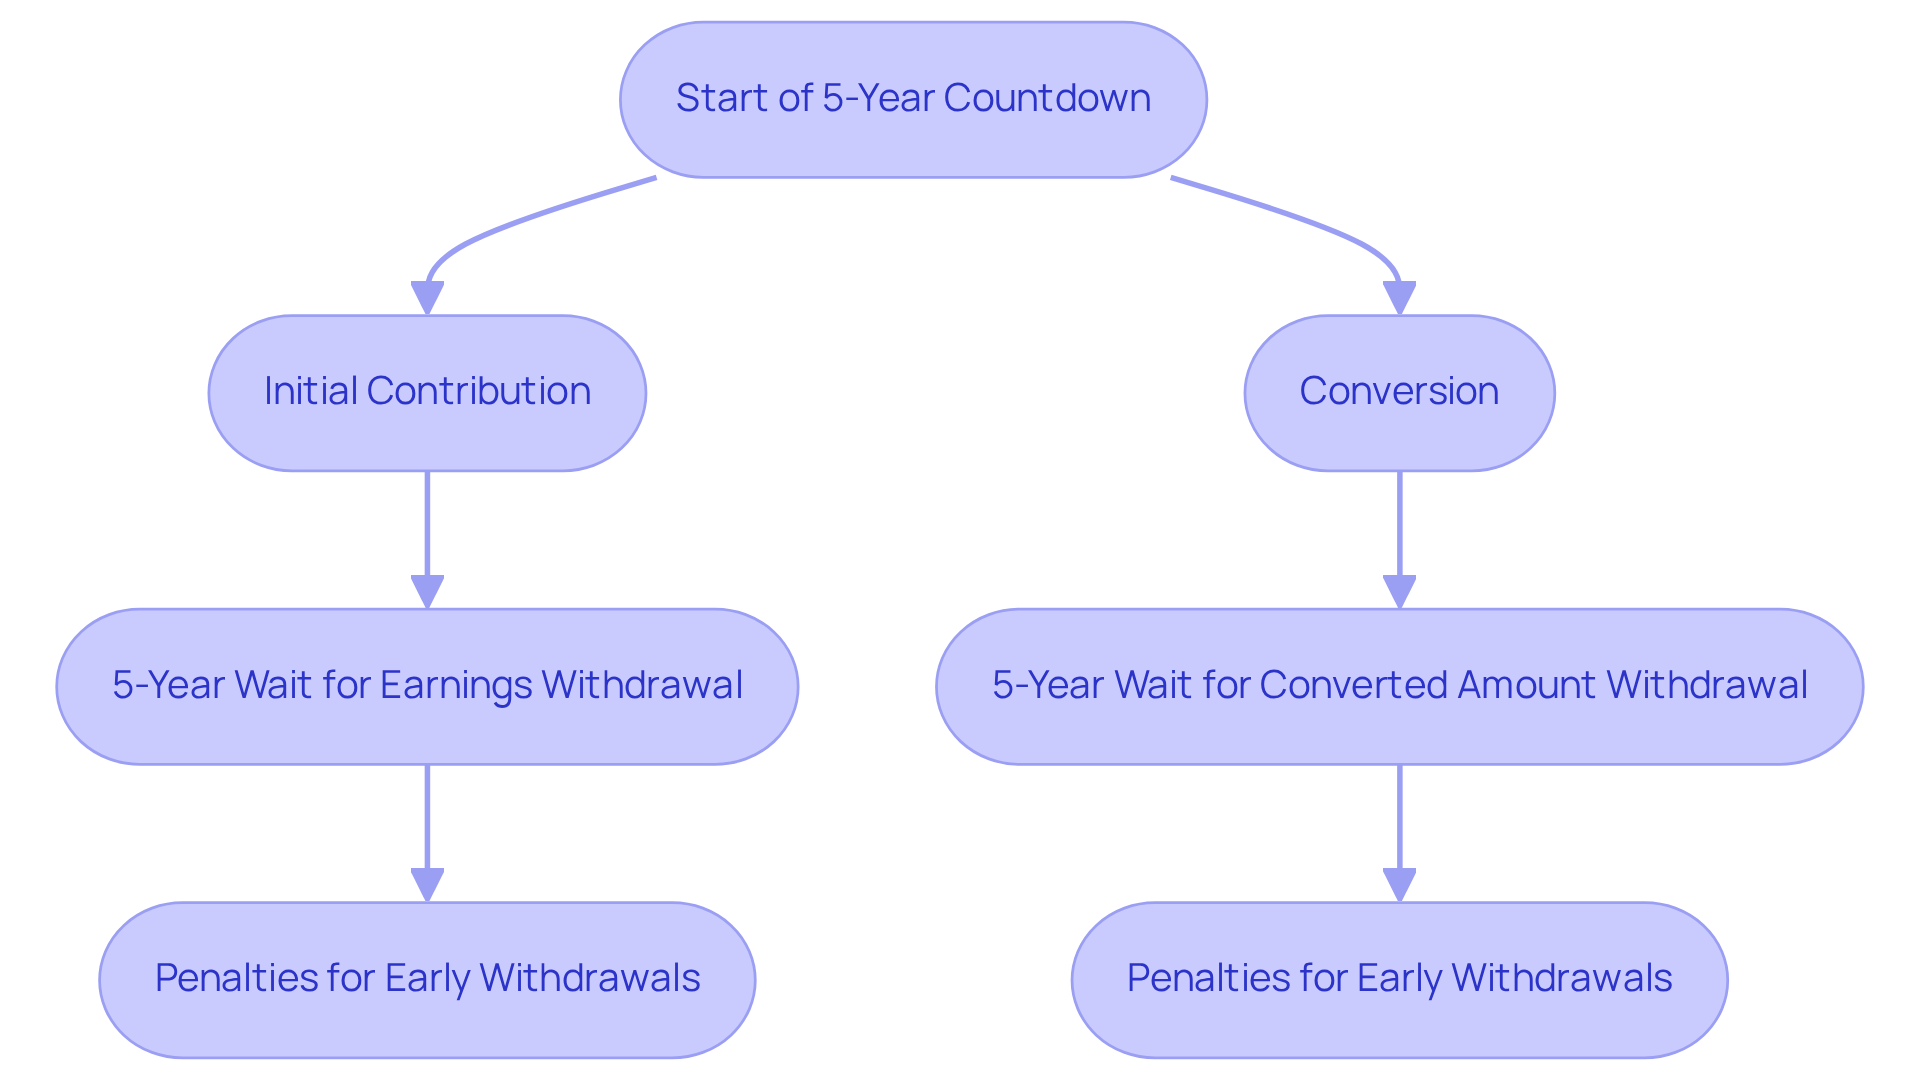
Navigating the world of individual retirement accounts can feel overwhelming, especially for young parents facing unexpected expenses. One crucial aspect to understand is the transfer Roth IRA to another broker 5-year rule, which specifies that you must wait five years from the start of the tax year in which you made your initial contribution before you can withdraw earnings without incurring taxes. Here’s what you need to know:
- Start Date: The 5-year countdown begins on January 1 of the year you first contribute to any Roth IRA, regardless of whether it’s the account you’re transferring.
- Withdrawals: If you withdraw earnings before this period ends, you could face taxes and a 10% penalty, unless you qualify for specific exceptions like disability or a first-time home purchase.
- Conversions: When moving funds from a traditional IRA to another type of IRA, a different 5-year rule applies. According to the transfer Roth IRA to another broker 5-year rule, you’ll need to wait five years from the conversion date to withdraw those converted amounts tax-free.
Understanding this rule is essential for effective budgeting, particularly for young families who may encounter unforeseen costs. It’s important to recognize that a significant number of early withdrawals from individual retirement accounts happen before the 5-year mark, often resulting in tax penalties.
Imagine if you could avoid these pitfalls and secure your family’s financial future. Consulting with a monetary advisor at Bright Advisers can provide valuable insights into these penalties and help you strategize effectively. Together, we can navigate this journey, ensuring personalized planning and tax optimization tailored to your unique needs. Remember, we’re here for you, ready to support you in achieving your family’s financial goals.
Follow Steps to Transfer Your Roth IRA
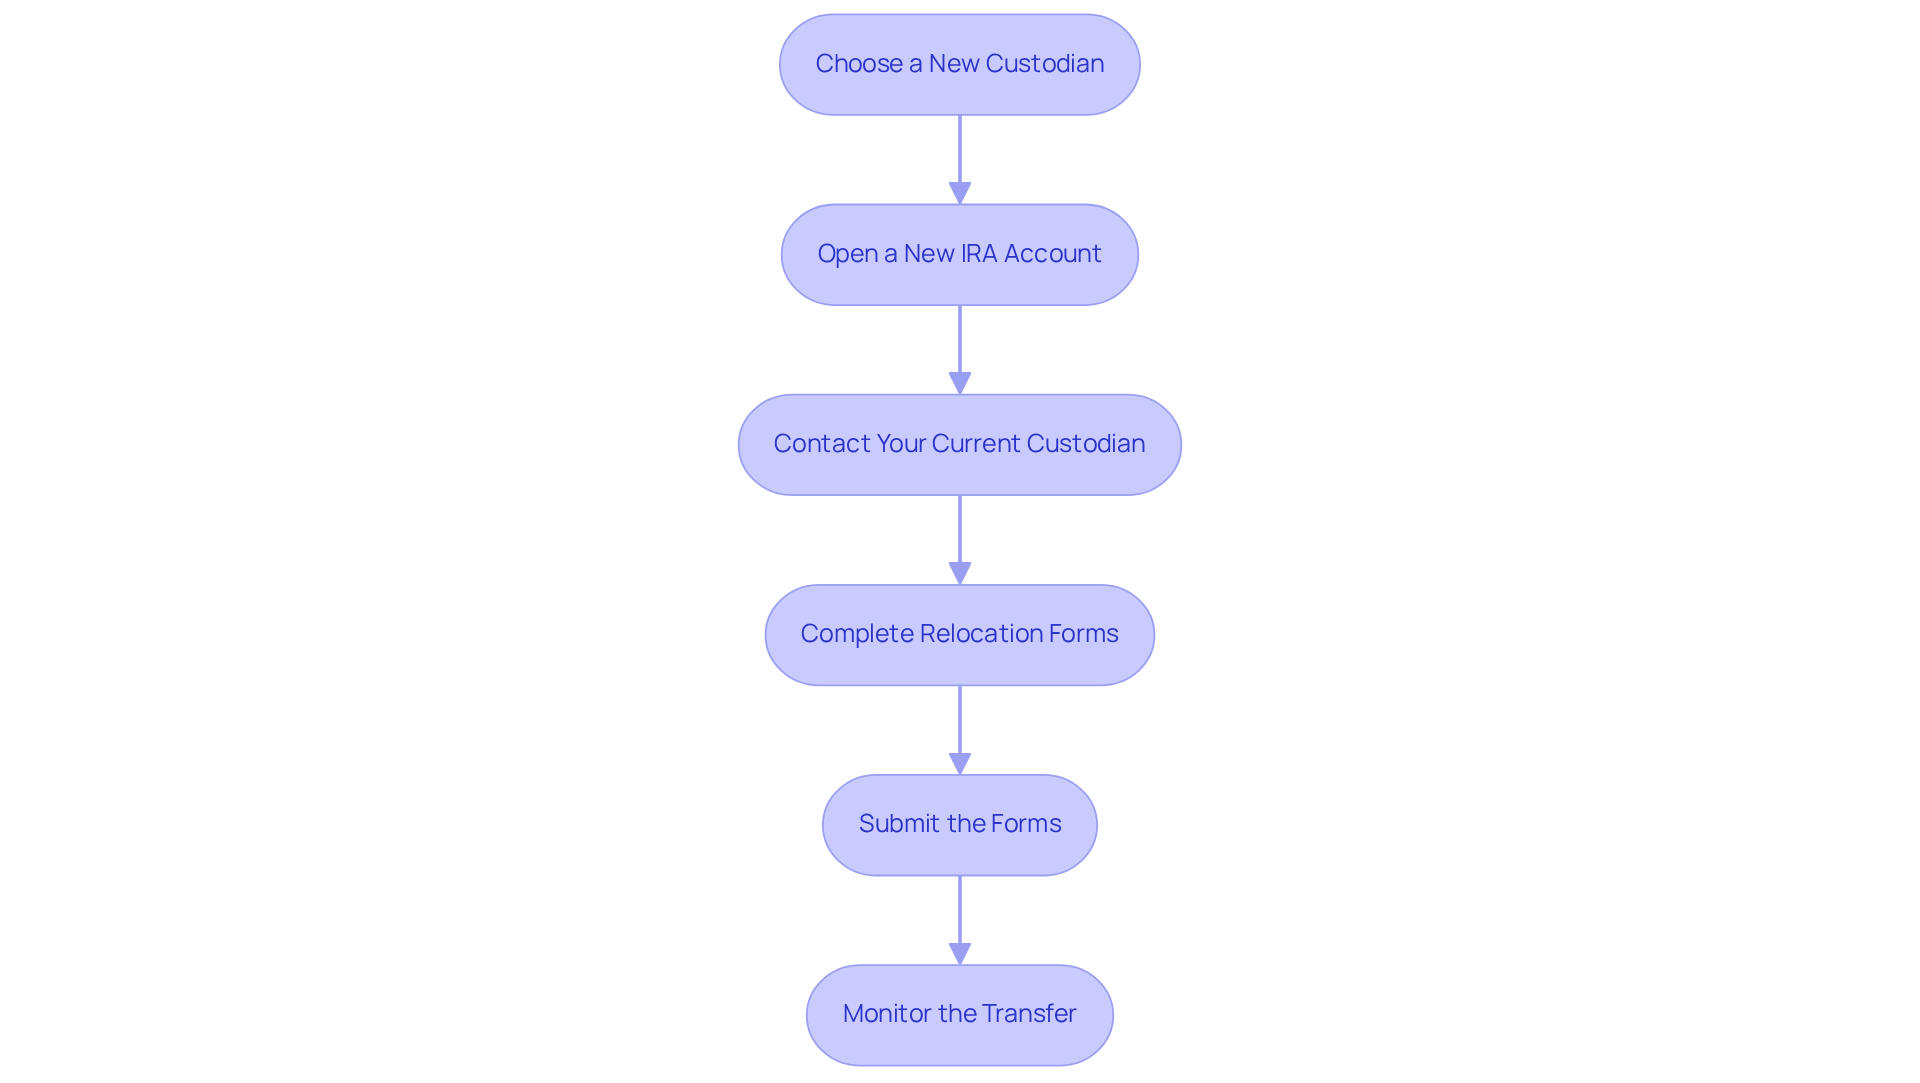
Transferring your Roth IRA can be a straightforward process if you follow these steps:
-
Choose a New Custodian: Take your time to research and select a financial institution that offers individual retirement accounts. Consider factors such as fees, investment options, and customer service. Remember, the fees related to IRA transfers can vary significantly, making it essential to evaluate your choices carefully. For example, the maximum contribution amount for a rollover IRA in 2025 is $7,000, which can help you understand potential costs involved.
-
Open a New IRA Account: After selecting a custodian, establish a new IRA account. Ensure that it is designated as a retirement account to maintain those valuable tax advantages.
-
Contact Your Current Custodian: Reach out to your current Roth IRA custodian and let them know about your intention to move your account. They will provide you with the necessary forms and instructions, guiding you through this process.
-
Complete Relocation Forms: Fill out the relocation forms provided by your new custodian. You may need to share details about your current account and the amount you wish to transfer. Financial planners often recommend double-checking all information to avoid any delays along the way.
-
Submit the Forms: Send the completed forms to your new custodian. They will begin the relocation process, which typically takes 1-2 weeks. To avoid any tax implications, it is advised to follow the transfer Roth IRA to another broker 5-year rule by opting for direct rollovers. The easiest approach for moving IRA funds is through a trustee-to-trustee or direct method, where institutions handle the transfer between accounts for you.
-
Monitor the Transfer: Keep an eye on both accounts to ensure the transfer is completed successfully. Confirm that all funds have been moved and that your new account is set up correctly. Engaging with a monetary advisor during this process can provide you with extra guidance and reassurance. As banking and retirement expert Javier Simon states, “Planning for retirement can be complex and overwhelming, but a monetary consultant can assist.”
By following these steps, you can ensure a smooth movement of your IRA without incurring taxes or penalties. Furthermore, consider seeking advice from a monetary consultant before making substantial transactions or complex retirement choices. Together, we can navigate this journey and help you make the most suitable decisions for your family’s financial future.
Access Resources and Tips for a Smooth Transfer
To facilitate a seamless transfer of your Roth IRA, consider these helpful tips and resources designed with your family’s needs in mind:
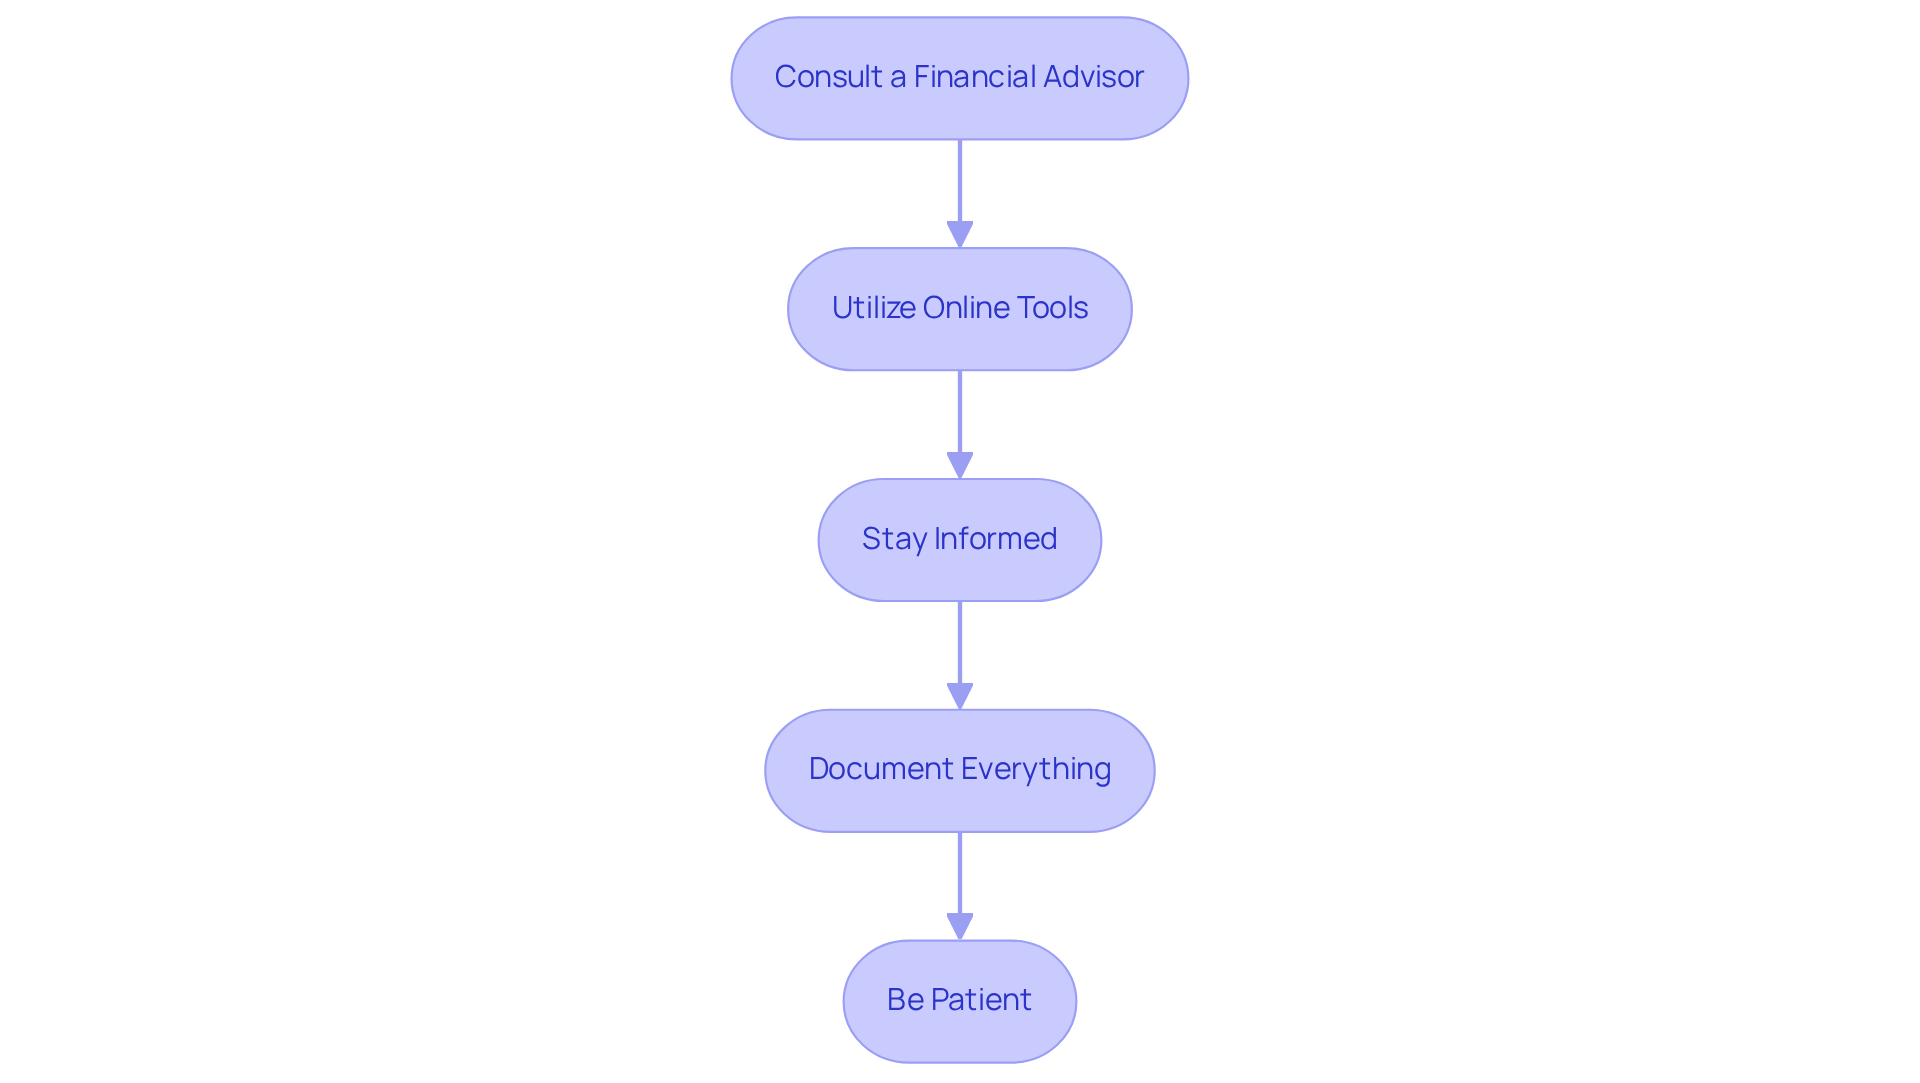
- Consult a Financial Advisor: Engaging with a financial advisor can provide tailored guidance specific to your family’s financial landscape. Imagine having someone by your side to help you navigate the complexities of the relocation process while ensuring compliance with the transfer Roth IRA to another broker 5-year rule and other IRS regulations. Advisors can also offer insights into any legacy fee-bearing mutual funds or ETFs you may hold. Keep in mind that hourly consultations typically cost between $200 to $400, so it’s wise to factor this into your planning.
- Utilize Online Tools: Many financial institutions offer online calculators and resources aimed at assisting you in evaluating the implications of transferring your IRA. These tools can clarify potential fees and tax consequences, making the process more transparent. It’s important to be mindful of any fees associated with your current funds, especially if they are higher than the minimal fund fees offered by other investment options.
- Stay Informed: Regularly reviewing IRS guidelines regarding Roth IRAs and movements can empower you. The IRS website is a valuable resource for comprehensive information and updates on retirement accounts, ensuring you remain compliant with current regulations. Remember to be aware of the once-per-year rollover rule, which limits you to one indirect rollover per 12 months across all your IRAs.
- Document Everything: Keeping meticulous records of all communications and documents related to your relocation is a crucial step. This practice can be invaluable in resolving any issues that may arise during the process, providing a clear trail of your actions. Additionally, ensure you adhere to the 60-day rule for completing the transfer of a Roth IRA to another broker while considering the 5-year rule to avoid unnecessary complications.
- Be Patient: Recognize that movements can take time. Allow for processing periods and proactively follow up with both custodians if you encounter any delays.
By leveraging these resources and strategies, you can confidently navigate the transfer process. Together, we can ensure that your Roth IRA continues to play a vital role in your family’s financial planning while being mindful of the fees associated with your investments.
Conclusion
Understanding the intricacies of transferring a Roth IRA is vital for anyone looking to secure their financial future. It’s important to recognize the significance of the 5-year rule, which governs the tax-free withdrawal of earnings. By grasping this rule, you can make informed decisions about your retirement savings and avoid unnecessary penalties.
Imagine if you knew exactly when the 5-year period begins and the implications of early withdrawals. Key insights highlight the steps involved in transferring an IRA to another broker, such as:
- Choosing the right custodian
- Ensuring compliance with IRS regulations
Utilizing resources like financial advisors and online tools can facilitate a smooth transfer process, making it more manageable for you.
Ultimately, navigating the complexities of Roth IRA transfers isn’t just about understanding rules and regulations; it’s about empowering families to make strategic financial decisions. By taking the time to educate yourself and seeking professional advice, you can optimize your retirement savings and secure a more stable financial future. Together, we can embrace the opportunity to take control of your retirement planning, ensuring that your investments continue to grow without the burden of unexpected tax consequences.
Frequently Asked Questions
What is a Roth IRA?
A Roth IRA is a specific type of individual retirement account that allows you to contribute after-tax income, meaning you pay taxes on your contributions upfront.
What are the tax benefits of a Roth IRA?
A Roth IRA offers tax-free growth of your investments and tax-free withdrawals in retirement, provided certain conditions are met.
Can I withdraw my contributions from a Roth IRA at any time?
Yes, you can withdraw your contributions at any time without penalties or taxes.
What is the 5-year rule for Roth IRAs?
The 5-year rule states that earnings can only be withdrawn tax-free if the account has been open for at least five years and you are at least 59½ years old.
Are there required minimum distributions (RMDs) for Roth IRAs?
No, unlike traditional IRAs, Roth IRAs do not require you to take distributions at any age, allowing your investments to grow tax-free for longer.
What are the contribution limits for Roth IRAs in 2025?
For 2025, the contribution limit is $7,000 for individuals under 50 and $8,000 for those 50 and older, subject to income limits.
List of Sources
- Navigate the Roth IRA 5-Year Rule
- Download – Rutgers, The State University of New Jersey (https://yumpu.com/en/document/view/40474073/download-rutgers-the-state-university-of-new-jersey)
- What Is The Roth IRA 5-Year Rule? | Carr, Riggs & Ingram (https://criadv.com/insight/roth-ira-five-year-rule)
- Individual Retirement Account (IRA) Ownership: Data and Policy Issues (https://congress.gov/crs-product/R46635)
- Follow Steps to Transfer Your Roth IRA
- Rollover IRAs (https://capitalgroup.com/retirement/participant/rollovers/iras.html)
- How Direct IRA Transfers Work (https://smartasset.com/retirement/how-direct-ira-transfers-work)
- Access Resources and Tips for a Smooth Transfer
- Key Steps for IRA Rollover with Remote Financial Advisors (https://investgrape.com/post/key-steps-for-ira-rollover-with-remote-financial-advisors)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading