

Overview
Understanding mutual fund fees is essential for your family’s financial future. Did you know that these fees, which include management costs, administrative expenses, and operational expenditures, can significantly impact your investment returns? Imagine if a 1% fee could reduce your portfolio’s value by nearly 30% over 30 years compared to lower-fee options. This is why it’s so important to be aware of these costs.
As parents, your financial goals are closely tied to your family’s well-being. Opting for low-cost mutual funds can enhance your long-term financial outcomes, helping you achieve the dreams you have for your children. Picture the possibilities: a secure future, the ability to invest in your child’s education, or even the chance to take that family vacation you’ve always wanted.
We’re here for you on this journey. By understanding and choosing the right investment options, you can make informed decisions that align with your family’s values. Together, we can navigate the complexities of financial planning, ensuring that you are set up for success. Remember, every small step you take today can lead to a brighter tomorrow for your family.
Key Highlights:
- Mutual fund fees include management costs, administrative expenses, and operational expenditures, typically expressed as a percentage of assets under management (AUM).
- A 1% fee can significantly reduce long-term capital growth, potentially lowering a portfolio’s value from $100,000 to $74,000 over 30 years due to compounding effects.
- Families should prioritise low-cost mutual funds to enhance their investment returns and achieve financial goals.
- The average expense ratio for actively managed funds is 0.65%, while passively managed index funds average just 0.05%.
- Key types of mutual fund fees include management charges (0.5%-2%), 12b-1 charges (0.25%-1%), load fees (front-end or back-end), and expense ratios, which reflect total operating costs.
- The average expense ratio for equity funds is approximately 0.40%, and for bond funds, it is around 0.38%, indicating a trend towards lower fees.
- A 1% expense ratio can decrease overall returns by nearly 30% over 30 years compared to a 0.25% expense ratio due to compounding.
- Investors are increasingly favouring low-cost options, with no-load investments growing from 46% in 2000 to 92% in 2024.
- Understanding mutual fund fees is essential for making informed investment decisions and maximising financial outcomes.
Introduction
Understanding the nuances of mutual fund fees is essential for you as you aim to secure your family’s financial future. These fees, often perceived as minor, can significantly erode your investment returns over time, especially if you’re planning for long-term goals.
Imagine if a seemingly small charge, like a 1% fee, could lead to a stark difference in your portfolio’s growth. This article delves into the various types of mutual fund fees, their implications on your returns, and strategies for minimizing costs.
Together, we can navigate this journey, empowering you to make informed investment decisions that align with your family’s aspirations.
Define Mutual Fund Fees and Their Importance
The average mutual fund fees encompass the expenses associated with managing a mutual investment, including management costs, administrative expenses, and other operational expenditures. Typically expressed as a percentage of the fund’s assets under management (AUM), these charges are deducted from the fund’s returns. It’s crucial for investors, especially young families, to grasp their implications. Imagine a seemingly small charge of 1%—over time, this can significantly hinder capital growth due to the compounding effect of fees. Over a 30-year investment period, this could mean the difference between a portfolio growing to $100,000 versus $74,000, illustrating how costs can dramatically impact net returns.
Families must remain vigilant about these costs, as they directly influence long-term financial goals. At Bright Advisers, we are committed to providing low charges, making wealth management more accessible for families. Recent trends show that investors are increasingly leaning towards low-cost options, with no-load investments experiencing gross sales growth from 46% in 2000 to 92% in 2024. This shift reflects a growing awareness of the importance of minimizing costs to enhance returns. Moreover, the average expense ratio for actively managed investment vehicles stands at 0.65%, while passively managed index portfolios boast significantly lower costs, averaging just 0.05% for equity index investments.
Real-world examples can shed light on how families might be affected by these charges. Consider a family investing in a high-fee investment; they may find their returns diminished compared to those investing in lower-cost alternatives. Experts emphasize that understanding average mutual fund fees is essential for making informed investment decisions. As the financial landscape evolves, families are encouraged to prioritize resources with lower expense ratios, enhancing their potential to achieve financial goals. Additionally, the notable decline in market share for bundled share classes—from 42% in 2005 to only 12% by the end of 2024—highlights a broader trend towards lower-cost financial options, underscoring the importance of fee awareness. Together, we can navigate this journey towards financial security.

Explore Different Types of Mutual Fund Fees
Understanding average mutual fund fees is essential for making informed investment choices, especially when considering your family’s financial future. Let’s explore the key types of fees that can influence your investment returns.
-
Management Charges are the fees paid to asset managers for overseeing your portfolio. These typically range from 0.5% to 2% of the assets under supervision (AUS). In 2025, the average management charge reflects this range, significantly impacting your overall performance. Imagine how these fees can affect your savings for your children’s education or family vacations.
-
12b-1 Charges are annual marketing costs that cover advertising expenses related to your investment. Usually ranging from 0.25% to 1%, these charges add to the total cost of ownership. It’s important to understand how average mutual fund fees can accumulate over time and potentially affect your family’s financial goals.
-
Load Fees are sales charges you might encounter when buying or selling shares in a mutual fund. These can be front-end loads, paid at purchase, or back-end loads, paid upon selling. Understanding average mutual fund fees is crucial, as they can directly influence the net returns on your investments, impacting your family’s financial stability.
-
Expense Ratios represent all operating costs of the investment vehicle, expressed as a percentage of its average net assets. The typical expense ratio for equity collective schemes has seen a decrease, from 0.43% in 2023 to 0.40% in 2024. This trend towards lower-cost options is encouraging for families seeking to maximize their investments.
By understanding these charges, you can make informed choices that align with your family’s values and financial priorities. Remember, we’re here for you, guiding you through this journey to ensure that your investments work hard for your family’s future.

Calculate and Compare Average Expense Ratios
Understanding the expense ratio of a mutual investment can feel daunting, but it’s quite simple: just divide the total annual expenses by the average mutual fund fees. For instance, if an investment pool has total expenses of $1 million and average net assets of $100 million, its expense ratio would be 1% (1,000,000 / 100,000,000). This metric is crucial for families, as average mutual fund fees directly impact their returns. At Bright Advisers, we genuinely care about minimizing average mutual fund fees across our models, allowing families to access wealth management solutions that enhance their financial security without the worry of high costs. However, it’s important to recognize that some clients may still hold legacy fee-bearing investment vehicles and ETFs, which can impact their overall investment costs.
Imagine if you could easily compare the average mutual fund fees across various investments. Families can utilize resources like Morningstar or the Investment Company Institute, which provide comprehensive data on average mutual fund fees across different categories. As of 2024, the average mutual fund fees for equity investment vehicles are approximately 0.40%, whereas bond investment products have average mutual fund fees of about 0.38%. This indicates a slight rise of 1 basis point. By examining these ratios, families can discover lower-cost alternatives that may significantly enhance their returns over time, ultimately supporting their financial goals.
It’s also reassuring to note that investment vehicle fees have been declining over the decades, driven by a growing demand for lower-cost products. This trend underscores the importance of comparing average mutual fund fees and expense ratios. Together, we can navigate this journey toward financial well-being, ensuring that your family can thrive without unnecessary financial burdens.

Analyze the Impact of Fees on Investment Returns
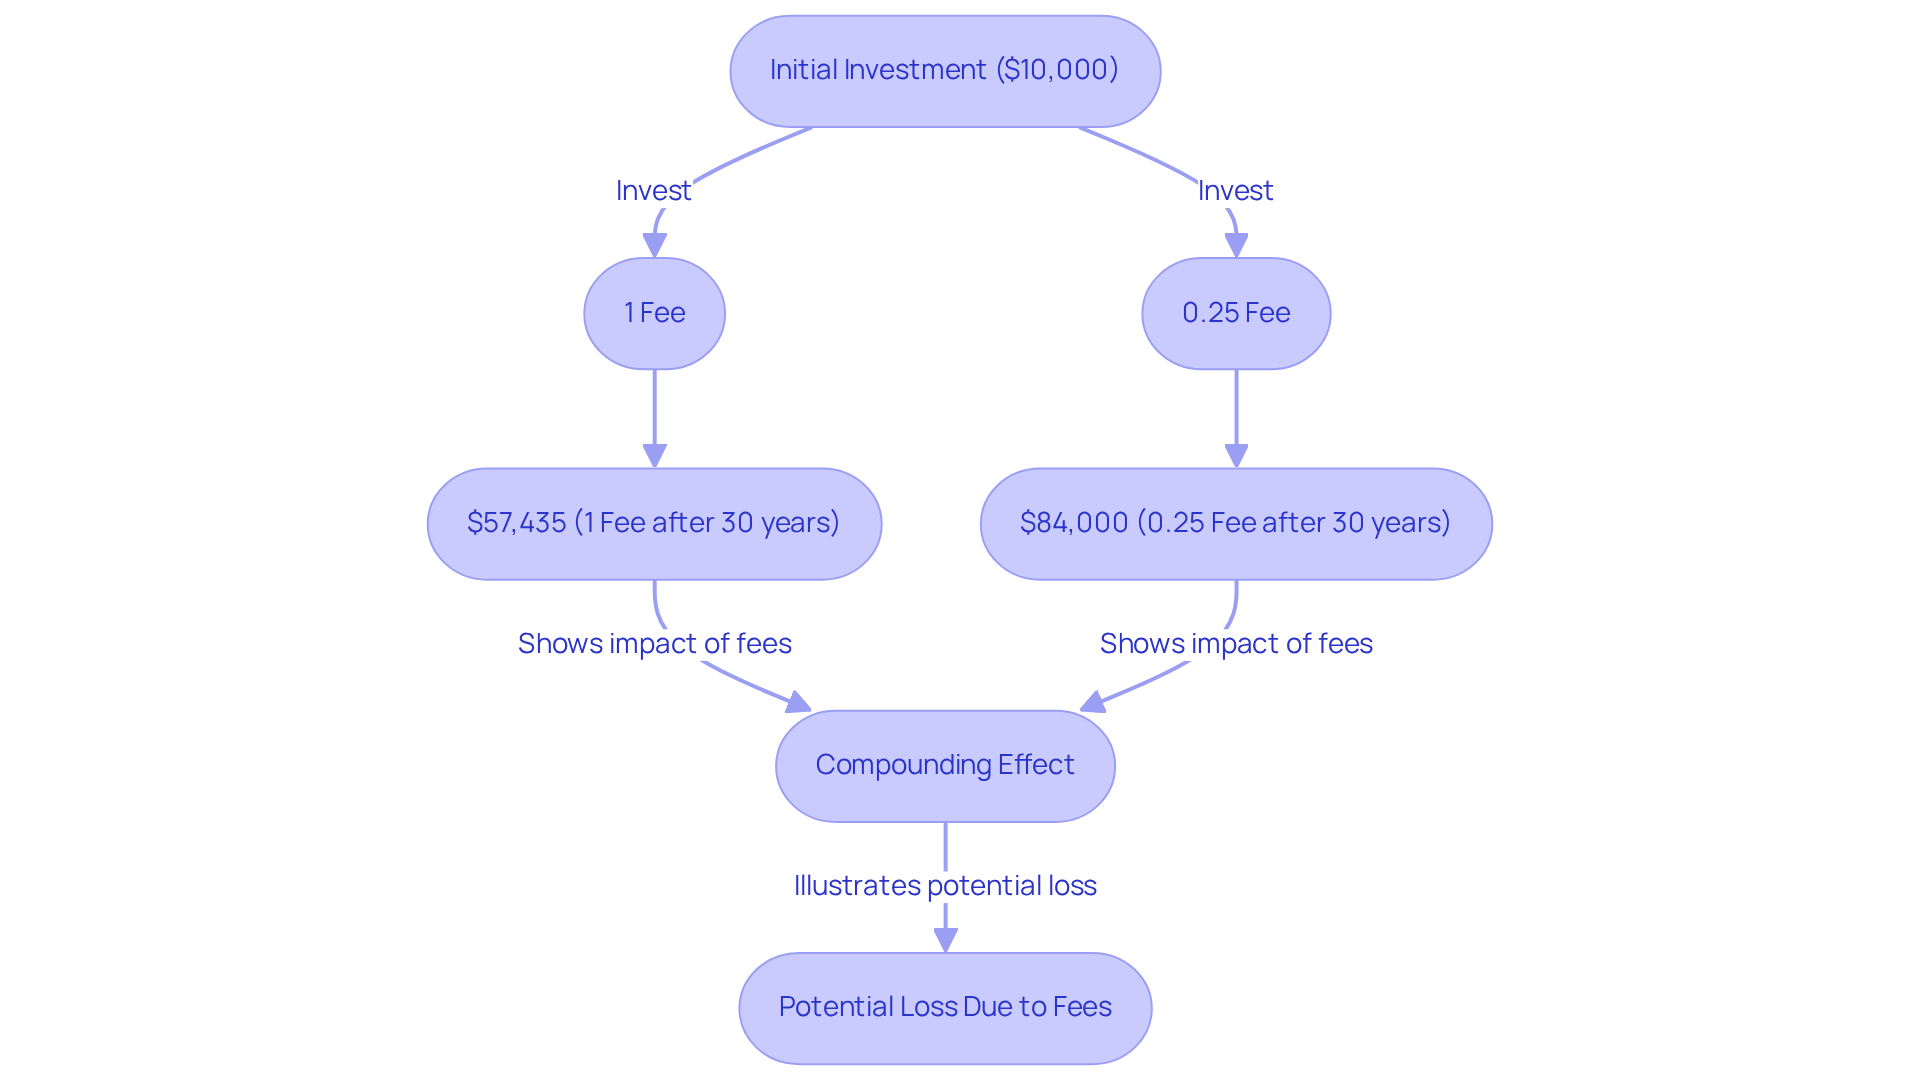
Investment returns can be dramatically influenced by average mutual fund fees, especially over the long term. Imagine this: a mutual investment with a 1% expense ratio might reduce your overall returns by nearly 30% over 30 years compared to an investment with a 0.25% expense ratio. This reduction stems from the compounding impact of charges, where not only is the charge itself lost, but also the potential returns that could have been generated on that amount.
At Bright Advisers, we understand the importance of reducing fees. Our mission is to ensure families like yours can access wealth management options that truly enhance your financial security. Think about this: if you contribute $10,000 to a portfolio with a 1% charge, growing at an average yearly return of 6%, after 30 years, this investment could yield approximately $57,435. Now, consider the same investment in a portfolio with a 0.25% fee; it would grow to about $84,000. This clear contrast underscores the need for families to be mindful of average mutual fund fees when selecting mutual investment options, especially as they work to create and preserve wealth for future generations.
Real-world examples further illustrate this point. Picture two investors: one selects a fund with a 0.25% annual fee, while the other opts for a fund with a 1% fee. Despite the seemingly minor difference, the compounding effect leads to a significant disparity in their final savings, with the lower-fee investor accumulating substantially more wealth over the same period.
Expert analysis consistently shows that even small differences in average mutual fund fees can result in considerable losses over time. For instance, a portfolio without charges could grow to $6.17 million, while standard costs might reduce this to $4.85 million, resulting in a loss of roughly $1.32 million. This underscores the importance of managing average mutual fund fees effectively to maximize financial outcomes, particularly for families focused on securing their financial future. Additionally, some clients may have legacy fee-bearing mutual funds and ETFs, which can further impact their overall financial strategy. Families should also consider low-fee-bearing ETFs, especially for exposure to fixed income or alternative asset classes, as these options can significantly enhance your investment returns.
Together, we can navigate this journey toward financial well-being, ensuring that your family’s future is bright and secure.
Conclusion
Understanding average mutual fund fees is essential for families looking to secure their financial future. These fees, while they may seem minor at first, can significantly erode investment returns over time. By recognizing the impact of management charges, 12b-1 fees, load fees, and expense ratios, you can make informed decisions that align with your financial goals and ultimately enhance your wealth accumulation.
Imagine if even small differences in fees could lead to substantial losses in potential returns. For instance, a mere 1% fee can diminish a portfolio’s growth by nearly 30% over 30 years compared to a lower-cost alternative. This highlights the importance of choosing investment vehicles with lower expense ratios, as families can potentially save thousands of dollars simply by being fee-conscious. The trend toward lower-cost options further supports the notion that being informed about mutual fund fees is crucial for maximizing investment outcomes.
Ultimately, the journey toward financial security requires vigilance and knowledge about mutual fund fees. We encourage you to actively seek out low-cost investment options and utilize resources to compare average mutual fund fees effectively. By prioritizing investments with lower fees, you can enhance your potential for achieving long-term financial goals, ensuring a brighter future for yourself and your loved ones. Together, we can navigate this journey toward financial well-being.
Frequently Asked Questions
What are mutual fund fees?
Mutual fund fees are the expenses associated with managing a mutual investment, including management costs, administrative expenses, and other operational expenditures. These fees are typically expressed as a percentage of the fund’s assets under management (AUM) and are deducted from the fund’s returns.
Why are mutual fund fees important for investors?
Mutual fund fees are important because they can significantly impact capital growth over time. Even a seemingly small charge of 1% can hinder returns due to the compounding effect of fees, potentially resulting in a substantial difference in portfolio value over a long investment period.
How can mutual fund fees affect long-term financial goals?
High mutual fund fees can diminish returns, making it more challenging for families to achieve their long-term financial goals. It is essential for investors to remain vigilant about these costs to maximize their investment outcomes.
What is the trend regarding mutual fund fees among investors?
There is a growing trend among investors to lean towards low-cost options. For example, no-load investments have seen significant sales growth, increasing from 46% in 2000 to 92% in 2024, indicating a heightened awareness of the importance of minimizing costs to enhance returns.
What are the average expense ratios for different types of mutual funds?
The average expense ratio for actively managed investment vehicles is 0.65%, while passively managed index portfolios have significantly lower costs, averaging just 0.05% for equity index investments.
How can families be affected by high mutual fund fees?
Families investing in high-fee mutual funds may experience diminished returns compared to those who choose lower-cost alternatives. This can affect their overall financial health and ability to reach their financial goals.
What is the significance of understanding average mutual fund fees?
Understanding average mutual fund fees is essential for making informed investment decisions. As the financial landscape evolves, prioritizing resources with lower expense ratios can enhance the potential for achieving financial objectives.
What does the decline in market share for bundled share classes indicate?
The decline in market share for bundled share classes—from 42% in 2005 to only 12% by the end of 2024—indicates a broader trend towards lower-cost financial options, highlighting the increasing importance of fee awareness among investors.
List of Sources
- Define Mutual Fund Fees and Their Importance
- Vanguard mutual fund fees and minimums | Vanguard (https://investor.vanguard.com/investment-products/mutual-funds/fees)
- What Is an Expense Ratio? – NerdWallet (https://nerdwallet.com/article/investing/mutual-fund-expense-ratios)
- US Equity Fund Fees Continue to Decline Amid Rising Investor Demand for Lower-Cost Options (https://ici.org/news-release/25-news-fund-fees-decline)
- Fund Fees Are Still Declining, But Not as Quickly as They Once Were (https://morningstar.com/financial-advisors/fund-fees-are-still-declining-not-quickly-they-once-were)
- 4 Fund Fee Trends to Watch in 2025 (https://morningstar.com/funds/4-fund-fee-trends-watch-2025)
- Explore Different Types of Mutual Fund Fees
- Mutual Fund Fees: Average Expense Ratio and More – NerdWallet (https://nerdwallet.com/article/investing/mutual-fund-fees-what-investors-need-to-know)
- US Equity Fund Fees Continue to Decline Amid Rising Investor Demand for Lower-Cost Options (https://ici.org/news-release/25-news-fund-fees-decline)
- Mutual Fund Costs, Minimums, Fees (https://folioinvesting.com/folioinvesting/brokerage-features/mutual-funds/costs-minimums-fees)
- Mutual Fund Fees, Costs & Expense Ratios | Charles Schwab (https://schwab.com/mutual-funds/costs-fees)
- Calculate and Compare Average Expense Ratios
- US Equity Fund Fees Continue to Decline Amid Rising Investor Demand for Lower-Cost Options (https://ici.org/news-release/25-news-fund-fees-decline)
- Fund fees continue long-term slide as investors favor lower-cost options (https://investmentnews.com/etfs/fund-fees-continue-long-term-slide-as-investors-favor-lower-cost-options/259863)
- What Is an Expense Ratio? – NerdWallet (https://nerdwallet.com/article/investing/mutual-fund-expense-ratios)
- Analyze the Impact of Fees on Investment Returns
- Small fees, big impact: Understanding the long-term cost of investment fees (https://fifthperson.com/small-fees-big-impact-long-term-cost-fees)
- How Fund Fees are the Best Predictor of Returns (https://sg.morningstar.com/sg/news/154499/how-fund-fees-are-the-best-predictor-of-returns.aspx)
- Impact of Fees on Long-Term Investment Growth (https://mezzi.com/blog/impact-of-fees-on-long-term-investment-growth)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading