

Key Highlights
- FDIC insurance protects depositors up to $250,000 per depositor, per insured bank, for each ownership category.
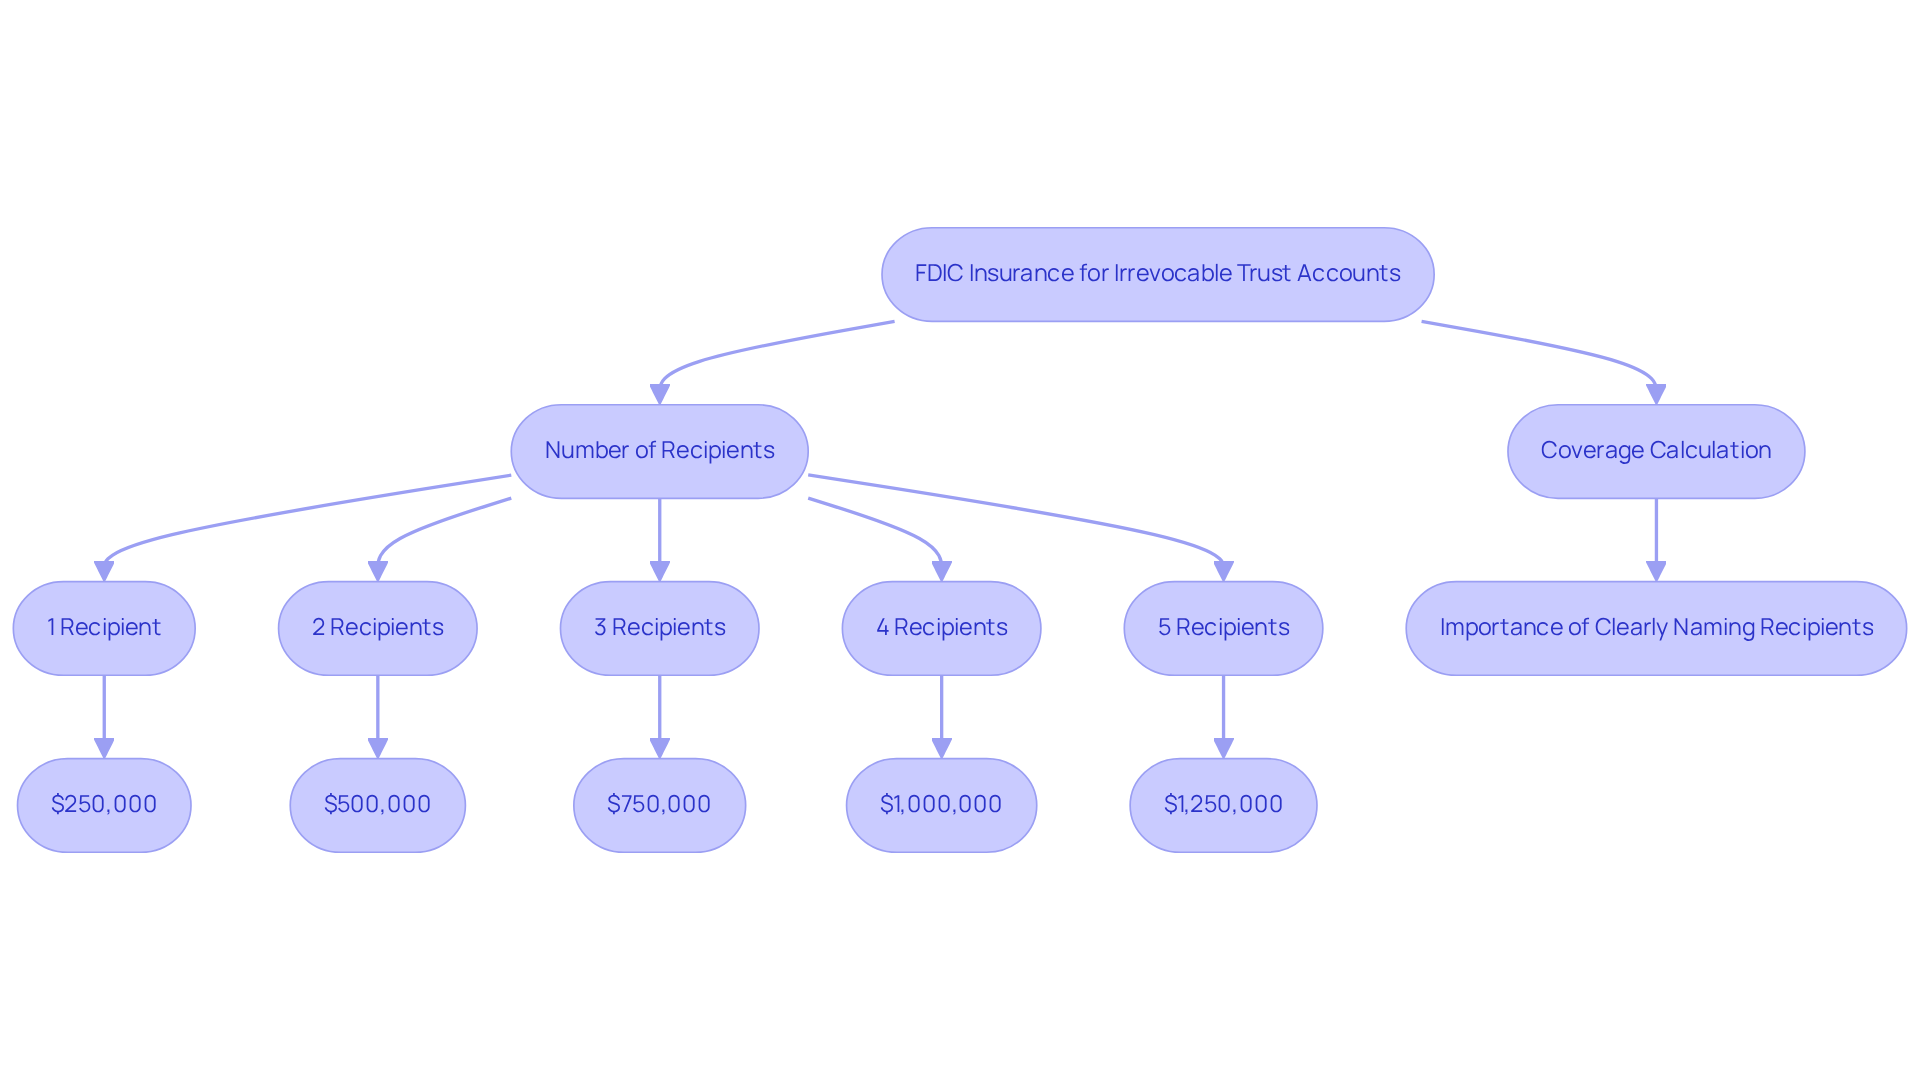
- For irrevocable trust accounts, coverage is determined by the number of eligible recipients, allowing up to $1,250,000 for five recipients.
- New regulations effective April 1, 2024, simplify coverage calculations for irrevocable trust accounts.
- Properly designating beneficiaries is crucial to ensure full FDIC coverage; failure to do so may reduce coverage.
- Families can enhance FDIC coverage by distributing deposits among multiple banks and using different ownership categories.
- Understanding FDIC insurance helps families make informed financial decisions and secure their assets against bank failures.
Introduction
Imagine feeling secure about your family’s financial future, even amidst changing regulations. Understanding FDIC insurance for irrevocable trust accounts is vital for families like yours who want to protect their financial well-being. With coverage limits of up to $250,000 per recipient, you can safeguard significant assets from potential bank failures, ensuring your children’s future is secure.
However, these changes may create confusion and uncertainty for families trying to protect their assets. It’s important to understand how recent regulatory changes set to take effect in 2024 could impact how you manage your trust accounts.
With the right guidance, you can confidently navigate these changes and protect what matters most to your family.
Clarify FDIC Insurance Basics for Irrevocable Trust Accounts
Imagine the peace of mind that comes from knowing your family’s financial future is secure, even in uncertain times. FDIC insurance safeguards depositors in the event of a bank failure, offering coverage of up to $250,000 per depositor, per insured bank, for each ownership category. For irrevocable account types, FDIC insurance for irrevocable trust accounts is determined by the number of eligible recipients. Each recipient is covered for $250,000, which means that FDIC insurance for irrevocable trust accounts with five recipients can provide total coverage of up to $1,250,000. This coverage helps families protect their children’s financial future, making sure their assets are safe from bank failures. Grasping these basics allows families to make informed choices regarding their account management and overall financial strategy, particularly when evaluating the minimal fund fees linked to their investments.
Recent modifications to regulations regarding FDIC insurance for irrevocable trust accounts, effective April 1, 2024, have streamlined the coverage calculations for both revocable and irrevocable arrangements. According to the new regulations, deposit accounts, including those eligible for FDIC insurance for irrevocable trust accounts, are insured up to $250,000 for each recipient, with a maximum of five recipients per insured bank. For example, a trust with three recipients can be covered by FDIC insurance for irrevocable trust accounts up to $750,000, while a trust with five recipients can reach the maximum coverage of $1,250,000. This change enhances the financial security of families by clarifying how much insurance coverage is available and aligns with Bright Advisers’ commitment to providing minimal fund fees, ensuring families can maximize their investment potential.
Imagine the worry of losing coverage simply because a name wasn’t added. Case studies demonstrate the significance of clearly identifying recipients. If an account owner fails to designate eligible recipients, the account’s deposit holdings may not qualify for the Account category under FDIC regulations, potentially resulting in reduced coverage. But if you clearly name your loved ones, like ‘my children and grandchildren,’ you can ensure they’re covered properly, as long as the names are clear and precise.
By understanding these protections, you can take confident steps toward securing your family’s financial future, ensuring they thrive no matter what comes their way. Utilizing the revised coverage regulations and ensuring appropriate designations for recipients, families can navigate the intricacies of account management with assurance, all while considering the minimal fund fees that Bright Advisers promotes in their wealth strategies.
Explore Recent Changes in FDIC Rules for Trust Accounts
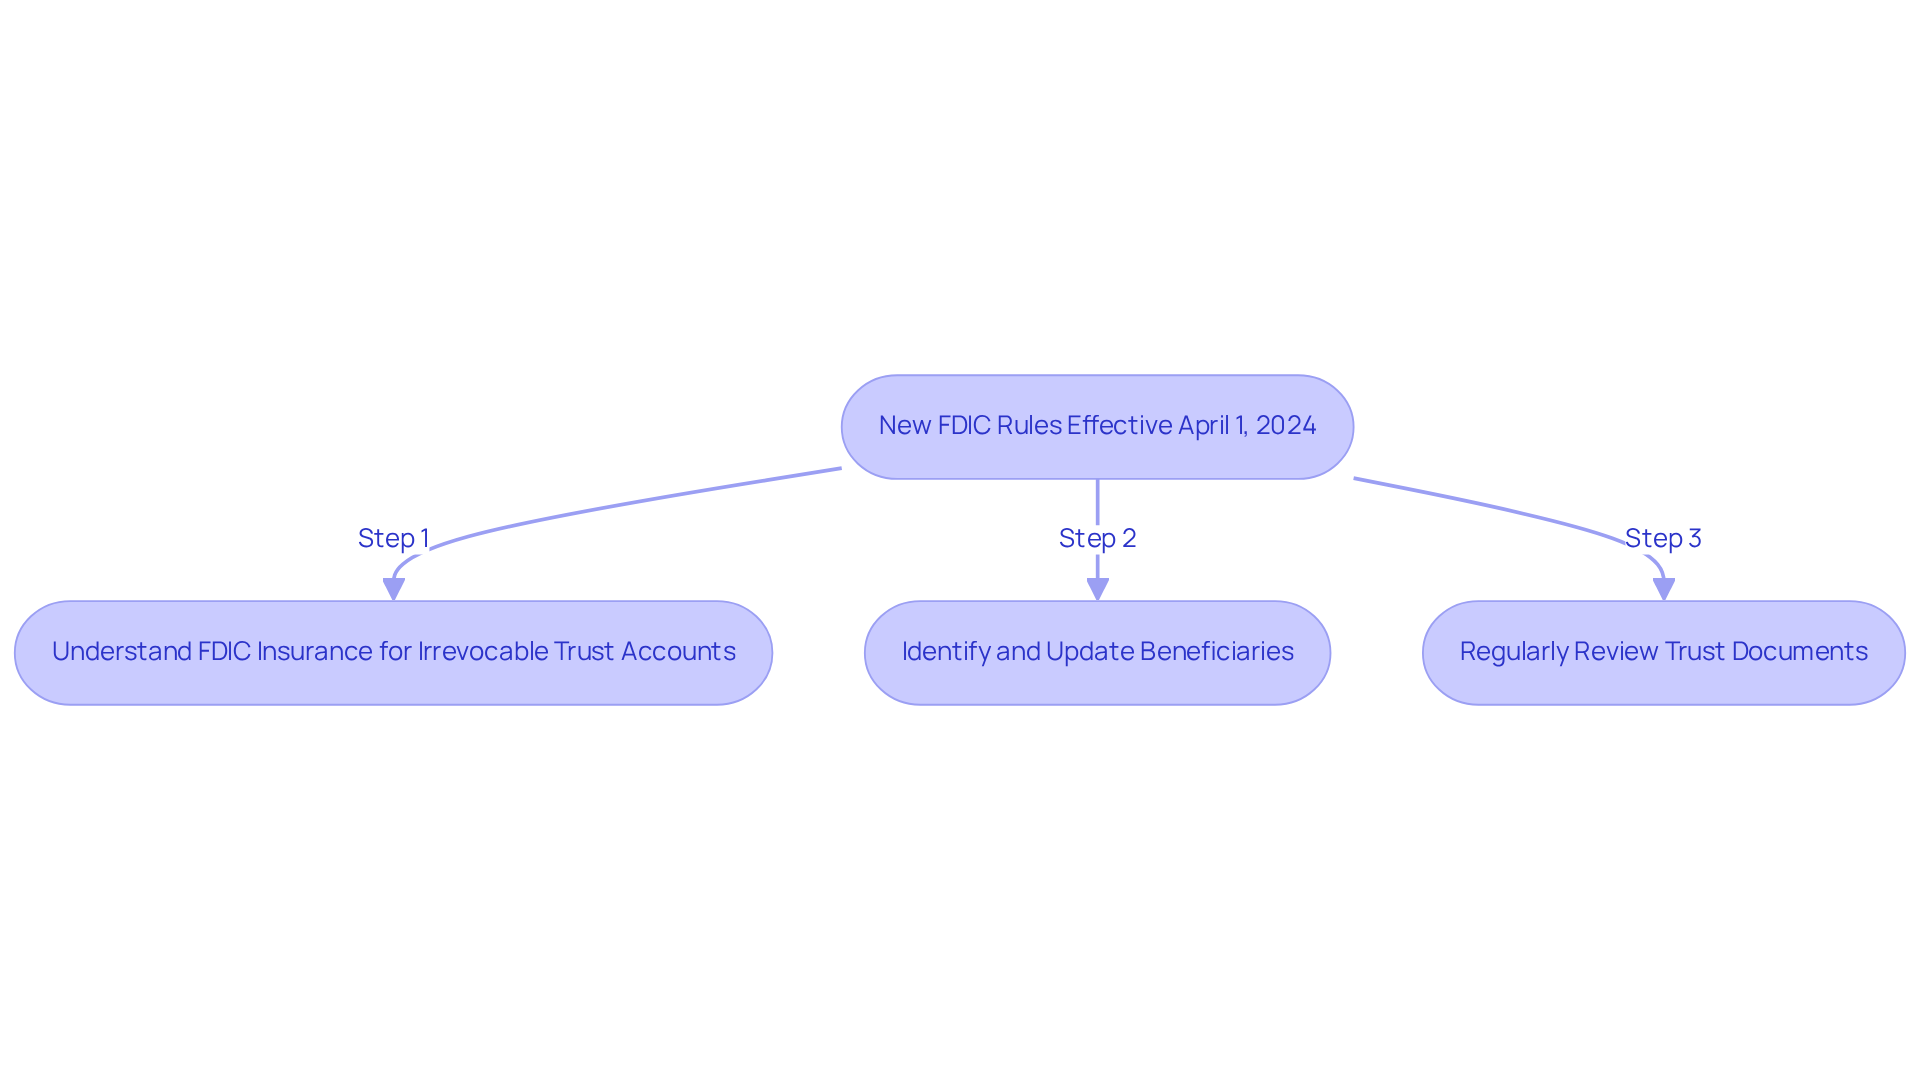
Imagine trying to navigate new rules while juggling family responsibilities – it’s overwhelming, isn’t it? Starting April 1, 2024, new FDIC rules will make it easier for families to understand how FDIC insurance for irrevocable trust accounts protects their fiduciary accounts. These changes aim to make it simpler for families to know how to protect their hard-earned savings. It’s crucial for families to grasp these changes so they can make the most of their FDIC insurance for irrevocable trust accounts and keep their assets safe.
Think about it: knowing who your beneficiaries are can make all the difference in protecting your family’s future. Regularly checking and updating your trust documents can help ensure your family’s financial security in light of these new rules.
We know that families like Jay & Emma, Emily & Mark, and Allison & Brian face unique financial challenges every day. Our tailored financial planning services are designed to help families like yours navigate these complexities with ease. We’re here to help you align your financial goals with smart budgeting and planning, so you can secure your family’s future.
With us, you can trust that there are no hidden fees – just honest guidance as you build a strong financial foundation for your family. Remember, while we strive for the best, all investments come with risks, and past performance isn’t a guarantee of future success. If you’d like to learn more about how we can support your family’s financial journey, we invite you to join our waitlist today!
Calculate Insurance Coverage for Irrevocable Trust Accounts
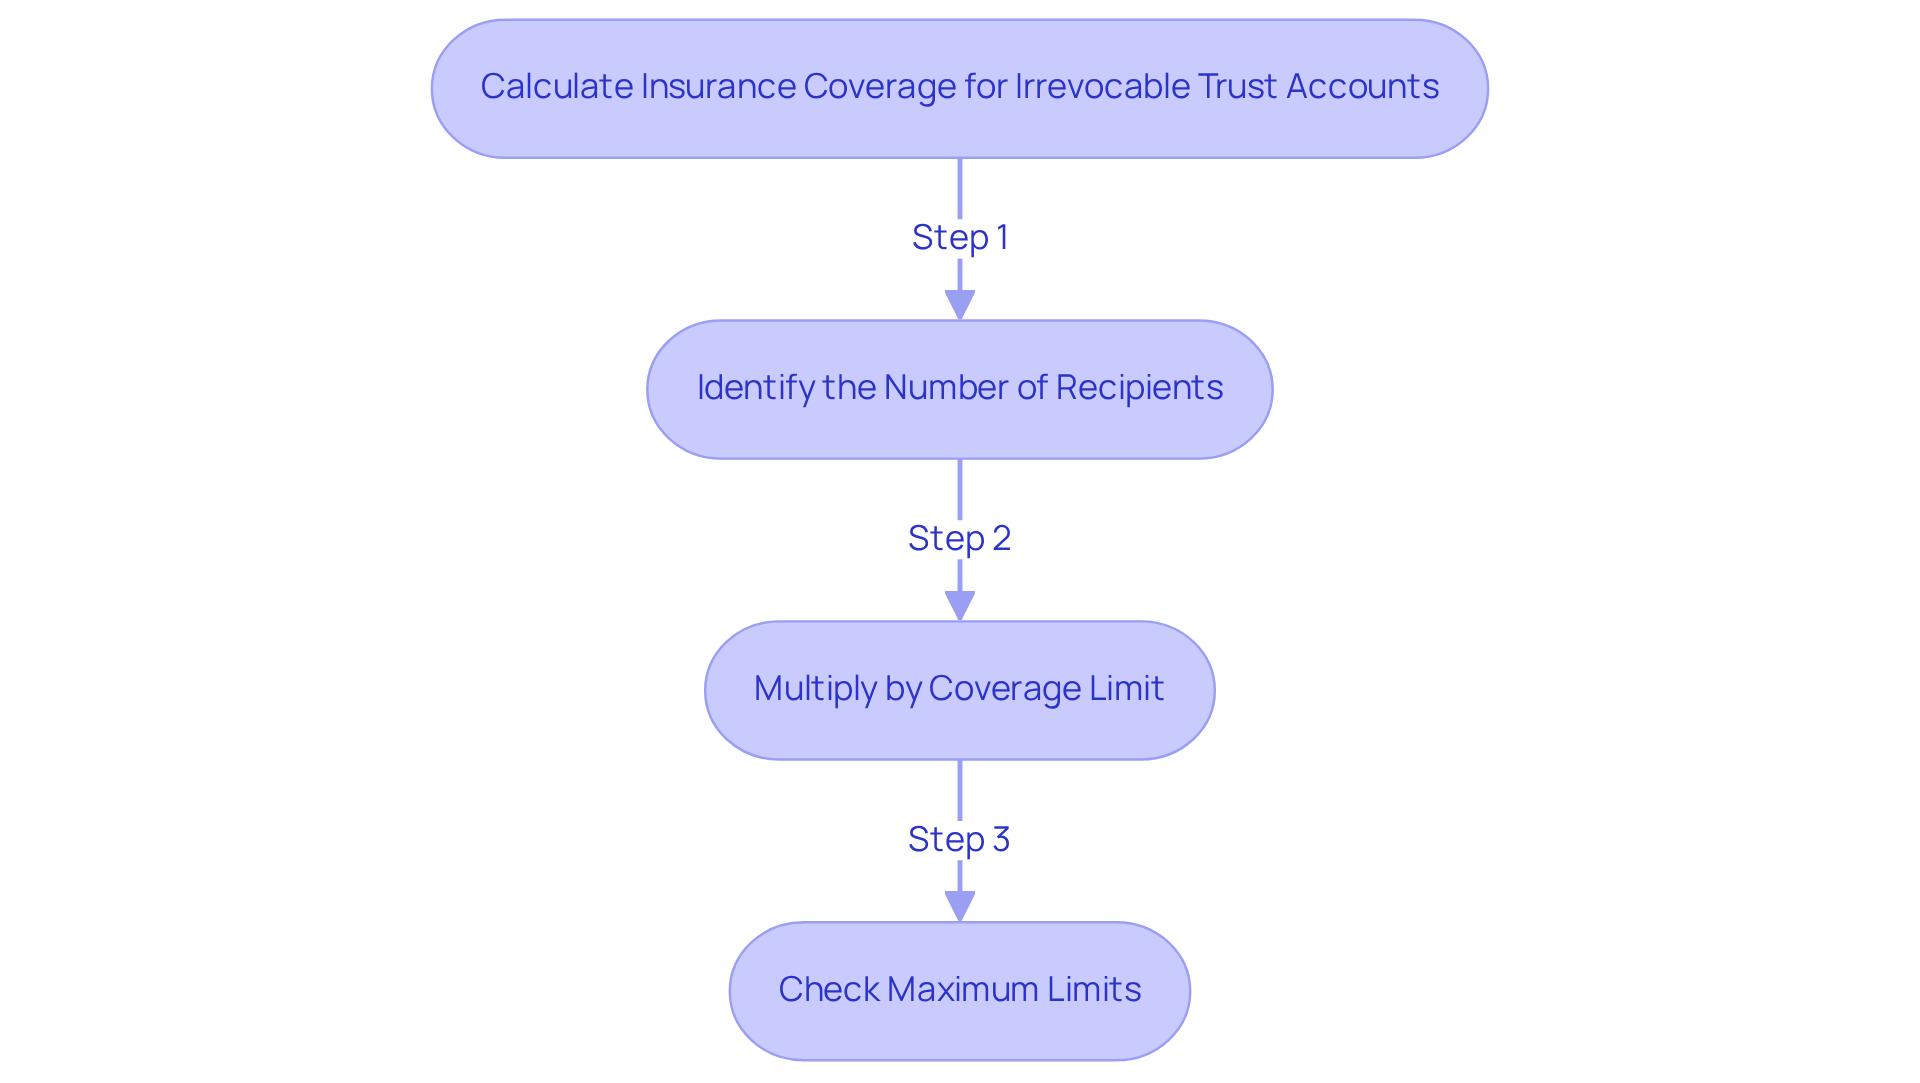
Imagine the peace of mind that comes from knowing your family’s assets are fully protected. To determine the FDIC insurance coverage for an irrevocable account, follow these steps:
- Identify the Number of Recipients: Count the eligible individuals named in the trust.
- Multiply by Coverage Limit: Multiply the number of recipients by $250,000. For instance, if there are three recipients, the calculation would be 3 x $250,000 = $750,000.
- Check Maximum Limits: Ensure that the total does not exceed $1,250,000, which is the maximum coverage for five recipients.
Understanding these calculations helps families protect their assets and make informed choices about their financial future. Each individual named in the trust can receive up to $250,000 in coverage, ensuring that your family’s needs are prioritized. If the trustee has discretion over distributions, the irrevocable arrangement qualifies for FDIC insurance for irrevocable trust accounts with a single coverage of $250,000.
By understanding these coverage limits, you can take proactive steps to secure your family’s financial well-being. Moreover, households can use the EDIE tool to gain a clearer understanding of coverage rules and limits, offering a useful resource for enhancing their FDIC protection. With the right knowledge, you can confidently safeguard your family’s future and make informed financial decisions.
Assess the Impact of FDIC Insurance on Depositors
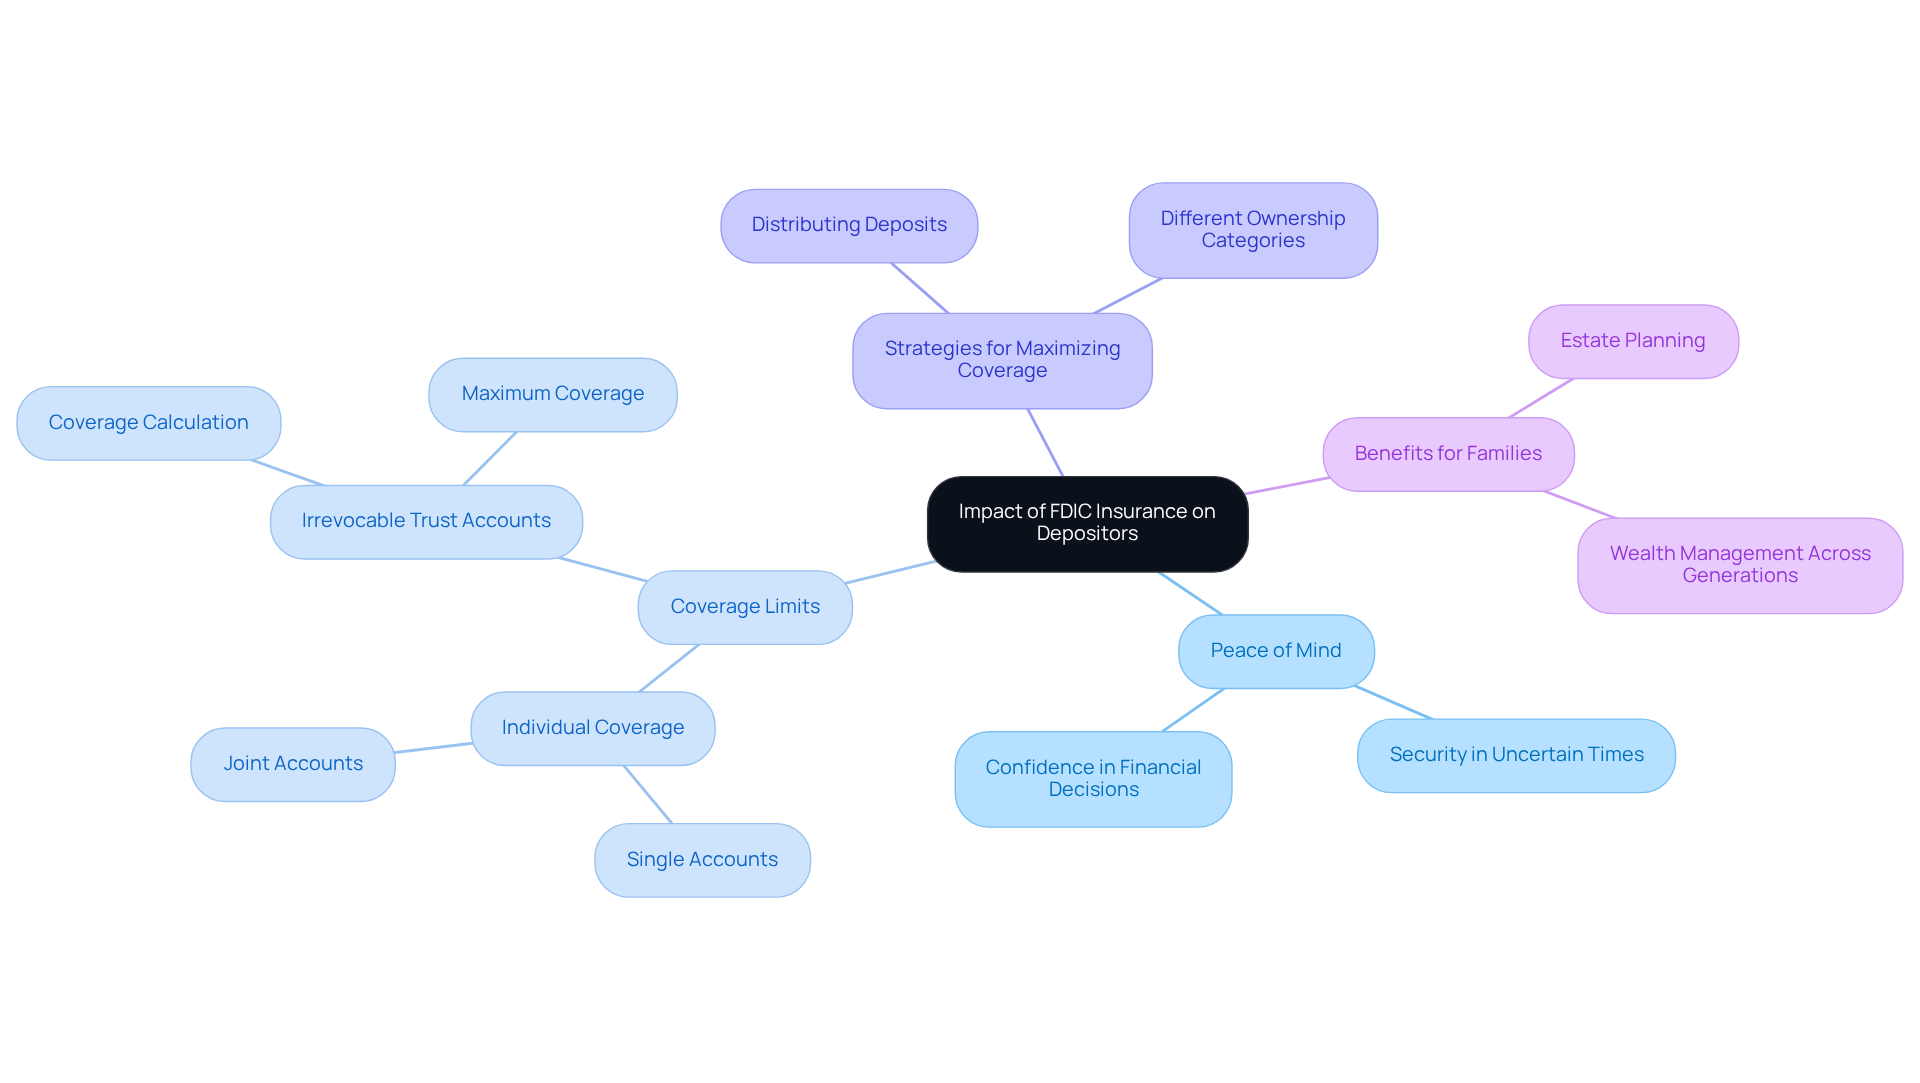
Imagine the peace of mind that comes from knowing your family’s savings are secure, even in uncertain times. FDIC insurance for irrevocable trust accounts is crucial for securing depositors, especially households. Understanding that your funds are insured up to $250,000 per recipient allows you to focus on your financial goals without the worry of possible bank failures. This coverage protects your assets and helps you feel more confident in your financial decisions, allowing you to adopt more aggressive investment methods knowing your core capital is safe.
It’s important to regularly check your account holdings to make sure you’re getting the most out of your FDIC coverage. For example, households can benefit from understanding the FDIC insurance for irrevocable trust accounts. Coverage is calculated based on the number of owners and beneficiaries, with a maximum limit of $1,250,000 for five or more beneficiaries. This structure enables families to effectively plan their estate and manage their wealth across generations.
Moreover, it’s essential to know that accounts held in different ownership categories at the same bank are insured separately, which can further enhance your overall coverage. In practical terms, you can enhance your FDIC coverage by distributing deposits among several banks and using different ownership categories. This strategy can significantly increase your total insurance coverage, providing an added layer of security for your financial assets.
When you stay informed and take action, you can confidently navigate the financial planning journey for your family, ensuring your wealth is protected for future generations. With the right knowledge and strategies, you can ensure your family’s financial future is bright and secure.
Conclusion
Imagine the peace of mind that comes from knowing your family’s financial future is secure. Understanding FDIC insurance for irrevocable trust accounts is a vital step for families looking to protect their wealth. This insurance offers essential protection against bank failures, ensuring that each eligible recipient can receive coverage of up to $250,000. With recent regulatory changes simplifying the coverage calculations, families can now more easily determine their total insurance limits, which can reach up to $1,250,000 for trusts with multiple beneficiaries. With this clarity, families can feel empowered to make informed decisions that truly reflect their values and priorities.
Throughout this article, we’ve shared key insights about the importance of clearly identifying beneficiaries to maximize FDIC coverage. The new rules, effective April 1, 2024, enhance our understanding of how these accounts are insured, allowing families to navigate their financial responsibilities with greater confidence. Additionally, we outlined practical steps for calculating coverage, emphasizing the need for regular updates to trust documents and the strategic distribution of assets across different banks to optimize insurance benefits.
In conclusion, staying informed about FDIC insurance for irrevocable trust accounts is vital for protecting family wealth across generations. By understanding the coverage limits and recent regulatory updates, families can take proactive steps to secure their financial well-being. We encourage you to reach out to resources like Bright Advisers, who are here to help you align your financial goals with effective planning strategies. Taking these steps today can make all the difference for your family’s tomorrow.
Frequently Asked Questions
What is FDIC insurance and how does it protect depositors?
FDIC insurance safeguards depositors in the event of a bank failure, offering coverage of up to $250,000 per depositor, per insured bank, for each ownership category.
How is FDIC insurance coverage determined for irrevocable trust accounts?
For irrevocable trust accounts, FDIC insurance is determined by the number of eligible recipients. Each recipient is covered for $250,000, meaning a trust with five recipients can have total coverage of up to $1,250,000.
What are the recent changes to FDIC insurance regulations for irrevocable trust accounts?
Effective April 1, 2024, the regulations have streamlined coverage calculations, ensuring that deposit accounts, including those for irrevocable trust accounts, are insured up to $250,000 for each recipient, with a maximum of five recipients per insured bank.
How can families ensure they receive the maximum FDIC insurance coverage for their irrevocable trust accounts?
Families can ensure maximum coverage by clearly identifying eligible recipients in the account. If recipients are not designated properly, the account may not qualify for full coverage under FDIC regulations.
Why is it important to clearly identify recipients in an irrevocable trust account?
Clearly identifying recipients is crucial because failure to do so may result in reduced coverage if the account does not qualify under FDIC regulations. Precise naming ensures that loved ones are properly covered.
How does understanding FDIC insurance help families with their financial strategies?
Understanding FDIC insurance allows families to make informed choices regarding account management and overall financial strategy, ensuring their assets are protected and aligned with their investment goals.
List of Sources
- Clarify FDIC Insurance Basics for Irrevocable Trust Accounts
- FDIC Insurance Coverage of Trust Accounts (https://hansonbridgett.com/publication/031423-0500-fdic-coverage-trust-accounts)
- FDIC Insurance for Trusts | Pinnacle Financial Partners (https://pnfp.com/learning-center/personal-finance/managing-your-money/fdic-insurance-for-trusts)
- Trust Accounts | FDIC.gov (https://fdic.gov/financial-institution-employees-guide-deposit-insurance/trust-accounts)
- The FDIC Has New Deposit Insurance Rules For Trust Accounts (https://conaelderlaw.com/fdic-new-deposit-insurance-rules-for-trust-accounts)
- Your Insured Deposits | FDIC.gov (https://fdic.gov/resources/deposit-insurance/brochures/insured-deposits)
- Explore Recent Changes in FDIC Rules for Trust Accounts
- Trust Accounts | FDIC.gov (https://fdic.gov/financial-institution-employees-guide-deposit-insurance/trust-accounts)
- FDIC Insurance Rule Updates for Trusts Explained (https://bosshardparkelaw.com/blog/fdic-changes-deposit-insurance-rules-for-trust-accounts)
- The FDIC Has New Deposit Insurance Rules For Trust Accounts (https://conaelderlaw.com/fdic-new-deposit-insurance-rules-for-trust-accounts)
- New FDIC Rules Change Coverage For Trust Accounts | Loeb & Loeb LLP (https://loeb.com/en/insights/publications/2023/06/new-fdic-rules-may-change-coverage-for-trust-accounts)
- FDIC Updates Rules for Trusts Effective April 1, 2024 – David Okrent Law (https://okrentlaw.com/fdic-updates-rules-for-trusts-effective-april-1-2024)
- Calculate Insurance Coverage for Irrevocable Trust Accounts
- FDIC Insurance Coverage of Trust Accounts (https://hansonbridgett.com/publication/031423-0500-fdic-coverage-trust-accounts)
- FDIC: Electronic Deposit Insurance Estimator (EDIE): Home (https://edie.fdic.gov)
- FDIC: Electronic Deposit Insurance Estimator (EDIE): SOC (https://edie.fdic.gov/rulechange_calculator.html)
- Trust Accounts | FDIC.gov (https://fdic.gov/financial-institution-employees-guide-deposit-insurance/trust-accounts)
- Assess the Impact of FDIC Insurance on Depositors
- Are My Deposit Accounts Insured by the FDIC? | FDIC.gov (https://fdic.gov/resources/deposit-insurance/financial-products-insured)
- Homepage (https://schwabmoneywise.com/essentials/understanding-fdic-and-sipc-insurance)
- Your Insured Deposits | FDIC.gov (https://fdic.gov/resources/deposit-insurance/brochures/insured-deposits)
- Protecting Your Deposits: Understanding FDIC Insurance (https://liveoak.bank/blog/protecting-your-deposits-understanding-fdic-insurance)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading