

Key Highlights
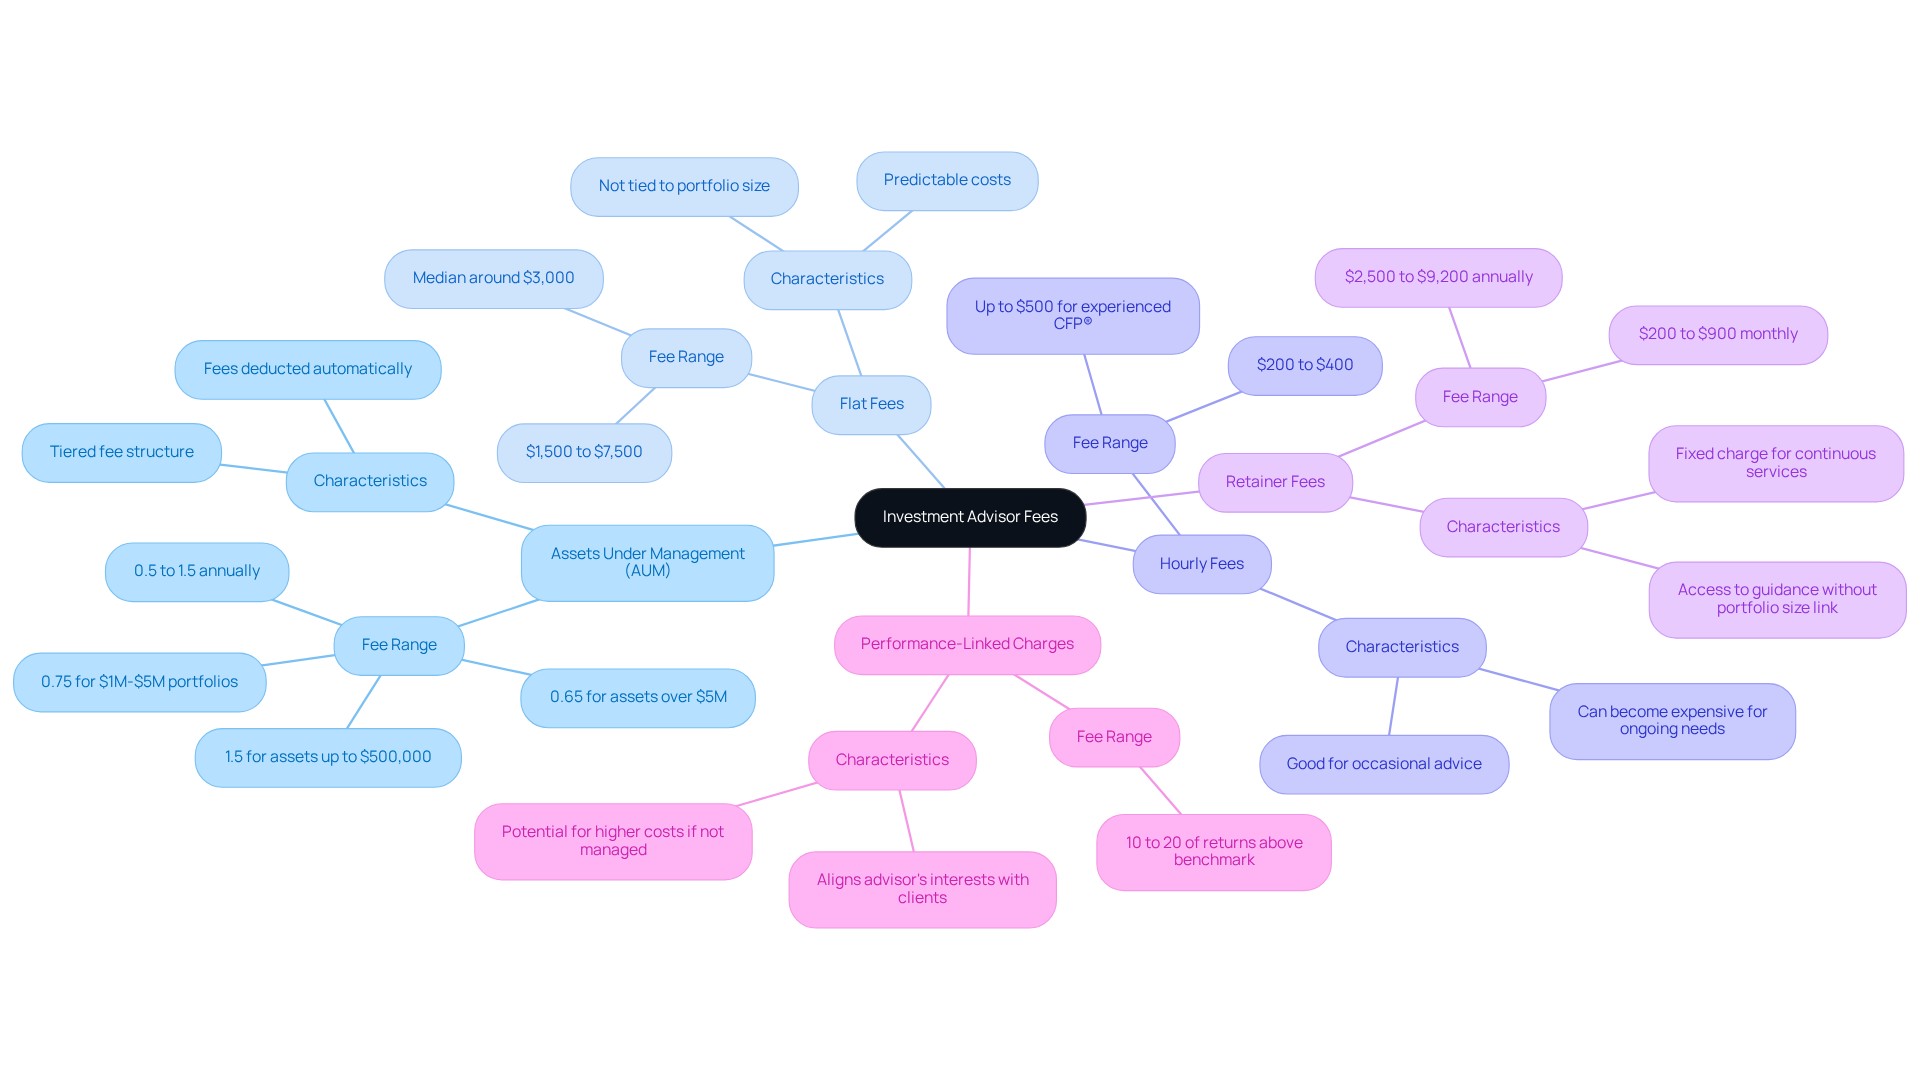
- Investment advisor fees can include Assets Under Management (AUM), flat fees, hourly fees, retainer fees, and performance-linked charges.
- AUM fees typically range from 0.5% to 1.5% annually, decreasing as portfolio size increases.
- Flat fees for specific services can range from $1,500 to $7,500, while hourly fees are usually between $200 and $400.
- Retainer fees are fixed charges for ongoing services, ranging from $2,500 to $9,200 annually.
- Performance-linked charges are based on investment success, typically ranging from 10% to 20% of returns above a benchmark.
- Families should gather information on potential advisors, cheque fee structures, and use comparison tools to assess costs.
- Creating a comparison chart can help visualise advisor fees and services, aiding in informed decision-making.
- Evaluating the value of services against fees involves listing services, assessing family needs, and considering long-term benefits.
- Effective communication with advisors includes preparing questions, requesting detailed fee breakdowns, and clarifying service expectations.
- Bright Advisers emphasises transparency, fiduciary duty, and personalised wealth management for families, ensuring no hidden fees or conflicts of interest.
Introduction
Imagine trying to secure your family’s financial future while feeling lost in a sea of investment advisor fees. Let’s explore the different ways advisors might charge you:
- Percentage-based fees
- Flat rates
Understanding these can make a world of difference for your family. With so many choices and the chance of hidden costs, how can you feel confident that you’re making the best decisions for your family’s future? We’re here to help you navigate this journey.
Identify Different Types of Investment Advisor Fees
Understanding how much does an investment advisor charge in fees can help you find the right professional for your family’s needs. Here are the most common types of fees:
- Assets Under Management (AUM): This fee is a percentage of the assets the consultant manages for you, usually ranging from 0.5% to 1.5% annually. For example, if you have a portfolio of $500,000 and your consultant charges 1%, you would pay $5,000 each year. As your portfolio grows, you might find that AUM fees decrease, often landing around 0.75% for portfolios between $1 million and $5 million, making it easier to manage your family’s investments.
- Flat Fees: Some advisors charge a flat fee for specific services, like planning or investment management. This can range from $1,500 to $7,500, depending on how complex the services are. Comprehensive financial plans typically cost around $3,000, reflecting the median charge for standalone financial plans.
- Hourly Fees: Advisors may also charge by the hour, with rates typically between $200 and $400. This model is great for families who need occasional advice rather than ongoing management. Hourly rates for experienced CFP® professionals can reach up to $500.
- Retainer Fees: This is a fixed charge paid yearly or monthly for continuous services, which can vary from $2,500 to $9,200 based on the consultant’s offerings. Monthly retainer charges can range from $200 to $900, allowing you to access guidance whenever you need it without linking expenses to portfolio size.
- Performance-Linked Charges: Some consultants impose costs based on the success of your investments, meaning they earn more if your portfolio does well. This model can align the advisor’s interests with yours but may also lead to higher costs if not managed carefully. Performance-based charges typically range from 10% to 20% of returns above a predefined benchmark.
At Bright Advisers, we are dedicated to reducing fund charges, ensuring that households can access wealth management services without the strain of high expenses. We also recognize that some clients may hold legacy fee-bearing mutual funds and low-fee-bearing ETFs, especially for exposure to fixed income or alternative asset classes like precious metals and cryptocurrencies. By understanding how much an investment advisor charges, you can make informed choices that truly benefit your family’s financial journey. It’s also essential to be aware of extra charges, such as transaction and custodial costs, to prevent any unforeseen expenses.
Research and Compare Advisor Fees
Navigating the world of investment advisor fees, specifically how much does an investment advisor charge, can feel overwhelming, especially when you’re trying to secure your family’s financial future.
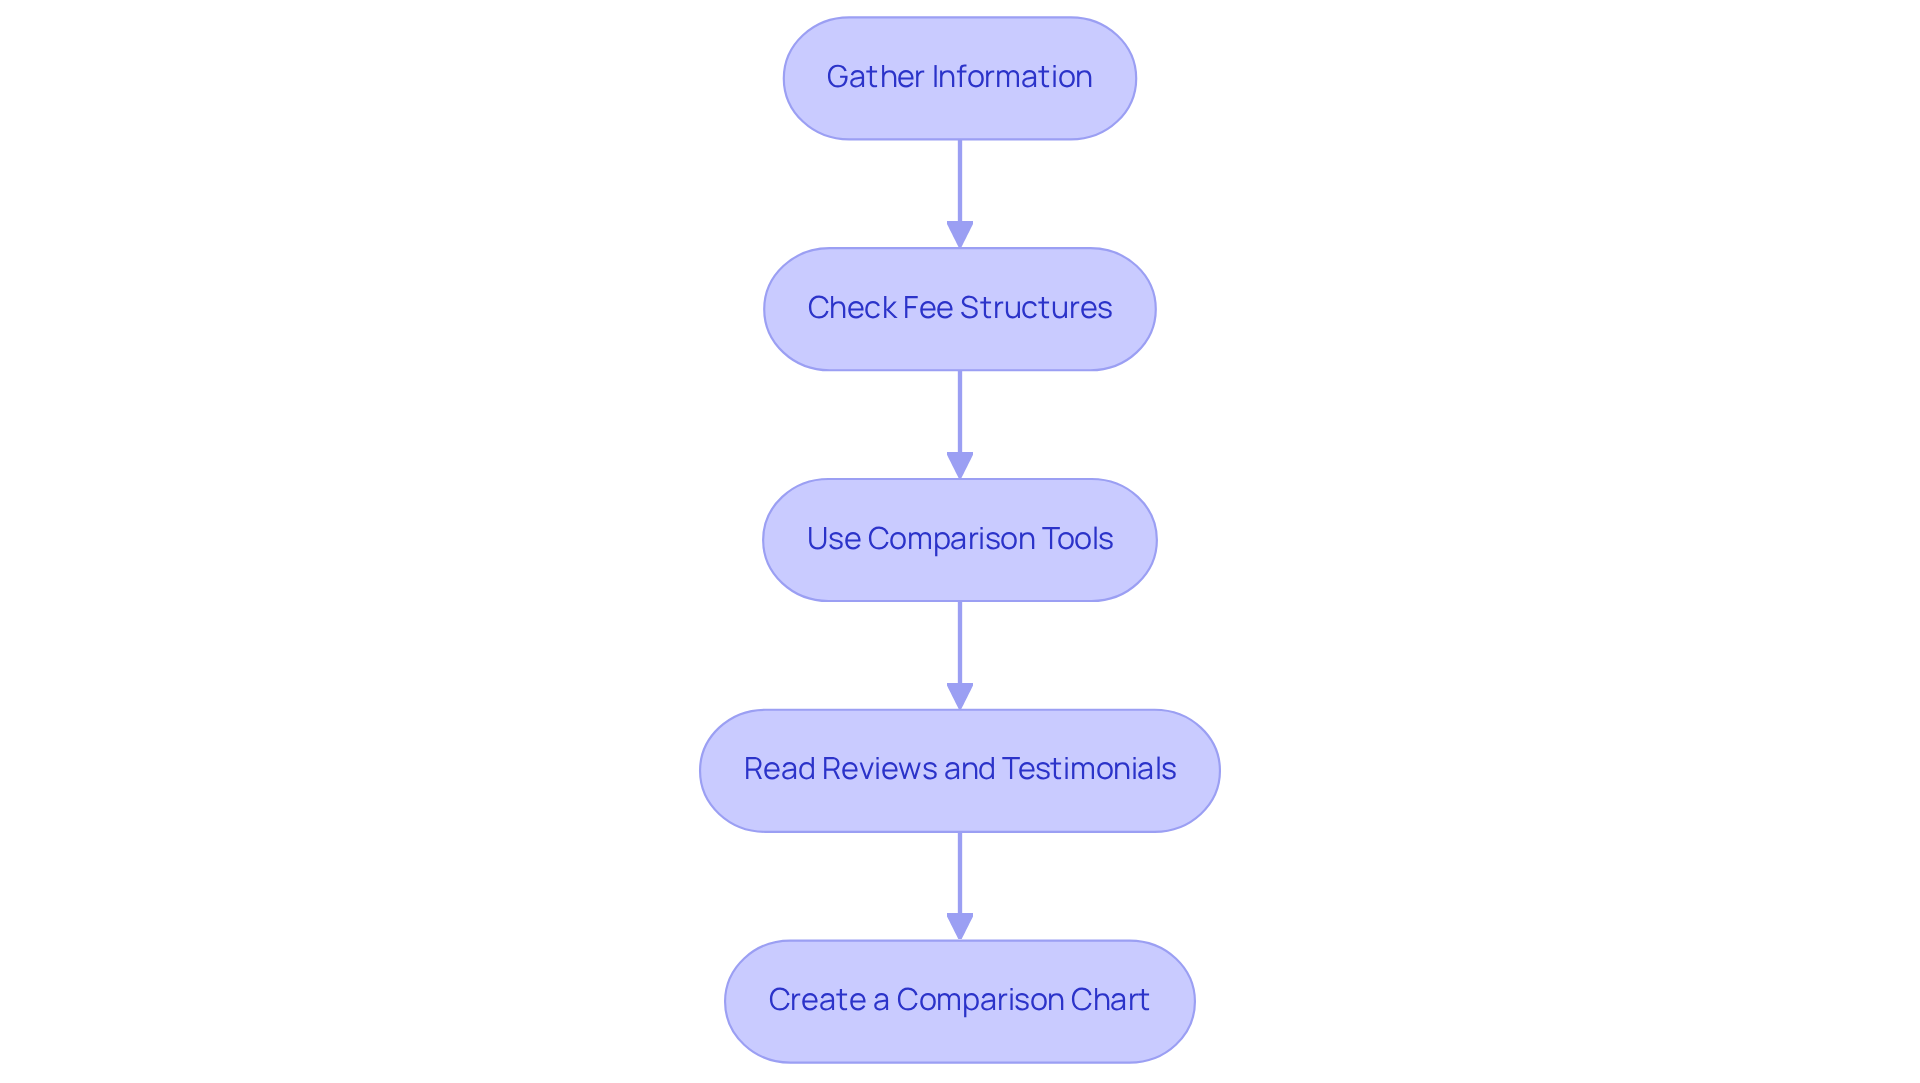
- Gather Information: Start by compiling a list of potential mentors. You can find them through online searches, referrals from friends, or financial planning associations.
- Check Fee Structures: Visit each advisor’s website or contact them directly to inquire about their fee structures. It can be tricky to find all the hidden costs associated with investment advisors, including how much does an investment advisor charge, fund expenses, or transaction costs. At Bright Advisers, we believe in being open about our fees, so families can access wealth management without any surprises.
- Use Comparison Tools: Utilize online calculators and comparison tools to assess the costs related to various consultants. Websites such as NerdWallet and SmartAsset provide resources to help you understand how charges can affect your investment returns over time.
- Read Reviews and Testimonials: Look for feedback from other clients to gauge their experiences with the consultants. Pay attention to remarks about openness and communication concerning charges.
- Create a Comparison Chart: Arrange your discoveries in a chart that details each consultant’s charges, services provided, and any extra expenses. This visual aid will help you make a more informed decision.
By comparing how much does an investment advisor charge, you can find a financial partner who truly understands your family’s goals. At Bright Advisers, we are dedicated to empowering families through personalized planning and tax optimization, making wealth management accessible for everyone. Choosing the right financial partner can make all the difference in achieving your family’s dreams.
Evaluate the Value of Services Against Fees
Imagine feeling confident about your family’s financial future, knowing you’ve made the right choices in selecting a financial advisor.
To effectively evaluate the value of financial advisor services against their fees, follow these steps:
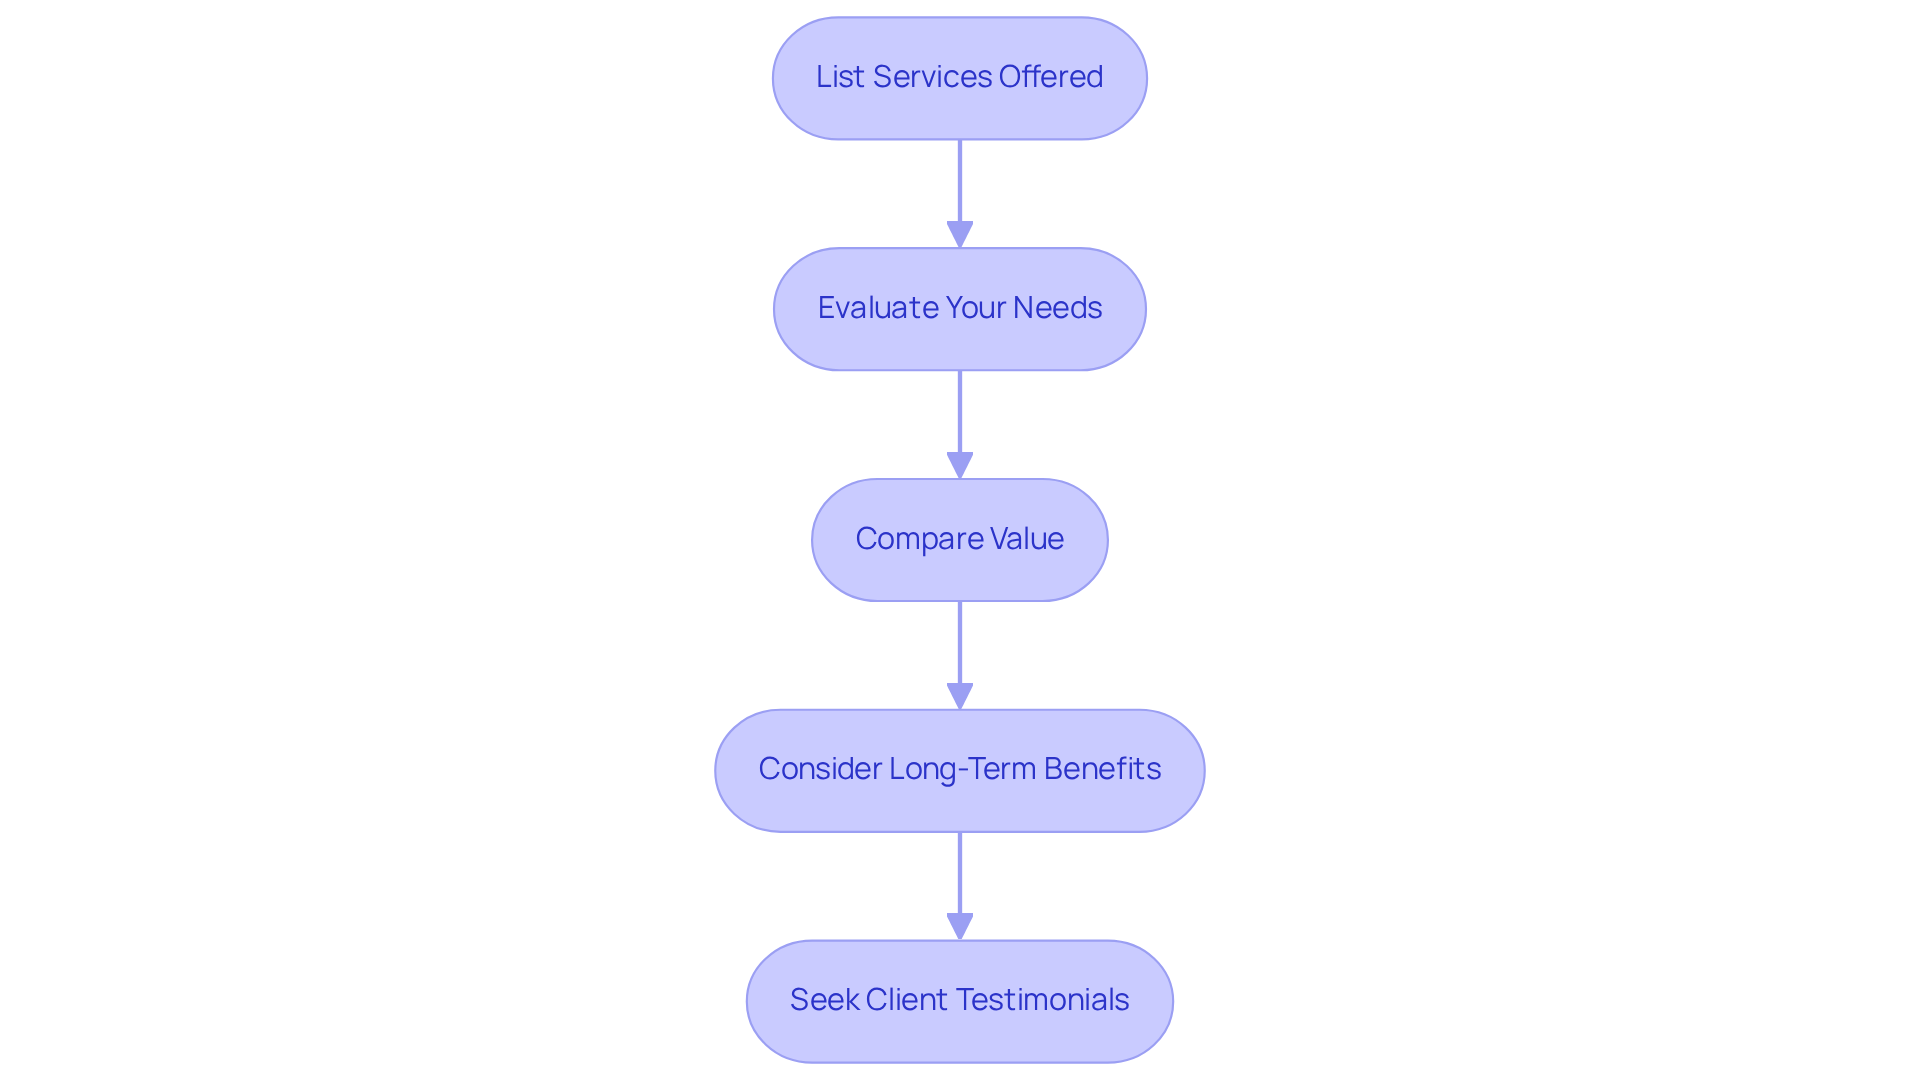
- List Services Offered: Compile a detailed list of services provided by each consultant, including monetary planning, tax planning, and estate planning. This clarity will help you understand the specific offerings and what you are paying for.
- Evaluate Your Needs: Think about what your family really needs when it comes to money. If thorough monetary planning and tax strategies are essential, ensure that the advisor can meet these needs. For instance, families like Allison and Brian, who sought guidance from Bright Advisers, found that optimizing their tax situation was crucial for maximizing their financial potential.
- Compare Value: Analyze how the services correspond with the costs incurred. For example, a consultant with a higher fee may provide comprehensive tax and estate planning services, which could validate the expense in comparison to a lower-cost consultant, especially when considering how much does an investment advisor charge for their services. Bright Advisers emphasizes a transparent fee structure with no hidden fees, ensuring clients understand what they are paying for.
- Consider Long-Term Benefits: It can be overwhelming to find the right financial advisor, especially when your family’s future is at stake. Evaluate the potential long-term advantages of collaborating with a specific consultant. A greater charge may be justified if the consultant has a strong history of assisting clients in reaching important economic milestones, such as retirement planning or wealth growth. Studies show that people collaborating with experts in finance express increased confidence in their finances and enhanced readiness for retirement, highlighting the importance of working with consultants. For example, through their collaboration with Bright Advisers, Allison and Brian secured their children’s future through education funding and gained the ability to retire sooner.
- Seek Client Testimonials: Connect with current or former clients to gain insights into their experiences. Ask if they believed the services provided were worth the costs incurred, as this can offer valuable insight into the consultant’s effectiveness.
By taking a closer look at how much does an investment advisor charge for their services, you can make choices that truly fit your family’s financial goals. This method not only improves your comprehension of the financial advisory landscape but also enables you to select a professional who best suits your needs, just as families like Allison and Brian have done with Bright Advisers. Remember, Bright Advisers operates with a fiduciary duty, ensuring that your best interests are always prioritized. Choosing the right financial advisor can be the key to unlocking a secure future for your family, ensuring you can focus on what truly matters.
Communicate with Advisors to Clarify Fees
Many families feel confused and overwhelmed when faced with complex fee structures, but understanding them is crucial for your financial well-being. Here are some steps to ensure clarity:
-
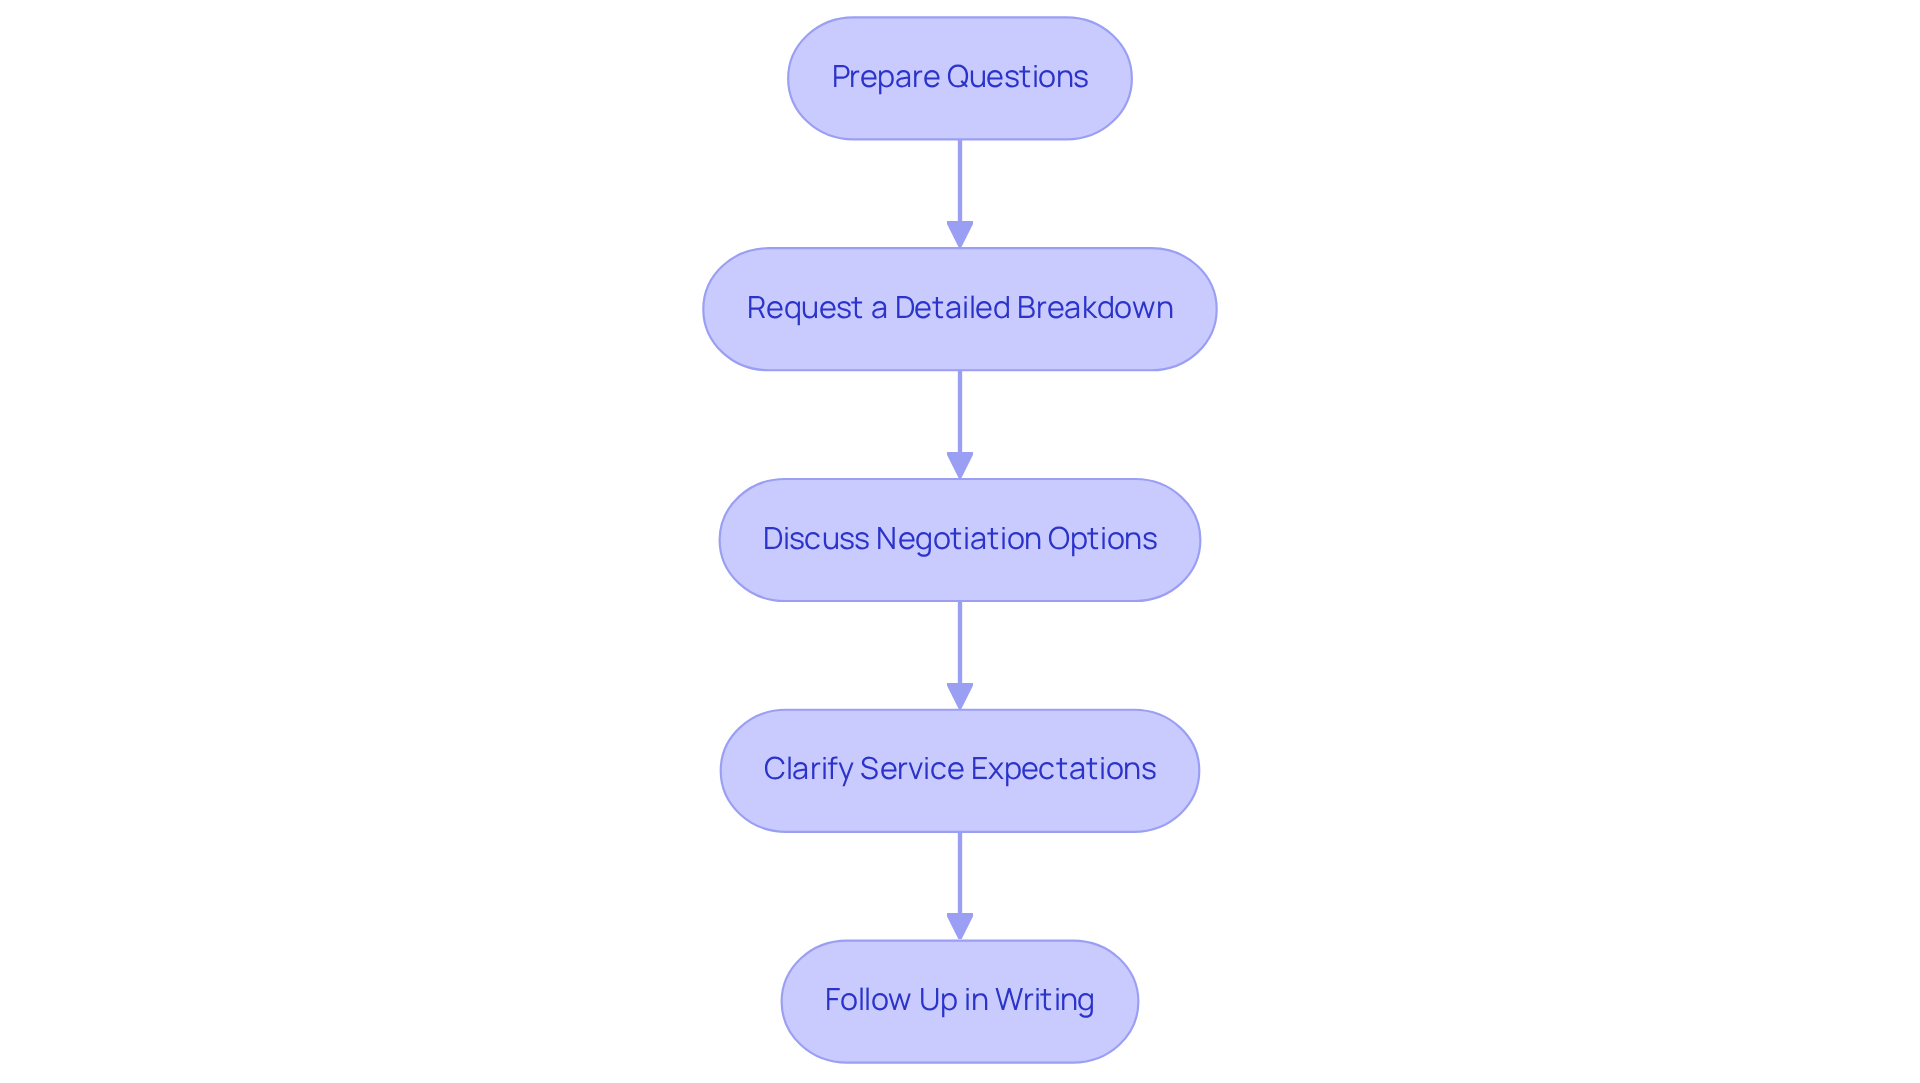
Prepare Questions: Before meeting with an advisor, take a moment to jot down your questions about their fees. You might want to ask:
- How are your fees structured?
- Are there any additional costs I should be aware of regarding how much does an investment advisor charge?
- How do you explain how much does an investment advisor charge for the services offered?
-
Request a Detailed Breakdown: Don’t hesitate to ask the consultant for a clear breakdown of their charges, including any hidden costs. Understanding how much does an investment advisor charge is vital, as high fees can significantly impact your family’s investment growth over time. At Bright Advisers, we prioritize low fund charges, ensuring that families can access wealth management services without breaking the bank.
-
Discuss Negotiation Options: It’s worth asking if there’s room to negotiate their fee structure. Some consultants may be open to discussing how much does an investment advisor charge based on your financial situation or the services you need, which can help your family achieve better financial stability. With yearly retainer charges rising by 52% since 2023, negotiating could be key to securing a more favorable arrangement.
-
Clarify Service Expectations: Make sure you understand what services are included in the fees. This will help you determine if the consultant’s offerings align with your family’s financial needs. For instance, consider whether the services provided, like comprehensive planning and tax strategies, justify the costs. Bright Advisers focuses on tailored wealth management solutions that empower families to achieve financial security and independence through personalized planning and tax optimization.
-
Follow Up in Writing: After your conversation, send a follow-up email summarizing your understanding of the fees and services discussed. This not only creates a record of your conversation but also helps prevent any misunderstandings down the line.
By communicating effectively with advisors, families can gain a clearer understanding of their fees and ensure they’re making informed choices for their financial future. Bright Advisers, founded by Kevin Luu and Kathleen Chou in 2010, is dedicated to helping families make wise financial decisions and protect their wealth for generations. By taking the time to understand these fees, you can pave the way for a more secure financial future for your family.
Conclusion
Many families feel lost when faced with the different fee structures of investment advisors, but understanding these fees is a crucial step toward securing your financial future. Imagine if you could easily understand the different fee structures – like flat fees or hourly rates – so you can make choices that truly fit your family’s financial goals. When you know what to look for, you can find advisors who are open and honest, helping you avoid any unexpected costs along the way.
We’ve shared some helpful tips on how to research and compare advisor fees, making this journey a little easier for you. Talking openly with potential advisors about their fees is so important. It helps you see exactly what you’re paying for and can lead to better financial choices for your family.
By taking the time to understand what an investment advisor charges and the value they bring, you’re making a choice that can truly shape your family’s financial journey. When you choose a transparent advisor like Bright Advisers, you can focus on what really matters – building a secure and happy future for your family together. For personalized guidance tailored to your family’s unique needs, consider reaching out to Bright Advisers at hello@brightadvisers.com or call (714) 987-2967.
Frequently Asked Questions
What are the common types of investment advisor fees?
The common types of investment advisor fees include Assets Under Management (AUM) fees, flat fees, hourly fees, retainer fees, and performance-linked charges.
How do Assets Under Management (AUM) fees work?
AUM fees are a percentage of the assets managed by the advisor, typically ranging from 0.5% to 1.5% annually. For example, if you have a portfolio of $500,000 and the fee is 1%, you would pay $5,000 each year. These fees may decrease as your portfolio grows.
What are flat fees in investment advising?
Flat fees are fixed charges for specific services, such as financial planning or investment management, ranging from $1,500 to $7,500 depending on the complexity of the services.
What are hourly fees charged by investment advisors?
Hourly fees typically range from $200 to $400, with experienced CFP® professionals charging up to $500. This model is suitable for families seeking occasional advice rather than ongoing management.
What are retainer fees?
Retainer fees are fixed charges paid yearly or monthly for continuous services, varying from $2,500 to $9,200. Monthly charges can range from $200 to $900, allowing access to guidance without linking costs to portfolio size.
How do performance-linked charges work?
Performance-linked charges are based on the success of your investments, where advisors earn more if your portfolio performs well. These charges typically range from 10% to 20% of returns above a predefined benchmark.
What additional costs should I be aware of when working with an investment advisor?
In addition to advisor fees, it’s important to be aware of extra charges such as transaction and custodial costs to avoid unforeseen expenses.
What is the mission of Bright Advisers regarding investment management?
Bright Advisers is dedicated to reducing fund charges and helping families make wise wealth decisions while preserving wealth across generations.
List of Sources
- Identify Different Types of Investment Advisor Fees
- How Much Does a Financial Advisor Cost? It Depends. – NerdWallet (https://nerdwallet.com/financial-advisors/learn/how-much-does-a-financial-advisor-cost)
- How Much Does a Financial Advisor Cost? Complete 2026 Fee Guide | Domain Money Financial Planning (https://domainmoney.com/post/how-much-does-a-financial-advisor-cost)
- How Much Does a Financial Advisor Cost in California? (https://randallwealthgroup.com/how-much-does-a-financial-advisor-cost-california)
- How Much Does a Financial Advisor Cost? (https://smartasset.com/financial-advisor/financial-advisor-cost)
- Research and Compare Advisor Fees
- Financial Advisor Cost | Fee Structures & Average Cost Backed by Data (https://financestrategists.com/financial-advisor/advisor-cost)
- Pros and cons of different advisory fee models (https://envestnet.com/financial-intel/pros-and-cons-different-advisory-fee-models)
- How Much Does a Financial Advisor Cost? Complete 2026 Fee Guide | Domain Money Financial Planning (https://domainmoney.com/post/how-much-does-a-financial-advisor-cost)
- How Much Does a Financial Advisor Cost? It Depends. – NerdWallet (https://nerdwallet.com/financial-advisors/learn/how-much-does-a-financial-advisor-cost)
- Evaluate the Value of Services Against Fees
- Pros and cons of different advisory fee models (https://envestnet.com/financial-intel/pros-and-cons-different-advisory-fee-models)
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- Why Flat Fees for Financial Advice Work When They’re Tied to Value Rather Than Portfolio Growth (https://kiplinger.com/retirement/retirement-planning/flat-fees-for-financial-advice-value-vs-portfolio-growth)
- Financial Advisor Statistics in 2026: Growth and Trends in the Financial Advisory Industry in the USA (https://randallwealthgroup.com/financial-advisor-statistics)
- Communicate with Advisors to Clarify Fees
- Pros and cons of different advisory fee models (https://envestnet.com/financial-intel/pros-and-cons-different-advisory-fee-models)
- Understanding Fees for Investment Advisors: A Guide for Young Families – Bright Advisers (https://brightadvisers.com/understanding-fees-for-investment-advisors-a-guide-for-young-families)
- Discussing Fees And The Value Of Financial Planning (https://kitces.com/blog/fees-value-financial-advice-client-communication-cost-anchoring)
- What to Know About Financial Advisor Fees and Costs (https://money.usnews.com/financial-advisors/articles/what-to-know-about-financial-advisor-fees-and-costs)
- The Value of Communication in the Client-Planner Relationship (https://financialplanningassociation.org/article/journal/AUG17-value-communication-client-planner-relationship)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading