

Key Highlights
- An Initial Public Offering (IPO) can lead to significant tax implications for employees, especially regarding stock options and RSUs.
- RSUs are taxed as ordinary income upon vesting, potentially leading to high tax bills based on their fair market value.
- Selling shares within a year of vesting incurs short-term capital gains tax, while holding them longer benefits from lower long-term capital gains tax rates.
- Proactive tax planning is essential for managing IPO-related tax responsibilities, including timing of sales and potential gifting strategies.
- Families should consider tax-advantaged accounts to help mitigate tax burdens from IPOs.
- Seeking professional guidance can help families navigate tax regulations, create customised strategies, and avoid common pitfalls.
- Bright Advisers assists families in developing sound financial strategies to address IPO tax considerations and secure their financial future.
Introduction
Imagine the excitement of an IPO, but also the worry of managing newfound wealth as a young parent. Navigating the financial landscape can feel overwhelming, especially when it comes to understanding tax implications. Many young parents find themselves juggling these complexities, and it’s important to grasp how they can shape your family’s financial future.
Without proper guidance, families risk making costly mistakes that could impact their long-term security. How can you effectively manage potential tax liabilities while ensuring your financial future remains secure? Together, we can navigate the critical tax implications of IPOs and find the best path for your family. This article offers insights and strategies to help you make informed decisions during this pivotal moment.
Clarify IPO Fundamentals and Tax Implications
Imagine the excitement and anxiety of your company going public, and the financial implications that come with it. An Initial Public Offering (IPO) can create a whirlwind of IPO tax considerations for employees, especially for those with stock options or restricted stock units (RSUs). When RSUs vest, they’re taxed as ordinary income based on their fair market value, which can lead to hefty tax bills. For example, if an employee receives shares valued at $100,000 during an IPO, they might face a tax rate as high as 37%, depending on their income bracket.
Understanding IPO tax considerations is crucial for families, as they can significantly impact budgeting and future investments. It’s also important to think about when to sell shares, since gains from sales may be subject to capital gains tax. If shares are sold within a year of vesting, they incur short-term capital gains tax, while holding them for over a year subjects them to long-term capital gains tax, which is generally lower.
Many families feel overwhelmed by the sudden financial responsibilities that come with an IPO, especially when it comes to understanding taxes. Employees at newly public companies like SpaceX and OpenAI face complex tax scenarios due to their equity compensation. They must navigate stock price volatility and the impact of share dilution, which can affect their overall wealth. Additionally, the IRS mandates that employers withhold 22% on supplemental income from RSUs up to $1 million, and 37% for amounts exceeding that. This can lead to under-withholding if not properly managed.
Proactive tax planning is essential when addressing IPO tax considerations. Employees ought to seek guidance from tax experts to comprehend their unique circumstances, particularly concerning the effects of selling shares, the timing of sales, and possible strategies such as gifting shares to relatives in lower tax brackets to reduce tax obligations. By being informed about these IPO tax considerations, families can better prepare for the economic impacts of an IPO and make more strategic decisions regarding their investments.
Take Jay and Emma, for instance. They were feeling the weight of financial uncertainty as parents of two young kids, so they turned to Bright Advisers for help. Together, they developed a sound strategy that included enhancing tax planning and creating a personalized retirement plan. Similarly, Emily and Mark, both driven professionals, collaborated with Bright Advisers to navigate the complexities of planning their finances, granting them the freedom to decide whether or not to continue working. Their comprehensive plan focused on managing cash flow and investing wisely, which is crucial when addressing IPO tax considerations.
Allison and Brian, another couple, realized they were losing money due to inadequate tax planning. With Bright Advisers’ help, they optimized their tax situation and secured their children’s future through education funding. These narratives demonstrate how Bright Advisers assists households in making informed monetary choices, ensuring they are ready for the IPO tax considerations associated with significant occurrences like an IPO.
When families understand the tax landscape and work with a caring advisor, they can create a plan that not only addresses their current needs but also paves the way for a secure future together. Remember, past performance does not guarantee future results, and all investments carry risks. With the right support, your family can turn the challenges of an IPO into opportunities for lasting financial security. For more personalized guidance, consider joining our current client waitlist to explore how Bright Advisers can assist your family in achieving financial success.
Explore Key Tax Considerations During an IPO
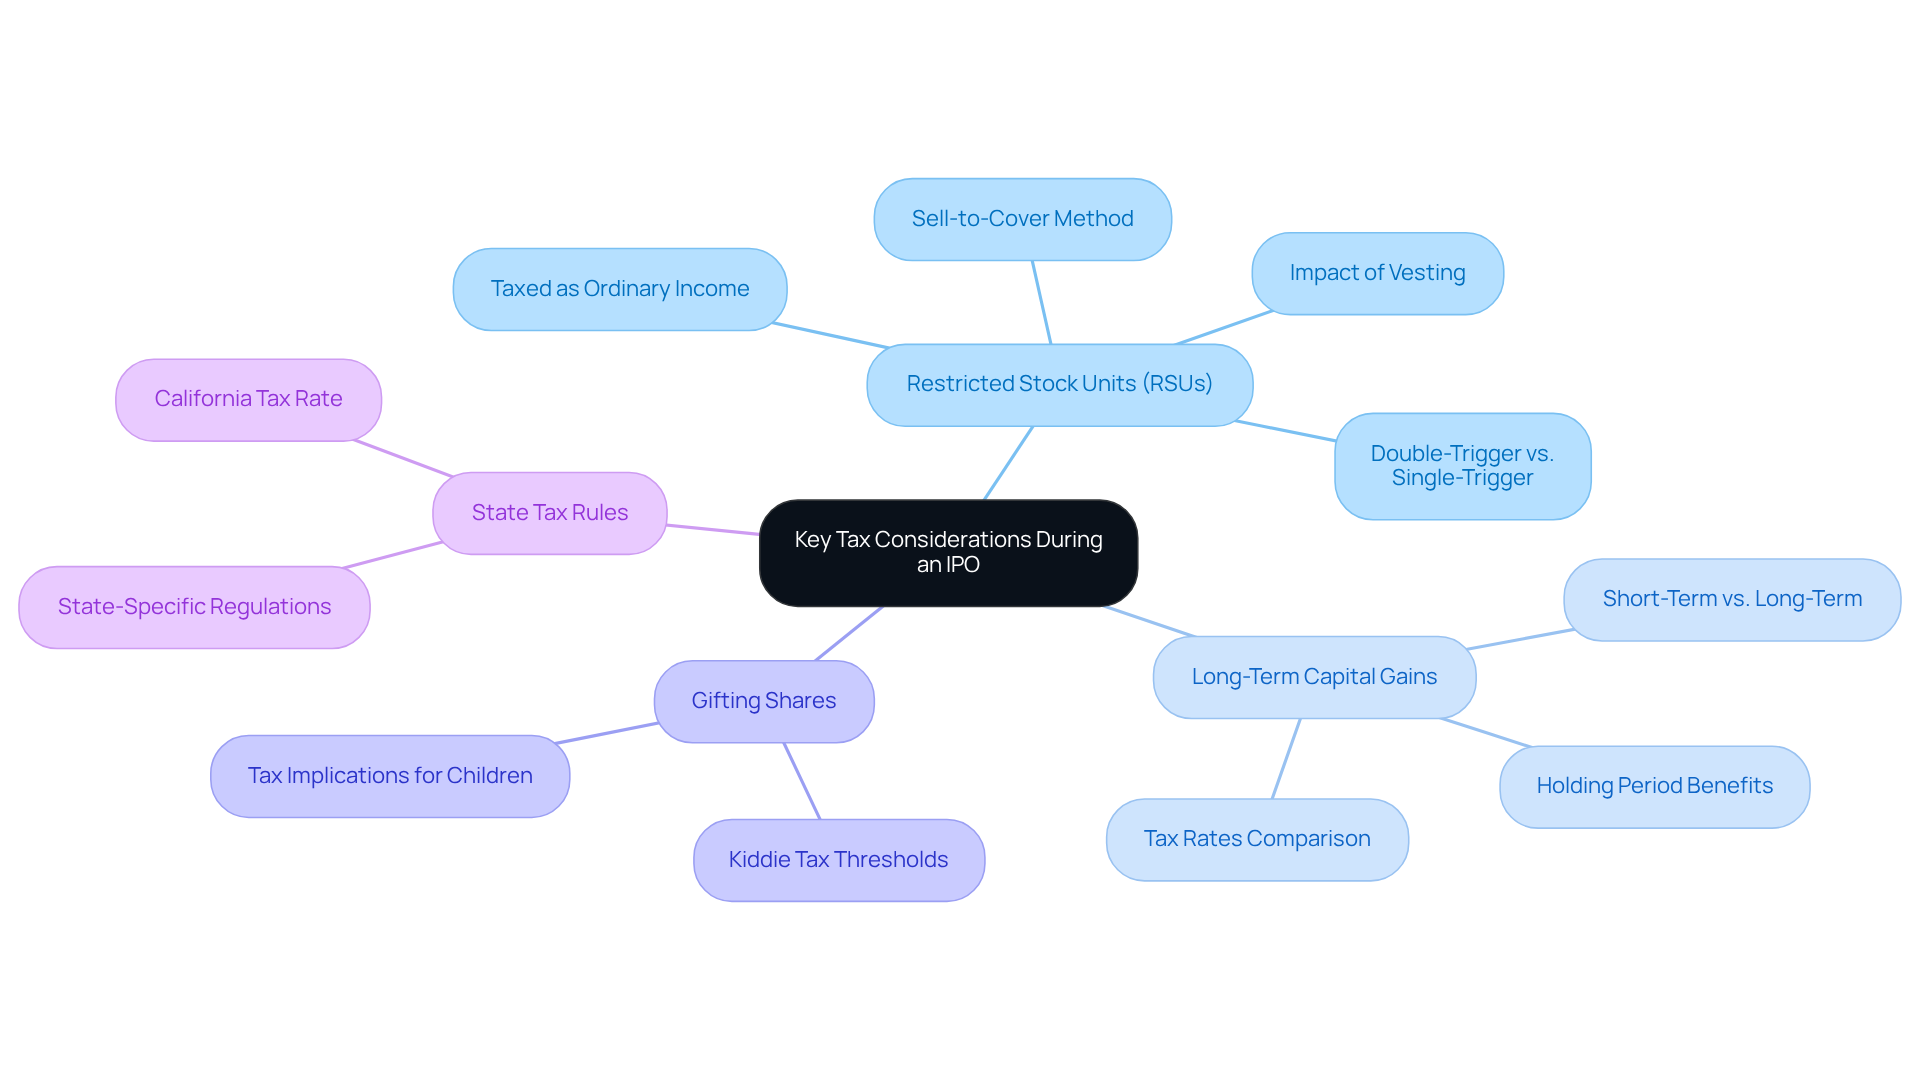
Navigating the IPO tax considerations of an IPO can be daunting, especially for young parents trying to secure their family’s future.
Imagine this: when your Restricted Stock Units (RSUs) vest, their value gets taxed as ordinary income. For example, if your RSUs vest at a value of $50,000, that amount is added to your taxable income for the year. This can lead to a significant increase in your tax liability, particularly if multiple RSUs vest at once.
Think about it – if you hold onto your shares for over a year before selling, you could benefit from lower long-term capital gains tax rates. Selling shares at a profit after that year can ease the tax burden on those profits, making timing crucial for maximizing your tax efficiency.
If you’re considering gifting shares to your kids, it’s important to know about the kiddie tax that could come into play. This tax applies to unearned income exceeding a certain threshold, which for 2026 is between $1,350 and $2,700. Understanding this can help you avoid unexpected financial obligations when passing on assets to your children.
And remember, your state might have its own tax rules that could affect your gains, so it’s worth checking into. For instance, California has a high income tax rate of 13.3%, which can significantly impact the net gains from an IPO.
By grasping these key IPO tax considerations, you can better navigate the complexities of wealth management during an IPO. Together, we can ensure that your family’s financial future remains bright and secure.
Implement Effective Tax Planning Strategies for IPOs
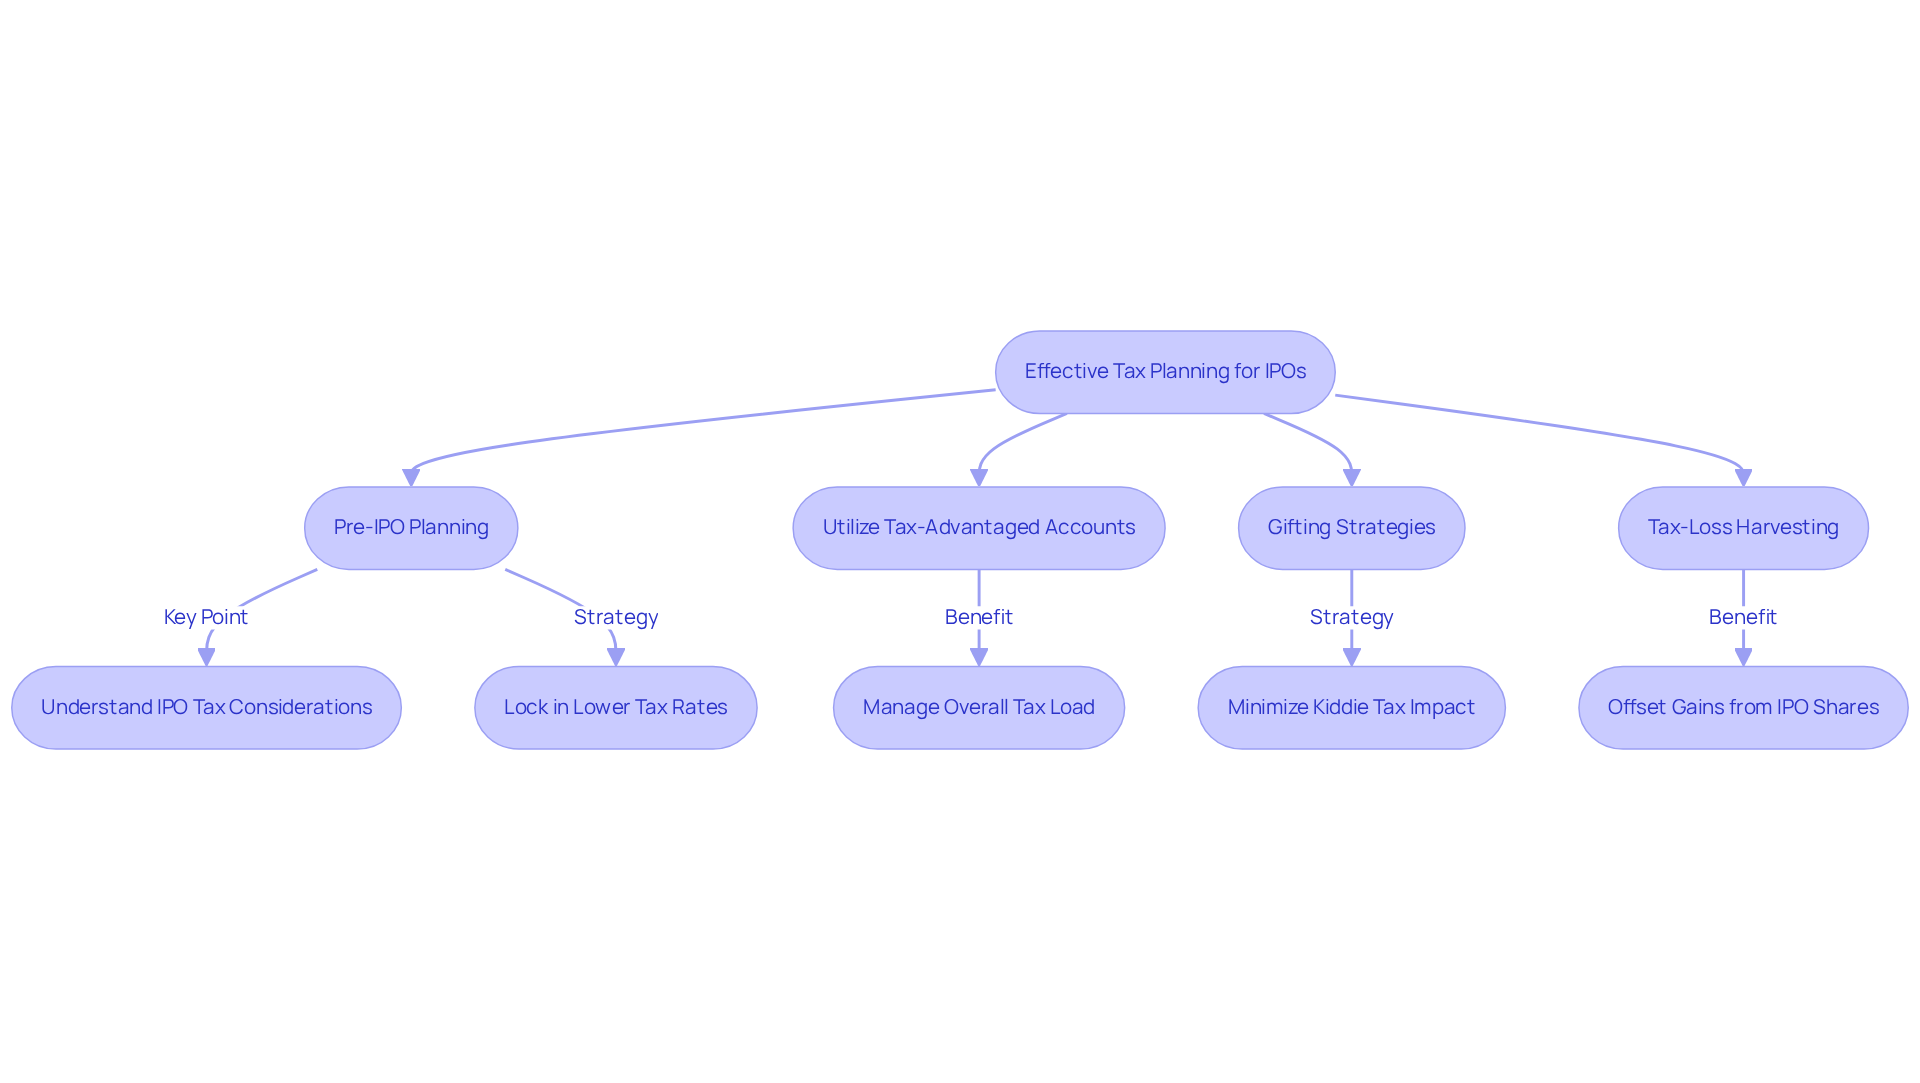
Imagine facing an IPO and feeling overwhelmed by the ipo tax considerations that accompany it. Here are some strategies to help you navigate this journey with confidence:
- Pre-IPO Planning: Engaging in tax planning well before the IPO event is essential. Understanding the ipo tax considerations related to stock options and Restricted Stock Units (RSUs) is crucial. Exercising options before the IPO tax considerations can help lock in lower tax rates, which is particularly beneficial since RSUs create ordinary income upon vesting, often coinciding with the IPO.
- Utilize Tax-Advantaged Accounts: Consider using tax-advantaged accounts, such as Health Savings Accounts (HSAs) or 529 plans for education savings. These accounts can help reduce some of the ipo tax considerations incurred from the IPO, allowing your family to manage its overall tax load more efficiently.
- Gifting Strategies: If you plan to gift shares to your children, do so strategically to minimize the impact of the kiddie tax. For 2026, you can gift up to $19,000 to each individual without affecting your lifetime federal gift/estate exemption. Gifting shares before the IPO tax considerations can help lock in a lower valuation, potentially reducing future tax burdens.
- Tax-Loss Harvesting: If you have other investments that have lost value, selling these can offset gains from IPO shares, effectively reducing your overall tax liability. This strategy is particularly useful in managing capital gains taxes and ipo tax considerations, as realized losses can help mitigate the tax impact of selling appreciated stock.
But with the right strategies, you can turn this challenge into an opportunity for your family’s financial growth. With these strategies, you can confidently approach your IPO, knowing you’re making informed decisions for your family’s future.
Seek Professional Guidance for IPO Tax Planning
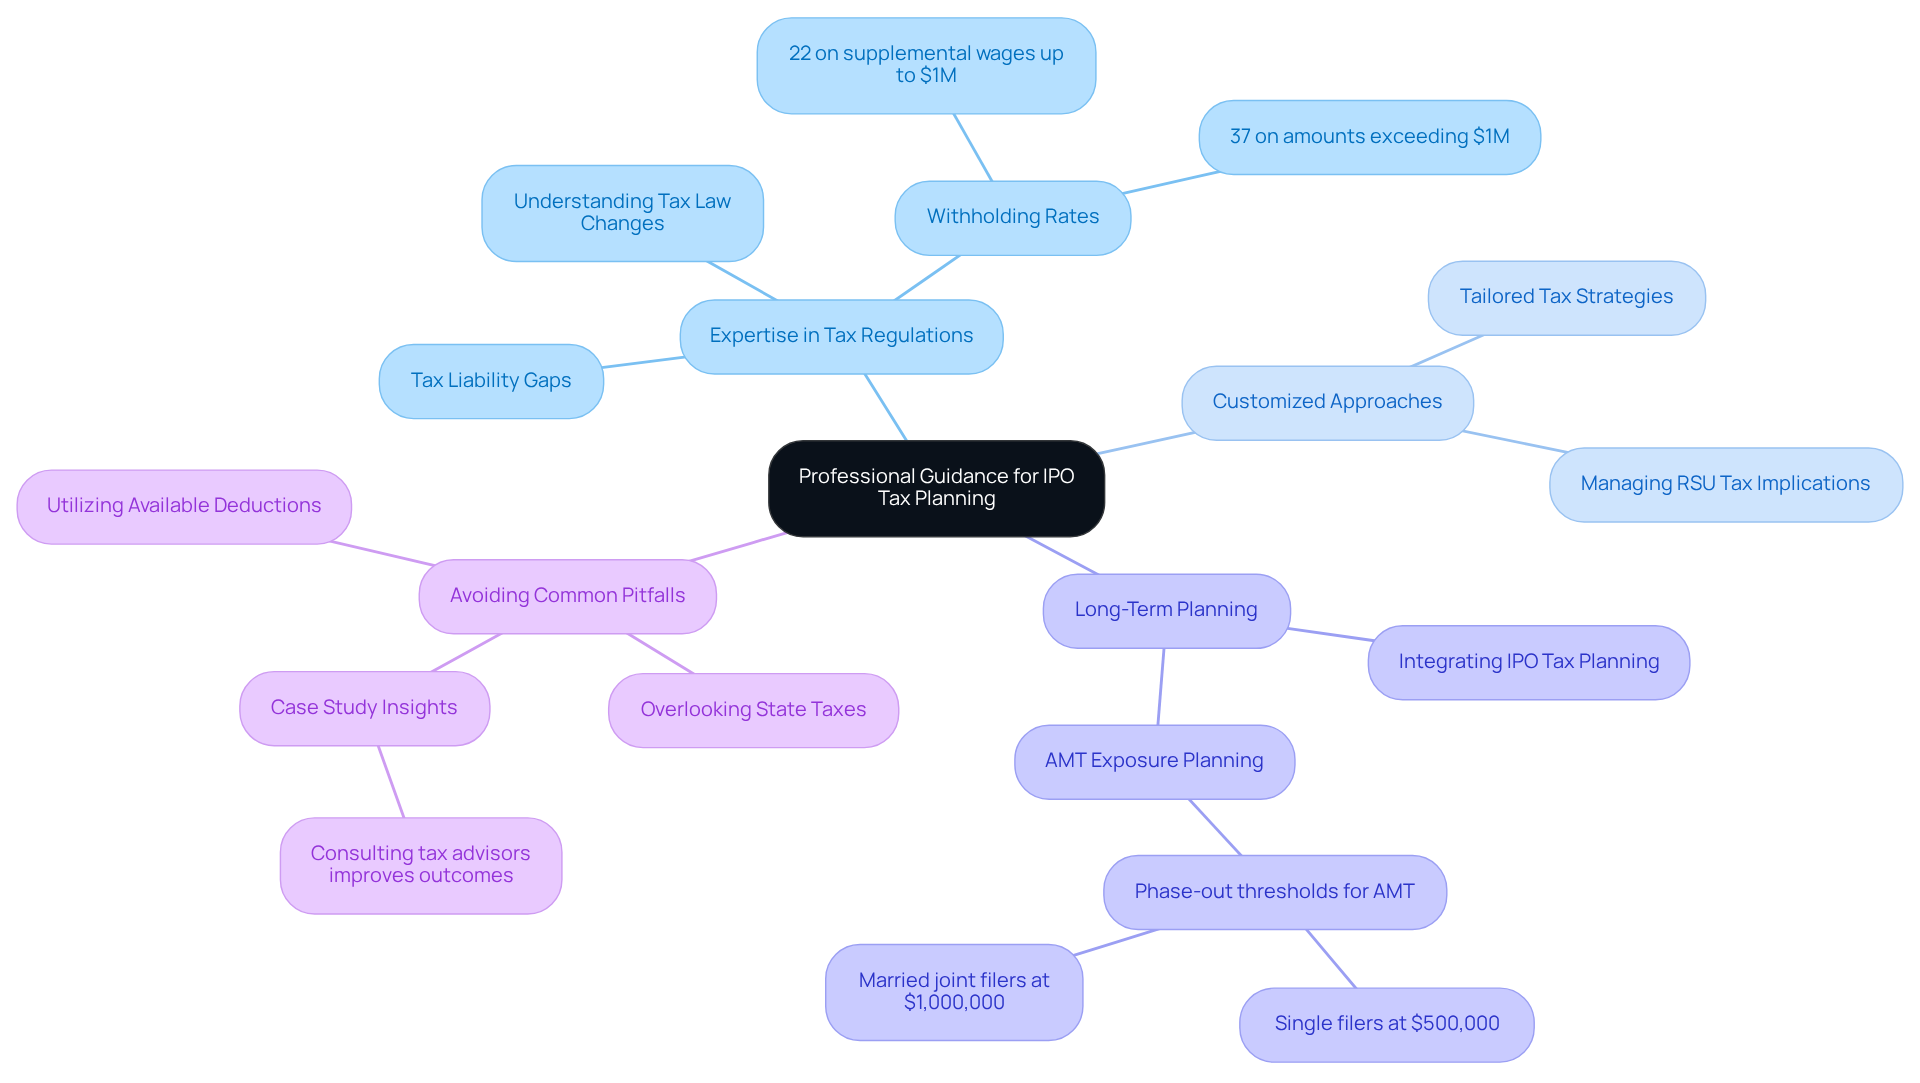
Many parents feel overwhelmed by IPO tax considerations, unsure of how to navigate this intricate landscape. Seeking professional guidance can make a world of difference in ensuring informed decision-making. Here are several key reasons to consider:
- Expertise in Tax Regulations: Tax laws are always changing, and a tax professional can provide the latest information on how these changes may affect your family’s financial situation. For instance, employers typically withhold 22% on supplemental wages up to $1 million, but they withhold 37% on amounts exceeding $1 million. This can lead to significant gaps between withheld amounts and actual tax liabilities, especially for those in higher tax brackets.
- Customized Approaches: An advisor can help create tax strategies tailored to your household’s unique situation, ensuring effective tax efficiency. This is particularly important as RSUs can create large taxable income years, potentially pushing executives into higher tax brackets.
- Long-Term Planning: Professionals can assist in integrating IPO-related tax planning into your broader financial strategy, helping align investments with your family’s long-term goals. For example, planning for the Alternative Minimum Tax (AMT) exposure is crucial, especially with the phase-out beginning at $500,000 for single filers and $1,000,000 for married joint filers in 2026.
- Avoiding Common Pitfalls: Experienced advisors can help you sidestep common mistakes that could lead to unnecessary tax liabilities, such as overlooking state taxes or failing to utilize available deductions. A case study shows that employees who consulted tax advisors before their IPO were more likely to adopt effective tax strategies, greatly enhancing their financial outcomes, as indicated by Rebecca Lester’s research.
Together with a caring advisor, families can feel confident that their financial planning is in good hands, focused solely on their needs. This proactive strategy not only prepares households for the immediate IPO tax considerations of an IPO but also establishes a foundation for long-term financial success. Additionally, Bright Advisers offers a transparent, all-inclusive fee structure with no hidden fees, commissions, or trade fees. Interested families are encouraged to join our current client waitlist to start their journey towards financial security. All advisory services are provided through Lifeworks Advisors, a registered investment adviser. Please note that past performance does not guarantee future results, and securities investments are subject to risk.
Conclusion
It can feel overwhelming to think about how IPO tax considerations impact your family’s future, especially when you’re juggling so many responsibilities. For families, the financial implications of an IPO can be significant, especially if you have stock options or RSUs to consider. It’s important to understand how these factors can affect your family’s tax situation and financial planning.
We’ve shared some key insights that can help you navigate tax planning, understand capital gains, and know when to seek professional help. It’s essential to know that RSUs are taxed as ordinary income, and the timing of when you sell shares can affect your capital gains tax. There are also strategies, like gifting shares or using tax-advantaged accounts, that can help ease your tax burden.
For instance, families like Jay and Emma, and Emily and Mark, found success in navigating these challenges with the caring support of Bright Advisers. The journey through IPO tax considerations can feel daunting, but with the right strategies and support, you can turn challenges into opportunities for your family’s financial growth. Working with a fiduciary advisor means you’ll get personalized advice that fits your family’s unique situation, helping you make informed decisions for a secure future.
If you’re ready to navigate this landscape with confidence, consider joining our waitlist at Bright Advisers to discover how our personalized support can help your family thrive.
Frequently Asked Questions
What is an Initial Public Offering (IPO)?
An Initial Public Offering (IPO) is the process through which a private company offers its shares to the public for the first time, allowing it to raise capital and become publicly traded.
How are Restricted Stock Units (RSUs) taxed during an IPO?
When RSUs vest, they are taxed as ordinary income based on their fair market value. For example, if an employee receives shares valued at $100,000 during an IPO, they may face a tax rate as high as 37%, depending on their income bracket.
What are the capital gains tax implications for selling shares after an IPO?
Gains from selling shares may be subject to capital gains tax. If shares are sold within a year of vesting, they incur short-term capital gains tax. Holding shares for over a year subjects them to long-term capital gains tax, which is generally lower.
What challenges do employees at newly public companies face regarding taxes?
Employees at newly public companies often deal with complex tax scenarios due to equity compensation, stock price volatility, and share dilution, which can affect their overall wealth. Additionally, the IRS requires employers to withhold 22% on supplemental income from RSUs up to $1 million and 37% for amounts exceeding that, potentially leading to under-withholding.
Why is proactive tax planning important for families during an IPO?
Proactive tax planning is essential to navigate IPO tax considerations effectively. It helps families understand the implications of selling shares, the timing of sales, and strategies such as gifting shares to relatives in lower tax brackets to reduce tax obligations.
How can families prepare for the financial impacts of an IPO?
Families can prepare by seeking guidance from tax experts to understand their unique circumstances and develop a strategic plan that addresses their current needs and future financial security.
Can you provide examples of how Bright Advisers has helped families with IPO tax considerations?
Bright Advisers has assisted families like Jay and Emma, who developed a sound strategy for tax planning and retirement. Similarly, Emily and Mark navigated financial complexities with Bright Advisers’ help, while Allison and Brian optimized their tax situation to secure their children’s future through education funding.
What should families remember regarding investment risks and past performance?
Families should remember that past performance does not guarantee future results and that all investments carry risks. With the right support, families can turn the challenges of an IPO into opportunities for lasting financial security.
List of Sources
- Clarify IPO Fundamentals and Tax Implications
- What is an RSU? How They Work, Benefits, & Taxes (https://carta.com/learn/equity/rsu)
- IPO Process: A Roadmap for Founders Going Public | Morgan Stanley at Work (https://morganstanley.com/atwork/employees/learning-center/articles/preparing-for-an-ipo)
- Tax Tips And Warnings For IPO Company Employees And Their Advisors (https://forbes.com/sites/brucebrumberg/2026/06/23/tax-tips-and-warnings-for-ipo-company-employees-and-their-advisors)
- RSUs and Your Company’s IPO: Taxes and Other Considerations (https://janefinancial.com/blog/ipo-rsu)
- What is an IPO? Initial Public Offerings Explained (https://schwab.com/learn/story/what-is-an-ipo)
- Explore Key Tax Considerations During an IPO
- How Are My RSUs Taxed, and What Can I Do to Pay Less in Taxes? (https://blog.sweeneyconrad.com/how-are-my-rsus-taxed-and-what-can-i-do-to-pay-less-in-taxes)
- What is an RSU? How They Work, Benefits, & Taxes (https://carta.com/learn/equity/rsu)
- How Restricted Stock Units (RSUs) are Taxed in California – Summitry (https://summitry.com/blog/rsu-taxes-in-california)
- Restricted Stock and Performance Stock Taxes: A Guide (https://schwab.com/learn/story/rsu-taxes-and-psu-taxes)
- How Are RSUs Taxed? | Monument Wealth Management (https://monumentwealthmanagement.com/resource/how-are-rsus-taxed)
- Implement Effective Tax Planning Strategies for IPOs
- Tax Tips And Warnings For IPO Company Employees And Their Advisors (https://forbes.com/sites/brucebrumberg/2026/06/23/tax-tips-and-warnings-for-ipo-company-employees-and-their-advisors)
- IPO Planning for Employees: Tax Strategies, Risks, and What to Do Before You Sell (https://missionwealth.com/resources/insights/ipo-planning-for-employees)
- IPO Tax Planning for Employees: What to Do Before Your Shares Become Tradable – True Wealth Design (https://truewealthdesign.com/ipo-tax-planning-for-employees)
- IPO tax readiness: Considerations for executives and private equity sponsors (https://rsmus.com/insights/services/business-tax/ipo-tax-readiness-considerations.html)
- What to Know About the Kiddie Tax for 2026 Planning (https://doeren.com/viewpoint/what-to-know-about-the-kiddie-tax-for-2026-planning)
- Seek Professional Guidance for IPO Tax Planning
- IPO Tax Planning for Employees: What to Do Before Your Shares Become Tradable – True Wealth Design (https://truewealthdesign.com/ipo-tax-planning-for-employees)
- IPO Planning for Employees: Tax Strategies, Risks, and What to Do Before You Sell (https://missionwealth.com/ipo-planning-for-employees)
- Tax avoidance has become a key part of IPO planning (https://siepr.stanford.edu/news/tax-avoidance-has-become-key-part-ipo-planning)
- How to Prepare for an IPO: Financial & Tax Planning Guide — Brooklyn Fi (https://brooklynfi.com/blog/how-to-prepare-for-an-ipo-2026)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading