

Key Highlights
- Incentive Stock Options (ISOs) allow employees to buy shares at a set price, potentially benefiting from lower capital gains tax rates if specific conditions are met.
- Non-Qualified Stock Options (NSOs) can be offered to a wider group and are taxed as ordinary income upon exercise, leading to a higher tax burden.
- Understanding the iso vs nso tax implications is crucial for young parents planning their financial futures, as it can significantly affect tax liabilities.
- Exercising ISOs early in the year can minimise Alternative Minimum Tax (AMT) implications, while exercising NSOs during lower income years can reduce overall tax burdens.
- Cashless transactions for NSOs can help manage cash flow by selling shares to cover purchase prices and taxes.
- Long-term holding of ISOs can lead to tax savings, provided the shares are held for the required duration to qualify for long-term capital gains treatment.
- Consulting a financial advisor can help families navigate the complexities of stock options and develop personalised strategies for financial security.
- Effective tax planning strategies include utilising tax-advantaged accounts, monitoring income levels, considering the 83(b) election, and working with tax professionals.
Introduction
Many parents feel lost when it comes to stock options, unsure of where to start. It’s important to understand the differences between Incentive Stock Options (ISOs) and Non-Qualified Stock Options (NSOs). Each type carries distinct tax implications that can significantly impact your family’s finances.
Imagine making choices that not only optimize your tax outcomes but also align with your family’s long-term goals. Together, we can navigate these important financial choices with confidence.
Define ISO and NSO: Key Concepts and Differences
Imagine trying to secure your family’s future while navigating the complexities of stock options. Let’s explore two types of stock options that companies offer: Incentive Stock Options and Non-Qualified Stock Options. Each has its own unique features and the iso vs nso tax implications.
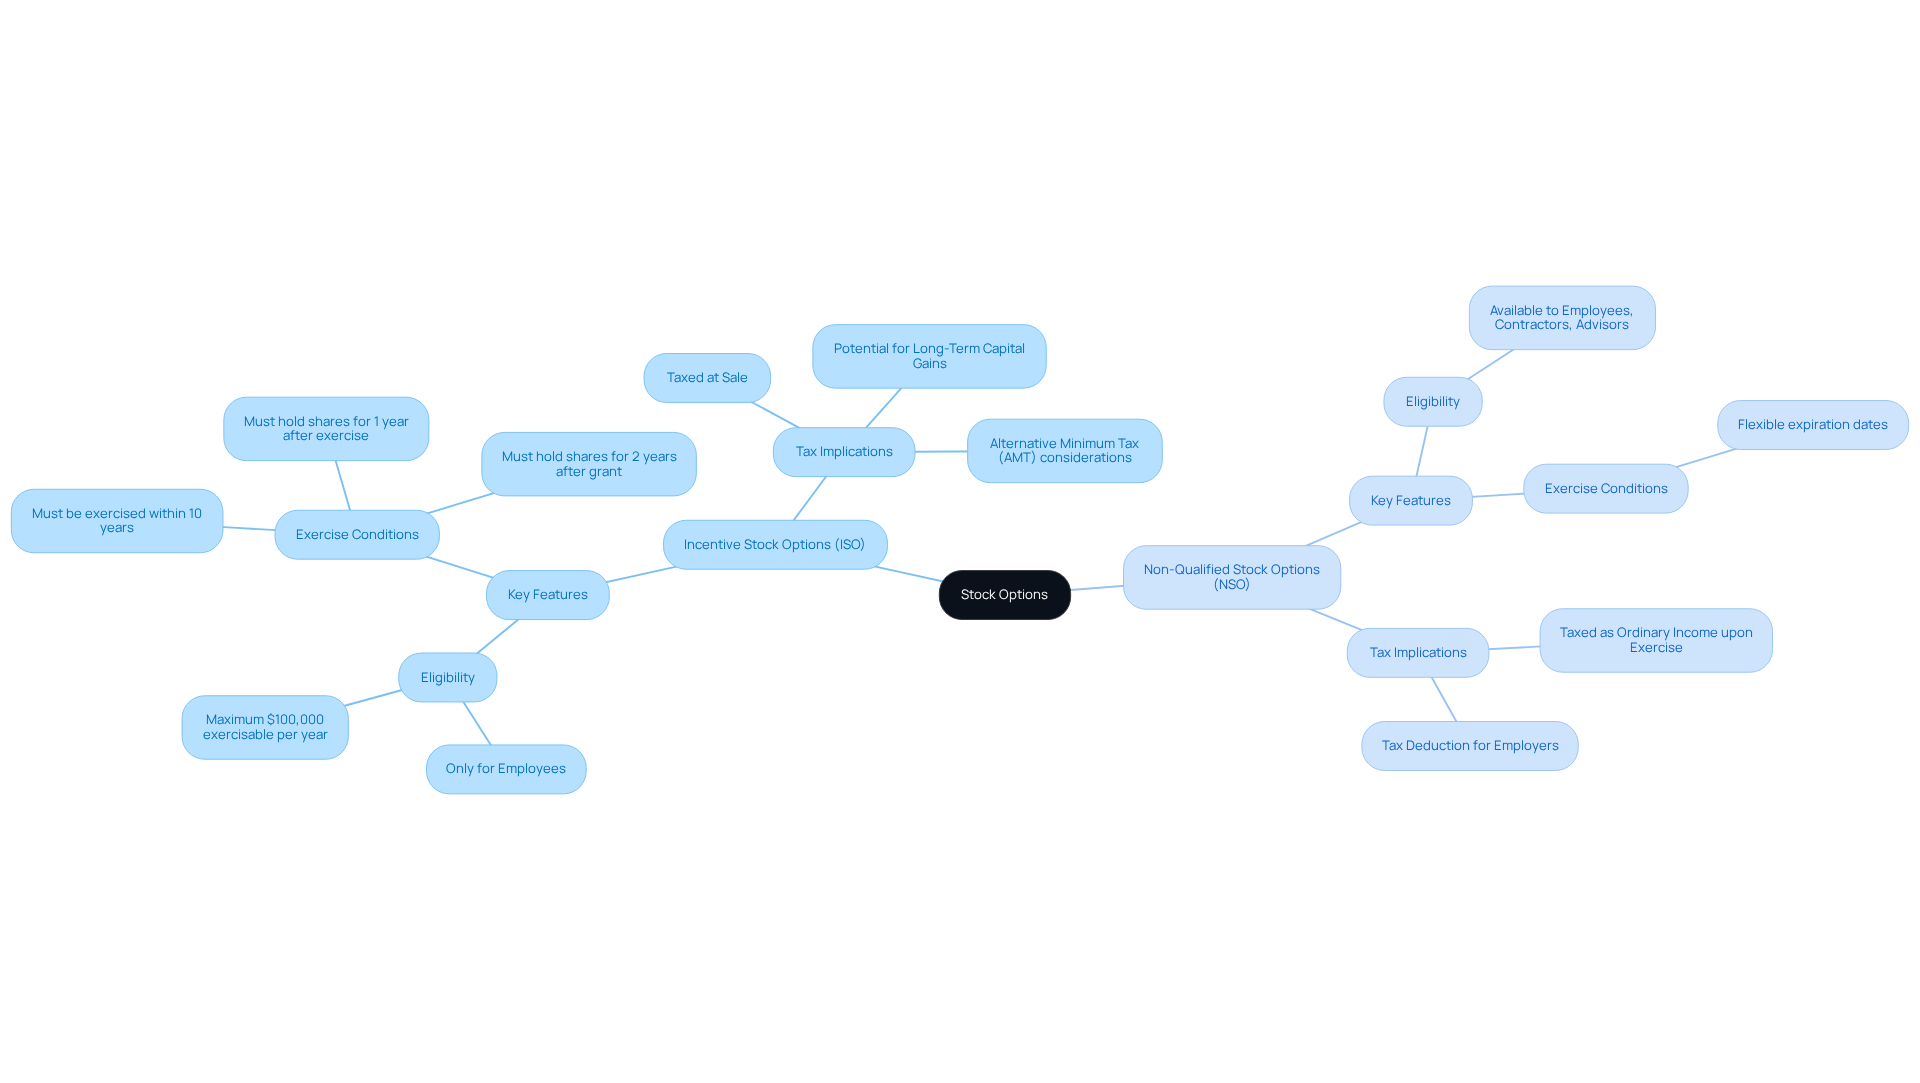
Incentive Stock Options let employees buy shares at a set price. If certain conditions are met, profits could be taxed at lower capital gains rates instead of regular income rates. But there are strict eligibility requirements. For instance, you can only exercise up to $100,000 per year, and you must hold the shares for a specific period to enjoy these tax benefits.
On the other hand, Non-Qualified Stock Options can be offered to a broader group, including employees, contractors, and advisors. When you exercise non-qualified stock options, the difference between the exercise price and the stock’s fair market value is taxed as ordinary income. This can mean a higher tax burden for you.
It’s important for young parents to understand these differences as they think about their financial strategies and plan for their children’s futures. Choosing between incentive stock options and non-qualified stock options can greatly affect your iso vs nso tax implications and financial outcomes. It’s essential to evaluate these options carefully.
Making informed choices today can pave the way for a brighter tomorrow for your children.
Explore Tax Implications: How ISOs and NSOs Are Taxed
Understanding the iso vs nso tax implications is vital for young parents who are planning for their family’s future.
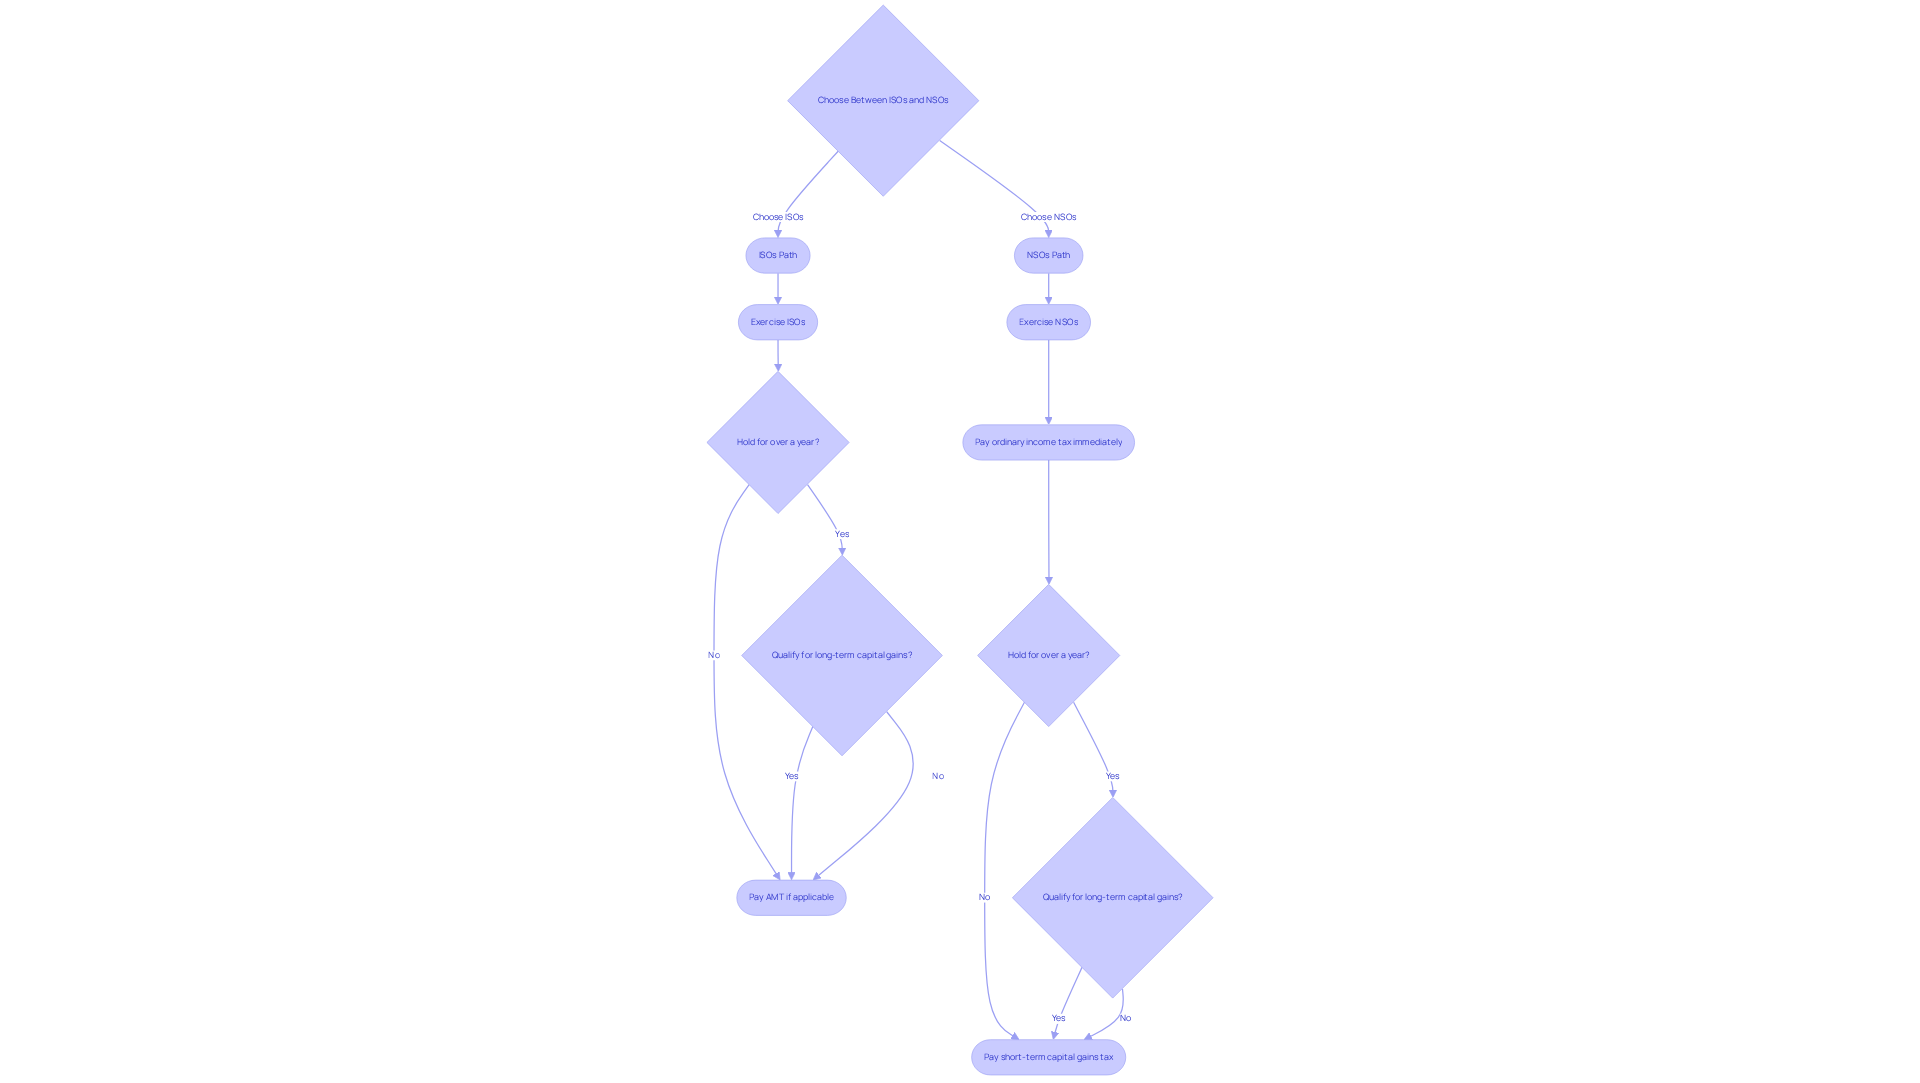
But here’s the thing: the difference between what you pay for the stock and its current value could lead to something called the Alternative Minimum Tax (AMT). Exercising ISOs generally doesn’t trigger regular income tax right away. If you hold onto those shares for over a year after exercising and two years from the grant date, any gains could qualify for long-term capital gains rates, which are usually lower than ordinary income tax rates. Imagine if you exercised your ISOs and the stock appreciated significantly; understanding AMT implications is essential to avoid unexpected tax bills.
On the flip side, Non-Qualified Stock Options incur taxes right when you exercise them. The difference between the strike price and the fair market value is taxed as ordinary income, which means you’ll pay income tax, Social Security, and Medicare taxes. If you sell those shares right away, you’ll only face ordinary income tax on the difference. However, if you hold onto them, you might benefit from reduced long-term capital gains rates if you keep them for over a year.
Navigating the iso vs nso tax implications can feel daunting, especially when you’re focused on your family’s future. Without a clear understanding, you might face unexpected tax bills that could impact your family’s financial stability. With California’s high tax rates, particularly the AMT, strategic planning that considers iso vs nso tax implications can help mitigate tax liabilities and enhance financial outcomes for families. Together, we can navigate these complexities, ensuring you make choices that safeguard your family’s financial well-being.
Strategize Your Options: When and How to Exercise ISOs and NSOs
Imagine feeling confident about your financial future while juggling the demands of parenthood. Exercising stock options can feel overwhelming, especially when balancing family priorities. Here are some key strategies that can help you navigate this journey:
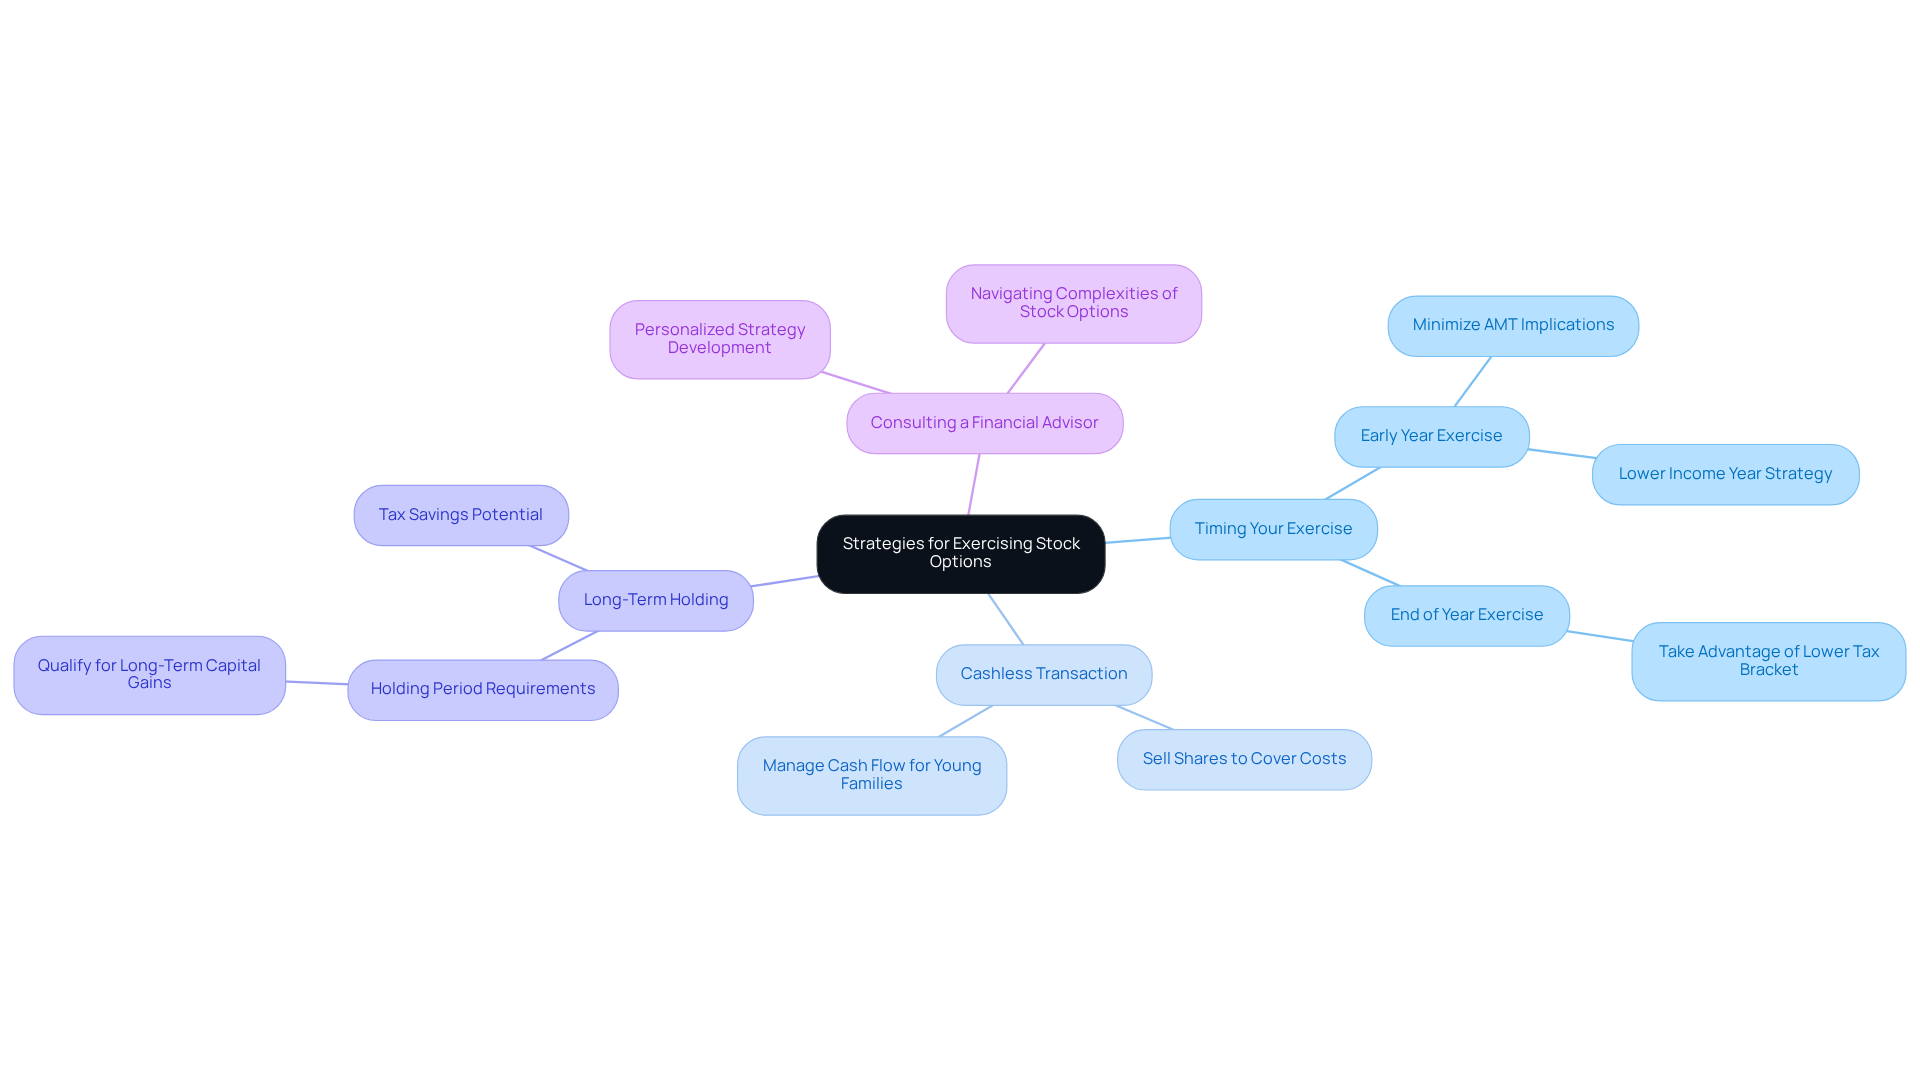
- Timing Your Exercise: Consider exercising your ISOs early in the year to minimize potential Alternative Minimum Tax (AMT) implications. If you expect a lower income year, such as during a sabbatical or following a job change, exercising your Non-Qualified Stock Options during this time can help lessen your overall tax burden.
- Cashless Transaction: For non-qualified stock options, a cashless transaction enables you to sell sufficient shares to cover the purchase price and taxes, reducing out-of-pocket costs. This strategy is particularly useful for young families who need to manage cash flow carefully, as it avoids tying up significant amounts of money in company stock.
- Long-Term Holding: If you exercise incentive stock options, retaining the shares for the necessary duration can result in considerable tax savings. Ensure you understand the holding period requirements to qualify for long-term capital gains treatment, which can be more favorable than ordinary income tax rates.
- Reaching out to a financial advisor can be a comforting step towards securing your family’s financial future. Given the complexities of stock options and the iso vs nso tax implications, consulting with a financial advisor can help you develop a personalized strategy that aligns with your family’s financial goals. This guidance is crucial for navigating the intricacies of stock options and maximizing their value for your family’s future.
With the right support, you can transform stock options into a stepping stone for your family’s dreams.
Plan for Success: Tax Planning Strategies for ISOs and NSOs
Imagine facing unexpected tax bills while trying to provide for your family – it’s a challenge many young parents encounter. Effective tax planning is crucial for addressing the iso vs nso tax implications of Incentive Stock Options (ISOs) and Non-Qualified Stock Alternatives. Here are several strategies specifically designed for young parents:
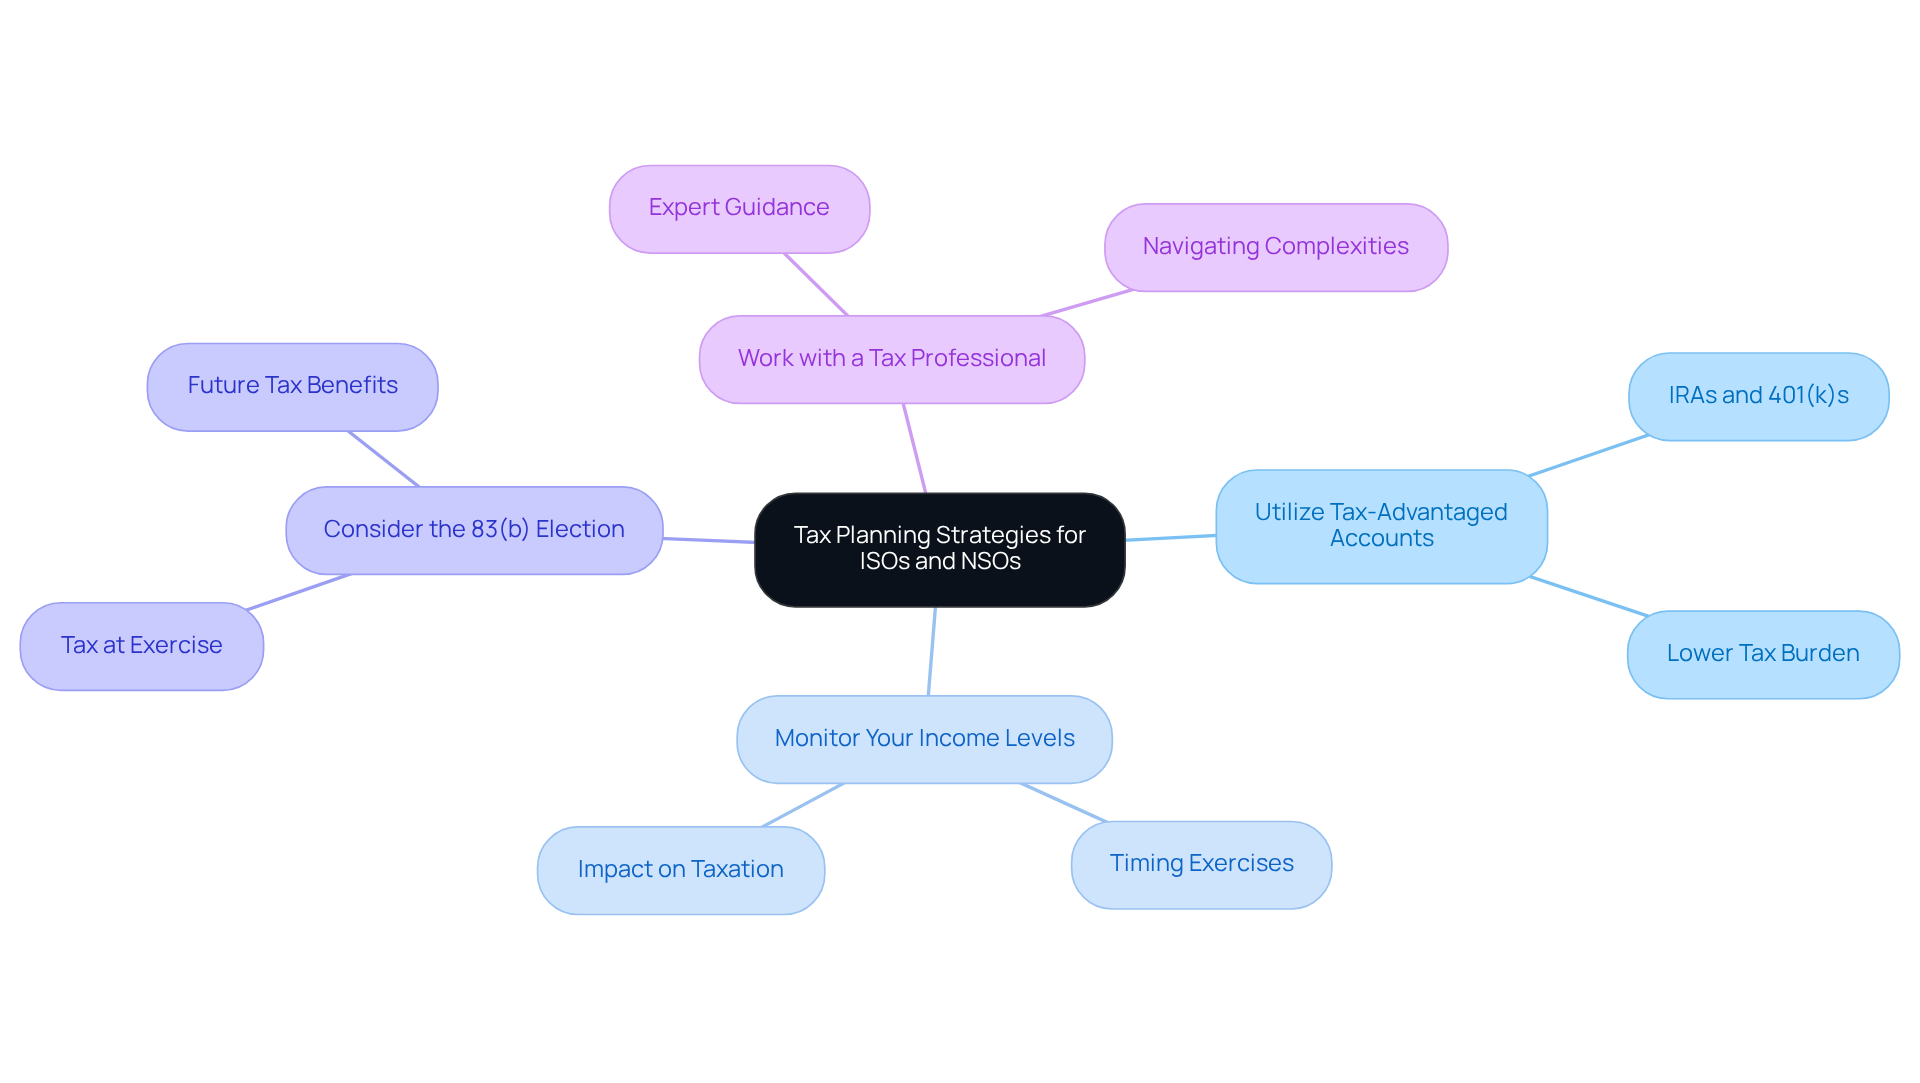
- Utilize Tax-Advantaged Accounts: Leverage tax-advantaged accounts like IRAs or 401(k)s to help lower your tax burden. This can help lower your tax burden, making it easier to manage your family’s finances.
- Monitor Your Income Levels: Pay close attention to your income levels when planning to utilize stock options. Working out in a year when your earnings are reduced can lessen the tax effect, especially for non-qualified stock options, which are taxed as regular income at the moment of utilization.
- Consider the 83(b) Election: If applicable, the 83(b) election allows you to pay taxes on the fair market value of the stock at the time of exercise rather than when the stock vests. This can be advantageous if you anticipate a significant increase in stock value, potentially lowering your future tax liabilities.
- Work with a Tax Professional: Working with a tax professional means you have someone in your corner, ready to help you navigate your unique financial landscape. Their expertise ensures you are well-prepared for any tax obligations arising from exercising your stock options.
Navigating the iso vs nso tax implications can feel daunting, especially when you’re juggling family responsibilities. Without proper planning, you might find yourself facing unexpected tax bills that strain your family’s budget. By taking these steps, you can protect your family’s financial future and enjoy peace of mind.
Conclusion
Imagine trying to secure your family’s future while feeling lost in the complexities of stock options. Understanding the differences between ISOs and NSOs can help families make choices that support their financial goals. The decisions you make today regarding stock options can significantly influence your family’s financial stability and growth.
Think about how knowing the tax treatments of ISOs and NSOs can change your family’s financial journey. ISOs offer potential tax advantages if certain conditions are met, while NSOs are taxed as ordinary income upon exercise. Strategies like timing exercises and utilizing tax-advantaged accounts can help families navigate these complexities effectively. By understanding these nuances, parents can better manage their financial responsibilities and plan for their children’s futures.
Managing stock options is more than just numbers; it’s about ensuring your children have the financial wisdom to thrive. Working with a financial advisor can help you create a plan that makes the most of your stock options and reduces tax burdens. By taking these steps, you’re not just planning for tomorrow; you’re building a brighter future for your children.
Frequently Asked Questions
What are Incentive Stock Options (ISOs)?
Incentive Stock Options (ISOs) allow employees to purchase shares at a predetermined price, with potential tax benefits if certain conditions are met, such as holding the shares for a specific period.
What are Non-Qualified Stock Options (NSOs)?
Non-Qualified Stock Options (NSOs) can be offered to a wider range of individuals, including employees, contractors, and advisors. When exercised, the difference between the exercise price and the stock’s fair market value is taxed as ordinary income.
What are the tax implications of ISOs?
If certain conditions are met, profits from ISOs may be taxed at lower capital gains rates instead of regular income rates, but there are strict eligibility requirements, including a limit of $100,000 that can be exercised per year.
What are the tax implications of NSOs?
The difference between the exercise price and the fair market value of the stock is taxed as ordinary income when NSOs are exercised, which can result in a higher tax burden.
Why is it important for young parents to understand the differences between ISOs and NSOs?
Understanding these differences is crucial for young parents as they plan their financial strategies and consider the long-term financial outcomes for their children, as the choice between ISOs and NSOs can significantly impact their financial future.
What should individuals consider when choosing between ISOs and NSOs?
Individuals should carefully evaluate the tax implications, eligibility requirements, and how each option aligns with their financial goals and strategies for securing their family’s future.
List of Sources
- Define ISO and NSO: Key Concepts and Differences
- ISOs vs. NSOs: What You Need to Know (https://citizensbank.com/private-banking/insights/iso-vs-nso.aspx)
- How companies decide between incentive and nonqualified stock options (https://rsmus.com/insights/services/business-tax/incentive-stock-options-nonqualified-stock-options.html)
- ISOs v. NSOs: What’s the Difference? | Cooley GO (https://cooleygo.com/isos-v-nsos-whats-the-difference)
- Explore Tax Implications: How ISOs and NSOs Are Taxed
- Exercising Stock Options in California: 2026 Tax Guide (https://esofund.com/blog/exercising-stock-options-in-california)
- How Stock Options Are Taxed: ISO vs NSO | Darrow Wealth Management (https://darrowwealthmanagement.com/blog/how-are-stock-options-taxed)
- How Stock Options Are Taxed: ISO vs NSO Tax Treatments (https://carta.com/learn/equity/stock-options/taxes)
- How are stock options taxed in California? — Secfi (https://secfi.com/learn/how-are-stock-options-taxed-in-california)
- Strategize Your Options: When and How to Exercise ISOs and NSOs
- Exercising Stock Options in California: 2026 Tax Guide (https://esofund.com/blog/exercising-stock-options-in-california)
- What to Do with Stock Options: When to Exercise & Tax Planning Strategies (https://aspiriant.com/fathom/stock-options-exercise-tax-planning)
- ISOs vs. NSOs: Options, Taxes, and Cashless Exercise Explained (https://nasdaqprivatemarket.com/youve-got-options-what-to-know-about-isos-and-nsos)
- Exercising Stock Options: Taxes, Timing & Strategies (https://jpmorganworkplacesolutions.com/insights/exercise-stock-options)
- Cashless Exercise of Stock Options (https://carta.com/learn/equity/stock-options/exercising/cashless-exercise)
- Plan for Success: Tax Planning Strategies for ISOs and NSOs
- California Capital Gains Tax: A Comprehensive Guide (https://definefinancial.com/blog/california-capital-gains-tax-a-comprehensive-guide)
- California’s Long-term Capital Gains Tax (https://edelmanfinancialengines.com/education/tax/capital-gains-tax-california)
- Exercising Stock Options in California: 2026 Tax Guide (https://esofund.com/blog/exercising-stock-options-in-california)
- Tax Planning Strategies for Incentive Stock Options (ISOs) (https://cbh.com/insights/articles/tax-planning-strategies-for-incentive-stock-options-isos)
- Stock Option Tax Planning in San Francisco | SD Mayer (https://sdmayer.com/stock-option-tax-planning)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading