

Key Highlights
- Incentive Stock Options (ISOs) allow the purchase of company stock at a predetermined price, potentially offering tax savings but may trigger the Alternative Minimum Tax (AMT).
- Restricted Stock Units (RSUs) are commitments to provide shares after meeting vesting conditions, taxed as ordinary income upon vesting without an exercise price.
- ISOs do not incur taxes at grant or exercise, allowing families to defer tax liabilities until shares are sold, while RSUs are taxed at vesting, creating immediate cash flow challenges.
- Families should consider tax implications of ISOs and RSUs, including AMT exposure and potential long-term capital gains rates for ISOs if holding periods are met.
- Consulting with a tax advisor can help families navigate the complexities of equity compensation and optimise their financial strategies.
- Diversification and timely decision-making regarding the sale of stock options or RSUs can mitigate risks and enhance financial stability.
Introduction
Many families feel lost when it comes to understanding equity compensation, especially when it comes to making the right choices for their future. It’s important to know the differences between Incentive Stock Options (ISOs) and Restricted Stock Units (RSUs), as each option has unique tax implications that can significantly affect family finances.
Imagine making choices that not only benefit your family today but also secure your future. How can families make informed decisions that optimize their tax strategies while aligning with their long-term financial goals? Without clarity, families might make choices that could jeopardize their financial well-being.
This article offers insights and strategies to help families effectively manage their equity compensation and avoid unexpected tax burdens.
Define ISOs and RSUs: Key Concepts for Families
Imagine feeling lost in the maze of equity compensation while trying to secure your family’s future.
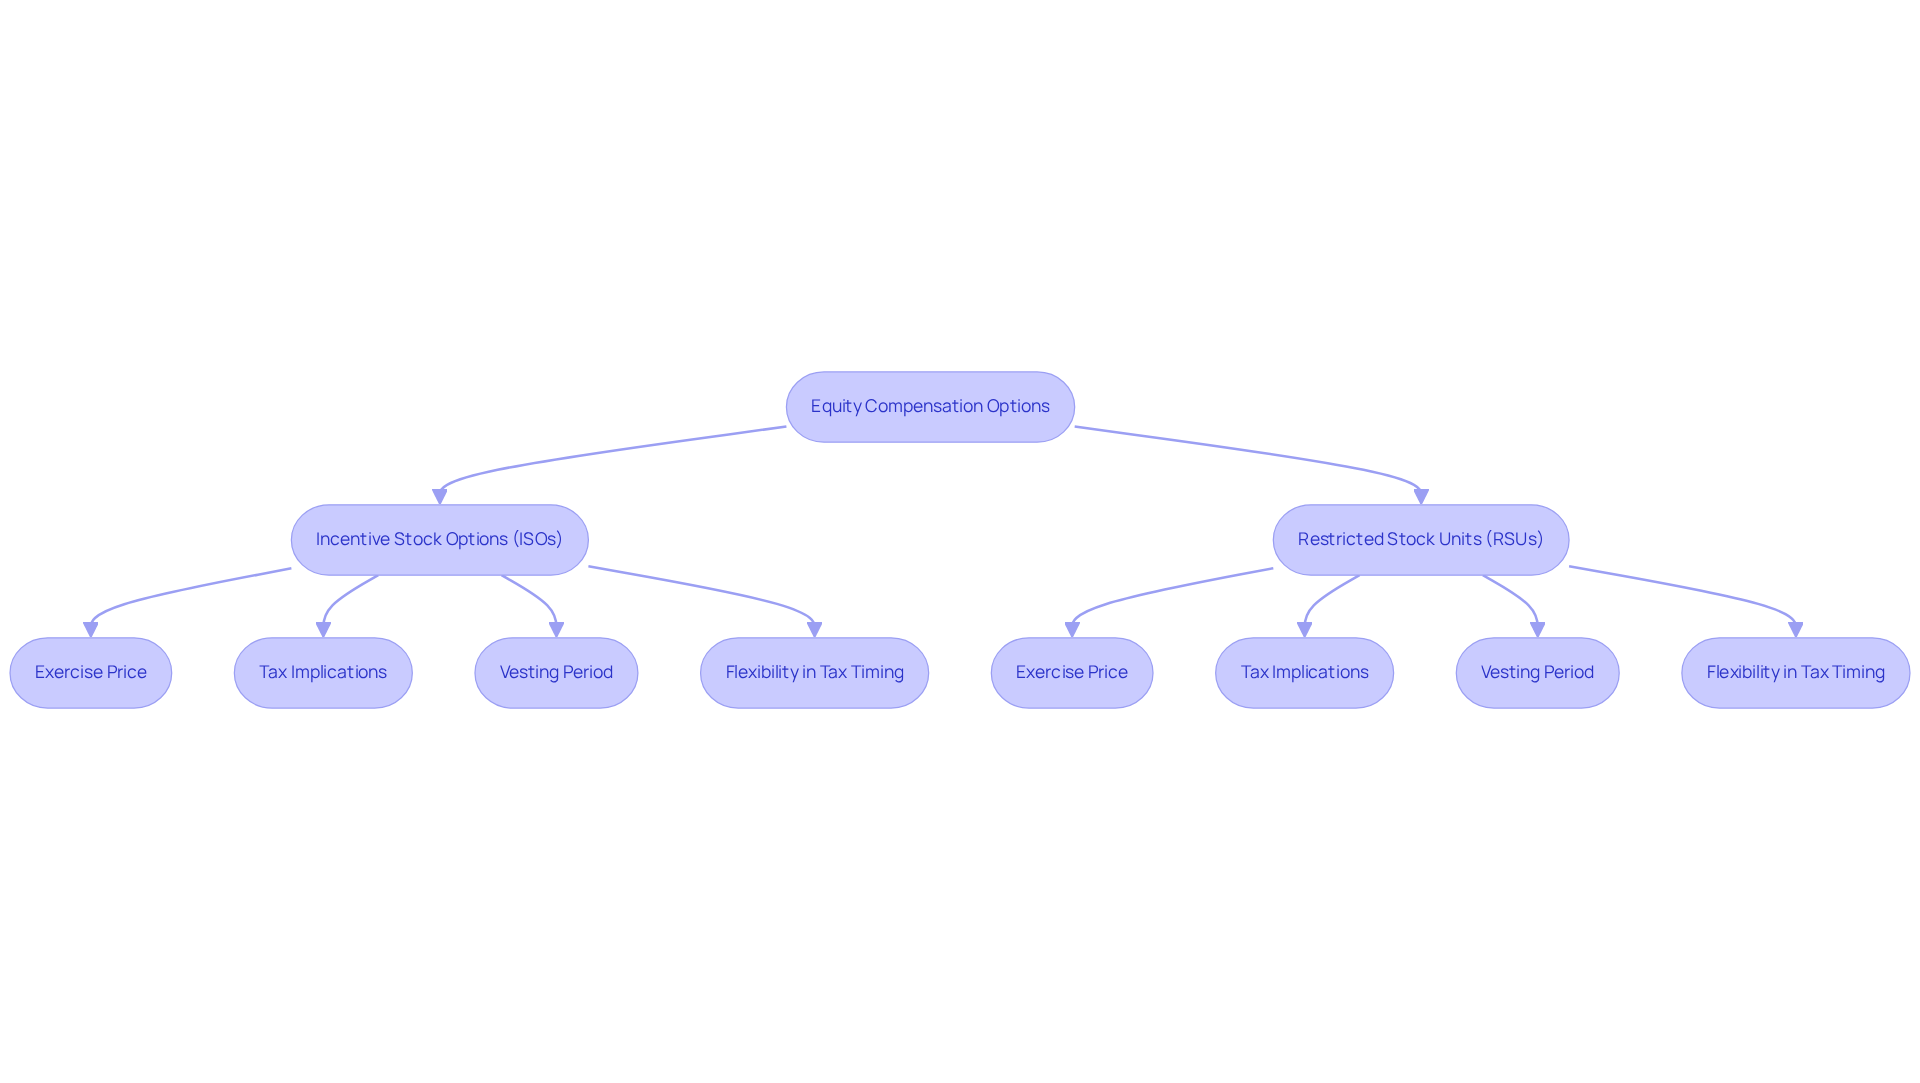
Incentive Stock Options: These options grant you the right to purchase company stock at a predetermined price, known as the exercise price. They might help you save on taxes, but it’s important to know the conditions involved, like holding the assets for a specific duration after exercising the options. However, exercising stock options can trigger the Alternative Minimum Tax (AMT), making it essential to consider iso vs rsu tax implications to avoid unexpected tax liabilities.
Restricted Stock Units: Unlike Incentive Stock Options, these are commitments to provide shares of stock once specific conditions, usually a vesting period, are met. Once vested, restricted stock units are taxed as ordinary income based on their fair market value at the time of vesting. The good news? You don’t need to pay an exercise price for restricted stock units, making them more straightforward regarding tax implications.
Navigating the world of equity compensation can feel overwhelming, especially when trying to balance family needs and financial goals. Misunderstanding these options could lead to unexpected tax burdens, impacting your family’s financial stability. With stock options, you can manage the timing of your tax responsibilities, potentially spreading them across years with lower income. In contrast, when examining iso vs rsu tax implications, RSUs don’t offer this flexibility, as you face tax liabilities upon vesting, regardless of whether you sell the shares immediately. By understanding these options, you can make informed decisions that protect your family’s financial well-being.
Explore ISO Tax Implications: Stages and Strategies
Imagine feeling overwhelmed by the iso vs rsu tax implications while trying to secure your family’s financial future. The tax implications can be intricate, but understanding the stages involved can help families navigate them effectively:
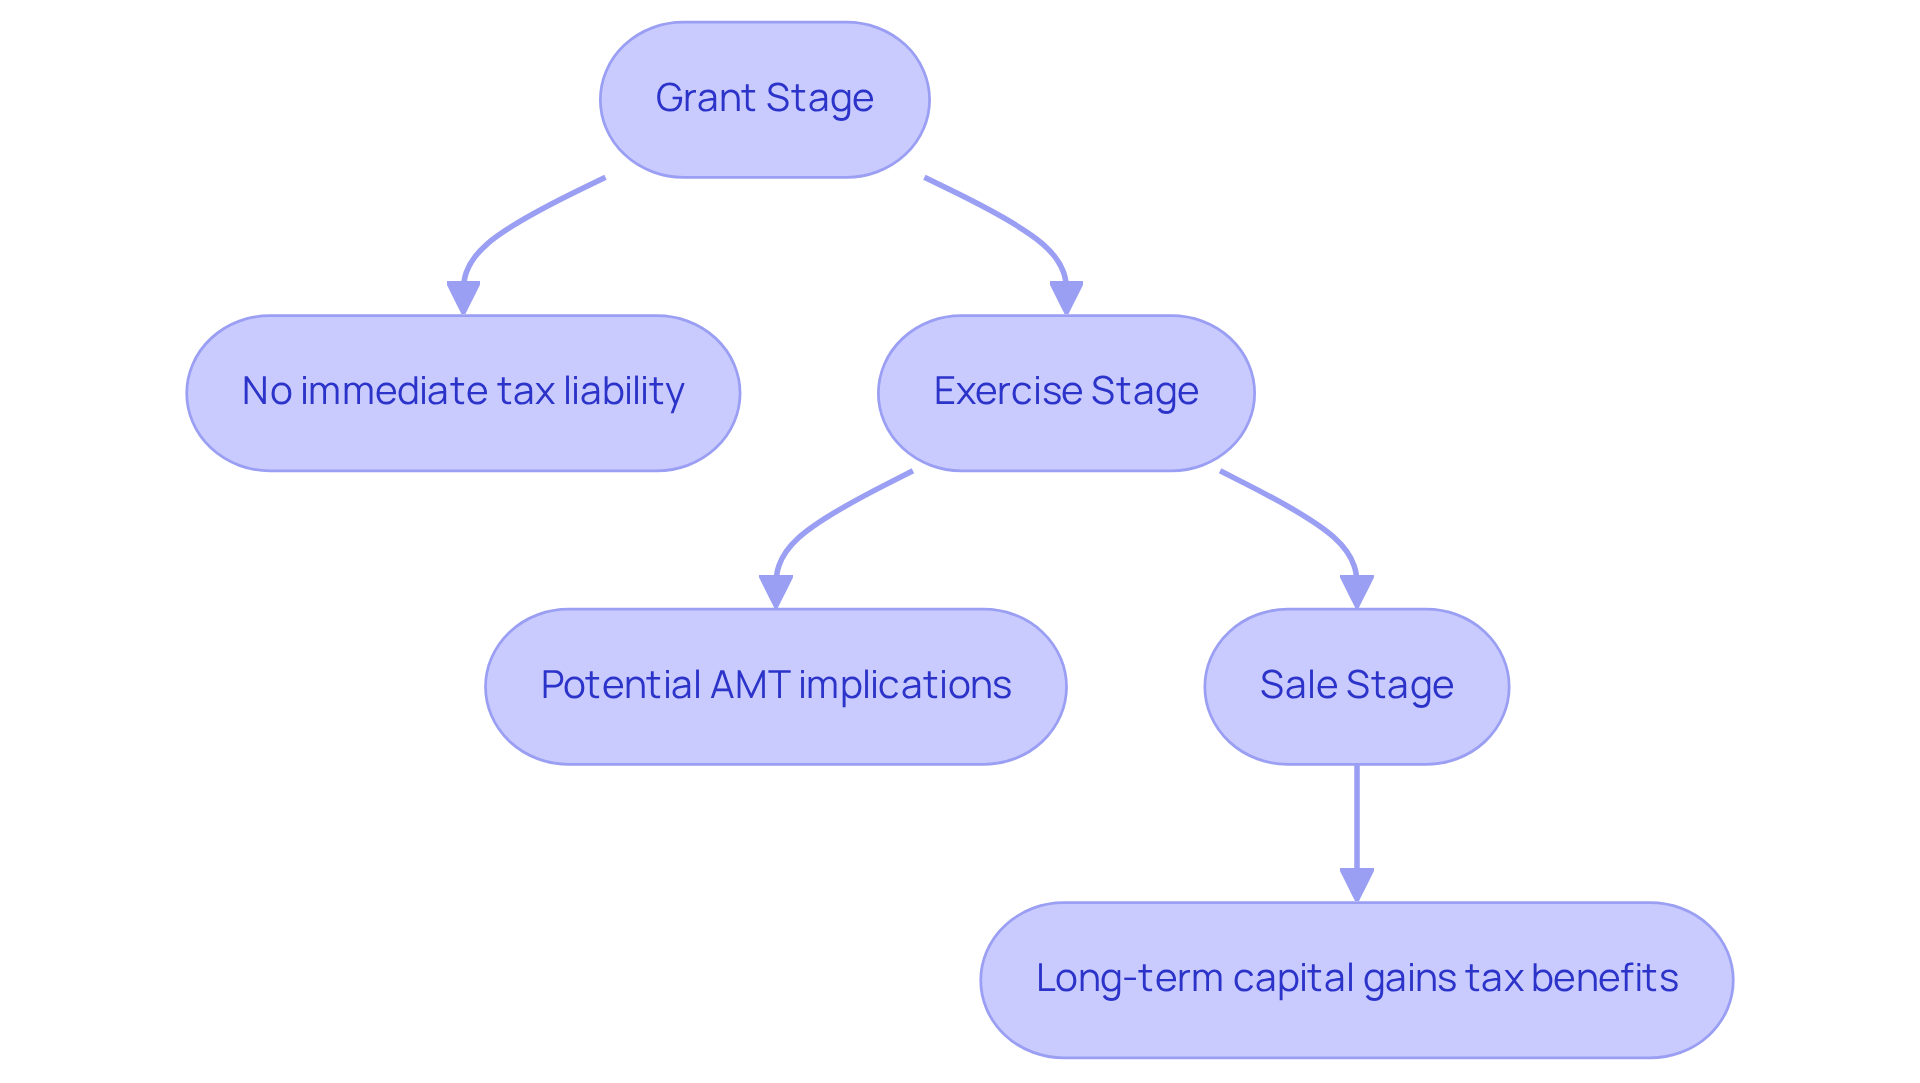
- Grant Stage: When stock options are granted, there’s no immediate tax liability. This is a notable benefit of stock options compared to other types of equity compensation, giving you a little breathing room.
- Exercise Stage: Exercising your stock options doesn’t incur regular income tax at that moment. However, the difference between the exercise price and the fair market value (FMV) of the stock at exercise may have iso vs rsu tax implications that could trigger the Alternative Minimum Tax (AMT). In 2026, the AMT exemption amount for married couples filing jointly is $140,200, and for single filers, it’s $90,100. It’s important to grasp these thresholds so you can make informed decisions that benefit your family’s financial future.
- Sale Stage: If you hold the shares for at least one year after exercising and two years after the grant date, any gains from the sale of the stock may be taxed at the lower long-term capital gains rate, which can be as low as 23.8% in 2025. This is a moment where thoughtful planning can really make a difference for your family. Families should consider timing their sales to maximize tax efficiency.
Strategies:
- Early Exercise: Consider exercising ISOs early in the year to minimize AMT exposure, especially if the company’s valuation is low at that time.
- Tax Planning: Collaborate with a tax advisor to model potential tax outcomes based on your income and the timing of your exercises and sales. This can help in understanding how to navigate AMT implications effectively.
- Diversification: Avoid concentrating too much wealth in company stock to mitigate risk and tax implications. This strategy can help protect your family’s financial future while addressing iso vs rsu tax implications.
For families like Allison and Brian, who are navigating the complexities of tax planning, working with Bright Advisers can provide the necessary guidance to optimize their financial situation. By incorporating tax optimization into their comprehensive financial plan, they can experience the peace of mind that comes with financial security, allowing them to enjoy more quality time with their loved ones. With the right support, you can turn these complexities into opportunities for your family’s financial growth and security.
Disclaimer: Past performance does not guarantee future results. Securities investments are subject to risk. Advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Examine RSU Tax Implications: Vesting and Beyond
Imagine the surprise of receiving a tax bill that feels overwhelming, all because of your RSUs. Understanding the iso vs rsu tax implications is crucial for families navigating their financial futures.
When your RSUs vest, your employer usually withholds taxes at a flat rate of 22% for federal taxes, but this might not cover everything you owe. This increase in taxable income can push families into higher tax brackets, especially in states like California, where combined tax rates can exceed 50% for high earners. Imagine receiving a hefty tax bill that you weren’t prepared for, all because of your RSUs.
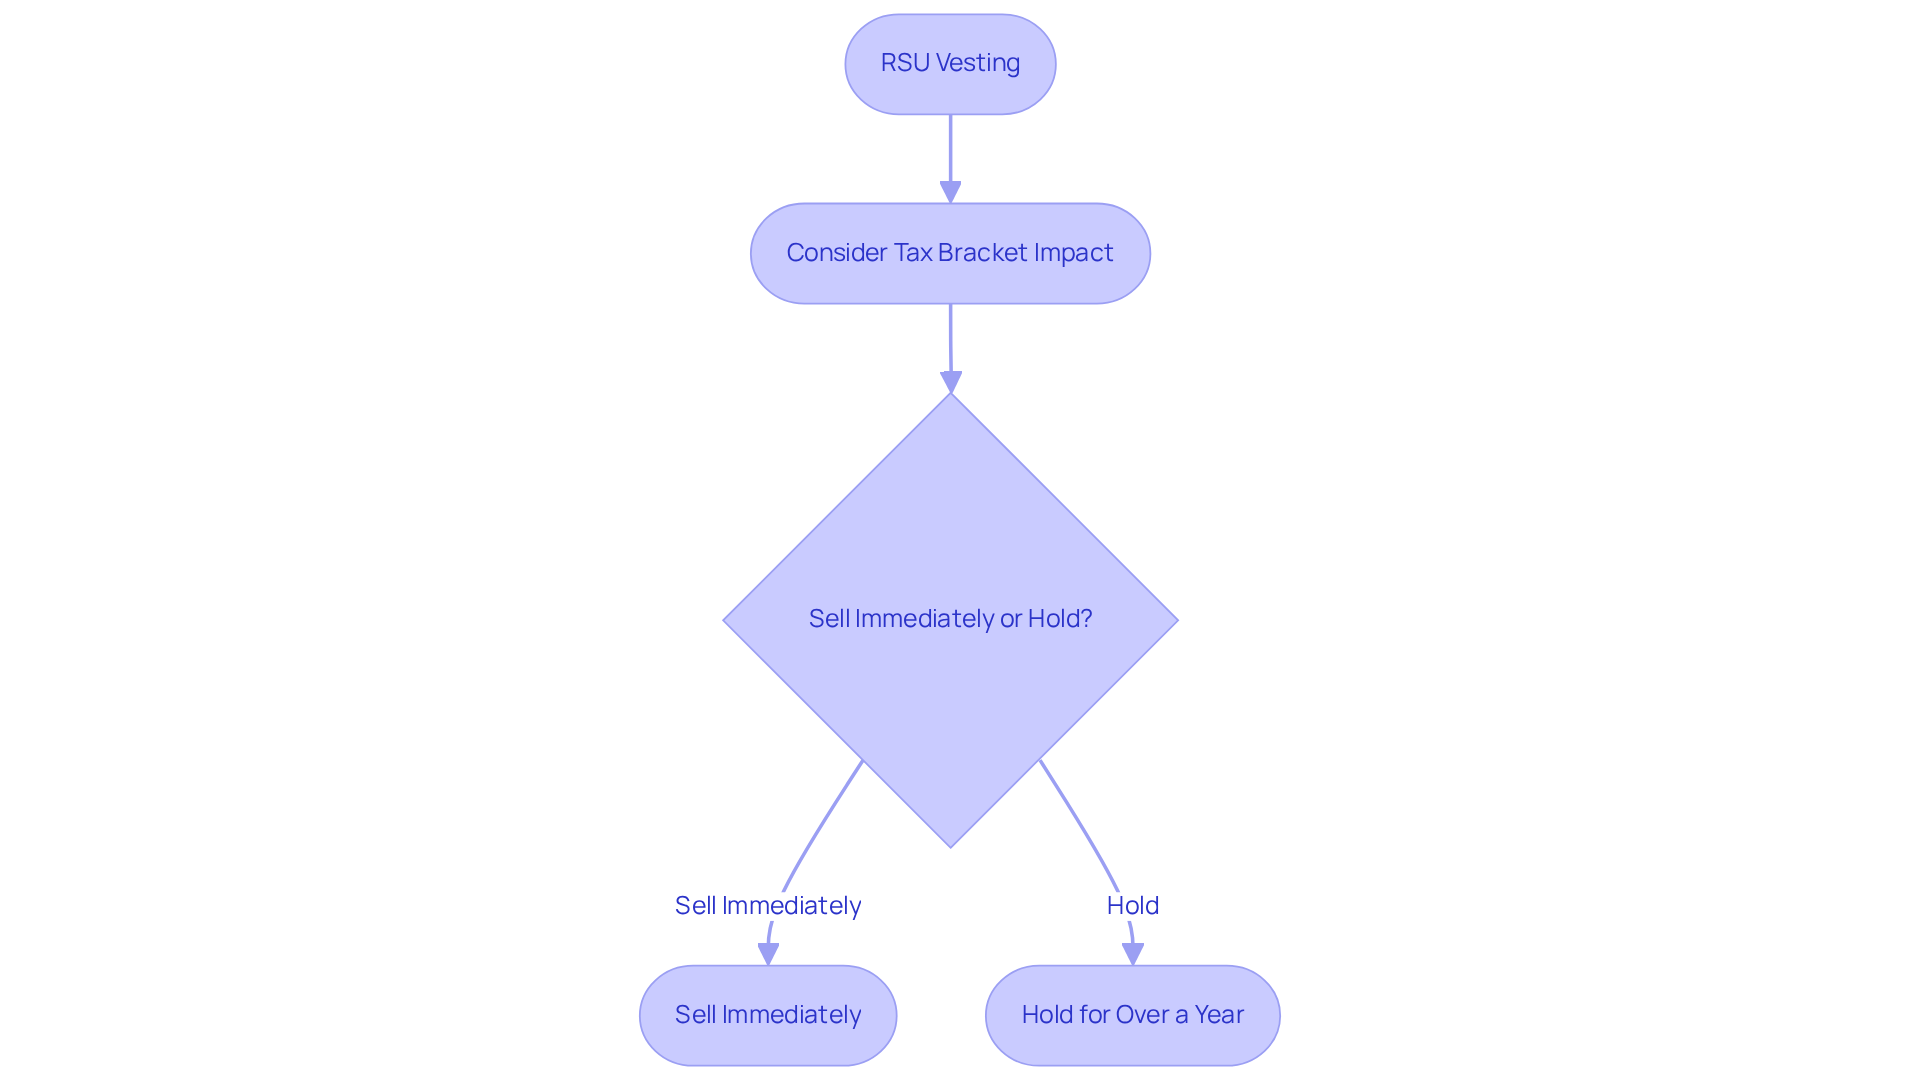
After vesting, if families choose to sell their RSU holdings, any gains or losses from the sale will be subject to capital gains tax. If the stocks are held for over a year, they may qualify for long-term capital gains rates, which are typically lower than standard income tax rates. For instance, selling stocks right after vesting incurs no capital gains tax since the sale price matches the tax basis.
It’s important for families to think ahead about the iso vs rsu tax implications and how RSUs will affect their taxes, considering their total income and any deductions they might qualify for. Consulting with a tax professional can help navigate the complexities of RSU taxation.
Deciding whether to sell immediately upon vesting or hold onto the assets for potential appreciation is a significant choice. It is essential to weigh the iso vs rsu tax implications of each option. Holding investments may result in reduced capital gains levies if sold after a year.
To keep your family’s finances safe, it’s wise to avoid putting all your eggs in one basket with company stock. Financial advisors suggest liquidating enough stock options to cover obligations and diversifying investments to reduce potential losses. Understanding these implications can empower families to make informed decisions and avoid unexpected financial stress.
Compare ISO and RSU Tax Implications: Making Informed Choices
Imagine navigating the complexities of Incentive Stock Options (ISOs) and Restricted Stock Units (RSUs) while trying to secure your family’s future. When it comes to these options, families should consider the iso vs rsu tax implications, as they can impact their financial journey.
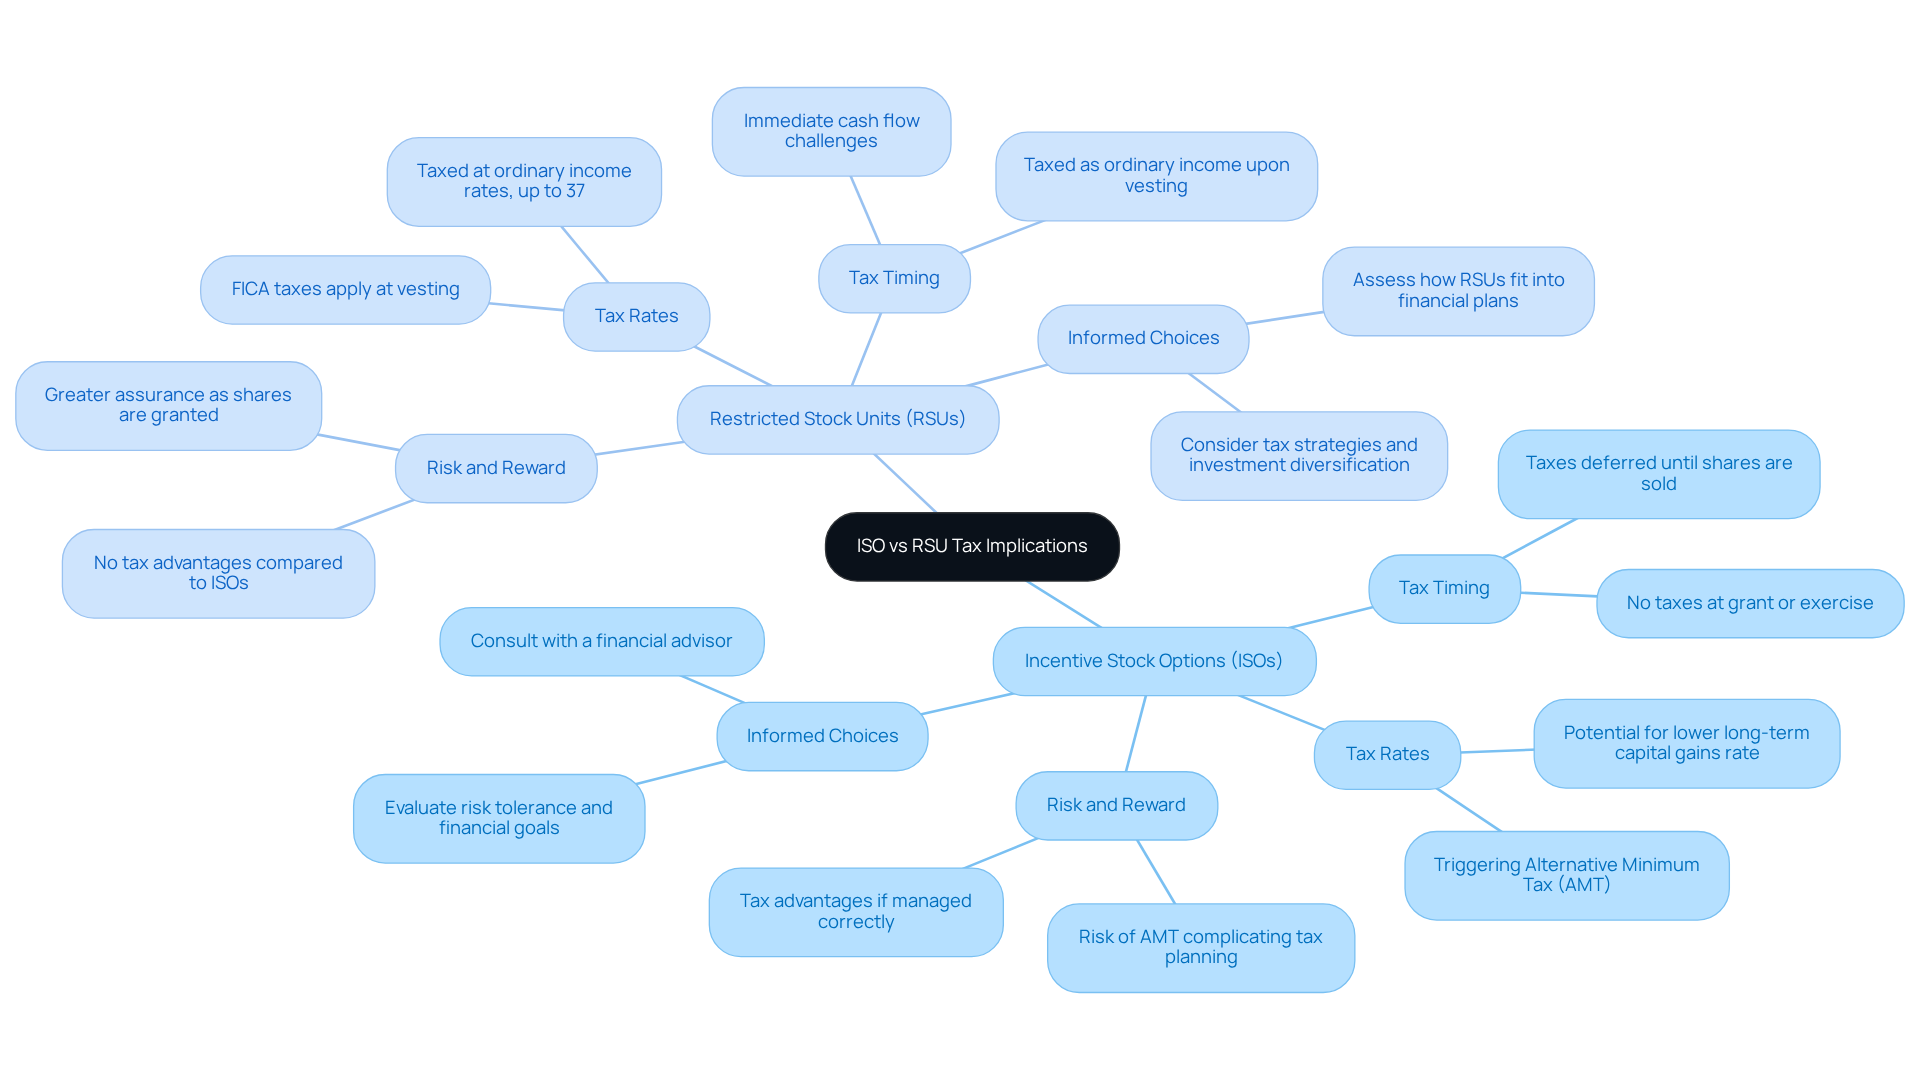
Tax Timing: ISOs don’t incur taxes at grant or exercise, allowing families to defer tax liabilities until shares are sold. This can be a relief for families trying to balance their budgets. On the other hand, restricted stock units are taxed as ordinary income upon vesting. This can create immediate cash flow challenges, making it tough for families to manage their finances. As Mel Whitney notes, “At vesting, the RSU tax rate is your ordinary income rate, up to 37% (2025), plus FICA.”
Tax Rates: Gains from incentive stock options can be taxed at the lower long-term capital gains rate if the holding periods are met – specifically, shares must be held for at least one year after exercising and two years after the grant date. This means that with the right guidance, families can turn these risks into opportunities. In contrast, restricted stock units are taxed at standard income rates upon vesting, which can be considerably higher, especially for high-income families. This means families might face a hefty tax burden, which can feel overwhelming, especially when planning for the future.
Risk and Reward: Incentive Stock Options carry the risk of triggering the Alternative Minimum Tax (AMT), complicating tax planning. However, they offer potential tax advantages if managed correctly. A case study of Allison and Brian illustrates this: by collaborating with Bright Advisers, they optimized their tax situation, secured their children’s future through education funding, and gained the ability to retire sooner. Restricted stock units provide greater assurance as they transform into shares upon vesting, but they don’t offer the same tax advantages as incentive stock options.
Informed Choices: Families should evaluate their risk tolerance and financial goals when assessing the iso vs rsu tax implications. Consulting with a financial advisor can help model potential outcomes based on different scenarios, particularly in light of the complexities surrounding tax implications. It’s important to assess how each option fits into the broader financial plan, including tax strategies and investment diversification, to ensure alignment with long-term family objectives. With the right support, families can confidently choose the path that best secures their financial future.
Disclaimer: Past performance does not guarantee future results. Securities investments are subject to risk. Advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Conclusion
Imagine the worry of facing unexpected tax bills when you’re just trying to provide for your family. Understanding the differences between Incentive Stock Options (ISOs) and Restricted Stock Units (RSUs) can help families make choices that fit their financial dreams and ease their worries about taxes.
Let’s break down how ISOs and RSUs work, so you can see when taxes might hit and how you can benefit from them. ISOs allow families to defer taxes until shares are sold, which can mean lower long-term capital gains rates. On the other hand, RSUs are taxed as ordinary income upon vesting, which can create immediate cash flow challenges.
Imagine the relief of having a plan in place! By exploring strategies like early exercise of ISOs and careful planning around RSU vesting, families can navigate these tax implications more smoothly.
Together, we can explore your unique financial situation and find the right support to help you navigate these choices. By understanding the tax implications of ISOs and RSUs and implementing effective strategies, families can enhance their financial stability and work towards a secure future. Taking proactive steps today can transform your financial future, giving you the peace of mind you deserve as you nurture your family.
Frequently Asked Questions
What are Incentive Stock Options (ISOs)?
Incentive Stock Options (ISOs) grant you the right to purchase company stock at a predetermined price, known as the exercise price. They may offer tax savings, but specific conditions must be met, such as holding the assets for a certain duration after exercising the options.
What are Restricted Stock Units (RSUs)?
Restricted Stock Units (RSUs) are commitments to provide shares of stock once certain conditions, typically a vesting period, are met. Once vested, RSUs are taxed as ordinary income based on their fair market value at the time of vesting, and there is no exercise price to pay.
How do ISOs and RSUs differ in terms of tax implications?
ISOs can trigger the Alternative Minimum Tax (AMT) upon exercising, allowing for potential tax management over time. In contrast, RSUs are taxed as ordinary income at vesting, regardless of whether the shares are sold immediately, offering less flexibility in managing tax liabilities.
Why is it important to understand ISOs and RSUs for family financial planning?
Misunderstanding ISOs and RSUs can lead to unexpected tax burdens, which may impact your family’s financial stability. By understanding these equity compensation options, you can make informed decisions that help protect your family’s financial well-being.
What should families consider when navigating equity compensation?
Families should consider the timing of tax responsibilities associated with stock options and the implications of exercising ISOs versus the immediate tax liabilities of RSUs upon vesting. This understanding can help in balancing family needs and financial goals.
List of Sources
- Define ISOs and RSUs: Key Concepts for Families
- Stock Options vs Restricted Stock Units (RSUs): A guide (https://jpmorganworkplacesolutions.com/insights/rsus-vs-stock-options)
- RSU vs Stock Options: Key Differences & Benefits (https://carta.com/learn/equity/rsu-vs-stock-options)
- NSO, ISO, RSU, ESPP, and ESOP: Making Sense of Equity Compensation Alphabet Soup – FPFoCo (https://financialplanningfortcollins.com/blog/nso-iso-rsu-espp-esop-equity-compensation)
- ISOs vs RSUs: Optimize Stock Benefits | Confluence FP (https://confluencefp.com/isos-vs-rsus-strategies-to-optimize-your-employee-stock-benefits)
- RSUs vs. ISOs: Equity Compensation 101 | Wealthspire (https://wealthspire.com/blog/rsus-vs-isos-equity-compensation-101)
- Explore ISO Tax Implications: Stages and Strategies
- What is the Alternative Minimum Tax? How AMT Works & Calculation (https://carta.com/learn/equity/stock-options/taxes/amt)
- AMT and Incentive Stock Options: What Employees Need to Know Before Exercising – True Wealth Design (https://truewealthdesign.com/amt-and-incentive-stock-options)
- How to help avoid AMT when exercising options — Secfi (https://secfi.com/learn/avoiding-amt-taxes-iso-stock-options)
- ISO Taxes: How AMT and AMT Credits Work + Avoiding AMT on ISO Exercises | Darrow Wealth Management (https://darrowwealthmanagement.com/blog/tax-isos-amt-credits)
- Incentive Stock Options (https://turbotax.intuit.com/tax-tips/investments-and-taxes/incentive-stock-options/L4azWgfwy)
- Examine RSU Tax Implications: Vesting and Beyond
- California RSU Tax Calculator 2026: Equity Tax Savings (https://sdocpa.com/rsu-tax-calculator-california)
- RSUs 101: A Tech Professional’s Guide to Equity, Tax Strategy, and Financial Planning (https://merceradvisors.com/investing/rsus-101-a-tech-professionals-guide-to-equity-tax-strategy-and-financial-planning)
- What is an RSU? How They Work, Benefits, & Taxes (https://carta.com/learn/equity/rsu)
- RSU Taxes Explained and 4 Tax Strategies for 2023 (https://ceritypartners.com/insights/rsu-taxes-explained-and-4-tax-strategies-for-2023)
- Restricted Stock Units and How They Work | Wealthspire (https://wealthspire.com/blog/restricted-stock-units-rsus-how-they-work-6-common-misconceptions)
- Compare ISO and RSU Tax Implications: Making Informed Choices
- California RSU Tax Calculator 2026: Equity Tax Savings (https://sdocpa.com/rsu-tax-calculator-california)
- RSU tax for expats: how foreign RSUs are taxed | 2026 (https://taxesforexpats.com/articles/tax-saving-strategies/foreign-rsu-tax.html)
- ISOs vs RSUs: Optimize Stock Benefits | Confluence FP (https://confluencefp.com/isos-vs-rsus-strategies-to-optimize-your-employee-stock-benefits)
- RSUs vs. ISOs: Equity Compensation 101 | Wealthspire (https://wealthspire.com/blog/rsus-vs-isos-equity-compensation-101)
- Tax Implications for Stock-Based Compensation – Bloomberg Tax (https://pro.bloombergtax.com/insights/federal-tax/tax-implications-for-stock-based-compensation)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading