

Key Highlights:
- Capital gains are profits from selling an asset for more than its purchase price, categorised as short-term or long-term based on the holding period.
- Short-term capital gains are taxed at ordinary income rates (10%-37%), while long-term gains benefit from lower rates (0%, 15%, or 20%) depending on income.
- For 2024, the 0% tax rate applies to single filers with income up to $47,025 and married couples up to $94,050.
- The 15% rate applies to single filers earning between $47,026 and $518,900, and married couples earning between $94,051 and $583,750.
- The 20% rate is for single filers with income over $518,900 and married couples over $583,750.
- Strategies to minimise capital gains taxes include holding investments longer, using tax-advantaged accounts, offsetting profits with losses, donating appreciated assets, and timing sales based on tax brackets.
- Different asset types have distinct tax implications: stocks and bonds benefit from long-term rates, real estate may have exclusions for primary residences, collectibles are taxed at 28%, and cryptocurrency profits are treated as property.
- Understanding these tax implications can help families make informed investment decisions and optimise their financial planning.
Introduction
Understanding capital gains tax can feel overwhelming, especially for families striving to make the most of their investments. As we look ahead to 2024, the long-term capital gains tax brackets will play a crucial role in how profits are taxed based on how long assets are held. This knowledge can empower families to make informed decisions that enhance their financial well-being.
Imagine if you could optimize your investment strategies to not only minimize tax liabilities but also ensure your family’s financial growth. It’s important to understand that navigating these tax rates doesn’t have to be daunting. By grasping the nuances of capital gains, you can unlock significant benefits that align with your family’s values and goals.
This article is here to guide you through the complexities of capital gains tax, offering insights and strategies designed specifically for families like yours. Together, we can explore how to secure your financial future while nurturing the dreams you hold dear. Remember, you’re not alone on this journey; we’re here for you every step of the way.
Define Capital Gains: Short-Term vs. Long-Term
Understanding capital gains is crucial for your family’s [financial health](https://brightadvisers.com/?p=13020). These gains represent the profit you earn when selling an asset for more than you paid for it, and they come in two forms based on how long you’ve held the asset.
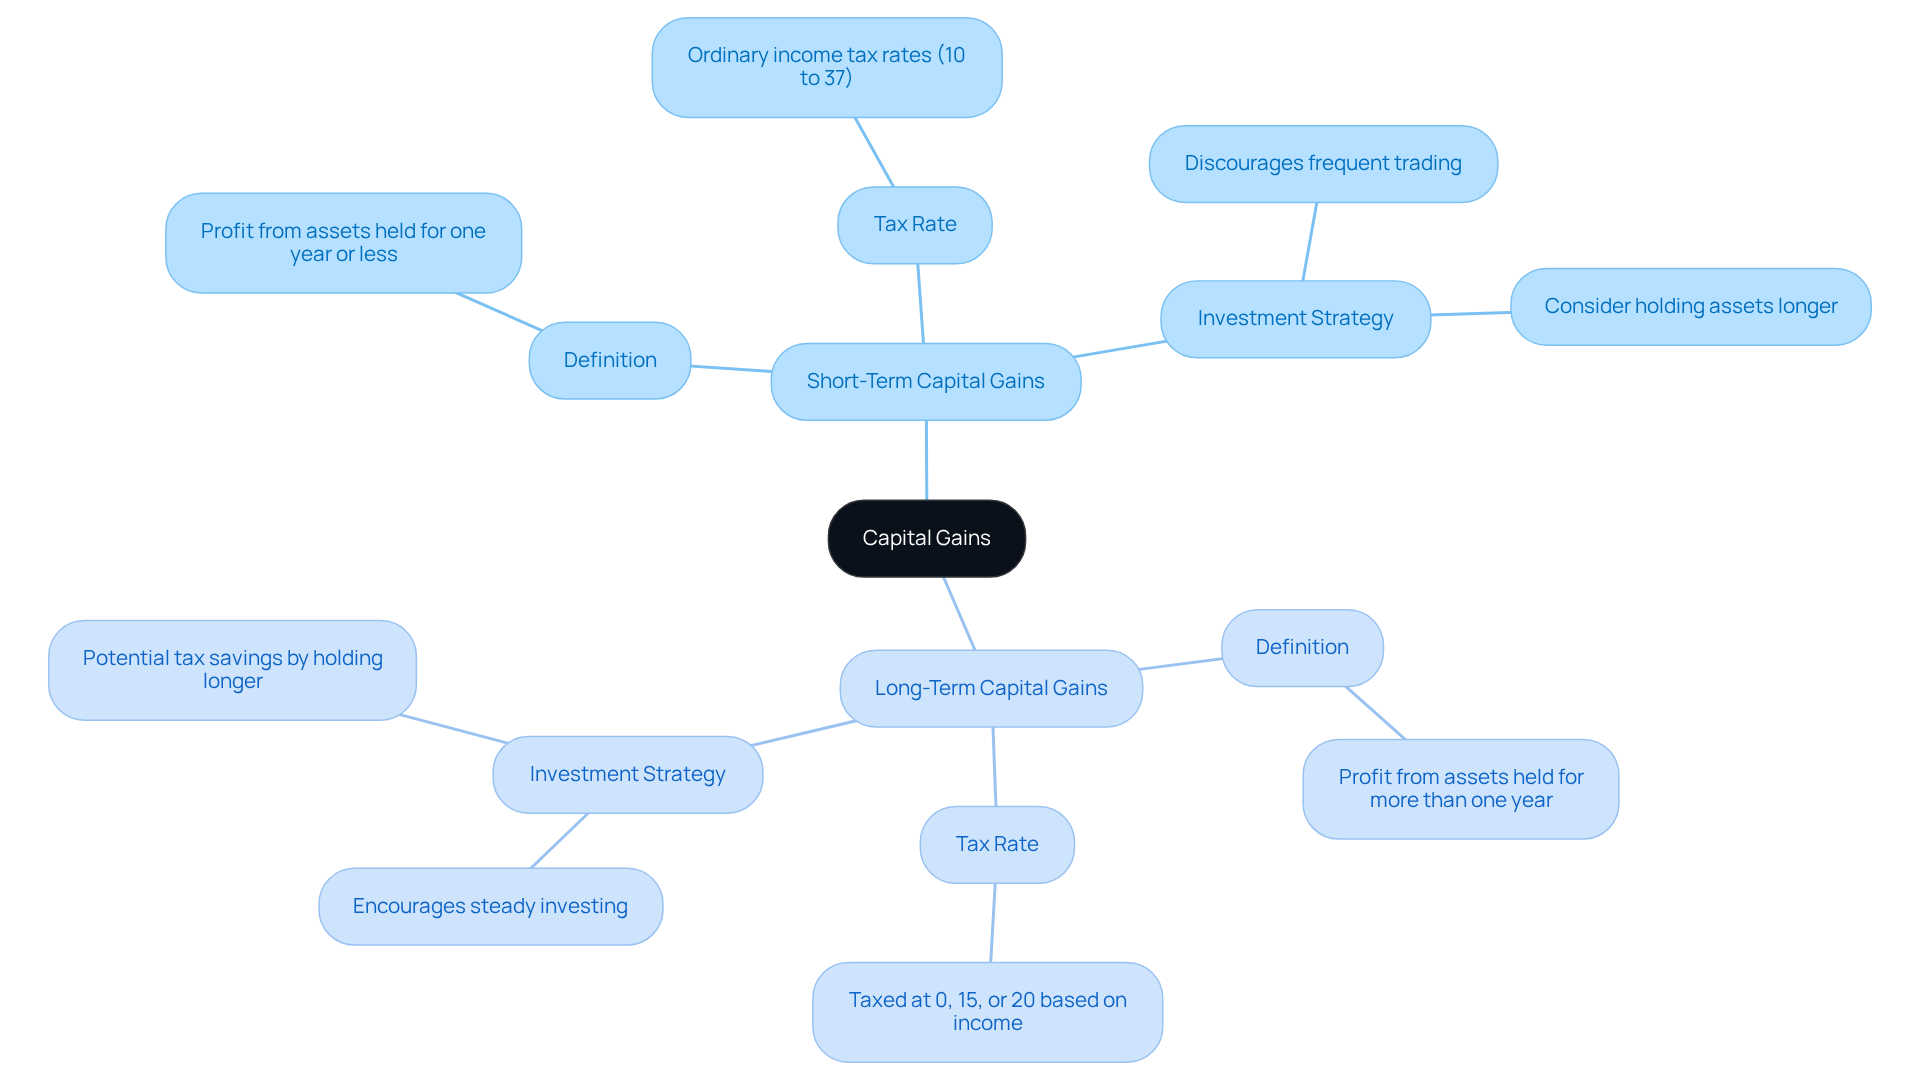
- [[Short-Term Capital Gains](https://investopedia.com/articles/personal-finance/101515/comparing-longterm-vs-shortterm-capital-gain-tax-rates.asp)](https://investopedia.com/articles/personal-finance/101515/comparing-longterm-vs-shortterm-capital-gain-tax-rates.asp): Imagine selling a toy your child outgrew after just a few months. If you sell it for more than you bought it, that profit is a short-term capital gain. These gains are taxed at ordinary income tax rates, which can range from 10% to 37%, depending on your income. This higher tax rate can take a bite out of your returns, so it’s important to think about when you sell your assets.
- [Long-Term Profit](https://schwab.com/learn/story/how-are-capital-gains-taxed): Now, picture holding onto that toy for over a year before selling it. The profit you make then is considered a long-term capital gain, and it’s taxed at the [long term capital gains tax brackets 2024](https://bradfordtaxinstitute.com/Free_Resources/2024-Capital-Gains-Rates.aspx) of 0%, 15%, or 20% based on your earnings. This distinction is vital for families looking to minimize their liabilities in the [long term capital gains tax brackets 2024](https://bradfordtaxinstitute.com/Free_Resources/2024-Capital-Gains-Rates.aspx). Holding onto your investments longer can lead to significant savings, allowing you to allocate more funds toward your family’s needs.
Understanding the difference between these two types of gains can help you craft a [smart tax strategy](https://brightadvisers.com/10-tax-planning-strategies-for-businesses-to-optimize-savings). For example, a married couple filing jointly with a [taxable income of $100,000](https://brightadvisers.com/?p=11049) could save over $200 in taxes simply by holding their investments for more than a year before selling. [Financial advisors](https://brightadvisers.com/10-essential-questions-to-ask-a-new-financial-advisor) often emphasize that the long-term profit tax framework encourages steady investing, which can help stabilize the market and reduce the stress of frequent trading.
As you navigate your investment portfolio, remember that recognizing changes in value is key. Seeking advice from a [[financial expert](https://brightadvisers.com/?p=12861)](https://brightadvisers.com/?p=12861) can provide valuable insights into enhancing your tax strategies. We’re here for you, ready to support you on this journey toward for your family.
Explore Long-Term Capital Gains Tax Rates for 2024
For the tax year 2024, understanding long-term capital gains tax rates can feel overwhelming, but we’re here to help you navigate it:
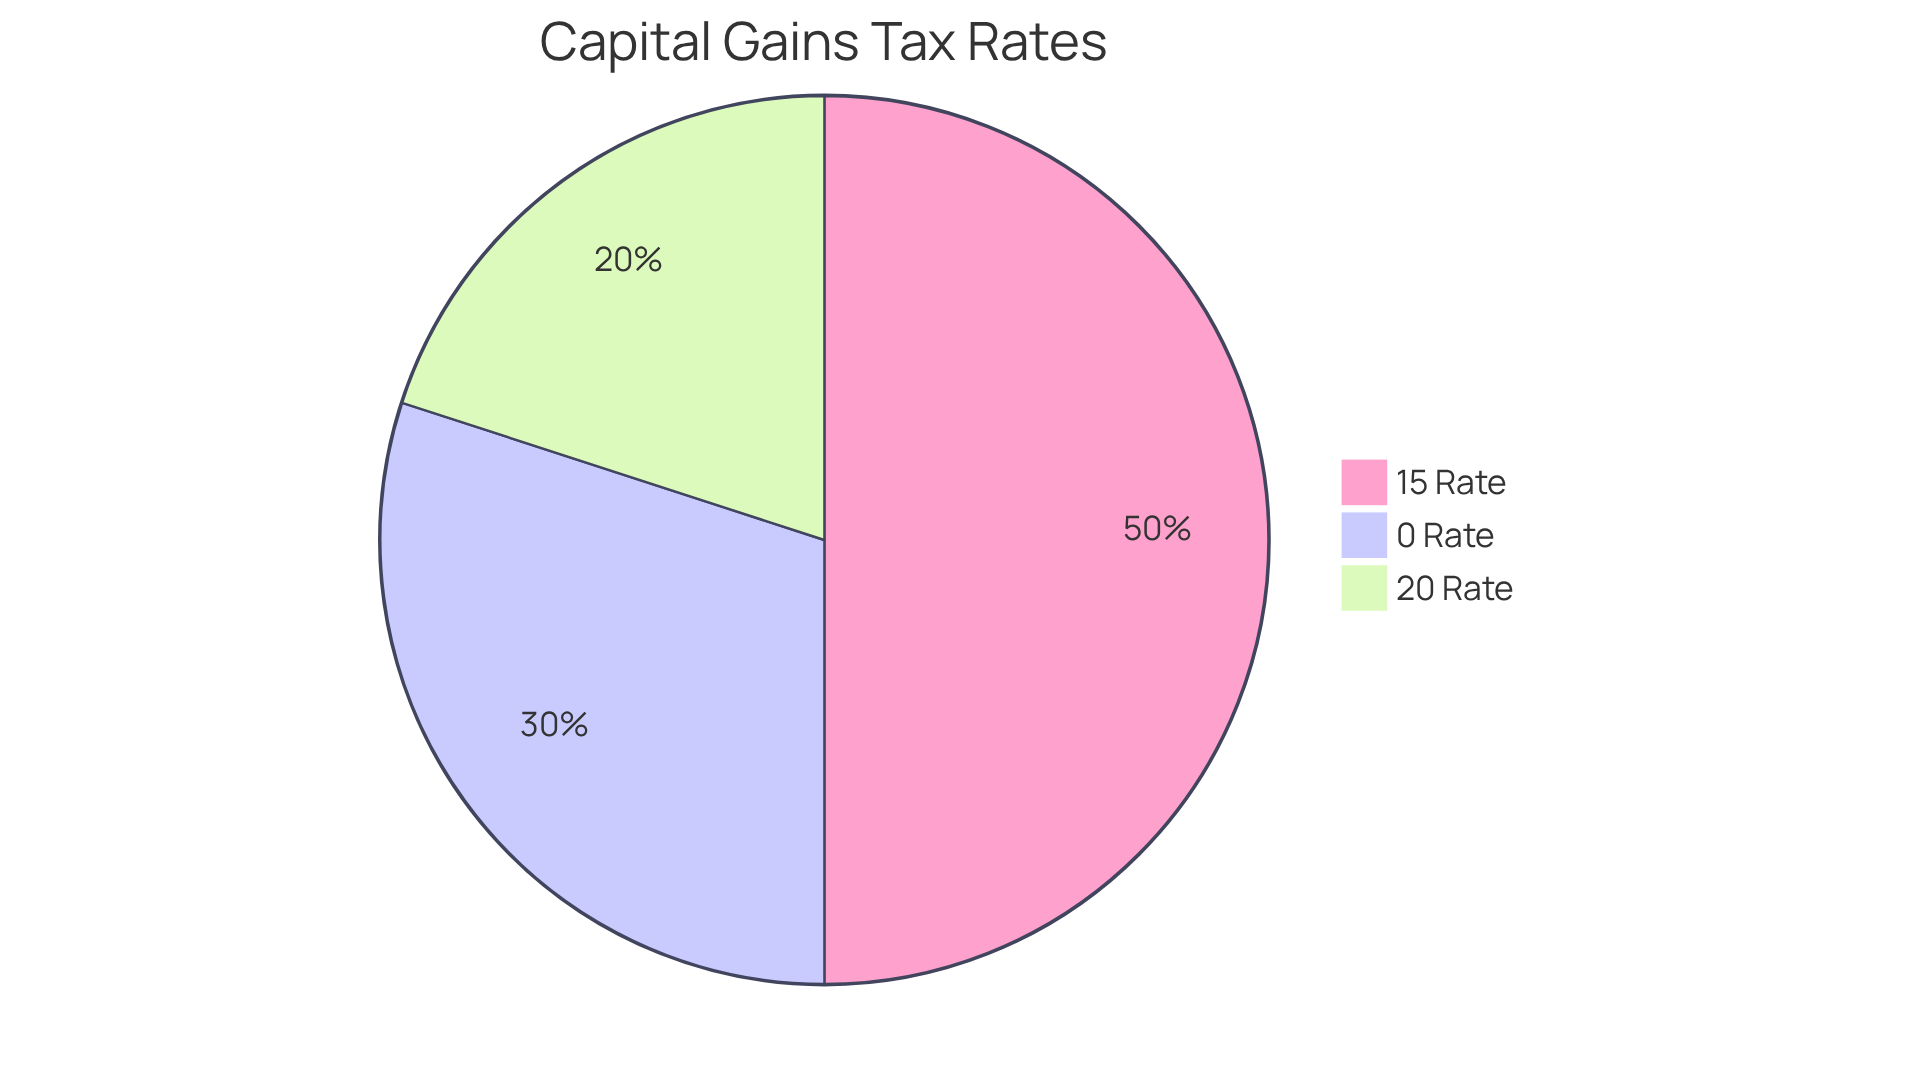
- 0% Rate: This applies to single filers with taxable income up to $47,025 and married couples filing jointly with income up to $94,050.
- 15% Rate: According to the long term capital gains tax brackets 2024, if you’re a single filer earning between $47,026 and $518,900, or a married couple filing jointly with earnings between $94,051 and $583,750, this rate is for you.
- 20% Rate: In the long term capital gains tax brackets 2024, this rate applies to single filers with earnings exceeding $518,900 and married couples filing jointly with earnings surpassing $583,750.
These brackets can help you gauge your potential tax liabilities based on your income and investment strategies.
Imagine if you could simplify this process. At Bright Advisers, we understand that young families like Jay and Emma, Emily and Mark, and Allison and Brian often seek [tailored wealth management solutions](https://brightadvisers.com/?p=11642) to navigate these complexities. By optimizing tax strategies like utilizing tax-loss harvesting and maximizing retirement account contributions, we empower families to achieve financial security and educational readiness.
Together, we can ensure you focus on your while effectively managing your current responsibilities. We’re here for you, ready to support you on this journey.
Implement Strategies to Minimize Capital Gains Taxes
To minimize [capital gains taxes](https://brightadvisers.com/10-high-w-2-income-tax-strategies-for-young-parents), let’s explore some thoughtful strategies that can truly make a difference for you and your family:
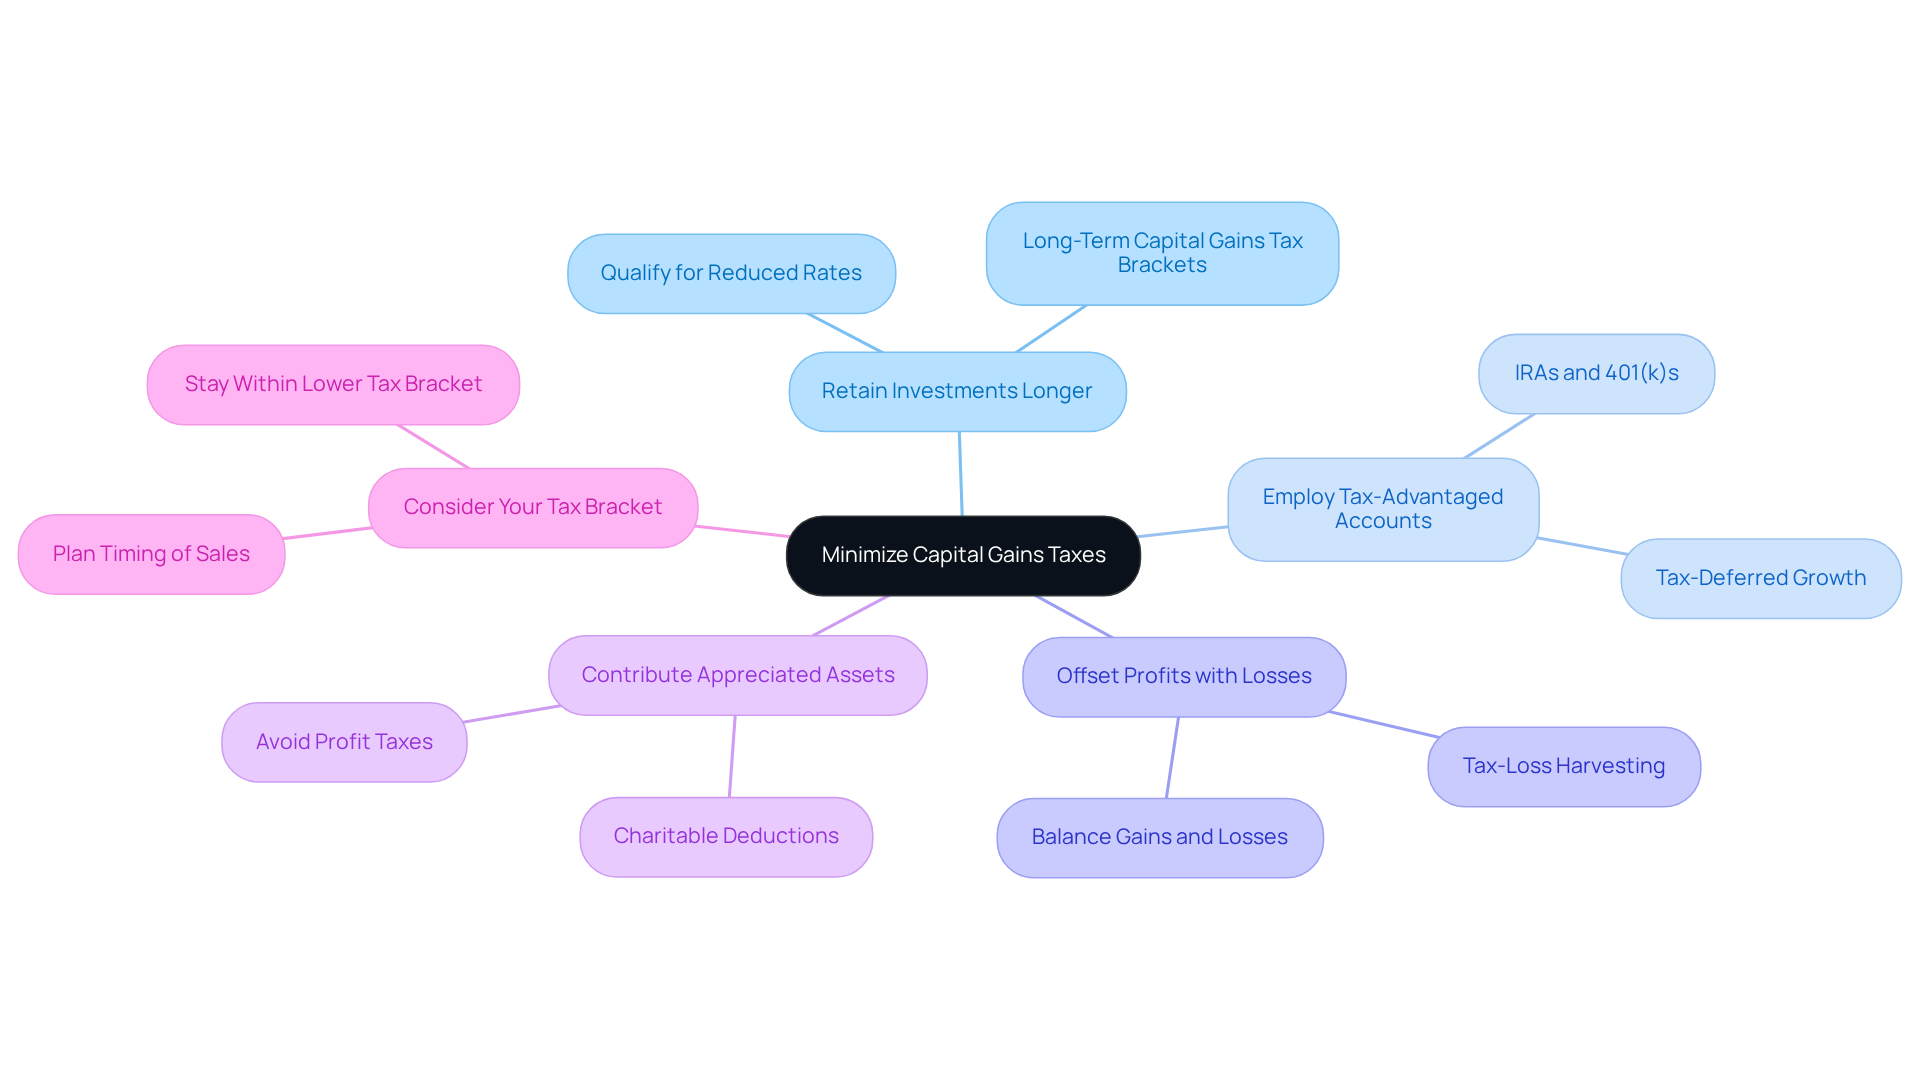
- [Retain Investments Longer](https://brightadvisers.com/?p=11594): Imagine holding onto your assets for over a year. By doing so, you can qualify for reduced rates within the long term capital gains tax brackets 2024 on your profits, allowing you to keep more of what you earn.
- Employ [Tax-Advantaged Accounts](https://brightadvisers.com/4-steps-for-planning-your-tax-strategy-as-a-young-family): Think about investing through accounts like IRAs or 401(k)s. These accounts let your profits grow tax-deferred or even tax-free, giving you peace of mind as you plan for your family’s future.
- Offset Profits with Losses: If you have investments that haven’t performed well, consider selling them to balance out your profits. This strategy, known as tax-loss harvesting, can help lighten your tax burden.
- Contribute Appreciated Assets: If you’re feeling charitable, donating appreciated stocks can be a wonderful way to avoid profit taxes while also receiving a charitable deduction. It’s a win-win for your heart and your wallet.
- [Consider your tax bracket](https://brightadvisers.com/?p=11969), including the long term capital gains tax brackets 2024, as it’s important to plan the timing of your asset sales. By managing your earnings wisely, you might stay within a lower tax bracket, which can be a great relief.
Together, we can to ensure your family’s [financial well-being](https://brightadvisers.com/4-steps-for-effective-family-financial-management). Remember, we’re here for you every step of the way.
Analyze Capital Gains Tax Implications on Different Asset Types
Understanding the long term capital gains tax brackets 2024 implications can feel overwhelming, especially for young families trying to navigate their [[financial futures](https://brightadvisers.com/?p=10998)](https://brightadvisers.com/?p=10972). But don’t worry; we’re here for you. Let’s break it down together.
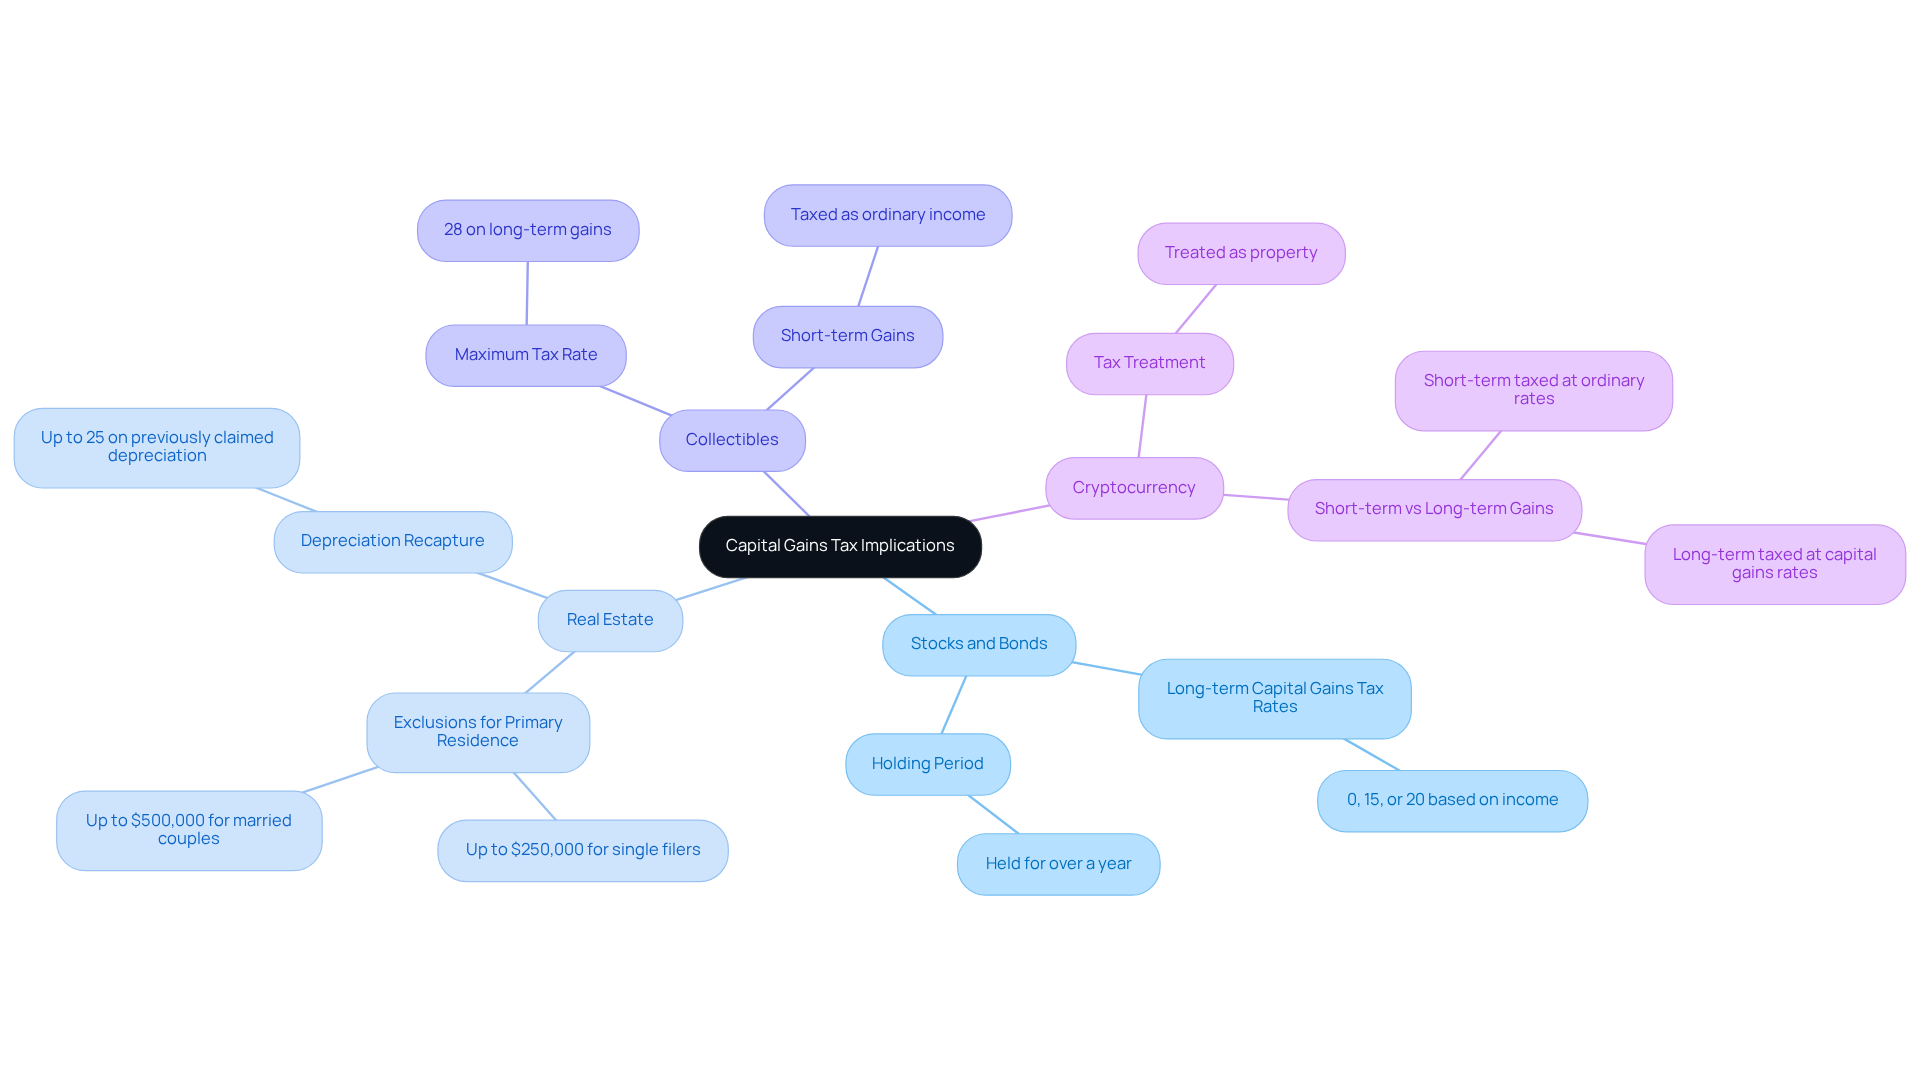
Stocks and Bonds: When you sell stocks or bonds, the capital gains tax you face depends on how long you’ve held them. If you’ve held them for over a year, you’ll benefit from the [long term capital gains tax brackets 2024](https://bankrate.com/investing/long-term-capital-gains-tax), which provide lower tax rates of 0%, 15%, or 20% depending on your income level. This can make a significant difference in your family’s financial planning.
Real Estate: Selling your home can be a bit more complex. You might encounter extra costs like depreciation recapture, which can hit up to 25% on profits linked to previously claimed depreciation. However, if your home has been your primary residence for at least two of the last five years, you could qualify for exclusions on gains – up to $250,000 for single filers and $500,000 for married couples filing jointly. In 2024, individual taxpayers earning more than $47,025 and joint filers above $94,050 will fall within the long term capital gains tax brackets 2024, with these limits set to rise in 2025. It’s important to understand these details to make informed decisions.
Collectibles: If you’re thinking about selling items like art, antiques, or coins, be aware that long-term profits from these collectibles are taxed at a maximum rate of 28%. This is higher than the standard long-term rates, so it’s crucial to factor this into your planning.
Cryptocurrency: With the rise of digital assets, it’s essential to know that profits from cryptocurrency transactions are treated as property for tax purposes. Just like stocks, short-term profits from cryptocurrency are taxed at regular income rates, which can be significantly higher than long-term rates. Understanding this can help you .
By understanding these implications, families can make [[smarter investment choices](https://brightadvisers.com/?p=13801)](https://brightadvisers.com/?p=13801) and reduce their liabilities within the long term capital gains tax brackets 2024. For instance, if you’re [selling real estate](https://investor.vanguard.com/investor-resources-education/taxes/realized-capital-gains), consider the timing of your transactions and how to utilize available exclusions to optimize your tax outcomes. Consulting with tax professionals can provide tailored strategies to manage these complexities and enhance your overall financial planning.
As David Watts, founder of Bright Advisers, wisely notes, “Effectively managing [capital gains is key to preserving and growing wealth](https://kiplinger.com/taxes/capital-gains-tax/602224/capital-gains-tax-rates) over time.” This approach reflects how Bright Advisers empowers families like Jay and Emma, Emily and Mark, and Allison and Brian to navigate their financial landscapes with confidence and security. Together, we can navigate this journey and ensure a brighter financial future for your family.
Conclusion
Understanding long-term capital gains tax brackets for 2024 is essential for effective financial planning. Imagine if you could significantly influence your tax liabilities and retain more of your hard-earned profits. By differentiating between short-term and long-term capital gains, you empower your family to make informed decisions that align with your financial goals, especially when it comes to selling assets to minimize tax impacts.
Throughout this journey, we’ve shared key insights, including the specific tax rates applicable to different income levels, the advantages of holding investments longer, and various strategies to reduce capital gains taxes. For instance, utilizing tax-advantaged accounts and engaging in tax-loss harvesting can lead to substantial savings for your family. It’s also important to understand how different asset types – such as stocks, real estate, and collectibles – are taxed, as this knowledge can help you optimize your investment strategies.
Ultimately, navigating the complexities of capital gains taxes is crucial for building and preserving wealth. By employing strategic tax planning and consulting with financial experts, you can enhance your family’s financial well-being and work toward long-term security. Together, we can navigate this journey, embracing strategies that not only aid in managing current responsibilities but also lay the foundation for a prosperous financial future.
Frequently Asked Questions
What are capital gains?
Capital gains are the profits earned when selling an asset for more than its purchase price.
What is the difference between short-term and long-term capital gains?
Short-term capital gains occur when an asset is sold after being held for one year or less, while long-term capital gains are realized when an asset is held for more than one year before selling.
How are short-term capital gains taxed?
Short-term capital gains are taxed at ordinary income tax rates, which can range from 10% to 37%, depending on your income.
How are long-term capital gains taxed?
Long-term capital gains are taxed at lower rates, with brackets of 0%, 15%, or 20%, based on your earnings.
Why is it important to understand the difference between short-term and long-term capital gains?
Understanding the difference can help individuals and families craft smart tax strategies, potentially saving money on taxes by holding investments longer.
Can holding investments for longer periods lead to tax savings?
Yes, holding investments for more than a year can lead to significant tax savings, as long-term capital gains are taxed at lower rates compared to short-term gains.
How much could a married couple filing jointly with a taxable income of $100,000 save in taxes by holding investments longer?
They could save over $200 in taxes by holding their investments for more than a year before selling.
What do financial advisors recommend regarding capital gains and investing?
Financial advisors often emphasize that the long-term profit tax framework encourages steady investing, which can help stabilize the market and reduce the stress of frequent trading.
How can individuals enhance their tax strategies related to capital gains?
Seeking advice from a financial expert can provide valuable insights into enhancing tax strategies related to capital gains.
List of Sources
- Define Capital Gains: Short-Term vs. Long-Term
- Long-Term vs. Short-Term Capital Gains (https://investopedia.com/articles/personal-finance/101515/comparing-longterm-vs-shortterm-capital-gain-tax-rates.asp)
- 2024 Capital Gains Rates (https://bradfordtaxinstitute.com/Free_Resources/2024-Capital-Gains-Rates.aspx)
- How Are Capital Gains Taxed? (https://schwab.com/learn/story/how-are-capital-gains-taxed)
- State Tax Rates on Long-Term Capital Gains, 2024 (https://taxfoundation.org/data/all/state/state-capital-gains-tax-rates-2024)
- Implement Strategies to Minimize Capital Gains Taxes
- Strategic Tax Plan: Timing Investment Gains to Reduce Tax Liability (https://commercetrustcompany.com/research-and-insights/articles/6-strategies-to-lower-capital-gains-taxes-on-investment-returns)
- 12 Strategies to Help Lower Long-Term Capital Gains Taxes (https://landsbergbennett.com/blogs/insights/12-strategies-to-help-lower-long-term-capital-gains-taxes)
- How to Reduce Capital Gains Taxes – NerdWallet (https://nerdwallet.com/investing/learn/how-to-reduce-capital-gains-tax)
- Analyze Capital Gains Tax Implications on Different Asset Types
- Capital Gains Explained: Key Facets for Affluent Investors to Know (https://wattsgwilliam.com/investing/understanding-capital-gains-what-investors-need-to-know-for-smart-wealth-management)
- Federal Capital Gains Tax Collections, Historical Data (1954-2018) (https://taxfoundation.org/data/all/federal/federal-capital-gains-tax-collections-historical-data)
- Capital Gains Tax Rates 2025 and 2026: What You Need to Know (https://kiplinger.com/taxes/capital-gains-tax/602224/capital-gains-tax-rates)
- What is capital gains tax? | Vanguard (https://investor.vanguard.com/investor-resources-education/taxes/realized-capital-gains)
- 2024-2025 Long-Term Capital Gains Tax Rates | Bankrate (https://bankrate.com/investing/long-term-capital-gains-tax)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading