

Overview
For young families, the 7702 Plans present some challenges that deserve careful consideration. One significant concern is the absence of tax deductions for contributions, which can feel like a missed opportunity. Additionally, families may face potential surrender penalties for early withdrawals, adding another layer of complexity to their financial planning. Early years often see slow cash value growth, which can strain budgets and limit the flexibility that families need during crucial times.
Imagine if you’re weighing your options between a 7702 Plan and term life insurance. Higher premiums can impact how you allocate your resources, making it essential to evaluate your financial goals thoroughly. It’s important to understand that these drawbacks don’t have to deter you; instead, they can serve as a foundation for informed decision-making.
We’re here for you, guiding you through these considerations. Together, we can navigate this journey and ensure that your financial choices align with your family’s values and priorities. Remember, thoughtful planning today can lead to a more secure tomorrow.
Key Highlights:
- A 7702 Plan is a life insurance policy that combines a death benefit with a growing cash value, governed by IRS Section 7702.
- The cash value grows tax-deferred, and death benefits are tax-free for beneficiaries, providing financial security.
- Policyholders can borrow against the cash value or withdraw funds, often without tax penalties, if compliant with IRS rules.
- 7702 Plans have no contribution limits, allowing for substantial savings without restrictions.
- Disadvantages include no tax deductions for contributions, potential surrender penalties for early withdrawals, and slow cash value growth in early years.
- Higher premiums compared to term life insurance can strain budgets, impacting resource allocation for other needs.
- Compared to 401(k)s and IRAs, 7702 Plans offer life insurance benefits but lack immediate tax advantages.
- 529 plans may be more suitable for education savings, while VestCred plans provide unique features for retirement and education without contribution limits.
Introduction
The 7702 Plan offers a unique opportunity for families to blend life insurance with savings, paving the way for a secure financial future while addressing immediate needs. However, as young families embark on this journey, they may find themselves navigating a landscape filled with potential pitfalls. From tax implications to access limitations, these challenges could impact their financial flexibility.
Imagine if you could uncover the hidden challenges that might undermine the advantages of this seemingly beneficial plan. It’s important to understand how these factors can affect your family’s long-term economic health. Together, we can navigate this journey, ensuring that you make the best decision for your family’s future.
By exploring the 7702 Plan, you can take proactive steps toward securing your family’s financial well-being. We’re here to support you every step of the way, helping you address your concerns and prioritize what truly matters for your loved ones.
Define the 7702 Plan: Key Features and Purpose
A 7702 Plan is a unique type of life insurance policy that not only provides a death benefit but also includes a growing monetary value, all governed by Section 7702 of the IRS tax code. This plan is designed to help families secure their financial future while meeting their immediate needs.
-
Imagine if you could ensure your loved ones are protected while also building savings for their future. One of the standout features of a 7702 Plan is its tax advantages. The cash value grows on a tax-deferred basis, meaning you won’t owe taxes on the growth until you decide to withdraw it. Plus, the death benefits are tax-free for your beneficiaries, offering essential financial security for those you care about most.
-
Flexibility is key. As a policyholder, you can borrow against the monetary value or withdraw funds, often without incurring taxes, as long as the policy remains compliant with IRS guidelines. This access can be a vital resource during your lifetime, providing support when you need it most.
-
What if there were no contribution limits? Unlike many retirement accounts, 7702 Plans allow you to maximize your savings without restrictions, giving you the freedom to plan for your family’s future. In addition to the monetary value, the policy guarantees a death benefit, ensuring your loved ones are taken care of financially.
The primary goal of a 7702 Plan is to combine life insurance with a savings element, making it an appealing choice for families looking to secure their future while addressing their children’s needs. For instance, families like Jay and Emma can utilize the monetary value for college expenses or other significant life events, ensuring they are prepared for what lies ahead.
- Financial advisors often highlight the dual benefits of these plans. They provide both security and a pathway for wealth growth, which is crucial for young families juggling financial responsibilities. However, it’s vital to be aware of the 7702 plan disadvantages, including the risk of surrender penalties for early withdrawals and the limitations on cash value accumulation if only the minimum premium is paid.
Moreover, certain plans can aid in preventing the taxation of Social Security benefits from extra income, which is a significant advantage for families. Did you know that 51% of American adults have at least one life insurance policy? This statistic underscores the importance of life insurance, including 7702 Plans, within the broader market. Additionally, 56% of households earning below $50,000 believe they need life insurance, highlighting the relevance of these plans across different income levels.
- We’re here for you. Together, we can navigate this journey of financial planning, ensuring your family’s needs are met while also preparing for a secure future.

Explore the Disadvantages of the 7702 Plan for Young Families
While the 7702 Plan offers several advantages, it’s essential for young families to consider some notable disadvantages carefully:
-
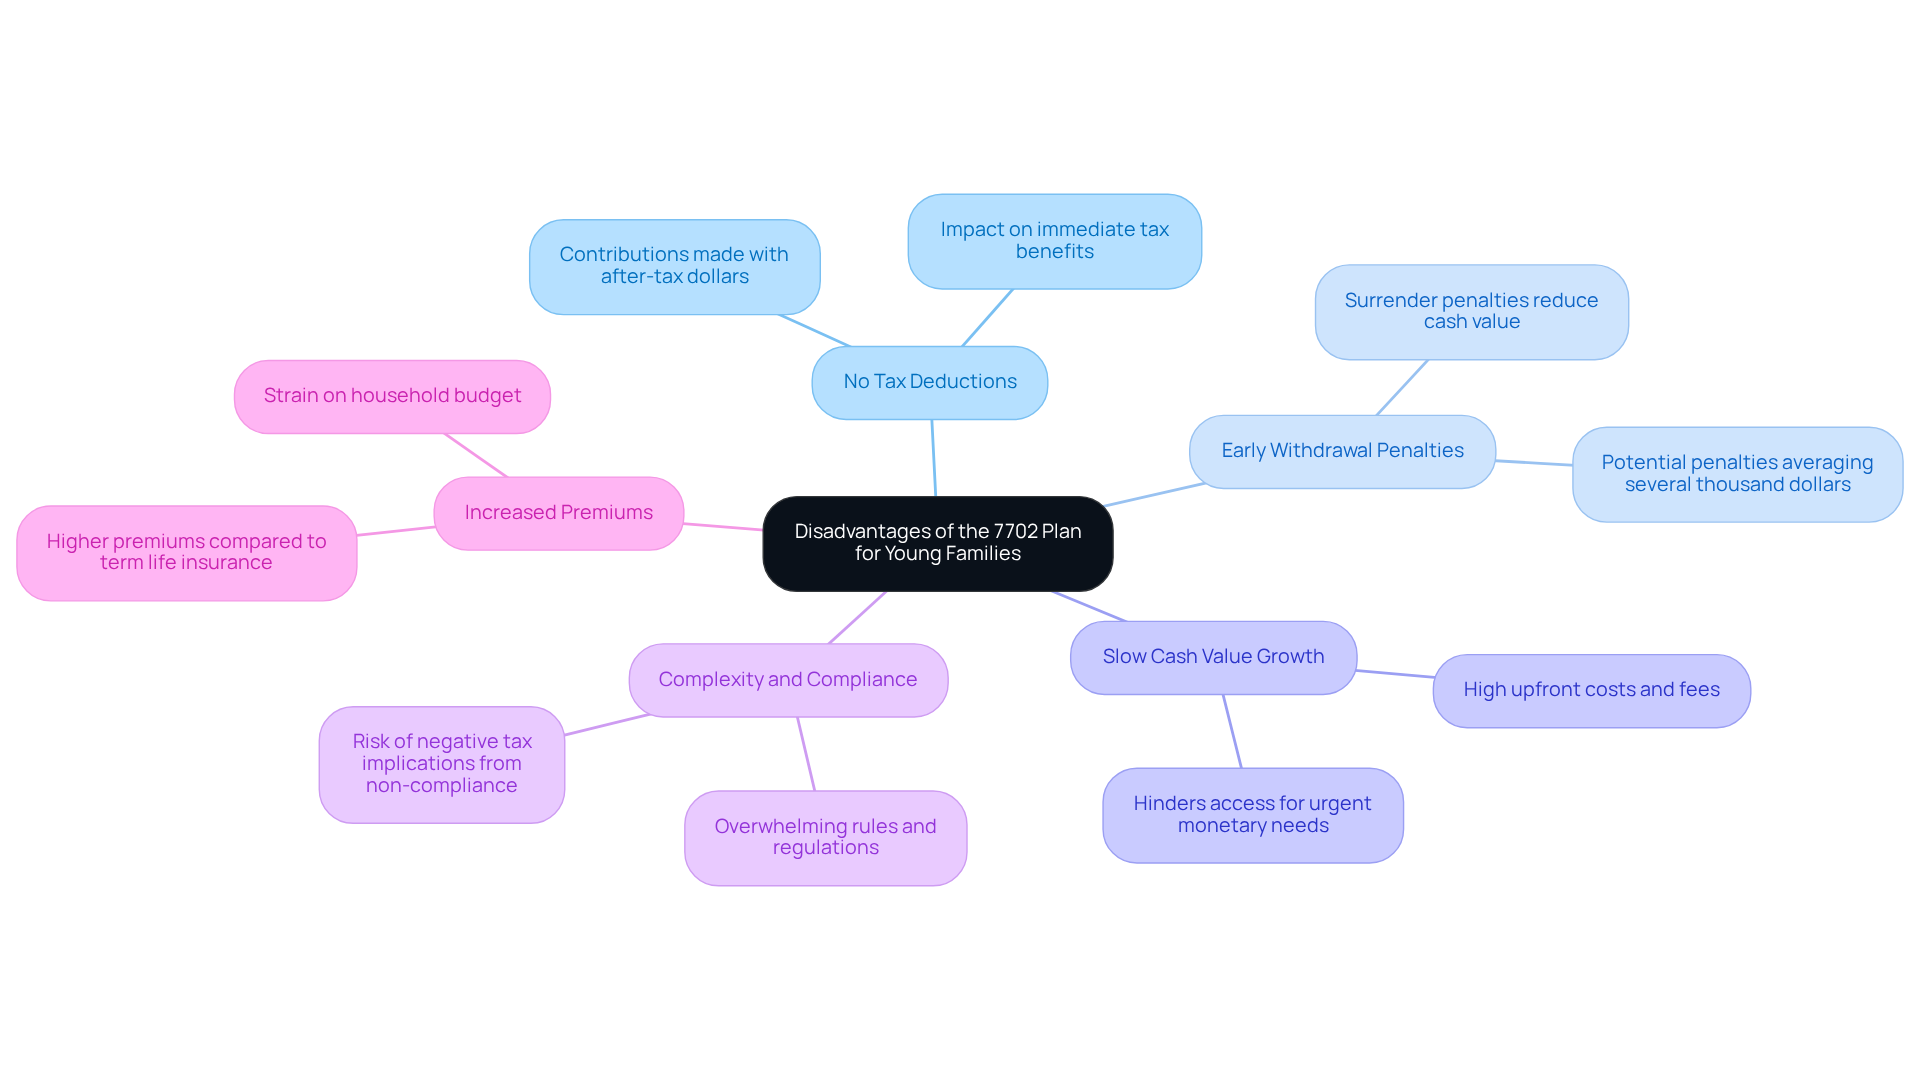
No Tax Deductions for Contributions: Contributions to a 7702 Plan are made with after-tax dollars and are not tax-deductible. This limitation can affect immediate tax benefits compared to traditional retirement accounts. For families like Emily and Mark, who are focused on optimizing their economic situation while managing their careers, this is an important consideration.
-
7702 Plan Disadvantages: Imagine needing to access your funds early, only to face surrender penalties associated with the 7702 plan that significantly reduce your cash value. Families have encountered penalties averaging several thousand dollars, impacting their economic flexibility. Understanding these potential expenses is crucial, as highlighted in Allison and Brian’s journey to enhance their financial potential.
-
7702 Plan Disadvantages: Slow cash value growth can be particularly slow in the early years due to high upfront costs and fees. This gradual growth can hinder families’ ability to tap into the policy for urgent monetary needs, a critical factor for young families striving for immediate economic security.
-
Complexity and Compliance: Navigating the rules governing these Plans, including the 7702 plan disadvantages, can feel overwhelming. Diligent management is necessary to ensure adherence to IRS regulations, as non-compliance can lead to negative tax implications, increasing the financial burden. Financial advisors at Bright Advisers emphasize the importance of careful oversight to avoid pitfalls, as seen in their clients’ experiences.
-
Increased Premiums: One of the 7702 plan disadvantages is that certain plans often require higher premiums compared to term life insurance, which can strain a young household’s budget. This financial obligation might limit their ability to allocate resources to other essential areas, like education or savings—a challenge that households like Jay and Emma have navigated with tailored financial strategies.
These drawbacks underscore the importance of thorough research and discussions with a financial consultant. Together, we can evaluate whether a specific plan aligns with your family’s long-term economic goals. Bright Advisers is dedicated to personalized planning and tax optimization, empowering families to make informed choices that enhance their financial security. We’re here for you on this journey.
Compare the 7702 Plan with Other Financial Options
When evaluating a 7702 plan, families should consider the 7702 plan disadvantages compared to other financial options, especially in the context of reducing financial anxiety and balancing their long-term goals.
-
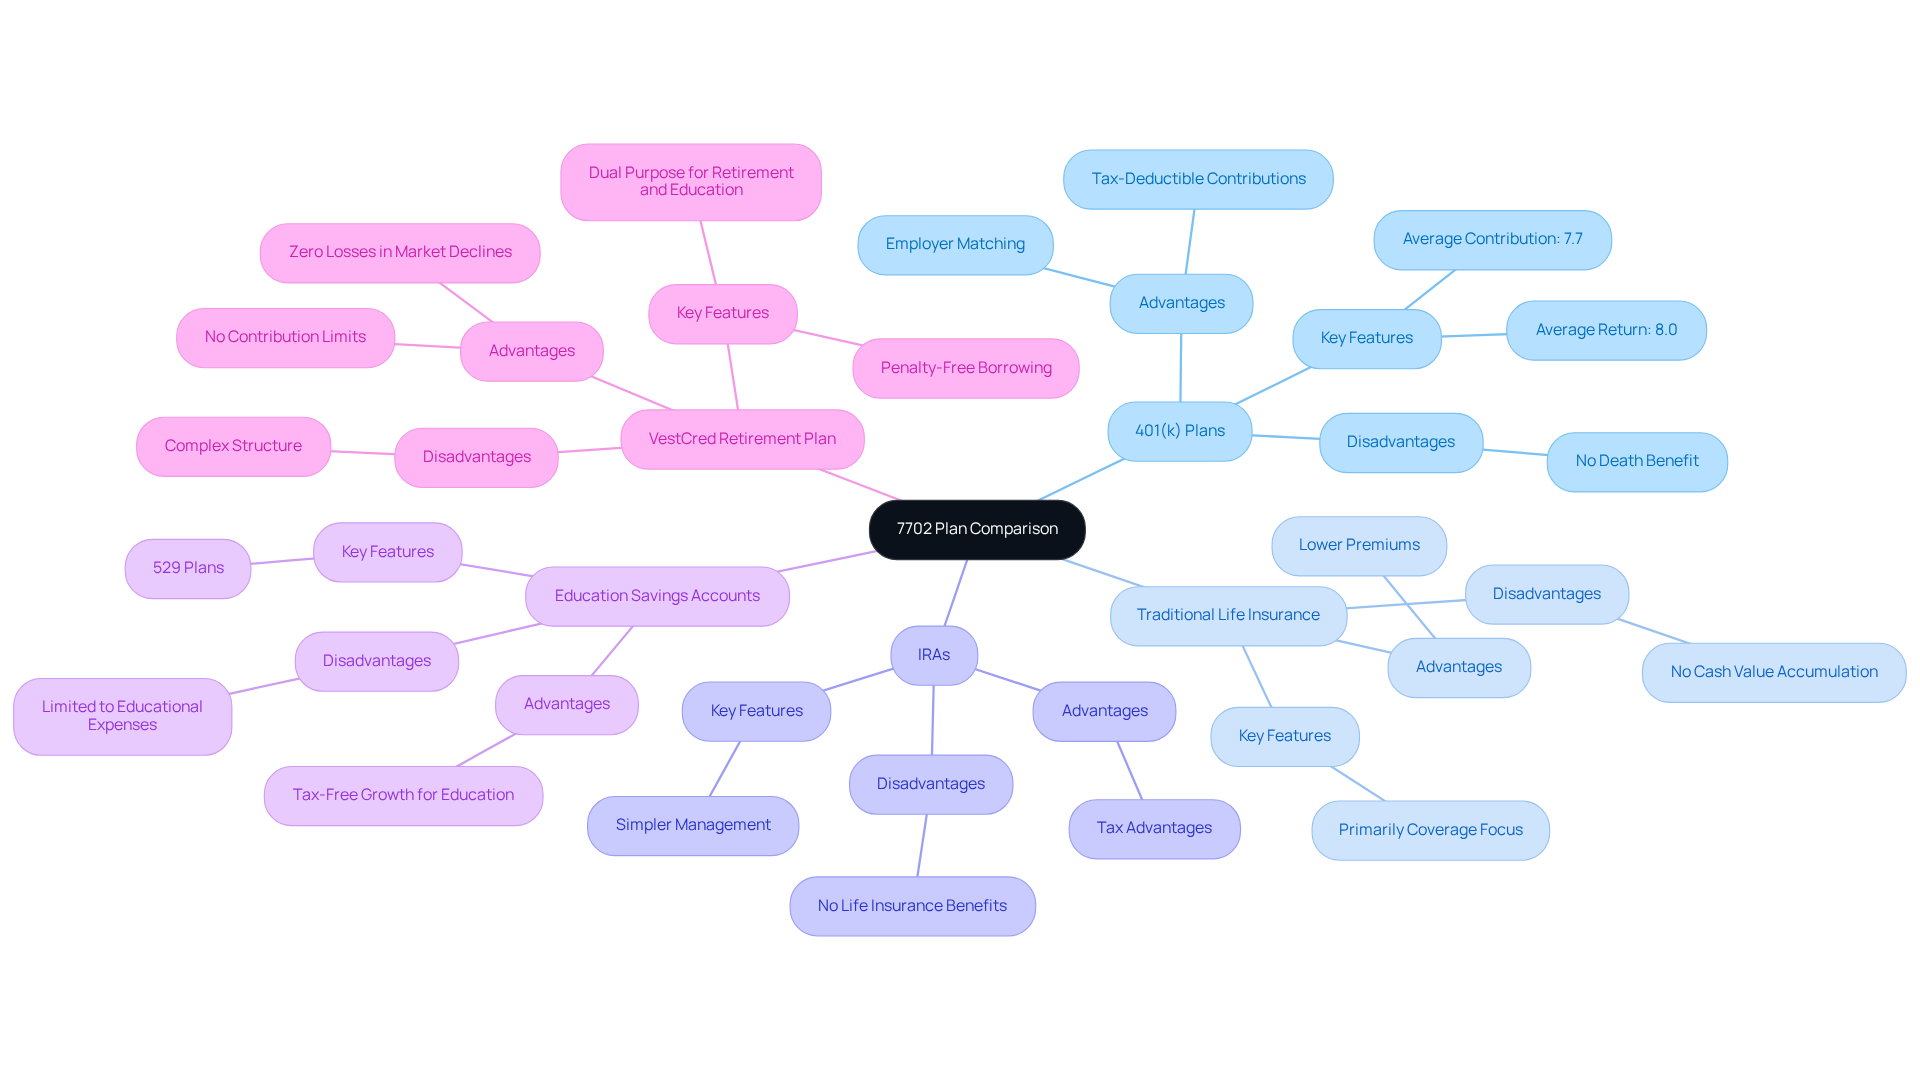
401(k) Plans: These plans allow for tax-deductible contributions and often include employer matching, making them a compelling choice for retirement savings. However, they do not provide a death benefit, which can be crucial for families seeking security for their loved ones.
-
Traditional Life Insurance: Term life insurance generally provides lower premiums in comparison to a certain plan, but it does not build cash value. Families primarily seeking life insurance coverage may find term policies more aligned with their needs. It’s important to recognize that such a plan is fundamentally a life insurance product promoted vigorously, which may not tackle wider financial planning issues.
-
IRAs: Individual Retirement Accounts (IRAs) offer tax advantages similar to those of 401(k)s, but they lack the life insurance benefits associated with 7702 Plans. IRAs are generally more straightforward and easier to manage, making them an attractive option for retirement savings.
-
Education Savings Accounts: For households prioritizing their children’s education, 529 plans are often a better fit. These accounts offer tax-free growth specifically for educational expenses, aligning with the educational objectives of young households.
-
VestCred Retirement Plan: This plan provides distinctive characteristics like no limit on contributions and assures no losses during market declines, making it attractive for households seeking flexibility and security. It tackles the dual requirements of saving for retirement while ensuring that educational needs can also be fulfilled without compromising long-term economic well-being.
By understanding these comparisons, families can make informed decisions about whether a 7702 plan aligns with their financial goals and priorities, while also considering the 7702 plan disadvantages and the ethical concerns surrounding its marketing.
Conclusion
Understanding the complexities of a 7702 Plan is crucial for young families as they navigate their financial futures. Imagine the peace of mind that comes with knowing your family’s financial security is in good hands. These plans offer unique benefits such as tax-deferred growth and a death benefit, but it’s important to recognize the significant disadvantages that can impact your family’s financial flexibility and security. We encourage families to weigh these pros and cons thoughtfully before committing to a policy.
It’s essential to consider key points, such as:
- The lack of tax deductions for contributions
- Potential surrender penalties for early withdrawals
- The slow growth of cash value in the initial years
- The complexity of compliance with IRS regulations
- The higher premiums associated with these plans
By understanding these drawbacks, families can better assess whether a 7702 Plan aligns with their long-term financial goals.
Ultimately, careful consideration and thorough research are vital. Together, we can navigate this journey. Engaging with a financial advisor can provide personalized insights and help families explore alternative financial options that may better suit their needs. The journey toward financial security is significant, and making informed decisions today can lead to a more stable and prosperous future for young families. Remember, we’re here for you every step of the way.
Frequently Asked Questions
What is a 7702 Plan?
A 7702 Plan is a unique type of life insurance policy that provides a death benefit and includes a growing monetary value, governed by Section 7702 of the IRS tax code.
What are the key features of a 7702 Plan?
Key features include tax-deferred cash value growth, tax-free death benefits for beneficiaries, flexibility in borrowing or withdrawing funds, and no contribution limits.
How does the cash value in a 7702 Plan grow?
The cash value grows on a tax-deferred basis, meaning you won’t owe taxes on the growth until you withdraw it.
Can policyholders access the cash value in a 7702 Plan?
Yes, policyholders can borrow against the monetary value or withdraw funds without incurring taxes, as long as the policy complies with IRS guidelines.
What is the primary goal of a 7702 Plan?
The primary goal is to combine life insurance with a savings element, providing financial security for families while addressing future needs, such as college expenses.
What are the disadvantages of a 7702 Plan?
Disadvantages include the risk of surrender penalties for early withdrawals and limitations on cash value accumulation if only the minimum premium is paid.
How can a 7702 Plan help with Social Security taxation?
Certain plans can aid in preventing the taxation of Social Security benefits from extra income, providing a significant advantage for families.
What percentage of American adults have at least one life insurance policy?
51% of American adults have at least one life insurance policy, highlighting the importance of life insurance, including 7702 Plans.
Why do households earning below $50,000 believe they need life insurance?
56% of households earning below $50,000 believe they need life insurance, indicating the relevance of these plans across different income levels.
List of Sources
- Define the 7702 Plan: Key Features and Purpose
- Types of cash value life insurance | Office of the Insurance Commissioner (https://insurance.wa.gov/insurance-resources/life-insurance/types-cash-value-life-insurance)
- Life Insurance Statistics, Data and Industry Trends 2025 (https://forbes.com/advisor/life-insurance/life-insurance-statistics)
- IRC 7702 Pros and Cons (2025) (https://mcfieinsurance.com/7702-plan)
- Life Insurance Facts and Statistics in the US (2025) (https://moneygeek.com/insurance/life/life-insurance-statistics)
- Cash Value Life Insurance: Is It Right for You? – NerdWallet (https://nerdwallet.com/article/insurance/cash-value-life-insurance)
- Explore the Disadvantages of the 7702 Plan for Young Families
- 7702 Account vs. 401(k) Plans [Top Pros and Cons of Each] – I&E | Whole Life & Infinite Banking Strategies (https://insuranceandestates.com/7702-plan-vs-401k)
- IRC 7702 Pros and Cons (2025) (https://mcfieinsurance.com/7702-plan)
- Compare the 7702 Plan with Other Financial Options
- Retirement Plans Compared: 7702 vs IRA vs 401k (https://vestcred.com/retirement-plan-comparison)
- Retirement Account Statistics 2025 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- 7702 Plans Are Not Retirement Plans | Wealthfront (https://wealthfront.com/blog/7702-retirement-plan)
- 7702 Plan: Always a Bad Idea or Simply Misunderstood? (https://theinsuranceproblog.com/7702-plan)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading