

Key Highlights
- Advisory platform fees vary widely, typically ranging from 0.25% to 1.65% of investments annually, with an average of around 1.02% for a $1 million portfolio.
- A 1% fee on a $2 million investment could result in over $375,000 lost in returns over ten years, highlighting the importance of understanding these costs.
- Families working with advisors often see income growth of about 7.5%, translating to approximately $4,384 more annually.
- Types of advisory fees include Assets Under Management (AUM) fees, flat fees, hourly fees, retainer fees, and performance-based fees, each with unique implications for budgeting.
- Fees can significantly erode investment returns over time; a 1% fee can reduce effective returns to 6%, impacting long-term savings for education or retirement.
- Strategies to minimise advisory fees include negotiating charges, choosing the right fee structure, engaging fee-only consultants, monitoring performance, and enhancing financial literacy.
- Bright Advisers emphasises transparency, with no hidden fees or conflicts of interest, and focuses on low-cost wealth management tailored to families’ needs.
Introduction
Imagine feeling overwhelmed by the costs of securing your family’s financial future – you’re not alone in this journey. Understanding the fees associated with advisory platforms can feel daunting, but it’s essential for your family’s financial health. These fees can change a lot depending on how your advisor charges, and they really matter when it comes to your family’s long-term financial health.
As young parents, you might feel lost in the maze of financial planning, wondering how these costs affect your family’s savings and future dreams. It’s important to understand how these fees can impact your wealth accumulation and overall financial well-being. So, how can you make sure you’re not paying more than you need to while still growing your family’s investments? Together, we can navigate this journey and find the best strategies for your family’s financial future.
Define Advisory Platform Fees and Their Importance
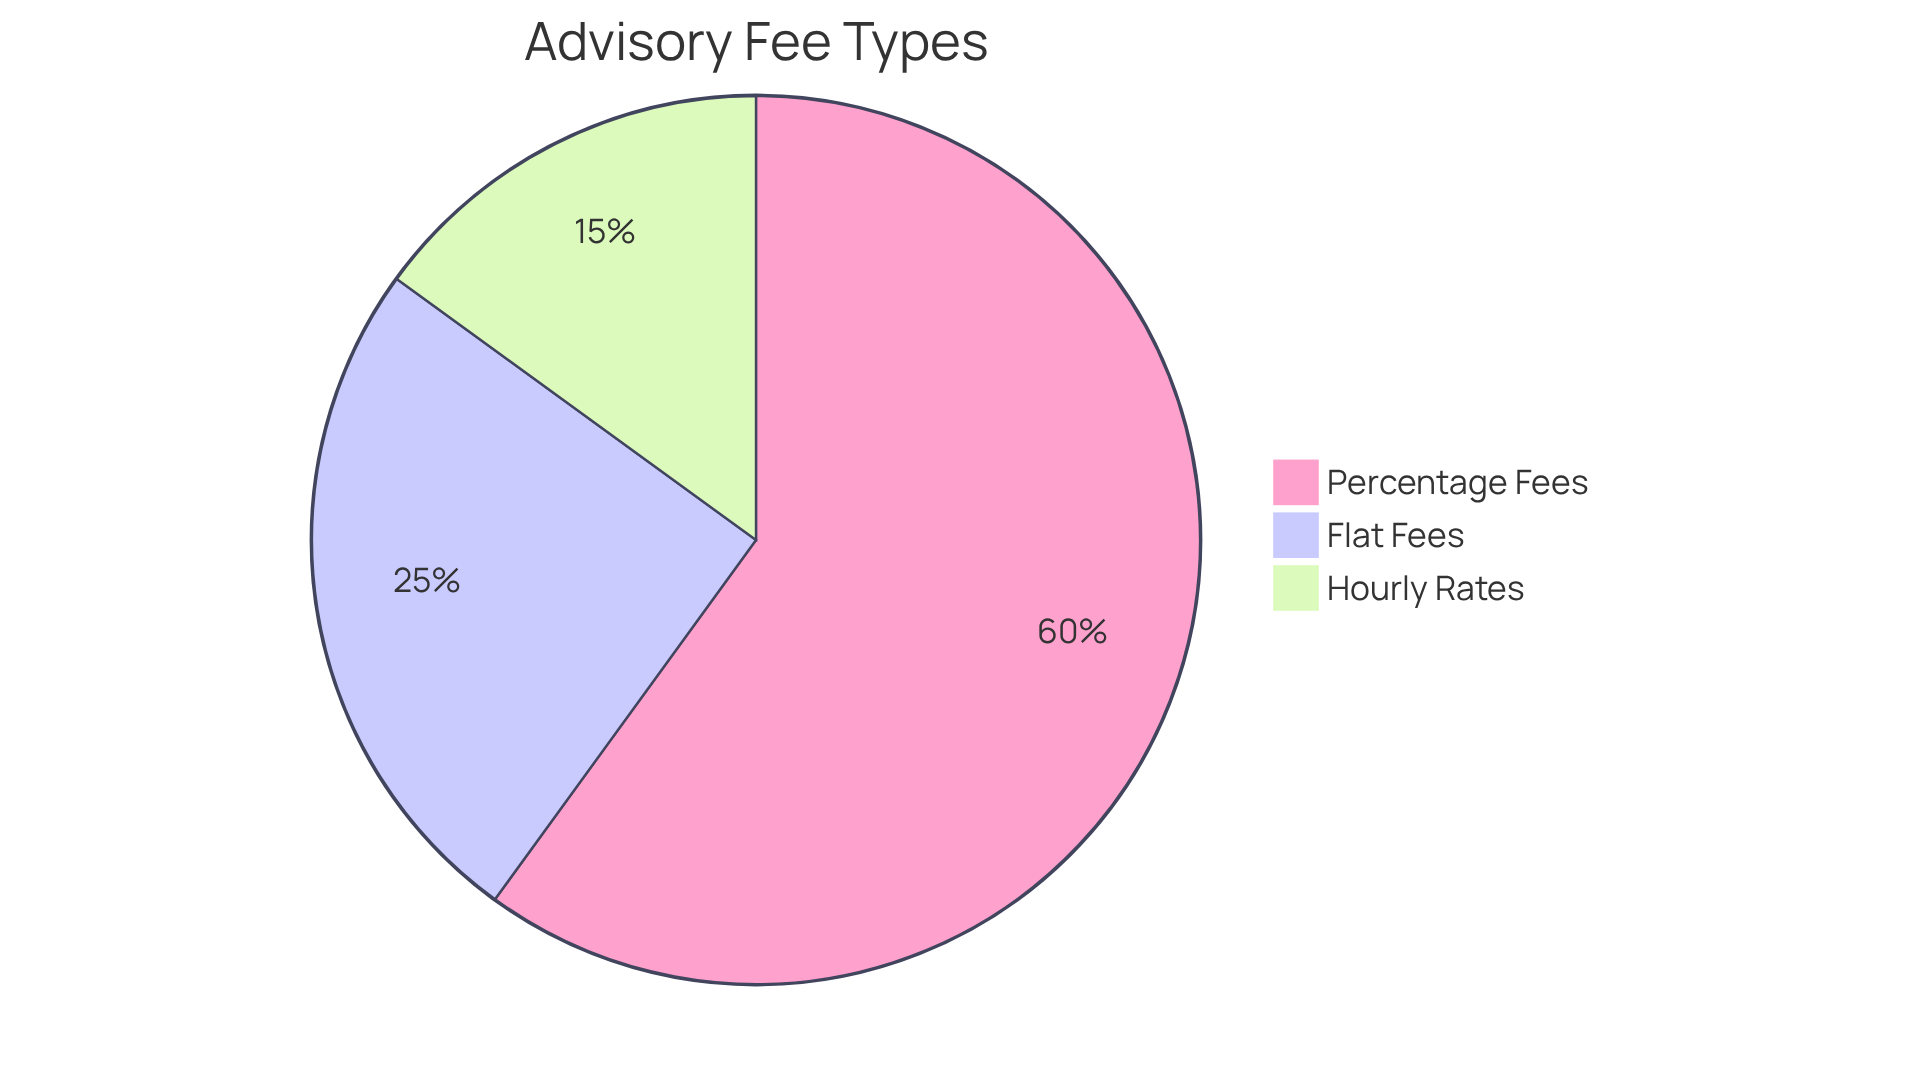
When it comes to managing your investments, understanding the advisory platform fee and other associated costs is essential for your family’s financial journey. The advisory platform fee can vary widely based on how your advisor charges – whether it’s a percentage of your investments, a flat fee, or hourly rates. On average, you might see an advisory platform fee between 0.25% and 1.65% of your investments each year, with many paying around 1.02% for a $1 million portfolio. Understanding the advisory platform fee is vital for young parents like you, as it can significantly impact your family’s financial future.
For example, a 1% fee on a $2 million investment could mean losing out on over $375,000 in returns over ten years – it’s the little costs that add up! When you understand the advisory platform fee, you can better assess the value of the services you receive, ensuring they fit your family’s goals and budget. Families who work with advisors often see their income grow by about 7.5%, which translates to around $4,384 more each year, along with less financial stress and greater happiness. Plus, when you grasp these costs, you can make smarter financial choices, easing the emotional burden that often comes with investing.
So, understanding the advisory platform fee isn’t just about the money – it’s about making informed decisions that can enhance your family’s financial well-being.
Explore Types of Advisory Platform Fees
Imagine feeling the weight of financial decisions as you strive to secure your family’s future. Understanding advisory platform fees can help ease financial anxiety for families like Jay and Emma, allowing them to allocate their resources effectively.
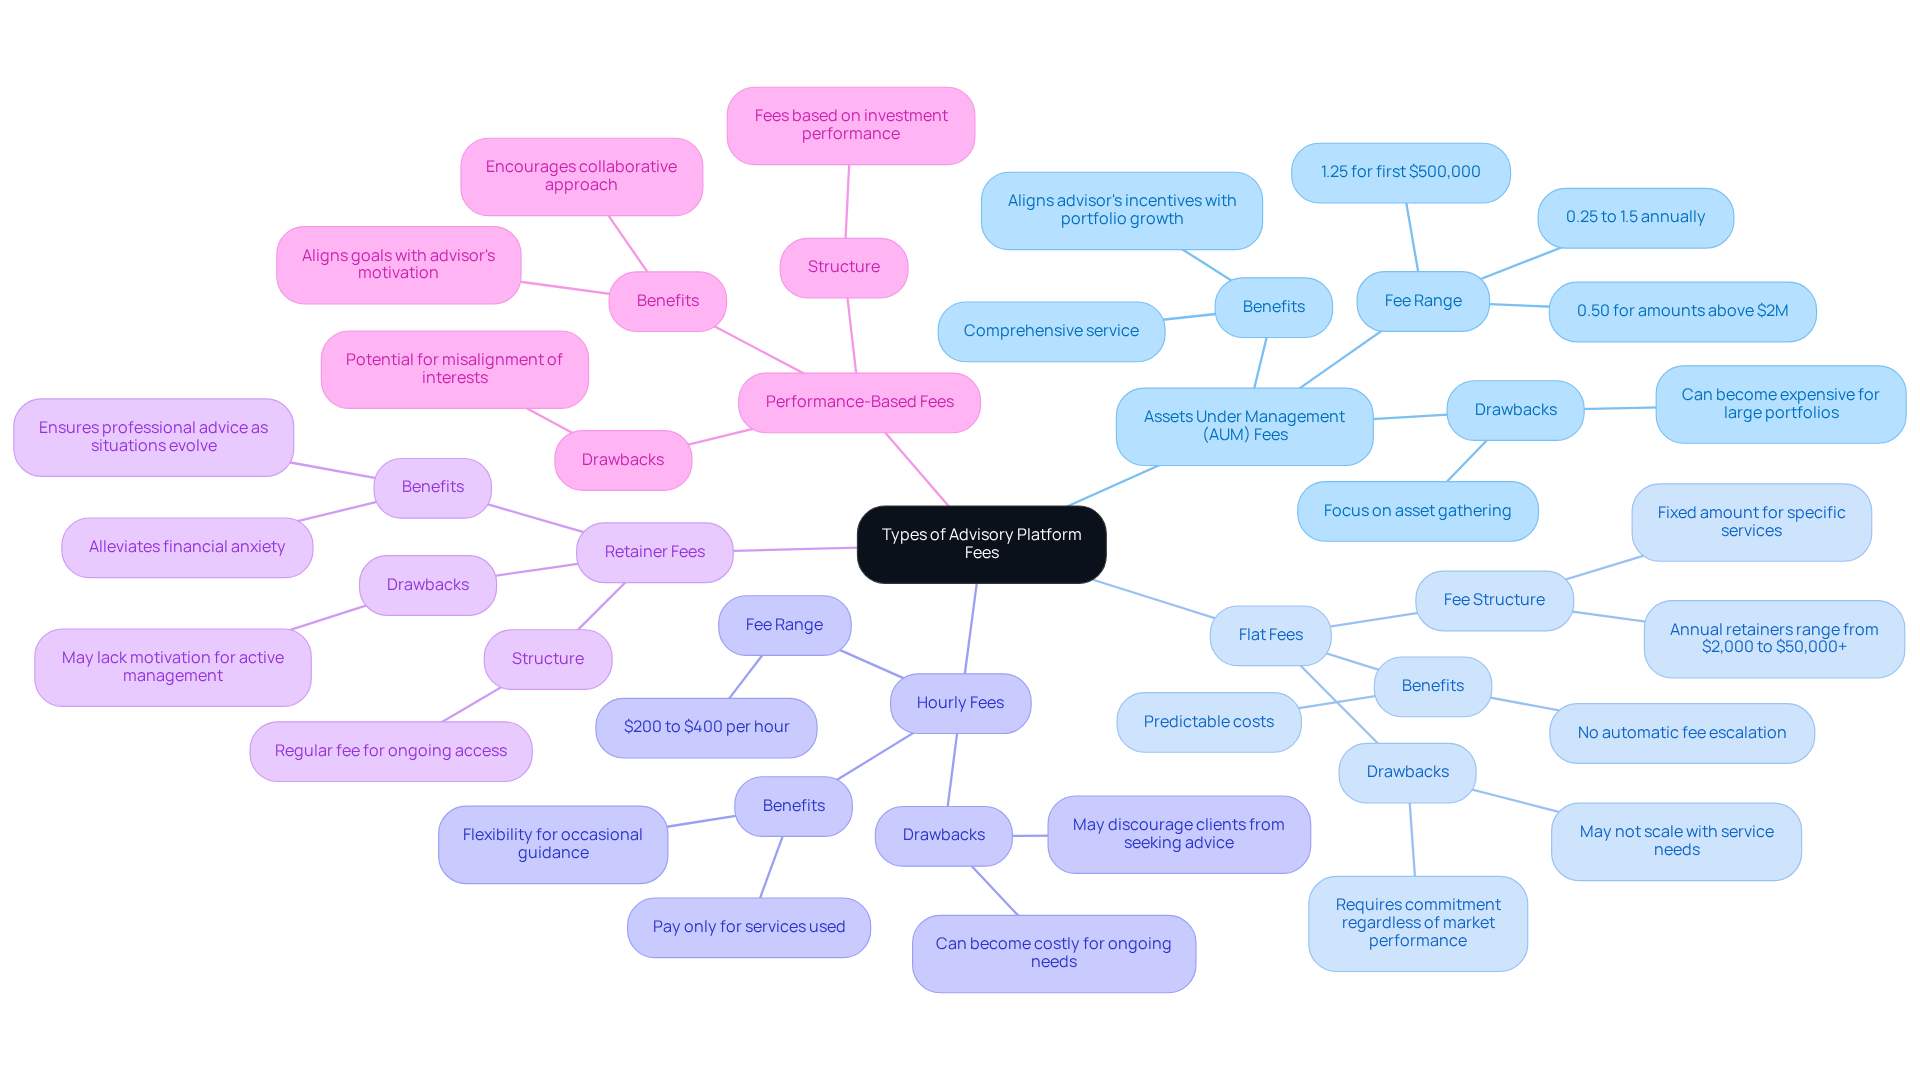
- Assets Under Management (AUM) Fees: These fees are typically a percentage of the total assets managed, usually ranging from 0.25% to 1.5% annually. This means that as your portfolio grows, your advisor benefits too, creating a partnership in your financial journey. For instance, a common AUM fee structure might charge 1.25% for the first $500,000, decreasing for larger amounts. At Bright Advisers, we focus on keeping fund fees low, so you can access wealth management services without excessive costs.
- Flat Fees: Imagine how comforting it would be to know exactly what you’ll pay for financial help each month. Flat fees are a fixed amount charged for specific services, like financial planning or portfolio management. This structure is especially beneficial for families who prefer predictable costs, allowing you to allocate resources effectively without sacrificing long-term goals.
- Hourly Fees: If you only need occasional guidance, hourly fees might be the right choice. Advisors typically charge between $200 and $400 per hour, depending on their experience. This option offers flexibility for households that require support without the commitment of ongoing oversight, making it easier to manage your budget.
- Retainer Fees: Think of retainer fees as a safety net for your financial journey. This regular fee provides ongoing access to advisory services, ensuring you have professional advice as your financial situation evolves. It’s essential for alleviating anxiety as you navigate your family’s financial future.
- Performance-Based Fees: Some advisors charge fees based on investment performance, which can be appealing for families looking for someone motivated to improve their returns. This structure aligns your goals with your advisor’s, fostering a collaborative approach to your investments.
Understanding these fee types can help you feel more in control of your family’s financial future. At Bright Advisers, we are committed to transparency, ensuring no hidden charges or conflicts of interest. We offer flexible monthly costs tailored to your family’s unique needs. Plus, our in-house technology helps create personalized portfolios, steering you away from costly mutual funds and ETFs while enhancing your investment strategies. With the right guidance, you can transform financial anxiety into confidence for your family’s future.
Analyze the Impact of Fees on Financial Outcomes
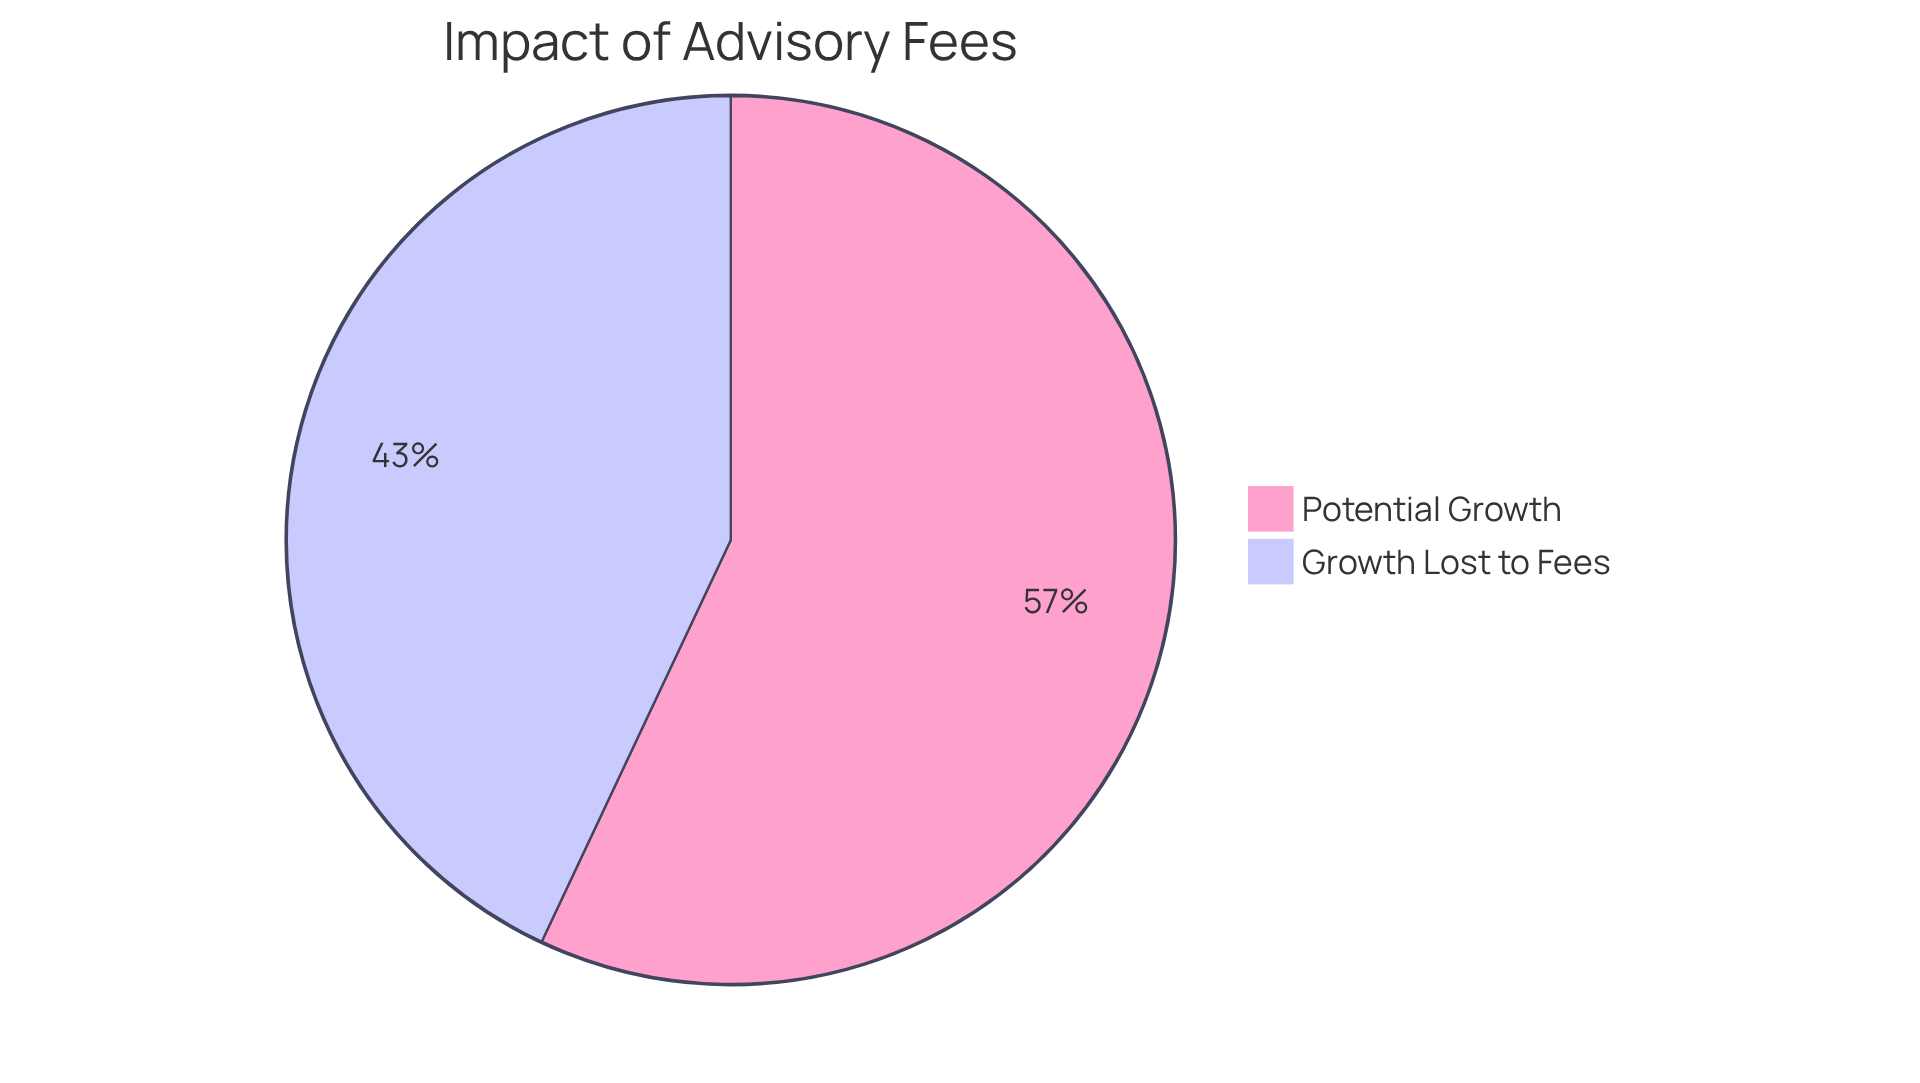
Imagine watching your hard-earned savings dwindle away due to the advisory platform fee; it’s a reality many families face today. At Bright Advisers, we truly care about keeping costs low, making wealth management more accessible for families like yours. A seemingly small advisory platform fee of 1% can erode investment returns over time, impacting your family’s financial stability.
- Compounding Effect: Fees reduce the amount of money that remains invested, which means less capital is available to grow over time. For instance, an investment of $250,000 with a 1% annual charge could lead to almost $1 million less over 30 years compared to an investment with no charges. Remember, compounding can be unforgiving, so seeking cheaper share classes or equivalent index alternatives is crucial. With Bright Advisers’ emphasis on low costs, families can retain a larger portion of their investments working for them.
- Long-Term Growth: The longer your investment horizon, the more significant the impact of charges. If you’re planning for your children’s education or your retirement, it’s vital to be mindful of how the advisory platform fee can impact your savings. A 1% annual fee reduces the effective return to 6%, significantly lowering your portfolio’s final value over decades. By choosing Bright Advisers, families can benefit from an advisory platform fee structure that is designed to maximize long-term growth potential.
- Comparative Analysis: When assessing various consultants, it’s important to consider not only the fee structure but also the potential returns. A lower fee doesn’t always equate to better value if the advisor’s performance is lacking. Portfolios with reduced costs frequently surpass those with elevated costs, as shown by funds in the lowest expense-ratio quartile exceeding those in the highest quartile by about 1.2 percentage points each year over a decade. Bright Advisers’ dedication to low charges ensures that households can focus on reaching their financial goals without unnecessary expenses.
Together, we can navigate the complexities of advisory services, ensuring your choices align with your family’s financial dreams. With Bright Advisers, you can trust that you’re receiving clear, all-inclusive pricing structures with no hidden charges, commissions, or conflicts of interest.
Implement Strategies to Minimize Advisory Fees
Managing advisory fees can feel overwhelming, but with the right strategies, you can take control of your financial future.
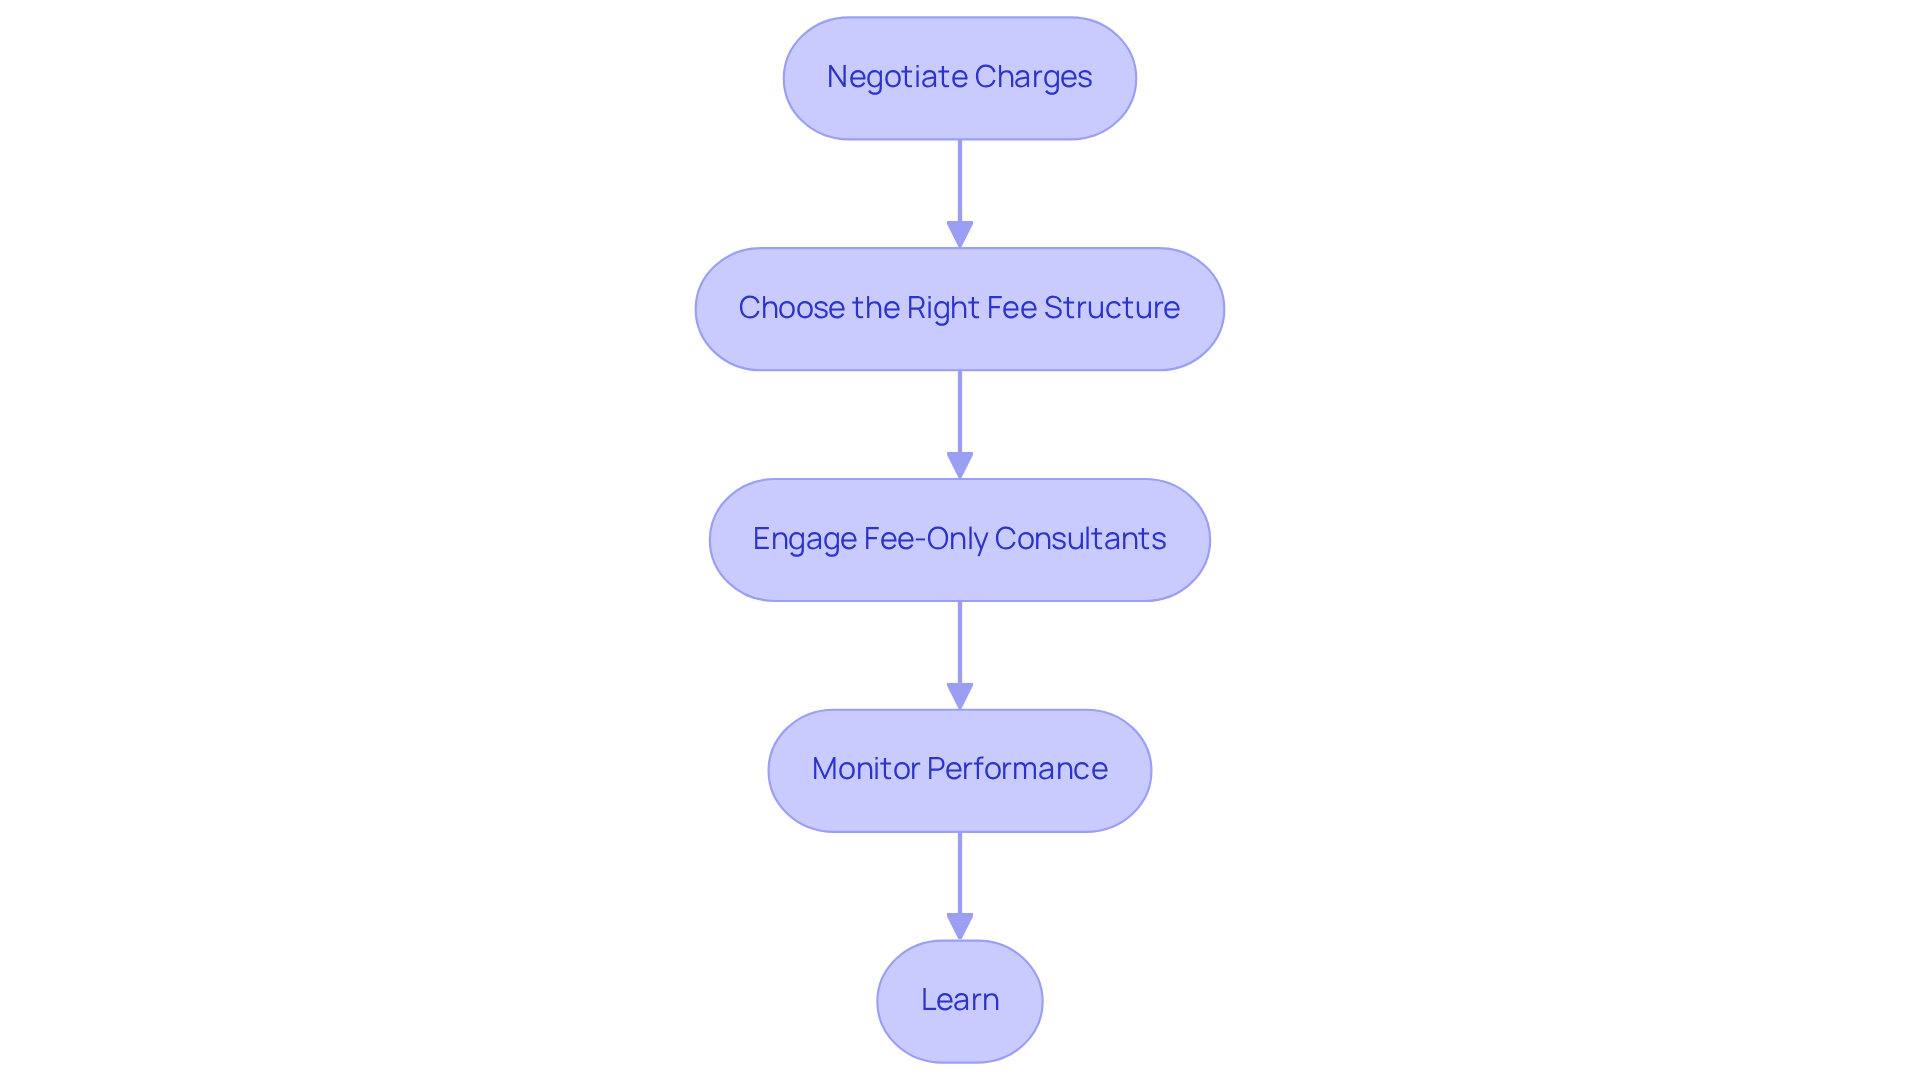
- Negotiate Charges: At Bright Advisers, we believe in open conversations about costs, ensuring you feel comfortable and informed every step of the way. Many advisors are willing to negotiate, especially if you have a substantial asset base or a long-term relationship with them.
- Choose the Right Fee Structure: It’s important to evaluate which fee model best fits your monetary situation. For instance, if you only need occasional guidance, opting for an hourly fee may be more economical than a retainer. Bright Advisers has a no minimum account size policy, making our services accessible to families at various financial stages.
- Engage Fee-Only Consultants: Collaborating with fee-only consultants like Bright Advisers means you’ll receive guidance that’s truly in your best interest. This approach removes possible conflicts of interest that can occur with commission-based consultants. We’re here to ensure that your best interests always come first, giving you peace of mind in your financial journey.
- Monitor Performance: Regularly assessing your consultant’s performance against relevant benchmarks is key. If they consistently fall short, it may be time to reconsider your advisory relationship. As the industry evolves, staying informed about your advisor’s performance becomes even more important for your family’s financial health.
- Learn: When you understand your finances better, you can ask the right questions and find the best value for your family’s needs. Case studies, like that of Jay and Emma, show that households who actively participate in their planning often achieve improved results and reduced costs. With Bright Advisers’ support, they developed a solid monetary strategy that included optimized tax planning and a tailored retirement plan, balancing their current responsibilities with long-term aspirations.
Taking these steps not only eases financial burdens but also empowers you to create a secure future for your family.
Conclusion
Navigating the world of advisory fees can feel overwhelming, especially when you’re trying to secure your family’s future. When you understand the different fee structures, it helps you make choices that truly benefit your family’s financial journey. With the right insights, you can confidently navigate financial planning, making sure your investments are working for your family.
We’ve shared important insights about various advisory fees, like AUM, flat fees, and more, to help you understand your options. Each fee structure has its pros and cons, and knowing these can guide you to the best choice for your family’s needs. It’s also important to see how fees can affect your investments over time, as lower costs can lead to better returns.
Your journey to financial well-being is about more than just managing costs; it’s about taking charge of your family’s financial future. We encourage you to have open conversations with your advisors, explore different fee options, and keep an eye on your financial progress. By taking these steps, you can turn financial worries into confidence, paving the way for a brighter future for your kids.
If you need personalized guidance for your family’s unique situation, we’re here for you. Reach out to Bright Advisers at hello@brightadvisers.com or call (714) 987-2967.
Frequently Asked Questions
What is an advisory platform fee?
An advisory platform fee is a cost associated with managing your investments, which can vary based on how your advisor charges-whether it’s a percentage of your investments, a flat fee, or hourly rates.
How much do advisory platform fees typically range?
Advisory platform fees typically range from 0.25% to 1.65% of your investments each year, with many clients paying around 1.02% for a $1 million portfolio.
Why is understanding the advisory platform fee important for families?
Understanding the advisory platform fee is crucial for families, especially young parents, as it can significantly impact their financial future and help them assess the value of the services they receive.
How can advisory platform fees affect investment returns?
For example, a 1% fee on a $2 million investment could result in losing over $375,000 in returns over ten years, highlighting how small costs can accumulate and affect overall returns.
What benefits do families experience when working with advisors?
Families who work with advisors often see their income grow by about 7.5%, which translates to approximately $4,384 more each year, along with reduced financial stress and increased happiness.
How does understanding advisory platform fees contribute to better financial decisions?
By grasping these costs, families can make smarter financial choices, easing the emotional burden that often accompanies investing and enhancing their overall financial well-being.
List of Sources
- Define Advisory Platform Fees and Their Importance
- Pros and cons of different advisory fee models (https://envestnet.com/financial-intel/pros-and-cons-different-advisory-fee-models)
- How Financial Advisors Actually Charge For Their Services (https://kitces.com/blog/financial-advisors-charge-services-fee-structure-advisory-firm-profession-aum-pricing-insight)
- Financial Advisor Cost | Fee Structures & Average Cost Backed by Data (https://financestrategists.com/financial-advisor/advisor-cost)
- Cerulli Associates | More Than 72% of Financial Advisors Are… (https://cerulli.com/press-releases/more-than-72-of-financial-advisors-are-compensated-by-fee-based-models)
- Understanding Average Advisory Fees: A Guide for Young Families – Bright Advisers (https://brightadvisers.com/understanding-average-advisory-fees-a-guide-for-young-families)
- Explore Types of Advisory Platform Fees
- Flat Fee vs 1% AUM Advisor: $1M and $2M Cost Math (https://flamesfp.com/financial-planning-guides/flat-fee-vs-1-percent-aum)
- How Much Does a Financial Advisor Cost? Complete 2026 Fee Guide | Domain Money Financial Planning (https://domainmoney.com/post/how-much-does-a-financial-advisor-cost)
- Pros and cons of different advisory fee models (https://envestnet.com/financial-intel/pros-and-cons-different-advisory-fee-models)
- Independent Financial Advisor Fee Comparison: All-In Costs (https://kitces.com/blog/independent-financial-advisor-fees-comparison-typical-aum-wealth-management-fee)
- Analyze the Impact of Fees on Financial Outcomes
- How Fees and Expenses Affect Your Investment Portfolio – Investor Bulletin | Investor.gov (https://investor.gov/introduction-investing/general-resources/news-alerts/alerts-bulletins/investor-bulletins/updated)
- Impact of Fees on Investment Returns (https://linkedin.com/top-content/finance/managing-investment-accounts/impact-of-fees-on-investment-returns)
- How fees affect investment performance (https://truthifi.com/education/fee-impact-on-performance)
- Implement Strategies to Minimize Advisory Fees
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)
- Pros and cons of different advisory fee models (https://envestnet.com/financial-intel/pros-and-cons-different-advisory-fee-models)
- How Fee-Only Financial Advisors Are Compensated (https://primefinancial.com/wealth-management-education/choosing-a-financial-advisor/how-fee-only-financial-advisors-are-compensated)
- Cerulli Associates | More Than 72% of Financial Advisors Are… (https://cerulli.com/press-releases/more-than-72-of-financial-advisors-are-compensated-by-fee-based-models)
- 35 Quotes for Financial Advisors on a Tough Day | Don Connelly & Associates (https://donconnelly.com/35-quotes-for-financial-advisors)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading