

Key Highlights
- Cliff vesting refers to the process where employees earn employer contributions to retirement plans after a specified period, often leading to significant financial implications for families.
- Understanding cliff vesting is crucial for families, especially during job transitions, to avoid forfeiting employer contributions and ensure financial security.
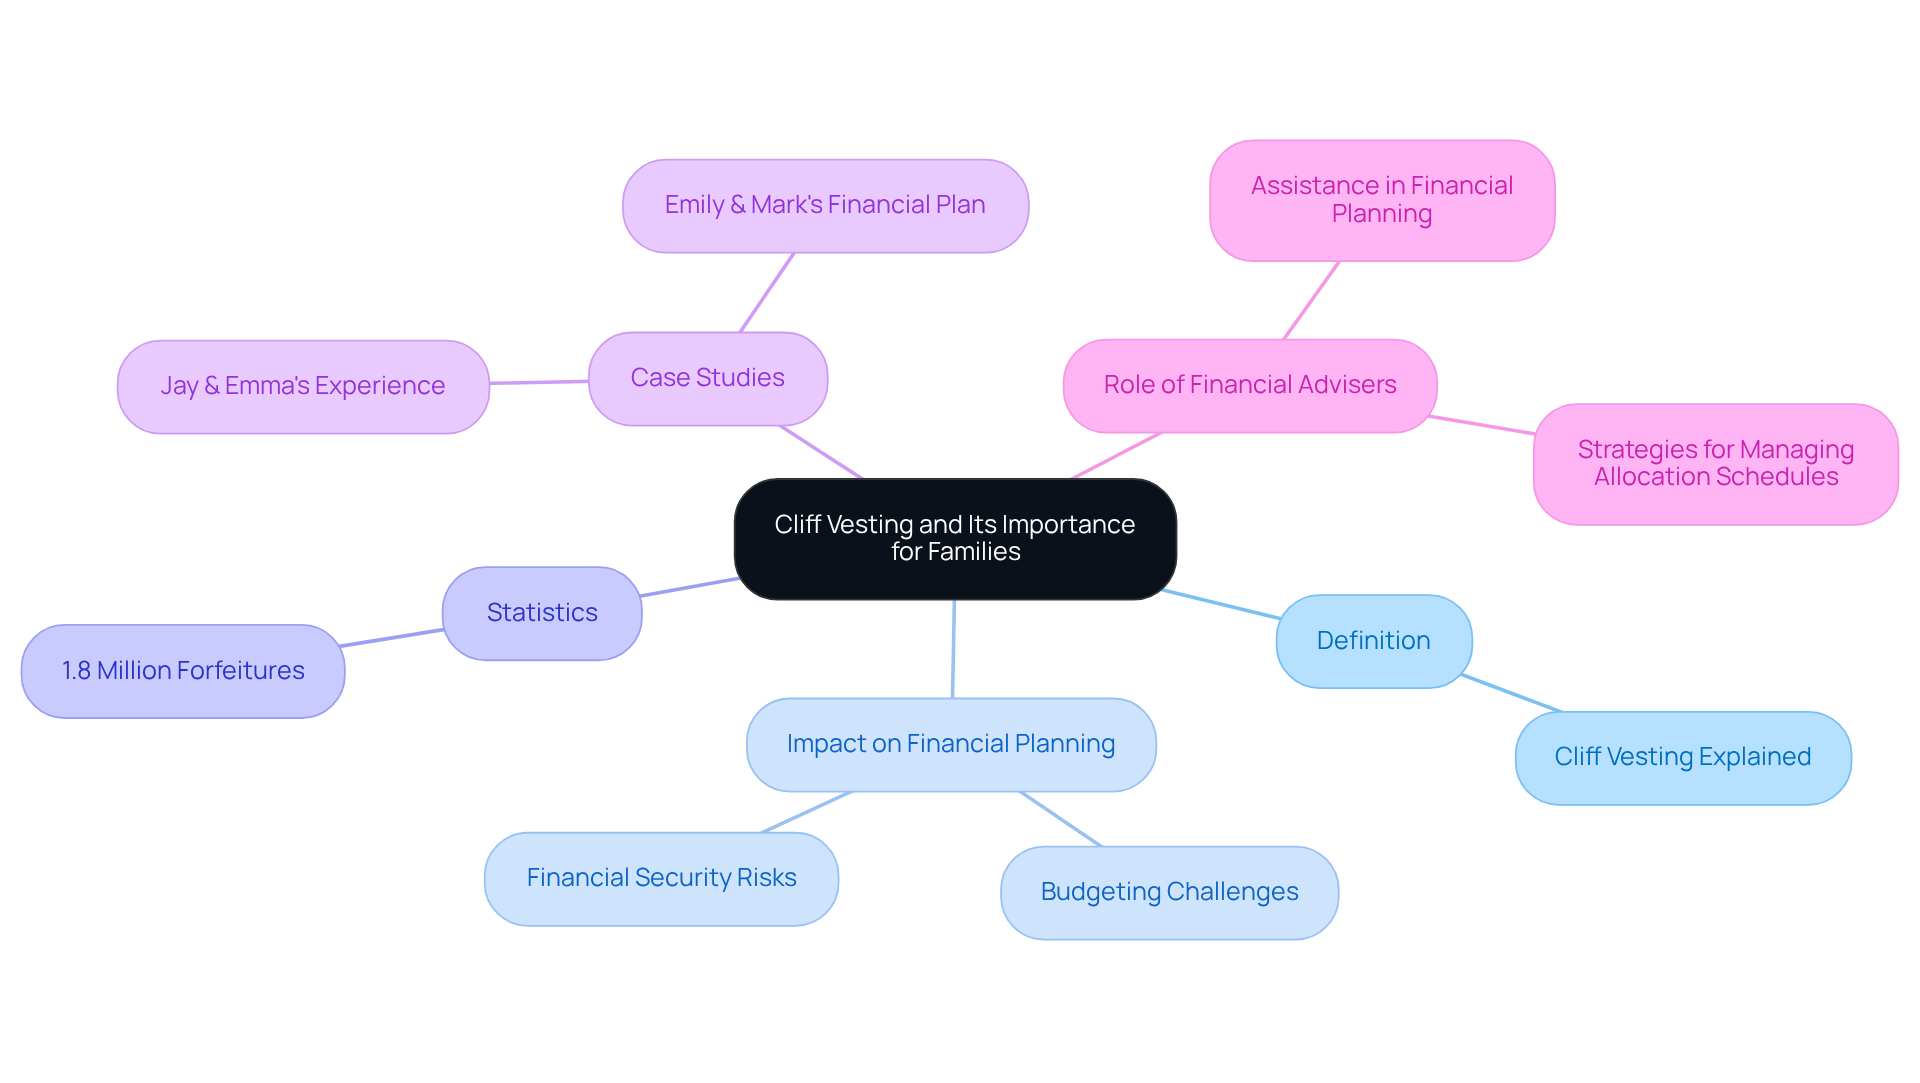
- Statistics indicate that over 1.8 million employees forfeited benefits in 2022 due to not meeting eligibility criteria, highlighting the risks associated with cliff vesting.
- Cliff vesting typically follows a four-year schedule with a one-year threshold, where employees lose all unvested benefits if they leave before one year.
- Benefits of cliff vesting include encouraging long-term employment and providing lump-sum benefits, which can aid families in major financial decisions.
- Drawbacks include the risk of losing benefits if leaving a job prematurely and delayed access to funds, which can create financial stress.
- Families can manage cliff vesting by evaluating job offers, planning for major life events, working with fiduciary advisors like Bright Advisers, and diversifying investments.
- All advisory services are provided through Lifeworks Advisors, a registered investment adviser, emphasising fiduciary duty and transparency.
Introduction
Imagine navigating a job change and realizing you’ve missed out on crucial benefits that could secure your family’s future. Understanding cliff vesting is essential for families striving to protect their financial well-being. As you navigate the complexities of retirement plans, remember that the stakes are high. Misunderstanding cliff vesting could jeopardize your family’s financial security during crucial transitions. Together, we can explore how to make informed decisions that protect your family’s financial well-being and legacy.
Define Cliff Vesting and Its Importance for Families
Imagine navigating a job change while worrying about your family’s financial future – it’s a challenge many parents face today. Cliff acquisition is a term that describes how employees earn their employer’s contributions to retirement plans after a set period, often called the ‘cliff.’ Understanding how gradual acquisition works is crucial for families, as it can significantly impact their budgeting and financial planning.
Many parents feel overwhelmed by the complexities of retirement plans and how they affect their family’s financial future. If you’re considering a job change, knowing about cliff rewards can help you make informed decisions that benefit your family’s monetary future. Without this understanding, families might make choices that could put their financial security and their children’s future at risk.
Statistics show that many employees, particularly those from lower-income backgrounds, struggle with understanding their allocation schedules, which can be really tough for families trying to make ends meet. In 2022, over 1.8 million participants forfeited compensation because they didn’t meet eligibility criteria, highlighting the potential losses that can arise from job transitions before full entitlement.
Case studies illustrate how families like Jay & Emma, who sought advice from Bright Advisers, managed job transitions while understanding their contribution schedules, ensuring they didn’t forfeit substantial employer contributions. Similarly, Emily and Mark worked with Bright Advisers to create a comprehensive financial plan that included strategies for managing their allocation schedules efficiently, along with tax optimization and tailored planning services. By acknowledging the significance of cliff vesting, families can enhance their planning for career moves and financial choices, ultimately improving their economic security and legacy.
By working with Bright Advisers, families can make smart financial choices that prepare them for today’s needs and tomorrow’s dreams. This approach not only helps in optimizing their financial well-being but also secures their children’s educational readiness and overall financial stability.
Explain How Cliff Vesting Works: Mechanics and Timelines
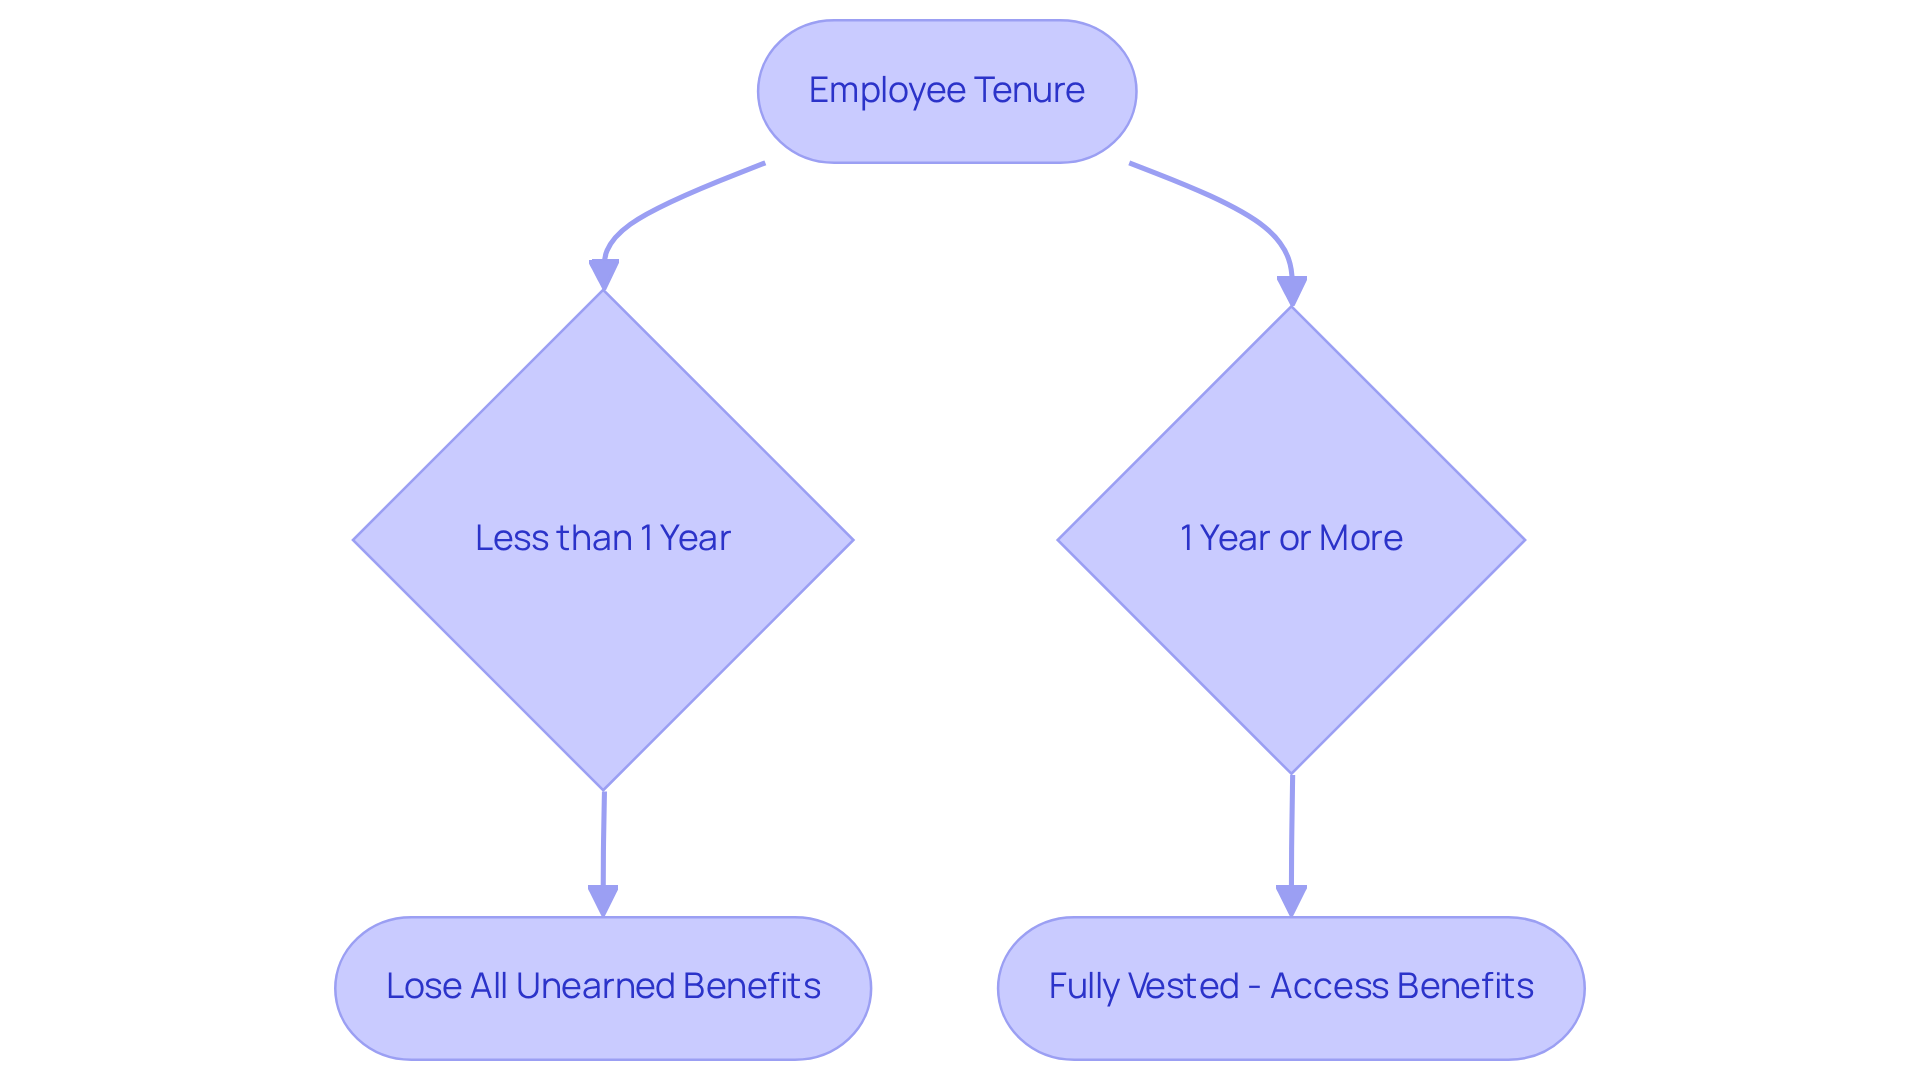
Imagine the worry of losing your hard-earned benefits just when your family needs them the most. Cliff vesting operates on a clear principle: employees must remain with their employer for a specified period before they gain full rights to their benefits. The most common arrangement is a four-year vesting schedule with a one-year threshold. During this gap period, employees do not accumulate any vested benefits. Once the peak is reached, they typically receive a lump sum of benefits, such as 100% of their employer’s contributions to a retirement plan or stock options.
For example, under a typical four-year acquisition timeline with a one-year threshold:
- If an employee departs the organization after 11 months, they lose all unearned benefits.
- Conversely, if they remain for the full year, they become fully vested and can access their benefits.
This timeline is especially important for households, particularly when preparing for major life events such as buying a home or financing their children’s education.
In fact, many families faced the heart-wrenching reality of losing benefits when they needed them most, with around 1.8 million participants affected last year alone. This emphasizes the economic risks linked to cliff vesting allocation. Moreover, the trend of increasing affected participants underscores the challenges many face in accumulating retirement savings. Understanding these timelines can be the key to securing your family’s financial future, ensuring you don’t miss out on what you’ve worked so hard for.
Evaluate the Benefits and Drawbacks of Cliff Vesting for Family Wealth
Cliff vesting can be a double-edged sword for families navigating their financial landscape:
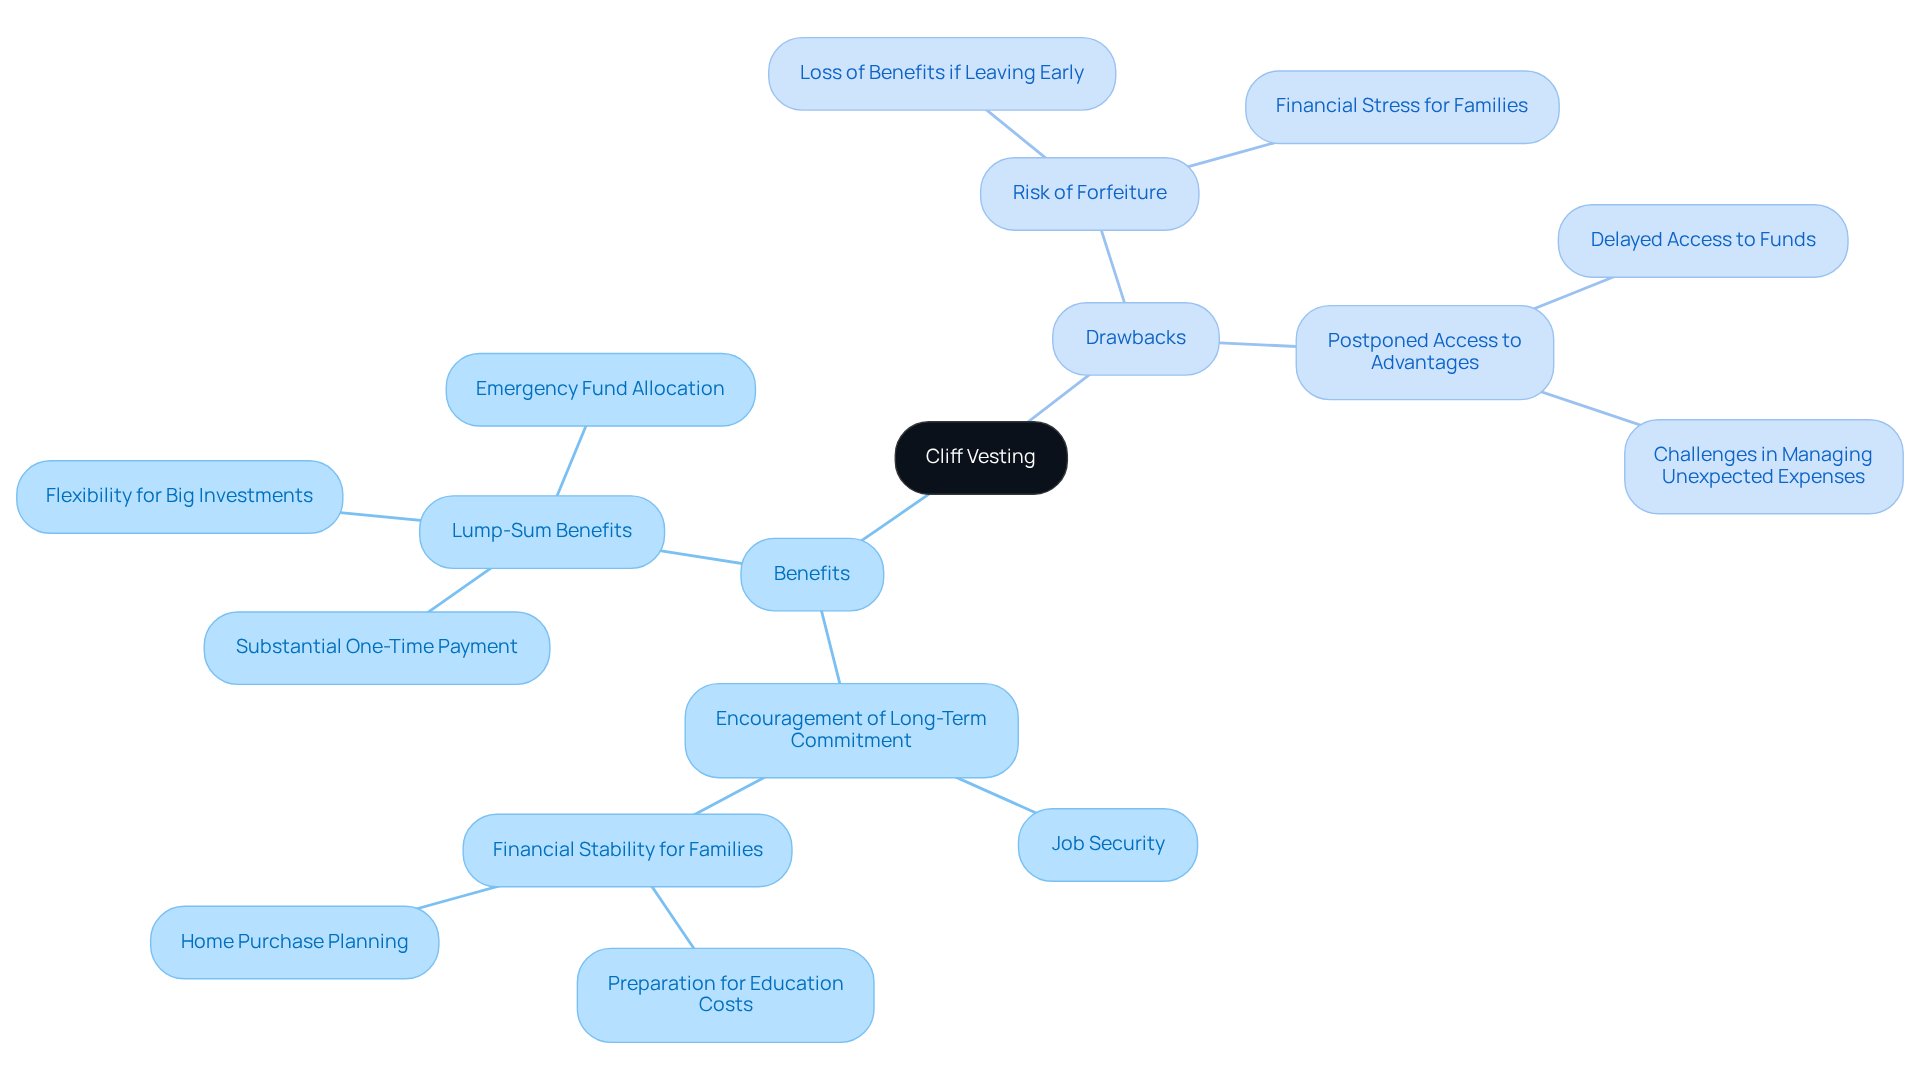
- Encouragement of Long-Term Commitment: This structure encourages employees to stay with their employer longer, which helps create job security and financial stability for their families. As workers remain longer, they can build a stronger economic foundation, essential for households preparing for upcoming costs like education and home purchases.
- Lump-Sum Benefits: Upon reaching the peak, employees receive a substantial benefit all at once. This can be a game-changer for families, allowing them to allocate funds wisely for big investments or unexpected emergencies.
However, there are notable drawbacks to consider:
- Risk of Forfeiture: Imagine leaving a job only to lose out on benefits you were counting on for your family’s future. If an employee departs before the cliff period concludes, they forfeit all unvested benefits. This can create real financial stress for families who are relying on these benefits to plan for their future.
- Postponed Access to Advantages: Families may face situations where immediate financial resources are crucial, yet they cannot access their benefits due to the vesting schedule. This delay can create challenges in managing unexpected expenses or opportunities.
Understanding these factors can empower families to make choices that align with their financial dreams and aspirations. For example, Emily and Mark, a couple in their mid-30s, sought advice from Bright Advisers to enhance their economic situation and gain the freedom to decide whether or not to keep working. Bright Advisers conducted a comprehensive evaluation of their monetary situation and implemented strategies for managing cash flow, reducing debt, and planning for retirement. This enabled them to make informed choices regarding their careers and personal life.
Implement Strategies for Managing Cliff Vesting in Financial Planning
Navigating the complexities of cliff vesting can feel overwhelming for many families, particularly when trying to balance financial goals with everyday needs. Here are some key strategies to help you manage this important aspect of financial planning:
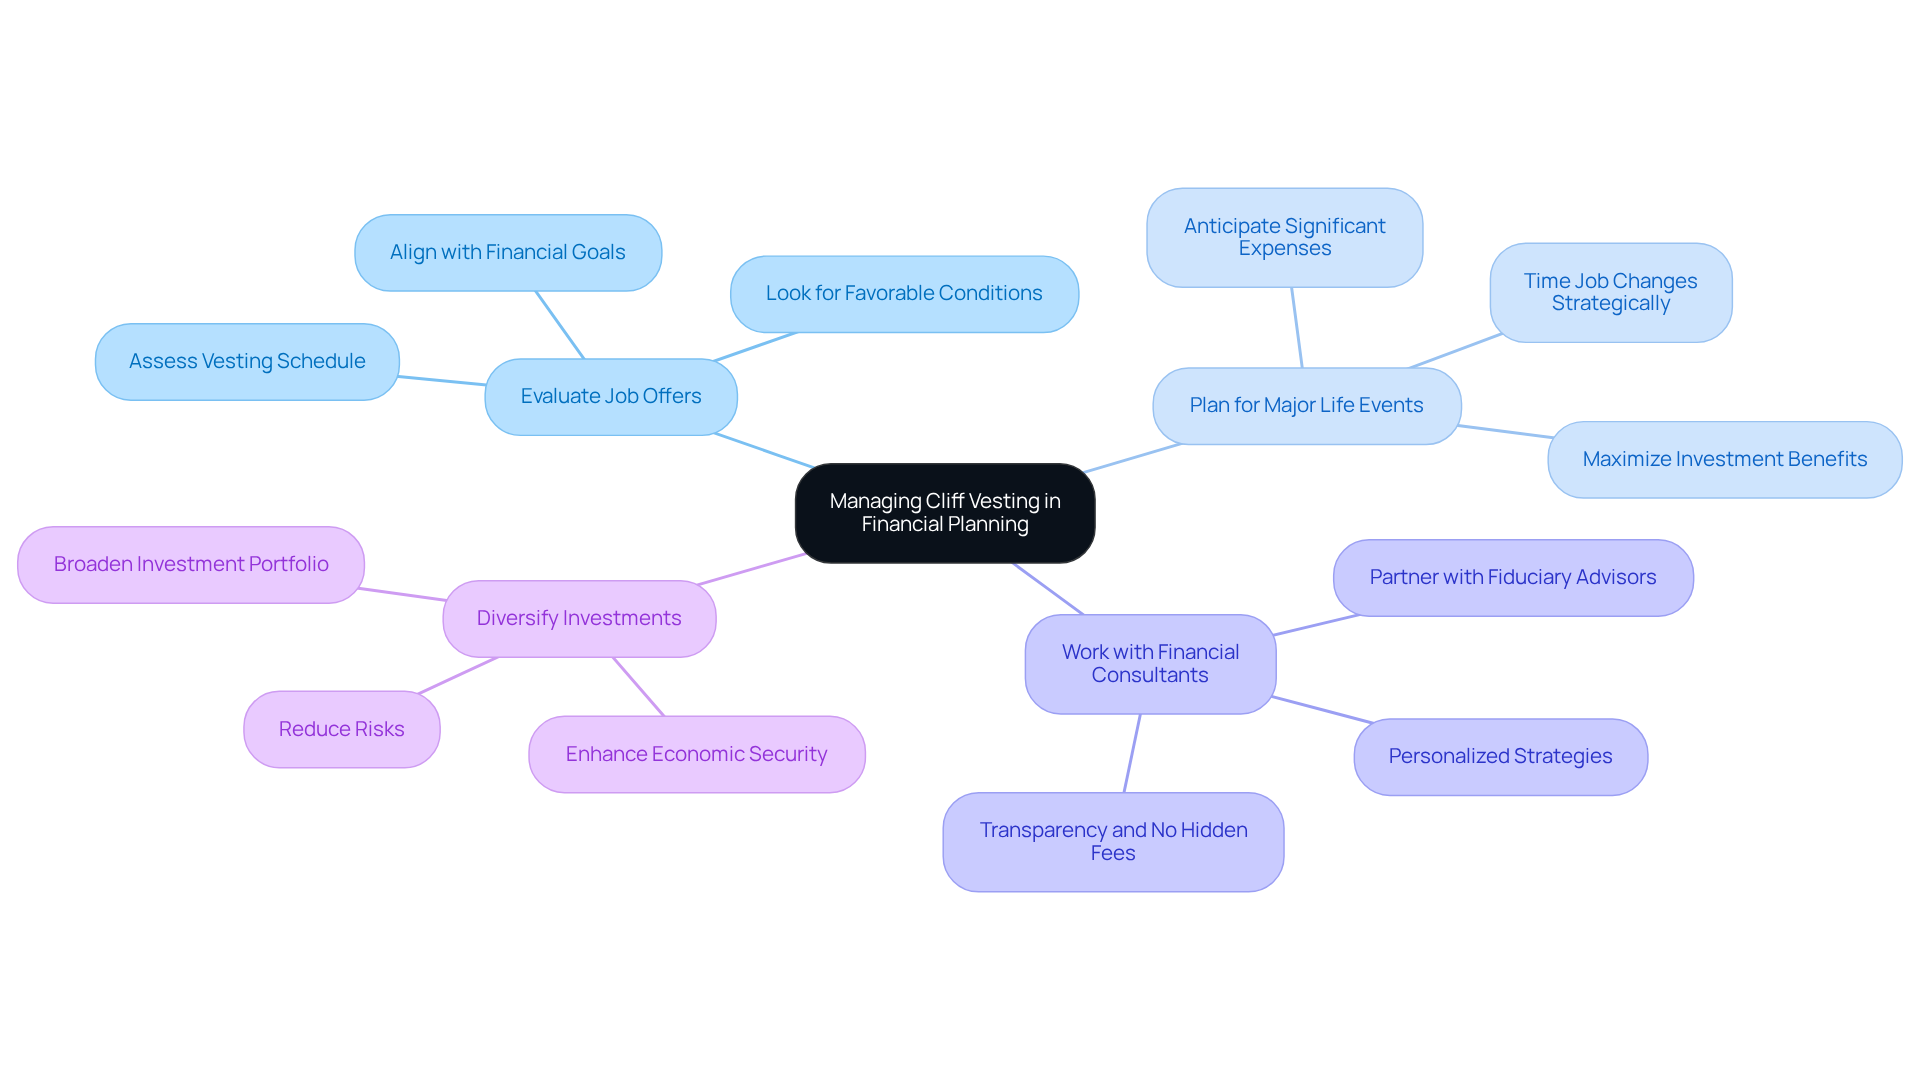
- Evaluate Job Offers Carefully: When considering new employment opportunities, take a moment to assess the vesting schedule and how it aligns with your family’s financial goals. Look for roles that offer more favorable allocation conditions to enhance your economic stability.
- Plan for Major Life Events: Anticipate significant expenses, like buying a home or supporting education, and time your job changes or financial decisions around your earning schedule. This thoughtful timing can help you maximize the benefits of your investment plan.
- Work with Caring Financial Consultants: Partnering with a fiduciary advisor, like Bright Advisers, can help you find personalized strategies that fit your family’s unique financial needs. Bright Advisers emphasizes fiduciary duty and transparency, ensuring no hidden fees or conflicts of interest. These specialists can assist you in managing the intricacies of gradual acquisition and seamlessly incorporate it into your broader financial strategy.
- Diversify Investments: Consider broadening your investment portfolio to reduce risks associated with gradual acquisition. A well-diversified portfolio can provide extra economic security while you wait for benefits to vest.
By embracing these strategies, your family can confidently navigate cliff vesting, paving the way for a brighter financial future. Remember, all advisory services are provided through Lifeworks Advisors, a registered investment adviser, and past performance does not guarantee future results. Securities investments are subject to risk. Additionally, Bright Advisers has a no minimum account size policy, making their services accessible to families at various financial stages.
Conclusion
Imagine the peace of mind that comes from understanding how cliff vesting can shape your family’s financial future. Cliff vesting is about how you earn your employer’s contributions to retirement plans, and it can really impact your family’s budgeting and future plans. When you understand cliff vesting, you can make choices that safeguard your family’s financial health and help you keep those important benefits, especially during job changes.
Throughout this journey, we’ve explored the ins and outs of cliff vesting, shedding light on its timelines and implications. Families can find comfort in the encouragement of long-term employment and the potential for lump-sum payouts, which can be a lifeline during significant life events. But it’s important to recognize that there are risks, like losing benefits or waiting too long to access them, which can be tough for families to handle. Strategies such as:
- Evaluating job offers
- Planning for major life events
- Working with fiduciary advisors like Bright Advisers
can empower families to manage these complexities effectively.
Ultimately, understanding and strategically managing cliff vesting is crucial for families striving for financial stability and growth. By taking proactive steps and seeking guidance from trusted advisors, you can enhance your financial planning, ensuring you’re well-prepared for both current needs and future aspirations. By embracing these practices, you’re not just securing your finances; you’re building a legacy of love and support for your family’s future.
Frequently Asked Questions
What is cliff vesting?
Cliff vesting is a term that describes how employees earn their employer’s contributions to retirement plans after a set period, known as the ‘cliff.’ Employees do not receive any contributions until they reach this specified time frame.
Why is understanding cliff vesting important for families?
Understanding cliff vesting is crucial for families as it can significantly impact their budgeting and financial planning, especially during job transitions. Without this knowledge, families may make decisions that jeopardize their financial security and their children’s future.
What are the potential risks associated with cliff vesting?
Many employees, particularly those from lower-income backgrounds, struggle to understand their allocation schedules. In 2022, over 1.8 million participants forfeited compensation because they didn’t meet eligibility criteria, which highlights the potential financial losses that can occur during job changes.
How can families benefit from working with financial advisors regarding cliff vesting?
Families can benefit from working with financial advisors, like Bright Advisers, by receiving guidance on managing their contribution schedules, ensuring they do not forfeit employer contributions, and creating comprehensive financial plans that include tax optimization and tailored strategies.
Can you provide examples of families who successfully navigated job transitions with the help of financial advisors?
Yes, families like Jay & Emma and Emily & Mark sought advice from Bright Advisers. They managed their job transitions effectively by understanding their contribution schedules and developing financial plans that secured their economic stability and prepared for their children’s educational needs.
What is the mission of Bright Advisers?
Bright Advisers’ mission is to help families make wise wealth decisions and preserve wealth across generations, ensuring their financial well-being and security for the future.
List of Sources
- Define Cliff Vesting and Its Importance for Families
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- Wealth Accumulation Quotes (50 quotes) (https://goodreads.com/quotes/tag/wealth-accumulation)
- Famous Quotes on Financial Stability and Well-Being – Center for the Advancement of Well-Being (https://wellbeing.gmu.edu/famous-quotes-on-financial-stability-and-well-being)
- The Effects of 401(k) Vesting Schedules—in Numbers | Yale Law Journal (https://yalelawjournal.org/essay/the-effects-of-401k-vesting-schedulesin-numbers)
- Explain How Cliff Vesting Works: Mechanics and Timelines
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- Vesting Explained: Schedules, Cliffs, Acceleration, and Types (https://carta.com/learn/equity/stock-options/vesting)
- The Effects of 401(k) Vesting Schedules—in Numbers | Yale Law Journal (https://yalelawjournal.org/essay/the-effects-of-401k-vesting-schedulesin-numbers)
- Cliff vesting schedule | Retirement Glossary Term | Human Interest (https://humaninterest.com/learn/retirement-glossary/cliff-vesting-schedule)
- Stock Option Vesting Schedules Explained: Types, Examples, and Key Strategies — Secfi (https://secfi.com/learn/stock-option-vesting-schedule)
- Evaluate the Benefits and Drawbacks of Cliff Vesting for Family Wealth
- Cliff Vesting – Schedules, how it works, examples (https://jpmorganworkplacesolutions.com/insights/cliff-vesting)
- Explaining Cliff Vesting: How it Works and Examples – Willow Wealth (https://willowwealth.com/blog/article/explaining-cliff-vesting)
- Cliff Vesting | Definition, Pros, Cons, & Employer Considerations (https://financestrategists.com/financial-advisor/long-term-incentive-plans/cliff-vesting)
- Cliff vesting schedule | Retirement Glossary Term | Human Interest (https://humaninterest.com/learn/retirement-glossary/cliff-vesting-schedule)
- Rho | What Is Cliff Vesting? A Complete Guide for Startups and Employers (https://rho.co/blog/cliff-vesting)
- Implement Strategies for Managing Cliff Vesting in Financial Planning
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- 7 Quotes from Warren Buffett on How Retirees Should “Invest” in What Matters the Most (https://keenwealthadvisors.com/insights/7-quotes-from-warren-buffett-on-how-retirees-should-invest-in-what-matters-the-most)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading