

Key Highlights:
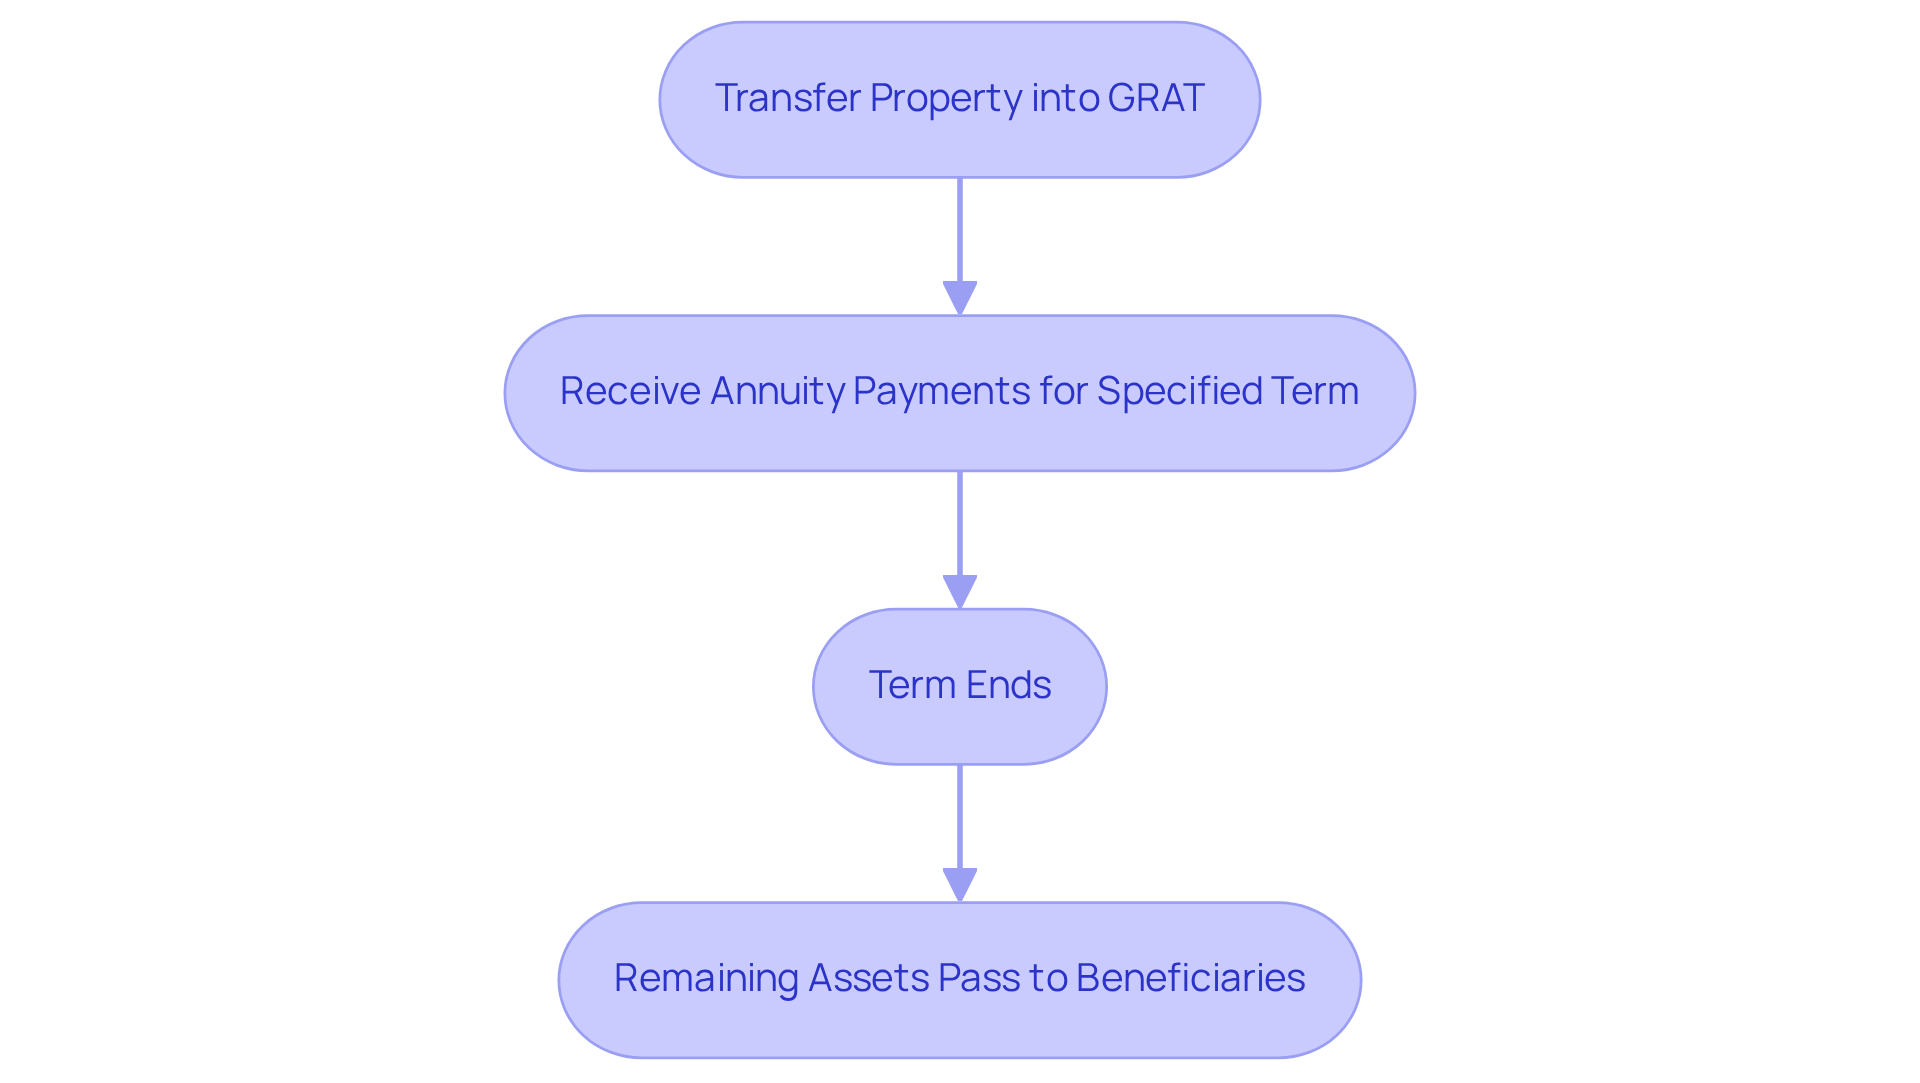
- A Grantor Retained Annuity Trust (GRAT) is an irrevocable trust allowing the grantor to transfer property and receive annuity payments for a specified term.
- After the term, remaining assets pass to beneficiaries without incurring significant tax liabilities, making GRATs effective for wealth transfer.
- GRATs help secure financial futures for families, especially young parents, by minimising gift and estate taxes.
- The trust structure freezes asset values for tax purposes, allowing any appreciation beyond IRS rates to be transferred tax-free to heirs.
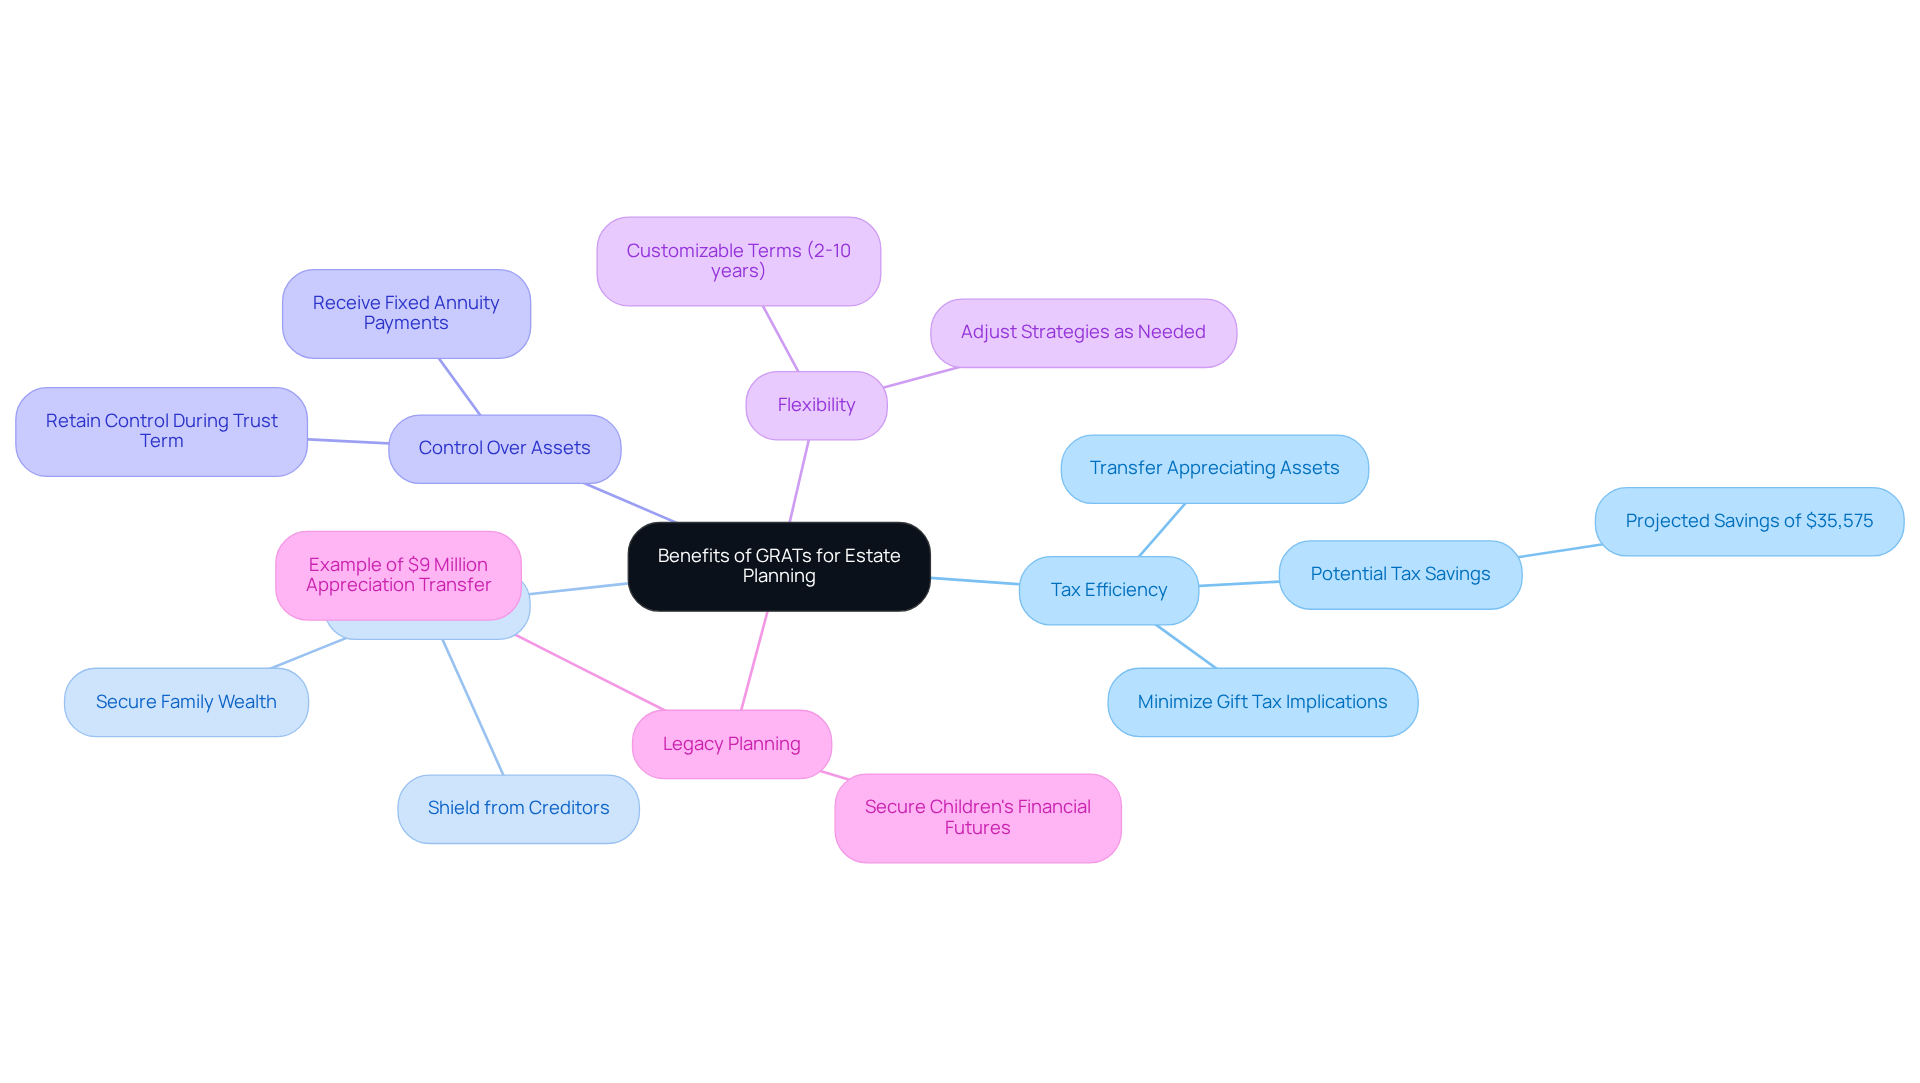
- Benefits of GRATs include tax efficiency, asset protection from creditors, control over assets during the trust term, flexibility in terms, and enhanced legacy planning.
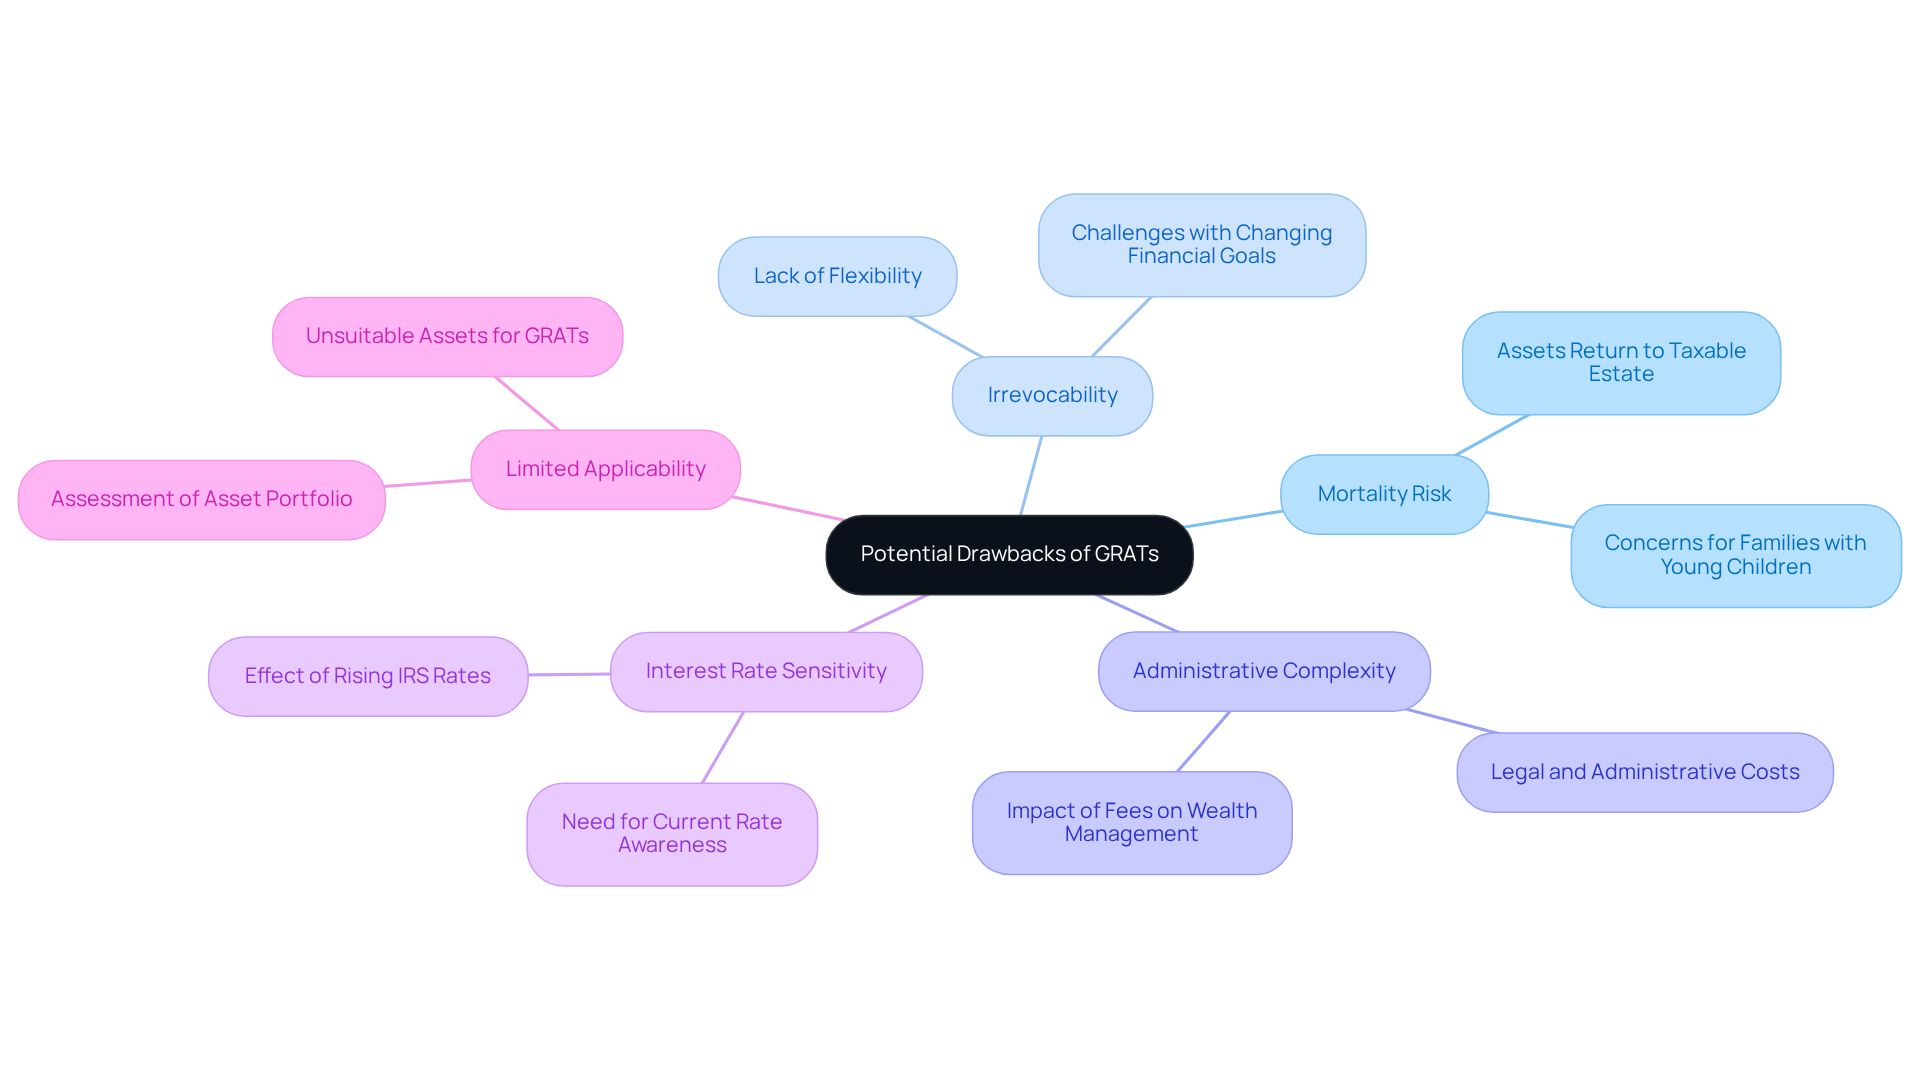
- Potential drawbacks include mortality risk, irrevocability, administrative complexity, interest rate sensitivity, and limited applicability to certain assets.
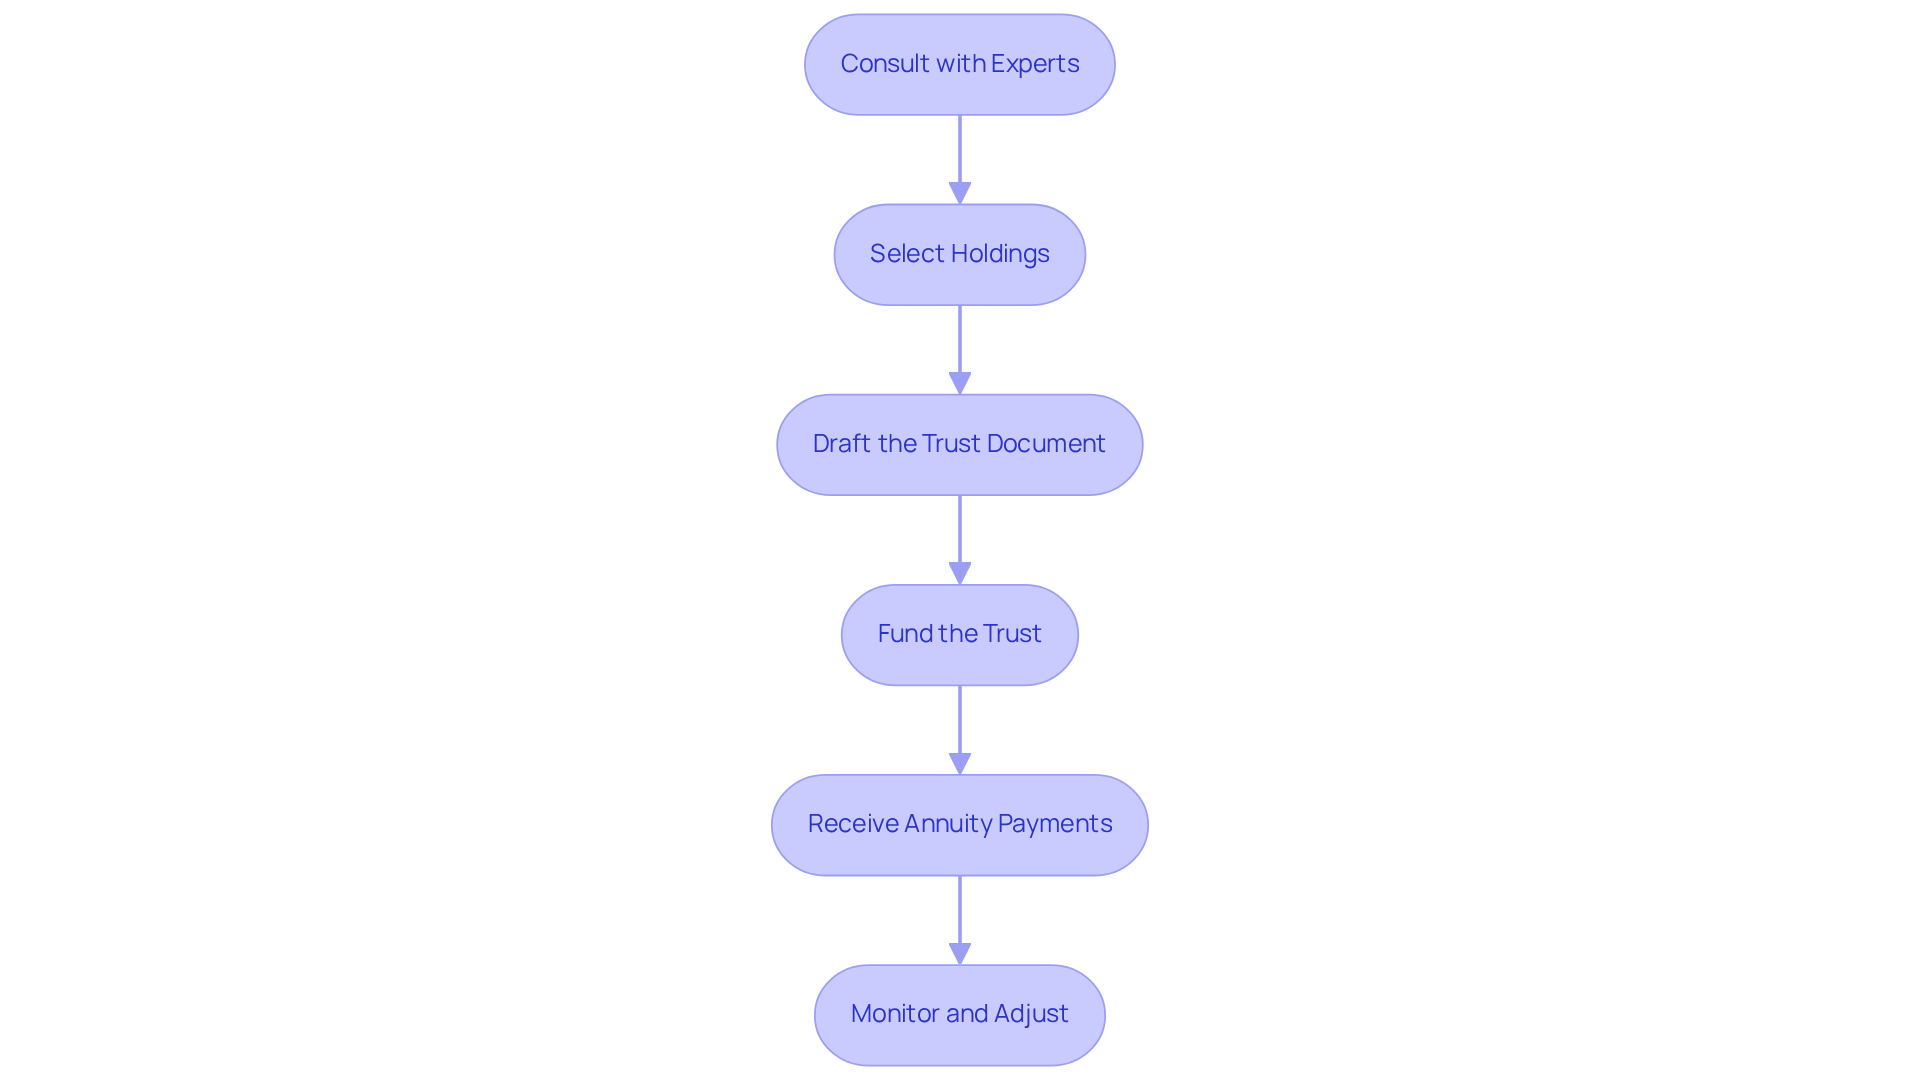
- Creating a GRAT involves consulting experts, selecting appropriate assets, drafting trust documents, funding the trust, receiving annuity payments, and ongoing monitoring.
Introduction
Imagine a future where financial security isn’t just a dream but a tangible reality for young families. Picture this: a world where you can provide for your children’s future without the heavy burden of taxes weighing you down. Grantor Retained Annuity Trusts (GRATs) offer a strategic approach to estate planning, allowing parents like you to transfer wealth to your children while minimizing tax burdens.
But we understand that navigating the complexities of GRATs can raise important questions. You might wonder:
- Are they truly suitable for your family?
- What are the key benefits?
- What potential pitfalls should you be aware of?
Let’s explore these together. By understanding the advantages of GRATs, you can secure your family’s financial legacy with confidence. We’re here for you, ready to help you navigate this journey toward a brighter future for your loved ones.
Define Grantor Retained Annuity Trusts (GRATs)
Imagine a future where your children are financially secure, no matter what life throws your way. A GRAT trust can help turn that dream into a reality. This specialized estate planning tool allows you to transfer wealth to your heirs while minimizing gift and estate taxes.
So, what exactly is a GRAT? It’s an irrevocable trust where you, the grantor, transfer property into the trust and keep the right to receive annuity payments for a specified term. After this term ends, any remaining assets in the trust pass on to your beneficiaries-usually your loved ones-without incurring hefty tax liabilities.
This approach is especially beneficial for young parents like you, who want to secure your children’s financial future while managing your own estate tax exposure. At Bright Advisers, we truly understand the importance of intentional wealth management. We’re here for you, offering and innovative strategies, including GRAT trusts, to empower families in achieving financial security and freedom.
Together, we can navigate this journey, ensuring that your family’s values and goals are at the forefront of your financial decisions. Let’s take the first step toward a brighter future for your children.
Explain How GRATs Work in Practice
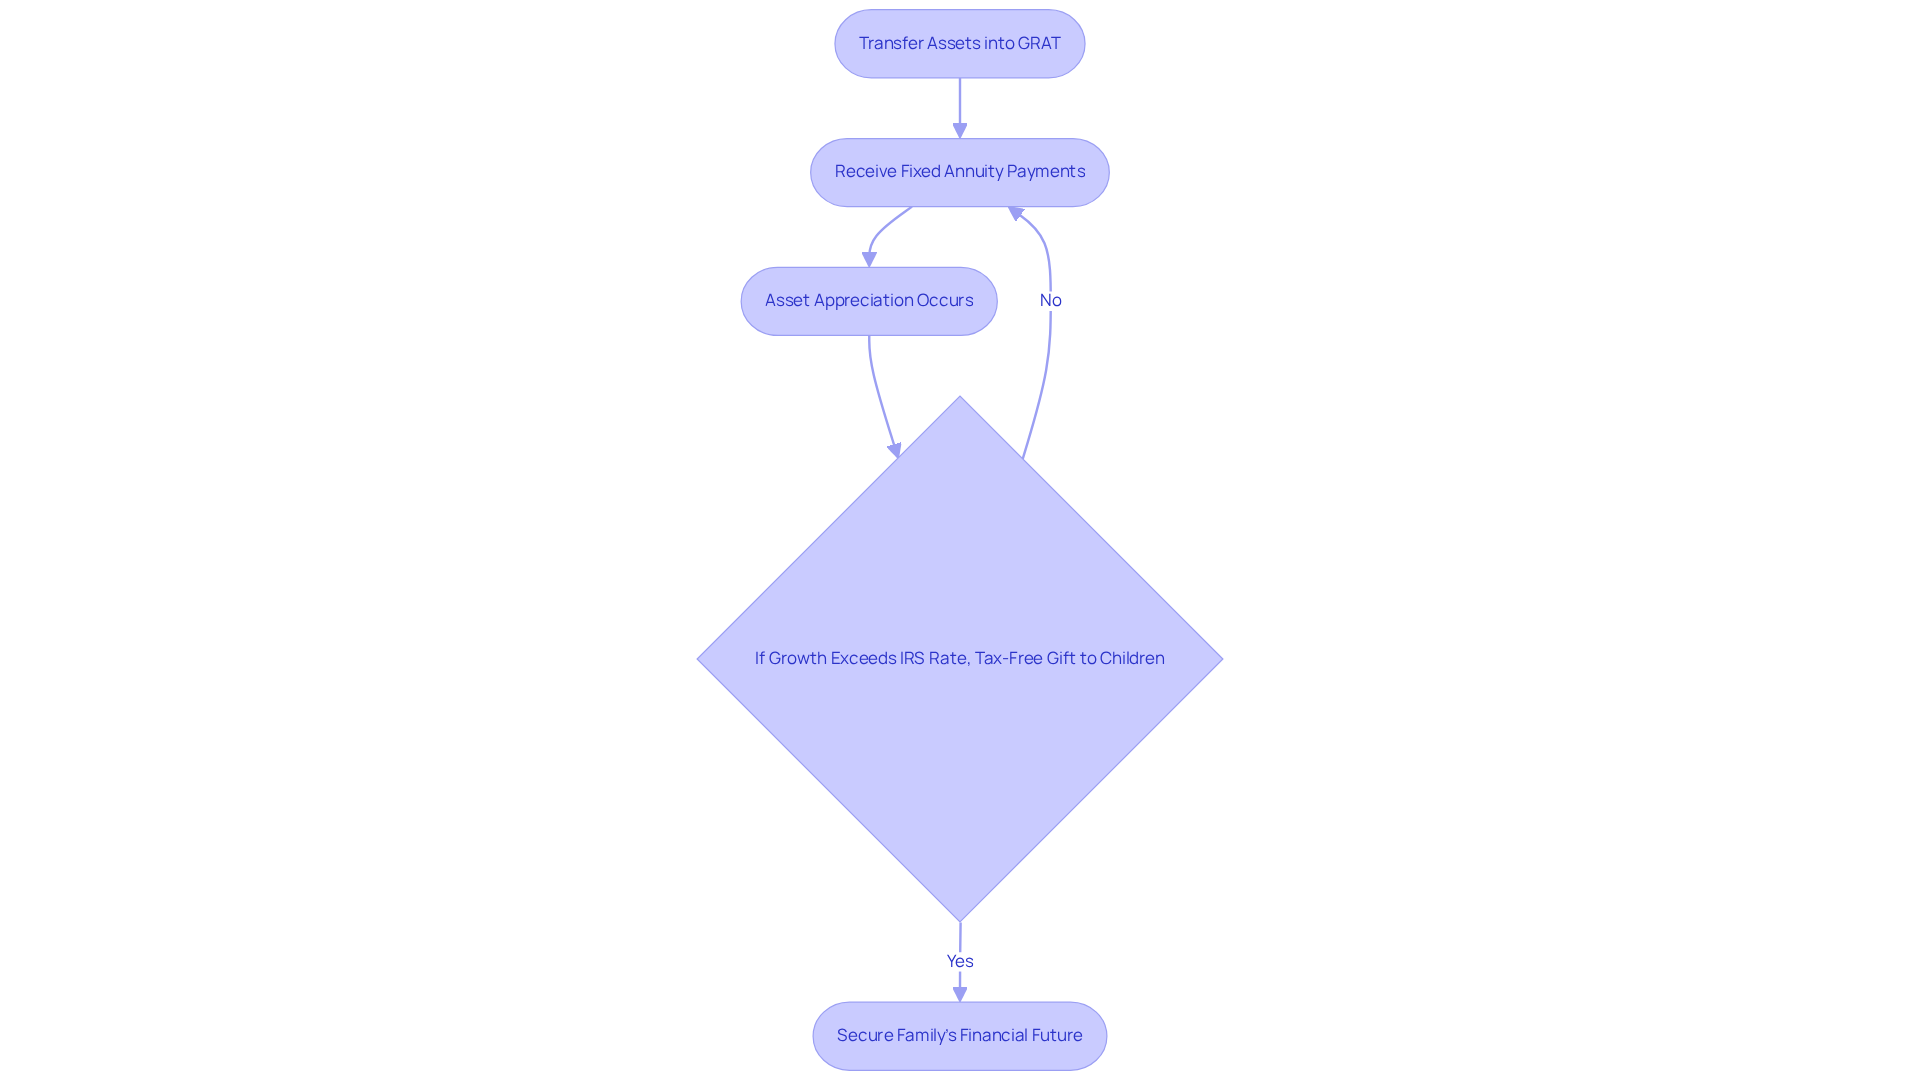
Imagine a way to secure your family’s future while easing financial worries. A Grantor Retained Annuity Trust (GRAT) allows you to transfer appreciating properties into a trust, all while receiving fixed annuity payments over a set term-usually between two to five years. This unique structure effectively ‘freezes’ the property’s value for tax purposes at the time of transfer, providing peace of mind.
Now, picture this: if the assets grow beyond the IRS’s established interest rate during the trust’s duration, that extra growth can be gifted to your children without incurring gift taxes. For example, if you transfer $1 million into a GRAT and the assets appreciate to $1.5 million, that $500,000 increase can be passed on to your kids tax-free, as long as you outlive the trust term.
Families like Jay and Emma, who are focused on reducing financial stress while securing their children’s future, can find immense value in GRATs. Over the past decade, households utilizing GRATs have reaped significant benefits, especially during periods of low-interest rates and market fluctuations. The fixed annuity payments provide economic stability, allowing for a tax-efficient transfer of wealth.
Financial consultants, such as those at Bright Advisers, emphasize that the mechanics of GRATs can be particularly beneficial for families looking to enhance their monetary legacy and minimize tax burdens. Together, we can navigate this journey toward a more secure future for your loved ones.
Highlight the Benefits of Using GRATs for Estate Planning
Use english for answers
Please return corrected/formatted text for:
Secure Your Family’s Future with a GRAT
As young parents, you want to ensure a bright financial future for your children. A grats trust can be a powerful tool in your estate planning arsenal, offering several compelling advantages that can help you achieve your family’s financial goals while minimizing tax burdens.
Tax Efficiency
Imagine being able to transfer appreciating assets to your heirs with little to no gift tax implications. The grats trust makes this possible, allowing you to pass on more of your wealth without the worry of significant tax liabilities. In fact, many of America’s wealthiest families have turned to grats trust for low-cost wealth transfer, showcasing their effectiveness in securing financial legacies.
Asset Protection
It’s essential to protect the wealth you’ve worked hard to build. Assets placed within a grats trust are generally shielded from creditors, ensuring that the resources intended for your children remain secure. This protection is vital for families striving to maintain their heritage and support future generations without the fear of losing what matters most.
Control Over Assets
During the trust term, you retain control over the assets, receiving fixed annuity payments that can help meet your financial needs. This arrangement allows you to maintain a sense of economic stability while preparing for your family’s future.
Flexibility
Life is full of changes, and your estate planning should reflect that. GRATs can be customized to fit your unique financial situation, with terms typically ranging from 2 to 10 years. This flexibility empowers you to adjust your strategies as circumstances evolve, whether due to shifts in asset values or family dynamics.
Legacy Planning
By effectively transferring wealth to the next generation, GRATs play a crucial role in legacy planning. They help you secure your children’s financial futures in a way that aligns with your family’s values. For instance, if you were to transfer startup shares valued at $1 million into a GRAT, you could potentially allow $9 million of appreciation to pass to your heirs tax-free if the company’s value grows significantly.
As we approach 2026, the benefits of GRATs become even more relevant for young families navigating the complexities of budgeting while prioritizing their children’s futures. By incorporating grats trust into your estate planning, you can achieve both tax efficiency and asset protection, ultimately fostering a lasting legacy for your loved ones.
We’re here for you
Together, we can navigate this journey and ensure that your family’s financial future is secure.
Discuss the Potential Drawbacks of GRATs
While grats trust can offer some advantages, it’s essential to also consider the potential drawbacks, especially for families navigating and associated fees.
- Mortality Risk: Imagine if the grantor passes away before the trust term ends. In that case, the resources return to the taxable estate, which can negate the intended tax benefits. This risk can be particularly concerning for families with young children, as it may undermine their estate planning efforts. For instance, John and Mary found that keeping assets in their estate might lead to greater after-tax wealth than using a GRAT, highlighting the possible downsides of this approach.
- Irrevocability: Once a GRAT is set up, it can’t be modified or revoked. This lack of flexibility can be challenging for families whose financial situations or goals may change over time.
- Administrative Complexity: Setting up and managing a GRAT can come with significant legal and administrative costs, typically ranging from 0.5% to 2% of the trust’s assets each year. These expenses can discourage families from using this strategy, especially when they’re already juggling the complexities of raising children. Understanding how even minimal fees can impact overall wealth management is crucial, as many families prefer strategies that minimize costs while maximizing benefits.
- Interest Rate Sensitivity: GRATs are influenced by IRS interest rates; if these rates rise, the effectiveness of the GRAT can diminish, making it less beneficial for wealth transfer. Families need to stay informed about current rates to evaluate the viability of this strategy.
- Limited Applicability: Not all assets are suitable for GRATs, particularly those that don’t show significant appreciation. Families should carefully assess their asset portfolio to identify which assets are best suited for this type of trust.
Understanding these potential disadvantages is vital for families considering a grats trust as part of their estate planning. As Rajiv Rebello wisely points out, “Protecting the client from an estate tax liability only to expose them to a larger tax-drag and income tax liability can pose more harm than good.”
We’re here for you. Consulting with investment advisors, like those at Bright Advisers, can provide valuable insights into these risks and help families make informed choices that align with their long-term financial goals, all while considering the impact of minimal fund fees. Together, we can navigate this journey.
Guide on Creating a Grantor Retained Annuity Trust
Creating a grats trust can be a wonderful way for families to secure their financial future. Here’s how you can navigate this journey together:
- Consult with Experts: Start by reaching out to an estate planning attorney and a financial advisor. About 25% of families looking to set up a GRAT find that consulting professionals helps ensure their strategy aligns with their financial goals. It’s a step that can bring peace of mind.
- Select Holdings: Think about choosing assets with high growth potential to transfer into the trust. This choice is crucial, as the value of these resources can lead to for your loved ones.
- Draft the Trust Document: Work closely with your attorney to create the gift annuity document. This should clearly outline the terms, including the annuity payment amount and how long the trust will last. It’s all about clarity and understanding.
- Fund the Trust: Next, transfer the selected assets into the GRAT, making sure to comply with all legal requirements. This step is essential for establishing the trust effectively.
- Receive Annuity Payments: As the grantor, you’ll receive annuity payments throughout the specified term. These payments are taxable as ordinary income, but they can be a helpful resource for your personal financial needs.
- Monitor and Adjust: Regularly check in on the GRAT’s performance with your advisors. This ongoing assessment ensures that the trust continues to meet your estate planning objectives and adapts to any changes in your financial situation.
By following these steps, families can utilize grats trust as a strategic tool for efficient wealth transfer while minimizing tax implications. Remember, we’re here for you, and together, we can navigate this journey toward a secure financial future.
Conclusion
Imagine securing your children’s financial future while navigating the complexities of estate taxes. A Grantor Retained Annuity Trust (GRAT) can be a powerful tool for young parents like you, offering a strategic pathway to protect your family’s wealth. By transferring appreciating assets into a trust, you can enjoy tax efficiency and safeguard your legacy for generations to come.
In this guide, we’ve explored the ins and outs of GRATs, from how they operate to their many advantages, such as flexibility and tax benefits. We’ve also touched on potential drawbacks, like mortality risk and administrative complexities. Understanding these elements is essential for families who want to make informed decisions that align with their long-term financial goals.
As the world of estate planning evolves, the significance of tools like GRATs becomes even clearer. We encourage you to consult with financial advisors who can help you navigate these complexities, ensuring your estate planning strategies are tailored to your unique circumstances. Together, we can foster lasting legacies and secure a brighter financial future for your children.
Frequently Asked Questions
What is a Grantor Retained Annuity Trust (GRAT)?
A GRAT is an irrevocable trust where the grantor transfers property into the trust while retaining the right to receive fixed annuity payments for a specified term. After this term, the remaining assets in the trust pass to beneficiaries without incurring significant tax liabilities.
How does a GRAT help in estate planning?
A GRAT allows individuals to transfer wealth to their heirs while minimizing gift and estate taxes. It is particularly beneficial for young parents who want to secure their children’s financial future while managing their own estate tax exposure.
What is the typical duration for receiving annuity payments from a GRAT?
The typical duration for receiving annuity payments from a GRAT is usually between two to five years.
How does a GRAT ‘freeze’ the property’s value for tax purposes?
When property is transferred into a GRAT, its value is ‘frozen’ for tax purposes at the time of transfer. This means that any appreciation in value beyond the IRS’s established interest rate during the trust’s duration can be passed on to beneficiaries without incurring gift taxes.
Can you provide an example of how a GRAT works in practice?
For instance, if you transfer $1 million into a GRAT and the assets appreciate to $1.5 million during the trust’s term, the $500,000 increase can be passed on to your children tax-free, provided you outlive the trust term.
What benefits have families seen from using GRATs?
Families using GRATs have experienced significant benefits, especially during low-interest rate periods and market fluctuations. The fixed annuity payments provide economic stability while facilitating a tax-efficient transfer of wealth.
Who can assist with setting up a GRAT?
Financial consultants, such as those at Bright Advisers, can provide guidance on establishing GRATs and navigating the complexities of estate planning to enhance monetary legacies and minimize tax burdens.
List of Sources
- Define Grantor Retained Annuity Trusts (GRATs)
- Grantor Retained Annuity Trust (GRAT): Definition and Example (https://investopedia.com/terms/g/grat.asp)
- The Basics of Grantor Retained Annuity Trusts | Carr, Riggs & Ingram (https://criadv.com/insight/grantor-retained-annuity-trusts)
- How Does a Grantor Retained Annuity Trust (GRAT) Really Work? (https://johnstevenson.com/grantor-retained-annuity-trust)
- Great time for a GRAT – Journal of Accountancy (https://journalofaccountancy.com/issues/2019/oct/wealth-transfer-grantor-retained-annuity-trusts)
- Understanding Grantor Retained Annuity Trusts – Sterlington PLLC (https://sterlingtonlaw.com/understanding-grantor-retained-annuity-trusts)
- Explain How GRATs Work in Practice
- Take Advantage of Historically Low IRS Interest Rates Using GRATs and Other Wealth-Transfer Tools | Loeb & Loeb LLP (https://loeb.com/en/insights/publications/2020/04/historically-low-afrs-using-grats-and-other-wealth-transfer-tools)
- How Does a Grantor Retained Annuity Trust (GRAT) Really Work? (https://johnstevenson.com/grantor-retained-annuity-trust)
- GRATs: Understanding a Popular Estate Planning Strategy (https://marinerwealthadvisors.com/insights/grats-understanding-a-popular-estate-planning-strategy)
- GRATS: Passing Along Assets Free of Estate and Gift Taxes (https://hbkswealth.com/insights/grats-passing-along-assets-free-of-estate-and-gift-taxes)
- Highlight the Benefits of Using GRATs for Estate Planning
- Startup Success Can Create Generational Wealth — It Also Brings Complex Tax Challenges (https://citizensbank.com/private-banking/insights/grantor-retained-annuity-trusts.aspx)
- What is a GRAT? And What Are The Benefits For Estate Planning? (https://wealthenhancement.com/blog/what-is-a-grat-and-what-are-its-benefits-for-estate-planning)
- Estate Planning with Grantor Retained Annuity Trusts (GRATs) (https://nasdaq.com/articles/estate-planning-with-grantor-retained-annuity-trusts-grats)
- Tax & Estate Strategies: What Is a GRAT and Do You Need One? (https://centraltrust.net/tax-and-estate-strategies-what-is-a-grat-and-do-you-need-one)
- Understanding Grantor Retained Annuity Trust (GRAT) (https://westernsouthern.com/retirement/grantor-retained-annuity-trust)
- Discuss the Potential Drawbacks of GRATs
- GRATs: Understanding a Popular Estate Planning Strategy (https://marinerwealthadvisors.com/insights/grats-understanding-a-popular-estate-planning-strategy)
- Understanding Grantor Retained Annuity Trust (GRAT) (https://westernsouthern.com/retirement/grantor-retained-annuity-trust)
- Issue 42 – More Harm Than Good – NAEPC Journal of Estate & Tax Planning (https://naepcjournal.org/issue/42/more-harm-than-good)
- Guide on Creating a Grantor Retained Annuity Trust
- GRATs: Understanding a Popular Estate Planning Strategy (https://marinerwealthadvisors.com/insights/grats-understanding-a-popular-estate-planning-strategy)
- Grantor Retained Annuity Trust Essentials: A Guide to Tactical Estate Planning (https://avidesq.com/blog/grantor-retained-annuity-trust)
- Keys to a successful GRAT – Sessions, Fishman & Nathan, L.L.C. (https://sessionsfishman.com/keys-to-a-successful-grat)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading