

Overview
K-1 distributions can feel overwhelming, but understanding them is essential for your family’s financial health. These distributions are taxed indirectly, meaning that the earnings reported on your K-1 must be included in your taxable income. This inclusion can significantly impact your overall tax liability, which is something every parent should consider.
It’s important to grasp the classification of these earnings—like ordinary income versus capital gains. Why does this matter? Because it dictates the tax rates that apply to you, leading to different financial outcomes as you navigate your tax situation. Imagine if knowing this could help you save money for your child’s future.
We’re here for you, guiding you through the complexities of financial planning. Understanding these concepts can empower you to make informed decisions that align with your family’s values and goals. Together, we can navigate this journey and ensure that your family’s financial future is secure.
Key Highlights:
- Schedule K-1 is a tax document that reports earnings, deductions, and credits for partners in businesses or beneficiaries of trusts.
- It is crucial for tax reporting, influencing individual tax returns and overall financial planning.
- Approximately 90% of partnerships and S corporations use K-1 forms, highlighting their significance in tax management.
- K-1 forms consist of three parts: entity details, partner/beneficiary earnings, and types of earnings, all essential for accurate tax documentation.
- K-1 distributions are not directly taxed, but the reported earnings must be included in taxable income, impacting tax liabilities.
- Understanding the classification of earnings (ordinary income vs. capital gains) is essential for tax rate implications.
- Timely receipt of K-1 forms is crucial for avoiding penalties, with a deadline of March 15 for distribution.
- Families are encouraged to consult tax professionals for personalised advice and to optimise their financial situations.
Introduction
Navigating the complexities of tax documents can feel overwhelming, particularly for young families focused on securing their financial futures. One crucial document in this landscape is the Schedule K-1, which outlines earnings, deductions, and credits from partnerships and S corporations. This article explores how K-1 distributions are taxed, providing families with essential insights that can significantly influence their financial planning and tax responsibilities.
Imagine the challenges that could arise from misinterpreting these distributions. It’s vital for families to understand their implications fully. By doing so, you can optimize your tax situations and prepare for a more stable financial future. Remember, we’re here to support you on this journey, ensuring that you have the knowledge and resources needed to navigate these important decisions together.
Define Schedule K-1 and Its Purpose
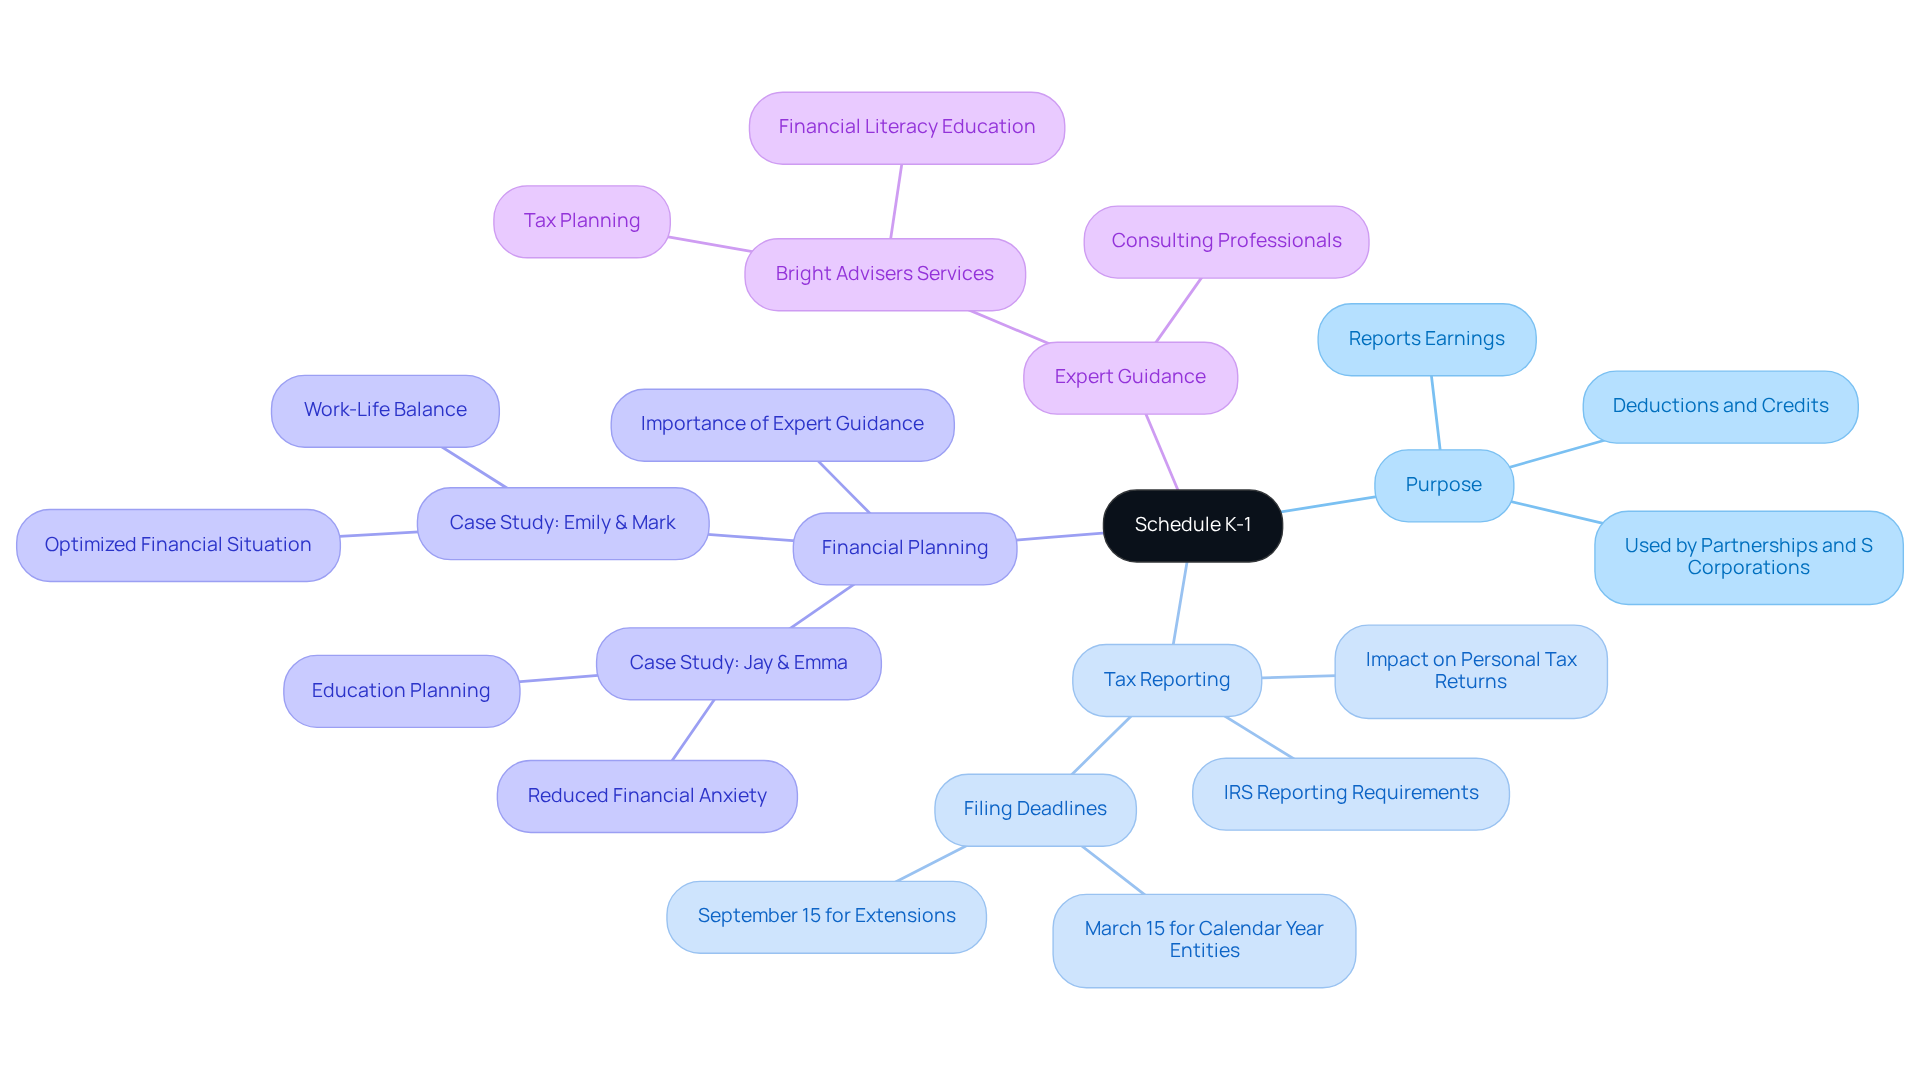
A Schedule K-1 is an essential tax document that reports earnings, deductions, and credits from partnerships, S corporations, estates, or trusts. For individuals involved as partners in a business or as beneficiaries of a trust, this form outlines their share of the entity’s financial activities. It plays a crucial role in tax reporting, informing the IRS about the income that must be included on individual tax returns.
Imagine if you could grasp the implications of a K-1 for your household. Understanding this form is vital for effectively managing your tax obligations and strategically planning for your family’s financial future. Approximately 90% of partnerships and S corporations utilize K-1 forms, underscoring their significance for individuals navigating complex tax situations.
Expert opinions emphasize that understanding the nuances of Schedule K-1 can greatly influence your family’s financial planning. This knowledge ensures you are well-prepared for any tax obligations that may arise. For instance, households like Jay and Emma, who sought guidance to reduce financial anxiety, benefited from understanding their tax situation. This allowed them to allocate resources effectively and plan for their children’s education while securing their retirement.
Similarly, Emily and Mark found that optimizing their financial situation through tax planning provided them the freedom to choose their work-life balance. It’s important to recognize that households like Allison and Brian, who might be unaware of financial opportunities due to insufficient tax planning, can significantly gain from expert support.
Bright Advisers offers tailored services to help families navigate how K-1 distributions are taxed and optimize their financial situations. Together, we can enhance your overall financial well-being, ensuring that you and your loved ones feel secure and supported in your journey.
Identify Key Components of a K-1 Form
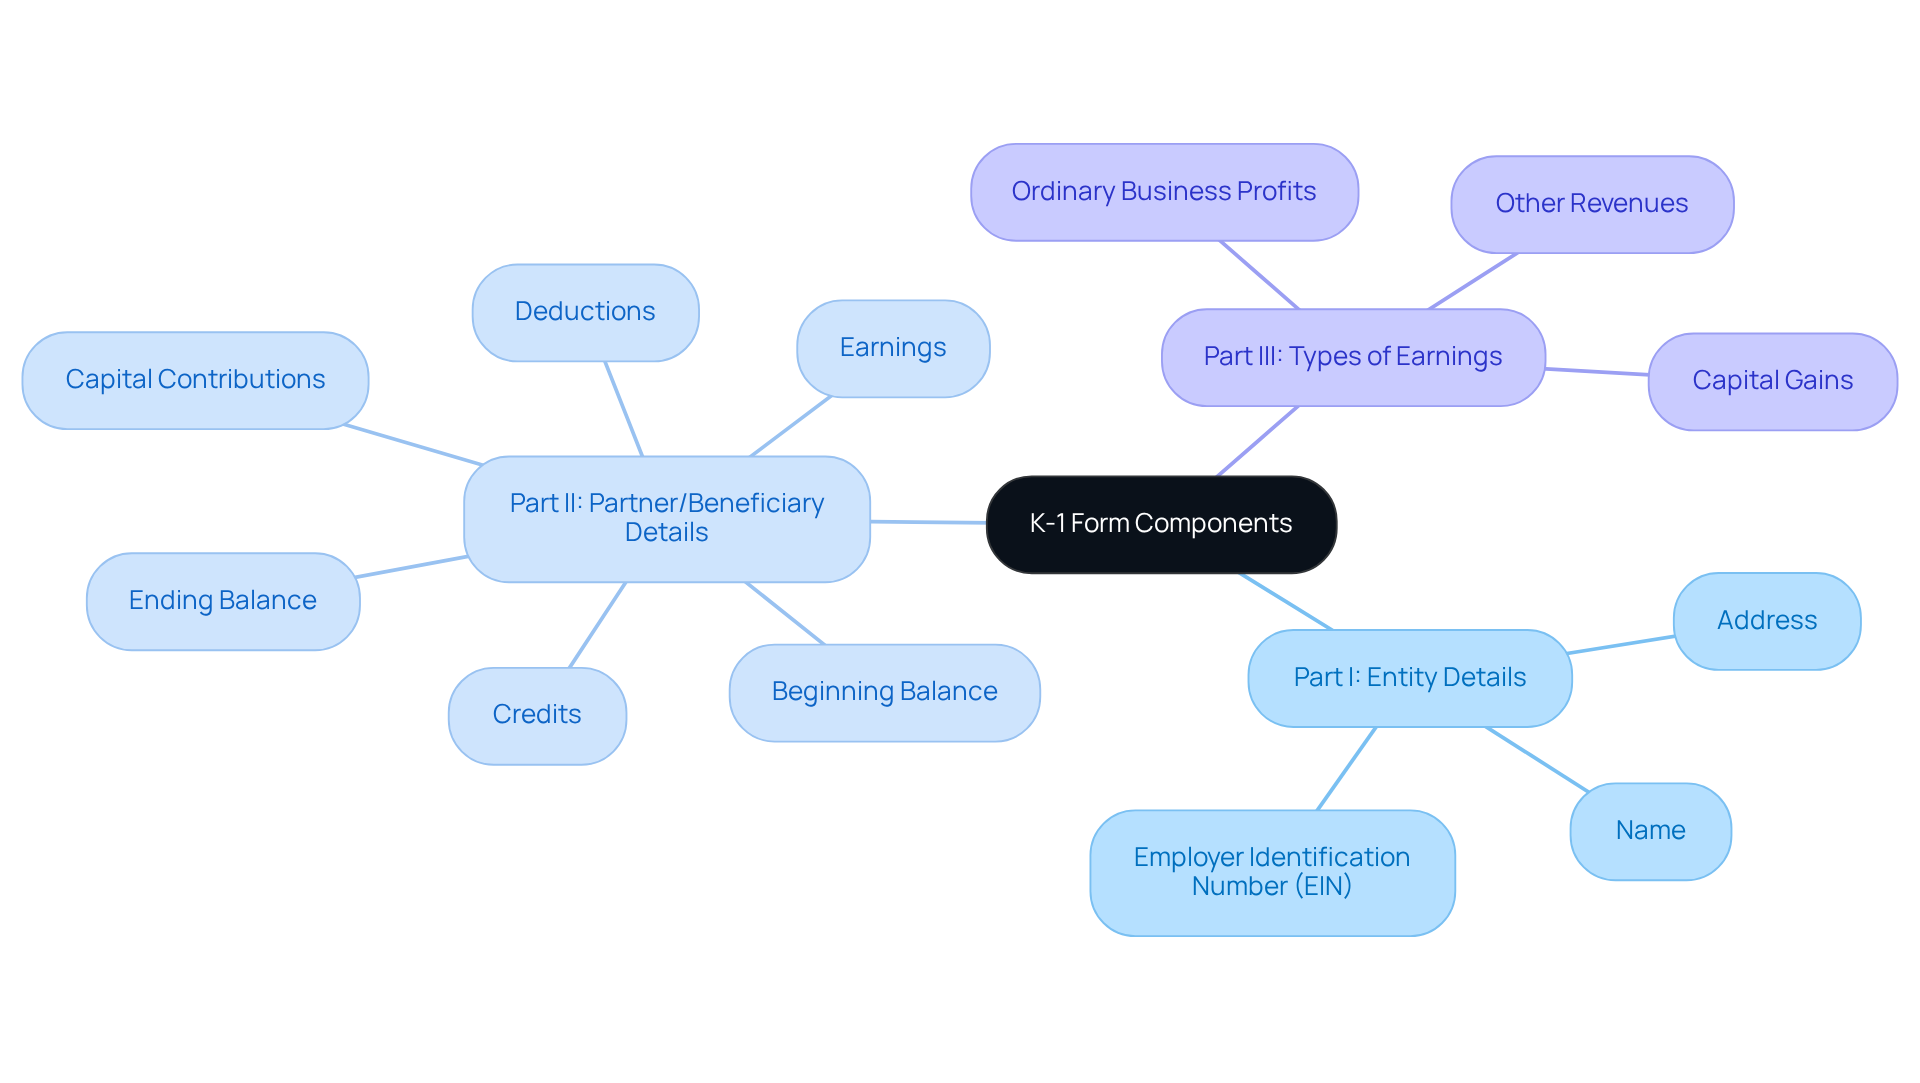
Understanding tax forms can feel overwhelming, especially for young families. A K-1 form, however, consists of three essential parts that help explain how K-1 distributions are taxed for tax reporting.
Part I includes details about the entity, such as its name, address, and Employer Identification Number (EIN). These details are necessary for identifying the source of revenue.
Part II offers insights into the partner or beneficiary, detailing their portion of earnings, deductions, and credits. This part is vital as it reflects each individual’s financial participation in the partnership or trust.
Part III outlines specific types of earnings, including ordinary business profits, capital gains, and other revenues. Grasping these elements is essential for accurately documenting earnings on your tax return, particularly in understanding how K-1 distributions are taxed, as they directly influence your total tax responsibility.
Imagine if you could maximize your tax circumstances and ensure adherence to IRS regulations. Tax experts emphasize that understanding the K-1 form is particularly important for young households like Jay and Emma, Emily and Mark, and Allison and Brian. This knowledge can greatly impact their financial planning and investment strategies. Bright Advisers is here to support families in navigating these complexities, ensuring they make informed decisions that align with their long-term goals.
It’s important to remember that K-1 forms must be received by March 15, and timely reporting is essential to avoid potential penalties. Consulting a tax professional can provide valuable guidance in navigating these complexities, empowering families to achieve financial security and freedom through personalized planning and tax optimization. Together, we can navigate this journey and ensure that your family’s financial future is bright.
Analyze Tax Implications of K-1 Distributions
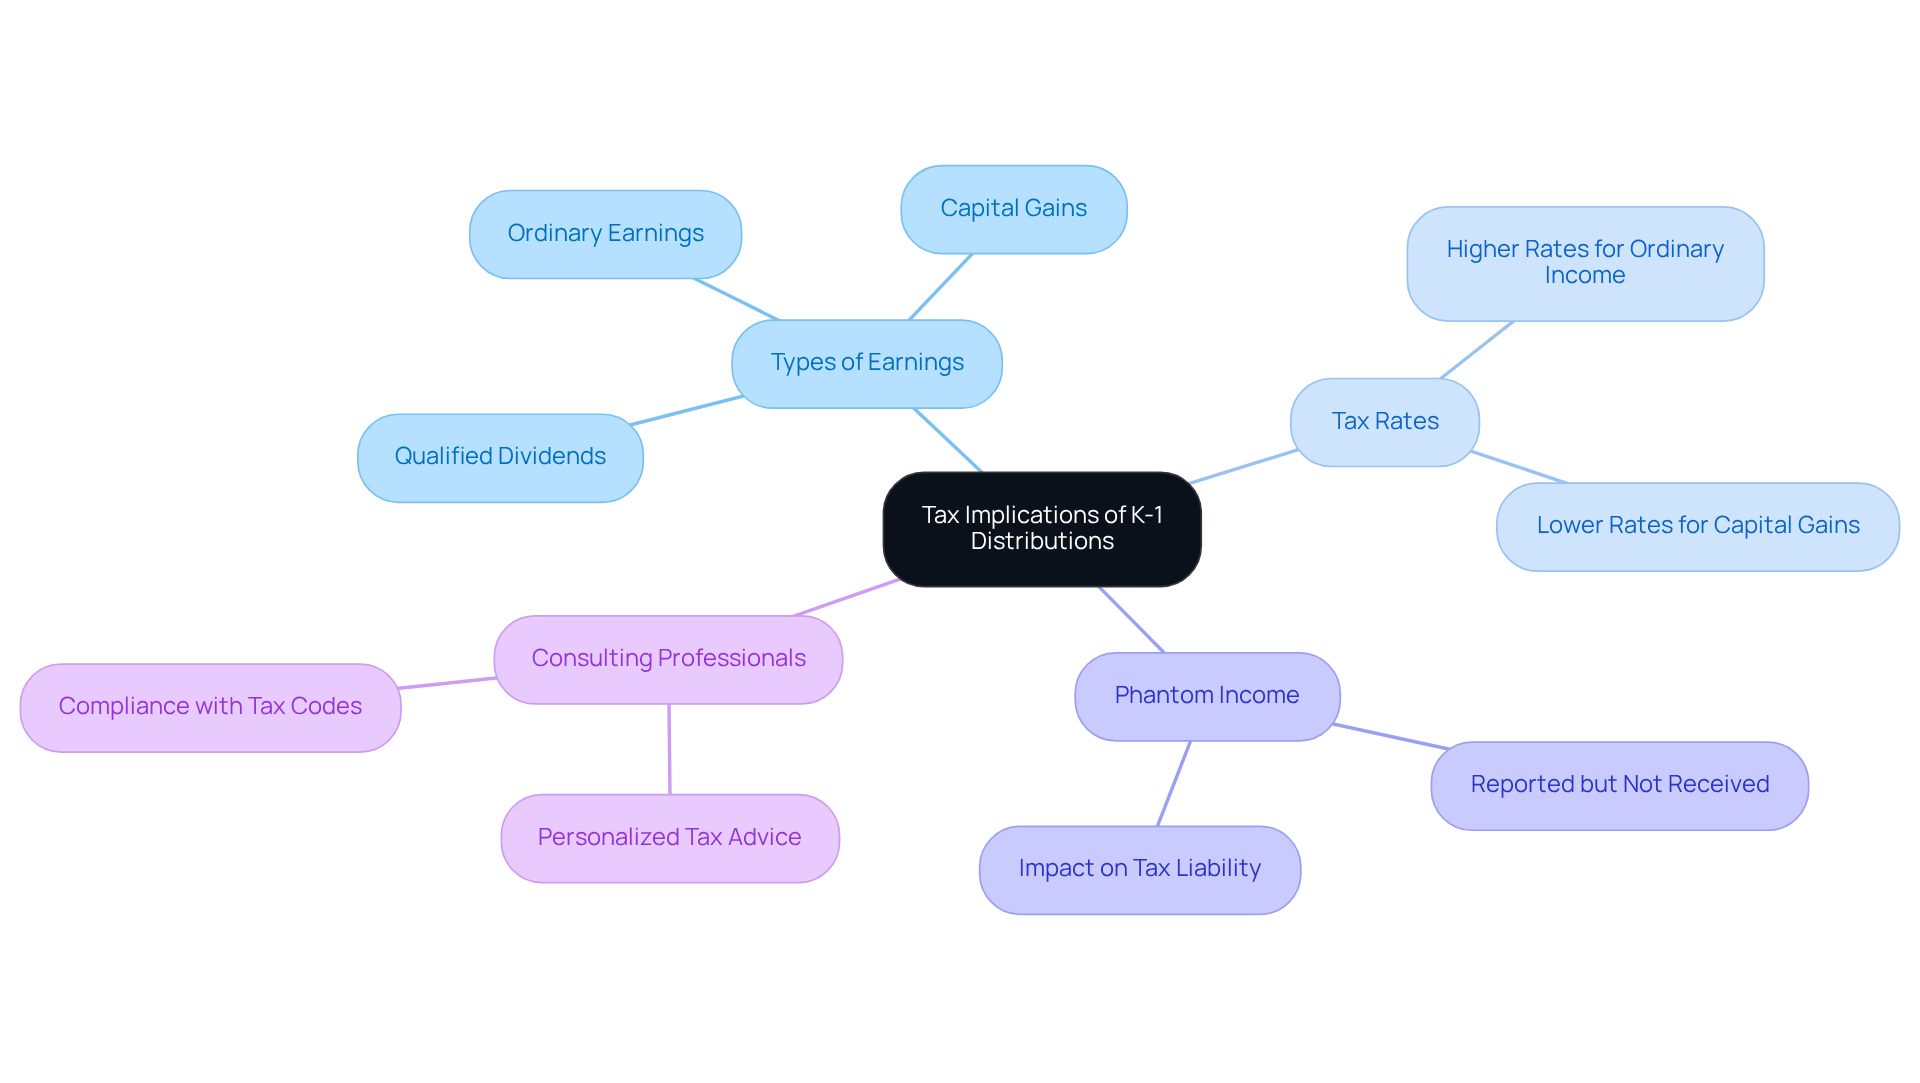
Understanding how K-1 distributions are taxed is essential for managing your family’s tax responsibilities. While the distributions themselves typically aren’t taxed, understanding how K-1 distributions are taxed is crucial, as the earnings reported on the K-1 must be included in your taxable income. For instance, if a partnership reports $10,000 in earnings and distributes $5,000 to a partner, that partner must report the full $10,000 as earnings, regardless of the cash received.
The classification of those earnings—ordinary earnings, capital gains, or qualified dividends—can significantly impact your tax rate. Ordinary earnings often face higher tax rates, while capital gains may enjoy lower rates. As we approach 2025, it’s crucial for households to be aware of how these distinctions could affect their overall tax liabilities.
Imagine a household receiving K-1 income from a partnership with substantial ordinary income. They may find themselves facing a heavier tax burden compared to if their income were primarily capital gains. Moreover, understanding ‘phantom income’—income reported on the K-1 that wasn’t actually received in cash—can add another layer of complexity to your tax situation, particularly in the context of how K-1 distributions are taxed.
To navigate these challenges effectively, we encourage you to consult with tax professionals who can offer personalized advice and help ensure compliance with tax codes. This proactive approach can empower you to optimize your tax situation and make informed financial decisions for your family. In the case of Allison and Brian, their collaboration with Bright Advisers not only illuminated these complexities but also helped them secure their children’s future through education funding and enabled them to retire sooner.
It’s also important to remember that limited partners do not pay self-employment taxes on their share of income, while general partners do. This distinction can significantly influence your household’s tax situation based on your role in the partnership. Typically, Schedule K-1 is provided to recipients by March 15, which is vital for your tax filing schedules and planning procedures. Together, we can navigate this journey and ensure your family’s financial well-being.
Guide to Filing Taxes with K-1 Forms
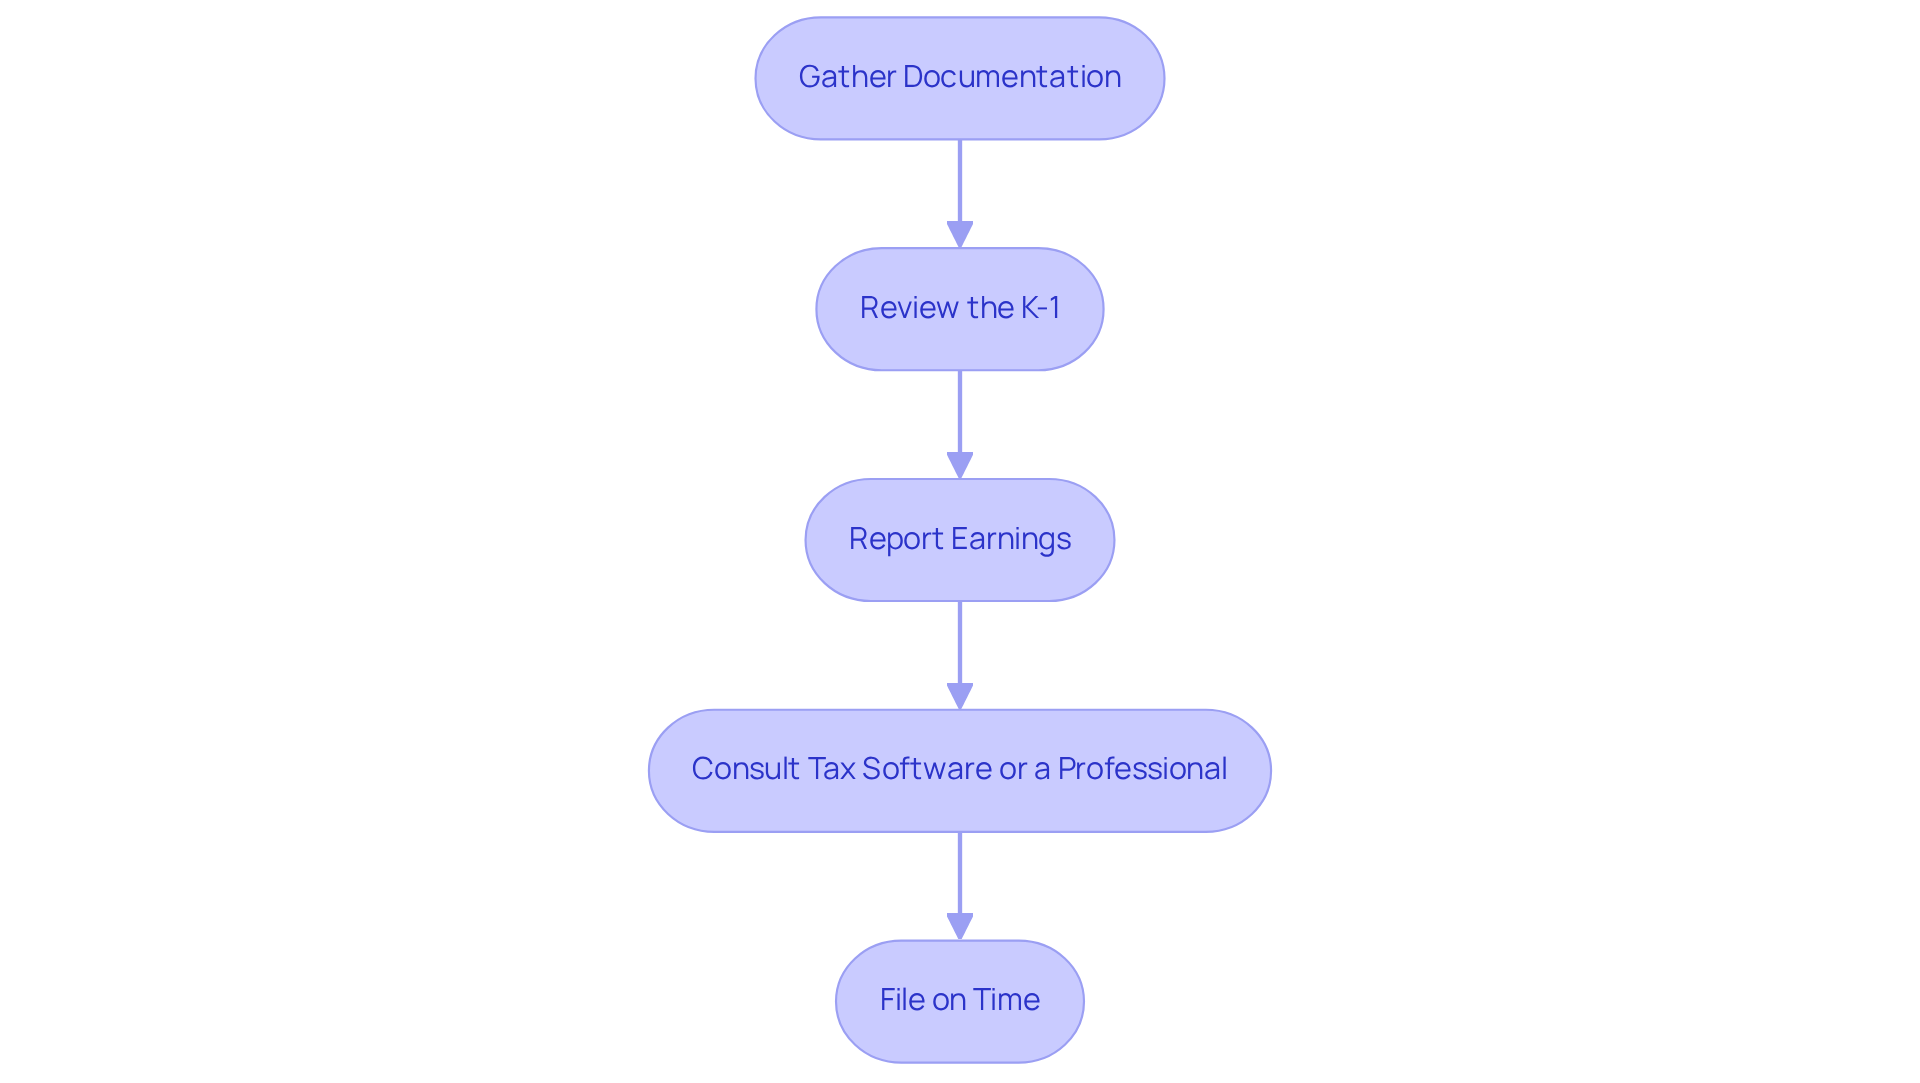
Filing taxes with K-1 forms can feel overwhelming, but understanding how K-1 distributions are taxed will help you tackle it with confidence. Here are the essential steps to help families like yours:
-
Gather Documentation: Start by collecting all K-1 forms you’ve received, along with other important tax documents such as W-2s and 1099s. This is your foundation for a smooth filing process.
-
Review the K-1: Take a moment to confirm that all information is correct, including revenue amounts, deductions, and entity details. Mistakes here can lead to costly penalties. For example, if a K-1 shows a loss, it might be deductible on your tax return, which leads to the question of how are K-1 distributions taxed, but only if you meet certain criteria.
-
Report Earnings: It’s important to include the earnings reported on the K-1 on your Form 1040. Make sure to use the correct lines for different types of income, like ordinary income and capital gains. Remember, K-1 forms are due by March 15, and late arrivals can complicate your filing process.
-
Consult Tax Software or a Professional: Consider utilizing tax software that can handle K-1 forms, or seek assistance from a tax professional. As Connor Emmert, a former NerdWallet writer, suggests, consulting with a tax advisor can help clarify your expectations and maximize deductions.
-
File on Time: Ensure your tax return is submitted by the deadline, typically April 15, to avoid penalties. If your K-1 arrives late, don’t hesitate to file for an extension using Form 4868.
By following these steps, you can navigate the complexities of K-1 tax filing with greater assurance. Many families find that consulting tax advisors helps clarify expectations and maximize deductions, leading to a smoother tax filing experience. Remember, reviewing each line item on the K-1 is crucial to avoid errors that could result in penalties, particularly regarding how K-1 distributions are taxed, as emphasized by Aprio’s Tax advisors. Together, we can navigate this journey and ensure your family’s financial well-being.
Conclusion
Understanding the taxation of K-1 distributions is essential for young families striving to navigate their financial landscape with confidence. It’s crucial to grasp how these distributions influence tax obligations and overall financial planning. By becoming familiar with the nuances of Schedule K-1, families can prepare for their tax responsibilities and make informed decisions that positively impact their future.
Consider the structure of the K-1 form, which outlines key components detailing both the entity’s and the individual partner’s financial involvement. The classification of earnings—ordinary income versus capital gains—can significantly affect tax rates and overall liability. It’s important to recognize the necessity of timely reporting and the potential benefits of consulting tax professionals to optimize financial outcomes.
Ultimately, the insights gained from understanding K-1 distributions can empower families to secure their financial futures. By taking proactive steps, such as seeking expert guidance and adhering to filing deadlines, households can confidently navigate the complexities of tax obligations. This proactive approach alleviates financial stress and enhances the family’s ability to plan for significant life events, like education and retirement. Embracing this knowledge is vital for achieving long-term financial well-being and stability. Together, we can navigate this journey toward a brighter financial future.
Frequently Asked Questions
What is a Schedule K-1?
A Schedule K-1 is a tax document that reports earnings, deductions, and credits from partnerships, S corporations, estates, or trusts. It outlines an individual’s share of the entity’s financial activities for tax reporting purposes.
Why is Schedule K-1 important?
Schedule K-1 is crucial for tax reporting as it informs the IRS about the income that must be included on individual tax returns. It helps individuals manage their tax obligations and plan for their financial future.
How common is the use of Schedule K-1?
Approximately 90% of partnerships and S corporations utilize K-1 forms, highlighting their significance for individuals dealing with complex tax situations.
How can understanding Schedule K-1 influence financial planning?
Understanding the nuances of Schedule K-1 can significantly impact a family’s financial planning by preparing them for tax obligations and helping them allocate resources effectively for expenses like education and retirement.
What benefits did families experience by understanding their K-1 tax situation?
Families like Jay and Emma reduced financial anxiety by understanding their tax situation, allowing them to plan for their children’s education and secure their retirement. Similarly, Emily and Mark optimized their financial situation, enhancing their work-life balance.
How can Bright Advisers assist families with Schedule K-1?
Bright Advisers offers tailored services to help families navigate K-1 distributions and optimize their financial situations, enhancing overall financial well-being and providing security for their loved ones.
List of Sources
- Define Schedule K-1 and Its Purpose
- K-1 Tax Form: How & When to File a Schedule K-1 (https://carta.com/learn/startups/tax-planning/schedule-k-1-tax-form)
- Schedule K-1 Federal Tax Form: What Is It and Who Is It For? (https://investopedia.com/terms/s/schedule-k-1.asp)
- What is a Schedule K-1 Form 1041: Estates and Trusts? (https://turbotax.intuit.com/tax-tips/estates/what-is-a-schedule-k-1-form-1041-estates-and-trusts/L6XWJCf3c)
- A Guide to Schedule K-1 (Form 1041) (https://smartasset.com/estate-planning/k-1-tax-form-inheritance)
- GAO Recommends Steps to Improve Partnership and S Corp Reporting | Tax Notes (https://taxnotes.com/lr/resolve/tax-notes-today-federal/gao-recommends-steps-to-improve-partnership-and-s-corp-reporting/fh3l)
- Identify Key Components of a K-1 Form
- Schedule K-1 Tax Form Explained: What Is it & How It Affects You (https://farther.com/resources/foundations/schedule-k-1-tax-form-explained-what-is-it-how-it-affects-you)
- K1 tax form for dummies: mish mosh turned SIMPLE! (https://vericrestprivatewealth.com/k-1-tax-form-for-dummies.php)
- Understanding Tax Form K-1: Reporting, Deadlines & Challenges (https://tax1099.com/glossary/k-1-reporting-rules)
- Schedule K-1: A Guide for Real Estate Investors | Windes (https://windes.com/schedule-k-1-guide-private-placement-re-investors)
- Schedule K-1: Partner’s Share of Income, Deductions, Credits, etc. (https://investopedia.com/ask/answers/09/k-1-tax-form.asp)
- Analyze Tax Implications of K-1 Distributions
- Are K-1 Distributions Considered Taxable? (https://realized1031.com/blog/are-k-1-distributions-considered-taxable)
- Schedule K-1 Tax Form: Essential Filing Tips for Taxpayers | Eqvista (https://eqvista.com/documents/schedule-k-1-tax-form)
- Understanding Your K-1 (https://withum.com/resources/understanding-your-k-1)
- Schedule K-1 Tax Form for Partnerships: What to Know to File | Bench Accounting (https://bench.co/blog/tax-tips/k1-tax-form)
- 2023 Instructions for Schedule K-1 565 | FTB.ca.gov (https://ftb.ca.gov/forms/2023/2023-565-k-1-instructions.html)
- Guide to Filing Taxes with K-1 Forms
- Schedule K-1: What to Know About Investment Partnership Interests – NerdWallet (https://nerdwallet.com/article/investing/schedule-k-1)
- Schedule K-1 Federal Tax Form: What Is It and Who Is It For? (https://investopedia.com/terms/s/schedule-k-1.asp)
- Understanding Schedule K-1: A Guide to Tax Form 1065 (https://aprio.com/understanding-schedule-k-1-a-guide-to-tax-form-1065-ins-article-tax)
- Schedule K-1 Tax Form for Partnerships: What to Know to File | Bench Accounting (https://bench.co/blog/tax-tips/k1-tax-form)
- FILING SEASON STATISTICS: (https://nstp.org/article/filing-season-statistics-)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading