

Key Highlights
- Understanding financial advisory fees is essential for effective budgeting and maximising value from financial services.
- Common fee structures include Assets Under Management (AUM), hourly fees, flat fees, and commission-based fees.
- AUM fees typically range from 0.50% to 1.50% annually, while hourly fees range from $200 to $400.
- Flat fees for specific services can range from $1,000 to $10,000, providing predictability in costs.
- Commission-based fees may lead to conflicts of interest; families are encouraged to consider fee-only advisors.
- Factors affecting advisory costs include the complexity of financial situations, consultant experience, geographic location, and the scope of services.
- Bright Advisers emphasises transparency, fiduciary duty, and no hidden fees, charging a standard investment management fee of 0.80%.
- Choosing the right financial planner involves defining goals, researching advisors, evaluating fee structures, and ensuring a good personal fit.
Introduction
Many families feel overwhelmed when faced with the complexities of financial planning costs. Let’s explore the different fee structures financial advisors use, so you can feel more confident about what to expect and how to budget for your family’s future. But with so many choices out there, how can you find a planner whose fees fit your family’s financial goals and help you avoid common pitfalls?
Explore Financial Advisory Fees: Understanding the Basics
We know that understanding how much do fee based financial planners charge can feel overwhelming for families, but it’s a crucial step toward effective budgeting and ensuring you get the most value from your financial services. Here at Bright Advisers, we truly care about keeping your fund fees as low as possible, ensuring that most of our models reflect that commitment.
Let’s explore some common fee structures that can help you understand what to expect:
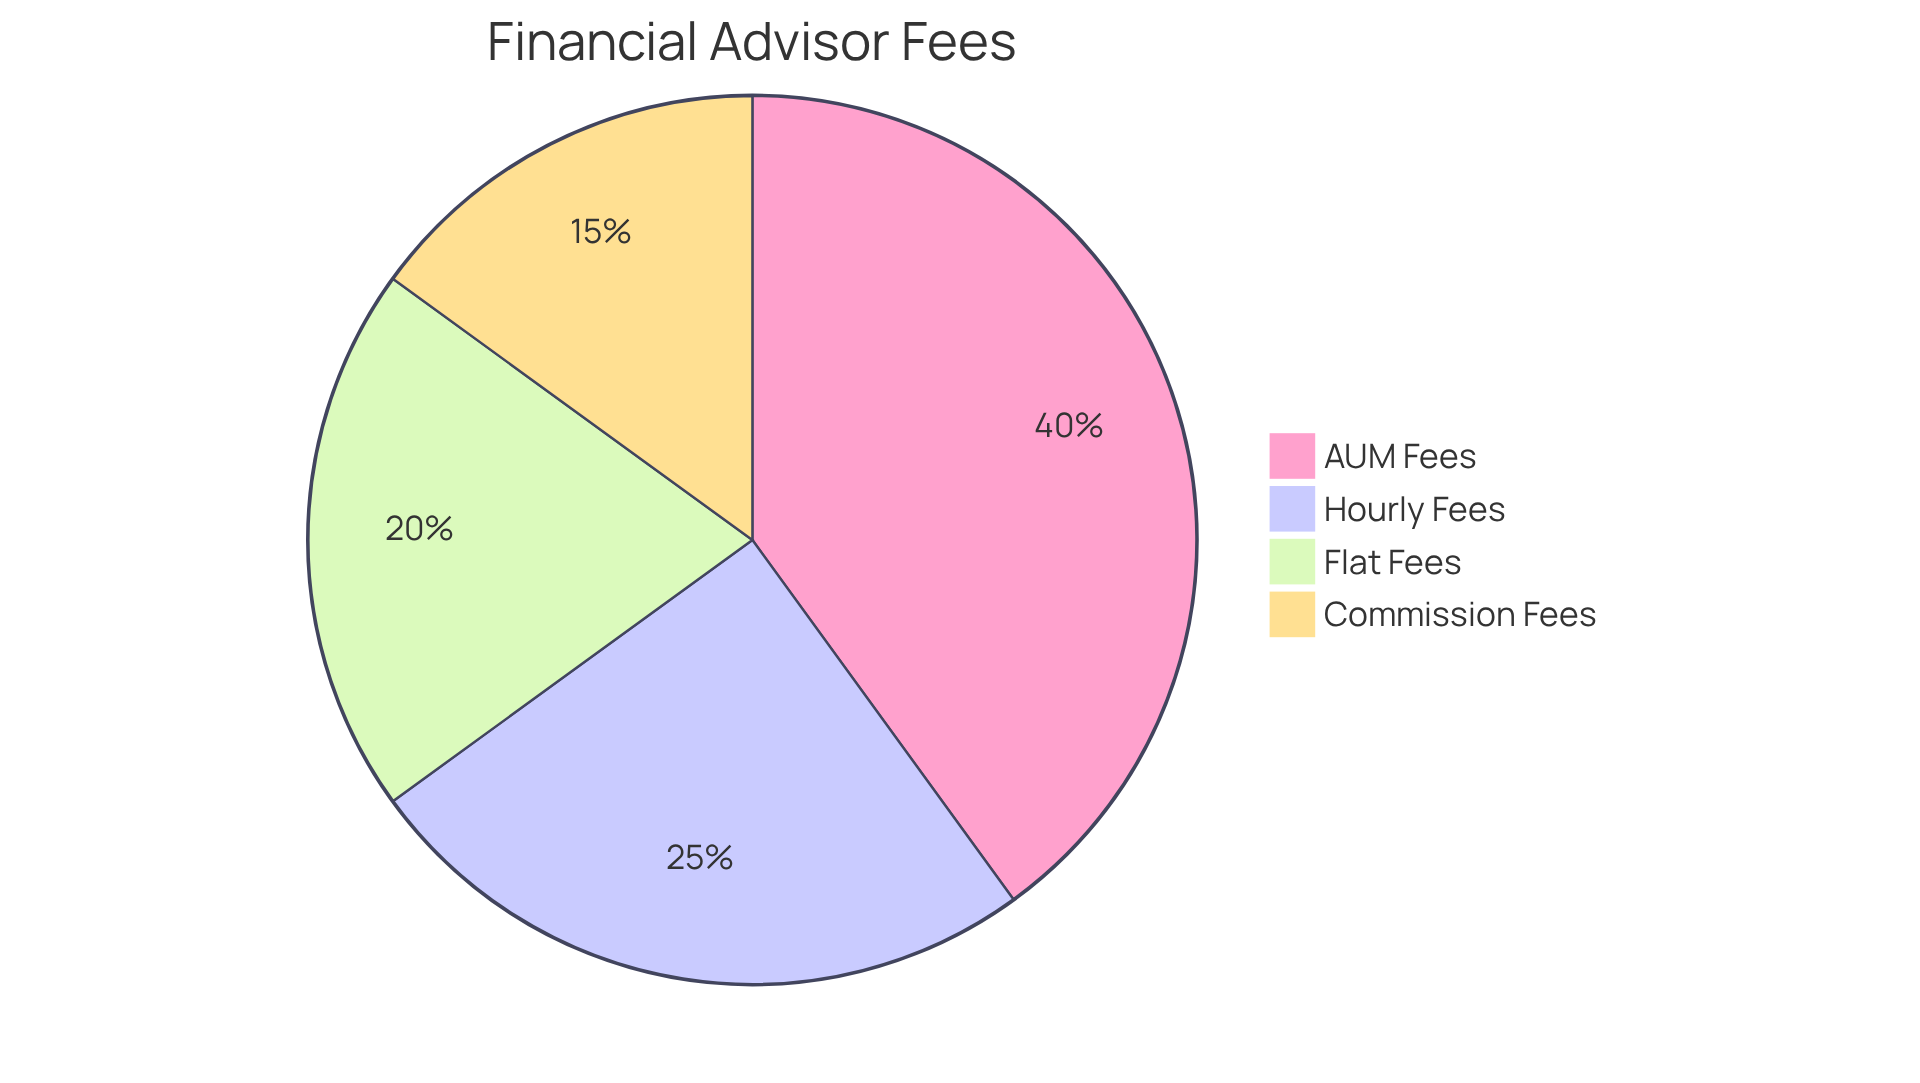
- Assets Under Management (AUM): This model charges a percentage of the total assets managed, typically ranging from 0.50% to 1.50% annually. For instance, a $1.5 million portfolio would incur an annual fee of approximately $15,000, reflecting a 1.0% effective rate.
- Hourly Fees: Advisors may charge based on the time spent, with rates generally between $200 and $400 per hour. This structure is particularly useful for families needing targeted advice without a long-term commitment.
- Flat Fees: A predetermined fee for specific services, which can range from $1,000 to $10,000 depending on the complexity of the services provided. Clients can anticipate how much do fee based financial planners charge for thorough monetary planning, which is between $2,500 and $5,000.
- Commission-Based Fees: These charges are obtained by consultants through the sale of monetary products, potentially resulting in conflicts of interest. Families should be cautious and consider fee-only consultants to minimize such risks.
Recent trends indicate a growing preference for flat fee structures among younger clients, who value clarity and predictability in financial dealings. Moreover, households are encouraged to discuss charges, as numerous advisors are receptive to modifying their pricing according to client requirements. At Bright Advisers, we emphasize transparency and a fiduciary duty, ensuring no hidden fees or conflicts of interest. When you grasp these fee structures, you empower your family to make choices that truly reflect your financial goals.
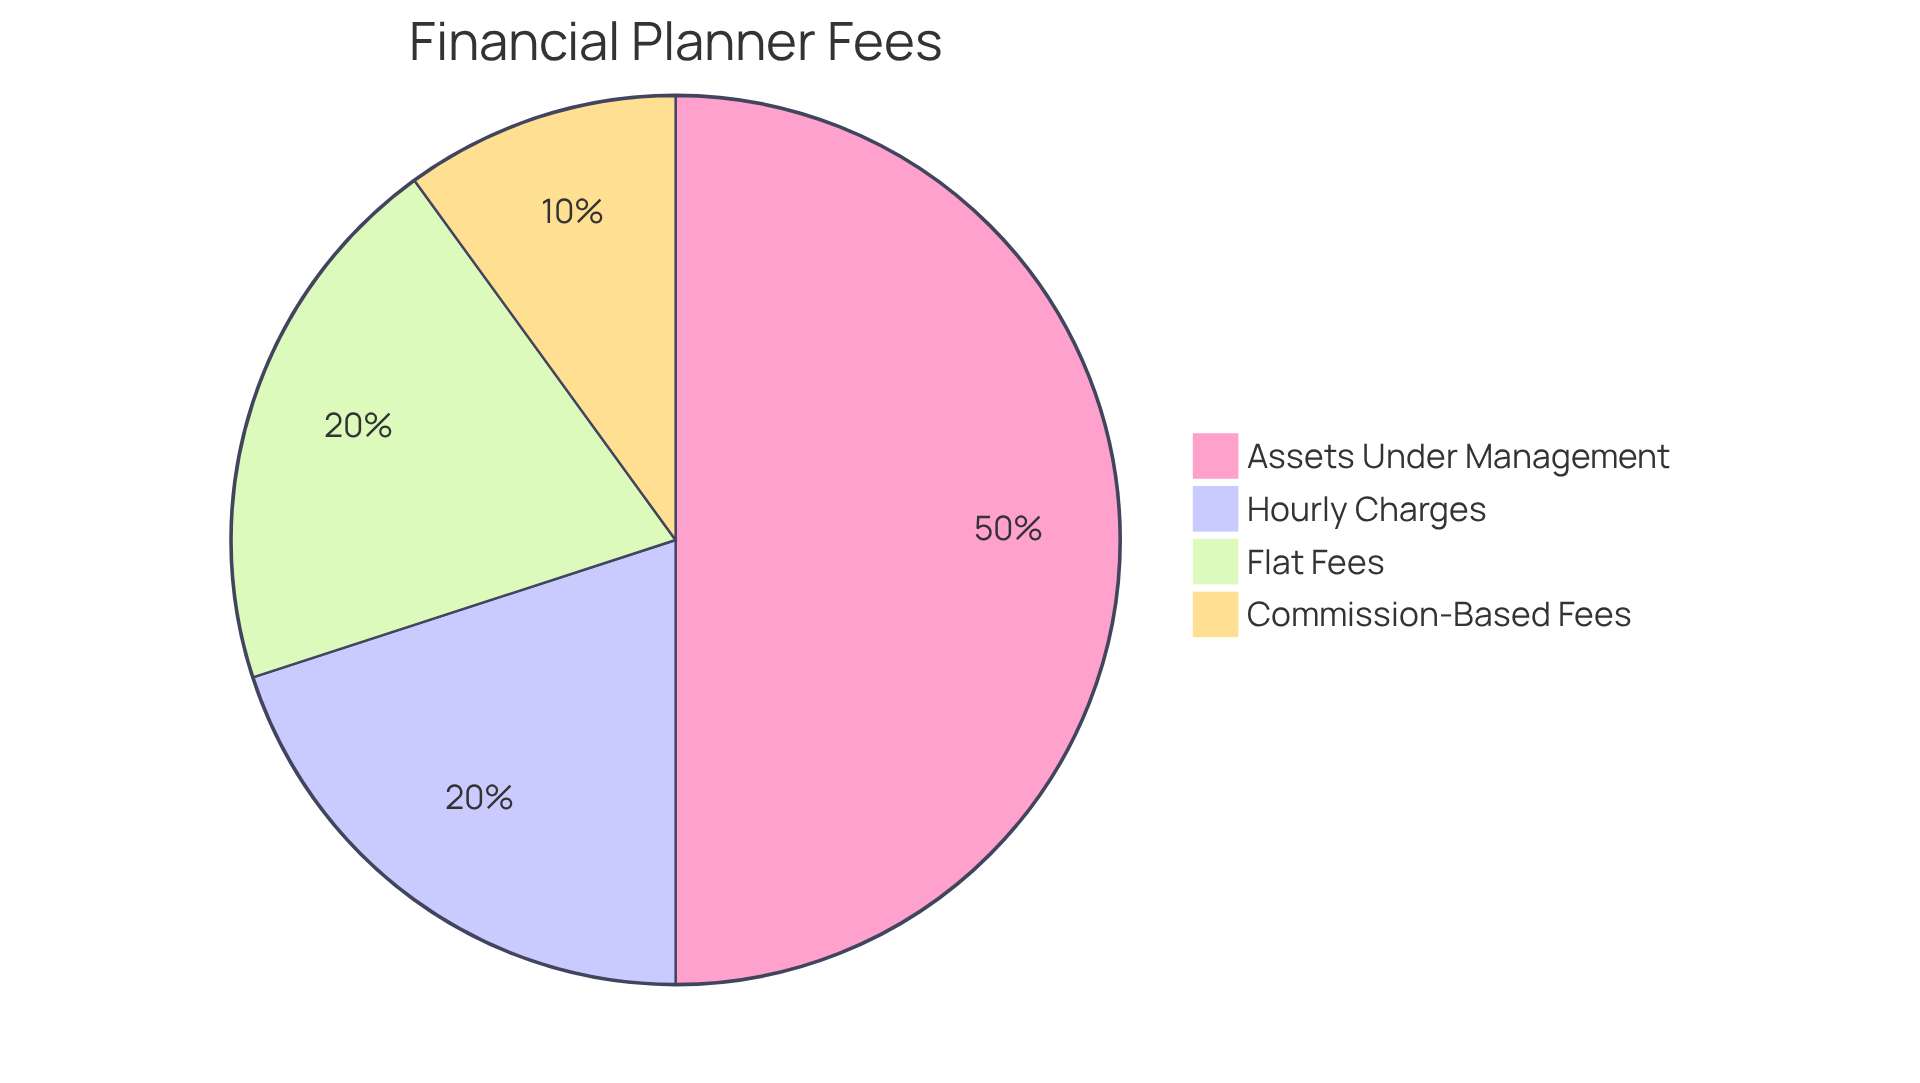
Compare Fee Structures: AUM, Hourly, Flat, and Commission-Based Models
Choosing the right financial planner can feel overwhelming, especially when you’re trying to secure your family’s future. Here’s a gentle breakdown of the most common fee structures to help you navigate this important decision:
-
Assets Under Management (AUM): Imagine a model where you pay a percentage based on how much your advisor manages for you, usually around 1% for portfolios up to $1 million. For example, a 1% fee on a $1 million portfolio translates to $10,000 annually. While this aligns your advisor’s incentives with your investment growth, it’s important to understand that as your portfolio grows, so do the fees, which can strain your budget.
-
Hourly Charges: This option offers flexibility, but if your family’s financial situation is complex, costs can add up quickly. Hourly charges typically range from $200 to $400, making it suitable for households needing occasional guidance.
-
Flat Fees: A predictable choice, flat fees can range from $1,000 to $10,000 for comprehensive services. This model is great for families who appreciate knowing their costs upfront, allowing for better budgeting and planning.
-
Commission-Based Fees: Some advisors earn commissions by selling investment products, which might lead them to recommend options that aren’t the best fit for your family. While this may seem economical, it’s crucial to be aware of potential conflicts of interest.
By understanding how much do fee based financial planners charge, you can confidently choose a planner who aligns with your family’s financial goals, ensuring peace of mind for your loved ones.
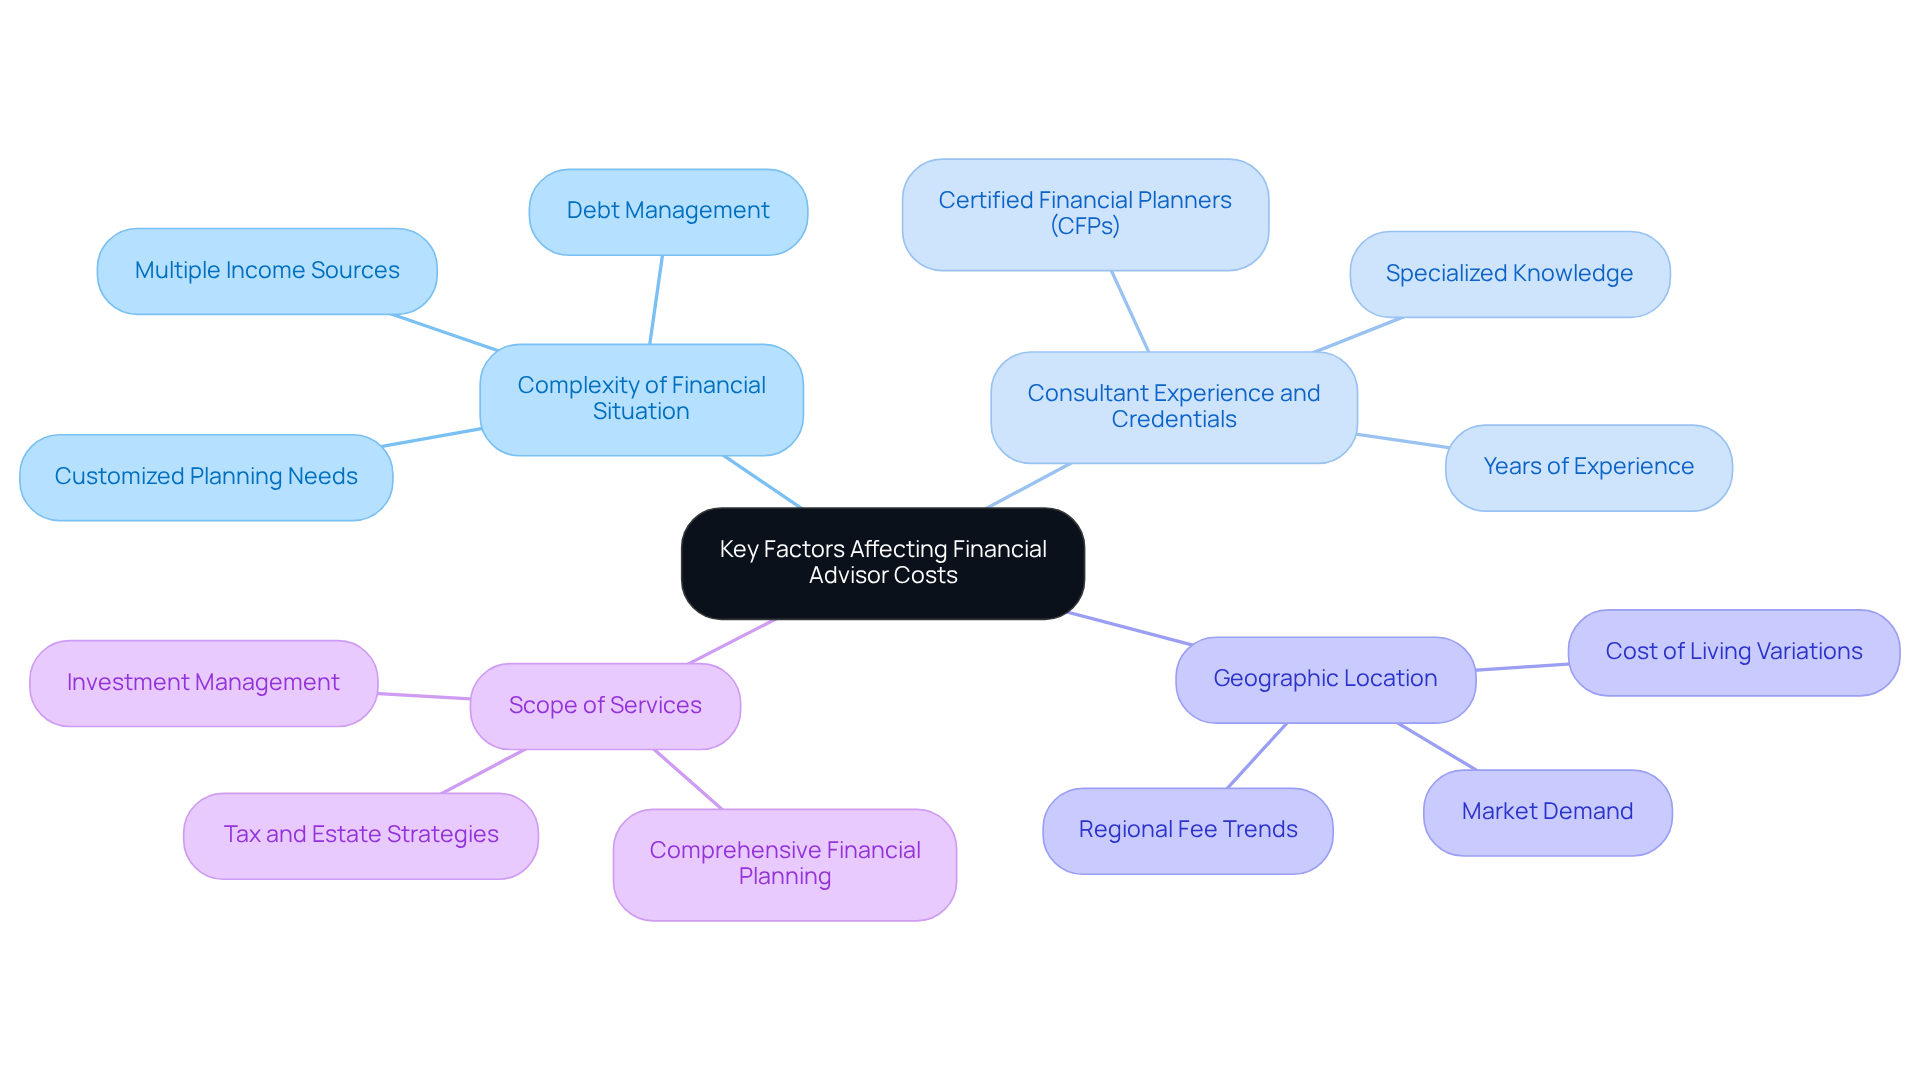
Identify Key Factors Affecting Financial Advisor Costs
Navigating the world of financial consulting can feel overwhelming, especially for families trying to balance their dreams and daily expenses. Multiple elements can greatly affect how much do fee based financial planners charge for households maneuvering through intricate economic environments. Let’s explore how these factors can help your family make the best financial choices:
-
Complexity of Financial Situation: If your family has different income sources or debts, it might mean needing more detailed planning, which can come with higher costs. For instance, consider Jay and Emma, who juggle multiple income streams while planning for retirement and saving for their children’s education. They may face extra expenses due to the customized approaches required to enhance their economic situation.
-
Consultant Experience and Credentials: The experience and qualifications of a consultant can also affect what you’ll pay. More seasoned consultants or those with specialized credentials, like Certified Financial Planners (CFPs), typically charge higher fees, leading to inquiries about how much do fee based financial planners charge, as this reflects their advanced expertise in managing intricate monetary situations.
-
Geographic Location: Fees can vary widely based on where the consultant is located. For example, in busy places like Los Angeles, consultants often charge more due to the higher cost of living and the complexity of their clients’ needs. This means that families may need to budget carefully to ensure they can afford the right support for their financial journey.
-
Scope of Services: The range of services provided by an advisor also affects costs. If you’re looking for complete financial planning that includes taxes and estate strategies, you should consider how much do fee based financial planners charge, as it will be more than for basic investment help. Families seeking a holistic approach to their economic well-being should anticipate higher costs for the added value of integrated services.
At Bright Advisers, our standard investment management fee is 0.80%, payable monthly in advance based on the market value of each client’s account. We also provide a wrap fee program that encompasses specific brokerage and other expenses, enabling households to manage their costs effectively. By understanding these factors, you can confidently choose a consultant who truly understands your family’s unique financial journey.
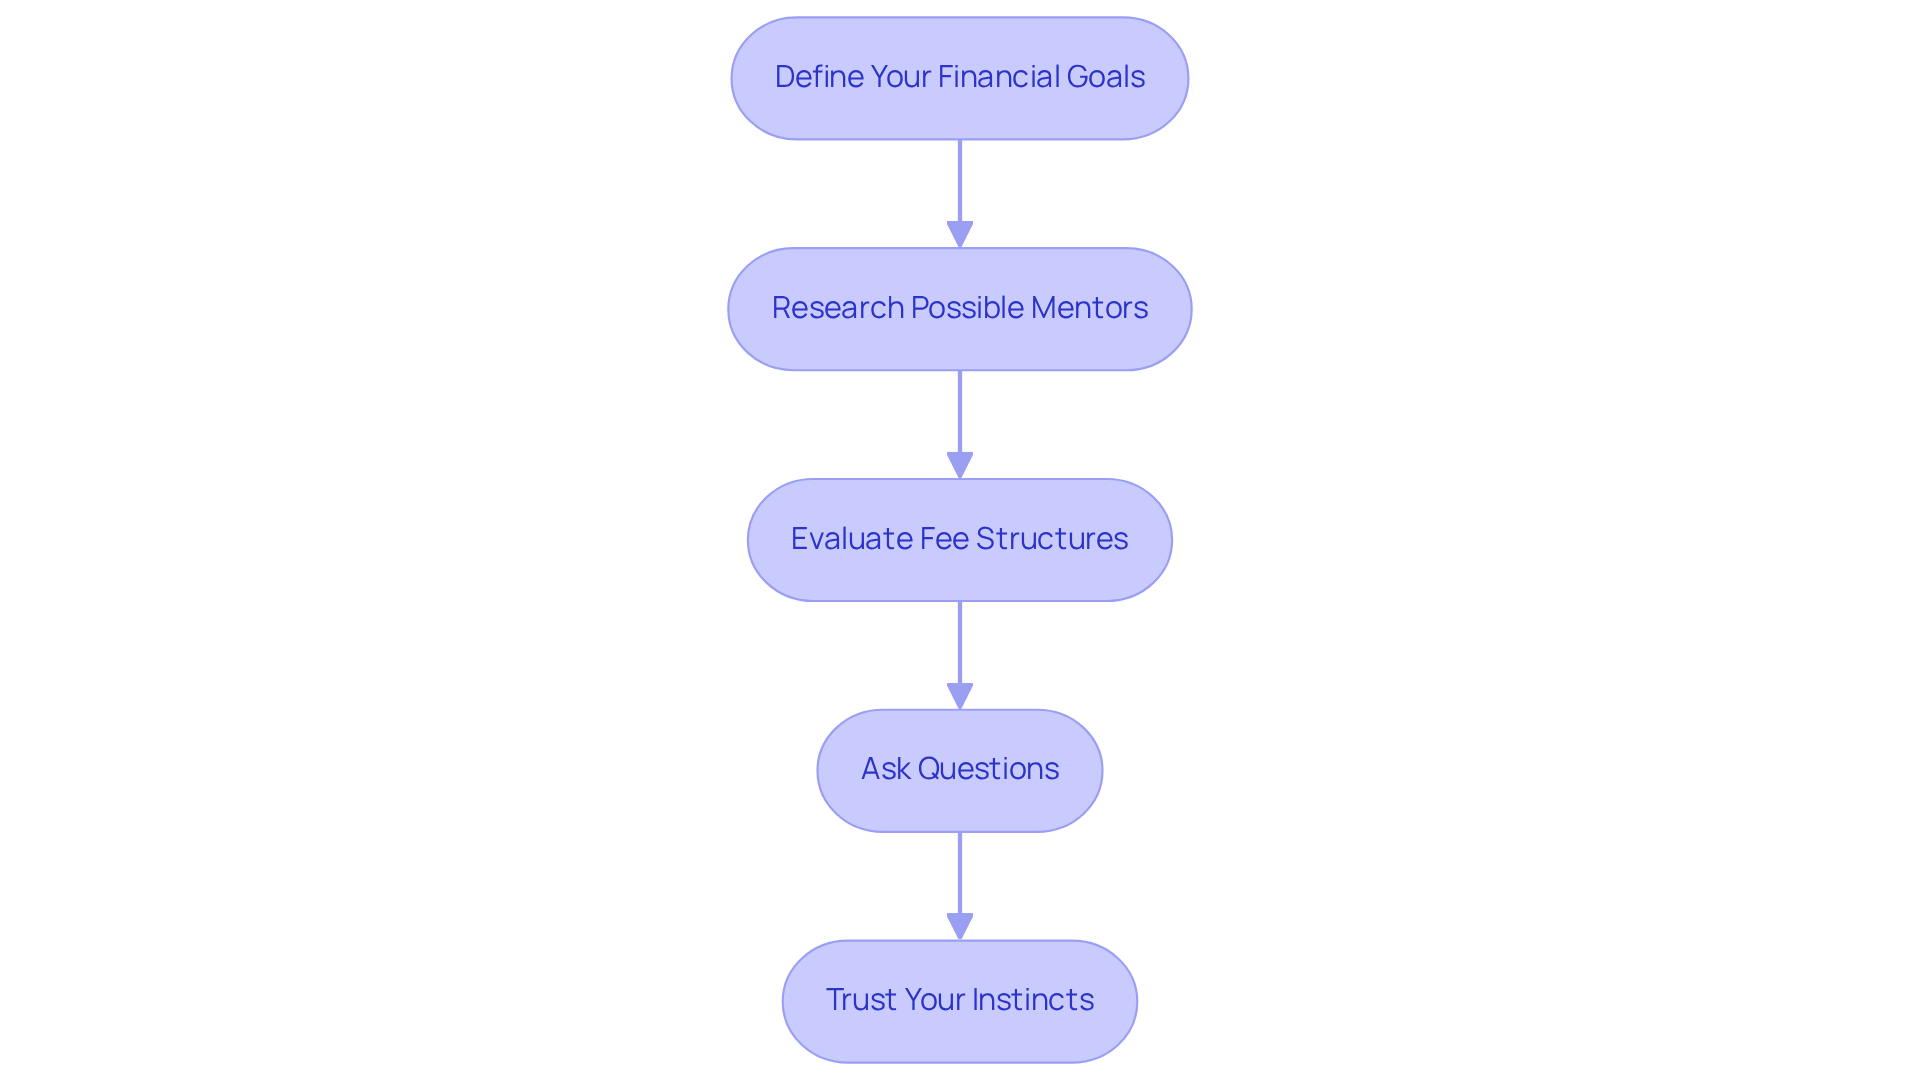
Select the Right Financial Planner: Aligning Fees with Family Goals
Imagine feeling overwhelmed by financial choices while trying to secure your family’s future; you’re not alone in this journey. Choosing the right planner is about more than just costs; it’s about aligning their services with your family’s dreams and goals. Here are essential steps to guide your selection:
-
Define Your Financial Goals: Clearly articulate your objectives, whether it’s saving for your children’s education, planning for retirement, or establishing an estate plan.
-
Research Possible Mentors: Look for mentors who focus on household monetary planning and have a proven track record with clients in similar situations. Review their credentials and client testimonials to gauge their expertise.
-
Evaluate how much do fee based financial planners charge and assess how each advisor’s fee structure aligns with your monetary goals. For families seeking predictability in costs, it is important to know how much do fee based financial planners charge, as a flat fee model may be more advantageous than percentage-based fees.
-
Ask Questions: During initial consultations, inquire about their monetary planning approach, fee structures, and fiduciary status. A fiduciary consultant is legally obligated to act in your best interest, ensuring transparency and trust.
-
Trust Your Instincts: Select a counselor with whom you feel at ease, as a solid relationship is essential for effective planning.
Together, we can navigate this journey to find a planner who truly understands your family’s values and aspirations. Finding the right planner can transform your financial journey, bringing clarity and confidence to your family’s future.
Conclusion
Imagine feeling confident about your family’s financial future, knowing exactly what to expect from your financial planner. It’s important to know what fees come with financial planning, especially when you’re trying to secure your family’s future. When you understand different fee structures – like hourly rates or flat fees – you can make choices that truly fit your family’s financial goals. At Bright Advisers, we believe in being open about costs, so you never have to worry about hidden fees or conflicts of interest.
It’s good to remember that things like your family’s financial situation and the advisor’s experience can affect costs. Take your time when choosing a financial planner; the right one can help you feel secure about your financial journey. It’s crucial to make sure your financial planner’s fees match your family’s goals. When you define your financial goals and ask the right questions, you can find a planner who truly understands your family’s needs and builds trust with you.
Working with a fiduciary advisor like Bright Advisers can help your family feel confident in managing your finances, making sure your wealth is cared for now and in the future. Together, we can navigate this journey, ensuring your family’s financial well-being for generations to come.
Frequently Asked Questions
What are the common fee structures for financial advisory services?
Common fee structures include Assets Under Management (AUM), hourly fees, flat fees, and commission-based fees. AUM typically charges a percentage of total assets managed, hourly fees are based on time spent, flat fees are predetermined for specific services, and commission-based fees come from the sale of financial products.
How does the Assets Under Management (AUM) fee structure work?
The AUM model charges a percentage of the total assets managed, usually ranging from 0.50% to 1.50% annually. For example, a $1.5 million portfolio would incur an annual fee of approximately $15,000 at a 1.0% rate.
What are hourly fees in financial advisory services?
Hourly fees are charged based on the time the advisor spends working with a client, typically ranging from $200 to $400 per hour. This structure is beneficial for families seeking targeted advice without a long-term commitment.
What are flat fees in financial advisory services?
Flat fees are predetermined charges for specific services, ranging from $1,000 to $10,000 depending on the complexity of the services. For comprehensive monetary planning, clients can expect fees between $2,500 and $5,000.
What are commission-based fees and what should families be cautious about?
Commission-based fees are earned by advisors through the sale of financial products, which can lead to conflicts of interest. Families should consider fee-only consultants to minimize these risks.
What trends are emerging in financial advisory fees?
There is a growing preference for flat fee structures among younger clients who value clarity and predictability in financial dealings.
How can families ensure they understand financial advisory fees?
Families are encouraged to discuss charges with their advisors, as many are open to adjusting their pricing based on client needs. At Bright Advisers, transparency and fiduciary duty are emphasized, ensuring no hidden fees or conflicts of interest.
Who provides the advisory services mentioned in the article?
The advisory services are provided through Lifeworks Advisors, a registered investment adviser, ensuring compliance and transparency.
List of Sources
- Explore Financial Advisory Fees: Understanding the Basics
- How Much Does a Financial Advisor Cost? Complete 2026 Fee Guide | Domain Money Financial Planning (https://domainmoney.com/post/how-much-does-a-financial-advisor-cost)
- How Much Does a Financial Advisor Cost? It Depends. – NerdWallet (https://nerdwallet.com/financial-advisors/learn/how-much-does-a-financial-advisor-cost)
- 7 Insights on Average Money Management Fees for Families – Bright Advisers (https://brightadvisers.com/7-insights-on-average-money-management-fees-for-families)
- How Much Does a Financial Advisor Cost? 2026 Fee Guide (https://endeavorfg.com/feeds/blog/best-financial-advisors-flat-fee-structure-2025)
- Compare Fee Structures: AUM, Hourly, Flat, and Commission-Based Models
- How Much Does A Financial Advisor Cost? Fee Guide & Analysis (https://savvywealth.com/blog-posts/financial-advisor-cost)
- How Much Does a Financial Advisor Cost in California? (https://randallwealthgroup.com/how-much-does-a-financial-advisor-cost-california)
- How Much Does a Financial Advisor Cost? (https://smartasset.com/financial-advisor/financial-advisor-cost)
- Free advisor fee calculator: is your 1% really 1%? (2026) (https://truthifi.com/education/advisor-fee-fair)
- Pros and cons of different advisory fee models (https://envestnet.com/financial-intel/pros-and-cons-different-advisory-fee-models)
- Identify Key Factors Affecting Financial Advisor Costs
- How Financial Advisors Actually Charge For Their Services (https://kitces.com/blog/financial-advisors-charge-services-fee-structure-advisory-firm-profession-aum-pricing-insight)
- Pros and cons of different advisory fee models (https://envestnet.com/financial-intel/pros-and-cons-different-advisory-fee-models)
- Understanding Financial Planner Costs: Key Factors for Families – Bright Advisers (https://brightadvisers.com/understanding-financial-planner-costs-key-factors-for-families)
- Financial Advisor Cost | Fee Structures & Average Cost Backed by Data (https://financestrategists.com/financial-advisor/advisor-cost)
- How Much Does a Financial Advisor Cost in California? (https://randallwealthgroup.com/how-much-does-a-financial-advisor-cost-california)
- Select the Right Financial Planner: Aligning Fees with Family Goals
- The Real Cost of a Financial Advisor (https://investopedia.com/articles/personal-finance/021216/can-you-afford-financial-advisor.asp)
- How To Choose a Financial Planner: Ten Questions to Ask | disAbilityNavigator (https://disabilitynavigator.org/article/12515/how-choose-financial-planner-ten-questions-ask)
- How to choose a financial advisor | Vanguard (https://investor.vanguard.com/investor-resources-education/article/how-to-choose-a-financial-advisor)
- Pros and cons of different advisory fee models (https://envestnet.com/financial-intel/pros-and-cons-different-advisory-fee-models)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading