

Key Highlights
- Incentive Stock Options (ISOs) allow employees to purchase company stock at a predetermined price, potentially enhancing financial security for families.
- Understanding ISOs is crucial for budgeting and long-term financial health, as they can provide significant financial benefits if managed wisely.
- As of 2022, 58% of households owned stocks, indicating a growing awareness of investment opportunities, including Employee Stock Ownership Plans (ESOPs).
- ISOs typically vest over a four-year schedule with a 12-month cliff, allowing access to 25% of options each year after the first year.
- Families must understand the implications of good leaver and bad leaver provisions, which can affect unvested equity retention upon employee departure.
- Exercising ISOs can trigger tax implications, particularly the Alternative Minimum Tax (AMT), which families need to plan for to avoid unexpected tax bills.
- Holding shares for at least one year after exercising can qualify families for long-term capital gains treatment, reducing tax burdens.
- Strategies for maximising ISO benefits include timing of exercise, holding periods for tax advantages, diversification of investments, and consulting with a fiduciary advisor.
- Bright Advisers emphasises fiduciary duty and transparency, helping families navigate the complexities of ISOs and secure their financial future.
Introduction
Imagine feeling confident about your family’s financial future, even amidst the complexities of incentive stock options. These options can open doors to wealth, but they also come with rules and tax implications that might feel daunting for families. As families face the challenges of vesting schedules and tax consequences, they might wonder: how can they make the most of these stock options while keeping risks in check? In this article, we’ll explore the key aspects of incentive stock options vesting, sharing insights and strategies to help your family make informed choices for a brighter financial future.
Define Incentive Stock Options and Their Importance for Families
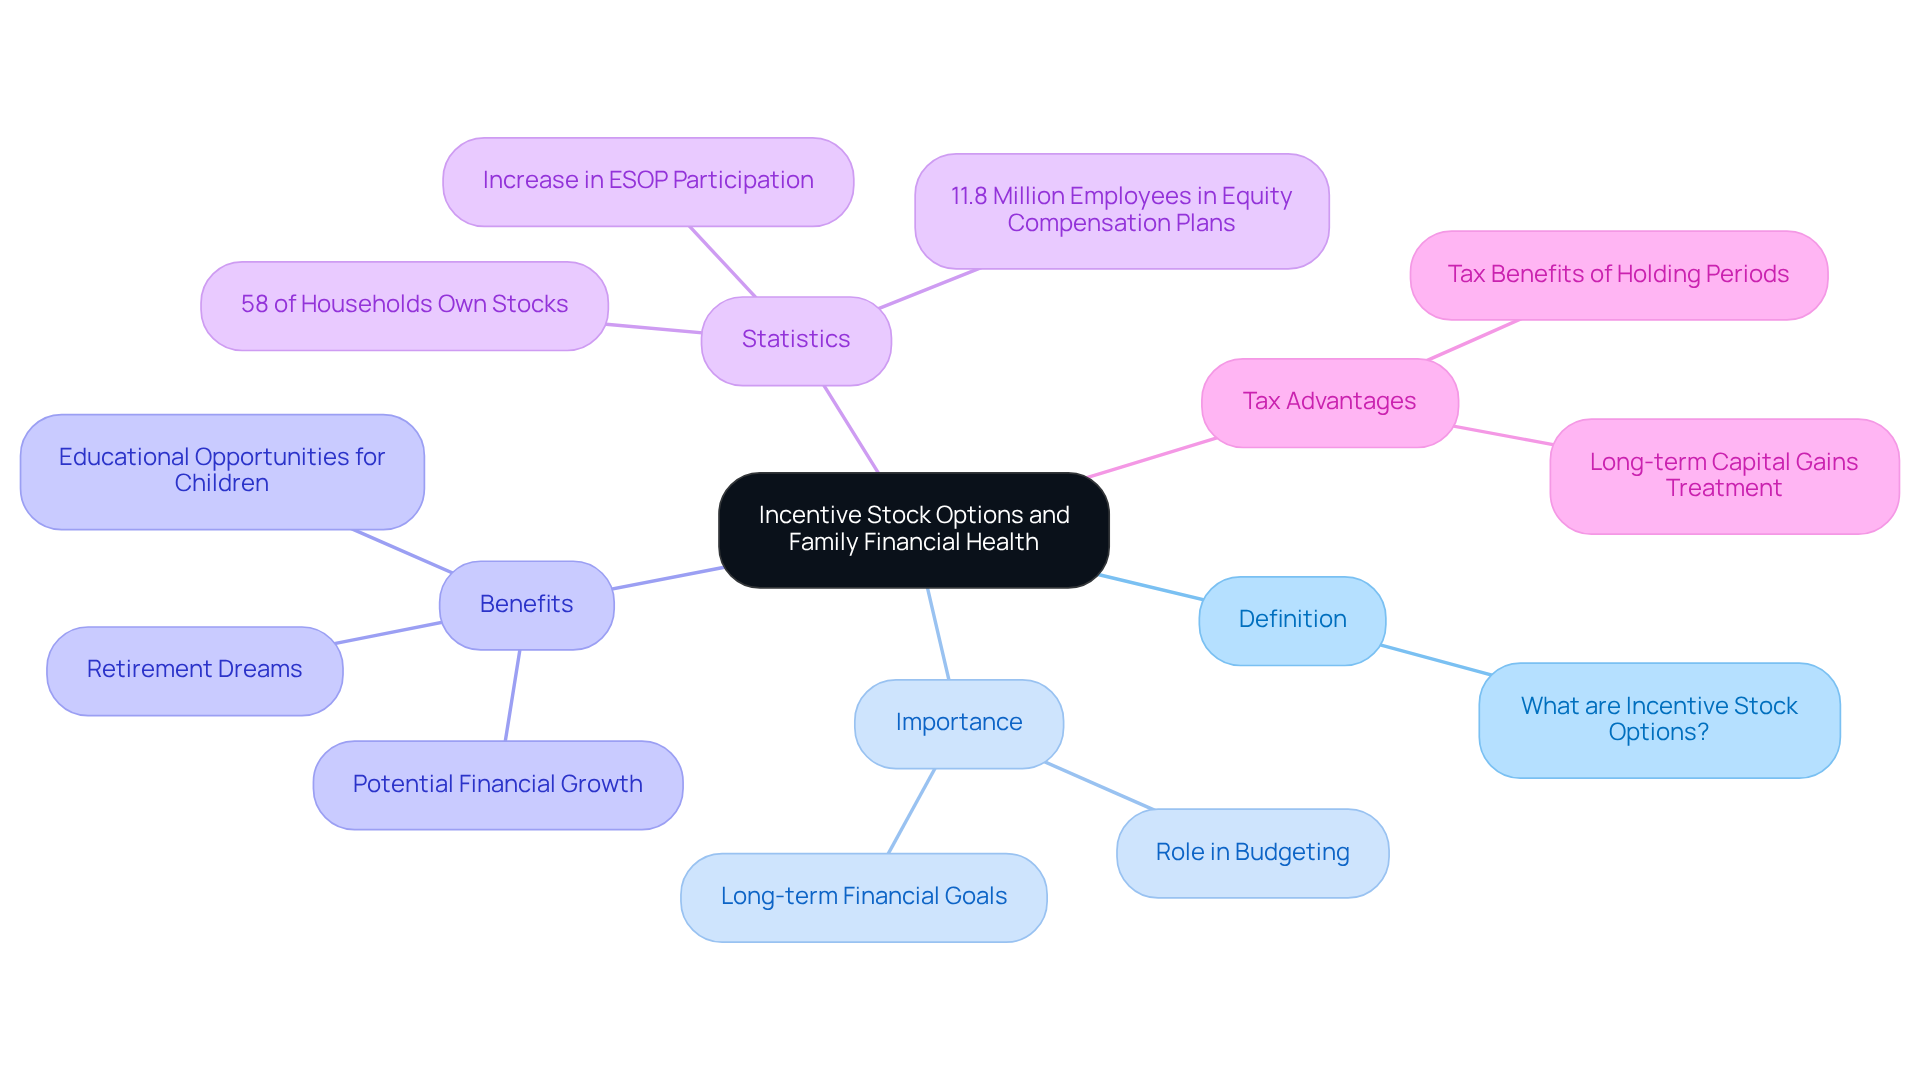
Imagine if you could turn your hard work into a brighter financial future for your family through smart stock options. Incentive stock options vesting allows you to buy shares of your company’s stock at a set price, making it easier to invest in your future. These options, particularly incentive stock options vesting, can be a significant part of your compensation, potentially leading to substantial financial benefits if your company does well.
Understanding stock options can feel overwhelming, but they play a crucial role in your family’s budgeting and long-term financial health. When you use stock options wisely, you’re not just improving your family’s finances; you’re opening doors for your kids’ education and your retirement dreams. Plus, if you meet certain criteria, stock options can offer tax benefits, making them a valuable tool in your financial toolkit.
Recent statistics show that 58% of households owned stocks as of 2022, highlighting the growing awareness of investment opportunities. The number of active participants in Employee Stock Ownership Plans (ESOPs) has also risen, reflecting a positive trend in employee ownership models. This shift underscores the importance of equity compensation in building household wealth.
Consider this: families that strategically utilize their shares through incentive stock options vesting can qualify for long-term capital gains treatment, which is taxed at a lower rate than regular income. By mastering stock options, families can unlock new opportunities for financial growth and security. Together, we can navigate this journey and build a lasting legacy for your loved ones.
Explain the Vesting Process of Incentive Stock Options
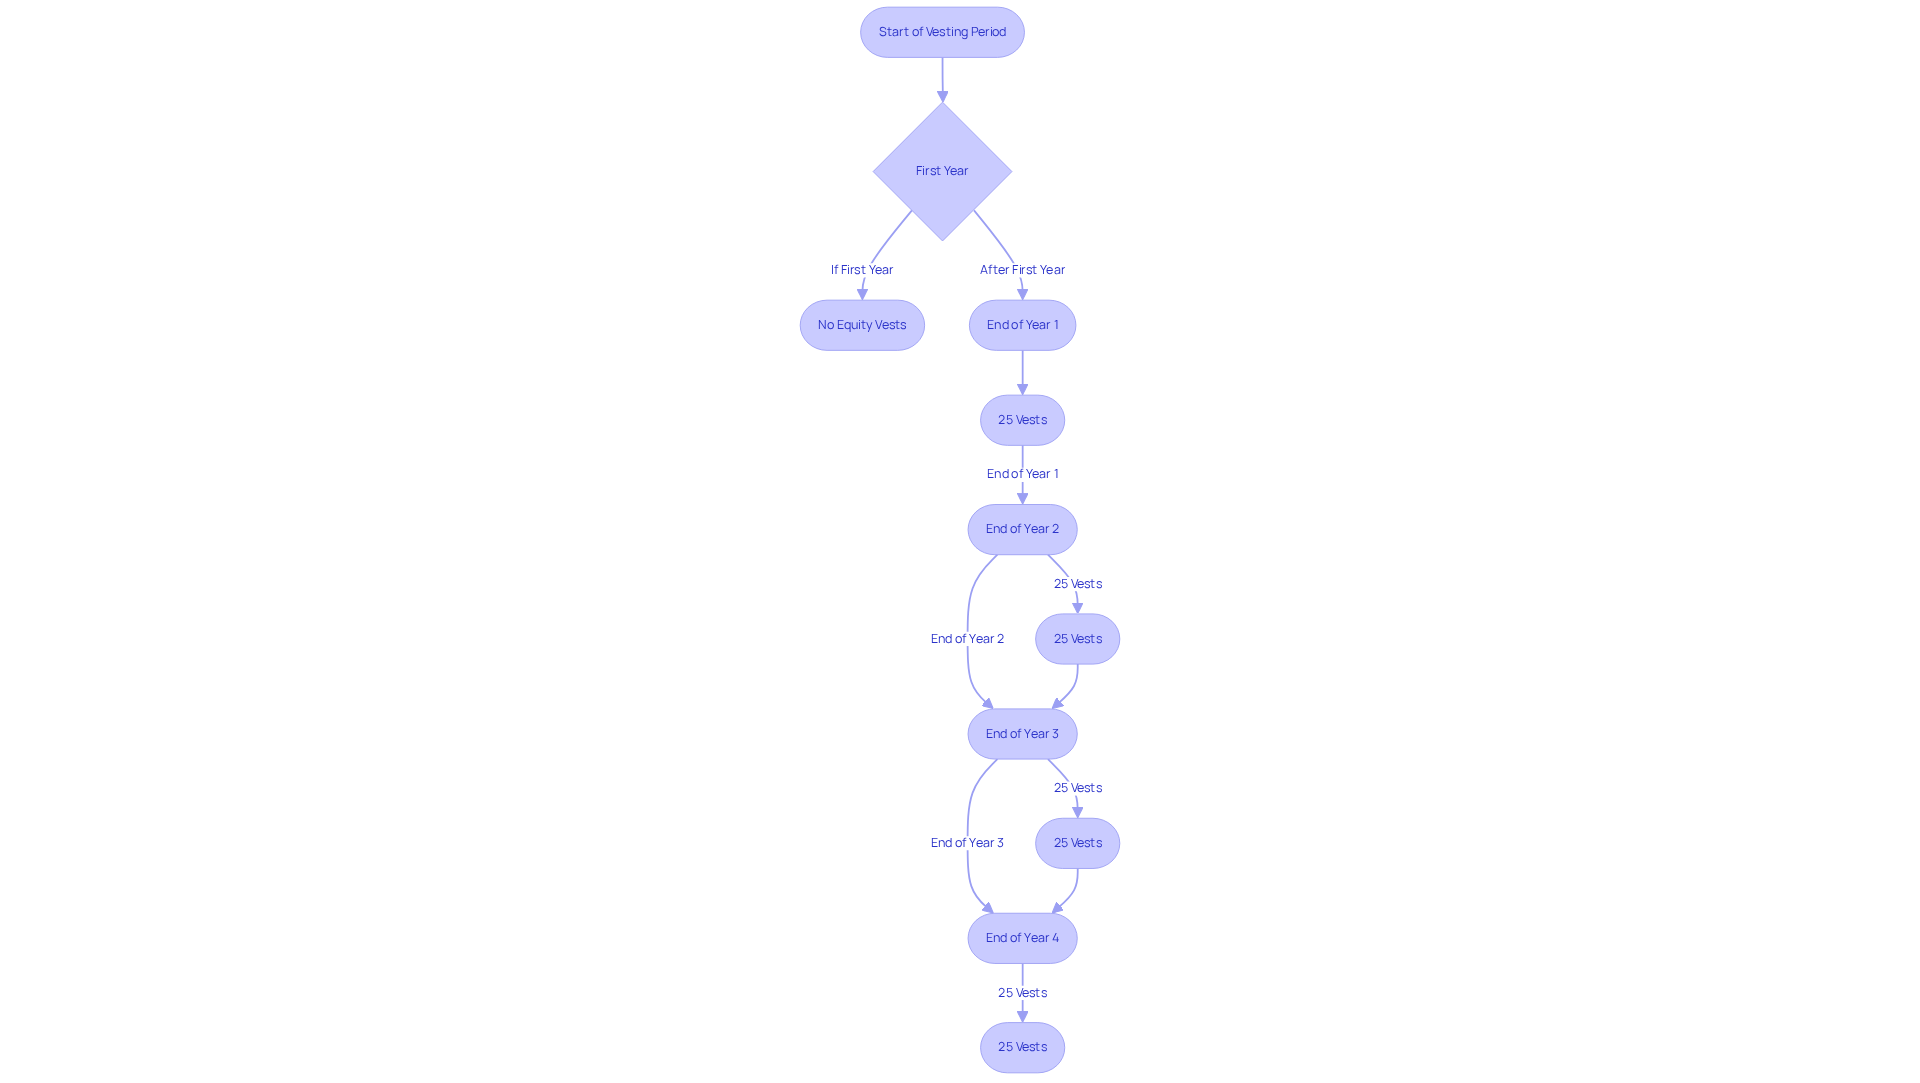
Imagine navigating the complexities of stock options and feeling empowered to make informed financial decisions for your family. The incentive stock options vesting process can be a key part of this journey. Typically, the vesting of incentive stock options follows a four-year schedule, often with a 12-month cliff. This means that no equity vests in the first year, but after that, you gain access to 25% of your options at the end of each year.
Many families find the complexities of stock options overwhelming, leading to missed opportunities and financial uncertainty. Understanding this process is essential, as it determines when you can utilize your options and potentially reap financial benefits. For instance, if a relative holds incentive stock options vesting over four years, they would gain access to 25% of their options each year. By grasping these concepts, families can turn confusion into clarity, paving the way for financial growth and security.
Did you know that nearly 90% of private companies choose a four-year vesting schedule? This common approach helps align employee interests with the company’s success, which can be a game-changer for your family’s financial planning. Some companies, like Amazon, even adopt variable vesting schedules, where equity vests unevenly over four years. This flexibility can enhance retention and hiring, making it crucial for families to understand how these structures can influence their planning.
It’s also important to consider the implications of good leaver and bad leaver provisions, which can affect the retention of unvested equity if an employee departs the company. Families should be mindful of the possible tax consequences of exercising stock options, as these elements play a crucial role in their overall strategy.
For example, Allison and Brian, a couple in their late 40s, sought assistance from Bright Advisers to navigate their monetary situation, which included stock options. They understood that without adequate tax planning, they were missing out on substantial economic opportunities. Through their collaboration with Bright Advisers, they optimized their tax situation, secured their children’s future through education funding, and gained the ability to retire sooner. This situation demonstrates how strategic financial planning, including comprehension of stock options, can result in improved financial security and independence for households.
Understanding these financial tools can transform your family’s future, ensuring you’re prepared for whatever comes next. It is important to note that past performance does not guarantee future results, and securities investments are subject to risk. All advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Discuss Tax Implications of ISOs During Vesting and Exercise
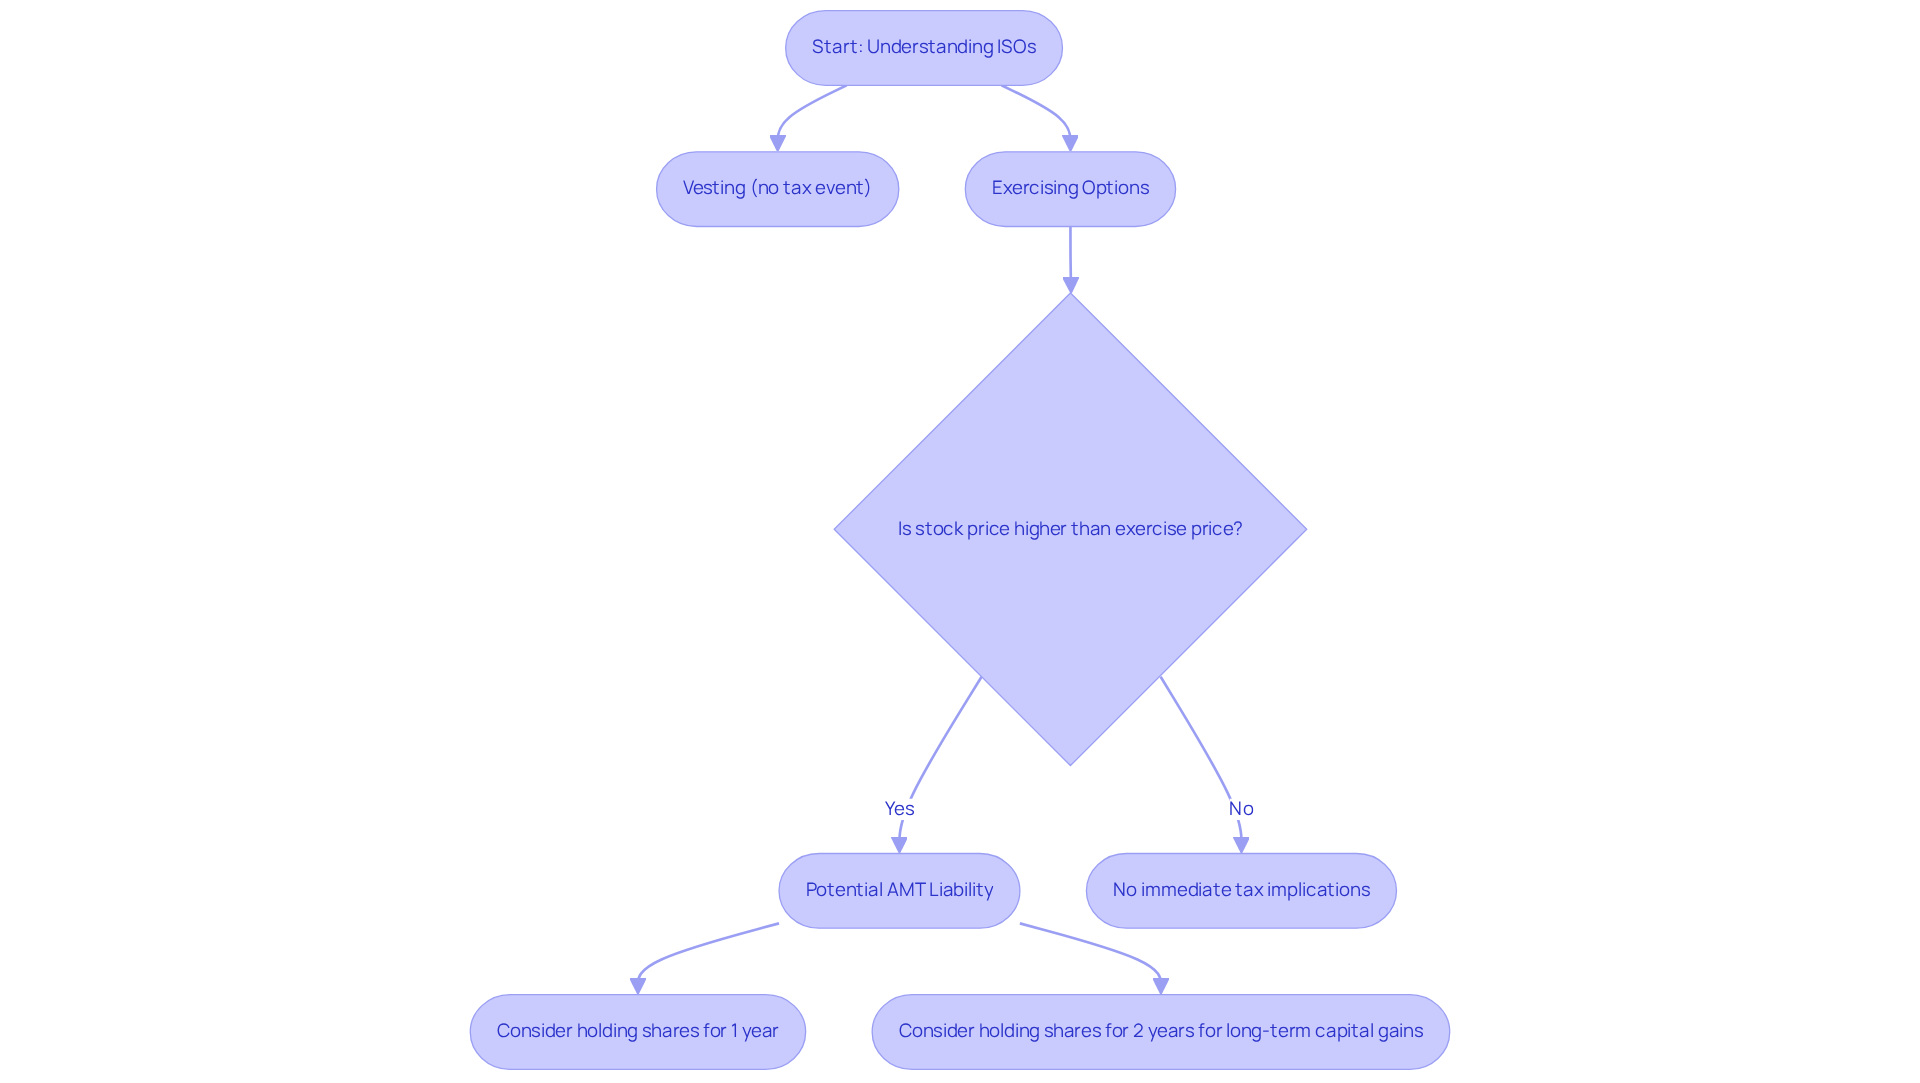
Imagine facing unexpected tax bills that could strain your family’s budget while trying to make the most of your equity compensation. The tax consequences of exercising Incentive Stock Options can feel overwhelming, but understanding them is crucial for families wanting to make the most of their equity compensation. Typically, you won’t face a tax event when incentive stock options vesting occurs, but exercising them can bring unexpected tax implications.
If you exercise your stock options and the stock price is higher than what you paid, you might find yourself facing the Alternative Minimum Tax (AMT). This means families need to plan carefully to avoid surprise tax bills. Holding onto your shares for at least a year after exercising them and two years after they were granted can help you qualify for long-term capital gains treatment, which usually means lower taxes on your gains. This tax advantage highlights why it’s important to think carefully about when to exercise and sell your options to maximize your benefits.
Real-life examples show just how complicated this can get. For instance, one case revealed that an employee could face an AMT liability of around $85,000 to $92,000, even without selling any shares. This is a classic example of ‘phantom income,’ where you might owe taxes on gains that aren’t actually in your pocket, which can create cash flow issues.
As families make these financial decisions, understanding the tax implications of incentive stock options vesting is vital. Starting in 2026, the AMT exemption will be $90,100 for individuals and $140,200 for married couples, making it crucial for families to stay informed about changes in tax laws that could affect their planning. By reaching out to tax professionals and using available resources, families can navigate their equity compensation and its tax implications more effectively. Together, we can navigate this journey and secure a brighter financial future for your family.
Outline Strategies for Maximizing Incentive Stock Options Benefits
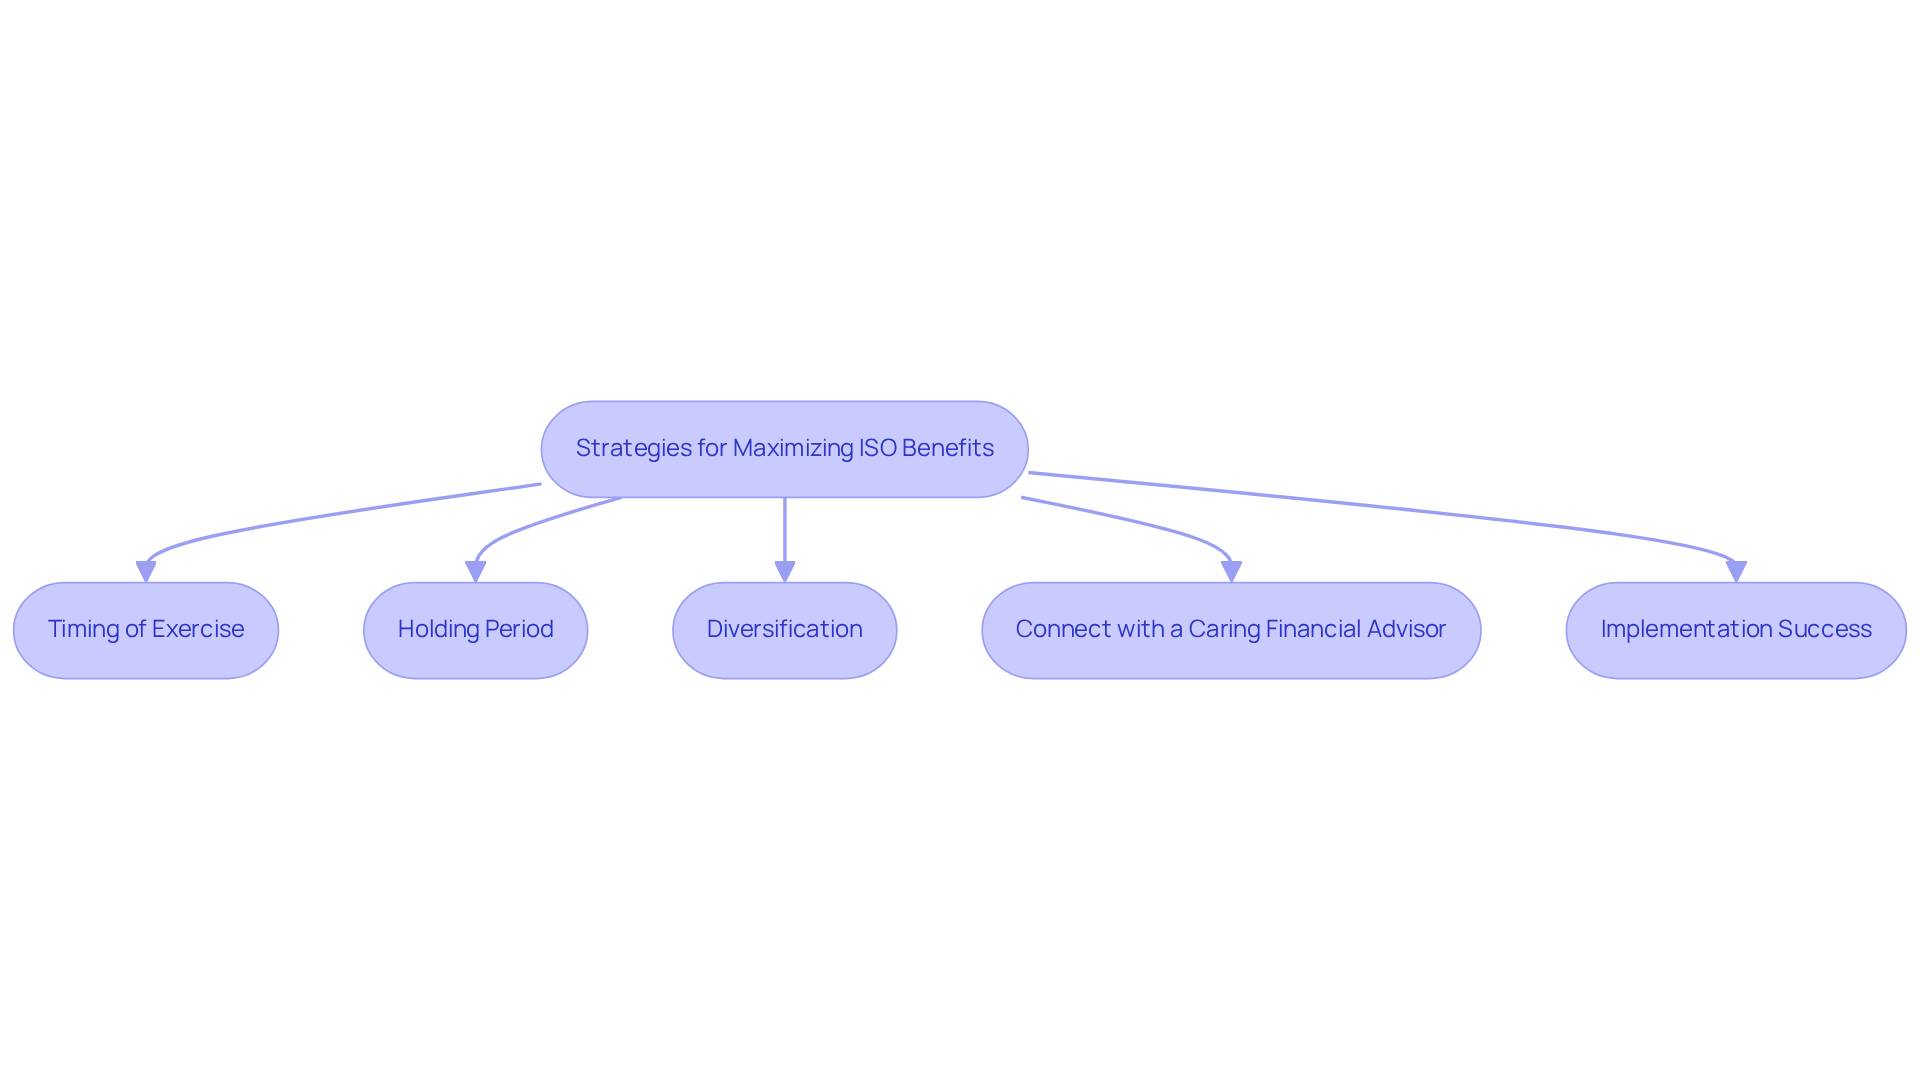
Imagine feeling secure about your family’s financial future while navigating the complexities of incentive stock options vesting. Here are some gentle strategies to help you enhance your financial security:
-
Timing of Exercise: Imagine exercising your ISOs early in the tax year, giving your family a chance to manage tax obligations more effectively and take advantage of potential market gains.
-
Holding Period: It’s important to hold onto those shares for the required period to qualify for long-term capital gains treatment. This simple step can significantly lighten the tax burden on any gains you realize from selling the stock.
-
Diversification: Avoid putting all your eggs in one basket. Once you exercise your options, consider diversifying your investments. This helps mitigate risk and ensures a more balanced investment portfolio for your family’s future.
-
Connect with a Caring Financial Advisor: We encourage you to connect with a caring fiduciary advisor who understands your family’s unique needs. At Bright Advisers, their dedication to minimal fund fees and in-house technology enhances personalized planning. They can help you avoid unnecessary expenses while capturing tax-loss harvesting opportunities. Together with a trusted advisor, you can uncover the best ways to manage your ISOs and secure your family’s financial future.
By implementing these strategies, families can enhance their financial security and optimize their incentive stock options vesting, just like Emily and Mark did by partnering with Bright Advisers to achieve their financial goals. With the right strategies and support, your family can thrive financially, just like Emily and Mark did.
Conclusion
Imagine feeling confident about how incentive stock options can help secure your family’s financial future. By understanding the intricacies of these options, you can leverage them to enhance your wealth and create opportunities for your children’s education and your own retirement plans.
When families understand how to use incentive stock options, they can unlock incredible opportunities for their future. Throughout this article, we’ve shared key insights about the vesting process, tax implications, and strategies for maximizing the benefits of these options. It’s important to know how vesting schedules work, what tax implications to expect, and how a trusted financial advisor can guide you through it all.
Real-life examples, like the experiences of families such as Allison and Brian, show how strategic planning can lead to improved financial security and independence. As you navigate the complexities of incentive stock options, remember that you’re not alone; seeking guidance can make all the difference for your family.
By implementing thoughtful strategies and connecting with a fiduciary advisor like Bright Advisers, you can optimize your financial decisions and build a lasting legacy. By taking these steps today, you’re not just planning for tomorrow; you’re building a legacy of security and opportunity for your loved ones.
Frequently Asked Questions
What are incentive stock options?
Incentive stock options are a type of employee benefit that allows you to purchase shares of your company’s stock at a predetermined price, which can lead to significant financial benefits if the company performs well.
Why are incentive stock options important for families?
They can be a substantial part of your compensation, contributing to your family’s financial health and helping to fund future expenses such as education and retirement.
How can stock options impact a family’s budgeting?
Understanding and utilizing stock options wisely can improve a family’s finances, providing additional resources for budgeting and long-term financial planning.
What are the potential tax benefits of incentive stock options?
If certain criteria are met, incentive stock options can qualify for long-term capital gains treatment, which is taxed at a lower rate than regular income, enhancing their value as a financial tool.
What is the current trend regarding stock ownership among households?
As of 2022, 58% of households owned stocks, indicating a growing awareness of investment opportunities and the importance of equity compensation in building household wealth.
How can families benefit from mastering stock options?
By strategically utilizing their shares through incentive stock options, families can unlock new opportunities for financial growth and security, ultimately helping to build a lasting legacy for their loved ones.
List of Sources
- Define Incentive Stock Options and Their Importance for Families
- Employee Ownership by the Numbers (https://nceo.org/research/employee-ownership-by-the-numbers)
- 3 Strategies To Optimize Incentive Stock Options (ISOs) (https://kitces.com/blog/incentive-stock-options-iso-amt-financial-plan-taxes-portfolio)
- 8 Advantages of Incentive Stock Options You May Want to Know (https://zajacgrp.com/insights/8-advantages-of-incentive-stock-options-you-should-know)
- Master Incentive Stock Options Exercise Planning for Your Family – Bright Advisers (https://brightadvisers.com/post/master-incentive-stock-options-exercise-planning-for-your-family)
- Incentive Stock Options Tax Planning Opportunities – GHJ (https://ghjadvisors.com/ghj-insights/incentive-stock-options-tax-planning-opportunities-and-pitfalls)
- Explain the Vesting Process of Incentive Stock Options
- Stock Option Vesting Schedules Explained: Types, Examples, and Key Strategies — Secfi (https://secfi.com/learn/stock-option-vesting-schedule)
- Vesting Schedules: What is vesting and how does it work (https://ledgy.com/blog/vesting-schedules)
- NAPP | Rethinking Four-Year Vesting (https://naspp.com/blog/rethinking-four-year-vesting)
- Stock Options 101: The Essentials | Morgan Stanley at Work (https://morganstanley.com/atwork/employees/learning-center/articles/stock-options-101)
- Equilar: Empowering Strategic HR Leaders (https://equilar.com/reports/3-equity-vesting-schedules.html)
- Discuss Tax Implications of ISOs During Vesting and Exercise
- How Stock Options Are Taxed: ISO vs NSO Tax Treatments (https://carta.com/learn/equity/stock-options/taxes)
- Stifel: Michigan Region (https://stifelmichiganregion.com/tax-consequences-of-isos.htm)
- Alternative Minimum Tax (AMT): How It Works for Stock Options in 2026 (https://esofund.com/blog/alternative-minimum-tax-amt)
- Tax Considerations for Incentive Stock Options: AMT Implications and Planning Framework – Morse (https://morse.law/news/tax-considerations-for-incentive-stock-options)
- Outline Strategies for Maximizing Incentive Stock Options Benefits
- Top Strategies for Managing Incentive Stock Options (https://abovethecanopy.us/top-strategies-for-managing-incentive-stock-options)
- 3 Strategies To Optimize Incentive Stock Options (ISOs) (https://kitces.com/blog/incentive-stock-options-iso-amt-financial-plan-taxes-portfolio)
- Incentive Stock Options Explained (https://marinerwealthadvisors.com/insights/incentive-stock-options-explained)
- 4 Strategies to Exercise Your Incentive Stock Options (https://zajacgrp.com/insights/4-strategies-for-exercising-your-isos-and-the-tax-impact)
- Maximizing Tax Benefits with Stock Options: A Comprehensive Guide Fusion CPA (https://fusiontaxes.com/thought-leadership/blog/maximizing-tax-benefits-with-stock-options-a-comprehensive-guide)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading