

Key Highlights
- Inheritance tax is a state-level tax on inherited assets, with varying rates based on the relationship to the deceased.
- In 2026, the federal estate exemption is set at $15 million per individual, reducing concerns about federal estate taxes for many families.
- States like New Jersey and Pennsylvania impose inheritance taxes, with rates as high as 16%, complicating financial planning.
- Wedding gifts are generally tax-free for recipients, but gifts exceeding $19,000 per recipient in 2026 may incur tax implications.
- Married couples can gift up to $38,000 together for wedding gifts without tax concerns.
- Contributions for educational or medical expenses are exempt from taxation, allowing for greater support.
- Gifting strategies can help reduce taxable estates and teach children financial responsibility.
- Establishing trusts can provide control over asset distribution and reduce estate taxes.
- 529 plans offer tax-free growth for educational expenses, with significant withdrawal benefits starting in 2026.
- Intra-family loans allow parents to support children at low-interest rates while teaching financial accountability.
Introduction
Many parents feel overwhelmed by the complexities of inheritance tax and wedding gifts as they navigate their financial futures. It’s important to understand that different state laws and tax implications can make preserving wealth for your children feel like a high-stakes game. In this article, we’ll explore the key points about inheritance tax and the tax-free limits on wedding gifts, helping families find ways to manage their wealth with confidence. Let’s consider how parents can share their love during important moments, like weddings, without facing unexpected financial stress.
Clarify Inheritance Tax and Wedding Gift Basics
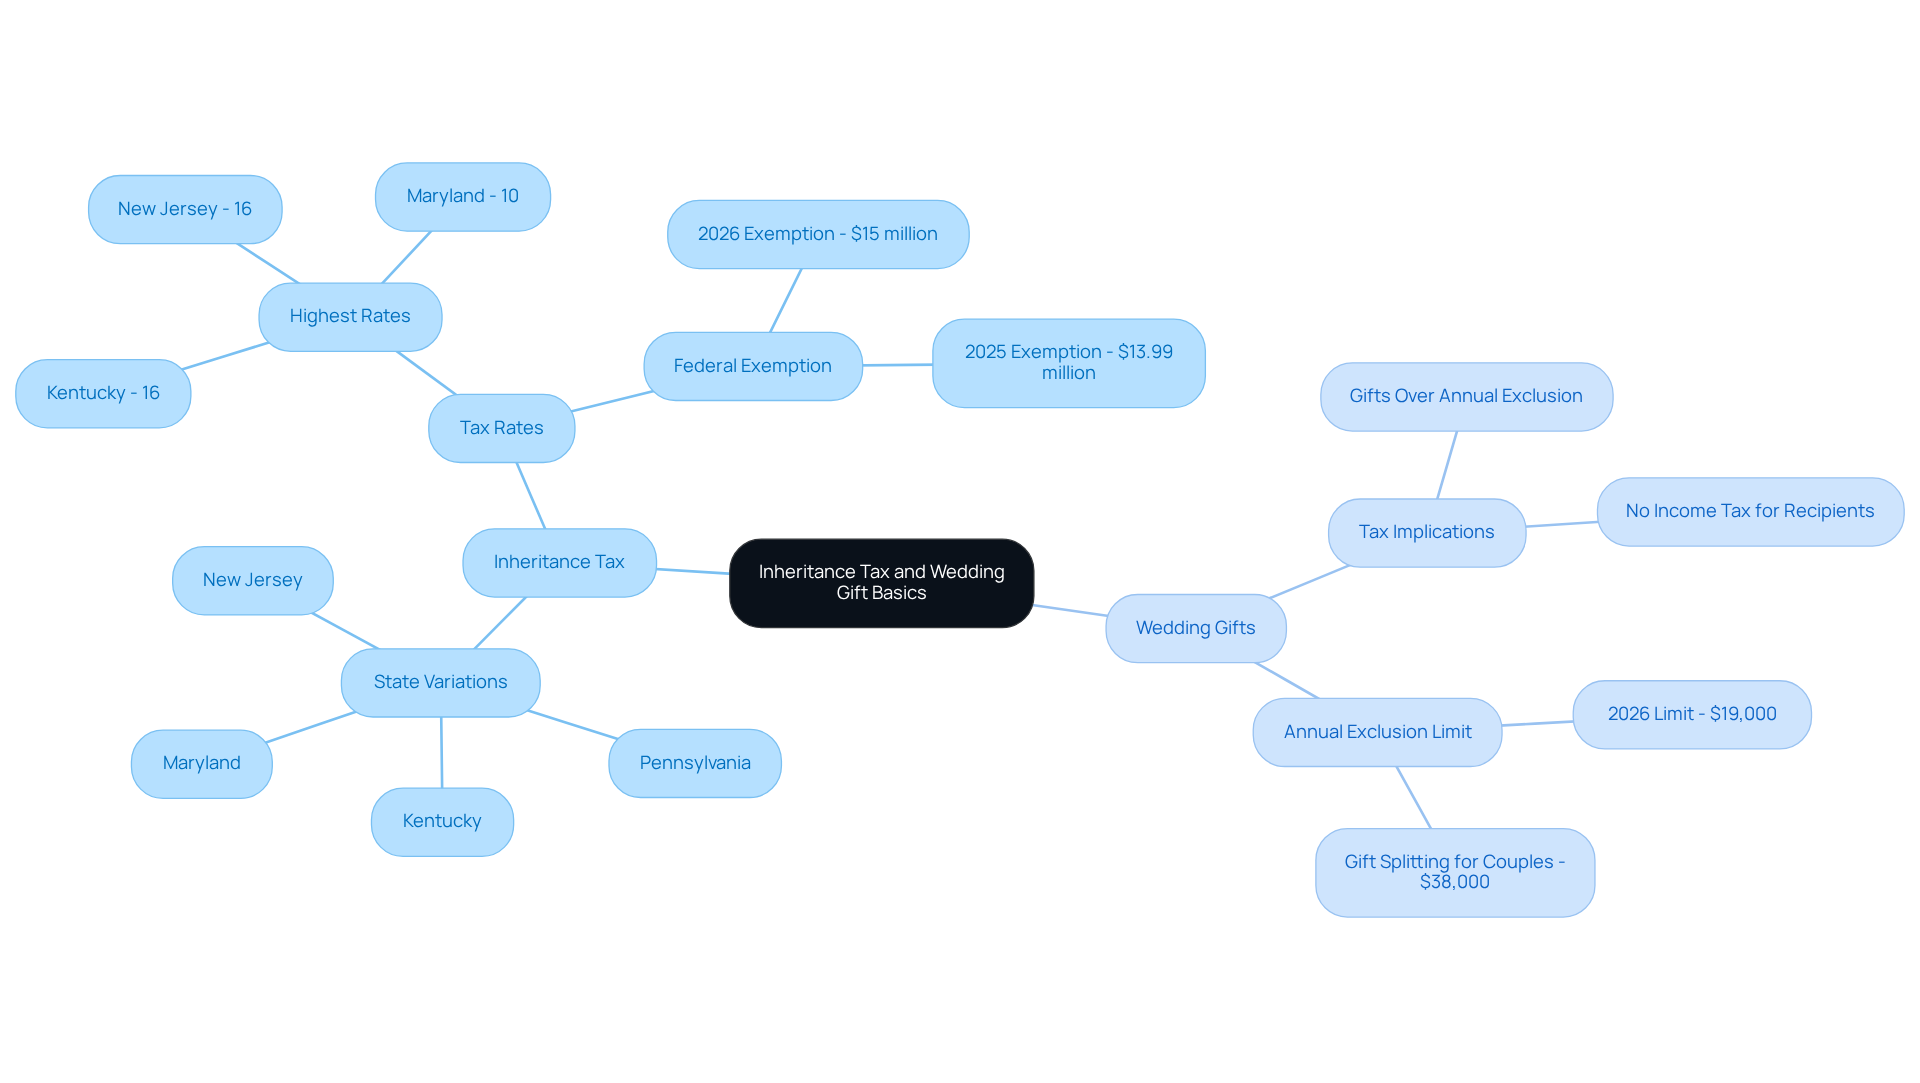
Imagine facing unexpected financial burdens when planning for your family’s future – this is the reality of inheritance taxes for many young parents. Inheritance tax is a state-level tax on the value of assets inherited from a deceased individual. While there’s no federal inheritance tax, some states, like New Jersey and Pennsylvania, do impose this tax, and rates can vary significantly based on your relationship to the deceased. For instance, children often face lower rates compared to more distant relatives. It’s important to understand these nuances so you can navigate your family’s financial future with confidence and care.
In 2026, families can breathe a little easier with the federal estate exemption set at $15 million per individual, meaning many won’t have to worry about federal estate taxes. But it’s essential to be aware of state-specific inheritance tax rates, as they can create unexpected financial burdens for your family. For example, Kentucky and New Jersey have the highest inheritance tax rates at 16%, while Maryland imposes both estate and inheritance taxes, complicating financial planning for residents.
On a brighter note, wedding presents usually come with no income tax for recipients, which can be a relief for parents wanting to support their children on their special day, unlike the implications of an inheritance tax wedding gift. However, if the amount exceeds the annual exclusion limit of $19,000 per recipient in 2026, the donor must consider the implications of the inheritance tax wedding gift. This means you can generously support your children on their wedding day without worrying about tax obligations, as long as you stay within the limits. By understanding these nuances, you can protect your family’s future and ensure that your legacy is a source of support, not stress.
Explore Tax-Free Gifting Limits for Wedding Gifts
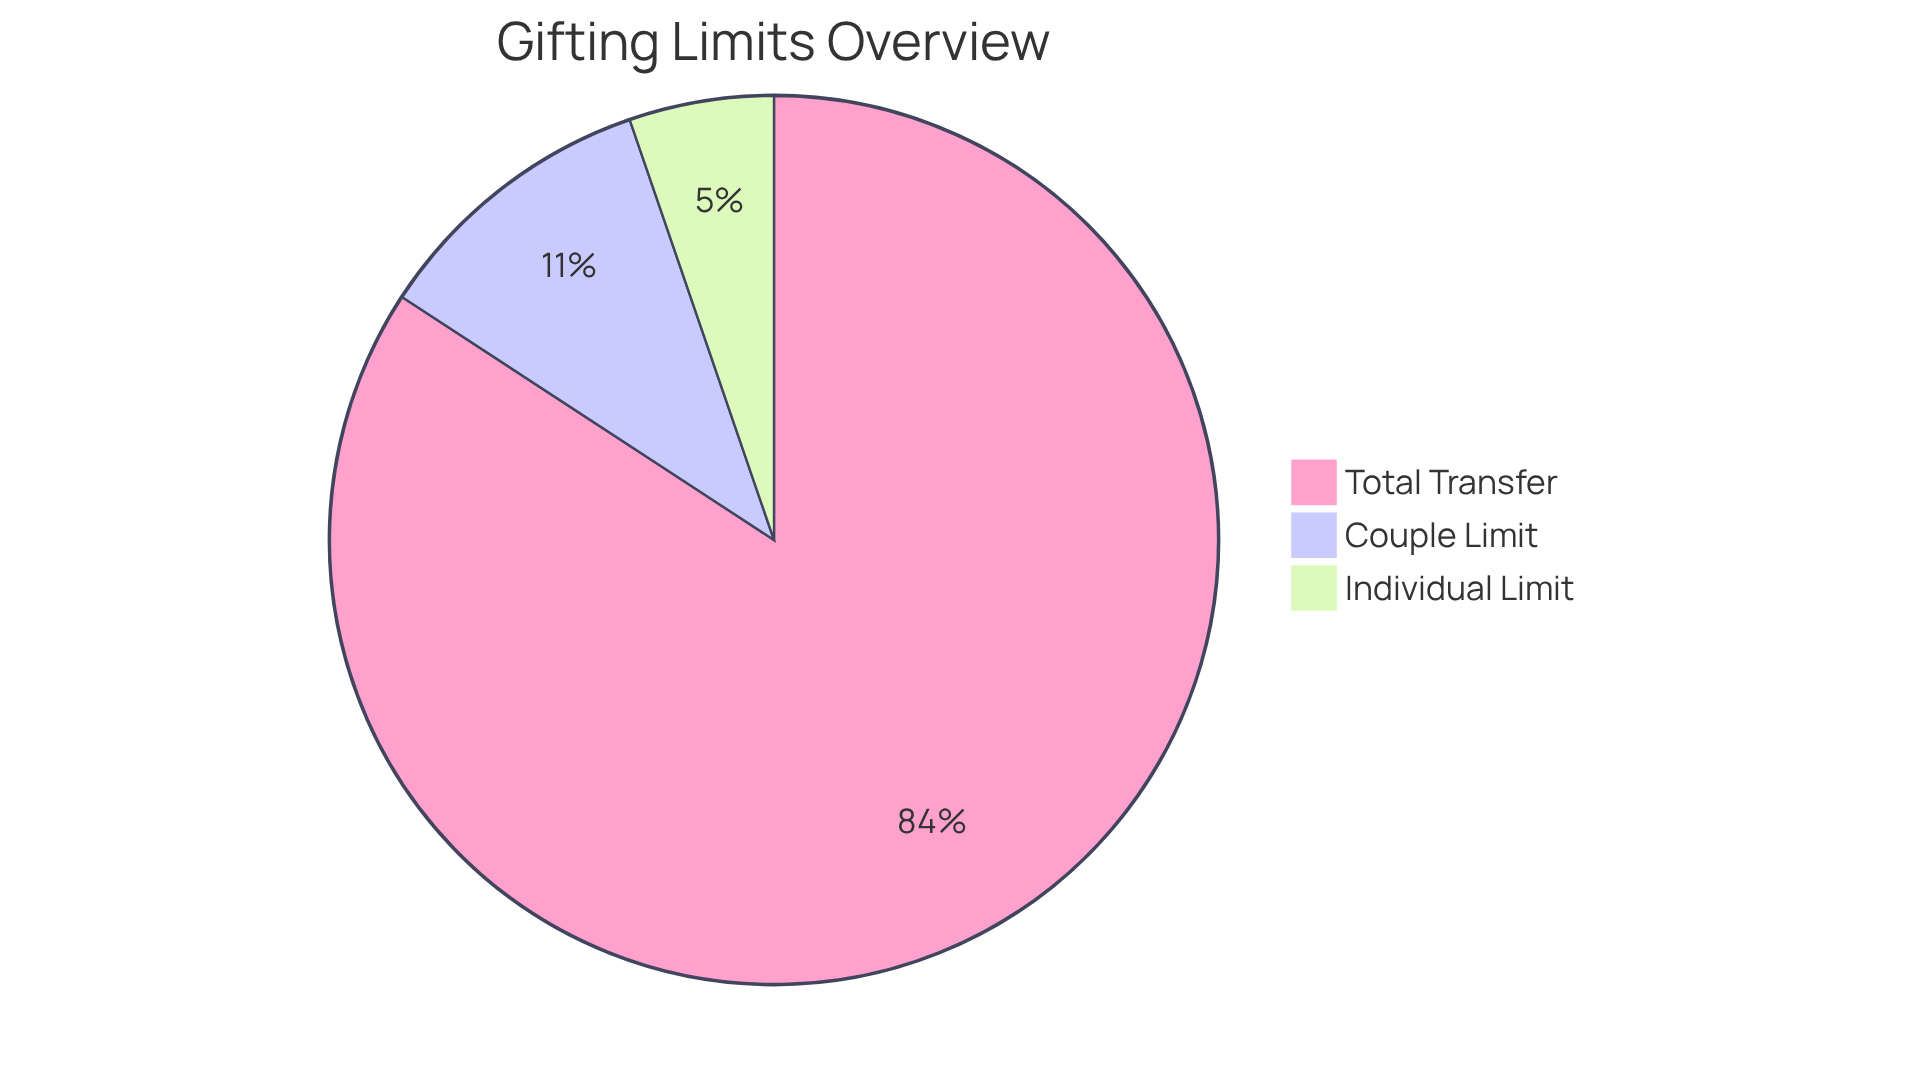
Imagine the joy of supporting your child’s wedding as an inheritance tax wedding gift without the worry of tax implications. In 2026, the IRS allows individuals to give up to $19,000 per recipient without incurring tax on the transfer. For married couples, this limit effectively doubles to $38,000 when both spouses contribute. If you and your partner want to help with your child’s wedding, you can give them up to $38,000 together as an inheritance tax wedding gift, without worrying about taxes.
Additionally, contributions made directly for educational costs or medical expenses are exempt from taxation, enabling even greater support. Understanding these limits not only aids in financial planning but also ensures that families can provide significant help during major life events, free from the anxiety of tax consequences.
For instance, a married couple with three children can transfer a total of $304,000 in 2026 to their descendants without using their combined $30 million gift tax exemption. This thoughtful way of giving not only helps your loved ones during special moments but also lightens the financial load for your family. By understanding these gifting strategies, you can focus on celebrating life’s milestones with your loved ones, free from financial stress.
Leverage Gifting as a Wealth Management Strategy
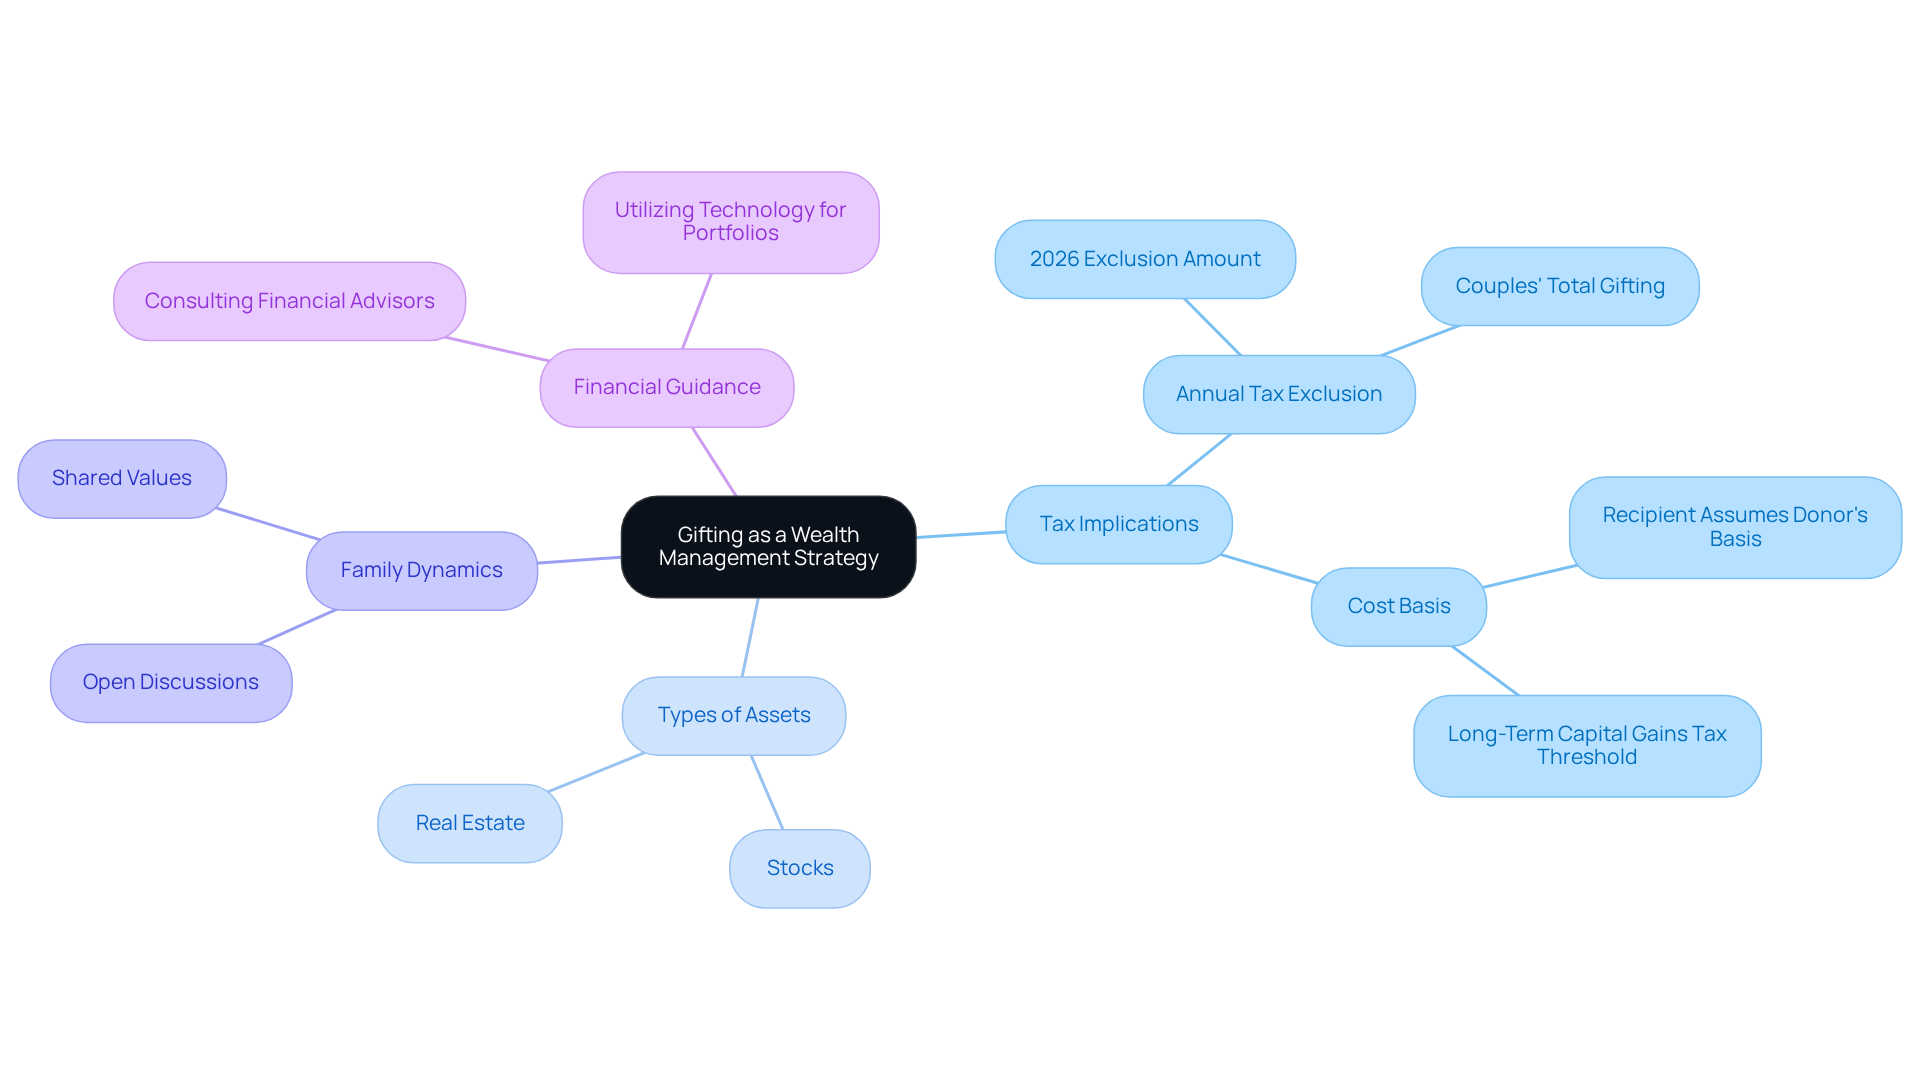
Imagine feeling empowered to pass on your hard-earned wealth to your children without the worry of tax implications. Gifting can be a wonderful way for families like Emily and Mark to share their financial journey with their children while working with Bright Advisers to find freedom in their finances. Parents can take advantage of the annual tax exclusion of $19,000 per recipient in 2026, allowing them to pass on wealth to their children while keeping tax implications low. For instance, a couple can gift a total of $38,000 to each child without incurring gift tax, effectively reducing their taxable estate over time without affecting their estate tax exemption.
Imagine gifting something meaningful, like stocks or real estate, which can bring even more benefits to your family. When these assets are gifted, the recipient assumes the donor’s cost basis, which can lead to substantial tax savings if the asset appreciates in value. For example, if a child sells gifted stock with a long-term gain, they may avoid long-term capital gains taxes if their Adjusted Gross Income (AGI) remains below $44,625, a threshold that applies to single filers in 2023.
When you weave gifting into your family’s financial plan, it not only helps pass on wealth but also teaches your children the importance of managing money responsibly. Emily and Mark’s experience shows that families who openly discuss their intentions about contributions can strengthen their connections and align their resources with shared values, enhancing the overall purpose of wealth within the household.
As you navigate the journey of passing on your wealth, reaching out to financial advisors and tax specialists can make all the difference. Bright Advisers provides guidance to structure gifts effectively, ensuring compliance with tax regulations and maximizing the impact of your generosity. Their innovative in-house technology supports the creation of hyper-personalized portfolios, avoiding expensive mutual funds and enhancing investment efficiency. By utilizing these strategies, households can secure their futures while alleviating anxiety surrounding financial planning. With the right guidance, you can transform financial anxiety into a legacy of love and responsibility for your family.
Consider Alternatives to Direct Gifting
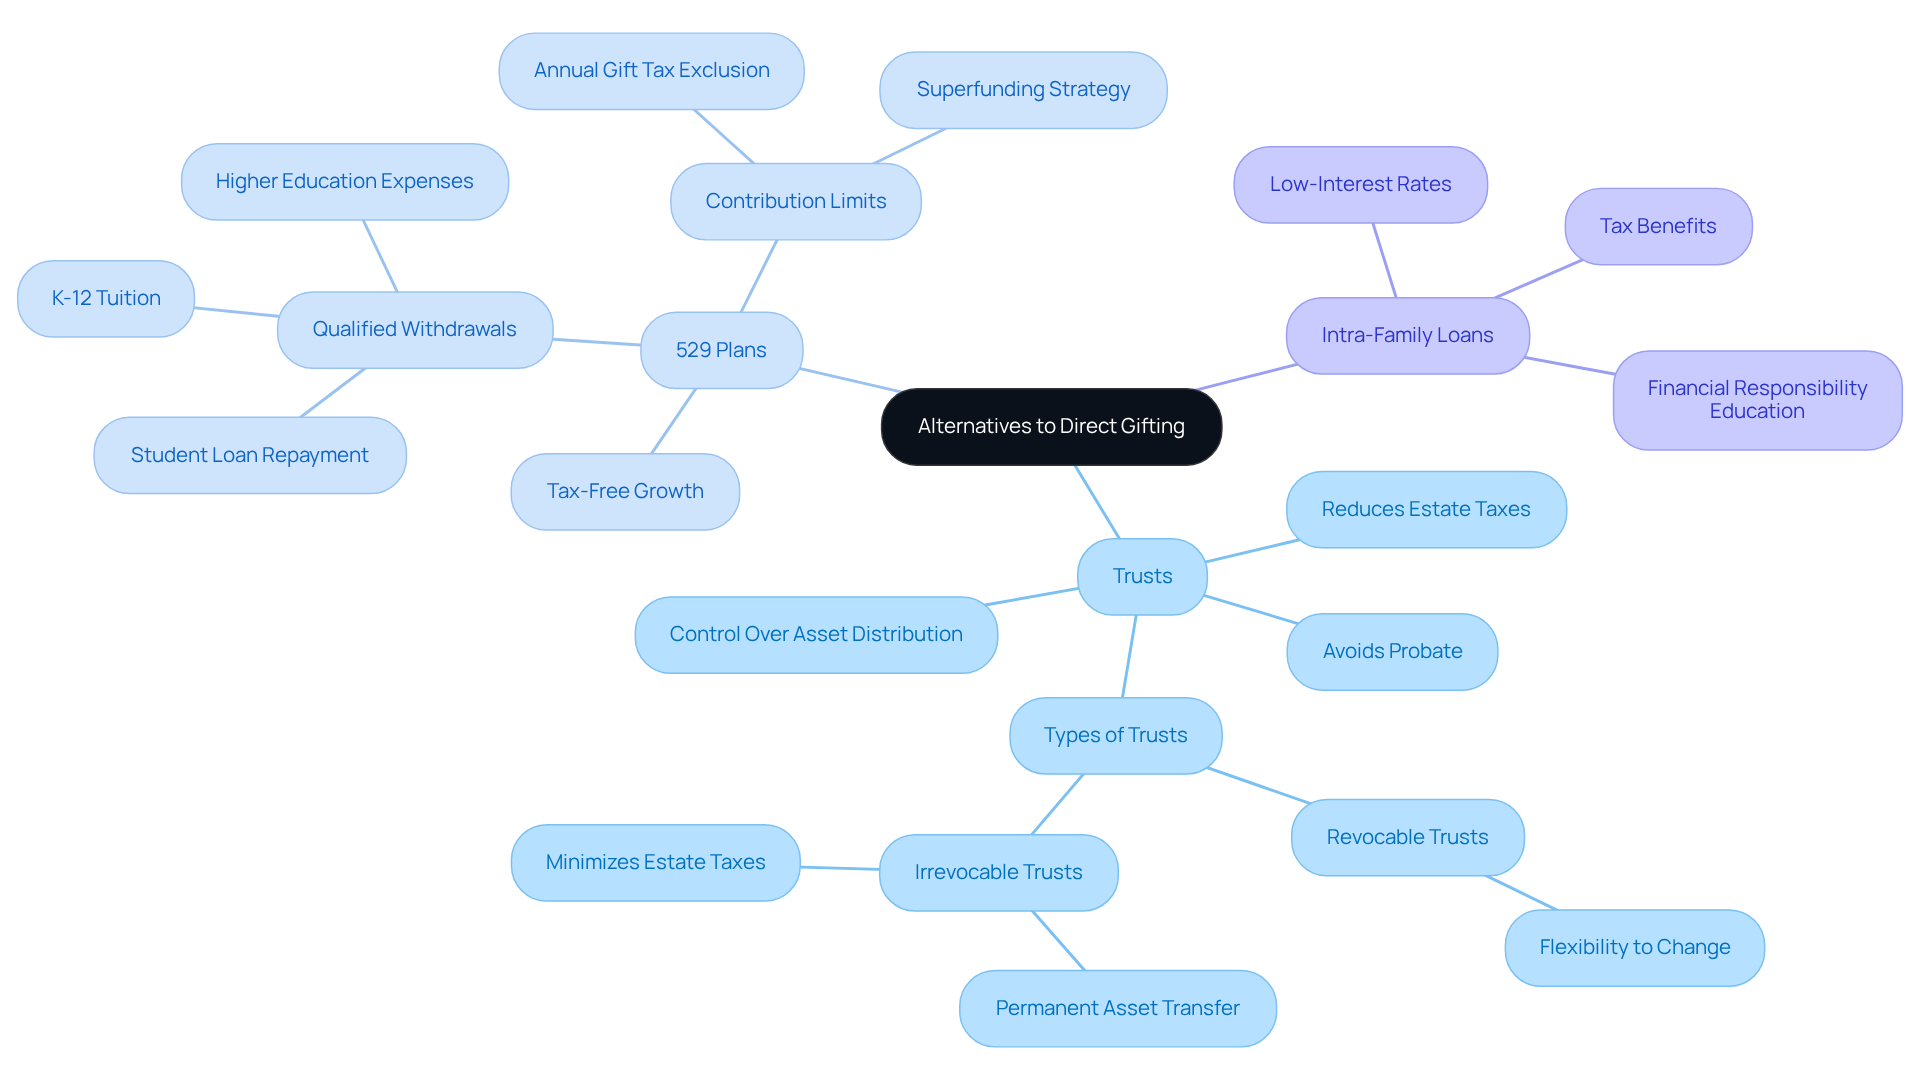
Navigating the world of wealth transfer can feel daunting for young parents. Instead of direct gifting, consider alternatives that offer more control and tax benefits.
Imagine having the power to decide how and when your hard-earned assets are shared with your loved ones. Establishing a trust can give you that control. Trusts not only help avoid probate, ensuring a smoother transition of assets, but they can also reduce estate taxes. This aligns perfectly with Bright Advisers’ mission to support families in making wise wealth choices and preserving their assets for future generations.
Another option to consider is a 529 plan for educational expenses. Contributions to these plans grow tax-free and can be withdrawn without penalties for qualified education costs. Starting in 2026, families can withdraw up to $20,000 annually for K-12 tuition and other qualified educational expenses. This makes 529 plans a fantastic way to support your children’s education while enjoying significant tax advantages. Plus, families can withdraw up to $10,000 to pay for qualified education loans for the beneficiary or their siblings, enhancing the utility of these plans even further.
Intra-family loans are another viable option. Parents can lend money to their children at low-interest rates, providing support while benefiting from favorable tax treatment. This approach not only improves wealth management but also teaches children about financial responsibility and accountability, preparing them for future monetary challenges.
By embracing these strategies, families can confidently pave the way for a secure financial future, ensuring their values and dreams are passed down through generations.
Conclusion
Many parents feel overwhelmed by the complexities of inheritance tax and wedding gifts, but understanding them is key to securing your family’s financial future. By grasping the differences between these two financial aspects, you can navigate potential pitfalls and make informed decisions that truly benefit your loved ones.
It’s important to recognize the varying state-level inheritance tax rates and the generous tax-free gifting limits for wedding gifts. These insights can help you see how proactive financial planning ensures that gifts and inheritances serve as a source of support rather than stress.
Imagine the peace of mind that comes from knowing your children are prepared for their financial future. You can take advantage of annual exclusion limits and explore alternatives to direct gifting, such as trusts and 529 plans, to maximize your financial impact while minimizing tax implications. These strategies not only facilitate wealth transfer but also instill financial responsibility in the next generation.
Ultimately, managing your family’s wealth is about creating a legacy filled with love and support for your children and their future. Engaging with financial advisors like Bright Advisers can provide the necessary guidance to navigate these complexities, ensuring that you can confidently pass on your values and resources. Taking these steps can turn financial anxiety into a nurturing environment where your children can thrive.
Frequently Asked Questions
What is inheritance tax?
Inheritance tax is a state-level tax imposed on the value of assets inherited from a deceased individual. While there is no federal inheritance tax, some states, such as New Jersey and Pennsylvania, do have this tax.
How do inheritance tax rates vary?
Inheritance tax rates can vary significantly based on your relationship to the deceased. For example, children typically face lower rates compared to more distant relatives.
What is the federal estate exemption for 2026?
In 2026, the federal estate exemption is set at $15 million per individual, meaning many families will not have to worry about federal estate taxes.
Which states have the highest inheritance tax rates?
Kentucky and New Jersey have the highest inheritance tax rates at 16%. Additionally, Maryland imposes both estate and inheritance taxes, complicating financial planning for its residents.
Are wedding gifts subject to income tax?
Wedding presents typically do not incur income tax for recipients, which can be beneficial for parents supporting their children on their wedding day.
What are the tax implications of giving a wedding gift that exceeds the annual exclusion limit?
If a wedding gift exceeds the annual exclusion limit of $19,000 per recipient in 2026, the donor must consider the implications of the inheritance tax on that gift.
How can understanding inheritance tax and wedding gift regulations help families?
By understanding these nuances, families can better protect their financial future and ensure that their legacy serves as a source of support rather than stress.
List of Sources
- Clarify Inheritance Tax and Wedding Gift Basics
- Estate tax vs. inheritance tax: Who pays & in which states? (https://thrivent.com/insights/estate-planning/estate-tax-vs-inheritance-tax-who-pays-and-in-which-states)
- Federal estate tax and gift tax limits announced for 2026 (https://agproud.com/articles/62714-federal-estate-tax-and-gift-tax-limits-announced-for-2026)
- Estate and Inheritance Taxes by State (https://taxfoundation.org/data/all/state/estate-inheritance-taxes)
- Annual Gift Tax and Estate Tax Exemptions for 2026 – McClelland Law Firm. P.A. (https://mcclellandfirm.com/annual-gift-tax-and-estate-tax-exemptions-for-2026)
- What is the estate tax exemption? | Fidelity (https://fidelity.com/learning-center/personal-finance/what-is-the-estate-tax-exemption)
- Explore Tax-Free Gifting Limits for Wedding Gifts
- Nelson Mullins – 2026 Estate and Gift Tax Update (https://nelsonmullins.com/insights/blogs/tax-reports/all/2026-estate-and-gift-tax-update)
- 2026 Gift Tax Exclusions (https://farmoffice.osu.edu/blog/tue-02172026-710pm/2026-gift-tax-exclusions)
- How Much Money Can You Gift Tax-Free? (2025) | Western Union US (https://westernunion.com/blog/en/us/how-much-money-can-gift-tax-free)
- What is the Annual Gift Tax Exclusion Limit for 2026? (https://adamsbrowncpa.com/blog/what-is-the-annual-gift-tax-exclusion-limit-for-2026)
- IRS Announces Increased Gift and Estate Tax Exemption Amounts for 2026 (https://morganlewis.com/pubs/2025/10/irs-announces-increased-gift-and-estate-tax-exemption-amounts-for-2026)
- Leverage Gifting as a Wealth Management Strategy
- Want a Little-Known Tax Secret? Learn the Benefits of the Annual Gift Tax Exclusion (https://wealthenhancement.com/blog/learn-the-benefits-of-the-annual-gift-tax-exclusion)
- Tax-Smart Ways to Gift Highly Appreciated Assets (https://schwab.com/learn/story/tax-smart-ways-to-gift-highly-appreciated-assets)
- The Gift of Wealth: How to Thoughtfully Share Financial Blessings with Family (https://tfowealth.com/gift-of-wealth)
- Gifting strategies | Estate tax and annual gifting| Fidelity Investments (https://fidelity.com/learning-center/wealth-management-insights/gift-and-estate-tax-changes)
- Gifting: 7 mistakes that could cost you (https://comerica.com/insights/wealth-management/wealth-preservation/gifting-mistakes.html)
- Consider Alternatives to Direct Gifting
- Potential Benefits of a Trust | U.S. Bank (https://usbank.com/wealth-management/financial-perspectives/trust-and-estate-planning/benefits-of-setting-up-a-trust.html)
- What Is a 529 Account? How It Works and Tax Rules (https://schwab.com/learn/story/saving-college-529-college-savings-plans)
- Are 529 contributions tax deductible? | 529 tax benefits | Fidelity (https://fidelity.com/learning-center/smart-money/529-contribution-deduction)
- Benefits of a Trust: The Key Role of Personal Trusts (https://ml.com/solutions/the-role-of-trusts.html)
- Tax Benefits of a 529 Plan | Learn (https://invest529.com/529-basics/tax-benefits)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading