

Key Highlights
- An Initial Public Offering (IPO) can create financial opportunities for families, enhancing their connexion to the market.
- Families should be aware of IPO tax implications, especially regarding equity compensation like stock options and Restricted Stock Units (RSUs).
- When RSUs vest, they incur ordinary income tax, and selling them can lead to capital gains tax based on the holding period.
- Effective tax planning strategies include timing of sales, gifting strategies, tax-loss harvesting, and charitable contributions to manage tax liabilities.
- Families must consider risks such as market volatility, potential tax bracket changes, liquidity issues, and state tax implications when engaging with IPOs.
- Proactive management and consultation with financial advisors can help families navigate the complexities of IPOs and equity compensation.
Introduction
Imagine facing unexpected tax bills just when you thought you were making progress in your family’s financial journey. Understanding the intricacies of an Initial Public Offering (IPO) can be a game-changer for families, especially when it comes to managing their financial future. As companies transition to public status, they often present unique opportunities for wealth creation. But with these opportunities come complex tax implications that can catch families off guard.
Together, we can explore the essential tax strategies that will help your family navigate these waters with confidence. How can families tackle these challenges while maximizing the benefits of an IPO? With the right guidance, you can turn the complexities of an IPO into a stepping stone for your family’s financial future.
Define IPO and Its Importance for Families
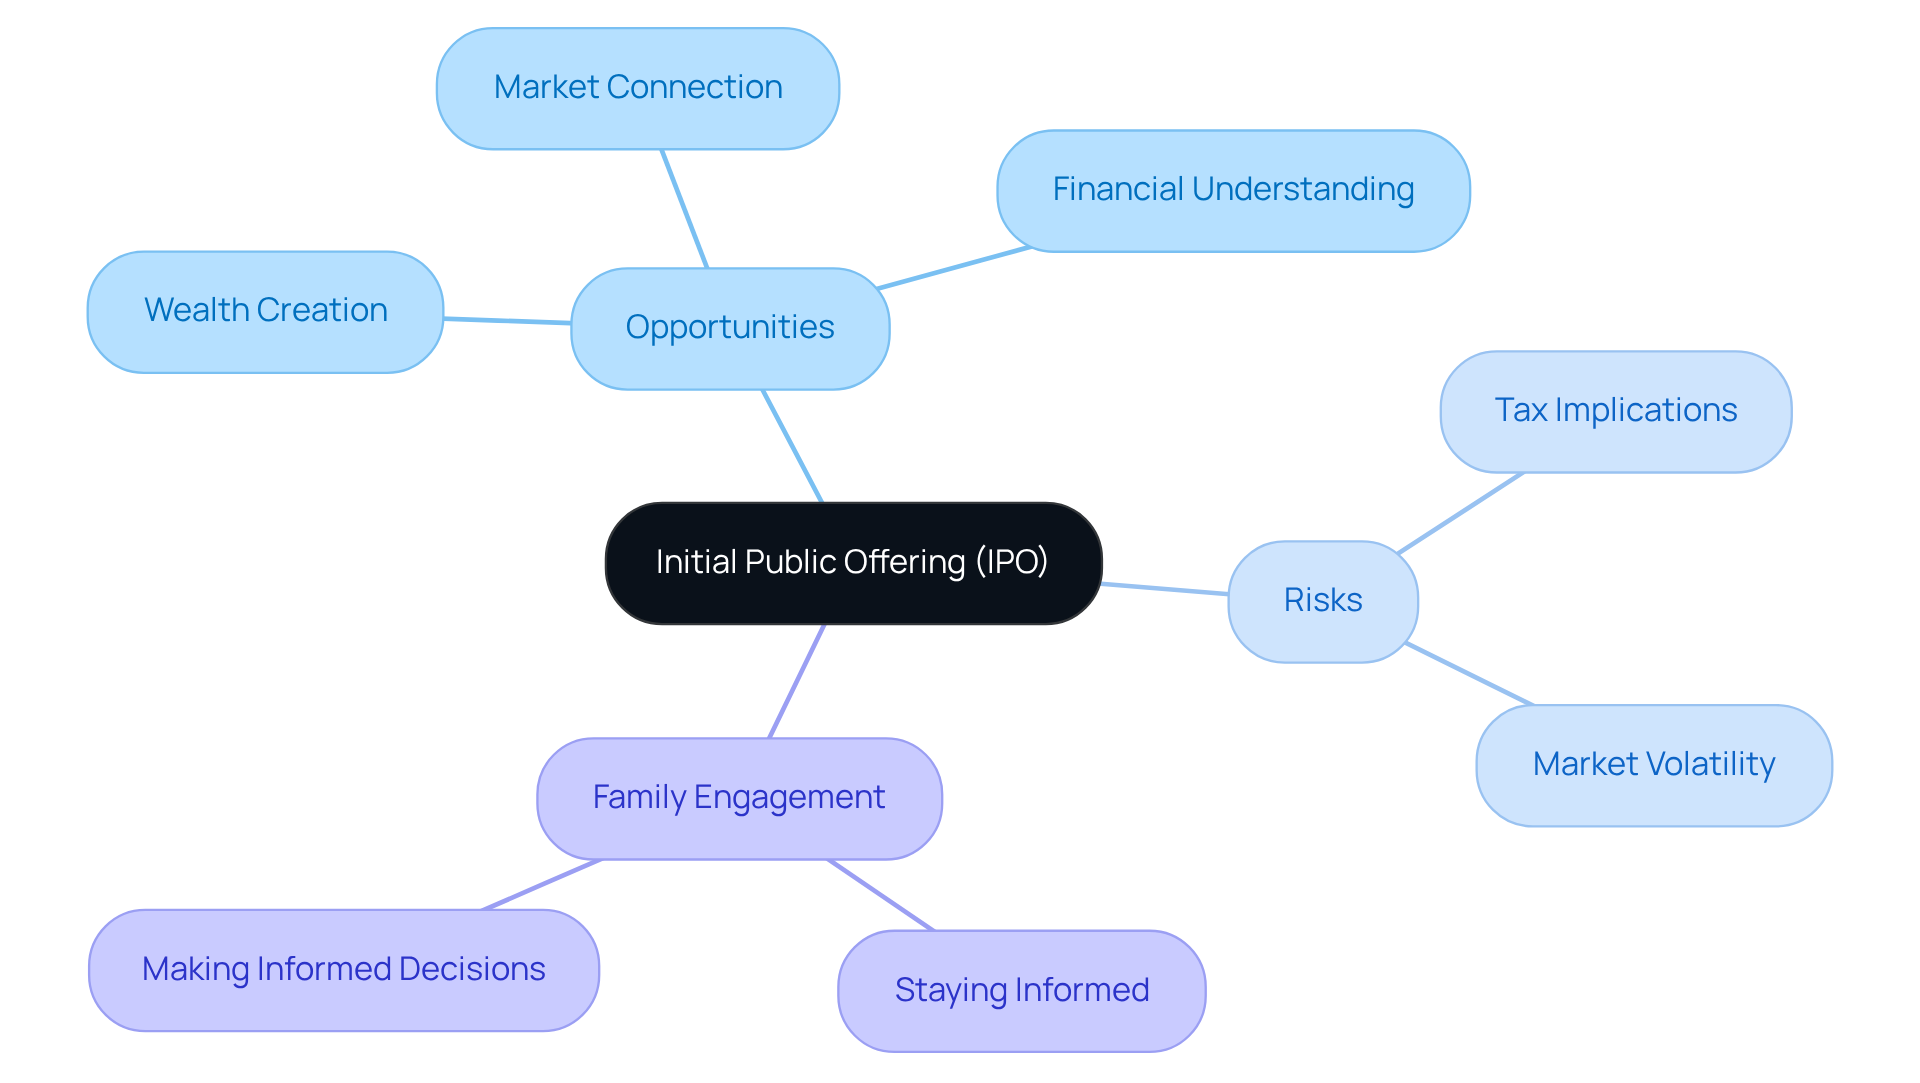
Imagine the excitement of a company you believe in going public for the first time – what does that mean for your family? An Initial Public Offering (IPO) can create opportunities that impact your financial journey in meaningful ways. This moment helps the company grow and can create exciting opportunities for you as a parent.
While this can open doors to wealth, it’s also important to be aware of the IPO tax implications and risks involved. When families engage with IPOs, they often feel more connected to the market, which can enhance their financial understanding and participation.
Recognizing the importance of IPOs helps families prepare for the financial changes ahead, allowing them to make informed decisions that support their goals. Families who stay engaged with IPO opportunities often find it easier to manage their wealth, making it vital to keep up with these developments. By staying informed about IPOs, you can turn potential challenges into opportunities for your family’s financial future.
Explore Tax Implications of Equity Compensation
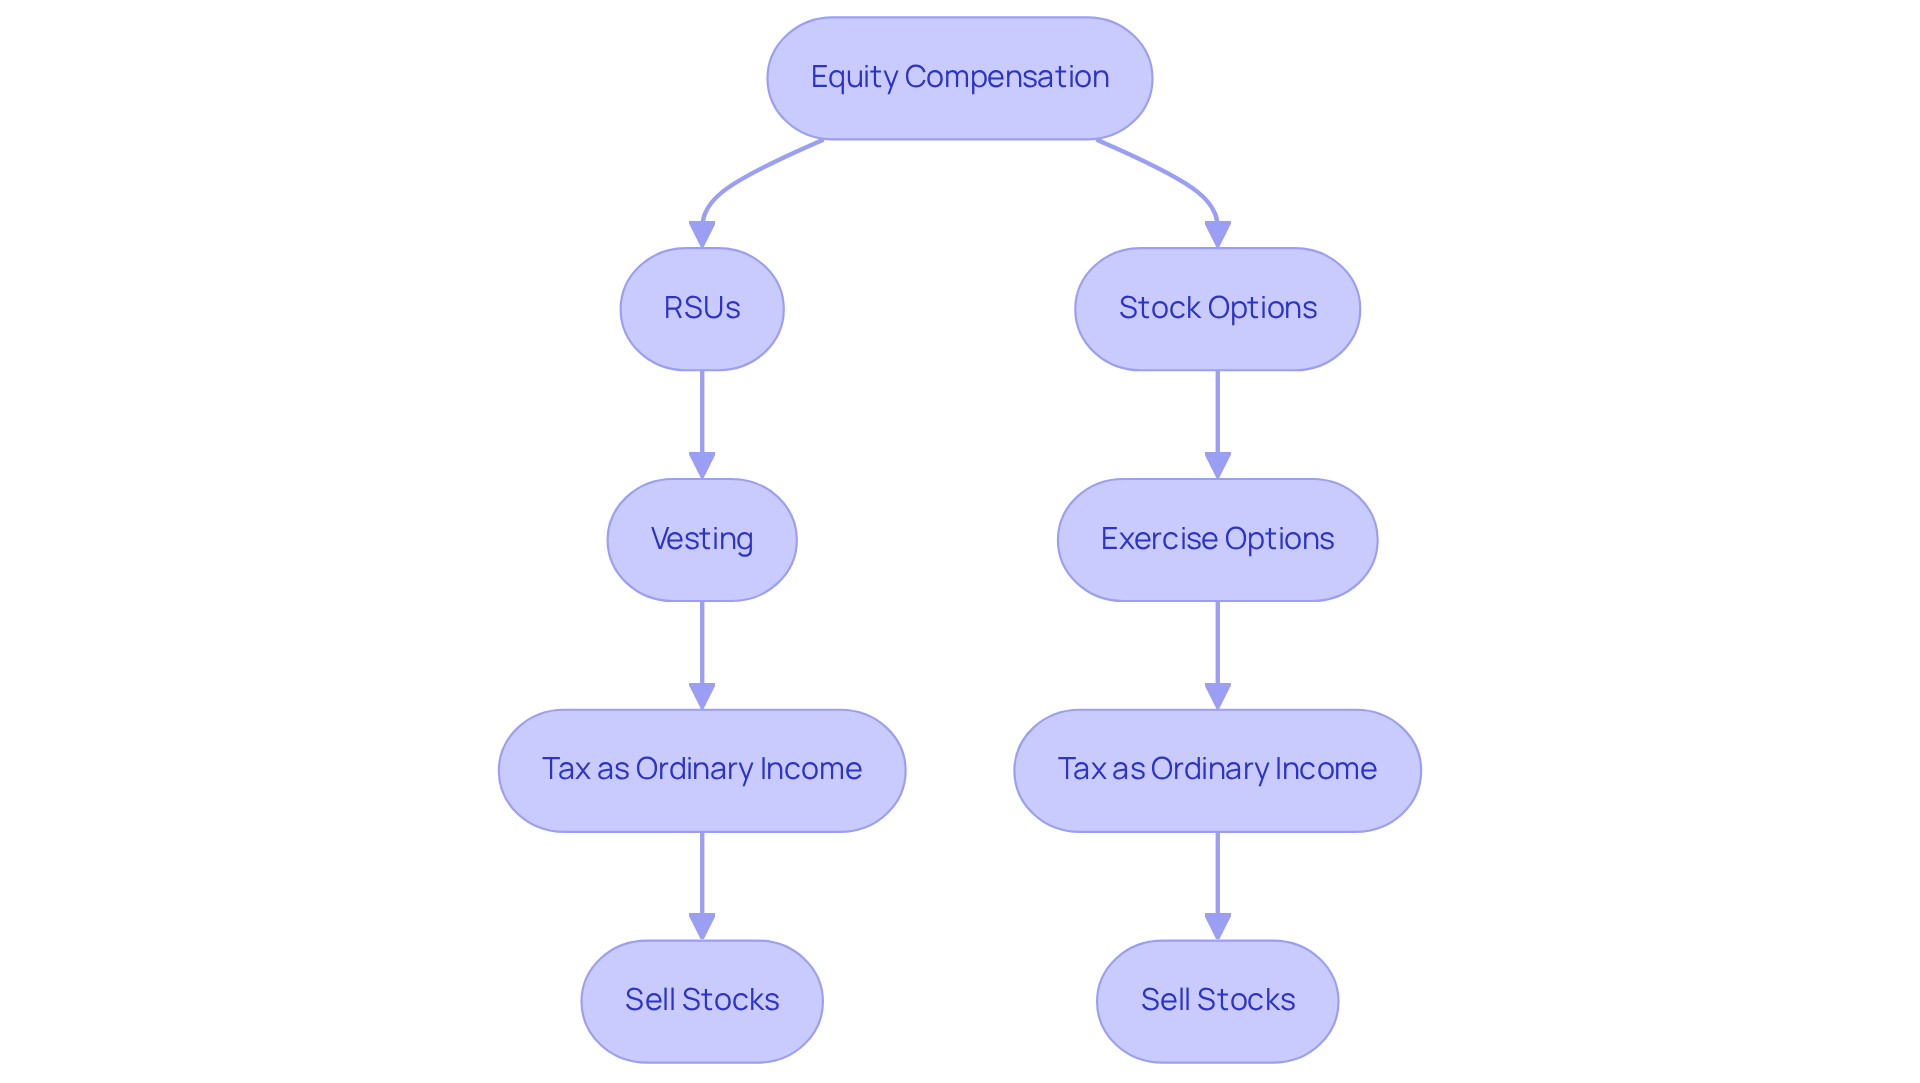
Imagine the surprise of receiving a hefty tax bill just when you thought you were on solid financial ground. When a company goes public, employees may receive equity compensation in the form of stock options or Restricted Stock Units (RSUs). Understanding the IPO tax implications can feel overwhelming, especially when you’re focused on your family’s future.
When RSUs vest or stock options are exercised, employees typically incur ordinary income tax. For instance, if you receive 1,000 RSUs that vest at the time of an IPO, the fair market value of those units at vesting is taxed as ordinary income. If you sell those stocks right away, any profit will be subject to capital gains tax, which varies based on how long you hold onto them. Short-term capital gains apply if you sell within a year, while long-term capital gains apply if you hold them for over a year, usually resulting in a lower tax rate. It’s crucial for families to stay informed about the IPO tax implications, so they can avoid surprises that could disrupt their financial peace of mind.
Consider this: employees receiving RSUs are taxed at vesting, with no option for a Section 83(b) election. This means you can’t lock in a lower tax basis before stock appreciation, which can lead to significant IPO tax implications if a large block of shares vests in a single year. Understanding the timing and conditions for selling RSUs is essential for accessing liquidity and managing investments effectively.
With proactive management of equity compensation, families can navigate these challenges and reduce tax liabilities. With the right guidance, you can turn these challenges into opportunities for your family’s financial growth.
Implement Effective Tax Planning Strategies
Imagine navigating the complexities of ipo tax implications while trying to prioritize your family’s future. Here are some strategies to consider:
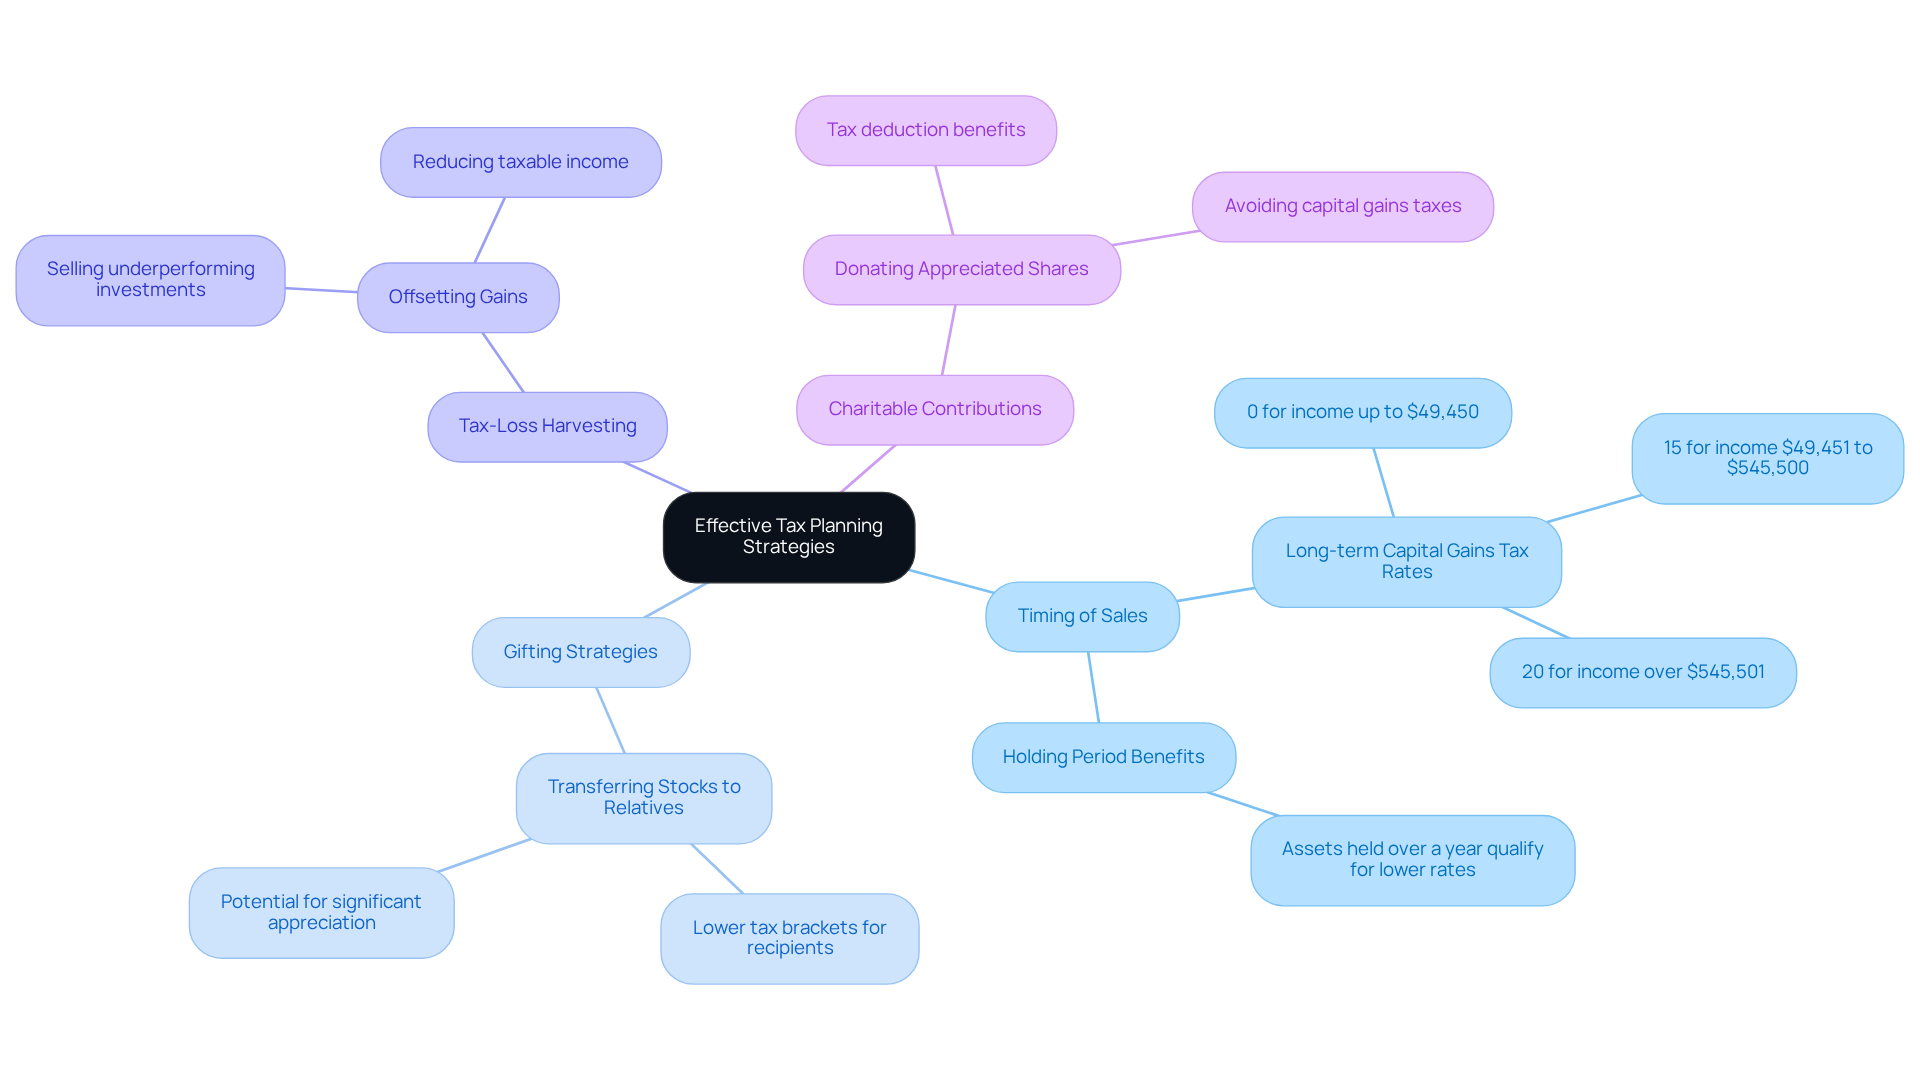
- Timing of Sales: Planning when to sell stocks is crucial. Holding investments for over a year allows families to benefit from long-term capital gains tax rates, which can significantly lessen tax obligations. For instance, in 2026, long-term capital gains tax rates for single filers are 0% for income up to $49,450, 15% for income between $49,451 and $545,500, and 20% for income over $545,501.
- Gifting Strategies: Have you thought about giving stocks to relatives in lower tax brackets? This approach can reduce overall tax exposure, especially if the assets are expected to appreciate significantly. By transferring ownership stakes, families can take advantage of the lower tax rates applicable to the recipients.
- Tax-Loss Harvesting: If certain investments aren’t performing well, selling them at a loss can offset gains from IPO equities, reducing taxable income. This strategy helps families balance their portfolios while effectively managing their ipo tax implications.
- Charitable Contributions: Donating appreciated shares to charity not only provides a tax deduction but also avoids capital gains taxes on the donated amount. This strategy can be especially beneficial for families looking to support causes they care about while managing their tax responsibilities.
With these strategies, you can confidently embrace your financial journey, knowing that support is available every step of the way.
Identify Risks and Considerations in IPO Tax Planning
Imagine the excitement of an IPO, but also the concerns about the ipo tax implications for your family’s financial future. While IPOs can present significant financial opportunities, they also come with risks that families must consider:
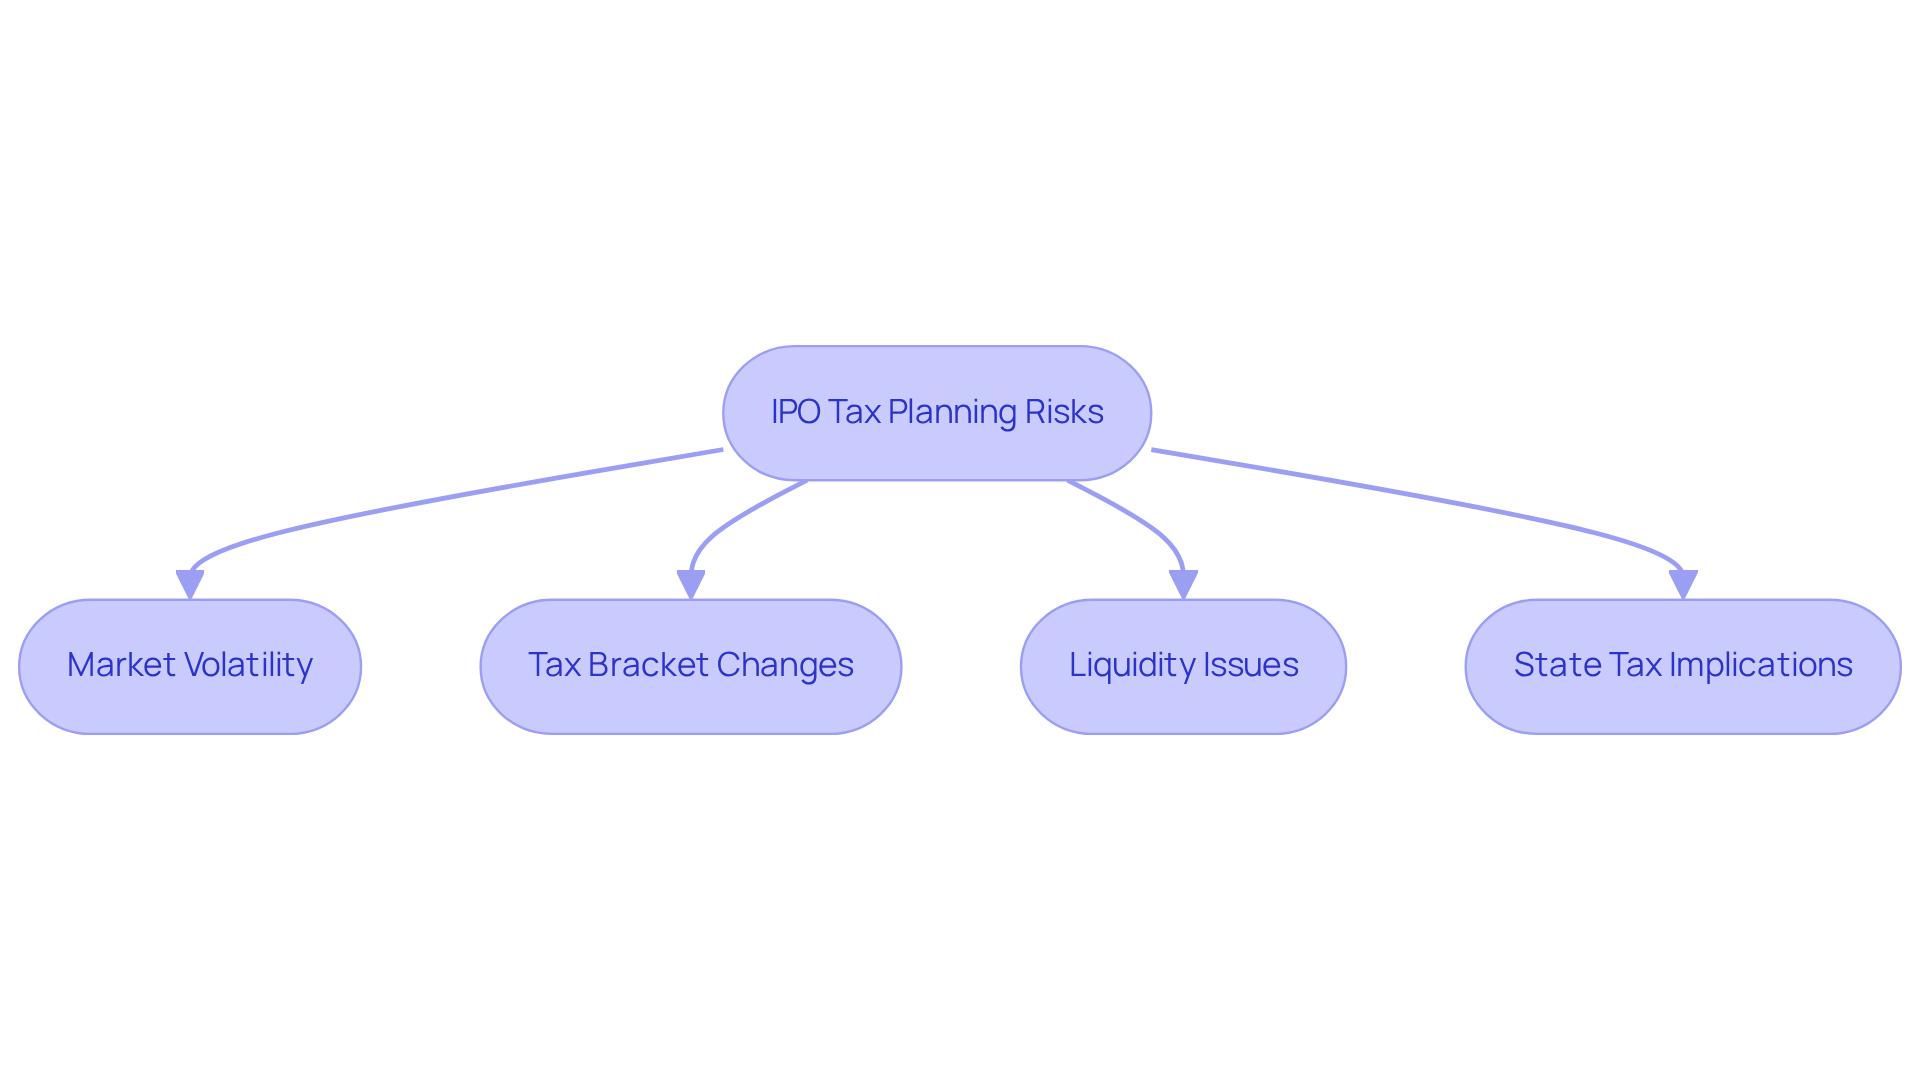
- Market Volatility: Imagine the stock price of a newly public company swinging wildly, leaving you worried about your family’s financial stability. Families should be prepared for fluctuations in their net worth, especially since the average IPO proceeds for U.S. issuers in 2025 reached $266.4 million, highlighting the potential for substantial gains or losses.
- Tax Bracket Changes: Think about how the sudden income from stock options and the ipo tax implications could unexpectedly push your family into a higher tax bracket, resulting in a larger tax bill than you anticipated. In 2025, the median IPO proceeds were $100.3 million, which could significantly impact your household’s taxable income.
- Liquidity Issues: Picture this: if you don’t sell your shares in time, you might find yourself struggling to meet your family’s cash flow needs, especially if tax obligations are due shortly after the IPO. The total IPO proceeds in 2025 reached approximately $70.3 billion, indicating a robust market but also the need for careful cash management.
- State Tax Implications: If your family is considering a move, it’s crucial to understand how different state tax rules could impact your financial situation. Families should consult with tax professionals to navigate these complexities effectively, especially regarding the ipo tax implications of non-U.S. issuers that generated around $9 billion in total proceeds in 2025, which may influence state tax considerations.
By understanding these risks, you can take proactive steps to safeguard your family’s financial well-being in the face of uncertainty. For instance, families who engage with financial advisors can better manage the complexities of equity compensation and ipo tax implications, ensuring they are prepared for the financial landscape following an IPO.
Conclusion
Imagine navigating the world of IPOs with confidence, knowing how to protect your family’s financial future. When companies go public, they open doors to wealth, but they also bring tax responsibilities that families need to understand. By understanding how IPOs impact your family’s finances, you can make choices that support your dreams and goals.
We’ve explored important insights about how IPOs can affect your family’s finances, from tax implications to planning strategies. Timing your sales wisely can help you benefit from lower capital gains tax rates, while gifting strategies and tax-loss harvesting can further enhance your financial position. It’s also essential to be aware of market volatility, tax bracket changes, and liquidity issues, as these factors can influence your family’s financial well-being.
Staying informed about IPO tax implications can truly empower your family to make wise financial choices. We encourage you to reach out to financial advisors who can guide you through these complexities. By taking these steps, families can transform potential challenges into pathways for lasting financial security.
Frequently Asked Questions
What is an Initial Public Offering (IPO)?
An Initial Public Offering (IPO) is the process through which a private company offers its shares to the public for the first time, allowing it to raise capital for growth and expansion.
Why are IPOs important for families?
IPOs can create opportunities that impact a family’s financial journey by potentially increasing wealth and enhancing financial understanding and participation in the market.
What are the potential benefits of engaging with IPOs for families?
Engaging with IPOs can help families feel more connected to the market, prepare for financial changes, and make informed decisions that support their financial goals.
What should families be aware of regarding IPO tax implications?
Families should be aware that IPOs can have tax implications, which may affect their overall financial situation and should be considered when participating in such opportunities.
How can staying informed about IPOs benefit families?
Staying informed about IPOs allows families to manage their wealth more effectively and turn potential challenges into opportunities for their financial future.
List of Sources
- Define IPO and Its Importance for Families
- Local IPOs and Household Stock Market Participation (https://alphaarchitect.com/ipo)
- Impact of family ownership, management, and generations on IPO underpricing and long-run performance (https://businessperspectives.org/journals/investment-management-and-financial-innovations/issue-393/impact-of-family-ownership-management-and-generations-on-ipo-underpricing-and-long-run-performance)
- Does the IPO of local firms impact household stock market participation? Evidence from China (https://sciencedirect.com/science/article/abs/pii/S1566014126000956)
- SEC.gov | Initial Public Offerings (IPOs) (https://sec.gov/data-research/statistics-data-visualizations/initial-public-offerings-ipos)
- Explore Tax Implications of Equity Compensation
- What is an RSU? How They Work, Benefits, & Taxes (https://carta.com/learn/equity/rsu)
- How Are My RSUs Taxed, and What Can I Do to Pay Less in Taxes? (https://blog.sweeneyconrad.com/how-are-my-rsus-taxed-and-what-can-i-do-to-pay-less-in-taxes)
- Tax Implications for Stock-Based Compensation – Bloomberg Tax (https://pro.bloombergtax.com/insights/federal-tax/tax-implications-for-stock-based-compensation)
- Equity Compensation and U.S. Federal Income Taxes: An Overview | Morgan Stanley at Work (https://morganstanley.com/atwork/employees/learning-center/articles/equity-comp-taxation)
- Tax Considerations for Equity-Based Compensation (https://claconnect.com/en/resources/blogs/private-equity/considering-equity-based-compensation-learn-the-tax-considerations)
- Implement Effective Tax Planning Strategies
- Federal Capital Gains Tax Collections, Historical Data (1954-2018) (https://taxfoundation.org/data/all/federal/federal-capital-gains-tax-collections-historical-data)
- What is the long-term capital gains tax? | Fidelity (https://fidelity.com/learning-center/smart-money/what-is-long-term-capital-gains-tax)
- Capital Gains Tax Rates: Short-term vs. Long-term (https://schwab.com/learn/story/how-are-capital-gains-taxed)
- Historical Capital Gains Rates (https://wolterskluwer.com/en/expert-insights/whole-ball-of-tax-historical-capital-gains-rates)
- What is the effect of a lower tax rate for capital gains? (https://taxpolicycenter.org/briefing-book/what-effect-lower-tax-rate-capital-gains)
- Identify Risks and Considerations in IPO Tax Planning
- SEC.gov | Initial Public Offerings (IPOs) (https://sec.gov/data-research/statistics-data-visualizations/initial-public-offerings-ipos)
- The Evolution of Household Income Volatility | Brookings (https://brookings.edu/articles/the-evolution-of-household-income-volatility-3)
- Cross-influence of information and risk effects on the IPO market: exploring risk disclosure with a machine learning approach – PMC (https://pmc.ncbi.nlm.nih.gov/articles/PMC9589735)
- Equity Compensation: Market Volatility | Morgan Stanley at Work (https://morganstanley.com/atwork/employees/learning-center/articles/equity-compensation-market-volatility)
- IPO Basics: What to Know Before Investing (https://schwab.com/learn/story/ipo-basics-what-to-know-before-investing)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Philanthropy for high-income W-2 families at Bright Advisers.
Keep reading