

Key Highlights
- Gift tax is a federal tax on the transfer of money or property without equal value in return, crucial for financial planning.
- In 2026, individuals can gift up to $19,000 per recipient annually without tax; married couples can combine this for $38,000.
- Utilising the annual exclusion can reduce taxable estates, allowing families to support loved ones without incurring taxes.
- A lifetime exemption of $15 million per person applies to gifts exceeding the annual limit, impacting estate tax planning.
- IRS Form 709 must be filed for gifts exceeding the annual threshold, even if no tax is owed, ensuring compliance.
- Common pitfalls include neglecting to elect the IRS gift to spouse option and not considering capital gains taxes on appreciated assets.
- Gifting to a non-U.S. citizen spouse involves different rules, complicating the gifting process.
- Understanding these regulations helps families make informed decisions and maximise tax benefits while securing their financial future.
Introduction
Imagine feeling confident about your family’s financial future, even when faced with the complexities of gift tax. It’s important to understand the IRS rules about gifting to a spouse. These rules can lead to significant tax savings through annual exclusions and lifetime exemptions. As you explore these regulations, you might be asking yourself: how can you use these gifting strategies to grow your wealth and avoid common pitfalls? Together, we’ll uncover the key rules and considerations for spousal gifting, offering insights to help you make informed financial decisions for your family.
Define Gift Tax and Its Importance in Spousal Gifting
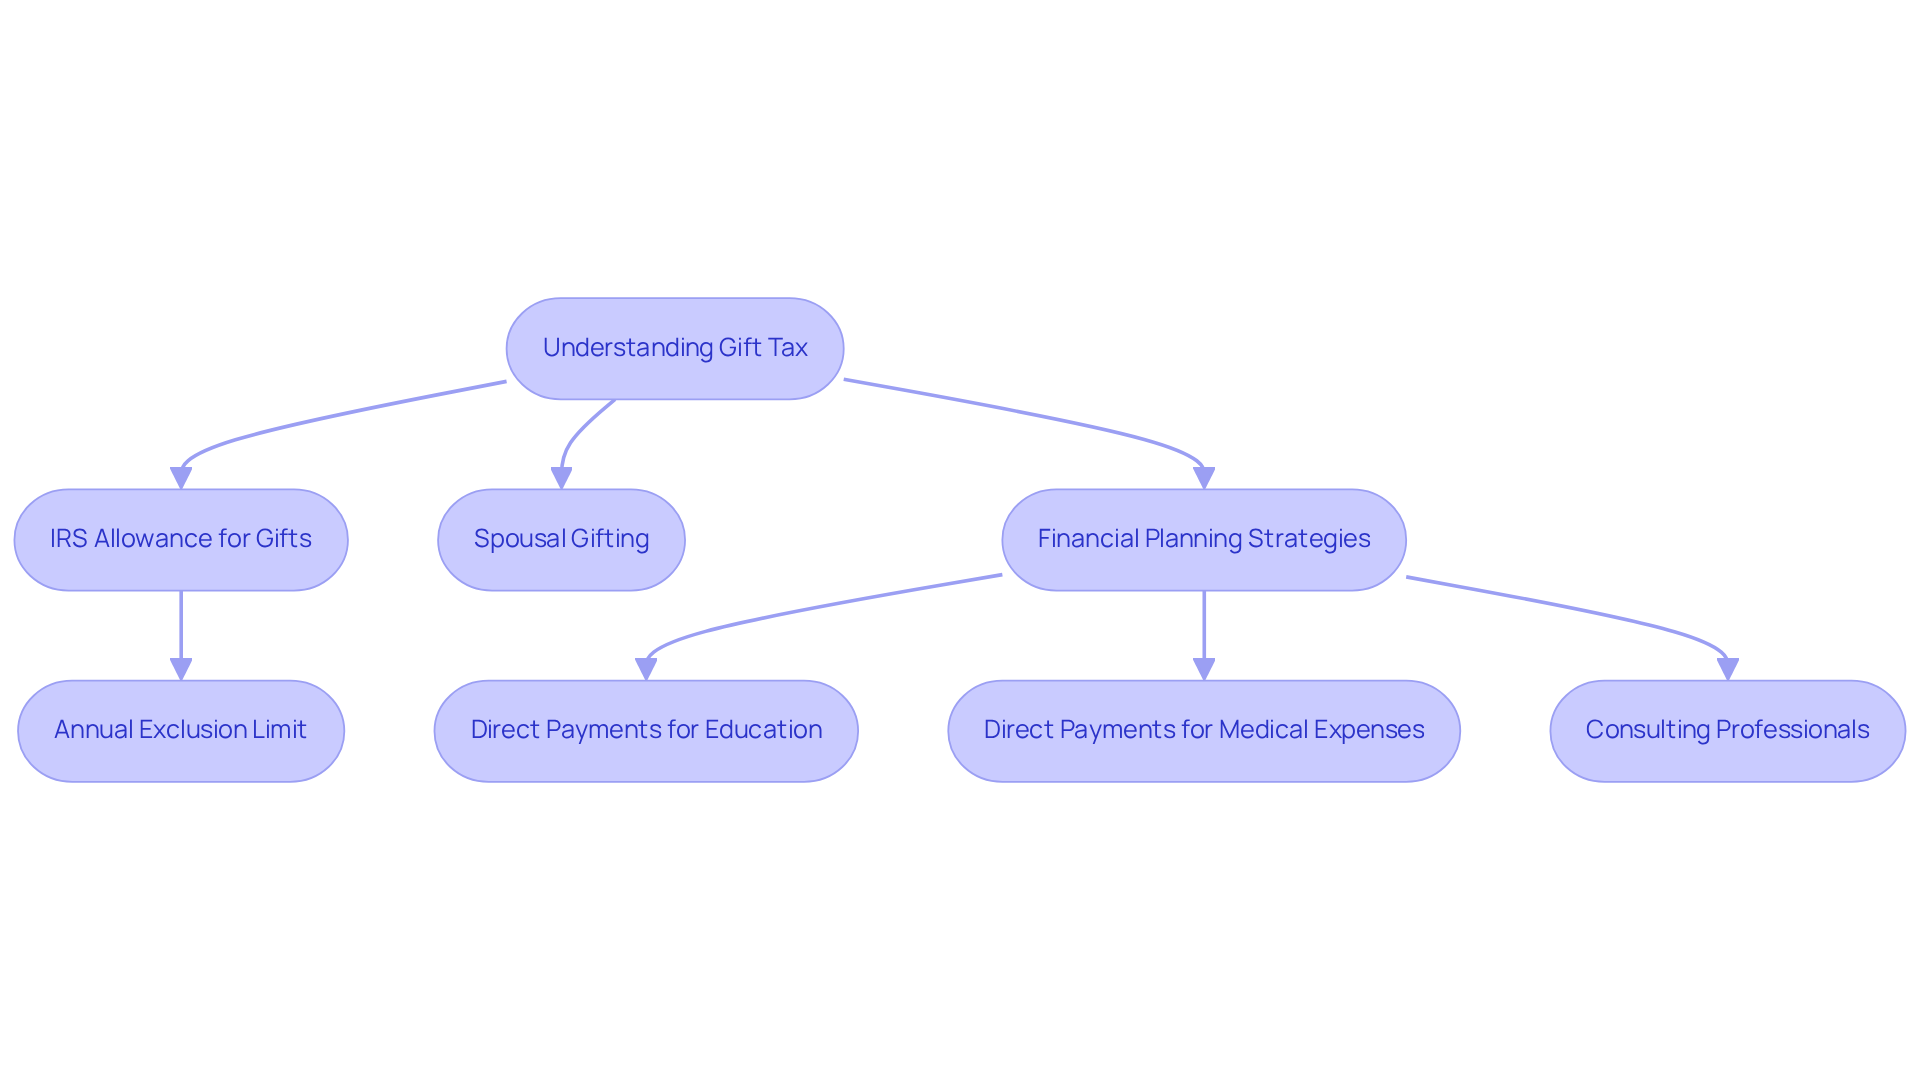
Navigating the world of gift tax can feel overwhelming, especially for young parents trying to secure their family’s future. Gift tax is a federal tax applied to the transfer of money or property from one individual to another without receiving equal value in return. For young parents, understanding transfer tax is essential, especially when considering financial strategies that involve the IRS gift to spouse. In 2026, the IRS permits individuals to give up to $19,000 per recipient each year without incurring tax on gifts, and married couples can combine their exclusions for a total of $38,000 per recipient. This exemption is crucial for households aiming to manage their wealth effectively, as it offers financial flexibility without the burden of additional taxes.
At Bright Advisers, we understand that the IRS gift to spouse can create daunting tax implications in spousal transfers. Utilizing the yearly allowance can significantly reduce the size of a taxable estate, allowing families to provide financial assistance to loved ones during their lifetime. For instance, one family used direct payments for educational costs, which do not count against the annual exclusion limit, to support their children’s education while preserving their lifetime estate exemptions.
Understanding gift tax regulations helps parents make informed decisions about their financial planning and how to transfer wealth. By taking advantage of existing tax exemptions, families can ensure that their assets are transferred effectively and responsibly, aligning with their long-term financial goals. Together, we can ensure you make choices that truly protect your family’s financial future.
Explore Annual Exclusions and Lifetime Exemptions for Spousal Gifts
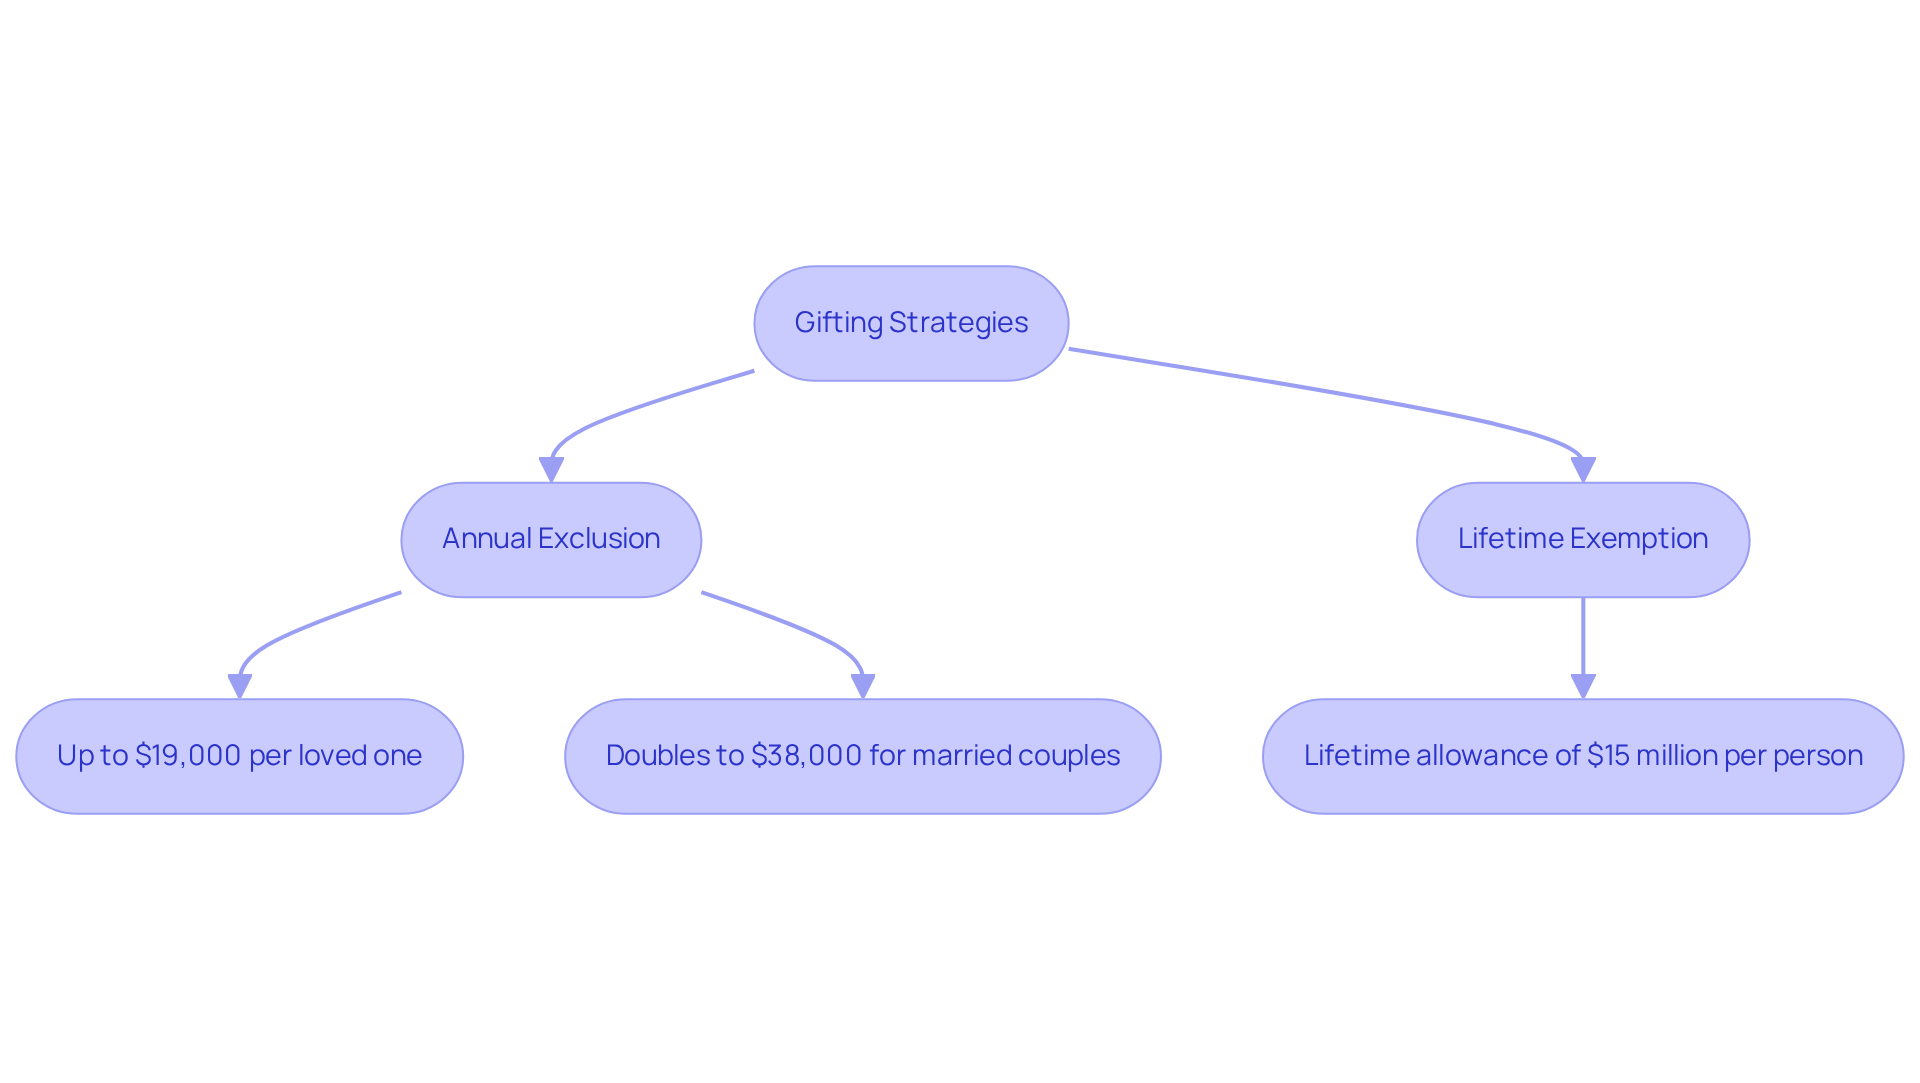
Imagine being able to support your loved ones without the worry of tax implications. Starting in 2026, you can gift up to $19,000 to each loved one without worrying about taxes. For married couples, this amount doubles to $38,000 when both partners agree to share the contribution. Plus, there’s a lifetime allowance of $15 million per person, meaning any transfers over the annual limit will count against this lifetime cap.
By effectively using these strategies, you can enhance your ability to pass on wealth to your spouse or children without facing tax issues. It’s important to keep track of all contributions to stay compliant with IRS regulations and make the most of these allowances. Regular gifting within the annual limit not only helps your family now but can also reduce the size of your taxable estate, easing potential estate tax burdens.
We recommend chatting with a tax advisor to ensure your generous gifts align with your family’s financial dreams. By understanding these strategies, you can ensure your family’s future is secure and filled with love.
Guide to Reporting Spousal Gifts: Forms and Filing Requirements
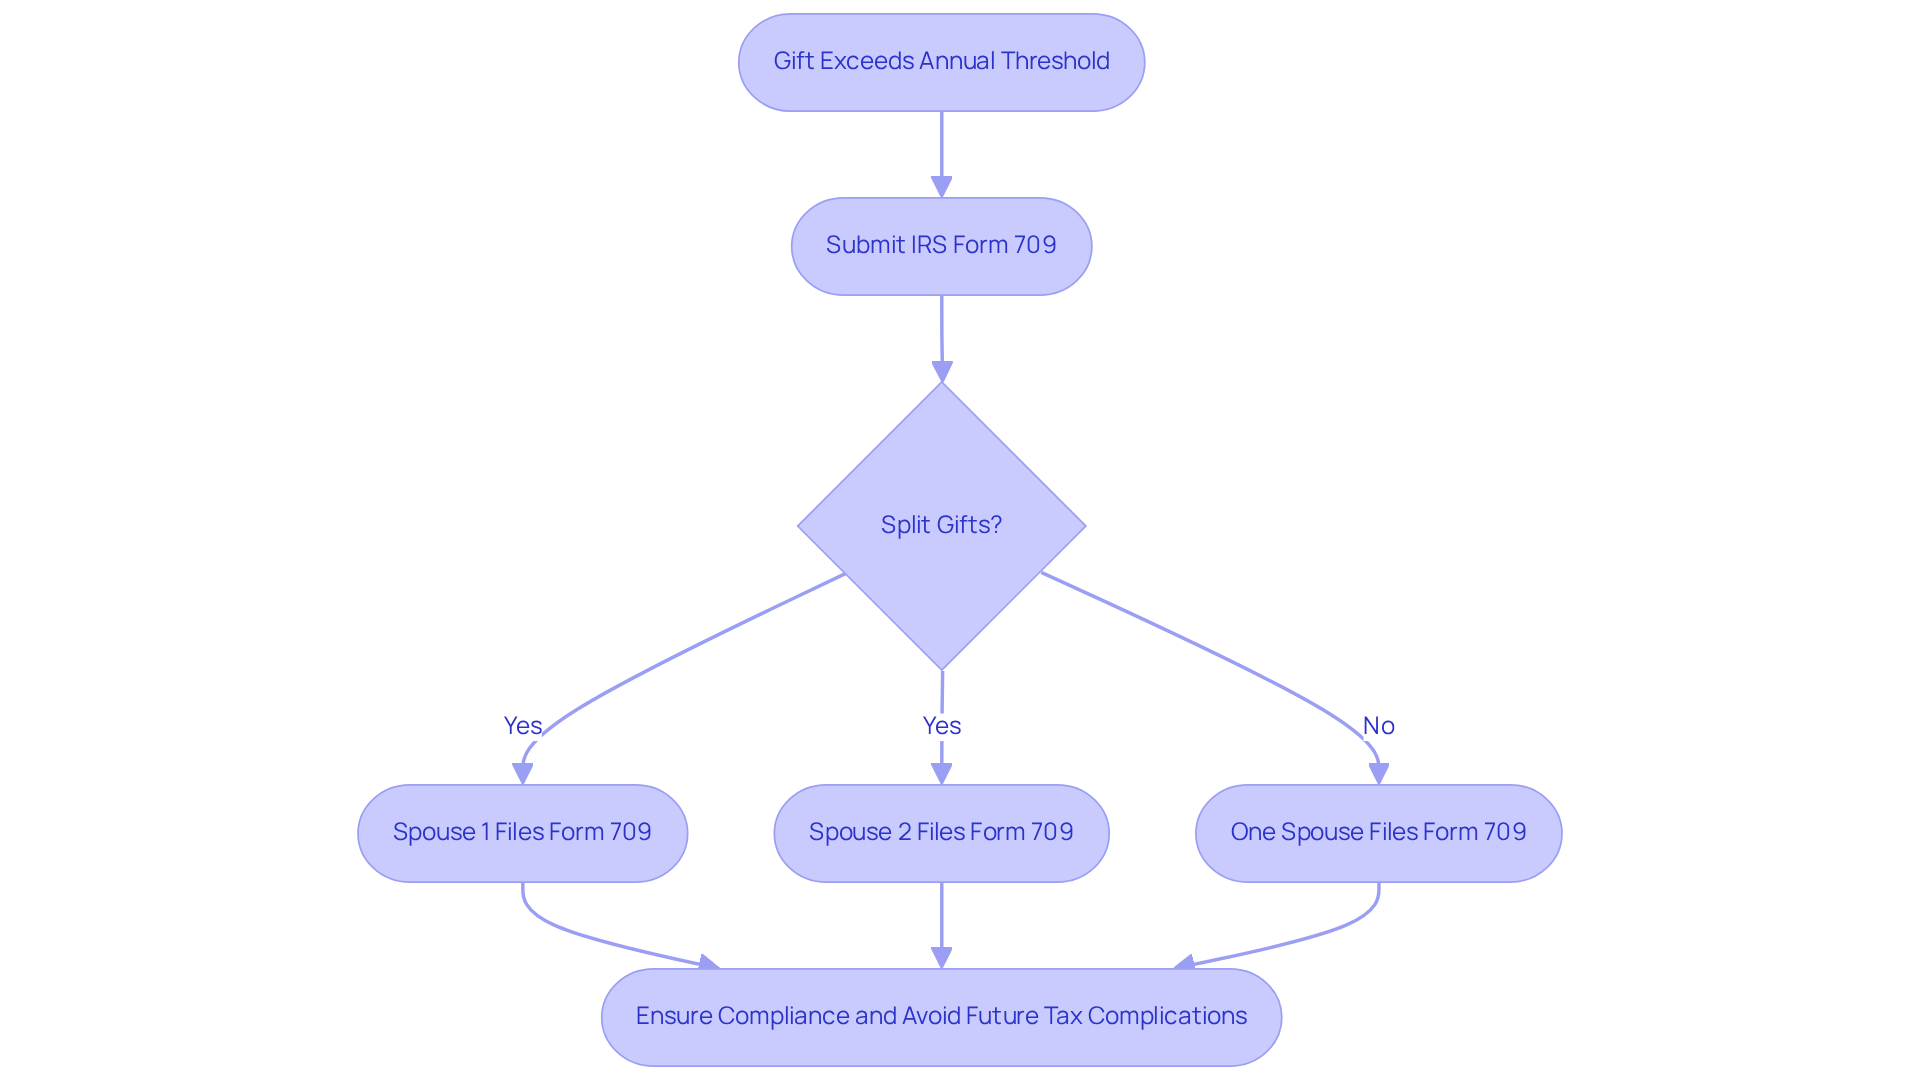
Imagine the relief of knowing your family’s financial gifts are handled correctly, without the stress of tax complications. When a gift exceeds the annual threshold amount, you’ll need to submit IRS Form 709, the United States Transfer Tax Return. If you and your spouse decide to split gifts, each of you will need to file your own Form 709, even if one of you doesn’t exceed the limit.
It’s really important for your family’s financial health to keep track of all your contributions. This documentation is necessary for tax reporting and compliance. Understanding these rules helps your family meet your tax responsibilities and make the most of available benefits. For instance, if one spouse gives $30,000 in 2026, $19,000 is excluded, and the remaining $11,000 counts against the lifetime exemption amount of $15 million.
Accurate reporting on Form 709 not only ensures compliance but also protects families from potential future tax complications. Failing to report correctly could lead to unexpected tax bills down the line. By understanding these requirements, you can protect your family’s future and enjoy peace of mind.
Identify Common Pitfalls and Strategic Considerations in Spousal Gifting
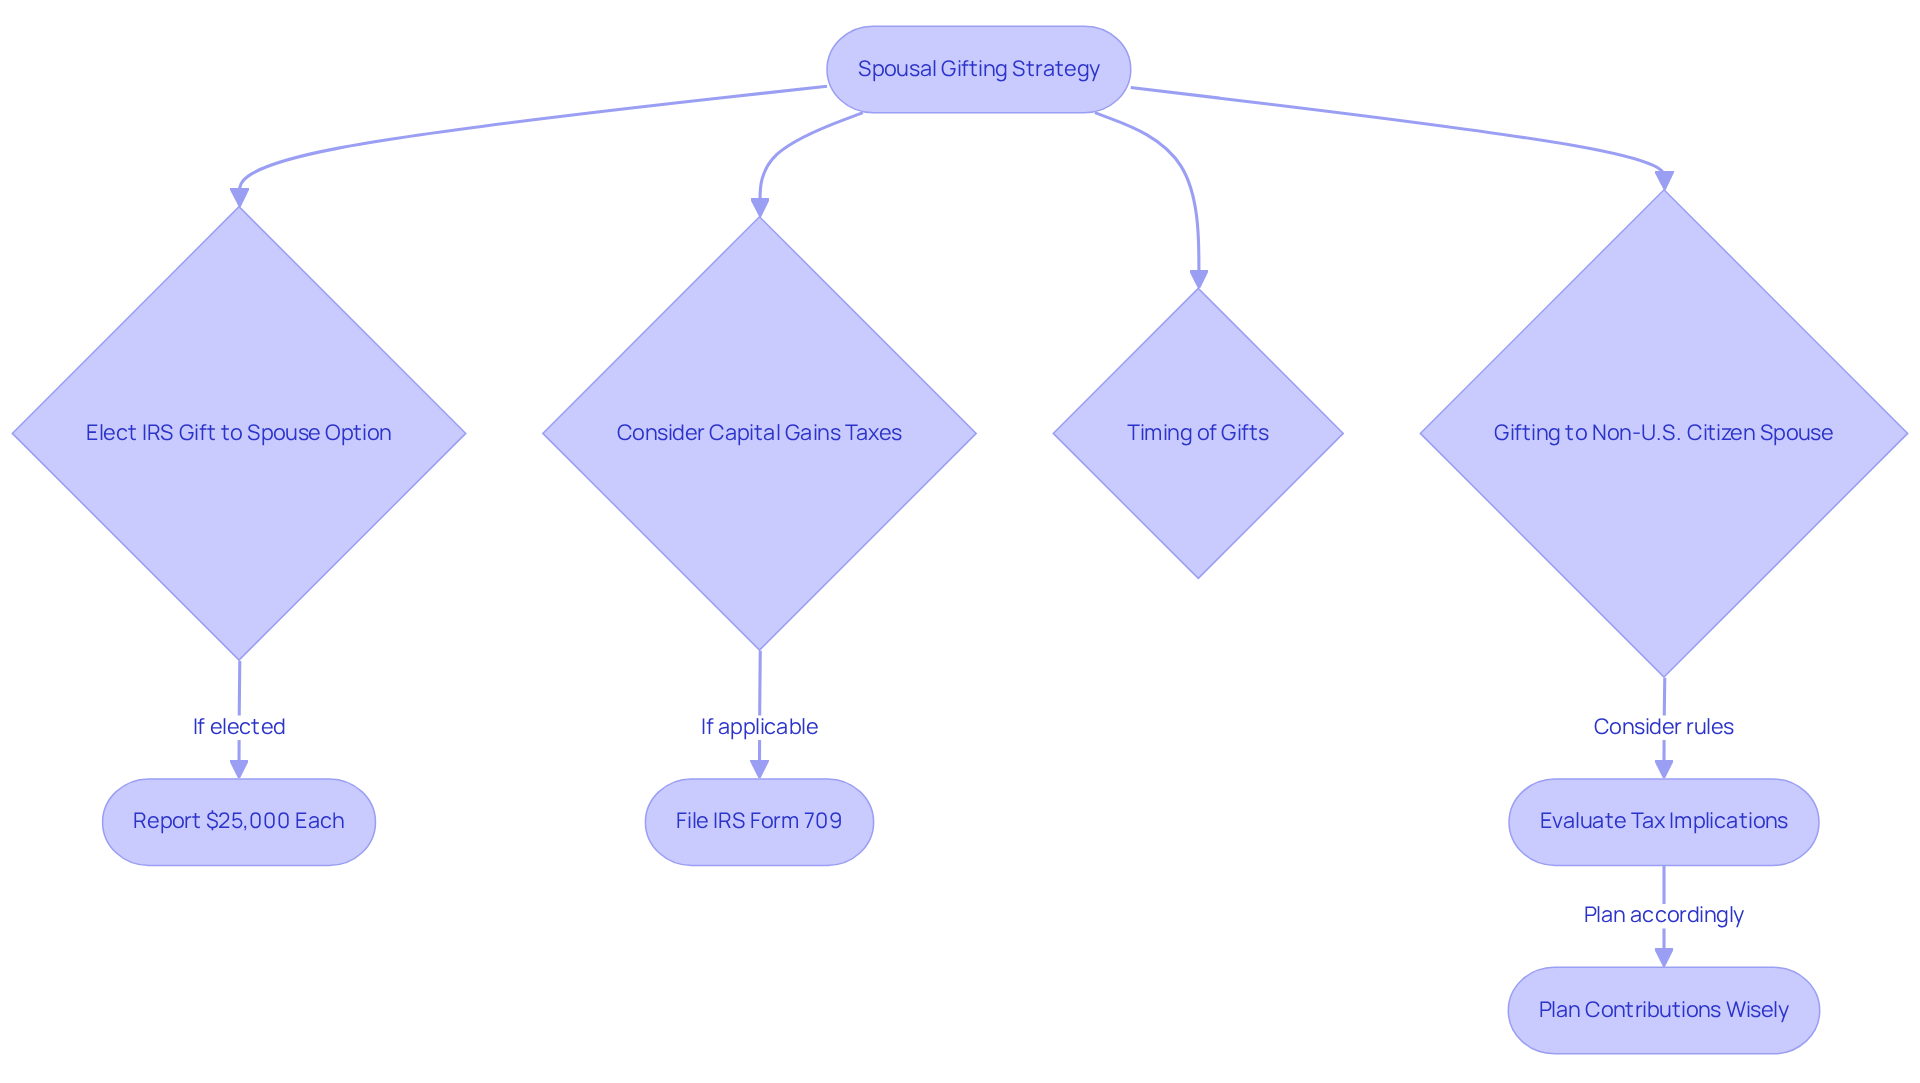
Imagine missing out on valuable tax benefits just because of a simple oversight in your gifting strategy. One significant pitfall in spousal gifting is neglecting to elect the IRS gift to spouse option. For instance, when a couple shares a gift of $50,000, they can each report $25,000, making the most of their combined annual exclusion of $38,000 in 2026. Not taking this step might mean missing out on potential tax savings.
It’s also important for parents to be mindful when gifting assets that have grown in value, as this could lead to capital gains taxes for the person receiving the gift. Timing matters too; gifts given at the end of the year can affect tax obligations differently than those given earlier. For example, if a gift exceeds the annual exclusion limit of $19,000 in 2026, the donor will need to file IRS Form 709, even if no tax is owed.
Parents should also keep in mind that gifting to a non-U.S. citizen spouse comes with different rules, which can make the process a bit more complicated. By being aware of these potential pitfalls and planning their contributions wisely, families can enhance their wealth transfer strategies and lower their tax burdens.
For example, if Jack and Sarah decide to split a $10,038,000 gift in 2026, they could protect a combined estate tax exemption of $30 million, which is vital for smart estate planning. By being aware of these common mistakes, families can better navigate the complexities of spousal gifting, particularly the IRS gift to spouse rules, ensuring they follow tax laws while maximizing the benefits of their gifting approach.
Conclusion
Imagine feeling confident about your family’s financial future, knowing you can gift to your spouse without the stress of tax liabilities. Being able to gift to your spouse without worrying about taxes gives you the freedom to manage your family’s wealth more effectively. Using annual exclusions and lifetime exemptions can help you navigate gifting to your spouse, making it easier to stay compliant with IRS rules.
Throughout this article, we’ve shared key insights about the importance of understanding gift tax implications and how to utilize annual exclusions and lifetime exemptions. We also highlighted common pitfalls, like forgetting to elect the IRS gift to spouse option or mismanaging the timing of gifts, to help you avoid costly mistakes. By being informed and strategic, you can enhance your wealth transfer strategies and minimize tax burdens.
Taking these steps today can pave the way for a more secure tomorrow for your family, and remember, we’re here to support you every step of the way.
Frequently Asked Questions
What is gift tax?
Gift tax is a federal tax applied to the transfer of money or property from one individual to another without receiving equal value in return.
Why is understanding gift tax important for young parents?
Understanding gift tax is essential for young parents as it helps them navigate financial strategies involving wealth transfer, ensuring they can secure their family’s future without incurring unnecessary tax burdens.
What is the annual gift tax exclusion for 2026?
In 2026, the IRS permits individuals to give up to $19,000 per recipient each year without incurring tax on gifts. Married couples can combine their exclusions for a total of $38,000 per recipient.
How can the annual gift tax exclusion benefit families?
The annual gift tax exclusion allows families to manage their wealth effectively by providing financial flexibility without the burden of additional taxes, which can help reduce the size of a taxable estate.
Can direct payments for educational costs affect the annual exclusion limit?
No, direct payments for educational costs do not count against the annual exclusion limit, allowing families to support their children’s education while preserving their lifetime estate exemptions.
How can understanding gift tax regulations aid in financial planning?
Understanding gift tax regulations helps parents make informed decisions about wealth transfer, ensuring that their assets are transferred effectively and responsibly in alignment with their long-term financial goals.
List of Sources
- Define Gift Tax and Its Importance in Spousal Gifting
- What is the Annual Gift Tax Exclusion Limit for 2026? (https://adamsbrowncpa.com/blog/what-is-the-annual-gift-tax-exclusion-limit-for-2026)
- Nelson Mullins – 2026 Estate and Gift Tax Update (https://nelsonmullins.com/insights/blogs/tax-reports/all/2026-estate-and-gift-tax-update)
- 2026 Federal & State Estate and Gift Tax Cheat Sheet (https://wealthspire.com/guides-whitepapers/federal-state-estate-gift-tax)
- The Estate Tax and Lifetime Gifting (https://schwab.com/learn/story/estate-tax-and-lifetime-gifting)
- Explore Annual Exclusions and Lifetime Exemptions for Spousal Gifts
- 2026 Gift Tax Exclusions (https://farmoffice.osu.edu/blog/tue-02172026-710pm/2026-gift-tax-exclusions)
- What is the Annual Gift Tax Exclusion Limit for 2026? (https://adamsbrowncpa.com/blog/what-is-the-annual-gift-tax-exclusion-limit-for-2026)
- Tax-Free Gifting in 2026: What Financial Givers Should Know (https://merceradvisors.com/family-finance/tax-free-gifting-in-2026-what-financial-givers-should-know)
- Nelson Mullins – 2026 Estate and Gift Tax Update (https://nelsonmullins.com/insights/blogs/tax-reports/all/2026-estate-and-gift-tax-update)
- Annual Gift Tax and Estate Tax Exemptions for 2026 – McClelland Law Firm. P.A. (https://mcclellandfirm.com/annual-gift-tax-and-estate-tax-exemptions-for-2026)
- Guide to Reporting Spousal Gifts: Forms and Filing Requirements
- Form 709: How U.S. Taxpayers Report Gifts to the IRS (https://brighttax.com/blog/us-gift-tax-limits-form-709)
- Gift Tax: Do I Have to Pay Taxes on a Gift? | Gift Tax Calculator (https://taxact.com/tax-resources/tax-calculators/gift-tax-calculator)
- SOI tax stats – Gift tax statistics | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-gift-tax-statistics)
- Instructions for Form 709-NA (2025) | Internal Revenue Service (https://irs.gov/instructions/i709na)
- IRS Form 709 | Gift and Generation | Skipping Transfers: Recent Updates and Common Mistakes (https://freemanlaw.com/irs-form-709-gift-and-generation-skipping-transfers-recent-updates-and-common-mistakes)
- Identify Common Pitfalls and Strategic Considerations in Spousal Gifting
- Avoid pitfalls when splitting gifts with your spouse – Capell & Howard P.C. Attorneys At Law (https://capellhoward.com/insights/avoid-pitfalls-when-splitting-gifts-with-your-spouse)
- Gift tax, how it works and the limits (https://jacksonhewitt.com/tax-help/tax-tips-topics/filing-your-taxes/what-is-a-gift-tax-gift-tax-limit-and-exemptions)
- What is gift splitting and how does it work? | Fidelity (https://fidelity.com/learning-center/wealth-management-insights/gift-splitting)
- Considering Splitting Gifts with Your Spouse? Here’s What to Consider – SEK CPAs (https://sek.com/blog/considering-splitting-gifts-your-spouse-heres-what-consider)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading