

Key Highlights
- Incentive Stock Options (ISOs) allow employees to buy company shares at a set price, offering potential tax benefits.
- Holding ISOs for at least one year after exercising and two years after the grant date can qualify for long-term capital gains tax treatment, which is generally lower than ordinary income tax rates.
- Families must be aware of the Alternative Minimum Tax (AMT) implications when exercising ISOs, as the bargain element can trigger unexpected tax liabilities.
- Exercising stock options early in the year and selling shares before year-end can help avoid AMT obligations.
- Tax-loss harvesting strategies can offset capital gains with losses from other investments, aiding in effective tax management.
- The AMT exemption thresholds are set to change in 2026, impacting families’ financial planning strategies.
- Understanding ISO tax implications is crucial for families to make informed decisions that align with their financial goals.
Introduction
Many families feel overwhelmed by the complexities of financial planning, especially when it comes to Incentive Stock Options (ISOs). For high-income families with young children, navigating these financial waters is crucial. The decisions made today can significantly impact your family’s future.
Let’s explore how families can navigate these options to ease tax burdens and enhance financial well-being. What happens when families overlook the nuances of AMT and other tax consequences? Ignoring these nuances could lead to unexpected tax burdens that strain family finances.
Understanding these complexities is vital for securing a stable financial future for your family.
Define Incentive Stock Options (ISOs)
Imagine being offered a chance to invest in your future, but feeling uncertain about the iso tax implications that come with it. Incentive Stock Options give you a chance to buy company shares at a set price, which can be a great opportunity for your family’s future. Unlike non-qualified stock options, these options come with some favorable tax treatment under specific conditions, making them an appealing part of your compensation package.
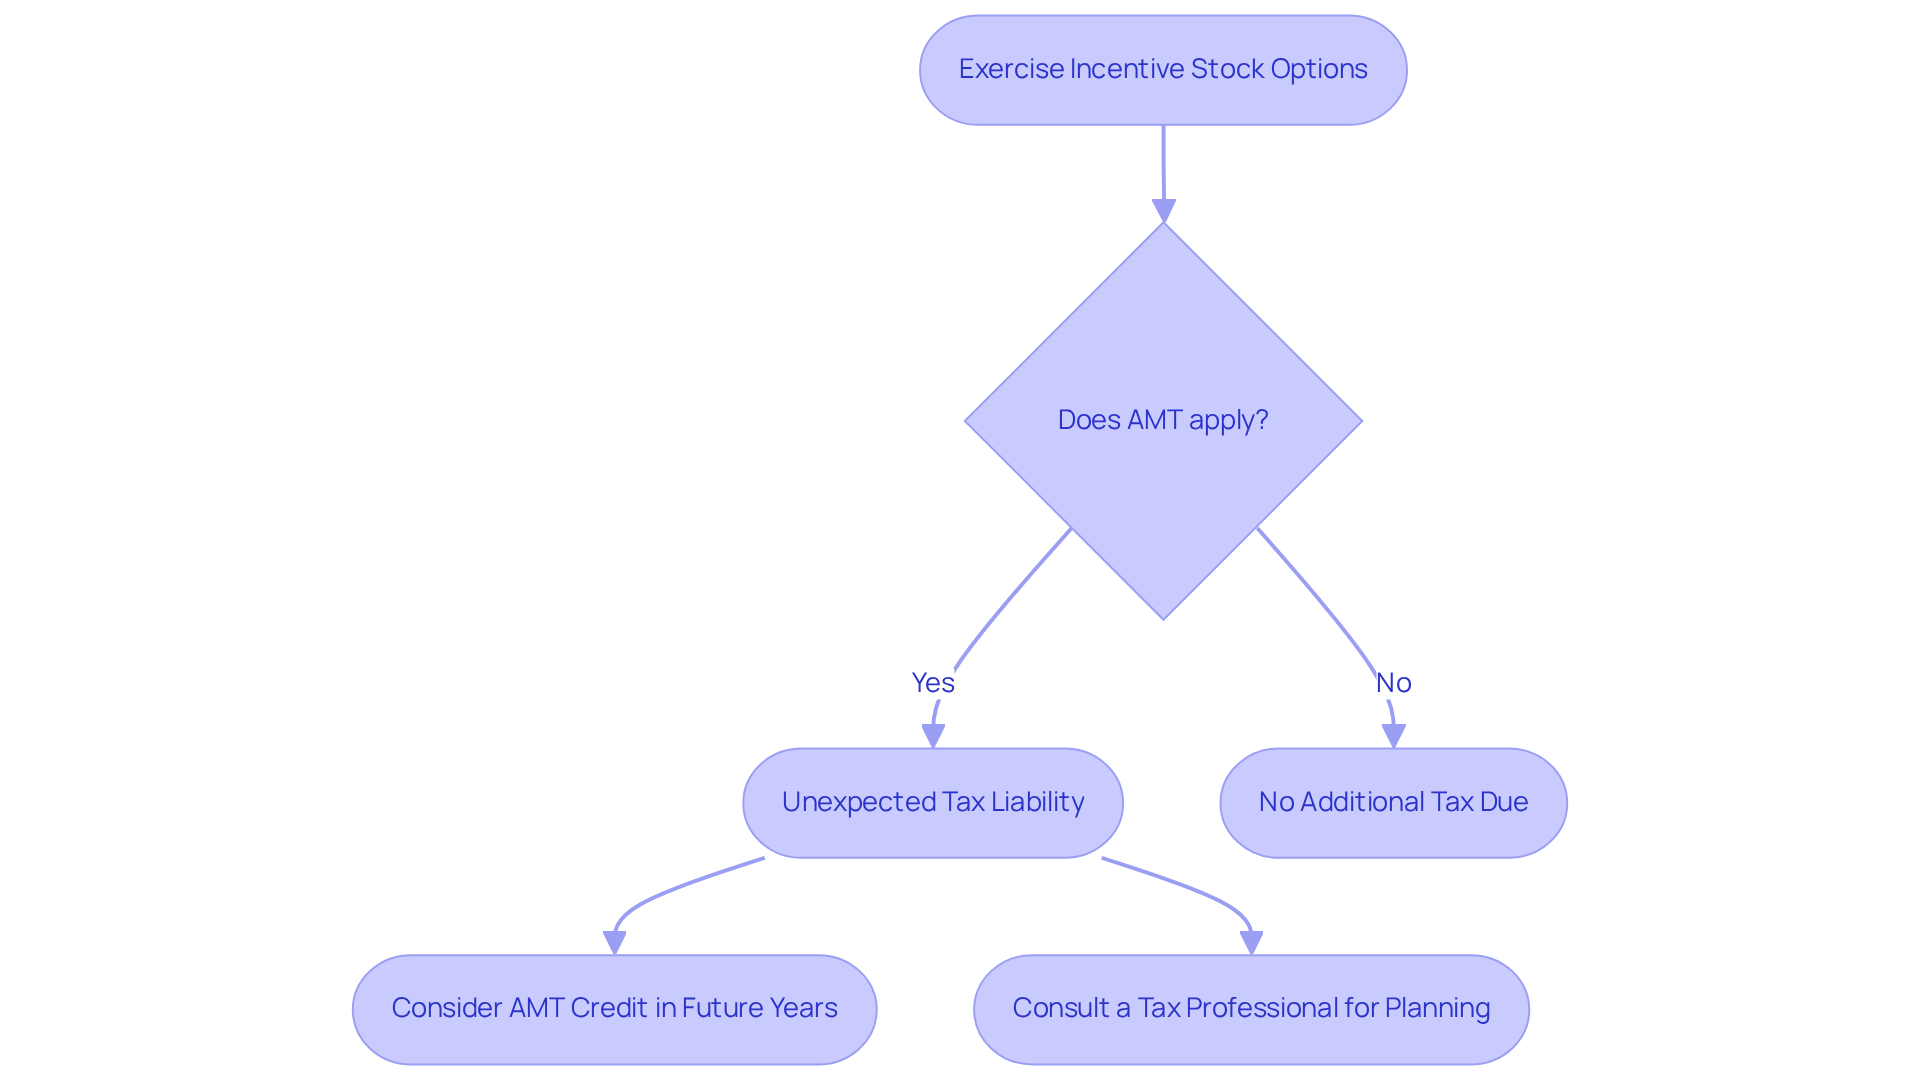
You might find that ISOs offer some great tax benefits, especially if you hold onto those shares for a while. If you keep the shares for at least one year after exercising and two years after the grant date, you could benefit from long-term capital gains tax treatment, which is usually lower than ordinary income tax rates. This can be a significant advantage for your family’s financial planning.
Incentive stock options often come with vesting schedules, encouraging you to stay with your company and contribute to its growth. However, it’s important to be aware of the iso tax implications related to the Alternative Minimum Tax (AMT). Navigating the complexities of iso tax implications can feel overwhelming, especially when you’re focused on securing your family’s future. The bargain element – the difference between the acquisition price and the fair market value at the time of utilization – must be reported as income for AMT purposes. Not grasping these iso tax implications could put unexpected financial strain on your family.
For instance, if you exercise stock options but don’t sell the shares in the same year, you might still incur AMT liabilities based on the initial market value at exercise. On the other hand, selling the stock in the same year as exercising can help you avoid AMT implications, allowing you to be taxed at ordinary income rates instead.
Grasping these stock options is crucial, especially for families looking to make the most of their compensation. Understanding these options can empower you to make informed decisions that benefit your family’s financial well-being.
Explore ISO Tax Treatment and Implications
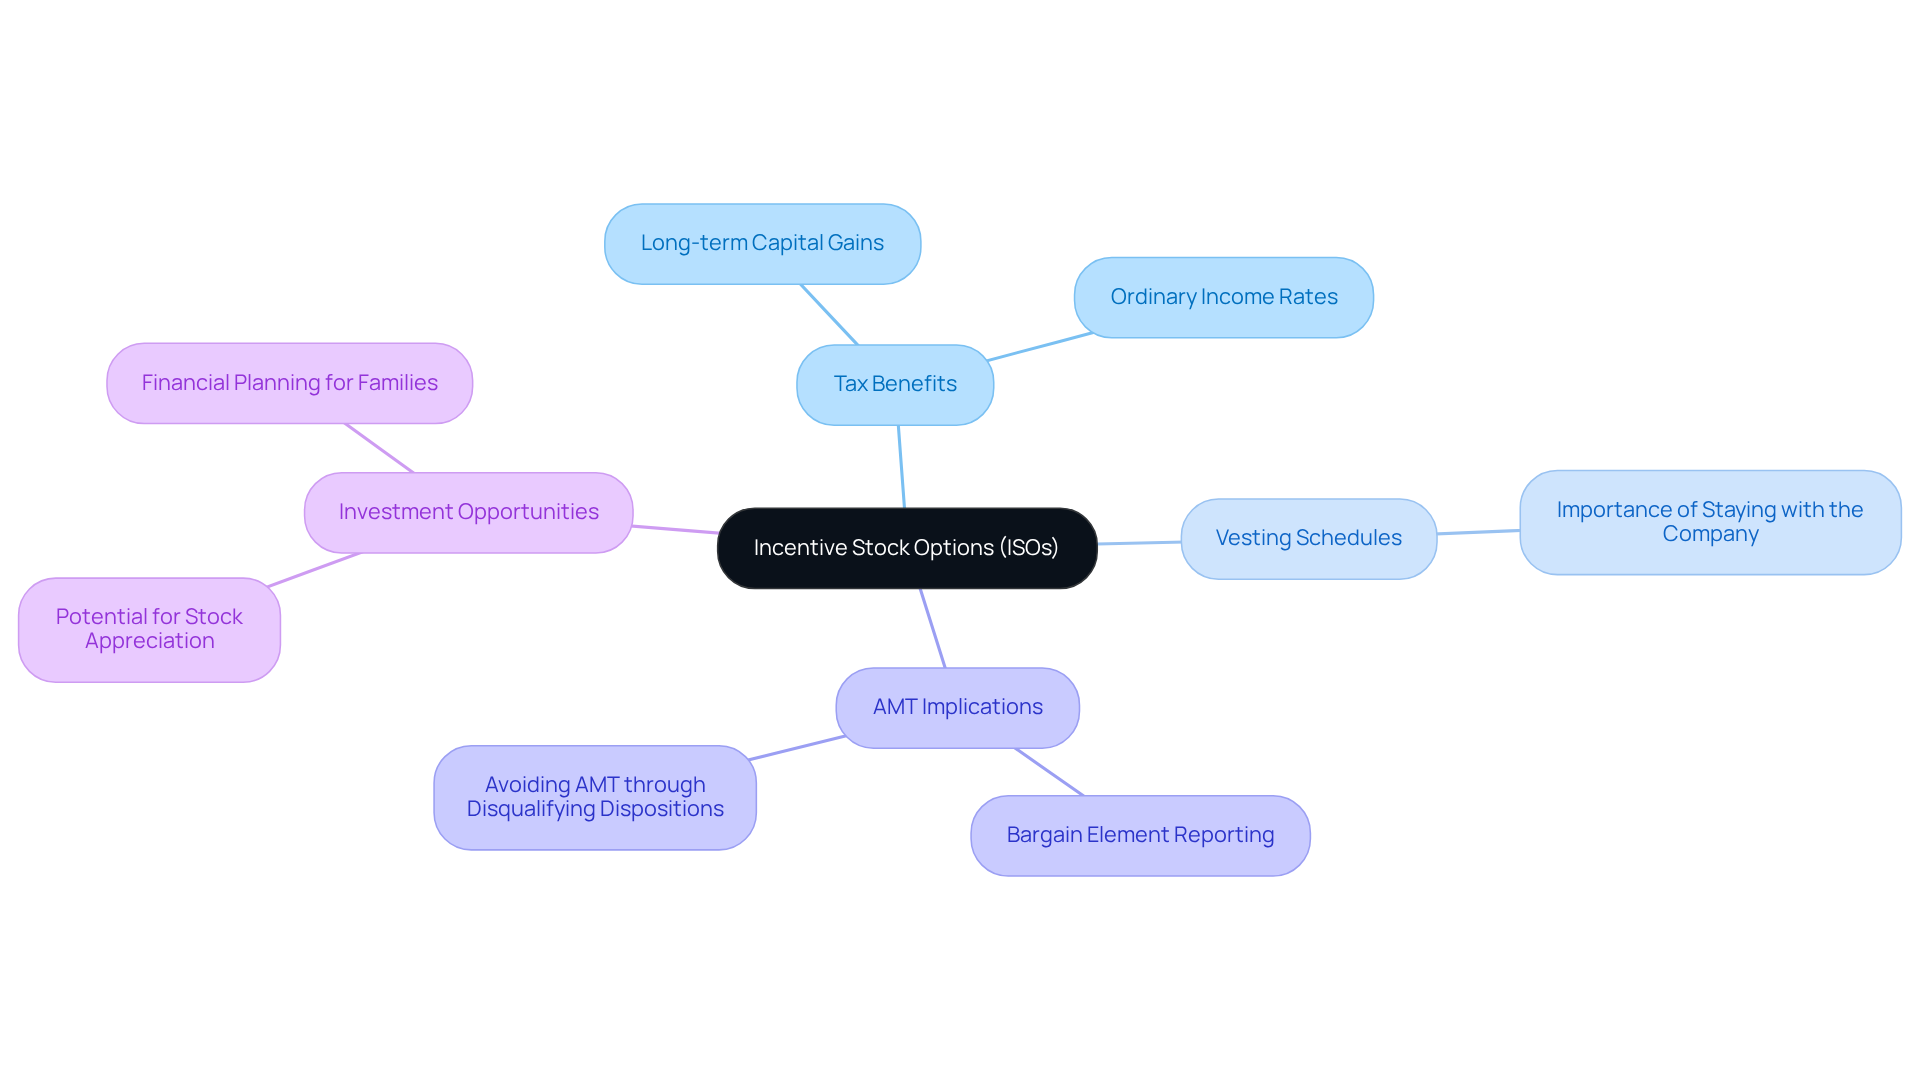
Navigating the world of Incentive Stock Options can feel overwhelming, especially when it comes to understanding the ISO tax implications for your family. Imagine being able to postpone your regular income tax until you sell your shares with Incentive Stock Options. If you hold onto your shares for at least one year after using the option and two years after the grant date, any profit you make could be taxed as long-term capital gains, which generally have lower rates than ordinary income. This means you could save money on taxes, allowing you to invest more in your family’s future.
However, it’s important for families to think about the potential for Alternative Minimum Tax (AMT) when they exercise their stock options. For instance, if a family utilizes 10,000 shares at a purchase price of $10, with a fair market value of $50, they could recognize AMT income of $400,000. This could mean a heavier tax load, which is something every family wants to avoid. Careful planning is essential to navigate these waters.
Let’s look at some real-life examples that demonstrate how timing and strategy can significantly impact the management of your ISO tax implications. Employees who utilize stock options early in the year and sell shares before year-end can evade AMT obligations, safeguarding their profits from declining stock values. Additionally, tax-loss harvesting strategies can offset capital gains with losses from other investments, allowing families to manage their taxable income effectively.
As we look ahead to 2026, it’s essential for families to know that the thresholds for long-term capital gains tax rates have changed, which could affect your planning strategies. Understanding the nuances of ISO tax implications, including the implications of AMT and the differences between regular and AMT cost basis, is crucial for families navigating these financial decisions. By taking the time to understand these nuances, you can make informed decisions that protect your family’s financial future.
Understand ISO Exercise Scenarios and Tax Consequences
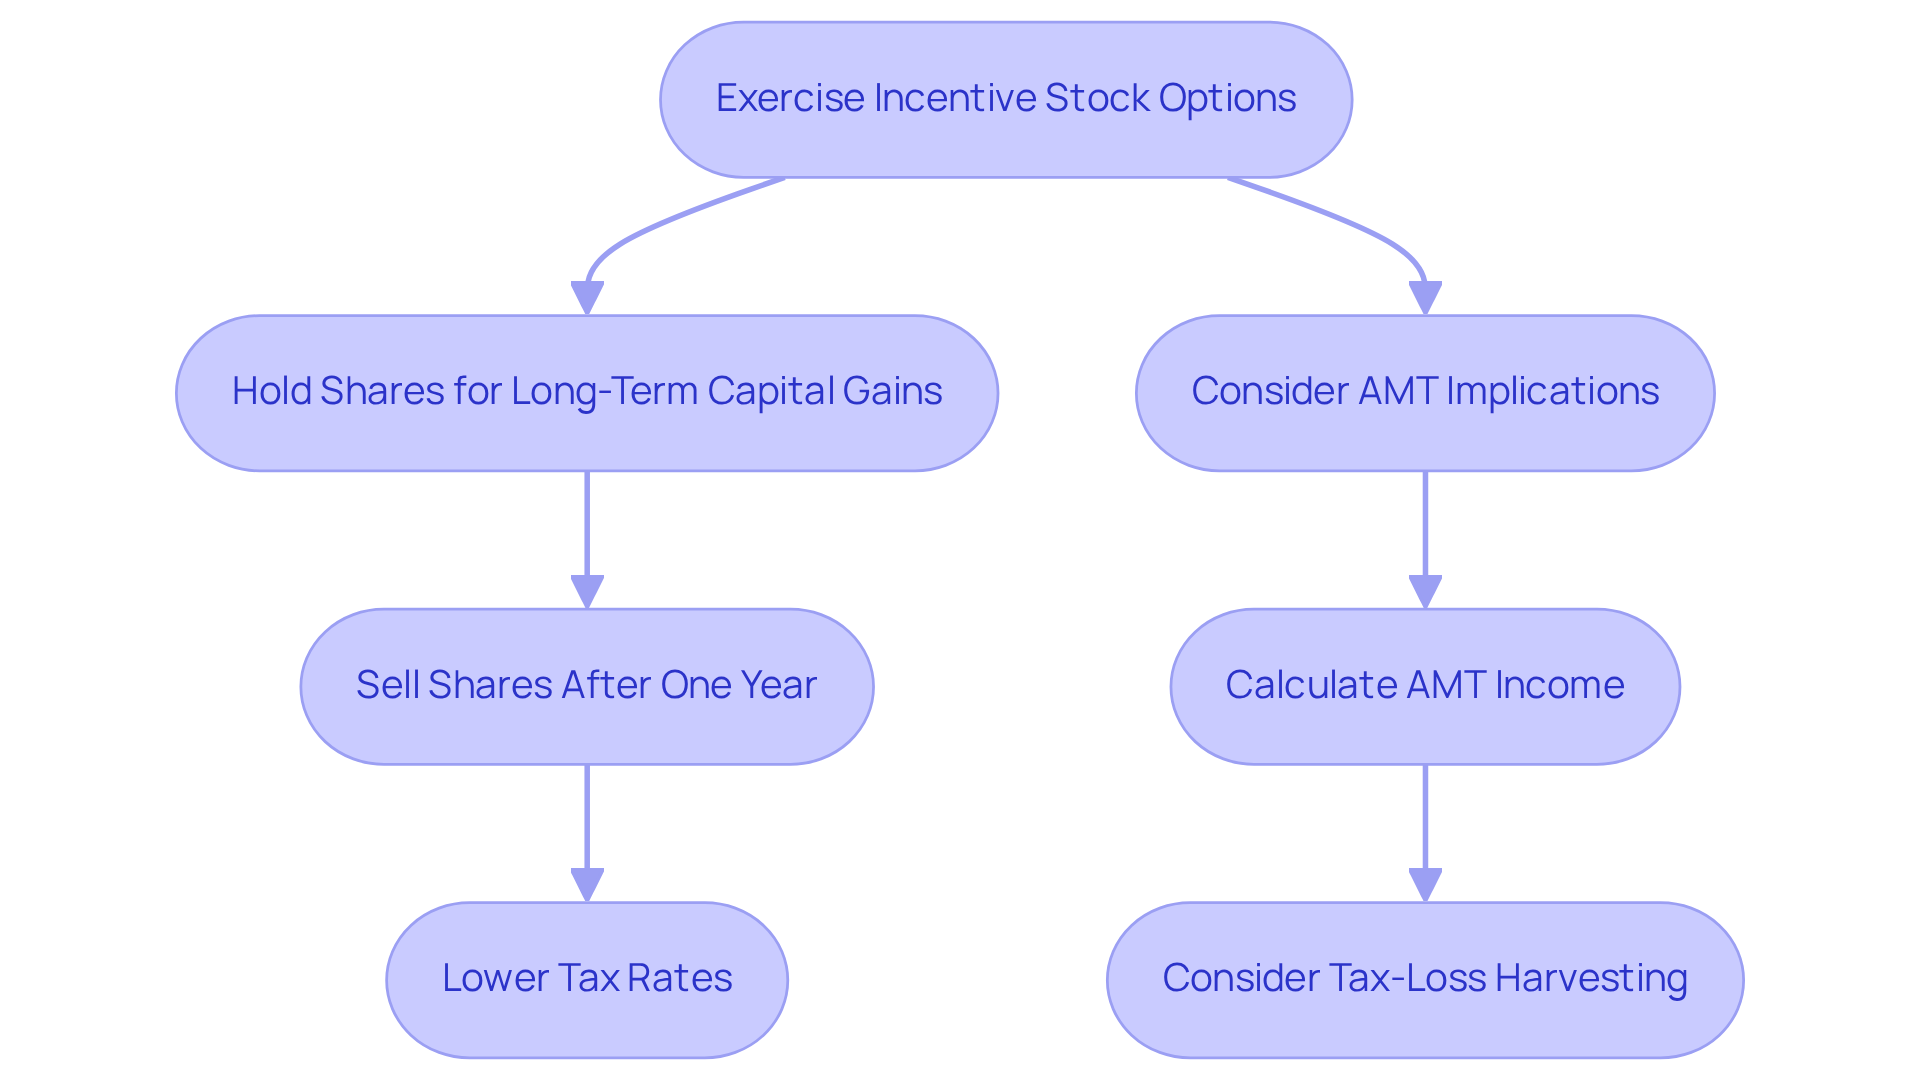
Navigating the world of Incentive Stock Options (ISOs) can feel overwhelming, especially when ISO tax implications come into play. Imagine selling your shares right after exercising your options; this could lead to a hefty ordinary income tax bill based on the difference between what you paid and what the shares are worth now.
But holding onto those shares might also mean facing the Alternative Minimum Tax (AMT), which can catch families off guard due to the difference in value when you exercise your options. As we look ahead to 2026, it’s crucial for families to be aware of the AMT implications, especially since California has one of the highest rates in the country, which can feel daunting.
By understanding these scenarios and their tax consequences, families can make informed decisions that align with their financial goals. Families like Allison and Brian, who sought guidance from Bright Advisers, learned how to navigate these complexities. They incorporated strategic tax planning, including tax-loss harvesting and other optimization strategies, into their financial plan. This approach allowed them to secure their children’s future while also gaining the ability to retire sooner. By grasping the ISO tax implications of their options, they found a sense of peace, reinforcing how vital it is to have a solid financial plan in place.
Analyze the Role of Alternative Minimum Tax (AMT) in ISOs
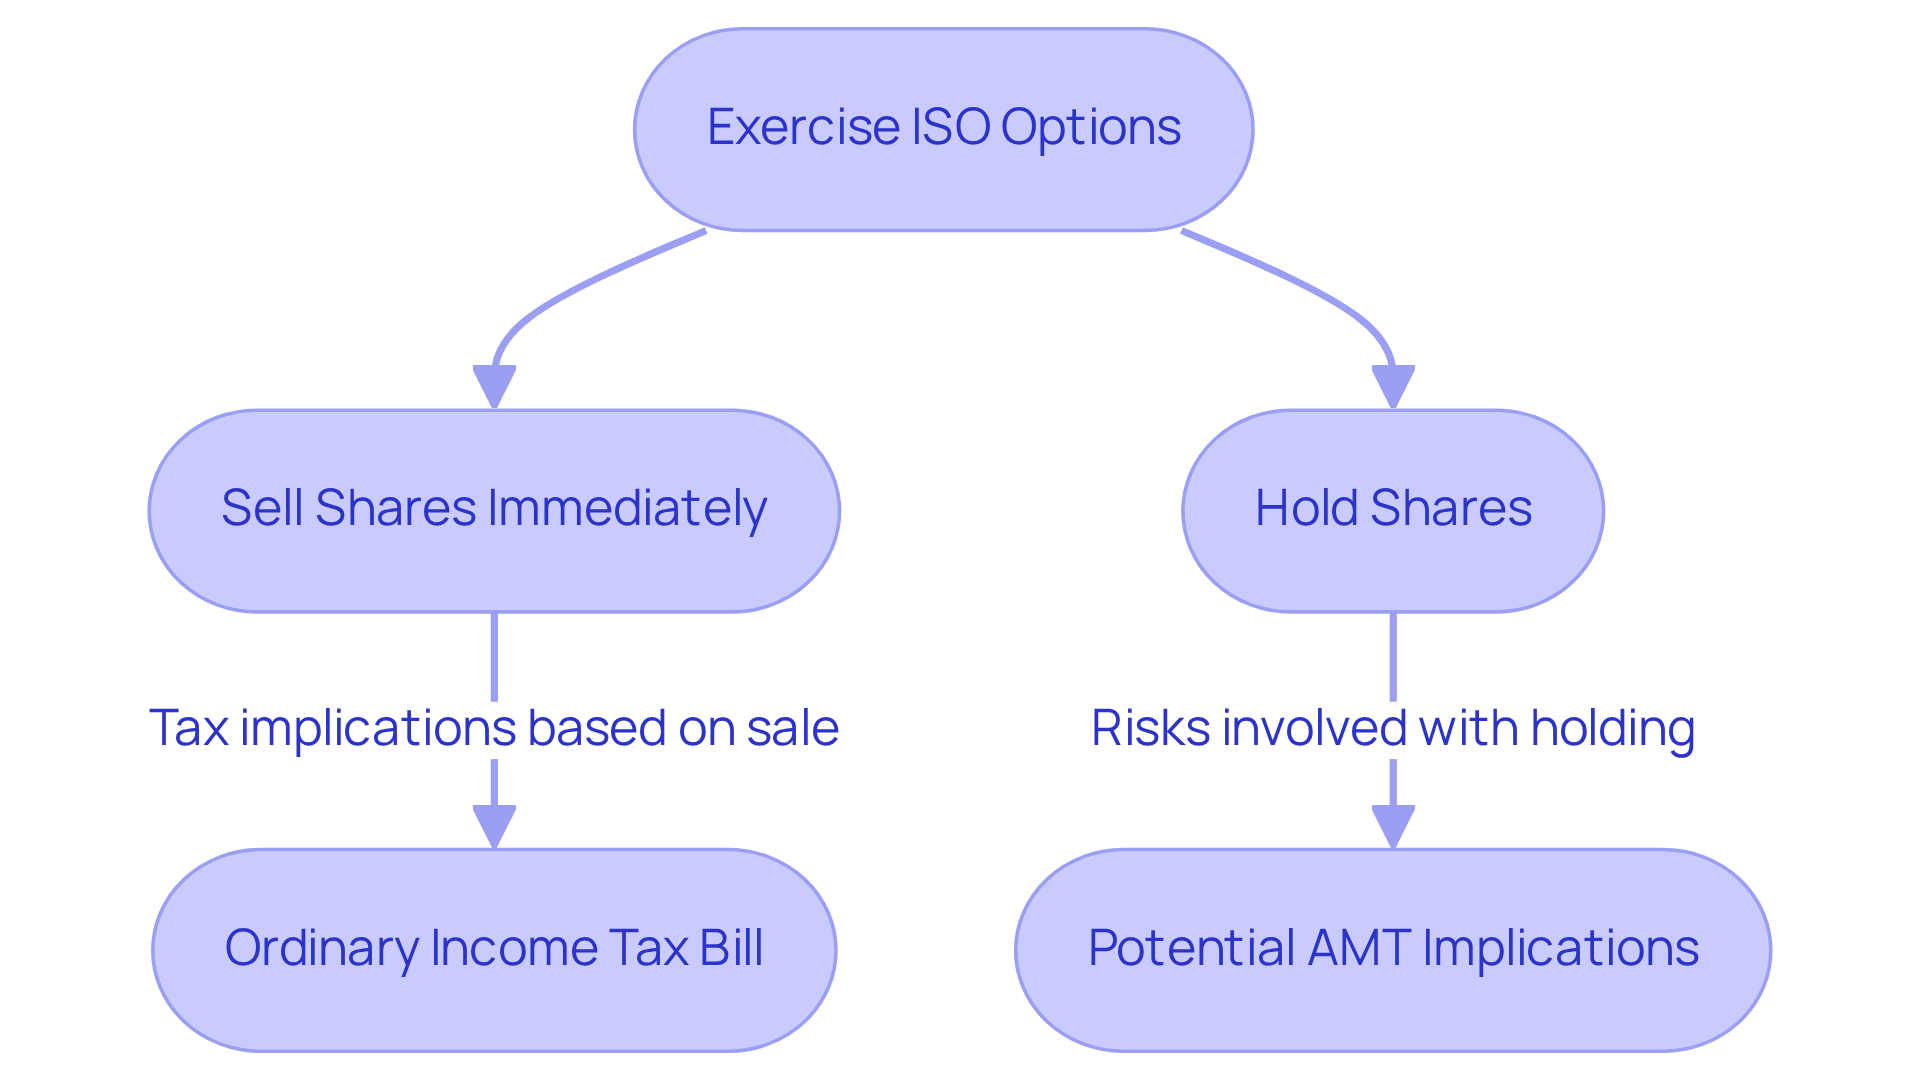
Imagine the surprise of receiving a tax bill when you thought you had no tax due. The Alternative Minimum Tax (AMT) can feel overwhelming, especially when it seems like it’s designed for high-income earners to pay their fair share. When families utilize Incentive Stock Options, the ‘bargain element’ – the difference between the purchase price and the fair market value at the time of utilization – can trigger AMT. This means that even if you don’t owe regular income tax when you exercise your options, the AMT might still apply, leading to unexpected tax liabilities.
In 2026, the AMT exemption is set at $90,100 for single filers and $140,200 for married couples filing jointly, with phaseout thresholds beginning at $500,000 for singles and $1,000,000 for married couples. If your family’s AMT ends up being higher than what you usually owe, it can lead to unexpected financial stress. But don’t worry, there’s a silver lining: you might receive an AMT credit in future years that can help ease your tax burden.
Understanding the ISO tax implications is crucial for families as they navigate the complexities of exercising ISOs and planning their finances effectively. For instance, exercising a smaller number of options or selling shares in the same year can help mitigate AMT exposure. We recommend reaching out to a tax professional who can help you create a plan that fits your family’s needs and keeps those AMT surprises at bay. Together, we can navigate these complexities and ensure your family’s financial future remains secure.
Conclusion
Imagine the relief of knowing how to navigate the tax implications of Incentive Stock Options (ISOs) for your family’s financial future. When you understand how ISOs work, you can make choices that not only grow your wealth but also help you avoid unexpected tax surprises. Holding onto your ISOs for the right time can mean big savings for your family, making them a smart part of your compensation package.
We’ve explored the ins and outs of ISO tax treatment, including how the Alternative Minimum Tax (AMT) can affect your family’s finances. You might find that exercising ISOs can lead to AMT liabilities, which can be a bit of a shock if you’re not prepared. We shared stories about how planning ahead – like timing when to sell shares – can help you manage taxes and keep your family finances safe.
Understanding ISO tax implications isn’t just about following the rules; it’s about giving your family the power to make smart financial choices for the future. Working with a caring advisor can help you navigate these complexities and ensure a bright financial future for your family. By taking these steps, you’re not just managing taxes; you’re paving the way for a secure and thriving future for your family.
Frequently Asked Questions
What are Incentive Stock Options (ISOs)?
Incentive Stock Options (ISOs) are a type of employee stock option that allows you to buy company shares at a set price, offering potential tax benefits under specific conditions.
What are the tax benefits of ISOs?
ISOs can provide favorable tax treatment if you hold the shares for at least one year after exercising and two years after the grant date, allowing you to benefit from long-term capital gains tax rates, which are typically lower than ordinary income tax rates.
How do vesting schedules work with ISOs?
ISOs often come with vesting schedules that encourage employees to remain with the company and contribute to its growth before they can exercise their options.
What is the Alternative Minimum Tax (AMT) in relation to ISOs?
The AMT can affect ISOs because the bargain element-the difference between the acquisition price and the fair market value at the time of exercise-must be reported as income for AMT purposes, which can lead to unexpected tax liabilities.
What happens if I exercise my ISOs but do not sell the shares in the same year?
If you exercise your ISOs and do not sell the shares in the same year, you may incur AMT liabilities based on the market value at the time of exercise, even if you haven’t realized any cash from the shares.
How can I avoid AMT implications when exercising ISOs?
To avoid AMT implications, you can sell the stock in the same year you exercise your options, which allows you to be taxed at ordinary income rates instead of AMT.
Why is it important to understand ISOs for family financial planning?
Understanding ISOs is crucial for families as it helps in making informed decisions regarding compensation and potential tax implications, ultimately benefiting their financial well-being.
List of Sources
- Define Incentive Stock Options (ISOs)
- Incentive Stock Options (https://turbotax.intuit.com/tax-tips/investments-and-taxes/incentive-stock-options/L4azWgfwy)
- Incentive Stock Options (ISO): How ISOs Work (https://carta.com/learn/equity/stock-options/iso)
- Windham Brannon (https://windhambrannon.com/blog/incentive-stock-options-considerations-for-tech-companies)
- Incentive Stock Options Explained (https://marinerwealthadvisors.com/insights/incentive-stock-options-explained)
- Explore ISO Tax Treatment and Implications
- Capital gains tax: Definition, rates, and ways to save | Fidelity (https://fidelity.com/learning-center/smart-money/capital-gains-tax-rates)
- Mastering ISO and AMT Implications (https://trayecto.io/blog/mastering-isos-and-amt)
- Got Incentive Stock Options? Beware of the AMT (https://kahnlitwin.com/blogs/tax-blog/got-incentive-stock-options-beware-of-the-amt)
- Stock Options and the Alternative Minimum Tax (AMT) (https://nceo.org/articles/stock-options-alternative-minimum-tax-amt)
- Understand ISO Exercise Scenarios and Tax Consequences
- 3 Strategies To Optimize Incentive Stock Options (ISOs) (https://kitces.com/blog/incentive-stock-options-iso-amt-financial-plan-taxes-portfolio)
- Incentive Stock Options (https://turbotax.intuit.com/tax-tips/investments-and-taxes/incentive-stock-options/L4azWgfwy)
- How ISOs Trigger Alternative Minimum Tax in 2026 (https://wealthgenadvisor.com/how-isos-trigger-alternative-minimum-tax-in-2026)
- Exercising Stock Options in California: 2026 Tax Guide (https://esofund.com/blog/exercising-stock-options-in-california)
- The Return of AMT: What High Earners Need to Know in 2026 (https://wealthspire.com/blog/the-return-of-alternative-minimum-tax-amt-what-high-earners-need-to-understand-about-2026)
- Analyze the Role of Alternative Minimum Tax (AMT) in ISOs
- What is the Alternative Minimum Tax? How AMT Works & Calculation (https://carta.com/learn/equity/stock-options/taxes/amt)
- What Is the Alternative Minimum Tax (AMT)? (https://schwab.com/learn/story/beware-these-amt-triggers)
- 2026 Tax Brackets (https://taxfoundation.org/data/all/federal/2026-tax-brackets)
- What is the alternative minimum tax (AMT)? — Secfi (https://secfi.com/learn/alternative-minimum-tax)
- Alternative Minimum Tax (AMT): Who Pays It and How It Works (https://reedcorp.tax/helpful-guides/alternative-minimum-tax-explained)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading