

Key Highlights
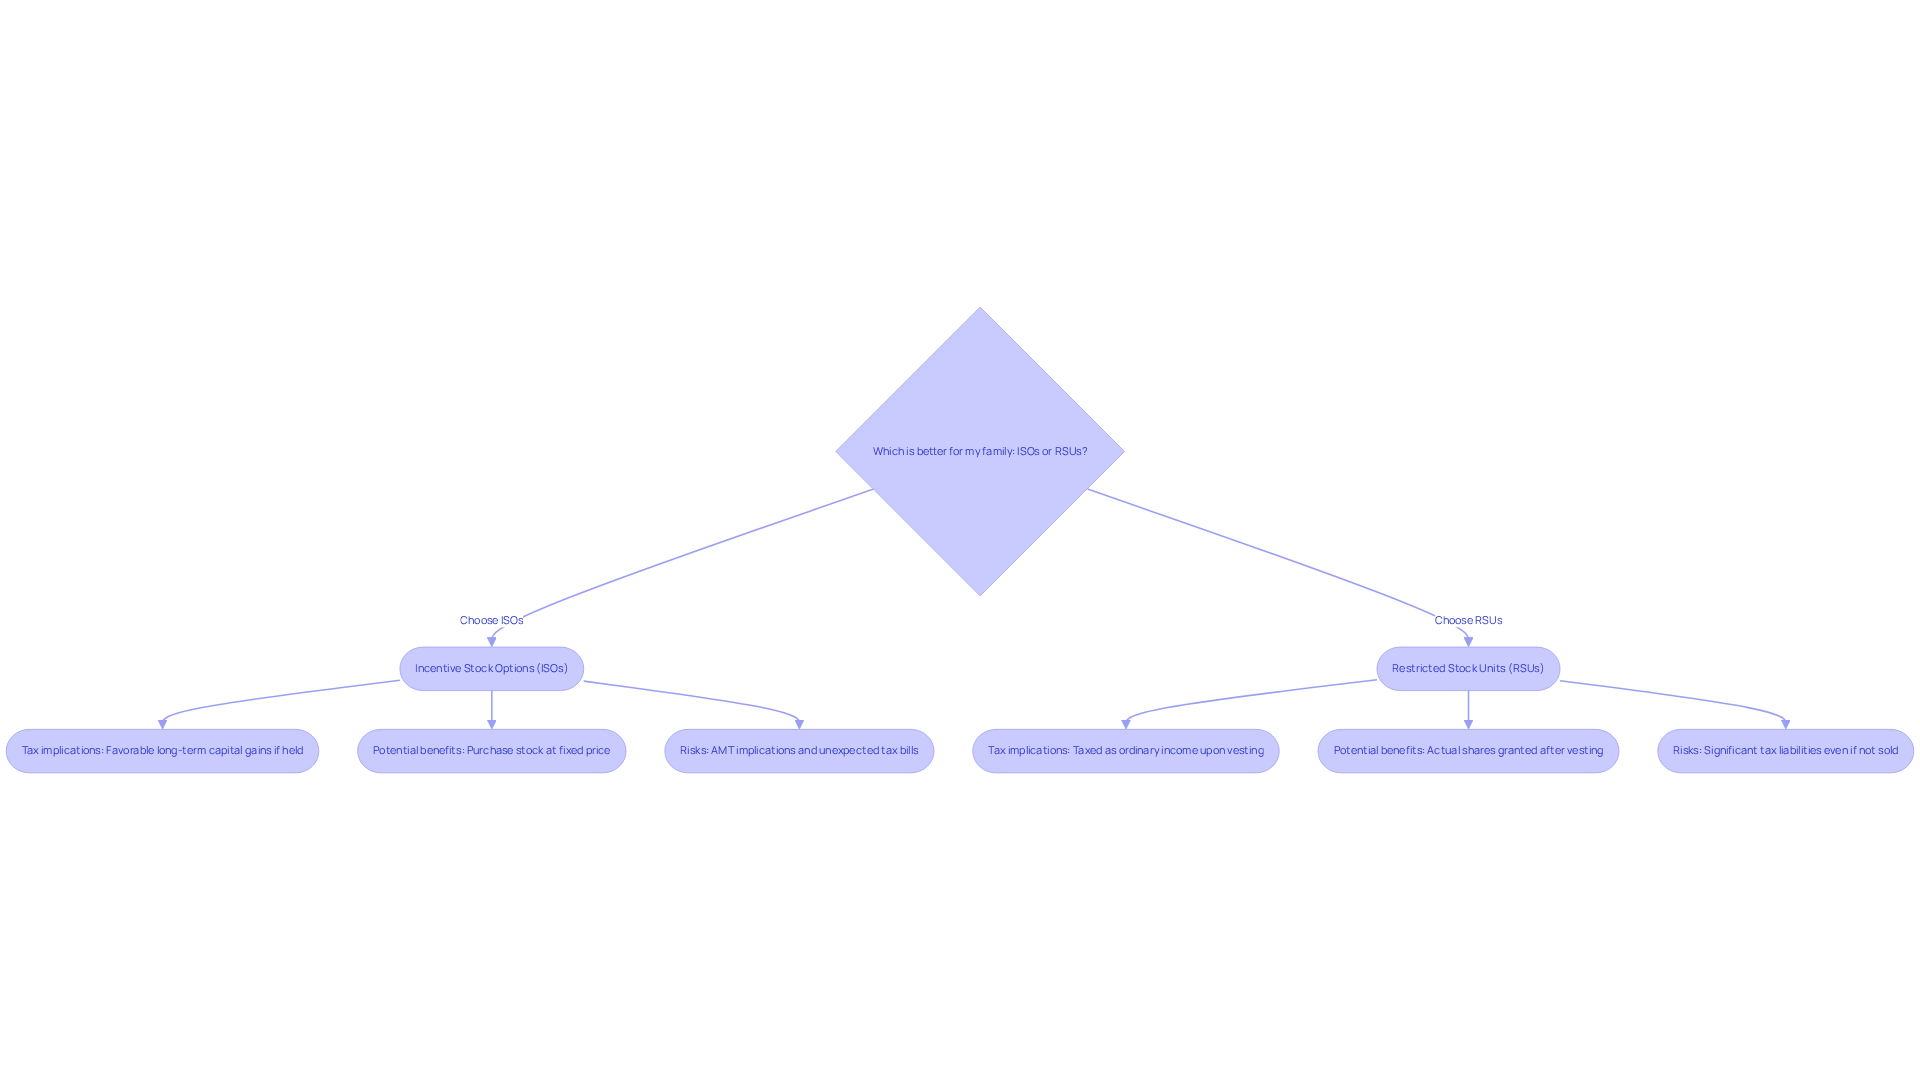
- Incentive Stock Options (ISOs) allow families to purchase company stock at a set price, potentially benefiting from lower tax rates if held long-term.
- Exercising ISOs may trigger the Alternative Minimum Tax (AMT), necessitating careful planning to avoid unexpected tax bills.
- Restricted Stock Units (RSUs) are taxed as ordinary income upon vesting, which can lead to significant tax liabilities, especially in high-tax states like California.
- Families should consider diversifying investments to mitigate risks associated with relying too heavily on company stock from vested RSUs.
- Understanding the tax treatment of ISOs vs. RSUs is crucial for effective financial planning and managing tax obligations.
- Consulting with financial and tax professionals can help families navigate equity compensation and develop strategies to minimise tax liabilities.
- Regular reviews of equity compensation strategies are essential to adapt to changing financial situations and tax laws.
Introduction
Imagine feeling overwhelmed by the complexities of stock options while trying to secure your family’s financial future. It’s important to understand how the tax implications of Incentive Stock Options (ISOs) and Restricted Stock Units (RSUs) can shape your family’s financial landscape. Many parents feel lost when it comes to understanding stock options and their implications. Without proper guidance, families may face unexpected tax burdens that could strain their finances.
In this article, we’ll explore the key differences between ISOs and RSUs, sharing insights and strategies designed to help you make informed financial choices for your family.
Define ISOs and RSUs: Key Concepts for Young Parents
Imagine the weight of financial decisions when you’re trying to secure your family’s future. Incentive Stock Options can be a way to invest in your family’s future by purchasing company stock at a set price. If you hold onto these shares for a while, you might benefit from lower tax rates under the iso vs rsu tax treatment. But, it’s important to be aware that exercising these options could lead to unexpected tax bills, particularly in the context of iso vs rsu tax treatment and timing.
Now, let’s talk about Restricted Stock Units (RSUs). These can feel like a promise of future security, but they come with their own set of challenges that you need to navigate carefully. When RSUs vest, they’re taxed as ordinary income, which can lead to a hefty tax bill, illustrating the implications of iso vs rsu tax treatment, even if you don’t sell the shares right away. Imagine the stress of facing unexpected tax bills when you’re trying to provide for your family.
Understanding these concepts, including iso vs rsu tax treatment, is crucial for young parents as they plan their financial futures. For instance, consider how relying too heavily on your company’s stock due to vested RSUs can be risky. By diversifying your investments, you can protect your family’s future from the uncertainties of the market.
At Bright Advisers, we’re here for you. We focus on customized planning strategies that can assist households in effectively managing their equity compensation. Consulting with our advisors can offer valuable insights into enhancing the advantages of stock options and restricted stock units while considering your household’s unique monetary circumstances. Navigating these options wisely can be the key to a more secure future for your loved ones.
Explore Tax Treatment: ISOs vs. RSUs Explained
Imagine trying to secure your family’s future while navigating the complexities of stock options and restricted stock units, including the ISO vs RSU tax treatment; it’s a challenge many parents face today.
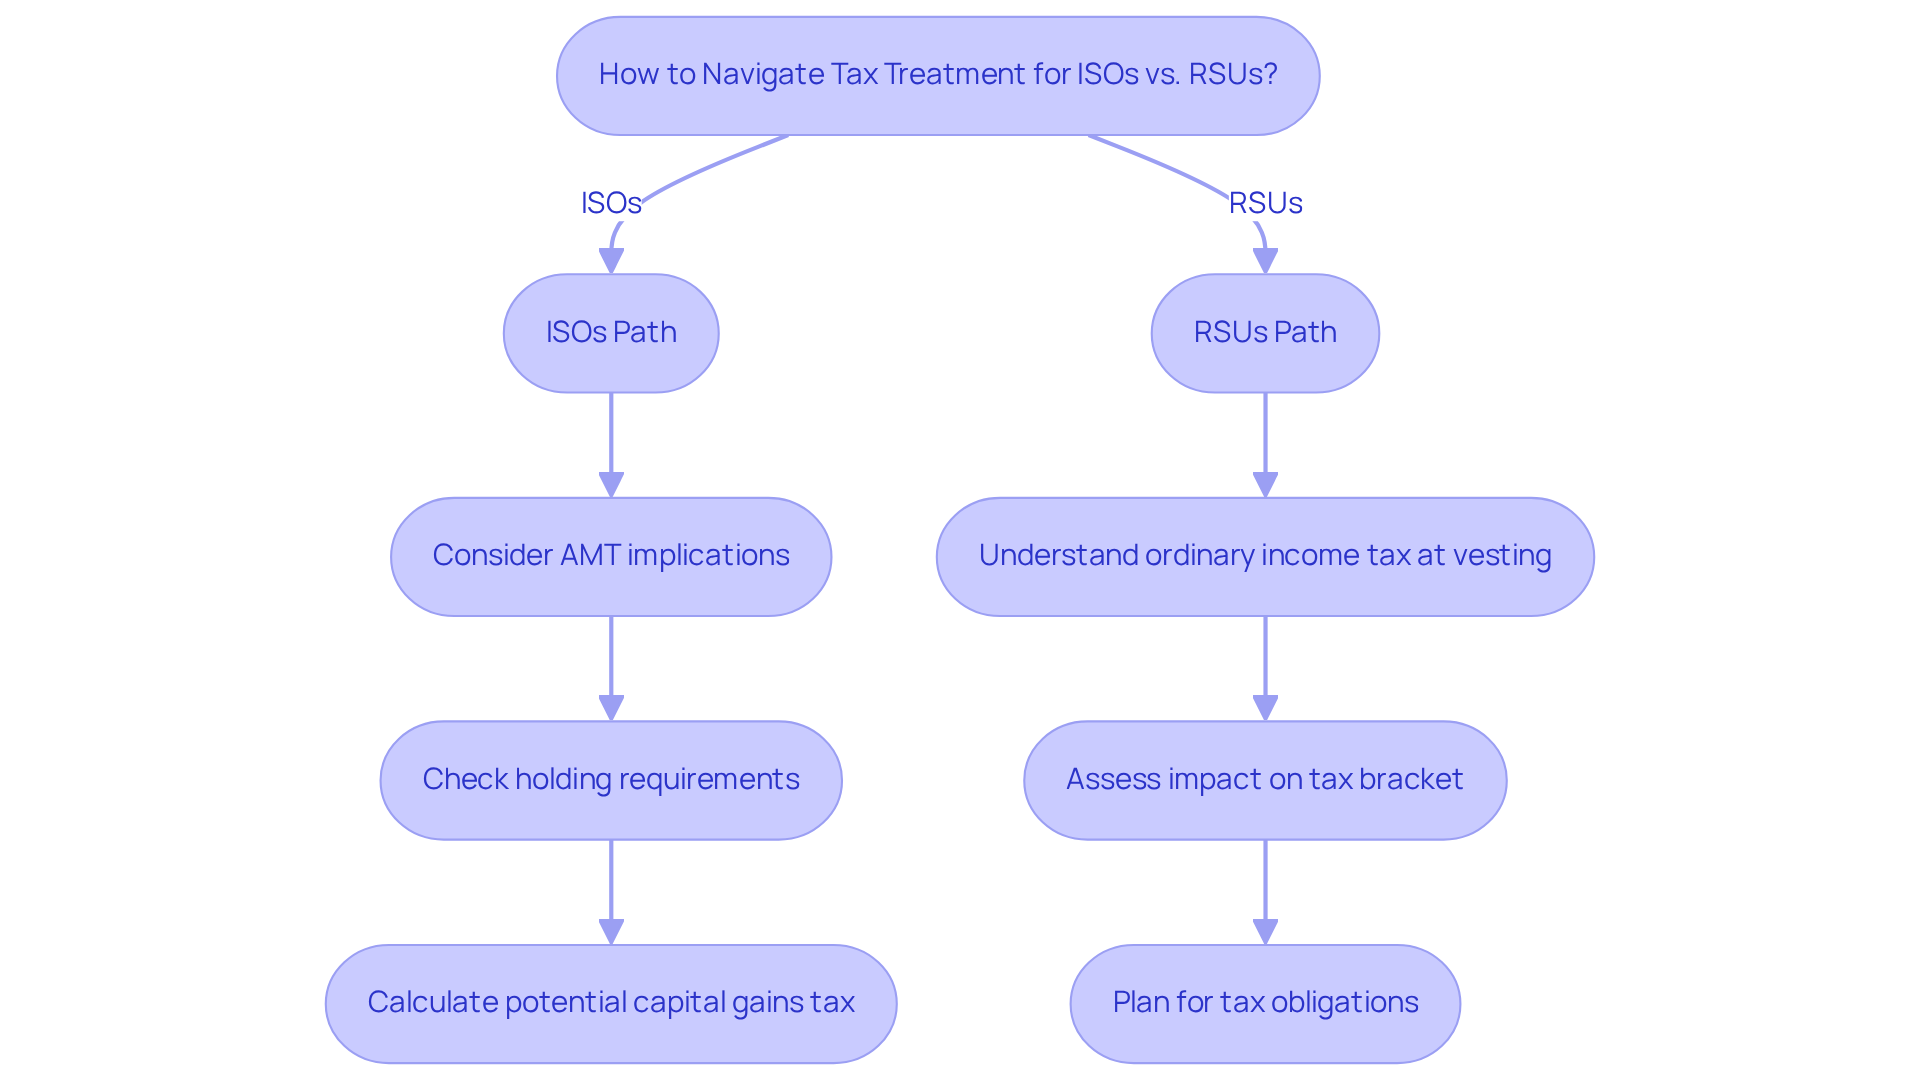
Stock Options: Exercising stock options might trigger the Alternative Minimum Tax (AMT), so it’s important to plan carefully. If you meet specific holding requirements, gains may be taxed at the lower capital gains rate. For instance, in 2026, the AMT exemption for single filers is set at $90,100, while for married couples filing jointly, it is $140,200. This means families need to think carefully about when and how many ISOs to exercise to steer clear of surprise tax bills.
RSUs: In contrast, RSUs are taxed as ordinary income when they vest. The fair market value of the shares at that time is added to your taxable income, which can potentially push your household into a higher tax bracket. For example, if you receive RSUs that vest at a value of $20,000, that amount is included in your taxable income for that year. Understanding the ISO vs RSU tax treatment is essential for families to effectively manage their tax obligations and prepare for upcoming expenses.
When you understand the ISO vs RSU tax treatment, you can make choices that truly support your family’s dreams and responsibilities. We’re here for you, ready to help you navigate this journey together.
Evaluate Your Options: Choosing Between ISOs and RSUs
When it comes to choosing between Incentive Stock Options (ISOs) and Restricted Stock Units (RSUs), young parents face important decisions that can impact their family’s financial future.
-
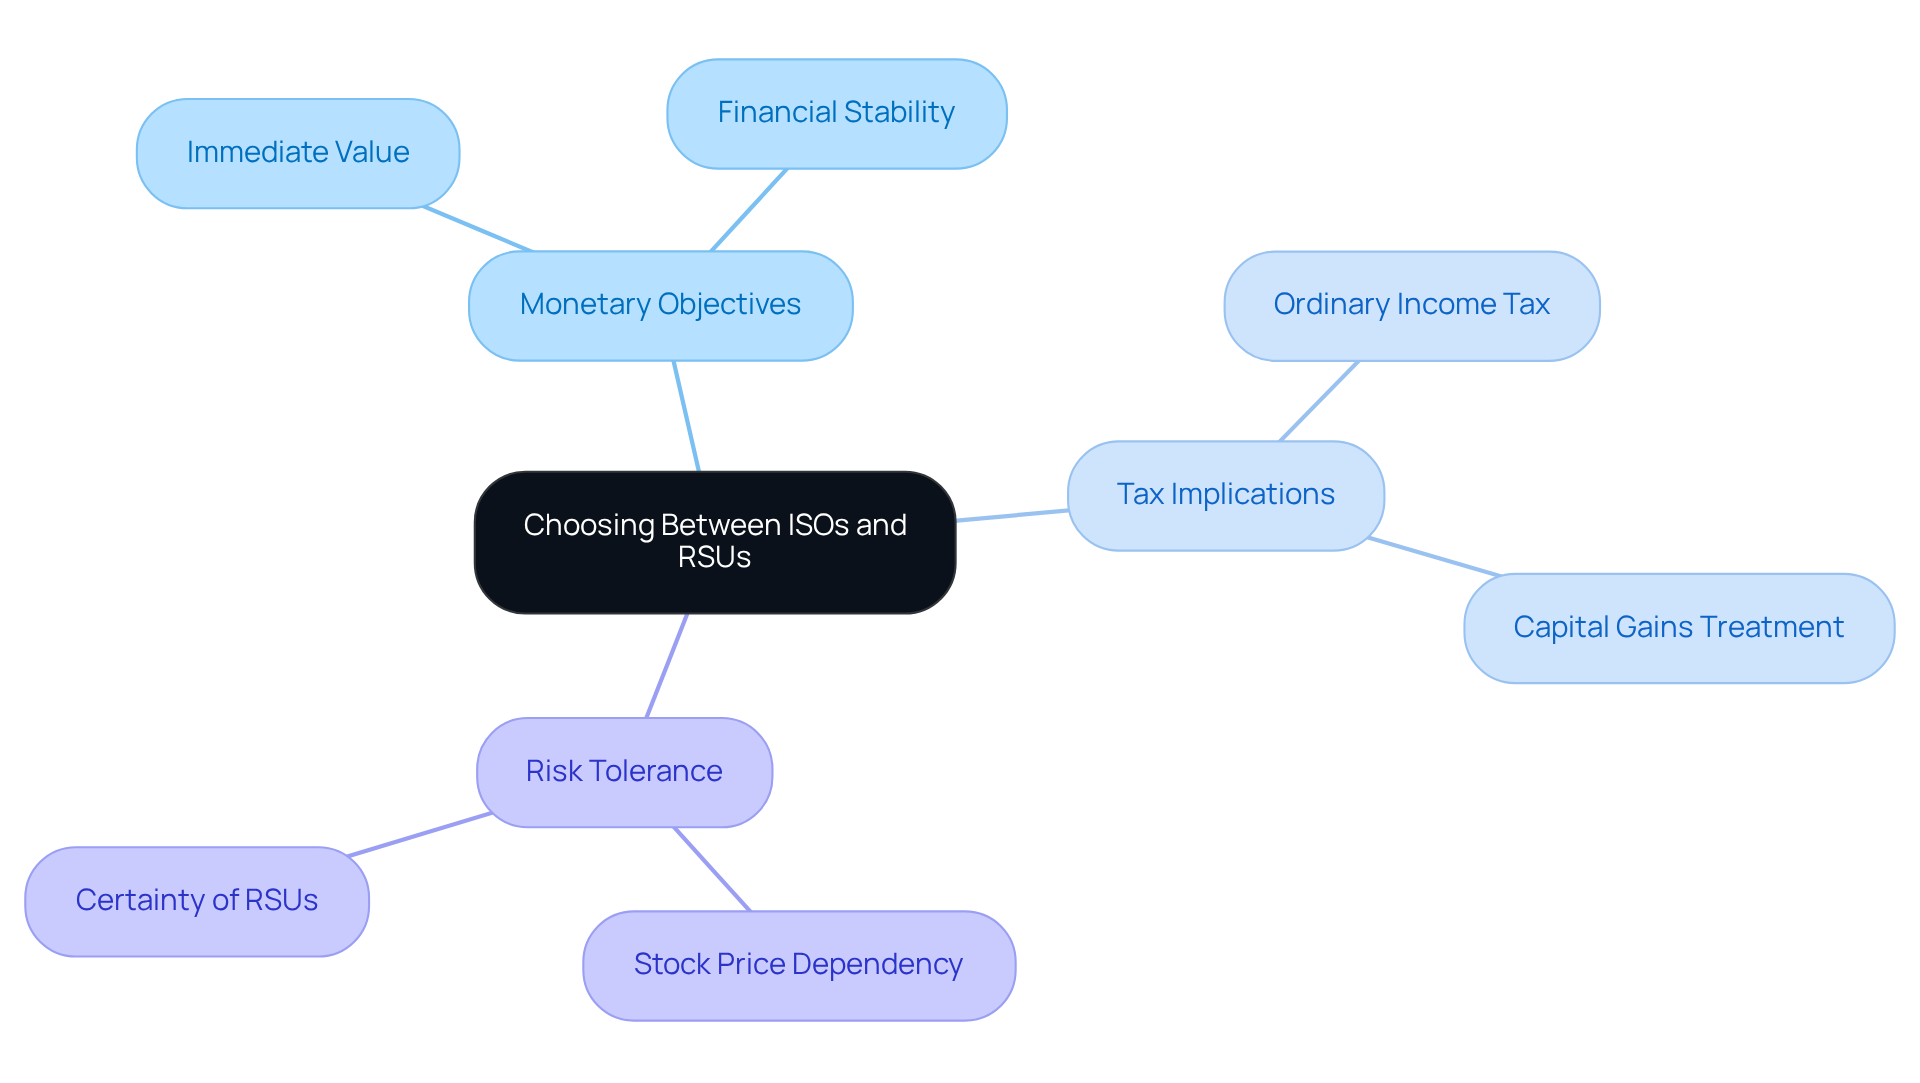
Monetary Objectives: If you’re looking for immediate value, RSUs might be the better choice since they give you shares right after they vest, making the outcome more predictable. For example, Emily and Mark, a couple seeking financial stability, found that understanding their options helped them create a plan that allowed them the freedom to choose whether or not to continue working.
-
It’s important to understand the tax implications associated with each option, particularly in the context of iso vs rsu tax treatment. RSUs are taxed as ordinary income at the time of vesting, which can lead to significant tax liabilities, especially in high-tax states like California, highlighting the differences in iso vs rsu tax treatment where rates can reach up to 50.3%. On the other hand, the iso vs rsu tax treatment may provide advantageous capital gains treatment if specific criteria are fulfilled, potentially benefiting households in lower tax brackets in the future. Bright Advisers highlights the significance of tax planning strategies, including tax-loss harvesting, to assist households in navigating these complexities effectively.
-
Risk Tolerance: Assess your comfort level with the risks tied to each option. ISOs can be riskier since their value depends on stock price performance; if the stock price does not exceed the strike price, the options may become worthless. In contrast, RSUs offer greater certainty, as they are granted outright upon vesting, making them a safer option for households prioritizing stability. Emily and Mark’s experience with Bright Advisers demonstrates how a thorough strategy can assist households in managing these risks while pursuing their objectives.
By taking the time to think through these factors, you can make informed choices that fit your family’s budget and needs. Almost 60% of millennials convey a positive outlook on their finances, suggesting an increasing awareness of the significance of strategic monetary planning. By partnering with a fiduciary advisor like Bright Advisers, families can confidently navigate their financial journey and work towards their goals together. If you’re interested in personalized planning for your finances, consider joining our waitlist to learn more about how we can assist you. Please note that past performance does not guarantee future results, and securities investments are subject to risk.
Consult Professionals: Navigating Equity Compensation Wisely
Imagine feeling overwhelmed by the complexities of Incentive Stock Options and Restricted Stock Units while trying to manage your family’s financial future. Here are some key steps to consider:
-
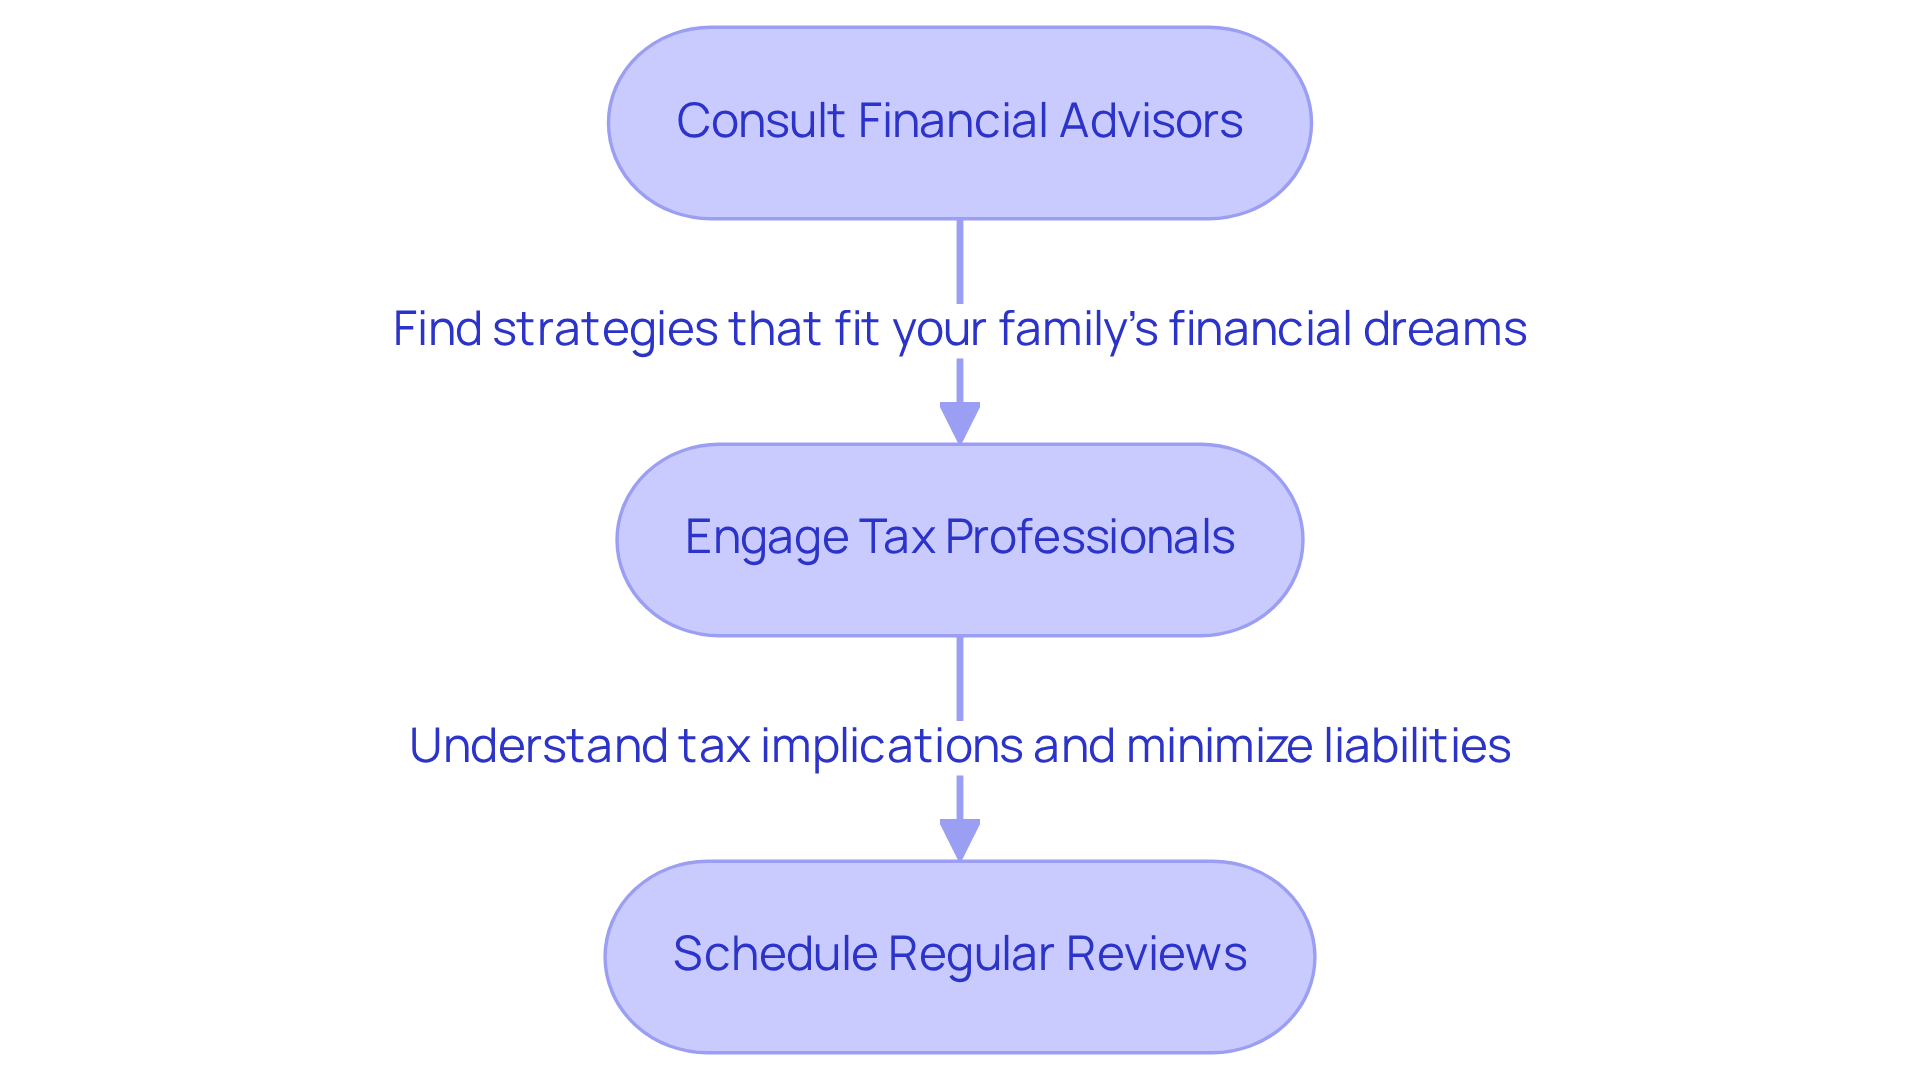
Talk to Financial Advisors: Talking to a financial advisor who understands equity compensation can help you find strategies that truly fit your family’s financial dreams. At Bright Advisers, our team works closely with families to create comprehensive plans that align with your values and vision. This way, your equity compensation can seamlessly fit into your overall wealth management plan. Our in-house technology enhances personalized planning by avoiding costly mutual funds and capturing tax-loss harvesting opportunities, which can significantly improve your strategy.
-
Engage tax professionals to understand the iso vs rsu tax treatment and its implications for equity compensation. Tax professionals can help you develop strategies to minimize liabilities and ensure compliance with tax regulations. For instance, in the context of iso vs rsu tax treatment, NSOs are taxed as ordinary income upon vesting, while ISOs may trigger alternative minimum tax upfront but allow for more favorable long-term capital gains treatment if held appropriately. Bright Advisers employs advanced technology to identify tax-loss harvesting opportunities, further enhancing your economic outcomes.
-
Schedule Regular Reviews: Regularly assessing your equity compensation strategy is essential as your economic situation evolves. This proactive approach can assist you in adjusting to changes in tax laws, market conditions, and your household’s needs. Families like Emily and Mark have found clarity and peace of mind by working with Bright Advisers, allowing them to make career choices that align with their family values.
By consulting professionals, young parents can navigate the complexities of equity compensation more effectively, ensuring informed decisions that support their family’s financial future. With the right support, you can confidently navigate these challenges and secure a brighter financial future for your family.
Conclusion
It can be tough to understand how Incentive Stock Options (ISOs) and Restricted Stock Units (RSUs) affect your family’s financial future, but we’re here to help you through it. The way these options are taxed can really change how you plan your finances, and we want to make sure you’re aware of that.
When you understand how ISOs and RSUs are taxed, you can make choices that truly fit your family’s goals. ISOs can be a great option if you hold onto them long enough, while RSUs might hit your income harder when they vest, which could affect your tax bracket.
Talking to a financial or tax professional can really help you find the best strategies to handle these complexities with confidence. It’s also important to think about your family’s financial goals and how much risk you’re comfortable with when choosing between these options.
Getting to a secure financial future for your family takes thoughtful planning and smart choices, and we’re here to support you every step of the way. Working with a caring fiduciary advisor like Bright Advisers can give you the support you need to understand equity compensation better.
When you take steps to seek guidance, you can feel more confident in managing your family’s financial future and moving toward your dreams.
Frequently Asked Questions
What are Incentive Stock Options (ISOs)?
Incentive Stock Options (ISOs) are a type of stock option that allows employees to purchase company stock at a predetermined price, potentially benefiting from lower tax rates if the shares are held for a certain period.
What are Restricted Stock Units (RSUs)?
Restricted Stock Units (RSUs) are a form of compensation where employees receive shares of stock that vest over time. Once vested, RSUs are taxed as ordinary income, which can result in a significant tax bill.
How does the tax treatment differ between ISOs and RSUs?
ISOs may offer lower tax rates if shares are held long enough, while RSUs are taxed as ordinary income upon vesting, regardless of whether the shares are sold immediately.
What are the potential tax implications of exercising ISOs?
Exercising ISOs can lead to unexpected tax bills, particularly if not planned for properly, especially in relation to the timing of the exercise and sale of the shares.
Why is it important for young parents to understand ISOs and RSUs?
Understanding ISOs and RSUs is crucial for young parents as they plan their financial futures, helping them navigate potential tax implications and make informed investment decisions.
What risks are associated with relying too heavily on company stock from vested RSUs?
Relying too heavily on company stock from vested RSUs can be risky, as it exposes families to market uncertainties. Diversifying investments can help mitigate this risk.
How can Bright Advisers assist families with equity compensation?
Bright Advisers offers customized planning strategies to help families effectively manage their equity compensation, providing insights into maximizing the benefits of stock options and RSUs based on their unique financial situations.
List of Sources
- Define ISOs and RSUs: Key Concepts for Young Parents
- ISOs vs RSUs: Optimize Stock Benefits | Confluence FP (https://confluencefp.com/isos-vs-rsus-strategies-to-optimize-your-employee-stock-benefits)
- Stock Options 101: ISO, NQSO, and Restricted Stock | Greenbush Financial Group (https://greenbushfinancial.com/all-blogs/stock-options-101-iso-nqso-restricted-stock)
- Incentive Stock Options (ISO): How ISOs Work (https://carta.com/learn/equity/stock-options/iso)
- Equity Compensation in 2026: ISO vs NSO vs RSU + Vesting & Taxes (https://waveup.com/blog/equity-compensation)
- mcdonaldjacobs.cpa (https://mcdonaldjacobs.cpa/comparing-nsos-isos-and-rsus-tax-and-planning-guide)
- Explore Tax Treatment: ISOs vs. RSUs Explained
- Tax Implications for Stock-Based Compensation – Bloomberg Tax (https://pro.bloombergtax.com/insights/federal-tax/tax-implications-for-stock-based-compensation)
- How ISOs Trigger Alternative Minimum Tax in 2026 (https://wealthgenadvisor.com/how-isos-trigger-alternative-minimum-tax-in-2026)
- ISO AMT: The 2026 Alternative Minimum Tax Math | Taxstra (https://taxstra.com/iso-amt)
- Tax Season 2026: Reporting RSUs, ISOs, ESPPs, and Stock Compensation (https://vipwealthadvisors.com/insights/tax-season-2026-reporting-stock-compensation)
- Equity Compensation in 2026: ISO vs NSO vs RSU + Vesting & Taxes (https://waveup.com/blog/equity-compensation)
- Evaluate Your Options: Choosing Between ISOs and RSUs
- 2024 CFP Board Millennials’ Financial Milestones Survey (https://cfp.net/industry-insights/reports-and-statistics/consumer-surveys/2024-cfp-board-millennials-financial-milestones-survey)
- Essential Checklist: Equity Grant vs RSU for Young Parents – Bright Advisers (https://brightadvisers.com/post/essential-checklist-equity-grant-vs-rsu-for-young-parents)
- RSUs vs. ISOs: Equity Compensation 101 | Wealthspire (https://wealthspire.com/blog/rsus-vs-isos-equity-compensation-101)
- RSU vs. Stock Options: Which is Best for Young Families? – Bright Advisers (https://brightadvisers.com/post/rsu-vs-stock-options-which-is-best-for-young-families)
- RSU vs Stock Options: Taxes, Risk, and Value Compared | Taxstra (https://taxstra.com/rsu-vs-stock-options)
- Consult Professionals: Navigating Equity Compensation Wisely
- Schwab Study: Equity Compensation Plays Major Role in Workers’ Retirement Plans and Financial Wellbeing (https://pressroom.aboutschwab.com/press-releases/press-release/2025/Schwab-Study-Equity-Compensation-Plays-Major-Role-in-Workers-Retirement-Plans-and-Financial-Wellbeing/default.aspx)
- Industry Statistics (https://investmentadviser.org/industry-snapshots)
- Financial Advisor Statistics in 2026: Growth and Trends in the Financial Advisory Industry in the USA (https://randallwealthgroup.com/financial-advisor-statistics)
- Tax Impacts of Equity Compensation (https://wsadvisors.com/tax-impacts-of-equity-compensation)
- Cerulli Associates | More Than 72% of Financial Advisors Are… (https://cerulli.com/press-releases/more-than-72-of-financial-advisors-are-compensated-by-fee-based-models)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading