

Key Highlights
- Per stirpes is a method of distributing assets where a deceased heir’s share passes to their descendants, ensuring family wealth is preserved.
- Over 50% of U.S. adults lack an estate plan, highlighting the need for proper beneficiary assignments.
- Case studies show that per stirpes designations prevent disinheritance of grandchildren in 25-30% of cases involving multiple generations.
- Per stirpes prioritises fairness among family branches, while per capita distributes assets equally among surviving heirs.
- Families should regularly review and update beneficiary designations, especially after significant life events, to reflect current wishes.
- Engaging an estate planning attorney can help ensure that beneficiary designations are clearly articulated and legally sound.
- Open communication with family members about estate planning decisions can prevent misunderstandings and disputes.
Introduction
Imagine feeling secure about your family’s financial future, even amidst the challenges of estate planning. One important idea to consider is the life insurance beneficiary designation called ‘per stirpes.’ This method ensures that if a beneficiary passes away before the policyholder, their share of the inheritance is automatically passed down to their descendants, preserving the family’s wealth across generations. Yet, many families might not realize how this designation can truly benefit them. By understanding per stirpes, families can take meaningful steps to protect their legacy and ensure their loved ones are cared for.
Define Per Stirpes Beneficiary Designation
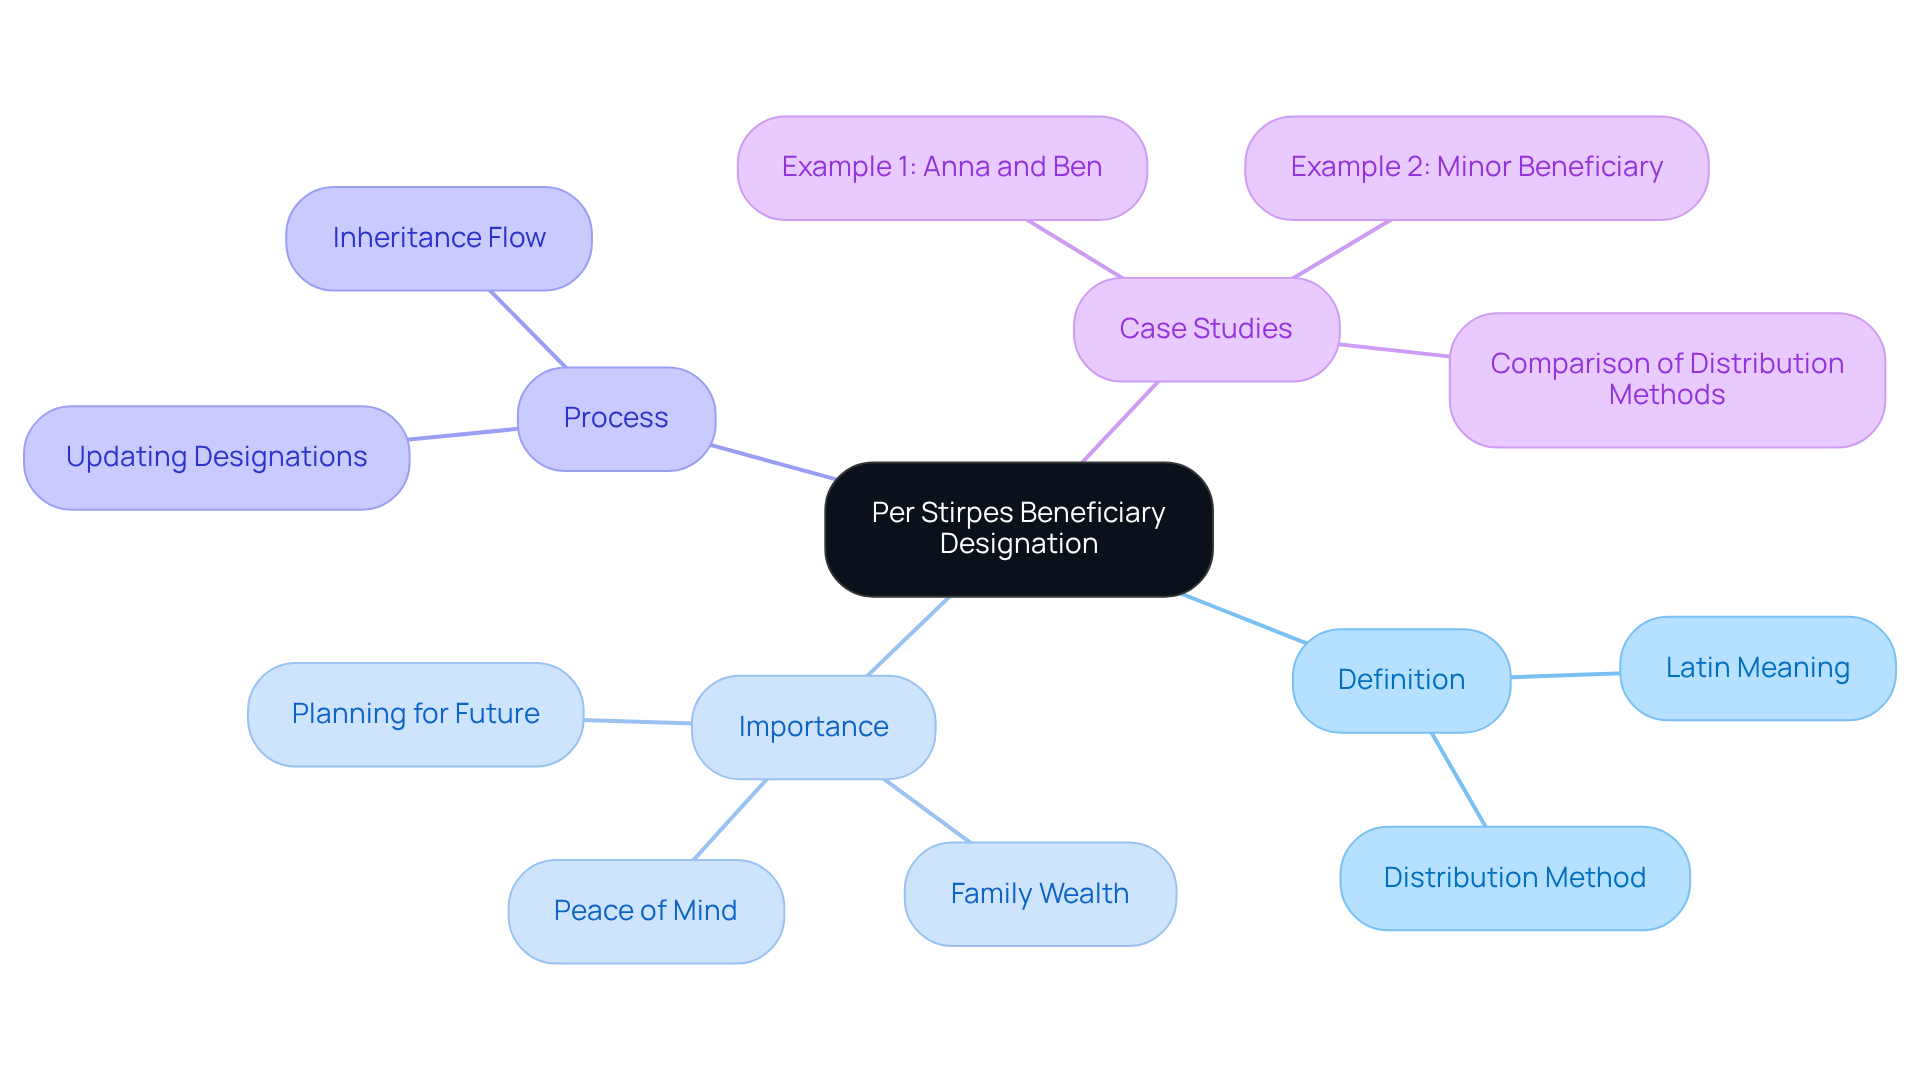
Imagine the peace of mind that comes from knowing your family’s future is secure, even when life takes unexpected turns. The term ‘per stirpes’ is a Latin phrase meaning ‘by branch.’ In estate planning, the concept of life insurance beneficiary per stirpes refers to a method of distributing assets where, if an heir dies before the testator, their portion of the inheritance automatically passes down to their descendants. For example, if a parent designates their offspring as a beneficiary and that offspring dies before the parent, the offspring’s children (the grandchildren of the testator) would receive their parent’s portion. This method helps keep your family’s wealth intact, passing down your legacy to future generations.
It’s common for young families to feel lost when it comes to estate planning. Understanding this concept is important for families like yours, as it aids in planning effectively for your children’s financial futures. You want to ensure that assets are not lost due to unexpected situations. Significantly, over 50% of U.S. adults lack an estate plan, highlighting the essential need for appropriate recipient assignments. Regularly reviewing and updating these designations, especially after major life events, can help ensure that assets are distributed according to current wishes and avoid complications.
Case studies demonstrate the importance of life insurance beneficiary per stirpes; for instance, if two offspring are designated as recipients and one dies, the living child retains their portion, while the deceased child’s portion is distributed among their offspring. This ensures that the inheritance adheres to the family lineage. Not having a plan can lead to uncertainty and potential loss of your family’s assets. This method serves as a generational safety net, enabling descendants to inherit as a life insurance beneficiary per stirpes if a designated recipient predeceases the account holder. By understanding per stirpes, you can ensure your family’s legacy is protected, no matter what happens.
Differentiate Between Per Stirpes and Per Capita Designations
Imagine the peace of mind that comes from knowing your family’s future is secure, even when you’re not there to guide them. Let’s explore two important ways to distribute your assets: one being life insurance beneficiary per stirpes and the other being per capita. Each has its own impact on your family’s future.
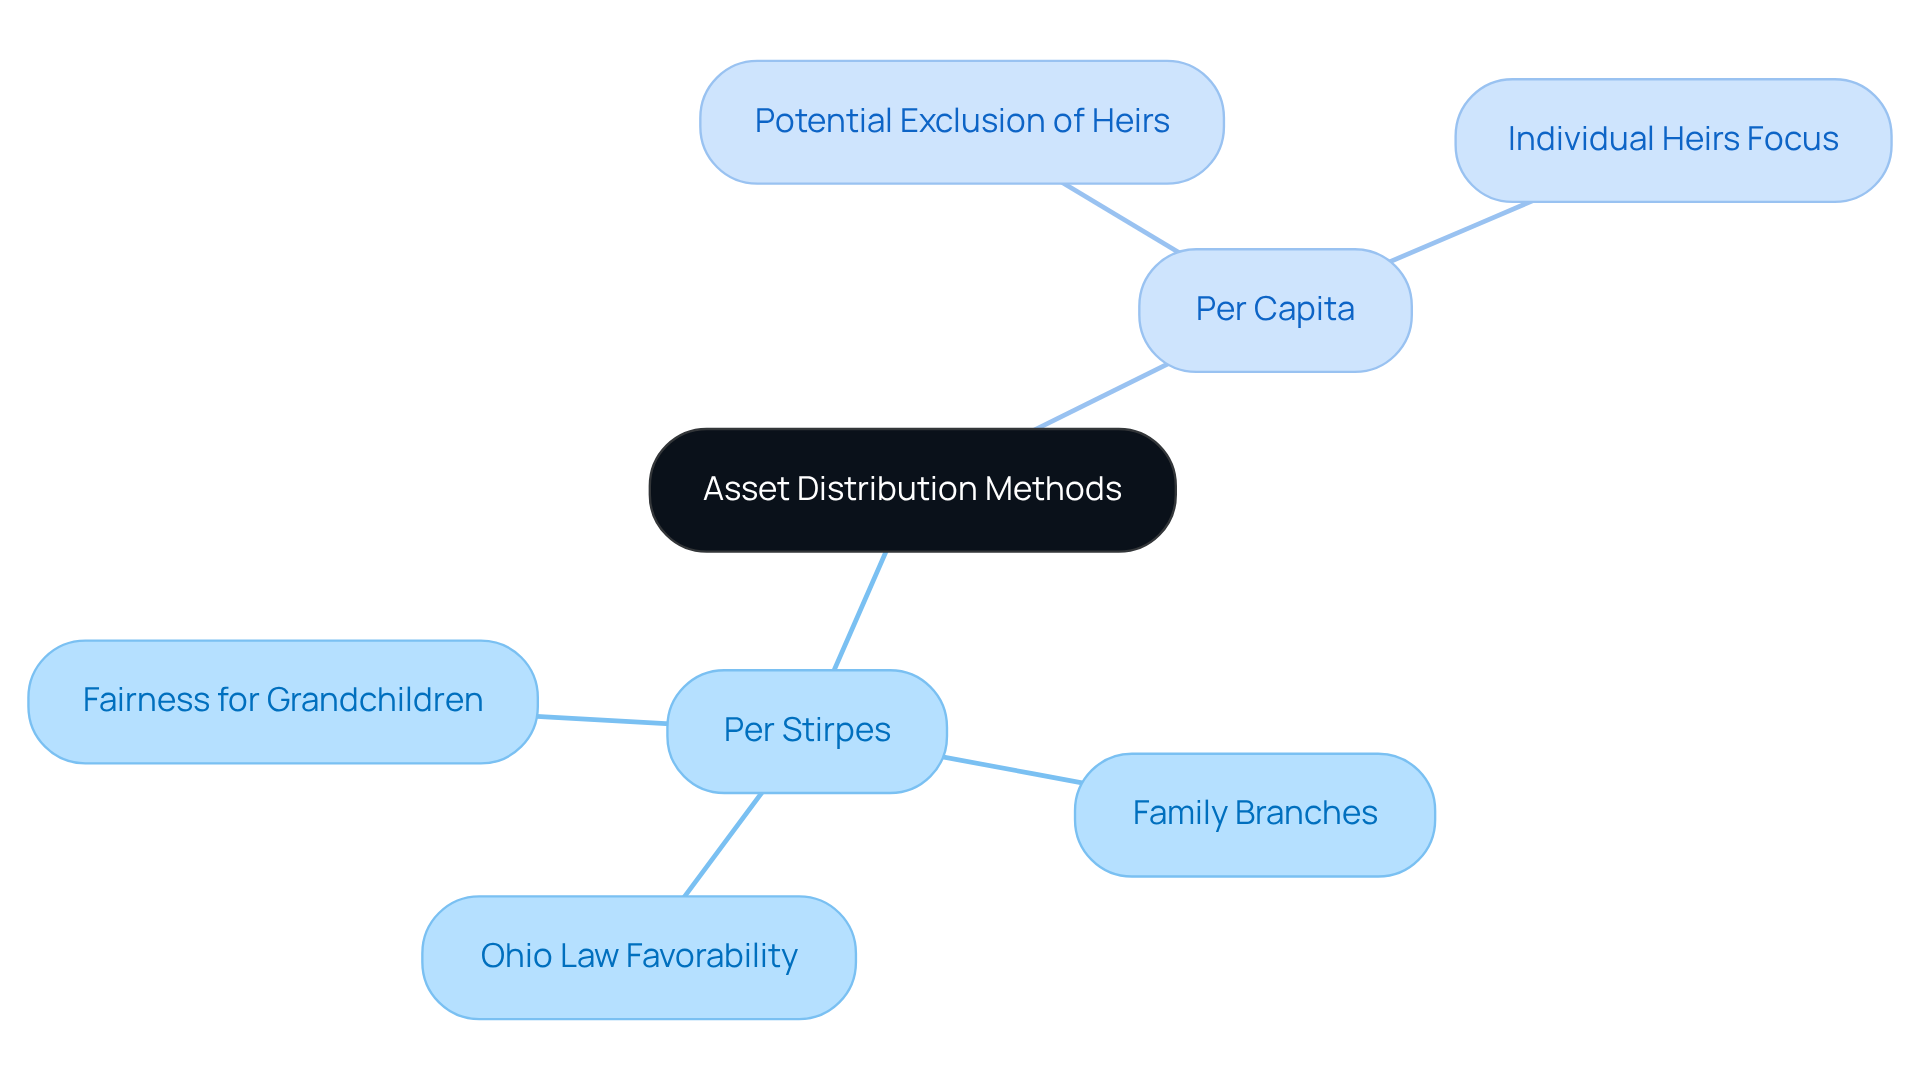
Understanding these differences is key to making sure your estate plan reflects what matters most to your family. Many families prefer using life insurance beneficiary per stirpes because it ensures that everyone, including grandchildren, is treated fairly, while per capita can sometimes leave loved ones out in the cold. As an expert puts it, the choice really comes down to whether you want to prioritize fairness among family branches or individual heirs.
In Ohio, if someone passes away without a will, the law favors distribution to the life insurance beneficiary per stirpes, which can help keep families united. It’s also important to remember that not all assets are covered by a will; some, like life insurance and retirement accounts, need separate beneficiary assignments. Choosing the right method can mean the difference between your grandchildren receiving their fair share or being left out entirely.
By understanding these options, you can ensure that your family’s legacy is honored and protected for generations to come. Together, we can navigate this journey and make informed decisions that reflect your family’s values.
Apply Per Stirpes Designations in Estate Planning
Imagine the peace of mind that comes from knowing your family’s future is secure, even when you’re not there to guide them. To effectively apply designations such as life insurance beneficiary per stirpes in estate planning, families should start by clearly identifying their heirs and understanding their family structure. Here are some gentle steps to consider:
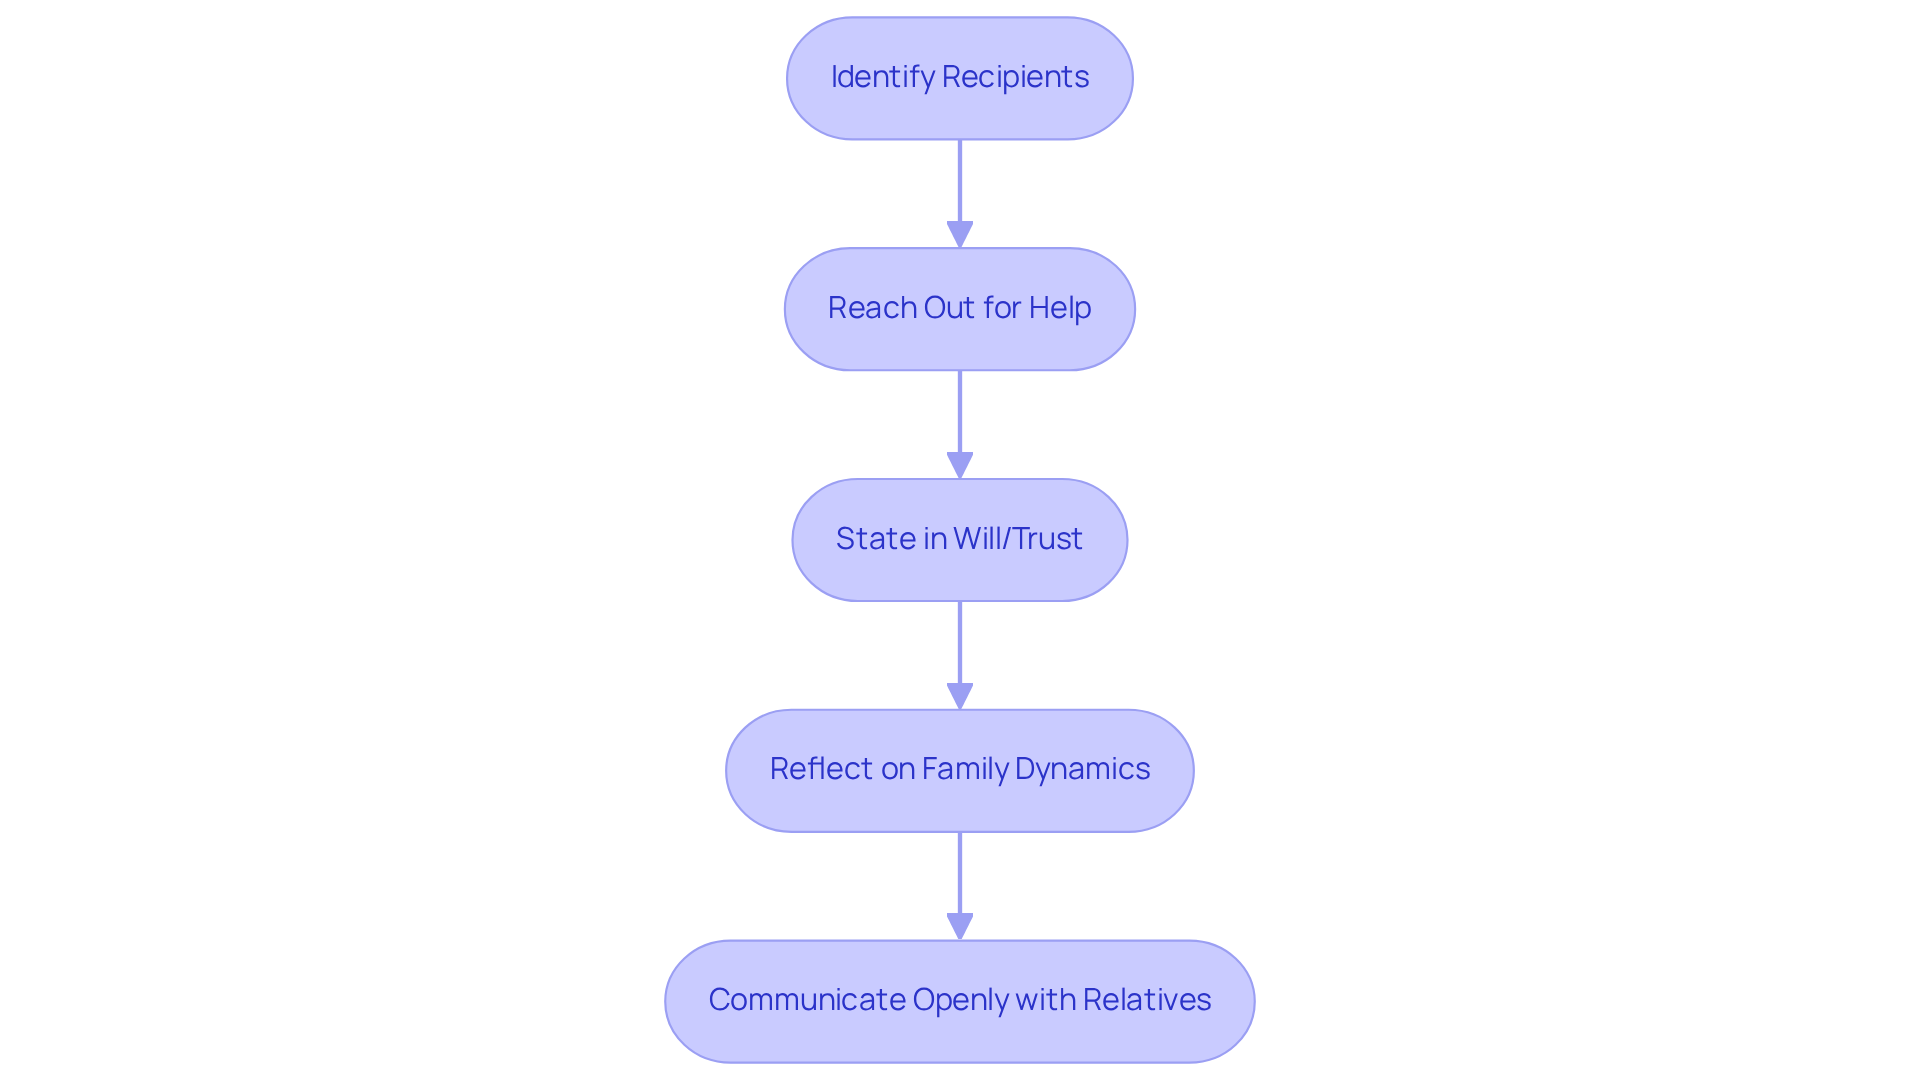
- Identify Recipients: Take a moment to list all potential recipients, including your children and grandchildren. This ensures that everyone who should inherit is accounted for, giving you confidence in your decisions.
- Reach Out for Help: It’s a good idea to reach out to an estate planning attorney who can help you navigate this important process. They can assist in drafting wills or trusts that include language specifying a life insurance beneficiary per stirpes, ensuring your wishes are clearly articulated.
- Clearly state in your will or trust that you wish for your assets to be distributed to your life insurance beneficiary per stirpes. For example, you might write, ‘I give my estate to my children, per stirpes.’ This ensures that if a beneficiary passes away, their share will be inherited by their descendants as a life insurance beneficiary per stirpes, keeping your family connected.
- Reflect on Family Dynamics: Take a moment to reflect on how your family dynamics may have changed over time. With combined households experiencing a 15% rise in major areas such as Houston and Dallas-Fort Worth from 2010 to 2020, it’s essential to adjust your estate plan to accommodate these changes.
- Communicate Openly with Relatives: Discuss your estate planning decisions with your relatives to ensure everyone understands your intentions. This can prevent misunderstandings and disputes later on, fostering a sense of unity and clarity.
By taking these thoughtful steps, you’re ensuring that your family’s legacy is honored and cherished for generations to come. The significance of life insurance beneficiary per stirpes allocations is highlighted by the fact that they prevented disinheritance of grandchildren in 25-30% of cases involving multiple generations, making them a crucial factor in estate planning.
Update Beneficiary Designations Regularly
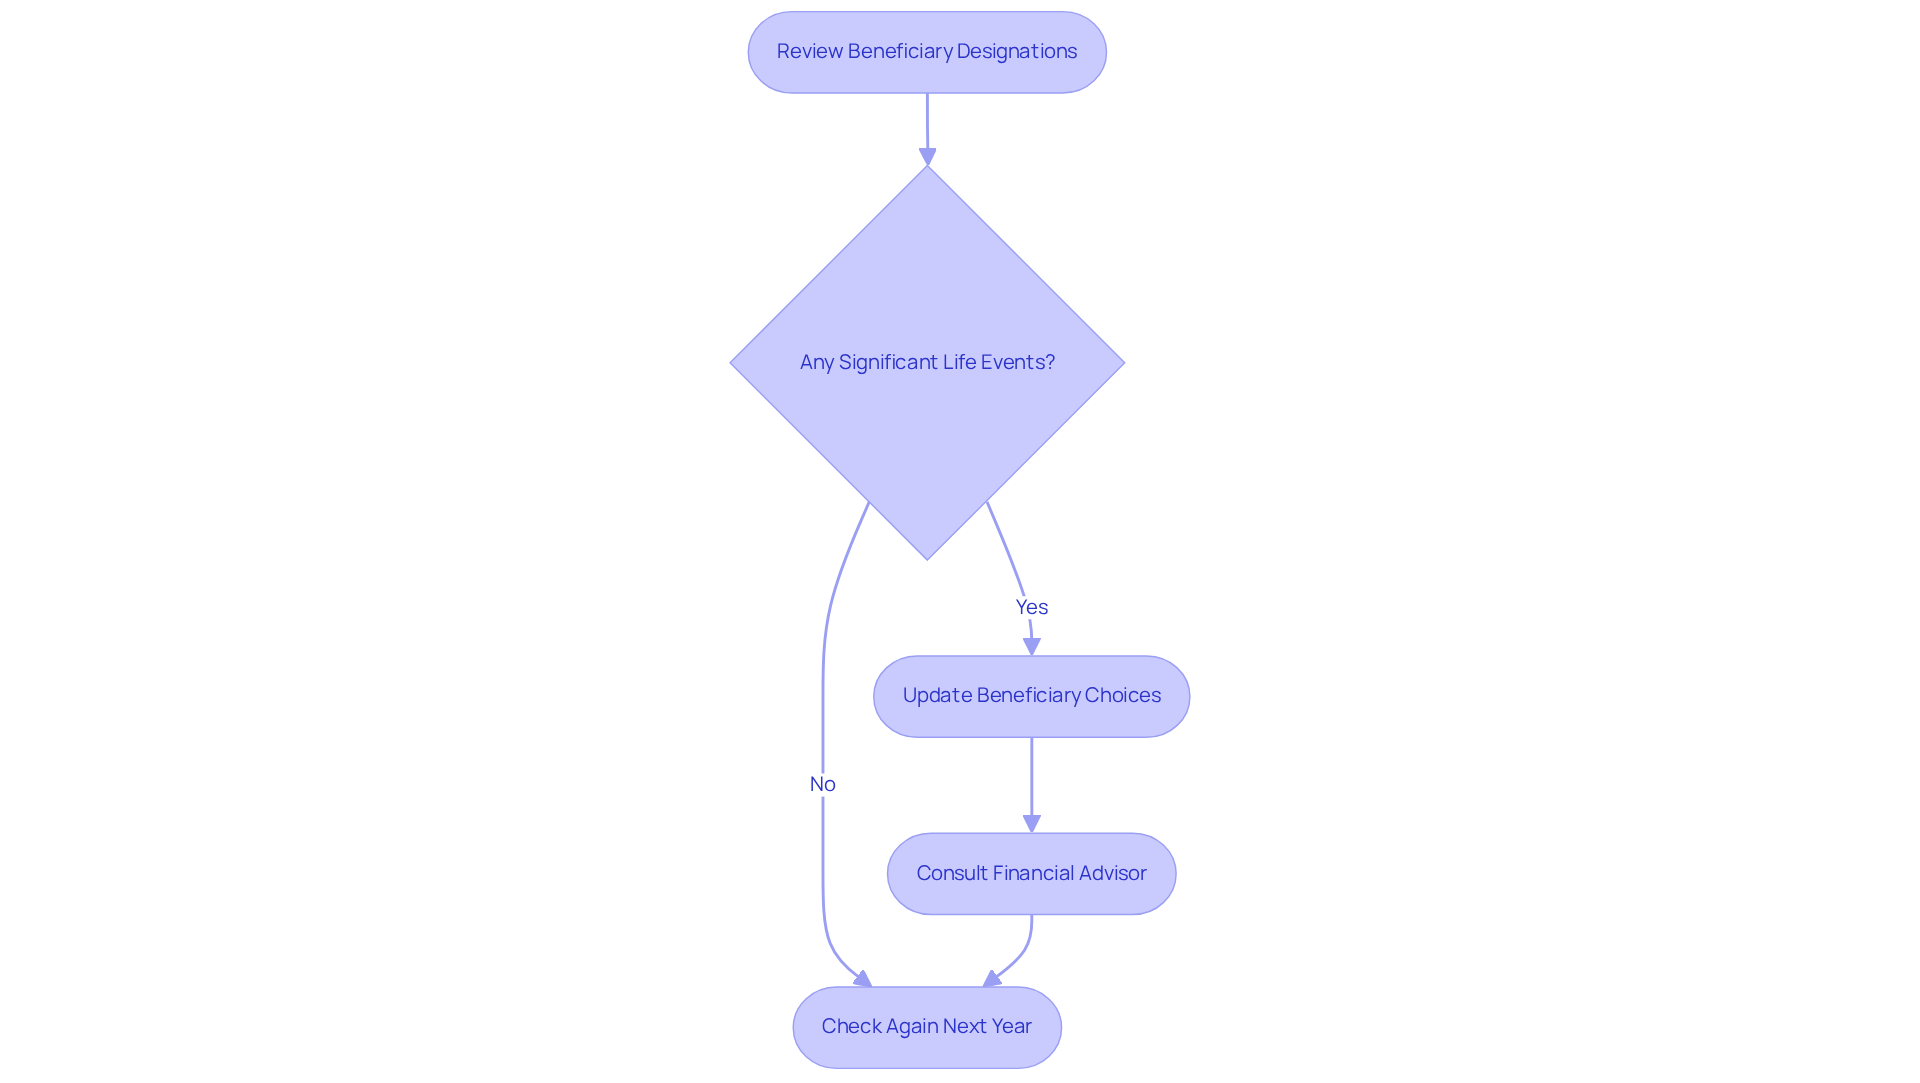
Keeping your beneficiary assignments up to date is essential for peace of mind in estate planning. Imagine the stress of an ex-spouse unexpectedly benefiting from your hard-earned assets. Significant life events – like marriage, divorce, the birth of a child, or the death of a beneficiary – can greatly affect your estate plan. It’s a good idea to check in on your beneficiary choices at least once a year. This practice helps ensure that your titles reflect your current wishes and family dynamics.
When big life changes happen, like welcoming a new baby or losing a loved one, make sure to update your choices right away. This proactive approach helps avoid confusion and potential disputes among heirs, especially if your will states equal sharing among children but your life insurance policy names only one child.
Partner with your financial advisor or estate planning attorney to make sure your choices reflect your family’s needs and goals. Their expertise can help you navigate complex situations and avoid legal complications. Share your choices with your family to keep everyone on the same page and avoid any confusion later on.
By remaining proactive and frequently updating your recipient designations, families can help ensure that their assets are allocated according to their desires, offering reassurance for the future. By staying proactive, you can ensure your loved ones are cared for according to your wishes, bringing you peace of mind for the future.
Conclusion
Imagine the peace of mind that comes from knowing your family’s future is secure, even when you’re not there to guide them. Understanding the concept of life insurance beneficiary per stirpes is a vital step for young families looking to protect their financial future. This choice helps ensure your assets are passed down through generations, providing a safety net for your loved ones if something unexpected happens. Choosing per stirpes means your family’s legacy is honored, ensuring fairness for all branches of your family tree.
We’ve explored how per stirpes designations can protect your family’s legacy and what steps you can take to implement them effectively. Regularly updating your beneficiary assignments is just as important, as life events can change family dynamics and intentions. Navigating the complexities of estate planning can feel overwhelming, especially when you want to ensure your loved ones are taken care of. Without thoughtful planning, families risk leaving their loved ones in confusion and potential conflict during difficult times.
Remember, estate planning is about more than just paperwork; it’s about ensuring your loved ones are cared for in the way you envision. Families are encouraged to engage with professionals, such as estate planning attorneys or financial advisors, to navigate this complex landscape. By taking these steps, you’re not just planning for the future; you’re ensuring that your family’s love and values endure, no matter what life brings.
Frequently Asked Questions
What does ‘per stirpes’ mean in estate planning?
‘Per stirpes’ is a Latin phrase meaning ‘by branch.’ In estate planning, it refers to a method of distributing assets where, if an heir dies before the testator, their portion of the inheritance automatically passes down to their descendants.
How does the per stirpes beneficiary designation work?
If a parent designates their offspring as a beneficiary and that offspring dies before the parent, the offspring’s children (the grandchildren of the testator) would receive their parent’s portion of the inheritance.
Why is understanding per stirpes important for families?
Understanding per stirpes is crucial for families as it aids in effective estate planning, ensuring that assets are preserved for future generations and not lost due to unexpected situations.
What percentage of U.S. adults lack an estate plan?
Over 50% of U.S. adults lack an estate plan, highlighting the essential need for appropriate beneficiary designations.
When should beneficiary designations be reviewed and updated?
Beneficiary designations should be regularly reviewed and updated, especially after major life events, to ensure that assets are distributed according to current wishes and to avoid complications.
Can you provide an example of how per stirpes works in practice?
If two offspring are designated as beneficiaries and one dies, the living child retains their portion, while the deceased child’s portion is distributed among their offspring. This ensures that the inheritance adheres to the family lineage.
What are the consequences of not having a per stirpes designation?
Not having a per stirpes designation can lead to uncertainty and potential loss of family assets, as there may be complications in how the inheritance is distributed.
How does per stirpes serve as a generational safety net?
Per stirpes serves as a generational safety net by enabling descendants to inherit as life insurance beneficiaries if a designated recipient predeceases the account holder, thus protecting the family’s legacy.
List of Sources
- Define Per Stirpes Beneficiary Designation
- Per Stirpes Beneficiaries: Meaning & Estate Planning | Greenbush Financial Group (https://greenbushfinancial.com/all-blogs/per-stirpes-beneficiary-designations-explained)
- What Does Per Stirpes Mean? A Simple Guide With Examples (https://definefinancial.com/blog/per-stirpes-beneficiary-designations-defined)
- Wealth Management Insights blog: The Importance of Per Stirpes and Per Capita Elections (https://fergusonwellman.com/resources/the-importance-of-per-stirpes-and-per-capita-elections)
- What’s the Difference between Per Stirpes vs. Per Capita in Estate Planning? – Annapolis and Towson Estate Planning (https://simscampbell.law/whats-the-difference-between-per-stirpes-vs-per-capita-in-estate-planning)
- Differentiate Between Per Stirpes and Per Capita Designations
- What is the Difference Between Per Stirpes and Per Capita? (https://ethos.com/will-and-trust/per-stirpes-vs-per-capita)
- “Per Stirpes” vs “Per Capita” Estate Distributions (https://burnerlaw.com/blog/per-stirpes-vs-per-capita-estate-distributions)
- Understanding “Per Stirpes” and “Per Capita” in Your Will | Walecka Law, P.C. (https://waleckalaw.com/understanding-per-stirpes-and-per-capita-in-your-will)
- Per Stirpes vs. Per Capita in a Will: Understanding the Distinction (https://plannedgiving.com/per-stirpes-vs-per-capita-in-a-will-understanding-the-distinction)
- Per Stirpes, Per Capita or By Representation…What Does It All Mean? (https://lbesq.com/per-stirpes-per-capita-or-by-representation-what-does-it-all-mean)
- Apply Per Stirpes Designations in Estate Planning
- Making Sure Your Wealth Goes to the Right People (https://canbyfinancial.com/blog/making-sure-your-wealth-goes-to-the-right-people)
- Per Stirpes vs. Pro Rata in Texas Estate Planning: A Clear Guide for Families (https://texastrustadministration.com/per-stirpes-vs-pro-rata)
- Estate Planning Statistics | Galanti & Copenhaver, Inc. (https://galantilawgroup.com/blog/estate-planning-statistics)
- Per Stirpes (https://benefitslink.com/boards/topic/38227-per-stirpes)
- Per Stirpes Designations in a Will (https://texastrustlaw.com/per-stirpes-designations-in-a-will)
- Update Beneficiary Designations Regularly
- Beneficiary Designations: Why You Should Regularly Update Them (https://jerseyelderlawyers.com/beneficiary-designations-why-you-should-regularly-update-them)
- Are Your Beneficiary Designations Up to Date? | Gudorf Law Group, LLC (https://daytonestateplanninglaw.com/beneficiary-designations-up-to-date)
- Make it a habit: Review your beneficiaries annually (https://today.iu.edu/live/news/45236-make-it-a-habit-review-your-beneficiaries-annually)
- [Real Life HR] How Often Should Employees Update Beneficiary Forms? (https://sbam.org/real-life-hr-how-often-should-employees-update-beneficiary-forms)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading