

Key Highlights
- Rental deficits occur when the costs of a rental property exceed its revenue, categorised as passive activity losses (PALs) by the IRS.
- Families with a modified adjusted gross income (MAGI) below $100,000 can deduct up to $25,000 of rental losses against non-passive earnings, with a phase-out for incomes between $100,000 and $150,000.
- To qualify for the $25,000 deduction, property owners must actively manage the property and own at least 10% of it.
- Real estate professionals can treat property losses as non-passive, allowing for current year deductions without the usual limits.
- The small landlord provision allows active participants in leasing activities to deduct up to $25,000 of property losses against non-passive earnings.
- Families should monitor their MAGI, actively participate in property management, and consult tax professionals to maximise deductions.
- Exploring short-term accommodations may provide different tax treatment and greater deductions.
- Strategic tax planning can significantly benefit families, as illustrated by case studies of families optimising their tax situations with Bright Advisers.
Introduction
Imagine feeling overwhelmed by the financial responsibilities of raising a family while trying to understand rental losses and tax regulations. Rental properties can lead to unexpected expenses. It’s important to understand how rental deficits and IRS regulations can impact your family’s finances and tax benefits.
With income thresholds and passive activity loss rules, many families wonder how to avoid leaving money on the table. Together, we can explore the limits on rental losses and discover insights and strategies that empower your family to navigate these challenges and secure a brighter financial future.
Define Rental Losses and Passive Activity Loss Rules
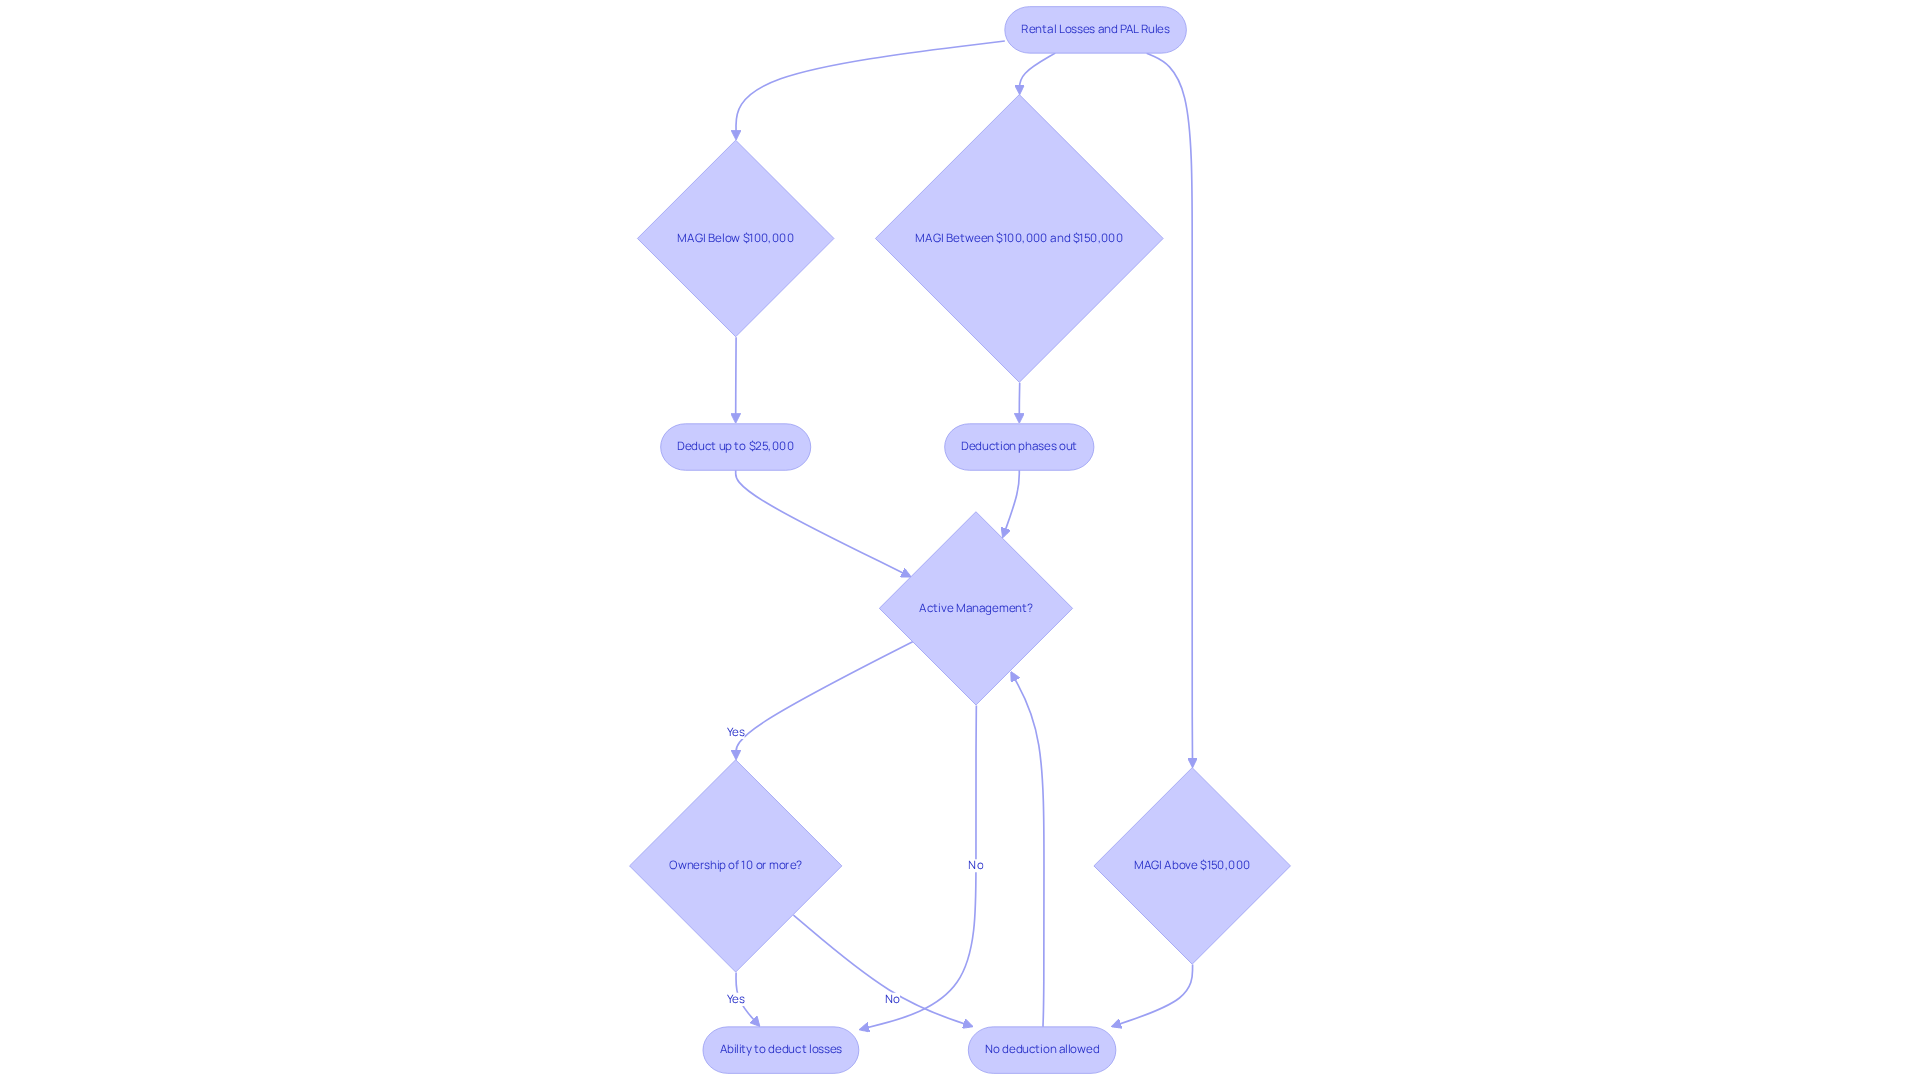
Imagine facing unexpected costs from your rental property while trying to provide for your family – this is where understanding rental deficits becomes essential. Rental deficits occur when the costs related to a rental property exceed the revenue it generates. When this happens, it’s important to know that these situations are categorized as passive activity setbacks, or PALs, by the IRS. Unfortunately, the rules around passive activity deductions can be tricky, as they create limits on rental losses that restrict how you can offset these deficits against other earnings, like your salary.
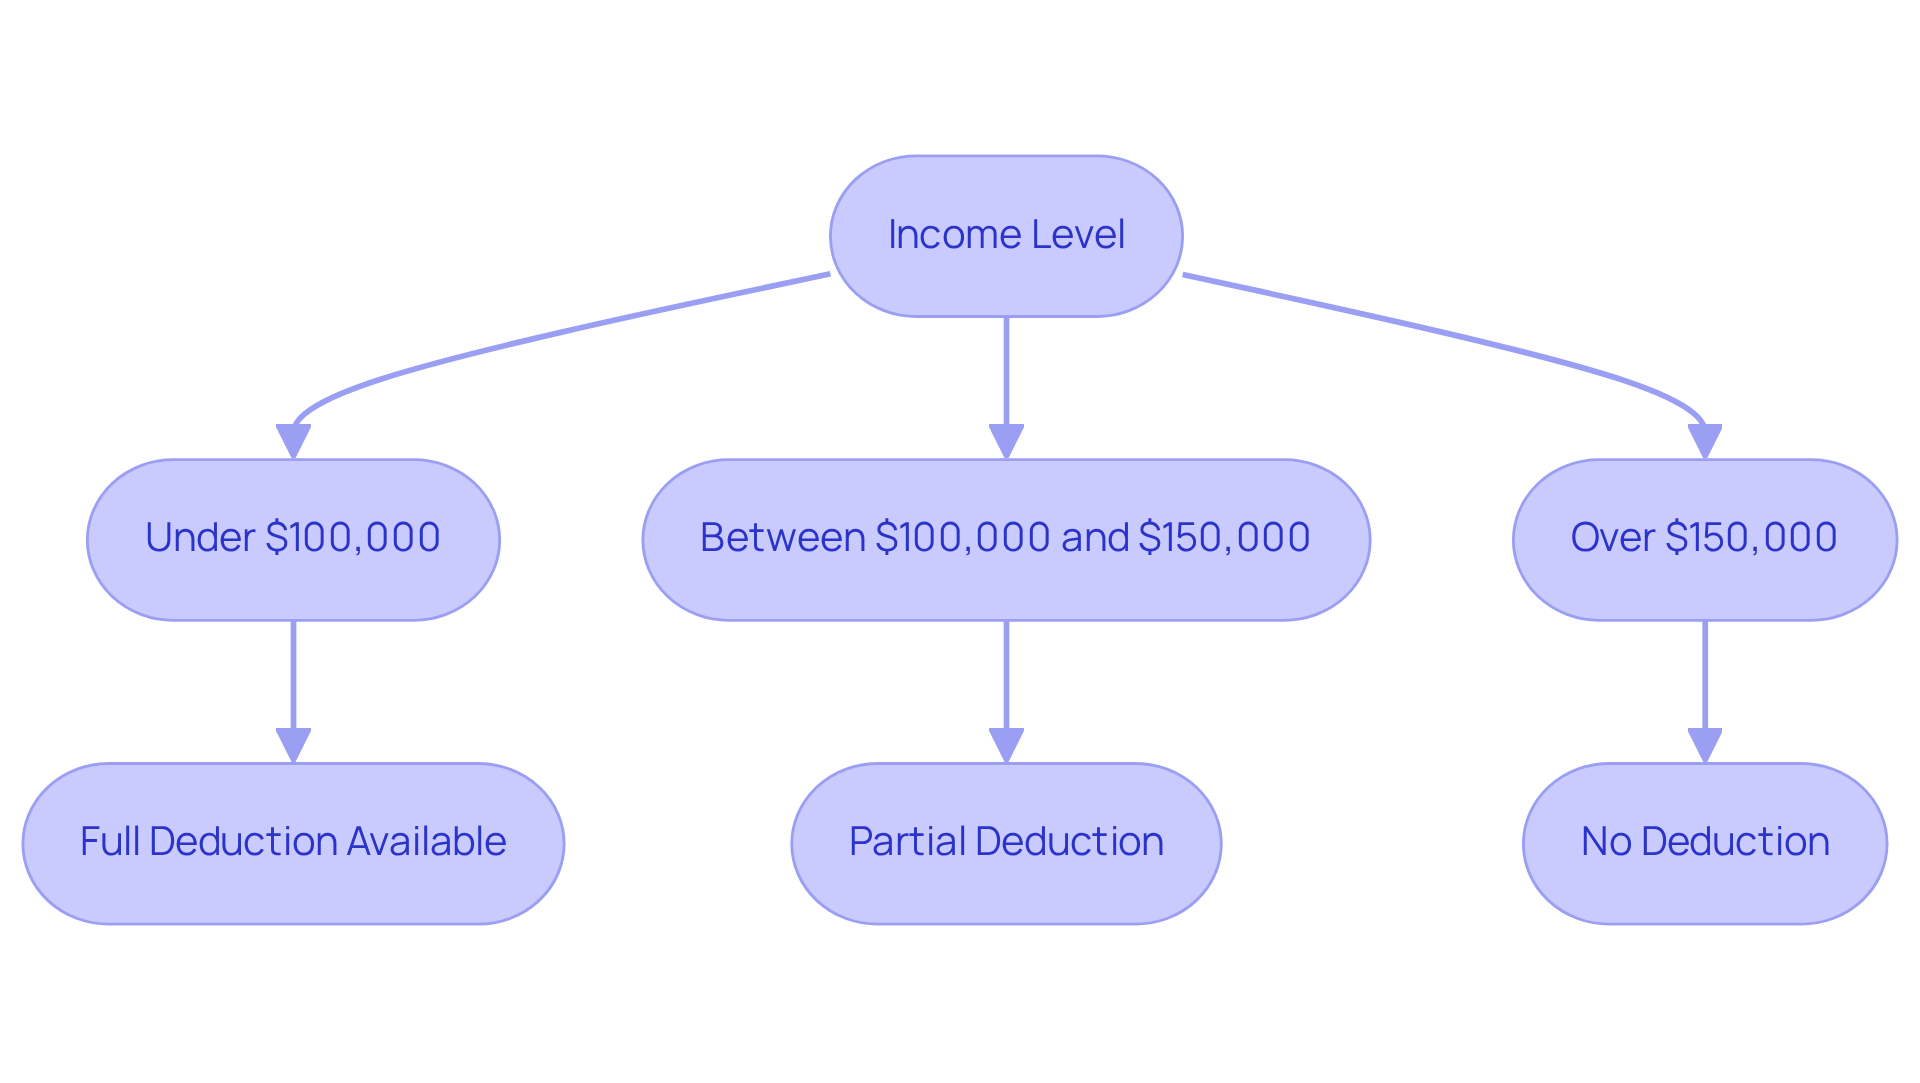
If your modified adjusted gross income (MAGI) is below $100,000, you might be able to deduct up to $25,000 of property losses against your non-passive earnings. However, this deduction phases out for incomes between $100,000 and $150,000. For instance, if your family has a MAGI of $120,000, your allowable deduction would drop to $15,000. It’s crucial to keep an eye on your income levels when planning your tax strategies.
To qualify for the $25,000 allowance, you need to actively manage the property and own at least 10% of it. If you meet these criteria, your family can benefit significantly from tax deductions on property-related deficits. But if your MAGI exceeds $150,000, that special allowance disappears entirely, highlighting the importance of understanding the limits on rental losses.
Consider a family that qualifies as real estate professionals. They can treat their property losses as non-passive, allowing them to deduct these losses in the current year without needing passive income. Additionally, properties with an average leasing period of 30 days or fewer, where substantial personal services are provided, may also be considered business activities, allowing for current deductions if the owner is significantly involved.
Understanding these guidelines can unlock valuable tax advantages for your family, helping you navigate the complexities of property investments effectively. By grasping these guidelines, you can ensure your family maximizes its tax benefits and secures a brighter financial future.
Explore Deductibility Limitations on Rental Losses
Imagine feeling overwhelmed by tax rules while trying to secure your family’s future. The deductibility of property-related deficits can be tricky, especially if your family’s income goes over $150,000. In that case, you might not be able to use property losses to lower your taxes. For families making between $100,000 and $150,000, the deduction slowly decreases, which can be frustrating. Families like Jay and Emma, trying to balance finances and save for their kids’ education, could miss out on a valuable $25,000 deduction, which can really affect their tax situation.
If you’re not hands-on with your property, you might find it harder to claim these deductions, which can be disheartening. Being involved means making decisions about tenants or repairs, which can feel like a lot to handle. For parents who want to maximize their tax benefits while managing property, understanding the limits on rental losses is crucial.
We’re here to help families create tailored plans that not only tackle these tax issues but also fit your family’s financial dreams, so you can feel ready for today and tomorrow. Bright Advisers can assist you in developing personalized strategies that align with your broader financial goals, ensuring you’re well-prepared for both present responsibilities and future aspirations.
Identify Exceptions to Passive Activity Loss Rules
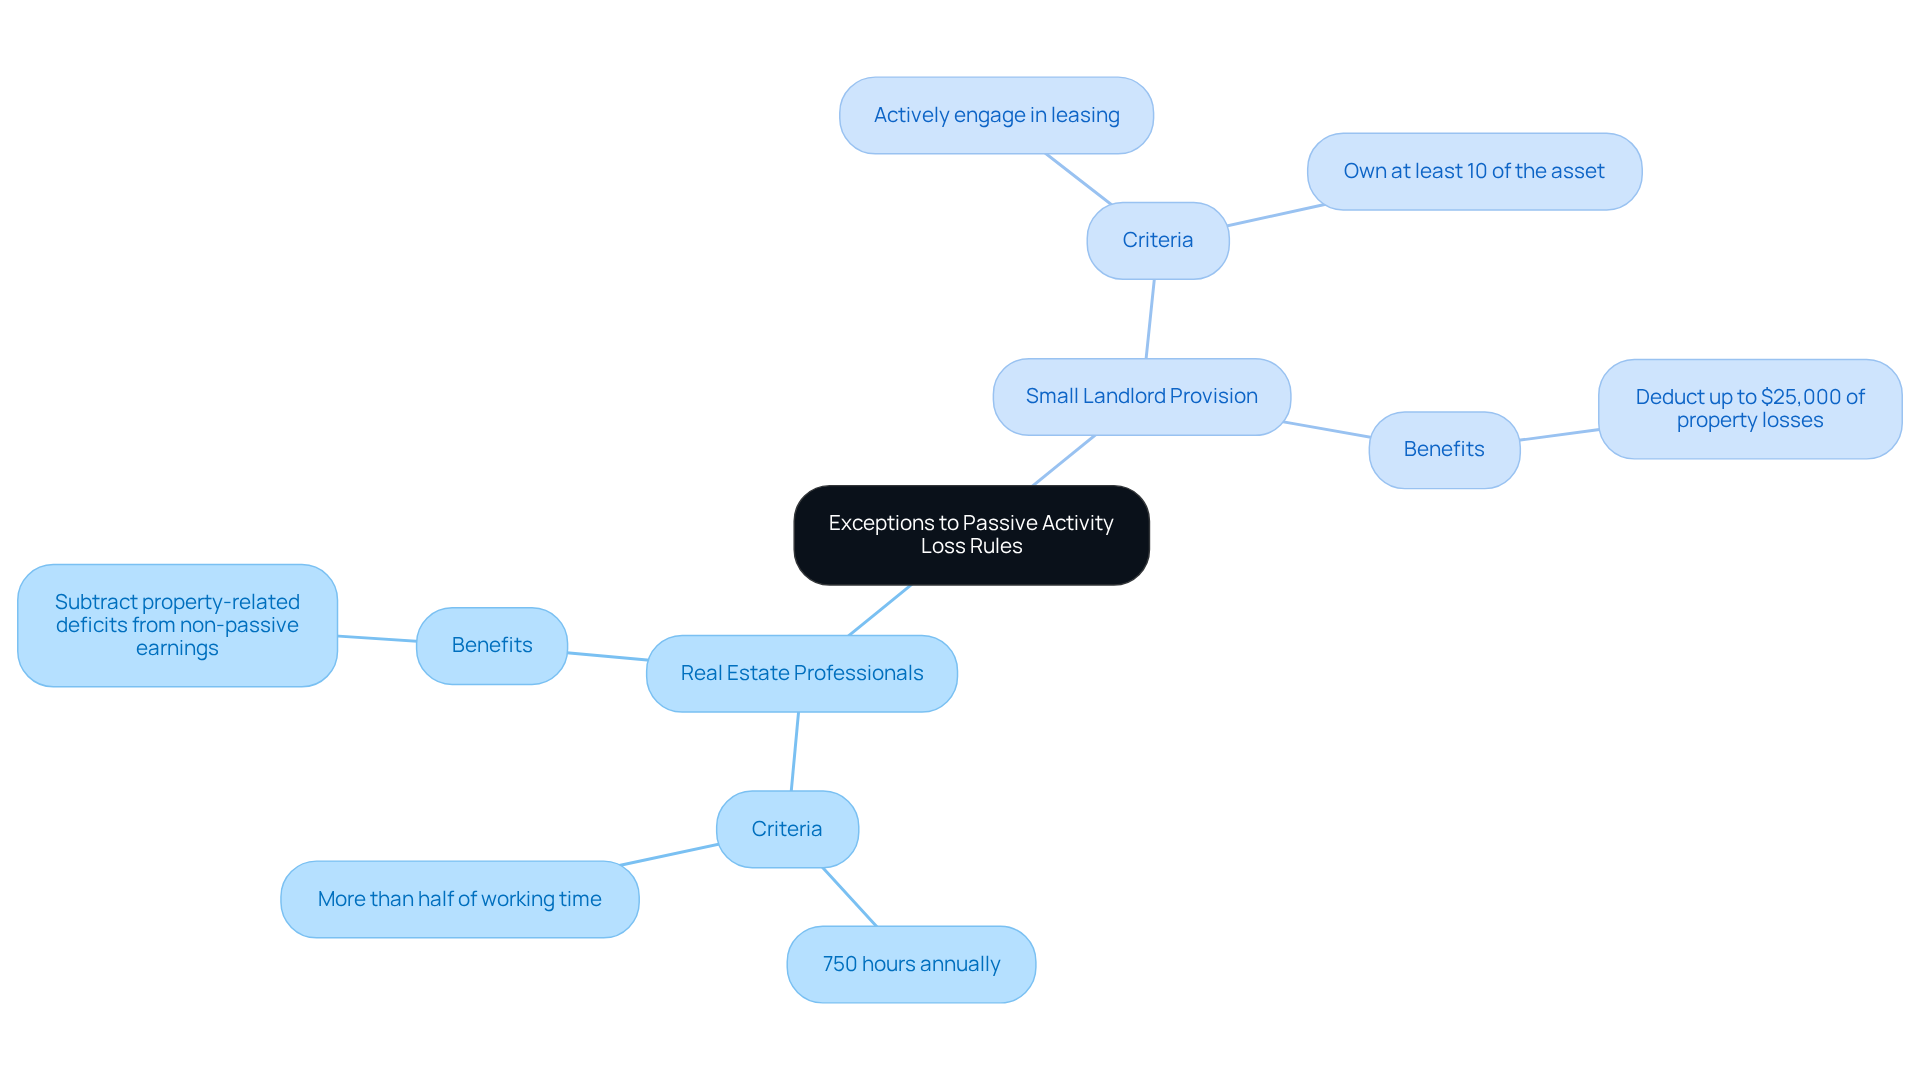
Understanding the limits on rental losses and the exceptions to passive activity deduction rules is crucial for families managing property investments. One significant exception applies to real estate professionals. If you meet the criteria as a real estate expert, you can subtract property-related deficits from your non-passive earnings without the typical limits on rental losses. To qualify, you must spend over 750 hours annually in real estate activities, dedicating more than half of your working time to this field.
Another important exception is the small landlord provision. This allows taxpayers who actively engage in leasing activities to deduct up to $25,000 of property losses against non-passive earnings, provided they own at least 10% of the asset. This exception is especially beneficial for families actively managing their properties, as it can significantly reduce their taxable income despite the limits on rental losses. For instance, families like Emily and Mark, who are hands-on in managing their properties, successfully lowered their tax liability by taking advantage of these exceptions.
When families grasp these exceptions, they can tackle their tax obligations with confidence and make the most of available deductions. With the help of Bright Advisers, Emily and Mark discovered how to make these strategies work for their family, allowing them to create a financial plan that supports their current lifestyle while giving them the freedom to choose whether or not to continue working. By understanding these tax rules, families can not only ease their financial burdens but also create a brighter future for their loved ones.
Implement Strategic Tax Planning for Rental Losses
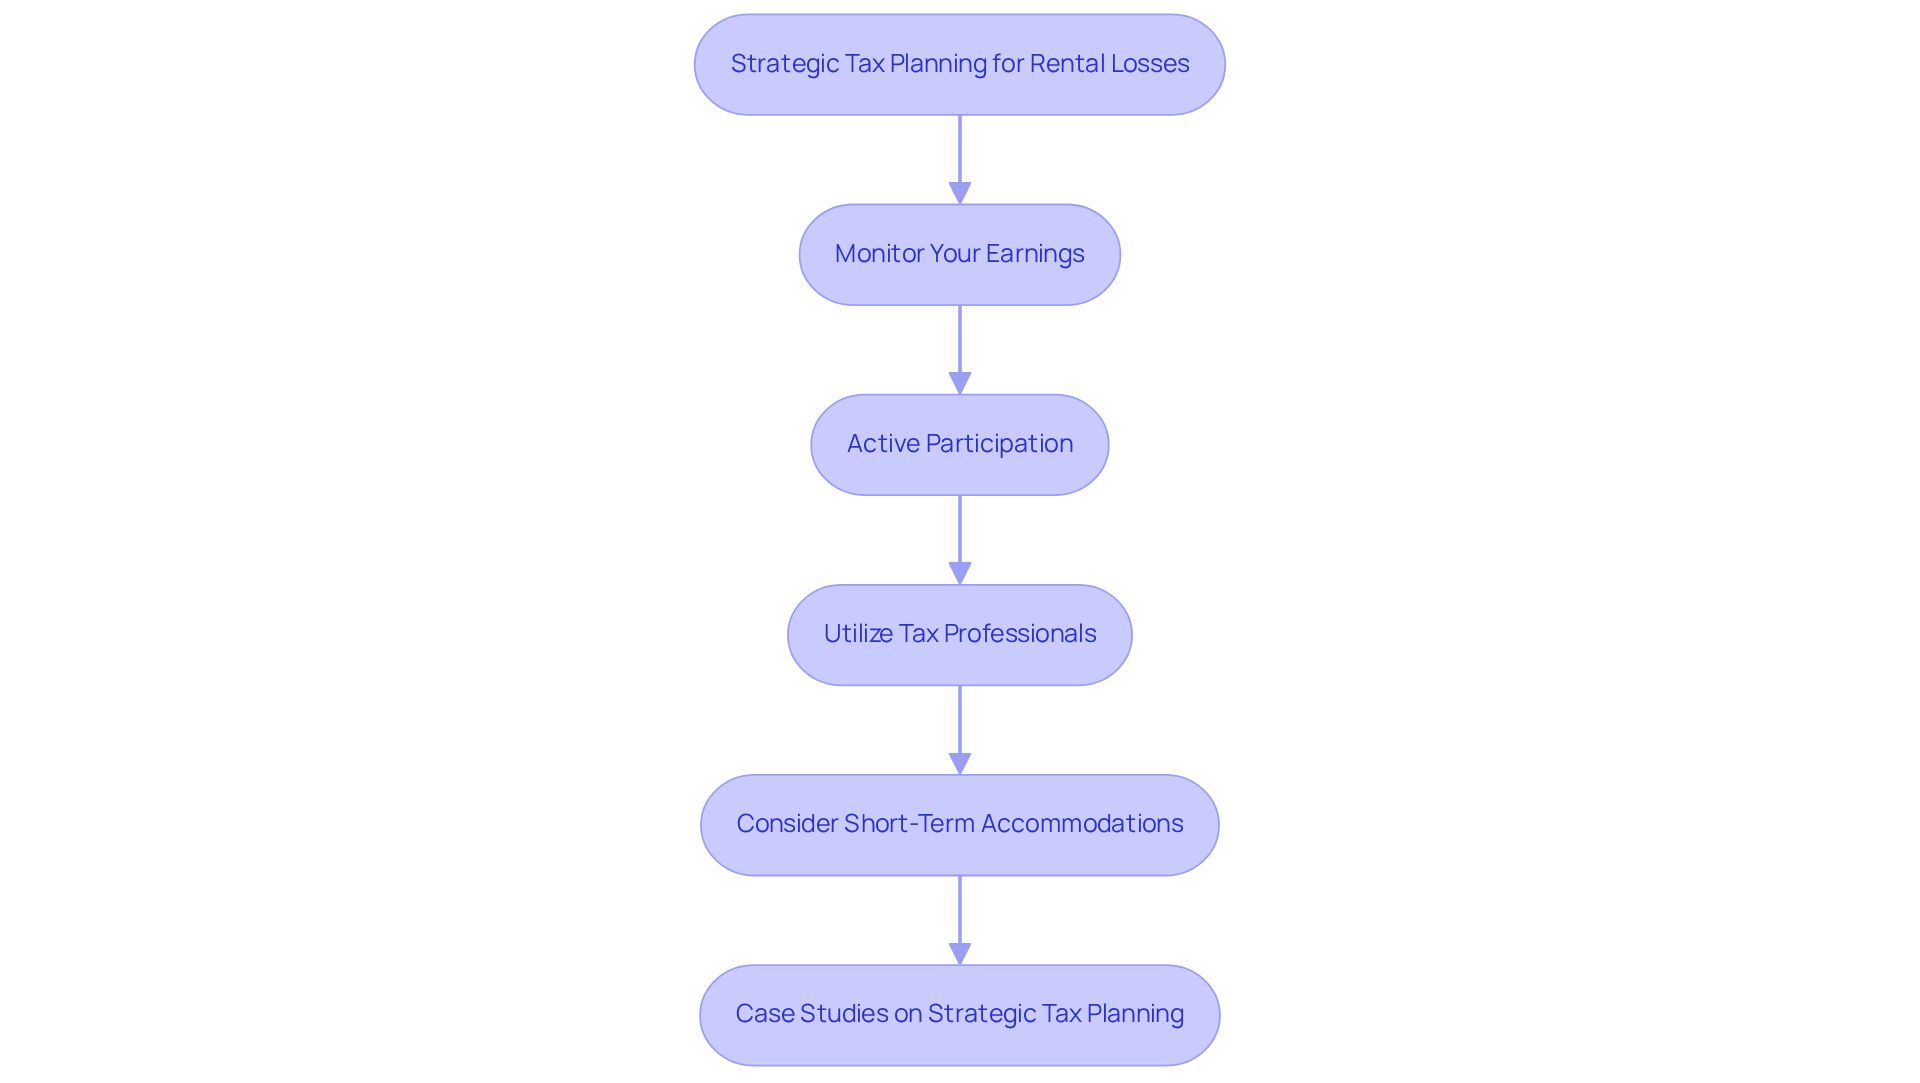
Imagine feeling secure about your family’s financial future while navigating the complexities of limits on rental losses and tax planning. To effectively manage rental losses and enhance tax outcomes, young parents should consider several strategic tax planning steps:
-
Monitor Your Earnings: Regularly track your modified adjusted gross earnings (MAGI) to ensure you remain within the thresholds that allow for the maximum deduction of rental deficits. If your MAGI is $100,000 or less, you may deduct up to $25,000 in passive losses. However, the deduction begins to phase out when MAGI exceeds $100,000, reducing by $1 for every $2 over this limit. If you think you might exceed these limits, it’s wise to explore ways to lower your AGI, like contributing to retirement accounts or using tax-loss harvesting techniques to offset gains and lower your taxable income.
-
Active Participation: Getting involved in managing your properties can make a big difference. Not only does it help you qualify for deductions, but it also gives you a clearer picture of how your property is doing, helping you make smarter financial choices. To qualify for the $25,000 deduction, you must own at least 10% of the leasing activity and actively participate in its operations.
-
Utilize Tax Professionals: Consulting with tax professionals who specialize in real estate can be a game-changer. They can help you leverage all available deductions and exceptions, providing tailored advice based on your unique financial situation and guiding you through complex tax regulations.
-
Consider Short-Term Accommodations: If it’s an option for you, exploring short-term accommodations might be beneficial. These can offer different tax treatment and allow for greater deductions, sometimes classified differently for tax purposes, which could provide additional advantages.
-
Case Studies on Strategic Tax Planning:
- Allison and Brian’s Success: Through their collaboration with Bright Advisers, Allison and Brian, a couple with substantial incomes, transformed their financial future by optimizing their tax situation. They secured their children’s future through education funding and gained the ability to retire sooner. Their experience illustrates how strategic tax planning can lead to significant financial benefits for families.
- Shifting Passive Activity Deductions: Taxpayers can transfer their interests in investment properties to closely held corporations to utilize passive deductions against active income, enhancing tax efficiency.
- Maximizing Deduction Allowance: Taxpayers can employ strategies to reduce AGI, such as contributing to retirement plans, to retain eligibility for the $25,000 deduction allowance.
- Phaseout of the $25,000 Deduction: The deduction begins to phase out when MAGI exceeds $100,000, necessitating careful tax planning to maximize allowable deductions.
When you embrace these strategies, you’re taking important steps to manage limits on rental losses and boost your family’s financial well-being. Bright Advisers is here for you, committed to helping families make wise wealth decisions and preserve wealth across generations. If you’re interested in learning more about how we can assist you, consider joining our current client waitlist. Please remember that past performance does not guarantee future results, and all investments are subject to risk. Taking these steps can empower your family to thrive financially, ensuring a brighter future for your loved ones.
Conclusion
Imagine feeling overwhelmed by the complexities of property investments and tax implications – you’re not alone in this journey. Understanding the limits on rental losses can be a game-changer for families like yours. When families understand the ins and outs of passive activity loss rules, they can make choices that truly benefit their financial future. This understanding not only aids in managing rental properties but also helps families unlock valuable tax benefits.
Keeping an eye on your modified adjusted gross income (MAGI) and being involved in property management can open doors to important deductions. Families can take advantage of exceptions to passive activity loss rules, which can significantly reduce taxable income. By embracing these strategies, families can feel more confident as they navigate the tax landscape together.
Bright Advisers is here to support you in making wise wealth decisions and preserving your financial legacy. Reaching out for personalized guidance can be the first step toward a more secure financial future for your family. Together, we can navigate this journey and ensure a brighter tomorrow.
Frequently Asked Questions
What are rental losses?
Rental losses occur when the costs associated with a rental property exceed the revenue it generates.
How does the IRS categorize rental losses?
The IRS categorizes rental losses as passive activity losses (PALs).
What are the passive activity loss rules?
The passive activity loss rules limit how rental losses can be deducted against other earnings, such as salary.
What is the maximum deduction for rental losses if my modified adjusted gross income (MAGI) is below $100,000?
If your MAGI is below $100,000, you may be able to deduct up to $25,000 of property losses against your non-passive earnings.
How does the deduction phase out for incomes between $100,000 and $150,000?
The deduction phases out for MAGI between $100,000 and $150,000. For example, if your MAGI is $120,000, your allowable deduction would decrease to $15,000.
What are the requirements to qualify for the $25,000 rental loss deduction?
To qualify for the $25,000 allowance, you must actively manage the property and own at least 10% of it.
What happens if my MAGI exceeds $150,000?
If your MAGI exceeds $150,000, the special allowance for rental loss deductions disappears entirely.
How can families qualify as real estate professionals benefit from rental losses?
Families that qualify as real estate professionals can treat their property losses as non-passive, allowing them to deduct these losses in the current year without needing passive income.
Are there any exceptions for properties with short leasing periods?
Yes, properties with an average leasing period of 30 days or fewer, where substantial personal services are provided, may be considered business activities, allowing for current deductions if the owner is significantly involved.
Why is it important to understand rental loss guidelines?
Understanding these guidelines can unlock valuable tax advantages, helping families navigate property investments effectively and maximize tax benefits.
List of Sources
- Define Rental Losses and Passive Activity Loss Rules
- Understanding Passive Activity Losses: A Comprehensive Guide|Greg O’Brien, CPA (https://anomalycpa.com/post/passive-activity-loss-guide)
- Passive Activity Loss Limits (https://wcginc.com/kb-rental-property/passive-activity-loss-limits)
- Avoiding passive loss limitations on rental real estate losses (https://thetaxadviser.com/issues/2024/jul/avoiding-passive-loss-limitations-on-rental-real-estate-losses)
- How to Deduct Rental Real Estate Losses: Passive Activity Rules and Key Exceptions – Landmark CPAs (https://landmarkcpas.com/how-to-deduct-rental-real-estate-losses)
- Explore Deductibility Limitations on Rental Losses
- Avoiding passive loss limitations on rental real estate losses (https://thetaxadviser.com/issues/2024/jul/avoiding-passive-loss-limitations-on-rental-real-estate-losses)
- Passive Loss Limitations in Rental Real Estate | KRS CPAs, LLC | Accountants & Advisors (https://krscpas.com/passive-loss-limitations-in-rental-real-estate)
- Understanding Passive Activity Loss Limitations (https://taxslayerpro.com/blog/post/understanding-passive-loss-limitations)
- Passive Activity Loss Rules for Real Estate 2026 (https://senecacostseg.com/feeds/blog/passive-activity-loss-rules-real-estate-2026)
- Identify Exceptions to Passive Activity Loss Rules
- Understanding Passive Activity Losses: A Comprehensive Guide|Greg O’Brien, CPA (https://anomalycpa.com/post/passive-activity-loss-guide)
- Qualifying as a Real Estate Professional May Be Harder Than You Think – Anders (https://anderscpa.com/learn/blog/qualifying-real-estate-professional-harder-than-you-think)
- Real Estate Professional Status: Qualify for Tax Benefits (https://therealestatecpa.com/guide-to-qualifying-as-a-real-estate-professional)
- Understanding Passive Activity Loss Limitations (https://taxslayerpro.com/blog/post/understanding-passive-loss-limitations)
- Passive Activity Loss Rules 2026: How Real Estate Investors Can Maximize Deductions – Uncle Kam (https://unclekam.com/tax-strategy-blog/passive-activity-loss-rules)
- Implement Strategic Tax Planning for Rental Losses
- Avoiding passive loss limitations on rental real estate losses (https://thetaxadviser.com/issues/2024/jul/avoiding-passive-loss-limitations-on-rental-real-estate-losses)
- Tax Reduction Letter – Deduct More of Your Rental Property Losses by Qualifying as a Real Estate Professional—Even If You Don’t Work in Real Estate! (https://bradfordtaxinstitute.com/Content/Deduct-More-Rental-Losses.aspx)
- Passive Activity Loss Limits (https://wcginc.com/kb-rental-property/passive-activity-loss-limits)
- 2026 Landlord Tax Guide (https://obieinsurance.com/blog/landlord-tax-guide)
- What Is the $25,000 Passive Loss Allowance? – Hall CPA (https://therealestatecpa.com/blog/what-is-the-25000-passive-loss-allowance)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading