

Overview
Long-term transactions without basis reporting to the IRS can lead to inflated tax liabilities and penalties, as the IRS might assume a zero basis. It’s crucial to understand the importance of accurately reporting your cost basis to prevent overpayment. Imagine if you could navigate this complex landscape with confidence, ensuring that your family’s financial future remains secure.
This article provides a step-by-step guide for taxpayers like you to ensure compliance, highlighting the significance of thorough documentation and the use of tax forms such as Form 8949 and Schedule D. Together, we can navigate this journey, making sure you feel supported every step of the way.
Key Highlights:
- Long-term transactions involve capital assets held for over a year, necessitating the disclosure of their cost basis to the IRS.
- The cost basis is the original value of an asset, adjusted for improvements or depreciation, and must be reported to avoid penalties.
- Failure to disclose the basis can lead to inflated tax liabilities, as the IRS may assume a zero basis, resulting in overpayment and potential penalties.
- In 2021, $167 billion of income was underreported, highlighting the risks of inadequate tax reporting.
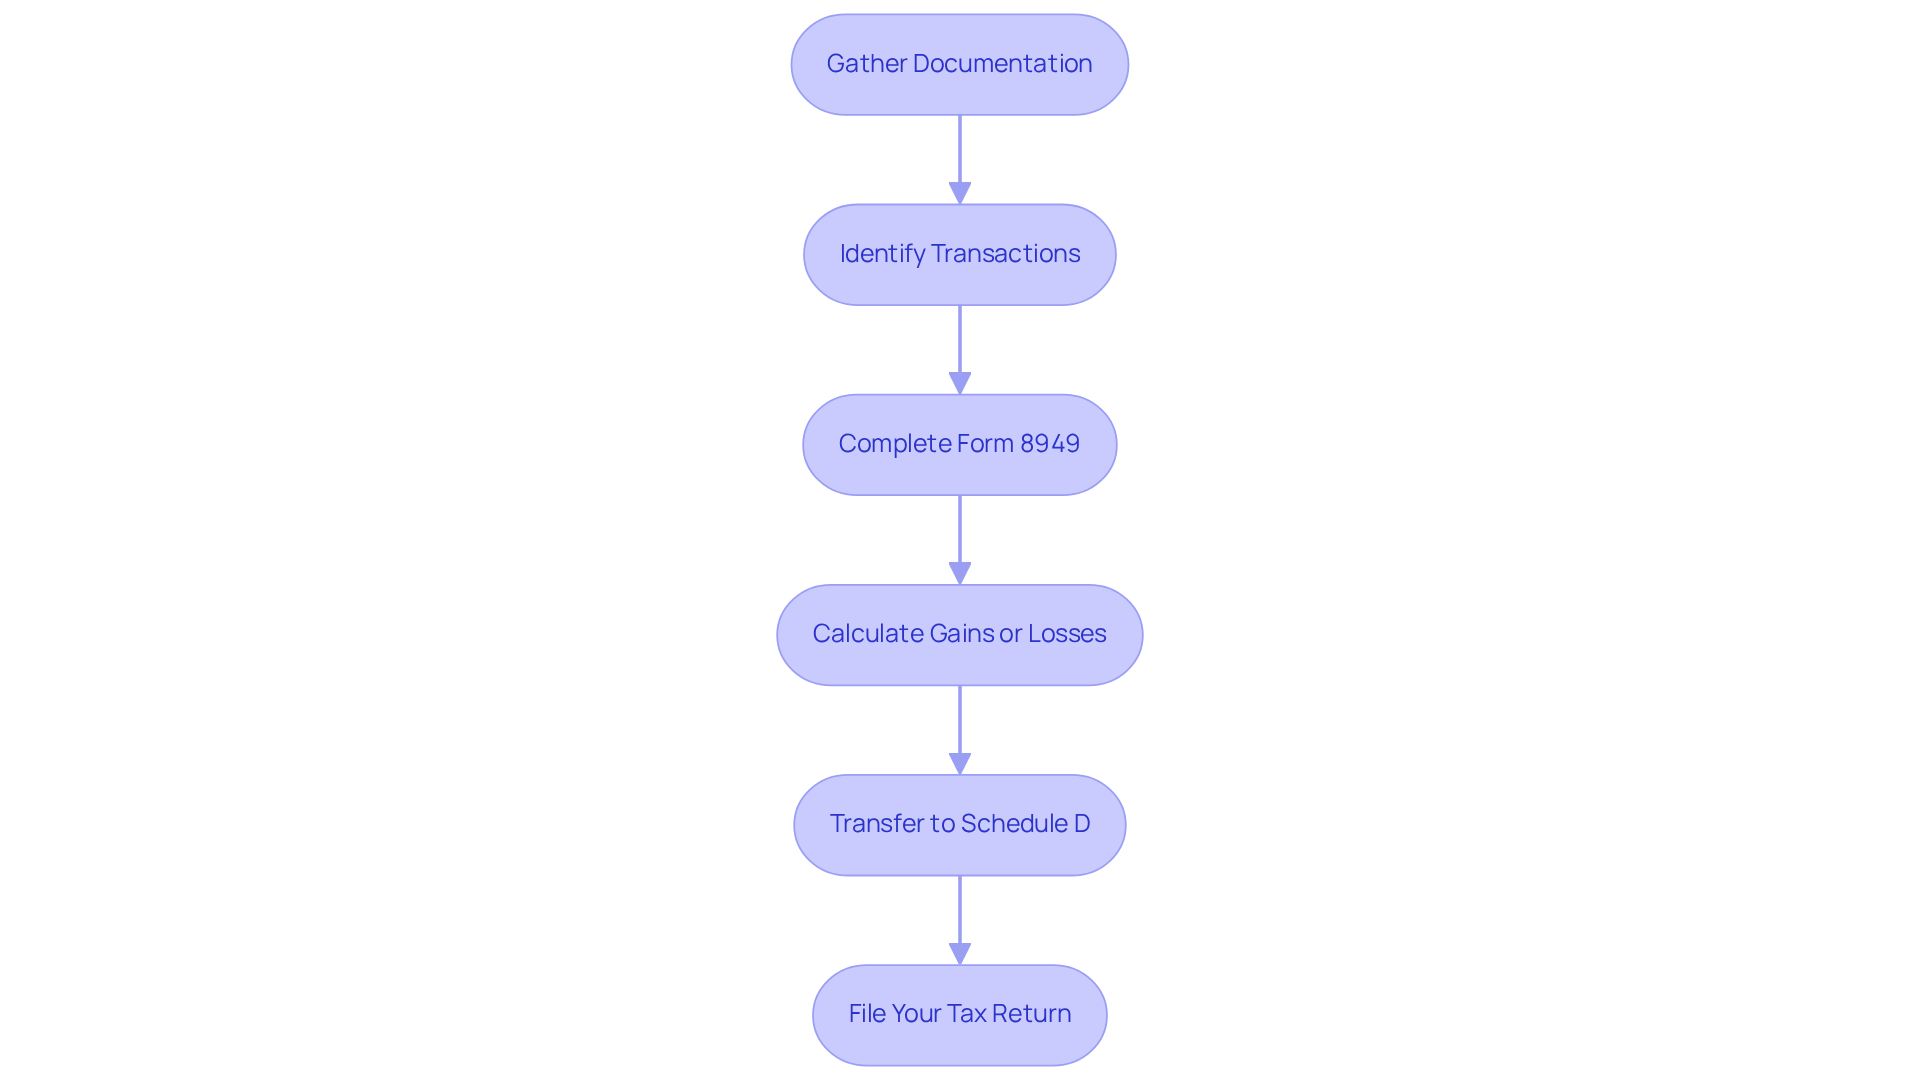
- To report long-term transactions without basis, taxpayers should gather documentation, identify transactions, complete Form 8949, calculate gains or losses, summarise on Schedule D, and file their tax return.
- Best practises for managing long-term transactions include maintaining accurate records, regularly reviewing investments, consulting tax professionals, staying informed about tax laws, and utilising financial management technology.
- The IRS has a three-year limitation period for most tax documents, which can extend to six or more years in cases of fraud or significant errors.
Introduction
Navigating the complexities of long-term transactions can feel overwhelming, especially when considering the nuances of basis reporting to the IRS. It’s essential for taxpayers to grasp the implications of these transactions to avoid costly mistakes and ensure compliance. In this article, we gently explore the critical steps for accurately reporting long-term transactions without basis, while also highlighting the potential pitfalls that can arise from neglecting proper documentation.
Imagine if taxpayers overlook these requirements—what could happen? Together, we can safeguard your financial future against unexpected tax liabilities, ensuring peace of mind for you and your family.
Define Long-Term Transactions and Basis Reporting
Understanding the sale of capital assets held for over a year is crucial when it comes to long-term transactions for which basis is not reported to the IRS. Imagine if you had to navigate tax documentation without knowing the importance of foundation disclosure. This step is essential because it requires revealing the cost foundation of these assets to the IRS, ensuring transparency and compliance.
The cost foundation represents the original value of the asset, adjusted for aspects like enhancements or depreciation. It’s important to grasp these details, especially for long-term transactions for which basis is not reported to the IRS. The IRS mandates submission on Form 1099-B, which indicates whether the foundation is disclosed. If you find yourself in a situation where the foundation isn’t disclosed, accurately documenting long-term transactions for which basis is not reported to the IRS becomes essential to prevent potential fines.
Tax experts emphasize that understanding and accurately declaring the foundation can significantly influence your tax obligations. By doing so, you not only ensure adherence to regulations but also reduce risks associated with erroneous submissions. We’re here for you, guiding you through these complexities so you can focus on what truly matters—your family’s future. Together, we can navigate this journey with confidence.

Explore Implications of Unreported Basis on Tax Obligations
Neglecting to disclose the foundation of long-term transactions for which basis is not reported to the IRS can lead to serious consequences for taxpayers, making it important to understand these implications. Imagine facing inflated tax liabilities because the IRS assumes a zero basis due to long-term transactions for which basis is not reported to the IRS. This miscalculation can dramatically increase your capital gain, often resulting in overpayment of taxes and exposing you to penalties for underreporting income. In fact, the typical penalties for underreporting income in 2025 are expected to be significant, underscoring the need for precise documentation.
Consider this: in 2021, taxpayers underreported $167 billion of income subject to minimal reporting requirements. This highlights the broader context of underreporting and its implications for families like yours. Unreported information complicates future tax submissions, making it challenging to align your records with IRS expectations. This misalignment can lead to further scrutiny and potential audits, which can be stressful.
Tax consultants emphasize the importance of keeping detailed records and ensuring that all dealings, including long-term transactions for which basis is not reported to the IRS, are reported accurately. One consultant shared, “Taxpayers who have encountered penalties for unreported transactions often mention challenges in aligning their financial records with IRS requirements.” This illustrates the essential need for thoroughness in tax reporting practices.
By understanding these implications, you can navigate your tax obligations more effectively and safeguard against unnecessary financial burdens. Remember, we’re here for you, and together, we can navigate this journey toward financial security for your family.

Detail Steps for Reporting Long-Term Transactions Without Basis
Navigating the world of long-term transactions can feel overwhelming, but we’re here to help you every step of the way. To report these transactions without a basis, follow these gentle steps:
-
Gather Documentation: Start by collecting all relevant documents, including Form 1099-B from your broker, which outlines your activities. This is your foundation for understanding the situation.
-
Identify Transactions: Look for those long-term transactions for which basis is not reported to the IRS that lack reported details, often indicated by Code E on Form 1099-B. It’s crucial to establish a legitimate cost foundation; otherwise, you might be taxed on total proceeds, which can significantly increase your tax obligation. For instance, inaccurate cost reporting could lead to a tax discrepancy of $320,846, a situation no one wants to face.
-
Complete Form 8949: Use Form 8949 to report these transactions. In Part II, check Box E to indicate that the foundation was not reported in the context of long-term transactions for which basis is not reported to the IRS. Remember, as tax experts say, “If there is no basis on the 1099-B then you must provide it from your records.”
-
Calculate Gains or Losses: Determine the gain or loss for each transaction by subtracting the sale price from the amount you received (if known). Accurate calculations are vital, as incorrect reporting can lead to significant tax differences.
-
Transfer to Schedule D: Summarize the totals from Form 8949 on Schedule D, which is used to report capital gains and losses. This step ensures that your overall tax liability is accurately reflected, providing peace of mind.
-
File Your Tax Return: Make sure your tax return includes all necessary forms and is submitted by the deadline to avoid penalties. Connecting with tax specialists can offer further insight into complex situations, especially those involving noncovered stock or incremental purchases. Imagine facing considerable tax consequences due to an unreported cost foundation; this highlights the importance of following these steps.
Together, we can navigate this journey, ensuring that you feel supported and informed every step of the way.
Implement Best Practices for Managing Long-Term Transactions
To effectively manage long-term transactions, young families can adopt best practices that ensure accurate tax reporting and compliance with IRS regulations, ultimately optimizing their financial well-being.
Imagine if you could take control of your financial future. Maintaining accurate records is a crucial first step. Keep comprehensive records of all transactions, including purchase dates, amounts, and any adjustments to the basis. This diligence is essential, as almost one-third of taxpayers do not keep precise records for their investments, leading to potential overpayments. In fact, 93% of SME owners overpay their taxes due to overlooked deductions and credits. This highlights the importance of thorough documentation in a comprehensive family financial strategy.
Next, regularly reviewing your investments can make a significant difference. Periodically assess your investment portfolio to identify assets nearing the one-year mark for long-term capital gains treatment. This proactive approach can greatly impact your tax liabilities and align with your family’s financial goals.
It’s also vital to consult a tax professional. Engaging with a tax advisor ensures compliance with IRS regulations and helps you optimize your tax strategy. As John Ecton, founder of Ecton Law Firm, emphasizes, “Accurate record-keeping is foundational for effective tax management and can prevent costly mistakes.” Professional guidance can help navigate the complexities of tax planning, especially for high-income families like Allison and Brian, who may face unique financial challenges.
Additionally, educating yourself about changes in tax laws and documentation requirements is crucial to avoid surprises during tax season. Knowledge is power, and understanding the nuances of tax obligations can lead to better financial decisions, enhancing your family’s overall financial strategy, including budgeting and cash flow projections.
Consider utilizing technology as well. Leverage financial management software to track transactions and generate reports that simplify the tax reporting process. This technology can enhance your ability to maintain organized records, making tax season less stressful and more efficient.
Remember, the IRS has a three-year period of limitations for most tax documents, which can extend to six or more years in cases of fraud or significant error. It’s advisable to keep federal, state, and local tax returns for up to seven years after filing. By implementing these practices, you can ensure that your long-term investments are managed effectively, minimizing tax liabilities and maximizing financial success for your family. Together, we can navigate this journey toward a more secure financial future.

Conclusion
Understanding long-term transactions without basis reporting to the IRS is crucial for maintaining compliance and optimizing your family’s tax obligations. By grasping the significance of accurately reporting the cost basis of capital assets held for over a year, you can avoid unnecessary penalties and the risk of inflated tax liabilities. Transparency in tax reporting is essential to safeguard your family’s financial well-being.
Imagine if you could navigate the complexities of tax obligations with confidence. Key points throughout this article highlight the implications of unreported basis, the steps necessary for accurate reporting, and best practices for managing long-term transactions. The potential consequences of neglecting to disclose the basis can lead to severe financial repercussions, including increased capital gains taxes and the stress of potential audits. By maintaining thorough documentation, consulting with tax professionals, and utilizing technology for record-keeping, you can effectively manage these challenges.
Ultimately, taking proactive measures in managing long-term transactions is vital for your family’s financial security. By implementing best practices and staying informed about IRS guidelines, you can minimize tax liabilities and enhance your overall financial strategy. Embracing these insights not only empowers you to make informed decisions but also paves the way for a more secure financial future. Together, we can navigate this journey, ensuring your family’s financial health remains a top priority.
Frequently Asked Questions
What are long-term transactions in relation to capital assets?
Long-term transactions refer to the sale of capital assets that have been held for over a year.
Why is basis reporting important for long-term transactions?
Basis reporting is crucial because it requires disclosing the cost foundation of the assets to the IRS, ensuring transparency and compliance with tax regulations.
What does the cost foundation represent?
The cost foundation represents the original value of the asset, adjusted for factors such as enhancements or depreciation.
What form is used to report basis to the IRS?
The IRS mandates submission on Form 1099-B, which indicates whether the foundation is disclosed.
What should you do if the foundation is not disclosed?
If the foundation isn’t disclosed, it is essential to accurately document long-term transactions to prevent potential fines.
How can understanding and declaring the foundation impact tax obligations?
Understanding and accurately declaring the foundation can significantly influence your tax obligations, ensuring adherence to regulations and reducing risks associated with erroneous submissions.
List of Sources
- Define Long-Term Transactions and Basis Reporting
- Long-Term vs. Short-Term Capital Gains (https://investopedia.com/articles/personal-finance/101515/comparing-longterm-vs-shortterm-capital-gain-tax-rates.asp)
- 2024-2025 Long-Term Capital Gains Tax Rates | Bankrate (https://bankrate.com/investing/long-term-capital-gains-tax)
- Internal Revenue Bulletin: 2025-30 | Internal Revenue Service (https://irs.gov/irb/2025-30_IRB)
- SOI Tax Stats – Sales of capital assets reported on individual tax returns | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-sales-of-capital-assets-reported-on-individual-tax-returns)
- 130 Inspirational Quotes About Taxes (https://inc.com/geoffrey-james/130-inspirational-quotes-about-taxes.html)
- Explore Implications of Unreported Basis on Tax Obligations
- ‘Nothing is certain except death and taxes’ – Benjamin Franklin, 1789 | W1M (https://w1m.com/insights/nothing-is-certain-except-death-and-taxes—benjamin)
- Financial – Planning – Case – Studies 2023 | PDF | Investment Fund | Exchange Traded Fund (https://scribd.com/document/695749725/Financial-Planning-Case-Studies-2023)
- Breaking Down the Federal Tax Gap | Bipartisan Policy Center (https://bipartisanpolicy.org/explainer/breaking-down-the-federal-tax-gap)
- For Your Reading Entertainment: As Certain As Death, Quotations About Taxes. (https://taxfoundation.org/blog/your-reading-entertainment-certain-death-quotations-about-taxes)
- Detail Steps for Reporting Long-Term Transactions Without Basis
- Noncovered Transactions – Cost Basis not Reported to IRS – Form 8949 (https://ttlc.intuit.com/community/taxes/discussion/noncovered-transactions-cost-basis-not-reported-to-irs-form-8949/00/2873593)
- The Purpose of IRS Form 8949 (https://investopedia.com/articles/personal-finance/083015/purpose-irs-form-8949.asp)
- Charles Schwab: Box E: Long term sales with cost basis NOT reported to the IRS (https://ttlc.intuit.com/community/taxes/discussion/charles-schwab-box-e-long-term-sales-with-cost-basis-not-reported-to-the-irs/00/2496398)
- About Form 8949, Sales and other Dispositions of Capital Assets | Internal Revenue Service (https://irs.gov/forms-pubs/about-form-8949)
- Implement Best Practices for Managing Long-Term Transactions
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)
- The Importance of Investment Recordkeeping (https://finra.org/investors/insights/recordkeeping)
- The Importance Of Accurate Record-Keeping For Tax Compliance | Ecton Law Firm, PA (https://ectonlawfirm.com/the-importance-of-accurate-record-keeping-for-tax-compliance)
- The Importance of Accurate Record-Keeping for Small Businesses – Better Accounting (https://betteraccounting.com/the-importance-of-accurate-record-keeping-for-small-businesses)
- 10 Spend Management Statistics You Need to Know About (https://veridion.com/blog-posts/spend-management-statistics)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading