

Key Highlights
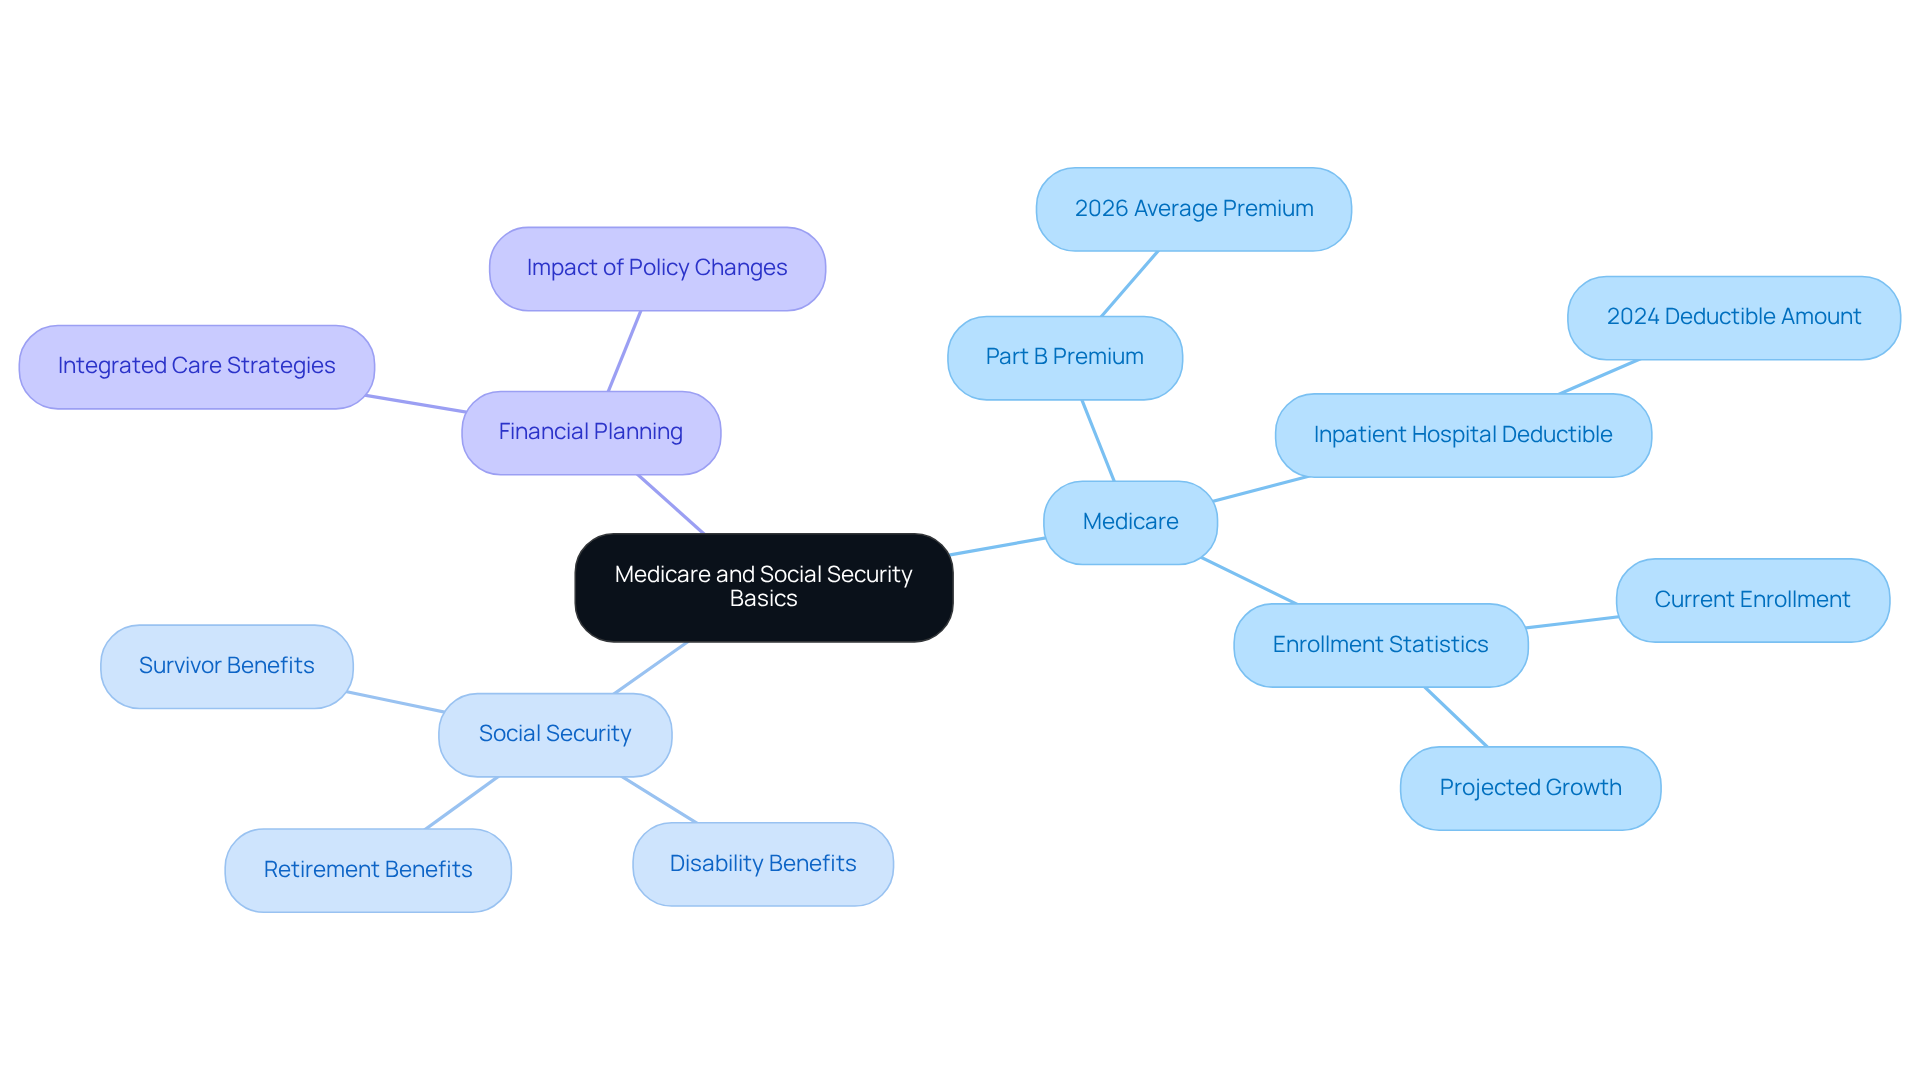
- Medicare primarily supports individuals aged 65 and older, while Social Security offers financial assistance through retirement, disability, and survivor benefits.
- In 2026, the average Part B premium is projected to be $202.90, significantly impacting retirement budgets.
- The inpatient hospital deductible for Original Medicare is expected to rise to $1,632, with various coinsurance rates for hospital stays.
- Over 69 million individuals are enrolled in Medicare, with the number expected to grow as the population ages.
- 19% of Medicare beneficiaries also receive Medicaid assistance, highlighting the need for integrated care strategies.
- Medicare Part B premiums are deducted from Social Security benefits, affecting net income for retirees.
- In 2026, the Part B deductible will increase to $283, which is crucial for beneficiaries to consider in their financial planning.
- Families can manage Medicare premiums through various payment options, including automatic deductions from Social Security or direct payments.
- Many Medicare recipients face financial challenges, with half earning less than $43,200, emphasising the importance of budgeting for healthcare costs.
- Working with a fiduciary advisor like Bright Advisers can help families navigate financial planning and healthcare costs effectively.
Introduction
Imagine feeling secure about your family’s financial future, even as healthcare costs rise and financial planning becomes more complex. As healthcare costs rise, it’s crucial to understand how Medicare premiums affect your Social Security checks. This knowledge is key to effective financial planning.
With the average Part B premium expected to hit $202.90 in 2026, families may find themselves facing tough choices about their budgets.
So, how can you prepare for these changes and make informed choices that protect your family’s financial health?
Clarify Medicare and Social Security Basics
Imagine trying to plan for your family’s future while navigating the complexities of Social Security and health insurance – it’s a challenge many parents face. The federal health insurance program mainly supports those 65 and older, while Social Security provides financial help through retirement, disability, and survivor benefits. It’s important to understand how these programs can work together to support your family’s financial future.
In 2026, families can expect the average Part B premium to be around $202.90 a month – an expense that can really impact your retirement budget. The inpatient hospital deductible for Original health insurance is set at $1,632, with various coinsurance rates for hospital stays. As of November 2025, over 69 million individuals are enrolled in the health insurance program, and this number is expected to grow as our population ages. As more families face these realities, it becomes crucial to integrate healthcare and Social Security into your financial planning.
Case studies show that households who actively prepare for medical expenses and retirement income through these programs can more effectively manage the challenges of aging. For instance, recognizing that 19% of individuals benefiting from the federal health program also receive Medicaid assistance emphasizes the necessity for integrated care strategies, especially for those with lower incomes.
In light of recent discussions around medical policy, including the Inflation Reduction Act aimed at lowering prescription drug costs, households must stay informed about changes that could affect their financial planning. When you understand how these programs work together, you can make informed choices that benefit your family’s health and financial future.
Explain Medicare Premium Deductions from Social Security
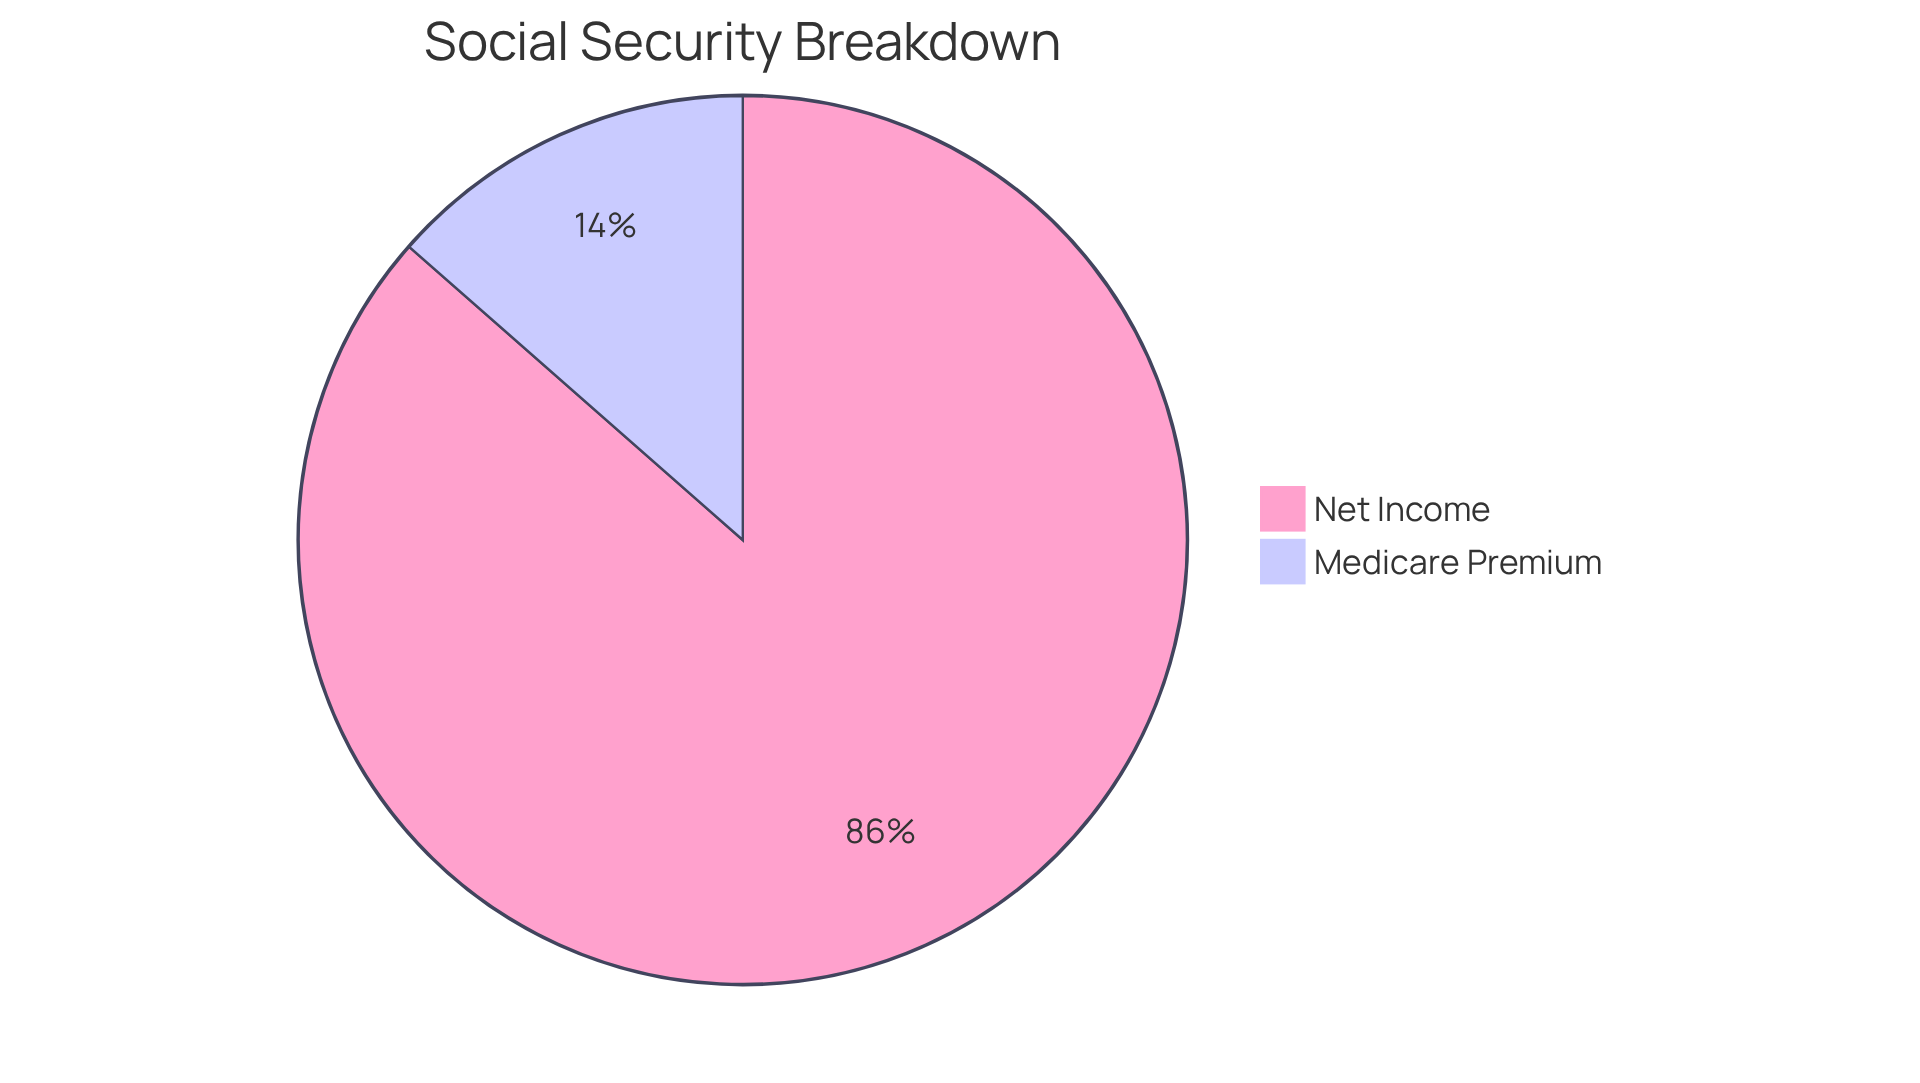
Imagine facing rising medical bills while your income barely keeps pace. How would that feel? For those enrolled in Medicare Part B, the Medicare payment deducted from Social Security check is automatically applied to the monthly premium. In 2026, if your Social Security benefit is $1,500, you can expect about $1,297.10 after the standard premium of $202.90 is deducted. About 8% of Part B and Part D recipients, those with incomes over $109,000 for individuals or $218,000 for joint filers, may face extra surcharges that affect their net income.
This deduction matters because many seniors feel the weight of rising medical expenses that often outpace their Social Security adjustments. The 2026 increase in the Part B premium of $17.90 coincides with a 2.8% COLA, which translates to an average increase of $56 in Social Security benefits. However, for many, this adjustment doesn’t fully offset the premium increase, leading to a net loss in monthly income. Furthermore, the Part B deductible will increase to $283 in 2026, a significant detail for beneficiaries to consider when planning for medical expenses.
Understanding the Medicare payment deducted from Social Security check can assist families in budgeting wisely and planning for other expenses as they navigate the challenges of healthcare costs in retirement. As Shannon Benton, executive director of The Senior Citizens League, stated, “Increasing healthcare premiums degrade the quality of life for American seniors over time.
Explore Payment Options for Medicare Premiums
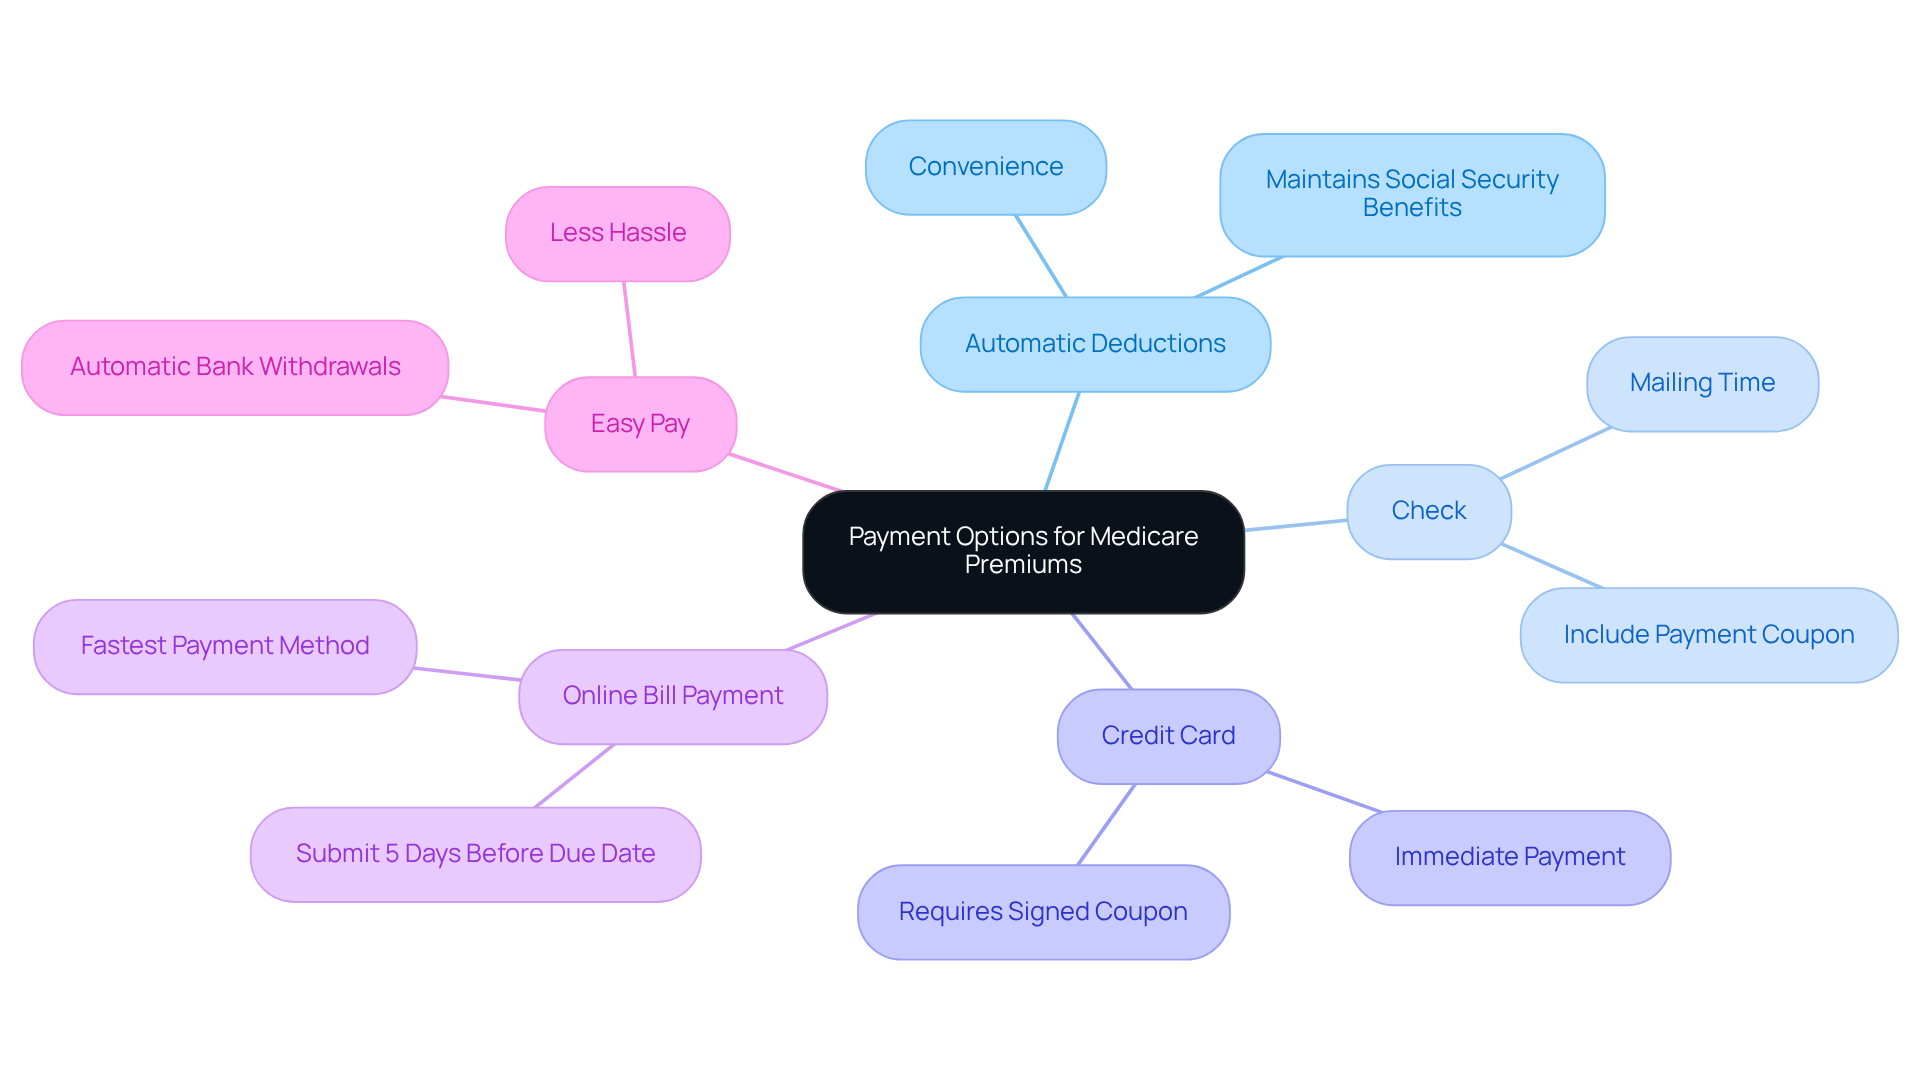
Imagine juggling family expenses while trying to keep your budget on track. You might be surprised to learn there are several ways to manage your health insurance premiums. Many families opt for automatic deductions from their Social Security benefits, such as the Medicare payment deducted from the Social Security check, but alternatives exist that might suit your needs better. You can pay by check, credit card, or even through your bank’s online bill payment service.
Additionally, Easy Pay offers automatic bank withdrawals, making it easier to handle payments without the hassle. It’s important for families to consider what works best for their unique financial situation and peace of mind. For instance, if you prefer to keep your Social Security benefits intact for other expenses, paying your premiums directly could be a wise choice.
By exploring these options, you can find a method that aligns with your family’s budgeting preferences and helps ease financial stress. Choosing the right payment method can make a world of difference in your family’s financial peace of mind.
Connect Medicare Deductions to Financial Planning
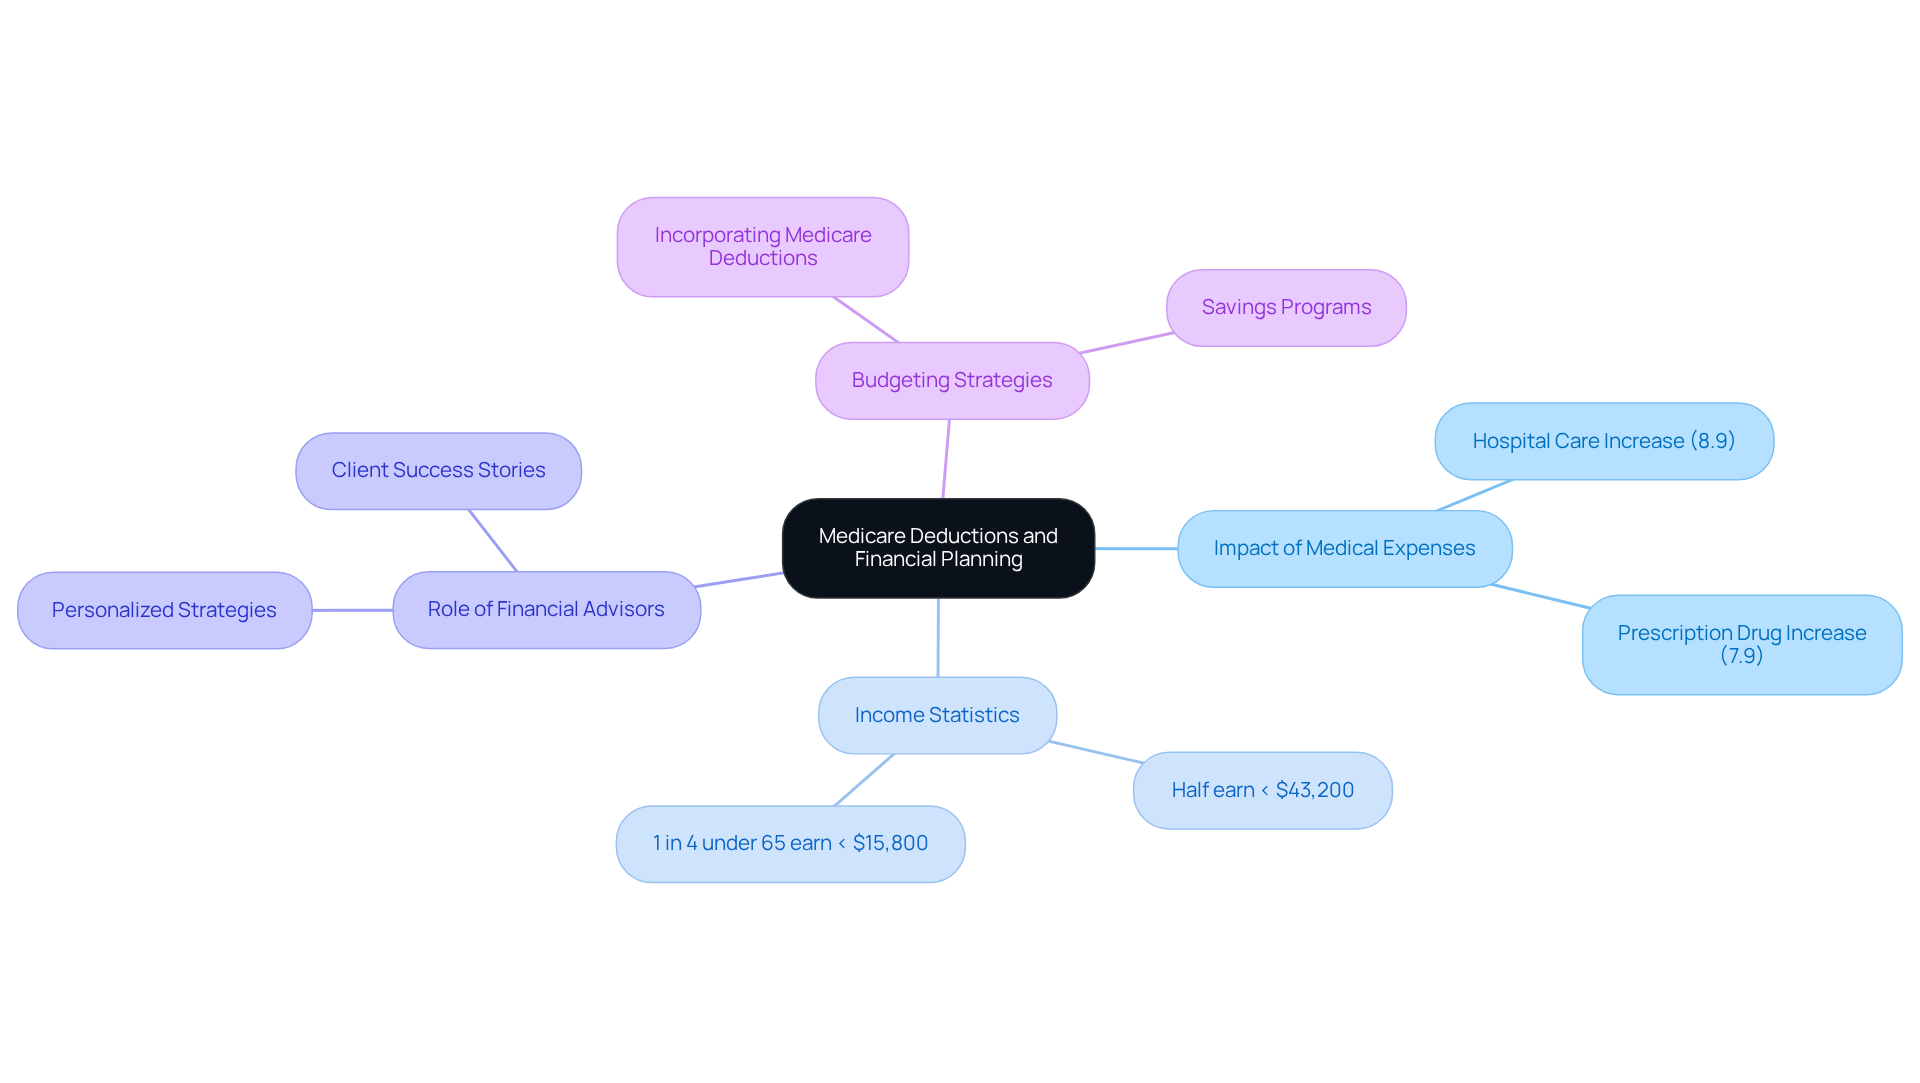
Imagine the worry of unexpected medical bills piling up, leaving you feeling overwhelmed and uncertain about your family’s financial future. As medical expenses continue to rise, it’s crucial to think about how medical deductions can fit into your family’s budget. In 2024, we saw significant increases in medical spending, with hospital care and prescription drugs rising by 8.9% and 7.9%, respectively. Understanding how healthcare premiums impact your overall financial situation is more important than ever.
Did you know that many Medicare recipients struggle financially, with half earning less than $43,200? This highlights the real challenges families face today. Moreover, one in four beneficiaries under age 65 lives on incomes below $15,800, which means younger households also need to consider these deductions in their budgeting.
Working with a caring money advisor, like those at Bright Advisers, can help your family find personalized strategies to navigate these challenges together. For instance, Savings Programs can assist individuals with limited income in managing premium costs, ensuring you’re prepared for both expected and unexpected healthcare expenses as your family grows. Bright Advisers has successfully supported clients like Emily and Mark, who wanted to improve their financial situation while balancing demanding careers. Through comprehensive assessments and personalized planning, they gained the flexibility to make career choices that align with their desired work-life balance.
By proactively incorporating the medicare payment deducted from social security check into your budgeting strategies, you can take control of your family’s financial future and navigate the complexities of healthcare costs with confidence. Bright Advisers is here to empower families to create a life that aligns with their personal and financial aspirations, ensuring you’re well-prepared for the journey ahead.
Conclusion
Imagine the worry of unexpected medical bills piling up, leaving you unsure about your family’s financial future. Understanding how Medicare and Social Security work together can help ease that concern. As healthcare costs rise, it’s important to know how Medicare premiums affect your Social Security checks and your family’s budget. When you understand these concepts, you can feel more confident in making choices that support your family’s future.
We’ve shared important insights about Medicare Part B premiums, rising costs, and your payment options. It’s crucial to include these deductions in your financial plan, especially when balancing healthcare costs and retirement income. Planning ahead can help you navigate the complexities of Medicare and Social Security with confidence.
We invite you to explore personalized strategies with a trusted advisor, like those at Bright Advisers, to prepare for both expected and unexpected healthcare costs. Together, we can navigate these financial waters, ensuring your family is prepared for whatever comes next.
Frequently Asked Questions
What are the main purposes of Medicare and Social Security?
Medicare primarily supports individuals aged 65 and older with health insurance, while Social Security provides financial assistance through retirement, disability, and survivor benefits.
What is the expected average Part B premium for Medicare in 2026?
The average Part B premium for Medicare is expected to be around $202.90 a month in 2026.
What is the inpatient hospital deductible for Original Medicare?
The inpatient hospital deductible for Original Medicare is set at $1,632.
How many individuals are currently enrolled in Medicare, and what is the trend?
As of November 2025, over 69 million individuals are enrolled in Medicare, and this number is expected to grow as the population ages.
Why is it important to integrate healthcare and Social Security into financial planning?
Integrating healthcare and Social Security into financial planning is crucial for effectively managing the challenges of aging and ensuring that families can handle medical expenses and retirement income.
What percentage of individuals benefiting from Medicare also receive Medicaid assistance?
Approximately 19% of individuals benefiting from Medicare also receive Medicaid assistance, highlighting the need for integrated care strategies, especially for those with lower incomes.
What recent policy changes should households be aware of regarding healthcare costs?
Households should stay informed about recent discussions around medical policy, including the Inflation Reduction Act, which aims to lower prescription drug costs, as these changes could affect financial planning.
List of Sources
- Clarify Medicare and Social Security Basics
- 31 Mind-Boggling Medicare Stats In 2026 & Beyond (https://seniorsmutual.com/medicare-stats)
- Medicare statistics 2026 (https://singlecare.com/blog/news/medicare-statistics)
- Medicare statistics 2026 (https://consumeraffairs.com/insurance/medicare-statistics.html)
- Monthly Statistical Snapshot, June 2026 (https://ssa.gov/policy/docs/quickfacts/stat_snapshot)
- Explain Medicare Premium Deductions from Social Security
- 2026 Medicare Premiums Announced, Last Weeks of Open Enrollment – Medicare Rights Center (https://medicarerights.org/medicare-watch/2025/11/20/2026-medicare-premiums-announced-last-weeks-of-open-enrollment)
- How are Medicare costs and benefits changing for 2026? | medicareresources.org (https://medicareresources.org/faqs/what-kind-of-medicare-benefit-changes-can-i-expect-this-year)
- How Much Will Your Medicare Part B Premium Rise in 2026? (https://moaa.org/content/publications-and-media/news-articles/2025-news-articles/health-care-and-earned-benefits/how-much-will-your-medicare-part-b-premium-rise-in-2026)
- 2026 Medicare Parts A & B Premiums and Deductibles – Center for Medicare Advocacy (https://medicareadvocacy.org/2026-medicare-rates)
- Medicare Part B Premium to Top $200 a Month in 2026 (https://aarp.org/medicare/medicare-part-b-premium-increase-2026)
- Explore Payment Options for Medicare Premiums
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- How to Pay Part A & Part B premiums (https://medicare.gov/basics/costs/pay-premiums)
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)
- Financial Advice Quotes (58 quotes) (https://goodreads.com/quotes/tag/financial-advice)
- Famous Quotes on Financial Stability and Well-Being – Center for the Advancement of Well-Being (https://wellbeing.gmu.edu/famous-quotes-on-financial-stability-and-well-being)
- Connect Medicare Deductions to Financial Planning
- Medical cost trend 2027: Behind the Numbers (https://pwc.com/us/en/industries/health-industries/library/behind-the-numbers.html)
- Income and Assets of Medicare Beneficiaries in 2024 | KFF (https://kff.org/medicare/income-and-assets-of-medicare-beneficiaries)
- How Your Income Affects Your Medicare Premium (https://aarp.org/videos/medicare/6386286525112)
- Trends in healthcare spending (https://ama-assn.org/about/ama-research/trends-healthcare-spending)
- How Higher Income Can Affect Medicare Premiums (https://schwab.com/learn/story/how-higher-income-can-affect-medicare-premiums)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading