

Overview
Understanding Modified Adjusted Gross Income (MAGI) is crucial for families. It plays a vital role in determining their eligibility for important tax benefits and credits, such as the Child Tax Credit and health insurance subsidies under the Affordable Care Act.
Imagine if you could optimize your tax benefits and secure crucial financial assistance for your family. By accurately calculating MAGI—starting from Adjusted Gross Income (AGI) and adding specific deductions—families can take significant steps toward achieving this goal.
We’re here for you as you navigate this journey, ensuring you don’t lose out on essential support. Together, we can ensure that your family receives the financial help it deserves.
Key Highlights:
- Modified Adjusted Gross Income (MAGI) is crucial for determining eligibility for various tax benefits and credits.
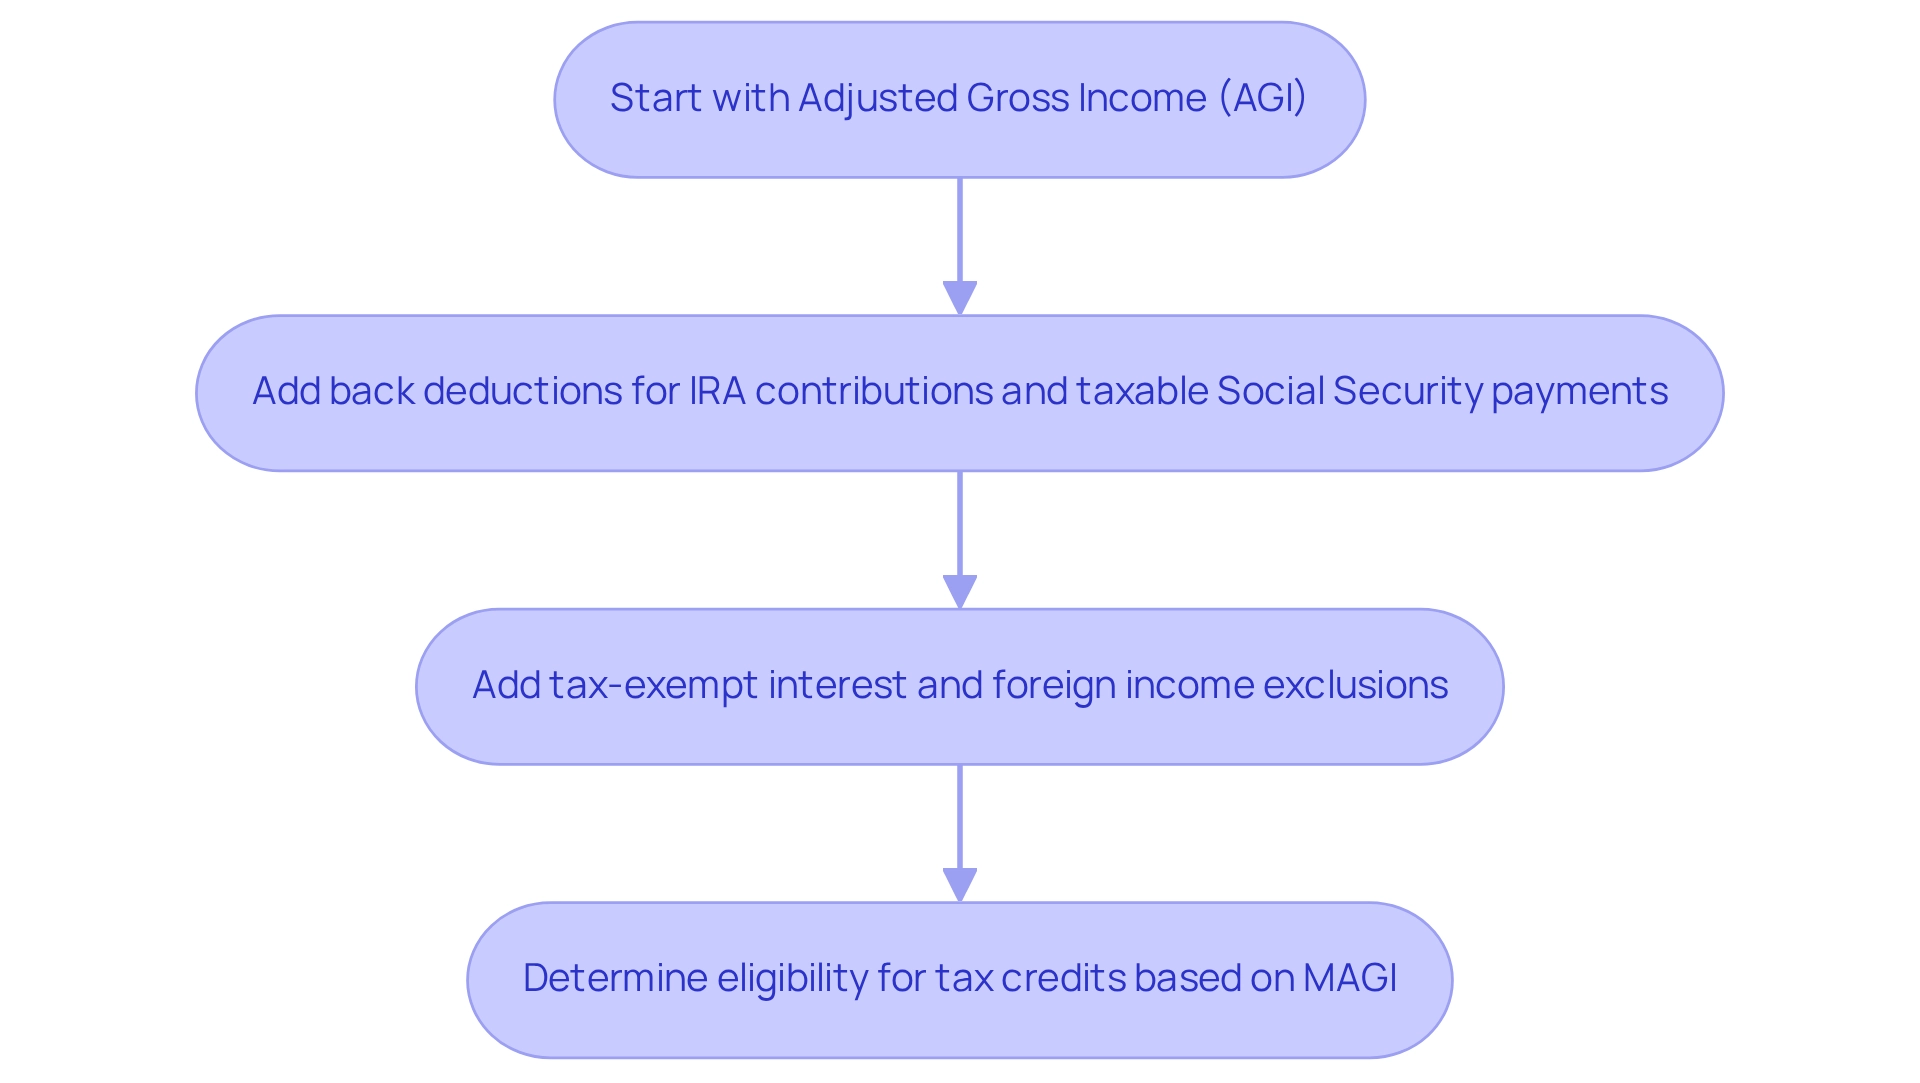
- MAGI is calculated by starting with Adjusted Gross Income (AGI) and adding specific deductions such as IRA contributions and tax-exempt interest.
- Understanding MAGI helps families optimize tax benefits, such as the Child Tax Credit and health insurance subsidies under the Affordable Care Act.
- Households with a MAGI below $200,000 (individual) or $400,000 (joint) can claim the Child Tax Credit, providing up to $2,000 per eligible child.
- MAGI also affects eligibility for premium tax credits, which can significantly reduce health insurance costs for families.
- Accurate MAGI calculation can prevent loss of tax credit eligibility if AGI exceeds certain thresholds.
- Examples illustrate the impact of MAGI on financial planning, including potential higher Medicare premiums for those exceeding income thresholds.
- Consulting a tax professional is recommended for families to navigate MAGI complexities and maximize tax benefits.
Introduction
In the intricate landscape of family finances, understanding Modified Adjusted Gross Income (MAGI) is essential. This financial metric, defined by the IRS, acts as a gateway to various tax benefits and credits that can help ease the financial burdens many families face. Imagine if you could unlock eligibility for crucial programs like the Child Tax Credit and health insurance subsidies under the Affordable Care Act—this is where calculating MAGI comes into play. By doing so, families can truly maximize their financial advantages.
As you navigate the complexities of income and deductions, the ability to accurately assess MAGI becomes a vital tool in your financial toolkit. It’s important to understand that with the right guidance, you can strategically manage your finances, optimize tax benefits, and work towards securing a more stable future for your loved ones. Together, we can navigate this journey and ensure that your family thrives.
Define Modified Adjusted Gross Income (MAGI)
Understanding modified adjusted gross income (MAGI) is crucial for families, especially in navigating the complexities of tax benefits and credits. This important financial metric, modified adjusted gross income (MAGI), defined by the IRS, plays a vital role in determining eligibility for various tax advantages. To calculate modified adjusted gross income (MAGI), begin with your Adjusted Gross Income (AGI) and add back specific deductions that were previously removed. As Michela Buttignol explains, ‘To determine your modified adjusted gross income (MAGI), take your AGI and add back: Any deductions you took for IRA contributions and taxable Social Security payments.’ This may also include tax-exempt interest and foreign earned income exclusions.
Imagine the impact this understanding can have on families like Jay and Emma, who are striving to alleviate financial stress. By grasping the concept of modified adjusted gross income (MAGI), they can optimize their tax benefits and ensure they remain eligible for crucial programs such as the Child Tax Credit and health insurance subsidies under the Affordable Care Act. It’s important to recognize that accurately calculating modified adjusted gross income (MAGI) can help prevent losing eligibility for certain tax credits if their AGI exceeds specific thresholds. For instance, if a household’s AGI goes over $200,000, they might forfeit access to valuable tax credits.
Together, we can navigate these complexities. By partnering with Bright Advisers, families can access customized wealth management solutions tailored to their unique needs. This collaboration not only helps them tackle financial challenges but also empowers them to safeguard their future and achieve their financial goals. Remember, we’re here for you, and together, we can make this journey smoother.
Explain the Importance of MAGI for Family Finances
Understanding your modified adjusted gross income (MAGI) is vital for your family’s financial health. It directly influences your eligibility for various tax credits and deductions that can significantly ease financial burdens. For example, if your modified adjusted gross income (MAGI) is below $480,000 as a married couple filing jointly, you may qualify for the Child Tax Credit (CTC), offering meaningful tax relief. Understanding modified adjusted gross income (MAGI) is also crucial for accessing premium tax credits under the Affordable Care Act, making it essential for families seeking affordable health insurance options. Imagine the peace of mind that comes with grasping the details of your modified adjusted gross income (MAGI). By doing so, families can skillfully manage their income and expenses, optimizing available tax benefits while minimizing liabilities.
Take Emily and Mark, for instance. This young couple is balancing their careers while striving for financial independence. With the help of Bright Advisers, they received personalized guidance to improve their financial situation, including a deep understanding of their MAGI. Bright Advisers empowered them by identifying specific deductions and credits, enabling informed financial decisions that align with their personal and professional goals.
Consider Genevieve, who has an Adjusted Gross Income (AGI) of $85,000, along with $10,000 in tax-exempt interest income and a $3,000 rental loss. After factoring in the tax-exempt interest and rental loss, her modified adjusted gross income (MAGI) totals $98,000. This amount exceeds the threshold for Medicare premium surcharges, resulting in higher premiums. This example illustrates how understanding modified adjusted gross income (MAGI) can have a profound impact on financial outcomes.
Important add-backs in modified adjusted gross income (MAGI) calculations include:
- Foreign earned income exclusion
- IRA contributions
While exclusions consist of:
- Roth IRA contributions
- 401(k) contributions
Looking ahead to 2025, the implications of modified adjusted gross income (MAGI) will continue to affect various household tax credits, including the CTC, which is designed to support families financially. For specific questions about MAGI, consulting a tax professional is a wise step. By staying informed about income thresholds and their calculations, families can navigate the complexities of tax credits and deductions more effectively, ultimately enhancing their financial well-being. Remember, together, we can navigate this journey towards financial security.
Detail How to Calculate MAGI and Its Components
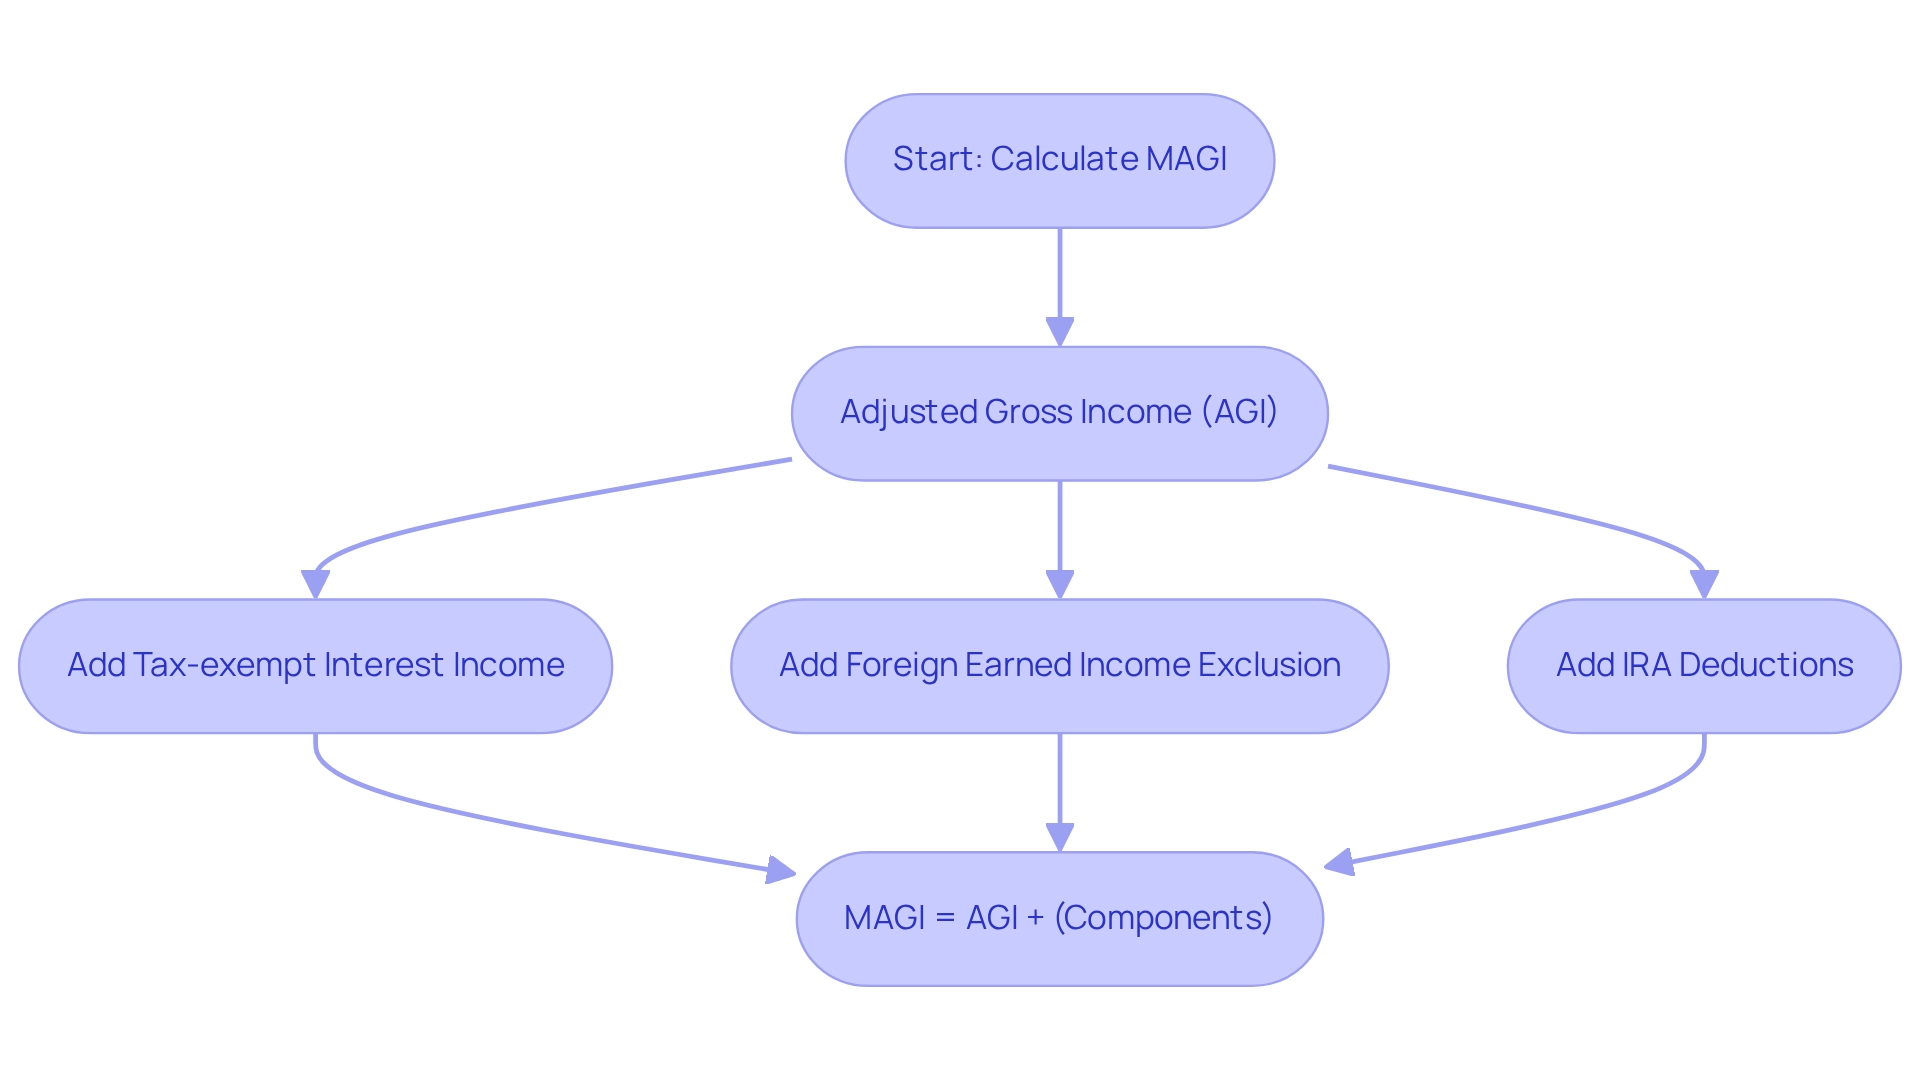
Calculating your modified adjusted gross income (MAGI) is an important step in understanding your financial landscape. Begin with your Adjusted Gross Income, which you can find on your tax return. Then, add back certain deductions that were excluded from your AGI. Here are the common components to consider:
- Tax-exempt interest income: This is the interest you earn from municipal bonds, which is not subject to federal tax.
- Foreign earned income exclusion: If you qualify for this exclusion, remember to add it back to your AGI. You’ll find this documented on Form 2555, especially important for Americans living abroad.
- Deductions for traditional IRA contributions: Any amounts you’ve deducted for contributions to a traditional IRA should also be included.
In summary, the calculation for modified adjusted gross income (MAGI) looks like this:
Modified Adjusted Gross Income (MAGI) = Adjusted Gross Income + Tax-exempt interest + Foreign earned income exclusion + IRA deductions.
Understanding how to accurately calculate your modified adjusted gross income (MAGI) is crucial for families, as it can influence eligibility for various tax credits, including the Child Tax Credit and Adoption Tax Credit. For example, your modified adjusted gross income (MAGI) is essential in establishing the boundaries for these credits, which can significantly impact your family’s financial situation. Additionally, if you and your spouse are filing jointly, be aware that you may have different limits for IRA deductions based on participation in retirement plans. This highlights the importance of considering your marital status in these calculations.
By grasping this calculation, families can make informed decisions about their tax situations and future planning. Imagine Jay and Emma, who worked with Bright Advisers to enhance their tax strategies. This partnership helped them reduce stress while preparing for their children’s education. Similarly, Emily and Mark utilized their modified adjusted gross income (MAGI) calculations to create a budget that allowed them the freedom to choose their career paths. Allison and Brian focused on tax optimization to secure their children’s future and enable an earlier retirement. Bright Advisers empowers young families by offering tailored wealth management solutions that enhance economic security. As Pamela de la Fuente, Leader of Consumer Credit and Debt Team at NerdWallet, emphasizes, understanding these economic metrics is vital for effective money management.
We’re here for you in this journey, helping you navigate the complexities of financial planning together.
Explore MAGI’s Role in Tax Credits and Deductions
Adjusted Gross Income is more than just a number; it plays a crucial role in determining eligibility for various tax credits and deductions that can greatly assist families like Jay and Emma, who are striving to reduce stress while planning for their children’s education and their own retirement. Understanding modified adjusted gross income (MAGI) is essential for optimizing monetary benefits, especially in the following areas:
- Child Tax Credit: Imagine a household with a modified adjusted gross income (MAGI) under $200,000 for individual filers and $400,000 for joint filers. They can claim this credit, which lowers their tax obligation by up to $2,000 per eligible child. This credit is vital for easing the financial strain of raising children and can be a crucial element in their overall financial plan.
- Premium Tax Credit: Under the Affordable Care Act, modified adjusted gross income is used to evaluate eligibility for subsidies that reduce health insurance premiums. Households with an adjusted gross income between 100% and 400% of the federal poverty level can receive significant assistance, making healthcare more affordable. In 2025, households earning below $101,077.25 may qualify for these credits, enhancing their access to necessary medical services. Advance payments of the tax credit can be utilized immediately to decrease monthly premium expenses, further assisting households in managing healthcare costs and alleviating economic pressure.
It’s important to understand that modified adjusted gross income (MAGI) also impacts eligibility for education-related tax credits, such as the American Opportunity Credit and the Lifetime Learning Credit. These credits can assist in reducing the expenses of higher education, offering households monetary support as they invest in their children’s futures, while real-world examples demonstrate the significance of modified adjusted gross income (MAGI) in obtaining tax advantages. Families who strategically handle their modified adjusted gross income (MAGI) can enhance their eligibility for these credits, ensuring they receive the greatest assistance available.
Additionally, taxpayers who reported excess Advanced Premium Tax Credit (APTC) repayment amounts in 2020 will automatically have their repayment amounts reduced to zero by the IRS, resulting in refunds without the need for amendments. This highlights how understanding modified adjusted gross income (MAGI) can lead to significant financial advantages for families, enabling them to navigate their financial challenges more effectively. By comprehending how modified adjusted gross income (MAGI) impacts these credits and deductions, families can effectively plan their finances to maximize tax benefits, ultimately securing a more stable financial future. Together, we can navigate this journey, ensuring that every family has the support they need.
Conclusion
Navigating the complexities of Modified Adjusted Gross Income (MAGI) is essential for families seeking to optimize their financial situation. Understanding MAGI not only provides clarity on how to calculate it but also highlights its significant impact on eligibility for various tax credits and deductions. By starting with Adjusted Gross Income (AGI) and adding specific deductions, families can accurately assess their MAGI. This can open doors to valuable financial benefits such as the Child Tax Credit and health insurance subsidies under the Affordable Care Act.
The importance of MAGI extends beyond mere calculations; it serves as a strategic tool for families like Jay and Emma or Emily and Mark, who are working towards financial stability and planning for their children’s future. Imagine if you could leverage the insights gained from understanding MAGI to make informed decisions that enhance your eligibility for tax credits. This could ultimately reduce your financial burdens. Real-life examples illustrate how tailored financial guidance can empower families to navigate these complexities and maximize their available resources.
In conclusion, grasping the nuances of MAGI is not just an academic exercise; it is a crucial component of effective financial management that can lead to substantial tax savings and improved financial well-being. By prioritizing the understanding and calculation of MAGI, families can work towards securing a brighter, more stable financial future for themselves and their loved ones. Remember, together, we can navigate this journey, and we’re here for you every step of the way.
Frequently Asked Questions
What is modified adjusted gross income (MAGI)?
Modified adjusted gross income (MAGI) is a financial metric defined by the IRS that is crucial for determining eligibility for various tax benefits and credits.
How do you calculate modified adjusted gross income (MAGI)?
To calculate MAGI, start with your Adjusted Gross Income (AGI) and add back specific deductions that were previously removed, such as deductions for IRA contributions, taxable Social Security payments, tax-exempt interest, and foreign earned income exclusions.
Why is understanding MAGI important for families?
Understanding MAGI helps families optimize their tax benefits and maintain eligibility for important programs like the Child Tax Credit and health insurance subsidies under the Affordable Care Act.
What can happen if a household’s AGI exceeds certain thresholds?
If a household’s AGI exceeds specific thresholds, such as $200,000, they may lose access to valuable tax credits.
How can families get assistance with calculating MAGI and navigating tax benefits?
Families can partner with financial advisors, such as Bright Advisers, to access customized wealth management solutions tailored to their unique needs, helping them tackle financial challenges and achieve their financial goals.
List of Sources
- Define Modified Adjusted Gross Income (MAGI)
- How to calculate modified adjusted gross income (MAGI) (https://peoplekeep.com/blog/how-to-calculate-modified-adjusted-gross-income-magi)
- Modified Adjusted Gross Income (MAGI): Calculating and Using It (https://investopedia.com/terms/m/magi.asp)
- Explain the Importance of MAGI for Family Finances
- Modified adjusted gross income (MAGI): How to calculate MAGI (https://jacksonhewitt.com/tax-help/tax-tips-topics/filing-your-taxes/magi-modified-adjusted-gross-income)
- What is Modified Adjusted Gross Income (MAGI) and how to calculate it? (https://taxesforexpats.com/articles/financial-planning/modified-adjusted-gross-income-magi.html)
- Detail How to Calculate MAGI and Its Components
- What Is a Modified Adjusted Gross Income? The MAGI Explained (https://efile.com/what-is-modified-adjusted-gross-income)
- Modified Adjusted Gross Income under the Affordable Care Act – UPDATED WITH INFORMATION FOR COVID-19 POLICIES – UC Berkeley Labor Center (https://laborcenter.berkeley.edu/modified-adjusted-gross-income-under-the-affordable-care-act)
- What Is Modified Adjusted Gross Income (MAGI)? – NerdWallet (https://nerdwallet.com/article/taxes/modified-adjusted-gross-income-magi)
- Explore MAGI’s Role in Tax Credits and Deductions
- FAQs: Premium Tax Credits (PTCs) and Cost-Sharing Reductions (CSRs) | TargetHIV (https://targethiv.org/library/ace-faq-premium-tax-credits-ptcs-and-cost-sharing-reductions-csrs)
- Publication 505 (2025), Tax Withholding and Estimated Tax | Internal Revenue Service (https://irs.gov/publications/p505)
- Premium Tax Credits | VTLawHelp.org (https://vtlawhelp.org/premium-tax-credits)
- Questions and answers on the Premium Tax Credit | Internal Revenue Service (https://irs.gov/affordable-care-act/individuals-and-families/questions-and-answers-on-the-premium-tax-credit)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading