

Overview
Understanding money managers’ fees is essential for young families. These costs can significantly impact your investment returns and overall financial health. Imagine if you could make informed decisions that truly align with your family’s goals. This article explains various fee structures—like percentage of assets under management, flat fees, and hourly rates. It’s important to understand these options to navigate your financial journey effectively.
Transparency is key. Carefully evaluating total costs, including hidden fees, can empower you to make choices that benefit your family’s future. Remember, every dollar counts when planning for your loved ones. We’re here for you, guiding you through these decisions with care and compassion.
By understanding these fees, you can take control of your financial well-being. Together, we can navigate this journey, ensuring that your investments work for you and your family. Let’s explore these concepts further, so you can feel confident in your financial decisions.
Key Highlights:
- Understanding financial advisor fees is crucial for families’ financial health, as these costs can significantly impact investment returns.
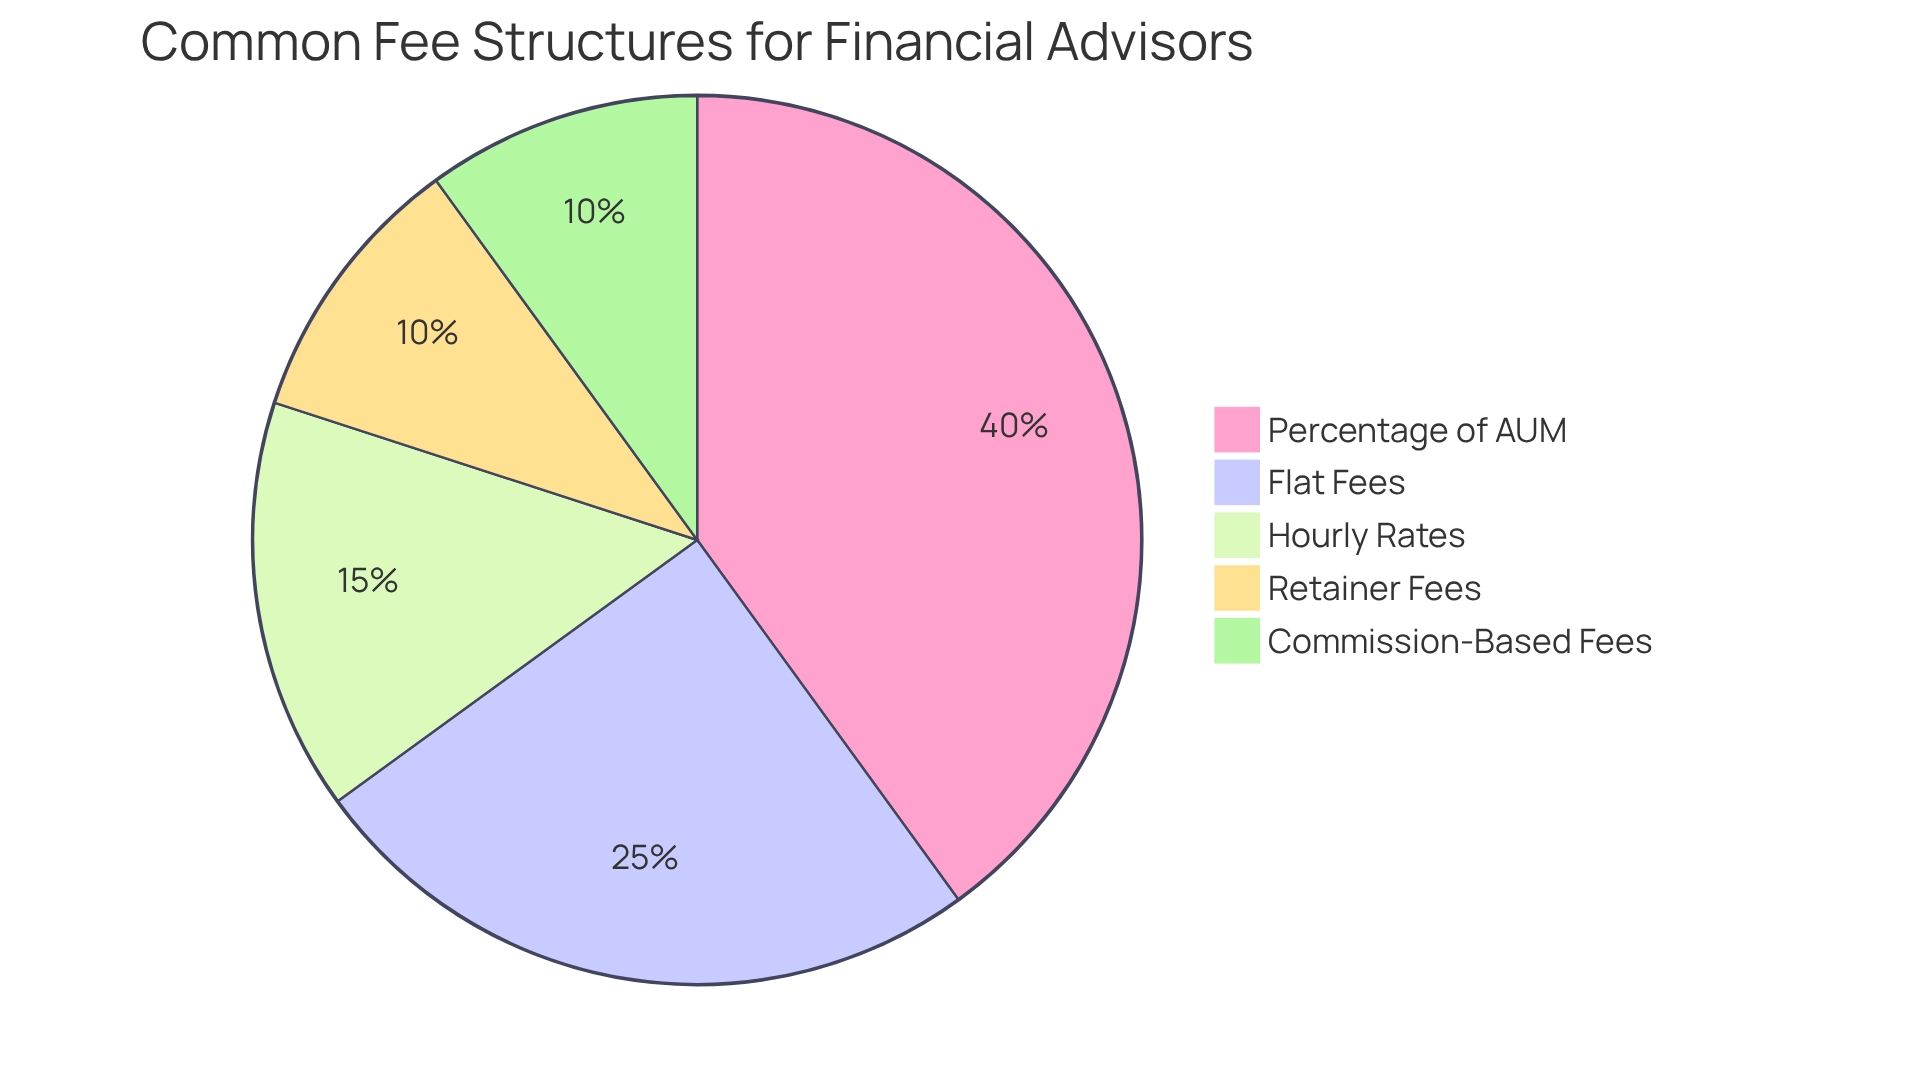
- Common fee structures include percentage of assets under management (AUM), flat fees, hourly rates, retainer fees, and commission-based fees.
- Average money managers fees are approximately 1.05% for AUM, an annual retainer of $4,484, and an hourly rate of $268.
- Families should assess their financial goals and complexity to determine the most suitable fee structure for their needs.
- Transparency in fee structures is vital for building trust and avoiding unexpected costs.
- Hidden fees, such as trading costs and product charges, should be carefully examined to understand total costs.
- Wealth management fees typically range from 0.65% to 1.00% of assets under management, with additional charges for personalized services.
- Balancing cost with the quality of service is essential for achieving desired financial outcomes.
Introduction
In the intricate world of financial planning, understanding the fees associated with hiring a financial advisor is crucial for families striving to secure their financial futures. These fees can vary widely based on the advisor’s compensation model, and they play a significant role in shaping investment returns and overall financial well-being.
Imagine navigating your unique financial landscape—deciphering the various fee structures, from percentages of assets under management to flat rates. This journey can feel overwhelming, but it’s essential to grasp these concepts to make informed decisions.
With insights from industry experts and current trends, this article will explore the importance of financial advisor fees. Together, we can navigate the complexities of cost evaluation, ensuring that your choices align with your family’s financial goals. Remember, we’re here for you, guiding you every step of the way as you make decisions that will positively impact your family’s future.
Define Financial Advisor Fees and Their Importance
Understanding the money managers fees associated with hiring a professional to manage your investments can feel overwhelming, but it’s crucial for your family’s financial health. These charges can vary widely and may include money managers fees, depending on the advisor’s compensation structure, which might consist of a percentage of assets under management (AUM), hourly rates, or fixed fees. For new households, understanding money managers fees is essential, as these costs can significantly impact long-term investment returns.
At Bright Advisers, we genuinely care about making wealth management accessible for families like yours. For instance, a typical fee of 1% on a $100,000 investment translates to an annual cost of $1,000. While this might seem manageable, the compounding effect over time can lead to substantial losses in potential growth. According to the 2024 State of Financial Planning and Fees study, average money managers fees include:
- A fixed-percentage charge of 1.05%
- An annual retainer of $4,484
- An hourly rate of $268
Additionally, the money managers fees charged by fee-only consultants average approximately 1 percent of the total assets they oversee. This information serves as a helpful benchmark for families assessing the expenses related to hiring a financial consultant, empowering you to make informed choices based on your unique financial situation.
Moreover, understanding these fee structures, particularly money managers fees, allows you to ask important questions when selecting an advisor, ensuring you are fully aware of all potential costs. Imagine if you could confidently navigate these decisions, knowing you have the right support. As John Schmidt, former Retirement and Investing Editor, wisely noted, “Whatever the explanation, one thing is clear: Investment costs should be kept to a minimum.” This insight highlights the importance of minimizing investment costs to enhance your family’s long-term gains.
By recognizing the various types of charges and their implications, you can take that vital first step toward effective financial planning. Together, we can ensure a more secure economic future for your family.

Explore Common Fee Structures for Financial Advisors
Navigating the world of financial planning can feel overwhelming, especially for young families. Understanding the different fee structures, such as money managers fees, that financial advisors use is crucial in making informed decisions that align with your family’s financial goals.
-
Percentage of Assets Under Management (AUM) is the most common model. Here, advisors charge a fee based on the total assets they manage, typically ranging from 0.25% to 2% each year. This structure aligns your advisor’s incentives with your investment growth, but it’s essential to assess whether the money managers fees reflect the services provided. Remember, transaction costs can vary based on the platform or consultant, impacting your overall expenses.
-
For families with straightforward financial needs, Flat Fees can be a great option. These fees usually range from $1,000 to $10,000, depending on the complexity of the services offered. This model offers clarity in budgeting, allowing you to know exactly what you will pay.
-
If you’re looking for specific advice without ongoing management, consider Hourly Rates. These typically vary from $100 to $400, enabling you to pay only for the time you need.
-
Retainer Fees involve regular payments, either monthly or annually, for ongoing access to financial advice and services. This can be particularly beneficial for families anticipating continuous assistance as their financial situations evolve.
-
Be cautious with Commission-Based Fees, where some advisors earn commissions on the products they sell. This model can create potential conflicts of interest, so ensure that the advisor’s recommendations are truly in your best interest.
Understanding the money managers fees structures is essential for determining which model best aligns with your financial objectives and budget. At Bright Advisers, we emphasize an open pricing model that reduces fund costs and money managers fees, making financial advice more accessible for families. Recent trends show a growing preference for transparent fee arrangements, with many families choosing flat fees or retainer models to avoid unexpected costs.
Moreover, Bright Advisers employs innovative investment strategies, such as smart beta and factor investing, to create hyper-personalized portfolios tailored to your family’s financial plans. The educational materials provided by financial consultants can empower families to make informed decisions about these fee structures, ultimately leading to better financial outcomes.
As highlighted in a recent case analysis, the availability of educational resources plays a vital role in helping families understand budget planning and investment strategies. Andrew Blake, an associate director, noted, “Open and candid discussions about the cost of services will build trust and strengthen relationships between clients and advisors while attracting prospective clients willing to pay for advice.”
As you and your family navigate your financial journey, choosing the right fee structure can significantly impact your ability to achieve long-term financial stability. Together, we can ensure that the value of the services you receive justifies the cost of advisory fees. We’re here for you, ready to support you every step of the way.
Determine the Right Fee Structure for Your Financial Needs
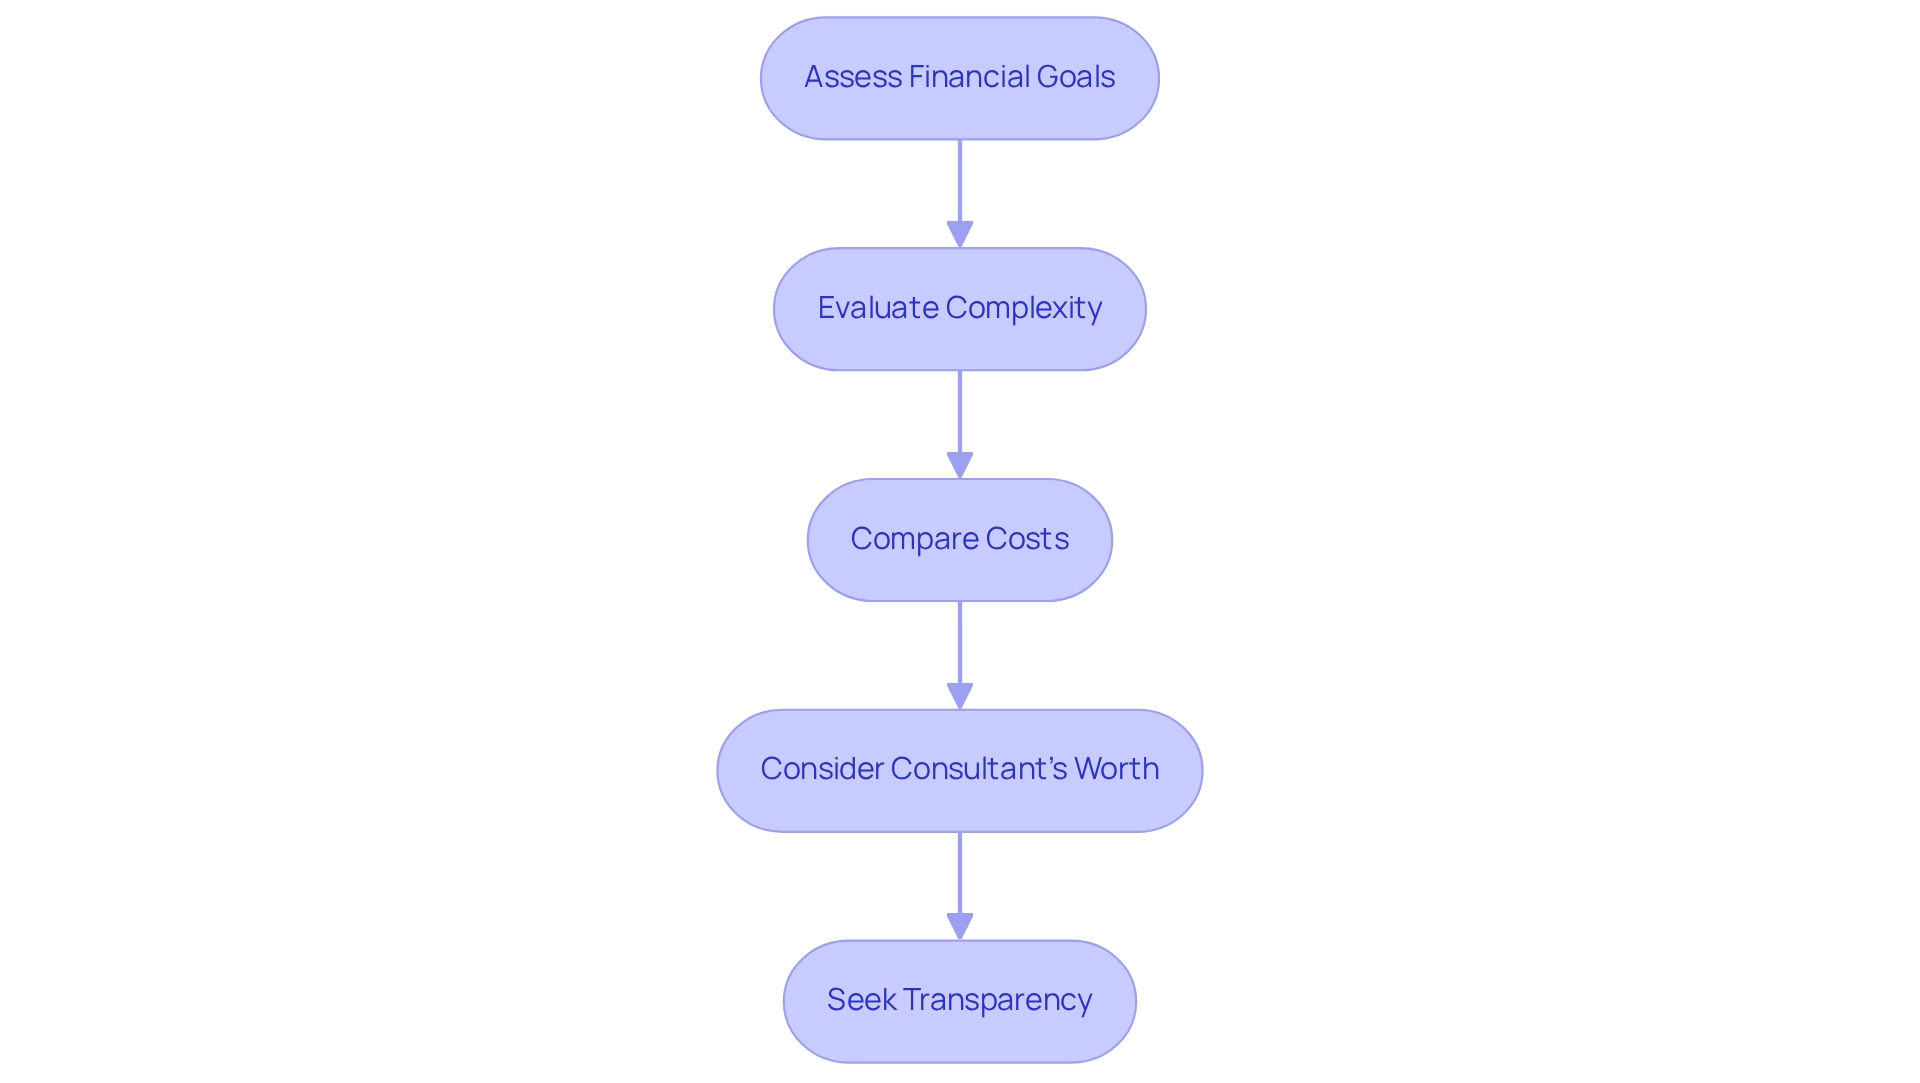
To determine the right fee structure for your financial needs, including money managers fees, let’s take a thoughtful approach together:
- Assess Your Financial Goals: Take a moment to clearly identify your short-term and long-term objectives. Are you saving for a home, planning for retirement, or funding your children’s education? Understanding these goals will help you choose an advisor who aligns with your vision.
- Evaluate Your Complexity: Think about the intricacies of your financial situation. If your finances are straightforward, a flat fee or hourly rate may work well. However, if you have multiple income streams, investments, or estate planning needs, a percentage-based model might be more appropriate. It’s important to remember that while a flat fee offers predictability, it can lead to challenges, such as higher costs for clients with smaller portfolios, potentially discouraging them from seeking advice.
- Compare Costs: Take the time to analyze the total costs associated with each fee structure, including money managers fees, based on your anticipated investment amount. For instance, investing $200,000 with a 1% assets under management (AUM) fee would incur an annual cost of $2,000, while a flat fee of $3,000 might be more economical depending on the services offered. Additionally, commission charges on items sold by investment consultants can vary from 3% to 6%, which is essential to consider when evaluating potential money managers fees.
- Consider the Consultant’s Worth: Reflect on the knowledge and significance the consultant brings to your financial planning. An increased charge might be justified if the consultant provides extensive services that align with your financial objectives. At Bright Advisers, we focus on providing tailored wealth management solutions that empower young families, ensuring our services are designed to meet your unique needs.
- Seek Transparency: It’s vital to ensure that your advisor provides a clear outline of their money managers fees and any potential additional costs. Transparency is crucial for building trust and avoiding unexpected fees in the future. As you embark on your financial journey with Bright Advisers, our team will guide you through a transparent onboarding process, helping you understand our fee structures and the value we provide.
Getting Started with Bright Advisers: Once you decide to move forward, we’re here to assist you in creating secure login credentials on our platform, acknowledging the disclosures, and setting your default billing preferences. You will safely upload any pertinent financial and tax documents to our portal, collaborate with your advisor to finalize your budget and cash flow forecasts, and create a precise balance sheet.
By following these steps, young families can make informed choices about the fee structures that best meet their financial needs, ultimately leading to a more stable economic future. Join our waitlist today to begin your journey with Bright Advisers!
Assess Total Costs and Hidden Fees in Financial Advisory Services
When evaluating total costs in financial advisory services, families can take steps to ensure their financial well-being:
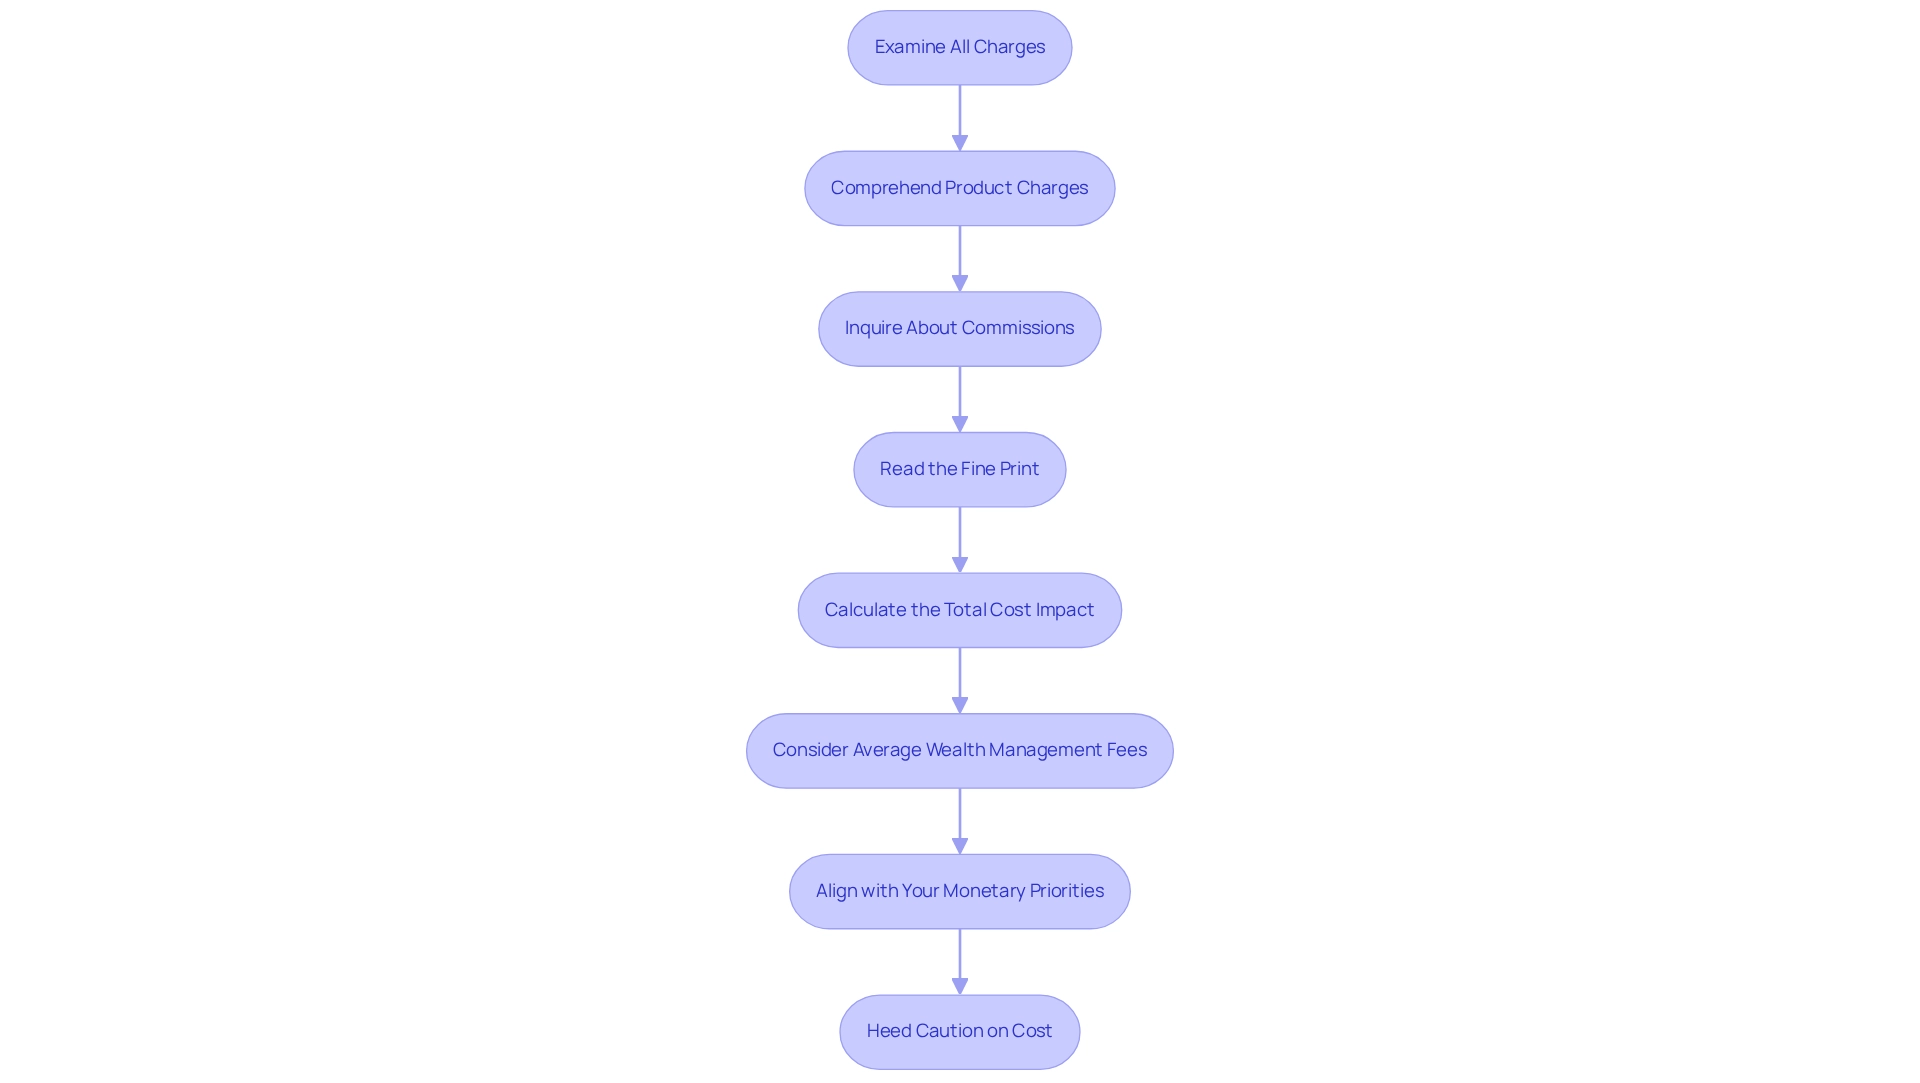
- Examine All Charges: Look beyond the primary cost structure to uncover additional expenses, including trading costs, fund expense ratios, and performance-based charges. These can significantly impact your overall expenses. At Bright Advisers, we prioritize minimal fund charges, ensuring that most of our models are designed to maintain low expenses for families. Additionally, some clients may hold legacy fee-bearing mutual funds and ETFs, which can also affect total costs.
- Comprehend Product Charges: It’s important to ask about costs linked to specific investment products suggested by your consultant. For instance, mutual funds typically have expense ratios that can vary from 0.1% to over 1%, impacting your investment’s growth potential.
- Inquire About Commissions: If your consultant operates on a commission basis, clarify how these commissions influence your total costs. Understanding this can help you gauge the true value of the advice you receive.
- Read the Fine Print: Take a moment to scrutinize the advisor’s contract and any disclosures to identify potential concealed charges. Many families overlook these details, which can lead to unexpected costs.
- Calculate the Total Cost Impact: Imagine using a fee calculator to project how various fee structures and hidden costs might affect your investment returns over time. For example, a 1% yearly charge on a $250,000 investment can lead to $2,500 in costs each year, accumulating substantially over decades and potentially costing you thousands in missed returns.
- Consider Average Wealth Management Fees: Wealth management fees typically range from 0.65% to 1.00% of assets under management, with additional charges for personalized services and platform expenses. Being aware of these ongoing costs is crucial for making informed decisions.
- Align with Your Monetary Priorities: Select a consultant whose services correspond with your fiscal objectives. This alignment is essential for achieving the value you expect from your advisory relationship.
- Heed Caution on Cost: As Andrea Coombes wisely observes, “if you have six figures to manage, working with the least expensive advisor you can find may mean you won’t receive the depth of guidance you need.” This highlights the importance of balancing cost with the quality of service.
By diligently assessing total costs and money managers fees, as well as hidden fees, families can make informed decisions that safeguard their financial futures. Remember, together, we can navigate this journey to ensure you receive the value you expect from your financial advisory services.
Conclusion
Understanding financial advisor fees is essential for families striving to optimize their financial planning. Imagine navigating the complexities of financial decisions while ensuring a bright future for your loved ones. This article has explored various fee structures, including:
- Percentage-based fees
- Flat fees
- Hourly rates
- Retainer fees
Highlighting how each model can impact overall costs and investment returns. It’s important to understand the significance of transparency in fee arrangements, enabling families to make informed decisions based on their unique financial situations.
By carefully assessing financial goals and evaluating the complexity of their needs, families can identify the right fee structure that aligns with their objectives. Furthermore, recognizing potential hidden costs and the total impact of fees on long-term investments is crucial for safeguarding financial futures. Together, we can navigate this journey towards financial security.
Ultimately, being proactive in understanding and managing financial advisor fees not only enhances the potential for better investment returns but also fosters a more secure financial foundation for families. Taking the time to evaluate these factors will lead to more informed decisions, empowering families to achieve their long-term financial aspirations. We’re here for you, ready to support you every step of the way.
Frequently Asked Questions
Why is it important to understand money managers fees when hiring a professional for investment management?
Understanding money managers fees is crucial for your family’s financial health as these costs can significantly impact long-term investment returns.
What are the different types of fees associated with money managers?
Money managers fees can vary widely and may include a percentage of assets under management (AUM), hourly rates, or fixed fees.
What is a typical fee structure for money managers?
A typical fee structure includes an average fixed-percentage charge of 1.05%, an annual retainer of $4,484, and an hourly rate of $268.
How does a 1% fee on an investment affect overall costs?
For example, a typical fee of 1% on a $100,000 investment translates to an annual cost of $1,000, which can compound over time, potentially leading to substantial losses in growth.
What should families consider when assessing the expenses of hiring a financial consultant?
Families should consider the average money managers fees, which typically average around 1 percent of the total assets managed, as a benchmark for evaluating costs.
How can understanding fee structures help in selecting a financial advisor?
Knowing the various fee structures allows families to ask important questions and ensures they are fully aware of all potential costs associated with hiring an advisor.
What is a key takeaway regarding investment costs?
Minimizing investment costs is essential for enhancing long-term gains, as highlighted by financial experts.
List of Sources
- Define Financial Advisor Fees and Their Importance
- How Much Does a Financial Advisor Cost? (2025) (https://talo.com/costs/financial-advisor-cost)
- How Much Does a Financial Advisor Cost in 2025? – NerdWallet (https://nerdwallet.com/article/investing/how-much-does-a-financial-advisor-cost)
- Small Fees Have A Big Impact On Your Investments (https://forbes.com/advisor/investing/impact-of-investment-fees)
- Explore Common Fee Structures for Financial Advisors
- How Much Do Financial Advisors Charge? Your Updated Guide for 2025 (https://moneylogue.com/blog/how-much-do-financial-advisors-charge-your-updated-guide-for-2025)
- How Much Does a Financial Advisor Cost? (https://smartasset.com/financial-advisor/financial-advisor-cost)
- How Much Does a Financial Advisor Cost in 2025? – NerdWallet (https://nerdwallet.com/article/investing/how-much-does-a-financial-advisor-cost)
- What is an appropriate fee for a financial advisor? (https://360financial.net/post/what-is-appropriate-fee-for-financial-advisor)
- Cerulli Associates | More Than 72% of Financial Advisors Are… (https://cerulli.com/press-releases/more-than-72-of-financial-advisors-are-compensated-by-fee-based-models)
- Determine the Right Fee Structure for Your Financial Needs
- Financial Advisor Cost | Fee Structures & Average Cost Backed by Data (https://financestrategists.com/financial-advisor/advisor-cost)
- Financial Advisor Fee Structures: Comparing Flat Fee and AUM (https://aldeninvestmentgroup.com/blog/financial-advisor-fee-structures)
- What is the cost of a financial advisor? — Sales Coaching and Marketing Agency for wealth managers (https://selectadvisorsinstitute.com/investor/financial-advisor-compensation-fee)
- Assess Total Costs and Hidden Fees in Financial Advisory Services
- What is an appropriate fee for a financial advisor? (https://360financial.net/post/what-is-appropriate-fee-for-financial-advisor)
- How Much Do Financial Advisors Charge? Your Updated Guide for 2025 (https://moneylogue.com/blog/how-much-do-financial-advisors-charge-your-updated-guide-for-2025)
- How Much Does a Financial Advisor Cost? (2025) (https://talo.com/costs/financial-advisor-cost)
- How Much Does a Financial Advisor Cost in 2025? – NerdWallet (https://nerdwallet.com/article/investing/how-much-does-a-financial-advisor-cost)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading