

Key Highlights
- Non-Qualified Stock Options (NSOs) allow employees to buy company shares at a set price, but their tax implications differ from Incentive Stock Options (ISOs).
- The difference between the purchase price and market value of NSOs is taxed as regular income, impacting financial planning for families.
- Families should be aware of the two-step taxation process: regular income tax upon exercising NSOs and capital gains tax upon selling shares.
- In California, high-income earners may face income tax rates up to 13.3%, making tax planning crucial for families managing NSOs.
- Timing the exercise of NSOs can optimise tax outcomes; exercising in a lower-income year can reduce tax liabilities.
- Cashless transactions can help families manage tax obligations without financial strain by selling enough shares to cover taxes.
- Families should monitor expiration dates of NSOs, as they typically expire after 10 years or within 90 days post-termination.
- Consulting with a fiduciary advisor like Bright Advisers can provide personalised strategies for navigating NSO complexities and optimising financial outcomes.
Introduction
Imagine trying to secure your child’s future while navigating the confusing world of Non-Qualified Stock Options (NSOs). As you work hard to build a secure future for your family, the complexities of NSO taxation can feel overwhelming. You’re not alone in this journey. Understanding these tax implications is essential for young parents like you, striving to create opportunities for your children’s education and well-being. This guide will walk you through the intricacies of NSOs, sharing insights and strategies to empower your family in making informed decisions that align with your dreams for the future.
Define Non-Qualified Stock Options (NSOs)
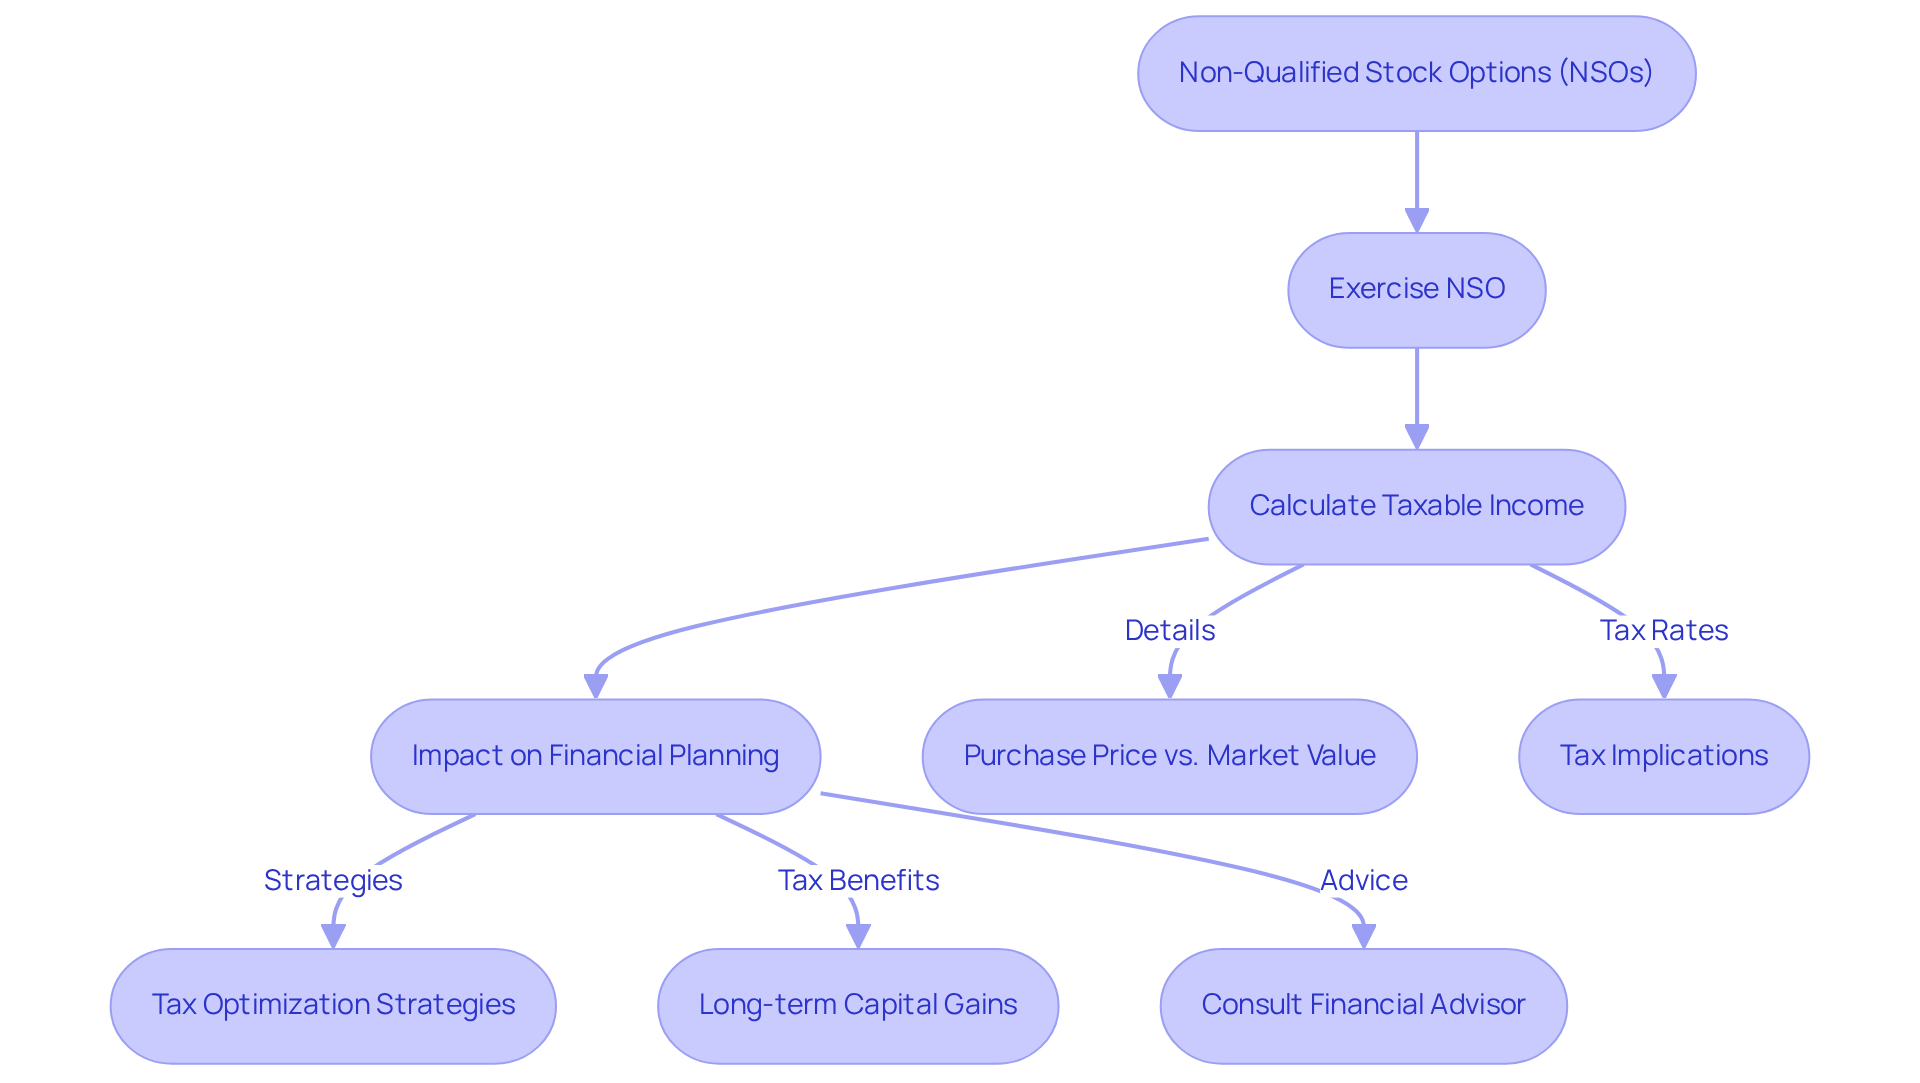
Imagine facing unexpected tax burdens just when you thought you were making progress in your financial journey. Non-Qualified Stock Options (NSOs) are a type of employee stock option that gives you the right to buy company shares at a set price, known as the purchase price. Unlike Incentive Stock Options (ISOs), the nso tax implications for NSOs do not provide the same favorable tax treatment under the Internal Revenue Code. When you use non-qualified stock options, the nso tax implications indicate that the difference between what you pay for the shares and their market value is taxed as regular income. For example, if you hold an NSO with an exercise price of $3 and the stock’s fair market value is $35 at the time you exercise it, you’ll owe taxes on the $32 difference. This tax can really impact your financial planning, so it’s important for young parents to grasp the nso tax implications on their wealth management and overall financial health.
Working with Bright Advisers means you’ll have support in navigating tax planning and strategies that can really boost your family’s financial health. Families like Jay & Emma and Emily & Mark have turned to Bright Advisers to help them understand the complexities of financial planning, ensuring they can achieve their goals while maintaining a work-life balance. By incorporating tax optimization into their financial plans, these families are enhancing their financial well-being and securing their children’s educational futures. Bright Advisers is dedicated to empowering families through personalized planning and tax strategies, helping you make informed decisions that align with your long-term aspirations. With the right guidance, you can turn potential pitfalls into stepping stones for your family’s future.
Explore NSO Taxation at Exercise and Sale
Navigating the world of Non-Qualified Stock Options can feel overwhelming, especially when it comes to understanding the tax implications that come with them. When you use Non-Qualified Stock Options, you’ll face regular income tax based on the difference between what you pay and the stock’s current market value. For example, if you exercise your NSOs when the stock is priced at $50 and your exercise cost is $20, you’ll be taxed on the $30 profit as regular income. Plus, your employer will need to withhold payroll taxes, including Social Security and Medicare taxes, from this amount.
When you decide to sell your shares, any increase in value will be subject to capital gains tax, which is something to keep in mind. If you hold onto those shares for over a year before selling, you might qualify for long-term capital gains rates, which are generally lower than ordinary income tax rates. This two-step taxation process is especially important for young parents, as it can greatly affect their economic strategies and tax planning.
In California, if you’re a high-income earner, you might face an ordinary income tax rate of up to 13.3%, so it’s really important to plan ahead. Case studies illustrate the implications of NSO taxation: for instance, Amanda, an employee at a California startup, faced challenges understanding her tax liabilities when exercising her ISOs. By utilizing equity planning tools, she was able to model different scenarios, highlighting the importance of strategic planning in managing tax obligations.
As of 2026, updates to NSO taxation highlight the necessity for families to seek guidance from advisors to navigate California’s complex tax landscape effectively. Without a solid plan, families could be caught off guard by tax bills that might strain their finances. Understanding these tax obligations is crucial for optimizing financial outcomes and ensuring that families can manage their wealth across generations. By seeking guidance and planning ahead, families can ensure they’re making the most of their financial opportunities while minimizing tax burdens.
Decide When to Exercise NSOs for Optimal Tax Outcomes
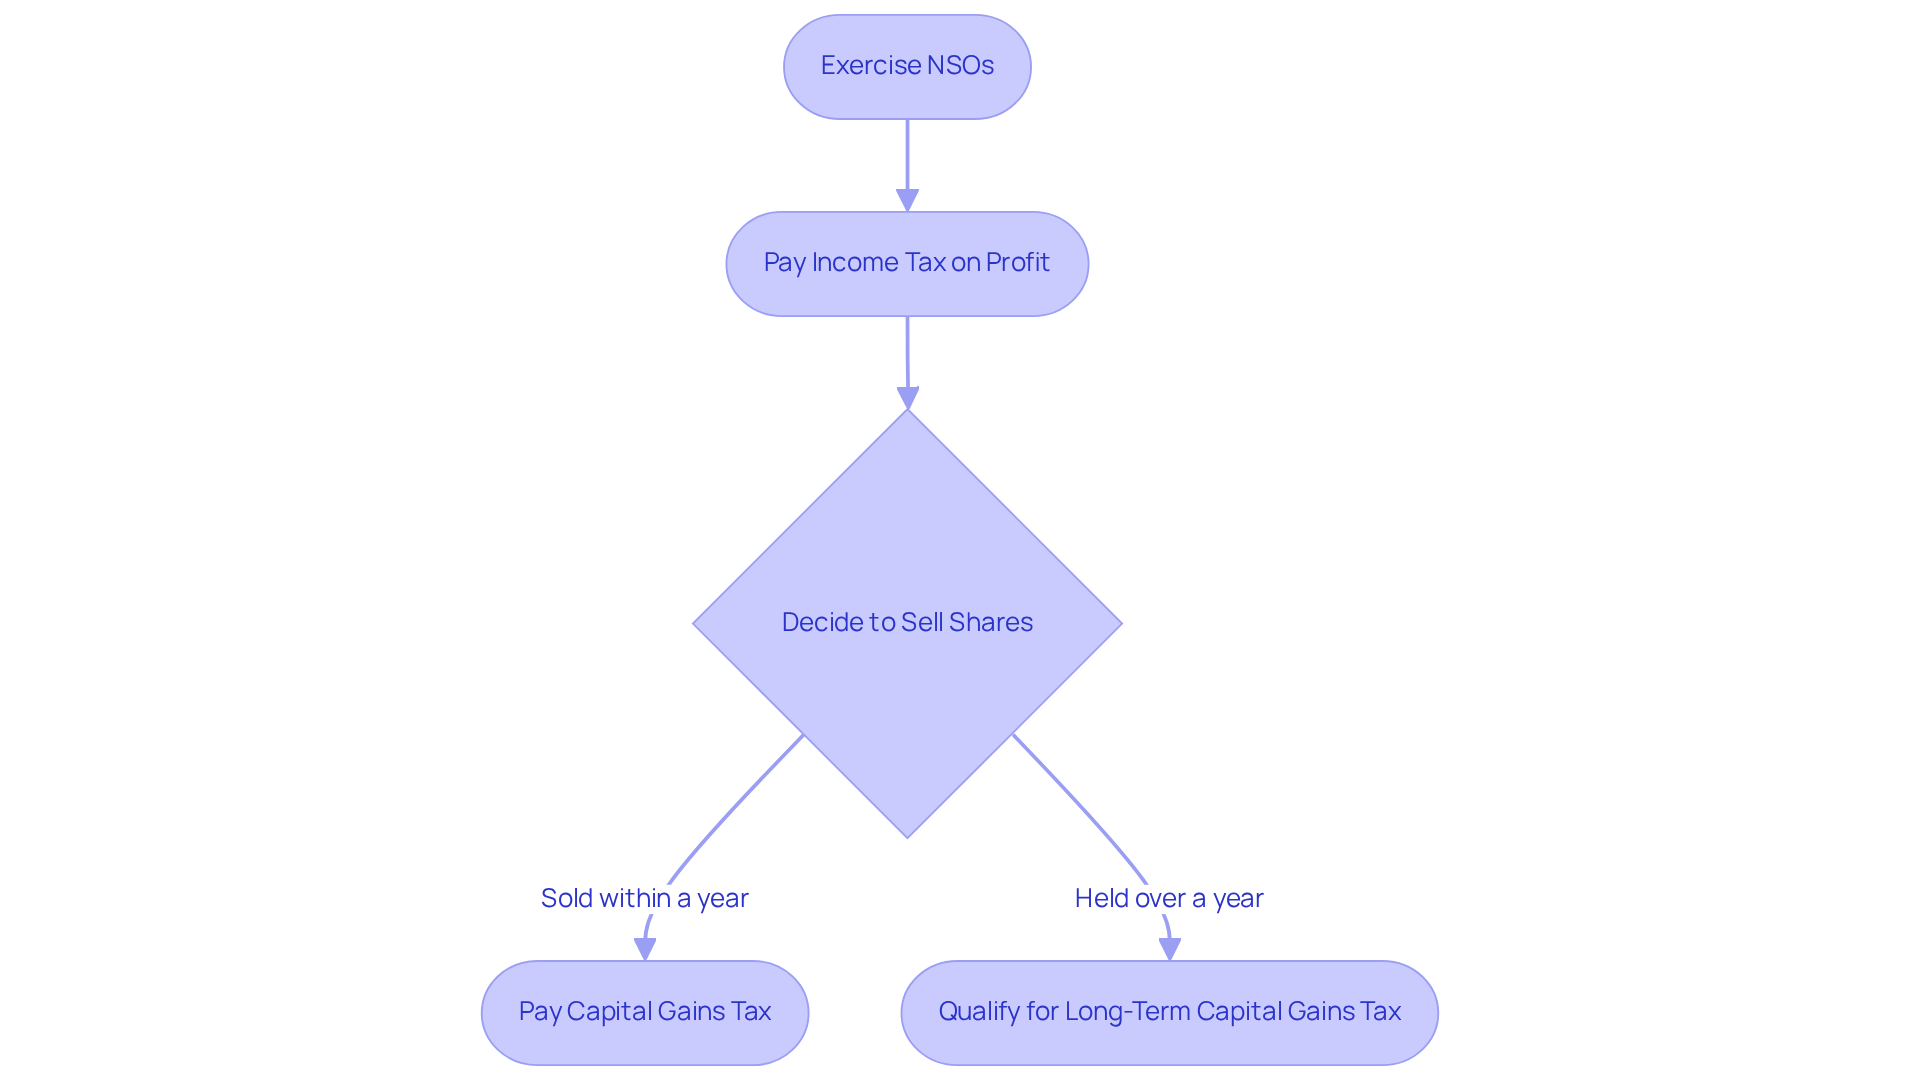
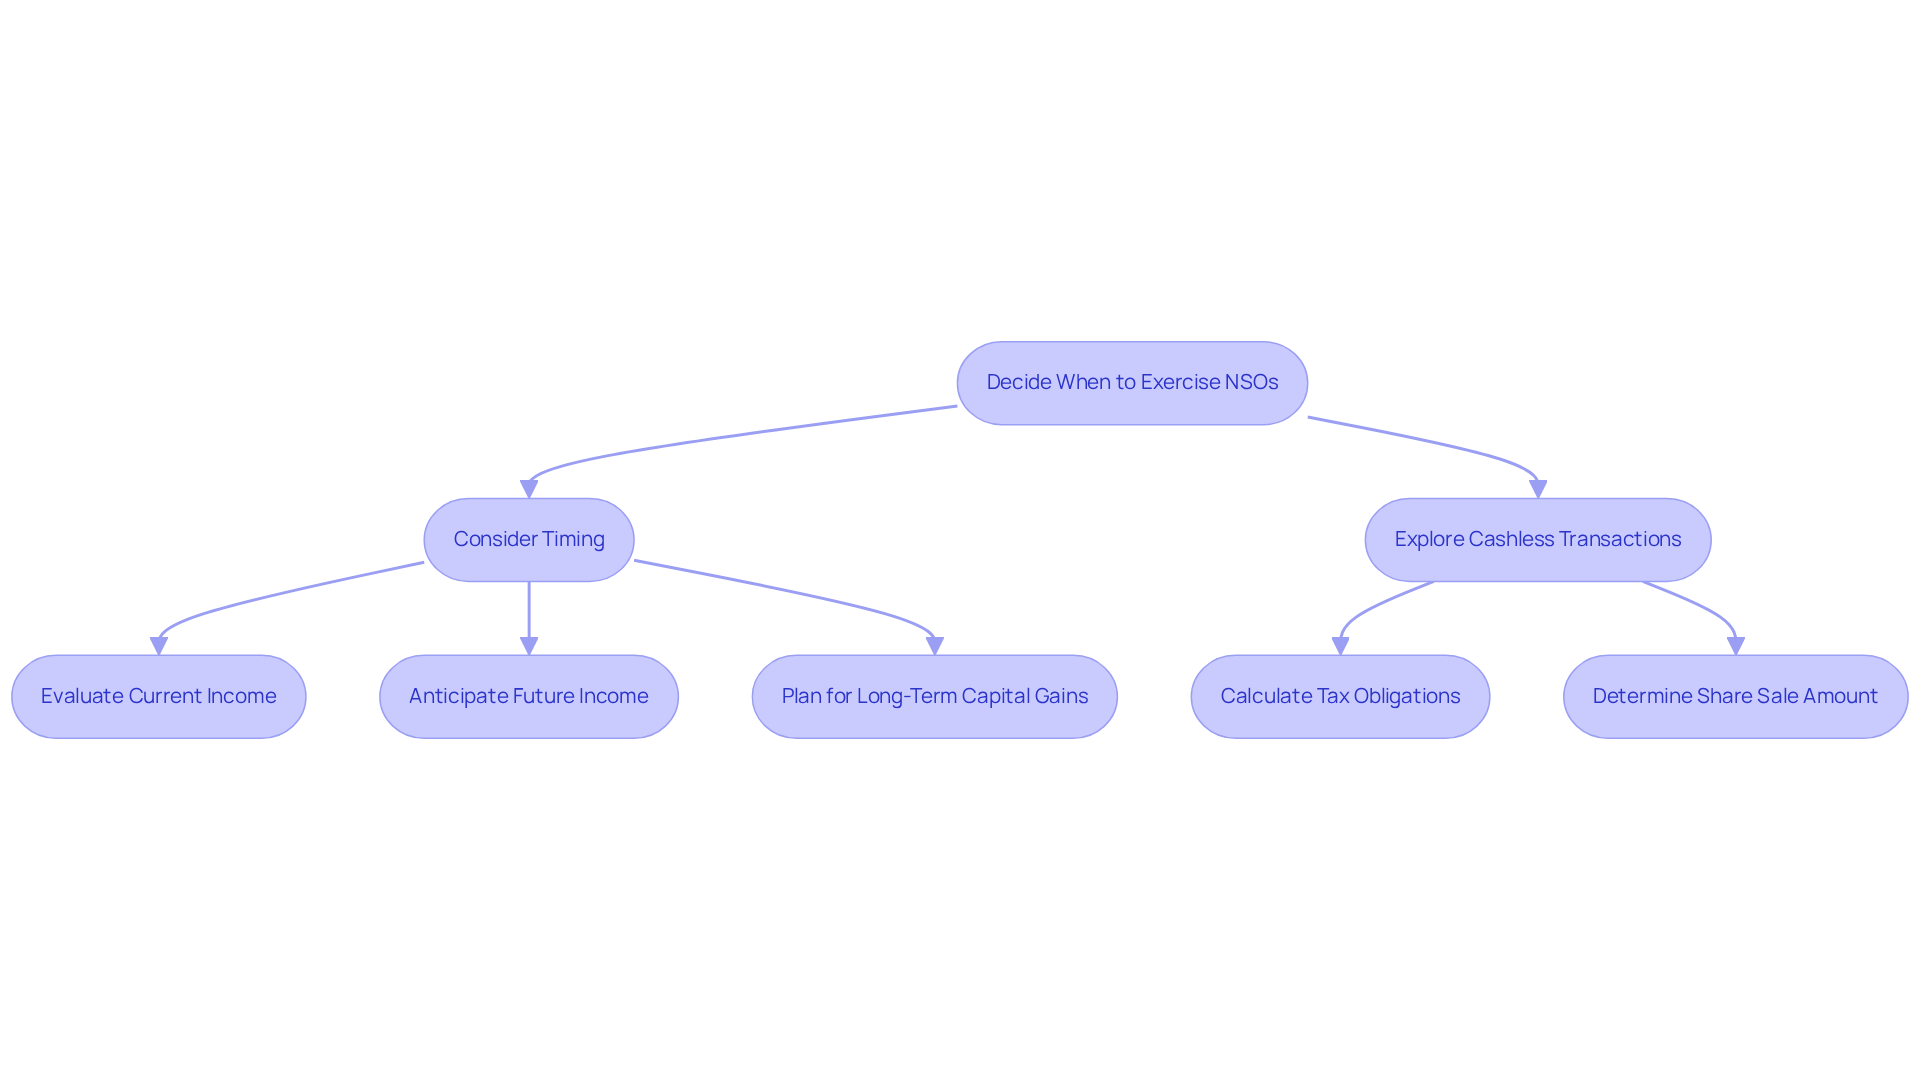
Imagine facing a tax bill that could have been avoided with a little planning – this is a reality many families encounter. Timing your NSO activity can significantly affect the nso tax implications of your tax liability. Think about timing your options for a year when your income is lower – this can really help with your tax situation. For instance, if you expect a big income increase next year, exercising your NSOs beforehand might be a smart move. Plus, holding onto those shares for at least a year after exercising can let you benefit from lower long-term capital gains tax rates when you sell.
Many families find that cashless transactions can be a lifesaver, allowing them to sell just enough shares to cover their tax obligations without feeling the pinch. A case study of Emily and Mark illustrates this point. By collaborating with Bright Advisers, they strategically scheduled their NSO activities and employed cashless options, which helped them avoid higher tax brackets and improved their overall financial situation. This ultimately granted them the freedom to decide whether or not to keep working.
It’s important to grasp the ins and outs of California’s tax rules, particularly the nso tax implications when exercising NSOs. The nso tax implications of exercising NSOs include state income tax on the difference between the strike price and the fair market value at exercise, which can be as high as 13.3%. You also need to calculate both your regular tax liability and the Alternative Minimum Tax (AMT) each year when filing your tax return. Therefore, careful planning and timing are essential to navigate these complexities effectively. By utilizing these strategies, young parents can make informed choices that align with their monetary goals and family needs, just as Emily and Mark did with the guidance of Bright Advisers. This personalized approach not only optimized their financial well-being but also empowered them to create a life that aligns with their personal and financial aspirations. With the right strategies in place, you can take control of your financial future and create a life that truly reflects your family’s values.
Answer Common Questions About NSOs and Taxes
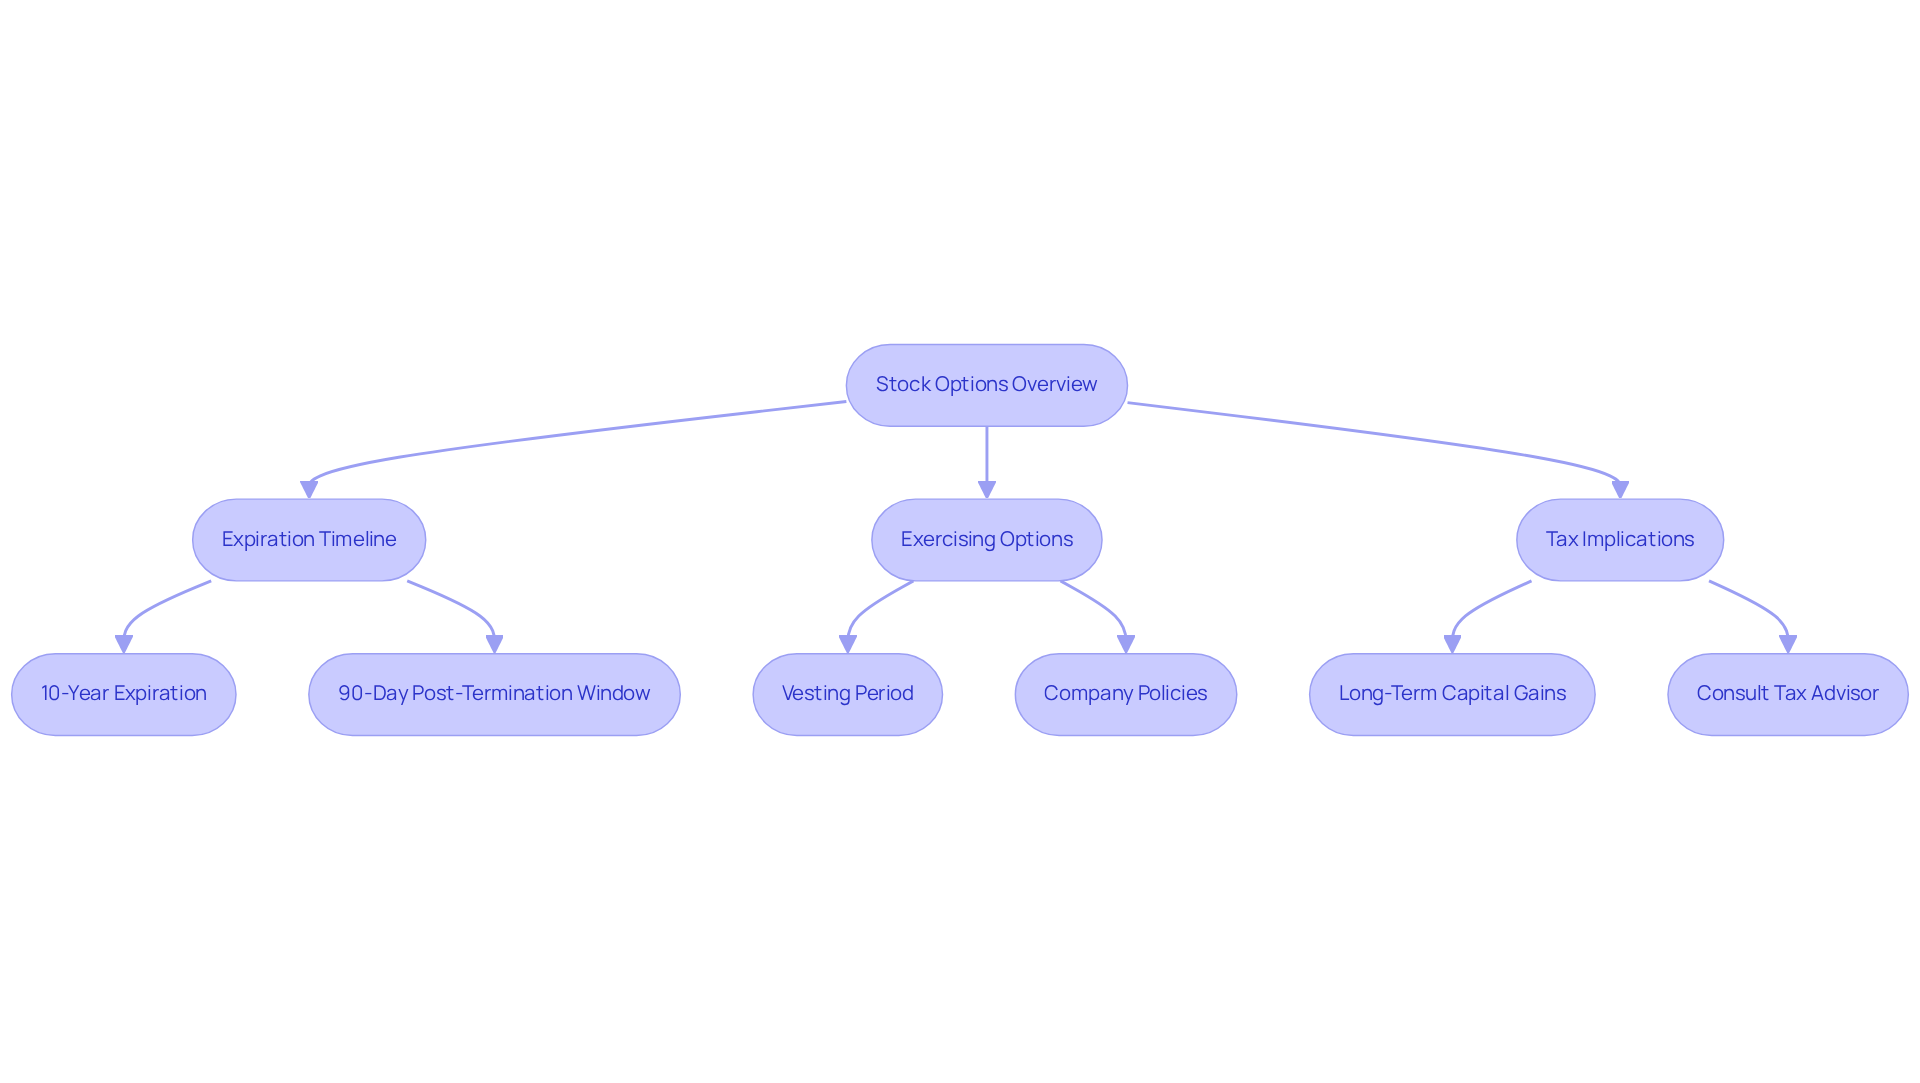
Imagine the disappointment of watching your hard-earned stock options expire without making the most of them. If you let your stock options slip away, they typically expire after a designated period, often 10 years from the grant date. It’s important to keep an eye on those expiration dates to avoid losing potential value, especially since many employees in California face a common post-termination action window of just 90 days.
You may be curious about when you can start using your stock options. Generally, you can exercise them once they have vested. However, your company’s policies might set specific windows for exercising options. It’s a good idea to review your company’s stock option plan to understand these timelines better.
What happens if you leave your job? Upon leaving, you usually have a limited timeframe – commonly 90 days – to exercise your stock options. Knowing your company’s policy regarding this situation is crucial to prevent losing your options, as unexercised stock options typically expire at the end of this post-termination window.
Think about exercising your options during a year when your income is lower; it could really help your family save on taxes. Holding shares for over a year can qualify you for long-term capital gains, and consulting with a tax advisor can provide personalized strategies. This proactive approach can help you navigate the complexities of NSOs while considering the NSO tax implications, enabling you to make informed decisions that align with your family’s financial goals.
Conclusion
Imagine feeling confident about your family’s financial future, even when faced with the complexities of Non-Qualified Stock Options (NSOs). Understanding NSO taxation can feel overwhelming for many families, especially when planning for the future. However, grasping how NSOs work and the associated tax responsibilities is crucial for securing your family’s financial well-being.
Throughout this guide, we’ve shared key insights about the taxation process at both the exercise and sale stages of NSOs. It’s important to understand the timing, capital gains, and the potential benefits of cashless transactions as effective strategies for minimizing tax burdens. Real-life examples, like those of families who have successfully navigated these challenges with the help of Bright Advisers, illustrate the value of personalized financial planning and proactive tax strategies.
Managing NSOs isn’t just about the numbers; it’s about helping families make choices that reflect their dreams and values. By seeking guidance and planning ahead, families can turn these challenges into stepping stones toward financial security, ensuring a brighter future for their children. Engaging with a trusted advisor like Bright Advisers can provide the necessary support to navigate these complexities, allowing families to focus on what truly matters – creating a fulfilling life for themselves and their loved ones. By taking proactive steps today, you can create a legacy of financial security for your children that lasts a lifetime.
Frequently Asked Questions
What are Non-Qualified Stock Options (NSOs)?
Non-Qualified Stock Options (NSOs) are a type of employee stock option that allows you to buy company shares at a predetermined price, known as the purchase price.
How do NSOs differ from Incentive Stock Options (ISOs)?
Unlike Incentive Stock Options (ISOs), NSOs do not provide the same favorable tax treatment under the Internal Revenue Code, leading to different tax implications when exercised.
What are the tax implications of exercising NSOs?
When you exercise NSOs, the difference between the purchase price and the market value of the shares is taxed as regular income. For example, if the exercise price is $3 and the market value is $35, you will owe taxes on the $32 difference.
Why is it important for young parents to understand NSO tax implications?
Understanding NSO tax implications is crucial for young parents as it can significantly impact their financial planning and overall financial health.
How can Bright Advisers assist families with NSOs and tax planning?
Bright Advisers provides support in navigating tax planning and strategies, helping families understand the complexities of financial planning and optimize their tax situations to enhance their financial well-being.
Can you provide examples of families who have benefited from Bright Advisers?
Families like Jay & Emma and Emily & Mark have turned to Bright Advisers for assistance in financial planning, ensuring they achieve their goals while maintaining a work-life balance.
What is the mission of Bright Advisers?
Bright Advisers is dedicated to empowering families through personalized planning and tax strategies, helping them make informed decisions that align with their long-term aspirations.
List of Sources
- Define Non-Qualified Stock Options (NSOs)
- How to Maximize Your NSO Stock Options: Tax Strategies and Exercise Tips for Startup Employees — Secfi (https://secfi.com/learn/nso-non-qualified-stock-options-tax-treatment)
- Range – Making the Most of Your Non-Qualified Stock Options (NSOs) (https://range.com/blog/nsos)
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- How Are Non-Qualified Stock Options (NSOs) Taxed? (https://abovethecanopy.us/how-are-non-qualified-stock-options-nsos-taxed)
- Non-Qualified Stock Options (NSO): How NSOs Work (https://carta.com/learn/equity/stock-options/nso)
- Explore NSO Taxation at Exercise and Sale
- Stock Option Taxes in California: ISO, NSO, and RSU Tax Planning for Tech Workers (https://ietaxattorney.com/stock-option-taxes-in-california-iso-nso-and-rsu-tax-planning-for-tech-workers)
- California’s Long-term Capital Gains Tax (https://edelmanfinancialengines.com/education/tax/capital-gains-tax-california)
- How are stock options taxed in California? — Secfi (https://secfi.com/learn/how-are-stock-options-taxed-in-california)
- Non-Qualified Stock Options (NSO): How NSOs Work (https://carta.com/learn/equity/stock-options/nso)
- How are stock options taxed? (https://jpmorganworkplacesolutions.com/insights/how-are-stock-options-taxed)
- Decide When to Exercise NSOs for Optimal Tax Outcomes
- How are stock options taxed in California? — Secfi (https://secfi.com/learn/how-are-stock-options-taxed-in-california)
- Exercising Stock Options in California: 2026 Tax Guide (https://esofund.com/blog/exercising-stock-options-in-california)
- Nonqualified Stock Options and the Tax Impact of NSOs – NerdWallet (https://nerdwallet.com/investing/learn/nsos)
- California Income Tax and Equity Compensation (https://savantwealth.com/savant-views-news/article/california-income-tax-and-equity-compensation)
- Answer Common Questions About NSOs and Taxes
- Non-Qualified Stock Options (NSO): How NSOs Work (https://carta.com/learn/equity/stock-options/nso)
- Non-Qualified Stock Options (NSO) in Private Companies: Tax, QSBS & California | Nauma (https://nauma.ai/knowledge/nso-private-company)
- Post-Termination Exercise Window: Why It Sucks and What You Can Do About It – Compound Manual (https://manual.compoundplanning.com/chapters/post-termination-exercise-window-why-it-sucks-and-what-you-can-do-about-it)
- Exercising Stock Options in California: 2026 Tax Guide (https://esofund.com/blog/exercising-stock-options-in-california)
- Understanding 90-Day Exercise Windows – S | StartEngine Blog (https://startengine.com/blog/90-day-exercise-window)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading