

Overview
The article highlights the significance of pre-IPO Restricted Stock Units (RSUs) as a meaningful form of equity compensation for young families, presenting an opportunity for long-term wealth accumulation and financial stability. It’s crucial to grasp the nuances of vesting schedules, tax implications, and the strategic choices surrounding the decision to sell or hold RSUs. These factors can profoundly impact a family’s financial planning and investment strategy, shaping a brighter future for those we care about most.
Imagine if you could secure a more stable financial future for your loved ones. Understanding RSUs can be a powerful step in that direction. As you navigate this journey, remember that we’re here for you, guiding you through the complexities of wealth management with empathy and support. Together, we can explore how these financial tools can align with your family values and shared goals.
It’s important to understand that the decisions you make regarding RSUs can significantly influence your family’s financial landscape. By taking the time to learn about these elements, you can create a solid foundation for your family’s future. Embrace this opportunity to make informed decisions that resonate with your aspirations for your loved ones.
Key Highlights:
- Restricted Stock Units (RSUs) are a form of equity compensation that promises delivery of shares contingent on specific conditions.
- For young families, RSUs can enhance overall compensation, contributing to long-term wealth accumulation and financial stability.
- RSUs typically vest over a three- to four-year schedule, providing a steady income stream for financial goals like education or home purchases.
- RSUs are taxed as ordinary income upon vesting, necessitating careful tax planning to manage potential liabilities.
- Families should consider RSUs as part of a diversified investment portfolio to mitigate risks associated with employer stock concentration.
- Proactive collaboration with financial and tax advisors is crucial for effectively managing RSUs and aligning them with family financial goals.
- Decisions on whether to sell or hold RSUs should reflect financial goals, risk tolerance, and market conditions, with a balanced approach often being beneficial.
- Only 28% of S&P 500 companies would have resulted in greater wealth if RSUs were kept instead of sold and reinvested, suggesting selling may often be advantageous.
Introduction
Understanding the complexities of Restricted Stock Units (RSUs) is essential for young families striving to build a secure financial future. Imagine the possibilities that pre-IPO RSUs can offer—significant opportunities for wealth accumulation. However, it’s important to recognize that they come with their own set of challenges and intricacies that require careful navigation.
How can families effectively leverage these financial tools to not only meet immediate needs but also secure long-term prosperity? This guide delves into the essential aspects of pre-IPO RSUs, from their mechanics and tax implications to strategic management. Together, we can navigate this journey, ensuring that families are well-equipped to make informed decisions for their financial well-being.
Define Restricted Stock Units (RSUs) and Their Importance for Young Families
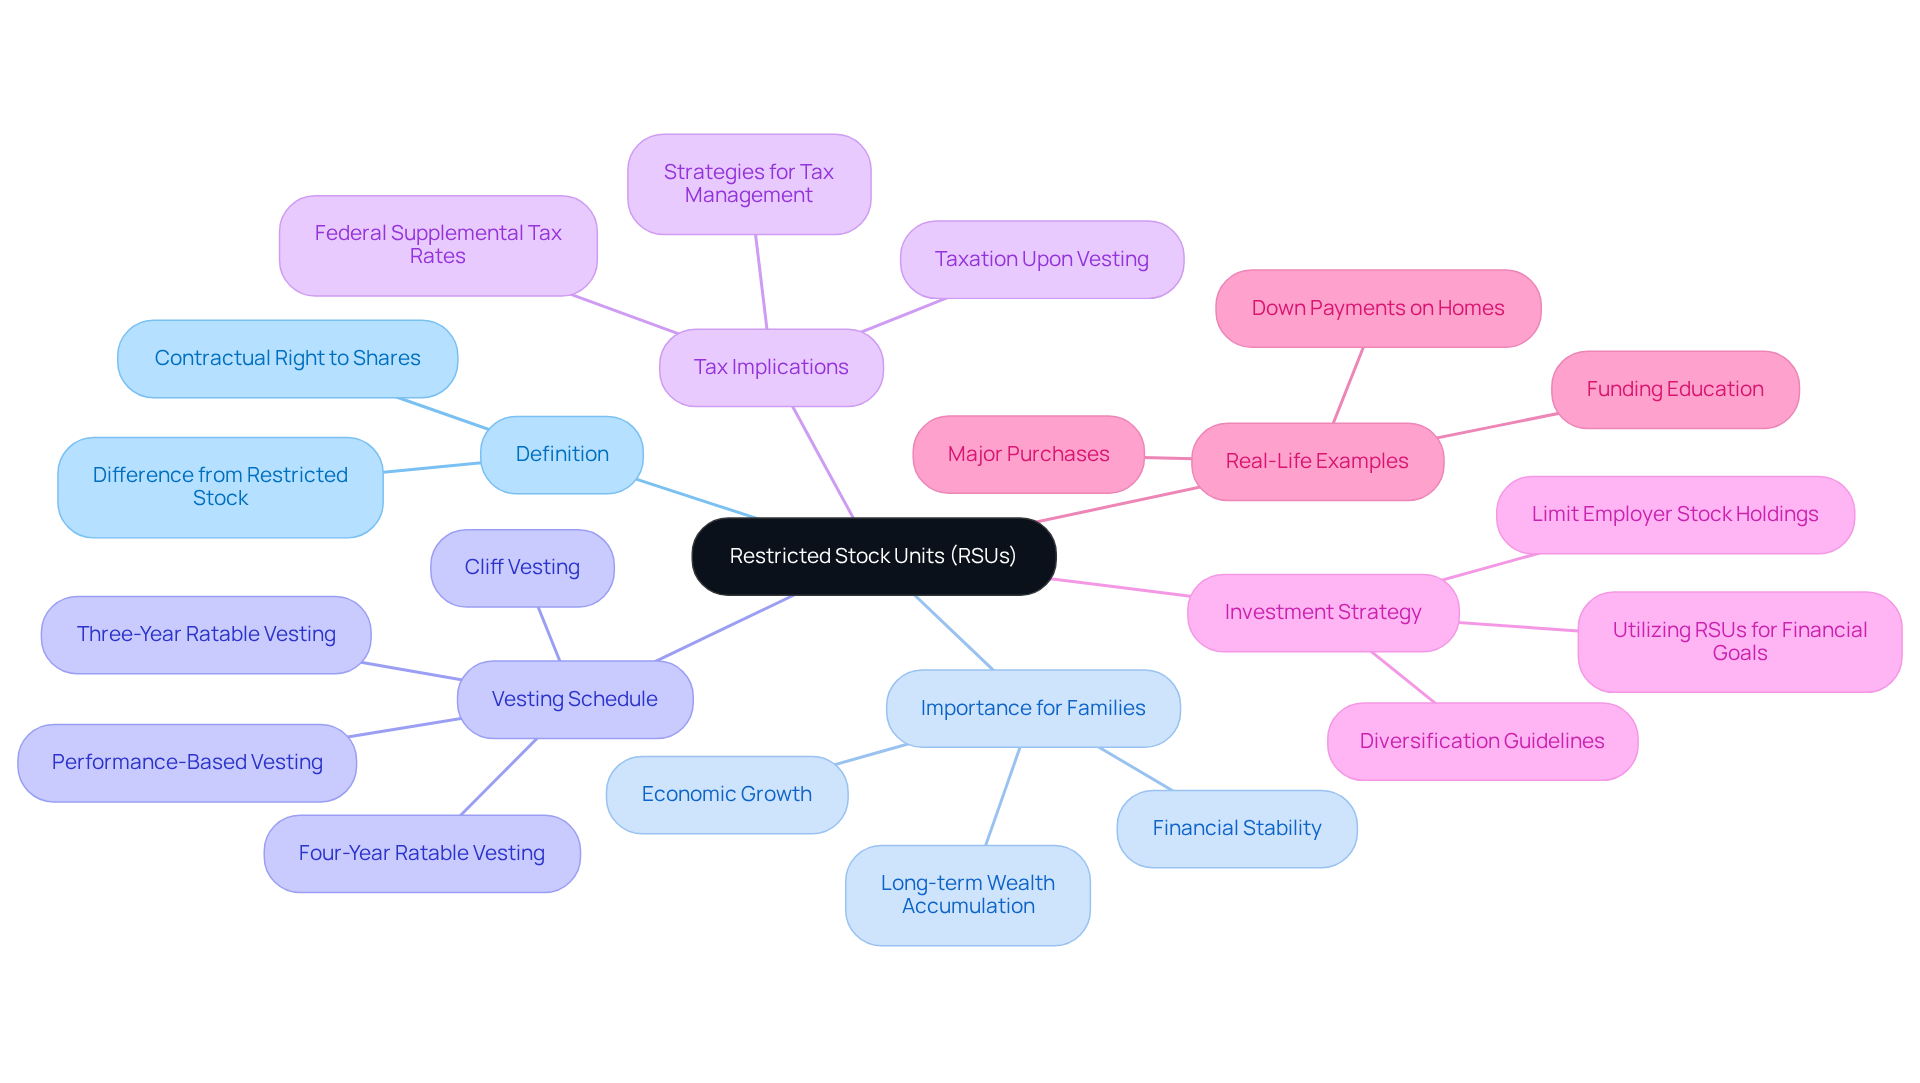
Restricted Stock Units (RSUs) are a meaningful form of equity compensation, often categorized as pre-IPO RSUs, that employers offer to employees. They represent a promise to deliver shares of stock at a later date, contingent on meeting specific conditions. For young households, RSUs can play a vital role in overall compensation, offering significant potential for economic growth and stability. Understanding the principles of pre-IPO RSUs is essential, as they can significantly contribute to long-term wealth accumulation, which is crucial for families striving to secure their children’s financial futures.
Typically, RSUs vest over a predetermined schedule, often structured as a three- or four-year ratable vesting plan. This allows employees to receive shares incrementally, creating a steady flow of income. Households can utilize this income for various financial goals, such as saving for education or purchasing a home. Furthermore, it’s important to note that RSUs are taxed as compensation upon vesting. Therefore, families should strategize accordingly to manage their tax obligations effectively.
The benefits of pre-IPO RSUs extend beyond immediate financial rewards. They can serve as a strategic component of a diversified investment portfolio, helping families reduce the risks associated with overconcentration in employer stock. A common guideline suggests limiting employer stock holdings to 10-30% of a portfolio, promoting a balanced investment approach.
Real-life examples illustrate how young households have successfully integrated RSUs into their financial plans. For instance, families have used RSU proceeds to fund significant life events, such as down payments on homes or education savings for their children. By understanding the nuances of pre-IPO RSUs and incorporating them into a broader financial strategy, families can enhance their economic resilience and achieve long-term wealth growth.
Experts emphasize the importance of viewing RSUs as part of a comprehensive wealth strategy rather than relying solely on them for asset accumulation. Proactive collaboration with financial advisors can support families in navigating the complexities of RSUs, ensuring they align with their overall financial goals and values. Ultimately, by effectively utilizing RSUs, young families can pave the way for a brighter financial future for themselves and their children.
Explain How RSUs Work: Vesting Schedules and Conditions
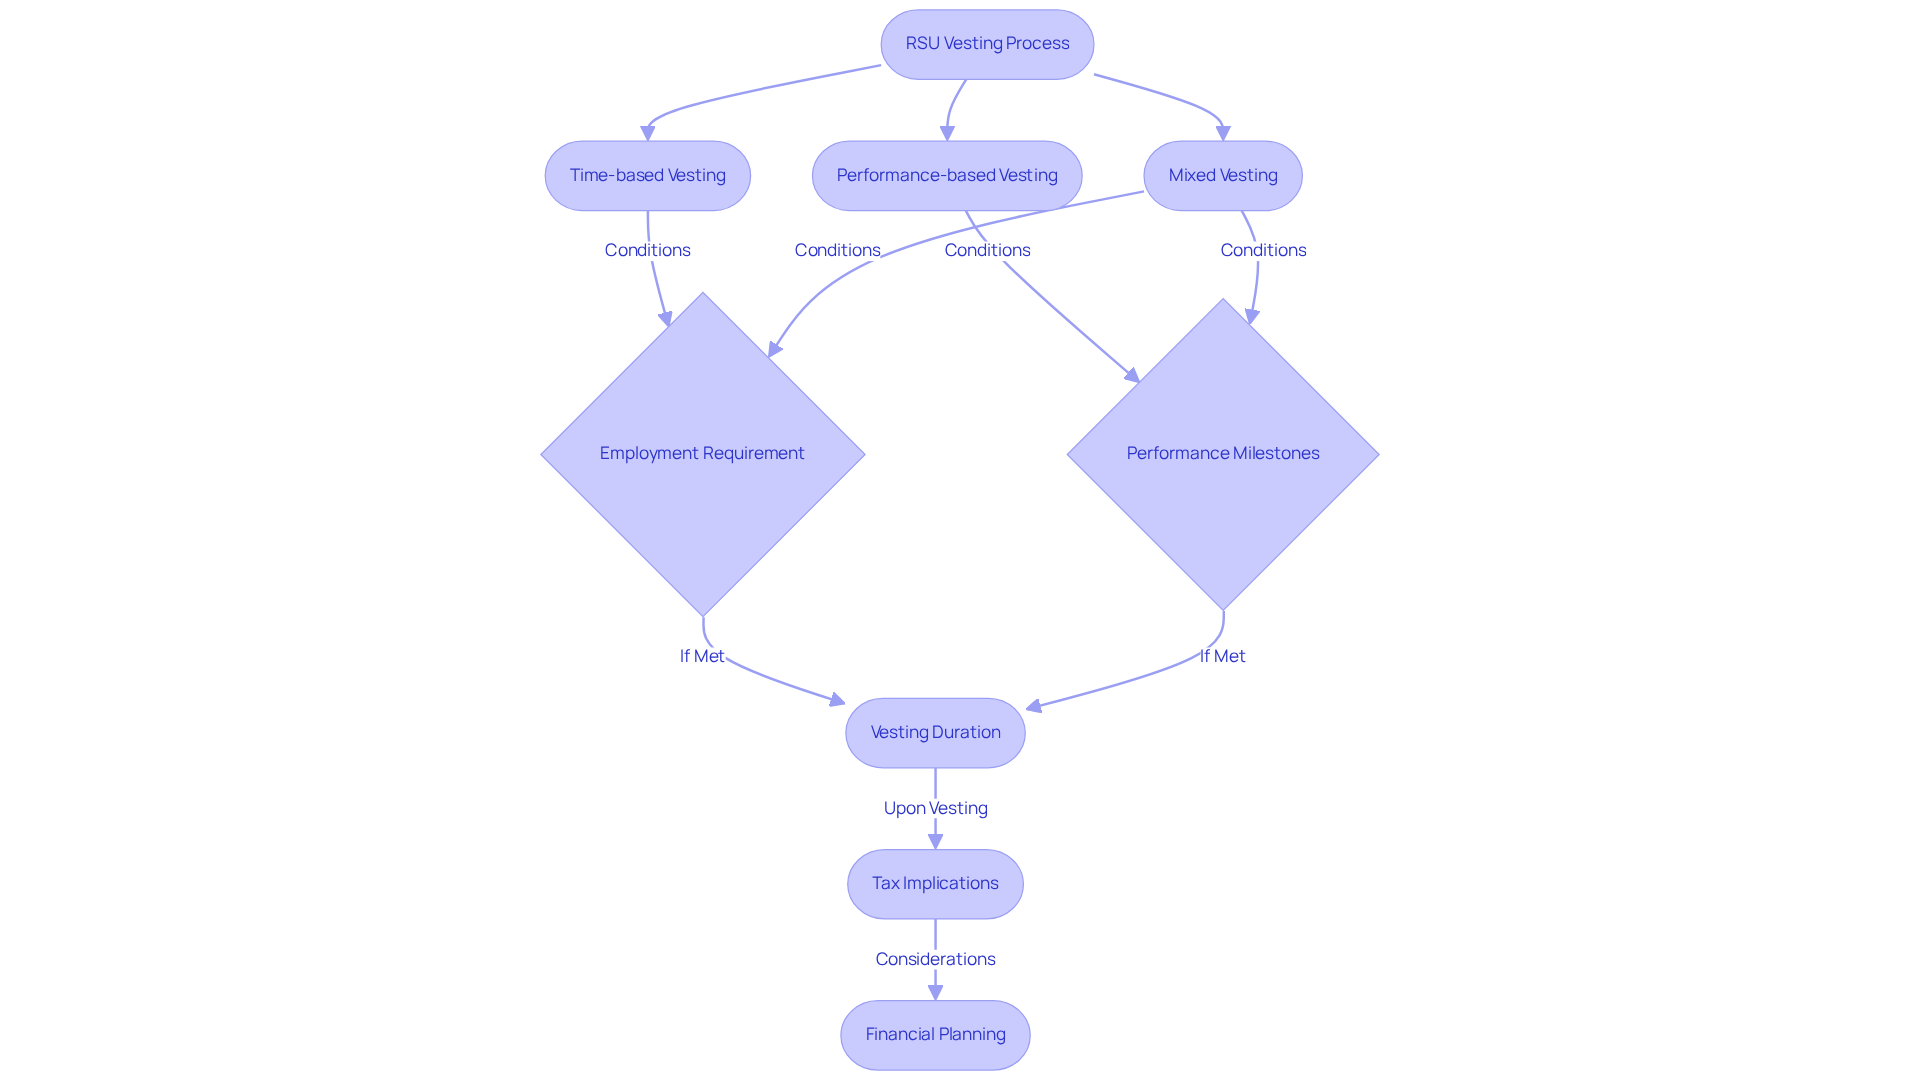
Restricted Stock Units (RSUs), including pre IPO rsus, often come with a vesting schedule that outlines the timeline over which you earn the right to receive shares. These schedules can be time-based, performance-based, or a mix of both. Imagine a typical arrangement where you receive 25% of your RSUs each year over a four-year period. Understanding these vesting schedules is essential for young families, as they directly influence the availability of pre ipo rsus and how this aligns with your broader financial goals.
It’s also crucial to consider any conditions that may affect vesting, such as the need to remain employed with the company or to meet specific performance milestones. Generally, the vesting duration for RSUs in the United States is around four years. This timeline can significantly impact your budgeting, especially if you anticipate major life changes like purchasing a home or funding education.
Navigating RSU vesting requirements can be illustrated through stories of families that have thoughtfully aligned their financial planning with these timelines. For instance, families who prepare for the tax implications of RSUs upon vesting often manage their cash flow and investment strategies more effectively. Experts emphasize that understanding these vesting conditions related to pre ipo rsus not only aids in financial planning but also empowers families to make informed decisions about when to sell shares, maximizing their financial benefits.
Together, we can navigate this journey, ensuring that your family’s financial future is secure and aligned with your values.
Discuss Tax Implications of RSUs: What Young Parents Need to Know
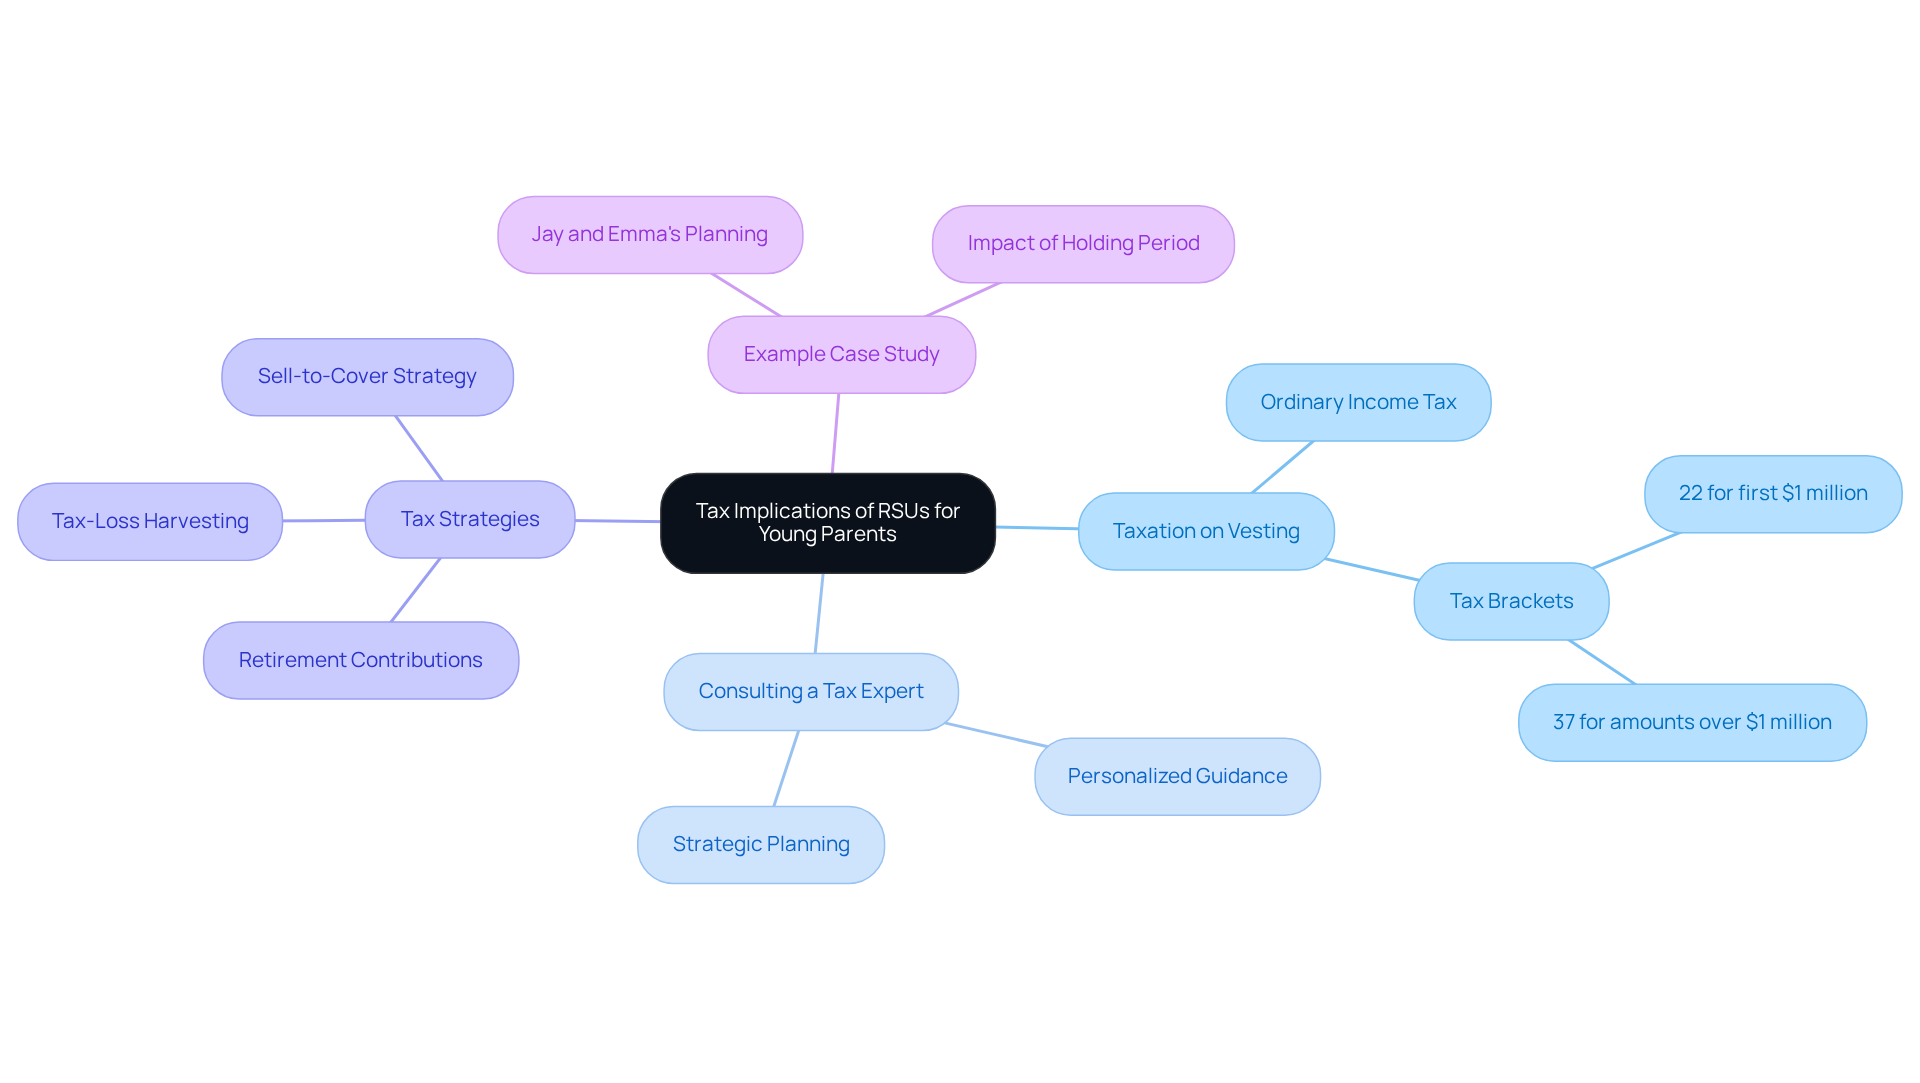
Navigating the world of Restricted Stock Units (RSUs) can feel overwhelming, especially for young families. When RSUs vest, they are taxed as ordinary income, with the taxable amount based on the fair market value of the shares at that moment. Imagine if 1,000 RSUs vest at $50 per share—this would mean a taxable income of $50,000, potentially pushing you into a higher tax bracket. It’s a significant obligation that requires thoughtful planning.
To ease this burden, consulting a tax expert can be a game-changer. Personalized guidance tailored to your unique financial situation can make all the difference. Remember, employers are required to withhold 22% for federal income taxes on the first $1 million of additional income, and rates can rise to 37% for amounts beyond that. Strategies like contributing to retirement accounts can help reduce your taxable income, while tax-loss harvesting offers another avenue for minimizing tax liabilities. It’s important to understand the intricacies of RSU taxation, particularly the possibility of additional taxes if your effective tax rate exceeds 22%.
Proactive tax planning not only helps families navigate the complexities of RSU taxation but also maximizes the benefits of these equity awards. Take, for example, Jay and Emma, who worked with Bright Advisers to implement effective strategies for their RSU tax implications while also preparing for their children’s education and retirement. By holding restricted stock units for over a year, families might enjoy reduced long-term capital gains tax rates, making timing of sales a crucial consideration.
By partnering with a tax consultant, families can make informed decisions, ensuring they are well-prepared for the financial implications of stock units vesting. This approach reflects Bright Advisers’ commitment to empowering young families through tailored financial planning and investment strategies, ultimately nurturing a sense of financial security and freedom. Remember, together, we can navigate this journey and achieve your family’s financial goals.
Offer Strategies for Managing RSUs: Selling vs. Holding
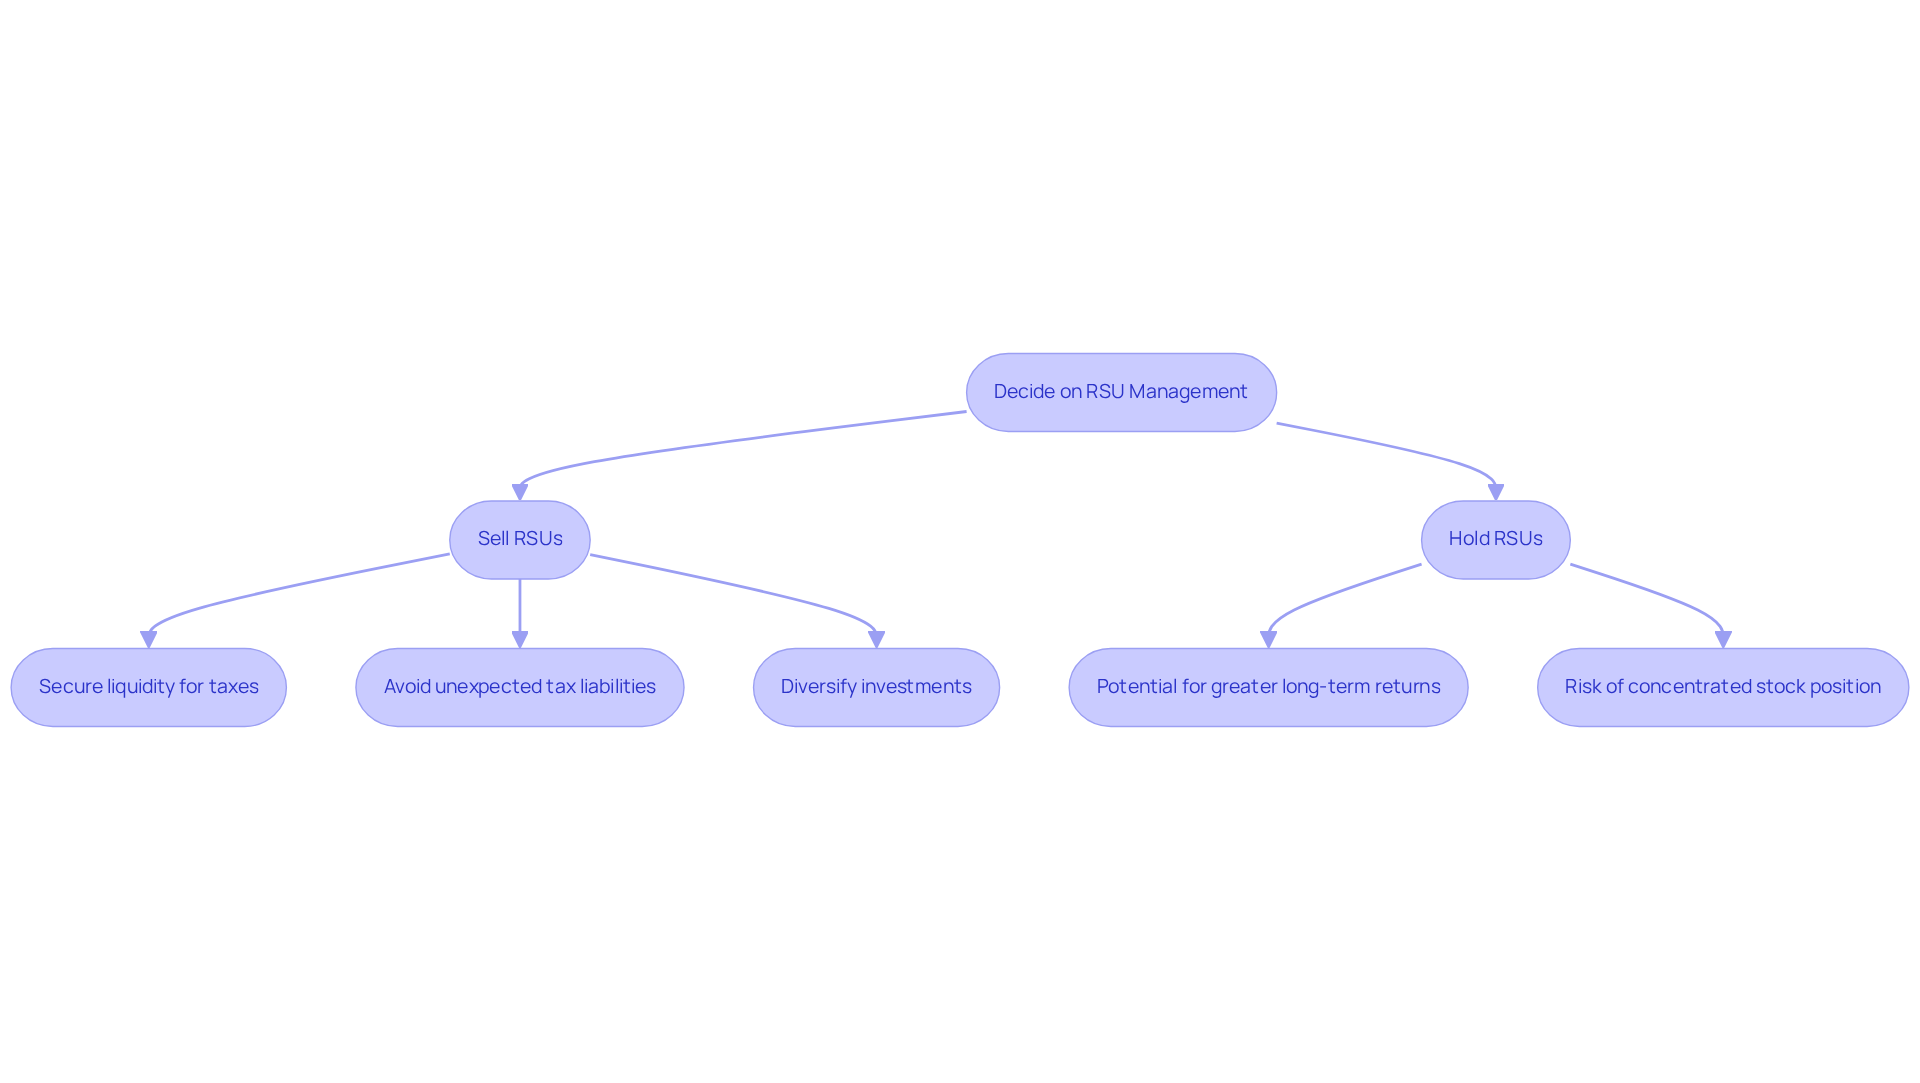
Families navigating the complexities of Restricted Stock Units often face a crucial decision: should they sell their shares immediately upon vesting, or hold them for potential future growth? Many employees opt to sell their restricted stock units right away, primarily to secure liquidity for taxes and other pressing expenses. This proactive approach can help avoid unexpected tax liabilities, particularly if a large vesting event pushes them into a higher tax bracket. On the other hand, retaining these units could lead to greater returns if the company’s stock performs well over time.
When considering this choice, it’s essential for households to reflect on their financial goals, risk tolerance, and current market conditions. A balanced strategy might involve selling a portion of the restricted stock units to address immediate financial needs while keeping some shares for long-term growth. For instance, families could think about selling enough stocks to cover the 22% statutory withholding tax on vested stock units, which can amount to significant sums depending on the overall value of the shares.
It’s important to recognize that psychological barriers, such as the endowment effect, can complicate this decision. Many individuals may feel hesitant to part with their RSUs, even when they wouldn’t choose to invest cash in the same company stock. Seeking guidance from a financial consultant can be invaluable in crafting a personalized strategy that aligns with the family’s broader financial plan, ensuring informed choices that support long-term wealth-building goals.
Consider the experience of Allison and Brian with Bright Advisers. They managed their decisions based on their unique financial situation, prioritizing diversification and liquidity. By doing so, they mitigated the risks associated with concentrated stock positions while positioning themselves for future financial success. Through their collaboration with Bright Advisers, they secured their children’s future through education funding and gained the ability to retire sooner.
Additionally, it’s crucial to remember that restricted stock units are taxed as ordinary income upon vesting, underscoring the importance of careful planning. Notably, only 28% of S&P 500 companies would have resulted in greater wealth if RSUs were kept instead of sold and reinvested into the S&P 500. This statistic highlights the potential benefits of selling RSUs immediately after vesting, providing families with options to navigate their financial journey effectively. Together, we can explore these choices and find the best path forward for your family’s future.
Conclusion
Understanding pre-IPO Restricted Stock Units (RSUs) is essential for young families striving to enhance their financial stability and long-term wealth. These equity compensation tools can open doors to significant economic growth, but they also require thoughtful management to align with your family’s goals and values. By grasping the intricacies of RSUs, you can harness their benefits while navigating the challenges they present.
Throughout this guide, we’ve shared key insights about RSUs, including:
- Vesting schedules
- Tax implications
- Strategic management approaches
Recognizing how RSUs can play a vital role in a diversified investment portfolio empowers families to make informed decisions that strengthen their financial resilience. Real-life examples illustrate how young households have successfully integrated RSUs into their financial planning, showcasing their potential to fund significant life events and secure brighter futures.
Ultimately, effectively utilizing RSUs can empower your family to build a more promising financial future. Engaging with financial advisors and tax experts can deepen your understanding and management of these assets, ensuring you are well-prepared to navigate the complexities of RSUs. By taking proactive steps, your family can leverage these financial tools not just for immediate needs, but also for long-term prosperity and security. Together, we can navigate this journey toward financial well-being.
Frequently Asked Questions
What are Restricted Stock Units (RSUs)?
Restricted Stock Units (RSUs) are a form of equity compensation offered by employers to employees, representing a promise to deliver shares of stock at a later date, contingent on meeting specific conditions.
Why are RSUs important for young families?
RSUs can significantly contribute to overall compensation and long-term wealth accumulation, which is crucial for young families aiming to secure their children’s financial futures.
How do RSUs typically vest?
RSUs usually vest over a predetermined schedule, often structured as a three- or four-year ratable vesting plan, allowing employees to receive shares incrementally.
How can families utilize the income from RSUs?
Families can use the income from RSUs for various financial goals, such as saving for education or purchasing a home.
How are RSUs taxed?
RSUs are taxed as compensation upon vesting, so families should strategize to manage their tax obligations effectively.
What are the benefits of pre-IPO RSUs beyond immediate financial rewards?
Pre-IPO RSUs can serve as a strategic component of a diversified investment portfolio, helping families reduce risks associated with overconcentration in employer stock.
What is a common guideline for employer stock holdings in a portfolio?
A common guideline suggests limiting employer stock holdings to 10-30% of a portfolio to promote a balanced investment approach.
Can you provide examples of how families have used RSUs?
Families have successfully used RSU proceeds to fund significant life events, such as down payments on homes or education savings for their children.
How should families view RSUs in relation to their overall wealth strategy?
Families should view RSUs as part of a comprehensive wealth strategy rather than relying solely on them for asset accumulation.
How can financial advisors assist families with RSUs?
Proactive collaboration with financial advisors can help families navigate the complexities of RSUs and ensure they align with their overall financial goals and values.
List of Sources
- Define Restricted Stock Units (RSUs) and Their Importance for Young Families
- Restricted Stock Units and Building a Diversified Portfolio (https://brightonjones.com/blog/restricted-stock-units)
- Restricted Stock Units: A Closer Look (https://havenwealthplanning.com/2024/07/restricted-stock-units-1)
- RSUs 101: A Tech Professional’s Guide to Equity, Tax Strategy, and Financial Planning (https://merceradvisors.com/insights/investing/rsus-101-a-tech-professionals-guide-to-equity-tax-strategy-and-financial-planning)
- Restricted Stock Units: 10 Fast Facts | JD Supra (https://jdsupra.com/legalnews/restricted-stock-units-10-fast-facts-68072)
- Explain How RSUs Work: Vesting Schedules and Conditions
- Vesting Schedules and Their Impact on RSUs (https://upstock.io/post/vesting-schedules-and-their-impact-on-rsus)
- How to Sell Restricted Stock Units (RSUs) (https://smartasset.com/investing/how-to-sell-restricted-stock)
- Restricted Stock Units (RSUs): Key Points You Must Know (https://mystockoptions.com/articles/restricted-stock-units-rsus-checklist-of-key-points-to-know)
- Here’s How Restricted Stock Units (RSUs) Work | Bankrate (https://bankrate.com/investing/restricted-stock-units)
- Restricted Stock Units: What You Need to Know About RSUs – NerdWallet (https://nerdwallet.com/article/investing/rsus)
- Discuss Tax Implications of RSUs: What Young Parents Need to Know
- The Taxation of Restricted Stock Units | Cerity Partners (https://ceritypartners.com/insights/the-taxation-of-restricted-stock-units)
- Tax Insights on ISOs, RSUs, and NQSOs: A Complete Guide | RGWM (https://rgwealth.com/insights/planning-for-taxes-generated-from-equity-compensation-plans)
- Restricted Stock Units: Understanding RSUs and Their Tax Implications – Dimov Tax & CPA Services (https://dimovtax.com/restricted-stock-units-guide)
- Restricted Stock and Performance Stock Taxes: A Guide (https://schwab.com/learn/story/rsu-taxes-and-psu-taxes)
- Restricted Stock Unit (RSU): A Complete Guide to RSUs (https://carta.com/learn/equity/rsu)
- Offer Strategies for Managing RSUs: Selling vs. Holding
- Should I Sell or Hold My RSUs? Key Factors to Consider. (https://usecache.com/companion/when-to-sell-rsu-stock)
- When Should You Sell Restricted Stock Units (RSUs)? – OPES Wealth (https://opeswealth.com/when-should-you-sell-restricted-stock-units-rsus)
- When Should I Sell My RSUs (Restricted Stock Units)? (https://nasdaq.com/articles/when-should-i-sell-my-rsus-restricted-stock-units)
- DATA showing WHY you should sell your RSUs when they vest (https://linkedin.com/pulse/data-showing-why-you-should-sell-your-rsus-when-vest-kris-barney-cfa-w74qe)
- How to Determine the Right Time to Sell RSUs (https://zajacgrp.com/insights/how-to-determine-the-right-time-to-sell-rsus-and-why-selling-immediately-might-make-sense)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading