

Overview
Navigating the world of Restricted Stock Units (RSUs) can feel overwhelming, especially for young parents looking to secure their family’s future. These units serve as a unique form of equity compensation, aligning employee interests with the success of their company. However, they also bring along specific tax and liquidity challenges that are essential to understand.
Imagine being granted RSUs without any upfront costs. They vest based on your employment or performance criteria, which means your hard work can truly pay off. Yet, it’s important to realize that these units are taxed as ordinary income upon vesting. Understanding these aspects is crucial for effective financial planning, ensuring you make the most out of your compensation.
By grasping how RSUs work, you can better prepare for the financial responsibilities that come with them. This knowledge empowers you to make informed decisions that align with your family’s values and long-term goals. Remember, we’re here for you, ready to support you in navigating this journey. Together, we can ensure that your family’s financial future is bright and secure.
Key Highlights:
- RSUs are a form of equity compensation offered by companies, promising shares based on conditions like employment or performance goals.
- They align employee interests with company success, enhancing retention and fostering ownership.
- Employees receive shares upon vesting without upfront purchase, but RSUs are taxed as ordinary income at vesting based on fair market value.
- If an employee leaves before vesting, they lose unvested shares, impacting overall compensation.
- RSUs differ from stock options, which require purchasing shares at a predetermined price and can lose value if stock price falls.
- RSUs maintain value as long as the stock’s fair market value is above zero, making them less risky than stock options.
- Other equity awards like Restricted Stock Awards (RSAs) provide shares upfront but come with restrictions.
- Vesting schedules for RSUs can be time-based or performance-based, requiring employees to meet specific conditions.
- Tax implications for RSUs include significant liabilities upon vesting, with potential under-withholding issues for higher income brackets.
- Liquidity for RSUs in private companies is often limited to events like acquisitions or IPOs, complicating tax obligation management.
- Double-trigger vesting conditions for RSUs in private firms require both a specific employment period and a liquidity event for shares to vest.
Introduction
Understanding the intricacies of Restricted Stock Units (RSUs) is vital for employees in private companies. These equity compensation tools can significantly influence financial outcomes and career paths. Imagine feeling a sense of ownership in your company without the burden of upfront costs. RSUs align your interests with company performance, offering a unique opportunity to engage with your workplace on a deeper level.
However, navigating the complexities of vesting schedules, tax implications, and liquidity events can be daunting. It’s important to understand how to tackle these challenges to maximize your benefits. What strategies can you employ to ensure financial stability for your family? This exploration into RSUs promises to unveil key insights that empower you to make informed decisions about your compensation packages. Together, we can navigate this journey and find the best path forward for your financial well-being.
Define Restricted Stock Units (RSUs) and Their Purpose
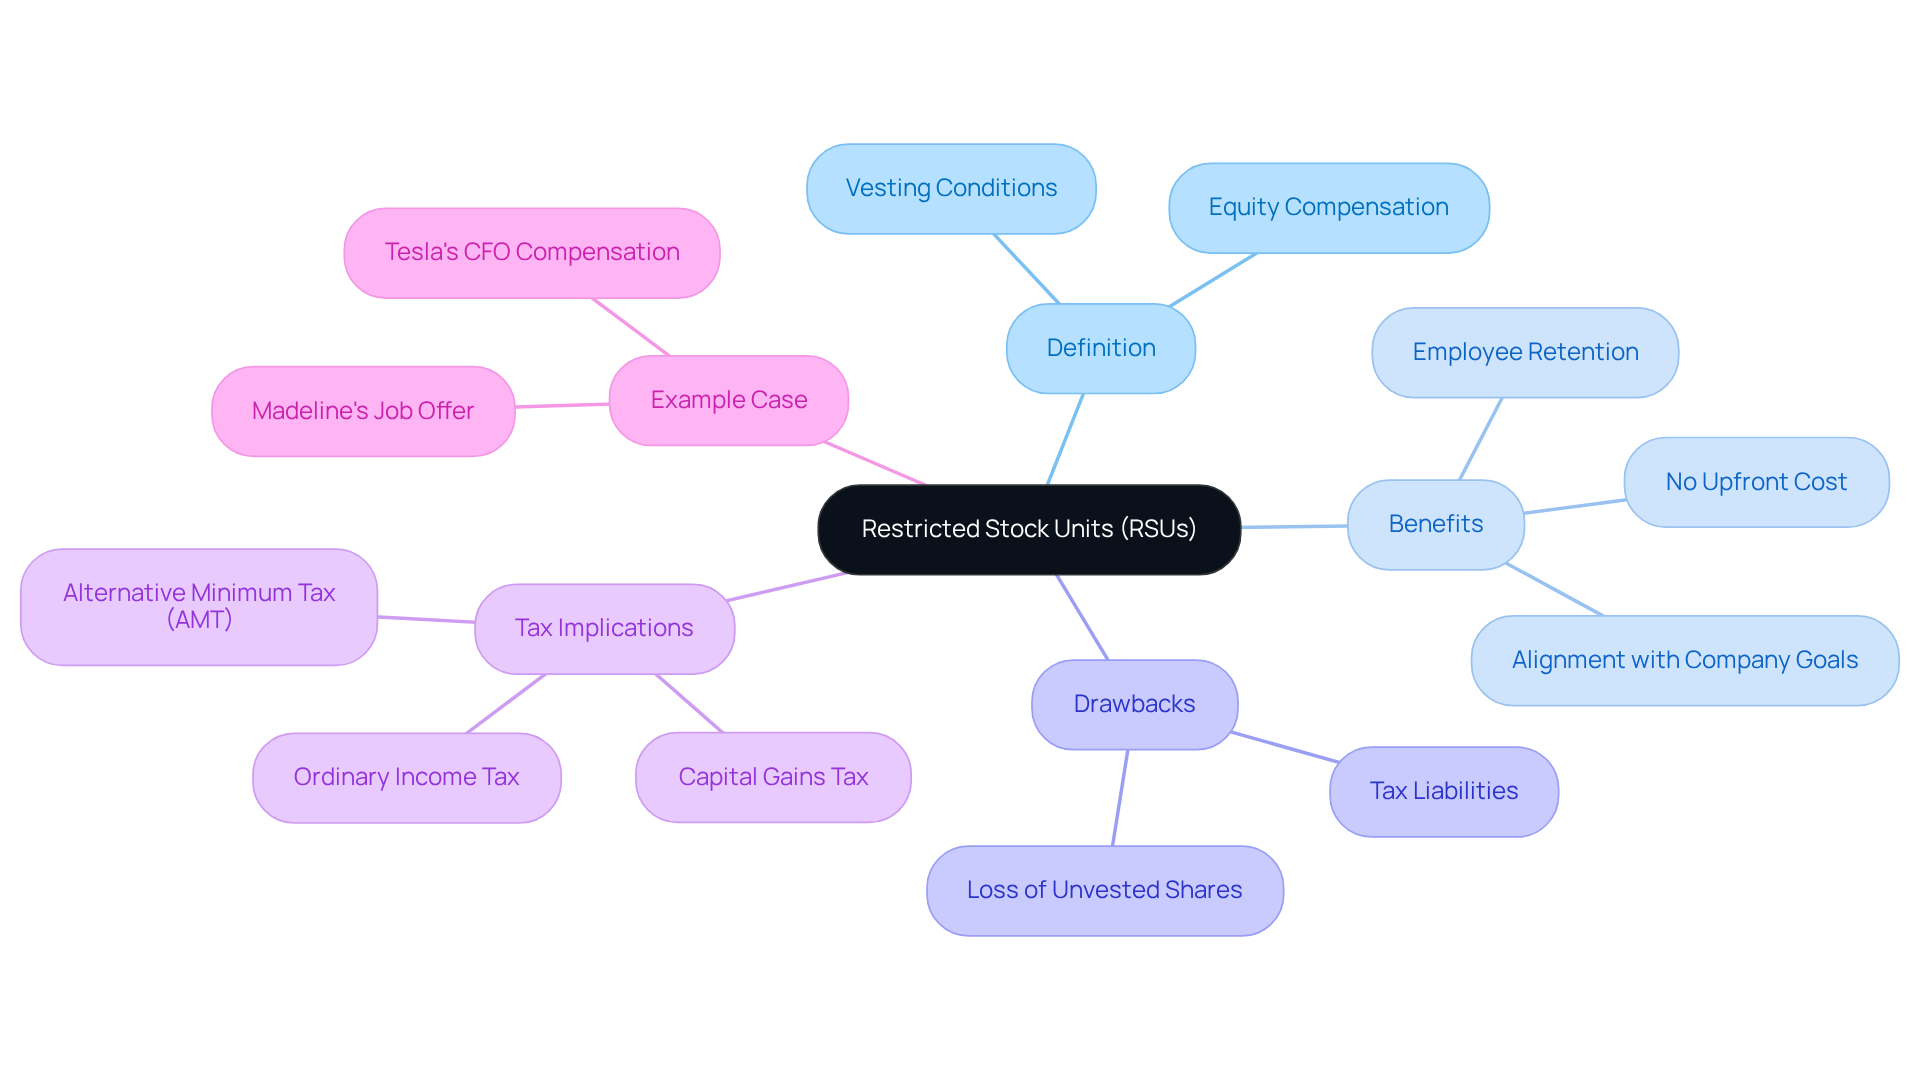
RSUs for private companies can be a wonderful form of equity compensation that companies offer to their employees. They represent a promise to grant shares of stock at a later time, based on certain conditions like ongoing employment or achieving performance goals. This thoughtful structure is designed to align the interests of employees with those of the company, fostering a sense of ownership and encouraging everyone to contribute to the company’s success. By promoting long-term commitment, restricted stock units can significantly enhance employee retention rates.
One of the most appealing aspects of restricted stock units is that they don’t require employees to purchase shares upfront. Instead, individuals receive the shares directly once the vesting criteria are met. This feature makes RSUs particularly attractive, as they provide employees with a stake in the organization’s performance without the financial burden of an initial investment. However, it’s important to understand that RSUs are taxed as ordinary income upon vesting, based on their fair market value. This can lead to significant tax liabilities. As of 2024, RSU income may also trigger the Alternative Minimum Tax (AMT), with tax rates of either 26% or 28% for qualifying taxpayers.
Imagine if an employee leaves the organization before their stock units vest; they typically lose any unvested shares, which can impact their overall compensation package. This reality has contributed to the growing popularity of RSUs for private companies, with many organizations incorporating them into their compensation strategies to attract and retain talent.
For instance, Tesla’s Chief Financial Officer, Taneja Vaibhav, received 104,619 restricted stock units as part of his compensation, illustrating how large companies leverage RSUs to align employee interests with corporate success. Such examples highlight the effectiveness of RSUs in nurturing a culture of commitment and shared objectives within organizations. Overall, restricted stock units not only acknowledge employees for their contributions but also help companies retain valuable talent by linking compensation to the long-term performance of the business. It’s also worth noting that RSUs do not provide dividends or voting rights until they are vested, which is an essential aspect to consider when evaluating their value and limitations.
Compare RSUs with Stock Options and Other Equity Awards
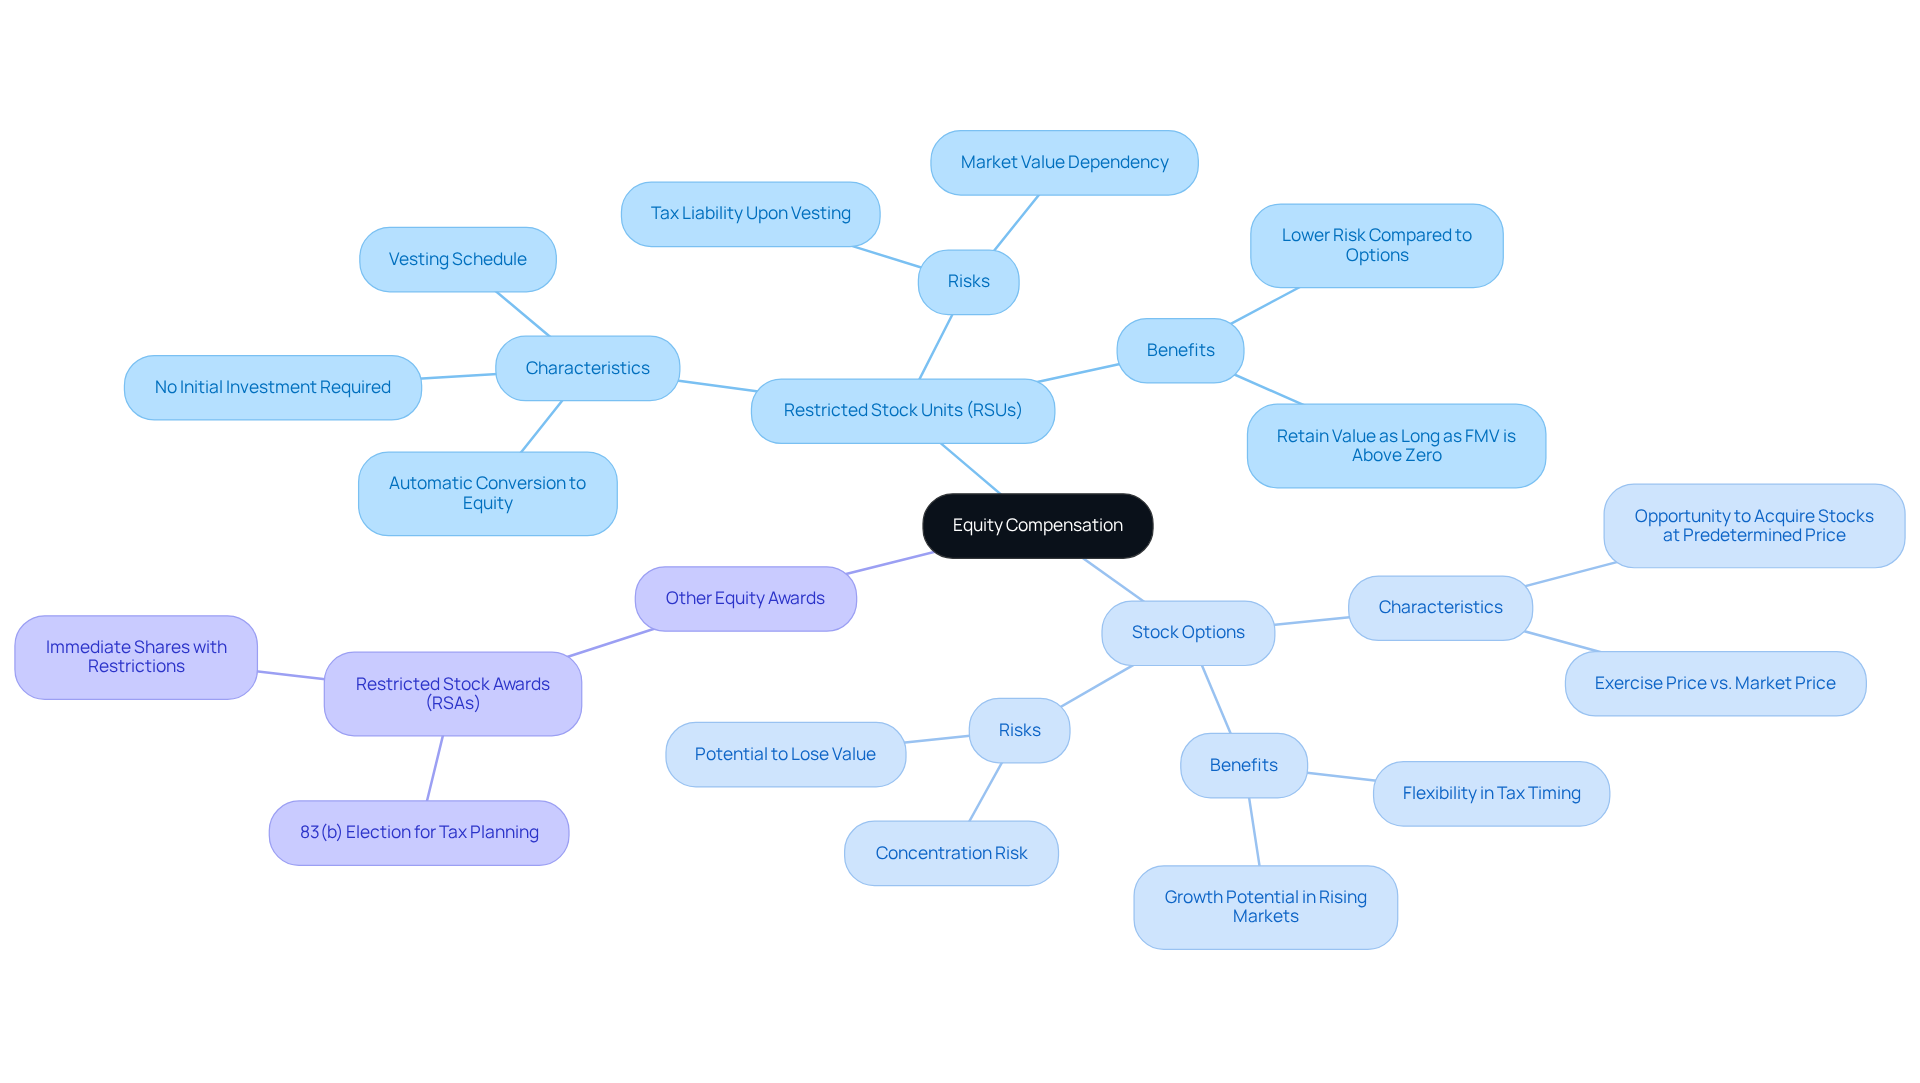
Restricted Stock Units (RSUs) and stock options represent two distinct forms of equity compensation, each carrying unique characteristics and implications for you and your family. Stock options grant the opportunity to acquire stocks at a predetermined price, which can be quite beneficial if the company’s stock appreciates. However, there are risks to consider; if the stock price dips below the exercise price, those options may lose their value, potentially leading to concentration risk if a significant portion of your wealth is tied to one company’s stock. Imagine a situation where a stock option is priced at $25, but the stock is currently valued at $20—this means the option holds no value.
On the other hand, restricted stock units automatically convert into equity upon vesting, providing immediate value without requiring an initial investment. This aspect makes RSUs inherently less risky, as they maintain value as long as the stock’s fair market value (FMV) stays above zero. For instance, if Alex’s restricted stock units vest when the stock price is $5 each, he would recognize $50,000 in taxable income over four years, which would be subject to capital gains taxes when sold.
Other equity awards, such as Restricted Stock Awards (RSAs), provide actual shares upfront but come with specific restrictions. While restricted stock units are often viewed as a safer option, they don’t offer the same growth potential as stock options in a rapidly rising market. Consider this: if a company’s stock price surges, stock options can yield significant profits, while restricted stock units deliver a fixed value based on the stock’s FMV at vesting.
Understanding these differences is crucial for you as you navigate your compensation packages. As companies increasingly adopt RSUs for private companies because of their straightforward nature and reduced risk profile, it’s important to weigh the advantages and disadvantages of each type of equity incentive. Experts like Brian Watson emphasize that restricted stock units signify a commitment from employers to provide equity once certain milestones are met, highlighting the importance of grasping the tax implications and management strategies associated with these awards. This knowledge empowers you to make informed decisions that align with your family’s financial goals and risk tolerance. Together, we can navigate this journey toward financial security.
Explain How RSUs Work: Vesting and Conditions
Understanding restricted stock units is crucial for your family’s financial planning. These units typically come with a vesting timeline, which outlines when you’ll gain full ownership of the stock. Imagine a scenario where your hard work translates into financial security for your loved ones. Vesting schedules often include:
- Time-based vesting, where stocks gradually become yours over a set period—like 25% each year for four years.
- Performance-based vesting, linking stock ownership to specific goals your organization or you might achieve.
It’s important to recognize that fulfilling these criteria is essential to secure your units. If, for any reason, you leave the organization before the units vest, those valuable assets could slip away. This reality can be daunting, but grasping these vesting conditions empowers you to make informed decisions for your family’s future. Remember, we’re here for you, ready to support you in navigating this journey toward financial stability and peace of mind.

Discuss Tax Implications of RSUs for Employees
When RSUs for private companies vest, they become taxable income, which can feel overwhelming for many. It’s essential to report the fair market value of these units as ordinary income on your tax returns. This tax obligation arises at the moment of vesting, not when you sell the shares. Employers are required to withhold taxes during this process, which can lead to a significant tax bill, especially for those in higher tax brackets.
Imagine this: if 250 shares vest at an FMV of $50 per share, your taxable income would total $12,500. This could push you into a higher tax bracket, potentially leading to under-withholding issues. Typically, the statutory withholding rate for restricted stock units under $1 million is 22%. However, this might not suffice if your income from RSUs places you in a higher tax bracket.
To navigate these challenges, it’s crucial to adopt proactive strategies for managing your tax liabilities. Consulting with a tax advisor can provide you with tailored guidance, helping you navigate your unique situation and optimize your financial outcomes. Promptly selling newly granted stock units can be a wise approach, allowing you to meet your tax responsibilities without incurring additional capital gains taxes.
Furthermore, if you hold your restricted stock units for over a year after they vest, the profits are taxed as long-term capital gains at lower rates. Understanding the nuances of tax treatment in different jurisdictions is also important, as some countries have varying rates and rules regarding RSU taxation.
By developing a well-structured plan and staying informed about your tax responsibilities, you can effectively manage your RSU income in a way that aligns with your long-term financial goals. Remember, we’re here for you, and together, we can navigate this journey towards financial stability for your family.

Address Unique Considerations for RSUs in Private Companies
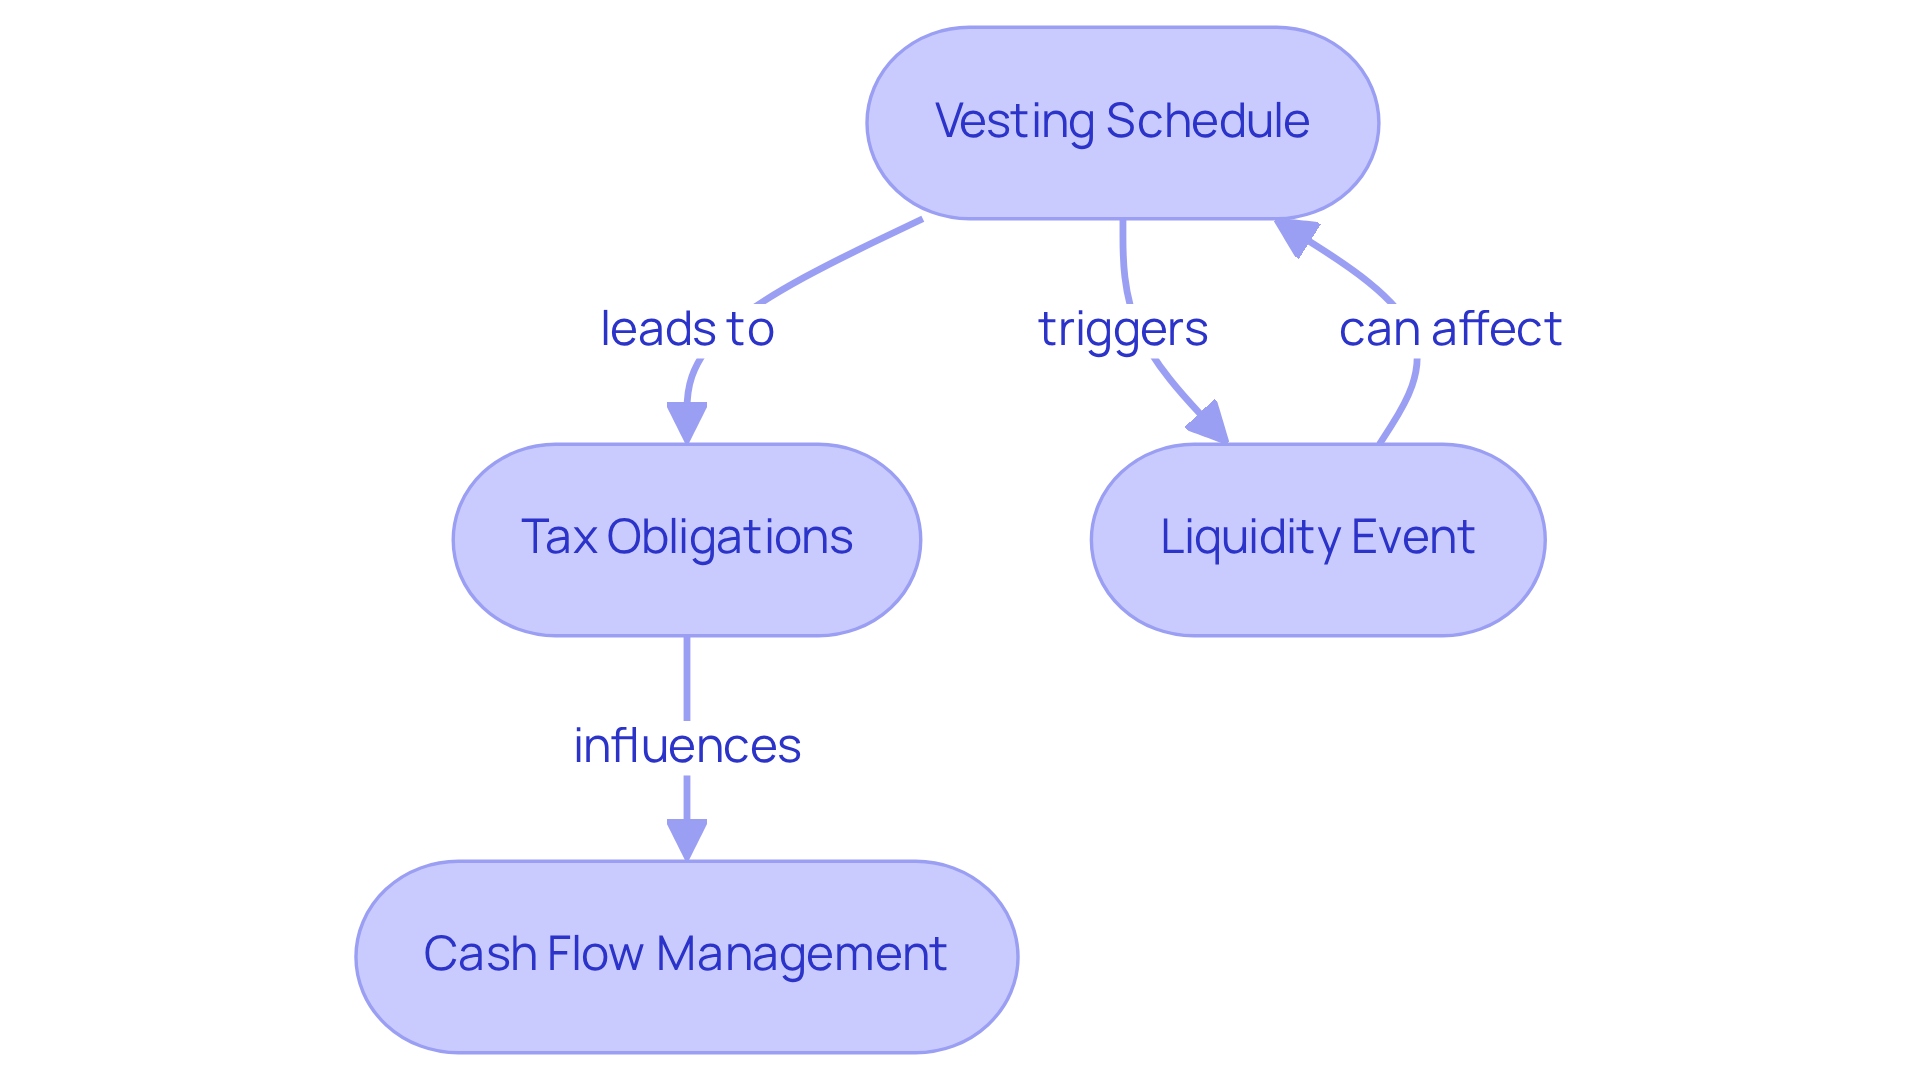
Navigating the world of RSUs for private companies can be a daunting experience, especially when it comes to liquidity. Unlike public companies, where you can easily sell your units on the stock market, private company interests often become liquid only during specific events, such as an acquisition or an initial public offering (IPO). This limited liquidity can create challenges for you and your family, particularly when tax obligations arise upon vesting. Imagine facing a cash flow shortage because you can’t sell your shares right away to cover these taxes. It’s important to understand that restricted stock units are taxed as regular income when they vest. Additionally, these units typically vest over a four-year period at a rate of 25% annually, meaning you’ll need to stay with your organization for a considerable time to fully enjoy their benefits.
Moreover, many private firms implement double-trigger vesting conditions for RSUs. This means that your shares will only vest when two criteria are met:
- A specified period of employment
- A liquidity event
Such conditions can complicate your financial landscape, as you must navigate both the timing of your employment and the occurrence of a liquidity event to realize the value of your RSUs. Until these vesting conditions are fulfilled, you don’t possess your restricted stock units, which limits your rights and potential benefits. However, it’s reassuring to know that RSUs are awarded without charge, making them an appealing option compared to stock options.
As you consider how restricted stock units fit into your compensation package, it’s essential to assess these factors carefully. They can have profound implications for your financial planning and overall cash flow management. Significantly, 93% of private company decision-makers believe that having a liquidity event is beneficial for job opportunities, underscoring the importance of these occurrences in relation to RSUs for private companies. In some cases, an exit event can even trigger accelerated vesting of RSUs, providing you with immediate ownership or liquidity options.
Together, we can navigate this journey and ensure that you have the support you need to make informed decisions for your family’s future.
Conclusion
Understanding Restricted Stock Units (RSUs) is essential for employees in private companies. These equity compensation tools offer a unique opportunity to foster a sense of ownership without the burden of upfront costs. Imagine if you could align your interests with your company’s performance. RSUs not only enhance engagement but also serve as a strategic method to attract and retain talent. However, the complexities surrounding vesting schedules, tax implications, and liquidity events can feel overwhelming, making it crucial to grasp their intricacies to fully leverage their benefits.
Throughout this article, we explored key insights, including the differences between RSUs and stock options, the various vesting conditions, and the significant tax implications that arise upon vesting. It’s important to understand how RSUs can provide immediate value to employees while mitigating risks compared to stock options. Additionally, we addressed the unique challenges faced by employees in private companies, such as limited liquidity and potential tax burdens. This underscores the importance of informed decision-making in financial planning, helping you navigate these complexities.
Ultimately, the journey of navigating RSUs in private companies is not just about understanding the mechanics. It’s about empowering you to make strategic choices that align with your financial goals. As the landscape of equity compensation continues to evolve, staying informed and proactive will be key to unlocking the full potential of RSUs. Together, we can ensure financial stability and success for you and your family.
Frequently Asked Questions
What are Restricted Stock Units (RSUs)?
Restricted Stock Units (RSUs) are a form of equity compensation offered by companies to employees, representing a promise to grant shares of stock at a later time based on conditions such as ongoing employment or performance goals.
What is the purpose of RSUs?
The purpose of RSUs is to align the interests of employees with those of the company, fostering a sense of ownership and encouraging long-term commitment, which can enhance employee retention rates.
Do employees need to purchase shares when receiving RSUs?
No, employees do not need to purchase shares upfront. They receive the shares directly once the vesting criteria are met.
How are RSUs taxed?
RSUs are taxed as ordinary income upon vesting, based on their fair market value. This can lead to significant tax liabilities, and as of 2024, RSU income may also trigger the Alternative Minimum Tax (AMT).
What happens to RSUs if an employee leaves the company before they vest?
If an employee leaves the organization before their RSUs vest, they typically lose any unvested shares, which can impact their overall compensation package.
How do RSUs compare to stock options?
RSUs automatically convert into equity upon vesting and provide immediate value without requiring an initial investment, making them less risky. In contrast, stock options grant the opportunity to acquire stocks at a predetermined price, which can lose value if the stock price falls below that price.
What are other types of equity awards besides RSUs?
Other types of equity awards include Restricted Stock Awards (RSAs), which provide actual shares upfront but come with specific restrictions. Unlike RSUs, stock options can offer higher growth potential in a rapidly rising market.
Do RSUs provide dividends or voting rights?
No, RSUs do not provide dividends or voting rights until they are vested.
Why are RSUs becoming popular among private companies?
RSUs are becoming popular among private companies because they are straightforward, reduce risk for employees, and help attract and retain talent by linking compensation to the long-term performance of the business.
List of Sources
- Define Restricted Stock Units (RSUs) and Their Purpose
- Restricted Stock Units (RSUs): Everything You Need to Know (https://harness.co/articles/what-you-need-to-know-about-restricted-stock-units-rsus)
- Restricted Stock Unit (RSU): A Complete Guide to RSUs (https://carta.com/learn/equity/rsu)
- Restricted Stock Unit (RSU): How It Works and Pros and Cons (https://investopedia.com/terms/r/restricted-stock-unit.asp)
- RSUs Explained: How Restricted Stock Units Work & Are Taxed (https://vestedfinance.com/blog/us-stocks/rsus-a-comprehensive-guide-to-restricted-stock-units)
- Here’s How Restricted Stock Units (RSUs) Work | Bankrate (https://bankrate.com/investing/restricted-stock-units)
- Compare RSUs with Stock Options and Other Equity Awards
- Stock Options and Other Equity Awards Explained | BartleyFinancial (https://bartleyfinancial.com/stock-options-and-other-equity-awards-explained)
- Stock Options and RSUs: What You Should Know (https://truepointwealth.com/viewpoint/stock-options-and-rsus-what-you-should-know)
- Differences Between Restricted Stock Units and Employee Stock Options (https://zajacgrp.com/insights/what-are-the-key-differences-between-restricted-stock-and-employee-stock-options)
- RSUs vs. RSAs: A Guide to Understanding Key Differences and Tax Treatment (https://plancorp.com/blog/restricted-stock-units-restricted-stock-awards-comparison)
- Stock Options vs Restricted Stock Units (RSUs): A guide (https://globalshares.com/insights/rsus-vs-stock-options)
- Discuss Tax Implications of RSUs for Employees
- The RSU Tax Withholding Conundrum (https://tciwealth.com/blog/rsu-tax-withholding)
- Tax Insights on ISOs, RSUs, and NQSOs: A Complete Guide | RGWM (https://rgwealth.com/insights/planning-for-taxes-generated-from-equity-compensation-plans)
- Restricted Stock Units (RSUs) and Tax Planning Strategy: 3 Key Questions for Tech Professionals in 2025 (https://maprivatewealth.com/insights/restricted-stock-units-tax-planning-strategy-tech-professionals)
- The Global Impact of RSUs: Taxation of Stock-Based Compensation Across Countries – CIGMA Accounting (https://cigmaaccounting.co.uk/the-global-impact-of-rsus-tax-stock-based-compensation)
- Restricted stock units (RSUs): Overview, tax and pros & cons (https://globalshares.com/insights/restricted-stock-units-rsus)
- Address Unique Considerations for RSUs in Private Companies
- Restricted Stock Units: How RSUs Works for Startups (https://cakeequity.com/guides/restricted-stock-units)
- morgan stanley at work private company liquidity trends | Morgan Stanley (https://morganstanley.com/press-releases/morgan-stanley-at-work-private-company-liquidity-trends)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading