

Overview
This article highlights the importance of understanding Restricted Stock Units (RSUs) for young parents, especially in terms of their vesting and tax implications. RSUs can serve as a valuable asset in building your family’s financial security.
Imagine if you could manage these wisely—by selling shares to cover taxes and diversifying your investments, you can navigate the complexities of financial planning with confidence.
By taking these steps, young families can ensure a brighter financial future together. Remember, we’re here for you as you embark on this journey.
Key Highlights:
- Restricted Stock Units (RSUs) are a form of equity compensation that can help employees build wealth over time.
- Understanding RSUs is crucial for young parents as they can assist in achieving financial security and covering major expenses.
- RSUs typically vest over a period (e.g., four years), affecting employees’ access to shares and their financial planning.
- Tax obligations arise when RSUs vest, regardless of whether the shares have been distributed, impacting cash flow for families.
- Strategies for managing RSUs include selling shares to cover taxes, diversifying investments, aligning RSUs with financial goals, and consulting financial advisors.
- Selling RSUs upon vesting can mitigate stock price risk and simplify tax reporting.
- Proactive tax planning can help families navigate complexities and enhance their financial strategies.
Introduction
Understanding the financial landscape can feel overwhelming for young parents. The complexities of Restricted Stock Units (RSUs) often add to this challenge. These equity compensation tools hold the potential to significantly enhance a family’s financial stability, yet many parents find themselves uncertain about how to leverage them effectively.
Imagine the moment when RSUs are vested but not yet distributed. This scenario introduces a critical challenge for young families: balancing immediate financial needs with long-term wealth accumulation.
It’s important to explore the nuances of RSUs, including their:
- Vesting schedules
- Tax implications
- Strategic management
By doing so, families can unlock opportunities that pave the way for a more secure economic future. Together, we can navigate this journey and ensure that your family’s financial well-being is prioritized.
Define Restricted Stock Units (RSUs) and Their Importance
Restricted Stock Units (RSUs) represent a meaningful form of equity remuneration that employers offer to their employees. They embody a commitment to provide shares of the company’s stock at a future date, contingent on specific conditions such as employment duration or performance milestones. For young parents, understanding RSUs is crucial, as they can play a significant role in building wealth and ensuring economic security. When managed wisely, these units can serve as a valuable resource, helping to cover essential expenses like children’s education, retirement savings, or other long-term financial goals.
The potential of restricted stock units to enhance a family’s financial stability is profound. Imagine if a worker receives 1,500 RSUs with a vesting schedule of 20% after one year. They could see substantial gains as the shares become accessible. If the share price stands at $10 at the time of vesting, selling 300 shares could generate $3,000—funds that can be directed toward pressing financial needs or invested in a diversified portfolio.
It’s important to understand that integrating RSUs into a broader financial strategy is vital. Financial advisors often recommend that young families limit their exposure to employer stock to 10-30% of their total portfolio to mitigate risks associated with overconcentration. This strategy not only safeguards against potential declines in company stock value but also encourages a more balanced investment approach. Bright Advisers employs innovative methods like smart beta and factor investing to help families optimize their portfolios, ensuring that RSUs are effectively managed within their overall financial plan.
In summary, restricted stock units can significantly support wealth accumulation for young parents, offering a pathway to financial stability and the opportunity to invest in their children’s futures. By understanding vesting schedules, tax implications, and the strategic selling of RSUs, families can leverage RSUs vested but not distributed as a form of compensation to achieve their long-term financial aspirations. Additionally, selling RSUs promptly upon vesting can be beneficial for immediate financial needs, such as funding major purchases or paying off high-interest debts. With the innovative wealth management strategies and advanced technology provided by Bright Advisers, young families can navigate these complexities with confidence, knowing that they have support every step of the way.
Differentiate Between Vesting and Distribution of RSUs
Vesting is a significant process for employees, as it allows them to gain rights to their restricted stock units over a specified period. Imagine a timeline where these units typically vest over four years, often with a one-year cliff. This means that workers don’t own any shares until they complete their first year of employment. Once that time is up, the shares are transferred to the employee, marking a crucial milestone.
For young parents, understanding vesting is particularly important. It directly influences their access to these assets and how they manage their family’s budget. For instance, if RSUs are vested but not distributed, parents need to consider how the situation of RSUs vested but not distributed affects their immediate needs and long-term aspirations. By grasping the common vesting durations in tech firms—often reflecting that four-year framework—parents can better plan their financial goals.
At Bright Advisers, our financial planners emphasize the importance of understanding the nuances of RSU vesting. This knowledge is essential for parents as they navigate their compensation packages and work towards optimizing their financial futures. Together, we can explore customized wealth management strategies that empower young families to make informed decisions about their restricted stock units. We’re here to help you handle the related risks and tax implications effectively, ensuring you feel supported every step of the way.

Explore Tax Implications of Vested but Undistributed RSUs
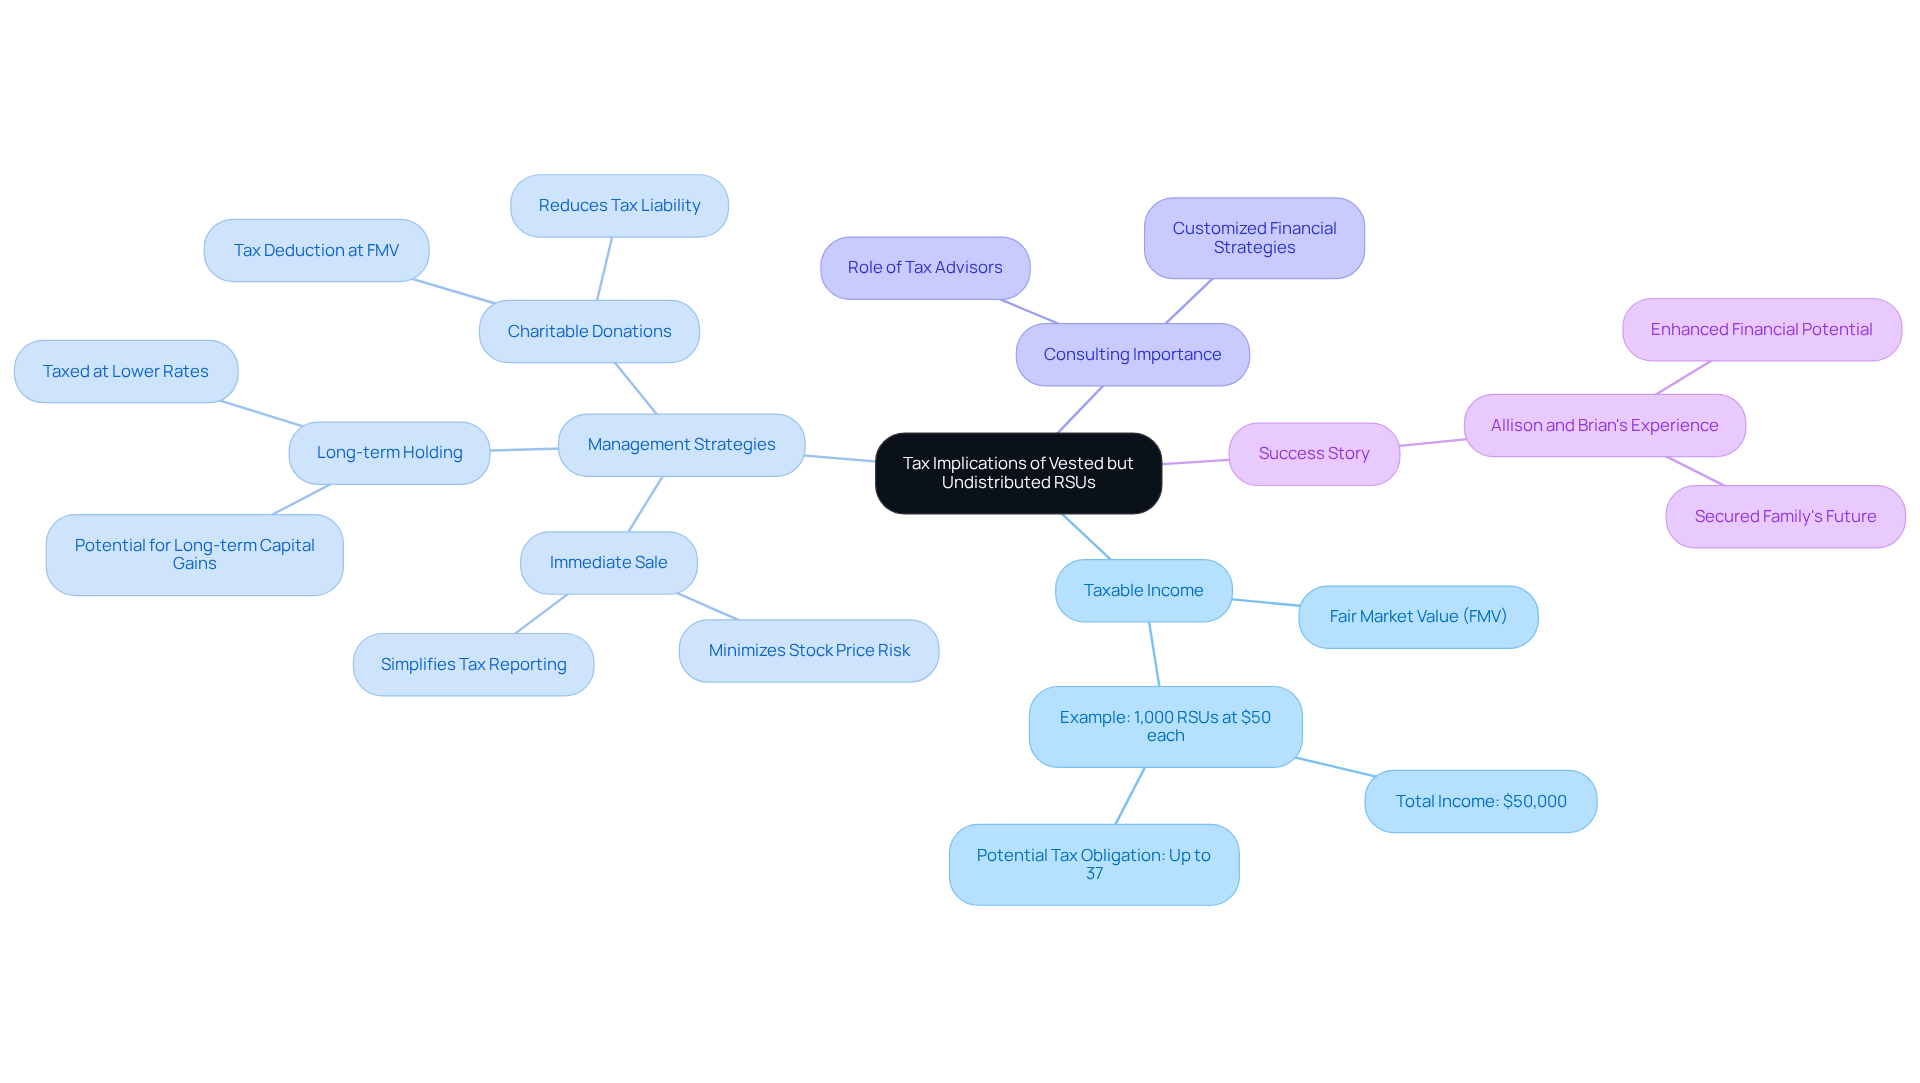
When RSU vested but not distributed, they become a part of your taxable income, regardless of whether the shares have been distributed. The taxable amount is determined by the fair market value (FMV) of the shares at the time of vesting. Imagine if a worker has 1,000 restricted stock units vesting at a value of $50 each; they would then declare an additional $50,000 in income, potentially facing a significant tax obligation. This situation can create cash flow challenges for young parents, as the tax is due even before the shares are sold or received.
To effectively manage this tax burden, it’s essential for parents to explore various tax planning strategies. One helpful approach is to sell restricted stock units immediately upon vesting. This can reduce the risk of stock price fluctuations and simplify tax reporting. Additionally, holding RSUs for over a year after vesting allows for long-term capital gains treatment on any future appreciation, which is generally taxed at a lower rate than ordinary income.
It’s important to understand that consulting with a tax advisor is crucial for households navigating these complexities. Bright Advisers offers customized services like budgeting, cash flow forecasts, and tax planning to assist families in enhancing their financial strategies. By comprehending the typical tax obligation arising from RSU vested but not distributed—possibly reaching as high as 37% for federal taxes—families can make informed planning choices.
By proactively addressing these tax implications, young parents can align their financial strategies with their household objectives, ensuring a more secure economic future. Furthermore, donating vested restricted stock units to charity can provide a tax deduction at their fair market value, offering another avenue for managing tax liabilities. The success story of Allison and Brian illustrates how strategic tax planning with Bright Advisers empowered them to enhance their financial potential and secure their family’s future. We’re here for you, ready to help you navigate this journey together.
Implement Strategies for Managing Vested RSUs
Managing RSUs that are vested but not distributed can feel overwhelming, especially for young parents navigating financial responsibilities. Here are several key strategies to consider:
- Sell to Cover Taxes: When restricted stock units vest, selling a portion of the shares can help cover tax obligations. This proactive approach prevents unexpected financial strain during tax season. Imagine if 1,000 restricted stock units vest at $50 each, totaling $50,000. By selling a portion, you can ensure that your tax obligations are met without disrupting your cash flow.
- Diversification: Concentrating too much wealth in a single asset can be risky. After selling a portion of your RSUs, consider reinvesting in a diversified portfolio. This can reduce risk and enhance your overall financial stability. Experts agree that diversification is crucial for families with significant wealth tied to one company’s performance.
- Set Monetary Goals: Align your RSU management strategy with your family’s financial objectives, such as saving for your children’s education or purchasing a family home. This alignment ensures that your financial decisions support your long-term aspirations.
- Consult a Wealth Consultant: Working with a money planner can provide tailored strategies that consider your family’s unique situation and long-term goals. Professional guidance can help you navigate the complexities of RSU management and optimize your tax implications.
By implementing these strategies, you can ensure that your RSUs, which are vested but not distributed, contribute positively to your family’s financial health. Remember, we’re here for you, helping you focus on what truly matters—your family’s future.
Conclusion
Understanding Restricted Stock Units (RSUs) is essential for young parents aiming to secure their financial future. These equity compensation tools not only provide a potential source of wealth but also require careful management to align with both immediate needs and long-term goals. Imagine having the knowledge to navigate the intricacies of how RSUs vest and the implications of their distribution. By doing so, families can better navigate their financial landscape.
Key insights reveal that the vesting process and tax obligations associated with RSUs can significantly impact a family’s financial strategy. It’s important to understand the importance of:
- Timely selling vested RSUs to cover taxes
- Diversifying investments
- Setting clear monetary goals
Furthermore, consulting with financial professionals can provide tailored strategies that enhance the management of RSUs, ensuring they contribute positively to overall financial health.
Ultimately, the journey of managing RSUs is one of empowerment. Young parents are encouraged to take proactive steps in understanding and leveraging these financial tools to build a more secure future for their families. By prioritizing financial education and strategic planning, families can transform the complexities of RSUs into opportunities for wealth accumulation and stability. Together, we can pave the way for a brighter economic outlook.
Frequently Asked Questions
What are Restricted Stock Units (RSUs)?
Restricted Stock Units (RSUs) are a form of equity compensation offered by employers to employees, representing a commitment to provide shares of the company’s stock at a future date, contingent on specific conditions such as employment duration or performance milestones.
Why are RSUs important for young parents?
Understanding RSUs is crucial for young parents as they can play a significant role in building wealth and ensuring economic security. When managed wisely, RSUs can help cover essential expenses like children’s education, retirement savings, or other long-term financial goals.
How can RSUs contribute to financial stability?
RSUs can enhance a family’s financial stability by providing substantial gains when shares become accessible. For example, if a worker receives 1,500 RSUs with a vesting schedule of 20% after one year, they could sell vested shares for cash that can be used for pressing financial needs or invested.
What is a recommended strategy for managing RSUs in a financial portfolio?
Financial advisors often recommend that families limit their exposure to employer stock to 10-30% of their total portfolio to mitigate risks associated with overconcentration. This strategy helps protect against potential declines in company stock value and encourages a balanced investment approach.
How can families effectively manage their RSUs?
Families can effectively manage their RSUs by understanding vesting schedules, tax implications, and strategically selling RSUs upon vesting. Selling RSUs promptly can be beneficial for immediate financial needs, such as funding major purchases or paying off high-interest debts.
What resources are available for families to navigate RSUs?
Bright Advisers offers innovative wealth management strategies and advanced technology to help families optimize their portfolios and navigate the complexities of managing RSUs, ensuring they can leverage these assets to achieve long-term financial aspirations.
List of Sources
- Define Restricted Stock Units (RSUs) and Their Importance
- Restricted Stock Units and Building a Diversified Portfolio (https://brightonjones.com/blog/restricted-stock-units)
- Restricted Stock Units: What You Need to Know About RSUs – NerdWallet (https://nerdwallet.com/article/investing/rsus)
- The Wealth Building Power of RSUs (It’s not what you think.) | Parkworth Wealth Management (https://parkworth.com/blogs/the-wealth-building-power-of-rsus-its-not-what-you-think)
- Restricted Stock Units: A Closer Look (https://havenwealthplanning.com/2024/07/restricted-stock-units-1)
- Use Restricted Stock Units to Fund Financial Planning Goals (https://zajacgrp.com/insights/restricted-stock-units-to-fund-financial-planning-goals)
- Differentiate Between Vesting and Distribution of RSUs
- Restricted Stock Unit (RSU): How It Works and Pros and Cons (https://investopedia.com/terms/r/restricted-stock-unit.asp)
- RSU Vesting: A Guide to Understanding Restricted Stock Units (https://brightonjones.com/blog/rsu-vesting)
- Vesting Schedules and Their Impact on RSUs (https://upstock.io/post/vesting-schedules-and-their-impact-on-rsus)
- Here’s How Restricted Stock Units (RSUs) Work | Bankrate (https://bankrate.com/investing/restricted-stock-units)
- Explore Tax Implications of Vested but Undistributed RSUs
- How Are Restricted Stock Units (RSUs) Taxed? (https://smartasset.com/investing/how-are-restricted-stock-units-taxed)
- RSU Taxes: How Are Restricted Stock Units (RSUs) Taxed? | Facet (https://facet.com/equity/rsu-taxes-calculations-reporting-strategies)
- A Comprehensive Guide to RSUs for Employees (https://vestedfinance.com/blog/us-stocks/rsus-a-comprehensive-guide-to-restricted-stock-units)
- Implement Strategies for Managing Vested RSUs
- RSUs: A Guide to Understanding Restricted Stock Units | Facet (https://facet.com/equity/understanding-restricted-stock-units-rsus-taxes-vesting-schedules-pros-cons)
- Restricted Stock Units (RSUs) and Tax Planning Strategy: 3 Key Questions for Tech Professionals in 2025 (https://maprivatewealth.com/insights/restricted-stock-units-tax-planning-strategy-tech-professionals)
- Sell to Cover RSU: Tax Strategies & Tips — Brooklyn Fi (https://brooklynfi.com/blog/sell-to-cover-rsu)
- The Sell to Cover Tax Strategy for Restricted Stock Units (RSUs) (https://kubera.com/blog/sell-to-cover-rsu)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading