

Key Highlights:
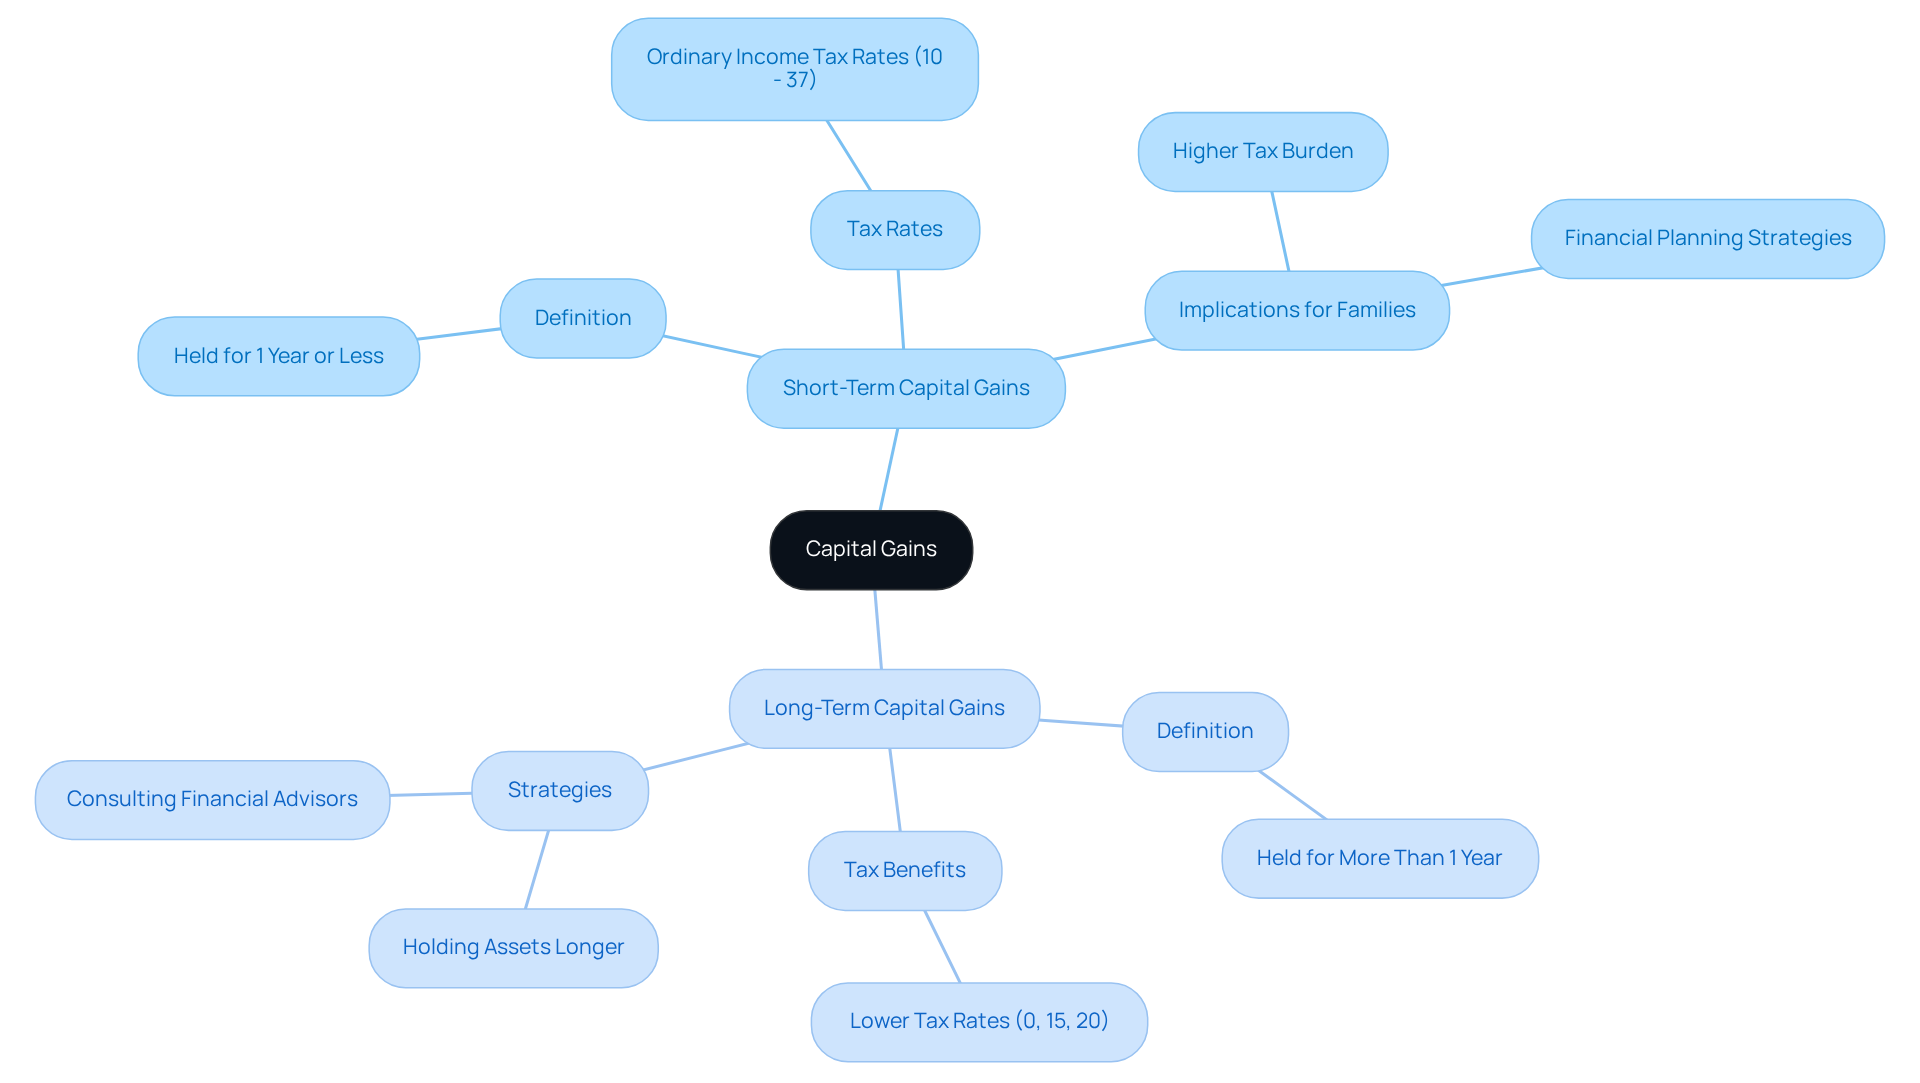
- Capital gains are profits from selling an asset for more than its purchase price, categorised as short-term or long-term based on ownership duration.
- Short-term capital gains arise from assets held for one year or less and are taxed at ordinary income rates (10% to 37%).
- Long-term capital gains come from assets held for over a year and benefit from lower tax rates (0%, 15%, or 20%) based on income levels.
- Families can reduce tax burdens by holding investments longer to qualify for lower long-term capital gains rates.
- Utilising tax-advantaged accounts like IRAs or 401(k)s can defer taxes on profits until withdrawal, often at a lower rate.
- Tax-loss harvesting involves selling underperforming investments to offset gains, helping to reduce taxable income.
- Gifting appreciated assets to family members in lower tax brackets can minimise tax burdens while supporting loved ones.
- Timing asset sales during years of lower income can help families take advantage of reduced tax rates.
- Strategic financial planning, including working with advisors, can enhance families’ economic security and optimise tax situations.
Introduction
Navigating the complexities of capital gains taxes can feel overwhelming, especially for families eager to secure their financial future. It’s essential to grasp the differences between short-term and long-term capital gains, as these distinctions can greatly influence tax liabilities and investment strategies. Imagine if you could minimize your tax burdens while making informed decisions for your family’s financial well-being.
Understanding these nuances is key. Families often explore various strategies, but what happens when the subtleties of tax implications are overlooked? This article aims to provide you with the essential knowledge and actionable tactics that can empower you to optimize your financial decisions. Together, we can navigate this journey toward enhanced economic security for your family.
Define Capital Gains: Short-Term vs. Long-Term
Understanding Capital Gains: A Guide for Families
Navigating the world of capital gains can feel overwhelming, especially for young parents trying to secure their family’s financial future. Capital gains represent the profit you make when selling an asset for more than you paid for it. They’re categorized based on how long you’ve owned the asset, and understanding the short term and long term capital gains tax can make a significant difference in your financial planning.
Short-Term Capital Gains:
Imagine selling a toy your child has outgrown. If you sell it for more than you bought it, that profit is a short-term capital gain. These gains, which are subject to short term and long term capital gains tax, come from assets held for one year or less and are taxed at ordinary income tax rates, ranging from 10% to 37% for 2025, depending on your total taxable income. This can hit families hard, as those in higher income brackets face steeper tax rates. For families like Jay and Emma, understanding how short-term profits affect their financial strategies is crucial. It can help them lessen financial stress and plan more effectively.
Long-Term Capital Gains:
Now, think about that same toy if you held onto it for over a year before selling. The profit you make then is a long-term capital gain. These gains benefit from lower tax rates of 0%, 15%, or 20%, depending on your income level. This distinction is vital for families looking to optimize their tax liabilities in relation to short term and long term capital gains tax and investment strategies. Emily and Mark turned to Bright Advisers for help in crafting a financial plan that gives them the freedom to choose whether to continue working, including strategies for managing capital returns effectively.
Understanding these differences is essential for effective tax planning, particularly in relation to short term and long term capital gains tax. For instance, if your family is considering selling an investment property, holding onto it for more than a year could qualify you for those reduced long-term capital gains rates. Financial advisors, like those at Bright Advisers, often emphasize this strategy, noting that it can lead to substantial tax savings.
Moreover, families should know they can subtract up to $3,000 of excess capital losses from other income, which can help balance out capital profits. Without proper tax planning, families might miss out on for savings and growth. Managing capital appreciation taxes can be complex, but seeking guidance from financial consultants can ensure you make informed choices that align with your family’s financial goals.
Together, we can navigate this journey. Understanding capital gains is just one step in your financial planning. We’re here for you, ready to support you in making the best decisions for your family’s future.
Explore Capital Gains Tax Rates and Their Implications
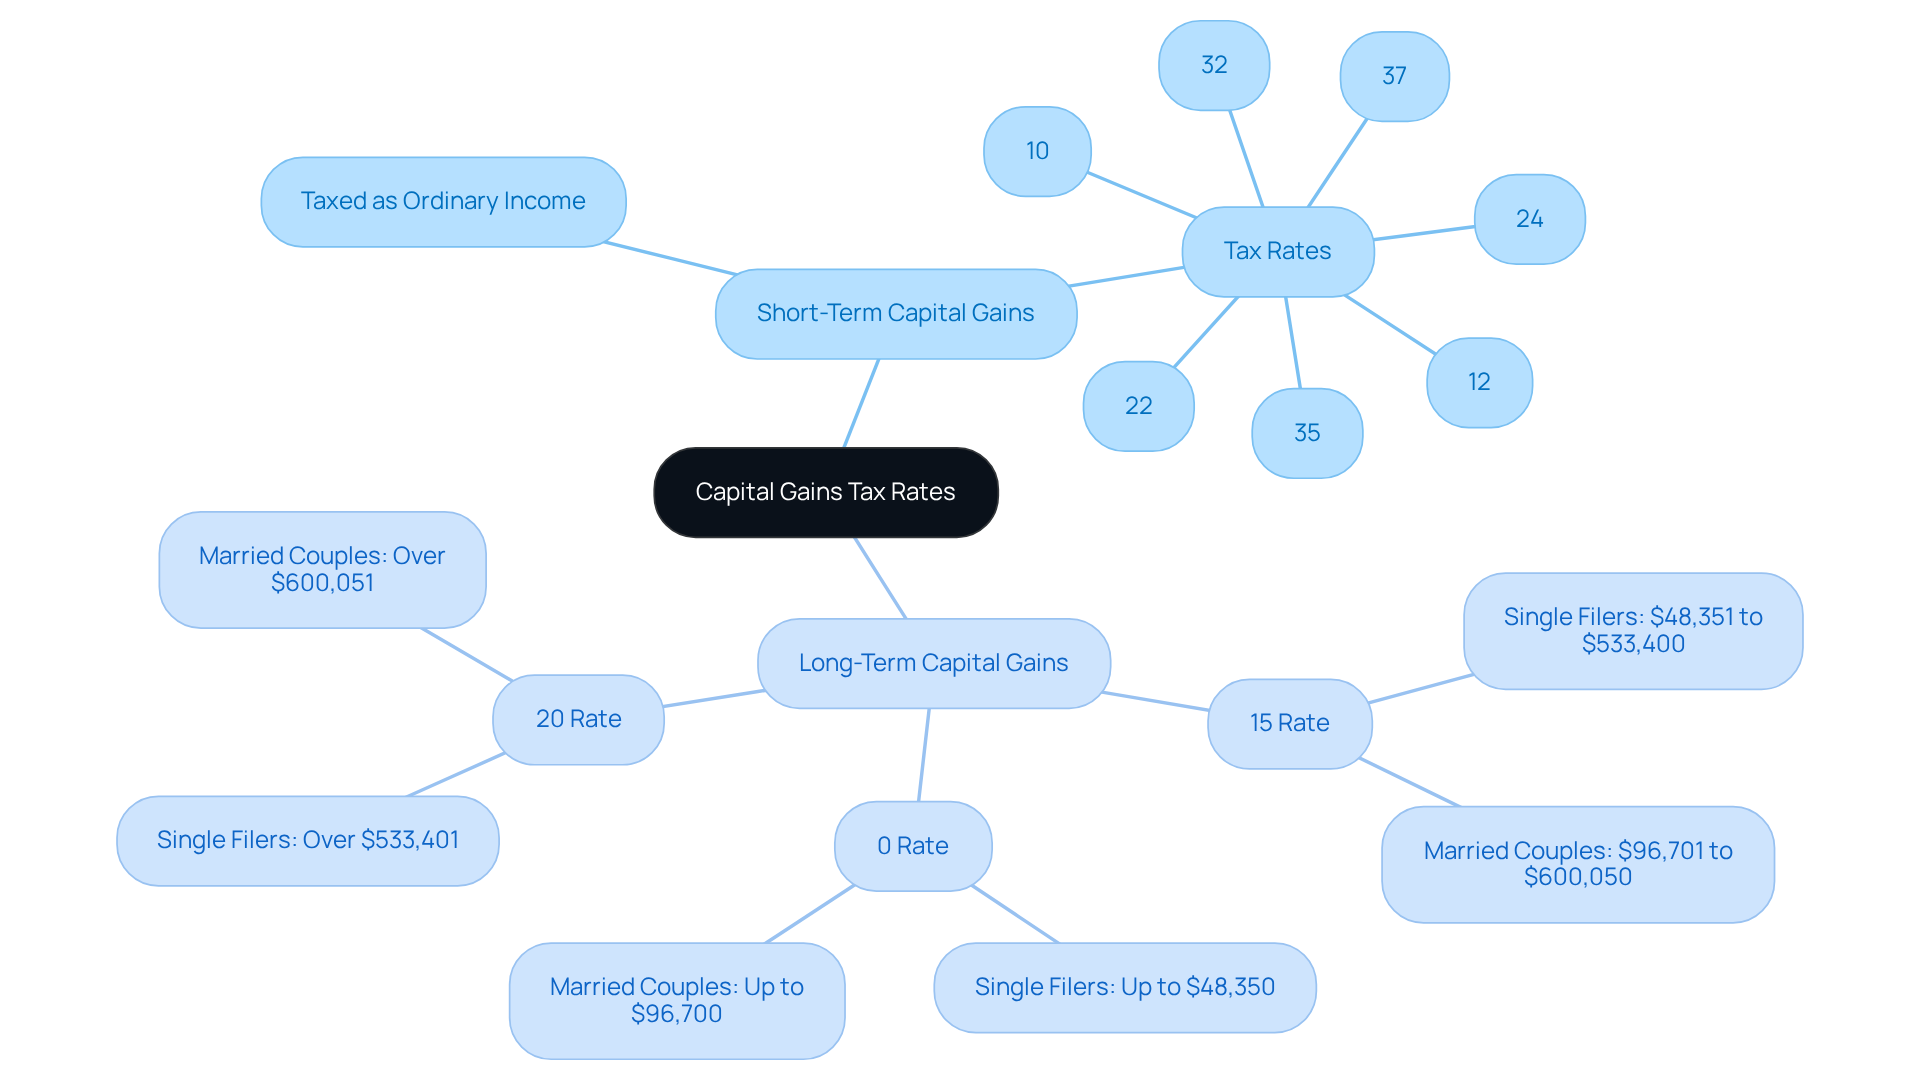
In 2025, understanding short term and long term capital gains tax is crucial for families looking to secure their financial future. Here’s a quick overview:
- Short-Term Capital Gains: These are taxed as ordinary income, with rates ranging from 10% to 37%, depending on your income bracket.
- Long-Term Capital Gains: The rates are tiered:
- 0% for single filers with taxable income up to $48,350 and married couples up to $96,700.
- 15% for single filers with income between $48,351 and $533,400, and married couples between $96,701 and $600,050.
- 20% for single filers earning over $533,401 and married couples over $600,051.
It’s important to grasp these rates as you plan your investments. Imagine if you could hold onto your assets for over a year, allowing you to benefit from those lower long-term capital gains rates. This simple strategy can help reduce your overall tax burden. Tax experts emphasize that effective planning around short term and long term capital gains tax rates can significantly enhance your family’s financial well-being, allowing you to optimize your investments while minimizing tax obligations.
Consider the journey of Allison and Brian. They turned to [[Bright Advisers for guidance](https://brightadvisers.com/?p=10152)](https://brightadvisers.com/?p=10152) on maximizing their economic potential through thoughtful tax planning. Despite their substantial incomes, they were unaware of the financial opportunities slipping through their fingers due to inadequate tax strategies. With the support of Bright Advisers, they embraced specific tactics like and proactive income management. These strategies not only improved their tax situation but also secured their children’s future through education funding, allowing them to dream of retiring sooner. This story illustrates how families can harness tax optimization techniques to bolster their economic security and independence.
As Neil Krishnaswamy, president of Krishna Wealth Planning, points out, the 0% short term and long term capital gains tax bracket offers a ‘significant opportunity’ for effective tax planning. It’s essential for families to explore methods like tax-loss harvesting to offset capital gains, further enhancing their financial strategies.
Together, we can navigate this journey toward financial stability. We’re here for you, ready to help you make the most of your family’s resources.
Implement Strategies to Minimize Capital Gains Taxes
Use english for answers
Please return corrected/formatted text for:
Navigating Capital Gains Taxes: A Caring Guide for Families
As a family, managing your finances can feel overwhelming, especially when it comes to capital gains taxes. But don’t worry; there are several thoughtful strategies you can embrace to ease this burden and secure your family’s financial future.
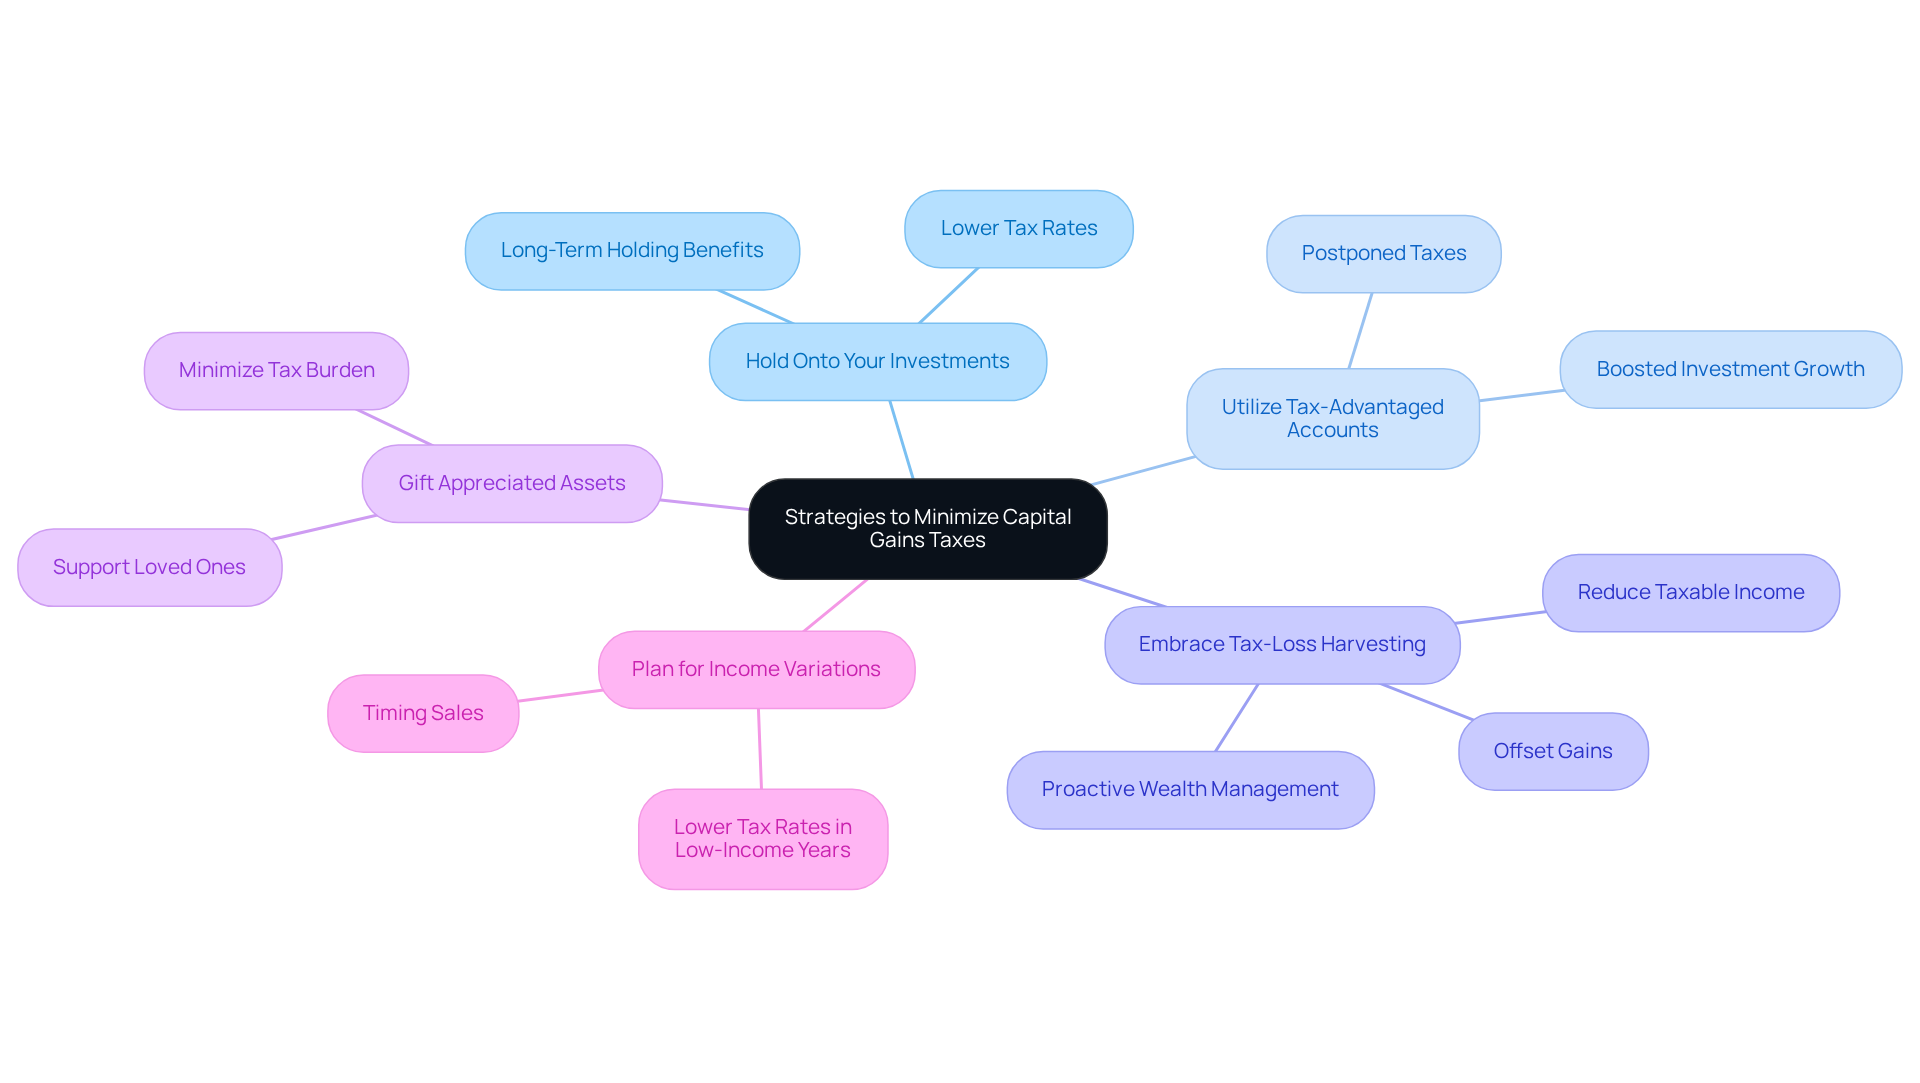
- Hold Onto Your Investments
Imagine if you could keep your hard-earned assets for just a little longer. By holding onto them for over a year, you can enjoy significantly lower rates under the short term and long term capital gains tax, sometimes as low as 0% for those in lower income brackets. This simple shift can make a big difference for your family. - Utilize Tax-Advantaged Accounts
Consider investing through options like IRAs or 401(k)s. These accounts allow you to postpone taxes on your profits until you withdraw them, often at a lower tax rate. This not only boosts your investment growth but also aligns perfectly with [Bright Advisers](https://brightadvisers.com/?p=10179)’ philosophy of comprehensive financial planning, helping you maximize your wealth potential. - Embrace Tax-Loss Harvesting
Have you ever thought about selling underperforming investments? This strategy, known as tax-loss harvesting, can offset gains and reduce your taxable income. Research shows that tailored strategies can enhance the benefits for families like yours. In fact, around 29% of households are already using this proactive approach to wealth management in 2025. - Gift Appreciated Assets
What if you could support your loved ones while minimizing your tax burden? Gifting appreciated assets to family members in lower tax brackets can help achieve just that. This thoughtful approach not only reduces taxes but also reflects the values and aspirations you hold for your family’s economic legacy. - Plan for Income Variations
Timing is everything! By planning to sell assets during years of reduced income, you can take advantage of lower tax rates, improving your overall tax situation.
These strategies empower you to take control of your financial future while navigating the complexities of short term and long term capital gains tax. As wealth planner Craig Copeland wisely notes, “Tax-advantaged retirement accounts play a major role in the average household’s net worth today.” This highlights the importance of strategic planning in managing your assets.
Through your partnership with Bright Advisers, you can achieve meaningful results-like improved tax situations, funding education for your children, and even retiring earlier. Together, we can enhance your family’s . Bright Advisers also offers essential services in budgeting, asset tracking, and cash flow projections, all vital components of a comprehensive family financial strategy.
We’re here for you. Together, we can navigate this journey toward a brighter financial future.
Conclusion
Understanding the ins and outs of short-term and long-term capital gains tax is crucial for families looking to secure their financial future. Imagine being able to make informed decisions that can significantly impact your financial planning and overall wealth management. The difference between short-term and long-term capital gains not only affects how much tax you owe but also shapes investment strategies that can lead to meaningful savings.
Throughout this article, we’ve highlighted several key strategies to help families navigate capital gains taxes effectively:
- Holding investments for over a year to enjoy lower tax rates
- Utilizing tax-advantaged accounts
- Engaging in tax-loss harvesting
- Gifting appreciated assets
- Planning for income variations
Each of these strategies underscores the importance of proactive financial planning.
Ultimately, the journey toward financial stability is a collaborative effort. By partnering with financial advisors like Bright Advisers, families can access tailored strategies that not only enhance their economic security but also align with their long-term goals. Embracing these practices can lead to improved tax situations, increased savings for education, and even the possibility of an earlier retirement.
Taking the first step toward understanding and managing capital gains taxes is crucial for families seeking a brighter financial future. Remember, we’re here for you, and together, we can navigate this journey.
Frequently Asked Questions
What are capital gains?
Capital gains represent the profit you make when selling an asset for more than you paid for it.
How are capital gains categorized?
Capital gains are categorized based on how long you’ve owned the asset: short-term (held for one year or less) and long-term (held for more than one year).
What are short-term capital gains?
Short-term capital gains come from assets held for one year or less and are taxed at ordinary income tax rates, which range from 10% to 37% for the year 2025, depending on your total taxable income.
How do short-term capital gains affect families?
Short-term capital gains can hit families hard, especially those in higher income brackets, as they face steeper tax rates. Understanding these gains is crucial for effective financial planning.
What are long-term capital gains?
Long-term capital gains are profits made from selling assets held for over a year and benefit from lower tax rates of 0%, 15%, or 20%, depending on your income level.
Why is it important for families to understand the difference between short-term and long-term capital gains?
Understanding these differences is essential for effective tax planning and can help families optimize their tax liabilities and investment strategies.
What tax benefits can families receive from long-term capital gains?
Families can qualify for reduced long-term capital gains rates by holding onto an investment for more than a year, leading to substantial tax savings.
Can families offset capital gains with losses?
Yes, families can subtract up to $3,000 of excess capital losses from other income, which can help balance out capital profits.
How can financial advisors assist families with capital gains?
Financial advisors can provide guidance on managing capital appreciation taxes and help families make informed choices that align with their financial goals.
List of Sources
- Define Capital Gains: Short-Term vs. Long-Term
- How Are Capital Gains Taxed? (https://schwab.com/learn/story/how-are-capital-gains-taxed)
- New research finds capital gains are highly concentrated and hardly taxed, underscoring widespread U.S. inequality (https://equitablegrowth.org/new-research-finds-capital-gains-are-highly-concentrated-and-hardly-taxed-underscoring-widespread-u-s-inequality)
- Short vs. Long-Term Capital Gains & Tax Rates (https://carta.com/learn/equity/stock-options/taxes/capital-gains)
- Long-Term vs. Short-Term Capital Gains (https://investopedia.com/articles/personal-finance/101515/comparing-longterm-vs-shortterm-capital-gain-tax-rates.asp)
- Capital gains income tax quotes – who said it? (https://washingtonpolicy.org/publications/detail/capital-gains-income-tax-quotes-who-said-it)
- Explore Capital Gains Tax Rates and Their Implications
- How much you can make in 2026 and still pay 0% capital gains (https://cnbc.com/2025/10/14/capital-gains-taxes-2026.html)
- Capital Gains Tax Rates 2025 and 2026: What You Need to Know (https://kiplinger.com/taxes/capital-gains-tax/602224/capital-gains-tax-rates)
- 2025 and 2026 Capital Gains Tax Rates and Rules – NerdWallet (https://nerdwallet.com/taxes/learn/capital-gains-tax-rates)
- Capital gains tax: Definition, rates, and ways to save | Fidelity (https://fidelity.com/learning-center/smart-money/capital-gains-tax-rates)
- Capital Gains Tax Worries Rank High Among Family Business Leaders, New Poll Finds – Policy and Taxation Group (https://policyandtaxationgroup.com/family-businesses/capital-gains-tax-worries-rank-high-among-family-business-leaders-new-poll-finds)
- Implement Strategies to Minimize Capital Gains Taxes
- Report on the Economic Well-Being of U.S. Households in 2024 – May 2025 – Savings and Investments (https://federalreserve.gov/publications/2025-economic-well-being-of-us-households-in-2024-savings-and-investments.htm)
- 8 New Stats on the Rise of IRAs and 401(k)s (https://thinkadvisor.com/2024/06/27/8-new-stats-on-the-rise-of-iras-and-401ks)
- Who Harvests? Tax Alpha and Heterogeneous Responses to Capital Gains Taxation (https://papers.ssrn.com/sol3/Delivery.cfm/5717362.pdf?abstractid=5717362&mirid=1)
- Tax-Loss Harvesting: An Individual Investor’s Perspective (https://researchgate.net/publication/354764538_Tax-Loss_Harvesting_An_Individual_Investor’s_Perspective)
- 60 Financial Strategy Quotes from Top Minds (https://deliberatedirections.com/financial-strategy-quotes)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading