

Overview
The article shines a light on the features and benefits of a Solo 401(k) tailored specifically for partnerships. Imagine if you, as a self-employed individual or partner without full-time employees, could enhance your retirement savings potential while enjoying financial flexibility. This plan offers remarkable advantages, including higher contribution limits and appealing tax benefits.
Furthermore, the option for Roth contributions allows you to plan for your family’s future in a way that aligns with your values. Picture the peace of mind that comes from knowing you can even borrow from the plan when necessary. Each of these aspects contributes to a more secure financial future for you and your loved ones.
We understand that financial planning can feel overwhelming, but with the right tools, it doesn’t have to be. Together, we can navigate this journey, ensuring that your family’s priorities are met while building a solid retirement foundation. We’re here for you, ready to support you every step of the way.
Key Highlights:
- A Solo 401(k) is designed for self-employed individuals or partners with no full-time employees, allowing for higher retirement savings.
- In 2025, individuals under 50 can contribute up to $70,000, while those aged 50 and older can contribute up to $77,500, including catch-up contributions.
- Pretax employee contributions are tax-deductible, and employer contributions can be made until the tax filing deadline, providing flexibility.
- The plan allows for Roth contributions, enabling tax-free growth of investments, beneficial for those expecting to be in a higher tax bracket during retirement.
- Participants can borrow up to $50,000 from their Solo 401(k), providing liquidity during financial challenges.
- Eligibility for a Solo 401(k) requires the partnership to consist solely of partners and their spouses, without full-time employees, although part-time employees are allowed.
- The contribution limits for 2025 include employee deferrals of up to $23,500 and employer contributions based on earnings, enhancing savings potential.
- Tax-deferred growth on contributions allows for significant savings over time, making Solo 401(k) plans advantageous for financial planning.
Introduction
Imagine if you could create a world where self-employed individuals and business partners can truly supercharge their retirement savings with a financial strategy designed just for them. The Solo 401(k) for partnerships presents a unique opportunity to maximize contributions, offering significant tax advantages and flexibility that traditional retirement plans simply cannot match. Yet, it’s important to understand that with intricate eligibility requirements and varying contribution limits, partners may wonder how best to navigate this powerful tool to secure their financial futures. Together, we can explore how to make this work for you and your family.
Define Solo 401(k) for Partnerships
Imagine a future where you can secure your family’s financial well-being. A solo 401k for partnership is a thoughtful retirement savings strategy tailored for self-employed individuals or business owners who work as partners in a partnership. Unlike traditional 401(k) plans that cater to multiple employees, a Solo 401(k) is crafted specifically for businesses with no full-time employees other than the owners or their spouses. This unique approach allows partners to significantly boost their retirement savings, benefiting from higher contribution limits compared to other retirement accounts.
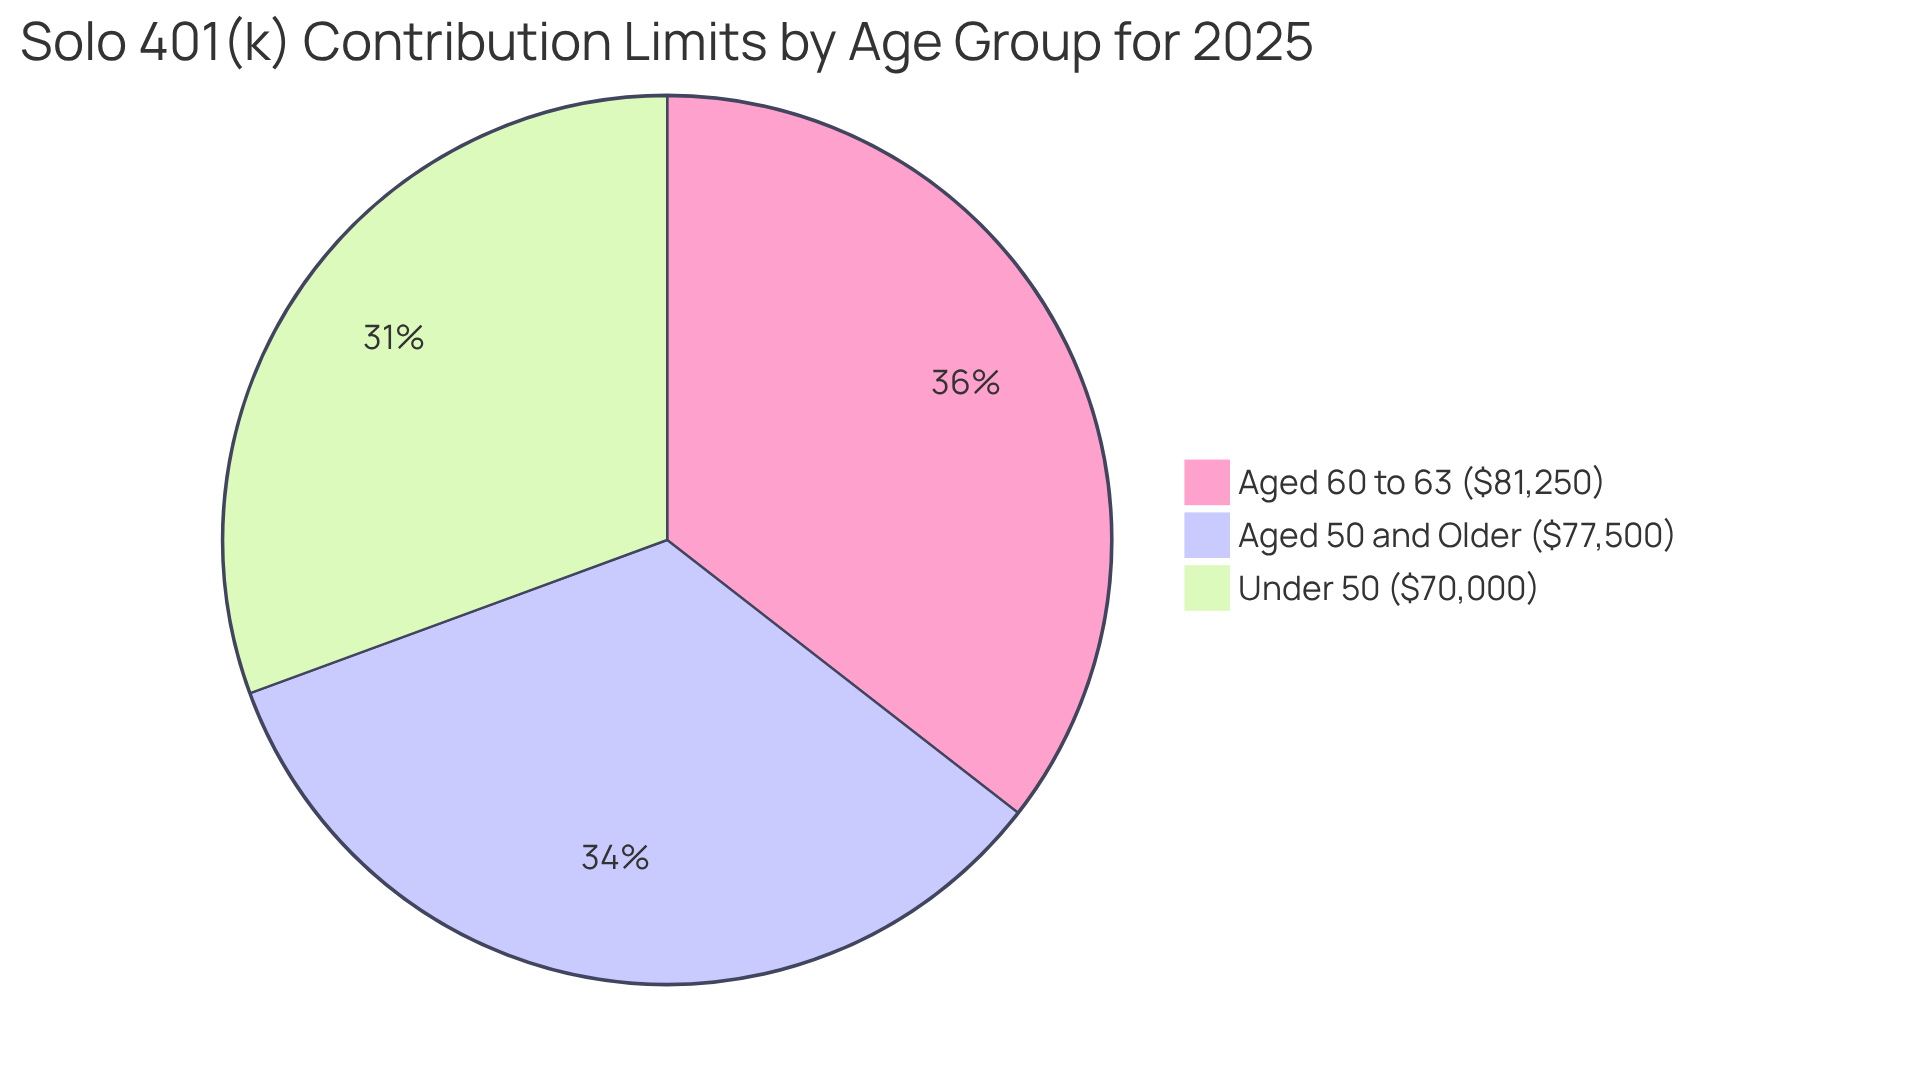
In 2025, for instance, the maximum contribution limit for individuals under 50 is $70,000. Those aged 50 and older can contribute up to $77,500, including catch-up contributions. Notably, individuals aged 60 to 63 have the opportunity to contribute a total of $81,250, further enhancing their savings potential. Each partner can participate in the same individual 401(k) plan with separate accounts, fostering a collaborative approach to retirement planning.
It’s important to understand that pretax employee contributions to an individual 401(k) are tax-deductible, providing additional financial advantages. Employer contributions can be made until the tax filing deadline, including extensions, adding flexibility to the program. This combination of features makes the solo 401k for partnership an appealing choice for partnerships looking to enhance their retirement planning strategies.
Together, we can navigate this journey towards a secure future for your family. We’re here for you, ready to support your financial planning needs.
Explore Key Features of Solo 401(k) Plans
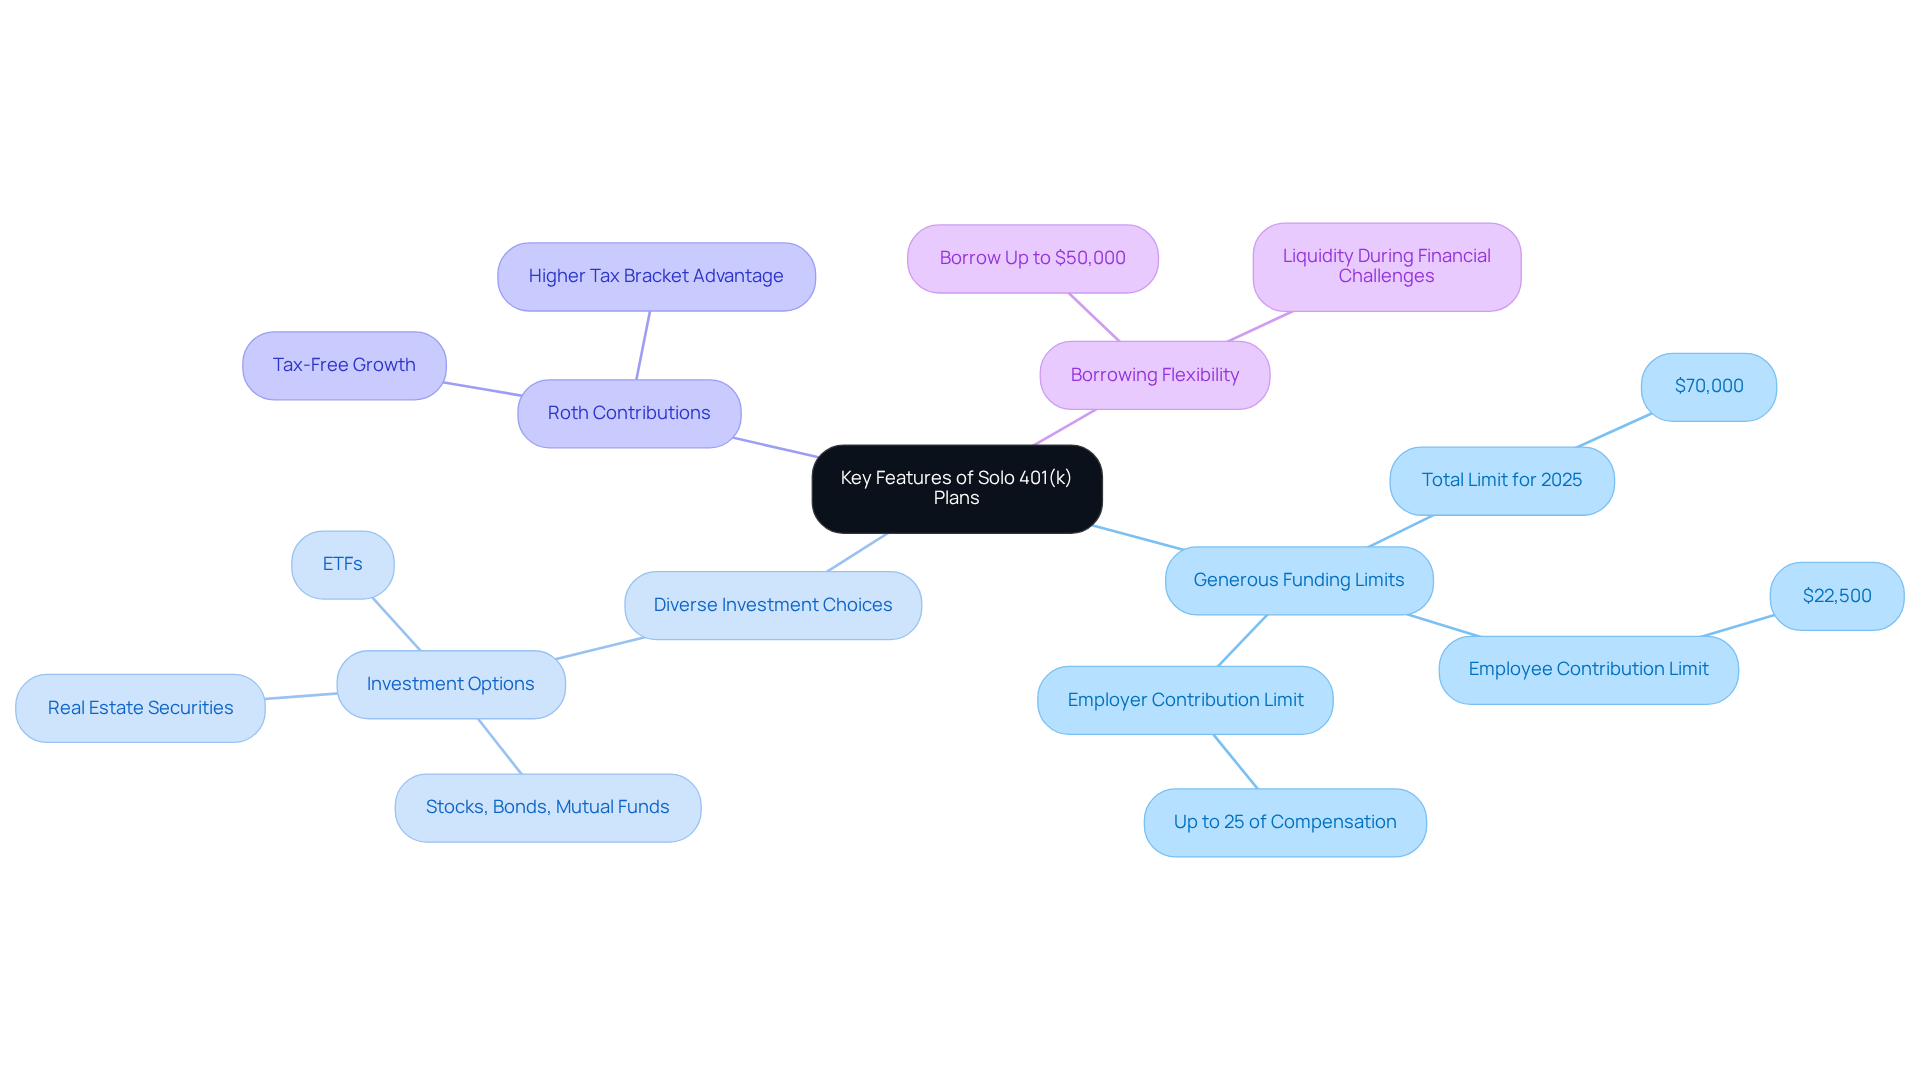
The solo 401k for partnership options stand out with their generous funding limits and diverse investment choices, making them a wonderful choice for self-employed individuals and small business owners. For 2025, the total funding limit is set at $70,000, encompassing both employee deferrals and employer contributions. This structure allows you to significantly boost your retirement savings, which is so important for your family’s future.
Imagine the peace of mind that comes from knowing a portion of 401(k) plans allows for Roth contributions. This means your investments can grow tax-free, which is especially advantageous if you anticipate being in a higher tax bracket during retirement. For young parents like Allison and Brian, who are understandably concerned about their financial well-being, this feature can be a vital part of effective tax planning, helping you optimize your situation with professional guidance.
Additionally, the solo 401k for partnership plans offer the flexibility to borrow against the account, allowing access to up to $50,000. This feature provides crucial liquidity during financial challenges, enhancing the adaptability of your financial strategy. Real-life stories illustrate how self-employed individuals can leverage a solo 401k for partnership to take advantage of these high contribution limits, building substantial retirement funds that ensure a secure financial future for their families.
With these compelling features, 401(k) plans become a powerful ally in your retirement savings journey. They particularly benefit high-income families seeking professional guidance to navigate their financial challenges. Remember, we’re here for you, and together, we can navigate this journey towards a brighter financial future.
Highlight Benefits of Solo 401(k) for Partnerships
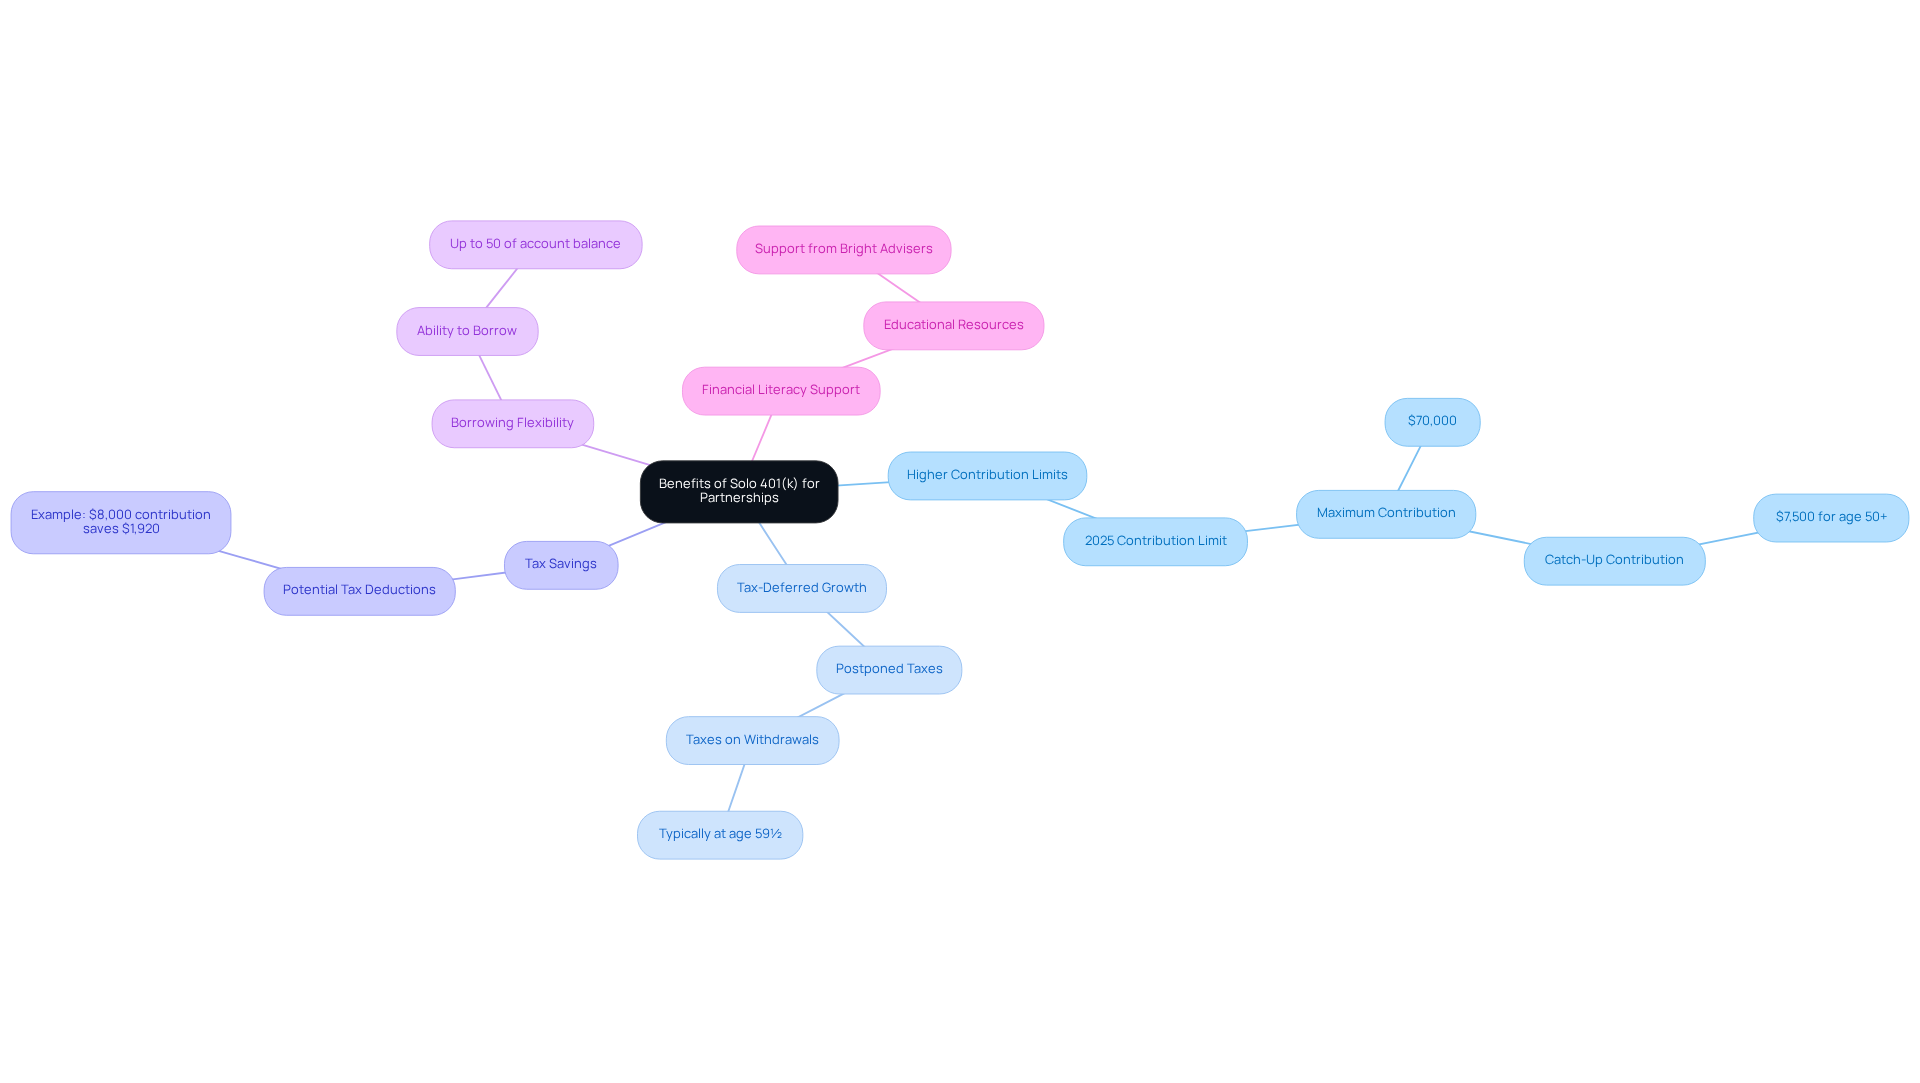
The advantages of a solo 401k for partnership are truly significant, especially for young families striving to enhance their financial security. Imagine having the ability to save more for your future. With savings limits that far exceed those of traditional IRAs or SEP IRAs, a solo 401k for partnership enables partners to set aside a greater amount for retirement. In 2025, self-employed individuals can contribute up to $70,000, along with an additional catch-up payment of $7,500 for those aged 50 and older. This flexibility in a solo 401k for partnership is particularly beneficial for partners with varying incomes, allowing them to adjust their contributions based on their earnings.
It’s important to understand that individual 401(k) accounts offer tax-deferred growth, meaning that taxes on deposits and investment earnings are postponed until withdrawal, typically at age 59½. This can lead to significant savings over time. For instance, contributing $8,000 to a 401(k) plan at a 24% tax rate can save a person approximately $1,920 in taxes. Additionally, the potential for tax deductions on contributions adds to the financial advantages of these plans, making them a smart choice for families.
Furthermore, the ability to borrow from a solo 401k for partnership provides partners with essential financial flexibility, helping them manage cash flow more effectively during challenging times. This feature, not available with SEP IRAs, combined with the robust tax advantages, positions the individual 401(k) as a powerful retirement strategy for young families looking to secure their financial futures.
Together, we can navigate these options with the support of Bright Advisers, who offer tailored wealth management solutions designed to empower families in achieving their financial aspirations. With minimal fund fees and educational resources available, families can enhance their financial literacy while feeling confident in their decisions. We’re here for you, every step of the way.
Understand Eligibility and Contribution Limits
Navigating the world of retirement savings can feel overwhelming, especially for young parents. To qualify for a solo 401k for partnership, it’s essential to know that a partnership must consist solely of partners and their spouses, without any full-time employees beyond these individuals. The good news? Having part-time employees won’t prevent your partnership from setting up a solo 401k for partnership.
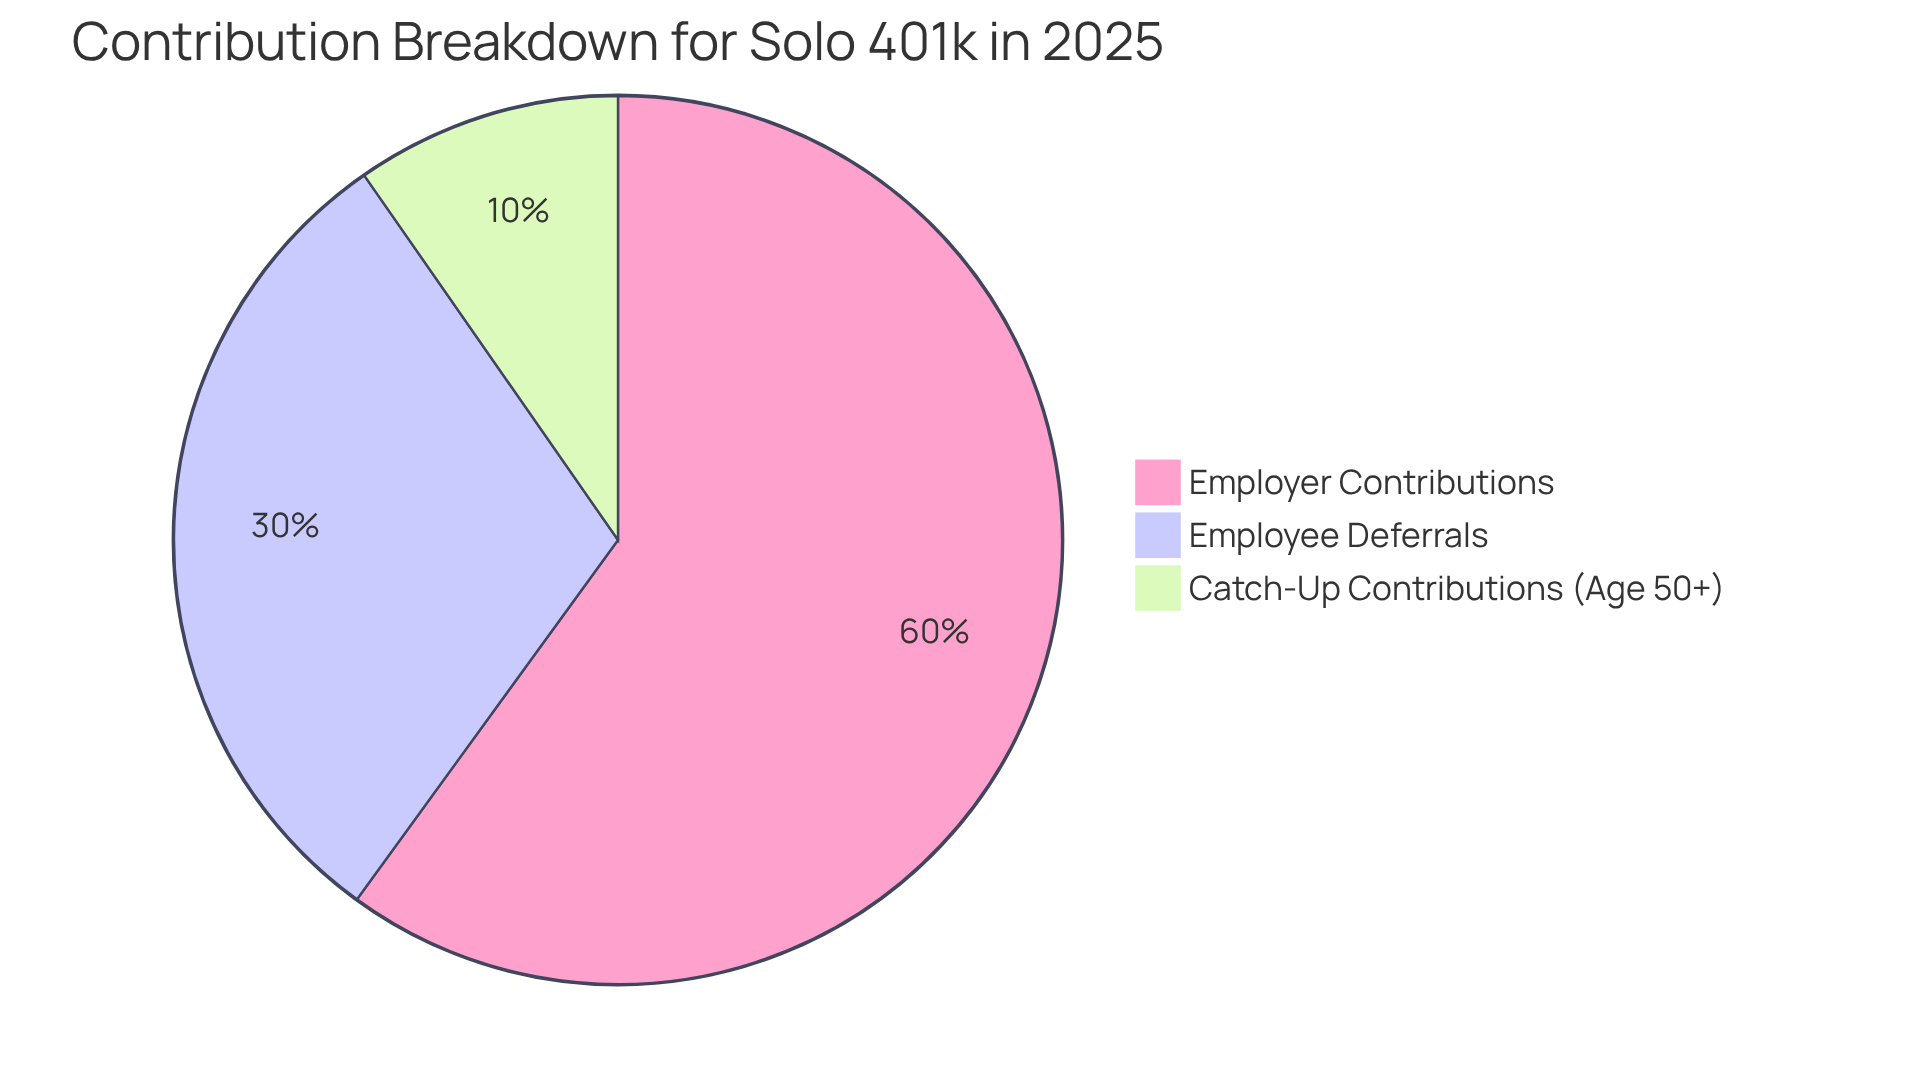
Imagine the possibilities for your family’s future: in 2025, the contribution limits are quite generous, allowing a total of $70,000. This includes employee deferrals of up to $23,500, along with employer inputs that can reach up to $46,500 based on your net earnings or W-2 wages. For those aged 50 and above, there’s even more room to save, with the ability to set aside a total of $31,000, including catch-up payments. This can significantly enhance your overall saving potential.
It’s important to understand that if your 401(k) plan has a minimum of $250,000 in assets, you’ll need to fulfill annual reporting obligations. But don’t worry; we’re here to help you navigate these requirements. Understanding these eligibility criteria and contribution limits, along with the flexibility to combine pre-tax and Roth contributions, is key to optimizing your retirement savings effectively.
Moreover, contributing to a solo 401k for partnership can lead to substantial tax savings, making it a strategic choice for self-employed individuals. Together, we can navigate this journey and ensure that your family’s financial future is secure.
Conclusion
The Solo 401(k) for partnerships presents a thoughtful approach to retirement savings, crafted specifically for self-employed individuals and partners who do not have full-time employees. This distinctive plan not only enables partners to significantly enhance their contributions but also offers meaningful tax benefits and flexibility that traditional retirement accounts often lack. By appreciating the features and advantages of a Solo 401(k), partners can effectively secure their financial futures, enjoying the peace of mind that comes with comprehensive retirement planning.
Imagine this: in 2025, individuals under 50 can contribute up to $70,000, while those aged 50 and older can reach an impressive $77,500. The option to make both pretax and Roth contributions further enriches the tax advantages, allowing for tax-deferred growth and potential savings on future tax liabilities. Plus, the ability to borrow against the account introduces a layer of financial flexibility that can be vital during challenging times.
Ultimately, embracing the Solo 401(k) for partnerships transcends mere retirement savings; it empowers families to take charge of their financial destinies. By leveraging this robust retirement strategy, partners can build a secure future for their loved ones. If you’re interested in exploring this opportunity, remember that seeking professional guidance can help you navigate the intricacies of eligibility and contribution limits, ensuring you make the most of this valuable financial tool. We’re here for you, ready to support you on this journey.
Frequently Asked Questions
What is a Solo 401(k) for partnerships?
A Solo 401(k) for partnerships is a retirement savings strategy specifically designed for self-employed individuals or business owners who are partners in a partnership. It is tailored for businesses with no full-time employees other than the owners or their spouses.
How does a Solo 401(k) differ from traditional 401(k) plans?
Unlike traditional 401(k) plans that cater to multiple employees, a Solo 401(k) is crafted specifically for partnerships with only the owners or their spouses as employees, allowing for higher contribution limits.
What are the maximum contribution limits for a Solo 401(k) in 2025?
In 2025, the maximum contribution limit for individuals under 50 is $70,000. Those aged 50 and older can contribute up to $77,500, including catch-up contributions. Individuals aged 60 to 63 can contribute a total of $81,250.
Can multiple partners participate in a Solo 401(k)?
Yes, each partner can participate in the same individual 401(k) plan with separate accounts, allowing for a collaborative approach to retirement planning.
Are pretax employee contributions to a Solo 401(k) tax-deductible?
Yes, pretax employee contributions to an individual 401(k) are tax-deductible, providing additional financial benefits.
When can employer contributions be made to a Solo 401(k)?
Employer contributions can be made until the tax filing deadline, including extensions, offering flexibility in the contribution process.
Why is a Solo 401(k) for partnerships considered an appealing retirement planning choice?
The combination of higher contribution limits, tax-deductible employee contributions, and flexible employer contributions makes the Solo 401(k) an attractive option for partnerships looking to enhance their retirement planning strategies.
List of Sources
- Define Solo 401(k) for Partnerships
- Solo 401(k) contribution limits 2024 and 2025 | Fidelity (https://fidelity.com/learning-center/smart-money/solo-401k-contribution-limits)
- Solo 401k contribution for partnership and compensation (https://mysolo401k.net/solo-401k/solo-401k-contribution-partnership-compensation)
- The Ultimate Guide to Solo 401(k)s | Guideline (https://guideline.com/education/articles/the-ultimate-guide-to-solo-401ks)
- 2025 Solo 401(k) Contribution Limits – IRA Financial (https://irafinancial.com/blog/what-are-the-solo-401k-contribution-limits)
- 401(k) Retirement Plans: A comprehensive guide for NRIs in the US (https://m.economictimes.com/nri/invest/401k-retirement-plans-a-comprehensive-guide-for-nris-in-the-us/articleshow/111800502.cms)
- Explore Key Features of Solo 401(k) Plans
- 50+ Important 401k Statistics for Companies and Employees in 2025 | Shortlister (https://myshortlister.com/insights/401k-statistics)
- Solo 401(k) Eligibility: Do You Qualify? | Human Interest (https://humaninterest.com/learn/articles/do-you-qualify-for-a-self-employed-401k)
- One Participant 401k Plans | Internal Revenue Service (https://irs.gov/retirement-plans/one-participant-401k-plans)
- Roth Solo 401(k) Plans: What You Need to Know – Capitalize (https://hicapitalize.com/resources/solo-roth-401k)
- 48 Interesting 401k Plan Statistics For 2023 – Carry (https://carry.com/learn/401k-statistics)
- Highlight Benefits of Solo 401(k) for Partnerships
- Solo 401(k) vs. SEP IRA: A comprehensive comparison (https://businessinsider.com/personal-finance/investing/solo-401k-vs-sep-ira)
- Are 401(k) Contributions Tax Deductible? – Intuit TurboTax Blog (https://blog.turbotax.intuit.com/income-and-investments/401k-ira-stocks/can-you-deduct-401k-savings-from-your-taxes-7169)
- Small Employers’ Economics of Offering Retirement Savings Plans (https://pew.org/en/research-and-analysis/issue-briefs/2024/07/small-employers-economics-of-offering-retirement-savings-plans)
- American Retirement and Tax-Preferred Savings Accounts, Tax Year 2018 (https://taxfoundation.org/data/all/federal/401k-ira-retirement-savings-accounts)
- How a Solo 401(k) Is Taxed and What Is Deductible? (https://smartasset.com/taxes/solo-401k-tax-deduction)
- Understand Eligibility and Contribution Limits
- Solo 401(k) 2024 and 2025 Contribution Limits | The Motley Fool (https://fool.com/retirement/plans/solo-401k/contribution-limits)
- Solo 401(k) Contribution Limits (https://smartasset.com/retirement/how-much-can-i-contribute-to-my-solo-401k)
- IRS Raises 401(k) Contribution Limits for 2025 | Paychex (https://paychex.com/articles/employee-benefits/annual-401k-contribution-limits)
- Solo 401(k) contribution limits 2024 and 2025 | Fidelity (https://fidelity.com/learning-center/smart-money/solo-401k-contribution-limits)
- Maximize Your Retirement: 2025 Solo 401k Contribution Limits Explained – Solo 401k (https://solo401k.com/contributions/2025-solo-401k-contribution-limits)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About Kevin