

Key Highlights:
- The stepped-up tax basis adjusts the cost basis of inherited assets to their fair market value at the time of the original owner’s death.
- This adjustment allows heirs to avoid capital gains taxes on appreciation that occurred during the deceased’s lifetime.
- Example: If a home bought for $500,000 appreciates to $800,000, heirs inherit it at $800,000, avoiding taxes on the $300,000 gain.
- In community property states, surviving spouses can benefit from a double step-up in valuation, enhancing wealth retention.
- Understanding which assets qualify for the stepped-up basis is crucial for effective estate planning and tax liability management.
- Heirs can save significant amounts in capital gains taxes, allowing for reinvestment into family needs like education and retirement.
- Utilising trusts can further enhance the benefits of the stepped-up basis, simplifying asset transfers and tax implications.
- Proactive estate planning and collaboration with financial advisors are essential for maximising the benefits of the stepped-up tax basis.
Introduction
Navigating the world of tax provisions can feel overwhelming, especially for young families striving to secure their financial futures. Imagine if you could understand a crucial concept that could make a significant difference: the stepped-up tax basis. This provision allows heirs to inherit assets at their current market value, effectively shielding them from capital gains taxes on any appreciation that occurred during the previous owner’s lifetime.
This advantage not only helps preserve wealth but also opens doors to better financial planning for future generations. However, many families remain unaware of how this provision works and the profound impact it can have on their financial legacy. It’s important to understand how families can leverage this tax strategy to ensure a more secure and prosperous future.
Together, we can navigate this journey, ensuring that your family’s financial well-being is prioritized. We’re here for you, ready to help you explore the benefits of understanding tax provisions and how they can support your family’s goals.
Define Step-Up in Basis and Its Importance for Families
It is essential for families, especially those with young children, to understand the stepped up tax basis. This important tax provision provides a stepped up tax basis for inherited assets, adjusting their cost basis to the fair market value at the time of the original owner’s death. Imagine not having to worry about [capital gains taxes](https://investopedia.com/terms/s/stepupinbasis.asp) on any appreciation that occurred during your loved one’s lifetime. This means that when you inherit wealth, you can preserve more of it for future generations, easing the financial burden on your family.
Consider this: if parents bought a home for $500,000 and it appreciated to $800,000 at the time of their passing, the heirs inherit the property valued at $800,000. If they sell it for that amount, they won’t owe any capital gains tax on the $300,000 increase because of the stepped up tax basis. This provision can make a significant difference in how families manage their financial futures.
Take the story of Allison and Brian, for instance. They wanted to maximize their financial potential while ensuring their children’s future. By working with Bright Advisers, they minimized their tax liabilities and secured funds for their kids’ education. This not only provided peace of mind but also allowed them to cherish quality time with their loved ones. In another scenario, a parent who purchased stock for $50,000 that grew to $125,000 at death allows the heirs to inherit it at the stepped up tax basis of $125,000. If they sell it for $100,000, they owe no capital gains tax because the difference between the sale price and the stepped up tax basis is $0. This strategic advantage is invaluable for families looking to build a lasting financial legacy.
In community property states, the benefits are even greater. Surviving spouses can receive a double step-up in valuation on community property, enhancing wealth retention. As families navigate the complexities of financial planning, understanding the implications of the stepped up tax basis is vital for safeguarding their financial future and creating a lasting legacy.
Together, we can navigate this journey, ensuring that your family’s financial well-being is prioritized. We’re here for you, ready to help you make that resonate with your family values.

Explain How Step-Up in Basis Works: Calculation and Asset Types
Understanding the step-up in value calculation can feel overwhelming, but it’s a straightforward process that can significantly benefit your family. When an asset is inherited, its value is adjusted to its (FMV) on the date of the decedent’s death. Imagine if a parent bought a house for $200,000, and at the time of their passing, it’s assessed at $500,000. In this case, the beneficiary’s value in the home becomes $500,000. This adjustment applies to various asset types, including real estate, stocks, bonds, and mutual funds.
It’s essential for families to understand which assets qualify for this adjustment, as it can greatly impact your estate planning strategies and tax liabilities. The good news? Heirs can save thousands or even millions in capital gains taxes due to the stepped up tax basis rule. This rule allows them to only pay taxes on appreciation that occurs after the inheritance. According to the Congressional Budget Office, more than half of the benefits from the step-up in value go to the top 5% of earners, highlighting the importance of this regulation in wealth transfer.
In community property states, both portions of jointly owned assets receive a complete step-up in value. This not only enhances tax efficiency for surviving spouses but also simplifies tax reporting for heirs. It’s a way to preserve assets with significant appreciation potential, allowing families to utilize the stepped up tax basis to reduce future tax responsibilities.
As tax laws evolve, it’s important to stay informed about potential changes that could affect the implementation of the stepped up tax basis valuation rule. Together, we can navigate this journey, ensuring you make the most informed choices in your estate planning. Remember, we’re here for you, ready to support you every step of the way.
Discuss the Impact of Step-Up in Basis on Capital Gains Taxes and Family Wealth
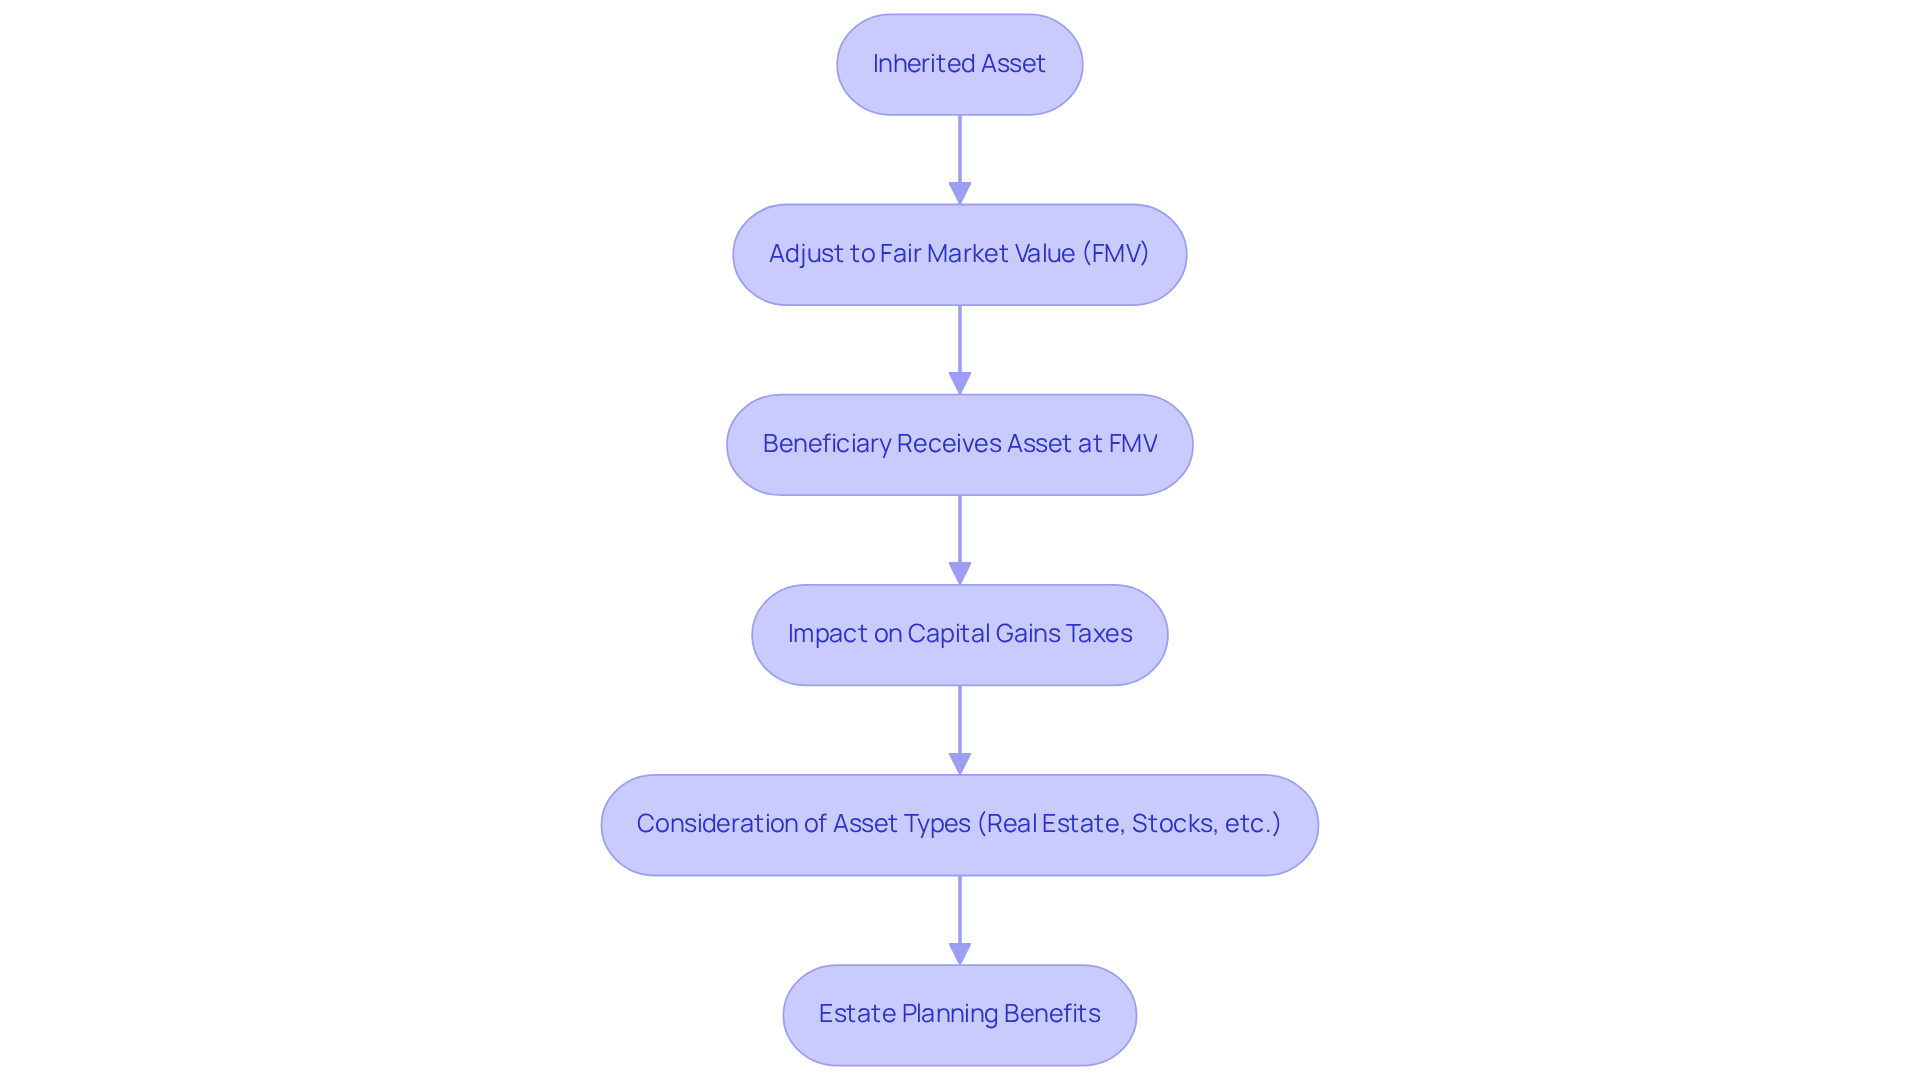
Imagine if you could save significantly on taxes when passing on your family’s wealth. The increase in valuation can greatly affect capital profits, providing considerable savings for heirs. When inherited assets are sold, taxes are only applied to the . For instance, if a house is sold for $550,000, the taxable profit would be determined using the stepped up tax basis, resulting in a taxable gain of just $50,000, instead of $350,000 if the initial purchase price were applied.
This tax efficiency not only helps preserve your family’s wealth but also allows you to reinvest those savings into your future. Think about financing your children’s education or enhancing your retirement savings. A case study of Allison and Brian illustrates this point effectively. Through their collaboration with Bright Advisers, they implemented strategic tax planning methodologies that optimized their tax situation, secured their children’s future through education funding, and gained the ability to retire sooner.
By understanding and utilizing the stepped up tax basis, families can effectively manage their tax obligations and enhance their financial legacy. We’re here for you, ready to help you navigate this journey toward a secure future for your loved ones.
Utilize Step-Up in Basis in Estate Planning for Long-Term Family Benefits
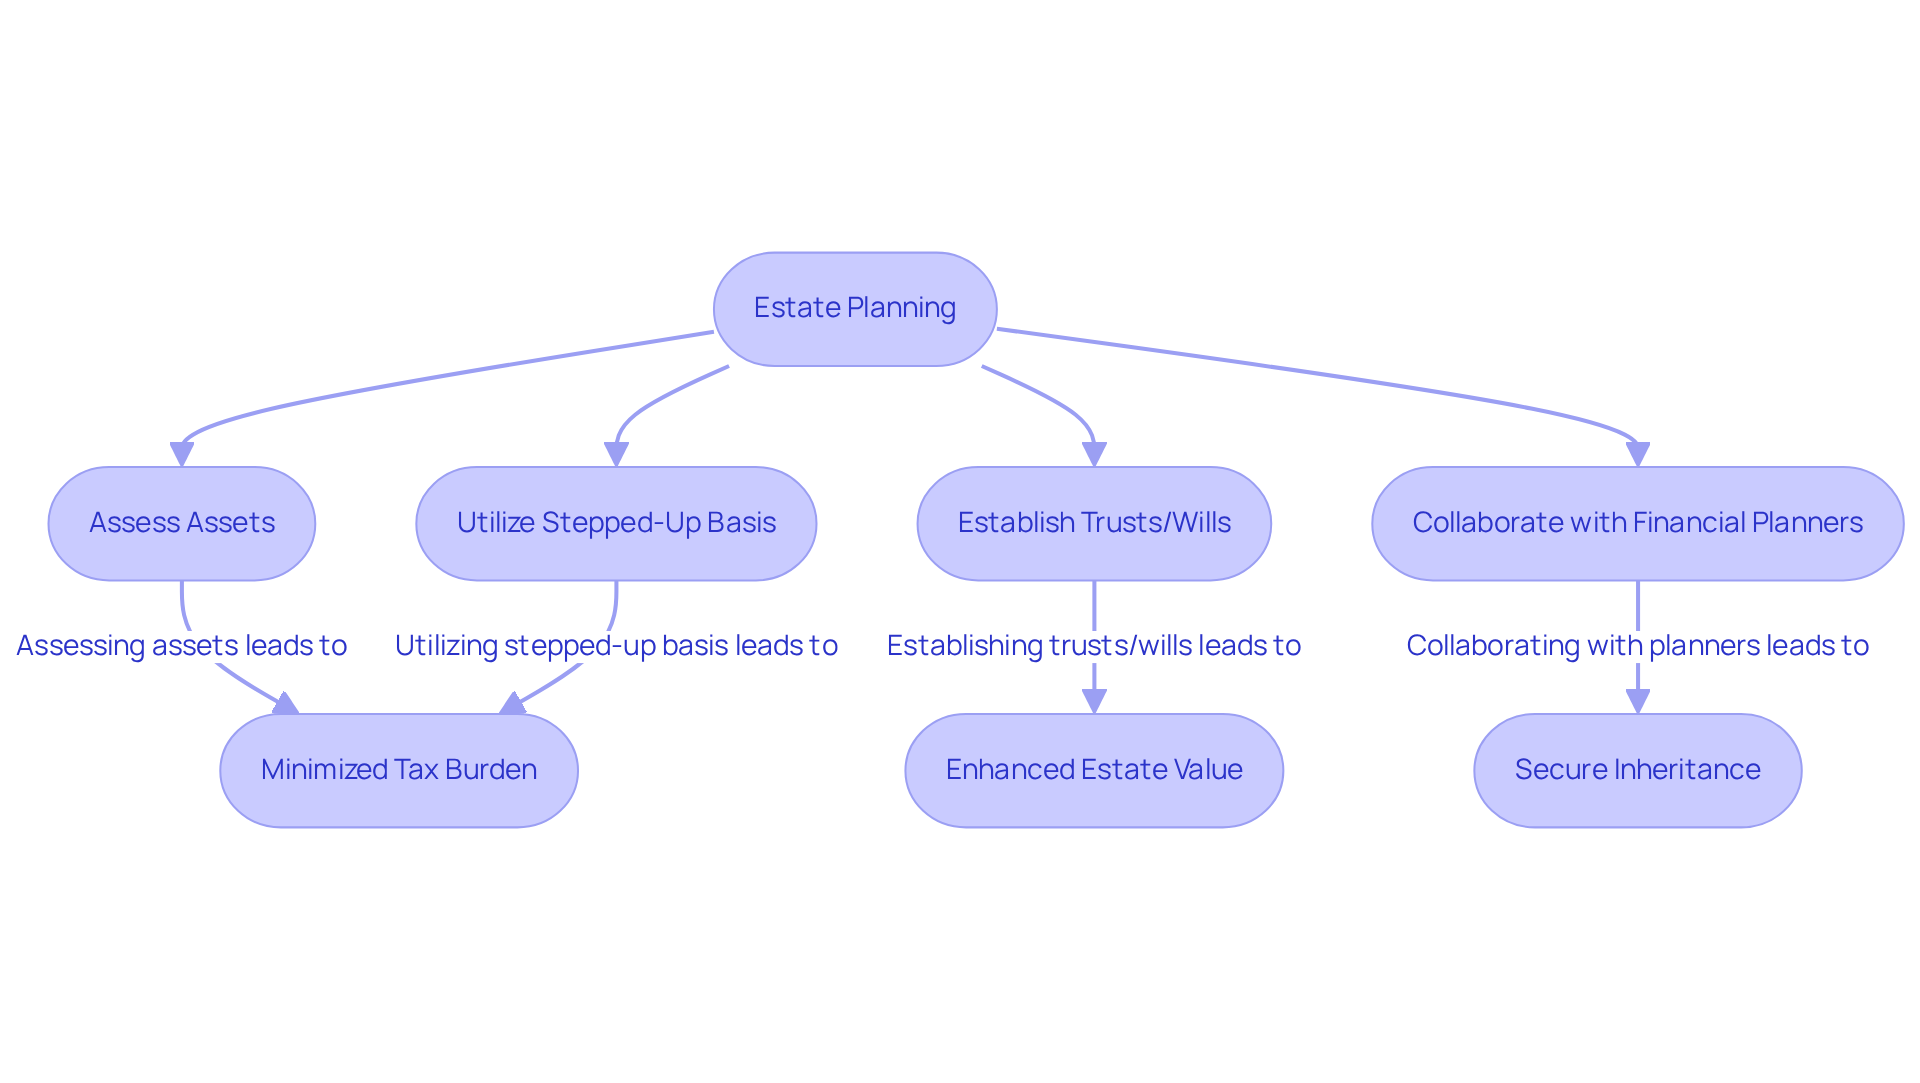
Navigating estate planning can feel overwhelming, especially for young parents. But imagine if you could secure your family’s future while minimizing tax burdens. By embracing the stepped up tax basis, you can create a solid foundation for your loved ones. Regularly assessing your assets and keeping detailed records of purchase prices and improvements is essential. This information will be invaluable for your beneficiaries, ensuring they understand the value of what they inherit.
Consider this: families that utilize trusts can significantly enhance their estate’s value while reducing tax liabilities. For example, a couple placed their $800,000 home into a revocable living trust. This allowed their heirs to sell the property without facing capital gains tax on the appreciated value, simplifying the transfer process. Without this adjusted valuation, a $300,000 profit would incur a hefty capital gains tax if sold at its current worth.
It’s also crucial to collaborate with [financial planners at Bright Advisers](https://brightadvisers.com/about) to establish wills or trusts that clearly outline how your assets will be distributed. This clarity helps your heirs understand the tax implications of their inheritances. Statistics show that households using trusts for estate planning can maximize the benefits of the stepped up tax basis. For instance, paying $7,500 in total taxes on a $50,000 capital gain is significantly less than the $18,750 owed on a $125,000 gain without the stepped-up basis.
By proactively planning and utilizing these strategies, you can secure a more stable financial future for your children, enhancing your legacy. However, it’s important to consider the potential risks of adding children to the deed, as this can complicate ownership and may not yield the desired tax benefits. At Bright Advisers, we’re here to help families navigate these complexities, ensuring your financial planning aligns with your long-term goals and values, including risk management and generational gifting strategies.
Together, we can navigate this journey, ensuring your .
Conclusion
Understanding the stepped-up tax basis is essential for families, especially those with young children. This provision can significantly influence your financial planning and wealth preservation. It allows inherited assets to be valued at their fair market value at the time of the original owner’s death. This effectively shields heirs from capital gains taxes on any appreciation that occurred during the decedent’s lifetime. By grasping this concept, families can navigate their financial futures more confidently and create a legacy that benefits future generations.
Imagine if you could pass on your hard-earned assets without the burden of unexpected taxes. The article highlights several key aspects of the stepped-up tax basis, including:
- How it’s calculated
- The types of assets that qualify
- Its profound impact on capital gains taxes
Real-life examples, like the stories of Allison and Brian, show how strategic tax planning can lead to substantial savings and enhanced financial security. In community property states, the advantages are even greater, as surviving spouses can benefit from a double step-up in asset valuation. This further emphasizes the importance of understanding this tax provision.
Ultimately, leveraging the stepped-up tax basis is a powerful strategy for families looking to secure their financial well-being. By proactively engaging in estate planning and collaborating with financial experts, you can ensure that you maximize the benefits of this tax provision. As tax laws evolve, staying informed and making thoughtful decisions becomes increasingly vital. Embracing these strategies not only safeguards your current wealth but also lays the groundwork for a prosperous future. This allows families to invest in education, retirement, and other essential areas of life.
Together, we can navigate this journey. We’re here for you, ready to support you in making informed choices that resonate with your family values.
Frequently Asked Questions
What is a stepped-up basis in taxation?
A stepped-up basis is a tax provision that adjusts the cost basis of inherited assets to their fair market value at the time of the original owner’s death, allowing heirs to avoid capital gains taxes on any appreciation that occurred during the owner’s lifetime.
Why is understanding the stepped-up basis important for families?
Understanding the stepped-up basis is important for families, especially those with young children, as it helps preserve wealth for future generations and eases the financial burden on the family by minimizing tax liabilities on inherited assets.
Can you provide an example of how the stepped-up basis works with real estate?
If parents bought a home for $500,000 and it appreciated to $800,000 at the time of their passing, the heirs inherit the property valued at $800,000. If they sell it for that amount, they won’t owe any capital gains tax on the $300,000 increase due to the stepped-up basis.
How does the stepped-up basis apply to stocks?
For example, if a parent purchased stock for $50,000 that grew to $125,000 at death, the heirs inherit it at a stepped-up basis of $125,000. If they sell it for $100,000, they owe no capital gains tax because the difference between the sale price and the stepped-up basis is $0.
What additional benefits does the stepped-up basis provide in community property states?
In community property states, surviving spouses can receive a double step-up in valuation on community property, which enhances wealth retention and provides greater financial advantages for families.
How can families navigate financial planning with respect to the stepped-up basis?
Families can navigate financial planning by understanding the implications of the stepped-up basis, which is vital for safeguarding their financial future and creating a lasting legacy. Seeking professional advice can also help in making informed decisions aligned with family values.
List of Sources
- Define Step-Up in Basis and Its Importance for Families
- Step-Up in Basis: Definition and How It Works for Inherited Property (https://investopedia.com/terms/s/stepupinbasis.asp)
- All About the Stepped-Up Basis Loophole (https://smartasset.com/financial-advisor/stepped-up-basis)
- “Step-Up in Basis” for Inherited Assets Explained (https://sdmayer.com/resources/step-up-in-basis)
- Maximizing Tax Benefits with the Stepped-Up Basis in Estate Planning (https://llklaw.com/legal-blog/understanding-the-stepped-up-tax-basis-and-how-estate-planning-can-maximize-its-benefits)
- “Step Up” Your Estate Planning Game (https://merceradvisors.com/insights/trust-estate/step-up-your-estate-planning-game)
- Explain How Step-Up in Basis Works: Calculation and Asset Types
- Step-Up in Basis: Definition and How It Works for Inherited Property (https://investopedia.com/terms/s/stepupinbasis.asp)
- What is step-in basis and how can it affect me?| Fidelity (https://fidelity.com/learning-center/personal-finance/what-is-step-up-in-basis)
- Understanding Stepped-Up Basis: A Guide (https://jec-llc.com/blog/understanding-stepped-up-basis-a-guide-for-heirs)
- Discuss the Impact of Step-Up in Basis on Capital Gains Taxes and Family Wealth
- What Is Stepped-Up Basis on Capital Gains and How Does It Affect the Federal Budget? (https://pgpf.org/article/what-is-the-stepped-up-basis-and-how-does-it-affect-the-federal-budget)
- Paying the 2025 Tax Bill: Step Up in Basis and Securities-Backed Lines of Credit (https://bipartisanpolicy.org/explainer/paying-the-2025-tax-bill-step-up-in-basis-and-securities-backed-lines-of-credit)
- Step-Up in Basis: Definition and How It Works for Inherited Property (https://investopedia.com/terms/s/stepupinbasis.asp)
- What the End of Step-Up in Basis Could Mean for Your Heirs | Avidian Wealth Solutions (https://avidianwealth.com/financial-insights/articles/end-of-step-up-in-basis-meaning-for-heirs)
- Utilize Step-Up in Basis in Estate Planning for Long-Term Family Benefits
- Maximizing Tax Benefits with the Stepped-Up Basis in Estate Planning (https://llklaw.com/legal-blog/understanding-the-stepped-up-tax-basis-and-how-estate-planning-can-maximize-its-benefits)
- Case Study: Retirees – Mariaca Wealth Management (https://mariacawealth.com/case_studies/retirees)
- “Step Up” Your Estate Planning Game (https://merceradvisors.com/insights/trust-estate/step-up-your-estate-planning-game)
- Estate Planning: Stepped-Up Tax Basis | Center for Agricultural Profitability | Nebraska (https://cap.unl.edu/news/estate-planning-stepped-tax-basis)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading