

Key Highlights:
- Homeownership offers significant tax benefits that can ease financial burdens for young families.
- Mortgage interest deduction allows homeowners to deduct interest on loans up to $750,000, potentially saving thousands.
- Property tax deduction enables homeowners to deduct state and local property taxes, capped at $10,000 for joint filers.
- Energy-efficient home improvements can qualify for tax credits up to $3,200, promoting sustainable living while providing financial relief.
- Capital gains exclusion permits homeowners to exclude up to $500,000 in gains when selling their primary residence, benefiting family investments.
- Maintaining organised records of home-related expenses simplifies the process of claiming deductions and maximising savings.
- Consulting a tax professional can help homeowners navigate tax laws and optimise deductions effectively.
- Staying informed about tax changes is crucial for maximising available benefits and savings.
- Investing in energy efficiency upgrades can lower utility bills and qualify for IRS incentives, benefiting overall family finances.
- Understanding capital gains exclusions is essential for planning future home sales and enhancing financial returns.
Introduction
Navigating the complexities of homeownership can feel overwhelming, especially for young families. But it also opens the door to financial relief through various tax benefits. Imagine being able to reduce your tax liabilities and redirect those funds toward what truly matters – your children’s education and healthcare.
It’s important to understand the deductions and credits available to you. By grasping these advantages, you can make informed decisions that positively impact your family’s financial future. What strategies can you employ to maximize your savings and secure a brighter tomorrow through homeownership?
Together, we can explore these opportunities. We’re here for you, ready to guide you through the process and help you make the most of your homeownership journey. Let’s take this step together, ensuring that your family’s needs are met while building a solid financial foundation.
Defining Tax Benefits of Homeownership
Unlocking the Tax Benefits of Homeownership: A Guide for Young Families
Navigating the world of homeownership can feel overwhelming, especially for young families. But did you know that the tax benefits of buying a house are designed to ease your financial burden? These deductions and credits can significantly reduce your taxable income and overall tax liability, making homeownership more attainable. Understanding the tax benefits of buying a house is essential as you balance budgeting with the joys and challenges of raising children.
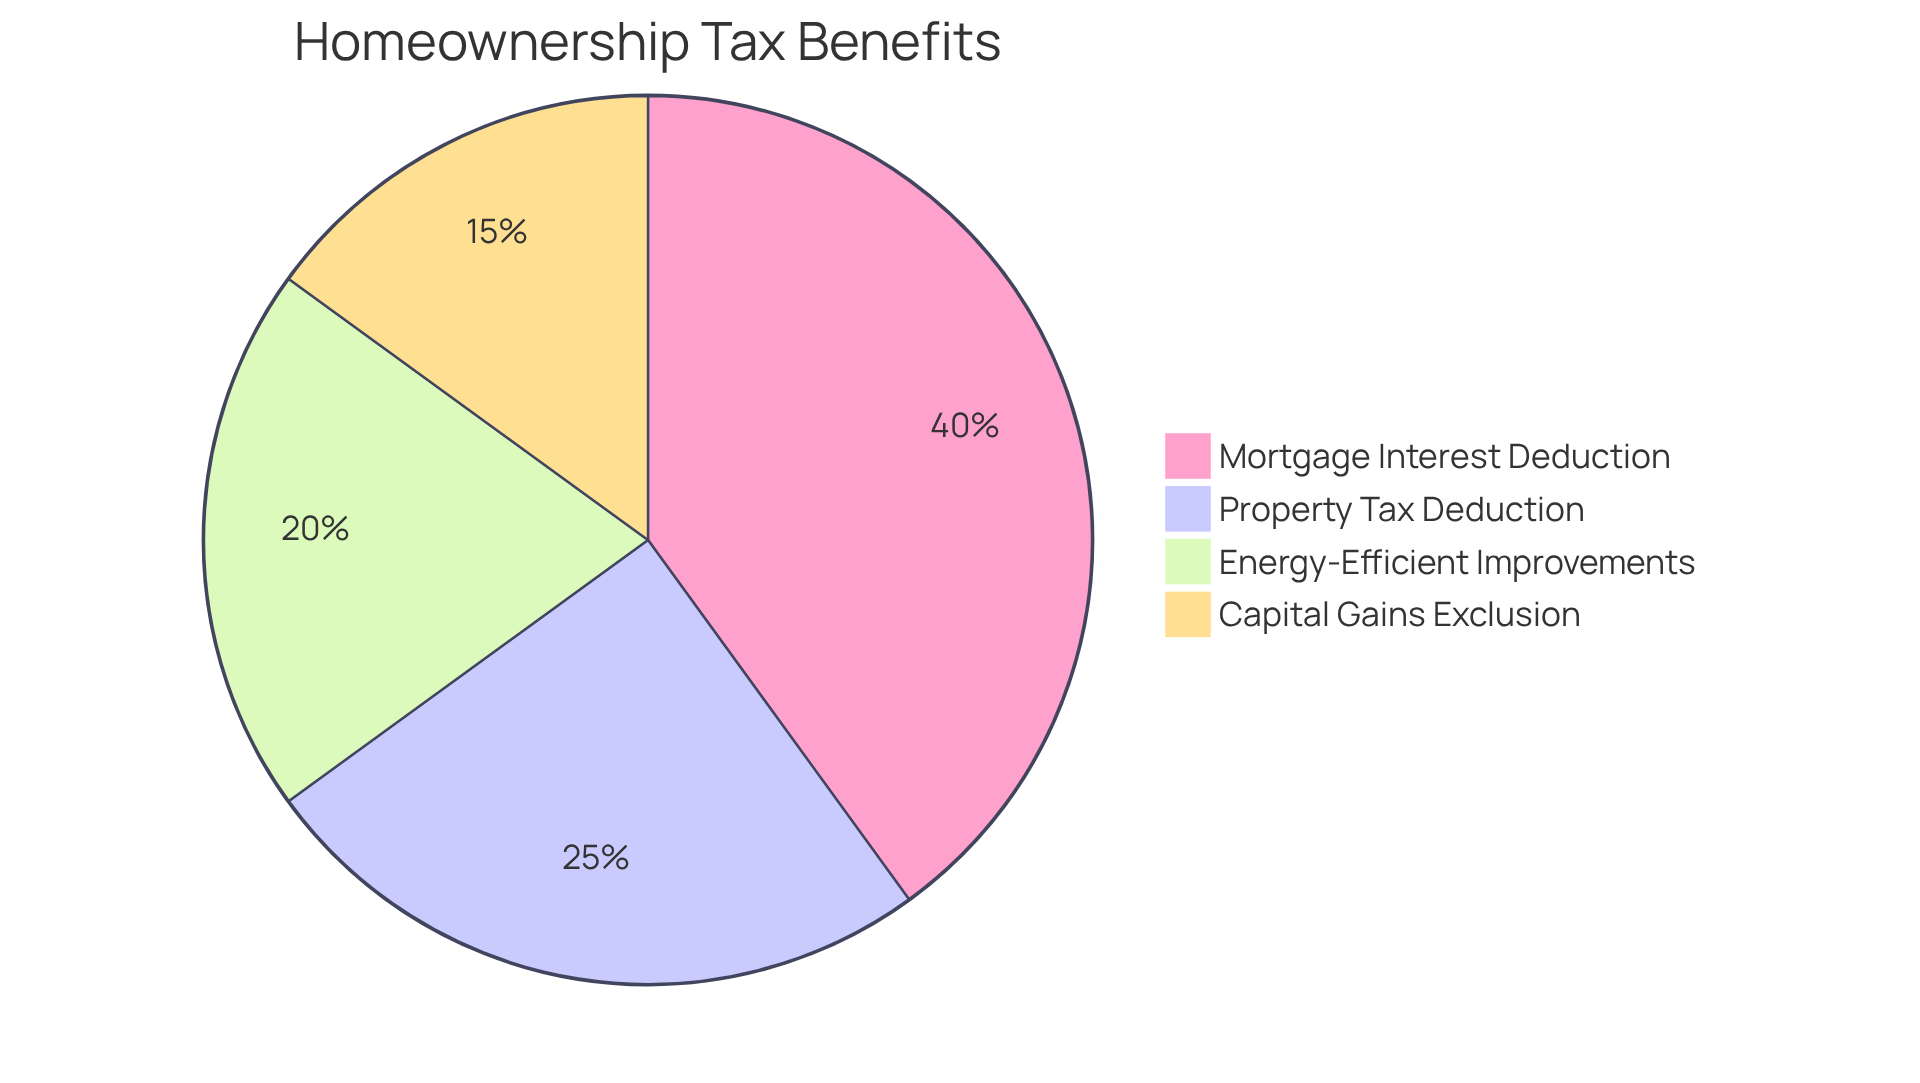
- Mortgage Interest Deduction
Imagine saving money just by owning a home! Homeowners can deduct interest on mortgage loans up to $750,000, leading to substantial savings. For instance, the first 12 months of interest on a $750,000 mortgage at a 6.5% interest rate amounts to approximately $48,503. That’s money you can redirect toward your family’s needs! - Property Tax Deduction
Every little bit helps, right? Homeowners can also deduct state and local property taxes, capped at $10,000 for single filers and married couples filing jointly. This deduction lowers your taxable income and demonstrates the tax benefits of buying a house, providing additional economic relief that can make a real difference in your household budget. - Energy-Efficient Home Improvements
Thinking about making your home more energy-efficient? You can claim like solar panels or energy-efficient windows, with credits reaching up to $3,200. Not only do these improvements help the environment, but they also lighten your financial load! - Capital Gains Exclusion
When it’s time to sell your primary residence, you may exclude up to $500,000 in capital gains for married couples. This significant benefit enhances the financial rewards of homeownership, allowing you to invest more in your family’s future.
Real-world examples demonstrate the significant impact of the tax benefits of buying a house. For instance, a household that invests in energy-saving enhancements not only lowers their utility expenses but also benefits from tax incentives that help cover the costs of these upgrades. Plus, families utilizing the mortgage credit certificate program can receive a tax credit of up to $2,000, directly reducing their tax bills and making homeownership even more affordable.
Experts emphasize the significance of the tax benefits of buying a house for families with children. Understanding and utilizing the tax benefits of buying a house can lead to substantial savings, enabling you to allocate more resources toward your children’s needs and future.
In conclusion, the tax benefits of buying a house available to homeowners in 2025 present a valuable opportunity for young families to enhance their financial stability. Remember, you’re not alone in this journey. Together, we can navigate these financial waters and build a brighter future for your family.
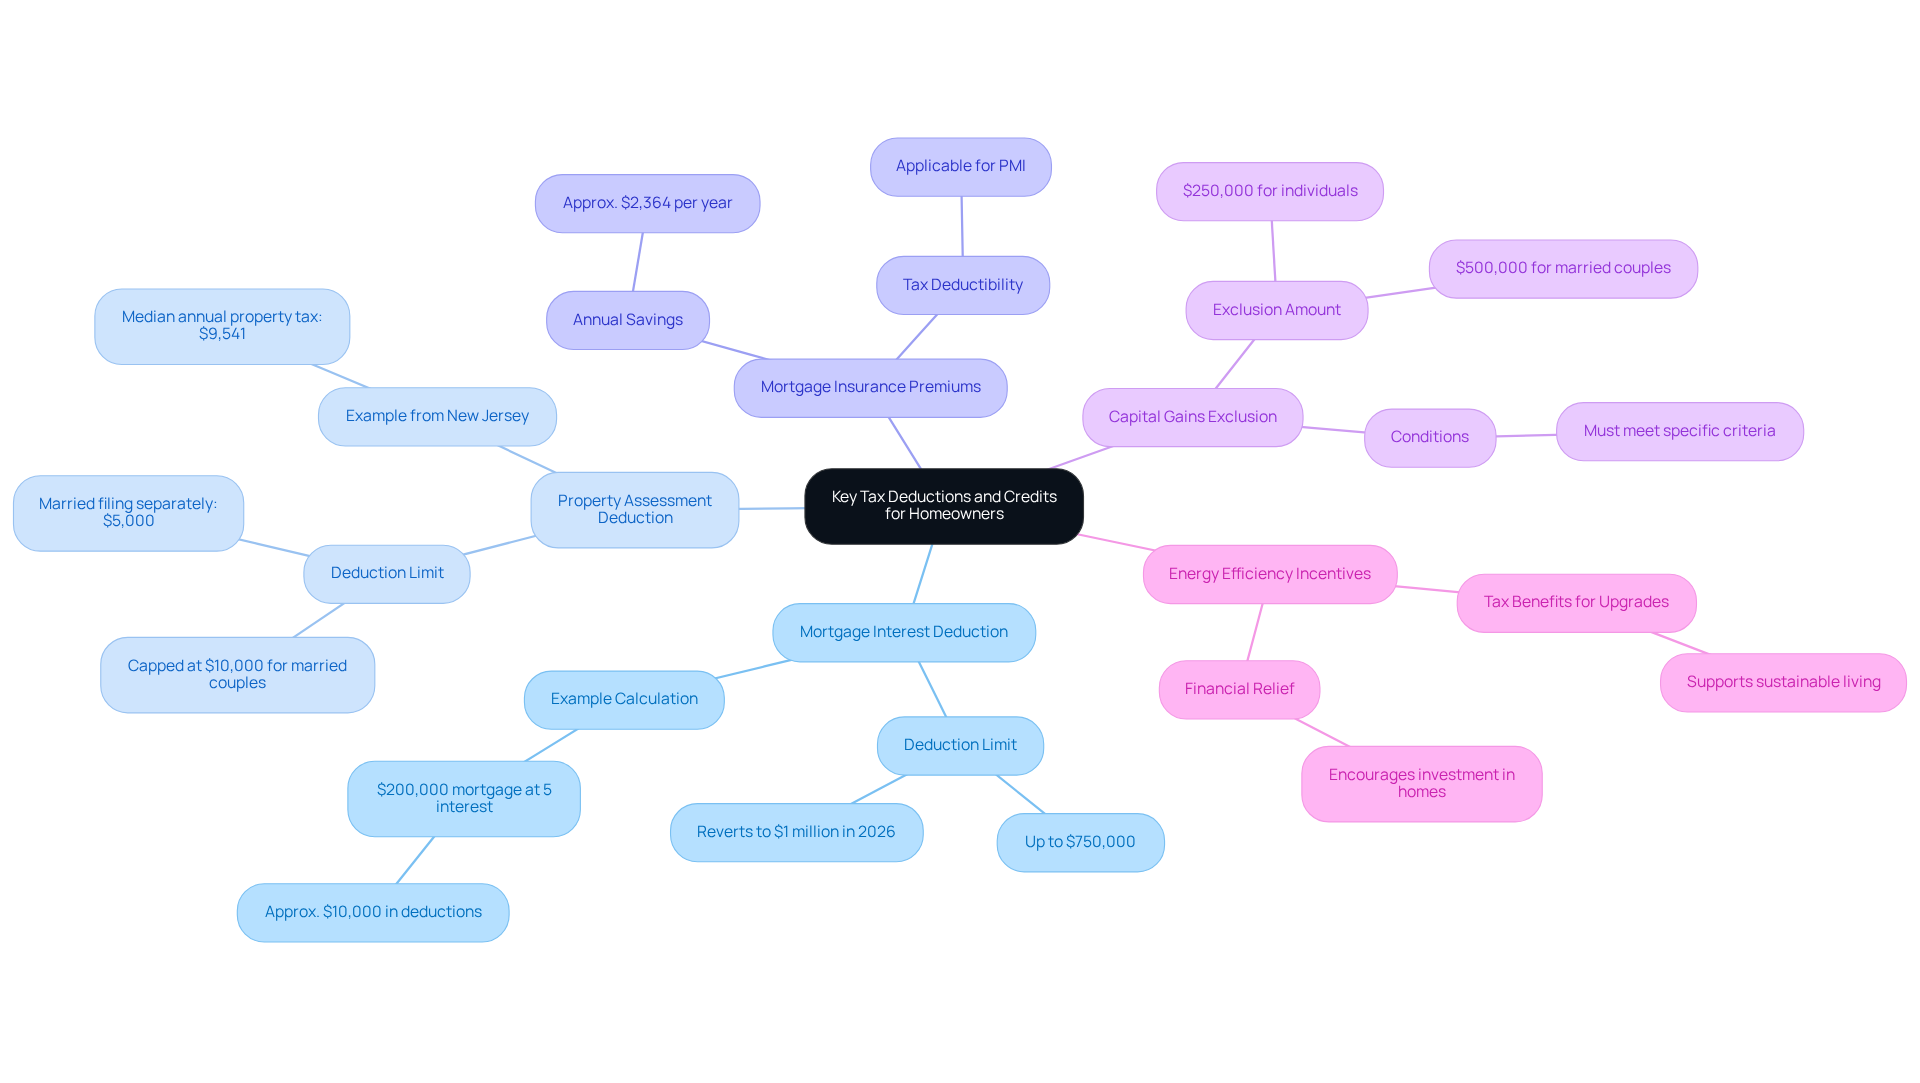
Key Tax Deductions and Credits for Homeowners
Homeowners, especially young families, can truly benefit from the [tax benefits of buying a house](https://irs.gov/newsroom/tax-benefits-for-homeowners), which include several key tax deductions and credits that can ease financial burdens and support their dreams of homeownership.
- Mortgage Interest Deduction: Imagine being able to deduct the interest you pay on your mortgage debt, up to $750,000. This can significantly lower your taxable income, which is a huge relief for families with larger mortgages. For instance, if you have a $200,000 mortgage at a 5 percent interest rate, you could see around $10,000 in interest deductions in your first year! Just keep in mind that this limit, set by the Tax Cuts and Jobs Act (TCJA), will revert to $1 million in 2026.
- Property Assessment Deduction: You can also deduct state and local property taxes, capped at $10,000 for married couples filing jointly. This deduction can really help lighten the load of property taxes, which can be quite hefty. For example, in New Jersey, the effective property tax rate is 2.23%, leading to a median annual property tax payment of about $9,541. This makes the property tax deduction essential for families living in high-tax areas.
- Mortgage Insurance Premiums: If you’re paying for private mortgage insurance (PMI), good news! You can , making homeownership more attainable for families who might not have a large down payment saved up. This reinstatement of tax-deductible mortgage insurance can save qualifying homeowners around $2,364 each year, making it easier to afford that dream home.
- Capital Gains Exclusion: When it comes time to sell your primary residence, you can exclude up to $250,000 in capital gains from your taxable income ($500,000 for married couples), as long as you meet certain conditions. This can be a significant financial advantage when moving to a larger home as your family grows, allowing you to reinvest in your future without a hefty tax bill.
- Energy Efficiency Incentives: If you’re making energy-efficient upgrades to your home, you might qualify for tax benefits that not only support sustainable living but also provide financial relief. These credits can make it easier for families to invest in their homes while contributing to a healthier planet.
By understanding and utilizing the tax benefits of buying a house, young families can enhance their financial stability and invest more in their children’s futures. Remember, we’re here for you, and together, we can navigate this journey toward a secure and prosperous home life.
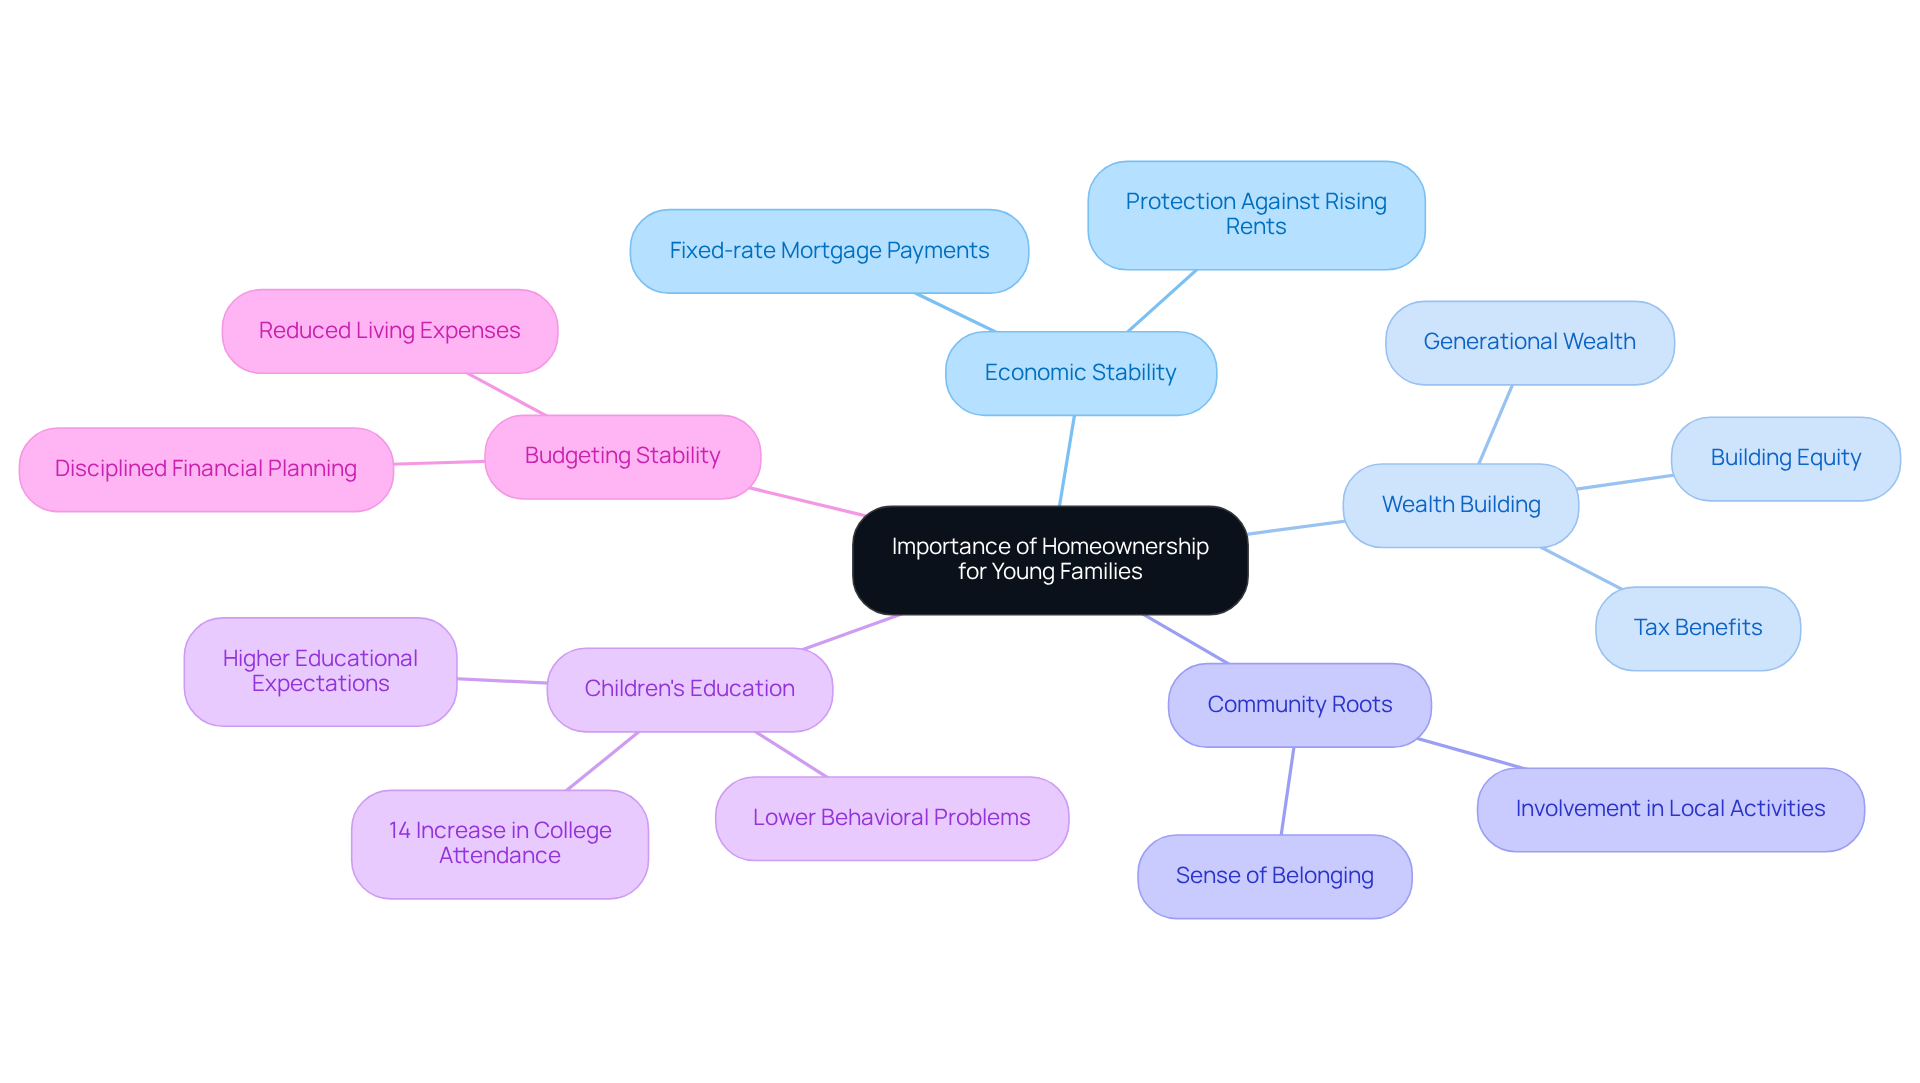
The Importance of Homeownership for Young Families
Owning a home is more than just a roof over your head; it’s a vital step toward economic stability and building wealth for young families. It brings a sense of security and permanence, allowing you to plant deep roots in your community. As property values rise, you can build equity that serves as a valuable asset for future investments or your children’s education.
Imagine this: studies show that a $10,000 increase in housing wealth can boost the chances of college attendance by 14% for lower- and moderate-income families. That’s a significant opportunity for your children’s future! Plus, with fixed-rate mortgage payments, you can budget more effectively, unlike the unpredictable rental market. This stability is crucial as you navigate the challenges of raising children and planning for their futures.
By embracing homeownership, you can foster a disciplined approach to budgeting, paving the way for a legacy of wealth that supports generations to come. [Bright Advisers exemplifies this journey](https://brightadvisers.com/?p=11117), as seen in Emily and Mark’s story. Through tailored wealth management strategies, they found the freedom to make work optional, showcasing the power of [strategic economic planning](https://brightadvisers.com/?p=9041) in achieving homeownership and its many benefits.
As Suze Orman wisely said, “Owning a home is a keystone of wealth… both financial affluence and emotional security.” Remember, we’re here for you. Together, we can navigate this journey toward a for your family.
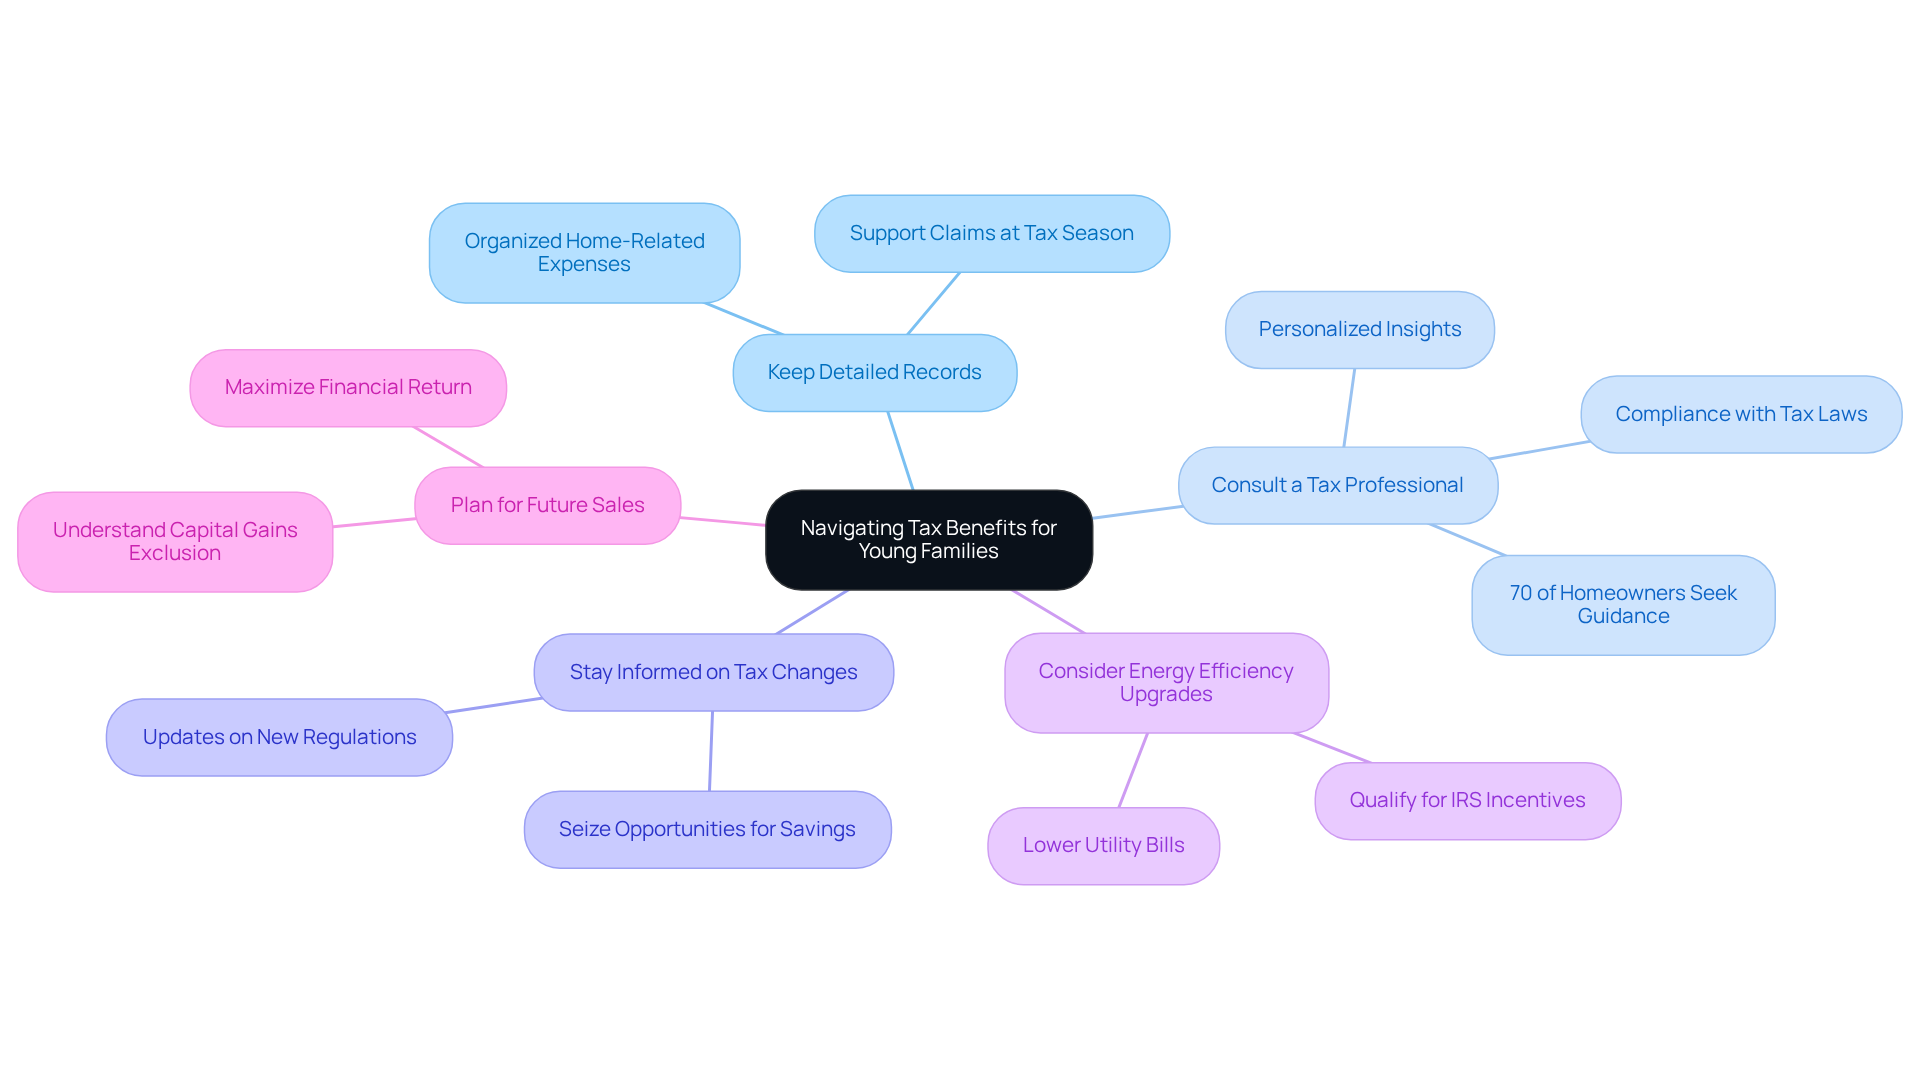
Navigating Tax Benefits: Tips for Young Families
Navigating the [tax benefits of buying a house](https://brightadvisers.com/essential-tax-planning-strategies-for-young-families-financial-health) can feel overwhelming, especially for [young families](https://brightadvisers.com/7-family-office-investment-services-for-young-families). But don’t worry; we’re here to help you through it. Here are some thoughtful strategies to consider:
- [Keep Detailed Records](https://henssler.com/maximize-your-tax-savings-the-importance-of-keeping-home-improvement-records-before-selling-your-home): Imagine having all your home-related expenses neatly organized – mortgage statements, property tax bills, and receipts for home improvements. This simple practice can make much easier and can lead to significant [[tax savings](https://brightadvisers.com/9-end-of-year-tax-strategies-for-young-families-to-save-big)](https://brightadvisers.com/10-best-tax-planning-strategies-for-young-families-financial-success). Families who maintain organized records are in a stronger position to support their claims come tax season.
- Consult a [Tax Professional](https://brightadvisers.com/7-personal-tax-return-services-for-young-families): Think about how beneficial it would be to have a tax advisor by your side, offering personalized insights to [[maximize your deductions](https://brightadvisers.com/?p=10344)](https://brightadvisers.com/?p=10344) and credits. According to the IRS, around 70% of homeowners seek the guidance of a tax professional to ensure they’re compliant with tax laws and making informed financial choices.
- [Stay Informed on Tax Changes](https://harness.co/articles/homebuyer-financial-and-tax-planning-guide): Tax laws can change frequently, and it’s important to stay updated on new regulations and benefits. By keeping informed, you can seize every opportunity available, potentially increasing your tax savings.
- Consider Energy Efficiency Upgrades: What if you could lower your utility bills while also benefiting from tax incentives? Investing in energy-efficient home improvements not only helps your wallet but may also qualify you for IRS incentives. It’s a win-win for your family’s finances.
- [Plan for Future Sales](https://congress.gov/crs-product/RL33755): If you’re thinking about selling your home down the line, understanding the capital gains exclusion is crucial. Homeowners can exclude up to $250,000 of capital gains from taxation when selling their primary residence, or up to $500,000 if married and filing jointly. Knowing how to optimize this exclusion can significantly enhance your financial return when relocating.
By embracing these strategies, young families can navigate the complexities of homeownership with confidence and take advantage of the tax benefits of buying a house. Together, we can leverage these tax benefits to secure a brighter financial future for your family.
Conclusion
Understanding the tax benefits of buying a house is essential for young families striving for financial stability and a brighter future. Homeownership not only provides a place to call home but also opens the door to valuable tax deductions and credits that can lighten financial burdens. Imagine redirecting those savings toward your children’s needs and long-term goals.
Throughout this article, we’ve explored key insights, including the mortgage interest deduction, property tax deduction, and incentives for energy-efficient improvements. Each of these elements plays a vital role in lowering taxable income and enhancing your family’s overall financial health. It’s important to understand how capital gains exclusions can empower you to make informed decisions when selling your home, maximizing your returns.
Ultimately, the journey of homeownership offers young families a pathway to economic stability and wealth accumulation. Embracing these tax benefits not only supports immediate financial relief but also lays the groundwork for future opportunities, like funding education or investing in new ventures. Together, we can navigate this journey with confidence, ensuring a prosperous future for you and your children.
Frequently Asked Questions
What are the tax benefits of homeownership for young families?
The tax benefits of homeownership for young families include deductions for mortgage interest, property taxes, and tax credits for energy-efficient home improvements, which can significantly reduce taxable income and overall tax liability.
How does the mortgage interest deduction work?
Homeowners can deduct interest on mortgage loans up to $750,000. For example, the first year of interest on a $750,000 mortgage at a 6.5% interest rate can amount to approximately $48,503 in savings.
What is the property tax deduction limit?
Homeowners can deduct state and local property taxes, capped at $10,000 for single filers and married couples filing jointly.
What kind of energy-efficient home improvements qualify for tax credits?
Upgrades such as solar panels and energy-efficient windows qualify for tax credits, which can reach up to $3,200.
What is the capital gains exclusion for selling a primary residence?
When selling a primary residence, married couples can exclude up to $500,000 in capital gains, enhancing the financial rewards of homeownership.
How can families benefit from the mortgage credit certificate program?
Families utilizing the mortgage credit certificate program can receive a tax credit of up to $2,000, which directly reduces their tax bills and makes homeownership more affordable.
Why is it important for families with children to understand tax benefits of homeownership?
Understanding and utilizing the tax benefits of homeownership can lead to substantial savings, allowing families to allocate more resources toward their children’s needs and future.
List of Sources
- Defining Tax Benefits of Homeownership
- 7 Tax Breaks for Homeowners (https://experian.com/blogs/ask-experian/tax-breaks-for-homeowners)
- Tax benefits for homeowners | Internal Revenue Service (https://irs.gov/newsroom/tax-benefits-for-homeowners)
- Tax Deductions for Homeowners 2025 Guide (https://farther.com/resources/foundations/tax-deductions-for-homeowners)
- Ten Tax Breaks for Homeowners and Homebuyers in 2025 (https://kiplinger.com/taxes/income-tax/603276/tax-breaks-for-homeowners-and-home-buyers)
- Key Tax Deductions and Credits for Homeowners
- Property taxes by state: Ranked from highest to lowest in 2025 (https://rocketmortgage.com/learn/property-taxes-by-state)
- The Home Mortgage Interest Deduction (https://taxfoundation.org/research/all/federal/home-mortgage-interest-deduction)
- Tax Deductions for Homeowners in 2025 – NerdWallet (https://nerdwallet.com/mortgages/learn/tax-deductions-for-homeowners)
- 5 Tax Changes for Homeowners in 2025 That Could Save You Money (https://preferredrate.com/blog/5-tax-changes-for-homeowners-in-2025-that-could-save-you-money)
- Tax benefits for homeowners | Internal Revenue Service (https://irs.gov/newsroom/tax-benefits-for-homeowners)
- The Importance of Homeownership for Young Families
- Top 25 Real Estate Quotes for Home Buyers | McColly Real Estate | Northern Indiana (https://mccolly.com/blog/top-25-real-estate-quotes-for-home-buyers)
- Owning Your Future: How Homeownership Is A Stable Path To Wealth (https://forbes.com/sites/andrejeanpierre/2024/07/31/owning-your-future-how-homeownership-is-stable-path-to-wealth)
- Research series: Outcomes associated with homeownership (https://habitat.org/our-work/impact/research-series-outcomes-associated-with-homeownership)
- Tough Market: 67% of Americans Now Believe Homeownership is an Unrealistic Milestone for Young People (https://citigroup.com/global/insights/67-americans-now-believe-homeownership-unrealistic-milestone-young-people)
- The impact of low- and moderate-wealth homeownership on parental attitudes and behavior: Evidence from the community advantage panel – PMC (https://pmc.ncbi.nlm.nih.gov/articles/PMC4437217)
- Navigating Tax Benefits: Tips for Young Families
- Maximize Your Tax Savings: The Importance of Keeping Home Improvement Records Before Selling Your Home – Henssler Financial (https://henssler.com/maximize-your-tax-savings-the-importance-of-keeping-home-improvement-records-before-selling-your-home)
- First-Time Homebuyer Guide: Tax Benefits & Financial Planning Tips (https://harness.co/articles/homebuyer-financial-and-tax-planning-guide)
- Federal Income Tax Treatment of the Family (https://congress.gov/crs-product/RL33755)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading