

Key Highlights
- An Initial Public Offering (IPO) allows a private company to sell shares to the public, potentially changing a family’s financial status significantly.
- Local IPO activity can correlate with a 5-6% increase in stock ownership among households, emphasising the importance of IPOs in wealth accumulation.
- The IRS taxes the value of stocks from an IPO as regular income, with potential tax rates reaching up to 37%, depending on the tax bracket.
- Long-term capital gains tax rates for 2026 are 15% for incomes up to $49,450 and 20% for incomes above $545,500.
- Strategies for managing IPO tax implications include timing sales, tax-loss harvesting, gifting shares, and consulting a tax professional.
- Families can minimise tax liabilities by holding stocks longer to qualify for lower long-term capital gains tax rates.
- Donating IPO stocks can provide tax advantages by avoiding capital gains taxes and offering a tax deduction based on the fair market value.
- Families should plan for potential tax bills after an IPO by adjusting withholdings or making estimated tax payments to avoid penalties.
- Bright Advisers offers personalised wealth management solutions to help families navigate the complexities of IPOs and tax implications.
Introduction
Imagine the possibilities for your family’s future when you understand the ins and outs of an Initial Public Offering (IPO). As companies transition from private to public, they open doors to significant wealth creation. But with that potential comes the complexities of tax implications.
Let’s explore how the IPO tax rate can affect your family’s finances and discover strategies to help you navigate this pivotal moment together. How can you and your family manage the tax consequences of an IPO while keeping your financial dreams alive?
Define IPO and Its Importance for Families
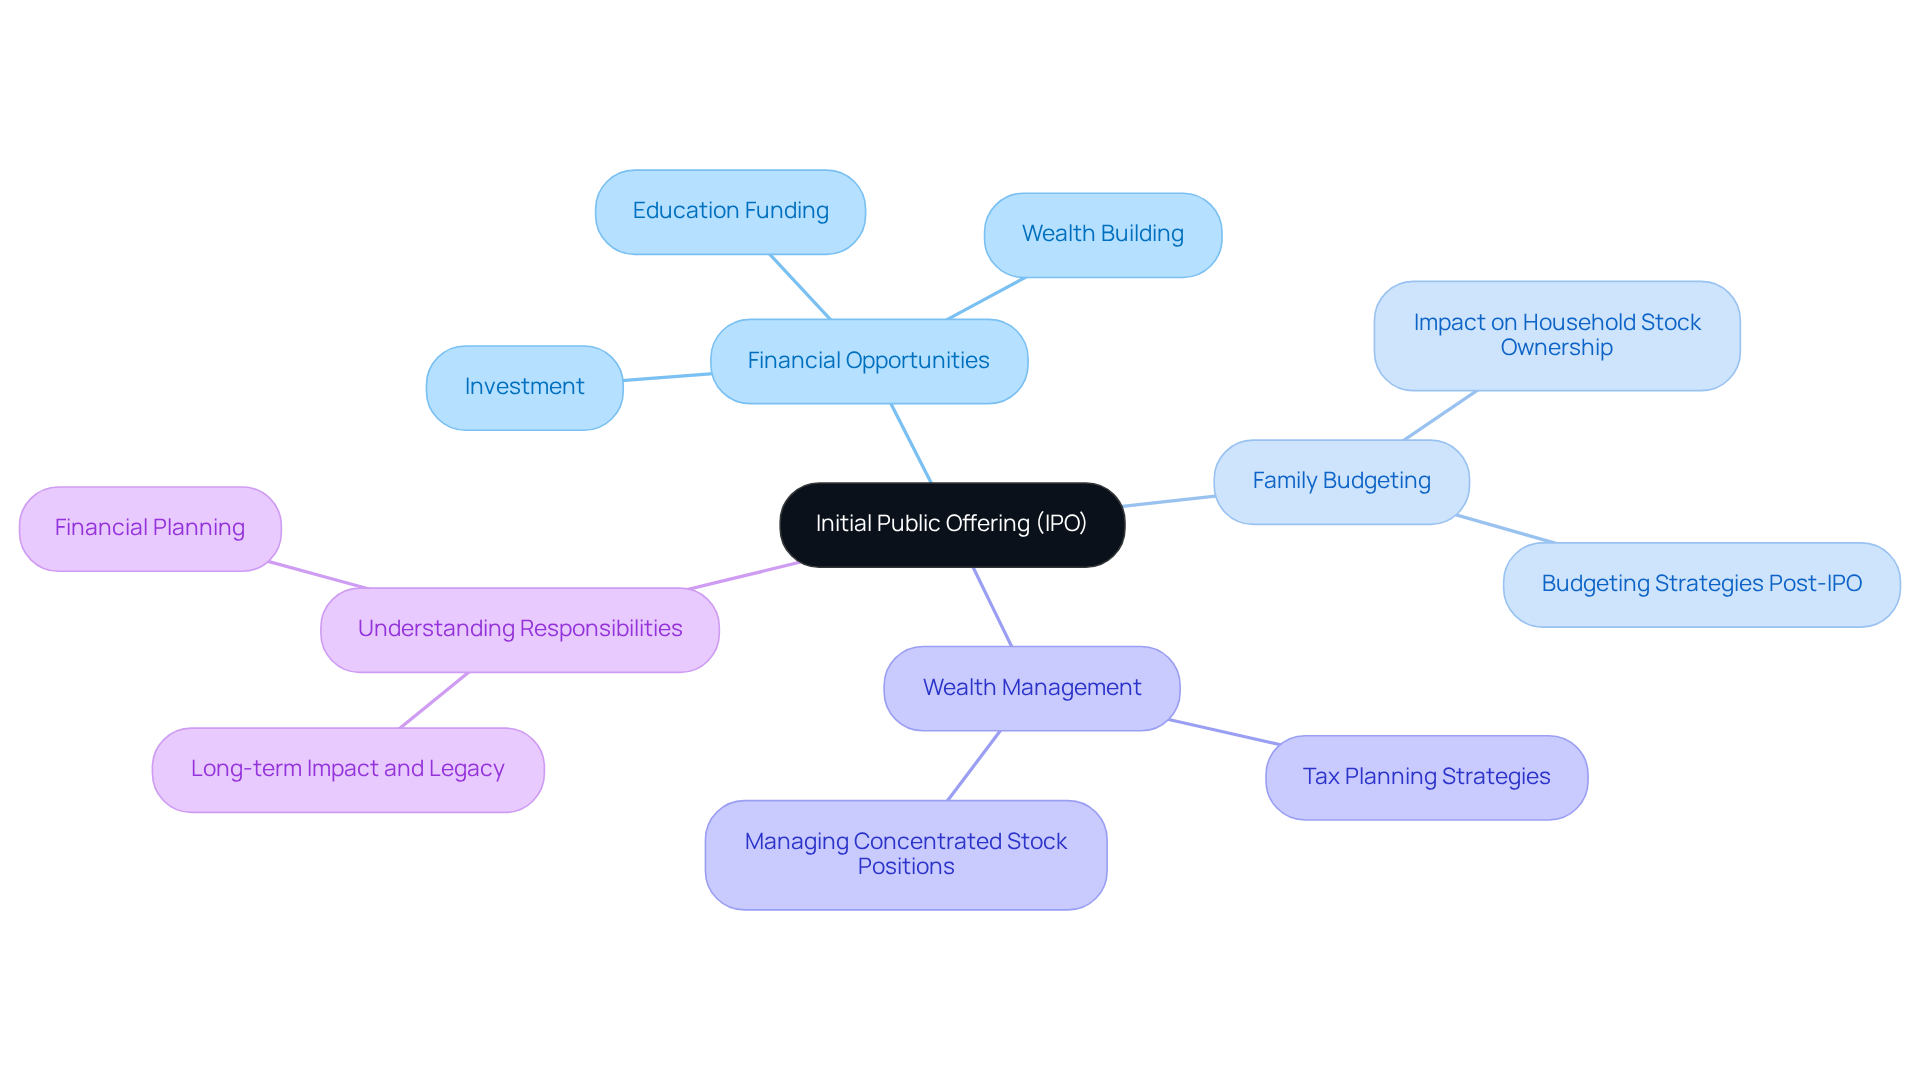
Imagine if your family’s financial future could change overnight with an IPO. An Initial Public Offering (IPO) lets a private company sell its shares to the public for the first time, which can be a big deal for families. This transition can lead to significant changes in monetary status, potentially providing new opportunities for investment, education funding, and long-term wealth building. Many parents feel overwhelmed by financial jargon, making it hard to grasp how an IPO affects their family. It’s important to understand how an IPO can influence your economic situation, including the possibility of increased income and the obligations that come with managing newfound wealth.
Case studies demonstrate the effect of IPOs on family budgeting. For instance, local IPO activity has been shown to correlate with a 5-6% increase in stock ownership among households, emphasizing the importance of local IPOs in wealth accumulation. Moreover, heightened media attention surrounding IPOs greatly boosts local stock market participation rates, further highlighting the importance of information in economic decision-making.
Understanding how an IPO works is crucial for families because it can change your financial situation today and shape your future plans. When families recognize the benefits and responsibilities that come with IPOs, they can feel more confident in planning for their financial future. Bright Advisers’ personalized wealth management solutions, including innovative tax planning strategies and investment approaches, can support families like Emily and Mark in achieving their financial goals and securing their family’s future.
Explore IPO Tax Implications for Family Finances
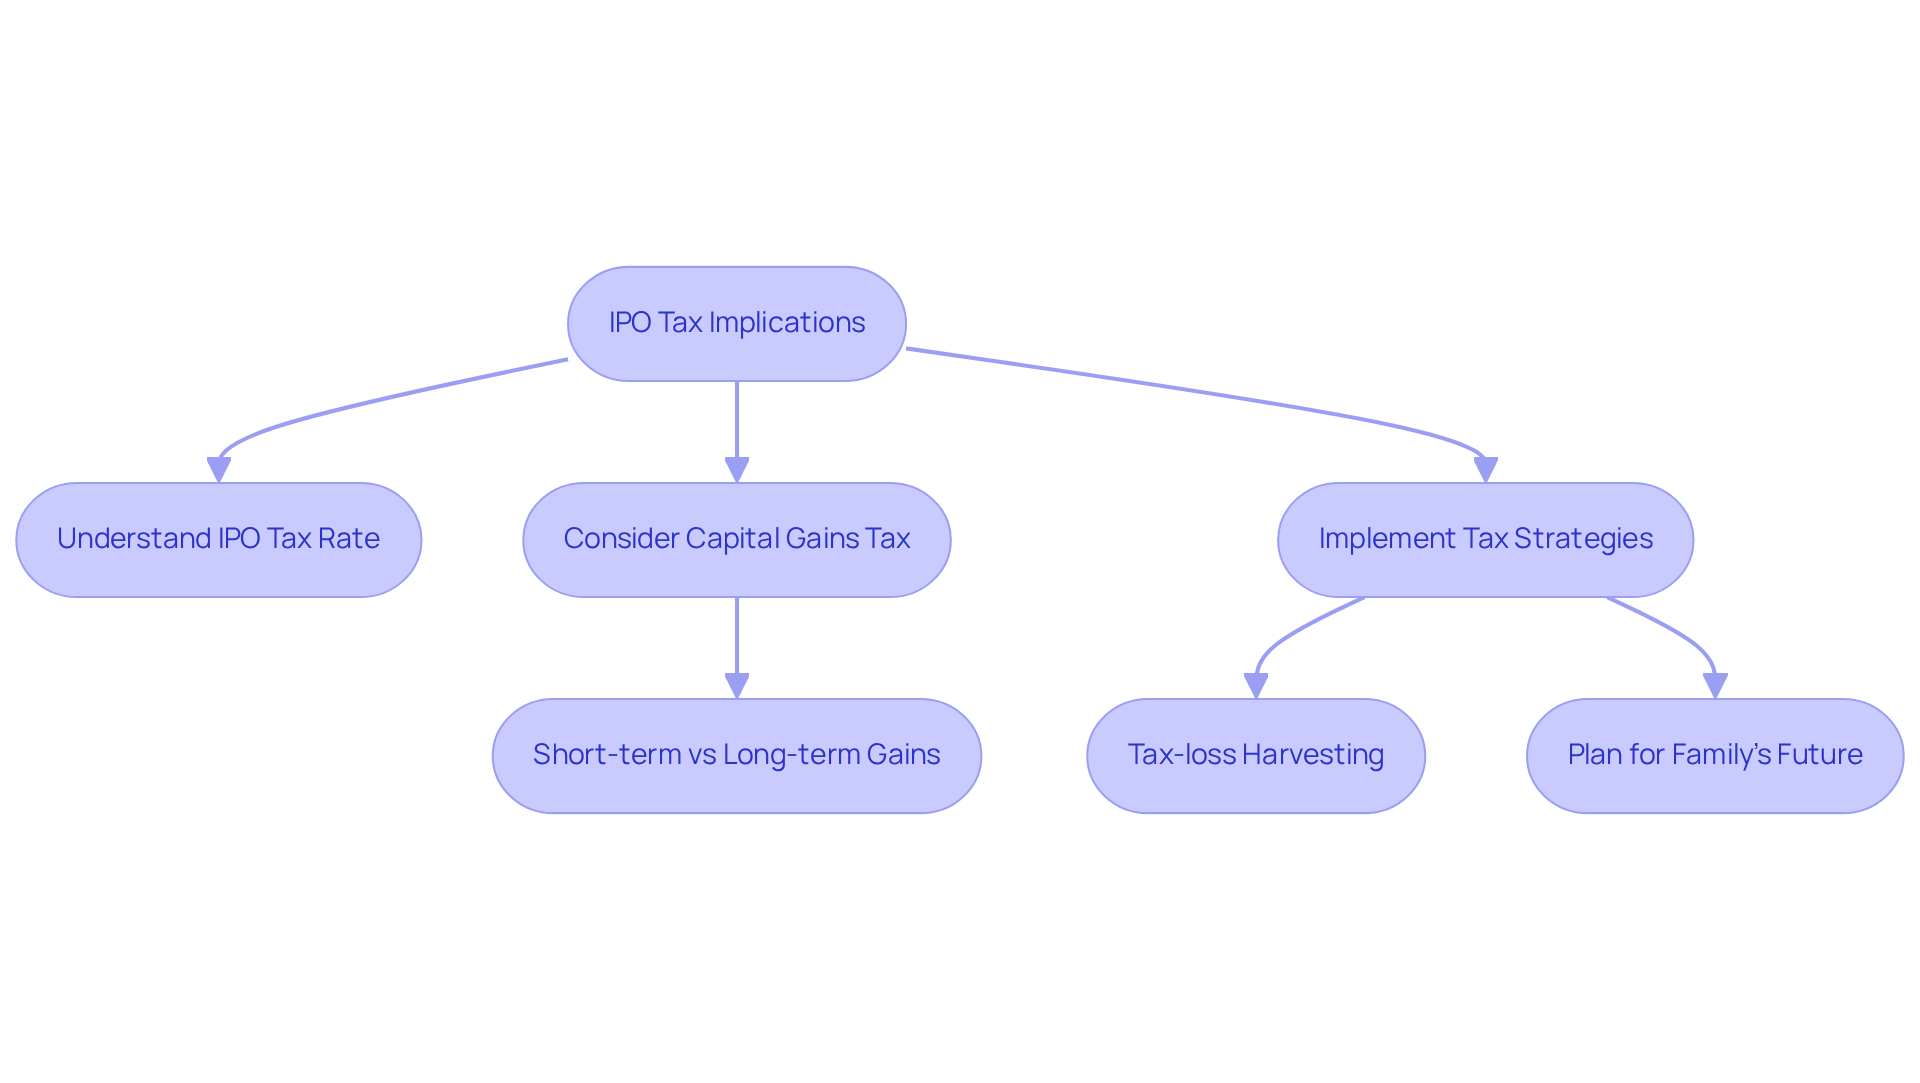
Imagine the excitement of your company going public, but then the worry sets in about how it will affect your family’s finances. When your company goes public, it can bring excitement, but it also comes with important implications regarding the ipo tax rate for you and your family. The IRS views the value of your stocks as regular income, which means it could be taxed at the ipo tax rate, potentially as high as 37%, depending on your tax bracket.
If you sell those shares, you might face capital gains tax, which can change based on how long you’ve held them. For 2026, if you’re a single filer, long-term capital gains tax rates are:
- 15% for incomes up to $49,450
- 20% for those above $545,500
It’s important to keep these numbers in mind as you plan for your family’s future. Planning carefully can help your family avoid those unexpected tax bills that can throw off your financial goals.
Understanding the difference between short-term and long-term capital gains is essential, as short-term gains are taxed at the ipo tax rate, which can be significantly higher than ordinary income rates. You might also consider tax-loss harvesting strategies, which can help offset gains with losses from other investments, reducing your overall tax liabilities.
For example, Allison and Brian worked with Bright Advisers to navigate their circumstances after the IPO. They implemented strategies like tax-loss harvesting and careful timing of asset sales, ensuring they could fund their children’s education while planning for retirement.
With the right strategies in place, you can turn potential tax challenges into opportunities for your family’s future. Remember, the maximum earned income tax credit (EITC) for 2026 is $664 for single filers with no children, which can further impact your financial planning.
We’re here for you, ready to help you navigate this journey together.
Implement Strategies for Managing IPO Tax Rates
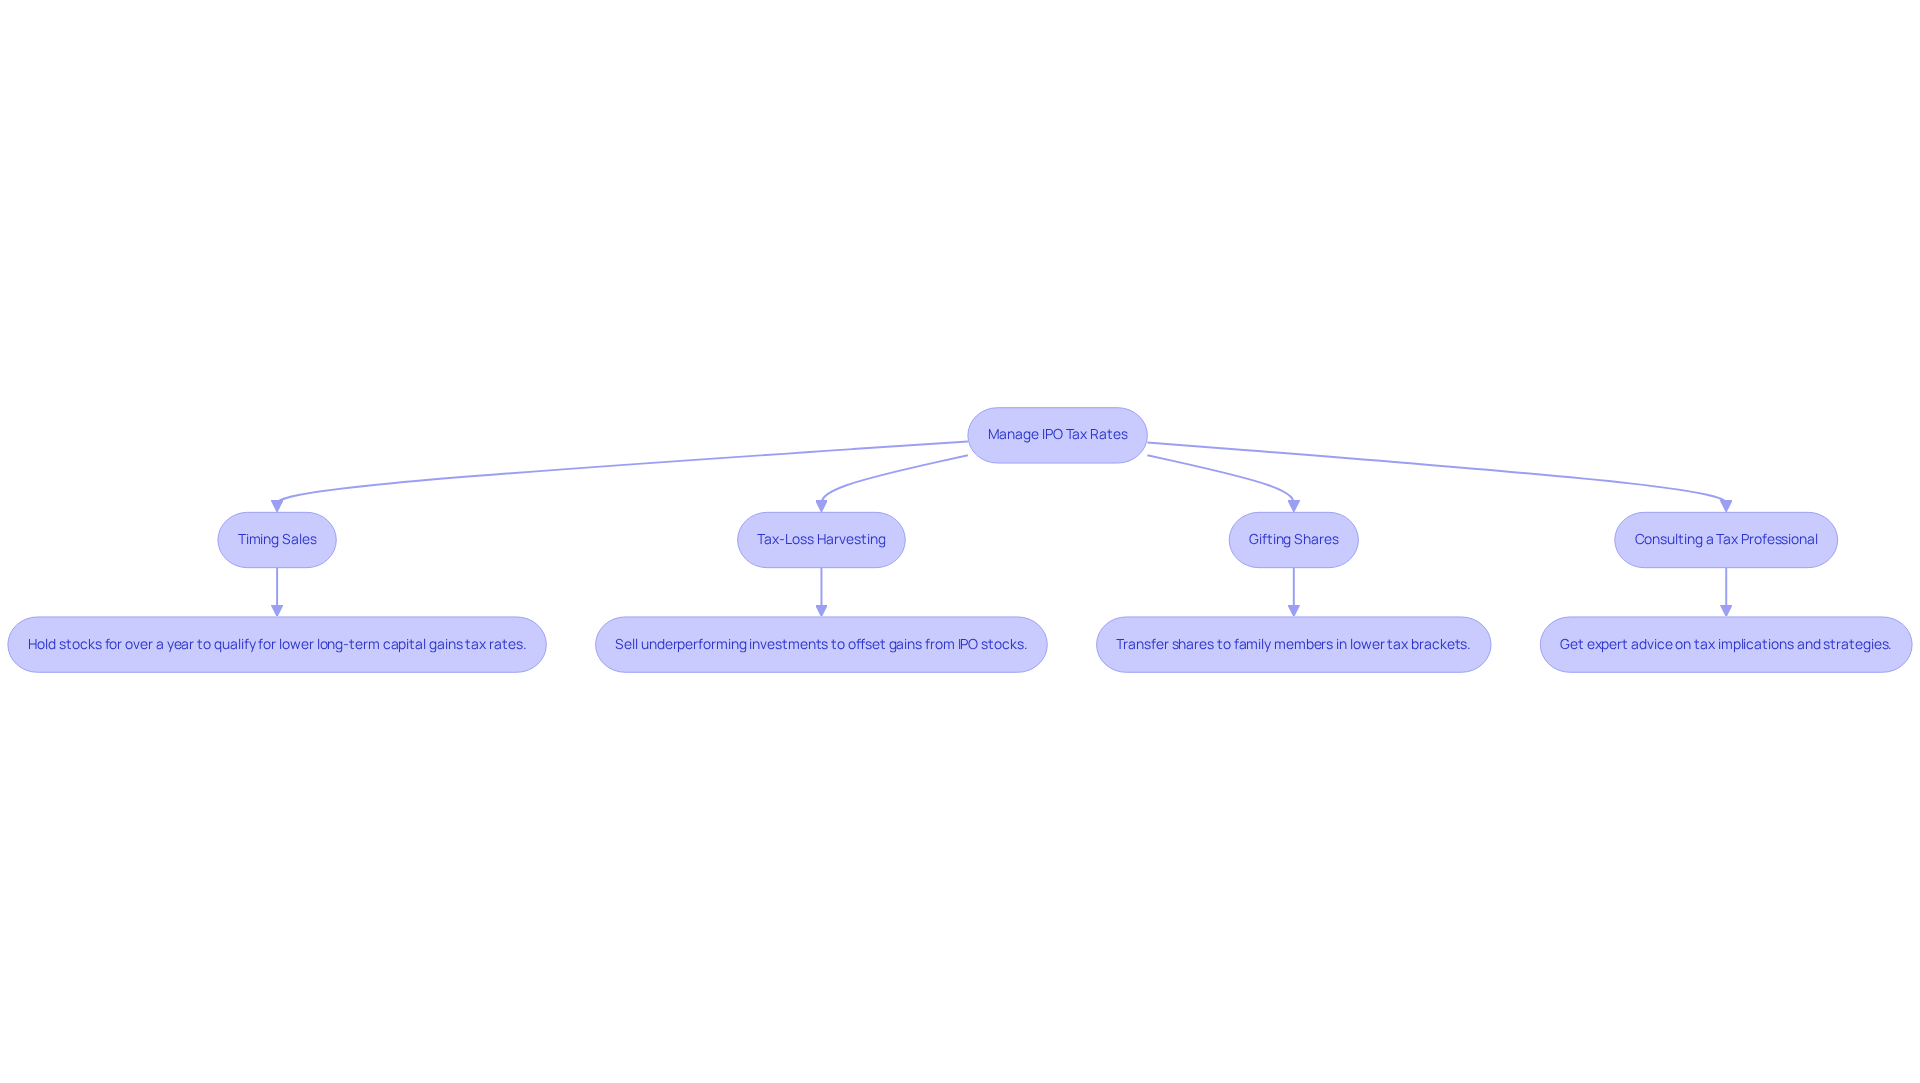
Imagine the relief of navigating the complexities of an IPO with confidence, knowing your family’s financial future is secure. To effectively manage the tax implications of an IPO, families can adopt several strategies:
-
Timing Sales: Picture this: holding onto your stocks for over a year can qualify you for long-term capital gains tax rates, which are generally lower than short-term rates. This method can significantly lessen the tax burden on profits realized from IPO stocks, thereby affecting the IPO tax rate.
-
Tax-Loss Harvesting: Imagine selling off some investments that haven’t performed well to help balance out the gains from your IPO stocks. It’s a smart way to ease the burden of the IPO tax rate while keeping your family’s financial goals in sight. Plus, you can reinvest those tax savings, enhancing long-term growth potential.
-
Gifting Shares: Think about transferring shares to family members in lower tax brackets. This can minimize the impact of the IPO tax rate and is a wonderful way for parents to teach their children about investing while managing tax liabilities effectively.
-
Consulting a tax professional who understands the IPO tax rate can really help you find the best path forward for your family’s financial dreams. They can navigate the complexities of tax laws and ensure compliance, maximizing potential benefits.
By taking these steps, you’re not just managing taxes; you’re investing in your family’s future and peace of mind. Together, we can navigate this journey and ensure that your financial health remains strong.
Clarify Common Questions About IPOs and Taxes
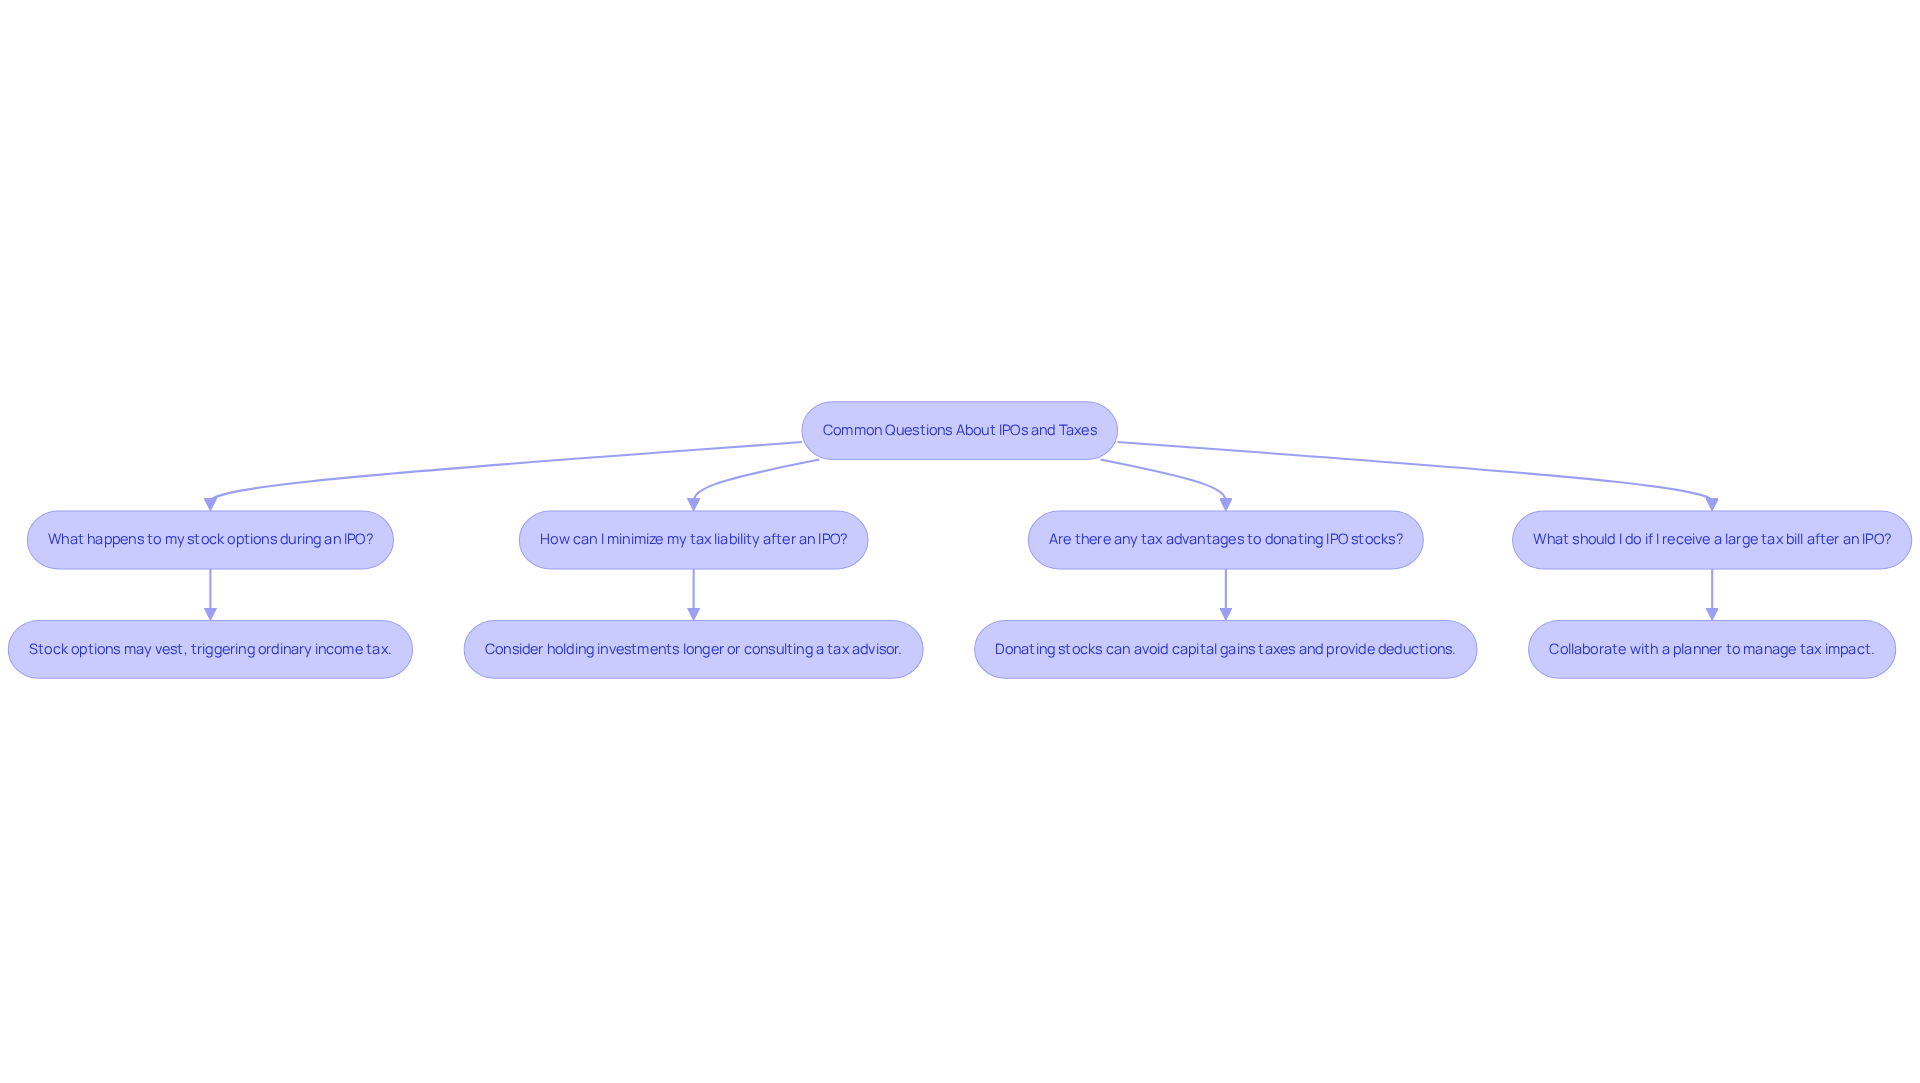
Many families feel overwhelmed by the complexities of IPOs and the potential burdens associated with the ipo tax rate that come with them. Here are some common inquiries:
-
What happens to my stock options during an IPO? When a company goes public, stock options may vest, which can trigger ordinary income tax on the value of the stocks. For instance, $100,000 in Incentive Stock Options (ISOs) can become exercisable in a single calendar year, significantly increasing your taxable income. Jay and Emma, a couple with two children, faced similar concerns as they sought to reduce their financial anxiety and allocate resources effectively.
-
How can I minimize my tax liability after an IPO? You might consider simple strategies like holding onto your investments a bit longer or talking to a tax advisor who understands your family’s needs. For example, holding shares for more than a year can qualify you for lower long-term capital gains tax rates, which can be as low as 0%, 15%, or 20% depending on your income level. Emily and Mark, both high-income professionals, successfully navigated these complexities by developing a comprehensive financial strategy with Bright Advisers that allowed them to manage their finances effectively while maintaining their demanding careers.
-
Are there any tax advantages to donating IPO stocks? Yes, donating stocks directly to charity can help you avoid capital gains taxes while supporting a cause you care about. This strategy not only benefits the charity but can also provide you with a tax deduction based on the fair market value of the shares at the time of donation. Allison and Brian discovered that incorporating such strategies into their budget helped secure their children’s future through education funding.
-
What should I do if I receive a large tax bill after an IPO? Consider collaborating with a planner to create a strategy for managing the tax impact. This may include adjusting your withholding or making estimated tax payments to avoid penalties. Planning ahead can make a big difference, especially when it comes to understanding the tax implications of stock options and RSUs, including the ipo tax rate, during an IPO. Additionally, keep in mind that the IRS default tax withholding rate for RSUs is 22%, which may not cover your actual tax liability if your income exceeds certain thresholds. Families in California should also note that there is no favorable capital gains rate at the state level, taxing all gains on RSUs or stock options as ordinary income. By collaborating with Bright Advisers, families can gain the confidence and clarity needed to navigate these financial challenges effectively.
Note: The above case studies are hypothetical and do not involve any actual Bright Advisers clients. No portion of the content should be construed by a client or prospective client as a guarantee that he/she will experience the same or certain level of results or satisfaction if Bright Advisers is engaged to provide investment advisory services.
Conclusion
Navigating the tax implications of an IPO can feel overwhelming, but it’s essential for families looking to secure their financial future. An IPO can change a family’s financial situation in big ways, bringing both new opportunities and challenges. Understanding these complexities is key to making choices that protect your financial future.
Throughout this guide, we’ve explored together how understanding the tax implications of IPOs can help families navigate their financial journeys more confidently. Families can benefit from strategies like:
- Timing sales to qualify for lower long-term capital gains tax rates
- Consulting with tax professionals to help manage these complexities
Real-life examples illustrate how families like Emily and Mark, and Allison and Brian, successfully managed their financial situations post-IPO with the help of Bright Advisers.
When families understand these tax implications, they can seize opportunities for financial growth and make choices that lead to lasting wealth. By taking proactive steps and seeking guidance, families can turn the challenges of an IPO into opportunities for growth and security. With the right support from Bright Advisers, you can feel confident navigating these waters, ensuring your family’s financial health stays strong.
Frequently Asked Questions
What is an Initial Public Offering (IPO)?
An Initial Public Offering (IPO) is when a private company sells its shares to the public for the first time, allowing it to raise capital and transition into a publicly traded company.
Why are IPOs important for families?
IPOs can significantly impact a family’s financial future by potentially increasing their monetary status, providing new investment opportunities, funding for education, and contributing to long-term wealth building.
How can an IPO affect a family’s financial situation?
An IPO can lead to increased income and wealth, but it also comes with responsibilities in managing newfound wealth, which can influence a family’s budgeting and financial planning.
What evidence supports the impact of IPOs on family wealth?
Case studies show that local IPO activity correlates with a 5-6% increase in stock ownership among households, indicating that IPOs play a significant role in wealth accumulation.
How does media attention influence participation in stock markets during IPOs?
Heightened media attention surrounding IPOs boosts local stock market participation rates, emphasizing the importance of information in making economic decisions.
How can families prepare for the changes brought by an IPO?
Families can prepare by understanding the benefits and responsibilities associated with IPOs, which can help them feel more confident in planning for their financial future.
What services does Bright Advisers offer to support families regarding IPOs?
Bright Advisers provides personalized wealth management solutions, including innovative tax planning strategies and investment approaches, to help families achieve their financial goals and secure their future.
List of Sources
- Define IPO and Its Importance for Families
- Local IPOs and Household Stock Market Participation (https://alphaarchitect.com/ipo)
- Does the IPO of local firms impact household stock market participation? Evidence from China (https://sciencedirect.com/science/article/abs/pii/S1566014126000956)
- Impact of family ownership, management, and generations on IPO underpricing and long-run performance (https://businessperspectives.org/journals/investment-management-and-financial-innovations/issue-393/impact-of-family-ownership-management-and-generations-on-ipo-underpricing-and-long-run-performance)
- A Goldman Sachs financial advisor shares 3 strategies for founders preparing to cash in on IPO wealth (https://businessinsider.com/tips-ipo-rich-founders-manage-wealth-according-to-goldman-sachs-2024-8)
- %%title%% %%page%% | Cresset (https://cressetcapital.com/articles/entrepreneurs/4-things-to-consider-for-a-successful-post-ipo-financial-life)
- Explore IPO Tax Implications for Family Finances
- 2026 Tax Brackets (https://taxfoundation.org/data/all/federal/2026-tax-brackets)
- Master Startup IPO Tax Strategy for Young Families’ Wealth – Bright Advisers (https://brightadvisers.com/master-startup-ipo-tax-strategy-for-young-families-wealth)
- Capital Gains Tax Rates: Short-term vs. Long-term (https://schwab.com/learn/story/how-are-capital-gains-taxed)
- Capital gains tax: Definition, rates, and ways to save | Fidelity (https://fidelity.com/learning-center/smart-money/capital-gains-tax-rates)
- 2026 Federal Income Tax Brackets and Interactive Calculator (https://bipartisanpolicy.org/explainer/2026-federal-income-tax-brackets-and-interactive-calculator)
- Implement Strategies for Managing IPO Tax Rates
- Tax-loss harvesting explained | Vanguard (https://investor.vanguard.com/investor-resources-education/taxes/offset-gains-loss-harvesting)
- After-Tax IPO Strategies for Early Investors | BlackRock (https://blackrock.com/us/financial-professionals/insights/after-tax-strategies-ipo-concentrated-stock)
- Tax-Loss Harvesting Strategies | BlackRock (https://blackrock.com/us/financial-professionals/investments/products/managed-accounts/tax-loss-harvesting)
- Help Maximize Your Savings With Tax-Loss Harvesting (https://creativeplanning.com/insights/financial-planning/tax-loss-harvesting-strategy)
- Clarify Common Questions About IPOs and Taxes
- 5 Steps to Solve Your IPO Tax Issues: IPO and Taxes (https://kbfinancialadvisors.com/5-steps-to-solve-your-ipo-tax-issues)
- The Employee’s Guide to IPO Tax Planning: How to Manage Your ‘Enormous Income Year’ – NerdWallet (https://nerdwallet.com/investing/learn/how-much-tax-will-I-pay-on-IPO-stock)
- 7 Most Common Tax Questions Answered by a CPA (https://turbotax.intuit.com/tax-tips/tax-pro/7-most-common-tax-questions-answered-by-a-cpa/L4Z70RBd8)
- IPO Planning for Employees: Tax Strategies, Risks, and What to Do Before You Sell (https://missionwealth.com/ipo-planning-for-employees)
- Tax Tips And Warnings For IPO Company Employees And Their Advisors (https://forbes.com/sites/brucebrumberg/2026/06/23/tax-tips-and-warnings-for-ipo-company-employees-and-their-advisors)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Philanthropy for high-income W-2 families at Bright Advisers.
Keep reading