

Key Highlights
- Liability Driven Investment (LDI) aligns cash flows from investments with future liabilities, helping manage risks associated with interest rate changes.
- LDI is primarily used by pension funds to create a stable financial base, ensuring obligations can be met without excessive risk.
- The LDI crisis has highlighted the need for families to understand financial management and secure their children’s futures.
- Recent economic shifts, including rising interest rates, have caused challenges for pension plans, affecting family financial security.
- Families should maintain cash reserves of six to nine months of living expenses to navigate financial uncertainties.
- Diversification of investments is crucial to reduce risk and enhance portfolio resilience during market fluctuations.
- Regularly reviewing financial goals and strategies helps families stay aligned with changing circumstances and market conditions.
- Promoting economic literacy empowers families to make informed financial decisions and manage challenges effectively.
- Bright Advisers offers personalised wealth management plans to help families secure their financial futures.
Introduction
Many parents feel lost when trying to navigate their family’s financial future. Understanding the complexities of financial planning can be daunting, especially with recent economic upheavals weighing heavily on your mind. Imagine facing a financial storm, where every decision feels heavy with responsibility for your family’s future.
The Liability Driven Investment (LDI) crisis highlights the need to align investments with future obligations. It’s important to understand how to adapt your financial strategies, not just to survive, but to thrive for your children’s sake. With the right support, you can create a secure and bright future for your children.
Define Liability Driven Investment (LDI) and Its Purpose
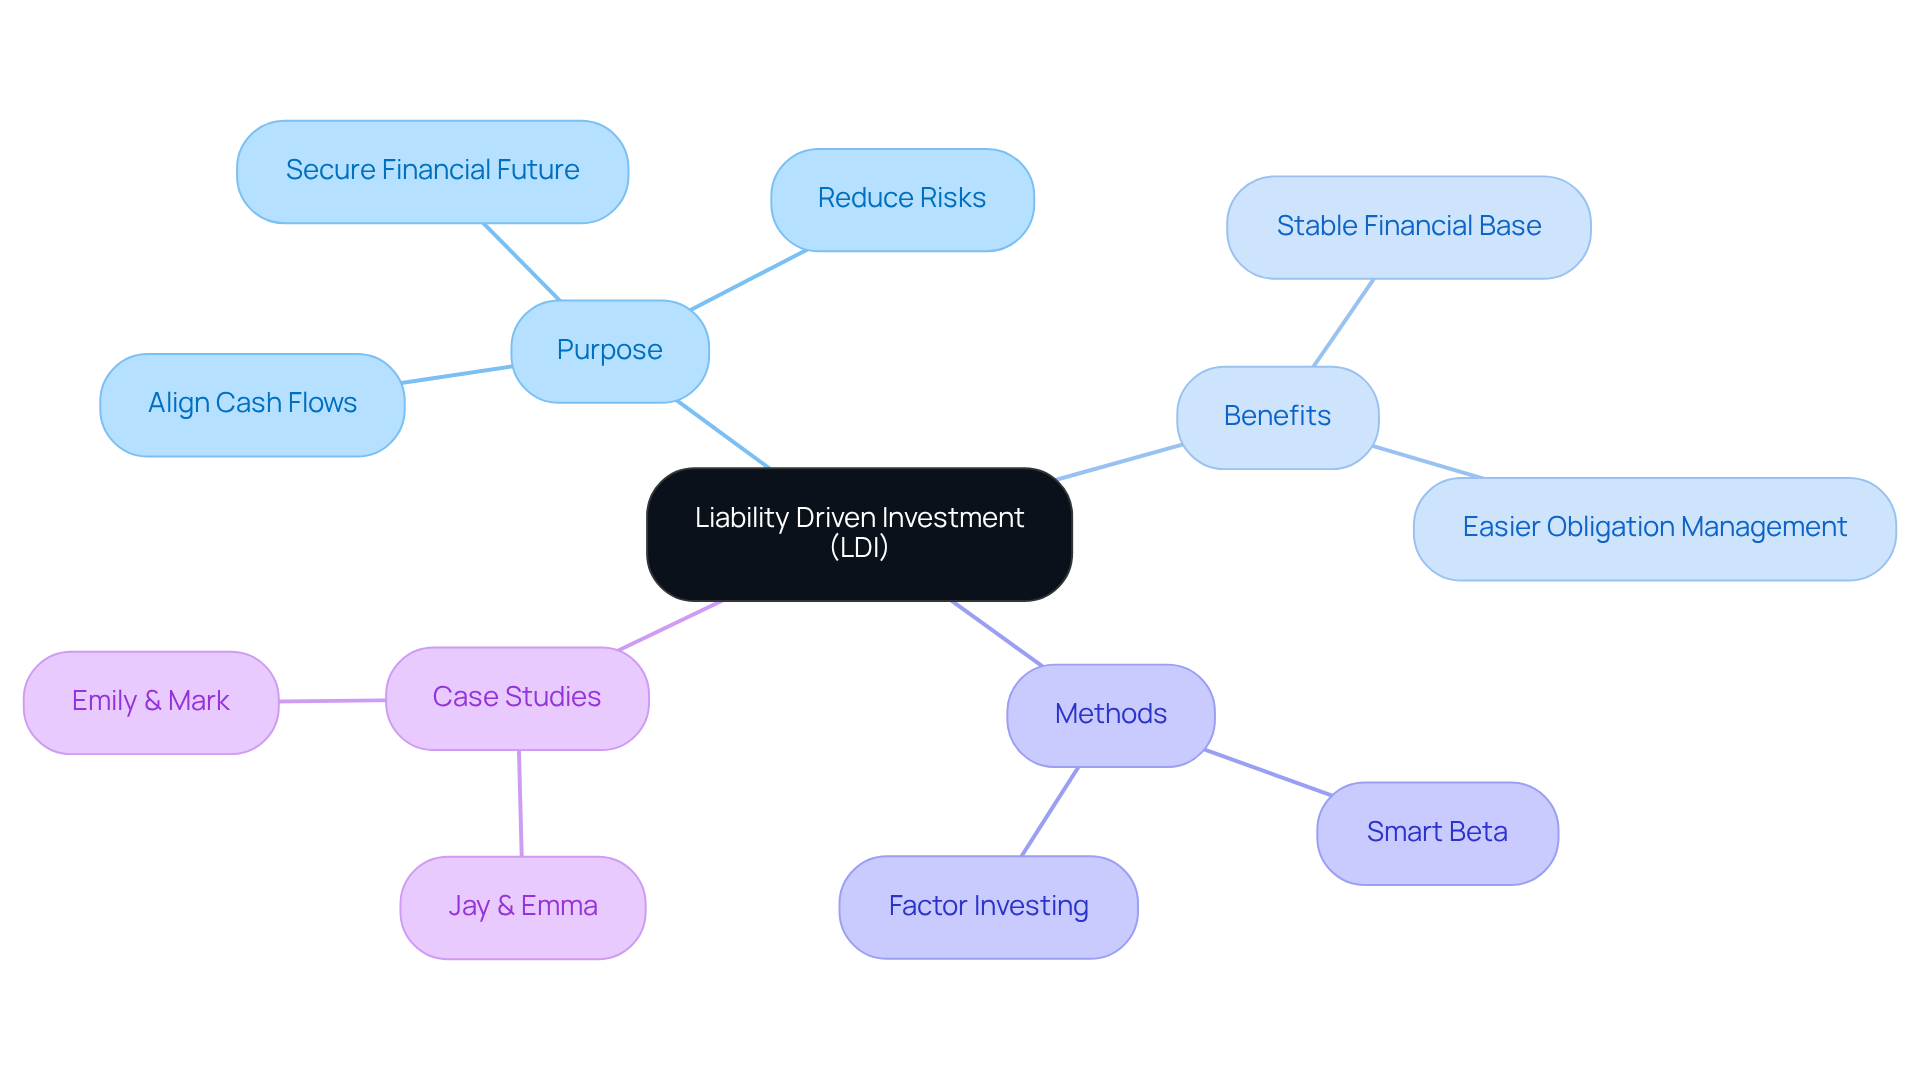
Many families feel overwhelmed when it comes to planning for their children’s futures, especially when it comes to managing finances. The concept of Liability Driven Investment (LDI) is part of the LDI crisis explained, highlighting its strategic approach that can help. It’s primarily used by pension funds and institutions to manage their liabilities effectively. The goal of LDI is to align cash flows from investments with the timing and amounts of future liabilities, like pension payouts. This alignment helps reduce risks from interest rate changes, ensuring funds are available when needed.
LDI helps organizations create a stable financial base, making it easier for them to meet their obligations without taking on too much risk. For families, the LDI crisis explained is crucial to grasp. It shows how aligning investments with your financial goals can help secure a bright future for your children. Bright Advisers uses innovative technology to create personalized portfolios, employing methods like smart beta and factor investing.
Imagine if you could take control of your family’s financial future. Recent statistics reveal that the LDI crisis explained indicates LDI approaches are gaining traction among pension plans, with allocations typically ranging from 30% to 60% of the portfolio. This growing acceptance highlights their effectiveness in managing economic stability.
Moreover, the glide path approach allows families to gradually adopt LDI methods as their financial situations improve, aligning with their evolving needs. Regular monitoring of LDI strategies is essential, especially for underfunded plans, as the LDI crisis explained emphasizes the importance of ensuring they remain effective in meeting future obligations.
Families like Jay & Emma and Emily & Mark have turned to Bright Advisers for help, finding tailored solutions that ease their financial worries and pave the way for their children’s futures. With the right support, families can confidently navigate their financial journey and secure a brighter future for their children.
Examine the Events Leading to the LDI Crisis
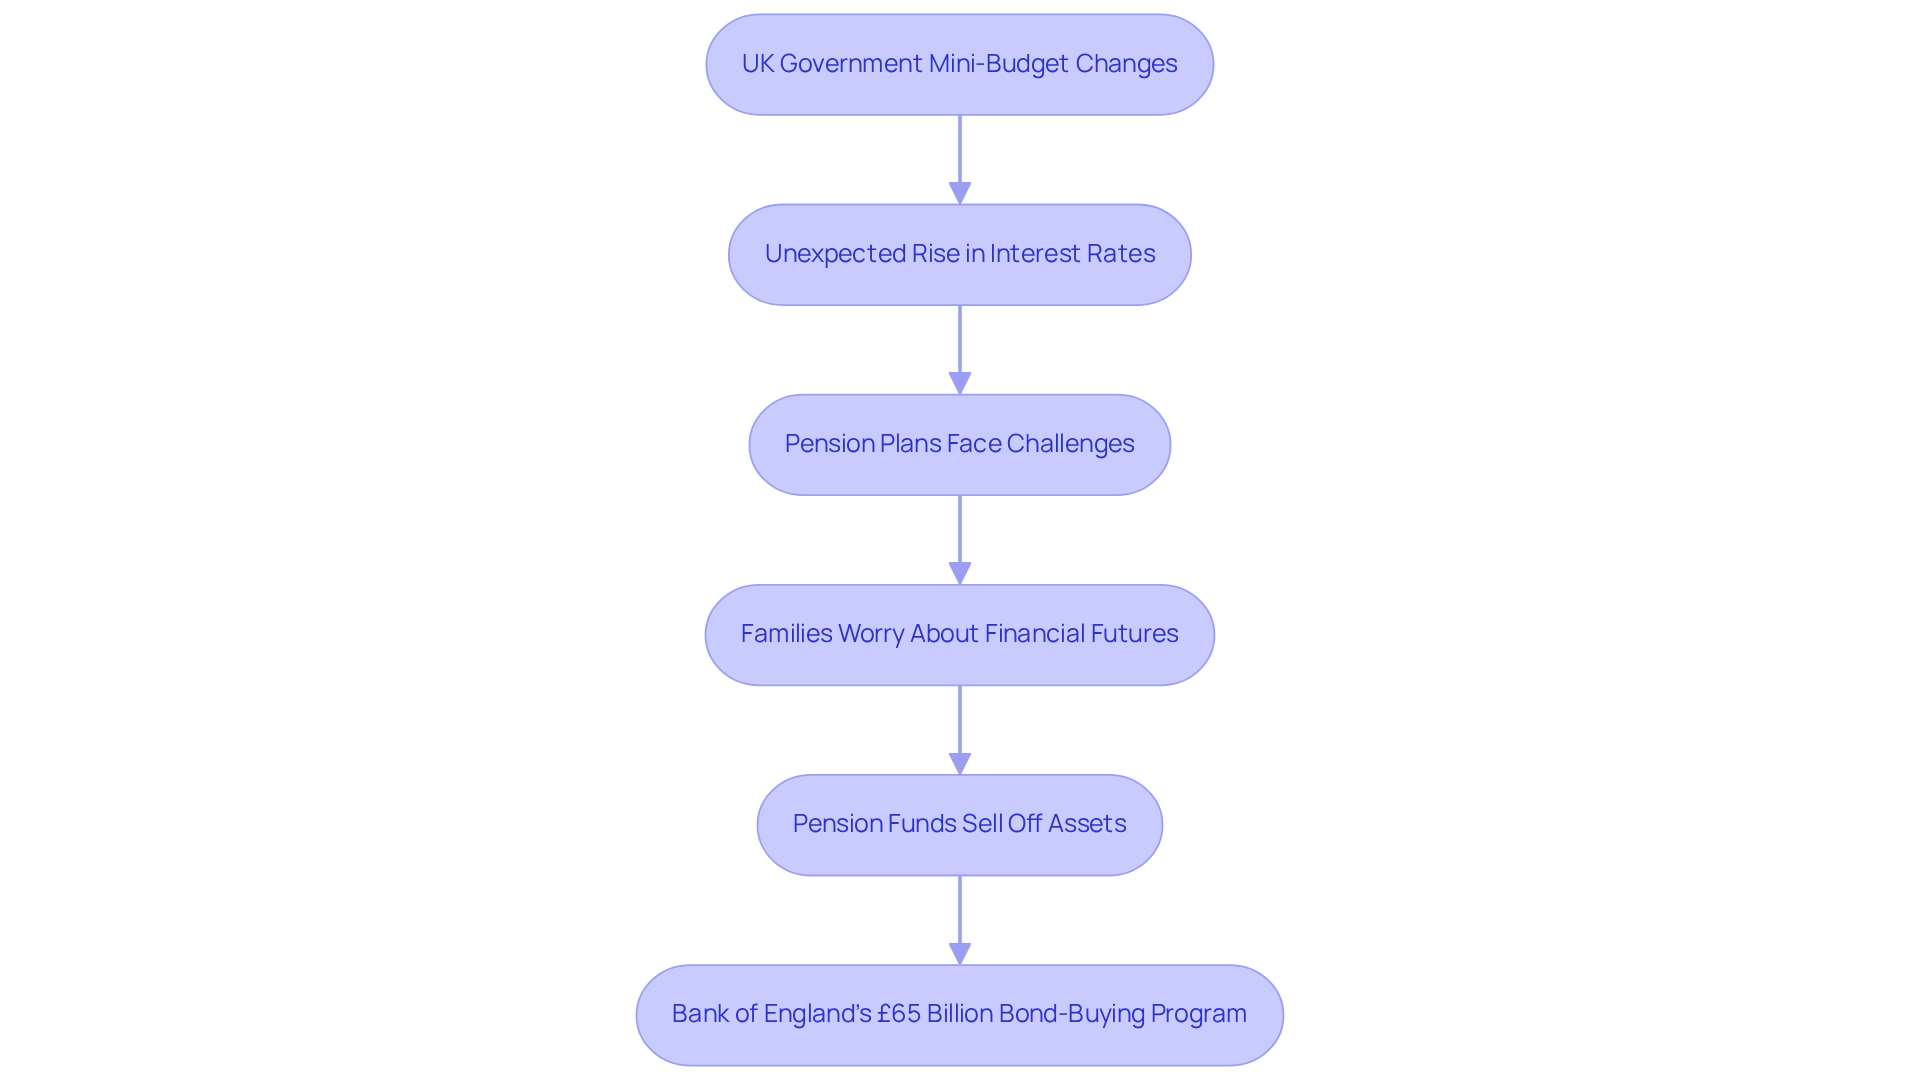
Imagine facing unexpected financial challenges just when you thought you had a secure plan for your family’s future. The recent changes in the UK government’s mini-budget have left many feeling uncertain, causing interest rates to rise unexpectedly. As a result, many pension plans faced challenges that made it hard for families to feel secure about their savings. The sudden rise in interest rates forced pension funds to sell off assets, leaving families worried about their financial futures.
In 2022, many families saw their pension plans take a hit, with returns dropping significantly, which was understandably distressing. James Bingham pointed out that not all schemes were affected equally, raising concerns for families about why some suffered while others did not. The Bank of England stepped in with a £65 billion bond-buying program to help ease the liquidity challenges faced by pension funds. However, the uncertainty surrounding LDI portfolios is still present, as the LDI crisis explained continues to affect them.
Understanding these economic shifts can empower you to make informed decisions that protect your family’s financial well-being. We’re here for you, ready to help you navigate this journey together.
Analyze the Implications of the LDI Crisis on Family Wealth Management
Imagine facing a financial storm that shakes your family’s future; the LDI crisis explained is that storm, affecting how we manage our wealth and plan for our children’s education and our retirement. Families may feel overwhelmed by the need to manage their finances during uncertain times.
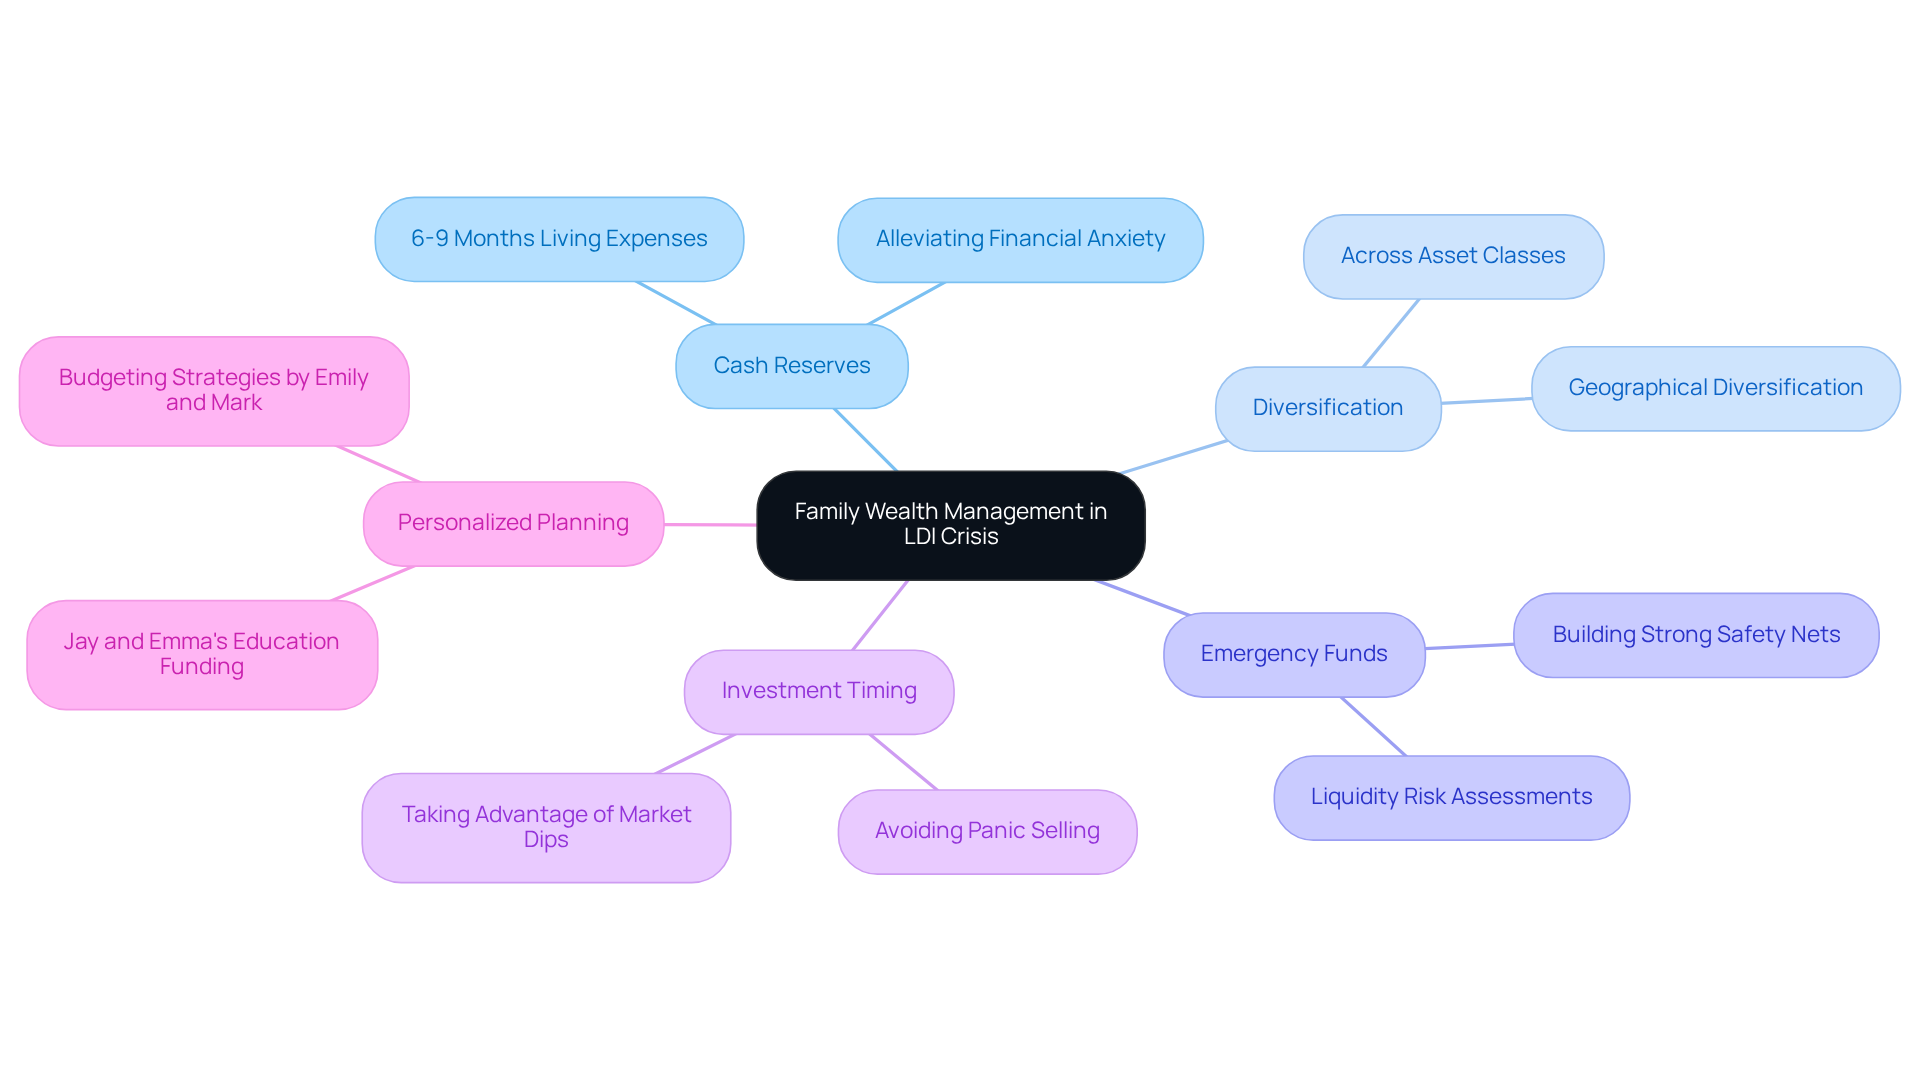
During these challenging times, it’s crucial for families to have enough cash reserves to weather the storm and keep their financial plans on track. Financial expert Douglas Boneparth suggests that families should aim for six to nine months of living expenses in cash, giving them a stronger safety net during market ups and downs.
The recent forced asset sales by pension funds remind us of the importance of not putting all our eggs in one basket and the need for a diversified investment strategy. By learning from these experiences, families can adopt stronger planning methods, like building emergency funds and timing their investments to meet their financial goals.
With a staggering $124 trillion expected to change hands in the U.S. by 2048, now is the time for families to rethink their wealth management strategies for lasting impact. Having a solid plan and a mix of investments is key to protecting your family’s future during these unpredictable times.
Take Jay and Emma, for instance; they’ve found a way to fund their children’s education while also saving for retirement, striking a balance that works for their family. Similarly, Emily and Mark have gained the freedom to choose whether to continue working by using budgeting strategies that fit their family’s needs.
At Bright Advisers, we help families create personalized wealth management plans that address immediate financial needs while securing their future through services like retirement income strategies and education funding.
Apply Lessons from the LDI Crisis to Enhance Financial Planning
Imagine navigating a financial storm without a clear plan – how would that impact your family’s future? To enhance financial planning in light of the LDI crisis, families should consider several key strategies:
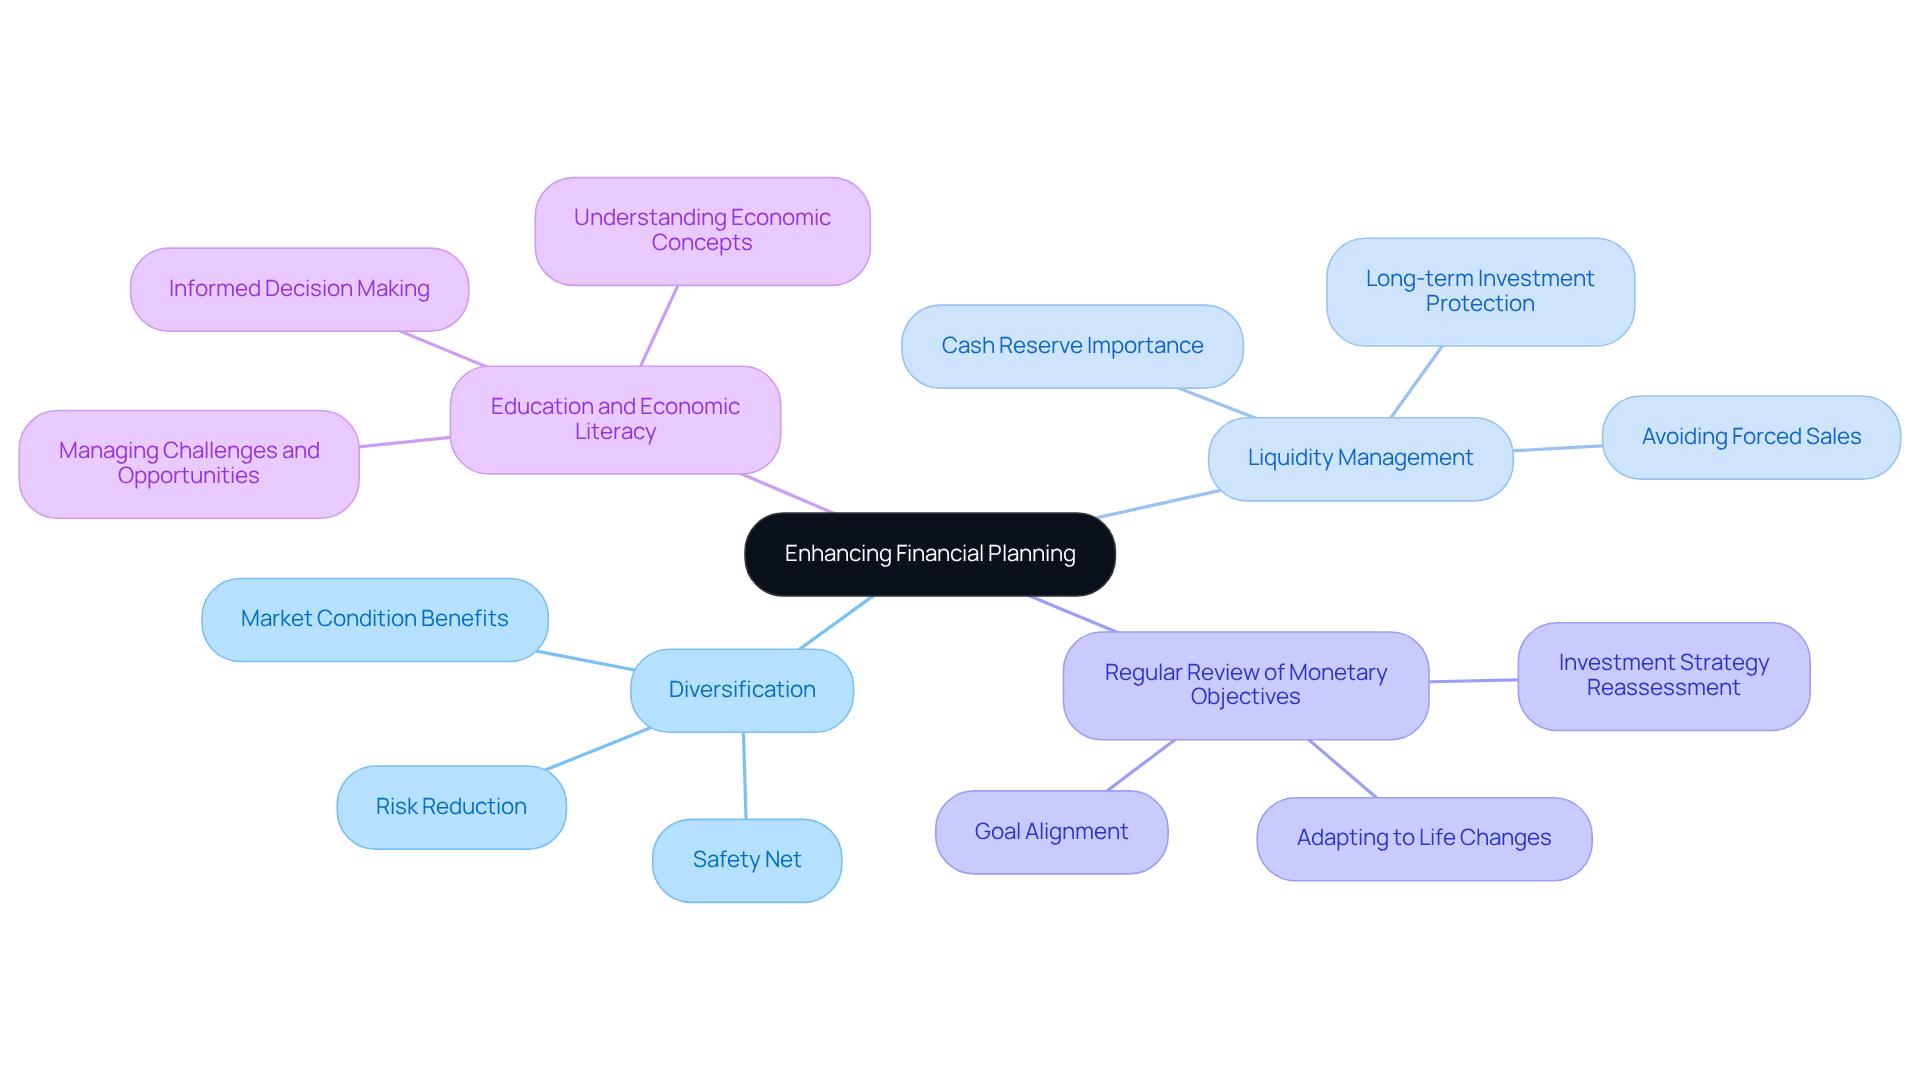
- Diversification: Think of diversification as a safety net – spreading your investments can help protect your family from financial falls. By avoiding concentration in a single asset class, you can reduce risk and enhance the resilience of your portfolio. This approach not only minimizes potential losses but also allows you to benefit from different market conditions.
- Liquidity Management: It’s crucial to have a cash reserve ready for those unexpected moments that life throws your way. This ensures that you’re not forced to sell investments at a loss during a crisis. Having a monetary buffer means you can navigate economic changes without jeopardizing your long-term investment plans.
- Regular Review of Monetary Objectives: Regularly checking in on your financial goals helps ensure you’re on the right path, especially as life changes happen. Periodically reassessing your monetary objectives and investment strategies keeps you aligned with shifting market conditions and personal circumstances.
- Education and Economic Literacy: Investing time in understanding economic concepts and market dynamics empowers you to make informed decisions. By promoting economic literacy, you can better manage challenges and seize opportunities in your financial journey.
By embracing these strategies, you’re not just securing your finances; you’re building a legacy of stability for your children. Together, we can navigate this journey and ensure a brighter financial future for your family.
Conclusion
Many families feel overwhelmed by financial jargon and uncertain economic conditions, but understanding the LDI crisis can help you feel more secure about your future. When you understand Liability Driven Investment, it becomes easier to navigate the ups and downs of the economy. This knowledge helps you align your investments with your family’s long-term goals, so you’re ready for whatever comes your way.
Throughout this article, we’ve shared key insights about the events leading to the LDI crisis, the importance of maintaining liquidity, and the necessity of diversification in investment strategies. Families are encouraged to:
- Build cash reserves
- Regularly review their financial objectives to adapt to changing circumstances
Real-life examples illustrate how families like Jay & Emma and Emily & Mark have successfully implemented these strategies to balance their immediate needs with future aspirations.
The lessons from the LDI crisis remind us that it’s time for families to rethink how they manage their wealth. By focusing on education, diversifying your investments, and planning ahead, you can weather economic storms and build a stable future for your family. Reaching out to a fiduciary advisor like Bright Advisers can give you the personalized support you need to navigate these challenges and secure a brighter financial future for your family.
Frequently Asked Questions
What is Liability Driven Investment (LDI)?
Liability Driven Investment (LDI) is a strategic approach primarily used by pension funds and institutions to manage their liabilities effectively by aligning cash flows from investments with the timing and amounts of future liabilities, such as pension payouts.
What is the purpose of LDI?
The purpose of LDI is to reduce risks from interest rate changes and ensure that funds are available when needed, helping organizations create a stable financial base to meet their obligations without taking on excessive risk.
How can LDI benefit families?
For families, understanding LDI can help them align their investments with financial goals, securing a brighter future for their children by managing financial risks effectively.
What methods does Bright Advisers use in LDI?
Bright Advisers employs innovative technology to create personalized portfolios using methods like smart beta and factor investing to help families manage their financial futures.
What are the typical allocations for LDI in pension plans?
Allocations for LDI in pension plans typically range from 30% to 60% of the portfolio, indicating its growing acceptance and effectiveness in managing economic stability.
What is the glide path approach in LDI?
The glide path approach allows families to gradually adopt LDI methods as their financial situations improve, aligning investment strategies with their evolving needs.
Why is regular monitoring of LDI strategies important?
Regular monitoring of LDI strategies is essential, especially for underfunded plans, to ensure they remain effective in meeting future obligations.
How have families benefited from Bright Advisers’ LDI solutions?
Families like Jay & Emma and Emily & Mark have found tailored solutions through Bright Advisers that ease their financial worries and help secure their children’s futures.
List of Sources
- Define Liability Driven Investment (LDI) and Its Purpose
- Frequently asked questions: Liability-driven investing (LDI) for pension plans (https://milliman.com/en/insight/frequently-asked-questions-liability-driven-investing-pension)
- Liability-Driven Investing (LDI) for Defined Benefit Plans (https://russellinvestments.com/content/ri/us/en/institutional-investor/solutions/investment-programs/defined-benefit/liability-driven-investing.html)
- What is Liability Driven Investment & LDI Pensions? (https://xpsgroup.com/news-views/insights-briefings/what-liability-driven-investment-and-ldi-pensions)
- What is LDI? Foundations of Liability-Driven Investing (https://business.bofa.com/en-us/content/workplace-benefits/what-is-liability-driven-investing-ldi.html)
- Examine the Events Leading to the LDI Crisis
- Elevated inflation and rising interest rates led to widespread investment losses: Pension Markets in Focus 2023 (https://oecd.org/en/publications/pension-markets-in-focus-2023_28970baf-en/full-report/component-3.html)
- How the pensions industry dealt with the LDI crisis (https://professionalpensions.com/analysis/4057307/pensions-industry-dealt-ldi-crisis)
- LDI and the Liz Truss mini budget: One year on, what – if anything – has changed? (https://pensions-expert.com/investment/ldi-and-the-liz-truss-mini-budget-one-year-on-what-if-anything-has-changed/65188.article)
- What caused the LDI crisis? (https://bankunderground.co.uk/2024/07/26/what-caused-the-ldi-crisis)
- Analyze the Implications of the LDI Crisis on Family Wealth Management
- 2025 Family Office Report: Trends, Statistics, and Insights (https://privatebank.bankofamerica.com/articles/family-office-report.html)
- ‘Volatility is part of the game’: What financial advisors are telling investors about market turmoil (https://cnbc.com/amp/2025/03/11/what-financial-advisors-are-telling-investors-about-market-volatility.html)
- LDI crisis is a ‘stark reminder’ on governance, diversification and risk management | SEI (https://seic.com/en-gb/institutional-investors/our-insights/ldi-crisis-stark-reminder-governance-diversification-and-risk-management)
- Volatilityquotes — Investment Masters Class (https://mastersinvest.com/volatilityquotes)
- Quotes on Volatility • Novel Investor (https://novelinvestor.com/quote-category/volatility)
- Apply Lessons from the LDI Crisis to Enhance Financial Planning
- Report on the Economic Well-Being of U.S. Households in 2024 – May 2025 – Savings and Investments (https://federalreserve.gov/publications/2025-economic-well-being-of-us-households-in-2024-savings-and-investments.htm)
- Rising Liquidity among U.S. Households and Its Policy Implications (https://stlouisfed.org/on-the-economy/2024/may/rising-liquidity-us-households-policy-implications)
- Money in the Bank? Assessing Families’ Liquid Savings using the Survey of Consumer Finances (https://federalreserve.gov/econres/notes/feds-notes/assessing-families-liquid-savings-using-the-survey-of-consumer-finances-20181119.html)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading