

Key Highlights:
- Rate of return (RoR) measures profit or loss as a percentage of the initial investment.
- RoR calculation: RoR = [(Final Value – Initial Value) / Initial Value] x 100.
- Example: Investing $1,000 that grows to $1,100 results in a RoR of 10%.
- Real-life scenarios illustrate RoR: Selling a house for a profit of 34% or a loss of 25%.
- RoR is crucial for financial planning, helping families evaluate investment strategies.
- Types of RoR include nominal, real, and internal rate of return (IRR), each serving different purposes.
- Nominal RoR does not account for inflation, while real RoR adjusts for it, providing a clearer picture of purchasing power.
- IRR is used in capital budgeting to assess the viability of investments based on cash flows.
- Understanding RoR assists families in making informed decisions to enhance long-term wealth.
- Practical examples demonstrate how to calculate RoR, real RoR, and IRR, aiding in financial planning.
Introduction
Understanding the complexities of financial returns is crucial for families looking to secure their economic future. The rate of return is more than just a number; it’s a vital measure that shows how well investments are performing. This insight can shape your financial strategies in meaningful ways.
Imagine if you could turn that seemingly simple percentage into a powerful tool for your family’s financial decisions. What factors should you consider to truly grasp its impact? By exploring these elements, you can empower yourself to make informed choices that align with your long-term goals.
We’re here for you as you navigate the world of investments. Together, we can uncover the insights that will help you feel confident in your financial journey. Remember, understanding your financial returns is not just about numbers; it’s about building a secure future for your loved ones.
Defining Rate of Return in Economics
Understanding the percentage of profit or loss is crucial for your family’s financial health. It helps you understand how your investments are performing over time, which is illustrated by the rate of return definition economics, expressed as a percentage of what you initially spent. This measure acts as a vital sign of your financial performance, allowing you to assess the rate of return definition economics and how well your resources are being utilized.
Imagine if you invested $1,000 in a mutual fund. After a year, if that investment grows to $1,100, you can calculate your rate of return (RoR) like this:
RoR = [(Final Value – Initial Value) / Initial Value] x 100 = [(1,100 – 1,000) / 1,000] x 100 = 10%.
This straightforward calculation illustrates how the rate of return definition economics provides a clear picture of a project’s profitability. It’s an essential tool for families looking to secure their financial futures. As we move into 2025, understanding RoR becomes even more important as you explore various investment options and strive to maximize your gains in a fluctuating market.
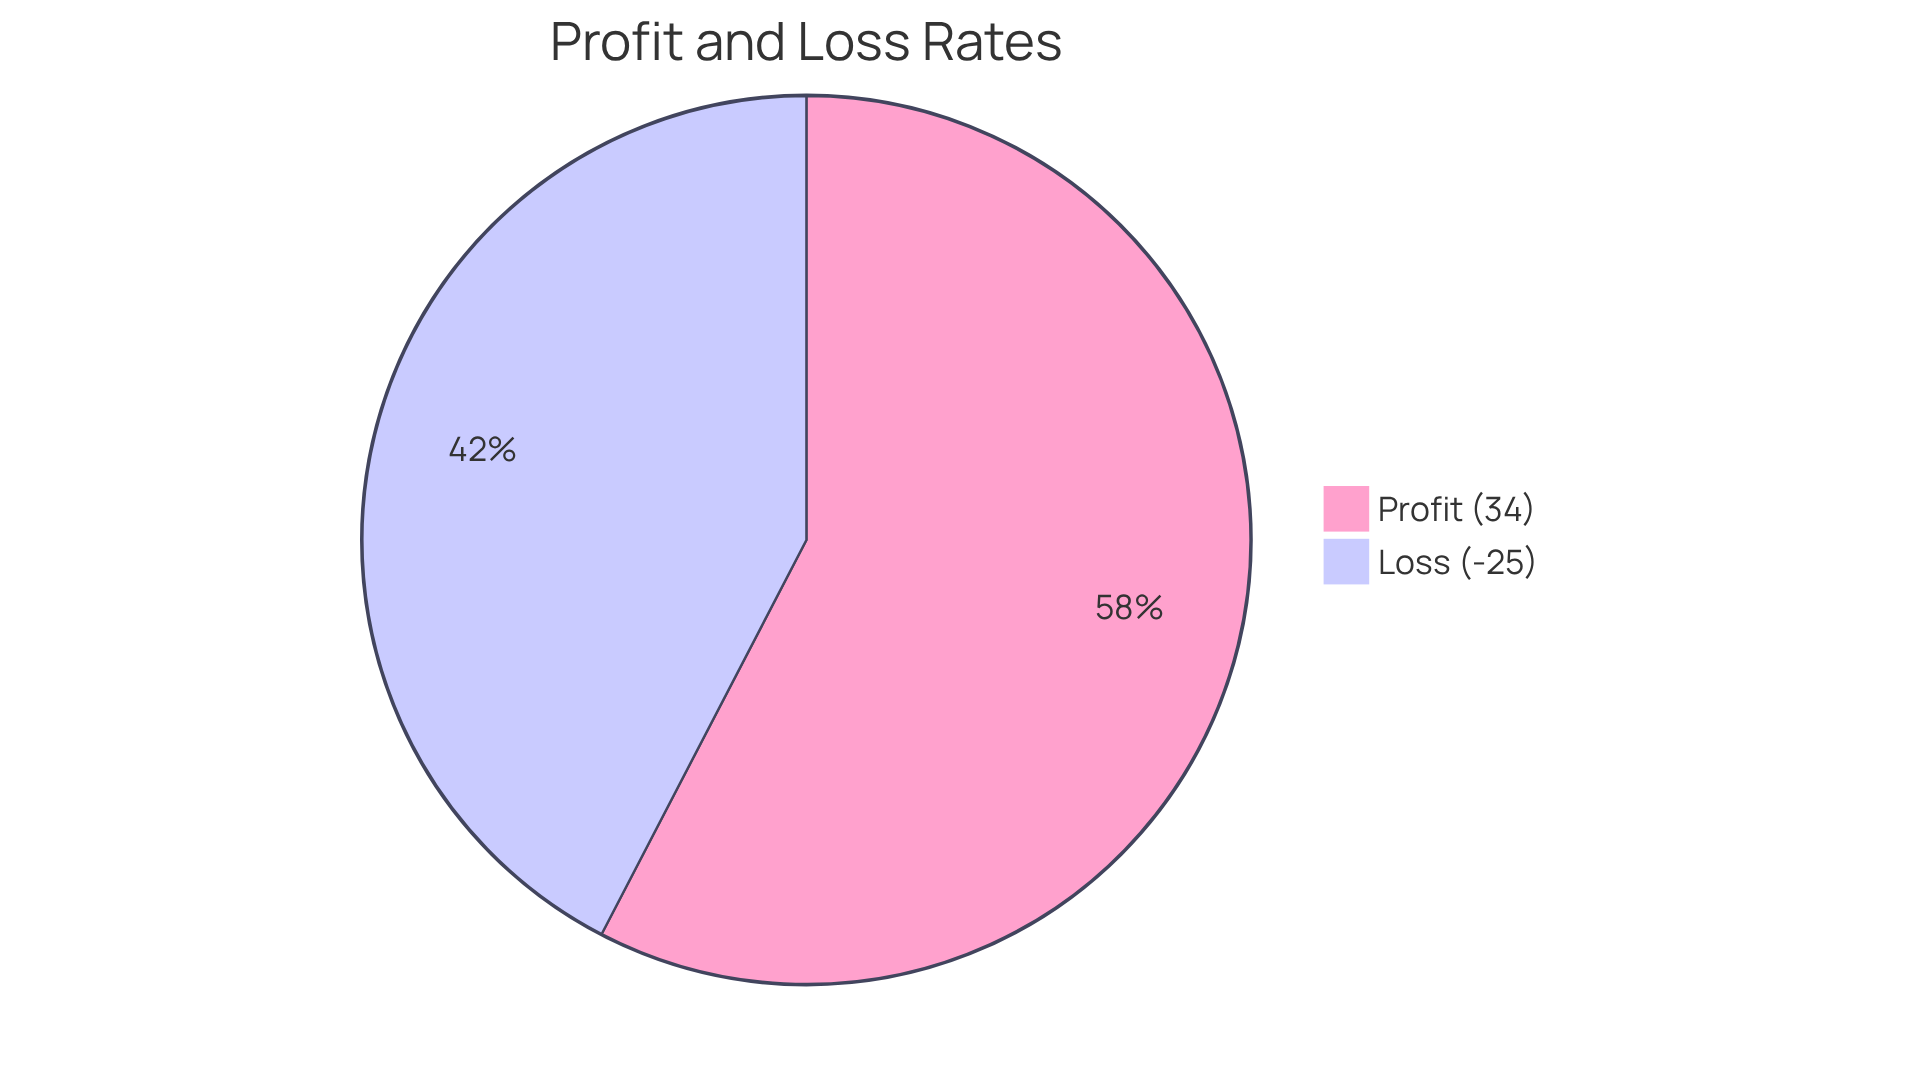
Real-life examples can really bring this concept home. Picture a family buying a house for $250,000 and selling it for $335,000. They realize a solid profit of 34%. Conversely, if they sell the house for $187,500, they face a loss of 25%. These scenarios underscore the importance of the rate of return definition economics in evaluating your financial performance and making informed decisions.
When , it’s also essential to consider the actual yield, which accounts for inflation and gives you a clearer picture of your asset growth. As you prepare for the future, understanding the nuances of the rate of return definition economics can empower you to make strategic financial choices that align with your family’s long-term goals.
Remember, we’re here for you. Together, we can navigate this journey toward financial security.
Importance of Rate of Return for Financial Planning
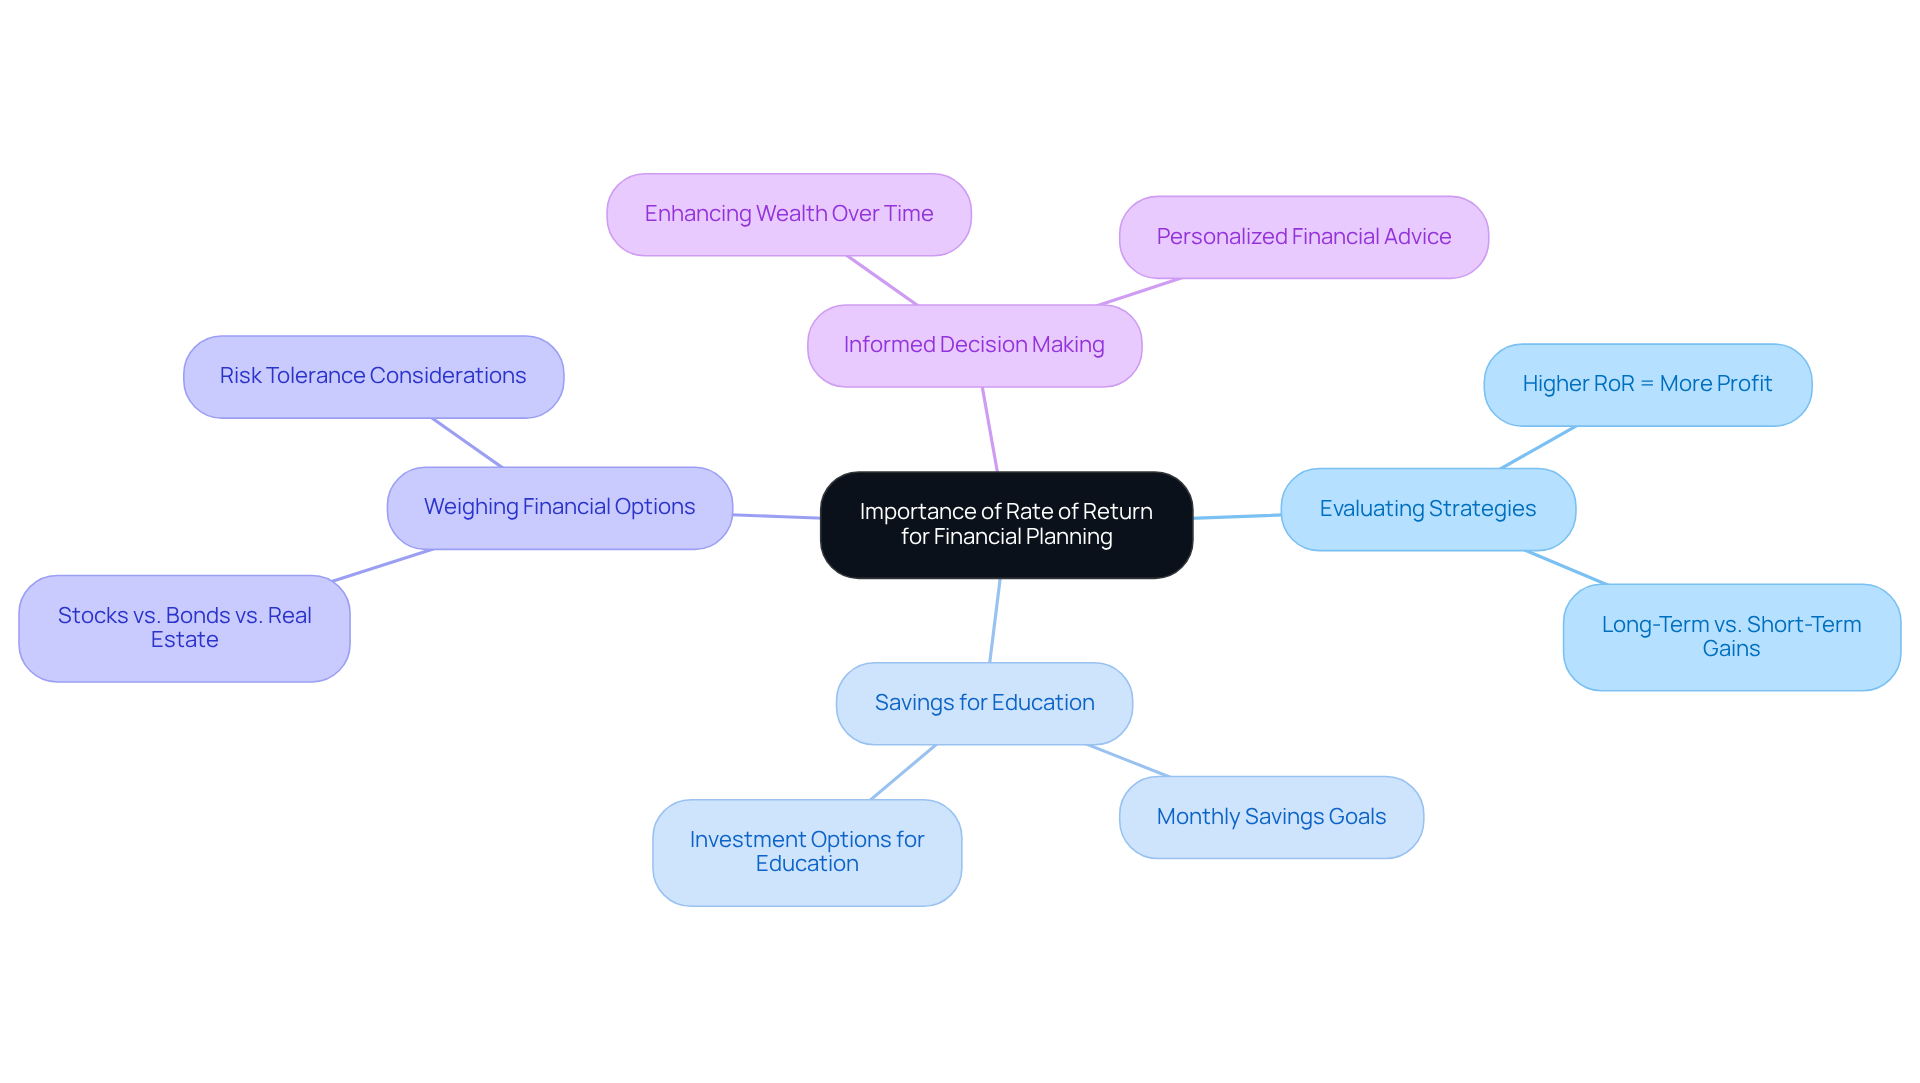
Understanding the is crucial for your family’s financial planning. It’s not just a number; it’s a way to evaluate how well your strategies are working. A higher RoR means a more profitable opportunity, which is especially important for families focused on building long-term wealth.
Imagine setting aside funds for your children’s education. Knowing the expected rate of return definition economics on your investments can help you determine how much you need to save each month to meet your goals. It’s all about making those dreams a reality, isn’t it?
The rate of return definition economics also assists you in weighing different financial options such as stocks, bonds, or real estate. By understanding these choices, you can select the ones that align with your family’s risk tolerance and financial aspirations.
By understanding the rate of return definition economics, you can make informed decisions that significantly enhance your family’s wealth over time. Remember, we’re here for you, guiding you through this journey toward financial security.
Types of Rate of Return: Understanding Variations
Understanding the [rate of return definition](https://brightadvisers.com/?p=9981) economics and the different types of rates of return is crucial for families looking to secure their financial future. Let’s explore these concepts together, so you can feel more confident in your financial planning.
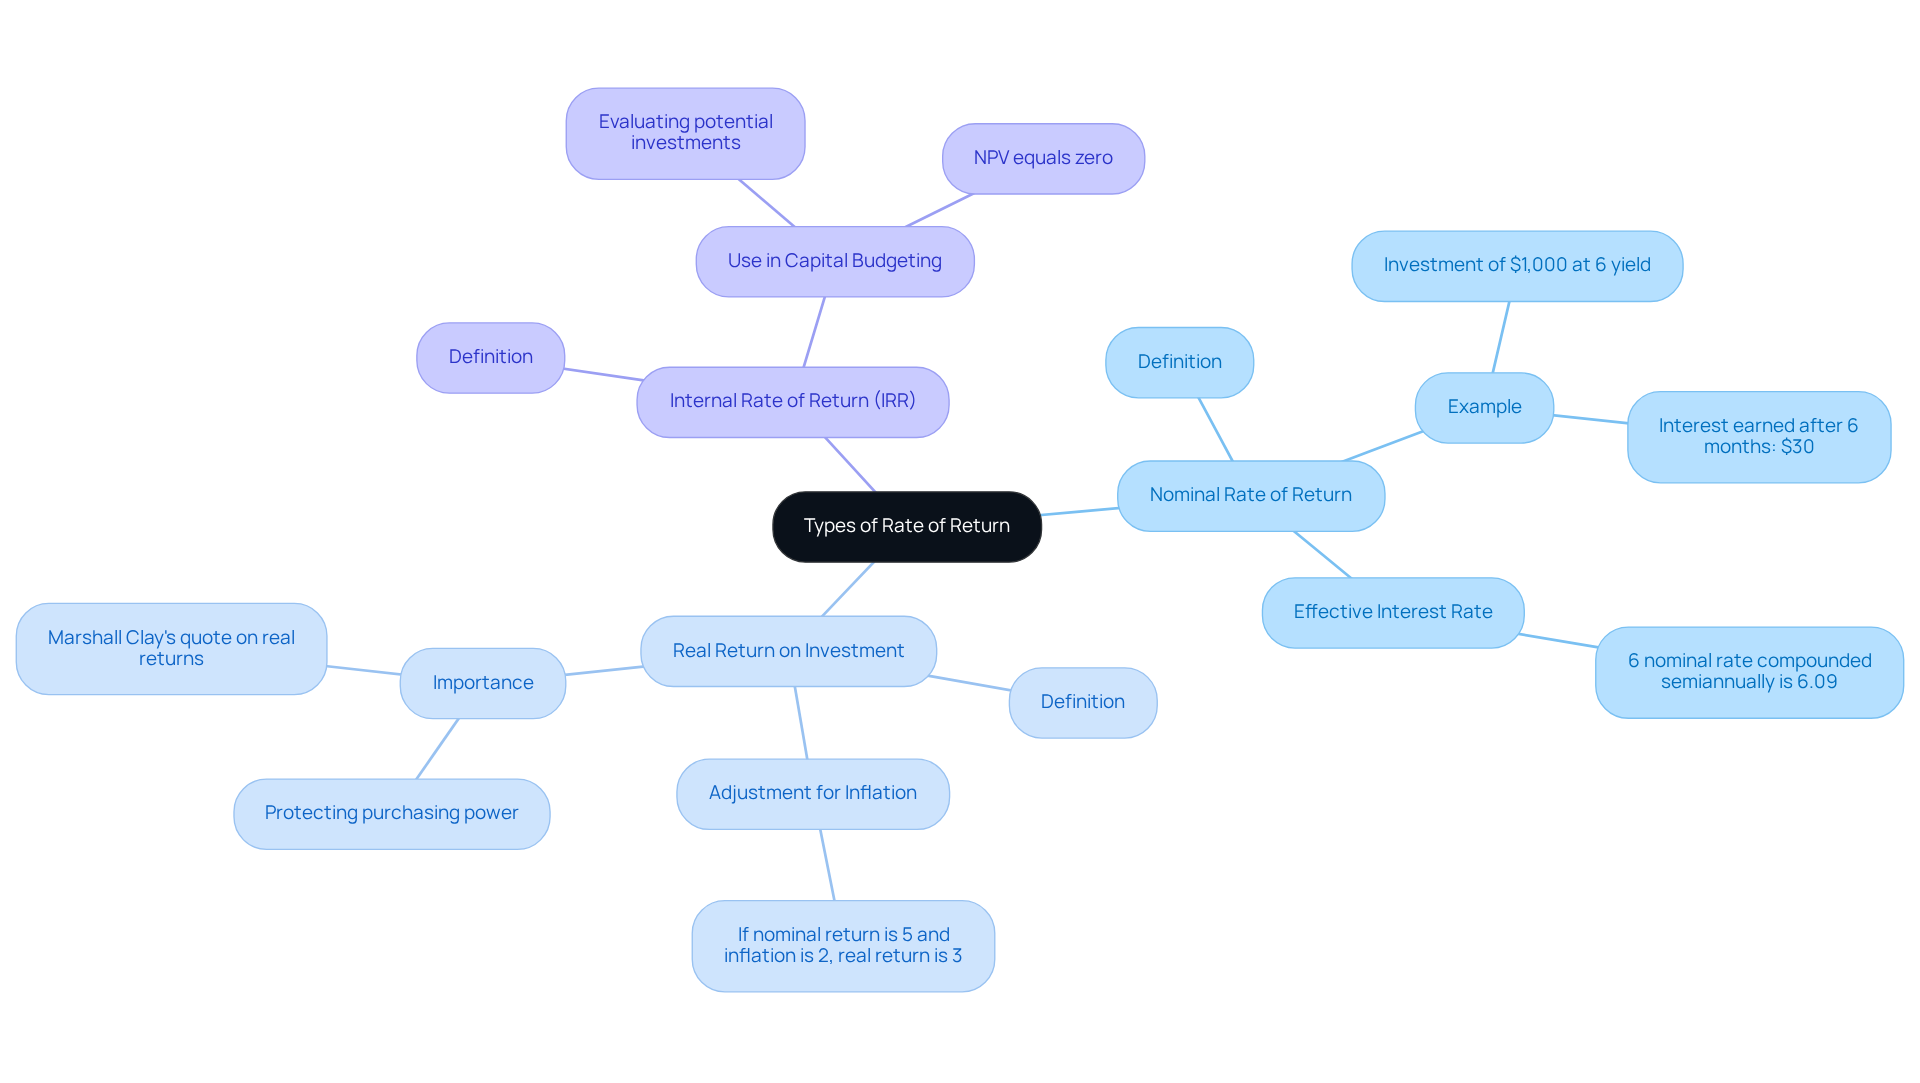
- Nominal Rate of Return: Think of this as the straightforward percentage return on your investment, calculated without considering inflation. It shows the total earnings from an investment over a specific time. For example, if you invest $1,000 in a bond with a 6% annual yield compounded semiannually, you’d earn $30 in interest after six months. This is how nominal gains work.
- Real Return on Investment: This figure takes inflation into account, giving you a clearer picture of your actual purchasing power. If your investment grows by 5% but inflation is at 2%, your real yield is about 3%. Understanding this adjustment is vital for grasping how over time. As Marshall Clay, a Partner and Senior Advisor, wisely notes, “Comprehending the distinction between real and nominal returns is essential for successful investing.”
- Internal Rate of Return (IRR): This one’s a bit more complex, often used in capital budgeting to evaluate potential investments. It’s the discount rate that makes the net present value (NPV) of all cash flows from an asset equal to zero. This helps families assess the viability of different [financial opportunities](https://brightadvisers.com/?p=10998).
It’s also important to think about how inflation affects various asset classes. While stocks tend to outpace inflation over time, cash and bonds might lose value. By diversifying your investments across different asset categories, you can help protect your actual value from inflation, ensuring your family maintains its buying power.
By grasping these differences and considering the broader effects of inflation, you can better evaluate your financial performance. Remember, we’re here for you, ready to support you in making strategic choices that align with your family’s goals.
Calculating Rate of Return: Practical Examples
Understanding profit percentages can be a straightforward process, especially when considering how low fund charges can enhance for families. Let’s explore a few relatable examples:
- Simple Rate of Return: Imagine a family investing $2,000 in a stock and selling it a year later for $2,500. The calculation would be:
RoR = [(2500 – 2000) / 2000] x 100 = 25%
This means they enjoyed a 25% return on their investment, showcasing how effective investment strategies can foster [financial growth](https://brightadvisers.com/?p=10183). - Real Rate of Return: Now, picture the same investment yielding a nominal return of 8%, but facing an inflation rate of 3%. The real rate of return would be:
Real RoR = Nominal RoR – Inflation Rate = 8% – 3% = 5%
This highlights the actual growth in purchasing power, a crucial factor for families as they plan their financial futures. - Internal Rate of Return (IRR): Consider a project that requires an initial investment of $10,000, with expected cash inflows of $3,000 each year for 5 years. Families can use [financial calculators or software](https://brightadvisers.com/?p=10183) to determine the IRR, which helps evaluate the project’s feasibility.
Understanding IRR is vital for families looking to strengthen their financial strategies and secure [long-term stability](https://whitecoatinvestor.com/expected-returns).
These examples illustrate how families can apply the [rate of return definition economics](https://sofi.com/learn/content/rate-of-return) in their financial planning. By doing so, they can make informed investment choices while benefiting from [Bright Advisers’ commitment to minimal fund fees](https://brightadvisers.com/?p=11007) and personalized financial planning. Remember, we’re here for you, and together, we can navigate this journey toward a secure financial future.

Conclusion
Understanding the rate of return is crucial for families looking to secure their financial future. It’s a key metric that reflects how well investments are performing, helping families make informed choices about where to put their resources. By grasping this concept, families can navigate the complexities of financial planning more effectively, ensuring their strategies align with their long-term goals.
Throughout this discussion, we’ve shared important insights, including the different types of rate of return – nominal, real, and internal – and why they matter when evaluating investment opportunities. Real-life examples show how these calculations can influence financial decisions, whether it’s saving for education or considering the purchase of a home. By learning how to calculate and interpret these rates, families can improve their financial outcomes and build lasting wealth.
In a world where financial landscapes are always shifting, understanding the rate of return is more important than ever. Families are encouraged to actively engage with their financial planning, using the tools and knowledge available to make smart choices. By prioritizing education on this topic, families can empower themselves to reach their financial dreams and secure a bright future for generations to come.
Imagine if you could confidently navigate your financial journey, knowing you’re making the best choices for your family. Together, we can explore these concepts and ensure that your financial aspirations become a reality. Remember, we’re here for you every step of the way.
Frequently Asked Questions
What is the rate of return (RoR) in economics?
The rate of return (RoR) in economics is the percentage of profit or loss on an investment, expressed as a percentage of the initial amount spent. It measures how well investments are performing over time.
How is the rate of return calculated?
The rate of return is calculated using the formula: RoR = [(Final Value – Initial Value) / Initial Value] x 100. For example, if you invest $1,000 and it grows to $1,100, the RoR would be 10%.
Why is understanding the rate of return important for families?
Understanding the rate of return is crucial for families as it helps assess financial performance, evaluate investment profitability, and make informed decisions to secure financial health and future stability.
Can you provide an example of the rate of return in real life?
Yes, for instance, if a family buys a house for $250,000 and sells it for $335,000, they realize a profit of 34%. Conversely, if they sell it for $187,500, they incur a loss of 25%. These examples illustrate the practical application of RoR in evaluating financial decisions.
How does the rate of return relate to retirement planning?
When planning for retirement, it’s important to consider the actual yield, which accounts for inflation. Understanding the rate of return helps provide a clearer picture of asset growth and assists in making strategic financial choices aligned with long-term goals.
What is the significance of understanding the rate of return as we approach 2025?
As we approach 2025, understanding the rate of return becomes increasingly important as families explore various investment options and strive to maximize gains in a fluctuating market, ensuring better financial planning and security.
List of Sources
- Defining Rate of Return in Economics
- Rate of Return (RoR): Formula and Calculation Examples | SoFi (https://sofi.com/learn/content/rate-of-return)
- Rate of Return (RoR): Meaning, Formula, and Examples (https://investopedia.com/terms/r/rateofreturn.asp)
- What Are the Average 401(k) Returns? See How Yours Compare (https://investopedia.com/401-k-returns-and-how-they-compare-to-others-8779625)
- Retirement Account Statistics 2025 – NerdWallet (https://nerdwallet.com/retirement/learn/retirement-statistics)
- What Is a Realistic Rate of Return for Retirement? (https://smartasset.com/retirement/conservative-rate-of-return-in-retirement)
- Importance of Rate of Return for Financial Planning
- Top 150 Financial Planning Quotes [2025] (https://digitaldefynd.com/IQ/financial-planning-quotes)
- The Top 25 Investing Quotes of All Time (https://investopedia.com/financial-edge/0511/the-top-17-investing-quotes-of-all-time.aspx)
- Retirement Account Statistics 2025 – NerdWallet (https://nerdwallet.com/retirement/learn/retirement-statistics)
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- Newsroom | Northwestern Mutual – Planning & Progress Study 2025 (https://news.northwesternmutual.com/planning-and-progress-study-2025)
- Types of Rate of Return: Understanding Variations
- Interest Rates Explained: Nominal, Real, and Effective (https://investopedia.com/articles/investing/082113/understanding-interest-rates-nominal-real-and-effective.asp)
- Nominal vs. Real Return: How Inflation Affects Investments (https://smartasset.com/investing/nominal-vs-real-return)
- Understanding Real vs. Nominal Rates of Return (https://welchgroup.com/understanding-real-vs-nominal-rates-of-return)
- Calculating Rate of Return: Practical Examples
- Rate of Return (RoR): Formula and Calculation Examples | SoFi (https://sofi.com/learn/content/rate-of-return)
- Average Investment Return Rate (ROI) | White Coat Investor (https://whitecoatinvestor.com/expected-returns)
- A 12% retirement return assumption is ‘absolutely nuts,’ expert says. Here’s a realistic rate to expect (https://cnbc.com/2024/01/19/heres-the-rate-of-return-you-may-expect-on-your-retirement-portfolio.html)
- The Top 25 Investing Quotes of All Time (https://investopedia.com/financial-edge/0511/the-top-17-investing-quotes-of-all-time.aspx)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading