

Overview
The Uniform Transfers to Minors Account (UTMA) is a custodial account designed specifically for adults to transfer various assets to minors, offering significant tax benefits and flexibility in managing those assets until the child reaches adulthood. Imagine being able to simplify the gifting process while having access to a broader range of asset types compared to UGMA accounts. This means families can accumulate wealth without facing contribution limits, making UTMA accounts a strategic choice for securing your children’s financial futures.
It’s important to understand that these accounts not only provide financial advantages but also nurture the values of family support and planning for the future. By choosing a UTMA account, you are taking a proactive step towards ensuring your children’s well-being. We’re here for you as you navigate this journey, helping you make informed decisions that align with your family’s goals. Together, we can create a solid foundation for your children’s financial success.
Key Highlights:
- UTMA accounts allow adults to transfer a variety of assets to minors, simplifying gifting without a formal trust.
- Custodians manage the funds until the minor reaches the age of majority, which varies by state (18-21 years).
- UTMA accounts provide tax benefits, with earnings taxed at the minor’s lower tax rate, enhancing savings potential.
- There are no contribution limits for UTMA accounts, allowing families to accumulate wealth significantly over time.
- Once assets are transferred, gifts are irrevocable, ensuring long-term financial planning stability.
- UTMA accounts offer greater asset flexibility compared to UGMA accounts, allowing for real estate and collectibles.
- Management flexibility in UTMA accounts enables custodians to make diverse investment decisions.
- Both UTMA and UGMA accounts enjoy favourable tax treatment, but UTMA offers broader asset inclusion.
- Custodial funds may impact financial aid eligibility as they are considered owned by the minor.
- Overall, UTMA accounts present a compelling option for families focused on securing their children’s financial futures.
Introduction
Navigating the path to secure your child’s financial future can feel overwhelming for many parents. The Uniform Transfers to Minors Account (UTMA) presents a valuable solution, offering a straightforward method to transfer assets while delivering significant tax benefits and flexibility.
But what truly sets UTMA accounts apart from other custodial options?
How can families harness these features to cultivate financial literacy and responsibility in their children?
Imagine if you could provide your child with the tools they need to thrive financially.
Exploring these questions reveals the potential of UTMA accounts as a thoughtful choice for nurturing the financial well-being of the next generation.
Define the Uniform Transfers to Minors Account (UTMA)
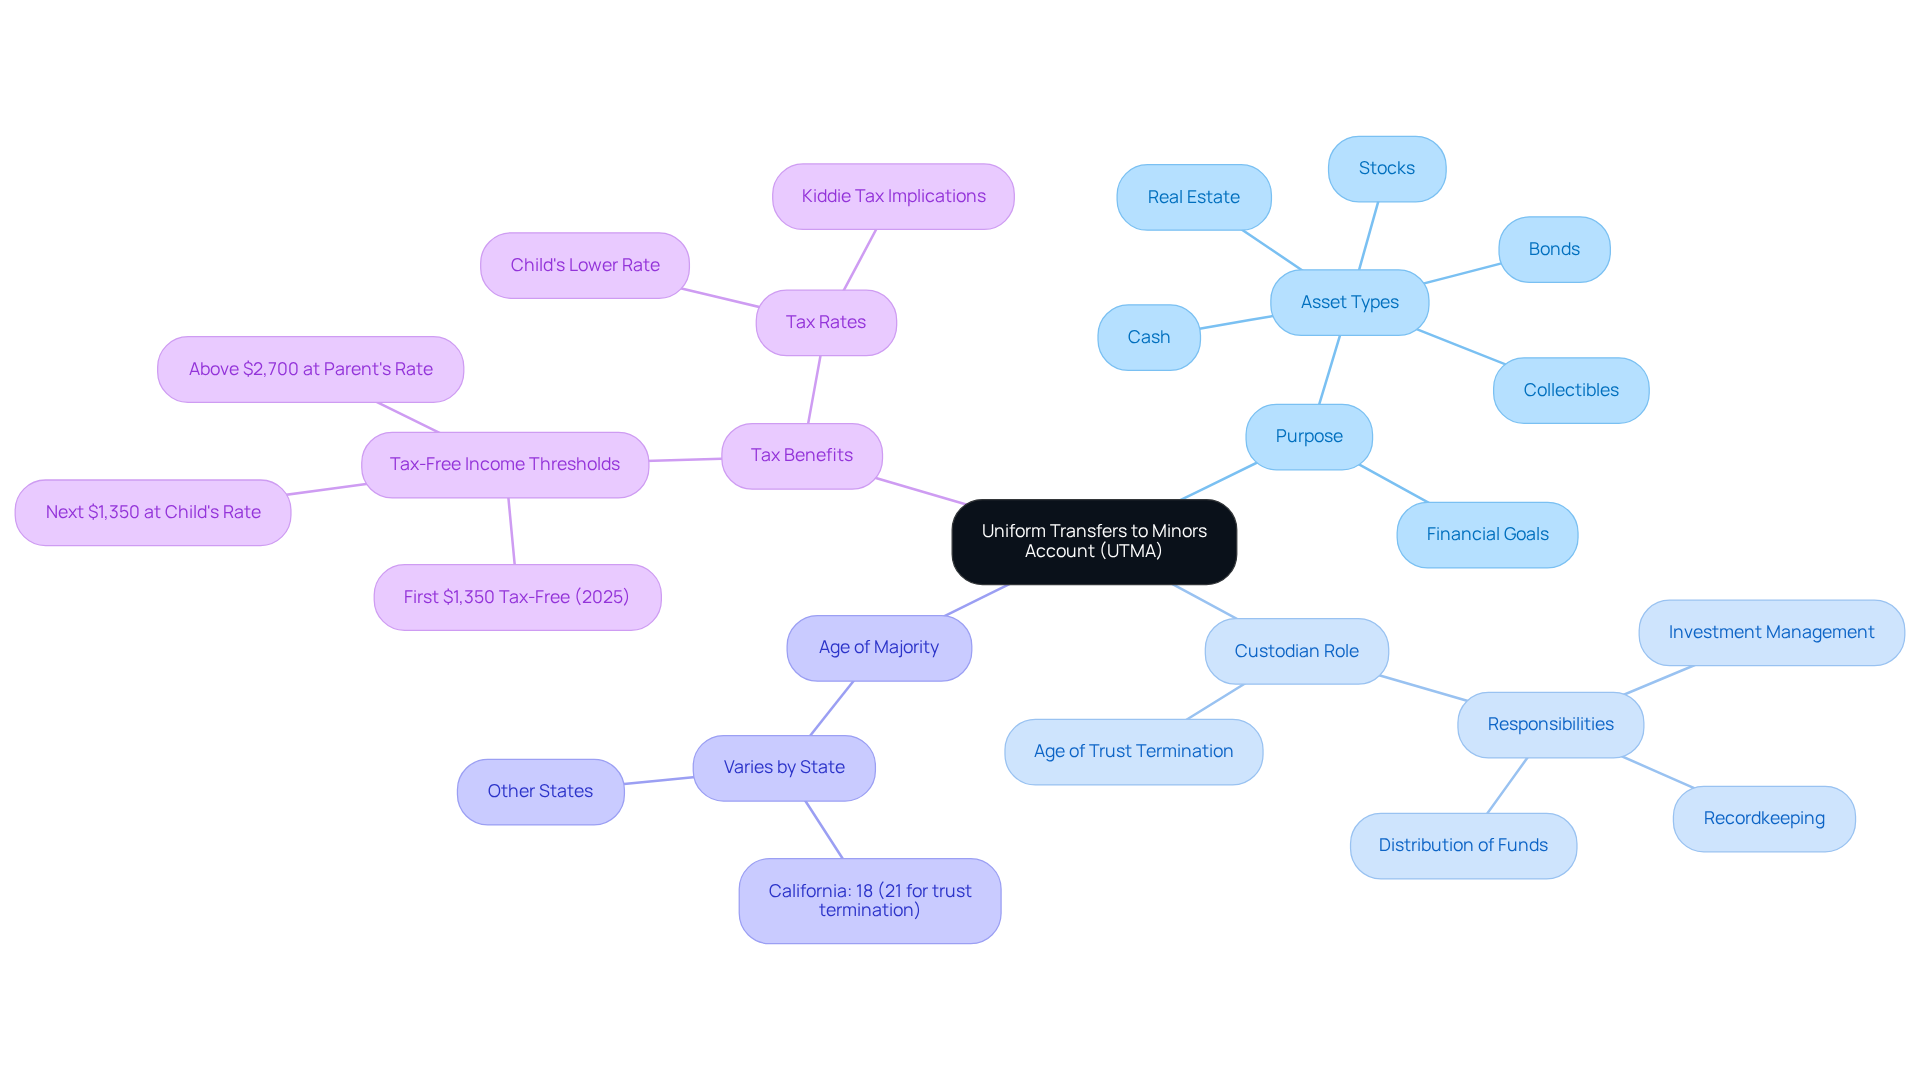
The Uniform Transfers to Minors account (UTMA) is a nurturing custodial setup established under state law. It allows adults to make uniform transfers to minors account, simplifying the process without the complexities associated with a formal trust. Imagine being able to gift your child cash, stocks, bonds, real estate, or even collectibles—all in one versatile option that supports your family’s financial goals.
As a custodian, typically a parent or guardian, you oversee these funds until your child reaches the age of majority. This age varies by state, generally between 18 and 21 years old. For example, in California, your child would be considered an adult at 18, but the trust can continue until they are 21, providing you with the opportunity to manage their funds a bit longer.
The uniform transfers to minors account not only streamlines the gifting process but also provides a tax-favored approach for saving for your child’s future. Earnings are taxed at your child’s lower income tax rate, up to specific thresholds. This flexibility and potential for tax savings make UTMA an appealing choice for families like yours, aiming to secure your children’s financial well-being.
Together, we can navigate this journey of financial planning, ensuring your child’s future is bright and secure. We’re here for you, ready to support you in making the best decisions for your family’s financial health.
Understand the Purpose and Importance of UTMA Accounts
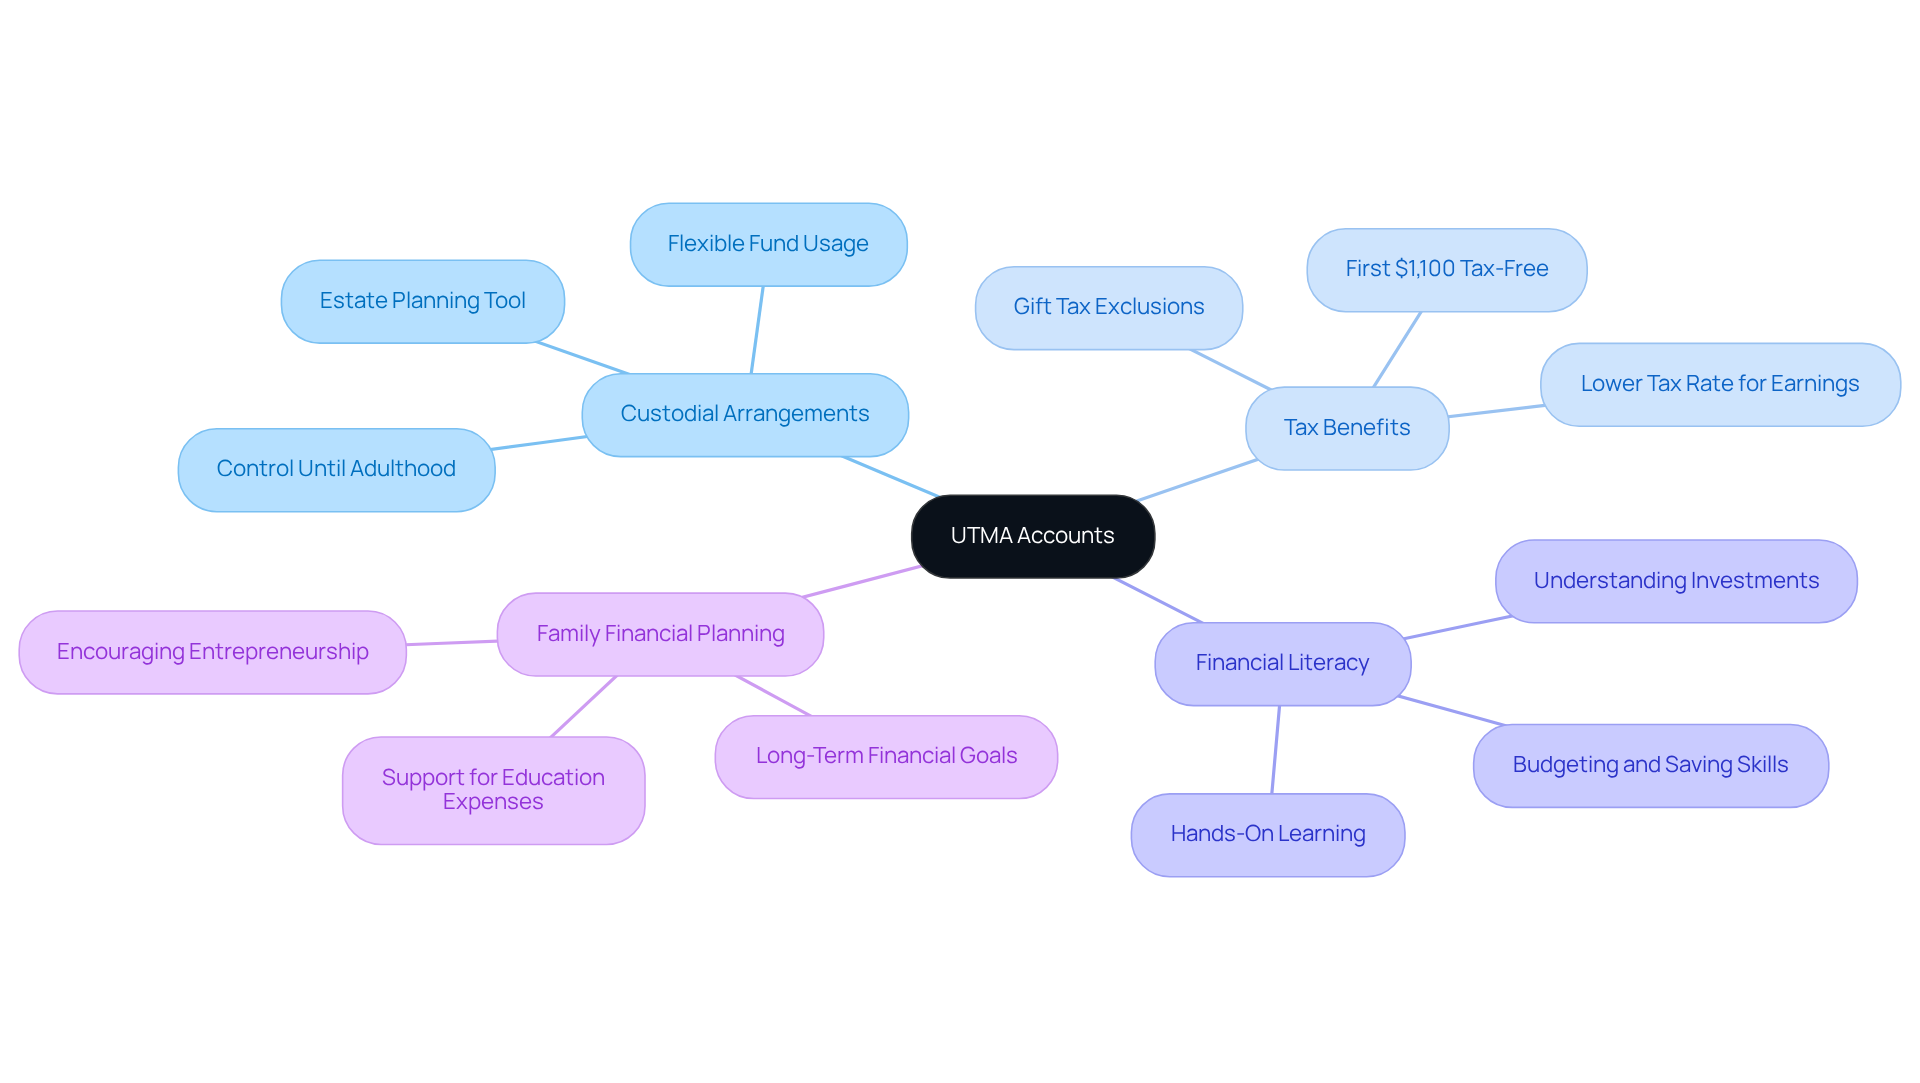
Custodial arrangements play a vital role in helping parents utilize uniform transfers to minors accounts to move assets to minors, offering significant tax benefits and flexibility in managing those assets. These funds allow you to set aside money for your children’s future needs in a uniform transfers to minors account, whether it’s for education or starting a business, all without the complexities of creating a trust.
Imagine if your children could learn about financial responsibility while you prepare for their future. UTMA funds are instrumental in fostering financial literacy among kids. As they interact with these portfolios, they gain hands-on experience in managing investments and understanding the value of money. Through practical experiences, such as overseeing their own custodial funds, children can learn about budgeting and saving.
By utilizing custodial savings, families can build a strong economic foundation that not only supports their children’s immediate goals but also equips them with essential skills for lasting success. We’re here for you, guiding you every step of the way as you navigate this important journey together.
Explore Key Features and Characteristics of UTMA Accounts
The uniform transfers to minors account offers several compelling features that make it an appealing option for families aiming to secure their children’s financial futures, especially when paired with innovative wealth management strategies like those offered by Bright Advisers.
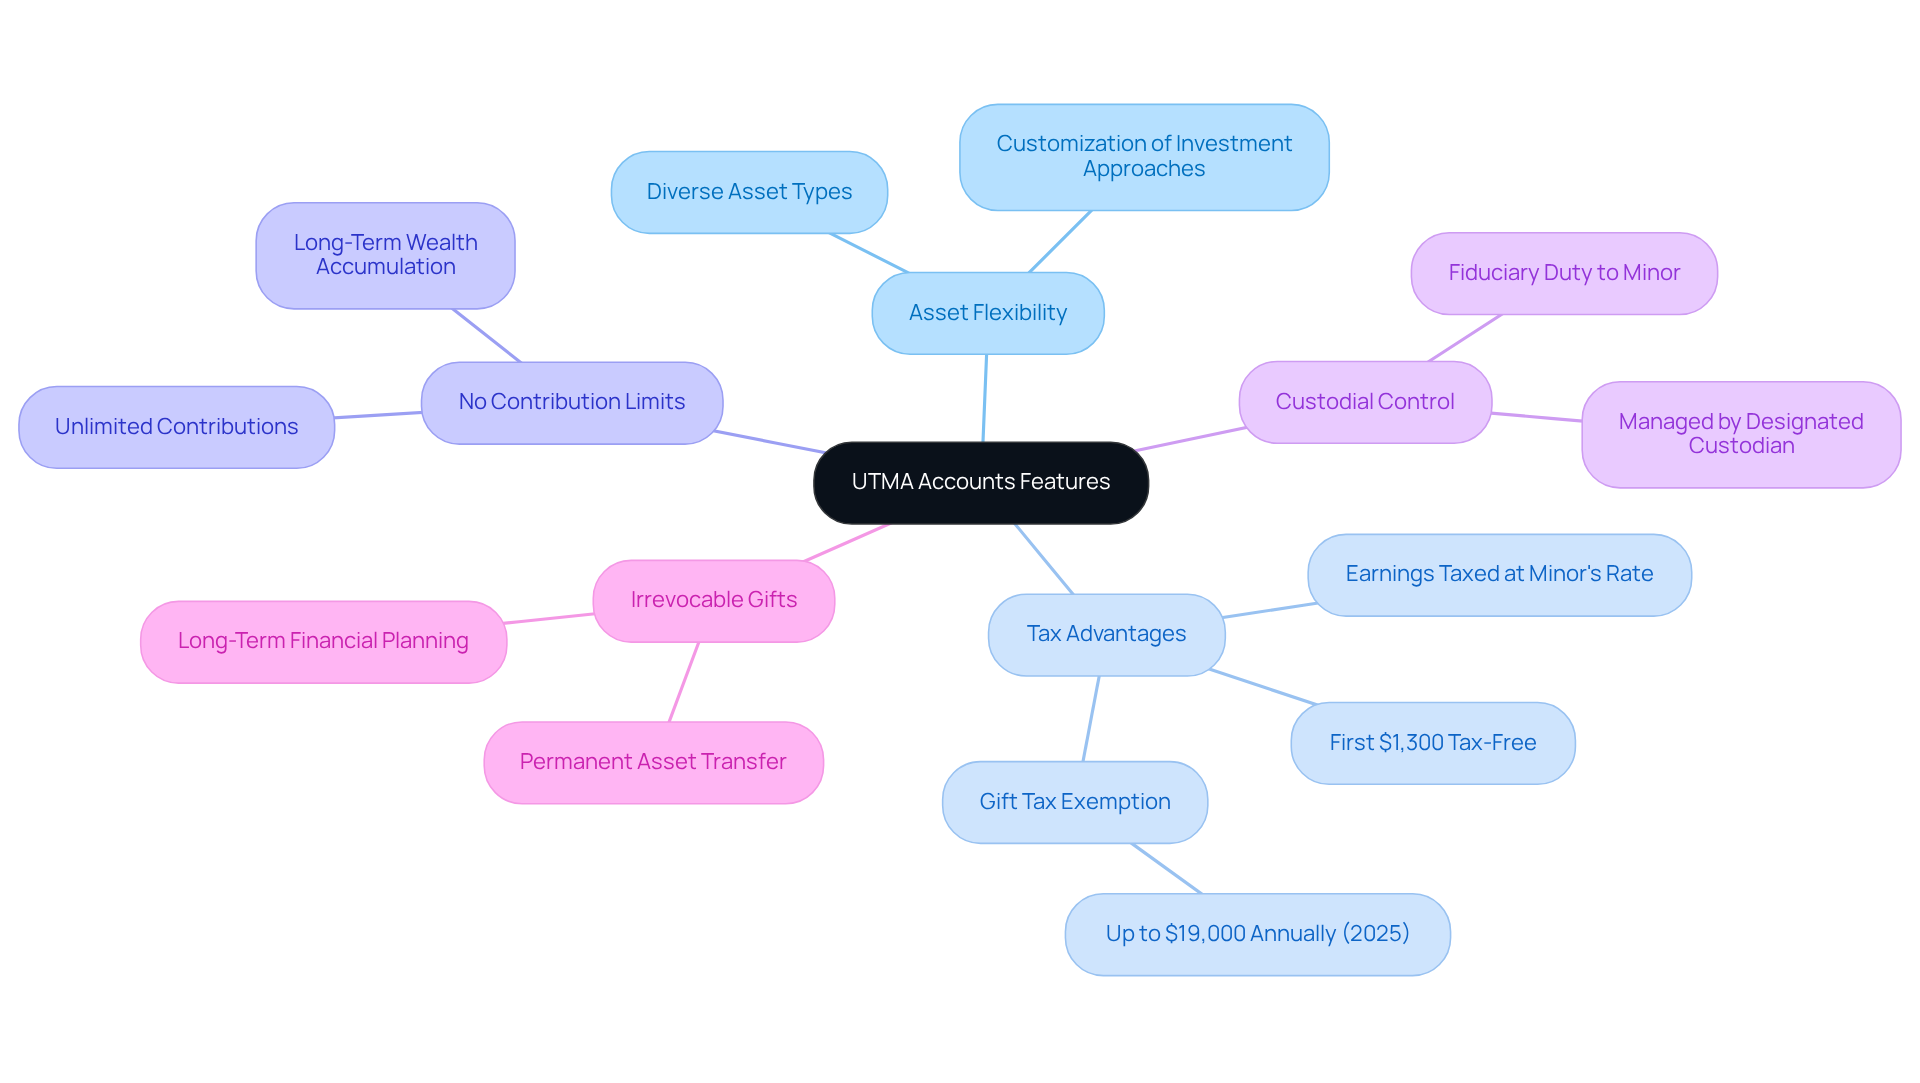
- Asset Flexibility: Unlike UGMA accounts, which restrict holdings to financial assets, UTMA accounts allow for a diverse array of assets, including real estate and collectibles. This flexibility empowers families to customize their investment approaches to their distinct financial objectives, supported by Bright Advisers’ hyper-personalized portfolio development, including strategies such as Diversified Premia and Opportunity Strategy, as well as uniform transfers to minors account.
- Tax Advantages: Earnings within a UTMA account are taxed at the minor’s tax rate, which is typically lower than that of the parents. This structure can lead to significant tax savings, especially as the first $1,300 of income is tax-free for minors, with the next $1,300 taxed at the child’s rate. Income surpassing $2,600 is taxed at the parent’s marginal tax rate, making it essential for families to consider the possible tax implications when planning. Bright Advisers highlights tax optimization in their planning solutions, which incorporate uniform transfers to minors account, improving wealth management accessibility for families while ensuring minimal fund fees.
- No Contribution Limits: UTMA funds do not impose restrictions on contributions, enabling families to accumulate wealth significantly over time. For 2025, contributions up to $19,000 annually are excluded from gift tax, offering a strategic benefit for wealth transfer, including uniform transfers to minors account, which aligns with Bright Advisers’ dedication to empowering families through tailored financial planning.
- Custodial Control: A designated custodian oversees the funds until the minor reaches the age of majority, ensuring that the assets are utilized for the minor’s benefit. This arrangement provides peace of mind for parents, knowing that the funds, particularly those in uniform transfers to minors account, are being managed responsibly, a principle that resonates with Bright Advisers’ approach to guiding young families.
- Irrevocable Gifts: Once assets are transferred into a custodial fund, these gifts cannot be revoked, providing assurance in asset management. This feature is especially advantageous for long-term monetary planning, as it ensures that the intended benefits are maintained through a uniform transfers to minors account.
Imagine the peace of mind that comes with knowing your child’s future is secure. Uniform transfers to minors accounts not only provide tax benefits but also serve as a flexible and secure method for families to invest in their children’s futures. By understanding these essential characteristics, families can make informed choices that align with their financial objectives, while also reflecting on the potential impact on aid eligibility. Together, with Bright Advisers’ innovative strategies, families can enhance these advantages, ensuring they are well-prepared for their financial journeys.
Compare UTMA Accounts with Other Custodial Options
When planning for your child’s future, it can feel overwhelming to understand the differences between UTMA accounts and the uniform transfers to minors account. However, these distinctions are essential for families looking to enhance their wealth management options, such as uniform transfers to minors account.
-
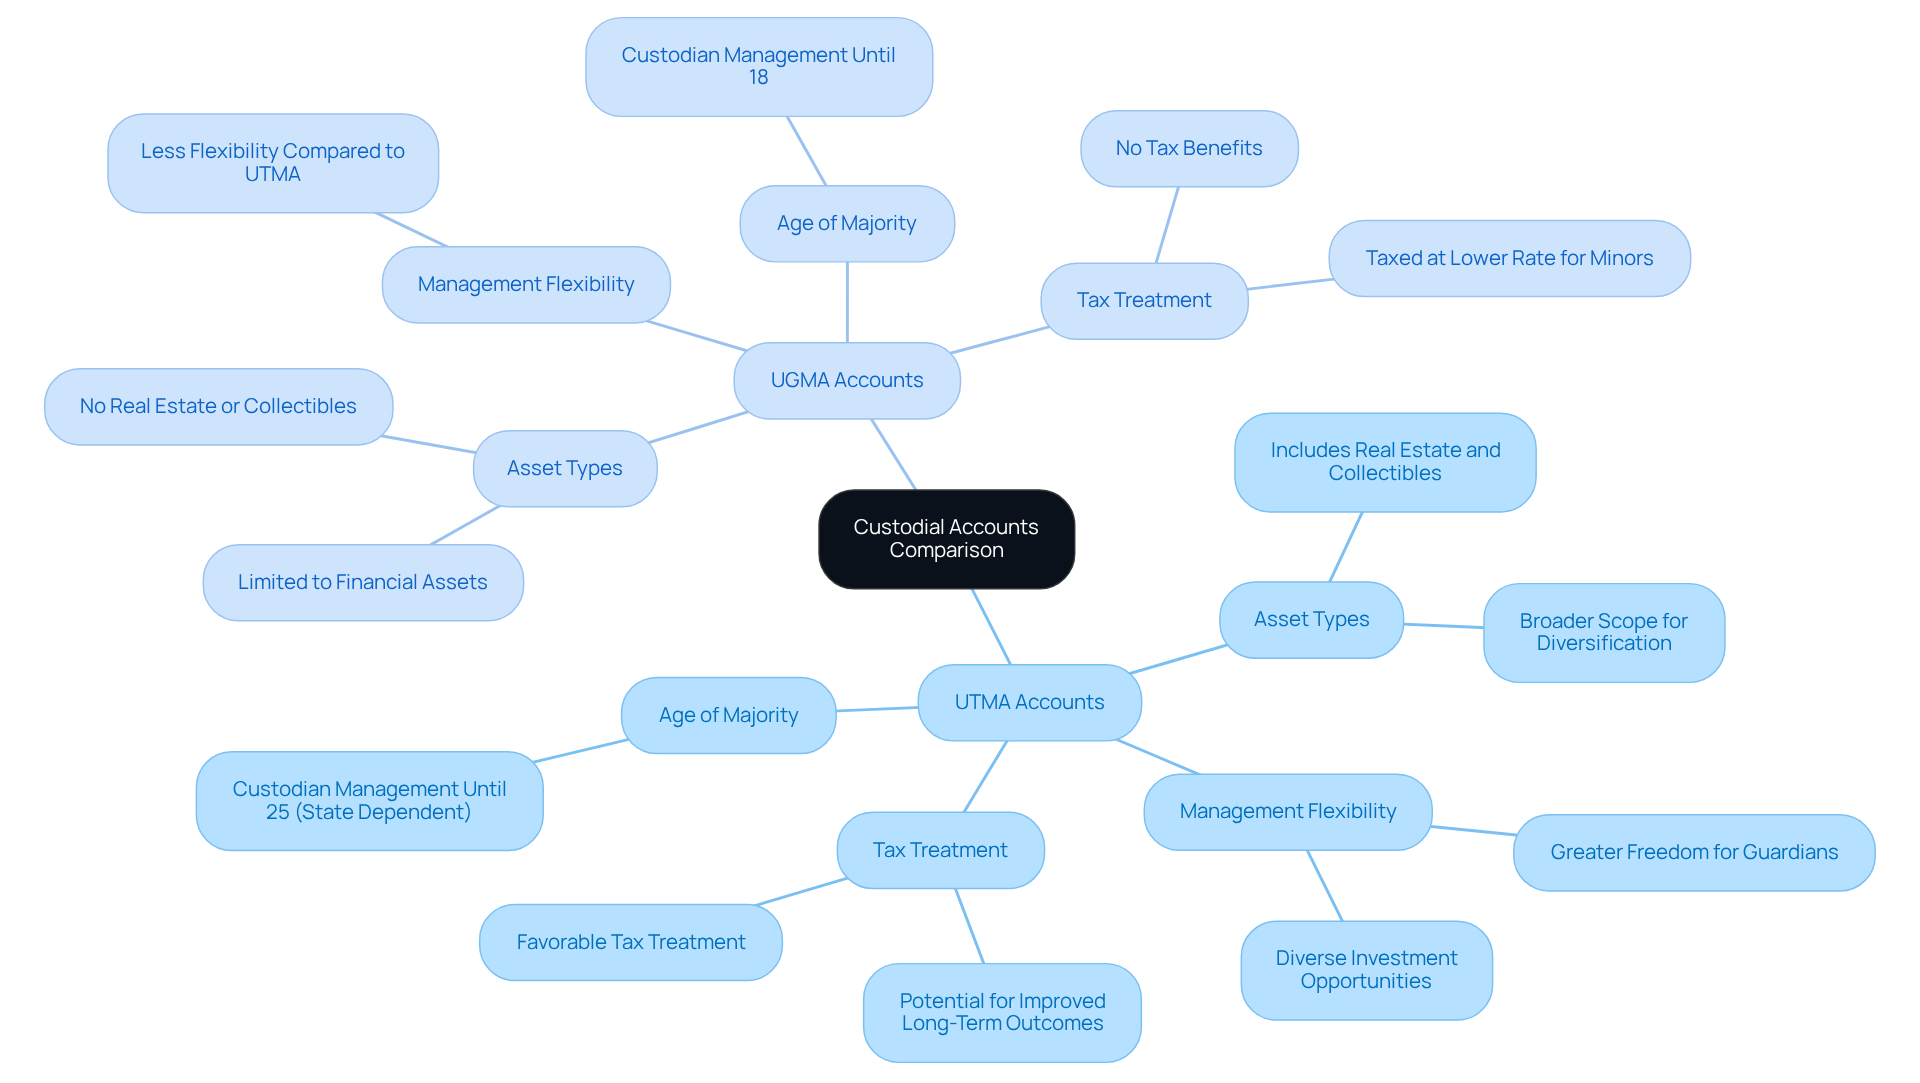
Asset Types: Imagine having the flexibility to choose from a wide range of assets for your child’s future. While UGMA accounts limit you to financial assets like cash and securities, uniform transfers to minors accounts, such as UTMA, open the door to real estate and collectibles. This broader scope, which includes uniform transfers to minors account, can be a game-changer for families eager to diversify their investments and strengthen their financial strategies.
-
Management Flexibility: Think about the freedom custodial plans provide. They empower guardians to manage assets with greater flexibility, allowing for investments in diverse opportunities that may not be available under a uniform transfers to minors account. This approach aligns perfectly with our philosophy at Bright Advisers, where we aim to support young households with personalized wealth management solutions.
-
Tax Treatment: It’s comforting to know that both account types enjoy favorable tax treatment. However, uniform transfers to minors account may offer additional advantages due to their broader asset inclusion. While UGMA funds don’t provide tax benefits, similar structures can hold appreciating assets over time, potentially leading to improved long-term financial outcomes. This can significantly assist families in achieving financial stability and independence by utilizing uniform transfers to minors account.
-
Age of Majority: Understanding the age at which your child can take charge of their fund is crucial. In some states, custodians can manage these funds until the minor is 21, compared to 18 for UGMA funds. This extended management period allows for more thoughtful investment decisions during your child’s formative years.
Additionally, it’s important to consider that custodial funds may impact aid eligibility, as colleges view these assets as owned by the minor, which can influence their qualification for need-based assistance.
In conclusion, while both UTMA and UGMA options serve similar purposes, the benefits of UTMA arrangements—such as greater flexibility in asset types and management—make uniform transfers to minors account an appealing choice for families dedicated to investing in their children’s futures. At Bright Advisers, our dedication to minimizing fund fees enhances the appeal of these accounts, ensuring that families can maximize their investments through personalized planning and financial strategies. Together, we can navigate this journey towards a secure future for your family.
Conclusion
The Uniform Transfers to Minors Account (UTMA) is a wonderful resource for parents eager to secure their children’s financial futures. By simplifying the transfer of assets and providing significant tax benefits, UTMA accounts empower families to invest wisely in their children’s well-being. This innovative approach not only eases the gifting process but also nurtures financial literacy, equipping children with essential skills for managing their finances.
Imagine if you could give your child a head start on financial responsibility. Throughout this discussion, we’ve highlighted several key features of UTMA accounts that make this possible. These include:
- Flexibility in asset types
- Favorable tax treatment
- Absence of contribution limits
- Custodial control
- Irrevocable nature of gifts
Each of these characteristics contributes to a strong framework for nurturing financial responsibility in minors while ensuring that funds are managed effectively until they reach adulthood.
Ultimately, embracing the advantages of UTMA accounts can pave the way for a brighter financial future for your children. By understanding these accounts and their potential impact on financial planning, families can make informed decisions that align with their long-term goals. The significance of investing in a child’s future cannot be overstated; it lays the groundwork for their success and independence. Together, we can navigate this journey, and engaging with custodial accounts like UTMA is not just a financial strategy—it’s a commitment to fostering a legacy of financial literacy and responsibility for the next generation.
Frequently Asked Questions
What is a Uniform Transfers to Minors Account (UTMA)?
A UTMA is a custodial account established under state law that allows adults to make uniform transfers to minors, simplifying the gifting process without the complexities of a formal trust.
What types of assets can be transferred into a UTMA?
You can gift various assets into a UTMA, including cash, stocks, bonds, real estate, and collectibles.
Who manages the UTMA funds until the child reaches adulthood?
A custodian, typically a parent or guardian, manages the UTMA funds until the child reaches the age of majority, which varies by state.
At what age do children gain control of their UTMA funds?
The age of majority for UTMA accounts generally ranges from 18 to 21 years old, depending on the state. For example, in California, a child is considered an adult at 18, but the trust can continue until they are 21.
What are the tax benefits of a UTMA?
Earnings in a UTMA are taxed at the child’s lower income tax rate, up to certain thresholds, providing a tax-favored approach for saving for the child’s future.
Why might families choose to set up a UTMA?
Families may choose a UTMA for its flexibility, potential tax savings, and its ability to help secure their children’s financial well-being.
List of Sources
- Define the Uniform Transfers to Minors Account (UTMA)
- What Is a UTMA or UGMA Account for 2025 | Research.com (https://research.com/student-loans/what-is-a-utma-or-ugma-account)
- UGMA & UTMA Accounts: What They Are, Differences – NerdWallet (https://nerdwallet.com/article/investing/utma-ugma)
- UGMA vs. UTMA Custodial Accounts (https://smartasset.com/investing/ugma-vs-utma)
- Uniform Transfers to Minors Act (UTMA): What It Is and How It Works (https://investopedia.com/terms/u/utma.asp)
- UTMA Accounts – What You Need To Know – Bridgeview Capital Advisors, Inc. (https://bridgeviewadvisors.com/utma-accounts)
- Understand the Purpose and Importance of UTMA Accounts
- What Is a UTMA or UGMA Account for 2025 | Research.com (https://research.com/student-loans/what-is-a-utma-or-ugma-account)
- Pros and cons of custodial accounts for minors | Dominick Feld Hyde, P.C. (https://dfhlaw.com/2022/10/pros-and-cons-of-custodial-accounts-for-minors)
- The Benefits Of Custodial Accounts For Teaching Financial Literacy – FasterCapital (https://fastercapital.com/topics/the-benefits-of-custodial-accounts-for-teaching-financial-literacy.html)
- What are the benefits and drawbacks of an UGMA / UTMA? (https://aboveboardfinancial.com/blog/what-are-the-benefits-and-drawbacks-of-ugma-utma-accounts)
- T. Rowe Price Personal Investor – Custodial Accounts (https://troweprice.com/personal-investing/accounts/general-investing/ugma-utma.html)
- Explore Key Features and Characteristics of UTMA Accounts
- What Is a UTMA or UGMA Account for 2025 | Research.com (https://research.com/student-loans/what-is-a-utma-or-ugma-account)
- UTMA Accounts Explained: Rules, Custodial Brokerages and More (https://kiplinger.com/personal-finance/603545/hey-parents-caution-is-critical-with-utma-custodial-accounts)
- Uniform Transfers to Minors Act (UTMA): What It Is and How It Works (https://investopedia.com/terms/u/utma.asp)
- Understanding UTMA Accounts | Los Angeles Estate Planning Attorneys (https://schomerlawgroup.com/estate-planning/understanding-utma-accounts)
- Uniform Transfers to Minors Act (UTMA) Accounts (https://financestrategists.com/banking/custodial-account/uniform-transfers-to-minors-act-utma-accounts)
- Compare UTMA Accounts with Other Custodial Options
- UGMA vs. UTMA | Unbiased (https://unbiased.com/discover/investing/ugma-vs-utma)
- Can You Use an UGMA or UTMA Account to Save for College? (https://savingforcollege.com/article/can-you-use-an-ugma-or-utma-account-to-save-for-college)
- UTMA vs. UGMA: Understanding for Investment Planning (https://westernsouthern.com/investments/utma-vs-ugma-accounts)
- First Command UTMA and UGMA Savings Accounts (https://firstcommand.com/banking/personal/savings/utma-ugma)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading