

Overview
For families, a Traditional IRA offers significant advantages that can make a real difference in your financial journey. Imagine being able to contribute to your savings in a way that not only reduces your taxable income but also allows your investments to grow tax-deferred. This means you could enhance your long-term savings potential, providing a more secure future for your loved ones.
However, it’s important to understand that there are some drawbacks to consider. Early withdrawals can lead to penalties, and taxable distributions during retirement can complicate your financial planning. These factors might impact your tax brackets, which can feel overwhelming at times.
As you navigate these considerations, remember that you’re not alone. We’re here for you, ready to support you in making informed decisions that align with your family’s values and goals. Together, we can explore the best options for your financial future, ensuring that you feel confident and secure every step of the way.
Key Highlights:
- A Traditional IRA allows for pre-tax contributions, reducing taxable income and enabling tax-deferred growth until withdrawal.
- Contributions may be tax-deductible, providing immediate tax benefits, especially advantageous for families.
- For 2025, contribution limits are $7,000 for individuals under 50 and $8,000 for those 50 and older.
- Withdrawals before age 59½ incur a 10% penalty, emphasizing the need for careful financial planning.
- There are no income restrictions for contributing to a Traditional IRA, making it accessible for a wide range of earners.
- Taxable withdrawals during retirement can affect tax brackets and overall income, highlighting a potential disadvantage.
- Required Minimum Distributions (RMDs) start at age 73, complicating tax planning and potentially increasing tax burdens.
- Comparisons with Roth IRAs, 401(k)s, SEP IRAs, and SIMPLE IRAs reveal different benefits and suitability for various financial situations.
- Families should consider their current and future tax situations when choosing between Traditional and other IRA options.
Introduction
In the quest for a secure financial future, families often grapple with the complexities of retirement savings options. Imagine if you could simplify this journey. Among these options, the Traditional IRA stands out as a powerful tool, offering tax advantages and flexible contributions that can significantly bolster your retirement funds.
It’s important to understand that navigating the intricacies of this retirement account requires a clear understanding of its features, benefits, and potential drawbacks. From immediate tax relief to the importance of strategic planning, this article delves into the essential aspects of Traditional IRAs, providing insights for families eager to make informed decisions about their financial well-being.
Together, we can navigate this journey. With expert guidance and real-life examples, you will discover how to leverage this retirement vehicle effectively while weighing it against other options to ensure a comprehensive approach to long-term savings.
Define Traditional IRA: Key Features and Functionality
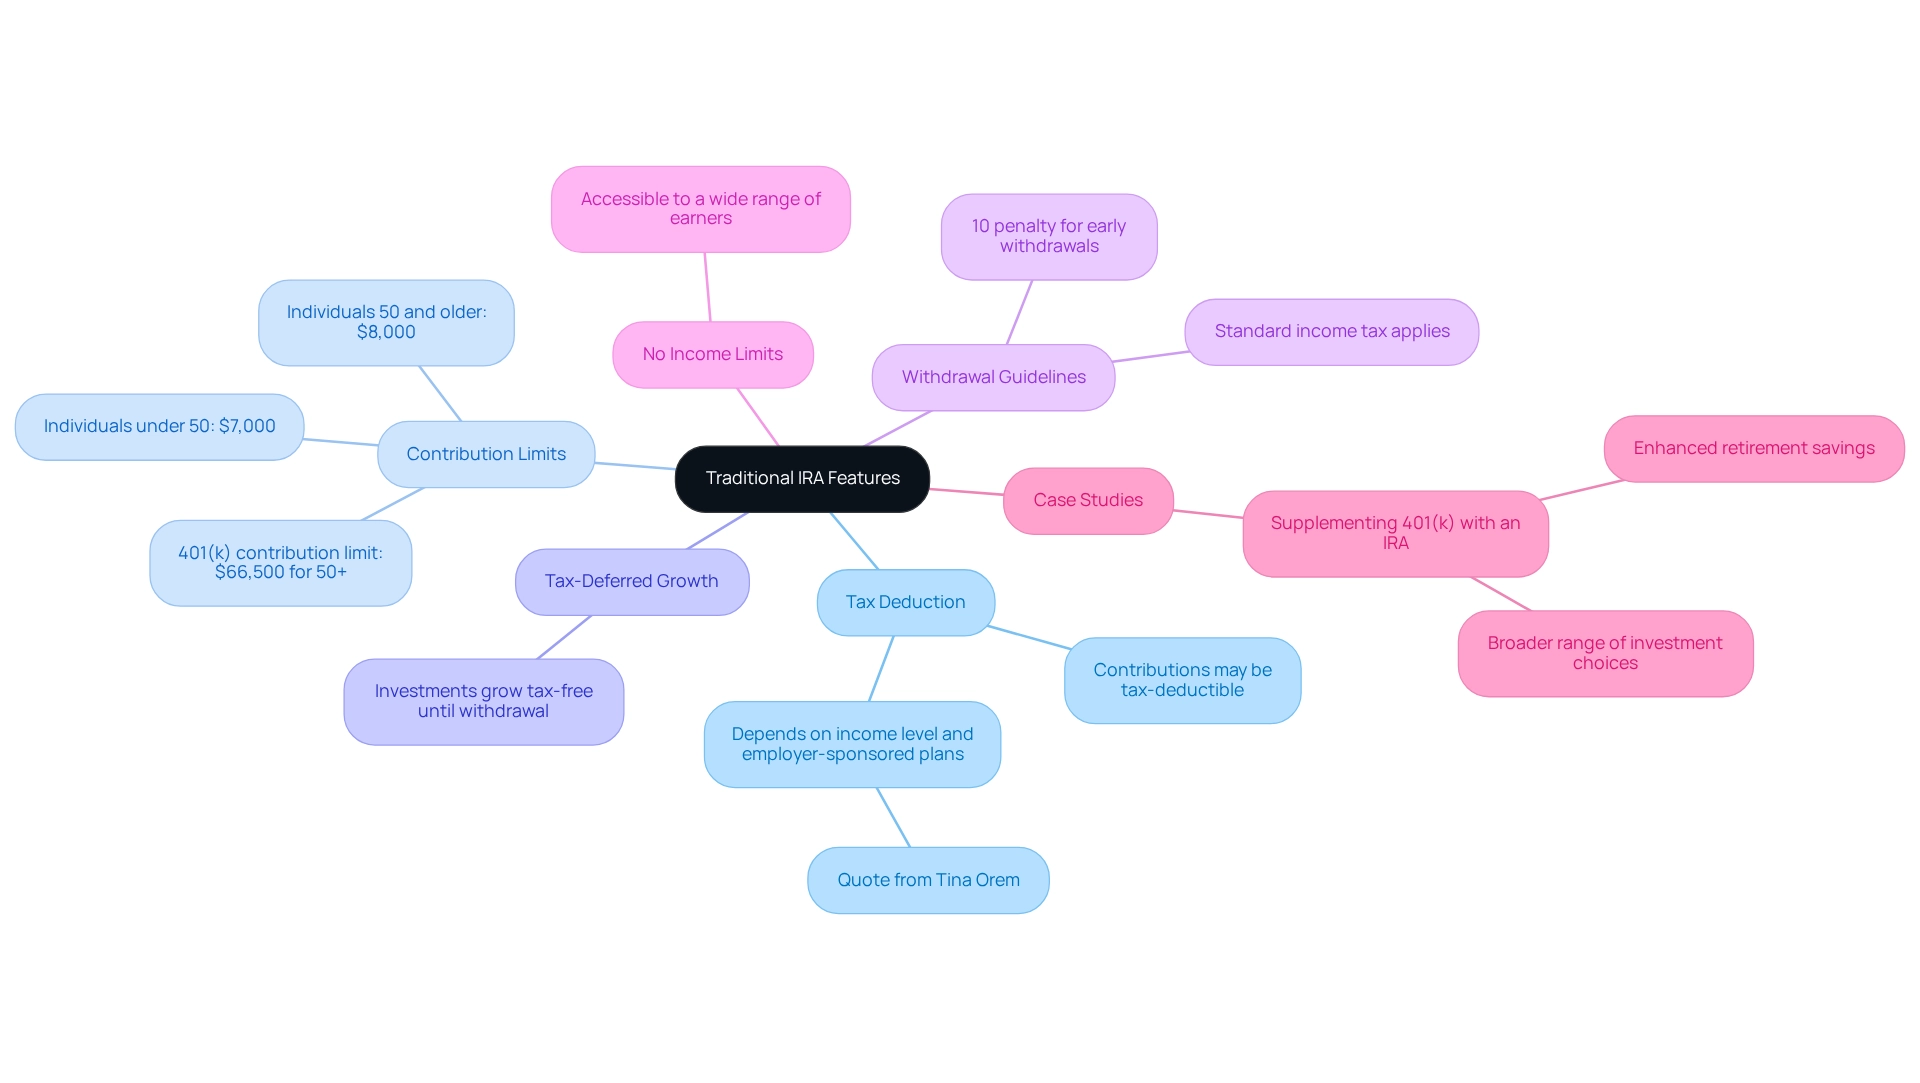
A Traditional IRA (Individual Retirement Account) serves as a tax-advantaged retirement savings vehicle, highlighting the traditional IRA advantages and disadvantages, as it allows individuals to contribute pre-tax income that can grow tax-deferred until withdrawal. This aligns with Bright Advisers’ commitment to empowering families through personalized wealth management solutions. Here are some key features of a Traditional IRA, highlighting the traditional IRA advantages and disadvantages:
- Tax Deduction: Contributions may be tax-deductible, significantly reducing taxable income for the year they are made. This feature is especially beneficial for families striving to maximize their tax efficiency. As Tina Orem, a specialist in tax strategies, notes, ‘Your traditional IRA contributions may also be tax deductible, depending on your income level and whether you (or your spouse if you’re married) have an employer-sponsored savings plan.’
- Contribution Limits: For 2025, individuals under 50 can contribute up to $7,000, while those aged 50 and older can contribute $8,000. This allows for increased savings as they approach retirement. Additionally, it’s important to note that total allowed contributions to a 401(k) can reach $66,500 for individuals age 50 or older, highlighting the advantages of supplementing a 401(k) with a Traditional IRA.
- Tax-Deferred Growth: Investments within the IRA grow tax-free until withdrawal, usually during later years, providing a substantial advantage in accumulating wealth over time.
- Withdrawal Guidelines: Withdrawals made before age 59½ may incur a 10% penalty alongside standard income tax, emphasizing the importance of planning for future financial needs.
- No Income Limits: Unlike certain savings accounts, there are no income restrictions for contributing to a Traditional IRA, making it accessible to a wide range of earners.
The flexibility of a Traditional IRA enables individuals to enhance employer-sponsored pension plans like 401(k)s, improving overall savings for the future. This is particularly advantageous for families looking to secure their financial future. For instance, Jay and Emma, a couple aiming to reduce financial stress, found that adding a Traditional IRA to their 401(k) provided them with greater control and investment choices, ultimately enhancing their savings.
Expert insights indicate that contributions to a Traditional IRA may also be tax-deductible, depending on income levels and whether the individual or their spouse has access to an employer-sponsored retirement plan. This aspect highlights the potential tax benefits, as well as the traditional IRA advantages and disadvantages, that can be utilized through thoughtful planning, a core principle at Bright Advisers. Moreover, Bright Advisers is committed to keeping fund fees low, ensuring that families can maximize their investment returns without incurring excessive costs. For further assistance, families can consult with experts like Jackson Hewitt Tax Pros to understand the tax implications of Traditional IRA investments, including the traditional IRA advantages and disadvantages. In summary, a Traditional IRA provides a solid foundation for retirement savings, combining tax advantages with flexible contribution options, making it a valuable resource for families focused on building a secure financial future. Together, we can navigate this journey towards financial well-being.
Explore Advantages of Traditional IRAs for Young Families
Explore the Advantages of Traditional IRAs for Young Families
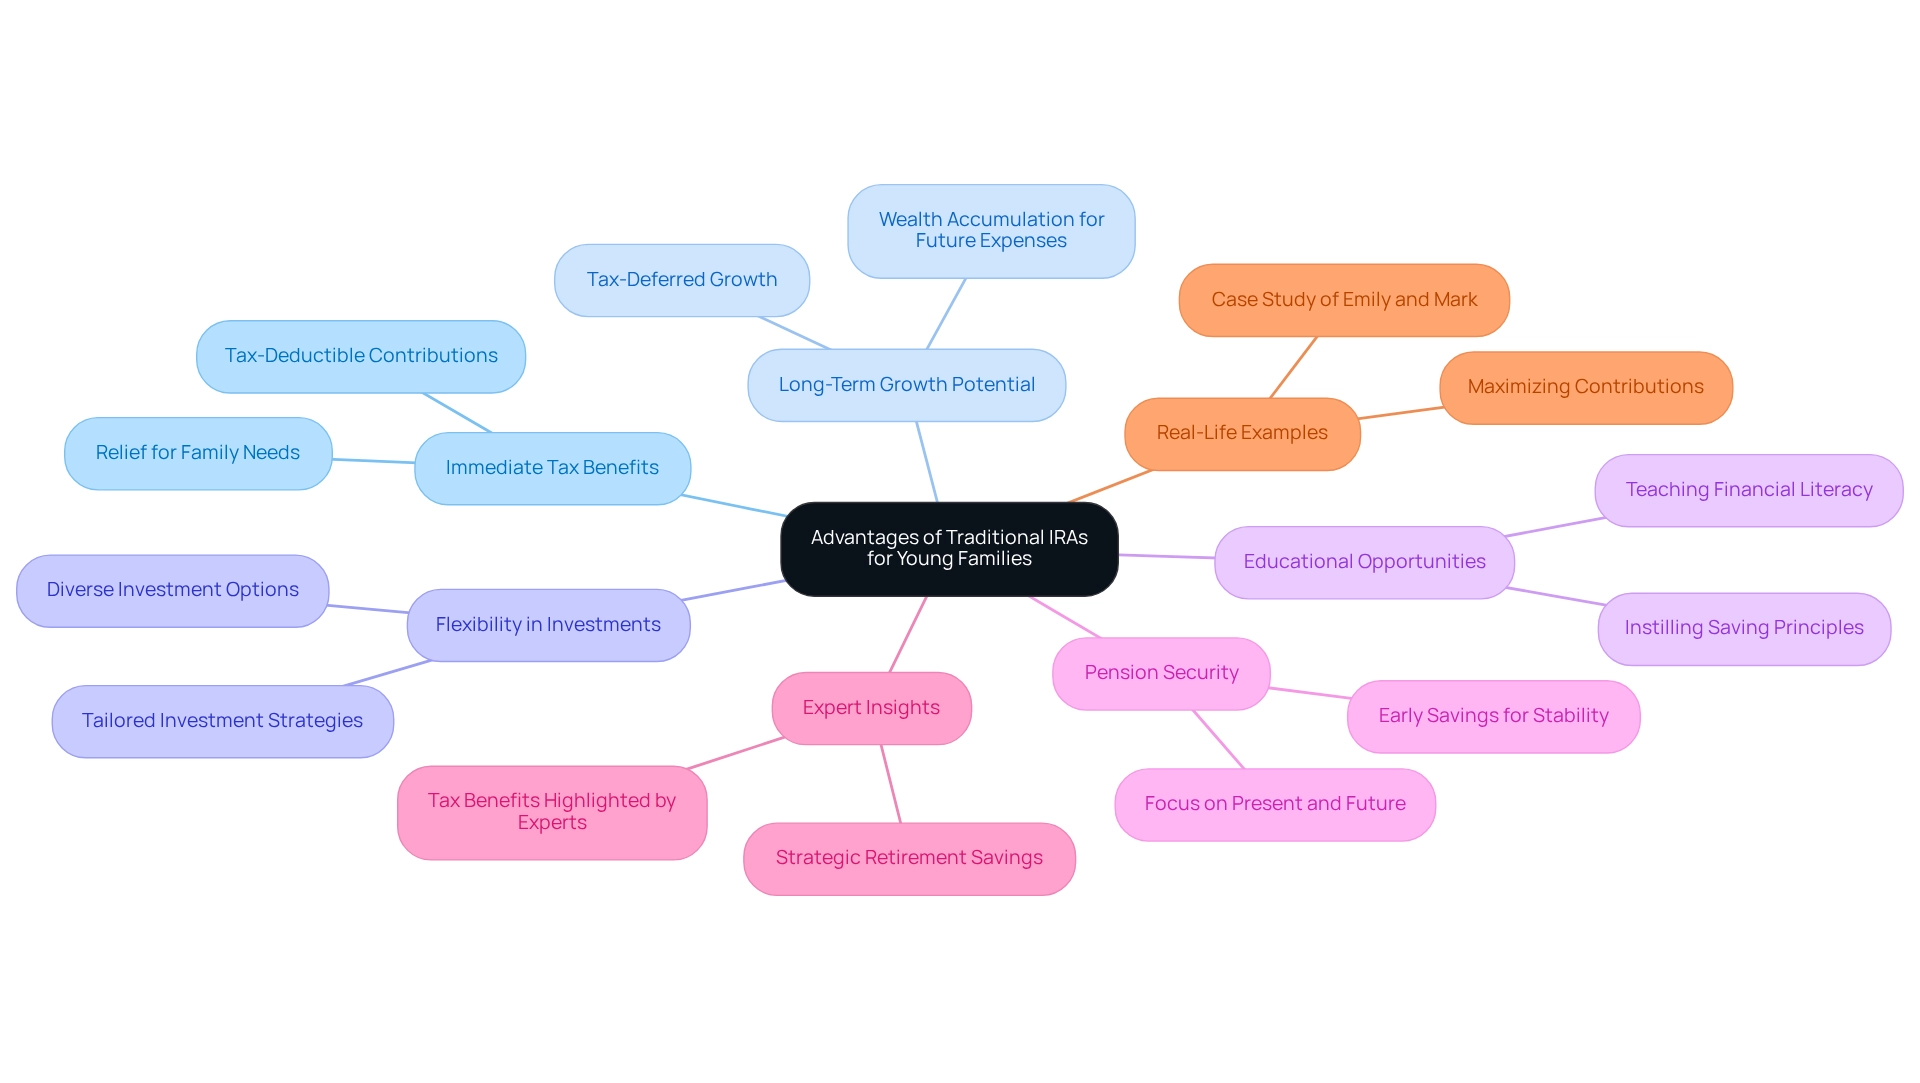
Traditional IRAs offer several compelling advantages for young families navigating their financial journeys.
-
Immediate Tax Benefits: Imagine having the ability to reduce your tax burden right now. Contributions to a Traditional IRA may be tax-deductible, providing immediate relief that can be redirected towards essential family needs. This can greatly alleviate economic stresses, especially for households managing various costs, much like Emily and Mark, who sought to improve their financial situation.
-
Long-Term Growth Potential: It’s important to understand that the tax-deferred growth of a Traditional IRA allows families to accumulate wealth over time. By contributing to a Traditional IRA, you can pave the way for substantial growth, creating a safety net for future expenses such as education and retirement—key goals for Emily and Mark as they planned their future together.
-
Flexibility in Investments: Families can take advantage of a diverse array of investment options, including stocks, bonds, and mutual funds. This flexibility enables you to tailor investment strategies that align with your unique family goals and risk tolerance, similar to the personalized approach Bright Advisers provides to clients.
-
Educational Opportunities: Engaging with a Traditional IRA can serve as a valuable teaching moment for your children, instilling the principles of saving and investing early on. This encourages financial literacy, equipping the next generation with essential skills for managing their resources—a principle that Emily and Mark embraced as they worked towards economic freedom.
-
Pension Security: Creating a savings fund early is vital for ensuring economic stability in later years. By emphasizing savings for the future, households can alleviate upcoming financial pressures, allowing you to focus on present concerns, just as Emily and Mark achieved by implementing strategies to manage their cash flow and prepare for the future.
-
Expert Insights: Financial planners often highlight the tax benefits of Traditional IRAs, noting that immediate tax deductions can significantly impact household finances. As banking and investment specialist Javier Simon puts it, “If you’re prepared to locate a consultant who can assist you in reaching your monetary objectives, begin now.” This strategic approach to retirement savings is particularly beneficial for young families striving to balance current expenses with future stability.
-
Real-Life Examples: In a case study involving Emily and Mark, the importance of maximizing contributions to their Traditional IRA was underscored. Their advisor suggested this approach to enhance tax efficiency and long-term growth, demonstrating how focusing on Traditional IRAs can support families in their financial journeys.
By understanding the traditional IRA advantages and disadvantages, young families can effectively secure their economic future while prioritizing immediate needs.
- Join our waitlist: Thank you for considering Bright Advisers for your financial planning needs. We are currently at capacity and encourage you to join our waitlist. Our team will reach out as soon as we have availability to discuss how we can help you achieve your financial goals.
Examine Disadvantages of Traditional IRAs: What Families Should Know
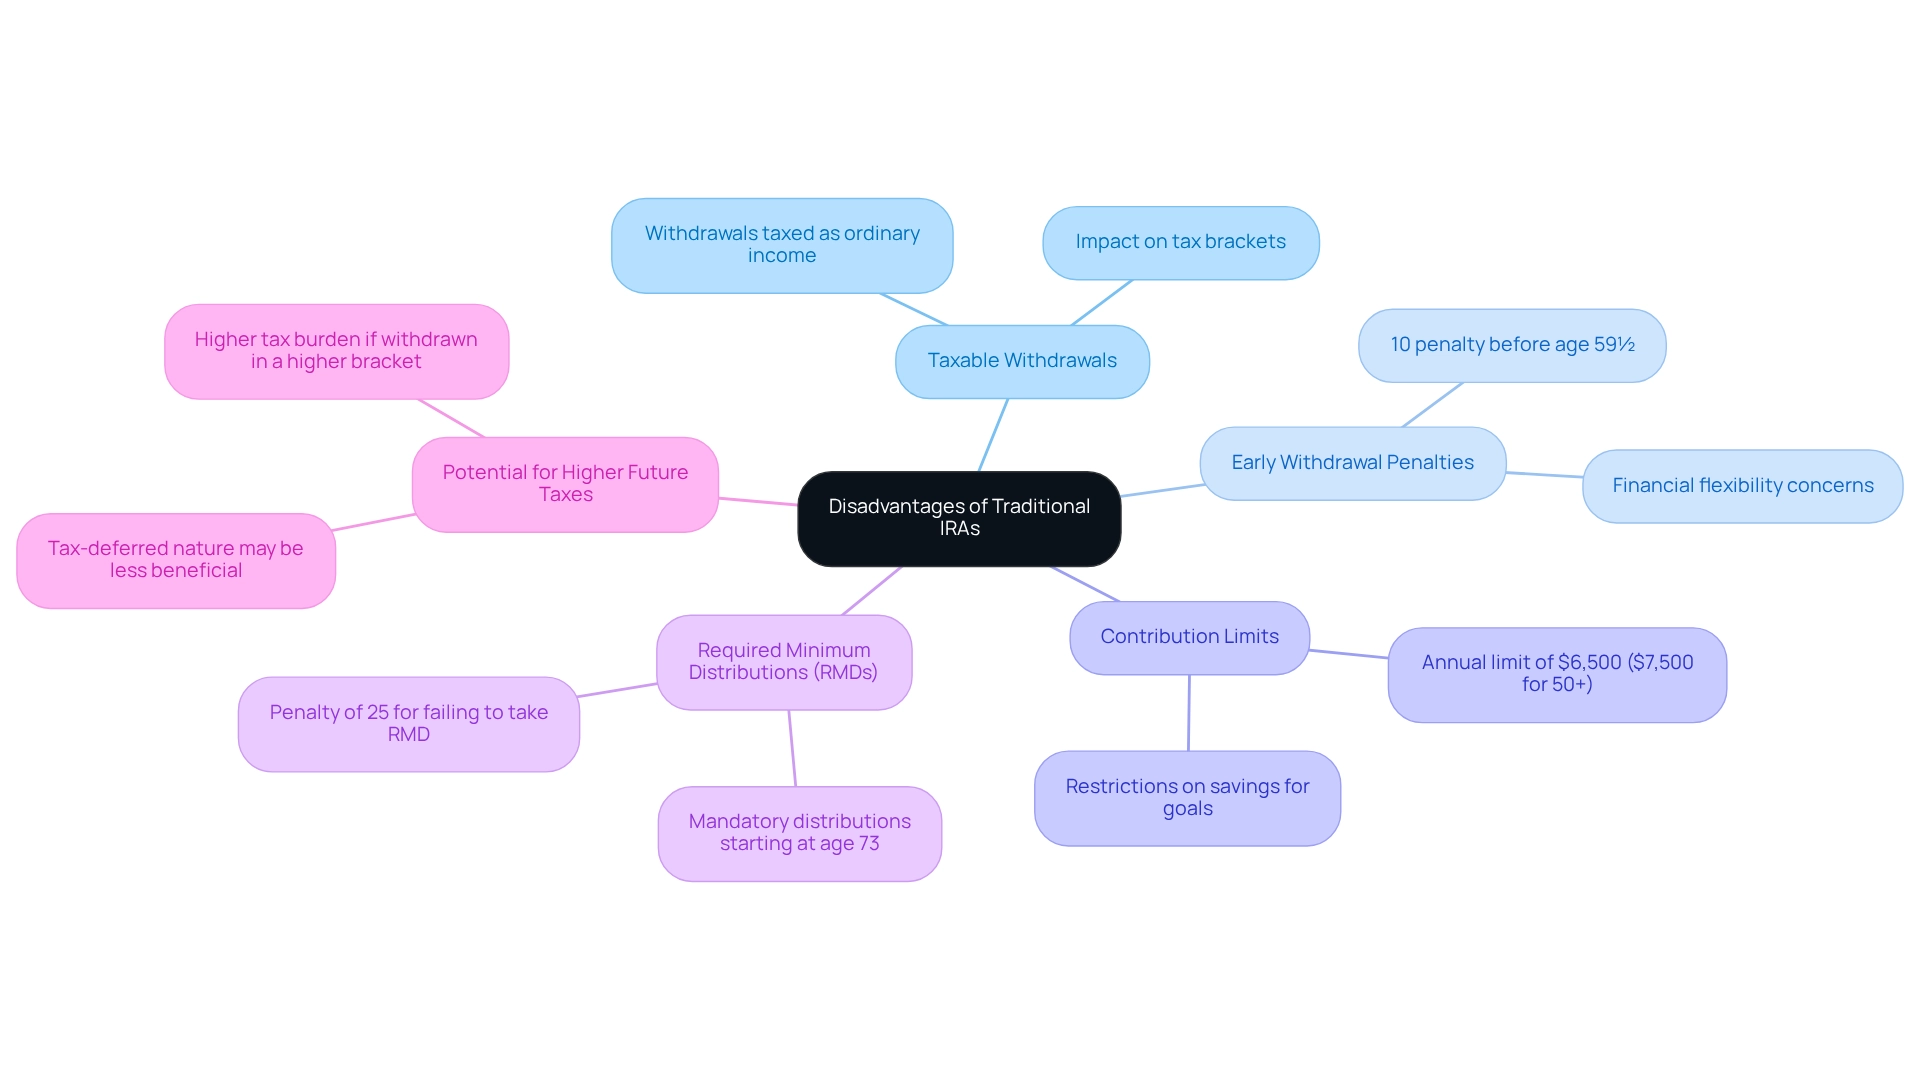
While Traditional IRAs present several advantages, it’s essential for families to be aware of some potential drawbacks:
- Taxable Withdrawals: When you withdraw funds during retirement, they are taxed as ordinary income. This can significantly impact your tax brackets and overall retirement income, leading to unexpected tax obligations, especially if your household income varies. Bright Advisers is here to help families like Jay and Emma effectively distribute their resources to lessen these effects and reduce financial stress.
- Early Withdrawal Penalties: If you need to access your funds before age 59½, a 10% penalty applies. This can be a considerable disadvantage for families facing unforeseen expenses or emergencies. Such penalties can hinder financial flexibility at critical moments, a concern shared by families like Emily and Mark, who are working hard to build a solid economic foundation while managing demanding careers. Bright Advisers offers strategies to navigate these challenges.
- Contribution Limits: Annual contribution limits can restrict how much families can save for their future, particularly for those looking to catch up on their savings. For 2025, the limit is $6,500, or $7,500 for individuals aged 50 and older. This may not be sufficient for families with significant goals, such as securing their children’s education, as illustrated in Allison and Brian’s story. Bright Advisers can assist in developing alternative savings strategies.
- Required Minimum Distributions (RMDs): Beginning at age 73, account holders must start taking distributions. If you fail to take an RMD, you could face a penalty of 25%, which can be reduced to 10% if corrected promptly. This requirement complicates tax planning and may push families into higher tax brackets later in life. Bright Advisers emphasizes the importance of comprehensive financial strategies to manage these requirements effectively.
- Potential for Higher Future Taxes: Families expecting to be in a lower tax bracket during retirement may find the tax-deferred nature of a Traditional IRA less beneficial. If funds are withdrawn while in a higher tax bracket, the tax burden could be larger than anticipated. Bright Advisers is dedicated to helping families like Allison and Brian avoid this situation through thoughtful tax planning.
As Ben Geier, an investing specialist at SmartAsset, wisely notes, “If you’re prepared to find an advisor who can assist you in reaching your financial objectives, begin now.” As families plan for their future, understanding the traditional IRA advantages and disadvantages is crucial. Additionally, families may want to consider a Roth IRA for tax-free withdrawals in retirement, especially if they anticipate being in a higher tax bracket. By carefully weighing the implications of taxable withdrawals and penalties, families can make more informed decisions about their financial futures. Remember, Bright Advisers is here to guide you through this journey together.
Determine the Right IRA: Comparing Traditional with Other Options
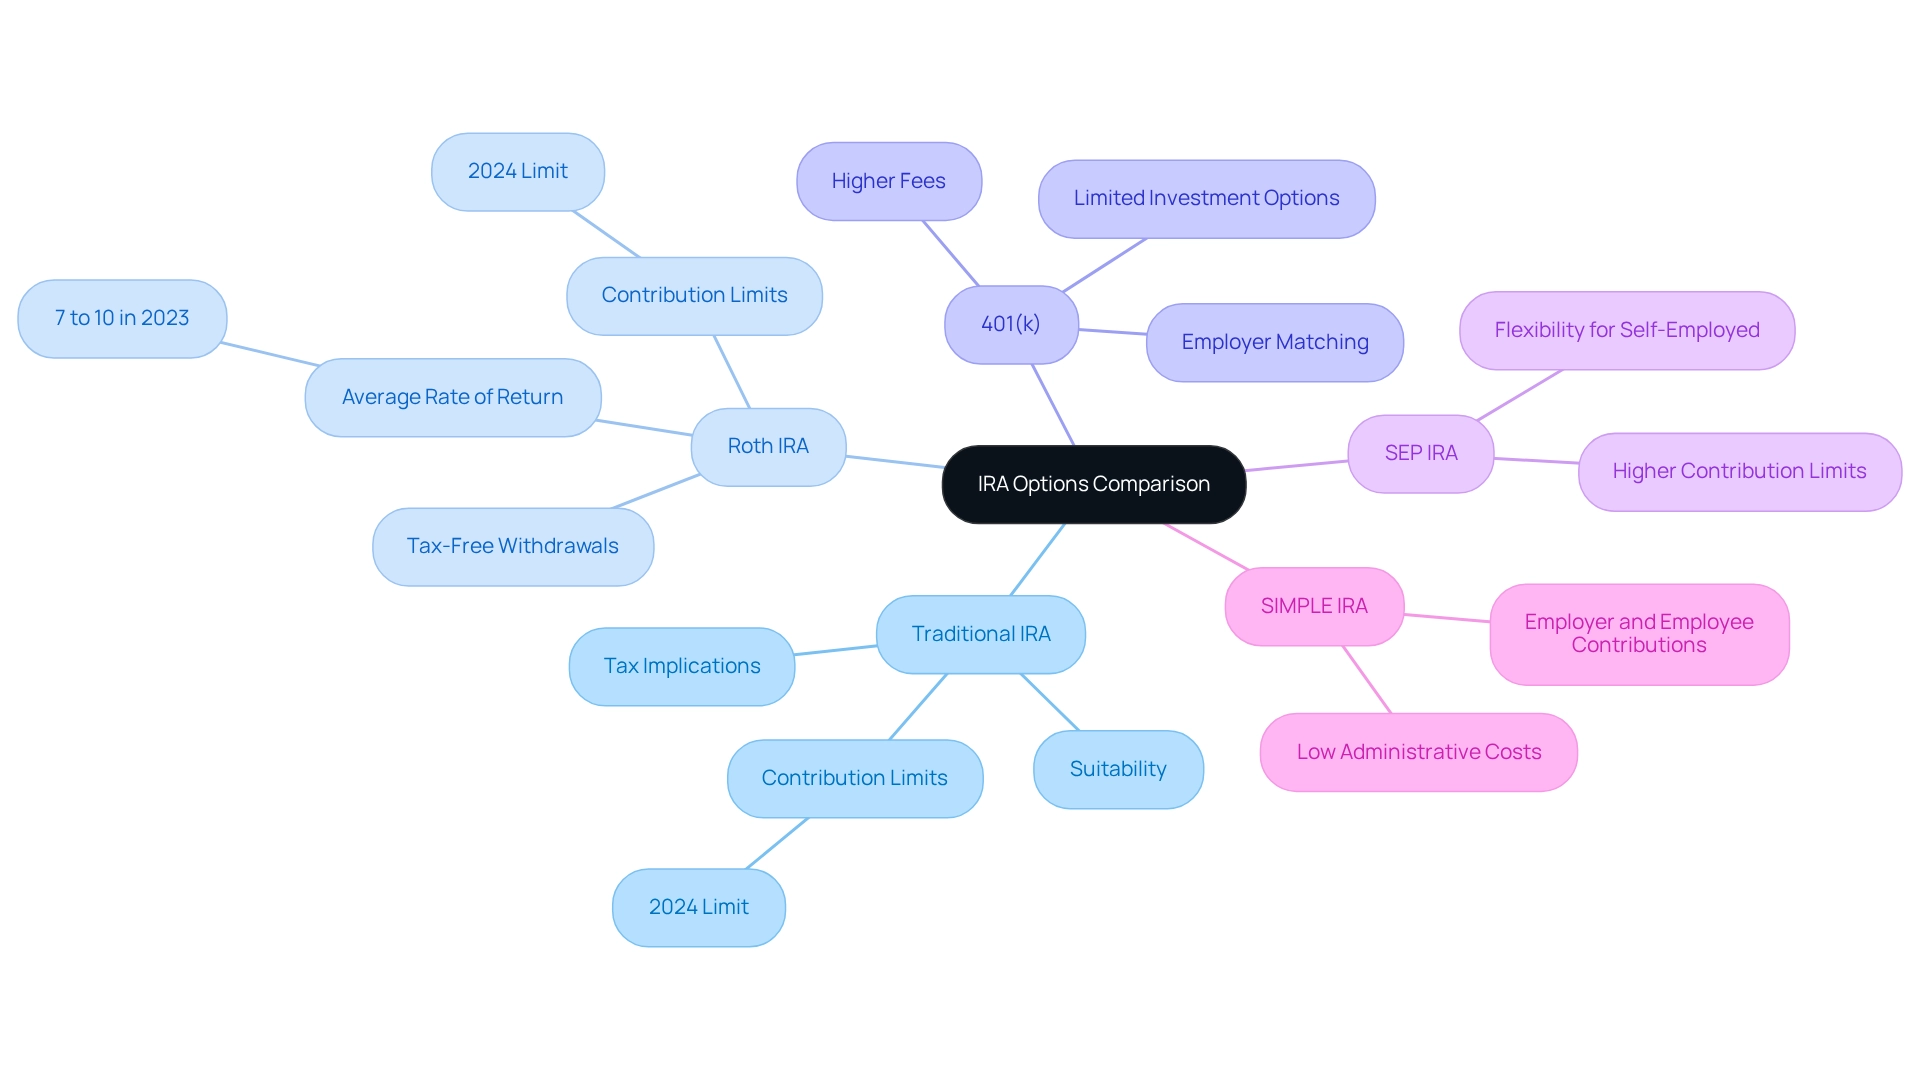
When considering savings options for your family’s future, it’s essential to thoughtfully compare the traditional IRA advantages and disadvantages with alternatives like Roth IRAs, 401(k)s, SEP IRAs, and SIMPLE IRAs.
Roth IRA: Imagine being able to withdraw your savings tax-free in your later years. Contributions to a Roth IRA are made with after-tax dollars, making it especially beneficial for families who anticipate being in a higher tax bracket in the future. In 2023, the average rate of return for investments within Roth IRAs was reported to be between 7% and 10%, reinforcing their appeal for long-term savings. Plus, with the contribution cap for Roth IRAs set to adjust for inflation in 2024, this becomes a crucial factor for families organizing their finances.
401(k): Many employers offer 401(k) plans with matching contributions, which can significantly boost your savings. However, it’s important to be aware that 401(k)s may come with higher fees and limited investment options compared to IRAs. Still, the potential for employer matching makes them an attractive option for many families.
SEP IRA: If you’re self-employed or a small business owner, a SEP IRA could be a flexible choice for you. It allows for higher contribution limits than Traditional IRAs, accommodating those with variable incomes.
SIMPLE IRA: Designed for small businesses, this plan supports both employer and employee contributions while keeping administrative costs low. It’s an accessible option for families working in smaller firms.
At Bright Advisers, we’re committed to minimizing fund fees across our investment strategies, ensuring that your family can maximize savings without the burden of excessive costs. Our customized wealth management solutions empower families to achieve economic security and freedom through personalized planning and tax optimization. As you assess your current economic situation, tax implications, and future goals, it’s vital to identify the IRA choice that best meets your family’s needs, taking into account the traditional IRA advantages and disadvantages. With contribution limits set at $7,000 in 2024, including catch-up contributions, understanding these differences is essential for effective money management. Furthermore, with proposed reforms aimed at ensuring the tax system supports financial success, staying informed about your retirement savings options is crucial. Together, we can navigate this journey toward a secure financial future for your family.
Conclusion
Navigating the world of retirement savings can feel overwhelming, but understanding the intricacies of a Traditional IRA offers families valuable insights to secure their financial future. This article has highlighted the key features of Traditional IRAs, including:
- Tax deductions
- Contribution limits
- The benefits of tax-deferred growth
For young families, the immediate tax advantages and the potential for long-term growth make Traditional IRAs an appealing option, allowing them to balance current expenses with future financial security.
However, it’s important to recognize the potential drawbacks of Traditional IRAs, such as:
- Taxable withdrawals
- Early withdrawal penalties
These factors can impact financial flexibility. Families must also consider their unique situations and retirement goals when comparing Traditional IRAs to other options, like Roth IRAs and employer-sponsored plans such as 401(k)s.
Ultimately, the decision to invest in a Traditional IRA should be based on a comprehensive understanding of both its benefits and limitations. By leveraging expert advice and engaging in strategic planning, families can effectively utilize this retirement vehicle to build a solid financial foundation for themselves and future generations. Prioritizing retirement savings today will pave the way for a more secure tomorrow, ensuring peace of mind in an ever-changing financial landscape. Remember, together, we can navigate this journey toward a brighter financial future.
Frequently Asked Questions
What is a Traditional IRA?
A Traditional IRA (Individual Retirement Account) is a tax-advantaged retirement savings vehicle that allows individuals to contribute pre-tax income, which can grow tax-deferred until withdrawal.
What are the tax advantages of a Traditional IRA?
Contributions to a Traditional IRA may be tax-deductible, which can significantly reduce taxable income for the year they are made, depending on income levels and access to employer-sponsored plans.
What are the contribution limits for a Traditional IRA in 2025?
For 2025, individuals under 50 can contribute up to $7,000, while those aged 50 and older can contribute up to $8,000.
How does a Traditional IRA provide tax-deferred growth?
Investments within a Traditional IRA grow tax-free until they are withdrawn, typically during retirement, allowing for substantial wealth accumulation over time.
Are there penalties for early withdrawals from a Traditional IRA?
Yes, withdrawals made before age 59½ may incur a 10% penalty in addition to standard income tax.
Are there income limits for contributing to a Traditional IRA?
No, there are no income restrictions for contributing to a Traditional IRA, making it accessible to a wide range of earners.
How can a Traditional IRA complement a 401(k)?
A Traditional IRA can enhance savings by supplementing employer-sponsored pension plans like 401(k)s, providing individuals with greater control and investment choices.
Who can provide assistance with understanding the tax implications of a Traditional IRA?
Families can consult with experts such as Jackson Hewitt Tax Pros for assistance in understanding the tax implications of Traditional IRA investments.
List of Sources
- Define Traditional IRA: Key Features and Functionality
- The benefits of a traditional IRA (https://jacksonhewitt.com/tax-help/tax-tips-topics/personal-finance-savings/benefits-of-a-traditional-ira)
- Benefits of an IRA | U.S. Bank (https://usbank.com/retirement-planning/financial-perspectives/benefits-of-an-ira.html)
- What is a Traditional IRA? – NerdWallet (https://nerdwallet.com/article/investing/what-is-a-traditional-ira)
- Explore Advantages of Traditional IRAs for Young Families
- I asked a financial planner what makes traditional IRAs and Roth IRAs different — and which one I need (https://businessinsider.com/financial-advisor-explains-choose-ira-your-needs-2024-3)
- Comparing IRA Benefits of Traditional and Roth IRAs (https://smartasset.com/retirement/ira-benefits)
- Roth vs Traditional IRA for Retirement | Gate City Investment Services (https://gatecity.bank/investment-services/resources/articles/roth-vs-traditional-ira-considerations)
- Roth vs. Traditional IRA: Which Is Right For You? – NerdWallet (https://nerdwallet.com/article/investing/roth-or-traditional-ira-account)
- Examine Disadvantages of Traditional IRAs: What Families Should Know
- Traditional and Roth IRAs: Benefits and Drawbacks (https://investopedia.com/articles/financial-advisors/120815/iras-advantages-disadvantages-and-which-one-right-you.asp)
- Roth IRAs vs. Traditional IRAs | Affinity Plus (https://affinityplus.org/personal/learn/learn-articles/roth-iras-vs-traditional-iras)
- Traditional IRA: Tax Rules, Limits and More (https://smartasset.com/retirement/traditional-ira)
- Determine the Right IRA: Comparing Traditional with Other Options
- American Retirement and Tax-Preferred Savings Accounts, Tax Year 2018 (https://taxfoundation.org/data/all/federal/401k-ira-retirement-savings-accounts)
- Roth IRA Savings Account Statistics | Unbiased (https://unbiased.com/discover/retirement/roth-ira-statistics)
- Americans’ Retirement Savings Show Real Progress (https://ici.org/viewpoints/24-view-real-progress)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading