

Overview
Understanding the Uniform Gift to Minors Act (UGMA) and the Uniform Transfers to Minors Act (UTMA) is crucial for families, especially when it comes to navigating tax consequences that can affect your child’s future. Imagine if the assets in these accounts could influence your child’s financial aid eligibility. It’s important to know that they can increase the Expected Family Contribution (EFC), which is a key factor in determining financial support for education.
Moreover, the income generated, capital gains, and contributions from these accounts carry tax implications that can feel overwhelming. But don’t worry; with strategic financial planning, you can mitigate these effects and secure a brighter future for your family.
By understanding these aspects, you can make informed decisions that align with your family values and priorities. Remember, we’re here for you, and together, we can navigate this journey towards effective wealth management for your children.
Key Highlights:
- UTMA accounts allow a wider range of assets, including real estate and art, while UGMA accounts are limited to cash and securities.
- Both account types are managed by custodians until the child reaches adulthood, typically between 18 and 21 years old.
- UTMA accounts can impact financial aid eligibility, with assets assessed at a rate of up to 20%, potentially increasing the Expected Family Contribution (EFC).
- Income generated from UTMA accounts is taxable, with specific thresholds for tax exemptions and rates depending on the child’s income.
- Contributions to UTMA accounts are considered gifts and can be made up to $19,000 per parent without incurring gift tax.
- Capital gains tax applies to profits from asset sales in UTMA accounts, with lower rates for long-term holdings.
- Families are encouraged to consider alternatives like 529 plans for college savings, which may offer better tax benefits and less impact on financial aid.
- Strategic timing of withdrawals from custodial accounts can help minimise their effect on financial aid eligibility.
Introduction
Navigating the complexities of financial planning for your children can feel overwhelming. It’s natural to worry about the implications of custodial accounts like the Uniform Transfers to Minors Act (UTMA) and the Uniform Gifts to Minors Act (UGMA). These accounts provide families with a structured way to manage assets until your children reach adulthood. However, it’s important to understand that the tax consequences associated with them can significantly affect financial aid eligibility and your overall wealth management strategies.
Imagine if you could leverage these accounts to secure your children’s financial futures while minimizing tax liabilities and maximizing aid opportunities. As you explore these options, remember that you’re not alone in this journey. We’re here for you, ready to guide you through the emotional and practical aspects of financial planning. Together, we can navigate this important chapter in your family’s life.
Define UTMA and UGMA Accounts
Navigating the world of financial planning for your children can feel overwhelming, but understanding the options available can bring peace of mind. The Uniform Transfers to Minors Act (UTMA) and the Uniform Gifts to Minors Act (UGMA) are here to help you manage resources for your little ones until they reach adulthood.
UTMA Funds offer you the flexibility to include a wide variety of assets, such as real estate, art, and various investments, alongside cash and securities. Picture this: a custodian manages these funds until your child reaches the age of majority, which varies by state—typically between 18 and 21 years old. This broader asset inclusion can be a wonderful opportunity for families looking to diversify their children’s financial futures.
On the other hand, UGMA Funds are a bit more straightforward, allowing only cash and securities. Like UTMA arrangements, a custodian oversees these funds until your child is ready to take charge.
Both plans serve as valuable tools for parents and guardians to ensure that funds are managed responsibly until your child is old enough to handle them. However, it’s important to be aware that the uniform gift to minors act tax consequences can significantly impact college aid eligibility due to the assets in these accounts. For instance, the uniform gift to minors act tax consequences can cause UGMA and UTMA holdings to reduce eligibility by 20% on the FAFSA and 25% on the CSS Profile.
As we approach 2025, more families are turning to these funds, yet many financial advisors recommend considering alternatives like 529 plans for college savings. These options often provide better tax benefits and have a lesser impact on financial aid.
Remember, we’re here for you on this journey. Together, we can navigate these choices and ensure a bright financial future for your family.

Explore Tax Consequences of UTMA Accounts
Navigating the uniform gift to minors act tax consequences of UTMA accounts can feel overwhelming for families, but understanding these intricacies is essential for securing your children’s future.
Income Tax: The income generated from UTMA account assets is taxable, and for the 2025 tax year, the first $1,350 of unearned income is exempt from taxes. The next $1,250 is taxed at the child’s marginal tax rate, typically around 10% or 12%. However, any income exceeding $2,700 is taxed at the parent’s rate, which can lead to significant tax liabilities if not managed wisely. Imagine families like Jay and Emma, who sought guidance from Bright Advisers; they successfully optimized their tax planning to balance growth potential and risk management, ensuring they could navigate these complexities with confidence.
Gift Tax: Contributions to a UTMA account are considered gifts to the minor. For 2025, parents can contribute up to $19,000 per parent without triggering gift tax. This allows families to provide substantial assistance without immediate tax consequences. This strategy can be particularly beneficial for young families looking to secure their children’s future, similar to how Allison and Brian maximized their financial potential through thoughtful tax planning.
Capital Gains Tax: When assets in a UTMA account are sold for a profit, capital gains tax applies. The applicable tax rate depends on how long the property was owned and the child’s total income level. For example, selling assets held for over a year qualifies for lower long-term capital gains rates, which can be advantageous for tax planning. Consider Emily and Mark, who gained the flexibility to make informed monetary decisions aligned with their aspirations by implementing strategies to manage their investments wisely.
Additionally, if a child’s unearned income exceeds $2,600, parents must submit IRS Form 8615 to report this income. Understanding the uniform gift to minors act tax consequences is essential for families looking to enhance their financial strategies and reduce tax responsibilities related to custodial funds. By effectively managing unearned income and utilizing tax-advantaged strategies, families can significantly improve their economic future, just as the clients of Bright Advisers have done. Together, we can navigate this journey and secure a brighter future for your family.

Compare Tax Implications of UTMA vs. UGMA Accounts
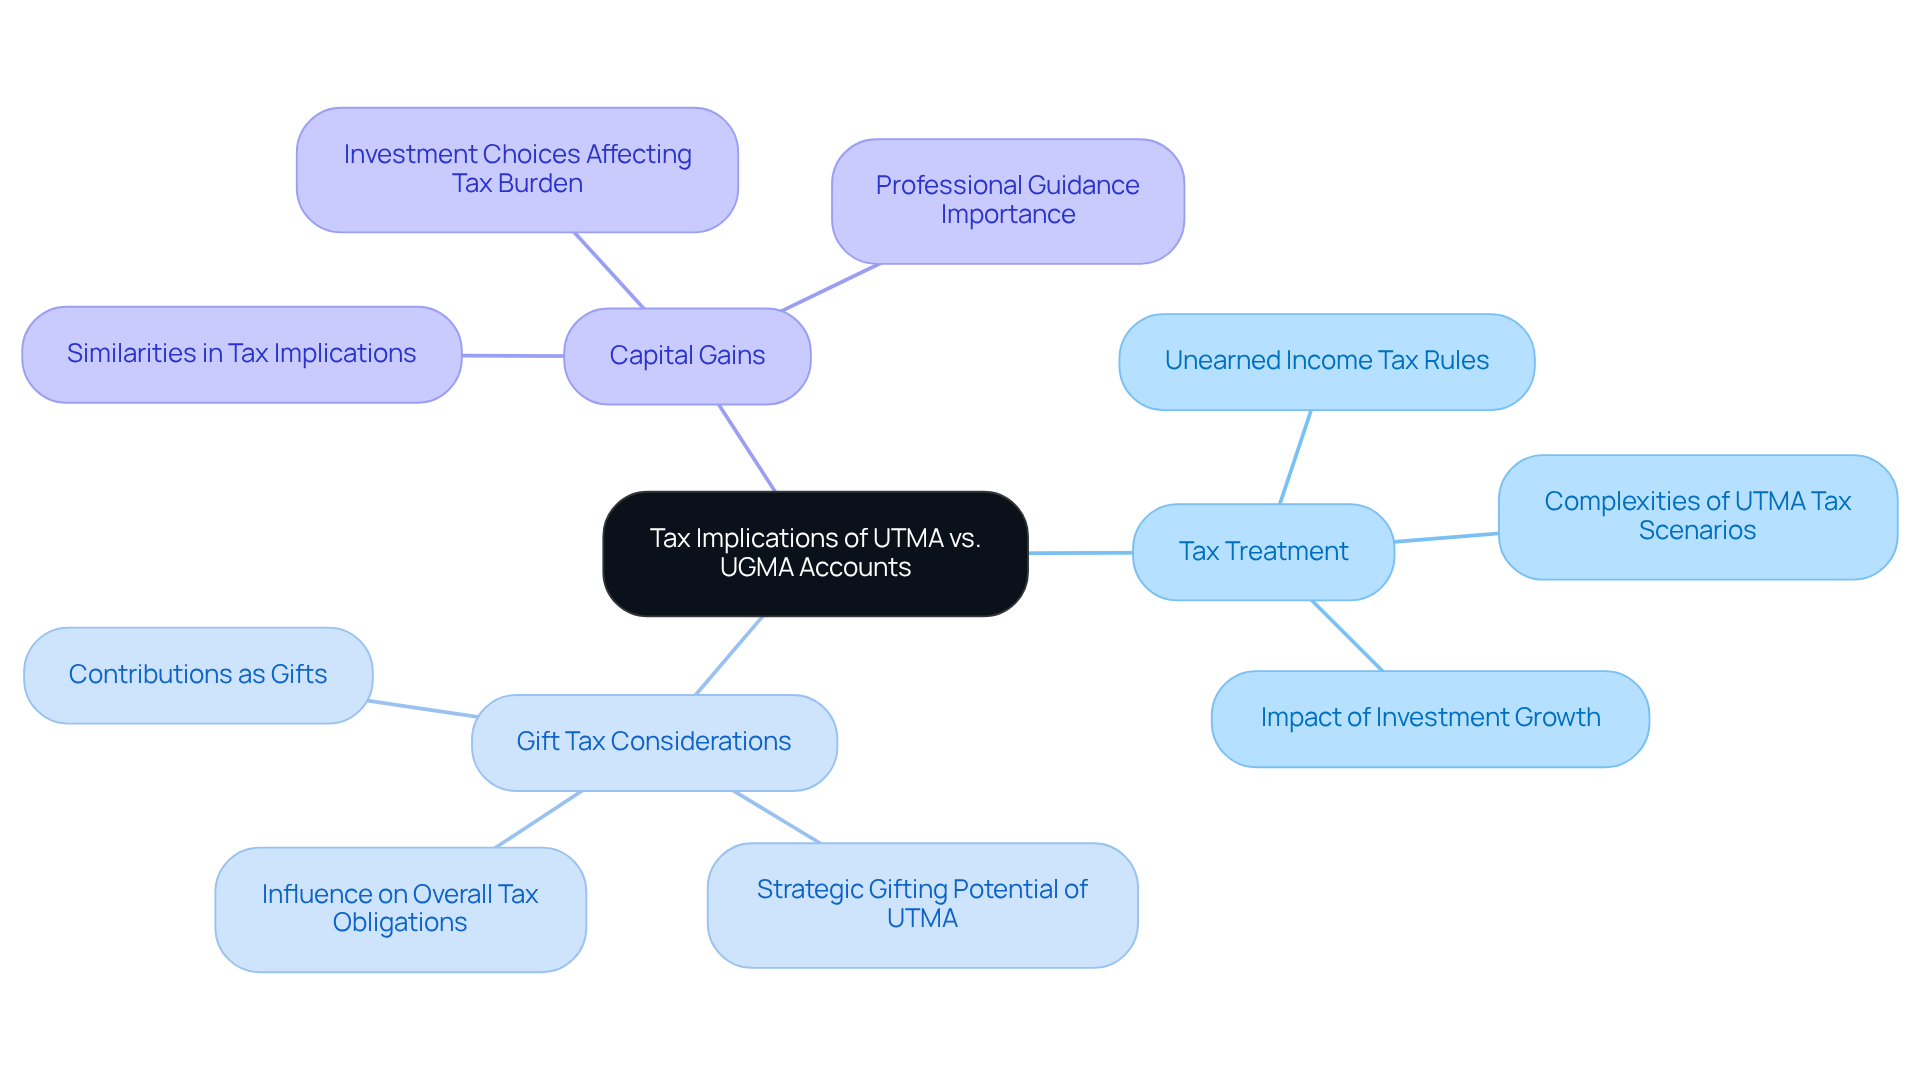
While both UTMA and UGMA accounts serve similar purposes, the differences in their uniform gift to minors act tax consequences are notable. Understanding these differences can empower you as a young family to make informed financial decisions.
Tax Treatment: Both account types are subject to the same income tax rules regarding unearned income. However, the wider selection of holdings permitted in UTMA arrangements can lead to more complicated tax scenarios, particularly related to the uniform gift to minors act tax consequences, especially if your investments grow significantly. At Bright Advisers, we understand how important it is to minimize fund fees, as this can enhance wealth management accessibility for families like yours, allowing you to allocate resources more effectively.
Gift Tax Considerations: Contributions to both funds are regarded as gifts. Yet, the flexibility of UTMA arrangements in terms of resource types may enable more strategic gifting, which can influence the uniform gift to minors act tax consequences and potentially decrease your overall tax obligations. This approach aligns with our commitment to customized wealth management solutions that help families secure their economic futures.
Capital Gains: The implications of capital gains tax are similar for both holdings, but the types of investments you choose can affect your overall tax burden. As you consider your investment strategy, remember that professional guidance from Bright Advisers can help high-income families navigate these challenges, optimizing wealth accumulation through effective tax planning and resource allocation.
Together, we can navigate this journey, ensuring that your family’s financial future is as bright as possible.
Assess Impact on Financial Aid Eligibility
Understanding how UTMA and UGMA accounts impact your child’s financial aid eligibility can feel overwhelming, but we’re here to help you navigate this journey with care. These accounts are classified as student assets, and it’s important to be aware of their implications.
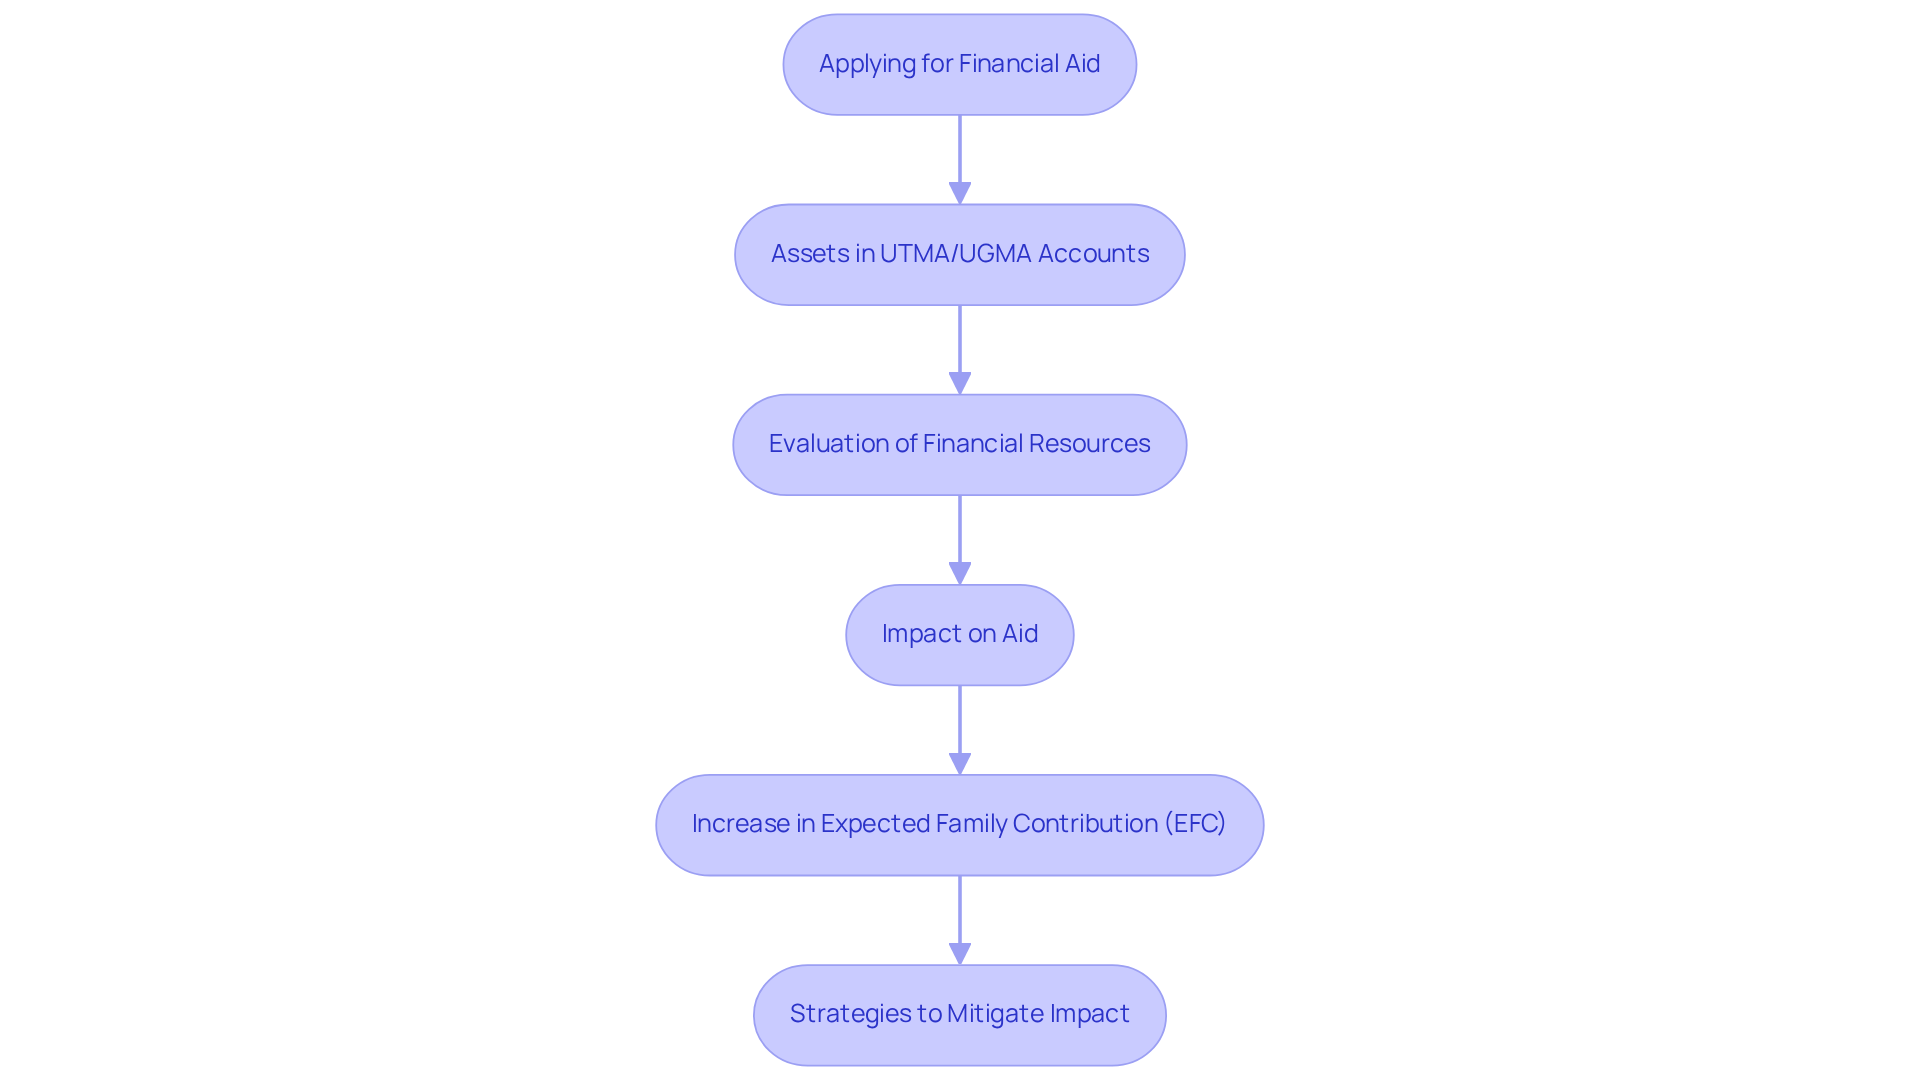
When you apply for financial aid, the assets in UTMA and UGMA accounts are taken into account during the evaluation of your child’s financial resources. This can lead to a decrease in the financial assistance offered, as schools consider these resources alongside your family’s overall financial situation.
Moreover, having funds in these custodial accounts can raise the Expected Family Contribution (EFC), a key factor in determining eligibility for need-based aid. For instance, student-owned resources are assessed at a rate of up to 20%. This means that a $10,000 fund could potentially increase the EFC by as much as $2,000, making it more challenging for your family to qualify for aid.
To ease the impact of these accounts on your aid eligibility, it’s wise to plan the timing of withdrawals carefully. By utilizing these resources before submitting aid applications, you can strategically reduce their effect on eligibility. Remember, consulting with financial aid advisors can provide you with tailored strategies to navigate these complexities effectively.
Together, we can explore the best options for your family, ensuring that your financial planning aligns with your values and goals. You’re not alone in this process, and support is available to help you make informed decisions.
Conclusion
Navigating the complexities of the Uniform Gift to Minors Act (UGMA) and Uniform Transfers to Minors Act (UTMA) is essential for families striving to secure their children’s financial futures. It’s important to understand the tax implications associated with these custodial accounts, as this knowledge not only aids in effective financial planning but also empowers families to make informed decisions that align with their long-term goals.
Imagine if you could confidently navigate the differences between UTMA and UGMA accounts. Key insights reveal that while UTMA accounts offer a broader range of asset types, both account types carry similar tax responsibilities that can significantly impact family finances. Moreover, considering the potential reduction in financial aid eligibility due to the assets held in these accounts is crucial for families planning for higher education costs.
Ultimately, the journey of financial planning for children should involve careful consideration of these tax implications and strategic decision-making. By consulting with financial advisors and exploring alternatives like 529 plans, families can optimize their resources and minimize tax burdens. Together, we can navigate this journey, embracing knowledge that not only secures a brighter financial future for children but also fosters a proactive approach to wealth management that can benefit families for generations to come.
Frequently Asked Questions
What are UTMA and UGMA accounts?
UTMA (Uniform Transfers to Minors Act) and UGMA (Uniform Gifts to Minors Act) accounts are financial tools designed to help manage and transfer assets to minors until they reach adulthood.
What types of assets can be included in UTMA accounts?
UTMA accounts offer flexibility to include a wide variety of assets, such as real estate, art, various investments, cash, and securities.
What types of assets can be included in UGMA accounts?
UGMA accounts are more straightforward and only allow cash and securities.
Who manages the funds in UTMA and UGMA accounts?
A custodian manages the funds in both UTMA and UGMA accounts until the child reaches the age of majority, which typically ranges from 18 to 21 years old depending on the state.
How do UTMA and UGMA accounts affect college financial aid eligibility?
Assets in UTMA and UGMA accounts can significantly impact college aid eligibility. They can reduce eligibility by 20% on the FAFSA and 25% on the CSS Profile.
Are there alternatives to UTMA and UGMA accounts for college savings?
Yes, financial advisors often recommend considering alternatives like 529 plans for college savings, as these options typically provide better tax benefits and have a lesser impact on financial aid.
Why is it important to understand the implications of UTMA and UGMA accounts?
Understanding these accounts is important as they can affect financial planning for children’s futures, including their college financial aid eligibility.
List of Sources
- Define UTMA and UGMA Accounts
- UTMA vs. UGMA: Understanding for Investment Planning (https://westernsouthern.com/investments/utma-vs-ugma-accounts)
- Can You Use an UGMA or UTMA Account to Save for College? (https://savingforcollege.com/article/can-you-use-an-ugma-or-utma-account-to-save-for-college)
- First Command UTMA and UGMA Savings Accounts (https://firstcommand.com/banking/personal/savings/utma-ugma)
- What Is a UTMA or UGMA Account for 2025 | Research.com (https://research.com/student-loans/what-is-a-utma-or-ugma-account)
- Explore Tax Consequences of UTMA Accounts
- What Are UGMA and UTMA Accounts? – Experian (https://experian.com/blogs/ask-experian/what-are-ugma-and-utma-accounts)
- Tax Filing Requirements For Minor Children with Investment Income | Greenbush Financial Group (https://greenbushfinancial.com/all-blogs/minor-child-investment-income-tax-return-filing)
- 7 Essential UTMA Withdrawal Tax Rules Every Parent Should Know – Bright Advisers (https://brightadvisers.com/7-essential-utma-withdrawal-tax-rules-every-parent-should-know)
- How to Slash Kiddie Taxes on Your Child’s UTMA Account (https://kiplinger.com/taxes/how-to-slash-kiddie-taxes-on-your-childs-utma-account)
- Confused About UTMA Tax Rules? Here’s a Breakdown (https://getearlybird.io/blog/utma-tax-rules)
- Compare Tax Implications of UTMA vs. UGMA Accounts
- UGMA vs UTMA: Which Is Better? | How Do They Work? (https://districtcapitalmanagement.com/ugma-vs-utma)
- UGMA vs. UTMA Custodial Accounts (https://smartasset.com/investing/ugma-vs-utma)
- UTMA & UGMA Custodial Accounts: Overview, Benefits – NerdWallet (https://nerdwallet.com/article/investing/utma-ugma)
- What Is a UTMA or UGMA Account for 2025 | Research.com (https://research.com/student-loans/what-is-a-utma-or-ugma-account)
- Assess Impact on Financial Aid Eligibility
- How does an UTMA account impact a child’s future financial aid? | Creative Advising, LLC (https://creative-advising.com/how-does-an-utma-account-impact-a-childs-future-financial-aid)
- What Is a UTMA or UGMA Account for 2025 | Research.com (https://research.com/student-loans/what-is-a-utma-or-ugma-account)
- UGMA vs. UTMA Custodial Accounts (https://smartasset.com/investing/ugma-vs-utma)
- Which Accounts Are Best To Help My Grandchildren Pay For College? 🎓 (https://seasidewealth.com/blog/which-accounts-are-best-to-help-my-grandchildren-pay-for-college)
- The Impact College Savings Has On Financial Aid – WSFS Bank (https://wsfsbank.com/resources/the-impact-college-savings-has-on-financial-aid)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading