

Overview
Imagine a world where your child’s financial future is secure and thriving. UTMA trust accounts serve as custodial arrangements, allowing you to transfer a variety of assets to your little ones. This not only provides significant tax benefits but also offers flexibility in how those funds can be used until they reach adulthood. It’s important to understand that the income generated in these accounts is taxed at your child’s lower rate, making it a smart financial choice.
These accounts present a broader range of investment options compared to UGMA accounts, positioning them as an effective tool for families like yours, who are dedicated to nurturing their children’s financial well-being. By choosing a UTMA account, you are taking a meaningful step towards securing your family’s future.
Together, we can navigate this journey, ensuring that your children have the resources they need to flourish. We’re here for you, ready to support you in making informed decisions that align with your family values.
Key Highlights:
- UTMA accounts allow adults to transfer assets to minors, managed by a custodian until the child reaches adulthood.
- They facilitate gifting various assets, including cash, stocks, and real estate, providing significant tax benefits.
- Income generated in UTMA accounts is taxed at the minor’s lower tax rate, leading to potential tax savings for families.
- UTMA accounts offer a broader range of asset types compared to UGMA accounts, allowing for diverse investment strategies.
- Funds in UTMA accounts can be used for educational and non-educational expenses, providing greater flexibility.
- Once assets are transferred to a UTMA account, the gift is irrevocable, meaning donors cannot reclaim the assets.
- Assets in UTMA accounts may affect eligibility for need-based financial aid, as they are considered the child’s resources.
- Upon reaching adulthood, the child gains full control over the custodial funds, which may differ from parental intentions.
- While income in UTMA accounts is taxed at the child’s rate, unearned income above $2,000 is taxed at the parents’ rate, which can complicate tax planning.
- Investment options in UTMA accounts can be limited compared to specialized accounts like 529 plans, necessitating careful financial planning.
Introduction
In the quest to secure your child’s financial future, many families are discovering the value of custodial accounts as a thoughtful strategy. Among these options, the Uniform Transfers to Minors Act (UTMA) account shines for its flexibility and tax benefits. It allows you to transfer a variety of assets to your child without the complexities of a formal trust. Imagine being able to include everything from cash and stocks to real estate and collectibles, all while building wealth and managing tax liabilities effectively.
However, as you explore this option, it’s important to understand both the benefits and limitations of UTMA accounts. This knowledge ensures that your financial strategies align with your family’s long-term goals. In this article, we will delve into the intricacies of UTMA accounts, comparing them with similar options. We will highlight the critical considerations you must keep in mind as you navigate this financial landscape. Together, we can ensure that your family’s financial future is secure and thriving.
Define UTMA Accounts and Their Purpose
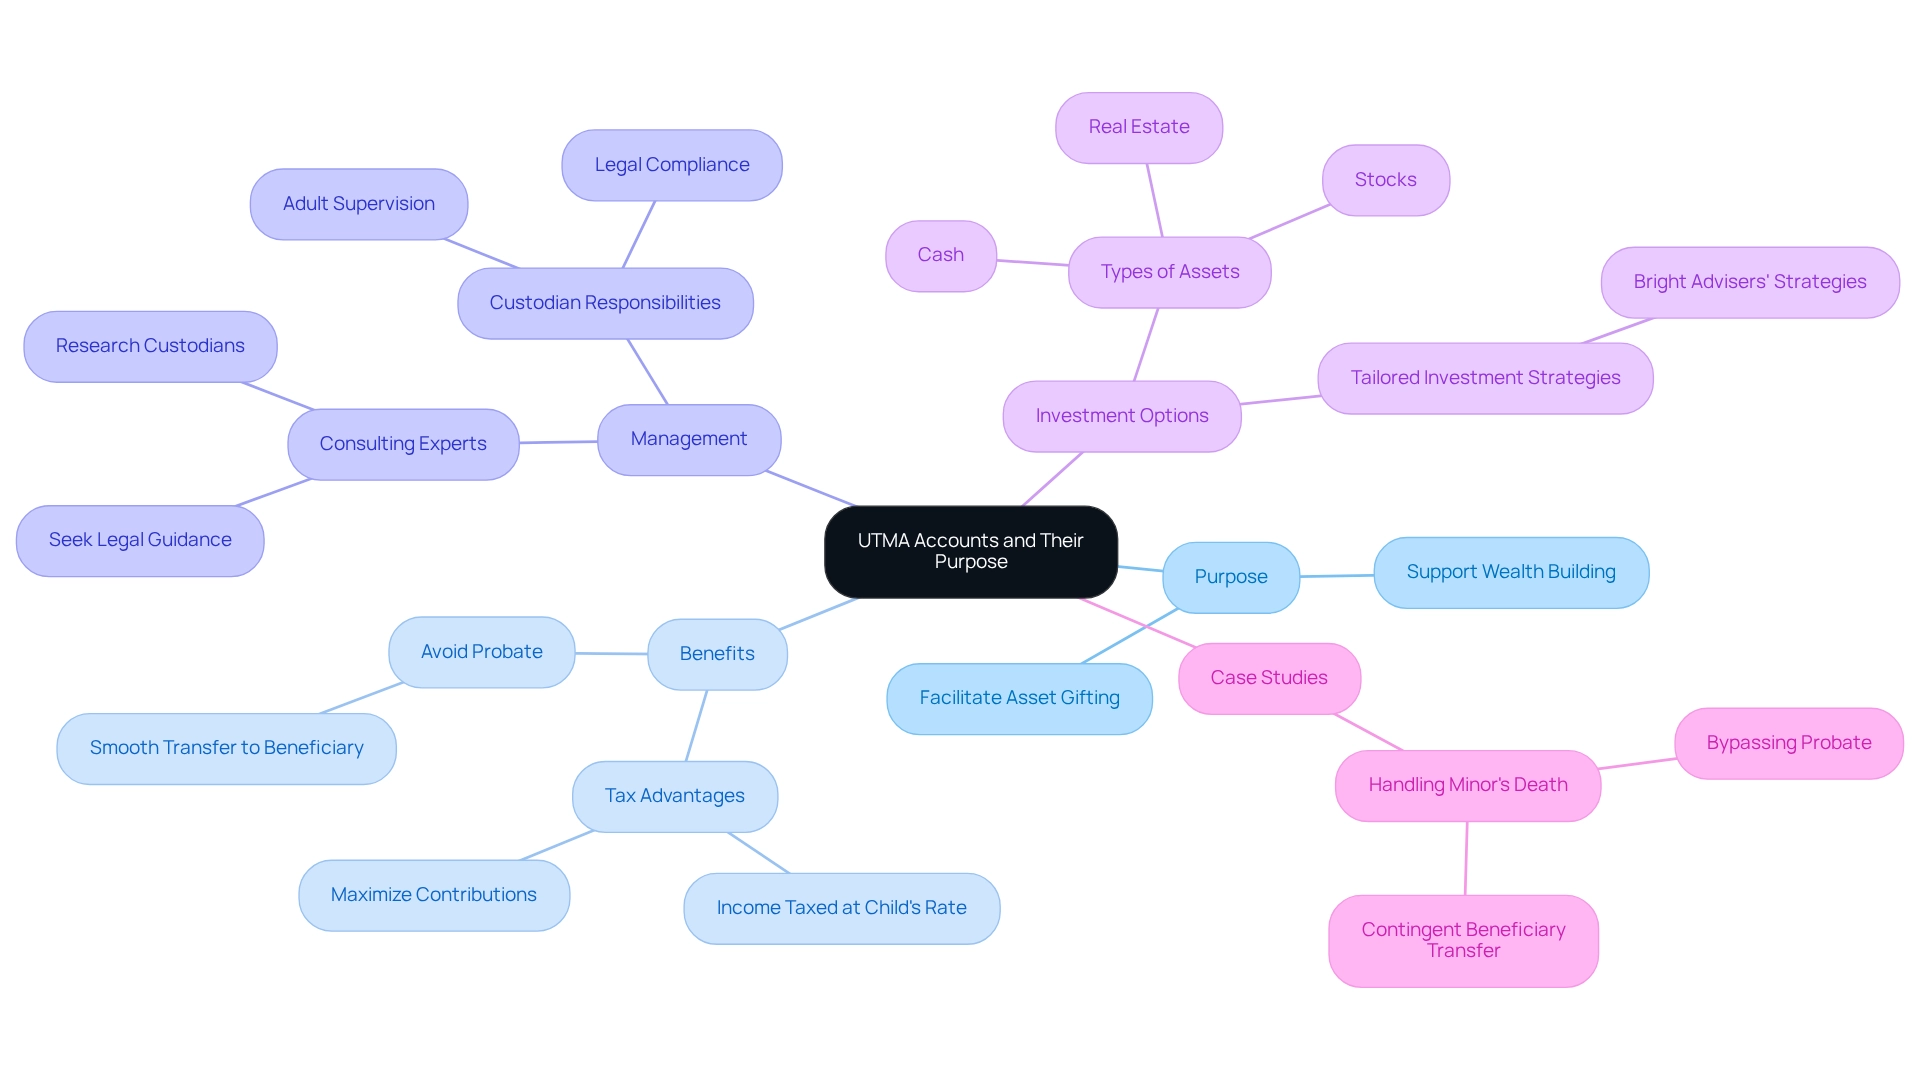
A UTMA trust account serves as a custodial arrangement that allows adults to transfer assets to minors without the need for a formal trust. Managed by a custodian—often a parent or guardian—these funds remain under adult supervision until the child reaches the age of majority, which varies by state, generally between 18 and 21 years old.
The primary purpose of a UTMA trust account is to facilitate the gifting of various assets, including cash, stocks, and even real estate, to minors while providing significant tax benefits. Unlike conventional savings options, these arrangements support a broader range of asset categories, making them an appealing choice for families looking to build wealth for their children.
One of the remarkable advantages of a UTMA trust account is that the income generated within it is typically taxed at the child’s lower tax rate rather than the adult donor’s rate. This feature can lead to substantial tax savings, allowing families to maximize their contributions and enhance their overall financial strategy. By incorporating a UTMA trust account along with custodial funds into a comprehensive wealth plan, families can leverage the expertise of asset management firms like Bright Advisers to improve their tax situation and secure their children’s futures.
Imagine if Bright Advisers’ Diversified Premia and Opportunity Strategies could elevate custodial funds by providing tailored investment options that align with your family’s financial goals. Real-life examples illustrate the benefits of custodial savings for minors. Families can allocate these savings into a UTMA trust account for future educational expenses, ensuring that children have the resources they need as they transition into adulthood. Moreover, in unfortunate circumstances where a minor passes away before reaching adulthood, assets held in a UTMA trust account typically bypass probate, allowing for a smooth transfer to a contingent beneficiary, ensuring that the designated recipient receives the funds without unnecessary delays. This process is highlighted in the case study of Allison and Brian, who successfully improved their financial situation through strategic tax planning and investment management.
As we approach 2025, custodial savings options continue to be a favored choice among families, with data indicating a growing trend in their use. Recent information shows a significant increase in custodial savings, underscoring the importance of the UTMA trust account in wealth management. They not only serve as a means for asset gifting but also play a vital role in financial planning for future generations, aligning with the aspirations of families striving to secure their children’s financial futures. It is also wise for parents to seek legal guidance to ensure compliance with withdrawal regulations, adding a layer of complexity to the management of these funds. As finance expert Alex Hillsberg suggests, “Research different custodians: Compare fees, investment options, and customer service to find the best fit for your needs.
Differentiate Between UTMA and UGMA Accounts
Understanding the utma trust account and the Uniform Gifts to Minors Act (UGMA) can be a journey for parents looking to secure their children’s financial futures. While both are custodial arrangements designed for minors, they differ significantly in asset management and flexibility.
Asset Types:
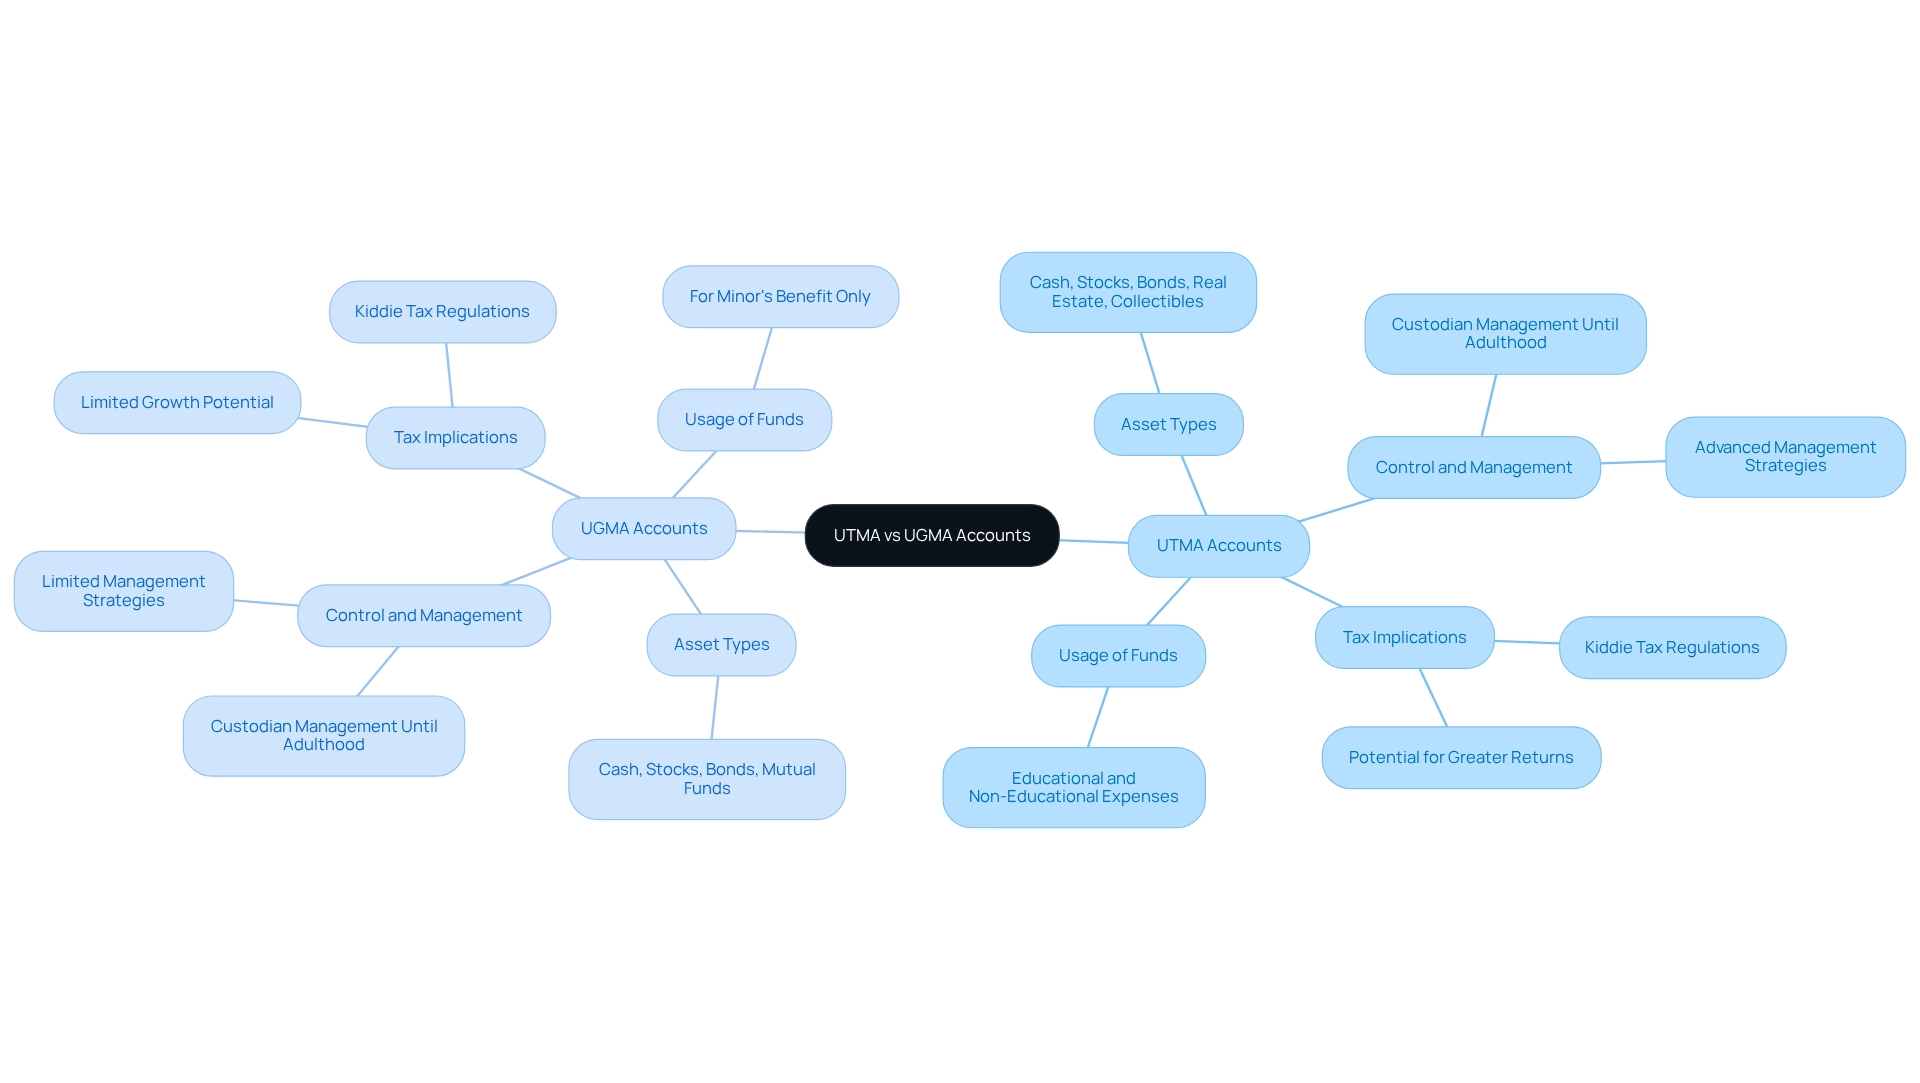
- UTMA Accounts: Imagine a world where you can invest in a wide array of assets for your child—cash, stocks, bonds, real estate, and even collectibles like art or patents. This versatility opens the door to various investment strategies, catering to your family’s unique financial goals. At Bright Advisers, we harness advanced technology to create hyper-personalized investment portfolios. Our strategies, such as Diversified Premia, provide exposure to U.S. large-cap equity, while the Opportunity Strategy focuses on dynamic growth factors. This way, families can optimize their asset allocation effectively.
- UGMA Accounts: On the other hand, UGMA accounts are limited to financial assets like cash, stocks, bonds, and mutual funds, leaving out physical assets. This limitation may impact the potential for growth and diversification.
Control and Management:
Both account types require a custodian to manage the assets until the minor reaches adulthood. However, the broader selection of resources in custodial funds may call for more advanced management strategies to enhance returns. Bright Advisers’ innovative approach can be especially beneficial for families navigating these waters.
Tax Implications:
Both accounts fall under the ‘kiddie tax’ regulations, which tax unearned income at the child’s tax rate up to a specified threshold. The potential for greater returns in custodial investment options, thanks to their diverse asset categories, may lead to distinct tax implications that families should consider. Bright Advisers highlights customized wealth management solutions to help you navigate these complexities with ease.
Usage of Funds:
Funds from both accounts can be used for the minor’s benefit, but the utma trust account provides greater flexibility regarding the types of expenses covered, including both educational and non-educational costs. This flexibility aligns with Bright Advisers’ commitment to enhancing wealth management accessibility for families through minimal fund fees.
In conclusion, while UTMA and UGMA accounts serve as effective tools for parents striving to secure their children’s economic futures, the choice between them should be guided by your desired asset types and overall financial strategy. Bright Advisers’ unique investment approaches and cutting-edge technology distinguish us from traditional methods, making us a valuable ally for families. Seeking guidance from a financial consultant, like those at Bright Advisers, can provide essential direction in making these decisions, ensuring that you are equipped with the right tools for your planning needs. Together, we can navigate this journey.
Benefits of UTMA Accounts
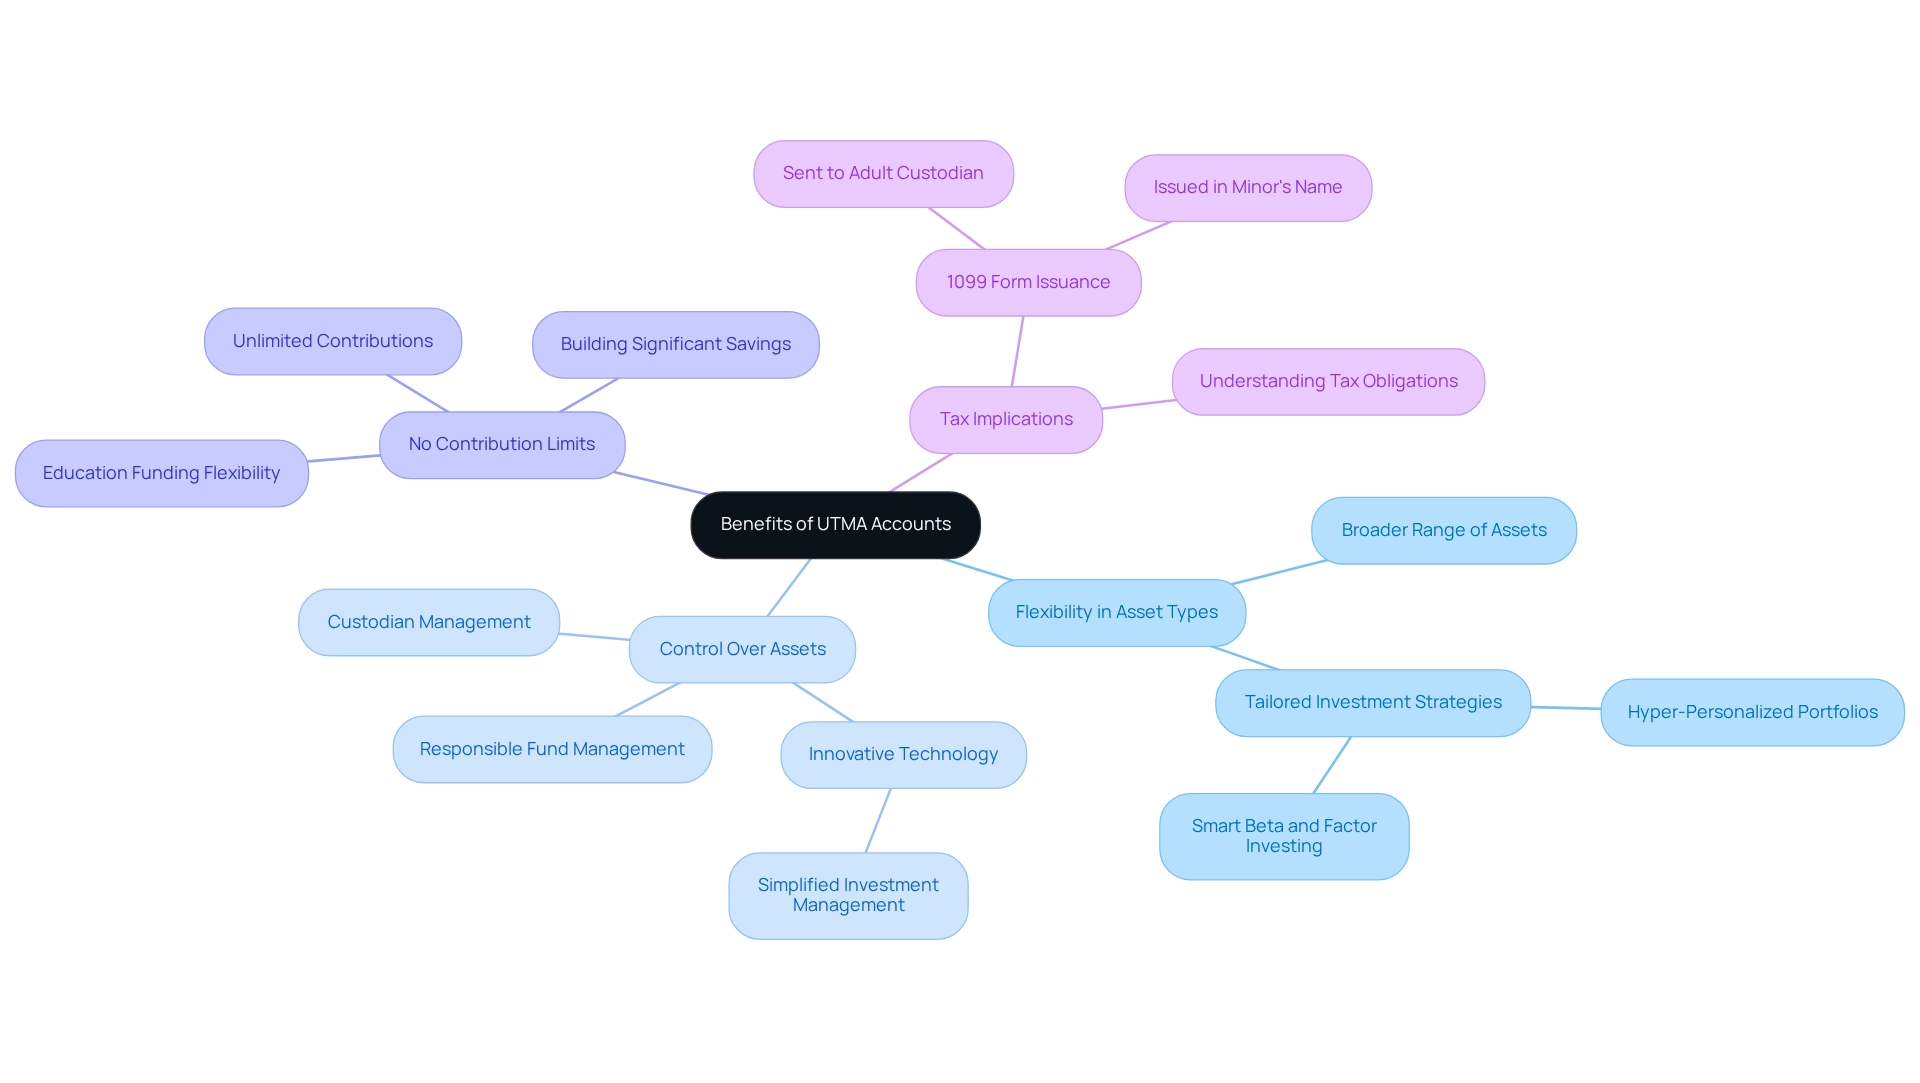
Custodial savings plans provide numerous attractive advantages for households aiming to secure their children’s economic future, particularly through the UTMA trust account, where the income generated is taxed at the child’s tax rate, typically lower than that of the parents. This can lead to substantial tax savings, especially as families accumulate wealth over time. Bright Advisers highlights the importance of strategic tax planning, demonstrated in the success story of Allison and Brian, who improved their tax situation through thorough monetary planning.
-
Flexibility in Asset Types: It’s important to understand that unlike UGMA accounts, the UTMA trust account permits a broader range of assets, including real estate and collectibles. This flexibility enables families to adopt various investment strategies tailored to their financial objectives, similar to the hyper-personalized portfolios designed by Bright Advisers that integrate smart beta and factor investing techniques.
-
Control Over Assets: The custodian maintains control over the assets until the child reaches the age of majority. This ensures responsible management of funds, safeguarding the child’s interests until they are ready to take over. Bright Advisers’ innovative technology simplifies this process, making it easier for families to manage their investments effectively.
-
No Contribution Limits: Custodial funds also do not impose annual contribution limits, allowing parents and relatives to contribute freely. This feature is particularly advantageous for families looking to build significant savings over time, aligning with Bright Advisers’ approach to maximizing financial potential through tailored strategies, especially since funds in a UTMA trust account can be utilized for various expenses, including education. This flexibility assists parents in preparing for their children’s educational needs without the limitations often linked to other savings options. Bright Advisers encourages families to think strategically about education funding, as illustrated by the case of Emily and Mark, who achieved economic independence to prioritize their children’s future.
-
Tax Implications: A pertinent case study clarifies that the 1099 form for a custodial trust is issued in the name of the minor, as they are the legal holder of the trust, and is usually sent to the adult custodian. This highlights the tax obligations related to certain custodial arrangements and the significance of understanding these consequences—a crucial element of the thorough financial planning provided by Bright Advisers.
In conclusion, these arrangements provide a flexible and tax-efficient method for families to save for their children’s futures, making them a vital part of successful financial planning. Together, we can navigate these opportunities with confidence, leveraging the expertise of Bright Advisers.
Considerations and Limitations of UTMA Accounts
While custodial funds offer significant advantages, it’s essential for families to recognize various key factors and restrictions that may impact their financial journey:
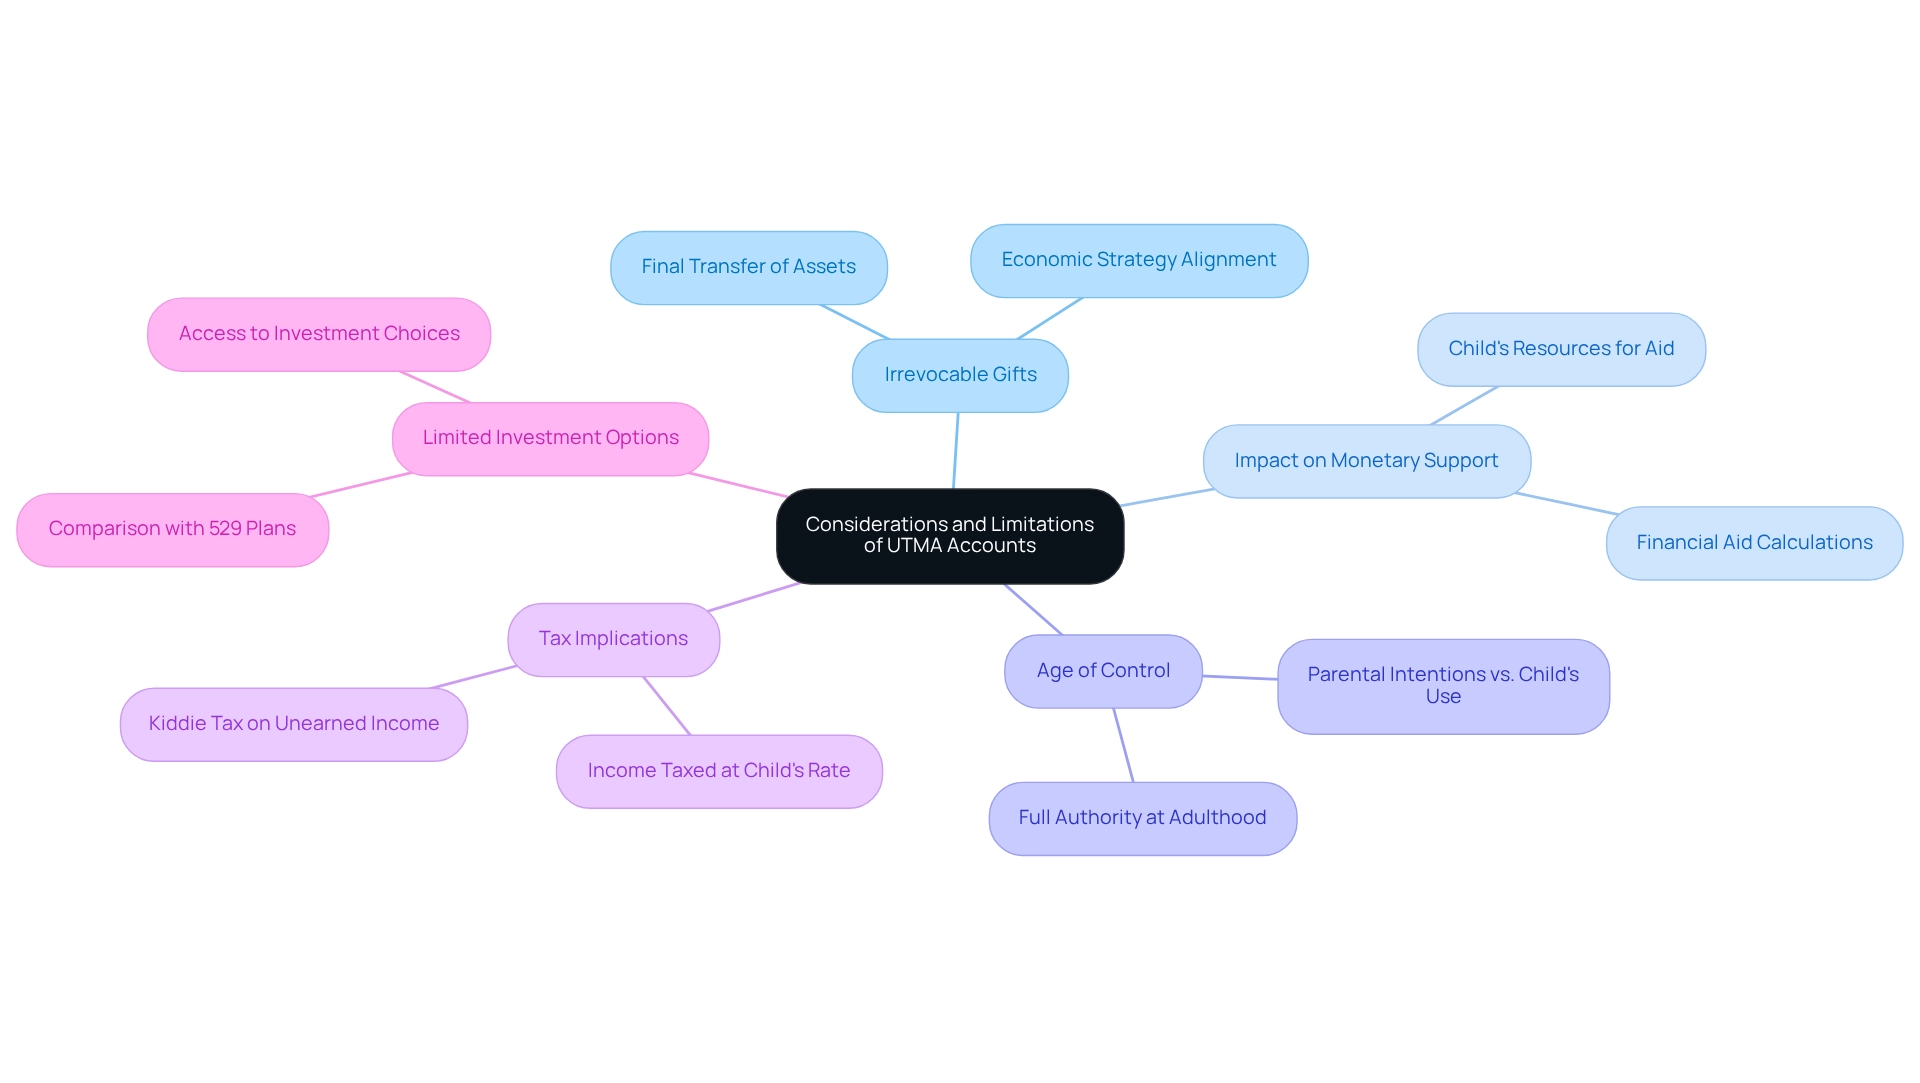
- Irrevocable Gifts: Once assets are placed in a custodial fund, the transfer is final. This means that the donor cannot reclaim the assets, which might not align with every family’s economic strategy. For families like Jay and Emma, who are focused on reducing monetary anxiety and ensuring their resources, including their UTMA trust account, are allocated effectively, this is a critical consideration.
- Impact on Monetary Support: Assets maintained in a UTMA trust account are categorized as the child’s resources when seeking aid, greatly influencing eligibility for need-based assistance. This is particularly crucial for families planning for college expenses, as student-owned assets can negatively impact financial aid calculations. Families like Emily and Mark, who seek to build a solid foundation for their future, often echo these concerns.
- Age of Control: Upon reaching adulthood, the child gains full authority over the custodial funds and can utilize the resources as they wish. This may diverge from the parents’ original intentions regarding the use of these funds, which is a consideration for parents aiming to secure their children’s future. For instance, parents like Allison and Brian may wish to ensure that funds from the UTMA trust account are used specifically for educational purposes rather than discretionary spending.
- Tax Implications: Although income generated in a UTMA trust account is taxed at the child’s rate, any unearned income exceeding $2,000 is taxed at the parents’ or custodian’s marginal tax rate. Additionally, any unearned income above a specific threshold is subject to the ‘kiddie tax.’ This can create a greater tax burden if the fund produces significant earnings, complicating budget planning. Families like Allison and Brian, looking to maximize their financial potential through proper tax planning, should be particularly mindful of these implications. Bright Advisers can assist in developing strategies to effectively mitigate these tax burdens associated with a UTMA trust account.
- Limited Investment Options: While a UTMA trust account permits a range of assets, its investment options may be more restricted compared to specialized accounts like 529 plans, which are tailored for education savings. This limitation can influence households’ capacity to enhance their investment strategies. Bright Advisers’ dedication to low fund charges improves access to a wider variety of investment choices, enabling households to make informed decisions that correspond with their monetary objectives.
Real-life examples demonstrate these challenges. Many families frequently shift assets from their child’s name to their own to improve aid eligibility, as student-owned assets can negatively impact aid computations. This process requires careful planning and consultation with financial experts to navigate potential fiscal, tax, and aid implications. As noted, custodial accounts, like any accounts that contribute to college savings, deserve close scrutiny to see if they can work for you.
In summary, while the UTMA trust account can be an effective tool for building wealth for minors, it’s crucial for families to thoroughly evaluate these limitations. Together, we can navigate this journey to ensure alignment with broader financial objectives, particularly in the context of personalized planning and tax optimization that Bright Advisers offers.
Conclusion
UTMA accounts present a wonderful opportunity for families eager to secure their children’s financial futures. By allowing a diverse range of assets to be transferred and managed under the care of a responsible adult, these accounts offer unique tax advantages and flexibility that can significantly enhance a family’s financial strategy. Imagine being able to invest in various asset types—from stocks and bonds to real estate—providing your family with the tools to craft personalized investment portfolios that align with your long-term goals.
However, it’s important to navigate the complexities of UTMA accounts with care. While the benefits are substantial, families must also be mindful of the limitations, such as the irrevocable nature of the gifts and potential impacts on financial aid eligibility. Understanding these considerations is essential to ensure that your financial planning aligns with your family’s objectives, particularly regarding educational funding and tax implications.
Ultimately, leveraging the expertise of financial advisors, like those at Bright Advisers, can empower families to make informed decisions that maximize the benefits of UTMA accounts while mitigating potential drawbacks. Together, we can navigate this journey, fostering a comprehensive approach to wealth management. By doing so, families can confidently secure a prosperous future for their children, ensuring that the financial resources intended for them are effectively managed and utilized. We’re here for you, every step of the way.
Frequently Asked Questions
What is a UTMA trust account?
A UTMA trust account is a custodial arrangement that allows adults to transfer assets to minors without the need for a formal trust. It is managed by a custodian, typically a parent or guardian, until the child reaches the age of majority, which varies by state, generally between 18 and 21 years old.
What is the primary purpose of a UTMA trust account?
The primary purpose of a UTMA trust account is to facilitate the gifting of various assets, including cash, stocks, and real estate, to minors while providing significant tax benefits.
How does a UTMA trust account provide tax advantages?
The income generated within a UTMA trust account is typically taxed at the child’s lower tax rate rather than the adult donor’s rate, which can lead to substantial tax savings and allow families to maximize their contributions.
Can a UTMA trust account be used for educational expenses?
Yes, families can allocate savings into a UTMA trust account for future educational expenses, ensuring that children have the necessary resources as they transition into adulthood.
What happens to the assets in a UTMA trust account if a minor passes away before reaching adulthood?
If a minor passes away before reaching adulthood, assets held in a UTMA trust account typically bypass probate, allowing for a smooth transfer to a contingent beneficiary without unnecessary delays.
Why are custodial savings options becoming more popular among families?
Custodial savings options, including UTMA trust accounts, are increasingly favored by families as they serve as a means for asset gifting and play a vital role in financial planning for future generations.
What should parents consider when managing a UTMA trust account?
Parents should seek legal guidance to ensure compliance with withdrawal regulations and consider researching different custodians to compare fees, investment options, and customer service.
List of Sources
- Define UTMA Accounts and Their Purpose
- Understanding UTMA Accounts and Their Role in Estate Planning . (https://legacycarelaw.com/blog/estate-planning-2/understanding-utma-accounts-and-their-role-in-estate-planning)
- What Is a UTMA or UGMA Account for 2025 | Research.com (https://research.com/student-loans/what-is-a-utma-or-ugma-account)
- T. Rowe Price Personal Investor – Custodial Accounts (https://troweprice.com/personal-investing/accounts/general-investing/ugma-utma.html)
- UTMA Accounts – What You Need To Know – Bridgeview Capital Advisors, Inc. (https://bridgeviewadvisors.com/utma-accounts)
- Differentiate Between UTMA and UGMA Accounts
- UGMA vs UTMA: What’s the Difference? (https://portfoliopilot.com/resources/posts/ugma-vs-utma-whats-the-difference)
- UGMA vs. UTMA accounts explained: Benefits & setup guide (https://thrivent.com/insights/college-planning/what-are-ugma-and-utma-accounts)
- UGMA vs. UTMA | Unbiased (https://unbiased.com/discover/investing/ugma-vs-utma)
- UTMA vs. UGMA: Understanding for Investment Planning (https://westernsouthern.com/investments/utma-vs-ugma-accounts)
- Benefits of UTMA Accounts
- What Is a UTMA or UGMA Account for 2025 | Research.com (https://research.com/student-loans/what-is-a-utma-or-ugma-account)
- Custodial Account vs. 529 Plan: Choosing the Best Account for Your Clients (https://feathery.io/blog/custodial-account-vs-529)
- Saving for College: 3 Tools for Playing the Long Game – Community Point Bank (https://ourcpb.bank/saving-for-college-3-tools-for-playing-the-long-game)
- UTMA Tax Rules 2023 & 2024 – Greatest Gift (https://greatestgiftapp.com/blog/utma-tax-rules)
- Considerations and Limitations of UTMA Accounts
- First Command UTMA and UGMA Savings Accounts (https://firstcommand.com/banking/personal/savings/utma-ugma)
- Are Custodial Accounts a Good Option for Parents Saving for College? (https://savingforcollege.com/article/are-custodial-accounts-a-good-option-for-parents-saving-for-college)
- How 7 Different Assets Affect Your Financial Aid Eligibility (https://savingforcollege.com/article/how-7-different-assets-can-affect-your-financial-aid-eligibility)
- FAFSA Assets | CollegeData (https://collegedata.com/resources/pay-your-way/how-student-and-parent-assets-affect-your-financial-aid)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading