

Overview
Understanding the wealth management fee structure is crucial for families, especially when it comes to securing a stable financial future. Imagine navigating the complex world of fees without clarity—this can be overwhelming. That’s why it’s important to explore various fee models together.
Consider the different options available:
- Assets Under Management
- Flat fees
- Hourly rates
- Retainer fees
- Commission-based fees
Each model has its own implications, and transparency is key to avoiding hidden costs that could diminish your investment returns.
By shedding light on these fee structures, we empower families to make informed financial decisions. It’s not just about numbers; it’s about ensuring that your family’s financial journey is as smooth and secure as possible. Remember, we’re here for you, ready to support you in navigating these important choices. Together, we can work towards a brighter financial future for your family.
Key Highlights:
- Wealth management is a holistic approach that includes investments, estate planning, tax strategies, and retirement planning, crucial for families to secure their financial future.
- Effective wealth management helps families align financial decisions with their values and long-term goals, particularly important for those with young children.
- The global asset management market was valued at $458.02 billion in 2023, with a projected growth rate of 36.4% CAGR from 2024 to 2030, highlighting the growing importance of wealth management.
- Women are increasingly taking leadership roles in wealth management, now representing 15% of private office positions worldwide.
- Common wealth management fee structures include Assets Under Management (AUM), flat fees, hourly rates, retainer fees, and commission-based fees, each with unique benefits and drawbacks.
- Families should understand their wealth management fee structure to avoid hidden costs that can erode investment returns, with transparency being crucial for trust and effective financial planning.
- Choosing the right financial advisor involves identifying needs, researching credentials, evaluating experience, and ensuring clear communication regarding fees.
- Families should request references and arrange meetings with potential advisors to ensure alignment with their financial goals and values.
Introduction
In a world where financial landscapes are increasingly complex, families find themselves facing the daunting task of managing their wealth effectively. Wealth management is not just about accumulating assets; it involves a comprehensive approach that aligns financial decisions with family values and long-term aspirations. Imagine if sound financial planning could pave the way for future security and opportunities for your children. For families with young children, the stakes are even higher, as the right strategies can create a lasting legacy.
As the market for wealth management continues to expand, it’s important to understand the nuances of various fee structures and the significance of transparency. This understanding can empower families to make informed decisions that resonate with their values. This article delves into the critical aspects of wealth management for families, exploring innovative strategies that not only ensure financial freedom but also nurture a legacy for future generations. Together, we can navigate this journey, ensuring that your family’s financial future is secure and aligned with your dreams.
Define Wealth Management and Its Importance for Families
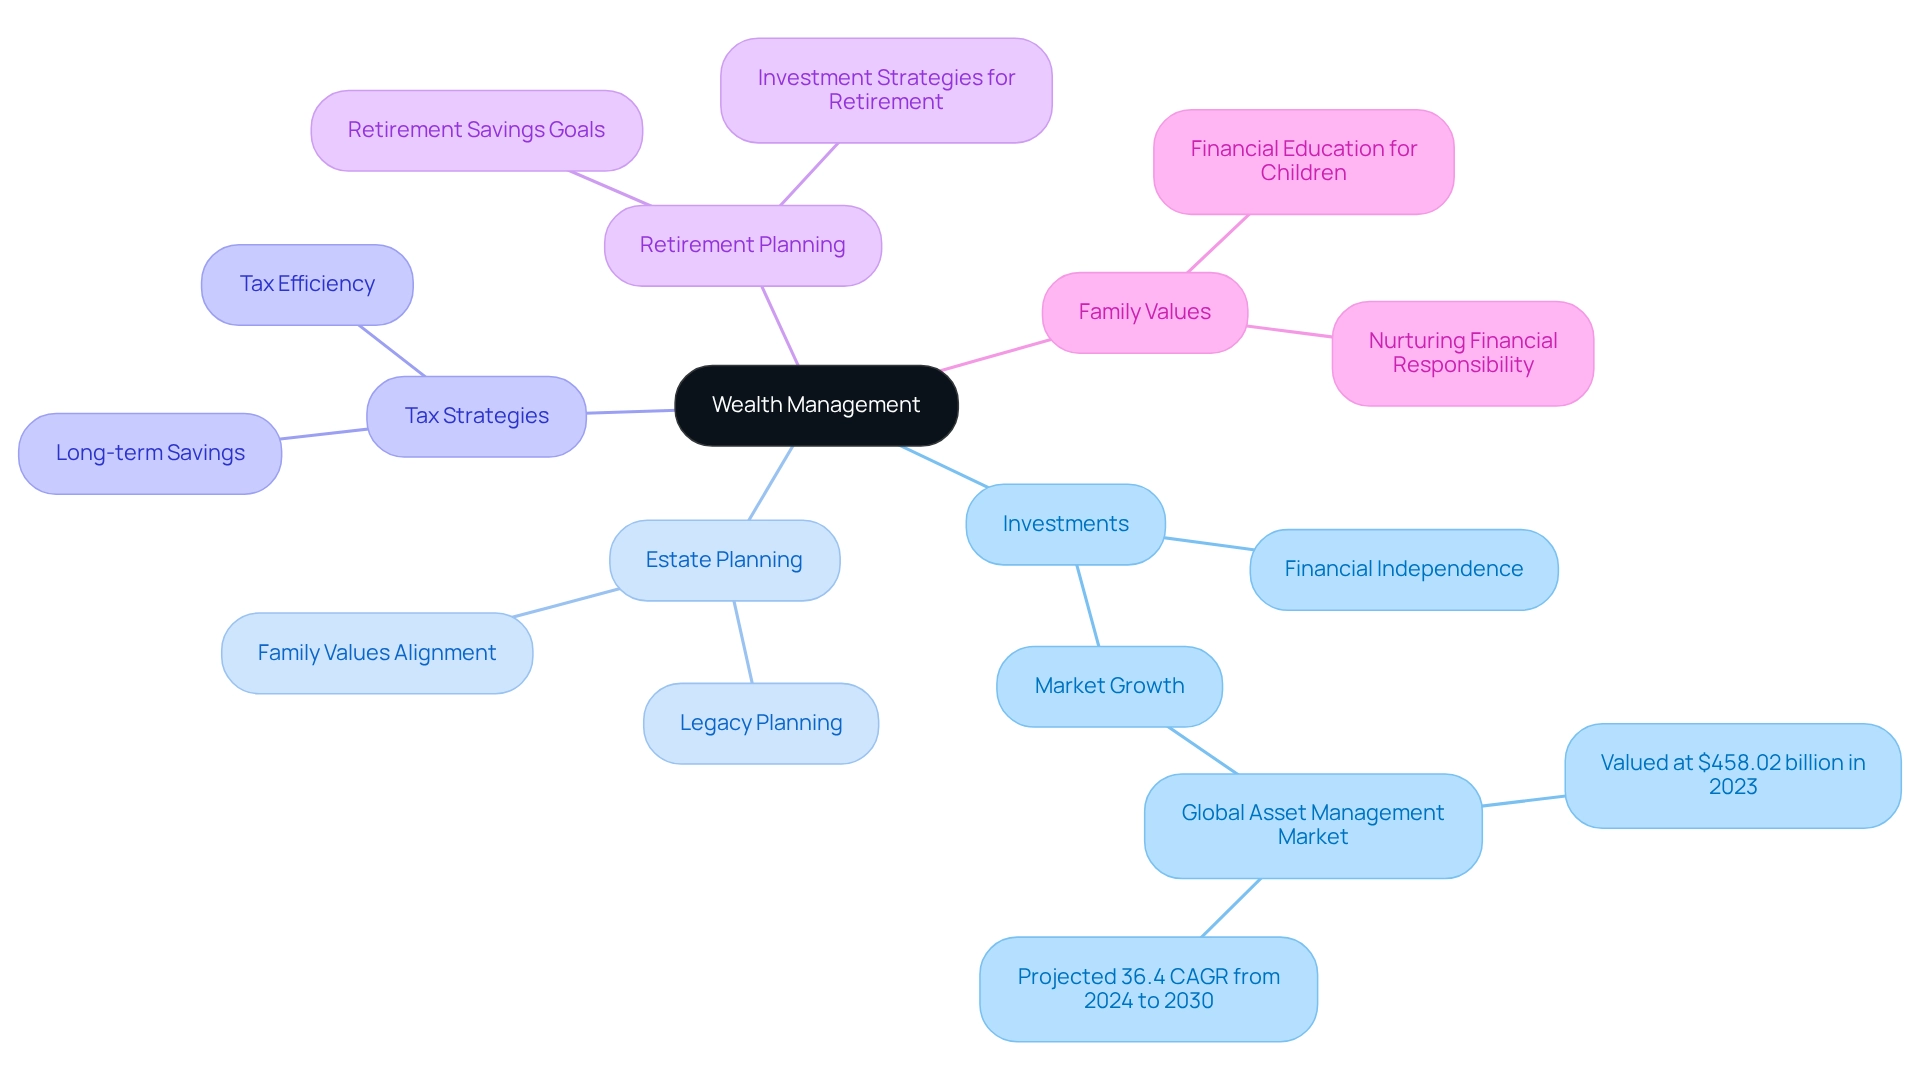
Wealth management is more than just numbers; it’s a comprehensive approach to nurturing your family’s resources. It encompasses investments, estate planning, tax strategies, and retirement planning. For families, especially those with young children, effective wealth management is vital. It not only fosters wealth accumulation but also ensures that your financial choices reflect your family’s values and long-term aspirations. By prioritizing wealth management, you can pave the way for a secure financial future, allowing you to focus on raising your children and preparing them for the financial responsibilities ahead.
At Bright Advisers, we are dedicated to empowering families with young children through personalized planning and innovative wealth management solutions. Take the journey of Emily and Mark, for example. They sought to improve their financial situation while juggling demanding careers. Our collaboration with them illustrates how tailored strategies can lead to financial independence. Their experience highlights the importance of crafting a comprehensive plan that aligns with personal goals, offering the flexibility needed for career choices and life decisions.
Did you know that the global asset management market was valued at $458.02 billion in 2023? Projections suggest a remarkable growth rate of 36.4% CAGR from 2024 to 2030. This surge reflects an increasing recognition of the importance of wealth management among families. Furthermore, a significant trend is emerging: women are stepping into leadership roles within private offices, now representing 15% of such offices worldwide. This shift indicates a growing preference for utilizing private offices for wealth management, particularly among women who often prioritize thorough financial planning.
It’s also essential to recognize that Americans’ expectations for returns are 123% higher than what advisors typically suggest. This gap in understanding the wealth management fee structure is crucial for families as they engage in wealth management. The impact of an effective wealth management fee structure on your family’s financial stability cannot be overstated. Families that commit to thorough financial planning are better equipped to navigate economic uncertainties and achieve their financial goals. By implementing sound wealth management strategies, you can ensure that your financial decisions resonate with your values, ultimately fostering a legacy of financial knowledge and accountability for generations to come.
As we approach 2025, the importance of wealth management for families with young children will only grow. It’s essential for these families to stay informed and proactive in their planning. Together, we can navigate this journey, ensuring a brighter financial future for your loved ones.
Explore Common Wealth Management Fee Structures
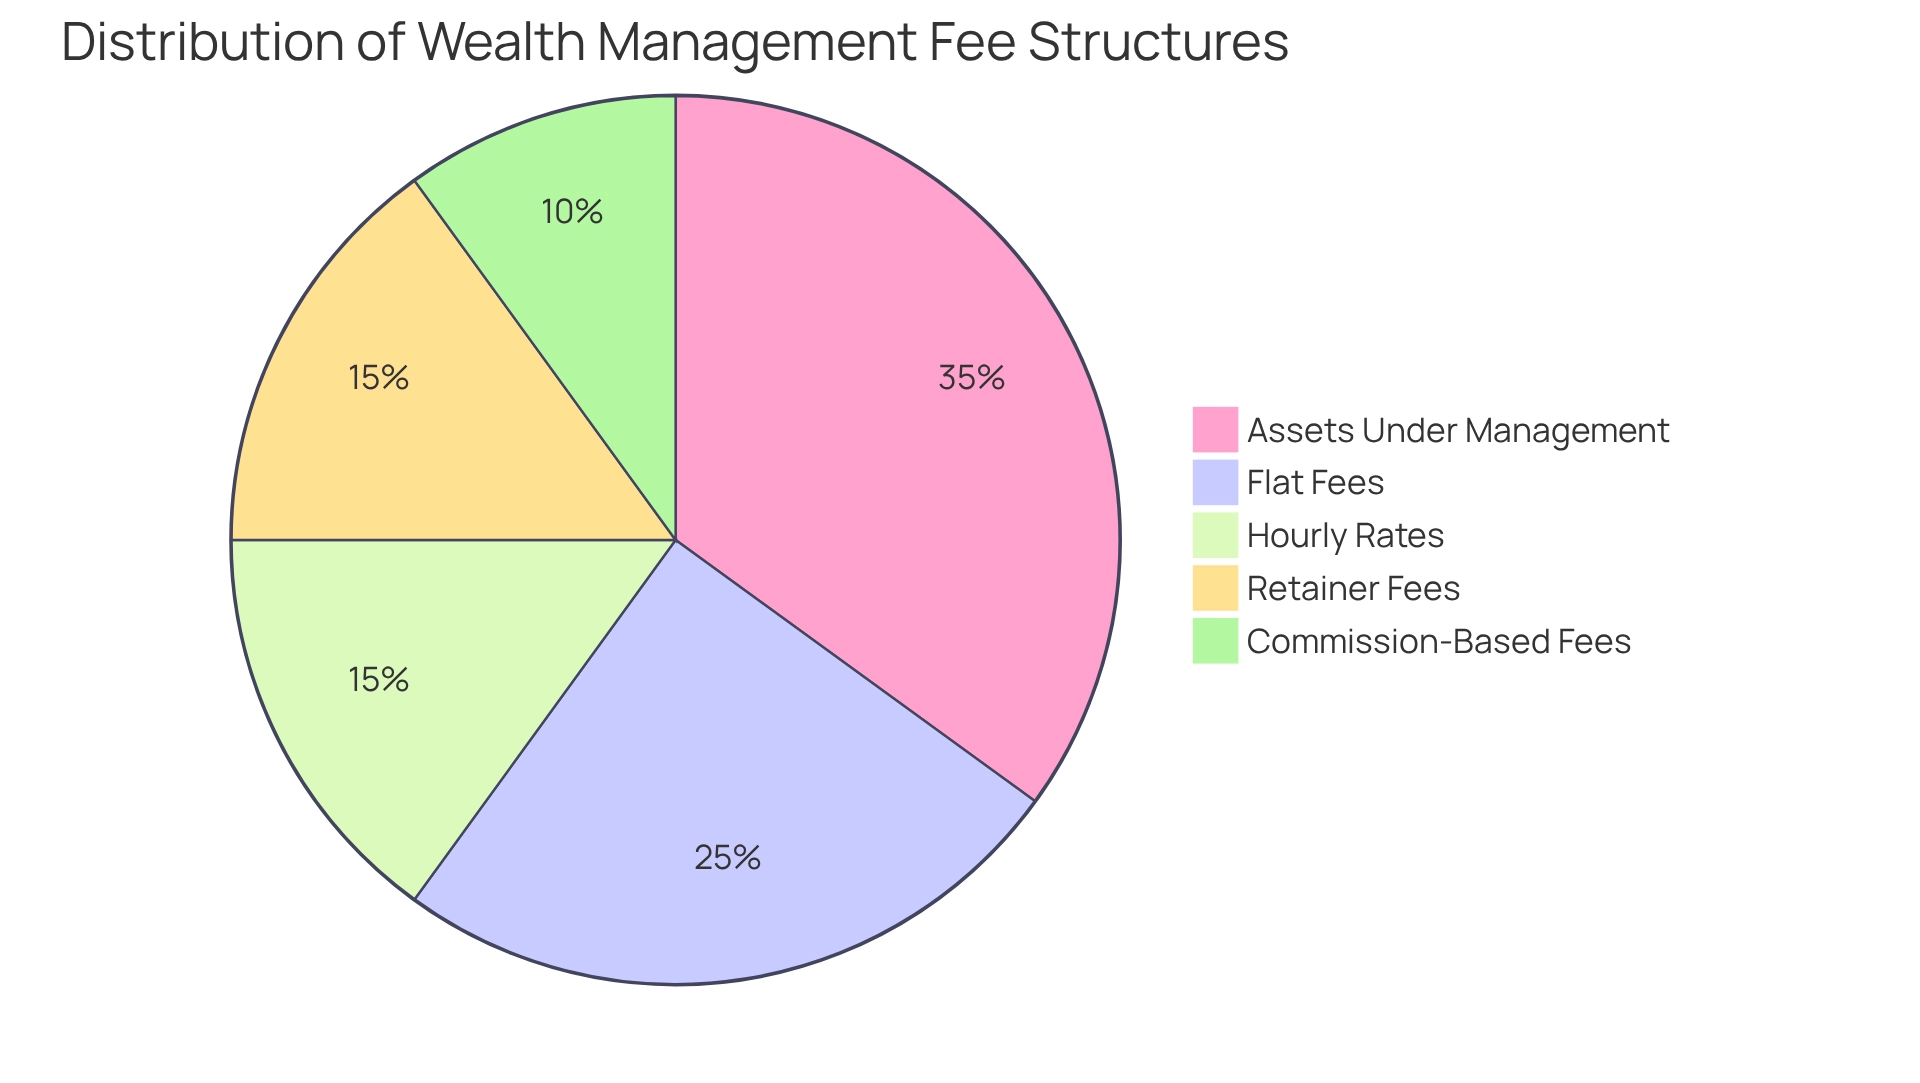
We understand that navigating wealth management can feel overwhelming, especially for young families. Common wealth management fee structures include a variety of models tailored to meet your diverse needs. Understanding these can significantly impact your financial planning decisions:
- Assets Under Management (AUM): This model typically charges between 0.25% and 2% of the total assets managed annually. It aligns the advisor’s incentives with your investment results, fostering a partnership in achieving your monetary goals.
- Flat Fees: A fixed annual fee ranging from $2,000 to $7,500, depending on the complexity of services provided. This structure provides predictability in expenses, making it simpler for your household to plan for monetary guidance.
- Hourly Rates: Advisors may charge between $200 and $400 per hour for consultations or specific services. This option is particularly beneficial for families seeking occasional guidance rather than ongoing management.
- Retainer Fees: A monthly or annual charge that provides your household ongoing access to your consultant’s expertise, ensuring you receive prompt guidance as your financial situation changes.
- Commission-Based Fees: Advisors earn commissions on the products they sell, which can introduce potential conflicts of interest. It’s important to approach this model with caution, ensuring transparency in the advisor’s recommendations.
Furthermore, mutual fund sales loads typically vary from 3% to 6% of your investment, which is a significant factor for families assessing investment products. At Bright Advisers, we are dedicated to low fund charges, which pertains to the vast majority of our models, ensuring that you can access wealth management services without high expenses. Recent trends suggest that numerous consultants utilize breakpoints in their pricing structures, where charges diminish as account sizes grow. This practice reflects the reduced effort required to manage larger portfolios, as evidenced by research showing that the median advisory fee decreases with rising assets. Understanding how breakpoints affect overall costs is crucial for families with varying portfolio sizes.
Imagine if you could navigate this journey with confidence. As Bob Veres observes, “the data indicates that consumers are less sensitive to total costs than ‘just’ the consultant’s fee,” emphasizing the significance of comprehending the complete range of fees involved. Lastly, it’s worth mentioning that Americans’ return expectations are 123% greater than the suggestions from financial consultants, which highlights the effects of fee structures on investment performance and expectations. Overall, comprehending the wealth management fee structure is essential for families aiming to navigate the intricacies of wealth management effectively. Together, we can explore innovative strategies that leverage advanced technology for hyper-personalized investment portfolios. We’re here for you, every step of the way.
Evaluate the Advantages and Disadvantages of Each Fee Structure
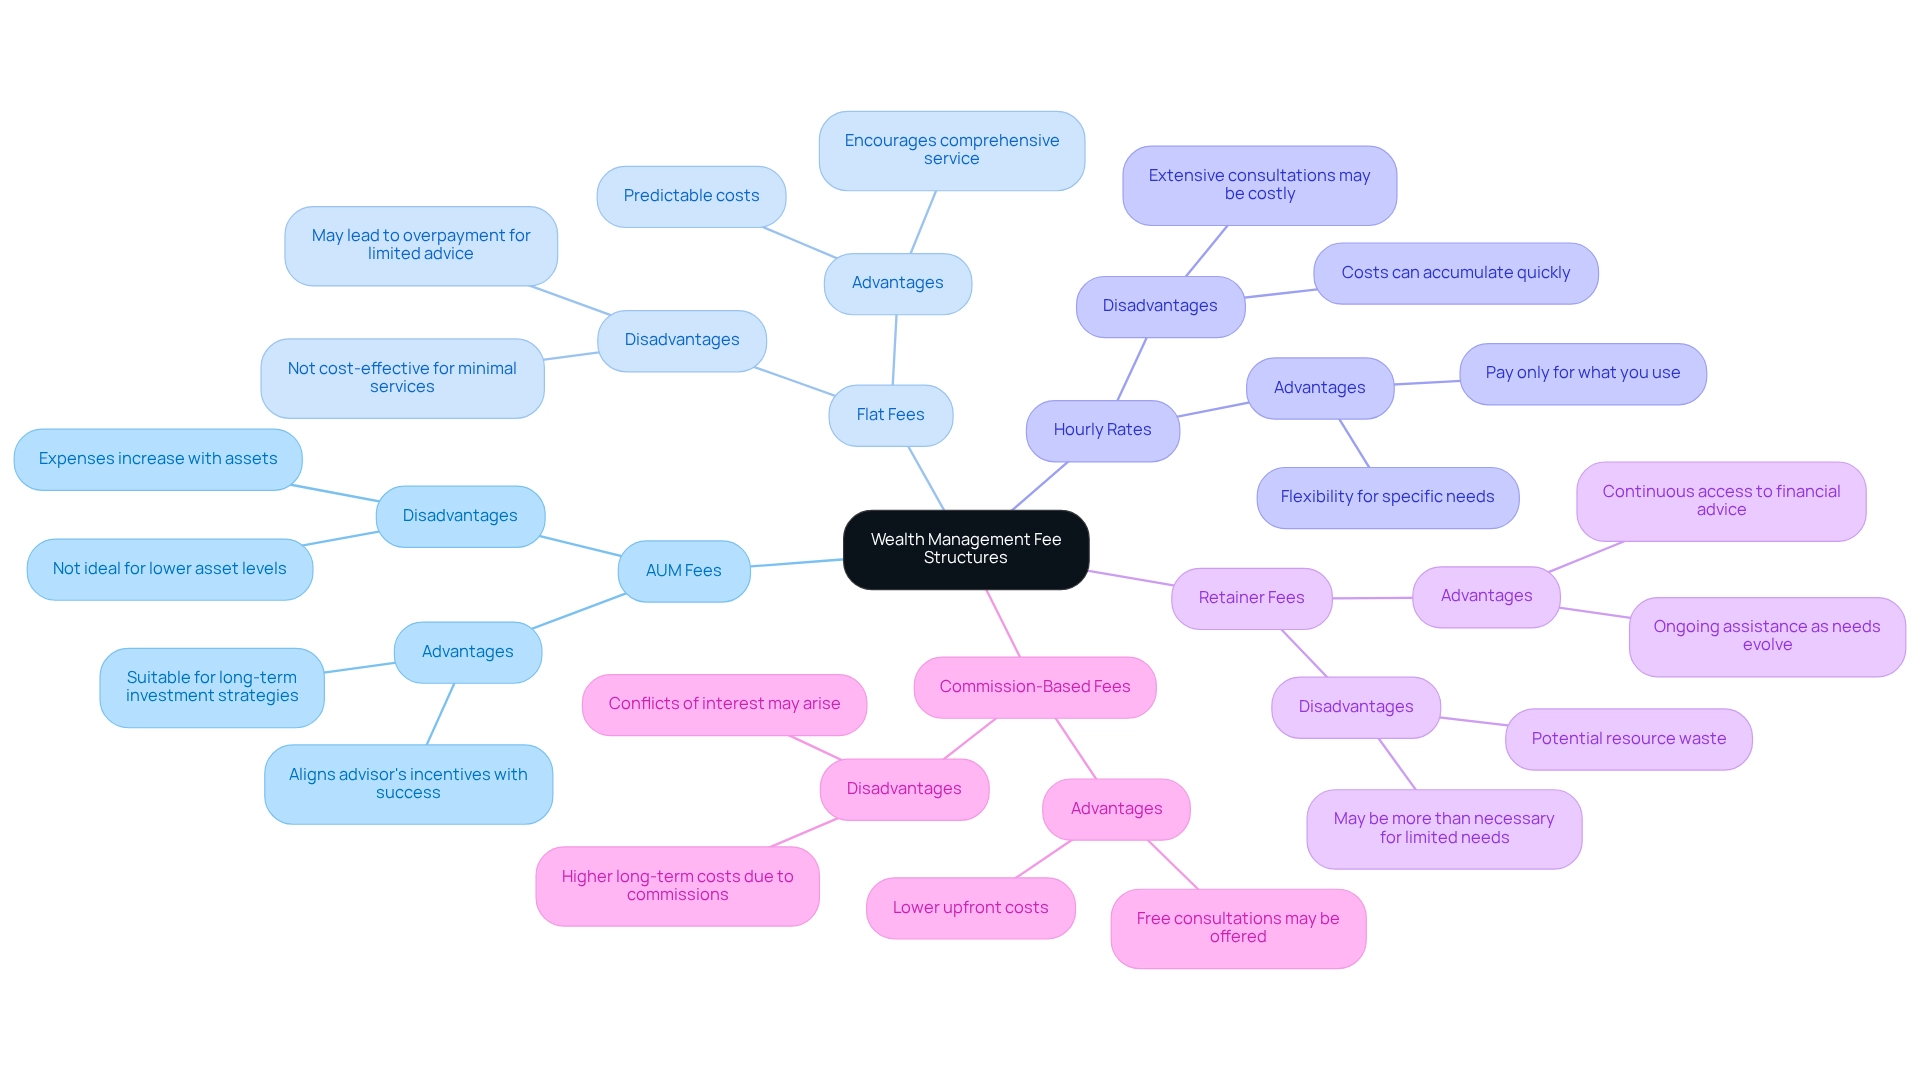
Navigating the world of financial planning can feel overwhelming, especially for families striving to secure a bright future. Each wealth management fee structure presents unique advantages and disadvantages that families should thoughtfully consider, particularly in light of Bright Advisers’ commitment to minimal fund fees, which enhances accessibility to wealth management services for families.
AUM Fees:
Imagine aligning your advisor’s incentives with your success. This structure is particularly suitable for long-term investment strategies, making it a great fit for households aiming to grow their wealth over time. However, as assets increase, so do expenses, which may not be ideal for families with lower asset levels—an income segment that has often been underserved by planners charging fees based on assets under management.
Flat Fees:
Picture a world where your costs are predictable. This approach encourages comprehensive service without hidden fees, allowing families to budget more effectively. Bright Advisers exemplifies this by providing a clear wealth management fee structure that enables households to plan with confidence. Yet, for those requiring minimal services, it may not be the most cost-effective option, potentially leading to overpayment for limited advice.
Hourly Rates:
Think about paying only for what you use. This model offers flexibility for families with specific needs and can be especially appealing for those wishing to manage costs while receiving targeted advice. On the flip side, expenses can accumulate quickly if extensive consultations are necessary, which might catch some families off guard.
Retainer Fees:
Imagine having continuous access to financial advice. This structure is beneficial for families with ongoing financial needs, ensuring a lasting connection with their consultant. Bright Advisers’ method allows households to receive ongoing assistance as their financial circumstances evolve. However, it may be more than what is necessary for families with limited needs, leading to potential resource waste.
Commission-Based Fees:
Consider the possibility of lower upfront costs. Often, advisors may offer free consultations under this model. Yet, it can create conflicts of interest, potentially resulting in higher long-term costs due to commissions on products sold, which may not align with the best interests of your household.
As Brandon Heid, a Practice Management Consultant, wisely notes, “There is no single fee structure that will work best in all situations.” This insight underscores the importance of understanding the nuances of the wealth management fee structure. Furthermore, the distinction between investment consultants and wealth managers, as highlighted in the case study ‘Understanding Wealth Management Roles,’ emphasizes the necessity for families to choose wealth managers like Bright Advisers who can effectively meet their unique monetary needs and complexities.
Together, we can navigate this journey, ensuring that your family’s financial future is secure and well-planned.
Understand the Role of Transparency in Wealth Management Fees
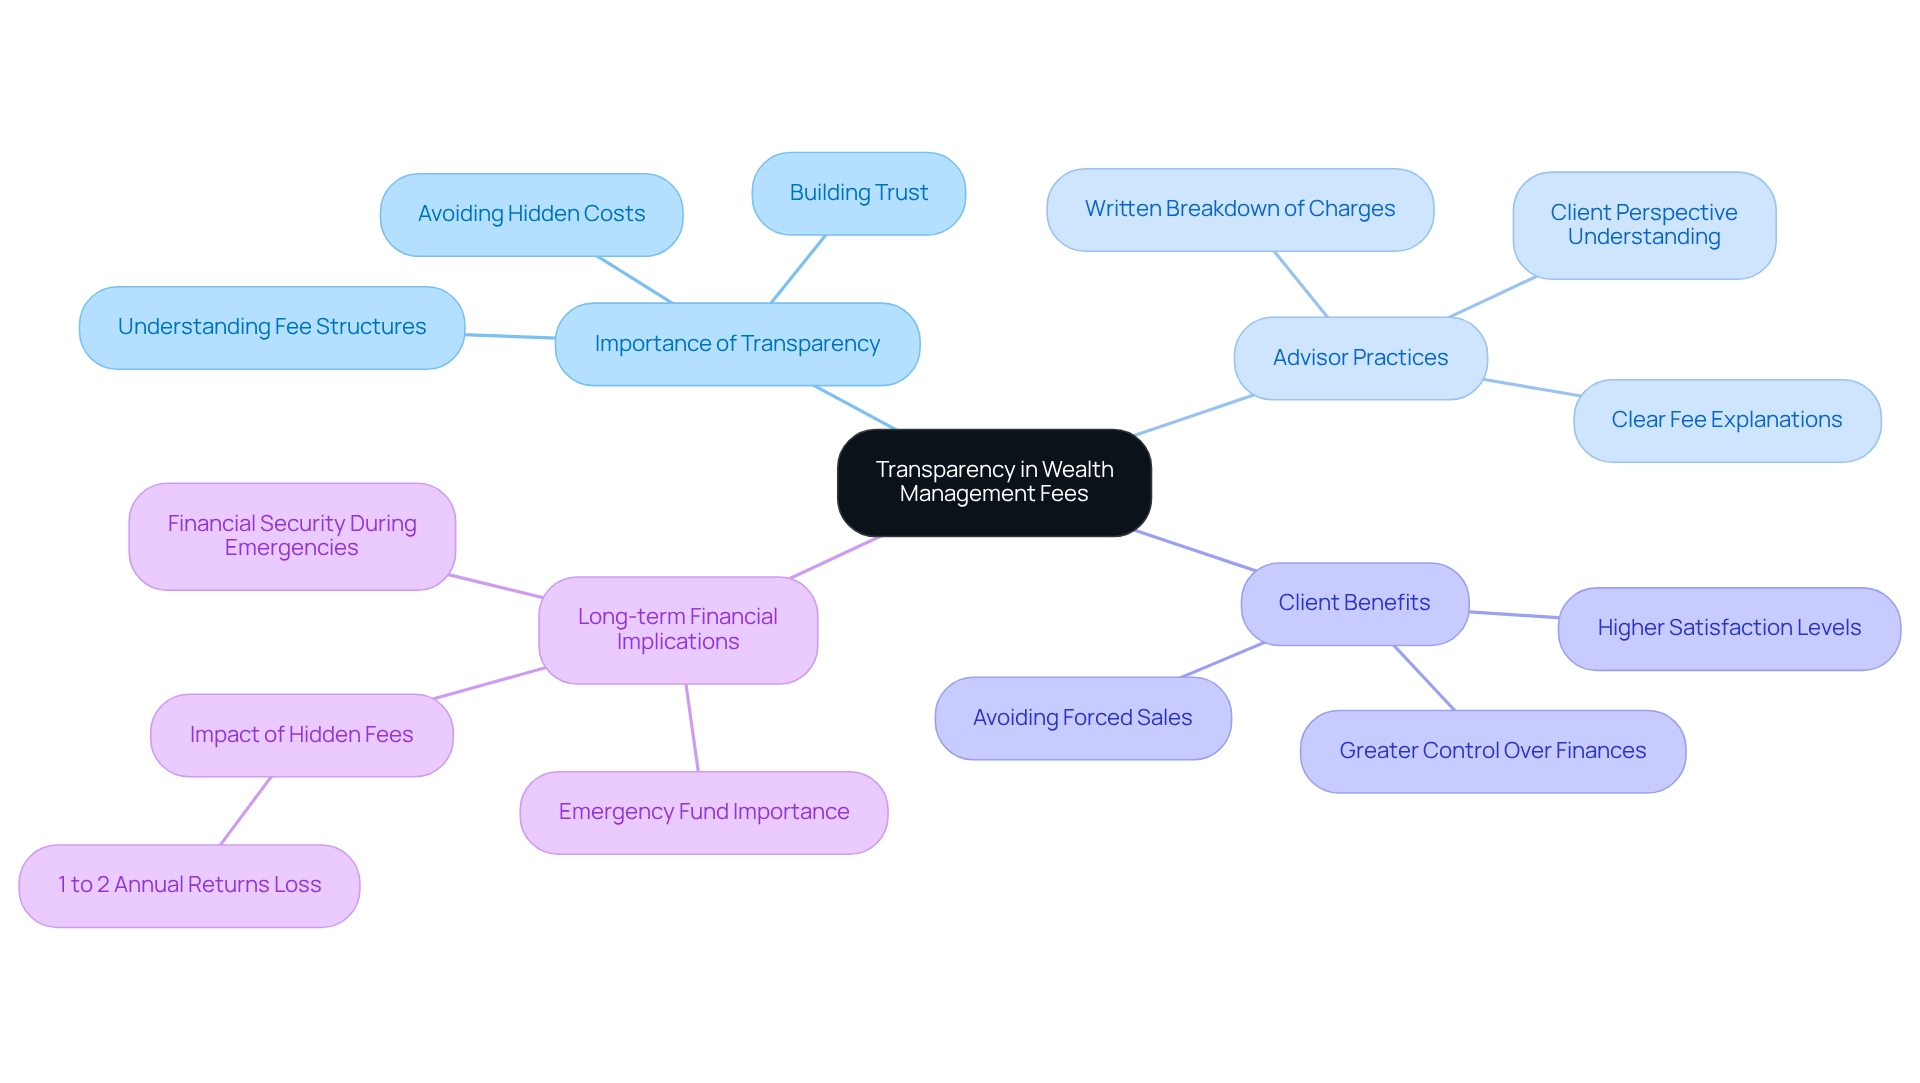
Understanding the wealth management fee structure is essential for families to comprehend their responsibilities and the benefits they receive from advisory services. Advisors should offer clear explanations of their wealth management fee structure, including any potential extra costs, to foster trust and empower families to make informed financial choices. It’s important for families to ask for a detailed, written breakdown of charges, clarifying the services included. This commitment to transparency not only strengthens the advisor-client relationship but also helps families avoid hidden expenses that can significantly impact their investment returns.
Bright Advisers exemplifies this commitment to openness by prioritizing low fund charges, ensuring that families can access wealth management services without overwhelming financial burdens. Research indicates that many investors remain unaware of the hidden fees associated with advisory services, which can erode returns over time. For example, studies have shown that these concealed charges can account for as much as 1% to 2% of annual returns, highlighting the critical need for clarity in the wealth management fee structure. Case studies further reveal the positive impact of transparent fee practices; families who partnered with advisors like Bright Advisers, who emphasize fee transparency, reported higher satisfaction levels and a greater sense of control over their financial futures.
Additionally, maintaining an emergency fund is vital, as it allows families to meet financial obligations without having to liquidate investments, thereby ensuring stability during challenging times. As we approach 2025, the emphasis on transparency in the wealth management fee structure is more crucial than ever, as families navigate increasingly complex financial landscapes. Advisors should actively seek to understand their clients’ perspectives on charges, ensuring they perceive the costs as fair relative to the services provided. As Michael emphasizes, understanding clients’ viewpoints is key when they inquire about expenses, as it helps advisors address concerns effectively. By fostering a culture of transparency, advisors can deepen their connections with clients, ultimately leading to better financial outcomes and a more secure future for families. Remember Warren Buffett’s wise words: “If you don’t find a way to make money while you sleep, you will work until you die,” underscoring the importance of understanding fees in relation to long-term financial well-being.
Guide to Choosing the Right Financial Advisor for Your Family
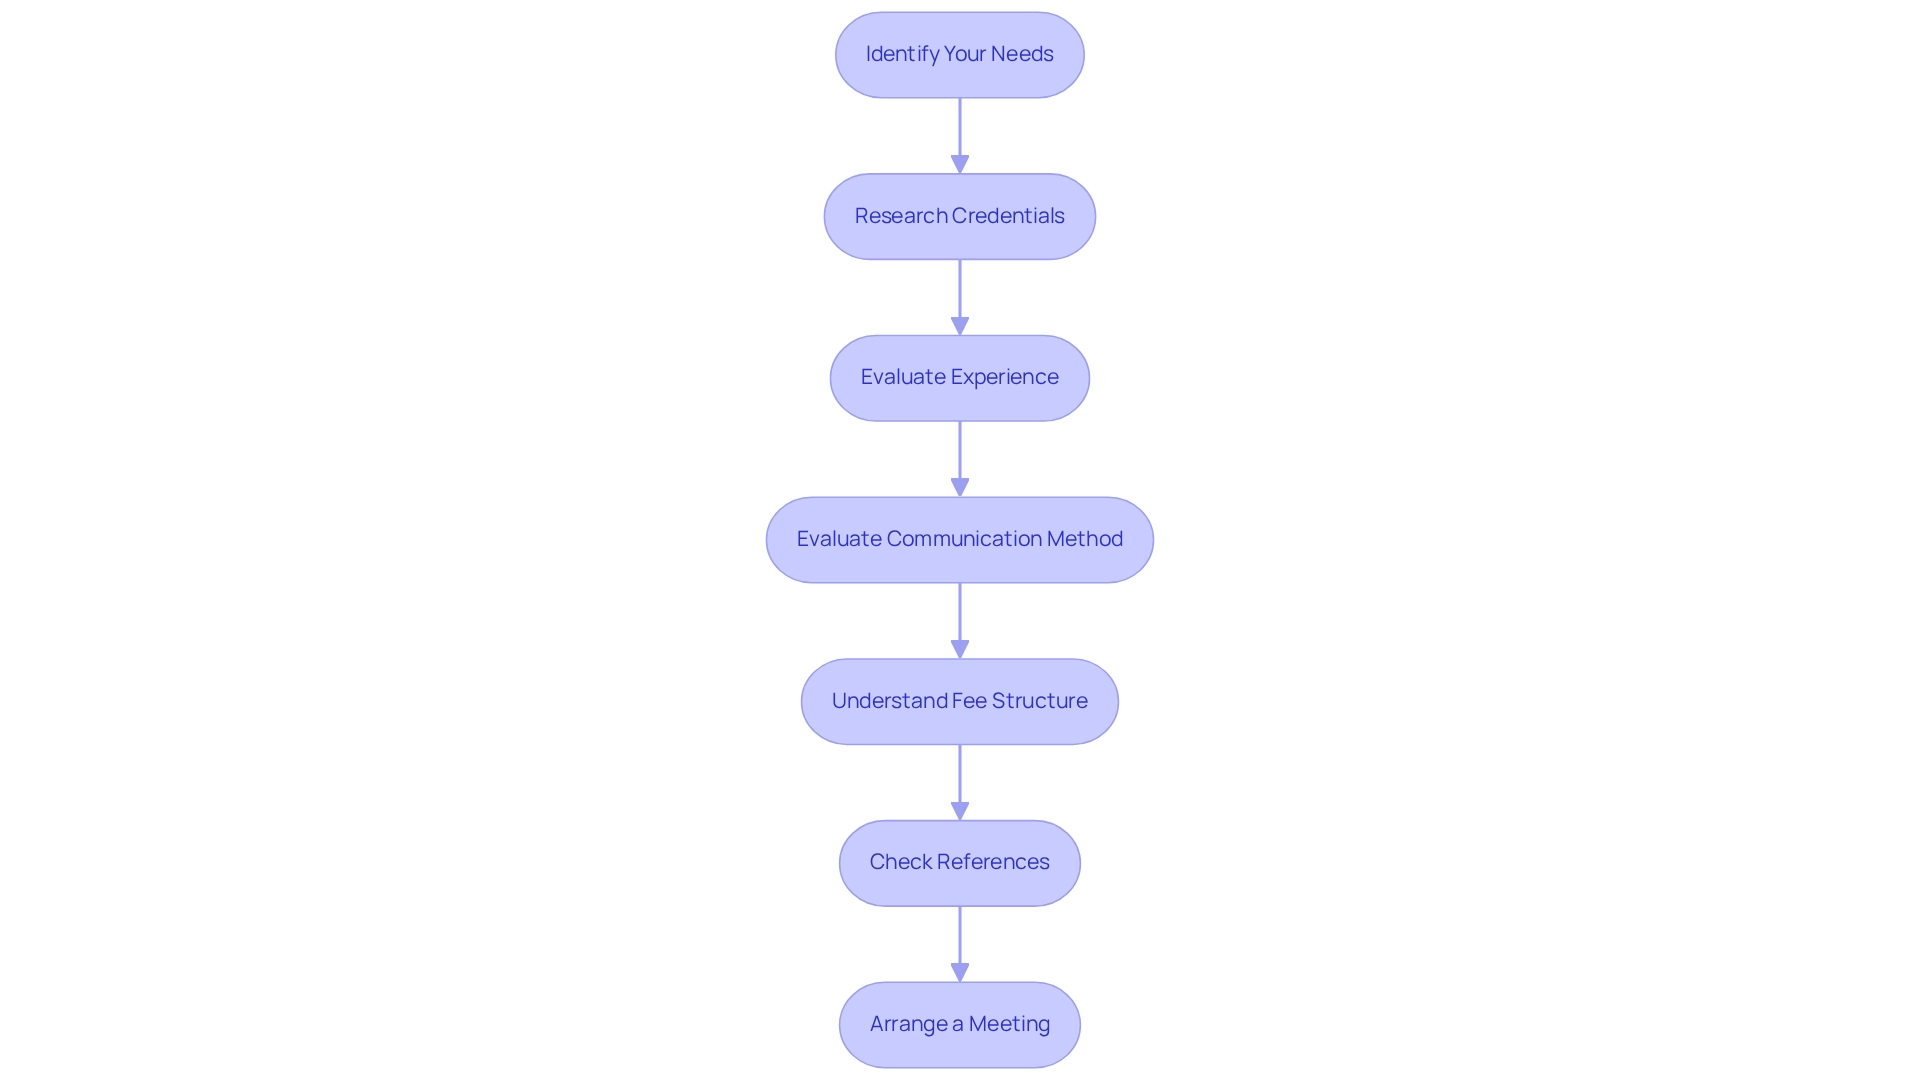
Choosing the right financial consultant is crucial for families eager to secure their financial future. Here are some essential steps to guide your decision-making process:
-
Identify Your Needs: Begin by pinpointing the specific services you require, such as investment management, estate planning, or tax advice. Understanding your priorities will help you narrow down your options.
-
Research Credentials: Look for consultants with recognized certifications, like Certified Financial Planner (CFP) or Chartered Financial Analyst (CFA). These credentials are important indicators of a consultant’s expertise and commitment to ethical standards.
-
Evaluate Experience: Select a consultant with a proven track record of working with families, especially those with young children. Their familiarity with your unique challenges can significantly enhance the advisory relationship. Imagine if you could work with someone who truly understands the dynamics of managing money during pivotal life events like marriage or inheritance. For instance, Emily and Mark, a couple in their mid-thirties, partnered with Bright Advisers to develop a comprehensive financial strategy that aligned with their values and goals, ultimately achieving financial independence and flexibility in their careers.
-
Evaluate Communication Method: Ensure that the consultant communicates clearly and is willing to simplify complex financial concepts into understandable terms. Effective communication fosters trust and collaboration.
-
Understand the wealth management fee structure by discussing and clarifying the consultant’s fee arrangement upfront. Bright Advisers provides a wealth management fee structure that is transparent and aligns with your budget and expectations, ensuring you understand the costs associated with their services. It’s noteworthy that the financial consulting landscape is evolving, with families increasingly selecting consultants who provide a transparent wealth management fee structure and competitive arrangements. By 2025, robo-advisors are projected to manage around $16 trillion in assets, underscoring the importance of understanding the different types of advisors available.
-
Check References: Request testimonials or references from other families. This feedback can provide valuable insights into the consultant’s effectiveness and reliability. Bright Advisers has received positive reviews from clients like Emily and Mark, who appreciated the tailored strategies that helped them achieve their objectives.
-
Arrange a Meeting: Finally, meet with potential consultants to discuss your financial goals. This interaction will allow you to assess their approach to wealth management and determine if it aligns with your family’s values and aspirations. Remember, a significant percentage of clients would consider changing advisors if estate planning services were available, highlighting the importance of this service in your selection process.
By following these steps, families can make informed decisions when choosing a financial advisor, ensuring they find a partner who understands their unique needs and can help them navigate the complexities of financial planning. If you’re interested in working with Bright Advisers, we invite you to join our waitlist as we are currently at capacity. We will reach out to you as soon as we have availability.
Conclusion
Wealth management plays a vital role in securing your family’s financial future, especially when young children are involved. A thoughtful approach to wealth management weaves together essential elements like investments, estate planning, tax strategies, and retirement planning, all while reflecting your family values and long-term dreams. By focusing on effective financial planning, you can create a legacy that empowers future generations, enabling them to face life’s financial responsibilities with confidence.
Understanding the various fee structures tied to wealth management is crucial for families looking to make informed financial choices. Whether it’s assets under management, flat fees, hourly rates, or commission-based fees, each model comes with its own set of advantages and disadvantages. It’s important for families to carefully assess these options, ensuring they select a fee structure that suits their financial needs while valuing transparency in these relationships. Clarity around fees can significantly build trust and satisfaction with financial advisors, ultimately leading to improved financial outcomes.
Choosing the right financial advisor is a pivotal step in your wealth management journey. By identifying your specific needs, researching credentials, evaluating experience, and ensuring open communication, you can find an advisor who not only understands your unique challenges but also aligns with your values. In an ever-evolving financial landscape, making informed choices about financial advisors and fee structures becomes increasingly important as families strive for financial security and freedom.
As you navigate the complexities of wealth management, remember that staying informed and proactive empowers you to make decisions that secure your financial future and nurture a lasting legacy for generations to come. We’re here for you, ready to support you on this journey together.
Frequently Asked Questions
What is wealth management?
Wealth management is a comprehensive approach to managing a family’s resources, including investments, estate planning, tax strategies, and retirement planning. It aims to align financial choices with the family’s values and long-term aspirations.
Why is wealth management important for families with young children?
Effective wealth management is vital for families with young children as it fosters wealth accumulation and ensures that financial decisions reflect the family’s values. It helps pave the way for a secure financial future, allowing parents to focus on raising their children and preparing them for financial responsibilities.
What services does Bright Advisers offer for families?
Bright Advisers provides personalized planning and innovative wealth management solutions tailored to empower families with young children, helping them improve their financial situations while managing demanding careers.
What is the current state of the global asset management market?
The global asset management market was valued at $458.02 billion in 2023, with projections suggesting a growth rate of 36.4% CAGR from 2024 to 2030, indicating a rising importance of wealth management among families.
What trend is emerging in wealth management leadership?
A significant trend is that women are increasingly stepping into leadership roles within private offices, now representing 15% of such offices worldwide, reflecting a growing preference for thorough financial planning among women.
What is the gap between Americans’ return expectations and advisors’ suggestions?
Americans’ expectations for returns are 123% higher than what financial advisors typically suggest, which highlights the importance of understanding the wealth management fee structure.
What are common wealth management fee structures?
Common fee structures include: – Assets Under Management (AUM): Charges between 0.25% and 2% of total assets managed annually. – Flat Fees: Fixed annual fees ranging from $2,000 to $7,500. – Hourly Rates: Charges between $200 and $400 per hour for consultations. – Retainer Fees: Monthly or annual charges for ongoing access to advisor expertise. – Commission-Based Fees: Earnings from product sales, which may present conflicts of interest.
How do mutual fund sales loads affect families?
Mutual fund sales loads typically range from 3% to 6% of the investment, which is significant for families assessing investment products. Understanding these costs is crucial for effective financial planning.
What are breakpoints in pricing structures?
Breakpoints refer to pricing structures where fees decrease as account sizes grow, reflecting the reduced effort required to manage larger portfolios. Understanding how breakpoints affect overall costs is important for families with varying portfolio sizes.
How can families navigate wealth management confidently?
Families can navigate wealth management confidently by understanding the complete range of fees involved and leveraging advanced technology for personalized investment portfolios. Bright Advisers offers support throughout this process.
List of Sources
- Define Wealth Management and Its Importance for Families
- The Most Important Wealth Management Statistics To Know (https://passivesecrets.com/wealth-management-statistics)
- Deloitte Private’s latest report in its Family Office Insights Series – Global Edition explores the rapid expansion of family offices and offers a vision of the future landscape (https://deloitte.com/global/en/about/press-room/global-edition-explores-the-rapid-expansion-family-offices-and-ffers-vision-of-the-future-landscape.html)
- Explore Common Wealth Management Fee Structures
- How Much Does a Financial Advisor Cost in 2025? – NerdWallet (https://nerdwallet.com/article/investing/how-much-does-a-financial-advisor-cost)
- Independent Financial Advisor Fee Comparison: All-In Costs (https://kitces.com/blog/independent-financial-advisor-fees-comparison-typical-aum-wealth-management-fee)
- The Most Important Wealth Management Statistics To Know (https://passivesecrets.com/wealth-management-statistics)
- Evaluate the Advantages and Disadvantages of Each Fee Structure
- Wealth Management Fees Comparison: Subscription, Retainer, and More (https://emoneyadvisor.com/blog/pros-and-cons-of-popular-financial-planning-fee-structures)
- Wealth Management Fees for High-Net-Worth Individuals (https://longangle.com/blog/wealth-management-fees)
- Understand the Role of Transparency in Wealth Management Fees
- 90 Warren Buffett Quotes on Investing, Business, and Life (https://sarwa.co/blog/warren-buffett-quotes)
- Discussing Fees And The Value Of Financial Planning (https://kitces.com/blog/fees-value-financial-advice-client-communication-cost-anchoring)
- Guide to Choosing the Right Financial Advisor for Your Family
- Wealth Management Statistics – Facts, Tips & Basics (https://plancorp.com/blog/wealth-management-statistics-facts-tips-basics)
- 20+ Financial Advisor Statistics You Must Know in ([currentyear]) (https://upmetrics.co/blog/financial-advisor-statistics)
- 30+ Financial Advisor Statistics (https://bizplanr.ai/blog/financial-advisor-statistics)
- Estate Planning Financial Advisor Statistics & Facts | Trust & Will (https://trustandwill.com/learn/financial-advisor-estate-planning-statistics-and-facts)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading