

Key Highlights
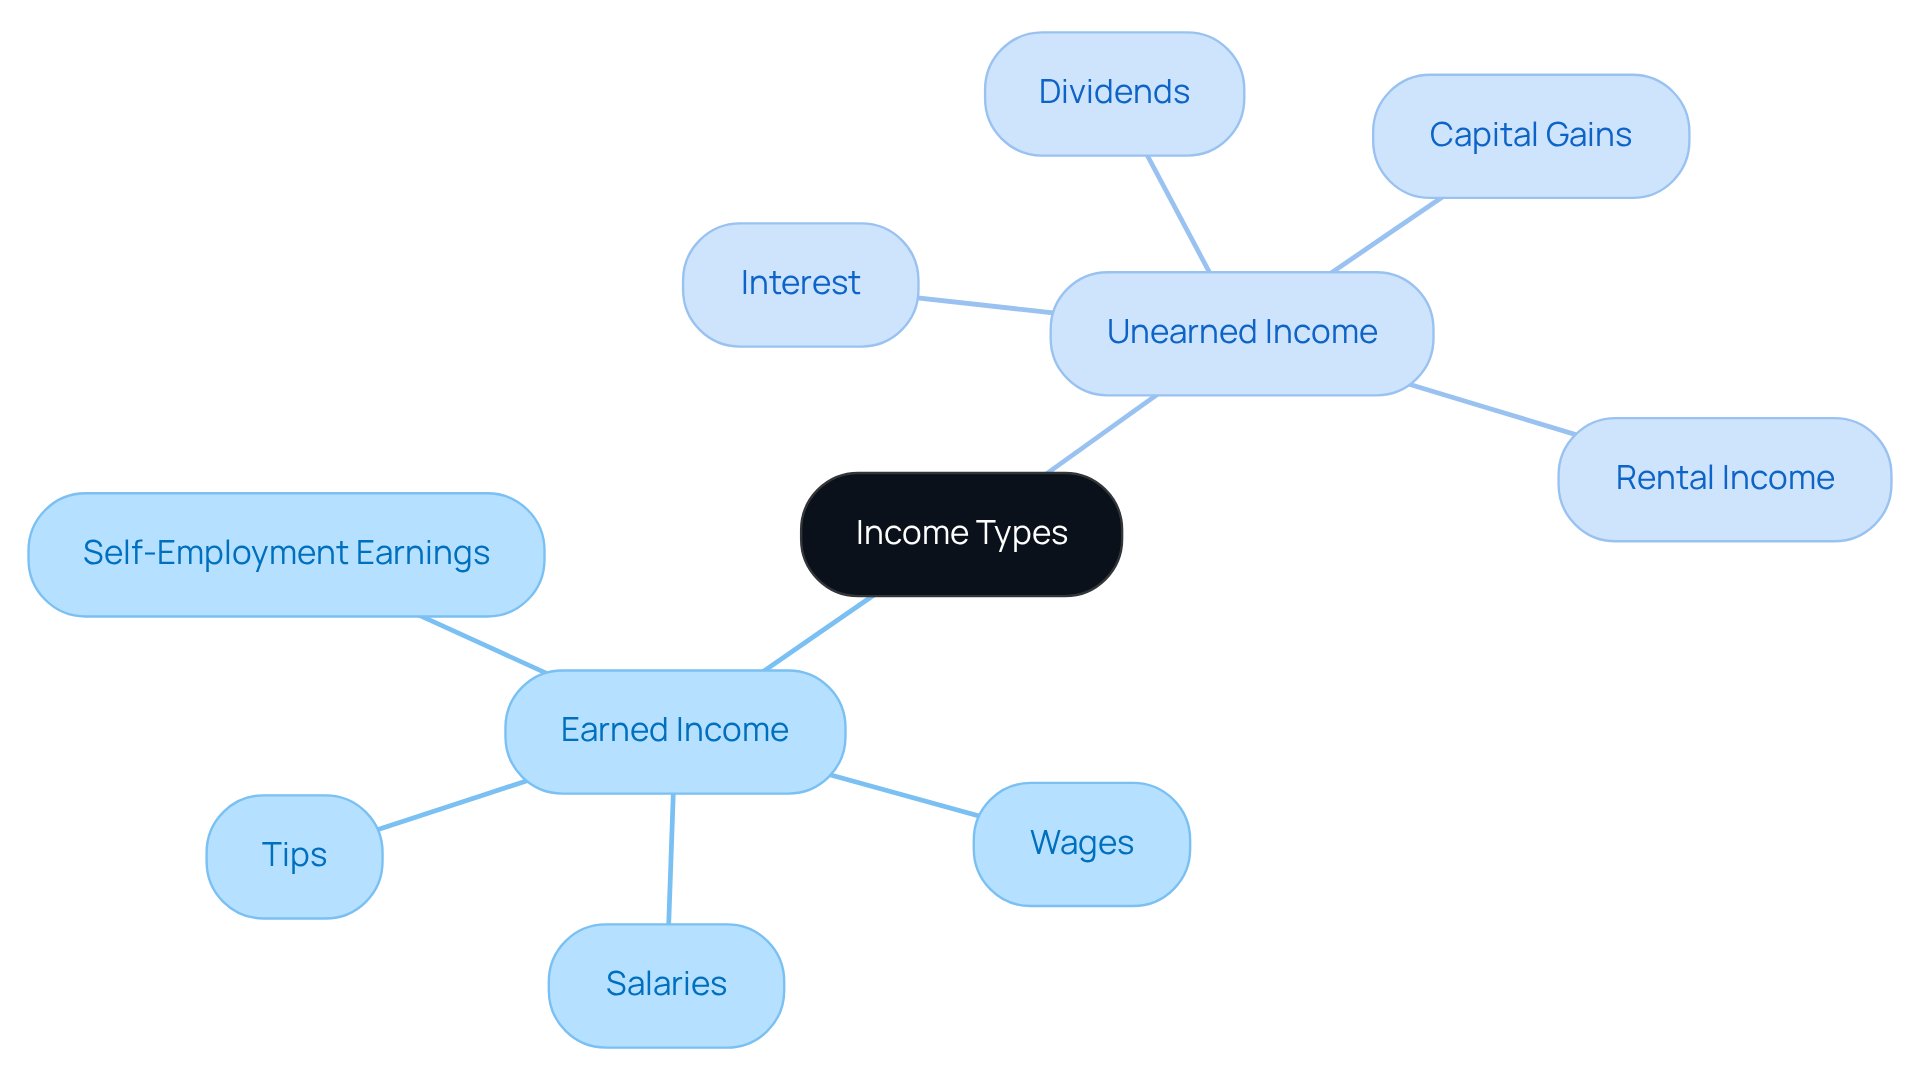
- Earned income includes wages, salaries, tips, and self-employment earnings, while unearned income comes from passive sources like interest, dividends, and capital gains.
- Understanding the differences between earned and unearned income is crucial for families in budgeting and planning for children’s future needs.
- The Earned Income Tax Credit (EITC) provides financial support to families, encouraging employment and highlighting tax treatment differences.
- Children’s unearned income exceeding $2,700 triggers the Kiddie Tax, affecting parents’ tax situations as their child’s income increases.
- Families can report a child’s unearned income on their tax return if it is below $13,500, but must be aware of tax consequences as it grows.
- Types of unearned income include interest from savings, dividends from stocks, capital gains from asset sales, rental income, and gifts or inheritances.
- Effective tax planning can help families maximise financial potential and secure their children’s future, as demonstrated by case studies of families working with Bright Advisers.
- Families must comply with IRS reporting requirements for unearned income, including using Form 8615 for Kiddie Tax calculations.
- Consulting a tax advisor can help families navigate tax regulations and optimise strategies for managing unearned income.
Introduction
Many families feel lost when trying to understand their finances, especially regarding income types and tax implications. Navigating the financial landscape can be overwhelming, but it doesn’t have to be. Imagine discovering how unearned income can open doors for your family’s financial future. While earned income is straightforward, unearned income presents unique opportunities that can enhance your financial well-being. It’s not taxable, which means it can be a valuable resource for budgeting and long-term planning.
As you explore the various forms of unearned income, it’s important to understand the potential benefits it offers. However, many families grapple with the complexities of tax regulations and reporting requirements. But what if you could turn this confusion into clarity and opportunity? Together, we can navigate this journey and make the most of your family’s financial opportunities.
Define Earned and Unearned Income
Imagine trying to balance your family’s needs while navigating the complexities of income types and taxes. Earned revenue is the money you earn through your hard work – think wages, salaries, tips, and even self-employment earnings that help support your family. On the other hand, since unearned income is not taxable, it comes from sources that don’t require active work, like interest, dividends, capital gains, and rental income – money that can help you save for your children’s future.
Understanding these differences is crucial for families, especially when it comes to budgeting and planning for your children’s future needs. For instance, imagine this: by 2026, the Earned Income Tax Credit (EITC) will have offered vital financial support to millions of families, helping them make ends meet. This program encourages employment while highlighting the differences in tax treatment between earned and unearned revenue.
If a child’s unearned income exceeds $2,700, it can trigger the Kiddie Tax, meaning parents need to be aware of how this affects their overall tax situation as their child’s income increases. While parents can report a child’s interest, dividends, and capital gains on their own return if the total is below $13,500, they must stay mindful of the tax consequences as their child’s income grows.
At Bright Advisers, we understand the unique challenges families encounter in navigating these economic waters. For example, Jay and Emma, a pair with two kids, sought our advice to lessen their monetary stress and efficiently distribute their resources. Through personalized planning, they optimized their tax situation and developed a customized retirement plan, ensuring they could fund their children’s education while also planning for their future.
Likewise, Emily and Mark, both driven professionals, collaborated with Bright Advisers to develop a strategy that granted them the freedom to decide whether or not to keep working. By implementing strategies to manage cash flow and invest wisely, they gained the flexibility to make career decisions based on their desired work-life balance.
In summary, while earned revenue is straightforward in terms of taxation, families face unique challenges and opportunities because unearned income is not taxable. With the right guidance, you can turn these challenges into opportunities for your family’s financial well-being.
Explore Types of Unearned Income
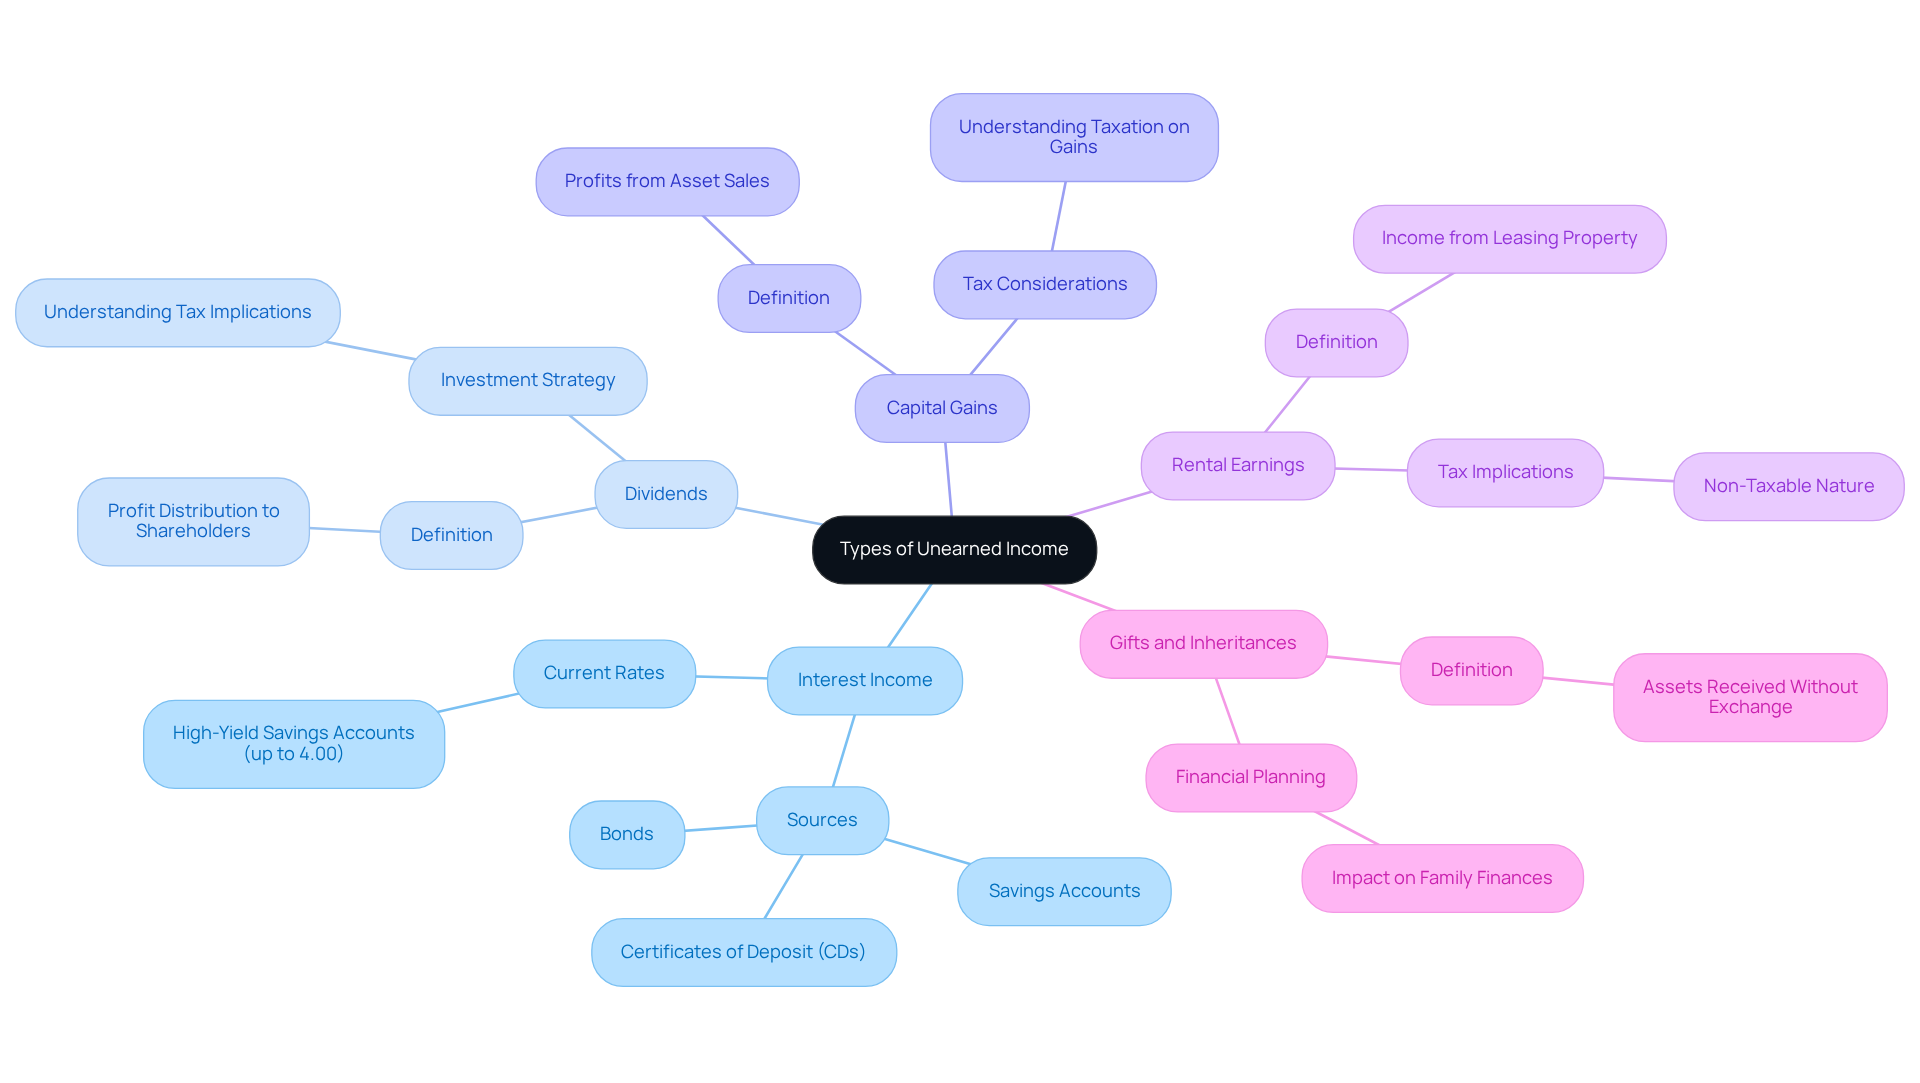
Imagine navigating the complexities of household finances without a clear understanding that unearned income is not taxable. Since unearned income is not taxable, it encompasses various types of passive revenue that can greatly impact your family’s finances and tax strategies. Here are the primary types of unearned income:
- Interest Income: This includes earnings from savings accounts, certificates of deposit (CDs), and bonds. As of July 2026, high-yield savings accounts can provide interest rates up to 4.00%, making them an appealing choice for families looking to grow their savings with minimal risk.
- Dividends: Corporations distribute profits to shareholders in the form of dividends. For families aiming to optimize their investment strategies, it is crucial to understand that unearned income is not taxable.
- Capital Gains: Profits from selling assets, such as stocks or real estate, that have appreciated in value fall under this category. Families should be aware that since unearned income is not taxable, it is important to understand how capital gains are taxed to make informed decisions about asset sales.
- Rental Earnings: Profits generated from leasing property to tenants can provide a steady revenue stream. Families should consider that unearned income is not taxable when assessing the tax obligations associated with this type of earnings.
- Gifts and Inheritances: Money or assets received without any exchange of services can also be classified as unearned revenue. Understanding that unearned income is not taxable is crucial for effective monetary planning regarding these gifts.
Understanding that unearned income is not taxable is vital for families. The fact that unearned income is not taxable can significantly impact how they budget and manage taxes. For example, the typical savings account balance for the highest earnings category is roughly 47 times greater than that of the lowest earnings category, emphasizing the significance of strategic money management. With this knowledge, families can confidently navigate their financial journey and find peace of mind. By understanding how dividends and capital gains are taxed, households can make informed investment choices, knowing that unearned income is not taxable, which aligns with their long-term monetary objectives. Moreover, case studies indicate that families who actively participate in economic literacy and planning are better equipped to manage the intricacies of unearned income, which is not taxable, ultimately resulting in enhanced economic security.
Take Allison and Brian, for instance. They’re a couple in their late 40s who learned the hard way about the importance of tax planning. Despite their remarkable earnings as a medical device sales representative and a restaurant owner, they were oblivious to the monetary opportunities they were overlooking because of insufficient tax planning. With the guidance of Bright Advisers, they optimized their tax situation through integrated tax planning and tax-loss harvesting strategies, secured their children’s future through education funding, and gained the ability to retire sooner. Their success story emphasizes how effective tax planning can enable families to maximize their financial potential and attain peace of mind. With the right knowledge and support, families can transform their financial landscape and secure a brighter future.
Understand Tax Treatment and Reporting of Unearned Income
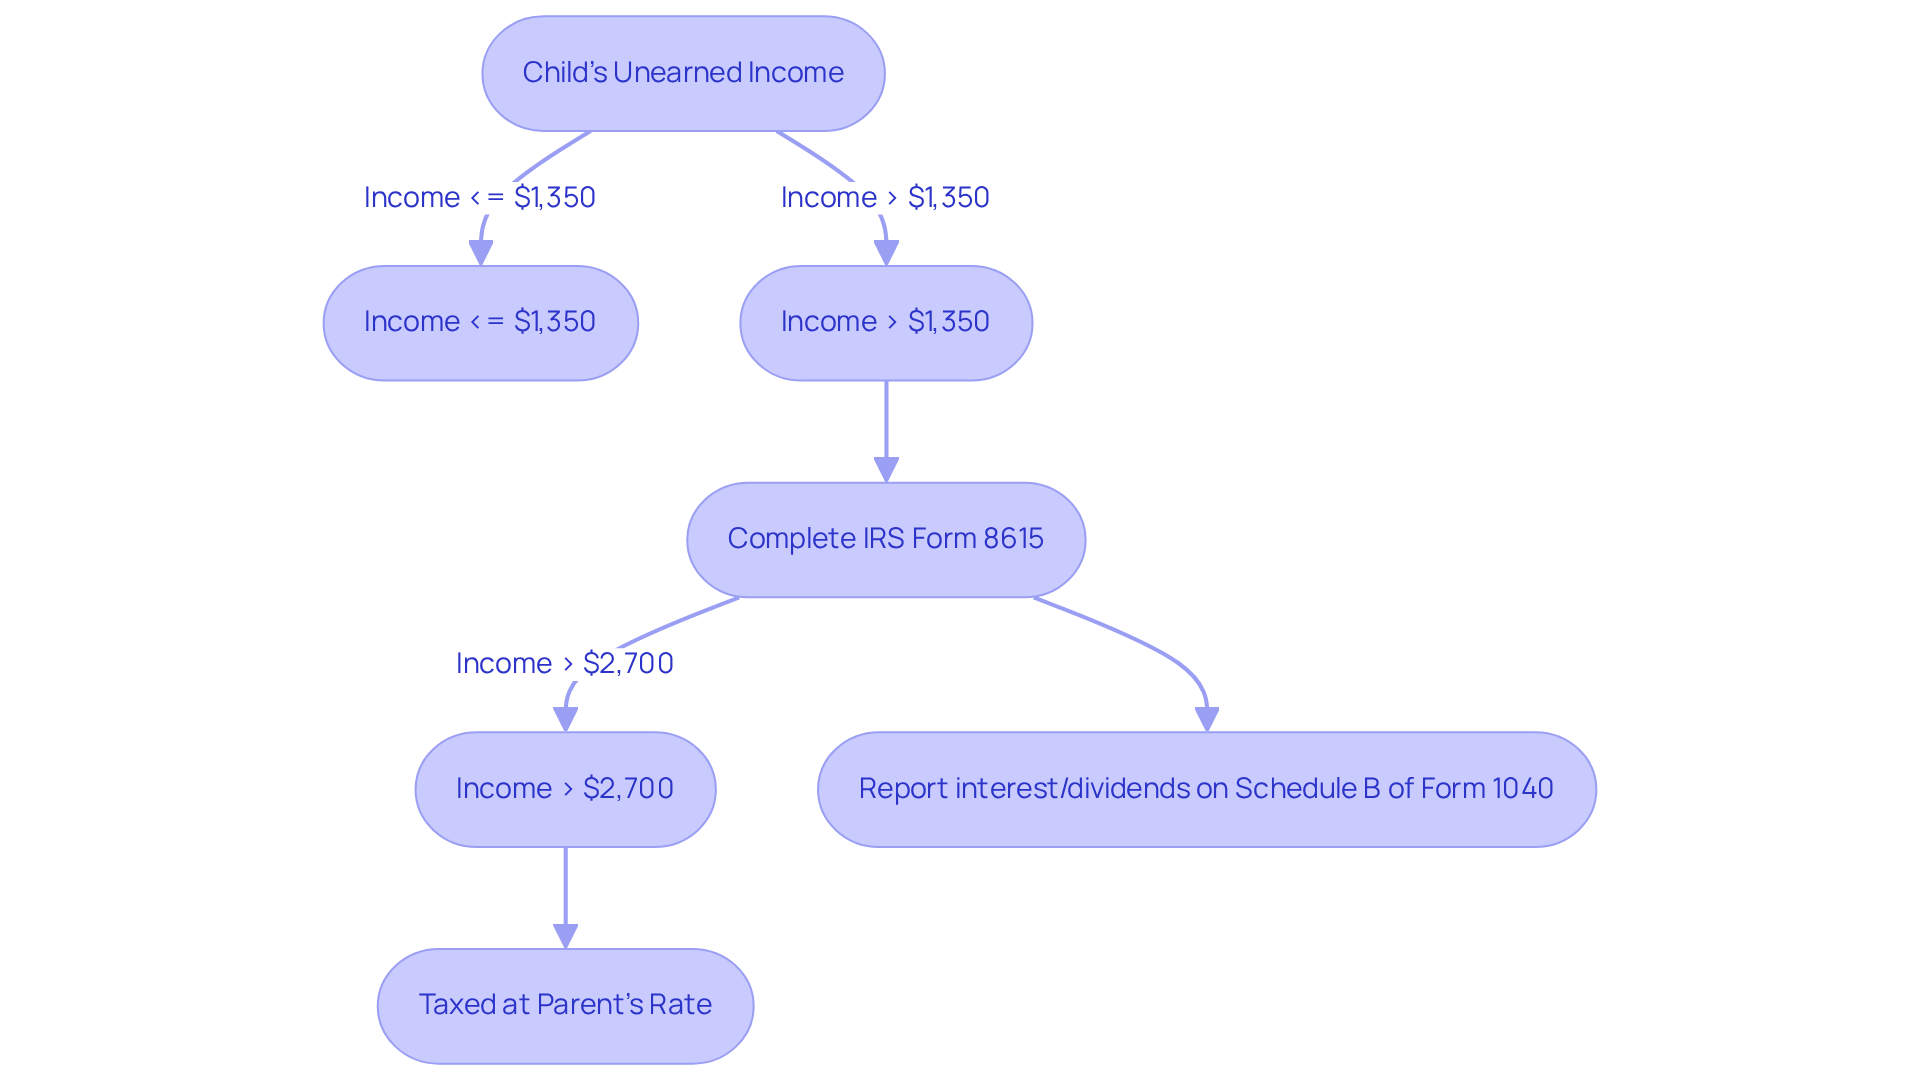
Imagine the surprise of discovering that your child’s unearned income could impact your family’s tax situation more than you thought. When your child’s unearned income goes over $2,700, it gets taxed at your higher rate, not their lower one. This distinction can significantly affect your family’s overall tax liability, making it essential to be aware of these thresholds.
It’s important to understand that families must comply with specific reporting requirements for unearned earnings. For children with unearned earnings exceeding $1,350, you’ll need IRS Form 8615 to calculate the Kiddie Tax. Plus, any interest or dividends must be reported on Schedule B of Form 1040, ensuring you stay compliant with IRS regulations.
Understanding these tax rules can help you feel more in control of your family’s financial planning. The Kiddie Tax was established to prevent wealth shifting to children to avoid higher tax rates, and it applies to children under 18 or full-time students under 24. In 2026, the Kiddie Tax will apply to unearned earnings between $1,350 and $2,700, with specific filing requirements for parents using Form 8615.
It can be tough to navigate tax regulations, especially when you’re trying to figure out how your child’s unearned income impacts your family’s finances. Case studies show that households using custodial accounts need to be aware that these accounts can complicate tax situations due to the Kiddie Tax. Consulting a tax advisor can help families optimize their strategies for managing unearned income, ensuring you make informed decisions about investments and savings that will benefit your children in the long run.
By understanding these tax implications, you can take proactive steps to secure your family’s financial future and ensure your children benefit from your hard work.
Conclusion
Many families feel overwhelmed by the complexities of financial planning, especially when it comes to unearned income. By recognizing that unearned income isn’t taxable, families can tap into various sources of passive revenue, like interest, dividends, and capital gains, to boost their financial well-being. When families understand unearned income, they can make choices that truly benefit their loved ones.
Throughout this article, we’ve shared key insights about the differences between earned and unearned income, the implications of the Kiddie Tax, and the importance of strategic tax planning. Real-life examples, like those of Jay and Emma, as well as Allison and Brian, show how families can thrive with personalized financial guidance. By grasping these concepts, families can confidently navigate their financial futures and make choices that benefit their loved ones.
The journey toward financial security is about more than just understanding income types. It’s about engaging in effective planning and decision-making together. Families are encouraged to seek expert advice, like that offered by Bright Advisers, to ensure they’re making the most of their unearned income opportunities. By taking proactive steps today, families can create a legacy of financial security for their children and beyond.
Frequently Asked Questions
What is earned income?
Earned income is the money you earn through active work, such as wages, salaries, tips, and self-employment earnings that support your family.
What is unearned income?
Unearned income is money received from sources that do not require active work, such as interest, dividends, capital gains, and rental income. This type of income is not taxable.
Why is it important for families to understand the difference between earned and unearned income?
Understanding the differences is crucial for budgeting and planning for children’s future needs, as it affects tax treatment and financial planning.
What is the Earned Income Tax Credit (EITC)?
The EITC is a program that provides financial support to millions of families, encouraging employment and highlighting the differences in tax treatment between earned and unearned income.
What is the Kiddie Tax?
The Kiddie Tax applies when a child’s unearned income exceeds $2,700, affecting the overall tax situation for parents as their child’s income increases.
How can parents report their child’s unearned income?
Parents can report a child’s interest, dividends, and capital gains on their own tax return if the total is below $13,500, but they must be mindful of tax consequences as the child’s income grows.
How can Bright Advisers assist families with financial planning?
Bright Advisers helps families navigate financial challenges by providing personalized planning to optimize tax situations and develop customized retirement plans, ensuring they can fund their children’s education and future needs.
What strategies can families implement to manage their finances effectively?
Families can implement strategies to manage cash flow and invest wisely, allowing them the flexibility to make career decisions based on their desired work-life balance.
List of Sources
- Define Earned and Unearned Income
- EITC reports and statistics | Internal Revenue Service (https://irs.gov/credits-deductions/individuals/earned-income-tax-credit/eitc-reports-and-statistics)
- Raising Rates on Unearned Income: An Equitable Way to Avoid Cuts and Support a Robust and Just Recovery – Mass. Budget and Policy Center (https://massbudget.org/2020/11/05/raising-rates-on-unearned-income-an-equitable-way-to-avoid-cuts-and-support-a-robust-and-just-recovery)
- The Earned Income Tax Credit (https://cbpp.org/research/policy-basics-the-earned-income-tax-credit)
- What is Unearned Income and Is It Taxable? Guide 2026 (https://taxesforexpats.com/articles/expat-tax-rules/what-is-unearned-income-vs-earned-income.html)
- Sources of Personal Income, Tax Year 2018 (https://taxfoundation.org/data/all/federal/personal-income-pi-data)
- Explore Types of Unearned Income
- Best High-Yield Savings Accounts – July 2026 | US News Money (https://usnews.com/banking/high-yield-savings-accounts)
- Savings Account Statistics (2026) (https://wallethub.com/edu/savings-account-statistics/143529)
- The Average Savings Account Balance In The U.S. | Bankrate (https://bankrate.com/banking/savings/savings-account-average-balance)
- Money Talk: 10 Great Quotes About Personal Finance (https://3riversfcu.org/resources/financial-education/detail/money-talk-10-great-quotes-about-personal-finance)
- Understand Tax Treatment and Reporting of Unearned Income
- Topic no. 553, Tax on a child’s investment and other unearned income (kiddie tax) | Internal Revenue Service (https://irs.gov/taxtopics/tc553)
- What Is the Kiddie Tax? Kiddie Tax Rules | U.S. Bank (https://usbank.com/wealth-management/financial-perspectives/financial-planning/kiddie-tax.html)
- Understand the Kiddie tax | Fidelity (https://fidelity.com/learning-center/personal-finance/kiddie-tax)
- Taxing Teens: Working Children, Family Businesses, and the Kiddie Tax | Baker Institute (https://bakerinstitute.org/research/taxing-teens-working-children-family-businesses-and-kiddie-tax)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading